📌 Today’s Highlights
Today we cover 26 IR announcements. Notable among them: G-Skyfall (625A), iFJリート2 (443A), iF米ドルブル1倍 (516A). Use the table of contents below to navigate to each company.
- 625A|G-Skyfall
- 443A|iFJリート2
- 516A|iF米ドルブル1倍
- 278A|G-テラドローン
- 229A|P-アスミHD
- 2307|クロスキャット
- 2788|アップル
- 2929|ファーマフーズ
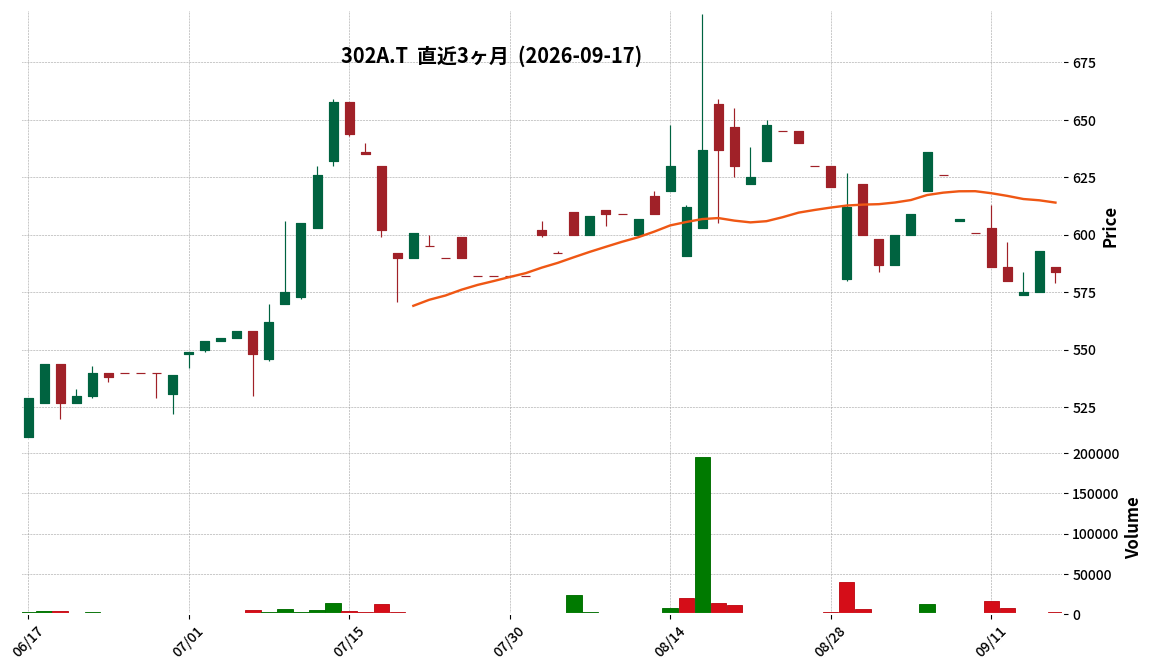
- 302A|G-ビースタイルHD
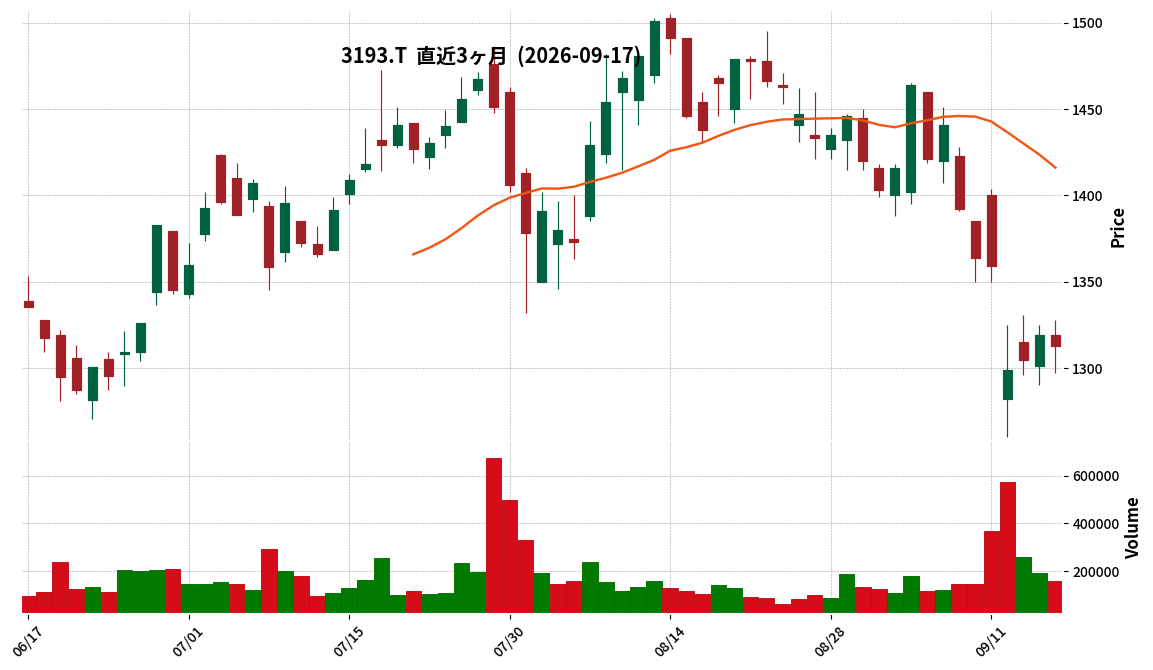
- 3193|エターナルホスピG
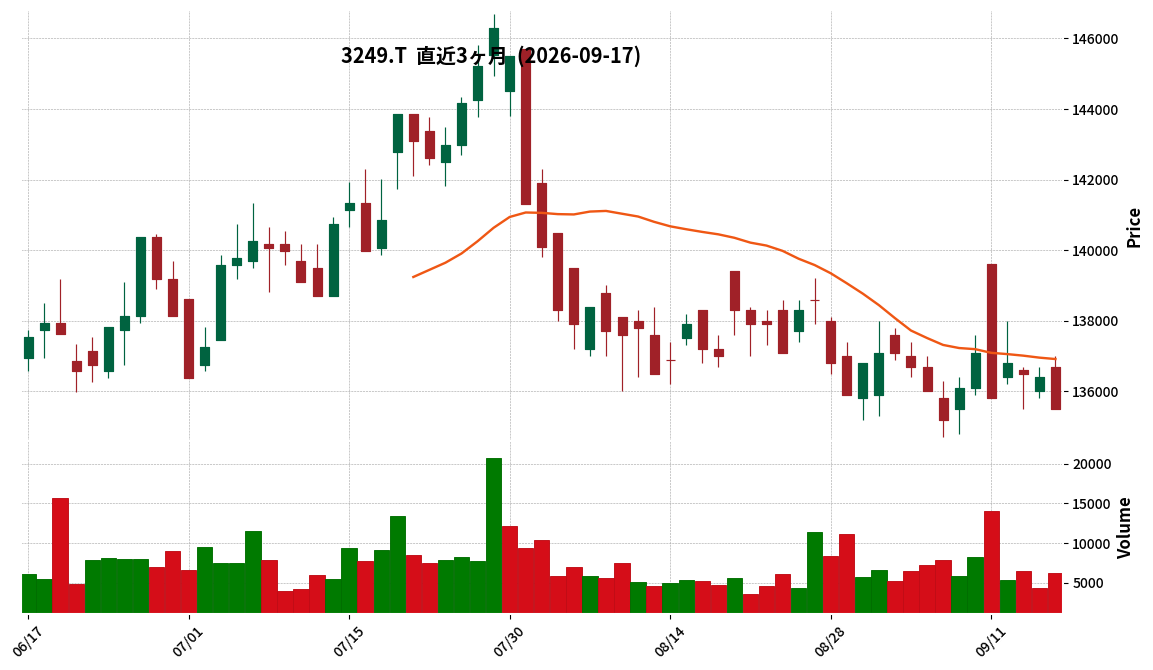
- 3249|R-産業ファ
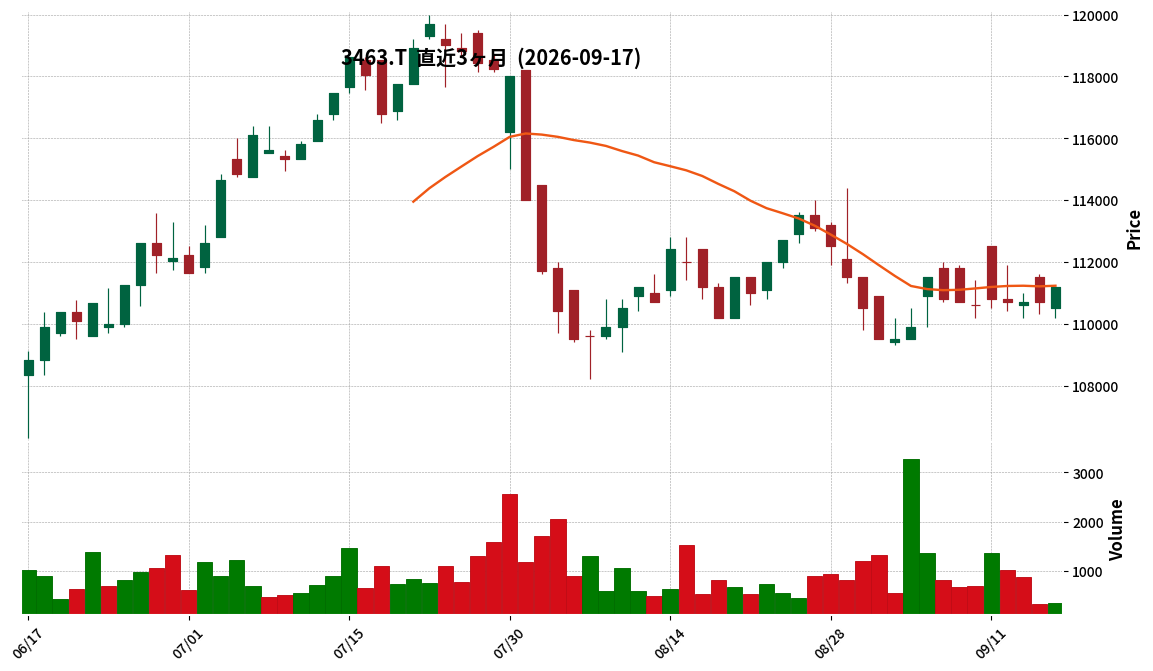
- 3463|R-いちごホテル
- 4441|トビラシステムズ
- 4592|G-サンバイオ
- 7571|ヤマノHD
- 7685|G-BUYSELL
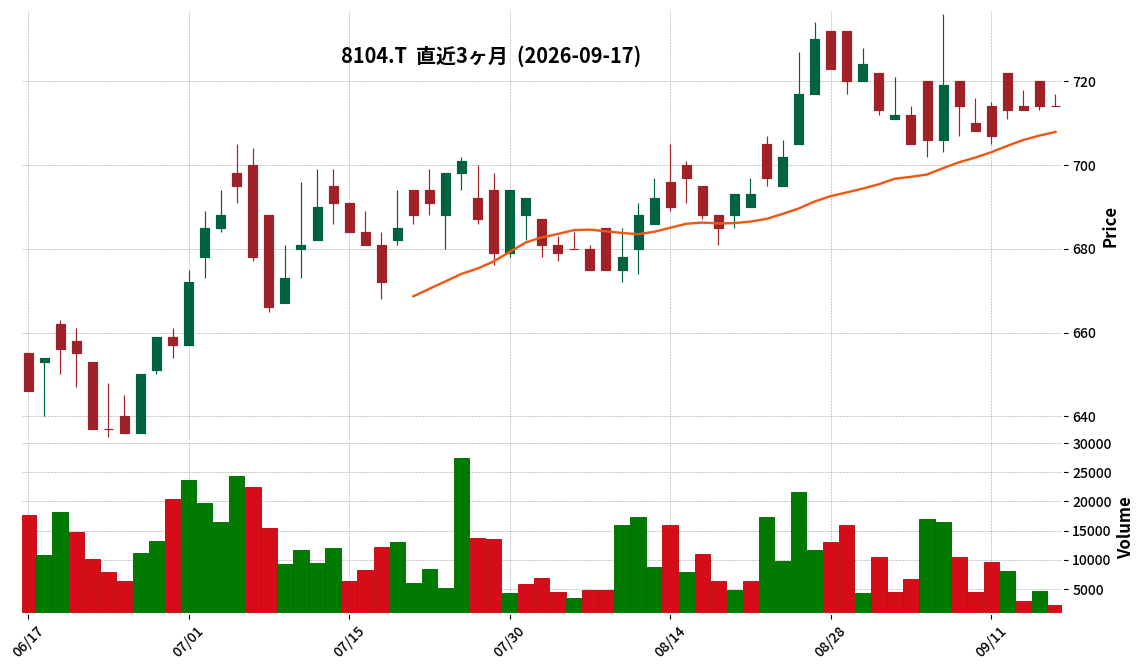
- 8104|クワザワHD
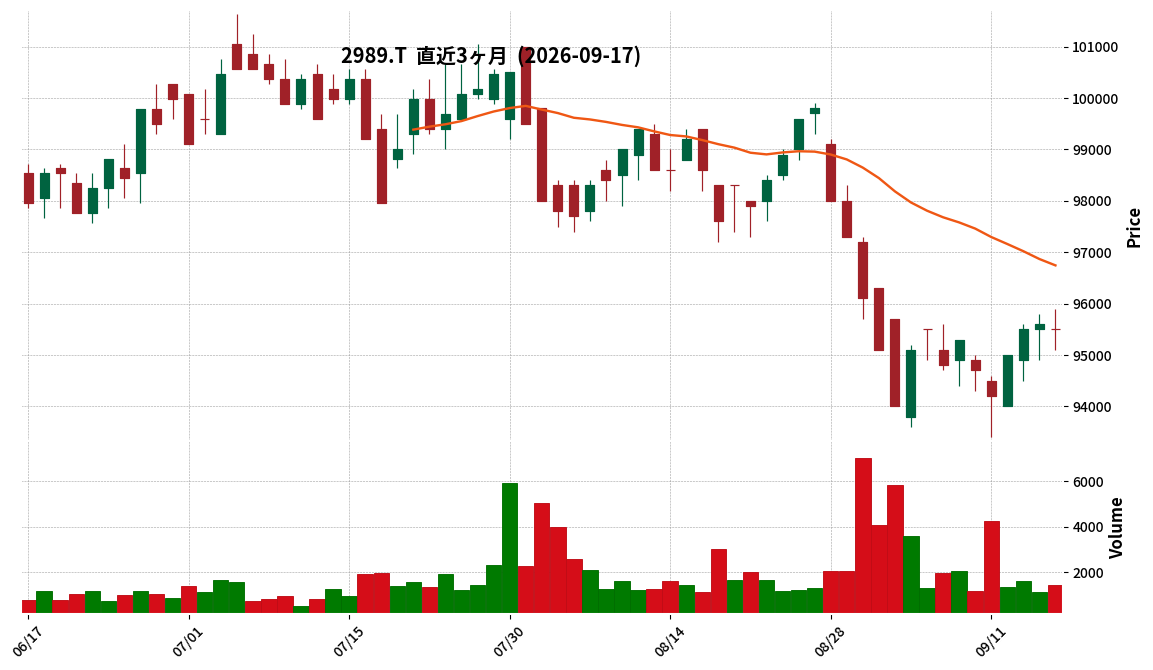
- 2989|R-東海道リート
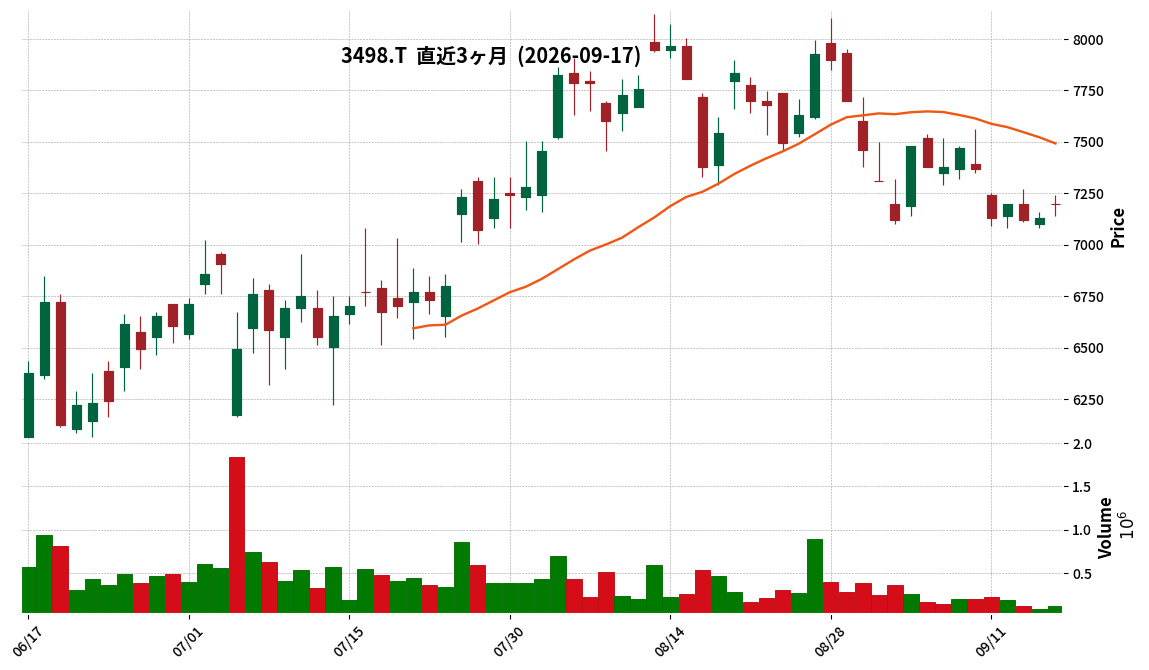
- 3498|霞ヶ関キャピタル
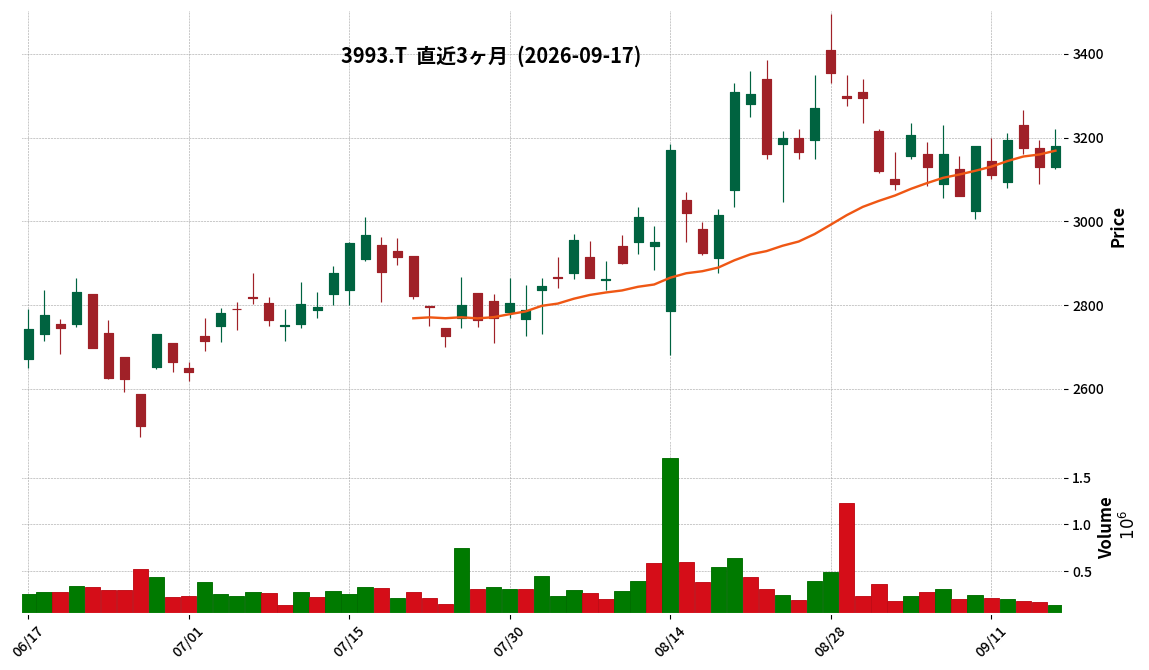
- 3993|PKSHA
- 4923|COTA
- 2796|ファーマライズHD
- 3269|R-ADR
- 4436|G-ミンカブ
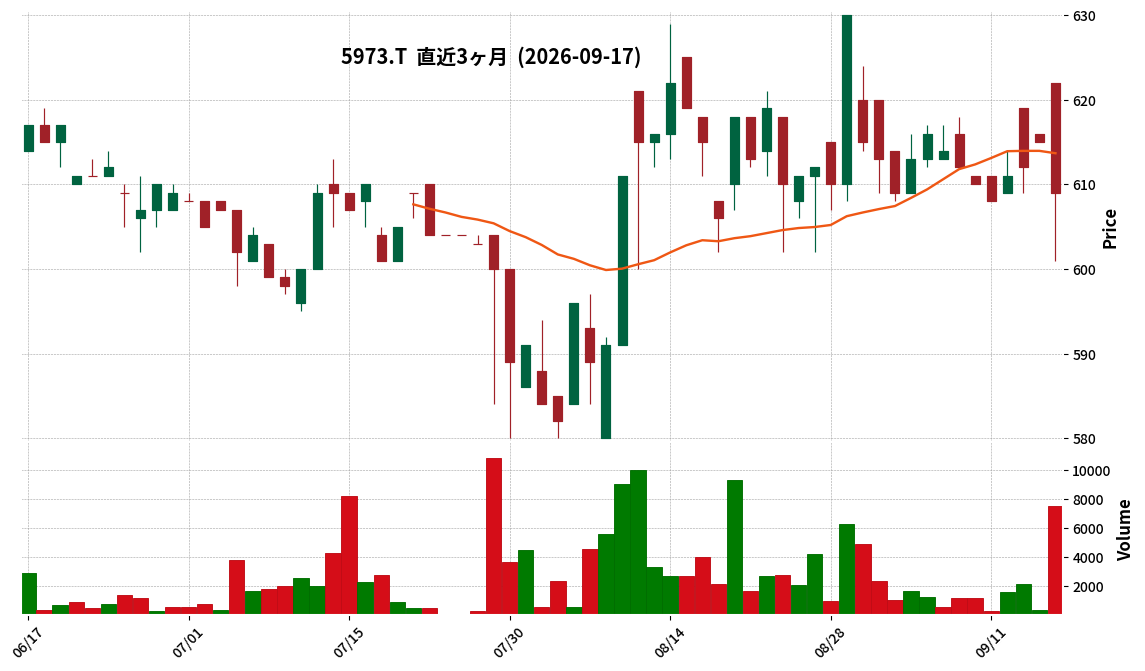
- 5973|トーアミ
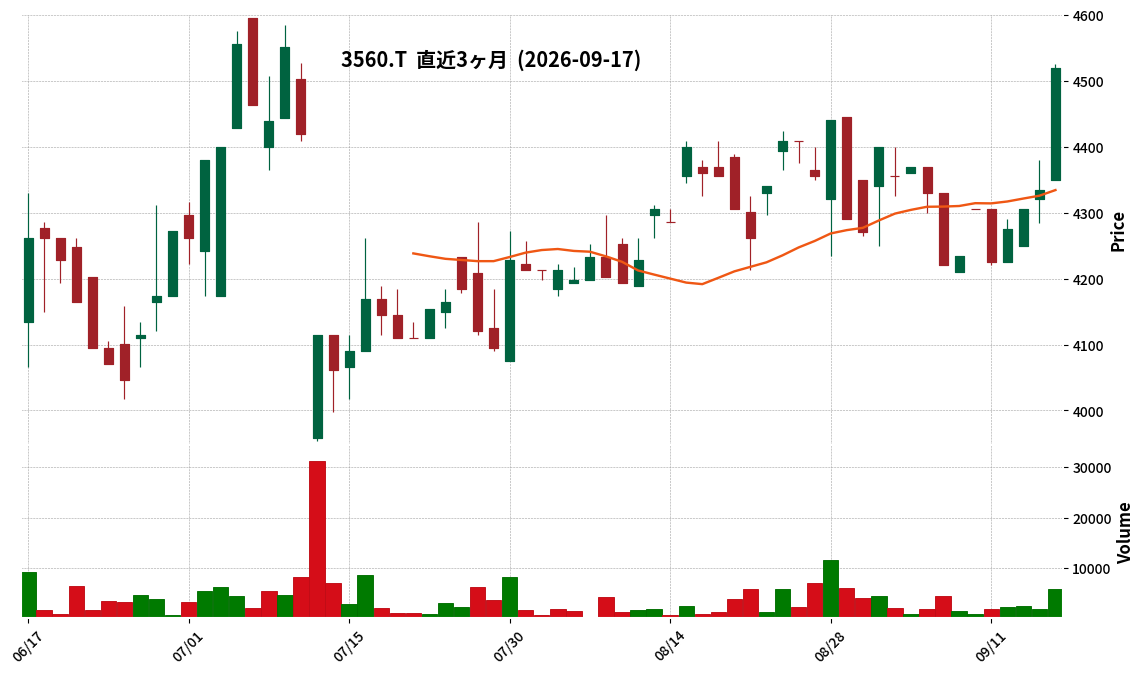
- 3560|ほぼ日
625A|G-Skyfall
—
▲ +0.00%
📎 Source:G-Skyfall Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Skyfall Inc. (G-Skyfall) was listed on the Tokyo Stock Exchange Growth Market on September 17, 2026.
- The forecast for the fiscal year ending September 2026 (non-consolidated) includes net sales of ¥18,497 million, operating profit of ¥1,144 million, ordinary profit of ¥1,176 million, and net profit of ¥807 million.
- Compared to the previous fiscal year, the FY2026 forecast (non-consolidated) shows an increase of 114.1% in net sales, 222.2% in operating profit, 212.6% in ordinary profit, and 180.8% in net profit.
- For the third quarter cumulative period of FY2026 (non-consolidated, actual), net sales were ¥14,059 million, operating profit ¥1,013 million, ordinary profit ¥1,065 million, and net profit ¥796 million.
- The forecast for FY2026 includes earnings per share of ¥130.00 and a dividend per share of ¥0.00.
🤖 AI Perspective
The announced earnings forecast on the day of listing indicates significant year-over-year increases across sales and profit metrics, primarily driven by the growth of its reward marketing platform business. A projected operating profit more than doubling suggests a potential improvement in business profitability. Investors may find it noteworthy to monitor how the company’s core service “SKYFLAG” and its strategies to adapt to evolving market conditions will influence future performance.
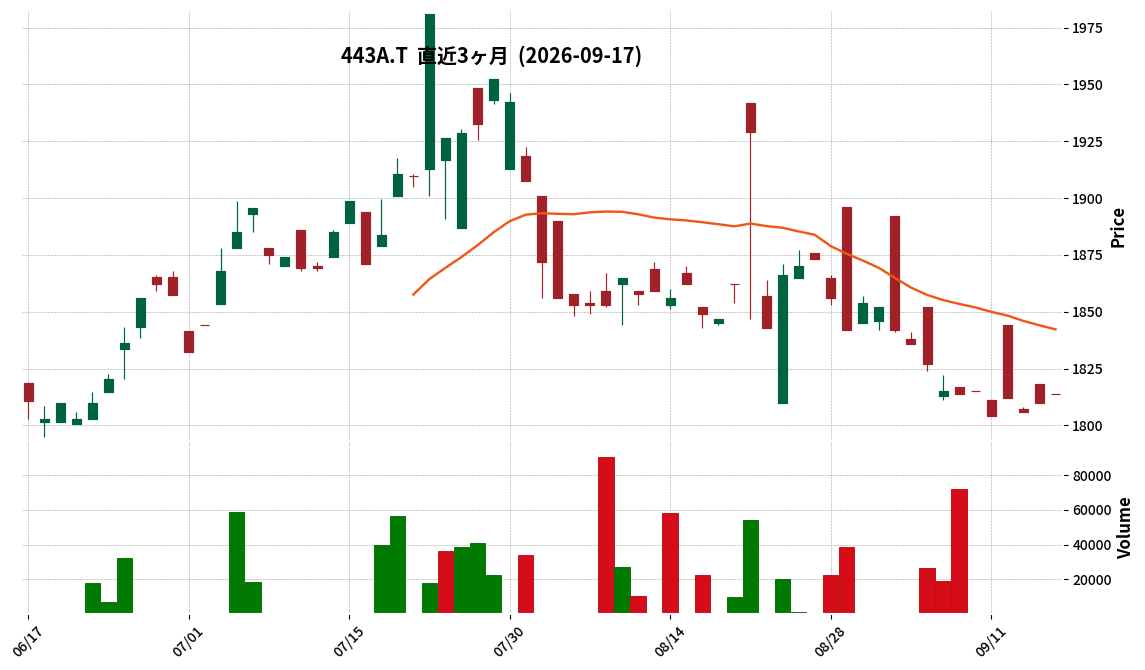
443A|iFJリート2
1814.0
▲ +0.22%
📎 Source:iFJリート2 Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- iFreeETF TOKYO REIT INDEX (iFJ REIT 2, Fund Name: iFreeETF 東証REIT指数(2・5・8・11月決算型), Code: 443A) announced its financial results for the fiscal period ending August 2026 (February 5, 2026 – August 4, 2026) on September 17, 2026.
- Net assets for the current period amounted to ¥15,190 million, increasing from ¥4,641 million in the previous period.
- The main investment assets constituted 98.4% of the portfolio, totaling ¥14,949 million.
- The number of outstanding units at the end of the period was 8,193 thousand units, an increase from 2,256 thousand units at the end of the previous period.
- The net asset value per unit was ¥1,853.93.
- The distribution per unit was ¥19.
- Operating revenue for the period was -¥500,569,476, operating expenses were ¥9,831,756, and the net loss for the period was -¥510,401,232.
🤖 AI Perspective
iFJ REIT 2 demonstrated a substantial increase in net assets and outstanding units for the August 2026 period, which may suggest significant new subscriptions. Despite reporting a negative operating revenue and a net loss for the period, the distribution per unit increased to ¥19 from ¥12 in the previous period. Investors may find this increase in distribution per unit noteworthy, especially considering the fund’s primary investment in REITs.
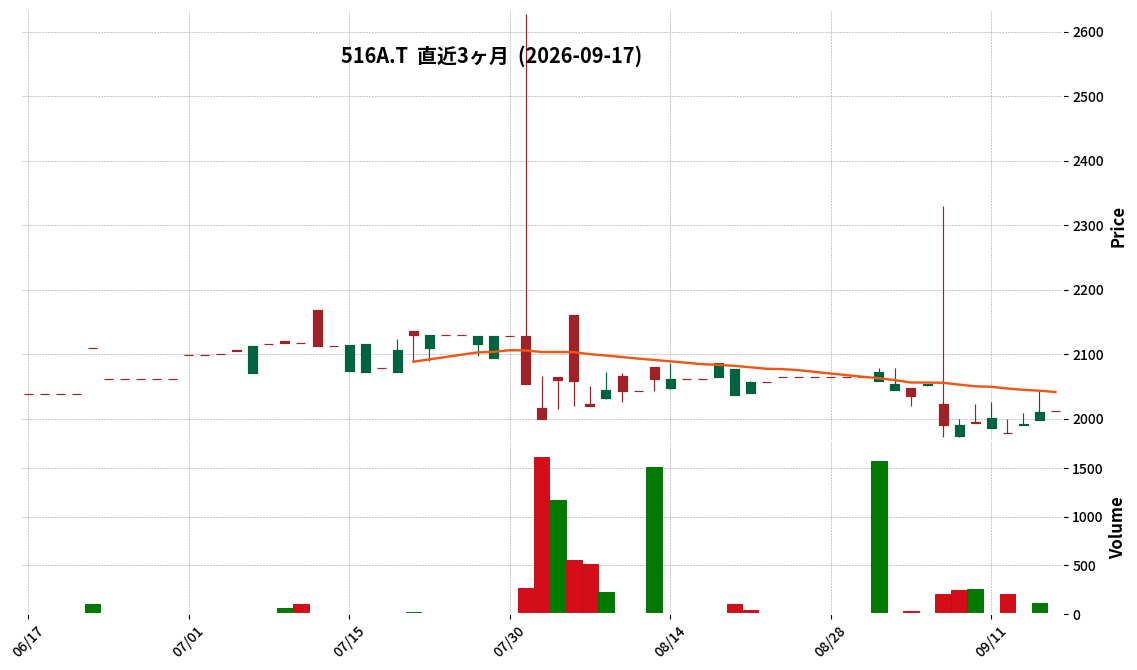
516A|iF米ドルブル1倍
2011.0
▲ +0.05%
📎 Source:iF米ドルブル1倍 Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- iFreeETF US Dollar Bull (1x) (Code: 516A) announced its financial results for the August 2026 fiscal period (March 2, 2026 – August 4, 2026) on September 17, 2026.
- Total net assets at the end of the calculation period amounted to ¥4,216 million (100.0% composition). Key investment assets included ¥4,238 million in beneficiary certificates of parent investment trusts (100.5% composition) and △¥21 million in cash, deposits, and other assets (net of liabilities) (△0.5% composition).
- The total number of units outstanding at the end of the period was 2,070 thousand units, with the NAV per unit reported at ¥2,037.19.
- A distribution of ¥2 per unit was declared, with the payment commencement date set for September 11, 2026.
- For the period’s Statement of Income and Retained Earnings, total operating revenue was △¥57,830,978, operating profit or loss was △¥59,399,286, and net profit or loss for the period was △¥59,399,286.
🤖 AI Perspective
The iFreeETF US Dollar Bull (1x) tracks the performance of the US dollar, making its operational results of interest to investors. The reported net assets, NAV per unit, and distribution per unit provide key metrics on the fund’s size and profitability. Given that its primary investments are in beneficiary certificates of parent investment trusts and foreign exchange forward contracts, the fund’s performance may be significantly influenced by currency market movements.
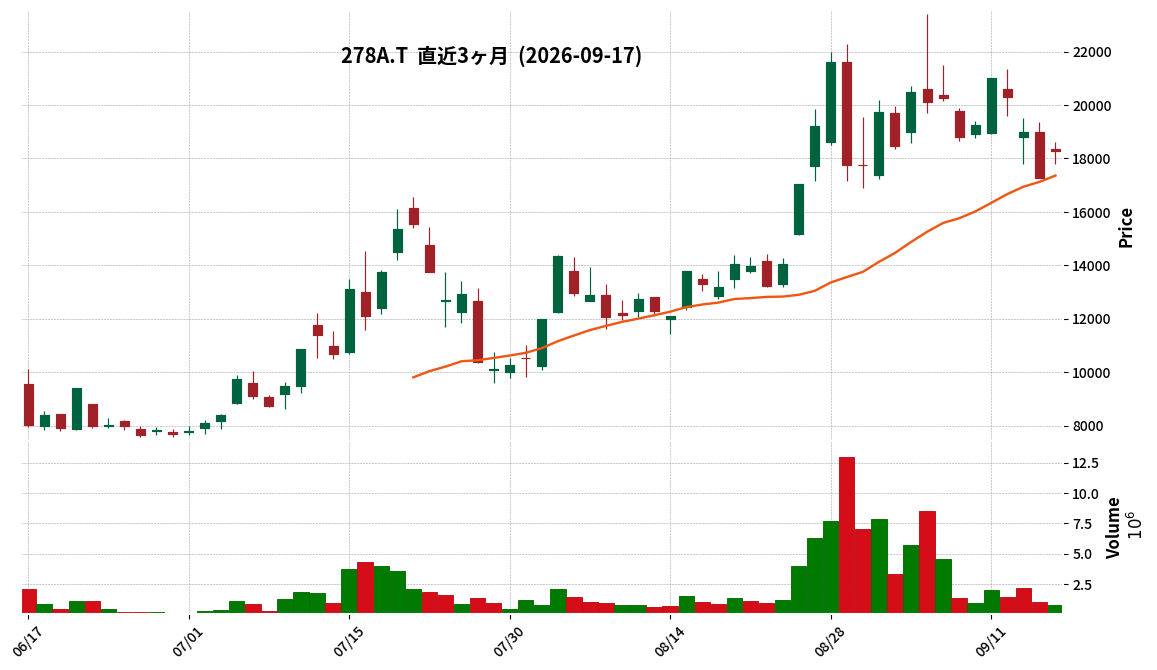
278A|G-テラドローン
18280.0
▲ +5.85%
📎 Source:G-テラドローン Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Terra Drone Co. (278A) released the transcript of its Q2 FY2027 earnings call for institutional investors and analysts on September 17, 2026.
- The presentation portion of the call was omitted from the transcript as it was identical to the “Financial Results Briefing and Defense & Other Business Strategy Presentation” held on September 14, 2026.
- The company attributes its lead in the defense business to three main factors: direct experience and knowledge gained in Ukraine, rapid development capabilities, and strong trust with defense prime contractors.
- The company emphasizes that the most crucial factor for benefiting from upcoming defense budget announcements would be the mandated domestic production of key components such as flight controllers, batteries, motors, and chargers.
- Initial sales revenue from the defense business is expected to be recorded starting around September to October 2026.
- Regarding the market size for interceptor drones, the company suggests its previously presented figures may be underestimated, citing the vast number of drones deployed in the Ukrainian conflict.
🤖 AI Perspective
This transcript provides valuable insights into how Terra Drone is building its strategic advantage in the defense sector and its plans for future business expansion. The company’s expectations for mandated domestic production, the timing of initial revenue recognition, and its global expansion strategy could be key areas for investors to monitor in evaluating future performance. The influence of real-world combat experience in Ukraine on technology development and market perception also appears to be a notable aspect of their strategy.
229A|P-アスミHD
760.0
▲ +0.00%
📎 Source:P-アスミHD Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- P-Asumi HD announced the cancellation of its acquisition (making it a subsidiary) of Casa Planning Co., Ltd., which was initially disclosed on March 24, 2026.
- Following the “Notice of Postponement of Share Transfer Execution Date” published on June 1, 2026, the Board of Directors resolved to terminate the share transfer agreement on September 17, 2026.
- The reason for the termination of the agreement is a recognized discrepancy between P-Asumi HD and Casa Planning regarding the establishment of an internal control system required for a subsidiary of a listed company.
- P-Asumi HD determined that building internal systems post-acquisition would be extremely difficult under the circumstances, leading to the decision to cease the share acquisition.
- The consolidated earnings forecast for the fiscal year ending November 2026, disclosed on January 14, 2026, did not include the performance of Casa Planning, therefore, there is no impact on earnings due to this cancellation.
🤖 AI Perspective
This announcement underscores the critical importance of non-financial factors, such as governance and internal controls, in corporate M&A, alongside financial considerations. The reported discrepancy in understanding regarding the required internal control framework for a subsidiary of a listed company appears to have been a pivotal factor in the decision to terminate the acquisition. The absence of any impact on the previously announced earnings forecast may offer some reassurance to investors.
2307|クロスキャット
1092.0
▲ +1.39%
📎 Source:クロスキャット Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
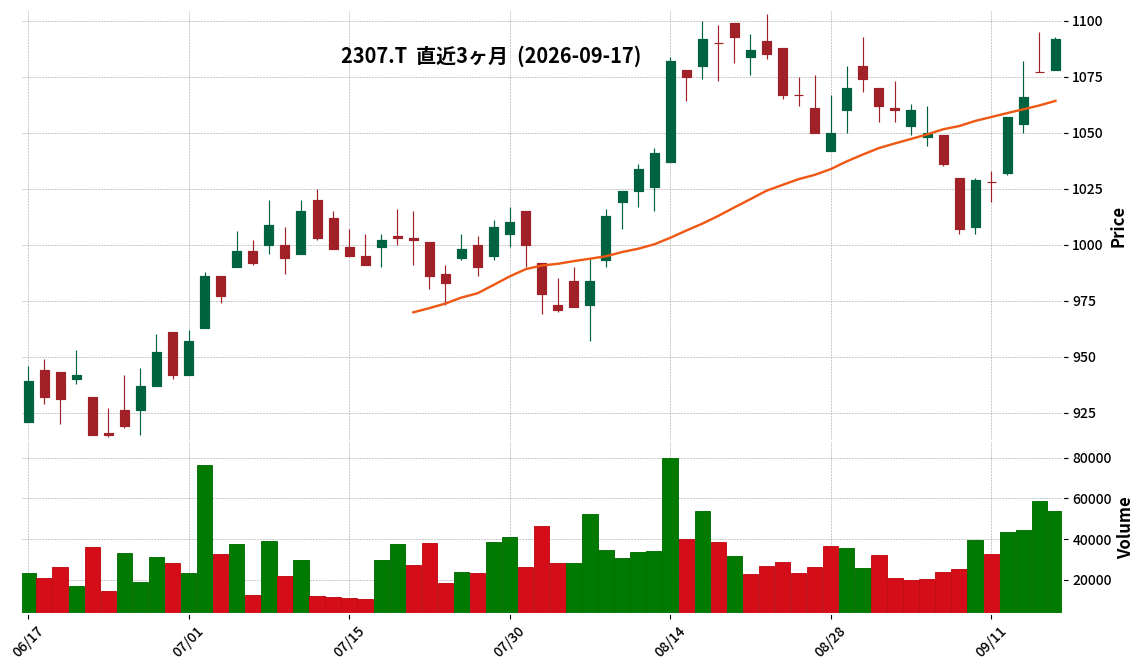
- Cross Cat Co., Ltd. resolved to change the content of its shareholder benefit program and the record date for shareholder benefits at today’s Board of Directors meeting.
- The shareholder benefit will change from the current “QUO cards and original calendar” to “selectable e-gifts and original calendar”.
- Examples of redemption options for the selectable e-gifts include Amazon Gift Cards, PayPay Money Lite, and d Points.
- The record date for shareholder benefits will be changed from September 30 annually to March 31 annually.
- The first application of the revised record date will be March 31, 2027.
- Shareholder benefits for the record date of September 30, 2026, will be implemented under the current system.
🤖 AI Perspective
The announced changes aim to enhance shareholder convenience and expand the selection of benefits. The shift to e-gifts, which offer broader utility similar to cash, may be perceived as an improvement in practicality for shareholders. Additionally, the change in the record date could influence how investors consider the timing of dividend and benefit entitlements relative to other companies.
2788|アップル
390.0
▲ +1.56%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
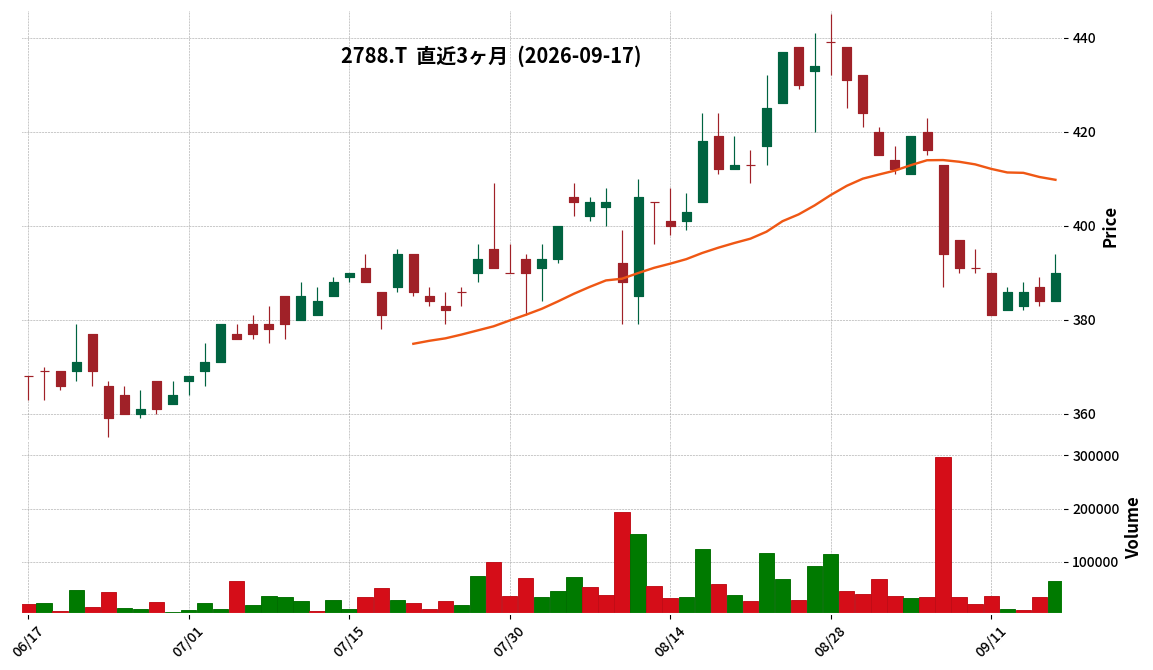
- Apple International Co., Ltd. announced on September 17, 2026, revisions to its full-year consolidated earnings forecast and year-end dividend forecast for the fiscal year ending December 2026.
- The full-year consolidated earnings forecast was revised as follows: Net sales from ¥35,856 million to ¥46,016 million (28.3% increase), operating profit from ¥769 million to ¥932 million (21.2% increase), ordinary profit from ¥930 million to ¥1,094 million (17.6% increase), and profit attributable to owners of parent from ¥615 million to ¥803 million (30.6% increase).
- Earnings per share (EPS) were revised from ¥47.96 in the previous forecast to ¥62.28 in the revised forecast.
- The year-end dividend forecast was increased from ¥10.00 per share to ¥15.00 per share.
- The reasons cited for the upward revision of the earnings forecast include the continued depreciation of the yen and the strong performance of the overseas used car export business.
🤖 AI Perspective
The upward revision of the earnings forecast, particularly the double-digit growth rates in net sales and net profit, suggests a positive assessment by management of the company’s profitability. The increased year-end dividend also indicates a commitment to shareholder returns. The strong performance of the overseas used car export business, driven by a weaker yen, is noted as a key factor, highlighting the impact of foreign exchange movements on the company’s results.
2929|ファーマフーズ
739.0
▼ -0.40%
📎 Source:ファーマフーズ Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
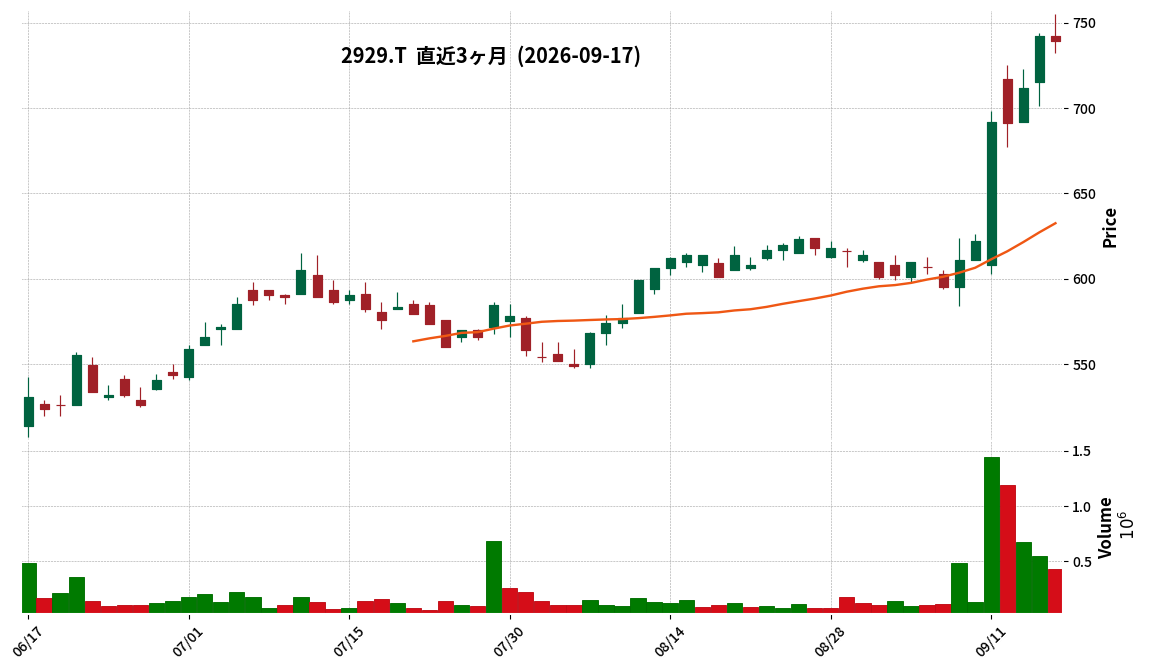
- PharmaFoods Co., Ltd. issued a “Correction to a Part of the Consolidated Financial Results for the Fiscal Year Ending July 2026 (Japanese GAAP)” on September 17, 2026.
- The correction addresses errors identified in the “Consolidated Financial Results for the Fiscal Year Ending July 2026 (Japanese GAAP)” initially disclosed on September 11, 2026.
- The specific area of correction is within the “Net Assets” section of the “Consolidated Balance Sheet,” under “3. Consolidated Financial Statements and Principal Notes,” as detailed on page 9 of the attached document.
- Corrected parts are indicated by an underline in the updated document.
🤖 AI Perspective
This correction to the financial results indicates that an error was identified in previously released disclosure, specifically impacting the net assets section of the consolidated balance sheet. Such amendments are a standard part of maintaining the accuracy of corporate financial reporting. Investors may wish to review the revised figures to ensure their assessment of the company’s financial health is based on the most accurate available data. The extent of the numerical changes could potentially influence perspectives on the company’s financial standing.
302A|G-ビースタイルHD
584.0
▼ -1.52%
📎 Source:G-ビースタイルHD Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- G-BStyle HD resolved to acquire all shares of HR Associé, making it a subsidiary, at a board meeting on September 17, 2026, and signed a share transfer agreement on the same date.
- The acquisition price is JPY 1,205 million for common shares of the target company, plus approximately JPY 9 million for advisory fees.
- HR Associé has been engaged in recruitment consulting, Recruitment Process Outsourcing (RPO) services, and talent development/training services for over 15 years, building a business foundation primarily with large corporations.
- The scheduled share transfer date is October 1, 2026, at which point HR Associé will become a consolidated subsidiary of G-BStyle HD.
- HR Associé’s revenue for the past three fiscal years (June 2024 to June 2026) increased from JPY 522 million to JPY 763 million, and net profit grew from JPY 36 million to JPY 61 million.
🤖 AI Perspective
This acquisition is part of G-BStyle HD’s “Bold Vision200” mid-term management plan, aiming to strengthen its Recruitment Process Outsourcing (RPO) business. Synergy is anticipated between HR Associé’s RPO services for large corporations and G-BStyle HD’s “ShufuJOB” job media platform. Integrating the RPO business, which is less susceptible to competition in the job advertising market, could indicate a strategic move towards diversifying the business portfolio and enhancing profitability.
3193|エターナルホスピG
1313.0
▼ -0.45%
📎 Source:エターナルホスピG Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Eternal Hospitality Group reported consolidated net sales of ¥51,254 million for the fiscal year ended July 2026, marking a 10.6% increase from the previous year.
- Operating profit was ¥2,797 million (down 10.4% year-on-year), ordinary profit was ¥2,800 million (down 9.8% year-on-year), and net profit attributable to parent company shareholders was ¥1,318 million (down 23.4% year-on-year), showing a decrease in profit compared to the previous fiscal year.
- Factors contributing to the decline in operating profit included a shortfall in domestic and international store openings compared to plans, increased selling, general and administrative expenses, and costs associated with store openings heavily concentrated in the fourth quarter.
- An impairment loss of ¥391 million was recorded for some domestic stores and four Torikizoku directly managed stores in China that were decided for closure.
- For the fiscal year ending July 2027, the company forecasts consolidated net sales of ¥57,231 million (up 11.7% year-on-year), operating profit of ¥3,078 million (up 10.0% year-on-year), and net profit attributable to parent company shareholders of ¥1,891 million (up 43.5% year-on-year), projecting growth in both revenue and profit.
🤖 AI Perspective
The FY2026 results showing increased revenue but decreased profit, alongside missed store opening targets and an impairment loss, may be key areas of focus for investors. The company’s projections for FY2027, anticipating revenue and profit growth driven by domestic existing store performance and expanded store networks, could suggest a potential turnaround. It might be worth monitoring how the company executes its growth strategies and manages costs in the upcoming fiscal year to achieve these targets.
3249|R-産業ファ
135500.0
▼ -0.66%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- R-Industrial Fund announced operating revenue of ¥23,440 million (down 2.4% from previous period), operating income of ¥11,533 million (down 7.6%), and net income of ¥9,942 million (down 9.3%) for the fiscal period ended July 2026.
- Distribution per unit (including excess distribution) was ¥4,094, with excess distribution per unit amounting to ¥162.
- Total assets at the end of the period were ¥569,954 million, net assets were ¥246,157 million, and the equity ratio stood at 43.2%.
- During the period from February 1, 2026, to July 31, 2026, the REIT acquired four properties: IIF Nagoya Logistics Center II, IIF Shizuoka Susono Logistics Center, IIF Sakai Logistics Processing Center (land), and IIF Nishinomiya Kita Logistics Processing Center (land).
- For the forecast of the fiscal period ending January 2027, the REIT projects operating revenue of ¥23,879 million (up 1.9% from previous period) and distribution per unit (including excess distribution) of ¥4,000.
🤖 AI Perspective
The decrease in revenue and profit for the July 2026 fiscal period may be attributed to the recognition of gains on sale of some assets and portfolio adjustments through new property acquisitions. However, the forecast for the January 2027 period indicates an expected increase in operating revenue, suggesting that future operational strategies could be a key focus for investors. The equity ratio of 43.2% demonstrates a stable financial position.
3463|R-いちごホテル
111200.0
▲ +0.45%
📎 Source:R-いちごホテル Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- R-Ichigo Hotel REIT announced its financial results for the 2026 July fiscal period (February 1, 2026, to July 31, 2026).
- During this period, operating revenue was ¥2,902 million (down 7.8% from the previous period), operating income was ¥1,625 million (down 5.7%), ordinary income was ¥1,232 million (down 9.1%), and net income was ¥1,231 million (down 9.1%).
- Distribution per unit was ¥3,761 (excluding excess distributions), and total distributions amounted to ¥1,231 million.
- As of the end of July 2026, total assets were ¥80,807 million, net assets were ¥40,929 million, and the equity ratio was 50.7%.
- For the forecast of the 2027 January period, operating revenue is projected to be ¥2,917 million (up 0.5% from the previous period), with a distribution per unit of ¥3,091.
- Nest hotel alt. Sapporo Odori has been closed entirely since March 2026, and HOTEL THE KNOT YOKOHAMA since April 2026, due to value-up renovations.
- Hotel Livemax Nihonbashi Hakozaki was sold at 1.3 times its book value, with the gain on sale distributed to unitholders.
🤖 AI Perspective
R-Ichigo Hotel REIT’s performance in the 2026 July fiscal period appears to have been impacted by temporary closures for value-up renovations and shifts in inbound demand. However, the strategy of securing funds through property sales, distributing gains to unitholders, and reinvesting for future asset acquisitions and value enhancement suggests a proactive approach to portfolio quality and growth. The revenue forecast for the next period indicates an expectation of recovery, making the post-renovation hotel performance and evolving market conditions key areas for investors to monitor.
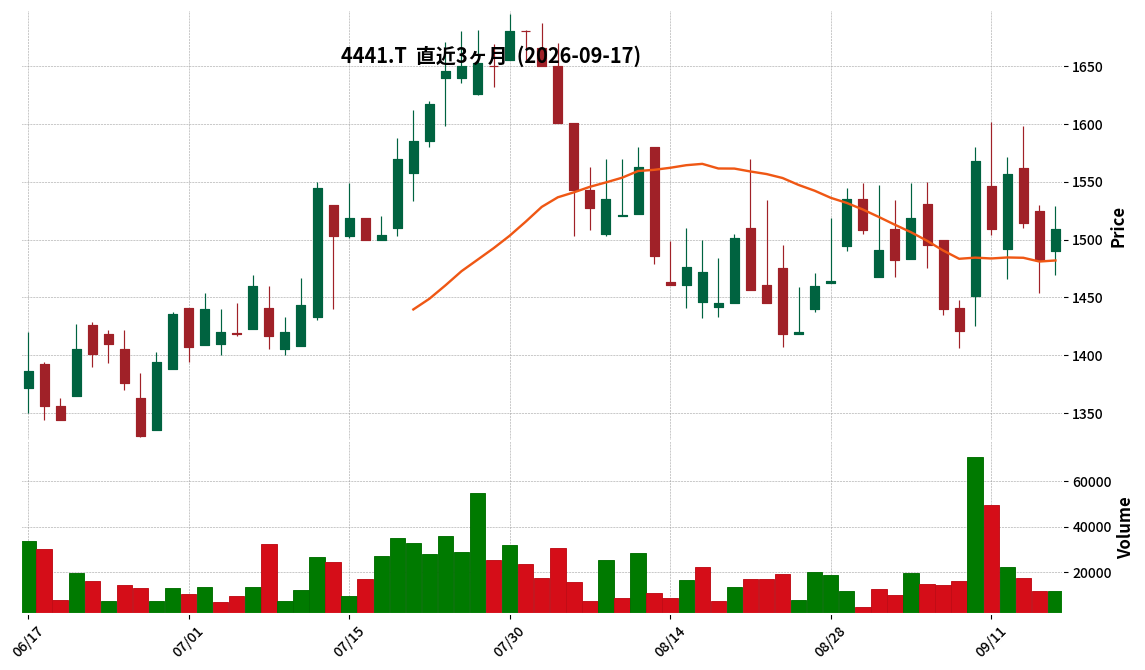
4441|トビラシステムズ
1509.0
▲ +1.82%
📎 Source:トビラシステムズ Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Tobila Systems disclosed its Q&A regarding the Q3 FY2026 financial results on September 17, 2026.
- The dividend policy for the Mid-term Management Plan 2028 period was confirmed to be a payout ratio of 35% as a guideline, with a minimum of ¥20 per share. If performance exceeds this guideline, the dividend will not be fixed at ¥20 but determined based on the 35% guideline.
- Regarding the capital and business alliance with Prodlight, specific collaboration details, including sales collaboration, service and function improvements, and product integration, are currently under discussion, with an aim to expand in the cloud PBX market.
- The decline in mobile security business revenue was primarily attributed to changes in the sales and operation strategy for 280blocker, with the company stating it does not perceive this as a structural plateau.
- The increase in Tobila Phone Biz revenue includes the impact of temporary revenue recognition, while sales units continue to accumulate. For existing customers upon contract expiration, the company anticipates new 5-7 year contracts, primarily involving advance payments for usage fees.
🤖 AI Perspective
The clarity regarding the dividend policy could enhance investor understanding of the company’s future performance linkage. Furthermore, the progress of specific discussions concerning the alliance with Prodlight is a notable point for evaluating the company’s growth strategy, particularly its positioning in the cloud PBX market. The explanation that the decline in revenue for the core mobile security business is due to a change in strategy rather than a structural issue may mitigate concerns about the business’s stability.
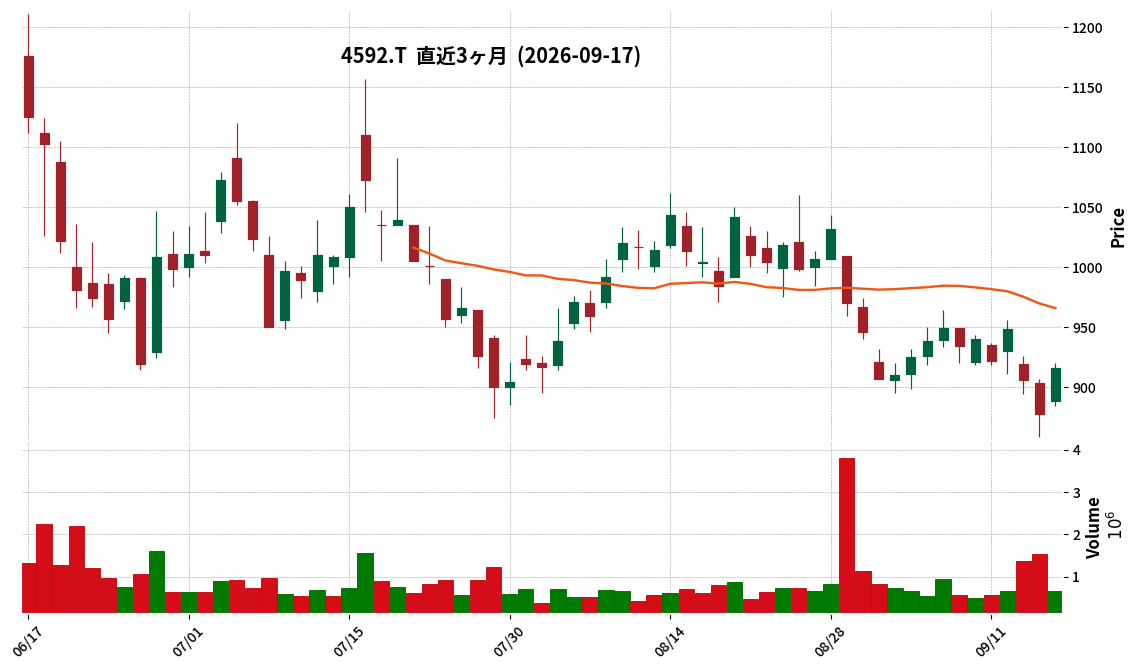
4592|G-サンバイオ
916.0
▲ +4.45%
📎 Source:G-サンバイオ Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- G-SanBio announced its Q2 FY2027 earnings presentation material on September 17, 2026.
- The company’s cell therapy product, Akugo® for intracerebral injection, commenced sales on May 21, 2026.
- For the Q2 FY2027 (cumulative) consolidated financial highlights, interim net loss was 1,791 million yen, an improvement of 205 million yen compared to a loss of 1,997 million yen in the previous fiscal year’s same period.
- Research and development expenses for the period were 1,226 million yen, a decrease of 120 million yen from 1,346 million yen in the prior year’s same period.
- To strengthen the commercial manufacturing system for Akugo®, G-SanBio concluded an agreement with Minaris Advanced Therapies Co., Ltd. for integrated domestic manufacturing and a trial manufacturing contract with JCR Pharma Co., Ltd.
🤖 AI Perspective
G-SanBio’s Q2 FY2027 earnings presentation highlights the launch of its key cell therapy product, Akugo®, and subsequent business progress. The reported improvement in interim net loss may suggest that reduced R&D expenses, along with a partial deferral of manufacturing-related costs to the second half, contributed to this outcome. The company’s focus on strengthening its domestic manufacturing base for stable supply of regenerative medical products could be a critical factor for its future business expansion, making this development worth monitoring.
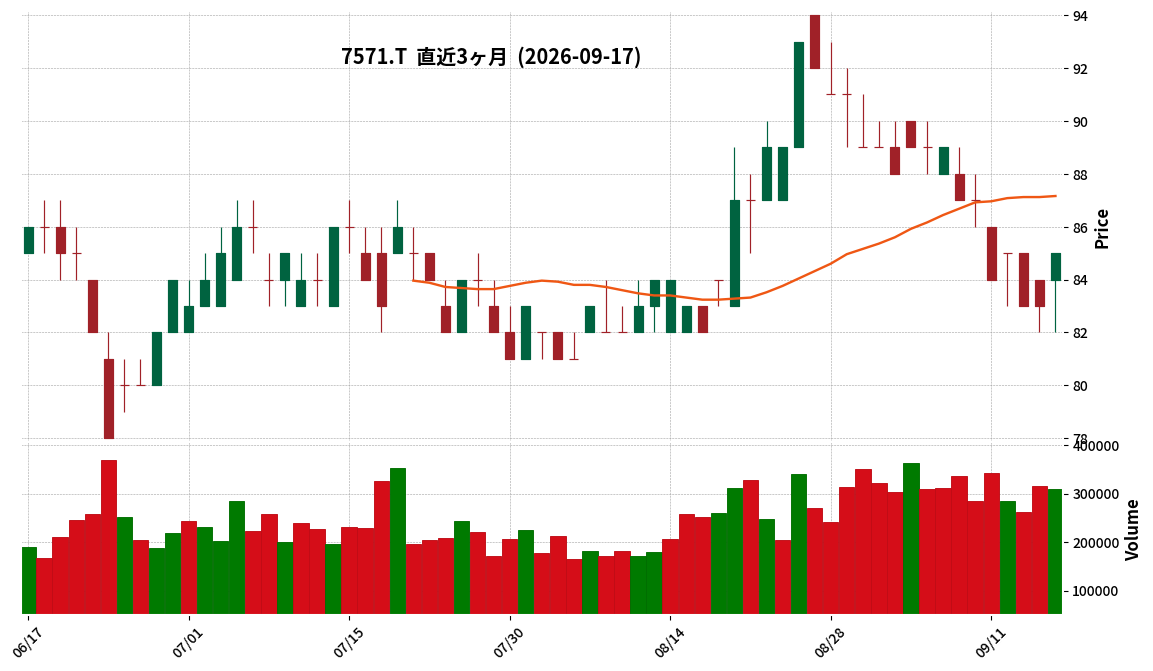
7571|ヤマノHD
85.0
▲ +2.41%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Yamano HD resolved to acquire 100% of shares in Japan Heart Co. on September 17, 2026, making it a subsidiary.
- Japan Heart Co. operates the kimono specialty store “Ginza Kimono Tiroir” in Ginza, Tokyo, and has developed a new customer acquisition strategy leveraging social media (YouTube, Instagram, etc.).
- The acquisition involves 300 shares, representing 100.0% of outstanding shares, for a total of 71 million JPY (59 million JPY for common stock and an estimated 12 million JPY for related costs).
- The share transfer agreement was signed on September 17, 2026, with the transfer date scheduled for October 1, 2026.
- For the fiscal year ended February 2026, Japan Heart Co. reported sales of 177 million JPY and an operating profit of 27 million JPY.
🤖 AI Perspective
This acquisition appears to align with Yamano HD’s “Business Succession M&A” strategy outlined in its “Tsunageru 2027” mid-term management plan, aimed at strengthening its traditional Japanese clothing and jewelry business. Japan Heart’s expertise in new customer acquisition through SNS could be a key growth driver for Yamano HD in the maturing kimono market. The subsidiary’s capacity to handle inbound demand may also suggest additional avenues for revenue expansion, which investors may find worth monitoring.
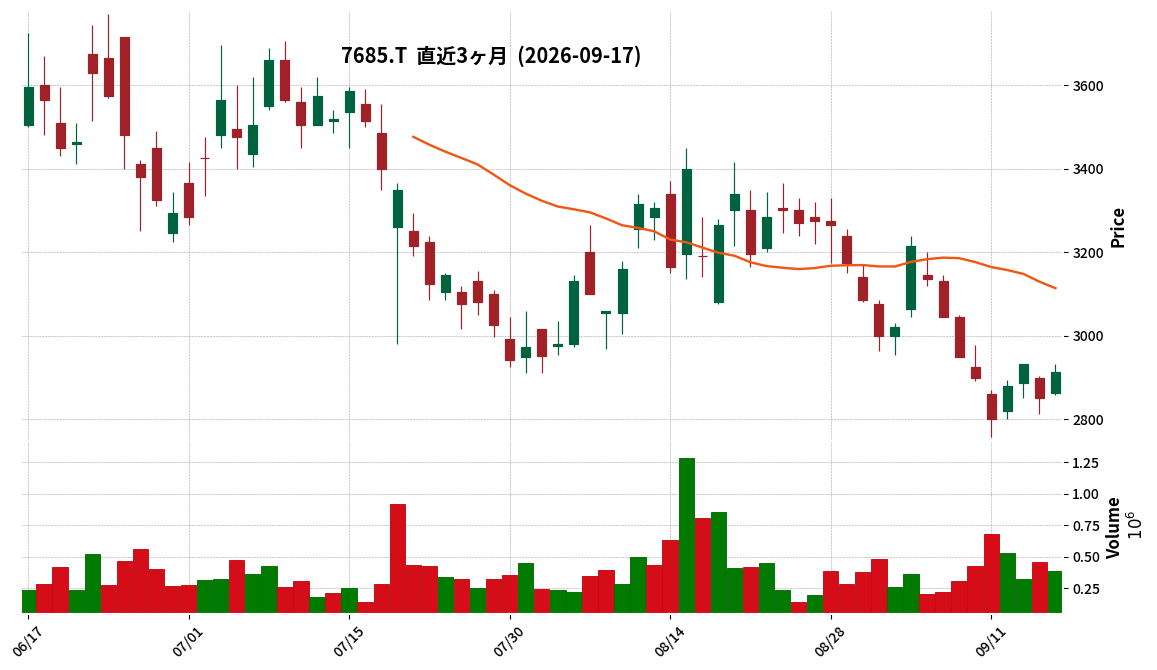
7685|G-BUYSELL
2914.0
▲ +2.25%
📎 Source:G-BUYSELL Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- BuySell Technologies, Inc. resolved at its Board of Directors meeting on September 17, 2026, to acquire all shares of HKS Victory Japan Inc., making it a wholly owned subsidiary.
- HKS Victory Japan Inc. operates 20 reuse item purchasing stores under the “Kaitori Senmon Tokyo Ichiba” brand, primarily in the Kyushu area (centered in Kagoshima Prefecture) and the Kanto area (as of September 2026).
- The acquisition involves 400 shares at a total cost of 525 million yen, comprising 500 million yen for the common shares of HKS Victory Japan Inc. and approximately 25 million yen for advisory fees.
- The scheduled execution date for the share transfer is October 30, 2026.
- Prior to the acquisition, HKS Victory Japan is expected to divest its real estate leasing business, which is separate from its core reuse business.
🤖 AI Perspective
This acquisition of HKS Victory Japan can be seen as part of G-BUYSELL’s dominant strategy to strengthen its store-based acquisition business in regional areas. HKS’s strong brand recognition, customer base, and prime locations, particularly in Kagoshima, could significantly enhance G-BUYSELL Group’s purchasing channels. For a company focused on inorganic growth through M&A, the potential for synergies and expansion of business scale will be a key point to monitor.
8104|クワザワHD
714.0
▲ +0.00%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Kuwazawa Holdings announced on September 17, 2026, partial revisions to its shareholder benefit program, including expansion and the addition of a continuous holding requirement.
- Under the revised program, shareholder benefits (QUO Card gifts) will be eligible only for shareholders who have continuously held shares for at least one year. A transitional measure will be applied for the initial implementation.
- A new shareholding category for “3,000 shares or more” has been established, offering a QUO Card worth 4,000 yen for holdings of 1 year to less than 3 years, and 5,000 yen for holdings of 3 years or more.
- Benefits for long-term shareholders holding for 3 years or more have been expanded; for instance, shareholders holding 100 shares or more will receive 2,000 yen, up from the previous 1,000 yen.
- These changes will be applied starting from shareholders listed or recorded in the shareholder registry as of March 31, 2027.
🤖 AI Perspective
The announced changes to the shareholder benefit program, including the introduction of a continuous holding requirement and expanded benefits, appear to be aimed at encouraging long-term share ownership. The enhanced rewards for shareholders holding for three years or more, along with the creation of a new 3,000-share category, could indicate a strategy to foster a stable shareholder base. The transitional measure for initial application may suggest a consideration for existing shareholders.
2989|R-東海道リート
95500.0
▼ -0.10%
📎 Source:R-東海道リート Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- R-Tokaido Reit announced its financial results for the 2026 July fiscal period (February 1, 2026 – July 31, 2026).
- Operating revenue was ¥2,731 million, marking a 17.9% increase compared to the previous period.
- Operating income reached ¥1,526 million (up 17.2% from previous period), ordinary income ¥1,123 million (up 6.5%), and net income ¥1,122 million (up 6.5%).
- Distribution per unit (including excess distribution) was ¥3,230, with a total distribution amount (including excess distribution) of ¥1,246 million.
- Total assets amounted to ¥82,037 million (up 20.8% from the end of the previous period), and net assets were ¥40,616 million (up 22.4%), with an equity ratio of 49.5%.
- For the 2027 January fiscal period, the forecast for operating revenue is ¥2,900 million (up 6.2% from the previous period), and distribution per unit (excluding excess distribution) is ¥3,027.
🤖 AI Perspective
R-Tokaido Reit’s FY2026 July results show an increase in operating revenue and all profit metrics, which may suggest an improvement in its operational performance. The significant increase in total assets could indicate portfolio expansion or asset value appreciation. The distribution per unit, including excess distribution, of ¥3,230, suggests continued returns to unitholders.
3498|霞ヶ関キャピタル
7200.0
▲ +0.98%
📎 Source:霞ヶ関キャピタル Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- KASUMIGASEKI CAPITAL resolved to revise its consolidated earnings forecast upward for the fiscal year ending August 2026, as announced on September 17, 2026.
- Revenue is now projected at ¥163,700 million, an increase of 9.1% from the previous forecast of ¥150,000 million.
- Operating income is revised to ¥27,600 million, up 4.2% from the previous forecast of ¥26,500 million.
- Ordinary income is revised to ¥25,700 million, an increase of 7.1% from the previous forecast of ¥24,000 million.
- Net income attributable to owners of parent is revised to ¥16,600 million, a 0.6% increase from the previous forecast of ¥16,500 million.
- The primary reason for the revision is stated as favorable progress in development projects, mainly in the hotel business, including expanded project revenue and earlier sales.
🤖 AI Perspective
The upward revision of the earnings forecast, primarily driven by strong performance in the hotel business, suggests robust progress in development projects. While the increase in revenue and profits may indicate business expansion, the relatively lower growth rate of net income attributable to owners of parent compared to other profit metrics could be a point of interest for investors. This update provides specific financial adjustments based on recent business trends.
3993|PKSHA
3180.0
▲ +1.60%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- PKSHA Technology Co., Ltd. has resolved to merge with its two consolidated subsidiaries, PKSHA Associates Co., Ltd. and PKSHA Infinity Co., Ltd., through an absorption-type merger.
- The effective date is scheduled for January 1, 2027, with PKSHA Technology as the surviving company and PKSHA Associates and PKSHA Infinity dissolving.
- The merger aims to maximize management resources, improve management efficiency, and accelerate decision-making processes.
- No new shares will be issued or cash delivered for PKSHA Associates, as it is a wholly-owned subsidiary. For PKSHA Infinity, 100.83 shares of PKSHA Technology stock will be delivered for each share of PKSHA Infinity stock to minority shareholders, utilizing treasury stock.
- The valuation of PKSHA Infinity’s shares was conducted by an independent third-party valuation institution, Plutus Consulting Co., Ltd., using the Discounted Cash Flow (DCF) method.
🤖 AI Perspective
This merger appears to be a strategic move to streamline operations and enhance decision-making speed within the PKSHA Group. The issuance of parent company shares to minority shareholders of PKSHA Infinity suggests a deeper integration of business operations across the group. Investors may wish to monitor how this consolidation impacts the future growth and profitability of the combined AI SaaS business.
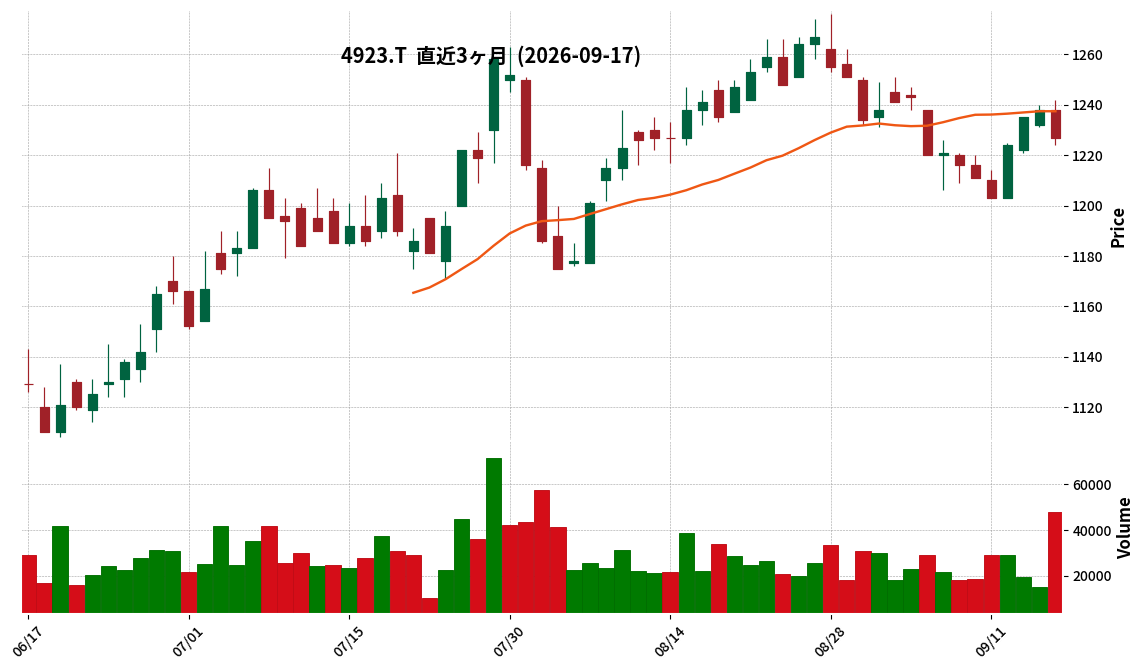
4923|COTA
1227.0
▼ -0.89%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- For Q1 FY2027, COTA reported net sales of ¥1,664 million, marking a 4.2% increase year-over-year.
- Operating income reached ¥9 million, a turnaround from an operating loss of ¥(49) million in the same period last year.
- Ordinary income was ¥61 million (vs. ¥(37) million loss YoY), and quarterly net income was ¥37 million (vs. ¥(33) million loss YoY).
- Quarterly net income per share was ¥1.28, up from ¥(1.16) in the prior year’s comparable quarter.
- As of the end of the quarter, total assets stood at ¥14,253 million, net assets at ¥11,556 million, and the equity ratio was 81.1%.
- The company implemented a 1.05-for-1 stock split of its common shares on April 1, 2026.
🤖 AI Perspective
COTA’s Q1 FY2027 results highlight an increase in net sales and a return to profitability across key income metrics. The positive shift in operating, ordinary, and net income from losses in the prior year’s first quarter could suggest an improvement in the company’s financial performance. Investors may wish to monitor how these trends develop in subsequent quarters, especially given the company’s statement that Q1 results typically have a small impact on full-year performance.
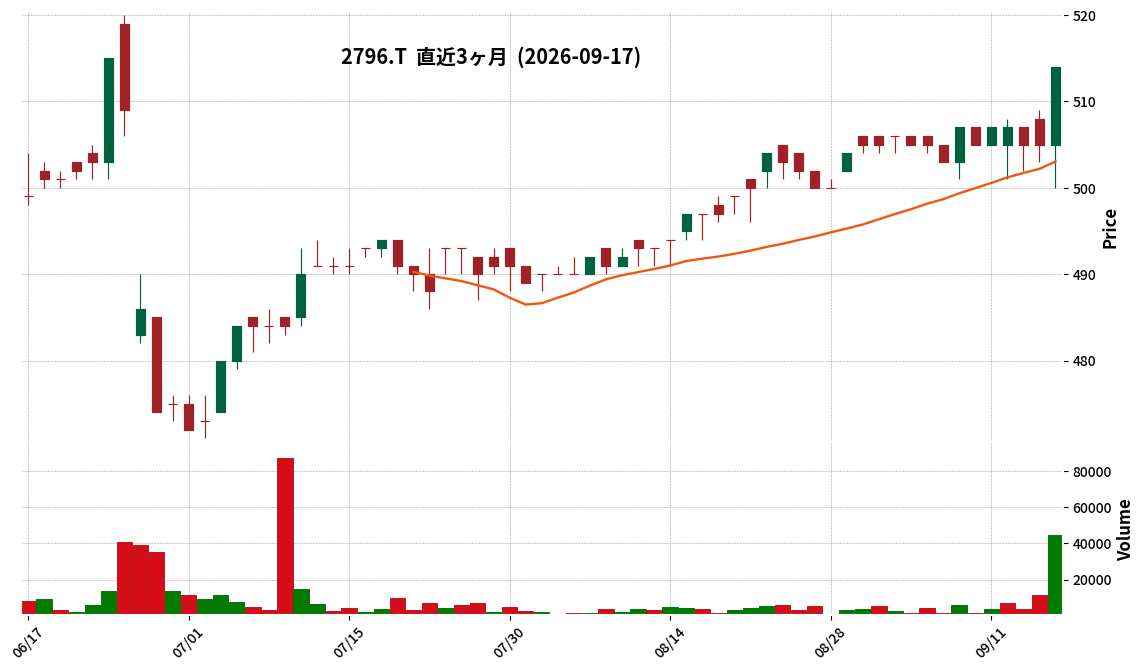
2796|ファーマライズHD
514.0
▲ +1.78%
📎 Source:ファーマライズHD Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Pharmarise Holdings announced its consolidated financial results for the first quarter of the fiscal year ending May 2027 (June 1, 2026, to August 31, 2026).
- Consolidated net sales totaled ¥17,242 million, representing a 2.9% increase compared to the same period of the previous fiscal year.
- Consolidated operating income was ¥68 million, a 54.8% decrease year-on-year.
- Net loss attributable to owners of parent was ¥36 million, compared to a loss of ¥18 million in the prior year’s first quarter.
- The full-year consolidated earnings forecast remains unchanged, projecting net sales of ¥70,604 million (up 1.6% YoY), operating income of ¥1,014 million (up 3.5% YoY), and net income attributable to owners of parent of ¥11 million (down 90.0% YoY).
🤖 AI Perspective
While Q1 sales increased, profit margins appear to have been impacted by revisions to pharmacy dispensing fees and drug prices, alongside rising cost of goods sold. The unchanged full-year forecast suggests the company anticipates improvements in subsequent quarters, making the progress of its M&A integration and profitability enhancement initiatives, particularly in the pharmacy business, key areas to monitor.
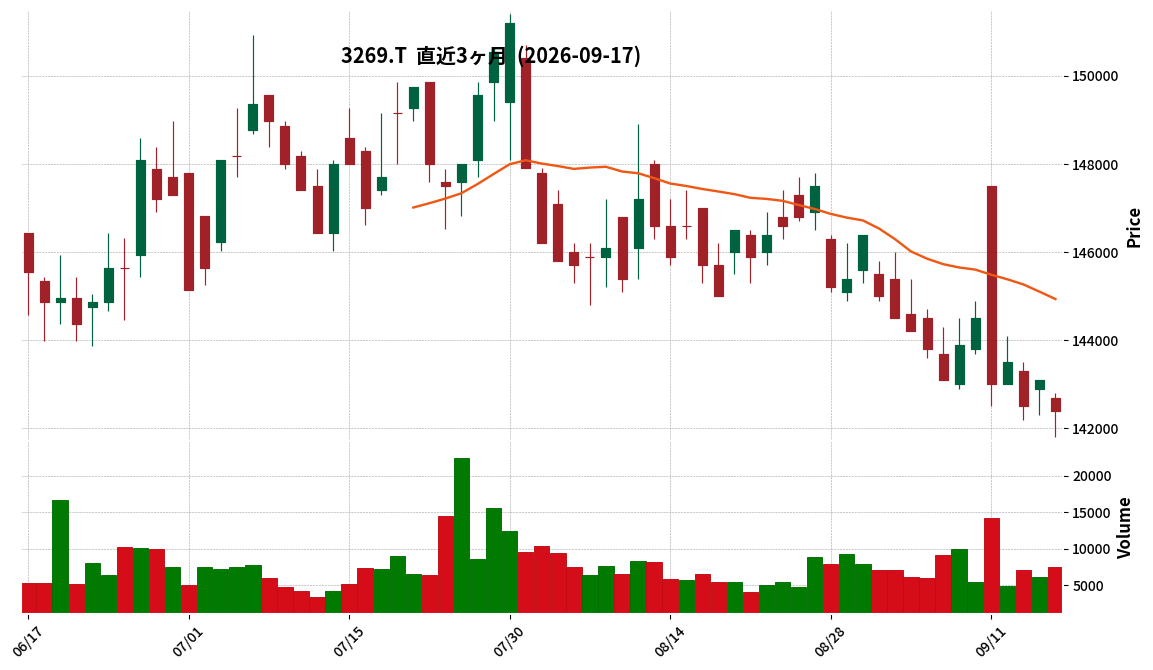
3269|R-ADR
142400.0
▼ -0.49%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- R-ADR announced its financial results for the 2026 July period (February 1, 2026, to July 31, 2026).
- For the current period, operating revenue was ¥20,560 million (down 0.5% from the previous period), operating income was ¥9,892 million (down 3.5%), ordinary income was ¥8,715 million (down 5.5%), and net income was ¥8,714 million (down 5.5%).
- Net income per unit was ¥3,055, and distribution per unit (excluding excess distribution) was ¥3,225.
- Forecasts for the 2027 January period and 2027 July period operations were also disclosed, anticipating a period-on-period decrease in operating revenue, operating income, ordinary income, and net income for both periods.
- During the period, four properties, including Residia Shoin-Jinja-Mae, were acquired for a total of ¥6.9 billion, and two properties, including Residia Bunkyo-Yushima II, were transferred for a total of ¥2.5 billion.
🤖 AI Perspective
R-ADR’s financial results for the 2026 July period show a decrease in key revenue and profit metrics compared to the previous period. Notably, the distribution per unit exceeded that of the prior period, with the report indicating that a portion of the distribution was sourced from the temporary difference adjustment reserve. The outlook for subsequent periods also projects a decline in revenue and profit, suggesting that future rental trends and external growth strategies may be key areas for investors to monitor.
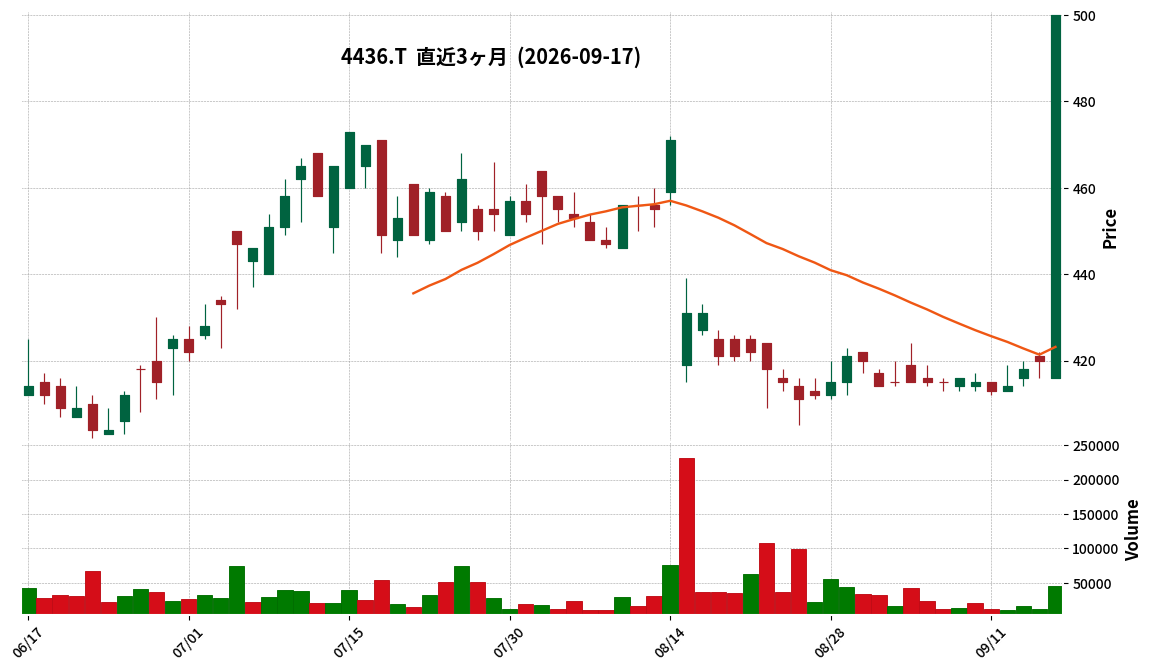
4436|G-ミンカブ
500.0
▲ +19.05%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Minkabu The Infonoid Co., Ltd. (the “Company”) resolved to transfer all shares of its wholly-owned subsidiary, Livedoor Co., Ltd., to the SBI Group, whose parent company is SBI Holdings, Inc.
- The Company entered into a capital and business alliance agreement with NTT Data Corporation and a three-party business alliance agreement with NTT Data and SBI Holdings.
- Upon completion of these transactions, NTT Data is expected to become the Company’s largest shareholder with 16.41% of voting rights, and SBI is expected to become the second largest shareholder with 8.04%.
- The Company plans to repay all group borrowings using funds from the Livedoor share transfer, focusing management resources on its financial solutions business.
- The three companies plan to jointly plan, develop, and verify financial services and advanced business solutions, develop new services utilizing financial data and media, and explore next-generation financial services and infrastructure.
🤖 AI Perspective
This announcement suggests a strategic shift for G-Minkabu, as it divests non-financial assets like Livedoor and brings in NTT Data and SBI Group as major shareholders to concentrate on and strengthen its financial solutions business. The collaboration leveraging NTT Data’s and SBI Group’s customer bases, technology, and financial expertise, combined with G-Minkabu’s financial data, content, and AI/DX solutions, could lead to significant synergies in creating new financial services. Furthermore, the full repayment of borrowings from the Livedoor share transfer is expected to improve the company’s financial health.
5973|トーアミ
609.0
▼ -0.98%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Toami Co., Ltd. resolved to acquire 99% of the issued shares of Techno Co., Ltd. on September 17, 2026, making it a subsidiary.
- Toami’s subsidiary, Watabe Construction Co., Ltd., will acquire the remaining 1% of shares, resulting in 100% ownership of Techno’s issued shares by the Toami Group.
- Techno is a company based in Iruma City, Saitama Prefecture, engaged in construction and civil engineering work and materials sales, and has an existing, continuous business relationship with Toami as one of its key suppliers.
- The acquisition price for Toami’s 99% stake is JPY 940,500,000, and for Watabe Construction’s 1% stake is JPY 9,500,000.
- The closing date for the share transfer is scheduled for October 1, 2026.
🤖 AI Perspective
This acquisition of Techno is likely intended to strengthen the Toami Group’s construction capabilities, expand its business foundation in materials sales and construction contracting, and generate new revenue opportunities. Bringing an existing business partner into the group could suggest expectations of supply chain reinforcement and synergistic effects. Techno’s financials show sales in the JPY 700 million range and net income around JPY 50 million over the past three fiscal years, and its future contribution to the Toami Group will be worth monitoring.
3560|ほぼ日
4520.0
▲ +4.27%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Hobonichi Co., Ltd. announced its transition from non-consolidated to consolidated financial statements starting from the fiscal year ending August 2026.
- This transition is a result of Hobonichi Inc. becoming a specified subsidiary through a capital increase, as announced on June 26, 2026.
- The full-year consolidated earnings forecast for the fiscal year ending August 2026 has been released, projecting net sales of JPY 10,726 million, operating income of JPY 1,114 million, ordinary income of JPY 1,137 million, profit attributable to owners of parent of JPY 740 million, and EPS of JPY 318.72.
- This consolidated earnings forecast is based on the conventional non-consolidated earnings forecast announced today (September 17, 2026).
- For reference, the non-consolidated earnings forecast for the fiscal year ending August 2026 was net sales of JPY 10,597 million, operating income of JPY 1,066 million, ordinary income of JPY 1,089 million, net income of JPY 709 million, and EPS of JPY 305.37.
🤖 AI Perspective
Hobonichi’s move to consolidated financial statements and the release of its inaugural consolidated earnings forecast provide investors with a more comprehensive view of the group’s overall business scale and profitability, including its subsidiaries. The consolidated forecast, which projects higher sales and profits compared to the previous non-consolidated forecast, could indicate expectations for business expansion and revenue contribution across the entire group. Investors may find it worthwhile to monitor future disclosures regarding the specific business strategies and contributions of consolidated subsidiaries, including Hobonichi Inc.
💡 Start investing with IR insights


※ 本ページには広告が含まれます(PR)
Disclaimer: This article is for informational purposes only and does not constitute investment advice. All investment decisions are at your own risk.
コメント