
📌 Today’s Highlights
Today we cover 24 IR announcements. Notable among them: P-ハイネス (638A), G-スローガン (9253), G-犬猫生活 (556A). Use the table of contents below to navigate to each company.
638A|P-ハイネス
—
▲ +0.00%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- P-Highness (Code: 638A) was listed on the Tokyo Stock Exchange’s TOKYO PRO Market on October 2, 2026.
- For the fiscal year ending February 2027 (March 1, 2026, to February 28, 2027), the company forecasts consolidated net sales of ¥3,810 million (down 22.5% year-on-year), an operating loss of ¥103 million, an ordinary loss of ¥60 million, and a net loss attributable to owners of the parent of ¥106 million.
- The consolidated results for the fiscal year ended February 2026 showed net sales of ¥4,917 million, operating income of ¥156 million, ordinary income of ¥448 million, and net income attributable to owners of the parent of ¥209 million.
- The forecast for FY2027 is primarily attributed to the absence of new “Churaku-bo” project completions and deliveries, despite proceeding with the handover of remaining units from key properties completed in the previous fiscal year.
- The company plans to concentrate management resources on its core “Churaku-bo” business, focusing on integrated group operations and establishing a business cycle that includes secondary market distribution and management.
🤖 AI Perspective
P-Highness’s listing on the TOKYO PRO Market may enhance its corporate profile and expand financing options. However, the projected revenue decline and operating loss for the fiscal year ending February 2027 highlight the company’s reliance on the timing of new project completions. Investors may wish to monitor future property development plans and their progress, as well as sales trends for existing properties.
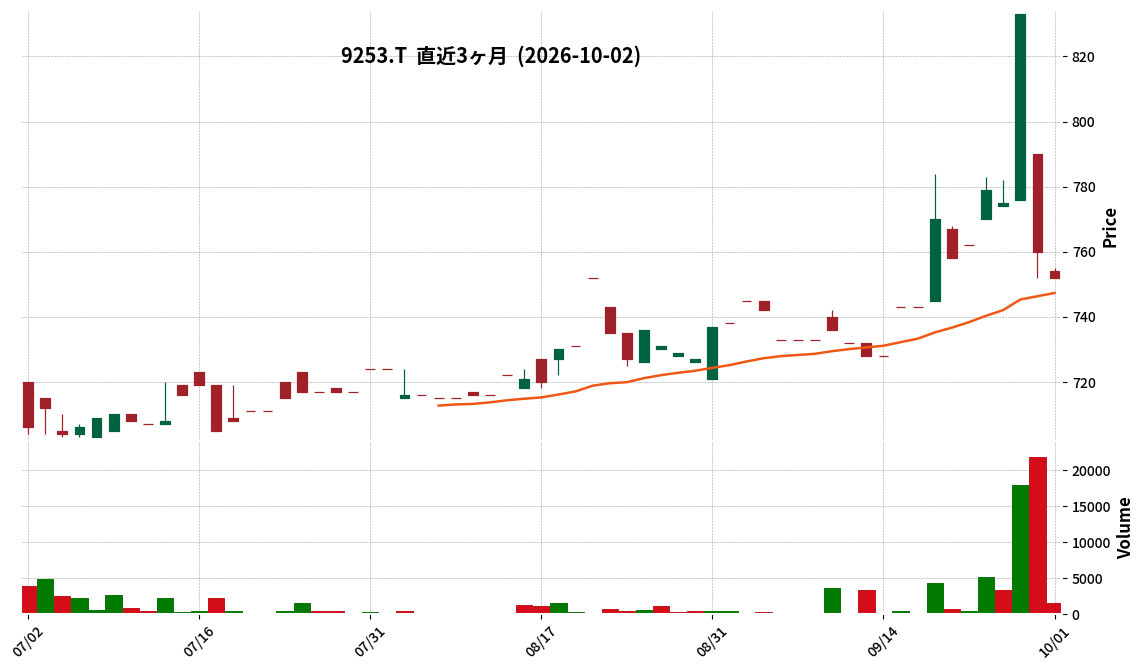
9253|G-スローガン
752.0
▼ -1.05%
📎 Source:G-スローガン Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- G-Slogan reported increased revenue and profit for the first half of the fiscal year ending February 2027 (March 1, 2026 – August 31, 2026), with revenue of ¥988 million (+1.4% YoY) and operating profit of ¥342 million (+3.6% YoY).
- By business segment, student-focused services grew to ¥836 million (+3.1% YoY), achieving a 62.1% progress rate towards the full-year plan. Services for professionals recorded ¥65 million (-8.2% YoY), and the media/SaaS sector ¥86 million (-5.8% YoY).
- The first-half revenue progress rate was 61.0% against the full-year forecast. The full-year earnings forecast (revenue ¥1,620 million, operating profit ¥302 million) remains unchanged.
- The company absorbed the revenue impact from terminating unprofitable services (“Goodfind Career,” partial consulting services for “TeamUp,” and “Metanobi”) through the robust performance of its core “Goodfind” business and improved productivity.
- Progress in “Circulation Management” led to an average operating profit per person (LTM) of ¥2.91 million (approx. 2.4 times the FY2025 full-year figure of ¥1.23 million) and an operating profit margin (LTM) of 18.2%.
- Regarding shareholder returns and capital policy, the company plans to report on the progress of discussions at the Q3 earnings release in December 2026, aiming to disclose its vision and financial targets around the full-year earnings in April-May 2027.
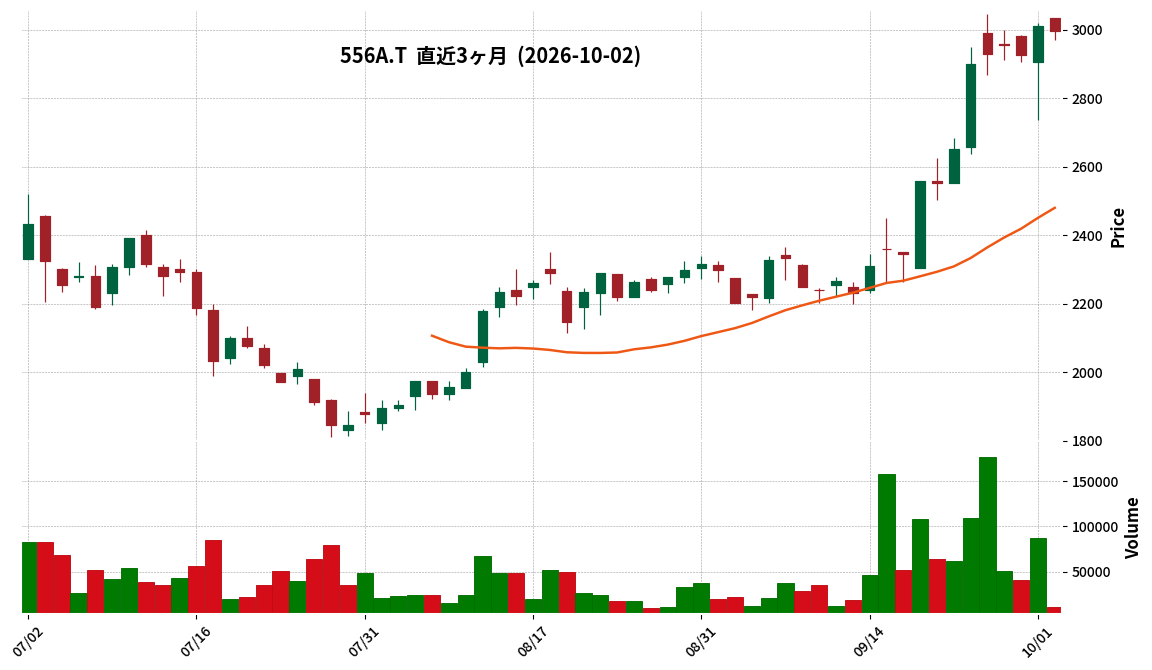
556A|G-犬猫生活
2997.0
▼ -0.43%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Trimming salon sales for Q1 FY2027 decreased by 38.4% year-on-year, primarily due to the closure of one unprofitable store, while a new “HANARE Shibuya store” opened in July of the same year.
- Sales growth in the animal hospital business is planned to be achieved mainly through expanding the number of hospitals via M&A, with a contract signed with Moriya Forest Animal Hospital in September 2026.
- For the retail wholesale business, the company prioritizes building a “sales-generating mechanism” by accumulating sales performance at existing wholesale partners (197 stores as of Q1 end) before accelerating expansion to major chains.
- In overseas expansion, test sales began in Taiwan in May 2025, with full-scale deployment initiated in Q1 FY2027, and plans to expand across Asia thereafter.
- Towards the goal of forming a group of over 50 animal hospitals nationwide, negotiations are underway with multiple hospitals, with approximately JPY 1.7 billion in cash on hand and potential debt financing expected to cover the costs.
🤖 AI Perspective
G-Inuneko Seikatsu’s Q1 FY2027 Q&A highlights a clear strategic focus on profitability-driven restructuring in its trimming salon business and growth through M&A in its animal hospital segment. The animal hospital M&A strategy, projected to be funded by existing cash and potential debt financing, appears to be a practical approach. Furthermore, the phased expansion in retail wholesale and the reported strong LTV in Taiwan’s overseas operations suggest a methodical approach to building sustainable growth across its diverse business portfolio.
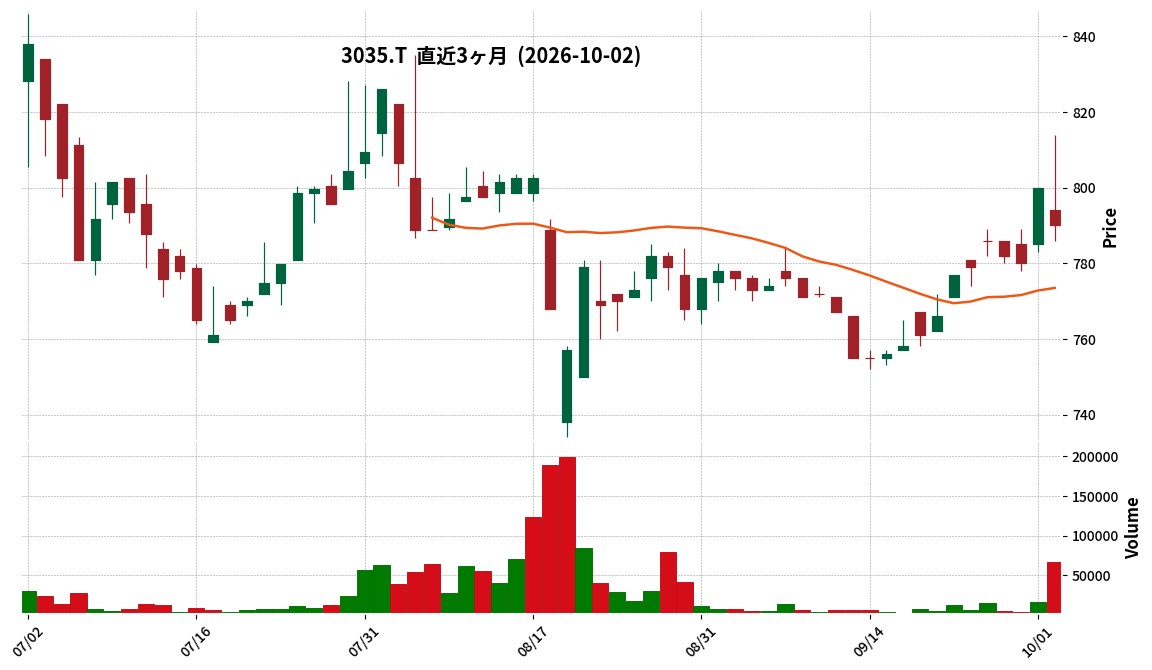
3035|KTK
790.0
▼ -1.25%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- KTK’s consolidated results for the fiscal year ended August 2026 show net sales of ¥20,192 million (+6.7% YoY), operating profit of ¥557 million (+30.8% YoY), ordinary profit of ¥648 million (+25.9% YoY), and profit attributable to owners of parent of ¥489 million (+47.4% YoY).
- All profit items reached record highs for the company.
- By segment, the Supply business recorded net sales of ¥15,372 million (+5.6% YoY) and segment profit of ¥954 million (+14.7% YoY).
- The IT Solution business reported net sales of ¥4,820 million (+10.2% YoY) and segment profit of ¥220 million (+37.2% YoY).
- For the fiscal year ending August 2027, the consolidated forecast projects net sales of ¥20,400 million (+1.0% YoY), operating profit of ¥610 million (+9.3% YoY), ordinary profit of ¥670 million (+3.3% YoY), and profit attributable to owners of parent of ¥425 million (-13.2% YoY).
🤖 AI Perspective
KTK achieved record-high results across all key profit metrics for the fiscal year ended August 2026, driven by growth in both its Supply and IT Solution segments. The Supply business benefited from new customer acquisition and expanded sales of proprietary products, while the IT Solution business saw strong PC sales and cross-selling/up-selling. While the company forecasts continued revenue growth for the next fiscal year, the projected decrease in profit attributable to owners of parent may warrant closer examination by investors.
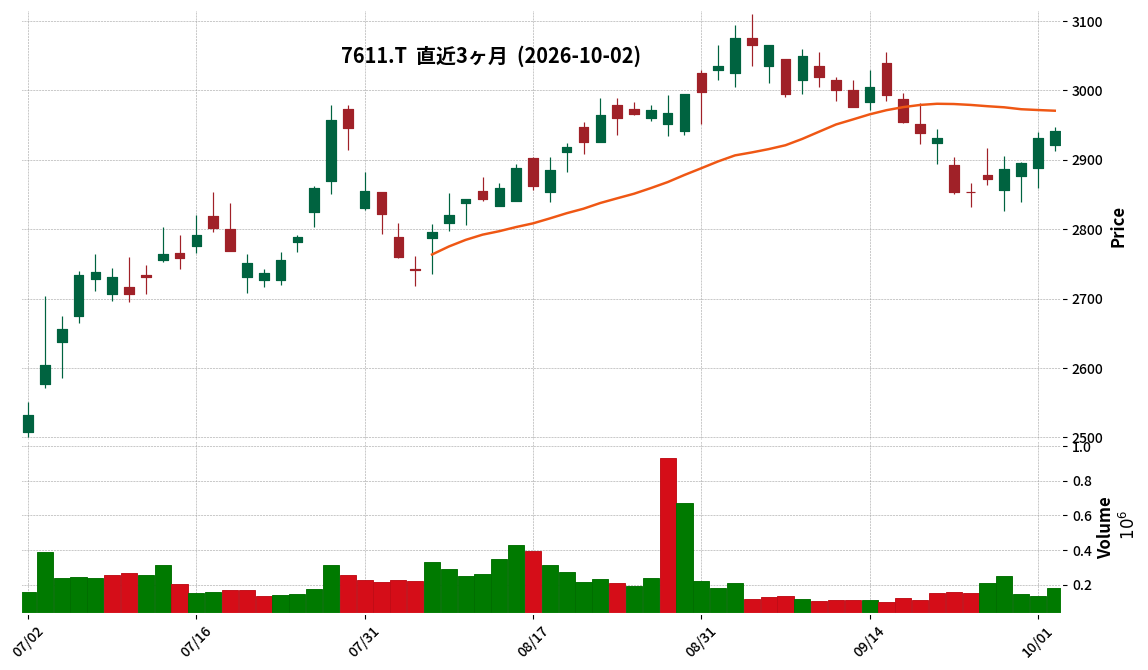
7611|ハイデ日高
2941.0
▲ +0.34%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Hiday Hidaka’s Board of Directors, at its meeting on October 2, 2026, resolved to implement an interim dividend and revise its year-end dividend forecast (an increase).
- The interim dividend for the record date of August 31, 2026, has been set at ¥28 per share (previous forecast ¥26, previous year’s actual ¥23).
- The year-end dividend forecast has been revised to ¥28 per share (previous forecast ¥26).
- This revision results in an expected annual dividend of ¥56 per share, including the interim dividend (previous forecast ¥52, previous year’s actual ¥52).
- The company’s dividend policy emphasizes long-term stable dividends while securing internal reserves for future capital investments such as new store openings and unexpected business risks, aiming to strengthen its financial base.
🤖 AI Perspective
This announcement suggests a proactive stance towards shareholder returns. The upward revision of both interim and year-end dividends, based on current business performance, could be interpreted as a reflection of the company’s confidence in its future operations. The balanced approach of prioritizing both stable dividends and internal reserves may indicate a commitment to enhancing long-term corporate value.
275A|ハンワホームズ
—
▲ +0.00%
📎 Source:ハンワホームズ Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- HANWA HOMES announced its consolidated financial results for the second quarter (interim period) of the fiscal year ending February 2027.
- For the interim period, consolidated sales revenue was ¥1,222 million, operating loss was ¥19 million, ordinary loss was ¥27 million, and net loss attributable to parent company shareholders was ¥17 million.
- The company began preparing quarterly consolidated financial statements from the first quarter of the fiscal year ending February 2027, therefore, comparative figures for the prior interim period (FY2026/2) and year-on-year percentage changes are not provided.
- During this interim period, Bridge Park Project Group Co., Ltd. and Brain Trust Co., Ltd. were included in the scope of consolidation.
- The full-year consolidated performance forecast for the fiscal year ending February 2027 remains unchanged from the most recently announced forecast, projecting sales revenue of ¥2,592 million, operating profit of ¥79 million, ordinary profit of ¥75 million, and net profit attributable to parent company shareholders of ¥39 million.
🤖 AI Perspective
This earnings announcement is significant as it marks the first report under the new consolidated financial statement system for HANWA HOMES. While the company reported a loss for the interim period, the unchanged full-year consolidated forecast may suggest an expectation for recovery or contribution from consolidated subsidiaries in the latter half of the fiscal year. Investors might consider monitoring how the newly consolidated entities contribute to the group’s overall growth strategy going forward.
3321|ミタチ
1878.0
▼ -2.14%
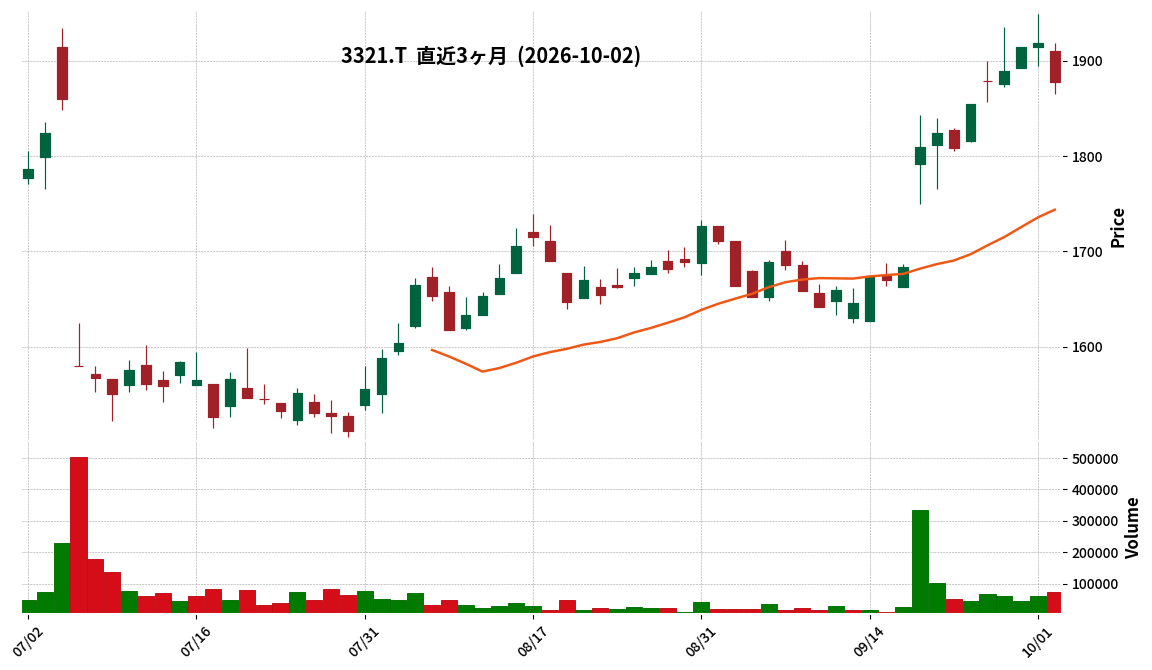
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Mitachi announced its consolidated financial results for the first quarter of the fiscal year ending May 2027 (June 1, 2026, to August 31, 2026).
- Consolidated net sales reached ¥31,591 million (up 13.9% year-on-year), operating profit was ¥682 million (down 3.8% year-on-year), ordinary profit was ¥778 million (up 7.0% year-on-year), and profit attributable to owners of parent was ¥516 million (down 8.2% year-on-year).
- Domestic segment sales totaled ¥26,320 million (up 13.7% year-on-year), with a segment profit of ¥561 million (down 6.9% year-on-year).
- Overseas segment sales reached ¥5,271 million (up 15.0% year-on-year), with a segment profit of ¥272 million (up 4.4% year-on-year).
- The consolidated earnings forecast for the fiscal year ending May 2027 and the annual dividend forecast (¥35.00 for year-end, total ¥70.00) remain unchanged from the announcement made on September 16, 2026.
🤖 AI Perspective
While Mitachi achieved overall sales growth in the first quarter, the decline in operating profit and profit attributable to owners of parent warrants attention. This might suggest shifts in cost of sales or selling, general and administrative expenses, or other factors such as currency fluctuations impacting profit margins. Conversely, the robust growth in both sales and profit within the overseas segment could indicate the positive effects of the company’s global expansion strategies.
4394|G-エクスモーション
798.0
▼ -3.51%
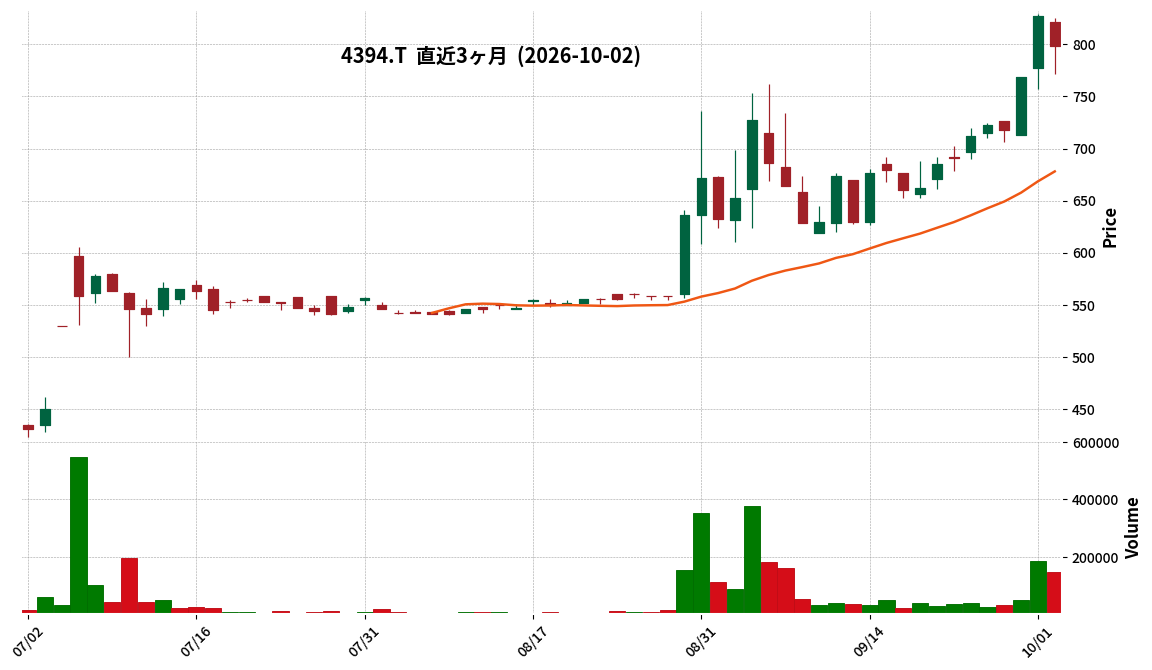
📎 Source:G-エクスモーション Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- G-eXmotion announced its supplementary financial materials for the third quarter of the fiscal year ending November 2026 on October 2, 2026.
- For the cumulative third quarter, revenue reached 1,062 million JPY (up 3.4% year-on-year), and operating profit was 155 million JPY (up 17.2% year-on-year), both marking new historical highs.
- Sales from AI-related companies surged by 105.8% year-on-year, with expanded support in Software-Defined Vehicle (SDV)/autonomous driving (including physical AI) and semiconductor manufacturing equipment sectors.
- The core consulting business remained strong, with a shift towards AI utilization projects that offer high productivity.
- While cumulative orders for the AI service “CoBrain” and the educational service “Eureka Box” have increased, they fell short of targets, prompting the implementation of measures to boost lead acquisition and negotiation volume, such as utilizing sales agencies and increasing investment in exhibitions.
🤖 AI Perspective
G-eXmotion’s Q3 results highlight robust growth in revenue and operating profit, driven significantly by the AI-related sector. This performance may indicate the company’s success in providing advanced AI technology support that balances “high quality” with “high productivity” to pioneering enterprises. However, the underperformance of its recurring revenue streams, particularly AI and educational services, presents a challenge, suggesting that the effectiveness of planned sales expansion strategies will be worth monitoring for sustained growth.
6664|オプトエレクト
238.0
▼ -6.30%
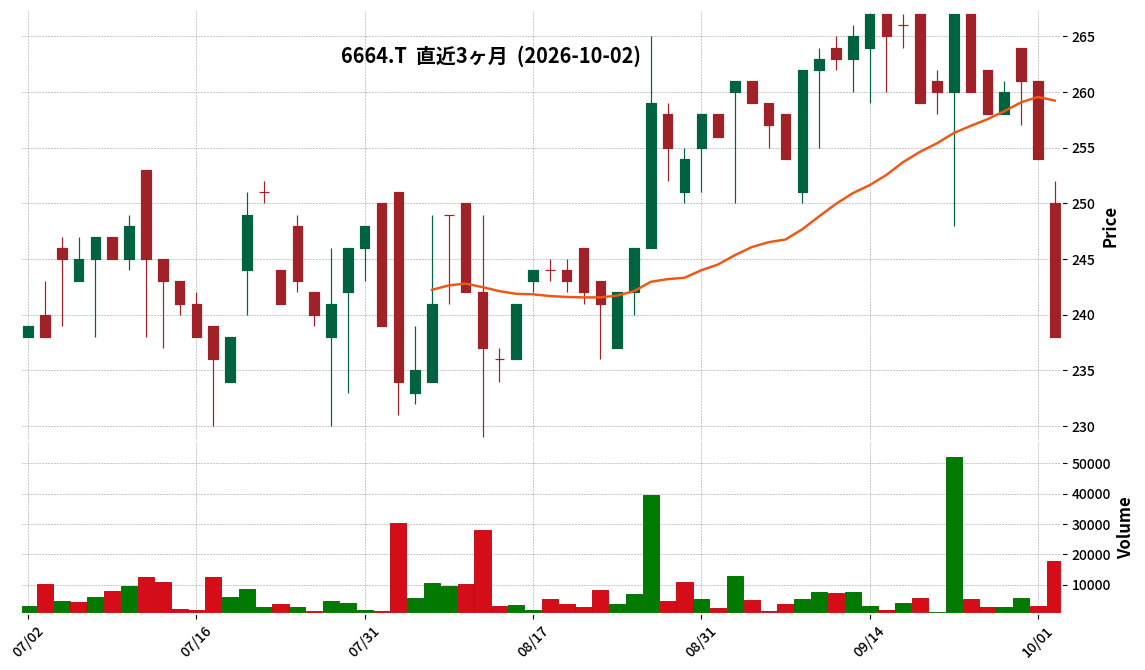
📎 Source:オプトエレクト Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Opto-Electronics reported consolidated net sales of ¥4,843 million for the third quarter of the fiscal year ending November 2026 (December 1, 2025 to August 31, 2026), representing a 0.8% decrease year-on-year.
- Operating loss narrowed to ¥128 million (from ¥158 million in the prior year period), and ordinary loss narrowed to ¥212 million (from ¥285 million).
- Net loss attributable to owners of parent expanded to ¥259 million (from ¥98 million in the prior year period), attributed to factors such as special gains in the previous year and the recording of ¥31 million in stock issuance expenses related to a third-party allotment as non-operating expenses.
- Total assets at the end of the quarter were ¥12,061 million, and net assets were ¥7,682 million, with an equity ratio of 63.7%.
- The company disclosed that it has breached financial covenants for borrowings of ¥471 million from some financial institutions, but stated that its cash and deposits balance of ¥5,173 million is sufficient.
- There is no revision to the consolidated full-year earnings forecast for the fiscal year ending November 2026, which projects net sales of ¥6,507 million and a net loss attributable to owners of parent of ¥681 million.
🤖 AI Perspective
Opto-Electronics’ Q3 results show a continued slight decrease in sales, but a notable narrowing of operating and ordinary losses. The expansion of net loss attributable to owners of parent appears to be influenced by one-off expenses and the absence of special gains seen in the prior year. While the breach of financial covenants is a point of concern, the company’s significant cash and deposit balance may suggest a degree of short-term financial stability, warranting ongoing monitoring of its efforts to resolve the covenant issue and improve profitability.
7384|プロクレアHD
5700.0
▲ +5.56%
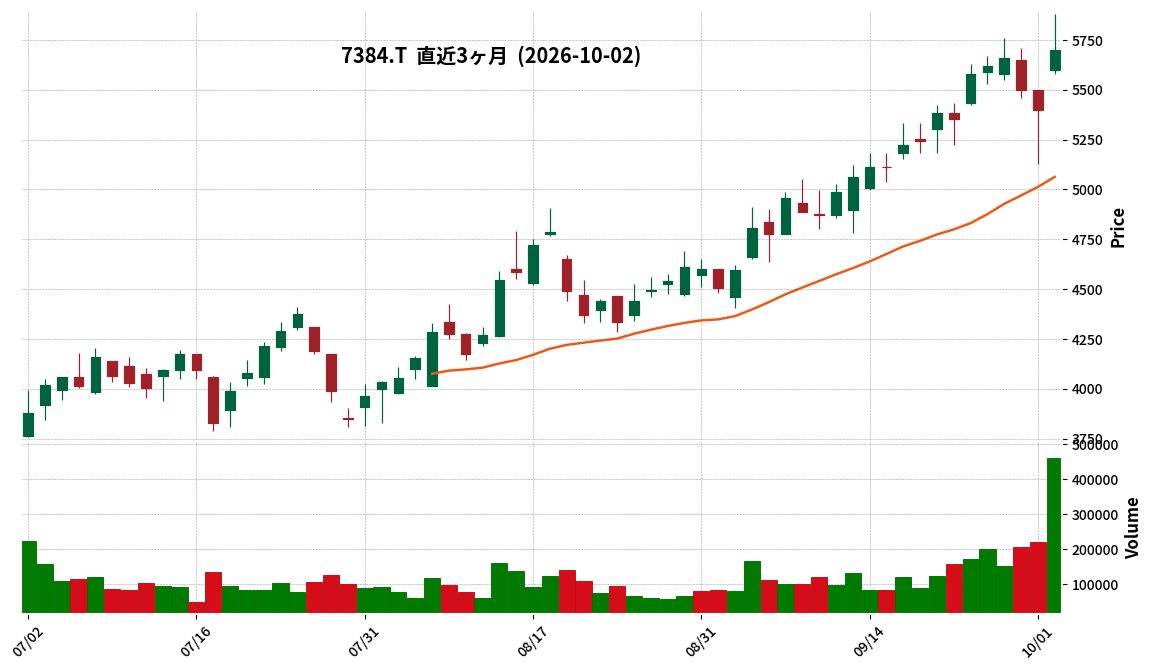
📎 Source:プロクレアHD Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Procrea Holdings, Akita Bank, and Iwate Bank have resolved at their respective board meetings to commence discussions and examinations towards a business integration.
- Procrea HD is a financial holding company that owns Aomori Michinoku Bank.
- The target date for this business integration is April 2028 (scheduled).
- The three companies have a history of collaboration, including the launch of mutual ATM fee waivers (AAI Net) in April 2000 and the establishment of the “Northern Tohoku Three-Bank Joint Business Net (Netbix)” for business matching in 2003.
- This matter is stated to have no impact on the consolidated results of the three companies for the fiscal year ending March 2027.
🤖 AI Perspective
This announcement highlights a significant move by three regional financial institutions in Aomori, Akita, and Iwate prefectures to enhance cooperation amid population decline and evolving business challenges. Building upon existing alliances, the proposed integration aims to strengthen regional production capabilities, improve capital and profitability, and further enhance their management foundations. Investors may closely monitor the future progress of the integration scheme and the realization of synergistic effects.
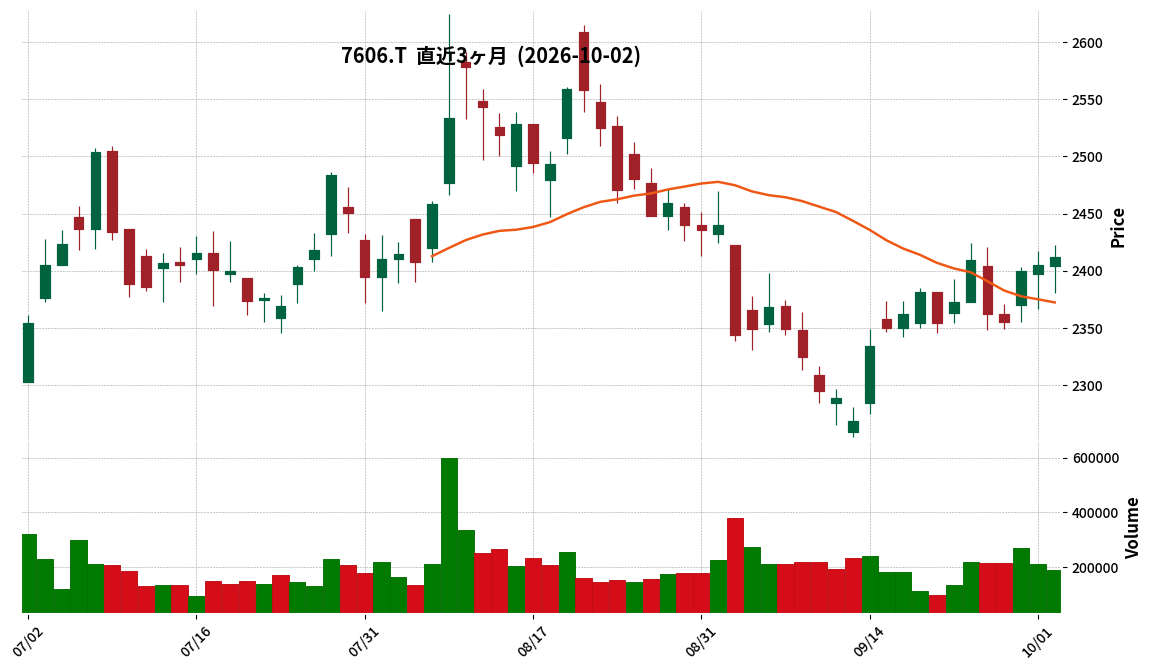
7606|TABAYA HD
2412.0
▲ +0.29%
📎 Source:TABAYA HD Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- TABAYA HD’s preliminary monthly sales for September 2026 show a company-wide increase of 116.4% year-on-year.
- Sales for existing stores (retail + e-commerce combined) increased by 110.5% compared to the previous year.
- Despite adverse weather conditions including approaching typhoons and increased rainy days, the decline in temperature stimulated demand for autumn items, leading to higher sales compared to the same month last year.
- Key performing items included shirts, knitwear, jackets, and outerwear for men, and knitwear, cardigans, jackets, and outerwear for women.
- The company noted that September had one more holiday compared to the previous year, which is estimated to have contributed approximately 1.7 percentage points to the year-on-year sales growth for existing retail + e-commerce stores.
- The preliminary figures do not include the impact of changes in revenue recognition standards, which are expected to reduce the final confirmed figures by a few percentage points. For August 2026, the confirmed figures showed a 1.9pt decrease for total company sales and a 2.5pt decrease for existing retail + e-commerce sales compared to the preliminary figures.
🤖 AI Perspective
TABAYA HD’s September monthly sales indicate a robust performance, with both company-wide and existing store sales exceeding the previous year, primarily driven by strong demand for autumn fashion despite unfavorable weather conditions. The additional holiday in September may have contributed to this positive trend. Investors may want to monitor the difference between preliminary and confirmed figures, as changes in revenue recognition standards are noted to cause downward revisions in final reports.
7870|福島印
—
▲ +0.00%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Fukushima Printing Co., Ltd. announced its non-consolidated financial results for the fiscal year ended August 2026.
- Net sales reached 6,732 million yen, marking an 8.2% decrease compared to the previous fiscal year.
- Operating profit increased by 51.4% to 374 million yen, ordinary profit grew by 63.4% to 403 million yen, and net profit for the period surged by 73.0% to 283 million yen.
- Earnings per share (EPS) stood at 51.97 yen, an increase from 29.00 yen in the prior fiscal year.
- The annual dividend per share was set at 12 yen (including a year-end dividend of 7 yen), a 1 yen increase from 11 yen in the previous year.
- For the fiscal year ending August 2027, the company forecasts net sales of 7,112 million yen (up 5.6% year-on-year), operating profit of 234 million yen (down 37.5%), ordinary profit of 232 million yen (down 42.4%), and net profit of 160 million yen (down 43.5%).
🤖 AI Perspective
Fukushima Printing’s FY2026 results show a notable increase in profits despite a decrease in net sales, which may suggest effective cost management or a shift in business focus. However, the projected decline in profits for FY2027 could indicate potential headwinds or planned investments. Investors may wish to monitor the company’s strategic initiatives and market conditions in the coming year.
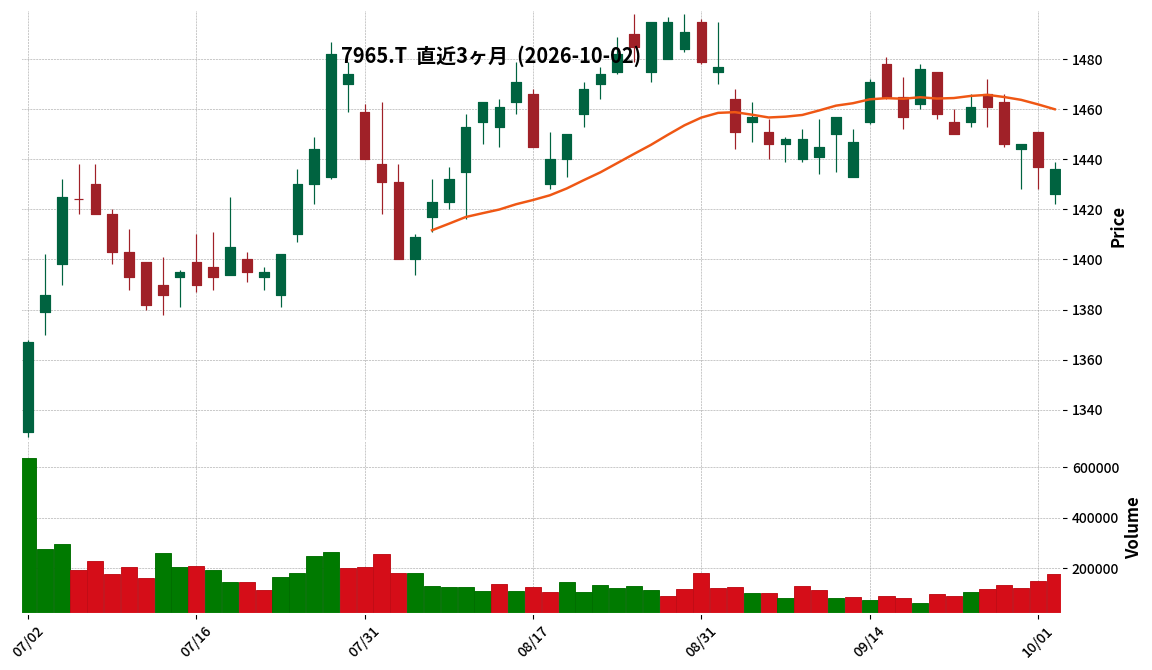
7965|象印マホービン
1436.0
▼ -0.07%
📎 Source:象印マホービン Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Zojirushi Corporation announced its consolidated financial results for the third quarter of the fiscal year ending November 2026 (November 21, 2025, to August 20, 2026).
- Net sales reached ¥69,987 million, a 3.4% increase year-on-year, while operating profit was ¥5,856 million, up 5.3% from the previous year.
- Ordinary profit grew by 3.9% to ¥6,348 million, but profit attributable to owners of parent decreased by 2.9% to ¥4,015 million.
- By product category, cooking appliances sales increased by 2.4% to ¥50,488 million, and living appliances sales grew by 15.9% to ¥4,323 million.
- Living products sales declined by 6.3% to ¥11,925 million, while “Other” sales significantly increased by 67.9% to ¥3,249 million. Overseas sales rose by 3.8% to ¥24,384 million, accounting for 34.8% of total sales.
- The full-year consolidated earnings forecast for FY2026 remains unchanged: net sales of ¥92.5 billion (up 1.5% YoY), operating profit of ¥6.6 billion (down 11.2% YoY), ordinary profit of ¥7.1 billion (down 14.5% YoY), and profit attributable to owners of parent of ¥4.8 billion (down 19.7% YoY).
🤖 AI Perspective
Zojirushi’s Q3 results show growth in net sales and operating profit, driven by strong sales of high-value-added products, successful price pass-throughs due to the weak yen, and expansion in overseas markets. However, the decline in profit attributable to owners of parent suggests other factors may have impacted the bottom line. The performance of cooking and living appliances, along with the significant growth in the “Other” segment from increased restaurant operations and the full-scale launch of Zojirushi Korea, may be key areas for investors to monitor going forward.
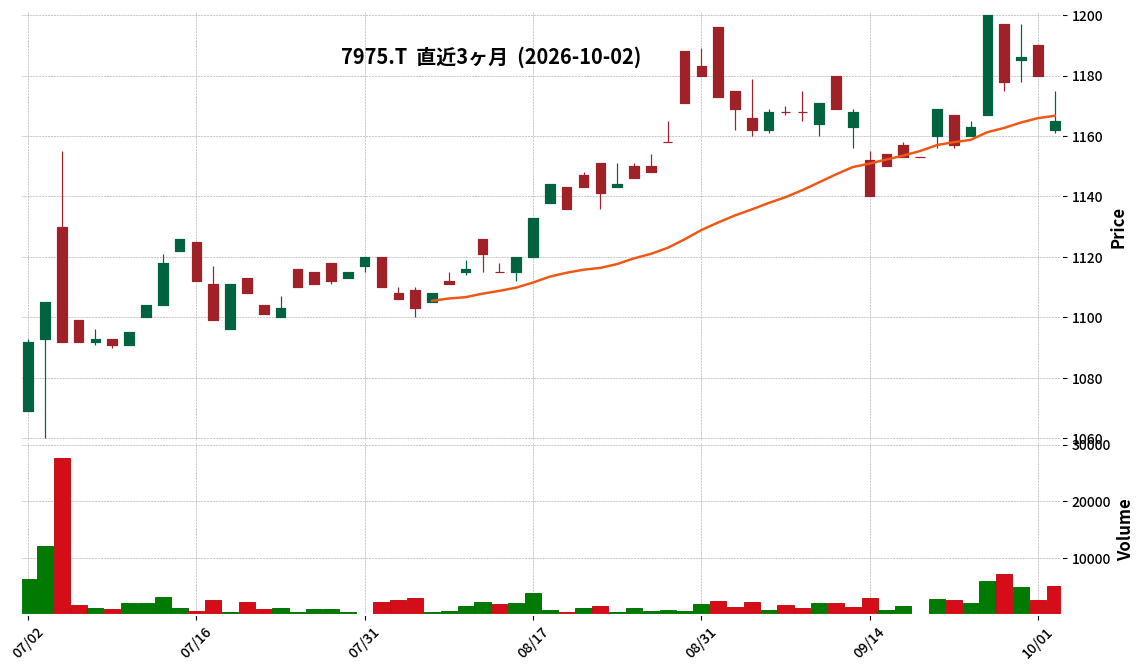
7975|リヒトラブ
1165.0
▼ -1.27%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- LIHIT LAB.’s consolidated financial results for the second quarter of the fiscal year ending February 2027 show net sales of ¥4,846 million, a 0.7% decrease compared to the previous year.
- Operating profit increased by 267.8% year-on-year to ¥23 million, ordinary profit by 40.9% to ¥63 million, and net income attributable to owners of the parent by 7.3% to ¥35 million.
- Sales for the office supplies business segment amounted to ¥4,619 million, a 1.0% decrease from the prior year, with declines in the storage and organization supplies division and other office supplies division.
- The real estate leasing business segment reported sales of ¥227 million, marking a 6.2% increase year-on-year.
- The full-year consolidated earnings forecast remains unchanged from the most recently published figures, projecting net sales of ¥9,350 million, operating profit of ¥80 million, ordinary profit of ¥120 million, and net income attributable to owners of the parent of ¥80 million.
🤖 AI Perspective
While net sales saw a slight decline, the significant improvement in profitability, particularly the 267.8% increase in operating profit, suggests effective cost management and a stable contribution from the real estate leasing business. Investors may consider monitoring the company’s strategies to address challenges within the office supplies segment, such as rising raw material costs, yen depreciation, and underperforming e-commerce sales, which could influence future performance. The unchanged full-year forecast indicates management’s confidence in achieving these targets despite some headwinds.
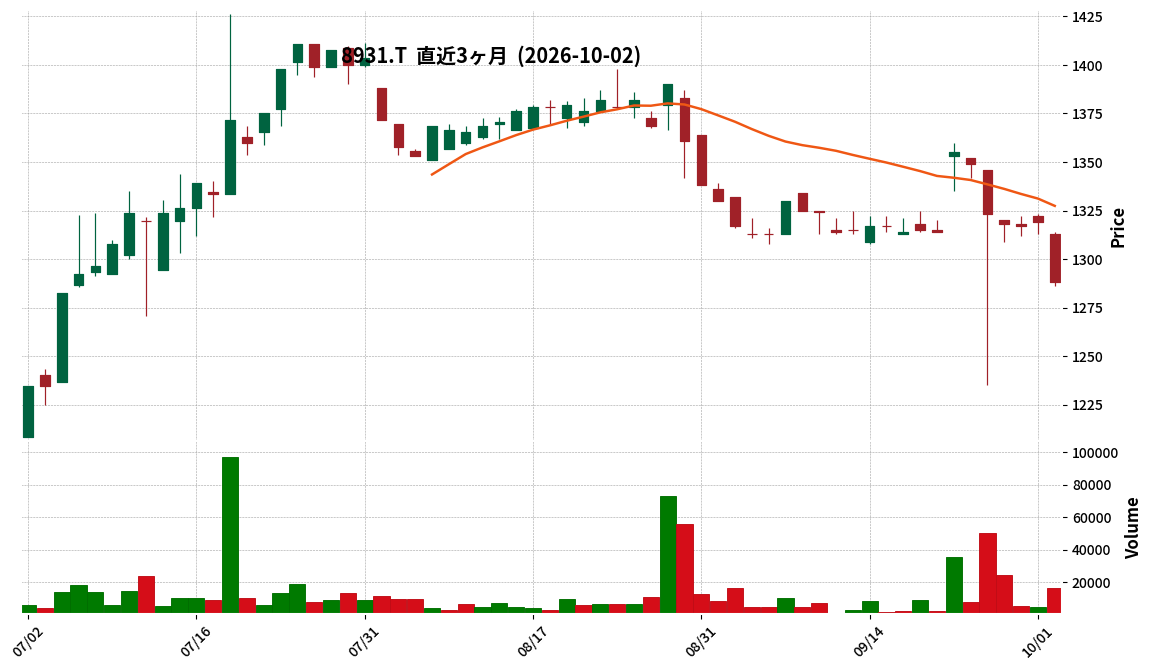
8931|和田興産
1288.0
▼ -2.35%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Wada Kohsan announced its Q2 FY2027 (interim) financial results (non-consolidated).
- Net sales were ¥22,182 million, flat year-on-year (0.0% change).
- Operating profit decreased by 25.7% to ¥2,049 million, ordinary profit by 38.2% to ¥1,425 million, and interim net income by 41.6% to ¥962 million.
- Interim net income per share was ¥87.85.
- The full-year forecast for FY2027 remains unchanged, projecting net sales of ¥46,000 million, operating profit of ¥4,300 million, ordinary profit of ¥3,000 million, and net income of ¥2,100 million.
- The interim dividend is ¥32.00, with a year-end dividend forecast of ¥35.00, totaling an annual dividend forecast of ¥67.00.
🤖 AI Perspective
The flat sales combined with a decline in profits could indicate challenges from elevated construction costs or shifts in the timing of property deliveries. The significant decrease in segment profit from condominium sales appears to be a key factor impacting overall profitability. The maintenance of the full-year forecast suggests management anticipates a recovery in performance during the second half of the fiscal year.
9842|アークランズ
1847.0
▼ -0.97%
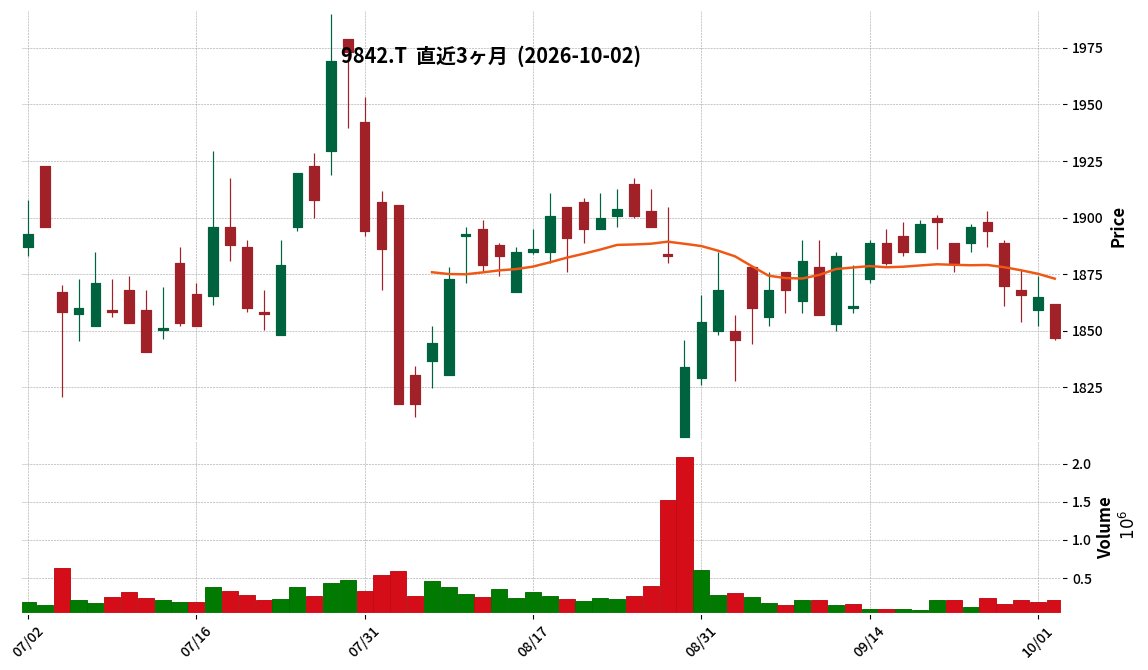
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Arclands Co., Ltd. received and publicly disclosed the investigation report from the Special Investigation Committee on October 2, 2026, concerning alleged improper accounting practices at its consolidated subsidiary, PETSFIRST HOLDINGS Co., Ltd. (PFH).
- The investigation revealed that from April 1 to December 31, 2025, PFH’s former CFO, Mr. A, led the creation of monthly performance reports and quarterly consolidated reporting packages (RP) using figures that differed from those in the accounting system, resulting in misrepresentations in Arclands’ consolidated financial statements.
- For the cumulative period, the figures reported to Arclands overstated operating profit by 857 million yen, ordinary profit by 718 million yen, and net income by 721 million yen, compared to figures based on the accounting system.
- Based on the investigation results, Arclands plans to amend its Q2, Q3, and full-year financial statements for the fiscal year ending February 2026, and submit amended semi-annual, annual, and internal control reports for the fiscal year ending February 2026 on October 13, 2026.
- The delayed Q1 earnings announcement for the fiscal year ending February 2027 will be combined with the Q2 (interim) earnings announcement for the same fiscal year and released on October 13, 2026.
🤖 AI Perspective
The publication of the special investigation committee’s report sheds light on the details and estimated impact of the improper accounting practices. Investors will likely focus on the formulation and implementation of recurrence prevention measures outlined in the report, as well as the final correction amounts to be disclosed. The upcoming announcements on these matters will be crucial in assessing the company’s commitment to transparency and restoring investor confidence.
Disclaimer: This article is for informational purposes only and does not constitute investment advice.
1914|日基礎
798.0
▼ -1.60%
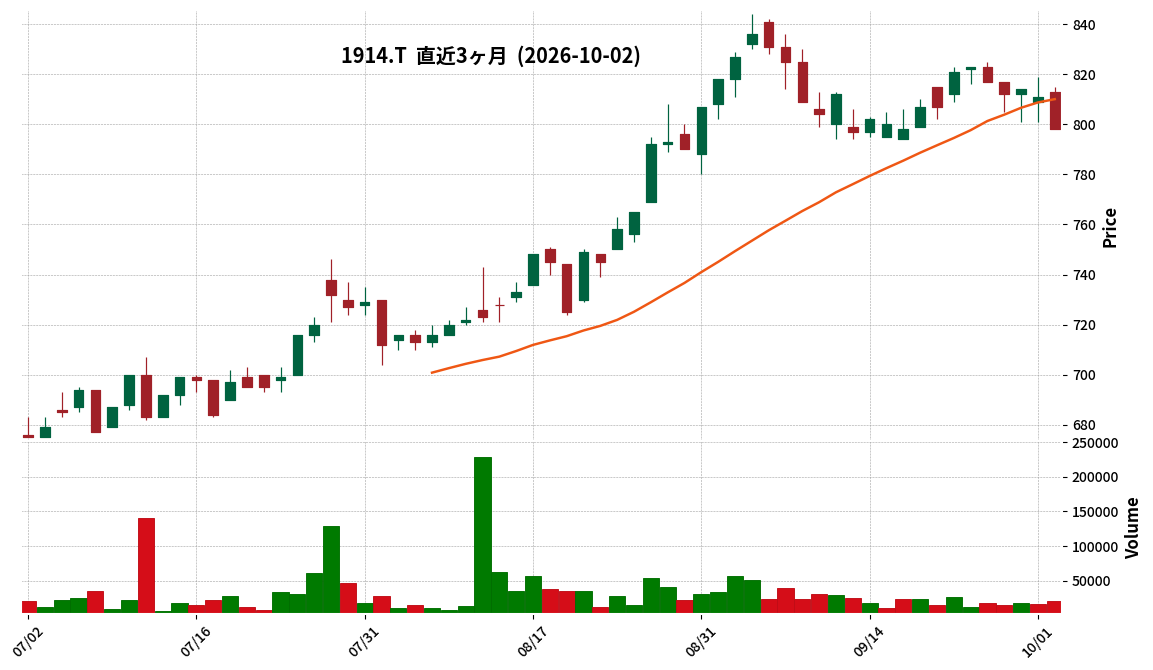
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Nihon Kiso Gijutsu Co., Ltd. entered into a business alliance agreement with JEC Corporation on October 2, 2026.
- The alliance aims to strengthen existing businesses by leveraging the strengths and business foundations of both companies, create new business opportunities through their expertise and infrastructure, collaboratively develop new technologies, and cooperate in overseas business.
- Nihon Kiso possesses drilling and injection technologies and automated construction techniques, while JEC has expertise and networks in heavy temporary construction materials and construction machinery businesses.
- JEC Corporation, headquartered in Bunkyo-ku, Tokyo, primarily engages in the rental and sale of construction temporary materials, design and construction of temporary works, and rental of construction machinery.
- Nihon Kiso has stated that the impact of this business alliance on its financial performance is minor.
🤖 AI Perspective
This business alliance appears to be a strategic move to integrate Nihon Kiso’s foundation engineering and ground improvement technologies with JEC’s heavy temporary construction materials and machinery businesses, leveraging their distinct strengths. The stated areas of cooperation, including strengthening existing businesses, creating new opportunities, joint development of new technologies, and overseas collaboration, suggest a comprehensive approach to synergy. While the immediate impact on financial performance is indicated as minor, investors may wish to monitor the long-term potential for diversification of business portfolios and enhancement of corporate value.
4475|G-HENNGE
1760.0
▼ -1.46%
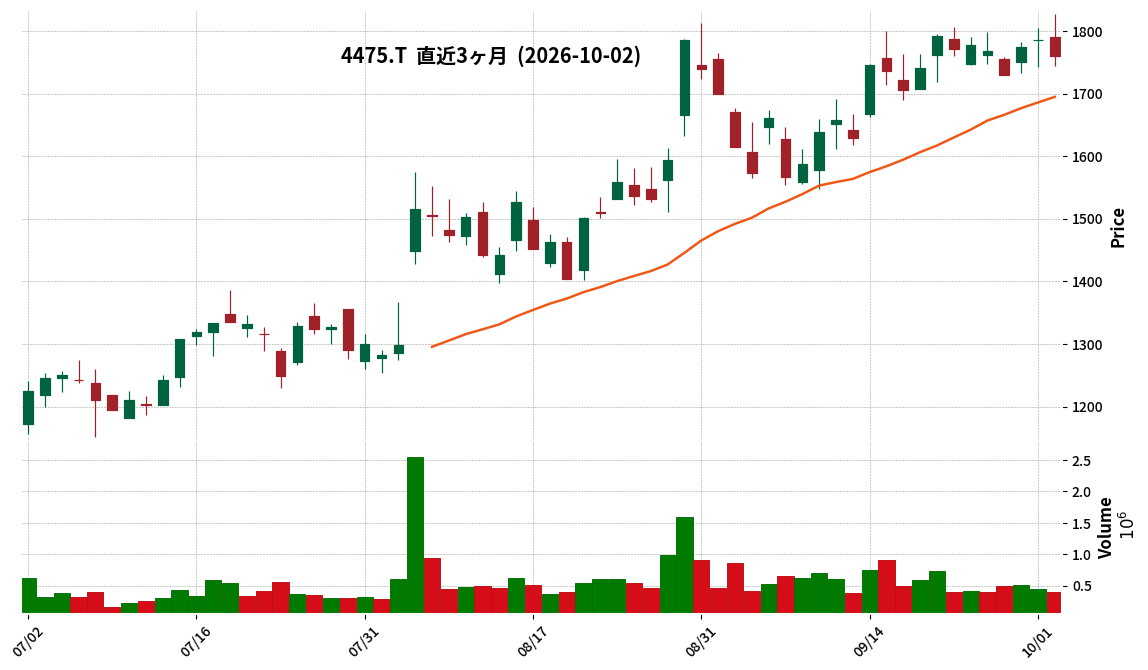
📎 Source:G-HENNGE Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- HENNGE K.K. resolved to revise its year-end dividend forecast per share for the fiscal year ending September 2026 at a Board of Directors meeting held on October 2, 2026.
- The year-end dividend forecast for the fiscal year ending September 2026 has been revised upwards from the previous forecast of JPY 3.00 to JPY 8.00 per share.
- Consequently, combined with the already executed interim dividend of JPY 3.00, the total annual dividend for the fiscal year ending September 2026 is expected to be JPY 11.00 per share.
- The company cited solid business performance and the maintenance of a stable financial foundation as reasons for this revision.
- The company’s dividend policy emphasizes balancing the securing of internal reserves for growth investments with shareholder returns to maximize shareholder profits.
🤖 AI Perspective
This dividend forecast revision may suggest the company’s commitment to returning profits to shareholders, reflecting its robust business performance and financial stability. An increase in dividends based on a progressive dividend policy could indicate a focus on enhancing shareholder value over the medium to long term. For investors, this information serves as a data point for continuous monitoring of the company’s performance and shareholder return strategies.
5076|インフロニアHD
2695.5
▼ -2.12%
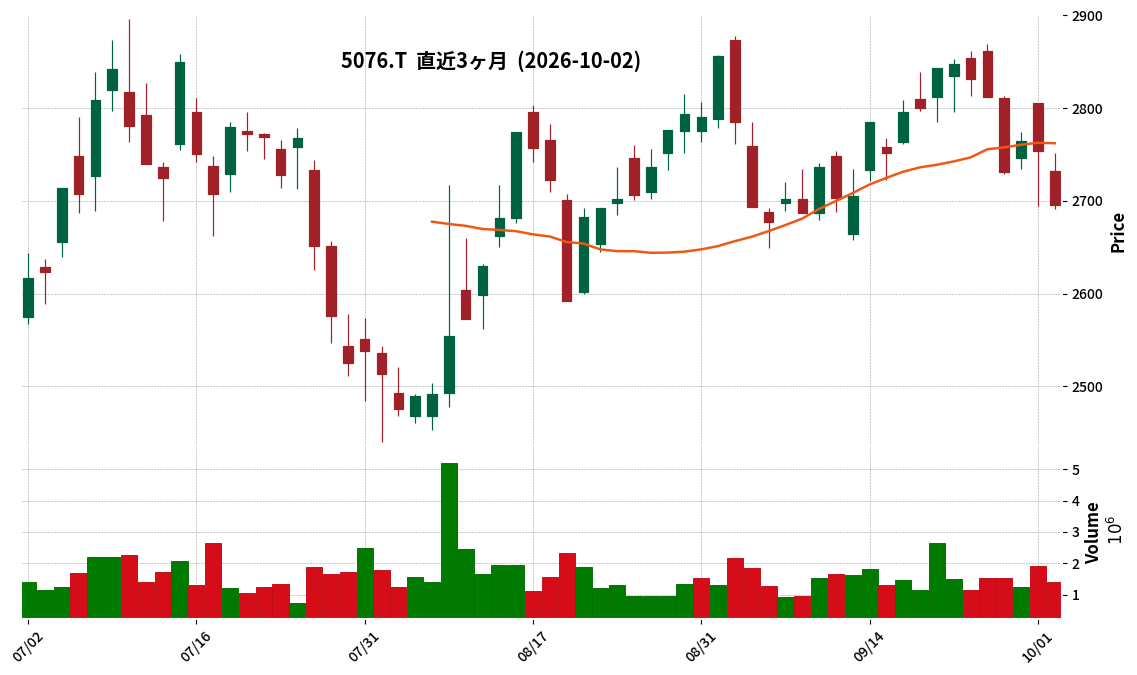
📎 Source:インフロニアHD Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Infroneer Holdings, Inc. announced on October 2, 2026, the completion of the interim review by certified public accountants for its Q1 FY2027 consolidated financial results (IFRS).
- This interim review was conducted in connection with the issuance of new shares and the sale of the company’s shares, resolved by the Board of Directors on the same date.
- There are no changes to the consolidated quarterly financial statements previously disclosed on August 7, 2026.
- For Q1 FY2027, consolidated revenue was JPY 308,365 million (up 60.9% year-on-year), business profit was JPY 14,770 million (up 103.1% year-on-year), and profit attributable to owners of the parent was JPY 76,135 million (up 840.4% year-on-year).
- The full-year consolidated performance forecast includes revenue of JPY 1,445,000 million (up 28.5% year-on-year) and profit attributable to owners of the parent of JPY 85,500 million (up 11.7% year-on-year).
🤖 AI Perspective
This announcement confirms the validity of the previously disclosed Q1 financial results through an external audit. The interim review was conducted in relation to a new share issuance and share offering, which may be a key point for investors to consider in the context of future financing and growth strategies. Furthermore, the updated full-year performance forecast, alongside the strong Q1 results, suggests that investors may closely monitor the company’s trajectory and execution of its business plans.
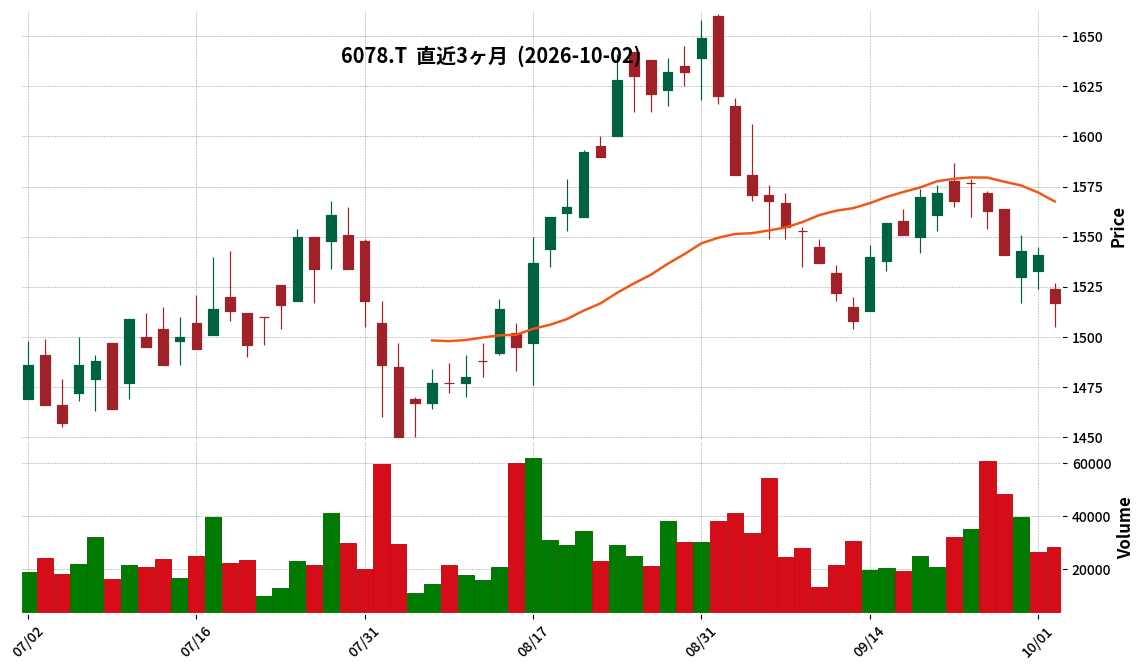
6078|バリューHR
1517.0
▼ -1.56%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Value HR Co., Ltd. resolved at its Board of Directors meeting on October 2, 2026, to acquire 100% of the issued shares of Shin Akasaka Health Management Association Co., Ltd., making it a subsidiary.
- Shin Akasaka Health Management Association provides proposal sales, reservation acceptance, and administrative services for medical check-ups and human dock services, serving over 850 health insurance associations and companies.
- The purpose of the acquisition is to integrate Value HR’s health management platform business with Shin Akasaka Health Management Association’s sales capabilities and customer base in the medical check-up field, aiming to improve medical check-up rates, enhance service quality, and expand health support services.
- The acquisition cost for the common shares of Shin Akasaka Health Management Association is ¥1,454 million, consisting of ¥1,300 million in cash and 100,000 shares of Value HR common stock (valued at ¥154 million), plus advisory fees of approximately ¥226 million, totaling an estimated ¥1,680 million.
- The scheduled share transfer date is November 18, 2026.
🤖 AI Perspective
This acquisition appears to be a strategic move by Value HR to integrate its digital health management platform with Shin Akasaka Health Management Association’s established expertise and client base in the medical check-up sector. This synergy could potentially expand Value HR’s service offerings and strengthen its market position in the health management industry. The use of a combination of cash and Value HR’s own shares for consideration may also reflect a diversified approach to M&A financing.
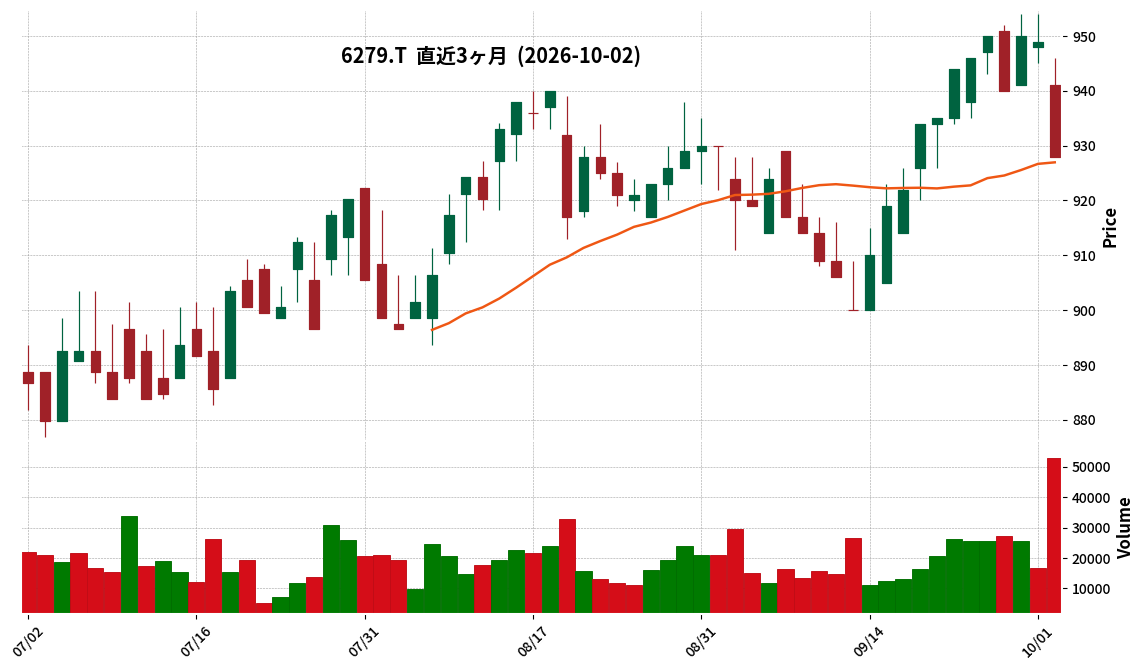
6279|瑞光
928.0
▼ -2.21%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Zuiko Corporation announced its financial results for the second quarter (interim) of the fiscal year ending February 2027.
- Consolidated net sales reached ¥10,899 million, representing a 3.9% increase year-on-year.
- The company reported a consolidated operating loss of ¥222 million (compared to an operating profit of ¥386 million in the prior-year interim period) and an ordinary loss of ¥158 million (compared to an ordinary profit of ¥422 million).
- Net loss attributable to owners of parent was ¥146 million (compared to a net profit of ¥316 million in the prior-year interim period).
- Sales for the cotton spunlace business were ¥2,089 million with a segment profit of ¥3 million. Sales for the hygiene product manufacturing machinery business were ¥8,656 million with a segment loss of ¥227 million.
- The full-year consolidated earnings forecast and dividend forecast (interim dividend of ¥8.00, commemorative dividend of ¥4.00, year-end dividend of ¥8.00, total ¥20.00) remain unchanged.
🤖 AI Perspective
While sales increased, the overall loss appears to stem from reduced sales at Zuiko (Shanghai) Electric Equipment Co., Ltd. and decreased profits within the hygiene product manufacturing machinery business. The contribution from the cotton spunlace business highlights a shift in the company’s business portfolio, which may be worth monitoring. The unchanged full-year forecast could suggest expectations for a stronger performance in the second half of the fiscal year.
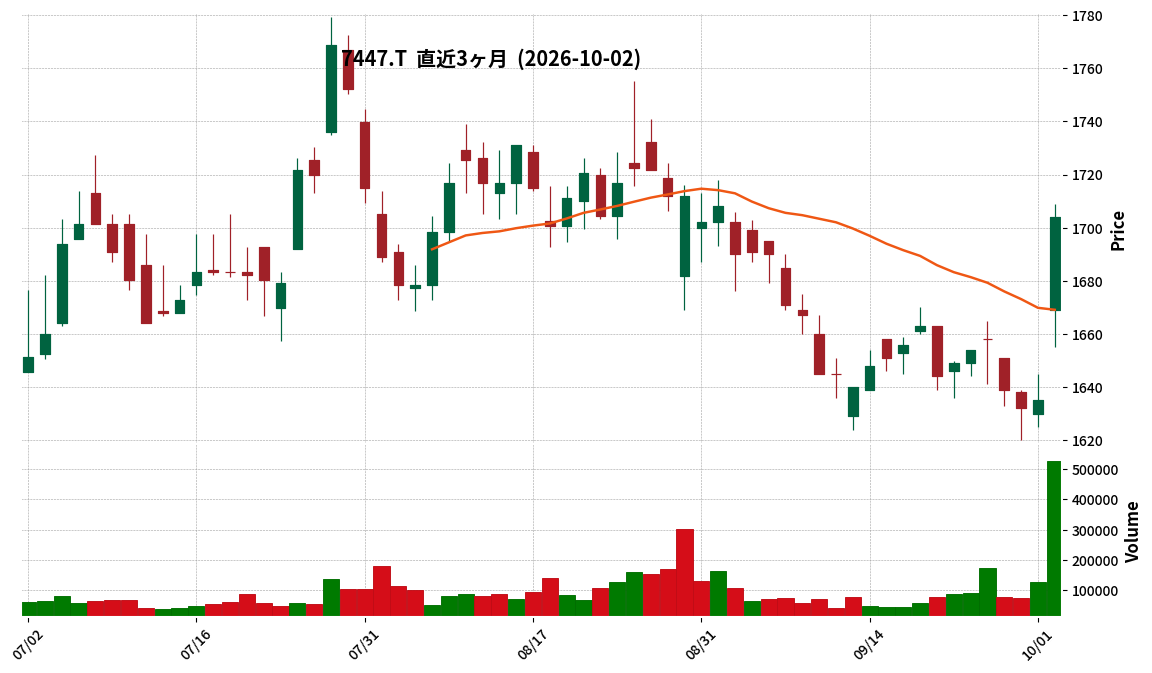
7447|ナガイレーベ
1704.0
▲ +4.22%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Nagaileben announced its full-year financial results for the fiscal year ended August 2026, with net sales of ¥17,205 million (+1.3% year-on-year), operating profit of ¥3,625 million (+1.2% year-on-year), and net profit of ¥2,650 million (+3.0% year-on-year).
- The company achieved two consecutive years of revenue growth; while patient wear experienced a significant decrease in revenue (-11.8%), core markets (+3.7%), surgical wear (+7.3%), and overseas markets (+16.9%) showed steady growth.
- The year-end dividend for FY2026 is projected to be ¥70, an increase of ¥10.
- For the full-year outlook for FY2027, the company plans for net sales of ¥17,500 million (+1.7% year-on-year), operating profit of ¥3,602 million (-0.7% year-on-year), and net profit of ¥2,660 million (+0.4% year-on-year), aiming for three consecutive years of revenue growth.
- To strengthen its management structure, an Executive Officer System was introduced on September 1, 2026.
🤖 AI Perspective
Nagaileben’s two consecutive years of revenue growth in FY2026 suggest resilience in core and overseas markets, though the decline in patient wear revenue warrants attention. The planned increase in the year-end dividend may signal a commitment to shareholder returns. The FY2027 outlook forecasts continued revenue growth but a slight decrease in operating profit, which could indicate potential pressures on profitability from external factors such as currency fluctuations or rising raw material costs.
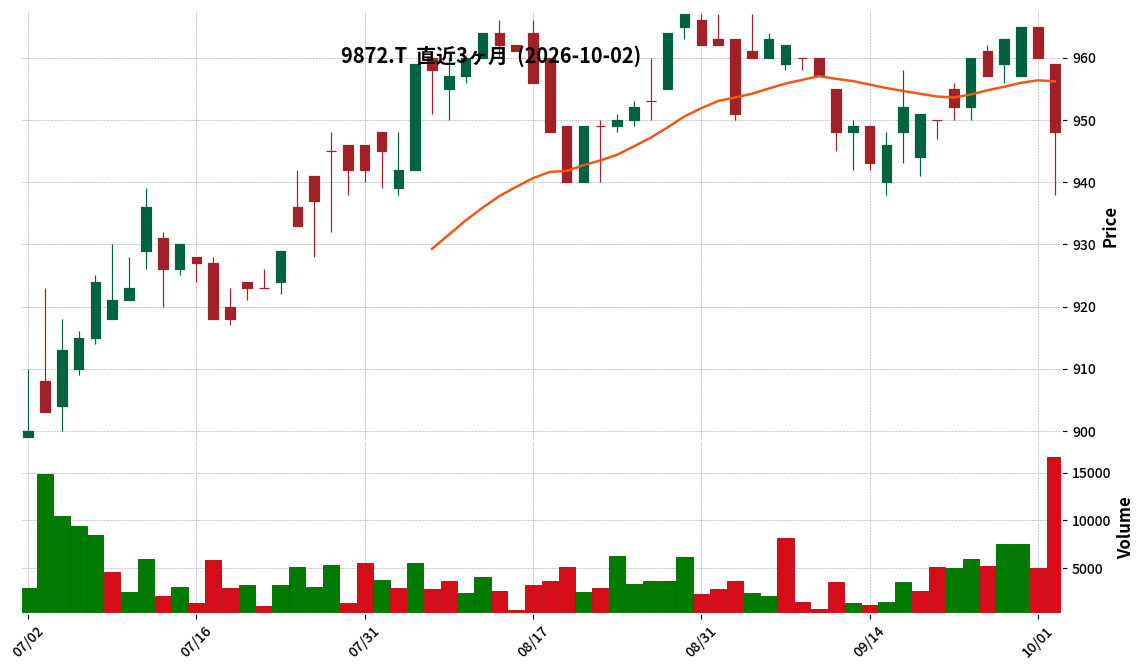
9872|北恵
948.0
▼ -1.25%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Kitakei Co., Ltd. announced its financial results for the third quarter of the fiscal year ending November 2026 (November 21, 2025, to August 20, 2026).
- Consolidated operating results show net sales of JPY 44.31 billion (up 0.4% year-on-year), operating profit of JPY 0.54 billion (up 8.9% year-on-year), ordinary profit of JPY 0.67 billion (up 3.1% year-on-year), and quarterly net profit of JPY 0.41 billion (up 4.2% year-on-year).
- Diluted earnings per share for the quarter were JPY 44.38.
- Regarding the financial position, total assets at the end of the third quarter were JPY 26.39 billion, and net assets were JPY 14.23 billion, with a capital adequacy ratio of 53.9%.
- The full-year earnings forecast for the fiscal year ending November 2026 (net sales JPY 59.30 billion, operating profit JPY 0.72 billion, ordinary profit JPY 0.91 billion, net profit JPY 0.56 billion) and the annual dividend forecast (JPY 28.00) remain unchanged.
🤖 AI Perspective
Kitakei’s Q3 FY2026 results show an increase in net sales and all profit categories compared to the prior year. This performance may suggest the positive impact of strengthening relationships in the new housing market, expanding sales channels in the renovation and non-residential sectors, promoting eco-friendly products, and enhancing construction capabilities. The unchanged full-year forecasts could indicate that the company anticipates maintaining its current performance trajectory.
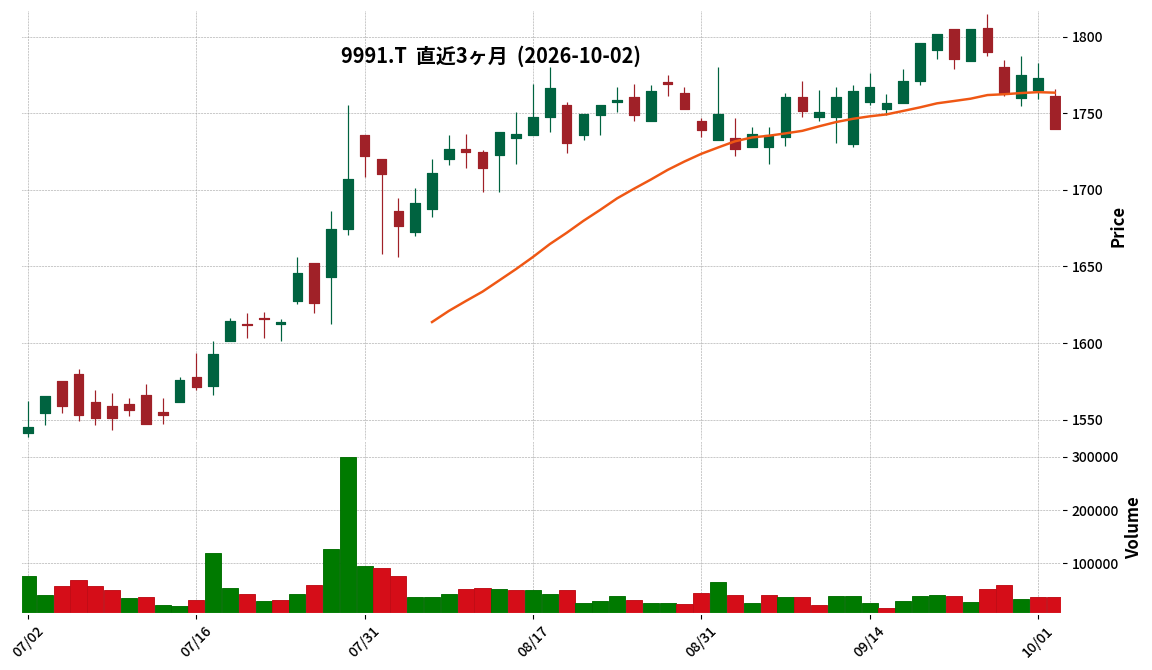
9991|ジェコス
1740.0
▼ -1.86%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Jecos Co., Ltd. announced on October 2, 2026, the signing of a business alliance agreement with Nippon Kiso Gijutsu Co., Ltd.
- The alliance aims to leverage both companies’ strengths and business foundations to strengthen existing businesses, create new business opportunities, jointly develop new technologies, and collaborate on overseas projects.
- Jecos specializes in temporary construction materials and construction machinery, while Nippon Kiso Gijutsu possesses expertise in drilling, injection, foundation work, and ground improvement technologies.
- Nippon Kiso Gijutsu’s consolidated net sales for the fiscal year ended March 2026 were 27,353 million yen, with consolidated operating profit of 1,455 million yen.
- Jecos stated that the impact of this business alliance on its financial performance is expected to be minor.
🤖 AI Perspective
This alliance aligns with Jecos’s mid-term management plan to diversify its business portfolio. The integration of both companies’ expertise and technologies could create synergies within the construction industry, potentially enhancing their competitive positions. Investors may find it noteworthy that the collaboration includes automated construction technologies aimed at labor-saving and safety improvements, as well as potential for expansion in overseas markets.
💡 Start investing with IR insights


※ 本ページには広告が含まれます(PR)
Disclaimer: This article is for informational purposes only and does not constitute investment advice. All investment decisions are at your own risk.
コメント