📌 Today’s Highlights
Today we cover 72 IR announcements. Notable among them: アウン (2459), アークス (9948), G-インタファクトリ (4057). Use the table of contents below to navigate to each company.
- 2459|アウン
- 9948|アークス
- 4057|G-インタファクトリ
- 209A|P-小野谷機工
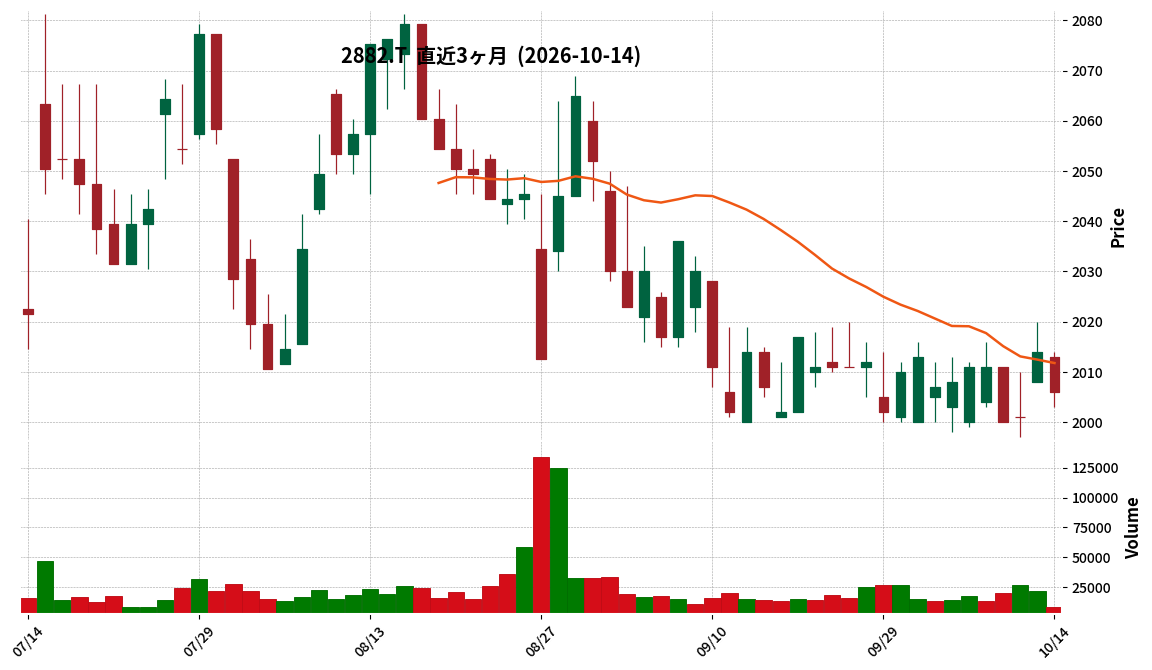
- 2882|イートアンドHD
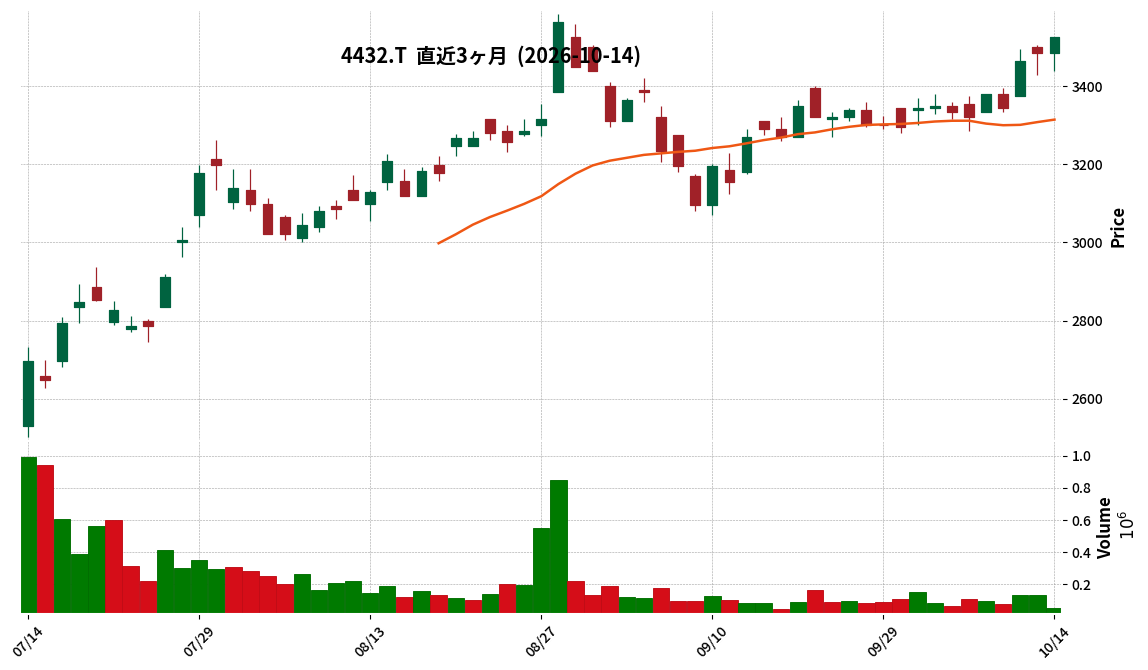
- 4432|ウイングアーク
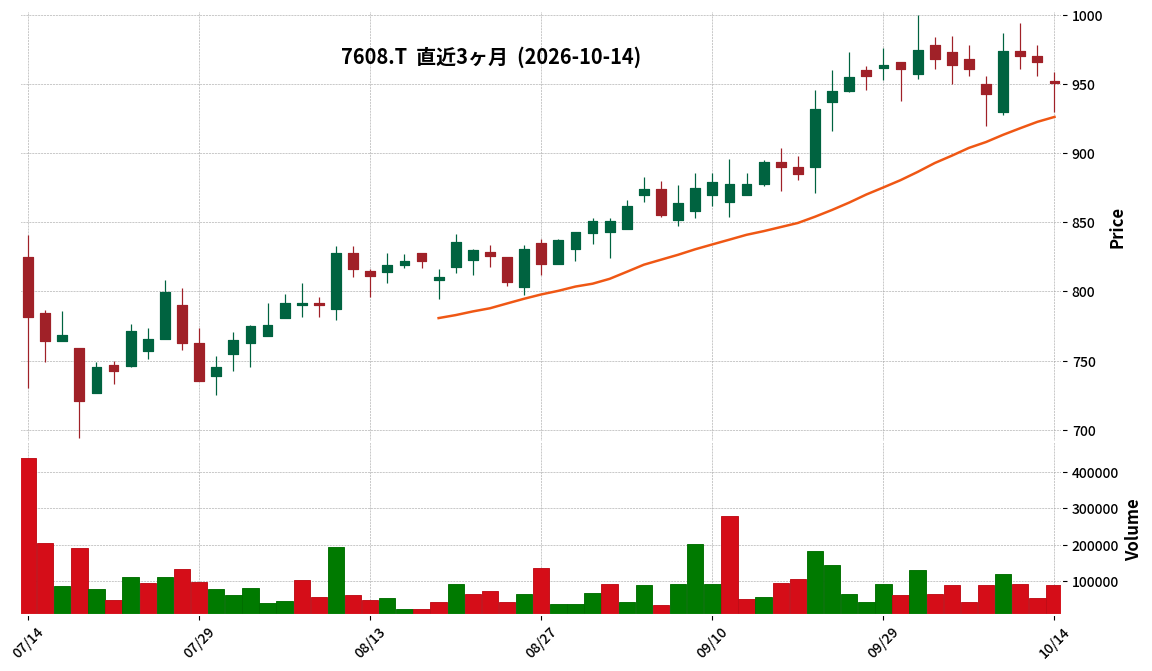
- 7608|SKジャパン
- 7805|プリントネット
- 3374|内外テック
- 3892|岡山製紙
- 3177|ありがとうS
- 3536|アクサスHD
- 3077|ホリイフード
- 640A|G-ASNOVA
- 6897|ツインバード
- 7601|ポプラ
- 9601|松竹
- 9837|モリト
- 3181|買取王国
- 7670|オーウエル
- 8904|AVANTIA
- 3065|ライフフーズ
- 365A|伊澤タオル
- 5250|GMOプライム
- 138A|G-光フードサービス
- 1434|JESCO HD
- 156A|G-マテリアルG
- 2153|イージェイHD
- 2186|ソーバル
- 2305|スタジオアリス
- 2471|エスプール
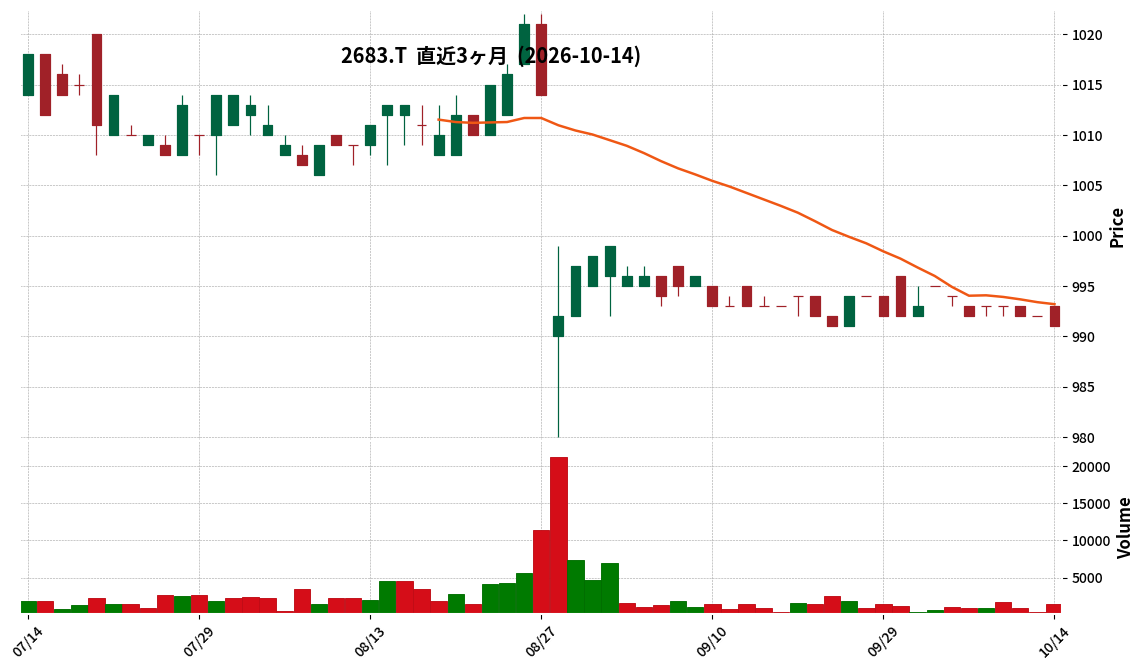
- 2683|UOGroup
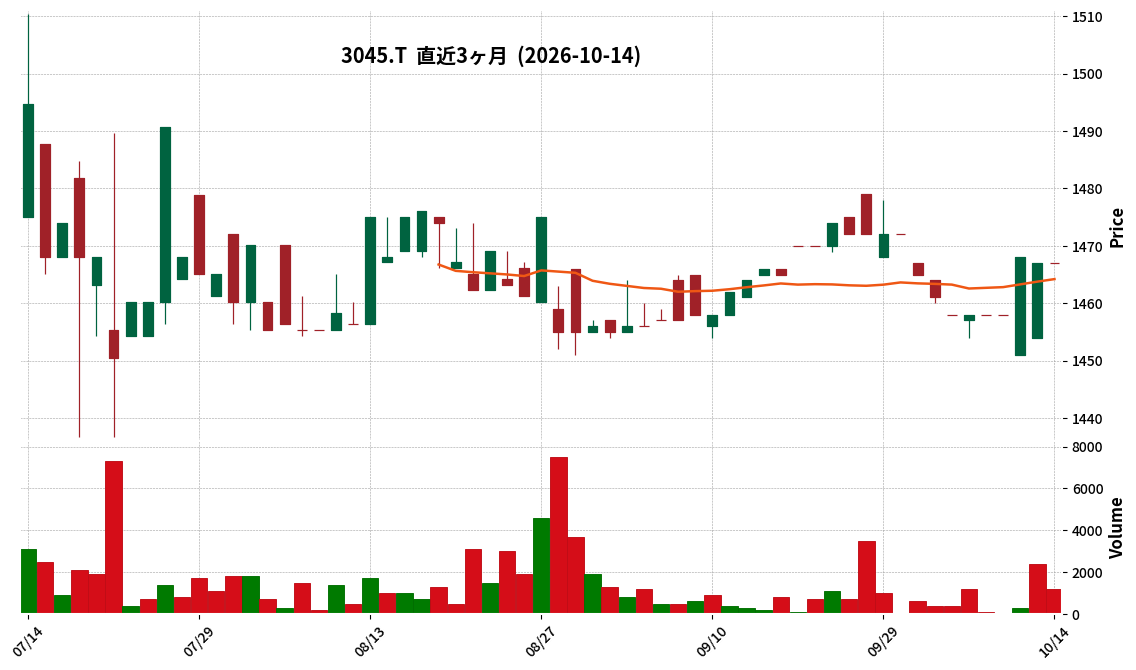
- 3045|カワサキ
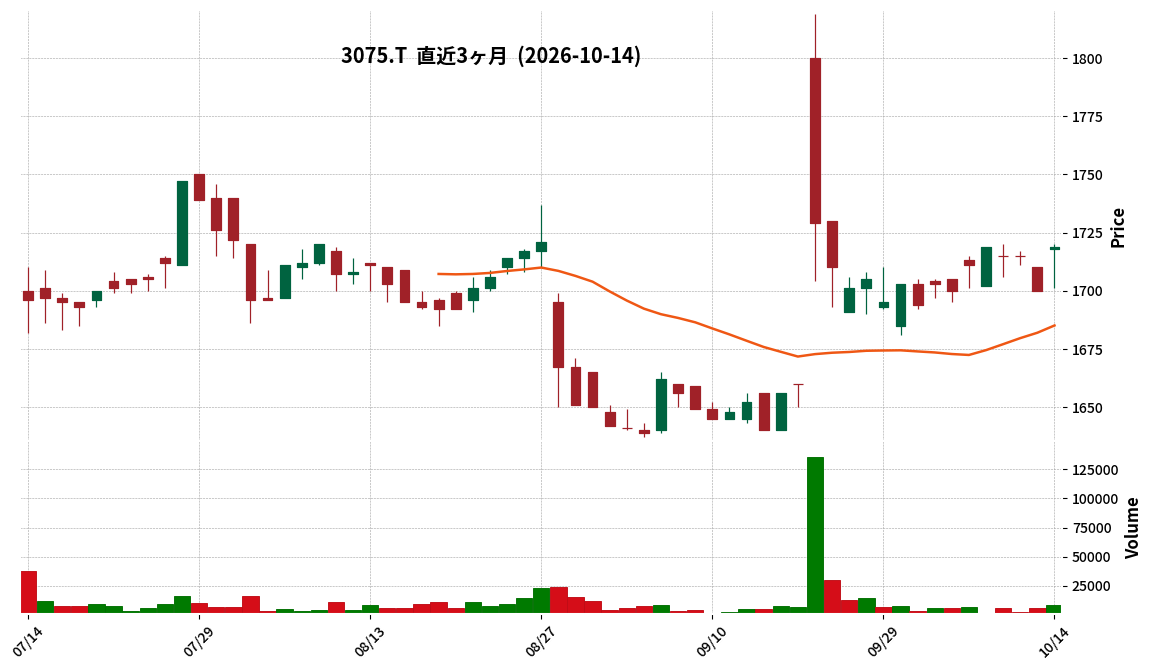
- 3075|銚子丸
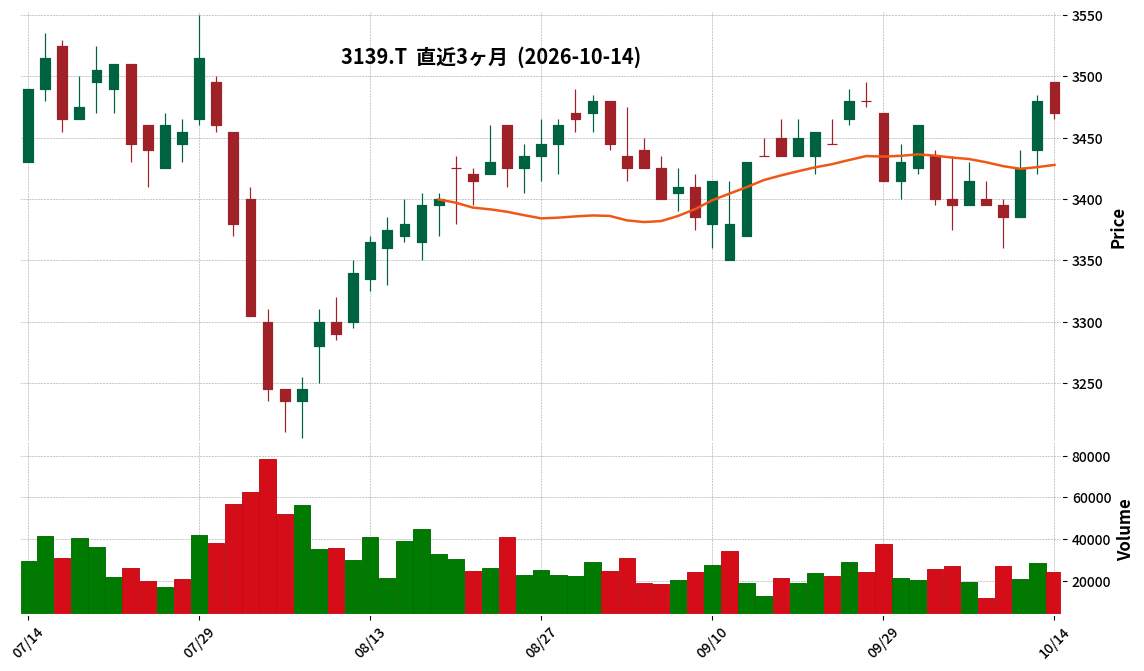
- 3139|ラクト・ジャパン
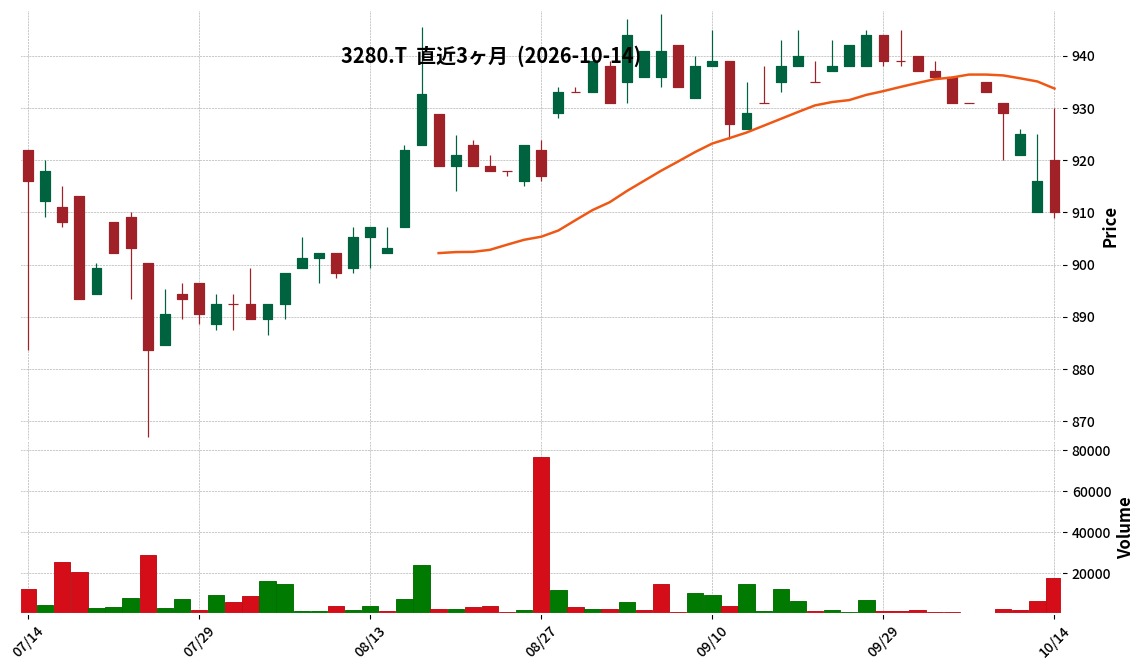
- 3280|エストラスト
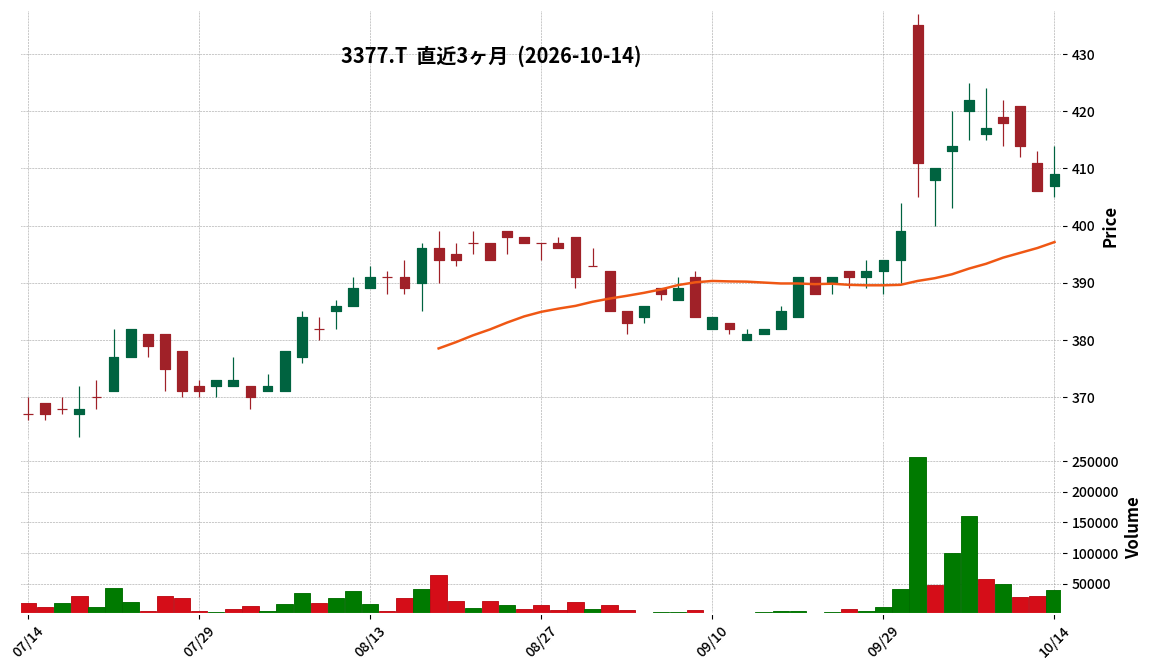
- 3377|バイク王
- 3384|アークコア
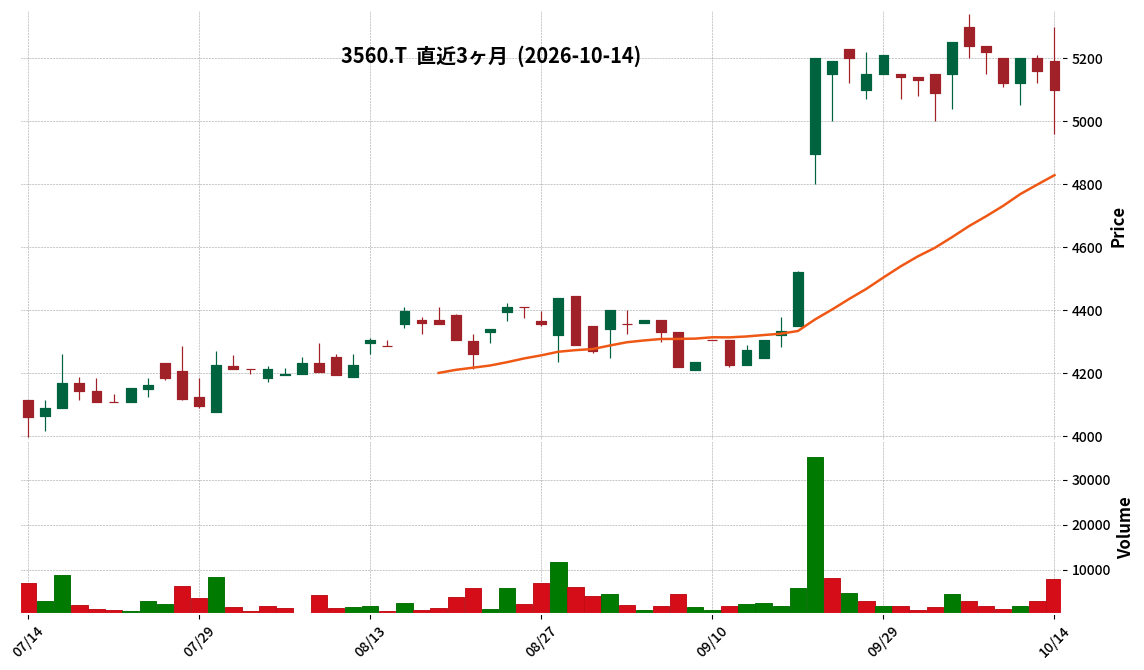
- 3560|ほぼ日
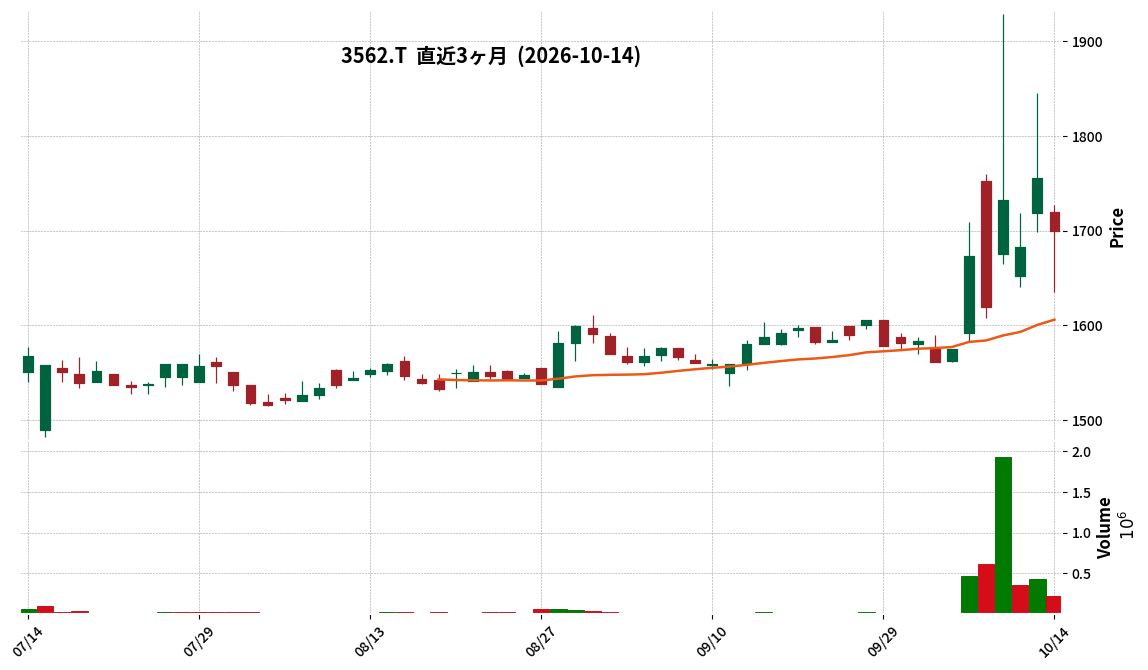
- 3562|No.1
- 3608|TSI HD
- 3612|ワールド
- 3760|ケイブ
- 3922|PRTIMES
- 3977|A-フュージョン
- 418A|ウリドキ
- 4317|レイ
- 434A|P-LOOPLACE
- 4372|G-ユミルリンク
- 2901|ウェルディッシュ
- 3361|トーエル
- 3678|メディアドゥ
- 3936|G-グローバルウェイ
- 4429|G-リックソフト
- 457A|P-ルリアン
- 4668|明光ネット
- 4829|日本エンタープライズ
- 5246|G-ELEMENTS
- 8143|ラピーヌ
- 8783|abc
- 9334|アイビスHD
- 9418|U-NEXT
- 135A|G-VRAIN
- 557A|P-フェリエスト
- 2796|ファーマライズHD
- 3387|クリレスHD
- 5129|G-FIXER
- 3823|WHY HOW DO
- 5122|オカモト
- 7879|ノダ
- 464A|G-QPSHD
- 9337|G-トリドリ
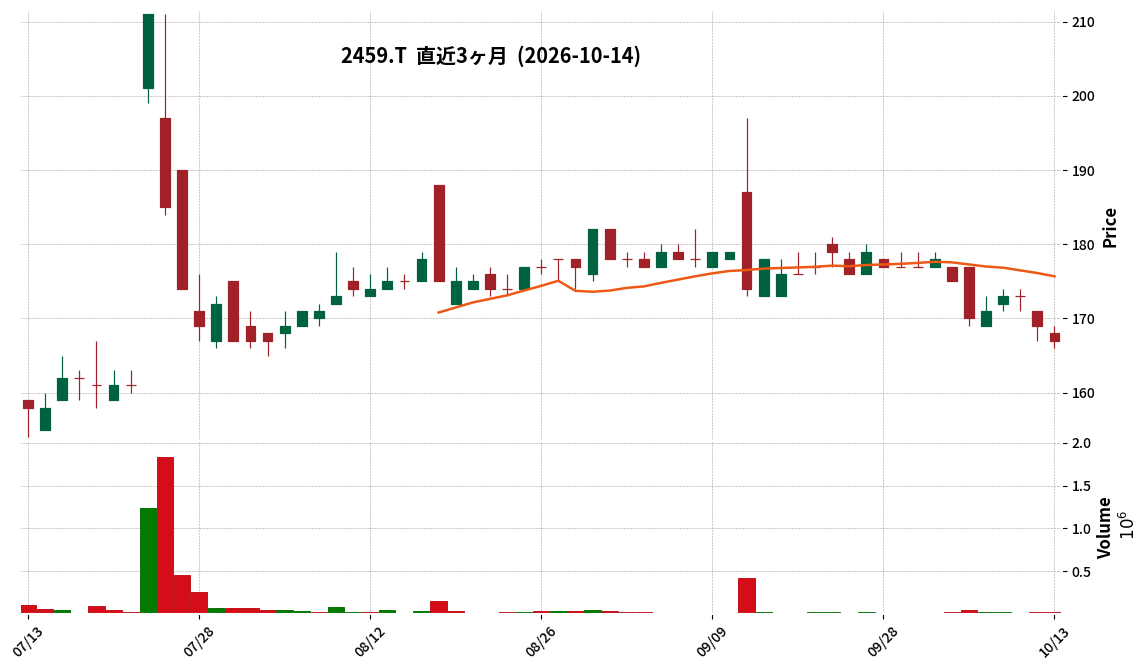
2459|アウン
167.0
▼ -1.18%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- AUN announced its consolidated financial results for the first quarter of the fiscal year ending May 2027 (June 1, 2026 – August 31, 2026).
- Net sales amounted to ¥43 million, representing a 13.2% decrease compared to the same period in the previous year.
- The company reported an operating loss of ¥15 million (compared to an operating loss of ¥23 million in the prior year period), an ordinary loss of ¥16 million (compared to an ordinary loss of ¥23 million), and a net loss attributable to owners of the parent of ¥16 million (compared to a net loss of ¥23 million), with all loss figures narrowing from the previous year.
- As for the consolidated financial position, total assets stood at ¥612 million, net assets at ¥291 million, and the equity ratio was 47.7%.
- The consolidated earnings forecast for the fiscal year ending May 2027 remains undetermined due to numerous uncertain factors impacting performance, making it difficult to provide specific figures at this time.
🤖 AI Perspective
AUN’s Q1 FY2027 results show a decrease in sales, but a narrowing of losses compared to the prior year, despite ongoing upfront investments. This might suggest progress in improving the profitability of existing businesses and restructuring the revenue model. Investors may want to monitor how new service deployments and business alliances aimed at new market development will contribute to future performance.
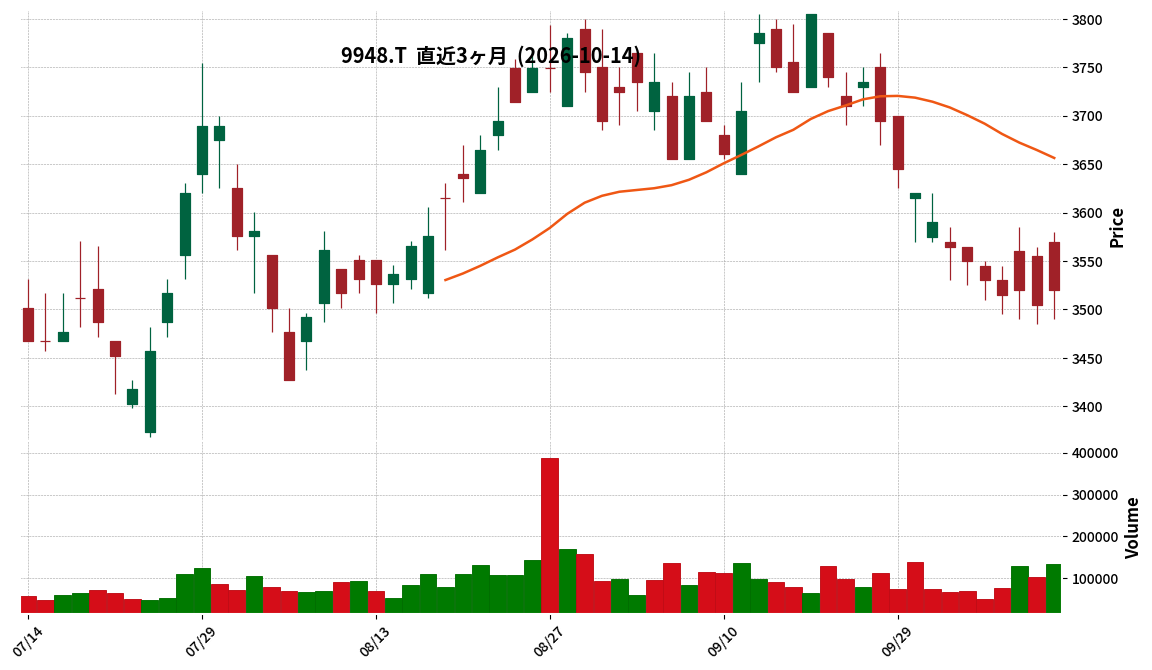
9948|アークス
3520.0
▲ +0.43%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- ARCS Group’s net sales for the second quarter (interim period) of FY2027 reached 318.6 billion yen, an increase of 101.6% year-on-year, marking a new record high for an interim period.
- Interim operating profit was 7.7 billion yen (97.3% year-on-year), ordinary profit was 8.5 billion yen (97.3% year-on-year), and interim net profit was 5.3 billion yen (94.1% year-on-year).
- Gross profit increased by 101.1% year-on-year to 79.2 billion yen, while the gross profit margin decreased by 0.1 percentage points year-on-year to 24.9%.
- Selling, general, and administrative (SG&A) expenses increased by 101.6% year-on-year to 71.4 billion yen, executed within budget (98.3% of budget).
- The impact of electricity costs on operating profit was reported as a year-on-year decrease of 200 million yen for the interim period.
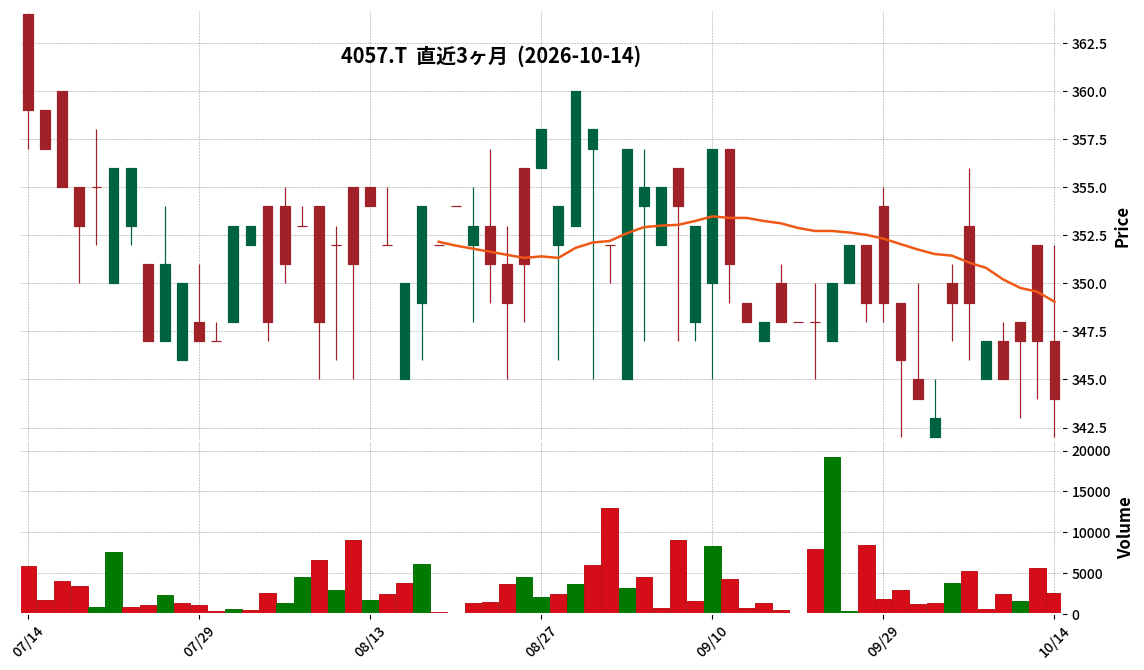
4057|G-インタファクトリ
344.0
▼ -0.86%
📎 Source:G-インタファクトリ Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- G-Interfactory announced its Q1 FY2027 non-consolidated financial results.
- Revenue for the quarter was 646 million yen, representing a 12.3% decrease compared to the same period last year.
- The company reported an operating loss of 70 million yen, a shift from an operating profit of 44 million yen in the prior year’s first quarter.
- Ordinary loss amounted to 74 million yen, and net loss for the quarter was 72 million yen.
- The Cloud Commerce Platform segment recorded revenue of 616,773 thousand yen (down 7.3% YoY) and segment profit of 101,320 thousand yen (down 54.8% YoY).
- The EC Business Growth Support segment reported revenue of 28,241 thousand yen (down 60.6% YoY) and segment profit of 487 thousand yen (down 66.8% YoY).
🤖 AI Perspective
G-Interfactory’s first-quarter results show a decline in revenue and a shift to losses across all profit metrics. The decrease in revenue and segment profit within the core Cloud Commerce Platform and EC Business Growth Support segments appears to be a significant factor. Investors may monitor how the company’s investments in new platforms and AI-powered services could potentially influence future performance.
Disclaimer: This article is for informational purposes only and does not constitute investment advice.
209A|P-小野谷機工
780.0
▲ +0.00%
📎 Source:P-小野谷機工 Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- P-ONODANI KIKO’s consolidated financial results for the fiscal year ended August 2026 reported net sales of ¥7,998 million, representing a 7.2% increase from the previous year.
- Operating profit was ¥399 million (up 22.5% year-on-year), while ordinary profit decreased by 4.4% to ¥398 million, and net profit attributable to parent company shareholders decreased by 28.0% to ¥279 million.
- Earnings per share (EPS) stood at ¥76.34, down from ¥106.05 in the prior fiscal year.
- The annual dividend per share increased to ¥12.00, up from ¥10.00 in the previous fiscal year.
- For the fiscal year ending August 2027, the company forecasts consolidated net sales of ¥8,160 million (up 2.0%), operating profit of ¥410 million (up 2.5%), and net profit attributable to parent company shareholders of ¥280 million (up 0.2%).
- As of the end of the period, total assets were ¥9,702 million, net assets were ¥5,241 million, and the equity ratio was 54.0%.
- A significant change in the scope of consolidation included the exclusion of Bridgestone Shop Fukui Co., Ltd.
🤖 AI Perspective
The FY2026 results show a divergence where net sales and operating profit increased, but ordinary profit and net profit attributable to parent shareholders decreased. This could suggest improved operational efficiency, potentially offset by non-operating or extraordinary factors impacting net income. The increase in the annual dividend may signal a commitment to shareholder returns. Looking ahead, the FY2027 forecast projects modest growth in both revenue and profit, which may indicate a period of steady rather than rapid expansion.
2882|イートアンドHD
2006.0
▼ -0.40%
📎 Source:イートアンドHD Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Eat&HD announced its consolidated financial results for the second quarter of the fiscal year ending February 2027 (March 1, 2026 – August 31, 2026).
- Revenue reached ¥20.255 billion, an increase of 1.7% year-on-year, and operating profit was ¥767 million, a significant increase of 51.7% year-on-year.
- The Food Business segment reported sales of ¥11.481 billion (up 3.0% YoY) and segment profit of ¥601 million (up 79.8% YoY).
- The Restaurant Business segment reported sales of ¥8.773 billion (down 0.1% YoY) and segment profit of ¥460 million (up 10.7% YoY).
- A dedicated xiao long bao production line was added and commenced operations at the Kanto factory in August 2026, and the first North American store opened in May 2026.
🤖 AI Perspective
Eat&HD’s achievement of increased revenue and operating profit amidst persistent inflation suggests the resilience and adaptability of its business operations. The enhancements in the food business, such as production line expansion and new product launches, along with the strategic adjustments in the restaurant business and accelerated overseas expansion, could be key drivers for future growth. The strong performance of the first North American store, in particular, may indicate promising potential for further international market penetration.
4432|ウイングアーク
3525.0
▲ +1.15%
📎 Source:ウイングアーク Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- WingArc1st Co., Ltd. has announced its consolidated financial results for the second quarter (interim period) of the fiscal year ending February 2027.
- Consolidated revenue for the interim period was ¥16,498 million, an increase of 12.1% compared to the same period in the previous year.
- Consolidated operating profit reached ¥5,168 million, marking a 25.8% increase year-on-year.
- Interim profit attributable to owners of the parent company amounted to ¥3,796 million, up 29.2% from the prior year’s interim period.
- Basic earnings per share for the interim period were ¥109.26, up from ¥84.84 in the previous year’s interim period.
- The company projects an annual dividend of ¥54.00 for the fiscal year-end, with an interim dividend of ¥54.00 planned.
🤖 AI Perspective
These results indicate a robust performance, with double-digit growth across revenue, operating profit, and net profit attributable to parent company owners compared to the prior interim period. The operating profit growth outpacing revenue growth may suggest an improvement in profitability. Investors may want to monitor the company’s progress against its full-year guidance going forward.
7608|SKジャパン
951.0
▼ -1.55%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- SK Japan announced its consolidated financial results for the second quarter of the fiscal year ending February 2027.
- Consolidated net sales for the interim period amounted to ¥10,035 million, representing a 32.0% increase compared to the prior interim period.
- Consolidated operating income was ¥988 million, a decrease of 1.9% year-on-year.
- Consolidated ordinary income rose by 2.7% to ¥1,037 million, and profit attributable to owners of parent increased by 2.0% to ¥723 million.
- The full-year consolidated earnings forecast has been revised to net sales of ¥19,500 million (up 20.1% year-on-year), operating income of ¥1,950 million (up 4.8%), and profit attributable to owners of parent of ¥1,370 million (up 2.7%).
- An interim dividend of ¥12.00 per share is planned, with no revision to the full-year dividend forecast of ¥24.00 per share.
🤖 AI Perspective
SK Japan’s Q2 results show a significant increase in net sales, but a slight decline in operating profit. This suggests that while revenue growth was strong, factors such as changes in sales mix or cost structures may have impacted profitability. The upward revision of the full-year forecast could indicate the company’s confidence in overcoming these pressures and achieving stronger performance in the latter half of the fiscal year.
7805|プリントネット
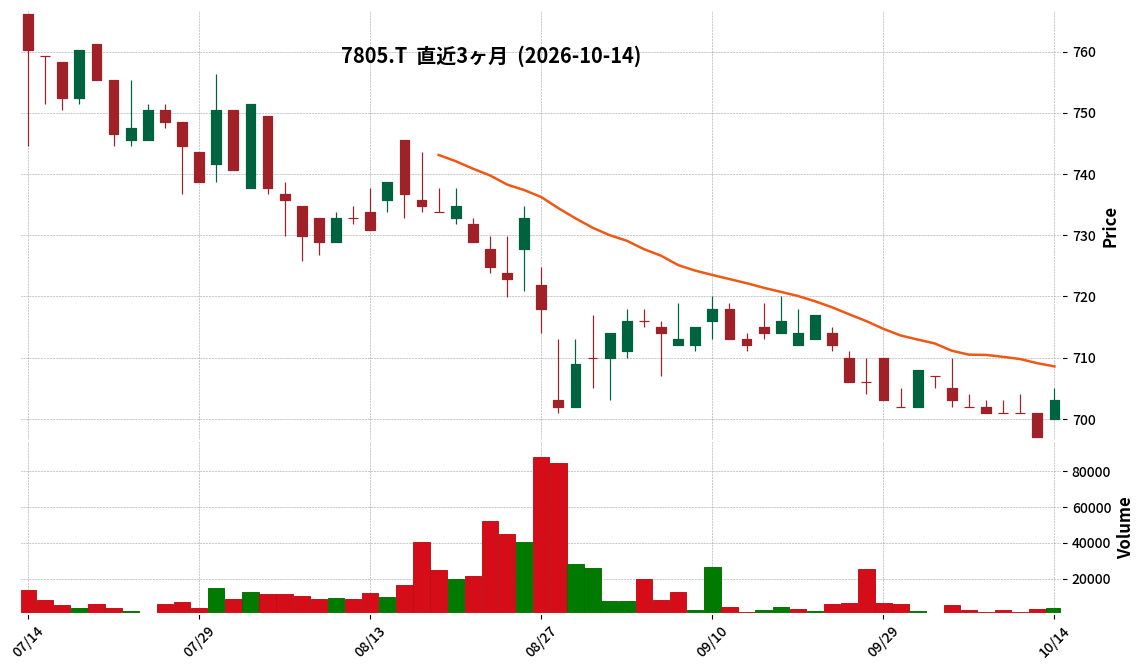
703.0
▲ +0.86%
📎 Source:プリントネット Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Printnet announced its non-consolidated financial results for the fiscal year ended August 2026.
- Revenue totaled ¥9,076 million, a 1.5% decrease year-on-year, while operating profit was ¥487 million, down 13.5% from the previous fiscal year.
- Ordinary profit reached ¥486 million, a 13.9% decrease, and net profit for the period was ¥327 million, a 24.3% decrease.
- Earnings per share for the period stood at ¥67.62.
- For the fiscal year ending August 2027, the company forecasts revenue of ¥9,653 million (up 6.4% year-on-year), operating profit of ¥264 million (down 45.8%), and net profit of ¥150 million (down 54.2%).
- The annual dividend per share for both FY2026 (actual) and FY2027 (forecast) is ¥13.00.
🤖 AI Perspective
The FY2026 results show a decline in key profit metrics, which appears to be influenced by reduced sales to major clients in the online print mail-order business and increased advertising costs for new customer acquisition. While the FY2027 forecast anticipates a revenue increase, a further decline in profits is projected, suggesting continued challenging business conditions. Investors may want to monitor the progress of strategic initiatives, such as improving profit margins and expanding production capacity, outlined in the company’s medium-term management plan.
3374|内外テック
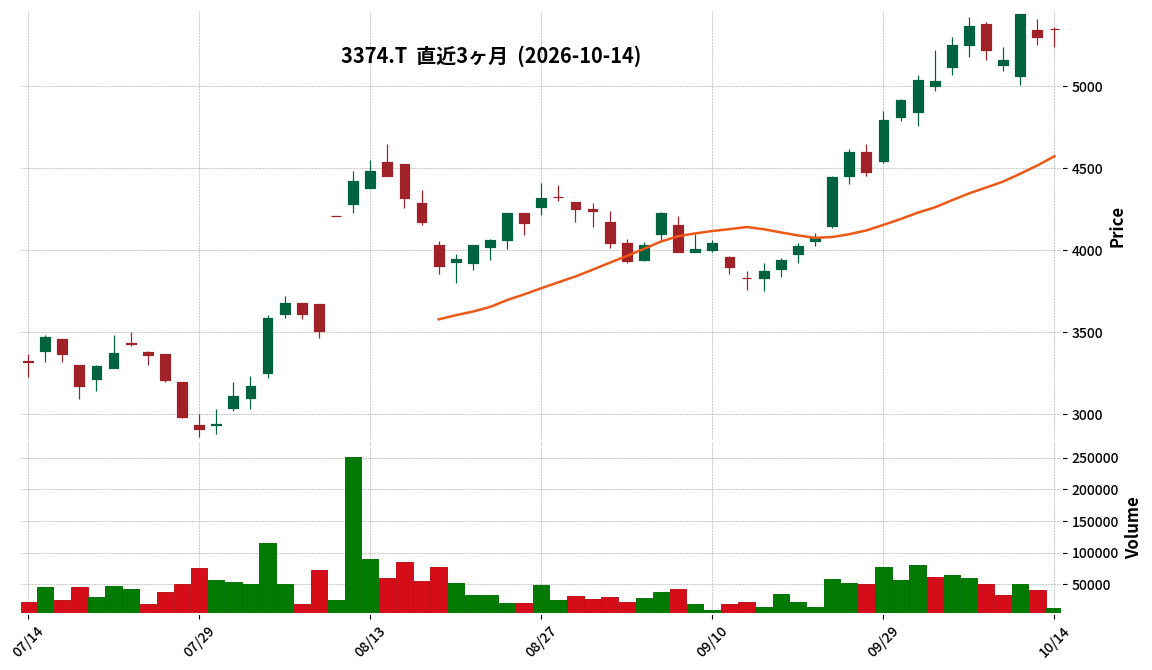
5350.0
▲ +0.94%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Naigai Tec announced on October 14, 2026, that its Board of Directors resolved on a stock split, an amendment to the Articles of Incorporation, and a revision to the dividend forecast.
- The stock split will be conducted at a ratio of one common share to two shares, with November 30, 2026, as the record date.
- As a result, the total number of outstanding shares will increase from 3,558,414 shares to 7,116,828 shares, and the total number of authorized shares will change from 8,500,000 shares to 17,000,000 shares.
- Article 6 of the Articles of Incorporation regarding the “Total Number of Authorized Shares” will be amended to 17,000,000 shares from 8,500,000 shares, effective December 1, 2026.
- The year-end dividend forecast for the fiscal year ending March 2027 has been revised from ¥144.00 per share (pre-split basis) to ¥72.00 per share due to the stock split, representing no substantial change.
🤖 AI Perspective
This stock split aims to reduce the investment unit, potentially making the company’s shares more accessible to a broader range of investors. The concurrent revision of the dividend forecast is solely to reflect the split ratio, indicating no change in the effective dividend per share for investors. This move could be viewed as a strategy to enhance liquidity and attract new shareholders.
3892|岡山製紙
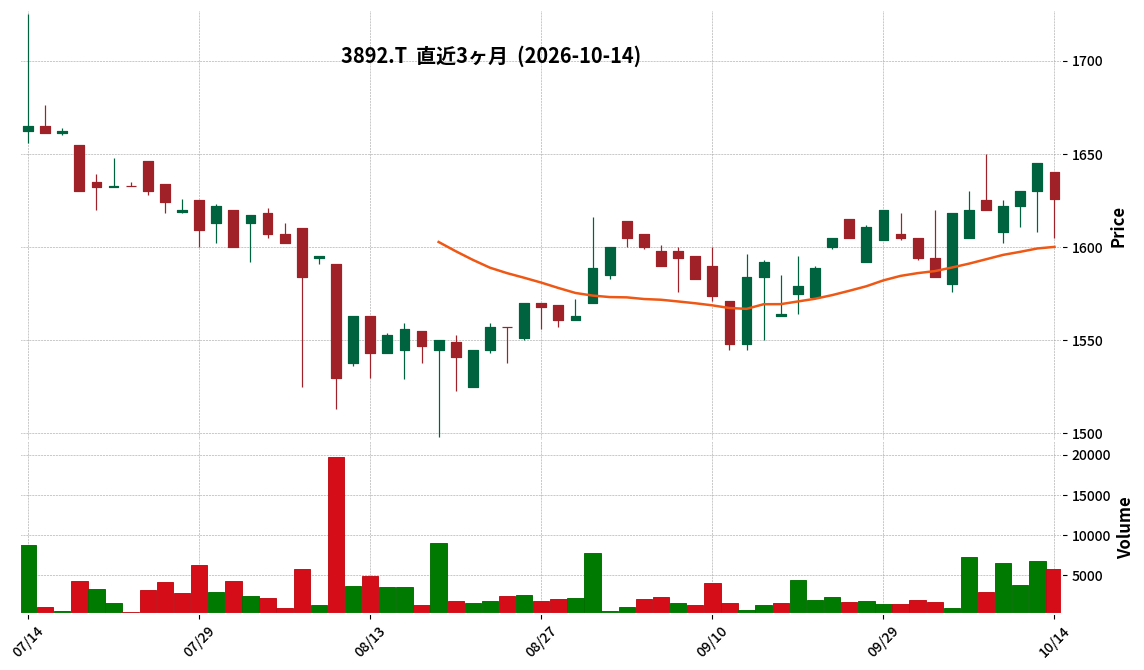
1626.0
▼ -1.16%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Okayama Seishi announced its Q1 FY2027 results for the period from June 1, 2026, to August 31, 2026.
- Revenue reached ¥2,846 million (up 3.0% year-on-year), operating profit was ¥261 million (up 17.9%), ordinary profit ¥333 million (up 19.6%), and net profit for the quarter ¥230 million (up 3.5%).
- The Paperboard Business reported sales of ¥2,431 million (up 3.3%) and segment profit of ¥237 million (up 12.2%).
- The Decorative Corrugated Board Business achieved sales of ¥414 million (up 1.5%) and segment profit of ¥24 million (up 134.5%).
- The equity ratio at the end of Q1 was 79.6%, an increase from 78.2% at the end of the previous fiscal year.
🤖 AI Perspective
Okayama Seishi’s first-quarter results show solid growth in both revenue and profit, primarily attributed to product price revisions. The significant increase in segment profit for the Decorative Corrugated Board Business suggests a strong positive impact from these revisions. The improved equity ratio may indicate enhanced financial stability, which could be a point of interest for investors monitoring the company’s balance sheet strength.
3177|ありがとうS
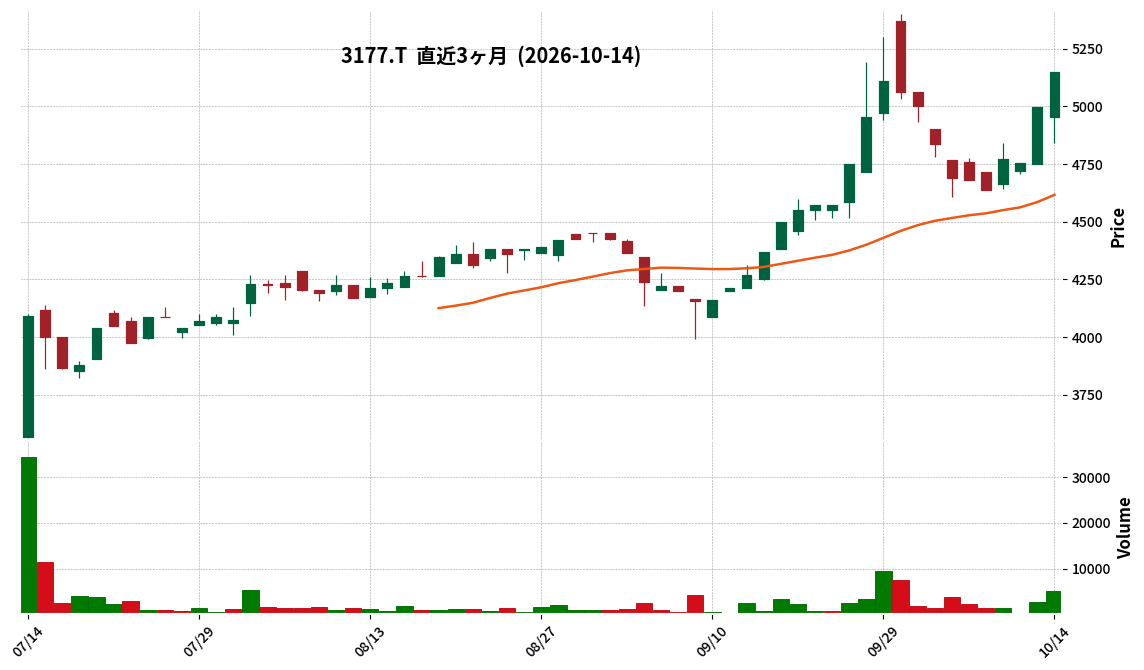
5150.0
▲ +3.10%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Arigato Service Co., Ltd. announced its consolidated financial results for the second quarter (interim period) of the fiscal year ending February 2027.
- Consolidated net sales reached ¥6,089 million, marking an 11.4% increase compared to the same period last year.
- Operating profit was ¥671 million (+65.3% YoY), ordinary profit was ¥693 million (+54.8% YoY), and net income attributable to owners of parent was ¥446 million (+64.2% YoY).
- By segment, the Re-use business reported sales of ¥4,687 million (+15.5% YoY) and segment profit of ¥854 million (+39.7% YoY). The Food Service business posted sales of ¥1,245 million (+2.1% YoY) and segment profit of ¥129 million (+13.1% YoY). The Regional Revitalization business recorded sales of ¥155 million (-17.8% YoY) and a segment loss of ¥76 million.
- The full-year consolidated performance forecast for the fiscal year ending February 2027 remains unchanged: sales of ¥11,398 million, operating profit of ¥944 million, ordinary profit of ¥1,033 million, and net income attributable to owners of parent of ¥492 million.
🤖 AI Perspective
Arigato Service’s interim results show significant double-digit growth across sales and profit metrics, with operating profit notably rising by 65.3% year-over-year. This performance appears to be primarily driven by the strong performance and expansion of the Re-use business, including a new store opening in Thailand. However, the full-year forecast remains unchanged, suggesting that investors may monitor the company’s performance in the latter half of the fiscal year and potential impacts from external factors.
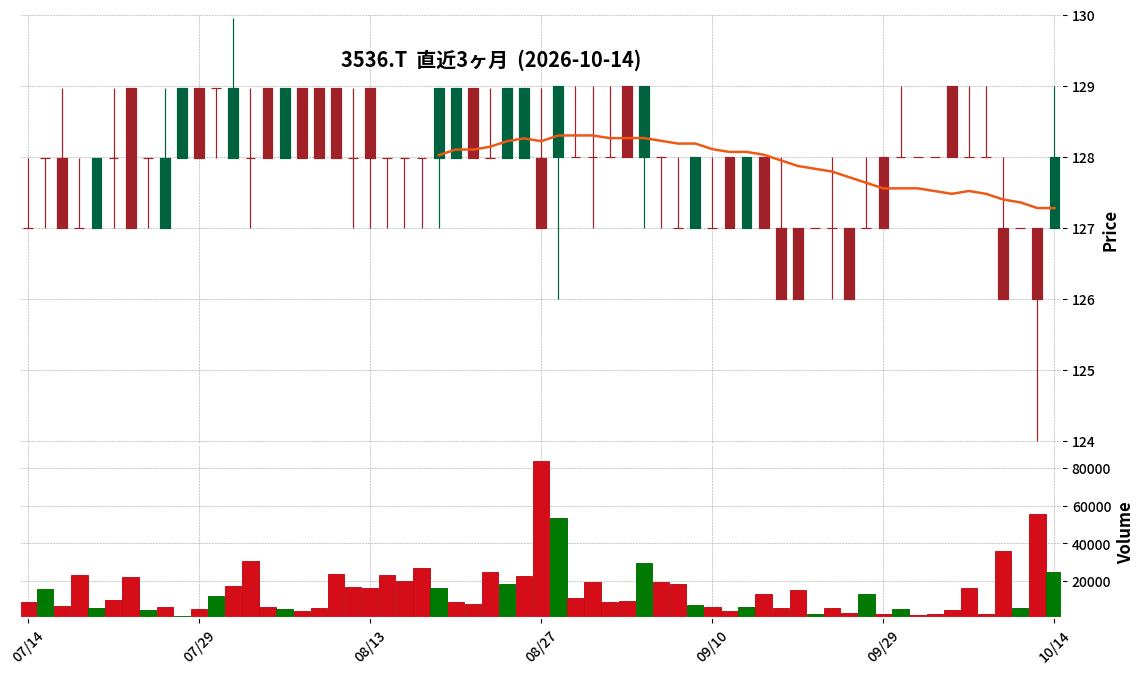
3536|アクサスHD
128.0
▲ +1.59%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- AXAS Holdings Co., Ltd. has announced its consolidated financial results for the fiscal year ended August 31, 2024.
- Net sales totaled ¥12,628 million, representing a 4.1% increase compared to the previous fiscal year.
- Operating profit reached ¥224 million, marking a 36.1% increase year-on-year.
- Ordinary profit was ¥5 million, an increase of 61.8% from the prior period.
- Net profit attributable to owners of the parent decreased by 80.2% to ¥43 million.
- Diluted earnings per share (EPS) for the period was ¥1.45.
- For the fiscal year ending August 31, 2025, the company forecasts consolidated net sales of ¥12,928 million (up 2.4% YoY), operating profit of ¥449 million (up 100.3% YoY), ordinary profit of ¥203 million, and net profit attributable to owners of the parent of ¥93 million.
🤖 AI Perspective
AXAS HD’s FY2024 results show growth in net sales, operating profit, and ordinary profit, contrasting with a significant decline in net profit attributable to owners of the parent. This suggests that factors such as cost structure or taxation may have notably impacted the bottom line. The substantial increase projected for operating, ordinary, and net profit in the upcoming fiscal year could indicate the company’s expectations for improved operational efficiencies or a more favorable business environment.
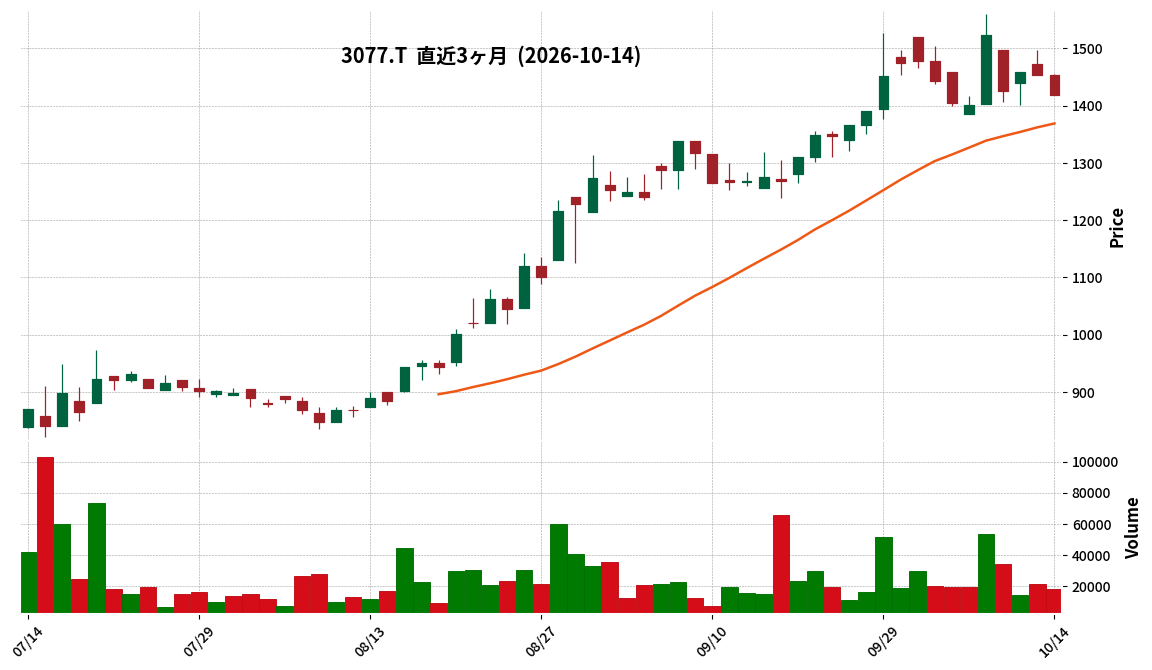
3077|ホリイフード
1419.0
▼ -2.34%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- For the third quarter ended November 2026 (December 2025 to August 2026), HORII FOOD reported consolidated net sales of ¥4,563,703 thousand, operating profit of ¥440,243 thousand, ordinary profit of ¥429,819 thousand, and net profit attributable to owners of parent of ¥487,313 thousand.
- The progress rates against the full-year consolidated earnings forecast (revised on July 15, 2026) are 76.3% for net sales, 82.7% for operating profit, 81.4% for ordinary profit, and 77.9% for net profit attributable to owners of parent.
- Year-on-year, net sales increased by 118.5%, operating profit by 137.3%, ordinary profit by 138.6%, and net profit attributable to owners of parent by 199.2%.
- The inbound business recorded Q3 cumulative sales of ¥273,503 thousand and operating profit of ¥32,330 thousand (profit margin of 11.8%).
- The company is promoting DX in existing businesses, with mobile order adoption reaching 78.1% as of Q3, and the implementation and expansion of the AI call reservation system “miraio” is ongoing.
🤖 AI Perspective
HORII FOOD’s Q3 FY2026 results show solid progress towards its upwardly revised full-year forecast, with operating profit achieving over 80% of the target. The significant contribution from the inbound business and efficiency improvements through DX in existing operations appear to be key drivers of performance. Achieving increased revenue and profit despite new store openings and upfront investments could indicate effective strategic execution, and the progress towards its 20% profit margin target may be of interest to investors.
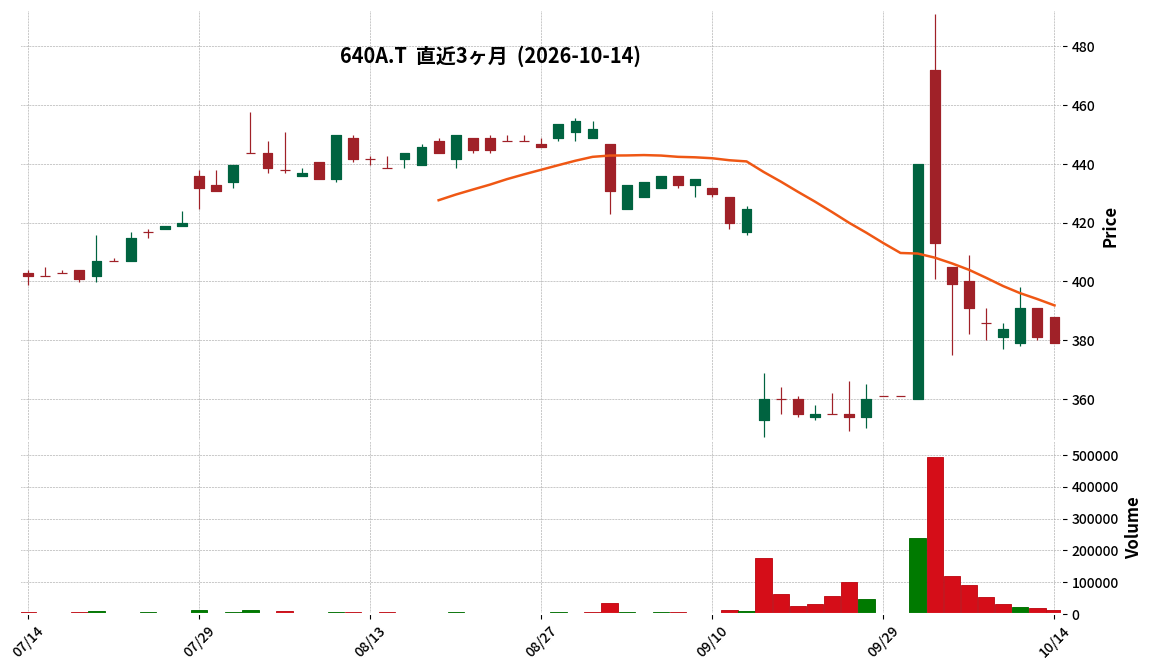
640A|G-ASNOVA
379.0
▼ -0.52%
📎 Source:G-ASNOVA Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- G-ASNOVA Companies, Inc. resolved to introduce a new shareholder benefit program named “‘ASNOVA×monotomoi’ Gift” at its Board of Directors meeting held on October 14, 2026.
- Eligible shareholders are those recorded in the company’s shareholder register as of March 31 of each year, who continuously hold 1,000 shares (10 units) or more of the company’s stock for at least one year.
- The content of the shareholder benefit varies based on the number of shares held: a product worth 5,000 yen for 1,000 to 4,999 shares, and a product worth 10,000 yen for 5,000 shares or more.
- The program will be implemented once a year, with March 31, 2027, as the first record date.
- For the first record date, a transitional measure will apply to shareholders who were recorded in ASNOVA Co., Ltd.’s shareholder register as of September 30, 2026, holding 500 or more shares at that date, and continuously holding 1,000 or more shares of the company as of March 31, 2027, exempting them from the one-year continuous holding requirement.
🤖 AI Perspective
This new shareholder benefit program aims to communicate the group’s values and future vision while strengthening relationships with long-term shareholders. The one-year continuous holding requirement may suggest a focus on fostering a stable shareholder base. The transitional measure for the first record date appears to be a consideration for shareholders of the former ASNOVA Co., Ltd. following the transition to a holding company structure.
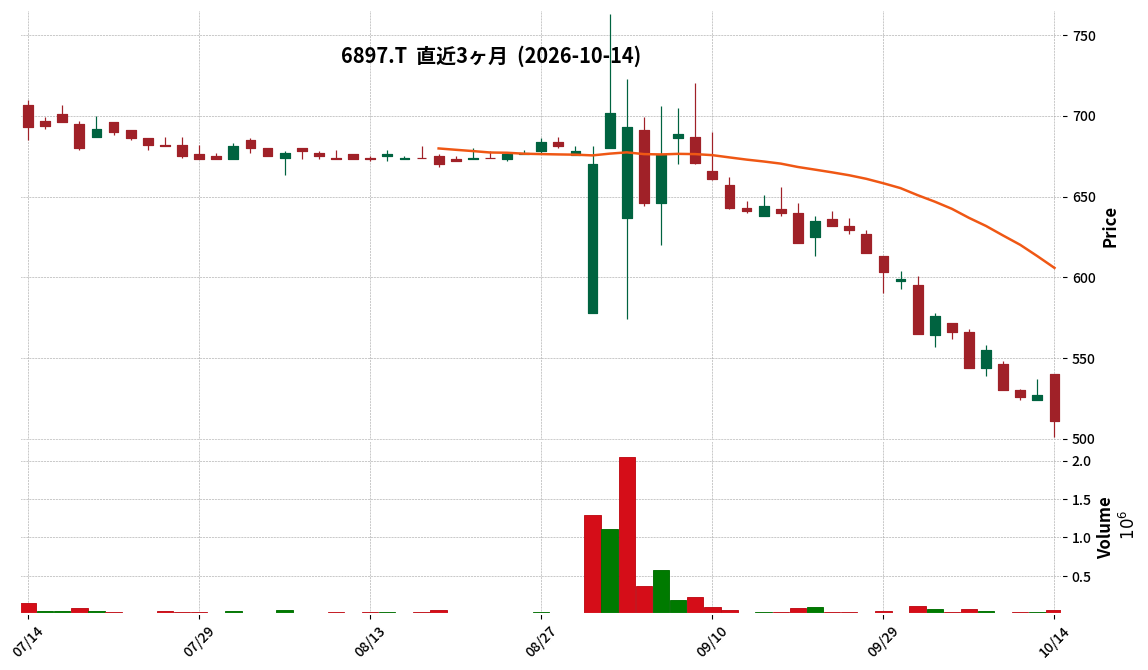
6897|ツインバード
511.0
▼ -3.04%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Twinbird Corporation announced its financial results for the second quarter (interim period) of the fiscal year ending February 2027 (March 1, 2026 – August 31, 2026).
- During this interim period, net sales were JPY 4,677 million, representing a 10.1% increase compared to the same period last year.
- Operating income was JPY 116 million (compared to an operating loss of JPY 399 million in the prior year), and ordinary income was JPY 108 million (compared to an ordinary loss of JPY 429 million in the prior year), both turning profitable.
- Net income for the interim period was JPY 32 million (compared to a net loss of JPY 432 million in the prior year), marking the first profit for an interim accounting period in 5 years.
- The Home Appliances business recorded sales of JPY 4,482 million (up 9.5% YoY) and segment profit of JPY 463 million (compared to a segment loss of JPY 8 million in the prior year). The FPSC business saw sales of JPY 194 million (up JPY 37 million YoY) and segment profit of JPY 53 million (up JPY 39 million YoY), achieving increased sales and profit.
🤖 AI Perspective
Twinbird’s Q2 FY2027 results show a significant turnaround, with operating, ordinary, and interim net income all shifting from losses to profits, and interim net income reaching a five-year high. This performance may suggest that the company’s strategic reforms, including the expansion of its B2B business, a shift towards higher-profitability business structures, and optimization of fixed and variable costs, are yielding positive results. Investors may also note the impact of gains from the sale of investment securities and expenses related to the tender offer on the interim net income figure.
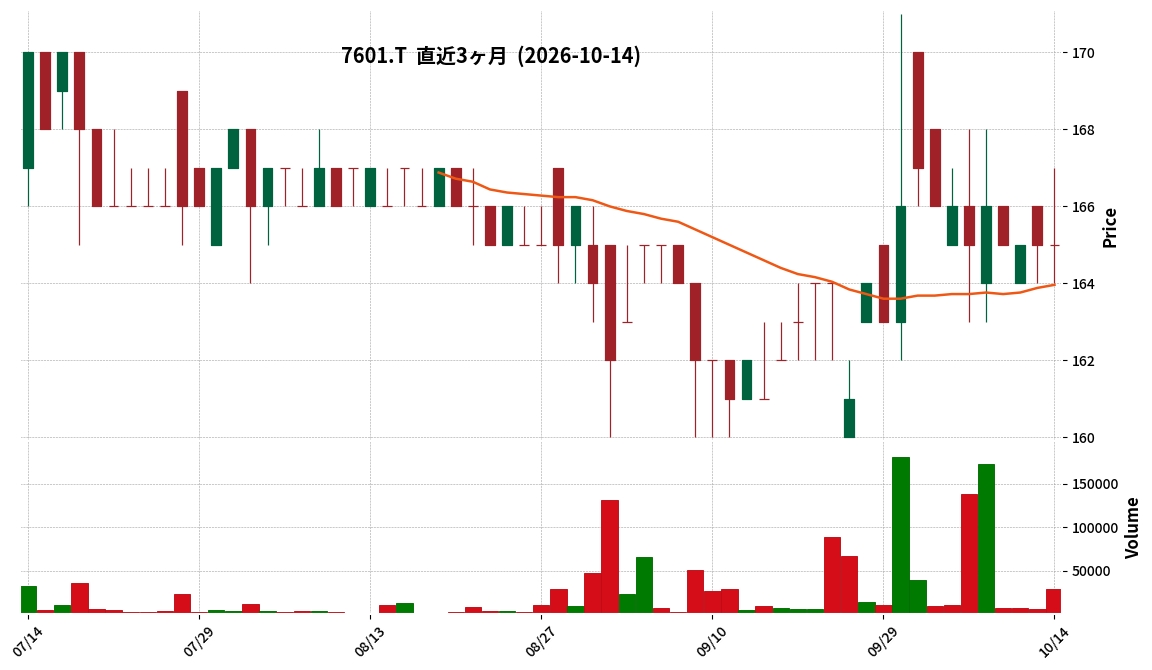
7601|ポプラ
165.0
▲ +0.00%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Poplar Co., Ltd. announced its consolidated financial results for the second quarter (interim) of the fiscal year ending February 2027, covering the period from March 1, 2026, to August 31, 2026.
- Total operating revenue for the consolidated interim period was ¥5,956 million, representing a 0.0% decrease compared to the same period in the previous year.
- Operating profit was ¥199 million (down 12.0% year-on-year), ordinary profit was ¥201 million (down 17.5% year-on-year), and net income attributable to owners of the parent was ¥143 million (down 18.9% year-on-year).
- By segment, the Smart Store segment reported total operating revenue of ¥2,566 million (down 0.9% year-on-year) and an operating loss of ¥158 million (compared to an operating loss of ¥123 million in the prior year’s interim period).
- The Lawson-Poplar segment reported total operating revenue of ¥3,055 million (up 1.3% year-on-year) and operating profit of ¥538 million (up 3% year-on-year).
🤖 AI Perspective
The interim results show that while total operating revenue remained almost flat year-on-year, operating profit, ordinary profit, and net income all declined. A notable point is the divergent performance between segments, with the Lawson-Poplar segment achieving increased revenue and profit, while the Smart Store segment experienced decreased revenue and an expanded operating loss. The ongoing challenges of rising raw material and energy costs, coupled with persistent consumer price sensitivity, suggest that the impact of the company’s various store strategies and cost control efforts on each business segment will be worth monitoring.
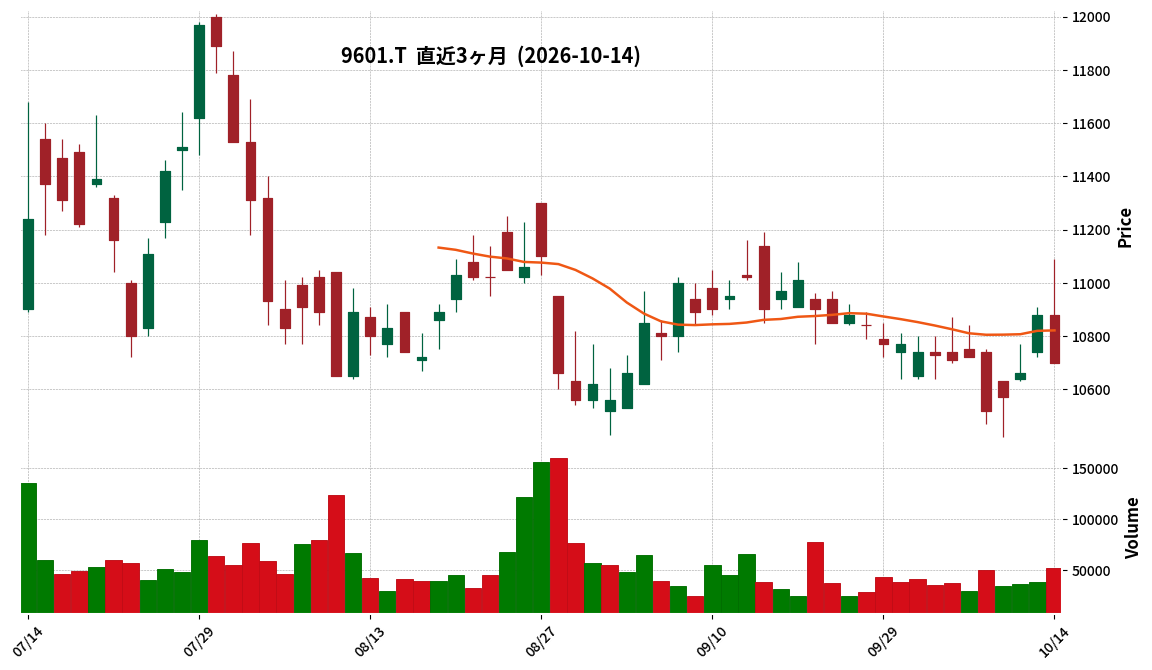
9601|松竹
10700.0
▼ -1.65%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Shochiku Co., Ltd. has announced its consolidated financial results for the second quarter (interim period) of the fiscal year ending February 2027.
- Consolidated cumulative performance shows revenue of ¥48,921 million (down 1.4% from the prior interim period), operating profit of ¥3,450 million (down 18.8%), and ordinary profit of ¥3,730 million (down 14.5%).
- Net profit attributable to parent shareholders was ¥736 million, representing an 82.1% decrease compared to the prior interim period.
- By segment, the Film and Video Business reported revenue of ¥25,652 million (down 8.4% year-on-year) and segment profit of ¥558 million (down 78.3%).
- In the Theater Business, performances at Kabuki-za, Shinbashi Enbujo, and Minamiza achieved favorable results, while Osaka Shochikuza closed in May.
- The full-year consolidated performance forecast remains unchanged from the latest public forecast, projecting revenue of ¥100,000 million, operating profit of ¥3,700 million, ordinary profit of ¥3,500 million, and net profit attributable to parent shareholders of ¥2,200 million.
🤖 AI Perspective
Shochiku’s Q2 FY2027 results indicate a slight decrease in revenue but a significant decline in net profit attributable to parent shareholders, primarily driven by the decrease in revenue and profit within the Film and Video business segment. Conversely, the Theater business demonstrated resilience, suggesting a dynamic interplay between the company’s various entertainment divisions. Investors may find it worthwhile to monitor the performance trends across these segments to understand future profitability drivers.
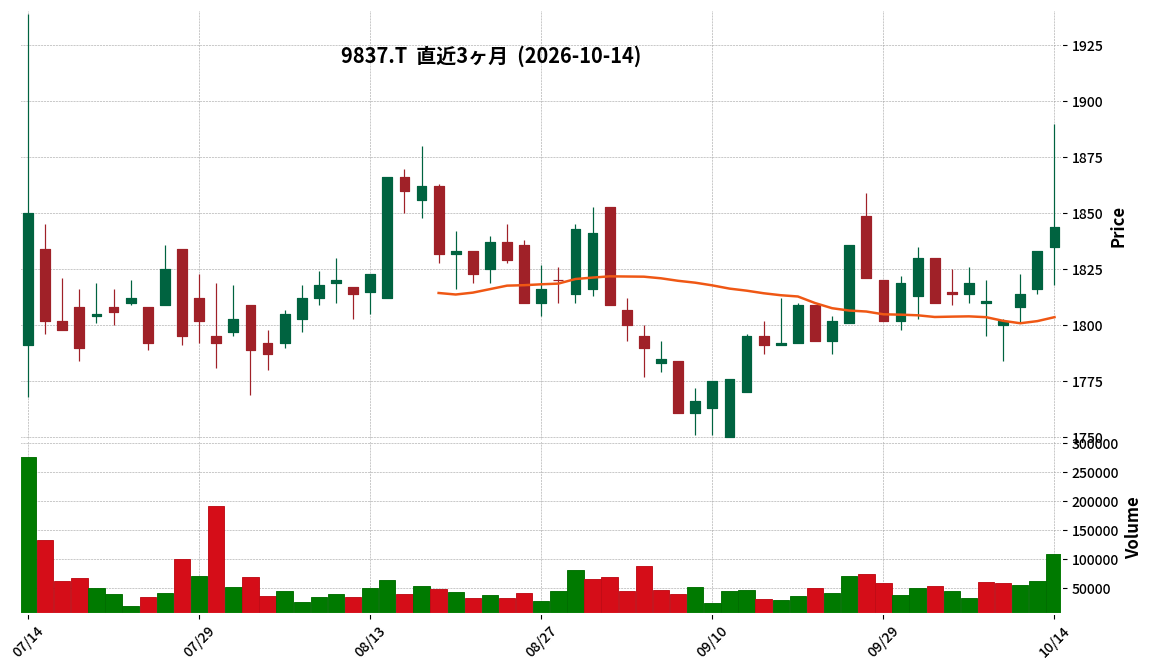
9837|モリト
1844.0
▲ +0.60%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Morito’s consolidated net sales for the third quarter of FY2026 (December 1, 2025 – August 31, 2026) were ¥49.305 billion, a 21.5% increase year-on-year.
- Operating profit was ¥2.917 billion (22.7% increase YoY), and ordinary profit was ¥3.109 billion (17.7% increase YoY).
- Net profit attributable to owners of the parent decreased by 21.6% year-on-year to ¥2.366 billion.
- The full-year consolidated earnings forecast has been revised, projecting net sales of ¥66.000 billion (16.1% increase YoY) and net profit attributable to owners of the parent of ¥3.050 billion (4.6% increase YoY).
- During the current consolidated cumulative period, Kusanaga Seisakusho Co., Ltd. was newly included in the scope of consolidation.
🤖 AI Perspective
Morito’s Q3 FY2026 results show robust growth in both net sales and operating profit, which may suggest positive contributions from newly consolidated companies and strong business segments. However, the decrease in net profit attributable to owners of the parent is worth monitoring, as it could indicate one-off factors or the impact of finalized accounting treatments. The upward revision of the full-year earnings forecast suggests management’s confidence in future performance.
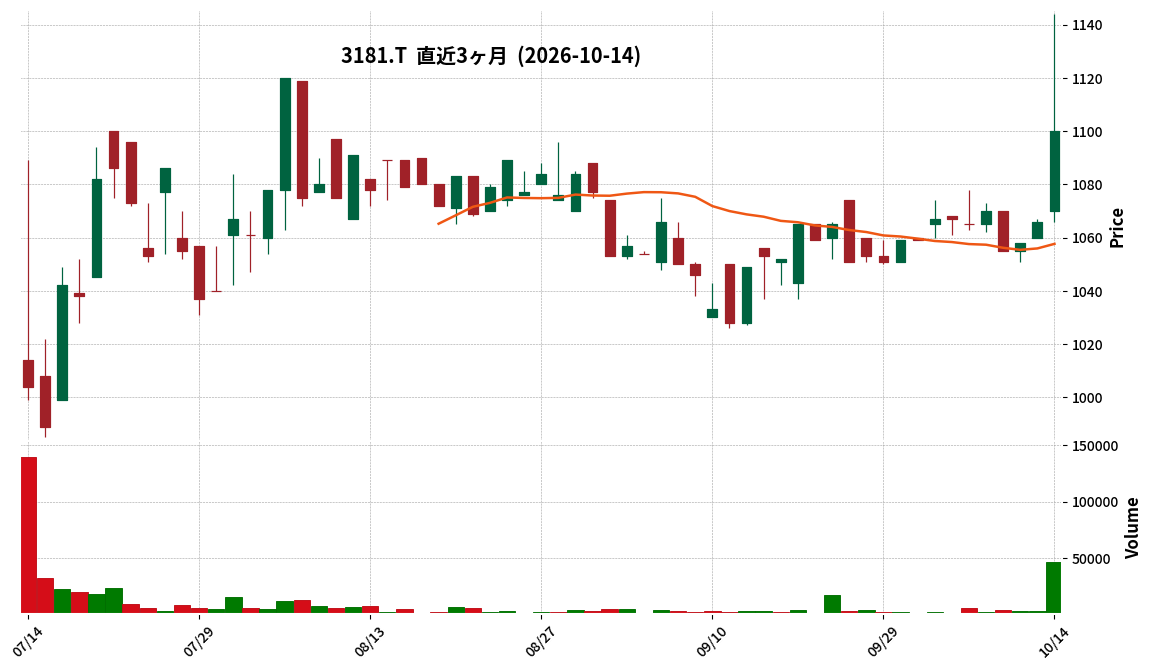
3181|買取王国
1100.0
▲ +3.19%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- For the second quarter (interim period) of the fiscal year ending February 2027, net sales reached 4,811 million yen, marking a 9.5% increase compared to the prior interim period.
- Operating profit for the same interim period was 289 million yen (up 63.0%), ordinary profit was 306 million yen (up 54.5%), and interim net profit was 219 million yen (up 70.7%).
- The strong performance was driven by robust sales of key merchandise categories including fashion, hobbies, and tools, along with reductions in general expenses.
- The company recorded a special gain of 21 million yen from the transfer of goodwill.
- The full-year forecast for the fiscal year ending February 2027 (net sales 10,012 million yen, operating profit 600 million yen, ordinary profit 610 million yen, net profit 403 million yen) remains unchanged.
🤖 AI Perspective
Kaitori Oukoku delivered a strong performance for the first half of FY2027, with significant increases across sales and all profit metrics compared to the previous year. This suggests that the company’s strategic initiatives, such as optimizing store operations and strengthening procurement, are effectively capitalizing on the expanding reuse market. The decision to maintain the full-year forecast indicates management’s confidence in achieving planned profitability improvements and investment returns in the latter half of the fiscal year.
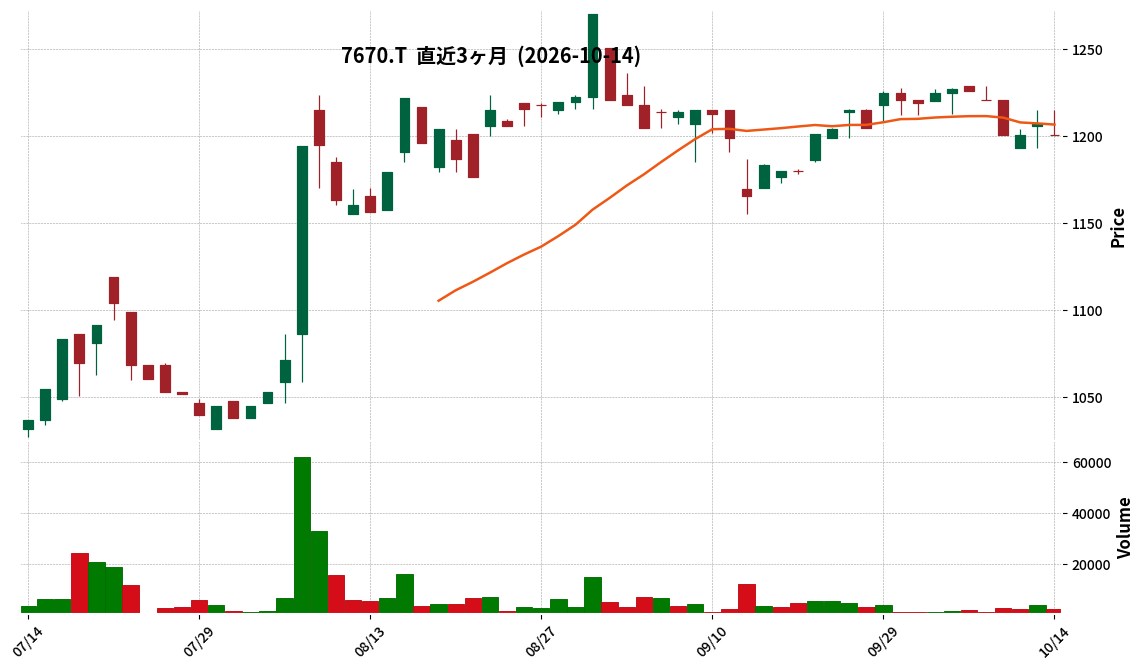
7670|オーウエル
1201.0
▼ -0.50%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- OWEL Corporation’s Board of Directors resolved on October 14, 2026, to absorb its wholly-owned subsidiary, Meihou Shoji Co., Ltd.
- The effective date of the merger is scheduled for April 1, 2027.
- OWEL will be the surviving company in this absorption-type merger, and Meihou Shoji will be dissolved.
- As this is a simple merger involving a wholly-owned subsidiary, no shares or money will be allotted.
- The purpose of the merger is to expand the coating-related business as part of the mid-term management plan “MAP24-26,” enhance value for Meihou Shoji’s customers, and streamline management resources.
- The company stated that the impact of this merger on consolidated business performance will be minor.
🤖 AI Perspective
This absorption merger can be seen as a strategic move by OWEL Corporation to expand its business domain and improve management efficiency, aligning with its “MAP24-26” mid-term management plan. By merging Meihou Shoji, its wholly-owned subsidiary, OWEL may aim to create synergies in the paint sales business and reduce costs through the centralization of administrative functions. While the impact on consolidated results is stated to be minor, this action could potentially contribute to strengthening the company’s business foundation over the long term.
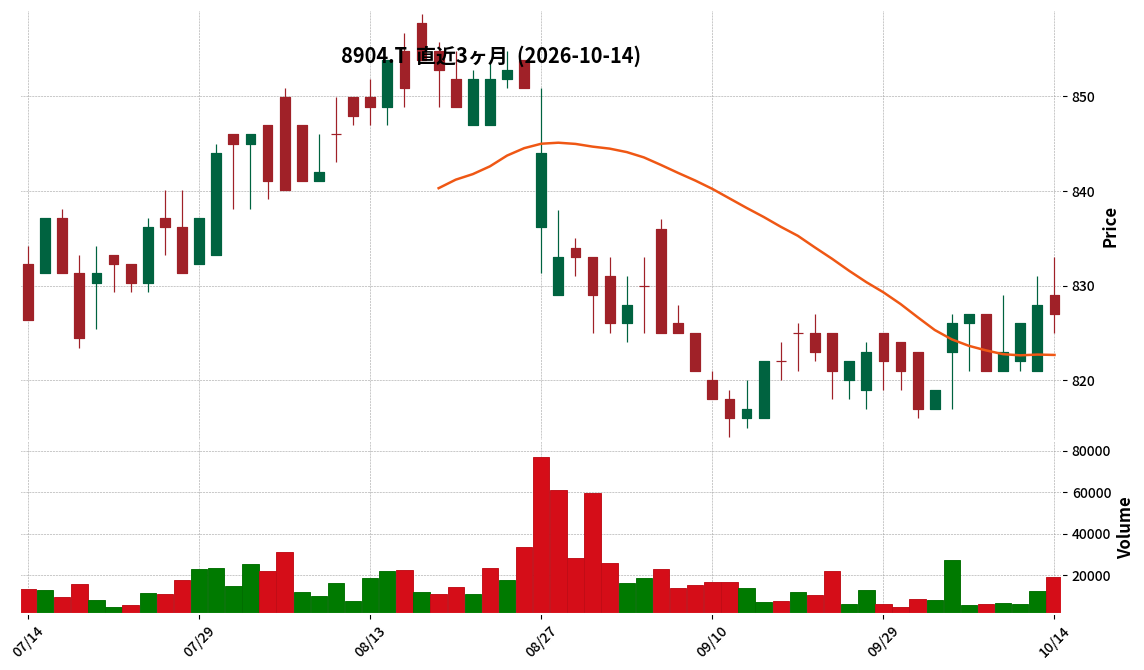
8904|AVANTIA
827.0
▼ -0.12%
📎 Source:AVANTIA Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- For the fiscal year ended August 2026, AVANTIA reported net sales of ¥67,888 million (down 2.0% year-on-year), operating profit of ¥2,008 million (up 52.9% year-on-year), and net profit attributable to owners of the parent of ¥1,423 million (up 122.6% year-on-year).
- The Condominium/Housing Sales segment’s net sales were ¥48,973 million (up 2.3% year-on-year), with operating profit reaching ¥1,161 million (compared to a loss of ¥11 million in the previous fiscal year).
- The gross profit margin for the detached housing business improved from 11.4% in FY2025/8 to 14.7% in FY2026/8.
- The Real Estate Distribution business recorded net sales of ¥9,947 million (down 20.7% year-on-year) and operating profit of ¥112 million (down 85.4% year-on-year).
- The Contracting business saw net sales of ¥6,632 million (down 6.3% year-on-year) and operating profit of ¥168 million (down 25.7% year-on-year), impacted by business reorganization aimed at group management efficiency.
🤖 AI Perspective
Despite a slight decrease in overall revenue, the significant surge in operating and net profits suggests a successful pivot towards higher-margin activities, particularly within the detached housing sector of the Condominium/Housing Sales segment. The improved profitability, even with challenges in real estate distribution and contracting, indicates effective cost management and strategic focus on core strengths. Investors may want to monitor how the company navigates ongoing market competition in real estate distribution and further integrates its contracting business for future synergy.
Disclaimer: This article is for informational purposes only and does not constitute investment advice.
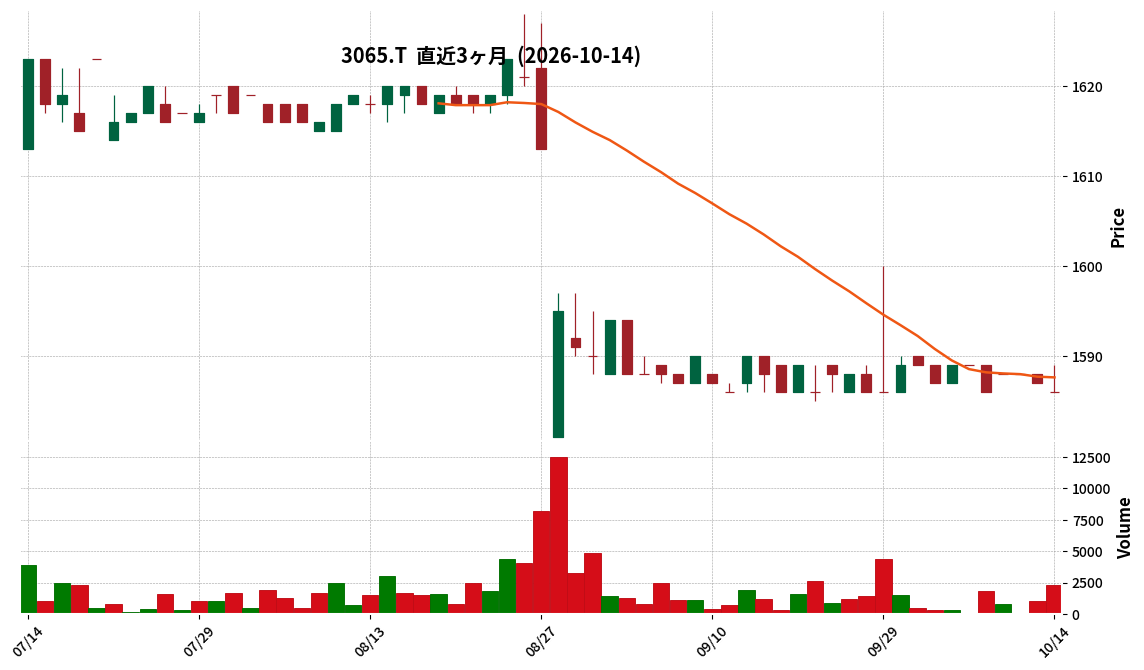
3065|ライフフーズ
1586.0
▼ -0.06%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Life Foods announced its financial results for the second quarter (interim period) of the fiscal year ending February 2027.
- Interim sales totaled ¥4,662,053 thousand, a 5.6% decrease compared to the same period in the previous year.
- Operating profit was ¥54,152 thousand (down 63.7% year-on-year), ordinary profit was ¥81,227 thousand (down 52.1%), and interim net profit was ¥39,613 thousand (down 68.3%).
- The equity ratio at the end of the interim accounting period improved to 47.2% (from 43.6% at the end of the previous fiscal year).
- The full-year forecast has been revised, anticipating sales of ¥9,439,246 thousand (down 1.8% year-on-year), operating profit of ¥25,237 thousand (down 71.2%), ordinary profit of ¥71,727 thousand (down 44.2%), and a net loss of ¥11,986 thousand (compared to a net profit of ¥35,783 thousand in the previous fiscal year).
🤖 AI Perspective
Life Foods’ Q2 FY2027 results show a significant year-on-year decline in both revenue and profit metrics. This performance may be attributed to the challenging operating environment for the restaurant industry, including rising raw material costs, high energy expenses, and increased labor costs. Despite the profit declines, the improvement in the equity ratio could indicate efforts to strengthen the company’s financial position. The revised full-year forecast to a net loss suggests ongoing operational challenges that warrant monitoring.
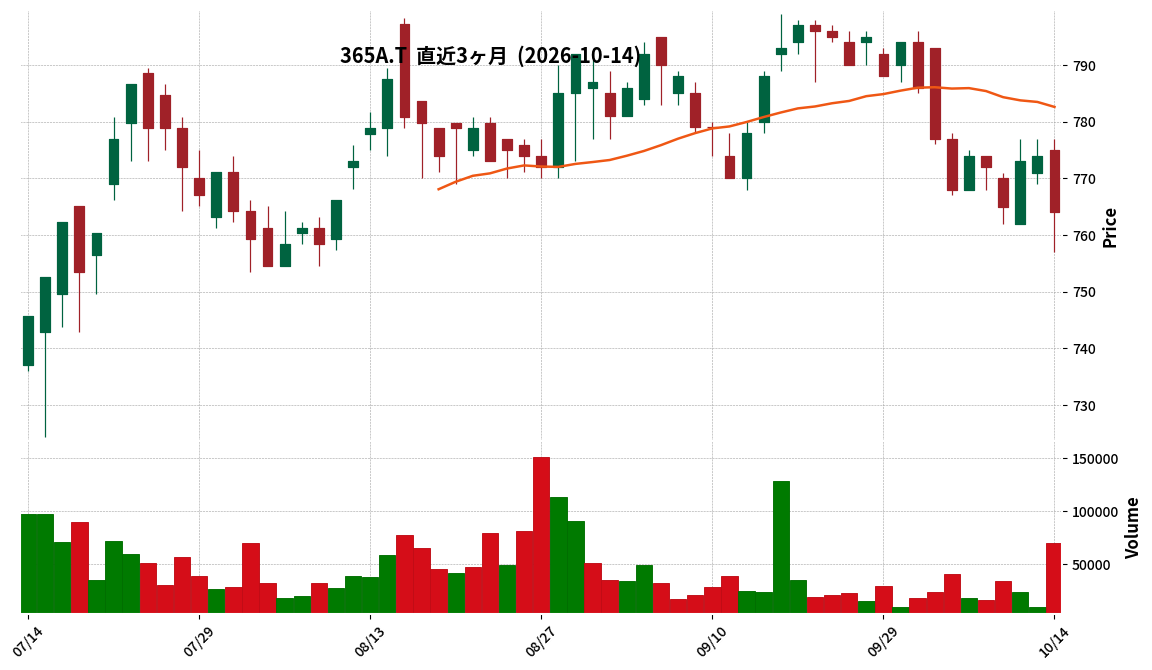
365A|伊澤タオル
764.0
▼ -1.29%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Izawa Towel Co., Ltd. has released its financial results briefing material for the second quarter of the fiscal year ending February 2027 (March 1, 2026 – August 31, 2026).
- Consolidated net sales for Q2 FY2027 cumulative period reached ¥5,380 million, with rebate-controlled net sales at ¥5,652 million, marking a new record high for an interim period.
- Consolidated operating profit stood at ¥52 million, and net income attributable to owners of the parent for the interim period was ¥174 million.
- The company recorded ¥277 million in foreign exchange gains, resulting in a consolidated ordinary profit of ¥308 million.
- An interim dividend of ¥21 per share was declared, with an annual dividend forecast of ¥42 (¥21 interim, ¥21 year-end), targeting a DOE of 10%.
- Izawa Towel decided to voluntarily adopt IFRS from the fiscal year ending February 2029 and consolidated two subsidiaries in the U.S. and Hong Kong starting from the second quarter.
🤖 AI Perspective
The record-high interim sales suggest robust top-line growth, while the impact of yen depreciation on procurement costs appears to have pressured operating profit. The significant foreign exchange gains bolstering ordinary profit highlight the material influence of currency fluctuations on the company’s financial performance. The decision to adopt IFRS and consolidate subsidiaries could indicate a strategic move towards enhanced financial reporting transparency and strengthened group governance.
5250|GMOプライム
1050.0
▲ +0.38%
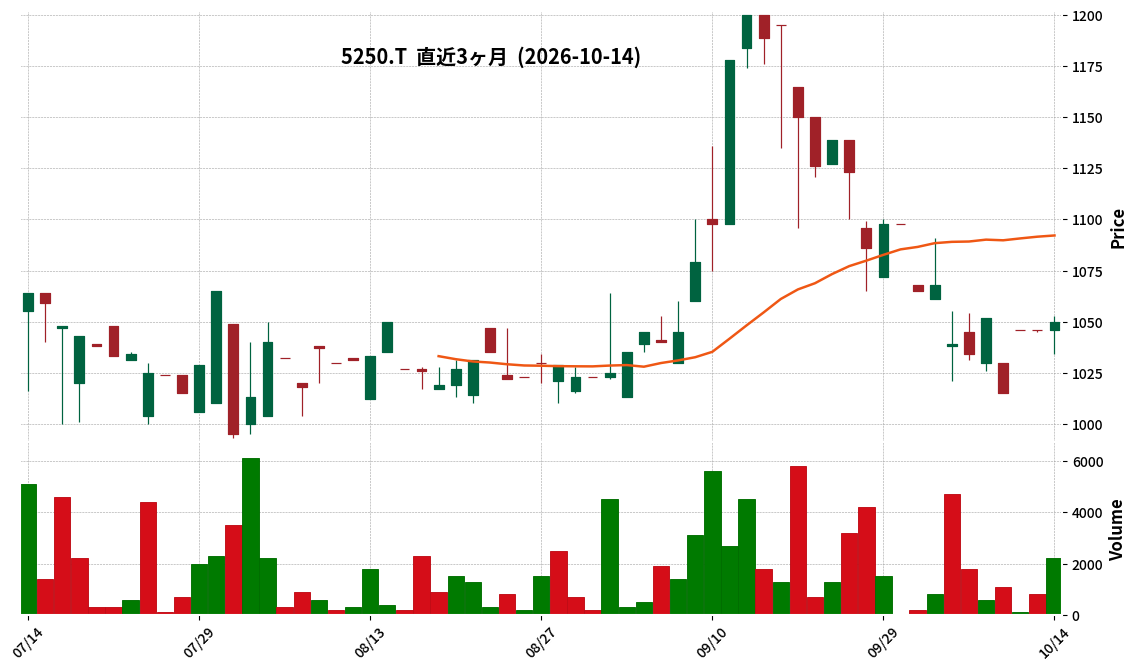
📎 Source:GMOプライム Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- GMO Prime’s consolidated net sales for the third quarter of the fiscal year ending December 2026 (December 1, 2025, to August 31, 2026) were JPY 711,458 thousand, an increase of 10.9% year-over-year.
- During the same period, operating profit was JPY 76,075 thousand (down 25.8% YoY), ordinary profit was JPY 80,288 thousand (down 22.5% YoY), and profit attributable to owners of parent was JPY 58,554 thousand (down 19.4% YoY).
- The full-year consolidated earnings forecast for the fiscal year ending December 2026 remains unchanged from the most recently announced forecast: net sales of JPY 1,124 million, operating profit of JPY 70 million, ordinary profit of JPY 72 million, and profit attributable to owners of parent of JPY 51 million.
- A new “AI Business” was launched during the third consolidated quarter, but due to its immateriality, segment-specific disclosures have been omitted.
- The equity ratio at the end of the third quarter of the fiscal year ending December 2026 was 91.4% (compared to 88.5% at the end of November 2025).
🤖 AI Perspective
GMO Prime’s Q3 FY2026 results show a year-over-year increase in revenue but a decline in profits. This trend is attributed to investments in mid-to-long term growth, increased outsourcing costs, and higher personnel expenses, according to the disclosed information. The launch of a new “AI Business” segment is also noteworthy, suggesting potential shifts in the company’s business portfolio going forward, which investors may find worth monitoring.
138A|G-光フードサービス
3120.0
▼ -0.95%
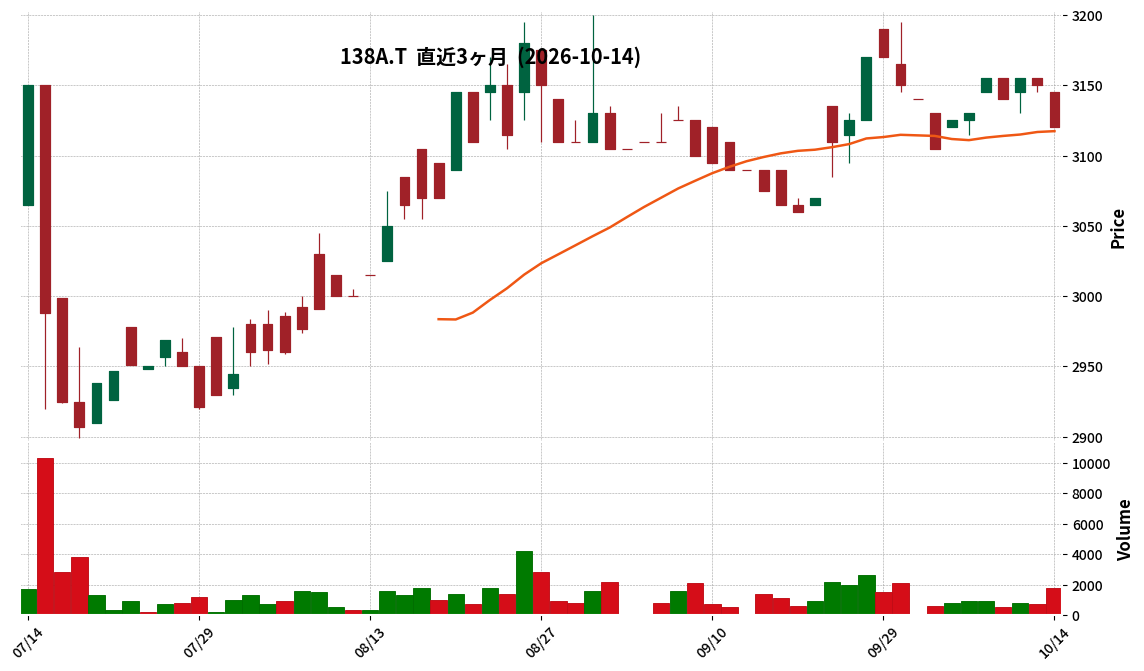
📎 Source:G-光フードサービス Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- G-Hikari Food Service announced its financial results for the third quarter of FY2026 (December 1, 2025, to August 31, 2026).
- Cumulative sales for the period reached ¥2,393 million, an 11.9% increase year-over-year. Operating profit was ¥209 million (up 19.4%), ordinary profit was ¥207 million (up 20.8%), and quarterly net profit was ¥139 million (up 18.7%).
- As of the end of the third quarter, total assets stood at ¥2,731 million, net assets at ¥1,410 million, and the equity ratio was 51.6%.
- During the cumulative third quarter, the company opened 1 new directly managed store and 1 new franchise store, while closing 2 directly managed stores and 1 franchise store. The total number of stores at the end of the period was 67 (including 16 franchise stores).
- The full-year financial forecast and dividend forecast (year-end dividend of ¥48.00) for FY2026 remain unchanged from the most recently published projections.
🤖 AI Perspective
G-Hikari Food Service reported significant double-digit growth in both sales and profits for the third quarter, demonstrating resilience within a challenging restaurant industry environment. This performance may be attributed to the company’s efforts in store expansion and continuous improvement in Quality, Service, and Cleanliness (QSC). The increase in total assets and equity ratio could indicate a strengthening of its financial position, which is worth monitoring for investors.
1434|JESCO HD
1682.0
▲ +3.76%
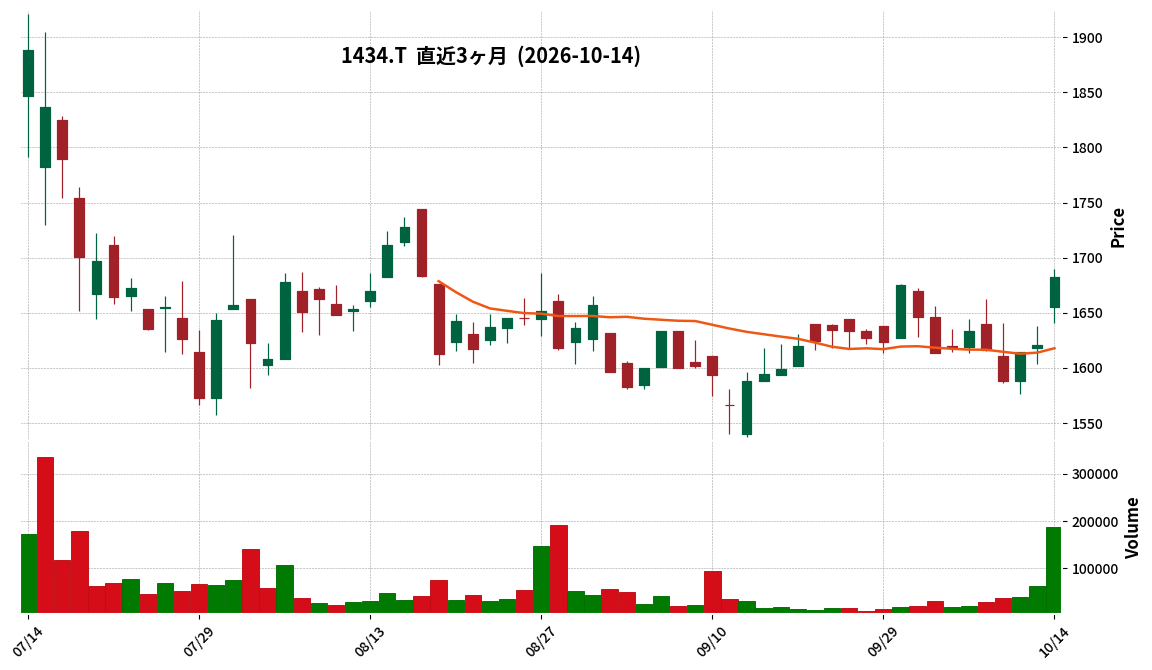
📎 Source:JESCO HD Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- JESCO HD’s consolidated results for the fiscal year ended August 2026 show net sales of ¥18,063 million, a 5.3% decrease compared to the previous fiscal year.
- Operating profit was ¥1,927 million (up 11.9% year-on-year), ordinary profit was ¥1,929 million (up 14.0% year-on-year), and profit attributable to owners of parent was ¥1,209 million (up 12.4% year-on-year).
- Basic earnings per share stood at ¥174.06, an increase from ¥155.31 in the prior year.
- The annual dividend per share increased from ¥40.00 in August 2025 to ¥48.00 in August 2026.
- For the fiscal year ending August 2027, the company forecasts consolidated net sales of ¥21,200 million (up 17.4% year-on-year), operating profit of ¥2,300 million (up 19.3% year-on-year), ordinary profit of ¥2,100 million (up 8.8% year-on-year), profit attributable to owners of parent of ¥1,350 million (up 11.6% year-on-year), and basic earnings per share of ¥194.01.
🤖 AI Perspective
Despite a decrease in net sales for FY2026, JESCO HD managed to secure increases in all profit metrics, which may suggest an improvement in profitability. The rise in basic EPS and the dividend increase could indicate a focus on shareholder returns. Furthermore, the robust guidance for FY2027, projecting double-digit growth in both sales and profits, might be interpreted as the company’s confidence in its business recovery and expansion plans.
Disclaimer: This article is for informational purposes only and does not constitute investment advice.
156A|G-マテリアルG
883.0
▲ +1.38%
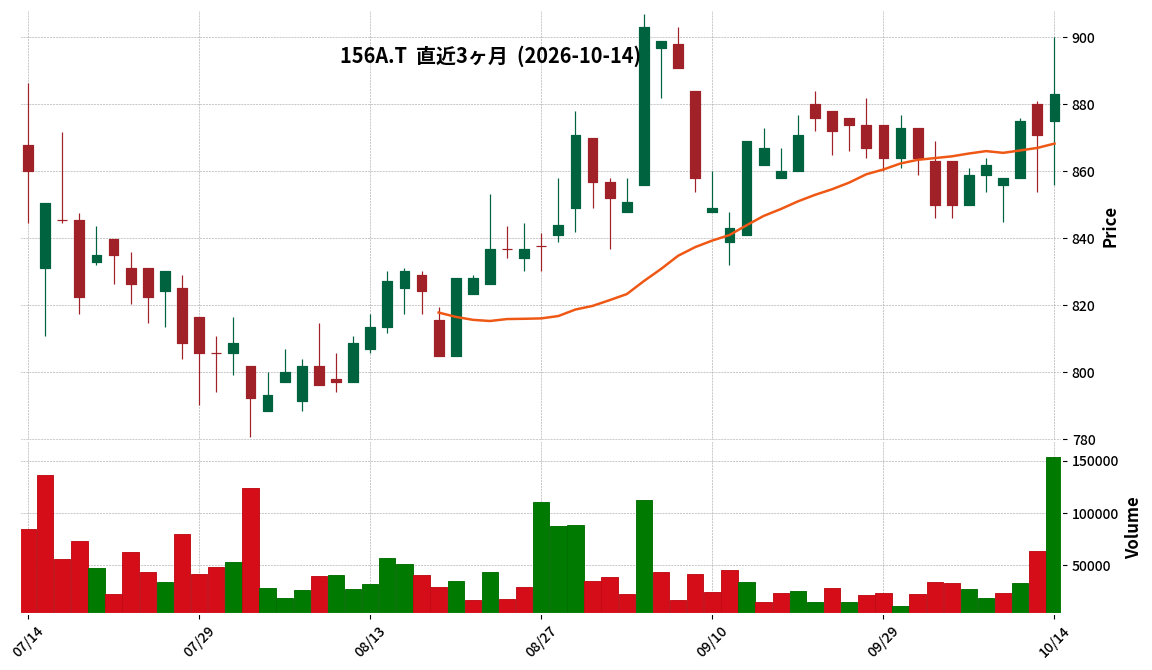
📎 Source:G-マテリアルG Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- G-Material G reported consolidated net sales of ¥8,714 million for the fiscal year ended August 2026, marking a 38.6% increase from the previous period.
- Operating profit reached ¥1,162 million (+39.7% year-on-year), and ordinary profit was ¥1,114 million (+47.8% year-on-year).
- Net profit attributable to owners of the parent company amounted to ¥656 million, a 40.1% increase compared to the prior year.
- Basic earnings per share for FY2026 were ¥69.00, and diluted earnings per share were ¥68.08.
- For the fiscal year ending August 2027, the company forecasts consolidated net sales of ¥9,601 million (+10.2% year-on-year), operating profit of ¥1,370 million (+17.8% year-on-year), and net profit attributable to owners of the parent company of ¥732 million (+11.5% year-on-year).
- The company voluntarily adopted International Financial Reporting Standards (IFRS) from FY2026. Under IFRS, the forecast for FY2027 full-year net sales is ¥9,601 million, operating profit is ¥1,509 million, and profit attributable to owners of the parent is ¥910 million.
🤖 AI Perspective
G-Material G’s robust growth across key profit metrics for FY2026 suggests that its strategies, including aggressive talent acquisition and M&A, may be driving significant business expansion. The positive outlook for FY2027, projecting continued revenue and profit increases, indicates the company’s confidence in its ongoing business development and profitability. The voluntary adoption of IFRS could enhance the comparability of the company’s financial results with international peers.
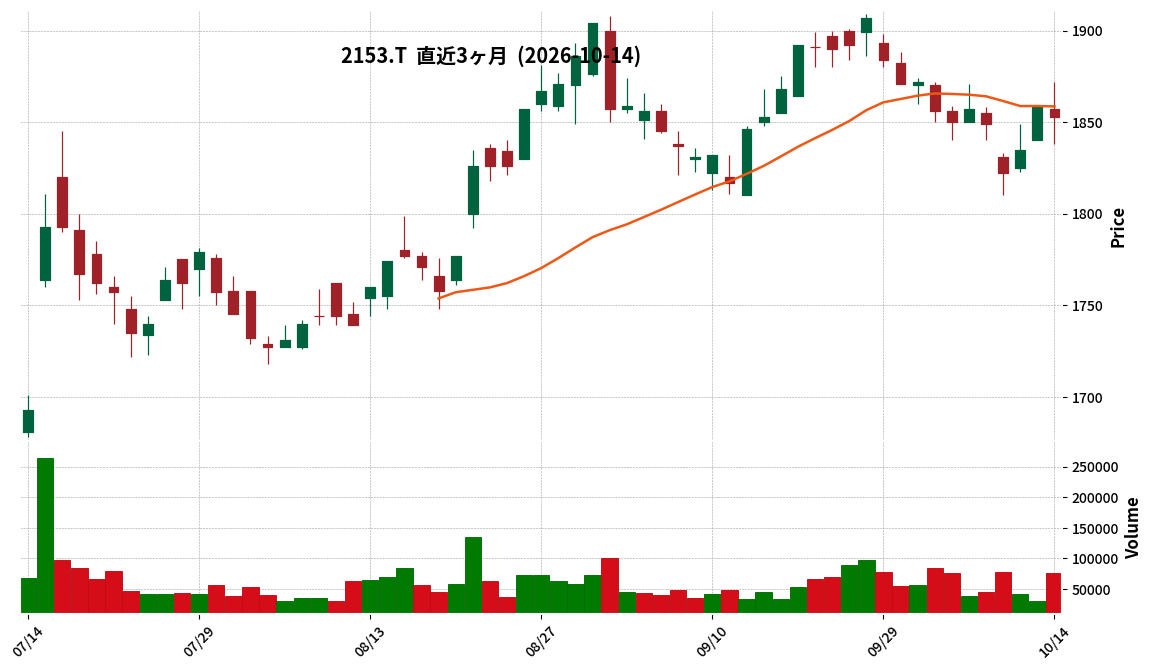
2153|イージェイHD
1853.0
▼ -0.27%
📎 Source:イージェイHD Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- EJ Holdings announced its consolidated financial results for the first quarter of the fiscal year ending May 2027.
- For the cumulative first quarter, net sales totaled ¥5,072 million, an increase of 18.3% compared to the same period of the previous year.
- The company reported an operating loss of ¥1,192 million (compared to a loss of ¥1,525 million in the prior year’s first quarter) and an ordinary loss of ¥1,146 million (compared to a loss of ¥1,466 million).
- Net loss attributable to owners of parent was ¥236 million (compared to a loss of ¥1,130 million in the prior year’s first quarter).
- The full-year consolidated earnings forecast and dividend forecast remain unchanged from the most recently published figures.
🤖 AI Perspective
EJ Holdings typically posts losses in the first quarter due to the nature of the construction consulting business, where sales are concentrated towards the fiscal year-end. This quarter’s net loss showed a significant improvement year-over-year, which may suggest a positive impact from increased revenue. The reaffirmation of the full-year earnings forecast indicates the company believes its first-quarter performance is in line with its overall plan.
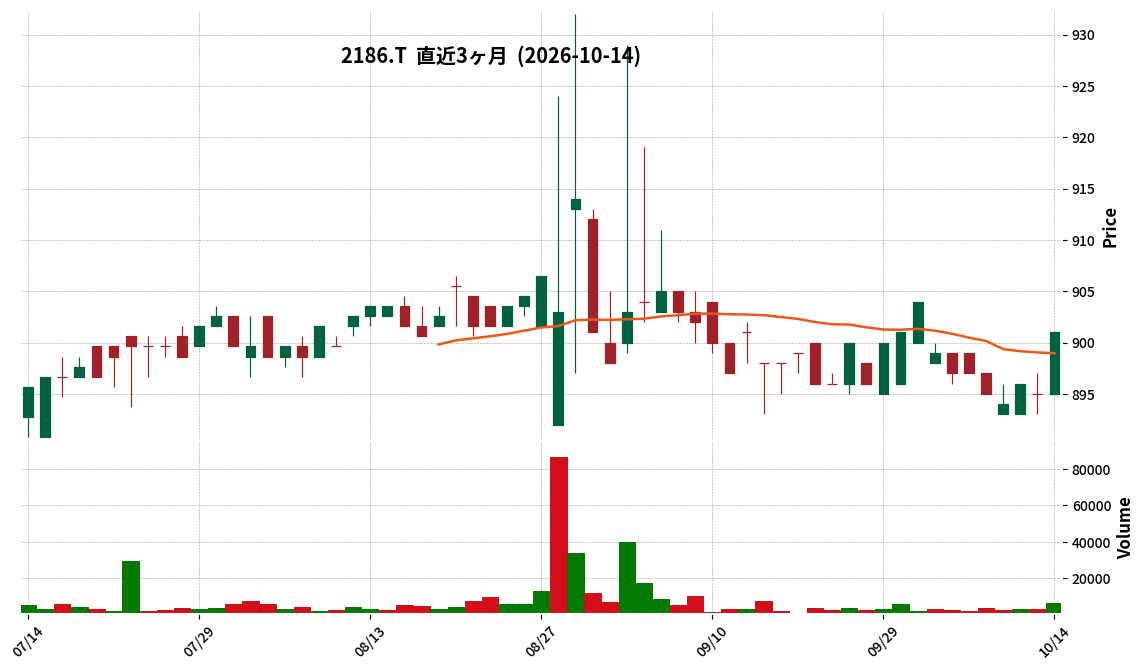
2186|ソーバル
901.0
▲ +0.67%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Sobal announced its consolidated financial results for the second quarter (interim period) of the fiscal year ending February 2027.
- Net sales reached ¥5,050 million, marking a 15.9% increase compared to the same interim period of the previous year.
- Operating profit was ¥394 million (+27.9% YoY), ordinary profit was ¥406 million (+29.7% YoY), and net profit attributable to owners of parent was ¥255 million (+22.5% YoY).
- Diluted interim net earnings per share stood at ¥32.42.
- As of the end of the interim period, total assets were ¥5,921 million, net assets were ¥4,662 million, and the equity ratio was 78.5%.
- The forecast for the annual dividend for the fiscal year ending February 2027 remains unchanged from the most recently published forecast, with an interim dividend of ¥16.50 and a year-end dividend of ¥16.50, totaling ¥33.00.
- The full-year consolidated earnings forecast also remains unchanged, with projected net sales of ¥10,000 million, operating profit of ¥650 million, ordinary profit of ¥670 million, net profit attributable to owners of parent of ¥420 million, and diluted net earnings per share of ¥53.39.
- Precise Inc. was newly included in the scope of consolidation during this interim period.
🤖 AI Perspective
Sobal’s interim results show increased sales and profits, with key profitability metrics surpassing the prior year. The growth in sales of the WEB/application and business system development segments, up approximately 23%, along with the resolution of a large unprofitable project and improved productivity through AI utilization, appear to have contributed to the performance. The reaffirmation of the full-year earnings forecast suggests the company views its progress as aligned with its plans.
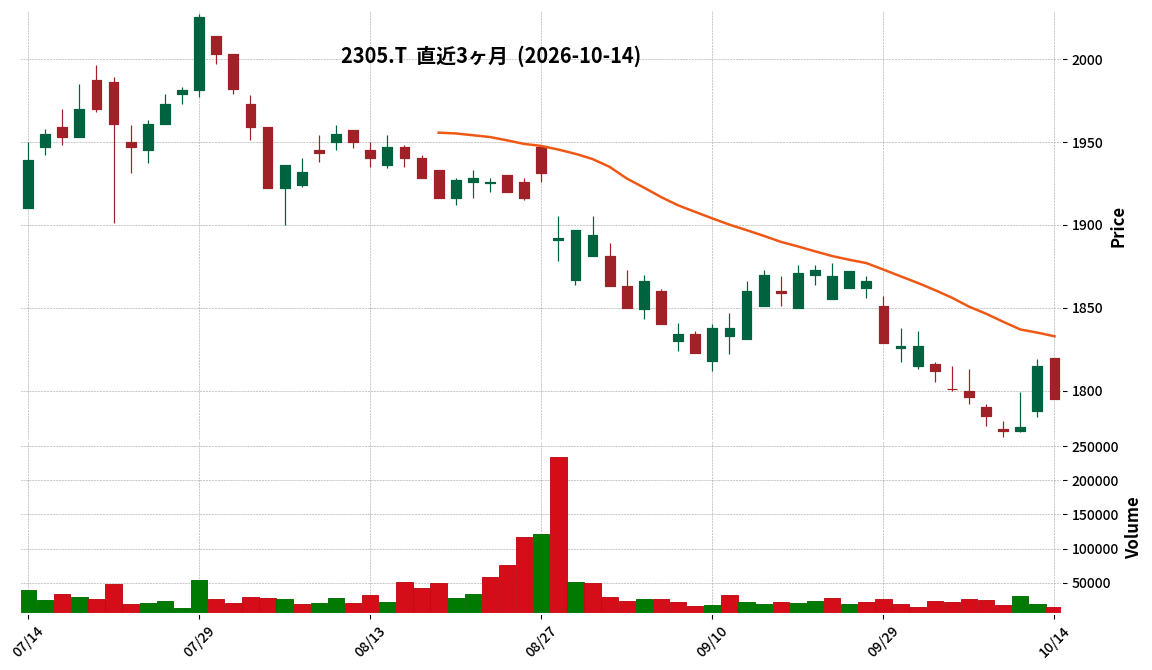
2305|スタジオアリス
1795.0
▼ -1.10%
📎 Source:スタジオアリス Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Studio Alice Co., Ltd. announced its consolidated financial results for the second quarter (interim) of the fiscal year ending February 2027.
- Net sales amounted to ¥14,521 million, an increase of 1.0% compared to the same period in the previous year.
- The company reported an operating income of ¥95 million (compared to an operating loss of ¥462 million in the prior year interim), an ordinary income of ¥174 million (compared to an ordinary loss of ¥434 million), and net income attributable to owners of the parent of ¥15 million (compared to a net loss of ¥379 million), showing a turnaround to profitability in all income categories.
- The Photography Business segment reported sales of ¥14,419 million (up 0.9% YoY) and a segment income of ¥92 million (compared to a segment loss of ¥460 million in the prior year interim).
- The Costume Manufacturing and Wholesale Business segment recorded sales of ¥686 million (down 5.4% YoY) and a segment income of ¥49 million (compared to a segment loss of ¥18 million in the prior year interim).
🤖 AI Perspective
Studio Alice’s interim results for FY2027 indicate a significant turnaround in profitability, with all key income metrics shifting from losses to gains despite only a marginal increase in net sales. The return to segment profitability in the core Photography Business may suggest that strategic initiatives are yielding positive results in terms of operational efficiency or customer engagement. While the Costume Manufacturing and Wholesale Business saw a decline in sales, its improved segment profit could indicate effective cost management.
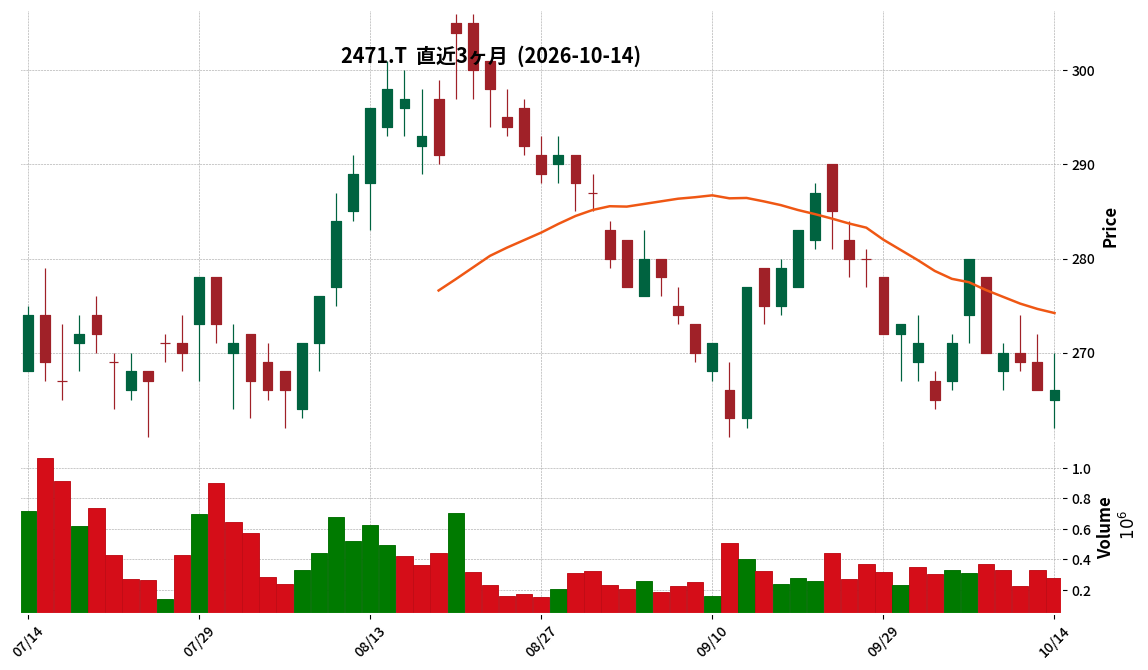
2471|エスプール
266.0
▲ +0.00%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Spool Inc. reported consolidated revenue of ¥19,118 million for the third quarter of fiscal year 2026 (cumulative), representing a 1.2% increase year-on-year.
- For the same period, operating profit was ¥1,068 million (down 20.3% year-on-year), pre-tax quarterly profit was ¥773 million (down 31.2%), and profit attributable to owners of the parent was ¥551 million (down 27.1%).
- The Business Solutions segment recorded revenue of ¥12,542 million (up 7.5% year-on-year) and operating profit of ¥2,279 million (up 2.2%).
- The Human Resources Solutions segment experienced a decrease in revenue during the period.
- There are no revisions to the full-year consolidated earnings forecast or the dividend forecast (year-end dividend of ¥10.00) from the most recently announced figures.
🤖 AI Perspective
While Spool Inc. achieved a revenue increase for the third quarter cumulative period, profits declined. This suggests that while the Business Solutions segment performed well with increased revenue and profit, the decline in the Human Resources Solutions segment and a negative impact from carbon credit sales in the environmental management support services may have offset overall profitability. The varying performance across business segments could be a key area for investors to monitor going forward.
Disclaimer: This article is for informational purposes only and does not constitute investment advice.
2683|UOGroup
991.0
▼ -0.10%
📎 Source:UOGroup Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- UOGroup announced its consolidated financial results for the second quarter (interim period: March 1, 2026, to August 31, 2026) of the fiscal year ending February 2027.
- Net sales were JPY 4,710 million (up 1.6% year-on-year), with an operating loss of JPY 65 million (compared to an operating loss of JPY 26 million in the prior interim period) and an ordinary loss of JPY 34 million (compared to an ordinary loss of JPY 30 million in the prior interim period). Net loss attributable to owners of the parent was JPY 33 million (compared to a net loss of JPY 27 million in the prior interim period).
- By segment, Fresh Fish Business sales were JPY 4,069 million (up 1.9% year-on-year), with segment profit of JPY 207 million (down 15.3%). Restaurant Business sales were JPY 433 million (down 2.7%), with segment profit of JPY 0 million (down 90.2%). Real Estate Business sales were JPY 227 million (up 4.3%), with segment profit of JPY 16 million (up 45.0%).
- During the interim consolidated accounting period, the group opened three new stores. Additionally, Uoya Co., Ltd., formerly a non-consolidated subsidiary, acquired the store business (“FOOD & TIME ISETAN YOKOHAMA Store” and “Kobe Hankyu Store”) and wholesale business from Uokin Co., Ltd., becoming a consolidated subsidiary as of August 1, 2026.
- The full-year consolidated earnings forecast for the fiscal year ending February 2027 remains unchanged from the most recently published forecast: net sales of JPY 9,500 million, operating profit of JPY 70 million, ordinary profit of JPY 70 million, and net profit attributable to owners of the parent of JPY 30 million.
🤖 AI Perspective
UOGroup’s interim results for FY2027/2 show increased sales, but also an expansion of operating and ordinary losses, which may suggest the impact of rising costs. The strategic moves of opening new stores and M&A could be interpreted as efforts to strengthen the future revenue base. With the full-year forecast remaining unchanged, investors might be looking for recovery in the second half of the fiscal year.
3045|カワサキ
1467.0
▲ +0.00%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Kawasaki Co., Ltd. announced its non-consolidated financial results for the fiscal year ended August 2026.
- For the fiscal year ended August 2026, net sales were ¥2,307 million (up 0.7% year-on-year), operating profit was ¥474 million (down 8.1% year-on-year), ordinary profit was ¥473 million (down 8.0% year-on-year), and net profit was ¥313 million (down 7.3% year-on-year).
- By segment, the apparel business recorded sales of ¥539 million (up 0.3% year-on-year) with an operating loss of ¥19 million. The rental and warehouse business reported sales of ¥1,404 million (up 0.2% year-on-year) with an operating profit of ¥555 million. The hotel business posted sales of ¥363 million (up 3.5% year-on-year) with an operating loss of ¥62 million.
- For the fiscal year ending August 2027, the company forecasts net sales of ¥2,340 million (up 1.4% year-on-year), operating profit of ¥419 million (down 11.4% year-on-year), ordinary profit of ¥419 million (down 11.5% year-on-year), and net profit of ¥270 million (down 13.7% year-on-year).
- The annual dividend for FY2026 (actual) and FY2027 (forecast) is ¥50.00 per share (interim ¥25.00, year-end ¥25.00).
🤖 AI Perspective
The FY2026 results show a slight increase in net sales but a decline in operating, ordinary, and net profits. Segment analysis indicates that while the rental and warehouse business is profitable, operating losses in the apparel and hotel businesses are impacting overall earnings. Given the projected decrease in profits for the next fiscal year, investors may focus on the company’s strategies for cost management and revenue improvement across its various business segments.
3075|銚子丸
1719.0
▲ +1.12%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Choushimaru announced its H1 FY2027 (ending February 2027) financial results.
- Net sales for the interim period were JPY 12,602 million, an 8.5% increase compared to the prior year’s interim period.
- Operating income reached JPY 1,297 million (+31.6% YoY), and ordinary income was JPY 1,330 million (+32.8% YoY).
- Interim net income totaled JPY 835 million, representing a 52.4% increase year-over-year.
- Diluted interim earnings per share stood at JPY 66.70.
- The company’s store count at the end of the interim accounting period was 92.
- The full-year forecast remains unchanged from the previous announcement, projecting net sales of JPY 25,300 million, operating income of JPY 1,880 million, ordinary income of JPY 1,930 million, and net income of JPY 1,220 million (EPS of JPY 97.62).
🤖 AI Perspective
Choushimaru’s H1 FY2027 results demonstrate strong growth across all key profitability metrics, with a notable increase in interim net income. This performance may suggest the positive impact of the company’s strategic initiatives, including enhancements to existing store formats, new store openings such as “Sushi Choushimaru Park City Nakano,” digital transformation efforts like the “En App” updates, human resource development, and expansion in overseas markets with a second store in the U.S. These factors could contribute to the sustained growth outlined in their unchanged full-year outlook.
3139|ラクト・ジャパン
3470.0
▼ -0.29%
📎 Source:ラクト・ジャパン Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Lacto Japan announced its consolidated financial results for the third quarter of the fiscal year ending November 2026 (December 1, 2025, to August 31, 2026).
- Net sales reached ¥144,886 million, marking a 5.4% increase compared to the same period of the previous year.
- Operating profit was ¥4,214 million (down 12.4% year-on-year), ordinary profit was ¥3,873 million (down 21.1%), and net profit attributable to owners of parent was ¥2,776 million (down 22.0%).
- Earnings per share for the quarter stood at ¥277.73.
- The full-year consolidated earnings forecast remains unchanged: net sales of ¥193,000 million (up 5.6% year-on-year), ordinary profit of ¥4,800 million (down 17.2%), and net profit attributable to owners of parent of ¥3,450 million (down 20.1%).
🤖 AI Perspective
While net sales showed an increase year-on-year, operating profit, ordinary profit, and net profit attributable to owners of parent all experienced double-digit declines. This could be attributed to the absence of a one-time extraordinary gain recorded in the previous year, as well as the combined effects of the international situation and the weak yen. However, it is notable that ordinary profit is trending above the initial forecast due to the delayed recording of expenses related to the new Singapore plant and the head office core system.
3280|エストラスト
910.0
▼ -0.66%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- ESTRUST Co., Ltd. announced its consolidated financial results for the second quarter of the fiscal year ending February 2027 (interim period: March 1, 2026 – August 31, 2026).
- Consolidated net sales amounted to JPY 6,133 million, representing a 58.3% decrease compared to the same interim period of the previous year.
- Consolidated operating profit was JPY 93 million, a 93.9% decrease from the prior year’s interim period.
- Consolidated ordinary loss was JPY 25 million (compared to a profit of JPY 1,511 million in the previous interim period), and interim net loss attributable to owners of the parent was JPY 19 million (compared to a profit of JPY 1,046 million in the previous interim period).
- Interim net loss per share was JPY △3.24.
- The annual dividend forecast remains unchanged at JPY 34.00 (JPY 17.00 for Q2-end and JPY 17.00 for year-end).
- The full-year consolidated earnings forecast also remains unchanged: net sales JPY 21,000 million, operating profit JPY 1,600 million, ordinary profit JPY 1,400 million, net profit attributable to owners of the parent JPY 1,000 million, and basic earnings per share JPY 164.19.
🤖 AI Perspective
The significant decline in sales and profit during the interim period appears to be primarily driven by a substantial reduction in condominium deliveries within the core real estate sales business. Conversely, the real estate rental and “other” segments demonstrated increased revenues and profits, which may suggest a degree of stability from portfolio diversification. The company’s decision to maintain its full-year earnings forecast indicates an expectation for a stronger performance in the second half of the fiscal year, particularly in its primary business.
3377|バイク王
409.0
▲ +0.74%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Bike O & Company resolved to change its shareholder benefits program at a Board of Directors meeting held on October 14, 2026.
- The previous program offered shareholders holding 100 shares or more a ¥30,000 discount voucher for the purchase of motorcycles (126cc or above) and a ¥10,000 discount voucher for a maintenance package (the latter could not be used independently).
- The revised program will provide “selectable digital gifts” based on the number of shares held: ¥3,000 for 500 to less than 1,000 shares, and ¥10,000 for 1,000 shares or more.
- The digital gifts offer choices such as PayPay Money Light, Amazon Gift Card, and QUO Card Pay, distributed via the digital gift service “Digi-Co”.
- This change will apply to shareholders recorded in the company’s shareholder register as of November 30, 2026, who hold 500 shares or more.
🤖 AI Perspective
Bike O & Company’s change in its shareholder benefits program appears to broaden the appeal of its incentives beyond just motorcycle purchasers to a wider base of shareholders. The shift to digital gifts could enhance convenience and expand choices, potentially contributing to an increase in shareholder engagement and long-term corporate value. Additionally, the increase in the minimum shareholding requirement from 100 to 500 shares, along with tiered benefits based on holdings, might suggest an effort to strengthen returns for larger shareholders.
3384|アークコア
—
▲ +0.00%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Arkcore Co., Ltd. has announced its consolidated financial results for the second quarter (interim period) of the fiscal year ending February 2027.
- For the interim period, net sales were ¥4,288 million (up 7.5% year-on-year), operating profit was ¥383 million (up 8.4%), ordinary profit was ¥381 million (up 8.4%), and interim net profit was ¥255 million (up 8.1%).
- By segment, the motorcycle business reported net sales of ¥4,016 million (up 7.7% year-on-year) and segment profit of ¥368 million (up 21.8%).
- The fitness business reported net sales of ¥256 million (down 1.6% year-on-year) and segment profit of ¥41 million (down 18.3%).
- A new IT business commenced following the absorption merger of Protonotes Co., Ltd. in April 2026, generating net sales of ¥15 million and a segment loss of ¥27 million.
- The full-year forecast for the fiscal year ending February 2027 remains unchanged, with projected net sales of ¥6,589 million, operating profit of ¥239 million, ordinary profit of ¥231 million, and net profit of ¥160 million.
🤖 AI Perspective
Arkcore’s Q2 FY2027 results demonstrate solid performance, with increases across all key profitability metrics compared to the prior year. The strong contribution from the motorcycle business is a significant highlight, while the introduction of the new IT business through merger indicates a strategic expansion of their business portfolio. As the full-year forecast has been maintained, investors may consider monitoring the continued performance of the motorcycle segment and the development of the nascent IT business to assess their impact on the company’s future financial trajectory.
3560|ほぼ日
5100.0
▼ -1.16%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Hobonichi Co., Ltd. resolved to increase its dividend from retained earnings at a board meeting held on October 14, 2026, with the record date set for August 31, 2026.
- The fiscal year-end dividend per share for the August 2026 term will be ¥100.00, an increase of ¥10 from the most recent dividend forecast of ¥90.00 (announced on October 10, 2025).
- Consequently, the annual dividend per share for the August 2026 term will total ¥100.00.
- The total dividend amount is ¥232 million, with an effective date of November 28, 2026.
- The dividend increase is attributed to strong net income attributable to parent company shareholders and a comprehensive consideration of the company’s financial condition.
🤖 AI Perspective
This dividend increase may suggest the company’s commitment to shareholder returns, supported by favorable financial performance. The ¥10 increase from the previous fiscal year’s annual dividend of ¥90 could be viewed positively by investors. As the company emphasizes a basic policy of ensuring stable long-term management, the consistency of its dividend policy alongside future earnings trends will be worth monitoring.
3562|No.1
1700.0
▼ -3.19%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- For the second quarter of the fiscal year ending February 2027, consolidated net sales increased by 28.0% year-on-year to JPY 9,801 million.
- During the same period, consolidated operating profit was JPY 571 million (down 3.2% year-on-year), consolidated ordinary profit was JPY 534 million (down 19.1% year-on-year), and net income attributable to owners of parent was JPY 304 million (down 6.3% year-on-year).
- Diluted earnings per share for the interim period was JPY 45.67.
- An interim dividend of JPY 39.50 per share was announced for the fiscal year ending February 2027.
- The full-year consolidated earnings forecast remains unchanged from the most recently announced forecast, with projected net sales of JPY 21,200 million, operating profit of JPY 1,650 million, ordinary profit of JPY 1,590 million, and net income attributable to owners of parent of JPY 1,000 million.
🤖 AI Perspective
No.1’s Q2 FY2027 results show a significant increase in net sales while profits decreased compared to the prior year’s interim period. This may suggest that while sales of core products like information security devices performed well, increased investment in management resources and selling expenses could have impacted profitability. The unchanged full-year outlook indicates the company’s confidence in its overall strategy, making future business developments and profit structure evolution worth monitoring.
3608|TSI HD
1208.0
▼ -0.58%
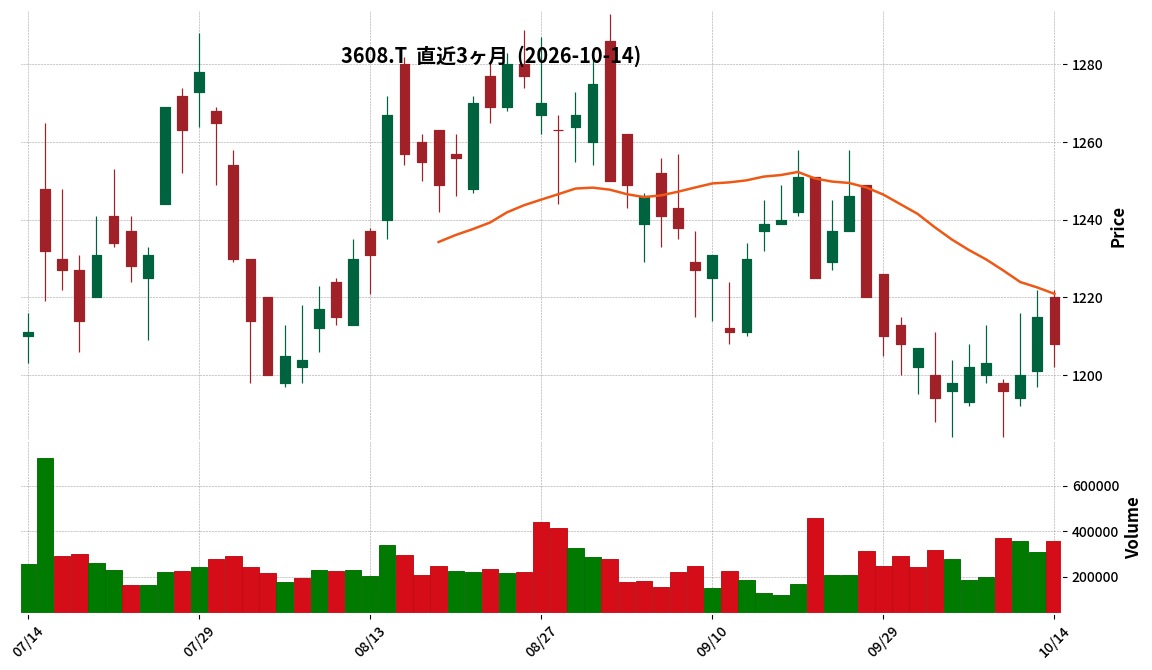
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- World Inc. and TSI Holdings have agreed to integrate their businesses by establishing a joint holding company, INFINITY UNITED Inc., through a joint share transfer, effective March 1, 2027 (scheduled).
- This business integration agreement and share transfer plan were jointly prepared and concluded today, based on resolutions passed by the boards of directors of both companies.
- The integration’s background includes the intense competition and optimization opportunities in the domestic fashion market, changes in customer demands and the potential for new creativity, and the need to shift from traditional fashion business models.
- The stated objective is to “establish a ‘third pole’ in the fashion industry and create a new value-creation industry.”
- Anticipated synergies from this integration include the pursuit of scale merits in business infrastructure and the realization of potential growth through the integrated operation of mutual know-how and resources.
🤖 AI Perspective
This business integration appears to aim for expanded scale and improved efficiency in business infrastructure among major Japanese apparel companies. Given the minimal overlap in their brand portfolios, there may be expectations for significant synergy generation through mutual complementarity. The emphasis on transitioning from conventional business models towards a circular business model is also a noteworthy aspect that could influence future trends in the fashion industry.
3612|ワールド
1571.0
▼ -0.57%
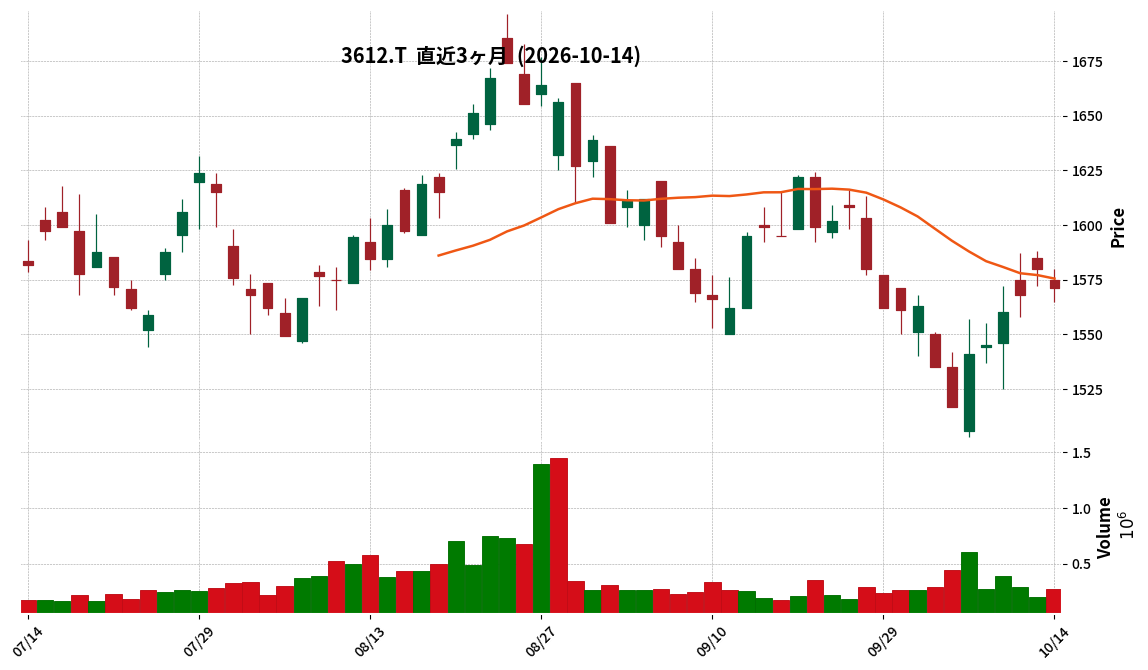
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- World Co., Ltd. and TSI Holdings Co., Ltd. signed a business integration agreement on October 14, 2026.
- The companies plan to establish a joint holding company, INFINITY UNITED Inc., as their wholly owning parent company through a joint share transfer on March 1, 2027 (scheduled).
- This business integration is contingent on the approval of both companies’ general meetings of shareholders and relevant regulatory authorities.
- The stated purpose of the integration is to “establish a ‘third pole’ in the fashion industry and create a new value-creation industry.”
- Anticipated synergies include pursuing scale merits in business infrastructure and realizing potential growth through integrated utilization of mutual know-how and resources.
🤖 AI Perspective
This business integration reflects a shared understanding of challenges in the Japanese fashion market, including intense competition, opportunities for industry optimization, evolving customer behavior, and the need for sustainability. The complementary nature of their business portfolios and individual strengths suggests that the integration aims to achieve significant scale advantages and foster new creative endeavors. Investors may monitor the execution of plans to integrate business infrastructure, such as IT systems and logistics, and the expansion of digital marketing through combined customer data, as these elements could be crucial for realizing the stated synergies.
3760|ケイブ
743.0
▲ +3.05%
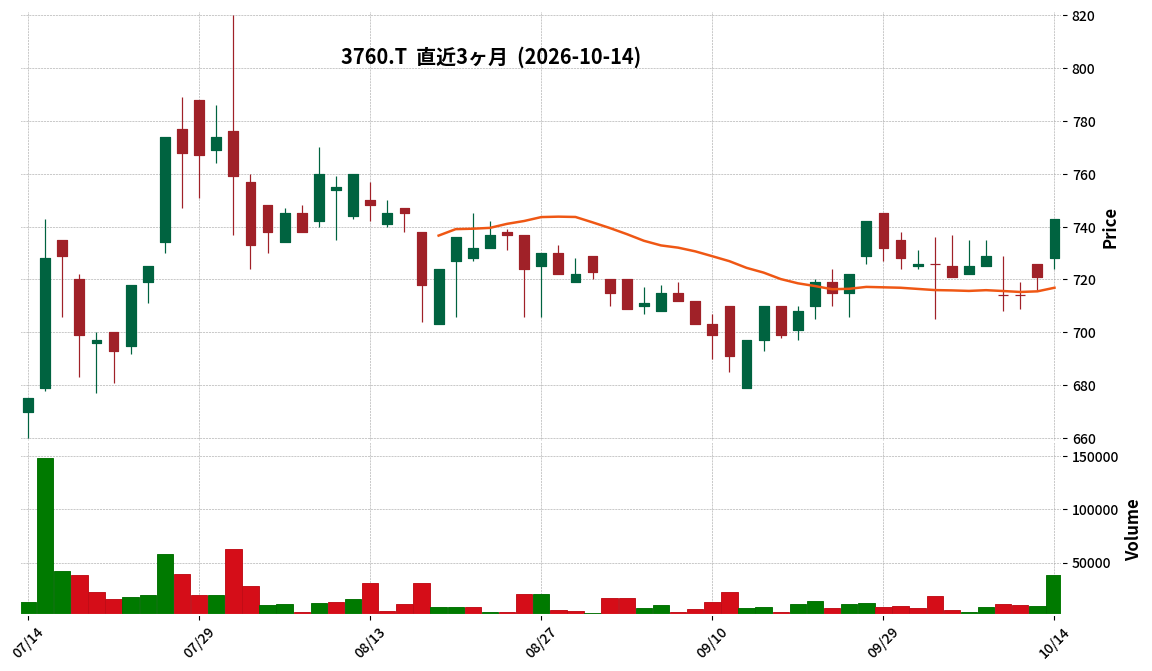
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- CAVE Interactive CO.,LTD. announced its supplementary financial materials for the first quarter of the fiscal year ending May 2027 (June 1, 2026 – August 31, 2026).
- Net sales for the first quarter reached ¥2,687 million, marking a 2.3% increase year-on-year.
- Operating profit turned positive to ¥555 million, compared to an operating loss of ¥565 million in the prior year’s same quarter, setting a new record high for a first quarter.
- Ordinary profit was ¥908 million (compared to an ordinary loss of ¥393 million year-on-year), and net profit attributable to parent company shareholders was ¥659 million (compared to a net loss of ¥285 million year-on-year), both turning profitable.
- Progress rates against full-year forecasts are: Net sales 25.6%, Operating profit 38.3%, Ordinary profit 58.6%, and Net profit attributable to parent company shareholders 55.0%.
- The company noted a seasonality in sales, with the first quarter typically having the smallest sales volume due to game consumption demand.
- A short-term financial target of achieving over ¥2 billion in operating profit within two years has been set.
- The company plans to enhance investor communication with over 12 IR media exposures annually.
🤖 AI Perspective
CAVE’s Q1 FY2027 results show a significant turnaround, with operating profit achieving a record high and strong profitability compared to the previous year’s loss, despite a modest increase in net sales. This performance appears to be driven by successful large-scale IP collaborations and campaigns, alongside fixed cost reductions and an increased share of external payment settlements. The robust progress towards full-year operating profit targets (38.3% in Q1) may suggest increased predictability and stability in the company’s financial outlook for the coming periods, a point that has been a past concern.
3922|PRTIMES
2131.0
▲ +0.00%
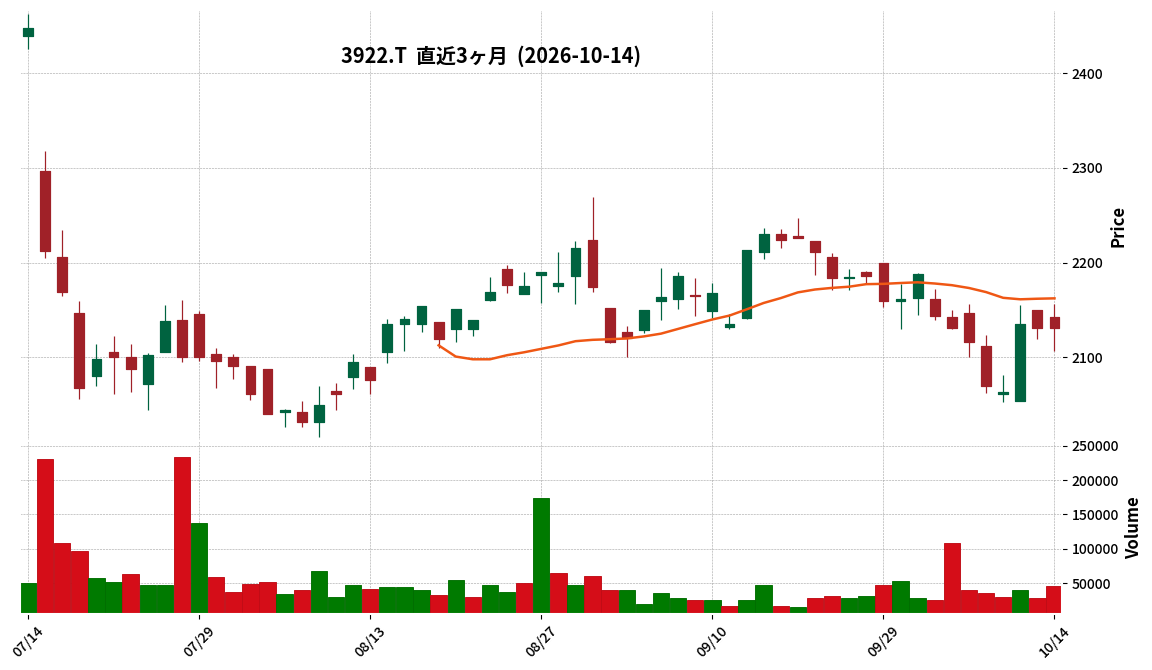
📎 Source:PRTIMES Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- PR TIMES Co., Ltd. resolved to change its capital allocation and dividend policy at a Board of Directors meeting held on October 14, 2026.
- The DOE (Dividend on Equity) target for ordinary dividends has been raised from the previous 2% or more to 9% or more, with progressive dividends as a general principle.
- The full-year dividend forecast for the fiscal year ending February 2027 has been revised upwards from JPY 16.80 (previous forecast announced April 13, 2026) to JPY 74.30.
- Interim dividends will be introduced from the fiscal year ending February 2028, changing the annual dividend frequency from once a year to twice a year.
- A M&A and strategic investment framework of JPY 4.5 billion has been established for the period from FY2026 to FY2030, with a policy to return at least 50% of any unused amount as special dividends at the end of the period.
🤖 AI Perspective
This announcement suggests PR TIMES has significantly revised its dividend policy, indicating a strengthened commitment to shareholder returns. The substantial increase in the DOE target and the adoption of progressive dividends as a principle could be seen as a move towards more stable shareholder distributions. Furthermore, the establishment of an M&A and strategic investment framework, coupled with the commitment to return unused funds as special dividends, appears to balance growth investments with shareholder returns, highlighting a focus on capital efficiency in management.
3977|A-フュージョン
—
▲ +0.00%
📎 Source:A-フュージョン Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- A-Fusion reported net sales of ¥904 million for the second quarter of the fiscal year ending February 2027, representing a 28.0% increase year-over-year.
- During the same period, the company achieved an operating income of ¥122 million, ordinary income of ¥122 million, and net income attributable to owners of the parent of ¥106 million, reversing losses of ¥42 million, ¥43 million, and ¥44 million respectively from the prior year’s interim period.
- Basic earnings per share for the interim period was ¥73.78.
- Regarding financial position, total assets stood at ¥813 million (up 18.3% YoY), net assets at ¥465 million (up 28.1% YoY), and the equity ratio was 57.2%.
- There were no revisions to the full-year earnings forecast or dividend forecast for the fiscal year ending February 2027 from the latest public announcement.
🤖 AI Perspective
A-Fusion’s Q2 FY2027 results highlight a significant increase in sales and a return to profitability across all income levels, which may suggest the positive impact of its “Rising2028” mid-term management plan and productivity improvement initiatives. The substantial shift from an operating loss to a strong operating income could indicate an improvement in the company’s revenue structure and operational efficiency, warranting continued monitoring by investors.
418A|ウリドキ
—
▲ +0.00%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Uridoki Co., Ltd. announced its unaudited financial results for the third quarter of the fiscal year ending November 2026 on October 14, 2026.
- For the nine months ended August 31, 2026 (December 1, 2025 – August 31, 2026), operating revenue was ¥1,913 million, representing a 79.2% increase compared to the prior year period.
- During the same period, operating profit reached ¥402 million (up 222.5% YoY), ordinary profit was ¥402 million (up 147.7% YoY), and quarterly net profit was ¥278 million (up 69.7% YoY).
- Quarterly net profit per share was ¥63.38, and diluted quarterly net profit per share was ¥57.85 (adjusted for a 2-for-1 stock split on December 1, 2025).
- The full-year consolidated earnings forecast for the fiscal year ending November 2026, originally announced on July 15, 2026, remains unchanged.
🤖 AI Perspective
The announced results demonstrate significant year-over-year growth in both revenue and profits, with a particularly strong increase in operating profit. This performance may suggest the continued effectiveness of the company’s investments in its C2B buying platform “Uridoki” and its ability to capitalize on the expanding reuse market, especially in high-value products. The decision to maintain the full-year earnings forecast could indicate that the company is progressing in line with its internal projections.
4317|レイ
601.0
▼ -1.15%
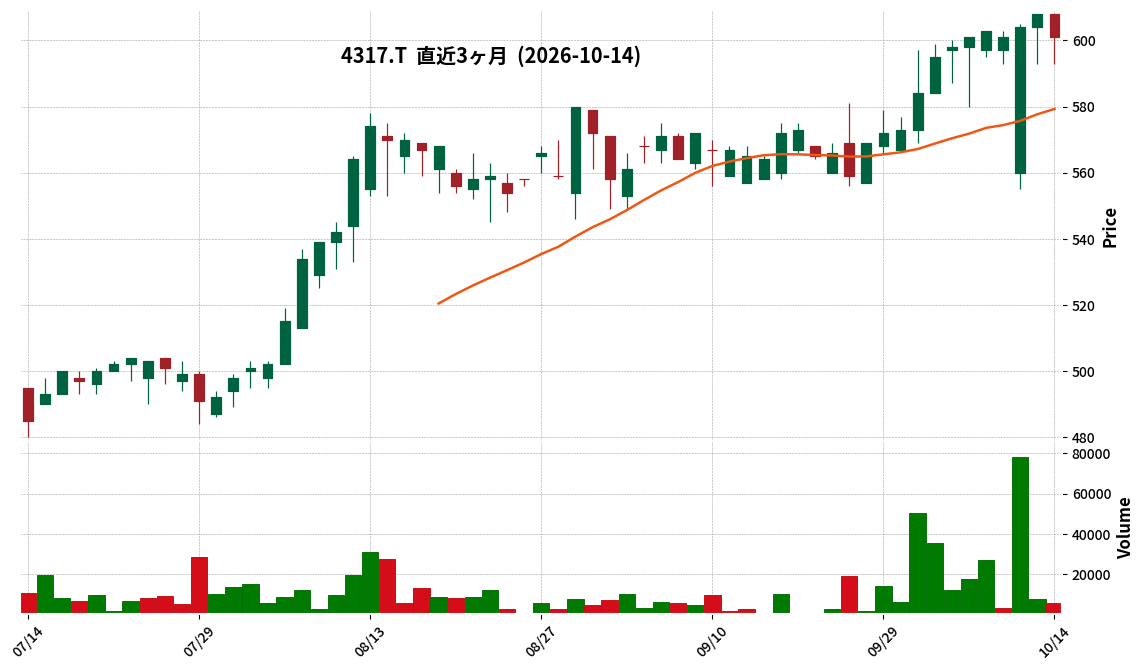
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Ray Co., Ltd. announced its consolidated financial results for the second quarter (interim period: March 1, 2024, to August 31, 2024) of the fiscal year ending February 2025.
- Net sales for the interim period amounted to ¥6,711 million, representing a 14.8% increase compared to the same period of the previous fiscal year.
- Operating profit was ¥546 million (down 22.9%), ordinary profit was ¥637 million (down 18.1%), and net income attributable to owners of the parent was ¥436 million (down 20.4%).
- By segment, Advertising Solutions recorded sales of ¥3,059 million (up 21.0%) with operating profit of ¥82 million (down 59.7%), while Technical Solutions reported sales of ¥3,651 million (up 10.1%) with operating profit of ¥804 million (down 2.5%).
- The full-year consolidated earnings forecast for the fiscal year ending February 2025 remains unchanged from the most recently published forecast, projecting sales of ¥13,500 million, operating profit of ¥1,200 million, ordinary profit of ¥1,300 million, and net income attributable to owners of the parent of ¥950 million.
🤖 AI Perspective
The announced results show an increase in net sales but a decrease across all profit metrics compared to the prior year. Notably, the Advertising Solutions segment experienced increased sales due to large projects but also a significant decline in profit, attributed to upfront personnel investments for future business expansion. While the Technical Solutions segment demonstrated solid performance, the overall group’s profit reduction suggests that the impact of these investments and the company’s ability to maintain its full-year forecast will be worth monitoring.
434A|P-LOOPLACE
930.0
▲ +0.00%
📎 Source:P-LOOPLACE Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- P-LOOPLACE Co., Ltd. announced its H1 FY2027 interim financial results (March 1, 2026 – August 31, 2026) on October 14, 2026.
- Revenue for the interim period was ¥1,615 million, representing a 25.7% decrease compared to the same period of the previous year.
- Operating profit declined by 54.7% to ¥153 million, ordinary profit by 64.4% to ¥114 million, and interim net profit by 64.7% to ¥74 million.
- Diluted earnings per share for the interim period were ¥74.94.
- The full-year forecast for FY2027 remains unchanged, projecting ¥3,428 million in revenue (up 23.1% year-on-year) and ¥73 million in net profit (down 54.7% year-on-year).
🤖 AI Perspective
The interim results show a decline in key profit figures compared to the prior year, primarily attributed to a reactionary decrease following the completion of large-scale revitalization projects in the Real Estate Solution business during the previous interim period. The company states that it is focusing on enhancing the value of existing properties and acquiring new properties to strengthen its mid-to-long-term growth foundation, with a view to realizing profits from sales in subsequent periods. The unchanged full-year forecast may suggest an anticipation of improved performance in the second half of the fiscal year.
4372|G-ユミルリンク
1304.0
▲ +0.00%
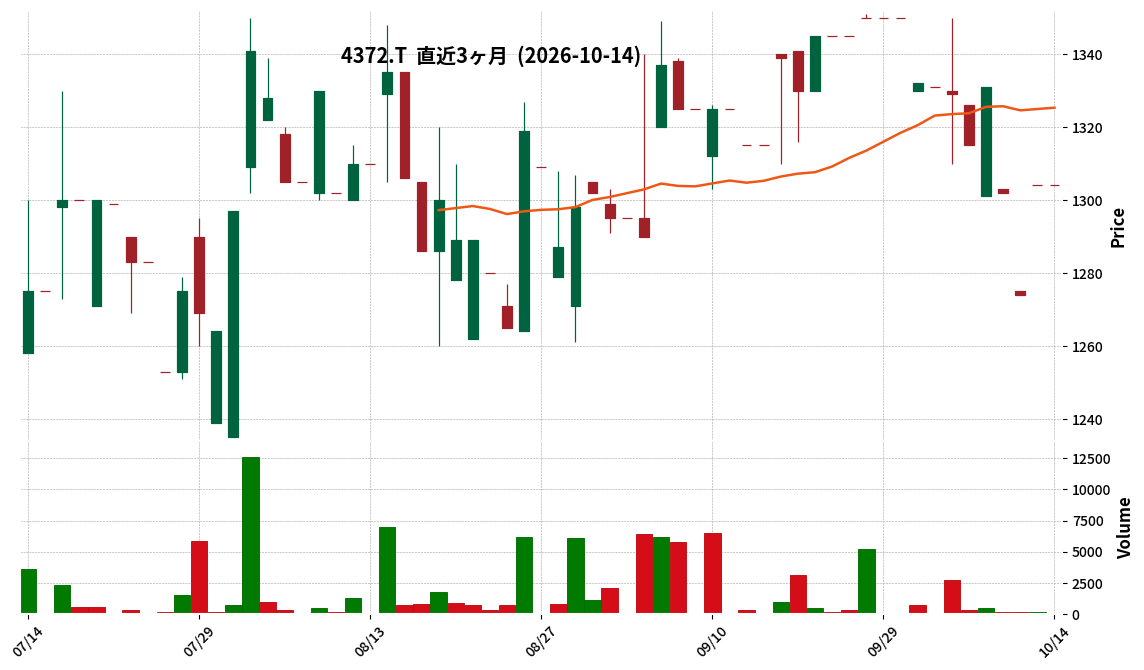
📎 Source:G-ユミルリンク Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- G-Umlink announced on October 14, 2026, that its Board of Directors resolved to enter into an investment agreement, including a capital and business alliance, with KOKU-CO., Ltd.
- The alliance aims to accelerate the nationwide dissemination of G-Umlink’s upcoming BtoB Marketing Automation (MA) tool to Small and Medium-sized Businesses (SMBs) across Japan.
- G-Umlink acquired 31,645 shares of KOKU-CO.’s Class D stock for ¥99,998,200, representing a 2.1% ownership stake, as part of KOKU-CO.’s Series D fundraising.
- KOKU-CO.’s business focuses on “Human Resources x Digital” solutions, with a particular strength in providing DX support to SMBs in collaboration with regional financial institutions.
- The alliance is expected to have a minor impact on G-Umlink’s financial results for the fiscal year ending December 2026 but is anticipated to contribute to an increase in corporate value over the medium to long term.
🤖 AI Perspective
This alliance suggests G-Umlink’s strategic intent to leverage KOKU-CO.’s established DX support and customer base in regional markets for the rollout of its new MA tool targeting the SMB segment. The investment of ¥99,998,200 into KOKU-CO.’s Class D shares appears to align both companies’ objectives: securing growth capital for KOKU-CO.’s potential future listing and ensuring the safety of G-Umlink’s investment. The focus on medium to long-term corporate value enhancement indicates that investors may wish to monitor the progress of the MA tool’s implementation and market adoption.
2901|ウェルディッシュ
128.0
▲ +0.00%
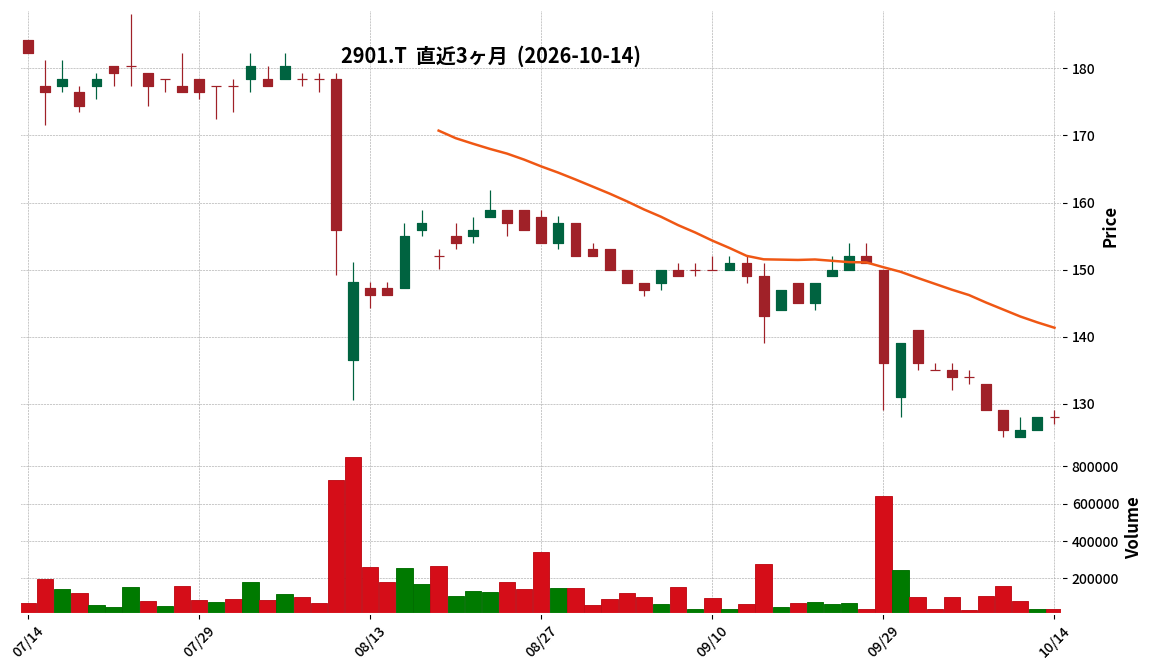
📎 Source:ウェルディッシュ Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Well-Dish Co., Ltd. announced on October 14, 2026, that the disclosure of its financial results for the fiscal year ending August 2026 is expected to be delayed beyond 50 days from the fiscal year-end.
- The original disclosure date was scheduled for October 15, 2026.
- The delay is attributed to the non-disclosure of the Q3 financial results due to the resignation of the accounting auditor (announced July 14, 2026), the time required for verifying accounting treatments for past and current fiscal years based on the independent investigation committee’s report, and ongoing audit procedures by temporary accounting auditor “Aria Audit Firm” (appointed September 21, 2026).
- The company plans to promptly disclose the Q3 financial results and expects to restate past financial results based on the independent investigation committee’s report.
- Specific disclosure dates for the Q3 financial results and the FY2026 August financial results, as well as the details and timing of past financial restatements, are currently undetermined.
🤖 AI Perspective
This announcement suggests a continuation of the accounting challenges faced by Well-Dish, linking back to previous IR disclosures regarding auditor changes and the establishment of an independent investigation committee. The delay in the annual financial report indicates that the company is still addressing significant accounting issues. Investors may wish to monitor the company’s progress in achieving transparency and the eventual disclosure of restatement details, as the indefinite timeline for key information could impact market perception.
3361|トーエル
913.0
▲ +0.11%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- TOELL Co., Ltd. resolved at its Board of Directors meeting on October 14, 2026, to acquire all shares of A-works Co., Ltd., making it a subsidiary.
- A-works Co., Ltd. is located in Saitama City, Saitama Prefecture, and engages in residential reform, restoration, and in-residence repair works.
- The acquisition’s purpose is to establish a new business foundation in the reform and restoration sectors to enhance customer services.
- TOELL will acquire 100 shares, resulting in a 100% voting rights ownership after the transaction.
- The acquisition price is undisclosed, but it does not fall under the timely disclosure standards.
- The planned share transfer execution date is November 2, 2026.
- The impact of this share acquisition on TOELL’s consolidated financial results is expected to be minor.
🤖 AI Perspective
TOELL’s acquisition of A-works, focused on strengthening its reform and restoration businesses, may suggest a strategic move to expand its service offerings and market presence. A-works’ recent three-year financial performance shows a consistent growth in sales and profits, which could contribute to the group’s overall business expansion. While the immediate impact on consolidated results is considered minor, investors may want to monitor potential medium to long-term synergies and the scale of business growth.
3678|メディアドゥ
1192.0
▲ +0.59%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Media Do Co., Ltd. has revised its consolidated earnings and dividend forecasts upward for the fiscal year ending February 2027.
- Net profit attributable to owners of parent is revised from the previous forecast of ¥1.20 billion to ¥2.76 billion, an increase of ¥1.56 billion (a 130.0% increase).
- This revision is attributed to an expected special gain of ¥1.56 billion from the sale of all shares and interests in consolidated subsidiaries Quality Solutions, Inc., NetGalley, LLC, and its three sub-subsidiaries.
- There are no changes to the revenue, operating profit, and ordinary profit forecasts, reflecting recent business trends.
- The year-end dividend forecast has been revised upward by ¥15 to ¥55 per share, from the previous forecast of ¥40.
- This revision is expected to result in a total shareholder return ratio of 30.3% for the fiscal year ending February 2027.
🤖 AI Perspective
This upward revision of earnings is primarily driven by a significant special gain from the divestiture of subsidiaries, highlighting the financial impact of strategic business restructuring. The increased dividend forecast aligns with the company’s policy of maintaining a total shareholder return ratio of 30% or more, indicating a commitment to shareholder returns. As revenue, operating profit, and ordinary profit forecasts remain unchanged, investors may continue to monitor the performance of the core business in future announcements.
3936|G-グローバルウェイ
132.0
▲ +0.76%
📎 Source:G-グローバルウェイ Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Globalway Inc. resolved to acquire shares of LHit Corporation and make it a subsidiary at its board meeting held on October 14, 2026.
- The acquisition involves 299 shares, representing an 89.8% ownership stake in LHit Corporation’s total outstanding shares of 333.
- The acquisition price for LHit Corporation’s common stock is 75 million yen (250,836 yen per share).
- LHit Corporation specializes in data analysis consulting utilizing low-code/no-code BI tools and data analysis talent development.
- The impact of this acquisition on Globalway’s consolidated performance for the fiscal year ending March 2027 is stated to be minor.
🤖 AI Perspective
This acquisition of LHit Corporation by G-Globalway appears to be a strategic move to strengthen its core digital solutions business. Integrating LHit’s expertise in data analysis and business intelligence could expand the scope of G-Globalway’s DX support services and accelerate in-house development of data analysis talent. Potential cross-selling opportunities through leveraging both companies’ customer bases may contribute to enhanced profitability.
4429|G-リックソフト
736.0
▲ +2.08%
📎 Source:G-リックソフト Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- G-Ricksoft revised its full-year consolidated earnings forecast for the fiscal year ending February 2027, as announced on October 14, 2026, following a board meeting.
- Consolidated operating profit is now projected to increase by 69.5% (¥139 million) from the previously announced ¥200 million to ¥340 million.
- Consolidated ordinary profit is expected to increase by 71.9% (¥144 million) from ¥200 million to ¥345 million.
- Net profit attributable to owners of parent is projected to increase by 61.8% (¥98 million) from ¥160 million to ¥258 million.
- Consolidated net sales remain unchanged at ¥12,195 million from the previous forecast.
- The revision is attributed to optimized organizational structure resulting from structural reforms and enhanced operational efficiency through AI utilization, leading to lower-than-planned personnel and recruitment costs.
🤖 AI Perspective
The upward revision of the earnings forecast, with no change in revenue but significant increases in profit figures, is a key point for investors. This may suggest that cost efficiency improvements through structural reforms and AI integration are positively impacting the company’s profitability. The emphasis on reduced personnel and recruitment costs as a primary driver for profit growth could indicate a successful shift towards a more efficient operational framework.
457A|P-ルリアン
4130.0
▲ +0.00%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- P-Le Lien reported operating revenue of ¥1,503 million for the fiscal year ended August 2026 (September 1, 2025 – August 31, 2026), marking a 16.4% increase year-on-year.
- During the same period, operating profit was ¥78 million (up 22.8% YoY), ordinary profit was ¥73 million (up 13.2% YoY), and net profit was ¥48 million (up 6.3% YoY).
- Revenue from the core inheritance support business was ¥1,474,921 thousand (up 17.2% YoY), while life support, primarily focused on end-of-life planning, saw revenue of ¥9,763 thousand (down 48.1% YoY).
- As of the end of August 2026, total assets stood at ¥746 million, net assets at ¥319 million, and the equity ratio was 42.8%.
- For the fiscal year ending August 2027, the company forecasts operating revenue of ¥1,734 million (up 15.3% YoY), operating profit of ¥130 million (up 65.9% YoY), and net profit of ¥85 million (up 75.4% YoY).
🤖 AI Perspective
P-Le Lien’s fiscal year 2026 results show a positive trend with increased revenue and profits across all stages compared to the previous period. The strong performance of the core inheritance support business appears to have been a key driver of overall growth. The significant increase projected for both revenue and profit in the fiscal year 2027 outlook suggests management’s confidence in continued business expansion.
4668|明光ネット
742.0
▼ -1.20%
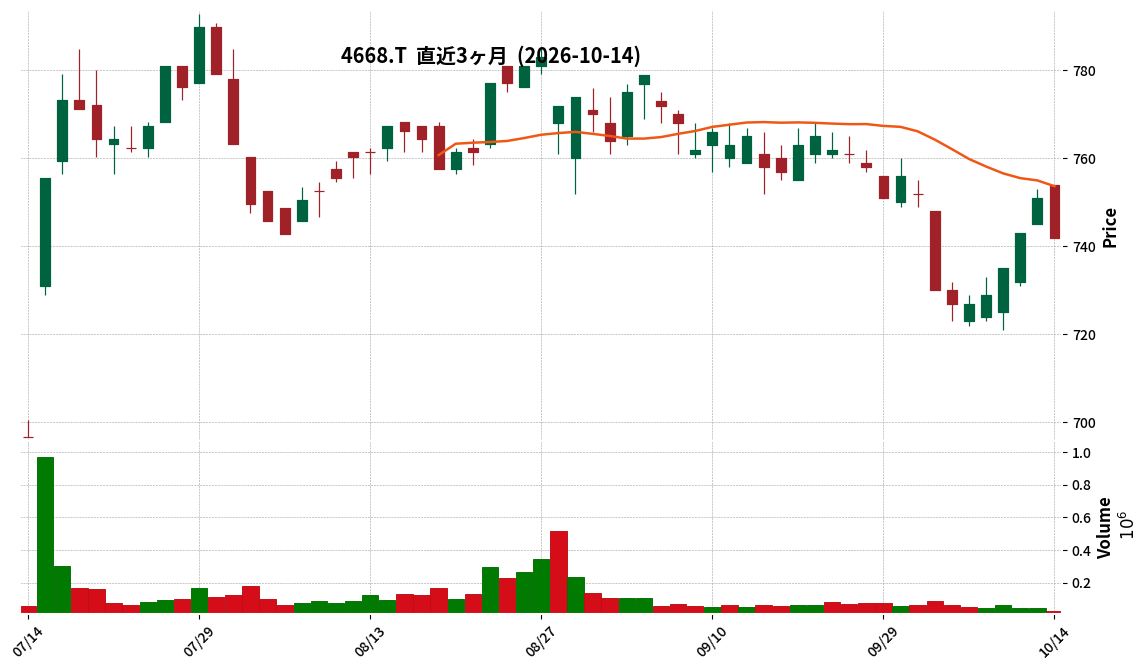
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Meiko Network Japan announced its consolidated financial results for the fiscal year ended August 31, 2026 (September 1, 2025 – August 31, 2026).
- Consolidated net sales reached ¥26,037 million, representing a 4.9% increase year-on-year.
- Consolidated operating profit was ¥1,510 million (down 10.7% year-on-year), and consolidated ordinary profit was ¥1,706 million (down 8.7% year-on-year).
- Profit attributable to owners of parent decreased by 51.3% year-on-year to ¥842 million.
- The annual dividend per share was set at ¥29 (interim ¥14, year-end ¥15), an increase of ¥2 from the previous fiscal year.
- For the fiscal year ending August 31, 2027, the company forecasts consolidated net sales of ¥27,000 million (up 3.7%), operating profit of ¥1,700 million (up 12.5%), and profit attributable to owners of parent of ¥950 million (up 12.8%).
🤖 AI Perspective
While net sales showed an increase, the decline in operating, ordinary, and net profits warrants attention. The significant decrease in net profit could potentially be attributed to specific factors in the previous fiscal year or the company’s positioning of the current period as an investment phase under its mid-term management plan. The continued increase in dividend and the positive outlook for sales and profit in the next fiscal year suggest that the progress of its business strategies will be worth monitoring.
4829|日本エンタープライズ
103.0
▲ +0.98%
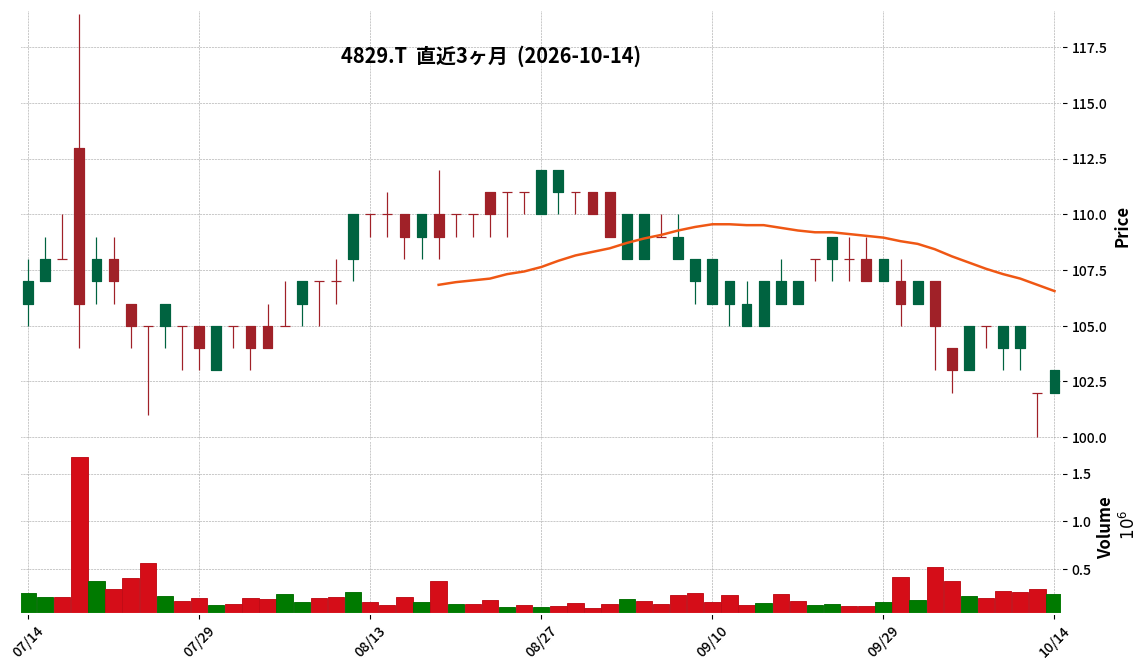
📎 Source:日本エンタープライズ Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Nihon Enterprise Co., Ltd. announced its Q1 FY2027 (June 2026 – August 2026) financial results on October 14, 2026.
- Consolidated net sales amounted to ¥993 million, representing an 8.2% decrease compared to the same quarter of the previous fiscal year.
- The company reported a consolidated operating loss of ¥40 million, an ordinary loss of ¥17 million, and a net loss attributable to owners of the parent of ¥22 million.
- The decrease in net sales was primarily due to declines in “Content Services” and “System Development Services,” although “Business Support Services” increased.
- The company is preparing for a transition to a holding company structure starting December 1, 2026, and has established Nihon Enterprise Spilt Preparation Co., Ltd., Kotsujyohoservice Co., Ltd., and NE Power Co., Ltd.
- NE Power Co., Ltd. has entered the grid-scale battery storage business in collaboration with Meihodo Engineering Co., Ltd., aiming to operate using three methods: “ID sales,” “sale after construction and completion,” and “self-ownership and operation.”
- The full-year earnings forecast remains unchanged.
🤖 AI Perspective
Nihon Enterprise’s Q1 results show a decline in revenue and profit, but the full-year forecast has been maintained. This might suggest the company is factoring in the current business fluctuations while placing expectations on strategic initiatives such as the entry into the grid-scale battery storage business and the shift to a holding company structure for future growth. The new energy business, in particular, could lead to a significant change in the long-term business portfolio and its progress will be worth monitoring.
5246|G-ELEMENTS
1030.0
▼ -3.38%
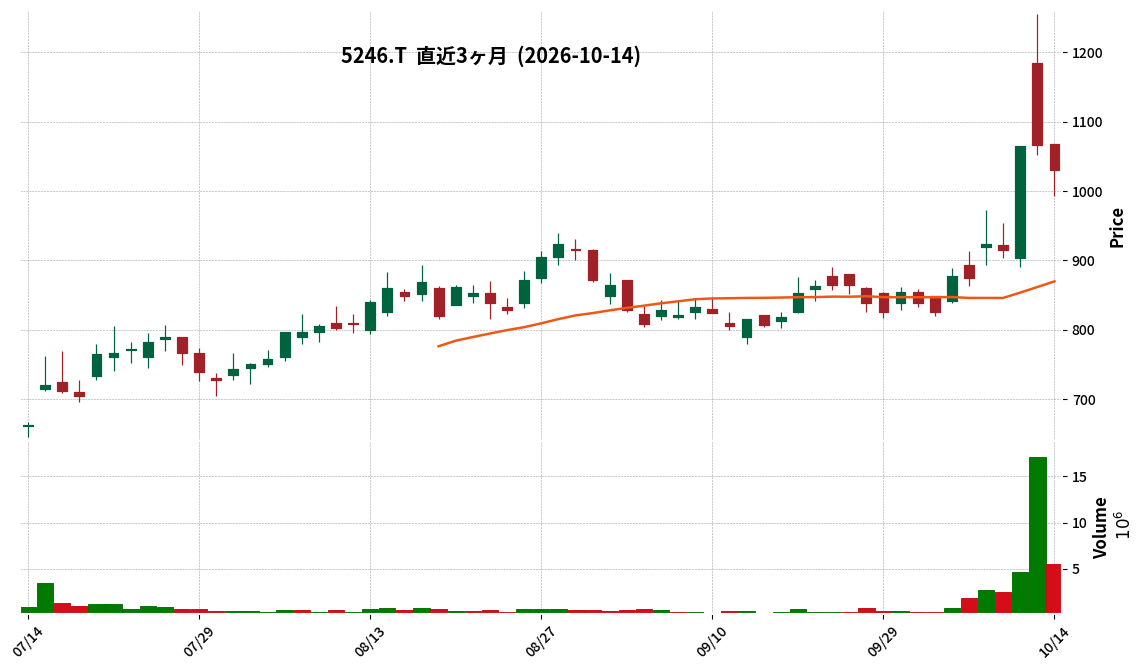
📎 Source:G-ELEMENTS Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- G-ELEMENTS announced its consolidated financial results for the third quarter of the fiscal year ending November 2026 (December 1, 2025, to August 31, 2026).
- Consolidated net sales reached ¥4,329 million, representing a 59.1% increase compared to the same period last year.
- EBITDA was ¥995 million (up 353.8% year-on-year), operating income was ¥457 million (compared to an operating loss of ¥136 million in the prior year), ordinary income was ¥413 million (compared to an ordinary loss of ¥179 million in the prior year), and net income attributable to owners of the parent was ¥410 million (compared to a net loss of ¥622 million in the prior year), indicating a return to profitability for all income items.
- Total assets stood at ¥6,974 million, net assets at ¥4,016 million, and the equity ratio was 52.1%.
- The full-year consolidated performance forecast for the fiscal year ending November 2026 has been revised: Net sales of ¥5,700 million (up 46.3% year-on-year), EBITDA of ¥1,200 million (up 343.3% year-on-year), operating income of ¥400 million, ordinary income of ¥300 million, net income attributable to owners of the parent of ¥300 million, and earnings per share of ¥11.03.
🤖 AI Perspective
G-ELEMENTS’ substantial increase in sales and the return to profitability across all income categories may suggest an acceleration in business growth. The significant rise in EBITDA could indicate improved operational efficiency and profitability. The upward revision of the full-year earnings forecast might reflect the company’s confidence in its future business developments.
8143|ラピーヌ
155.0
▲ +7.64%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Lapine Co., Ltd. announced its consolidated financial results for the second quarter of the fiscal year ending February 2027.
- For the interim period, net sales were ¥851 million, a decrease of 7.3% compared to the same period last year.
- The company reported an operating loss of ¥176 million (compared to a loss of ¥172 million in the prior year’s interim period) and an ordinary loss of ¥157 million (compared to a loss of ¥161 million in the prior year’s interim period).
- Net loss attributable to owners of the parent was ¥80 million (compared to a loss of ¥165 million in the prior year’s interim period).
- The full-year consolidated performance forecast projects net sales of ¥1,890 million (a 0.9% increase year-on-year) and a net loss attributable to owners of the parent of ¥132 million.
- As of the end of the interim period, total assets stood at ¥2,963 million, net assets at ¥701 million, and the equity ratio was 23.7%.
🤖 AI Perspective
Lapine’s Q2 FY2027 results show a year-over-year decline in net sales, but a reduced net loss attributable to owners of the parent compared to the previous year. This could suggest that cost control measures and other management efforts are having some impact. Maintaining a full-year sales forecast indicating an increase from the previous year suggests an expectation for improved business performance in the latter half, which may be worth monitoring for investors.
8783|abc
44.0
▲ +2.33%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- abc has determined the utilization methods and the start date of November 5, 2026 (planned) for its shareholder benefit point service “Yutai no Izumi” at partner locations.
- Utilization at partner locations will be either “benefits shown with an exchange ticket at stores” or “benefits displaying an application code,” depending on the type of benefit.
- Confirmation of shareholder benefit point balance and usage history within this service will be provided concurrently with the start of utilization at partner locations, conditional on the integration of the shareholder benefit app balance with the service screen.
- As of October 1, 2026 (October 2 on THANKS Map), nominations from shareholders who have received a “proof of shareholder” are accepted, with the operation method changed to be performed within the WOWOO app.
- As of the current date, no partnership agreements have been concluded with companies or stores; negotiations are ongoing, and partnered entities will be published on the service’s website once decided.
🤖 AI Perspective
This announcement suggests that abc’s shareholder benefit point service, “Yutai no Izumi,” is progressing towards an operational phase. The detailed clarification of utilization methods may enhance shareholder understanding and engagement with the service. The successful acquisition of partner companies will be a critical factor for the future development of the service and is worth monitoring.
9334|アイビスHD
—
▲ +0.00%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- IBIS Holdings Co., Ltd. announced on October 14, 2026, a “Correction to a part of ‘Announcement of our financial results and other information due to listing on Nagoya Stock Exchange Next Market and Fukuoka Stock Exchange Q-Board Market’.”
- The reason for the correction was the discovery of an error in a portion of the summary information for the 3rd quarter financial results for the fiscal year ending October 2026.
- The corrected section pertains to “(2) Consolidated Financial Position” within the consolidated results for the 3rd quarter of the fiscal year ending October 2026 (November 1, 2025 – July 31, 2026).
- Prior to the correction, total assets for the 3rd quarter of the fiscal year ending October 2026 were 957 million yen and the equity ratio was 24.0%. Post-correction, total assets are 945 million yen and the equity ratio is 24.3%.
- Net assets remain unchanged at 229 million yen before and after the correction.
- The company states that this correction does not result in any changes to the financial statement figures in the attached documents.
🤖 AI Perspective
This correction involves a numerical adjustment in the summary section of previously disclosed financial information, specifically impacting total assets and the equity ratio within the consolidated financial position. Given that the net assets amount remains unchanged, the direct impact on the company’s financial soundness may be limited. Investors might consider it important to continuously monitor future disclosures in conjunction with this correction to assess any potential implications for the company’s overall financial standing.
9418|U-NEXT
1765.0
▼ -0.45%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- U-NEXT HOLDINGS Co., Ltd. has announced its consolidated financial results for the fiscal year ended August 2026.
- Consolidated net sales reached ¥469,957 million, marking a 20.4% increase compared to the previous fiscal year.
- Consolidated operating profit was ¥30,255 million (down 4.2% YoY), consolidated ordinary profit was ¥28,169 million (down 8.8% YoY), and profit attributable to owners of parent was ¥14,959 million (down 18.7% YoY).
- Diluted earnings per share were ¥82.93 (compared to ¥101.99 in the previous year).
- The annual dividend per share increased from ¥15.50 in the prior year to ¥17.00. The forecast for the FY2027 annual dividend is ¥19.00.
- For the fiscal year ending August 2027, the company forecasts consolidated net sales of ¥524,000 million (up 11.5% YoY), operating profit of ¥32,500 million (up 7.4% YoY), and profit attributable to owners of parent of ¥16,500 million (up 10.3% YoY).
- XING Inc. was newly included in the scope of consolidation during the fiscal year.
🤖 AI Perspective
U-NEXT HOLDINGS’ FY2026 results show robust revenue growth, but a decline in profits year-over-year. This could be attributed to the expansion of business scale with the inclusion of XING Inc. in the consolidation scope, potentially impacting the cost structure. The positive outlook for FY2027, projecting growth in both revenue and profit, suggests that the company anticipates benefits from its new consolidated structure and strategic initiatives. Investors may monitor the progress of these new business integrations.
135A|G-VRAIN
4895.0
▼ -0.61%
📎 Source:G-VRAIN Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- G-VRAIN announced its unaudited Q2 FY2027 (interim) financial results on October 14, 2026.
- Net sales for the interim period totaled ¥1,884 million, marking an 80.0% increase compared to the same period last year.
- Operating profit reached ¥409 million (up 328.1% year-on-year), ordinary profit was ¥409 million (up 327.4% year-on-year), and interim net profit was ¥267 million (up 336.2% year-on-year).
- Interim net income per share was ¥26.06, and diluted interim net income per share was ¥25.94.
- The full-year FY2027 forecast remains unchanged from the most recently published figures, projecting net sales of ¥4,823 million (up 47.1% year-on-year) and net profit of ¥972 million (up 49.2% year-on-year).
🤖 AI Perspective
The interim financial results show significant year-on-year growth across net sales and all profit metrics, highlighting a strong performance in the first half of the fiscal year. The company attributes this expansion to its AI-powered image inspection systems and DX consulting services for the manufacturing industry, with order backlog of ¥1,308 million also reported, which could suggest a solid pipeline for future revenue. The affirmation of the full-year guidance may indicate that the company is progressing in line with its internal plans, providing a consistent outlook for investors.
557A|P-フェリエスト
2150.0
▲ +0.00%
📎 Source:P-フェリエスト Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- P-FERIEST Inc. (Code: 557A) announced its non-consolidated financial results for the fiscal year ended August 31, 2026 (September 1, 2025 – August 31, 2026).
- For FY2026 August, net sales were ¥891 million (up 62.2% year-over-year), operating profit was ¥85 million (up 136.3% YoY), ordinary profit was ¥90 million (up 111.6% YoY), and net profit was ¥66 million (up 194.9% YoY).
- Diluted earnings per share stood at ¥66.10, with an equity ratio of 25.8%.
- The company plans an annual dividend of ¥9.00 per share (¥9.00 at fiscal year-end) for FY2026 August, totaling ¥9 million with a dividend payout ratio of 13.6%.
- For the upcoming FY2027 August (September 1, 2026 – August 31, 2027), the company forecasts net sales of ¥1,350 million (up 51.4% YoY), operating profit of ¥129 million (up 51.4% YoY), ordinary profit of ¥138 million (up 54.1% YoY), and net profit of ¥100 million (up 51.5% YoY).
🤖 AI Perspective
P-FERIEST reported substantial growth in sales and profits for the fiscal year ended August 2026, indicating strong performance driven by expansion in the SNS marketing sector and strategic efforts in client acquisition and service enhancement. The company’s forecast for continued double-digit growth in the next fiscal year could suggest management’s confidence in sustaining its current growth trajectory. Investors may wish to monitor how the company manages increased personnel costs and strengthens its operational structure to support this expansion.
Disclaimer: This article is for informational purposes only and does not constitute investment advice.
2796|ファーマライズHD
504.0
▼ -0.40%
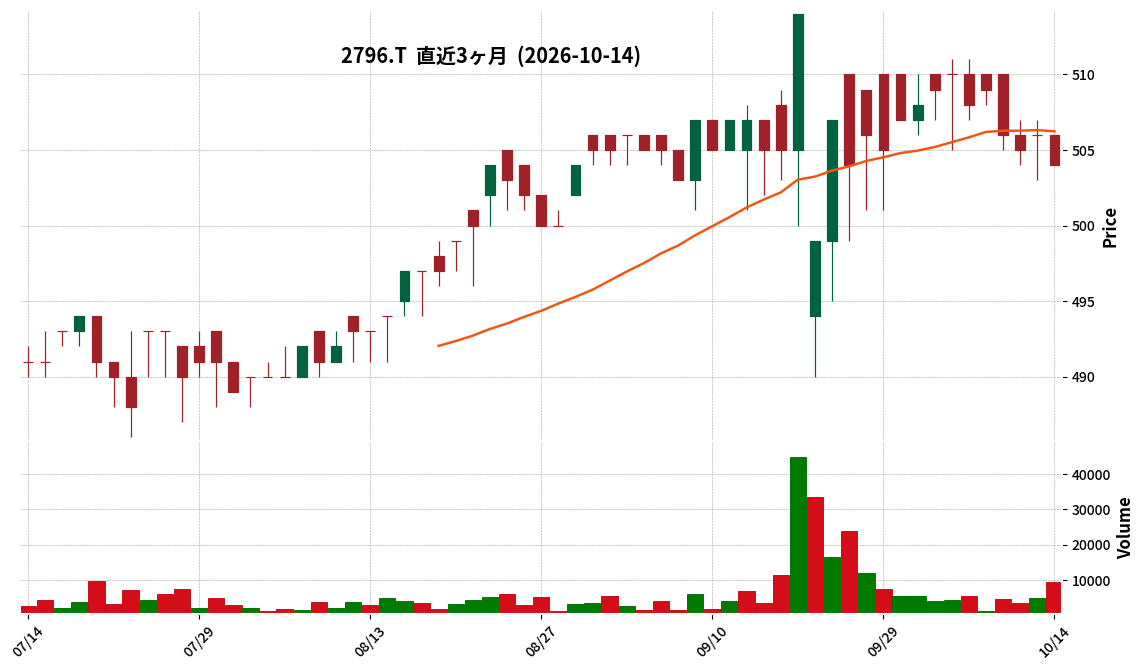
📎 Source:ファーマライズHD Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- PharmaRise Holdings has decided on its shareholder benefit program for fiscal year 2026 at a Board of Directors meeting.
- Eligible shareholders are those holding 100 or more shares for at least one year as of November 30, 2026, as recorded in the company’s shareholder registry.
- Shareholders can choose one of three benefits: “Dental Police DX” medicated toothpaste (two 80g tubes), a “1-Day Emergency Food Set” (one box), or a company product voucher worth ¥2,500 (tax included).
- The product voucher is valid for purchasing OTC medicines, etc., at all stores within the company group, with an expiration date of March 31, 2028.
- Application postcards for benefits will be sent around late February 2027, and benefits are scheduled to be shipped from mid-April to mid-June 2027.
🤖 AI Perspective
This announcement provides specific details regarding the company’s shareholder return policy for fiscal year 2026. The requirement for holding shares for at least one year may suggest an intention to encourage long-term shareholding and foster a stable shareholder base. Offering multiple choices for benefits could indicate an effort to cater to diverse shareholder preferences.
3387|クリレスHD
807.0
▲ +0.00%
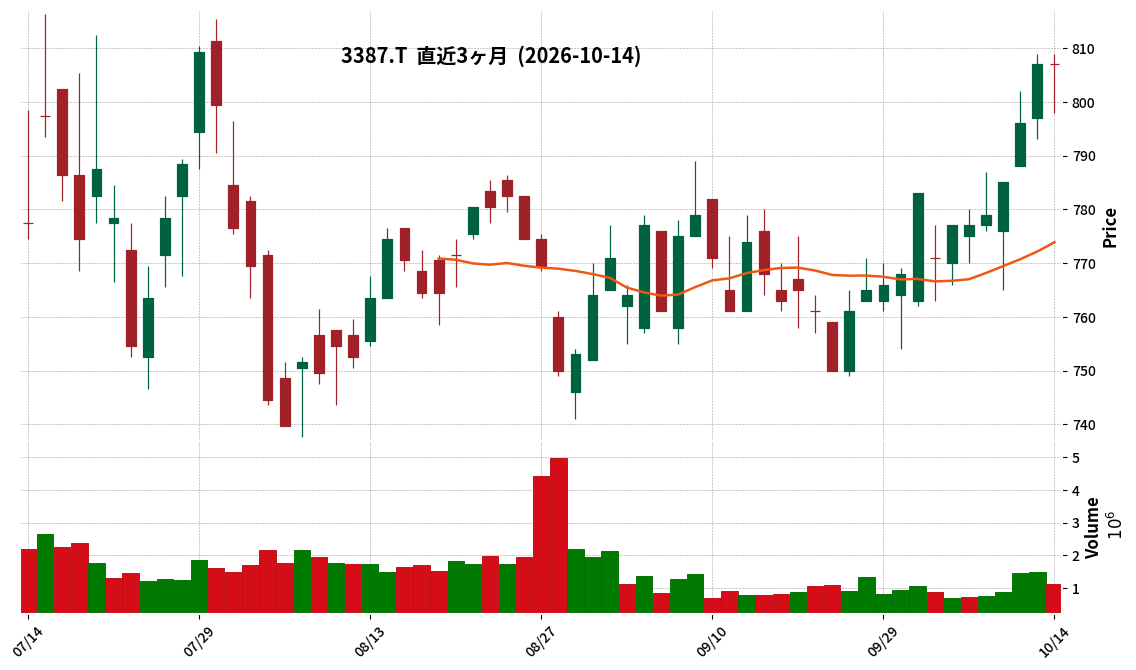
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Create Restaurants Holdings (CRH) completed an absorption-type merger of its consolidated subsidiary, SFP Holdings Co., Ltd., on July 1, 2026.
- As a result of this merger, CRH will record an extraordinary gain in its non-consolidated financial statements for the second quarter of the fiscal year ending February 2027.
- The extraordinary gain, specifically a “negative goodwill from business combination” (抱合せ株式消滅差益), amounts to ¥982 million.
- This gain represents the difference between CRH’s equity interest in the net assets of the merged entity and the book value of CRH’s shares in SFP Holdings.
- This extraordinary gain will be eliminated in the consolidated financial statements, therefore having no impact on CRH’s consolidated financial results for the fiscal year ending February 2027.
🤖 AI Perspective
This announcement provides clarity on the accounting treatment following CRH’s absorption-type merger of its consolidated subsidiary, SFP Holdings. The reporting of an extraordinary gain in non-consolidated statements, while having no impact on consolidated results, may be a point of interest for investors. This illustrates how inter-company reorganizations within a corporate group are reflected in financial reporting.
5129|G-FIXER
253.0
▼ -4.17%
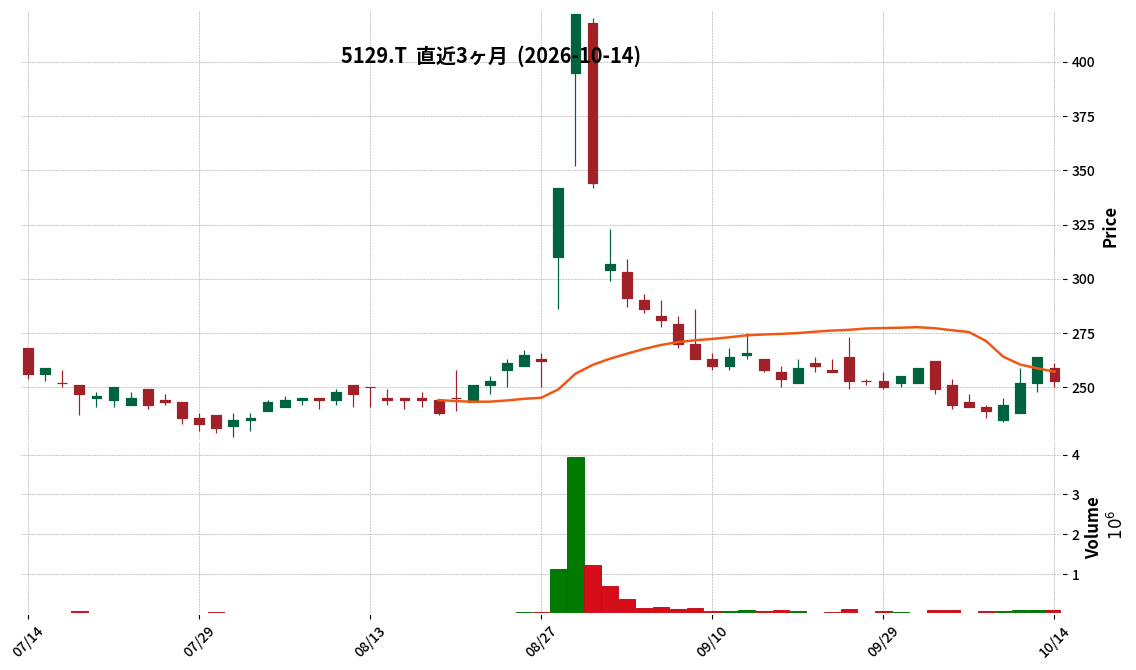
📎 Source:G-FIXER Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- G-FIXER reported full-year sales of ¥3,122 million for the fiscal year ended August 2026, a 21.6% decrease from the previous year, falling ¥1,225 million short of the initial forecast of ¥4,348 million.
- The company posted an operating loss of ¥2,316 million, an expansion of ¥586 million from the previous year’s loss of ¥1,729 million, and recorded a gross loss of ¥29 million.
- Cash and cash equivalents at the end of the period decreased to ¥1,205 million, and net assets declined to ¥1,862 million.
- The primary reason for the sales shortfall was a ¥845 million underperformance in the Sovereign GaiXer division (actual sales ¥16 million against a plan of ¥862 million) due to delays in establishing its sales system.
- Cash flow from operating activities showed an outflow of ¥2,239 million, and a going concern note was included in the financial statements.
🤖 AI Perspective
The FY2026 financial results show a significant revenue shortfall and an expanded operating loss, primarily attributed to delays in establishing the sales system for the new Sovereign GaiXer business. This highlights the challenges associated with new business launches and market penetration. The inclusion of a going concern note suggests that the company’s ability to continue as a going concern faces significant uncertainty, making ongoing monitoring of its financial strategies and business progress crucial for investors.
3823|WHY HOW DO
38.0
▲ +0.00%
📎 Source:WHY HOW DO Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- THE WHY HOW DO COMPANY resolved on October 14, 2026, to form a business alliance and sign a basic agreement with Colors Japan.
- The alliance aims to build a “Value Succession M&A Platform” targeting small and medium-sized enterprises (SMEs) facing successor issues and businesses with a high proportion of real estate assets.
- Colors Japan, established in December 2009, has executed 101 M&A deals and currently holds 61 group companies as of September 2026. Its standalone net sales for the fiscal year ended April 2026 were JPY 2,435 million, with an operating income of JPY 635 million.
- Under this platform, Colors Japan will be responsible for deal sourcing, initial due diligence, and operational improvements, while THE WHY HOW DO COMPANY will make acquisition decisions, provide governance and compliance, and co-manage operations.
- Acquisition funding is primarily expected to be through bank loans, aiming for stable income (income gain) and capital gains from future transfers to investors.
🤖 AI Perspective
This business alliance could be seen as a strategic move by THE WHY HOW DO COMPANY to expand its M&A deal pipeline and diversify its revenue streams, complementing its existing long-term holding M&A strategy. The combination of Colors Japan’s proven M&A track record and PMI expertise with THE WHY HOW DO COMPANY’s listed company governance framework may suggest a strong potential to address SME succession challenges and generate new profits. Investors might monitor how this platform contributes to the company’s M&A execution capabilities and the realization of concrete results moving forward.
Disclaimer: This article is for informational purposes only and does not constitute investment advice.
5122|オカモト
6300.0
▼ -1.56%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Okamoto announced on October 14, 2026, that its Board of Directors resolved to acquire shares of OKEHO SAS, a French sales agency, making it a subsidiary.
- The acquisition aims to strengthen Okamoto’s business foundation in Europe and achieve medium- to long-term business growth.
- OKEHO SAS is located in France, engages in sales agency and brokerage business, has a capital of 2,000 euros, was established in September 2009, and is 100% owned by Richard Robin.
- Okamoto will acquire 200 shares, representing 100.0% of voting rights, for an acquisition cost of 300,000 euros (¥54 million) for ordinary shares of OKEHO SAS, plus an estimated ¥3 million for advisory fees, totaling approximately ¥57 million.
- The scheduled contract signing date is November 20, 2026, and the share transfer execution date is December 15, 2026.
🤖 AI Perspective
Okamoto’s acquisition of OKEHO SAS, a long-standing European sales agency, appears to be a strategic move to bolster its sales network and customer base in the European market. This action suggests an intention to strengthen its direct sales capabilities and expand its business in Europe, identifying it as a crucial overseas market alongside China, Asia, and the Americas. Investors may view this as a step towards enhancing market presence and potentially introducing new products to drive revenue growth in the region.
7879|ノダ
667.0
▲ +0.00%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- NODA’s consolidated net sales for the third quarter of the fiscal year ending November 2026 (December 1, 2025 to August 31, 2026) increased by 2.0% year-on-year to ¥48,294 million.
- Operating profit reached ¥206 million (vs. ¥3 million in the prior year period), and ordinary profit was ¥20 million (vs. ordinary loss of ¥25 million in the prior year period), both turning profitable.
- Net profit attributable to owners of parent significantly improved to ¥557 million, compared to a net loss of ¥472 million in the same period last year.
- By segment, Wood Building Materials recorded sales of ¥29,169 million (down 0.2% YoY) and segment profit of ¥396 million (down 20.6% YoY). Plywood business sales were ¥19,124 million (up 5.6% YoY) and segment profit was ¥1,215 million (up 80.9% YoY).
- The full-year consolidated performance forecast for FY2026 has been revised: net sales of ¥65,000 million (up 0.5% YoY), operating profit of ¥400 million, ordinary profit of △¥100 million, and net profit attributable to owners of parent of △¥100 million (EPS of △¥6.65).
🤖 AI Perspective
NODA’s Q3 FY2026 results show a significant turnaround in profitability, with operating and net profits turning positive from losses in the prior year. The plywood business appears to be a strong driver, with segment profit increasing by over 80%. However, the revision of the full-year forecast, particularly the projected ordinary and net losses, suggests ongoing challenges that investors may need to monitor.
464A|G-QPSHD
1441.0
▼ -1.03%
📎 Source:G-QPSHD Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- G-QPSHD reported consolidated results for the first quarter of the fiscal year ending May 2027 (June 1, 2026 – August 31, 2026), with net sales of ¥1.895 billion (up 445.8% year-on-year) and operating profit of ¥594 million (compared to a loss of ¥410 million in the prior-year period).
- The company achieved a turnaround to profitability from a loss in operating profit, with ordinary profit reaching ¥530 million and net profit for the period at ¥480 million.
- The “Satellite Constellation Development and Operation Project” for the Ministry of Defense proceeded smoothly, contributing to the increase in net sales.
- QPS-SAR satellites 13 “Mikura-I” and 18 “Susanoo-II” were successfully launched in August 2026, bringing the total number of operational satellites in orbit to 11.
- The full-year consolidated performance forecast for the fiscal year ending May 2027 was revised, with business revenue now projected at ¥11.5 billion (previously ¥12.0 billion) and operating profit at ¥2.0 billion (previously ¥300 million). The operating profit projection was revised upward.
🤖 AI Perspective
G-QPSHD’s Q1 FY2027 results, featuring substantial revenue growth and a return to profitability, suggest positive momentum in its operations. The successful execution of projects for the Ministry of Defense and continued satellite launches could indicate a strengthening of its revenue base. The upward revision of the full-year operating profit forecast, attributed to a review of cost plans and revenue recognition timing, may suggest improved operational efficiency and certainty within the business.
9337|G-トリドリ
1475.0
▲ +0.07%
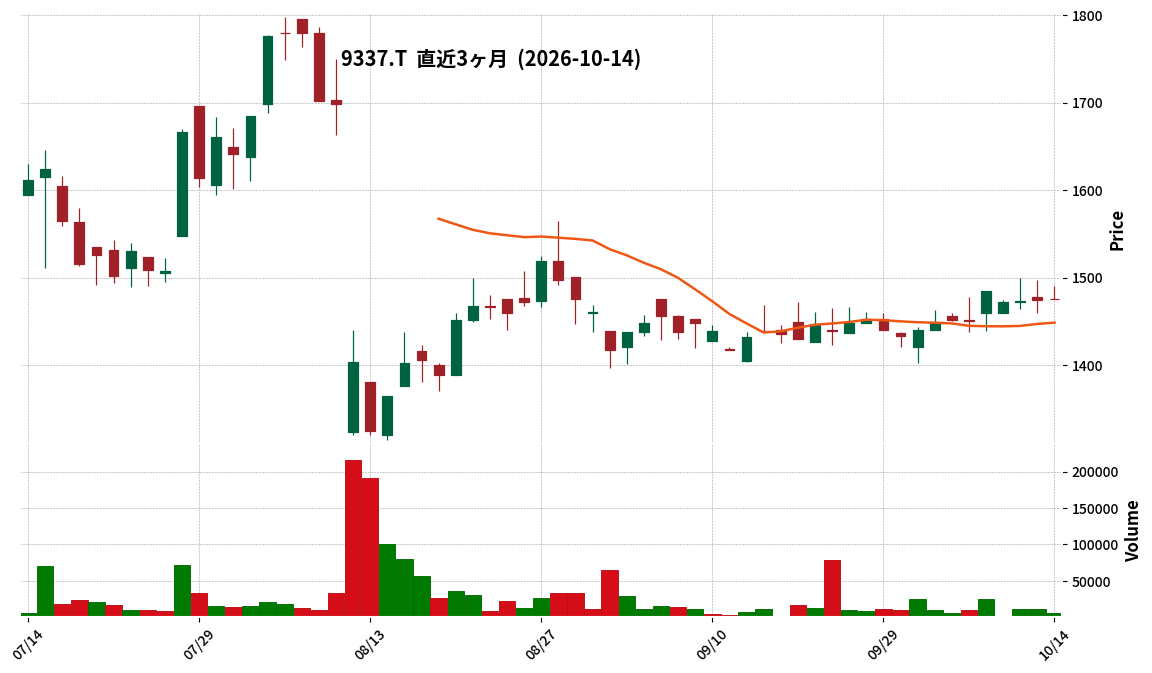
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- G-toridori Inc. resolved to merge its wholly-owned subsidiaries, Toridori IS Inc. and Vooster Inc., at a Board of Directors meeting held on October 14, 2026.
- The merger will be an absorption-type merger, with Toridori IS Inc. as the surviving company and Vooster Inc. as the dissolving company.
- The effective date of the merger is December 1, 2026.
- The new company name after the merger will be “Toridori Platforms Inc.”, with its head office located at 28-1 Maruyama-cho, Shibuya-ku, Tokyo, and capital of 10,000 thousand yen.
- As this merger is between consolidated subsidiaries, the impact on G-toridori’s consolidated financial performance is deemed minor.
🤖 AI Perspective
This merger aims to integrate Vooster, responsible for developing the AI-powered influencer advertising service “Vooster,” with Toridori IS, which handles its sales, establishing a unified development and sales structure. This move is intended to strengthen “Vooster’s” sales system, accelerate product development based on advertiser needs, and streamline decision-making and operational efficiency. The Toridori Group appears to be positioning this merger as a strategic step to enhance its mid-to-long-term corporate value.
💡 Start investing with IR insights


※ 本ページには広告が含まれます(PR)
Disclaimer: This article is for informational purposes only and does not constitute investment advice. All investment decisions are at your own risk.
コメント