📌 Today’s Highlights
Today we cover 76 IR announcements. Notable among them: G-ニフティライフ (4262), アルインコ (5933), ノジマ (7419). Use the table of contents below to navigate to each company.
- 4262|G-ニフティライフ
- 5933|アルインコ
- 7419|ノジマ
- 9022|JR東海
- 4043|トクヤマ
- 6723|ルネサス
- 1458|楽天225ダブルブル
- 6516|山洋電気
- 6902|デンソー
- 4205|日ゼオン
- 7326|G-SBIインシュ
- 8622|水戸証
- 5471|大同特鋼
- 4528|小野薬
- 7939|研創
- 8613|丸三証
- 4221|大倉工
- 4345|シーティーエス
- 4507|塩野義薬
- 4549|栄研化
- 7259|アイシン
- 3116|トヨタ紡織
- 4826|CIJ
- 5832|ちゅうぎんFG
- 7989|立川ブライ
- 8708|アイザワ証G
- 9534|北海瓦斯
- 9701|東京会館
- 9818|大丸エナ
- 4366|ダイトーケミックス
- 6301|コマツ
- 5482|愛知鋼
- 1959|クラフティア
- 6436|アマノ
- 6473|ジェイテクト
- 8071|東海エレ
- 9914|植松商会
- 2175|SMS
- 2491|Vコマース
- 2533|オエノンHD
- 2914|JT
- 3426|アトムリビン
- 4307|NRI
- 4502|武田薬
- 4552|JCRファーマ
- 4582|G-シンバイオ製薬
- 6370|栗田工
- 6702|富士通
- 6754|アンリツ
- 6810|マクセル
- 7191|イントラスト
- 7388|FPパートナー
- 1946|トーエネック
- 2811|カゴメ
- 7357|ジオコード
- 7950|デコラックス
- 3174|ハピネス&D
- 4290|PI
- 4755|楽天グループ
- 5819|カナレ電気
- 6861|キーエンス
- 7775|大研医器
- 7962|キングジム
- 7984|コクヨ
- 8151|東陽テクニカ
- 8894|REVOLUTION
- 8898|センチュリー21
- 9502|中部電力
- 9558|G-ジャパニアス
- 6111|旭精機
- 2989|R-東海道リート
- 5029|G-サークレイス
- 7148|FPG
- 7185|ヒロセ通商
- 8163|SRSHD
- 4380|G-Mマート
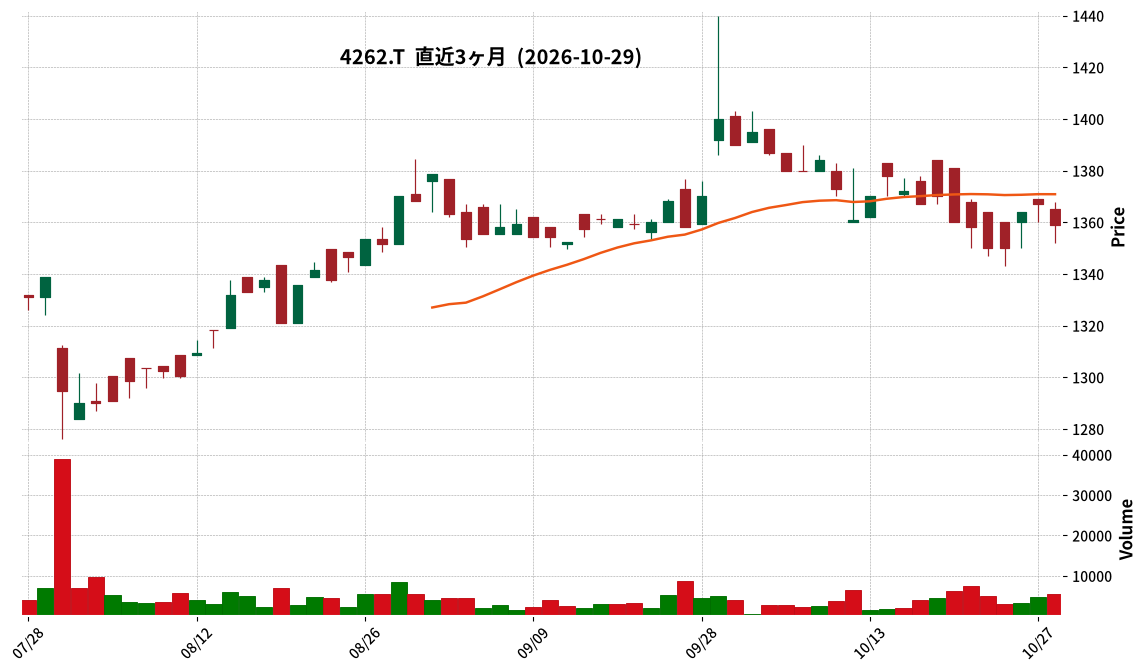
4262|G-ニフティライフ
1359.0
▼ -0.59%
📎 Source:G-ニフティライフ Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Consolidated revenue for the second quarter of FY2027 (interim) reached ¥2,617 million, marking a 6.7% increase year-on-year and a new record high.
- Operating profit was ¥341 million (down 28.0% YoY), ordinary profit was ¥351 million (down 26.0% YoY), and net income attributable to owners of parent was ¥184 million (down 38.4% YoY).
- EBITDA was ¥527 million (down 23.4% YoY). The decrease was attributed to increased amortization expenses due to M&A advancements.
- Two new companies, Replis Inc. and Asfur Inc., were added to the scope of consolidation.
- The forecast for the full-year dividend for FY2027 remains unchanged from the most recently announced forecast, with an interim dividend of ¥32.00 and a year-end dividend of ¥32.00, totaling ¥64.00.
🤖 AI Perspective
G-ニフティライフ’s Q2 FY2027 results show record-high revenue alongside a decline in various profit metrics. This performance is largely attributed to increased amortization expenses stemming from M&A activities. The expansion of the business through new consolidations and the resulting shift in the cost structure could be key factors to monitor for future performance.
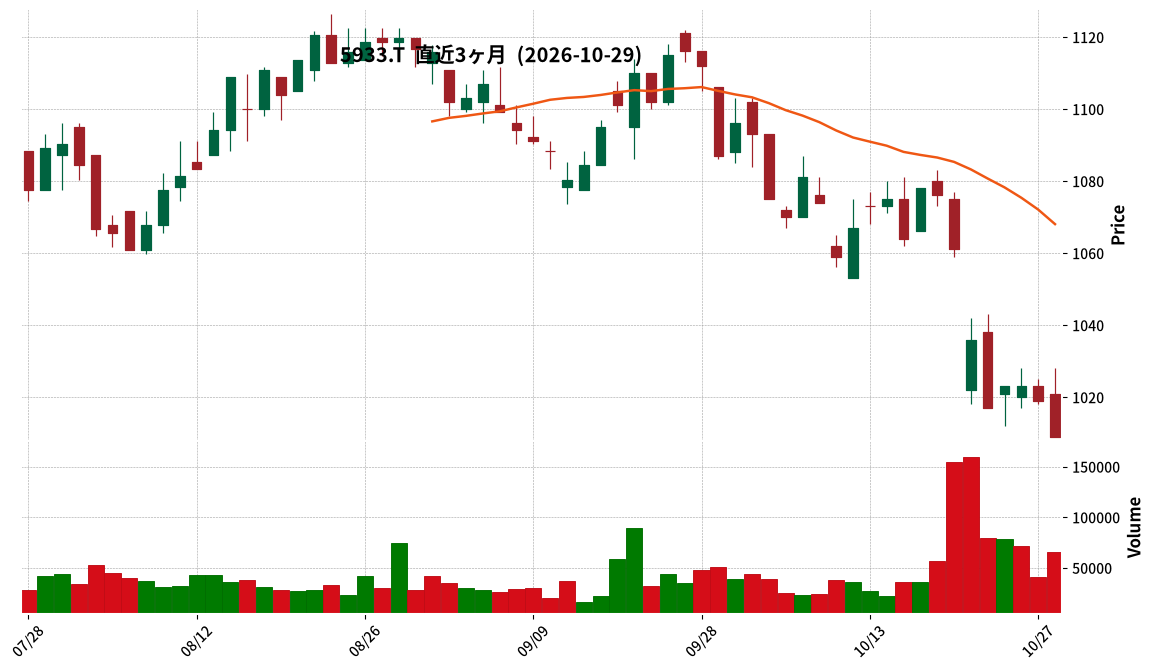
5933|アルインコ
1009.0
▼ -0.98%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- ALINCO announced its consolidated results for the second quarter of FY2027, reporting net sales of ¥33,024 million (up 4.0% year-on-year) and operating profit of ¥1,407 million (up 12.0% year-on-year).
- Ordinary profit was ¥1,317 million (down 7.4% year-on-year), and net income attributable to owners of the parent was ¥897 million (down 2.4% year-on-year).
- The Construction Equipment segment and Rental segment showed increased revenue and profit, with the Construction Equipment segment recording sales of ¥14,352 million (up 10.8% year-on-year) and segment profit of ¥1,569 million (up 55.5% year-on-year).
- The company is fully deploying its RFID/NFC hybrid temporary equipment management system “Milltag” and aims to launch the “(tentative name) AI Quantity Surveying” system in collaboration with KK Generation around spring 2027.
- ALINCO was certified as a “DX Certified Business Operator” by the Ministry of Economy, Trade and Industry on August 1, 2026, and invested approximately ¥800 million to establish a new automatic production line for hooked scaffolding boards at its Hyogo Plant, which became fully operational in August 2026.
🤖 AI Perspective
ALINCO’s Q2 FY2027 results indicate solid performance in net sales and operating profit, primarily driven by its core construction equipment and rental businesses. However, ordinary profit and net income declined, potentially influenced by a decrease in foreign currency-denominated asset valuations and exchange rate losses, suggesting a sensitivity to global economic shifts. The strategic focus on new technology adoption, capital expenditure, and DX promotion could strengthen its competitive position for future growth.
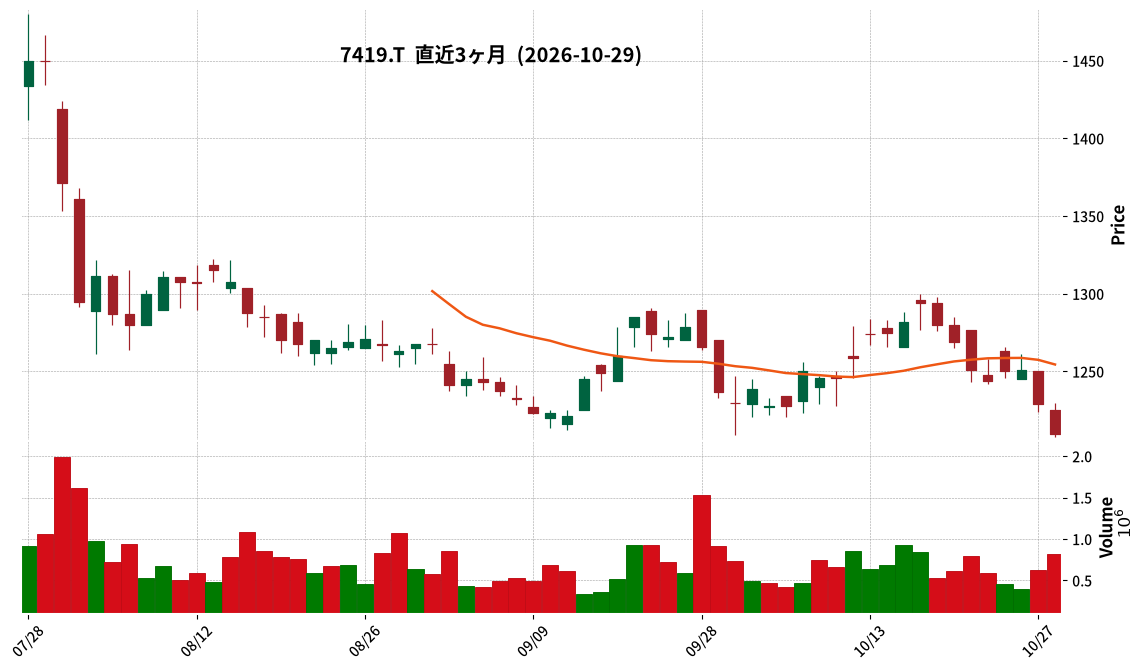
7419|ノジマ
1210.0
▼ -1.55%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Nojima announced its consolidated financial results for the second quarter (interim period) of the fiscal year ending March 2027.
- Consolidated net sales reached ¥503,756 million, an 8.9% increase year-over-year, exceeding ¥500 billion for the first time since listing.
- Operating profit was ¥32,542 million (up 17.6% YoY), ordinary profit was ¥49,502 million (up 61.7% YoY), and net profit attributable to owners of parent was ¥33,590 million (up 72.9% YoY). Sales, operating profit, and ordinary profit all marked new record highs.
- EBITDA also reached a record high of ¥61,308 million, a 44.0% increase year-over-year.
- The full-year consolidated earnings forecast for the fiscal year ending March 2027 was revised upward, projecting net sales of ¥1,060,000 million (up 7.9% YoY), operating profit of ¥65,000 million (up 11.9% YoY), ordinary profit of ¥83,000 million (up 33.2% YoY), and net profit attributable to owners of parent of ¥54,000 million (up 38.7% YoY).
- N Credit Finance Corporation was newly added to the scope of interim consolidation.
🤖 AI Perspective
Nojima’s interim results demonstrate robust growth, with net sales surpassing ¥500 billion for the first time and key profit metrics setting new records. The significant increase in ordinary profit (up 61.7% YoY) may suggest effective business strategies or improved operational efficiency. The upward revision of the full-year earnings forecast could indicate the company’s confidence in its future performance and market outlook.
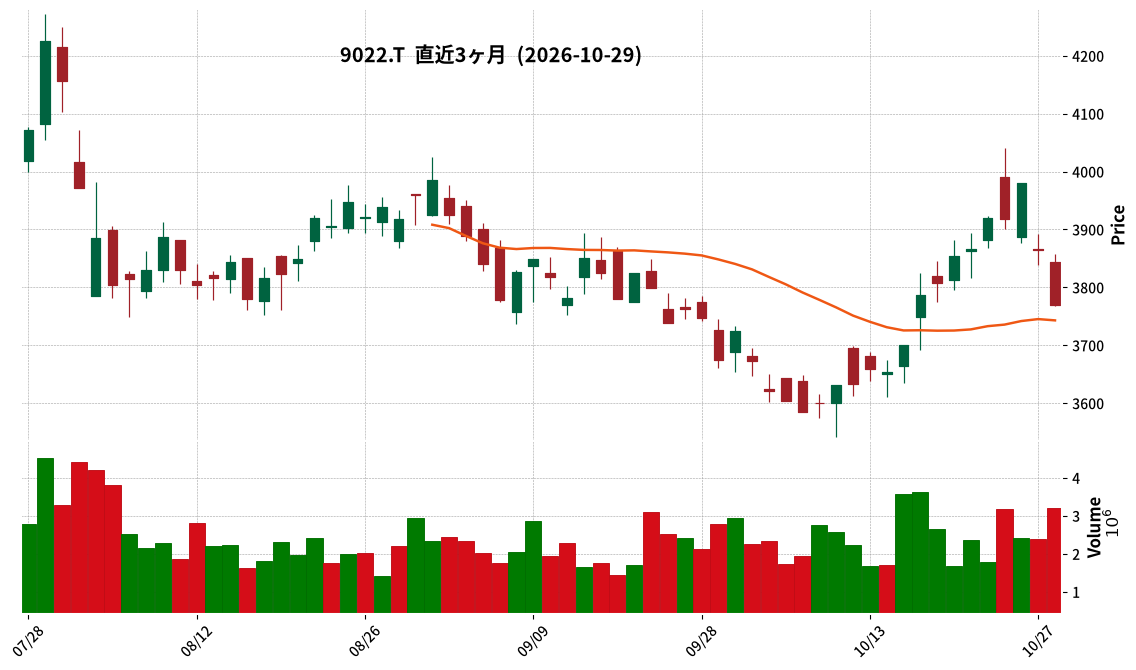
9022|JR東海
3770.0
▼ -2.43%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- For the second quarter (interim period) of the fiscal year ending March 2027, JR Central reported increased revenue but decreased profit on both a non-consolidated and consolidated basis.
- Transportation revenue for the first half increased by 1% year-on-year, primarily driven by a 5% increase in domestic usage and a 1% increase in inbound travel, despite a 5% negative impact from the Osaka-Kansai Expo.
- The full-year earnings forecast for revenue and all profit categories has been revised upward for both non-consolidated and consolidated results.
- Shareholder returns include an interim and year-end dividend of ¥17 per share, an increase of ¥1 from the initial forecast, and a new share buyback program with an upper limit of ¥10 billion, in addition to the approximately ¥20 billion already executed.
- Immediate growth strategies include increasing “Nozomi” train frequencies, revising “Nozomi” fares from July 2027 (projected annual revenue increase of ¥35-40 billion), and revising “Green Car” fares from December 2027 (projected annual revenue increase of ¥15-20 billion).
🤖 AI Perspective
JR Central’s announcement of an upward revision to its full-year earnings guidance, coupled with an increased dividend and a new share buyback program, could be viewed favorably by investors despite the interim period’s mixed results. The outlined growth strategies, focusing on the Tokaido Shinkansen through increased “Nozomi” frequencies, fare revisions, and the introduction of Supreme Class, suggest a proactive approach to enhancing long-term revenue streams. These strategic initiatives may indicate the company’s confidence in future profitability and are worth monitoring for their impact on the company’s financial performance.
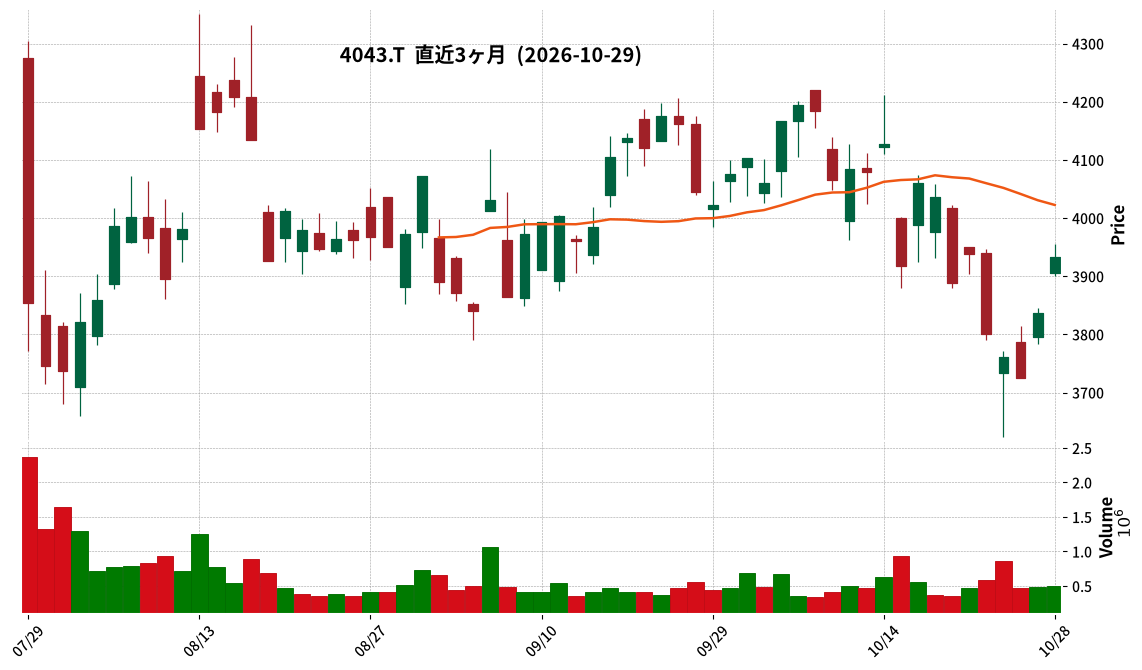
4043|トクヤマ
3933.0
▲ +2.53%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Tokuyama announced its consolidated financial results for the second quarter (interim period) of the fiscal year ending March 2027.
- Consolidated net sales totaled ¥178,676 million, a 9.1% increase compared to the same interim period of the previous year.
- Consolidated operating profit was ¥13,564 million (a 29.2% decrease YoY), and consolidated ordinary profit was ¥13,546 million (a 28.5% decrease YoY).
- Net profit attributable to owners of the parent reached ¥9,981 million, a 17.8% decrease from the previous interim period.
- The full-year consolidated performance forecast and annual dividend forecast have been revised, with the full-year dividend projected at ¥140 per share (interim ¥60, year-end ¥80).
- The increase in net sales is primarily attributed to the consolidation of the Tokuyama Life Science Group and increased sales of semiconductor-related products.
- The decrease in operating profit is explained by rising raw material and fuel costs, as well as increased general and administrative expenses and logistics costs associated with the Tokuyama Life Science Group consolidation.
🤖 AI Perspective
While Tokuyama reported an increase in net sales for the interim period, the decline in operating profit, ordinary profit, and net profit attributable to owners of the parent is a key point for investors. This suggests that rising raw material costs and increased expenses from the consolidation of the Life Science Group have impacted profitability. The concurrent revision of full-year performance and dividend forecasts indicates that market conditions and cost management will be important areas for investors to monitor going forward.
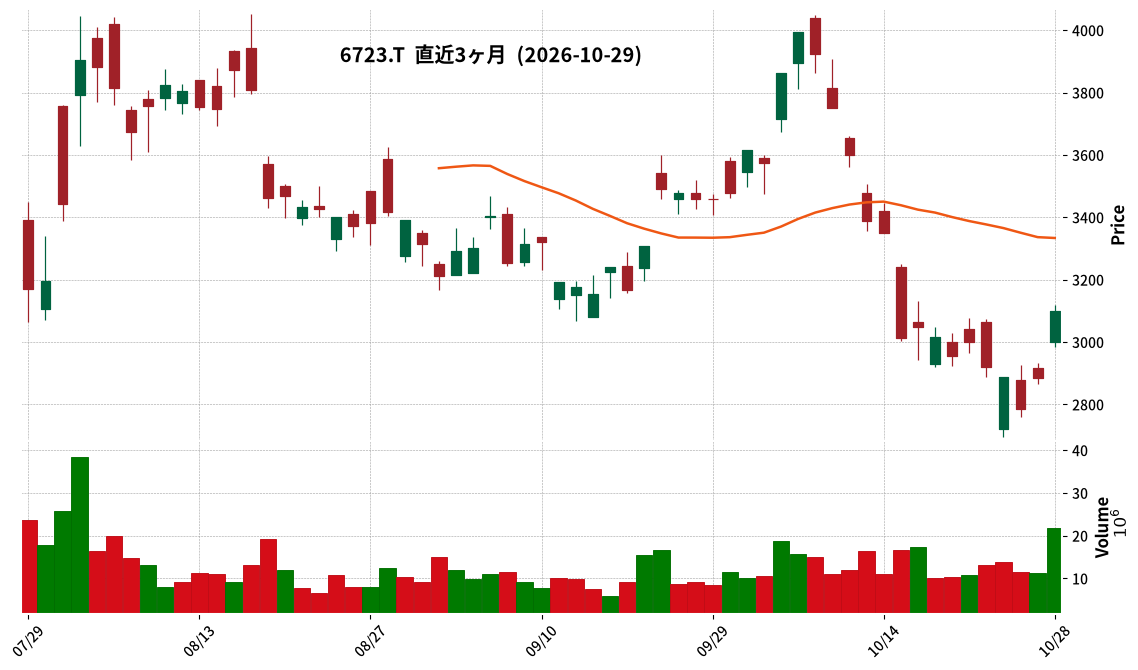
6723|ルネサス
3100.0
▲ +7.47%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- For the third quarter of the fiscal year ending December 2026 (January 1, 2026, to September 30, 2026), consolidated revenue reached ¥1,234,659 million, marking a 27.3% increase compared to the prior year.
- Consolidated operating profit for the same period was ¥757,991 million, a substantial increase of 466.0% year-on-year.
- Quarterly profit attributable to owners of the parent company amounted to ¥589,526 million, reversing a loss from the prior year.
- Basic earnings per share for the quarter were ¥323.53, and diluted earnings per share were ¥318.18.
- The consolidated full-year performance forecast for fiscal year 2026 (Non-GAAP basis) projects revenue between ¥1,659,281 million and ¥1,674,281 million (an increase of 25.8% to 27.0% year-on-year), with a Non-GAAP gross profit margin of 58.6% and a Non-GAAP operating profit margin of 33.2%.
- The forecast for the annual dividend for the fiscal year ending December 2026 remains ¥28.00 per share for the year-end, with no revisions from the most recently announced forecast.
🤖 AI Perspective
The significant year-on-year increases in both revenue and operating profit reported in this earnings announcement suggest strong business performance. The notable turnaround from a loss to a substantial profit attributable to owners of the parent company could be a key point of interest for investors. The full-year Non-GAAP outlook also indicates continued robust performance, making future business developments worth monitoring.
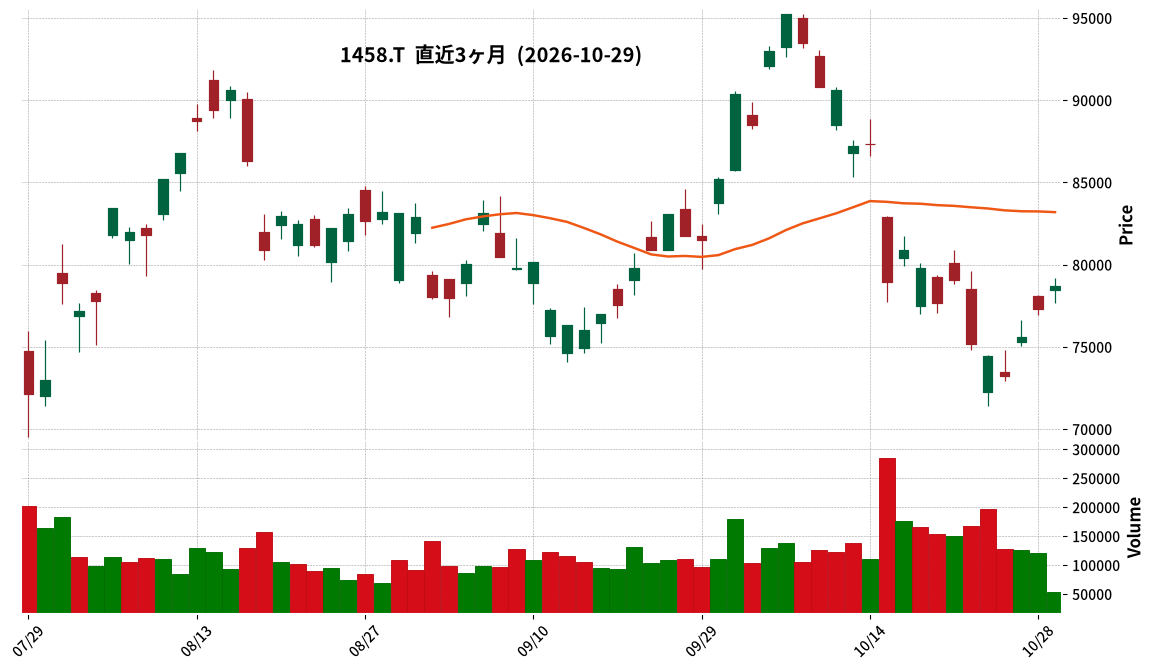
1458|楽天225ダブルブル
78700.0
▲ +1.81%
📎 Source:楽天225ダブルブル Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Rakuten ETF-Nikkei Leveraged Index Linked (1458) announced its interim financial results for the fiscal year ending March 2027 (March 16, 2026 to September 15, 2026).
- As of the end of the interim accounting period (September 15, 2026), total net assets were ¥49,549,314,639.
- The net asset value per 100 units was recorded at ¥7,596,093.
- The number of outstanding units at the end of this interim accounting period is 652 thousand units.
- Total operating revenue was ¥9,713,875,769, total operating expenses were ¥85,709,228, and interim net income was ¥9,628,166,541.
🤖 AI Perspective
These interim results indicate an increase in both net assets and net asset value per unit compared to the previous period, suggesting growth in the fund’s asset size. The significant rise in the net asset value per 100 units may draw attention to the fund’s operational performance. Additionally, the decrease in outstanding units could indicate shifts in investor supply and demand dynamics, which is worth monitoring.
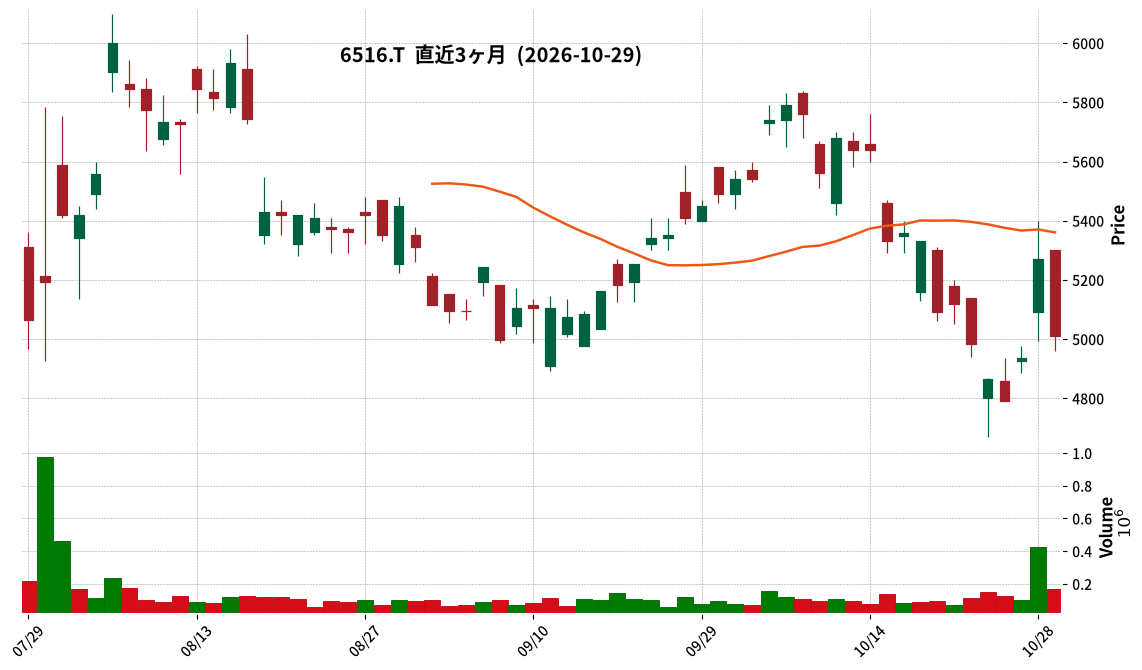
6516|山洋電気
5010.0
▼ -4.93%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- San-Ei Electric Co., Ltd. announced its consolidated financial results for the second quarter (interim period) of the fiscal year ending March 2027.
- Consolidated revenue reached 66,016 million yen, marking a 30.0% increase compared to the prior interim period.
- Profit attributable to owners of the parent company rose to 6,361 million yen, an 81.3% increase year-on-year.
- Segment-wise, San Ace Company reported revenue of 24,038 million yen (up 18.4%), Electronics Company 13,699 million yen (up 33.0%), and Motion Company 25,142 million yen (up 43.0%).
- The full-year consolidated earnings forecast for the fiscal year ending March 2027 remains unchanged from the most recently announced forecast, with revenue projected at 142,250 million yen (up 32.5% year-on-year) and profit attributable to owners of the parent company at 14,150 million yen (up 63.4% year-on-year).
🤖 AI Perspective
San-Ei Electric’s robust interim performance for FY2027 appears to be significantly driven by strong demand for AI-related equipment and semiconductor manufacturing devices. The substantial increase in demand for generative AI-related equipment and data center equipment within the San Ace Company, alongside the expansion of demand for semiconductor manufacturing equipment and wafer transfer robots in both the Electronics and Motion Companies, are noteworthy. This suggests that the company’s future performance may continue to be influenced by trends in the AI market.
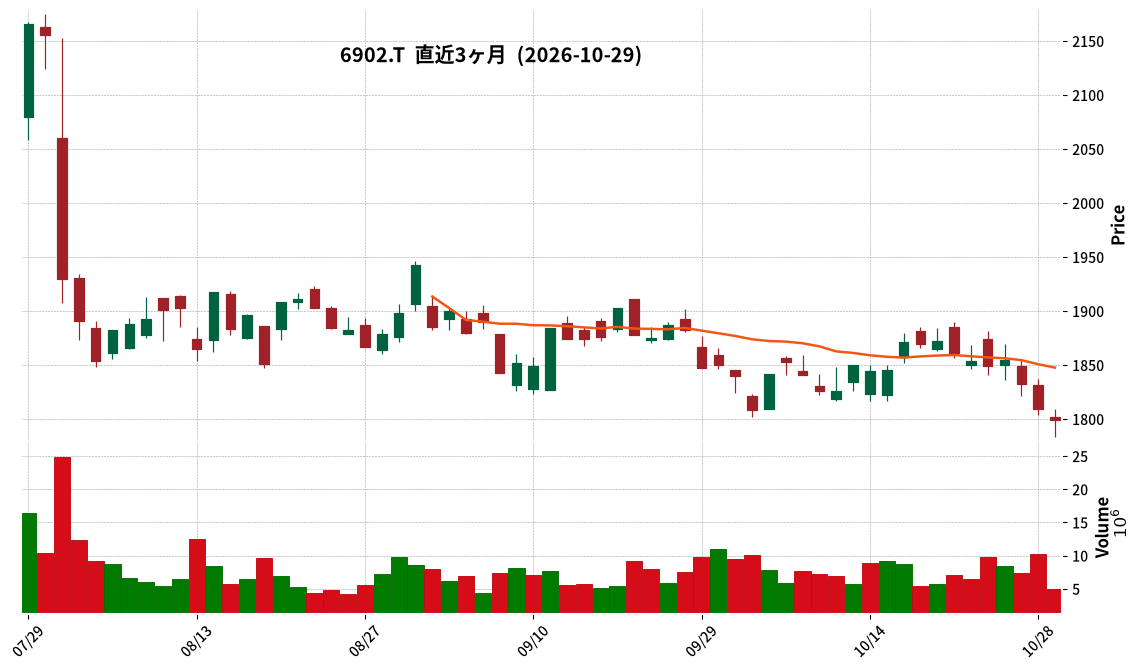
6902|デンソー
1799.0
▼ -0.55%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Denso Corporation announced its consolidated financial results for the second quarter (interim period) of the fiscal year ending March 2027 (April 1, 2026 – September 30, 2026).
- Revenue for the interim period was ¥3,843,550 million, a 7.0% increase compared to the same period in the previous year.
- Operating profit decreased by 19.5% to ¥170,147 million, and profit attributable to owners of the parent decreased by 8.8% to ¥119,794 million.
- The forecast for the annual dividend for the fiscal year ending March 2027 remains ¥74.00 per share (interim dividend of ¥37.00 and year-end dividend of ¥37.00), with no revisions from the most recently announced forecast.
- The full-year consolidated performance forecast for the fiscal year ending March 2027 also remains unchanged, with revenue projected at ¥7,750,000 million and operating profit at ¥500,000 million.
🤖 AI Perspective
Denso’s interim results show a revenue increase, driven by higher vehicle sales and the weaker yen, but a decline in profits attributed to rising material costs, increased R&D investments, and a one-off factor from the previous year. With the full-year forecast maintained, the focus for investors may shift to the company’s ability to achieve profitability improvements in the second half through rationalization efforts and favorable currency movements.
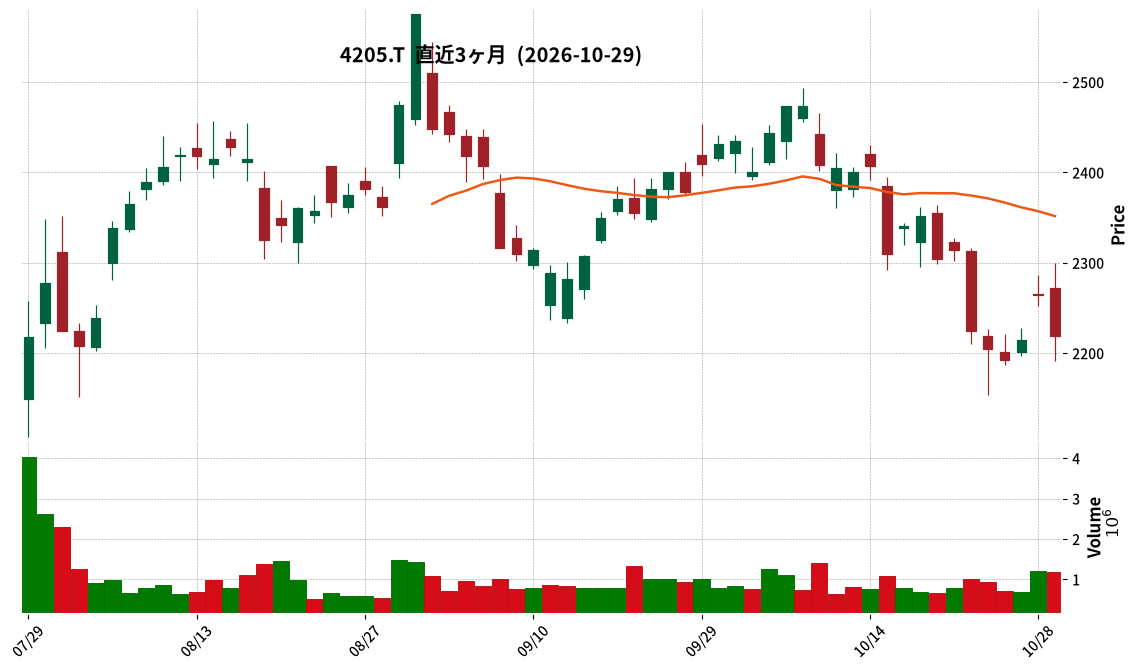
4205|日ゼオン
2218.5
▼ -2.03%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Zeon Corporation reported consolidated results for the second quarter (interim period) of the fiscal year ending March 2027, with net sales of ¥224,872 million (up 8.9% year-on-year), operating profit of ¥31,921 million (up 65.0%), ordinary profit of ¥33,562 million (up 75.4%), and profit attributable to owners of parent of ¥26,274 million (up 17.8%).
- The Elastomer Materials business segment recorded net sales of ¥120,426 million (up ¥7,881 million year-on-year) and operating profit of ¥10,789 million (up ¥4,285 million).
- The High-Performance Materials business segment recorded net sales of ¥70,114 million (up ¥7,810 million year-on-year) and operating profit of ¥19,154 million (up ¥7,424 million).
- The full-year consolidated earnings forecast for the fiscal year ending March 2027 has been revised, projecting net sales of ¥430,000 million (up 4.4% year-on-year), operating profit of ¥45,500 million (up 25.1%), ordinary profit of ¥46,500 million (up 16.1%), and profit attributable to owners of parent of ¥43,000 million (up 18.7%).
- The dividend forecast for the fiscal year ending March 2027 is ¥39.00 per share for the interim period and a projected ¥40.00 per share for the fiscal year-end, totaling ¥79.00 per share for the year.
🤖 AI Perspective
The interim financial results show significant increases in revenue and all profit metrics compared to the previous year, with operating profit demonstrating particularly strong growth. The High-Performance Materials business segment appears to be a key driver for both sales and operating profit increases. The revision of the full-year earnings forecast provides updated insights into the company’s future outlook.
Disclaimer: This article is for informational purposes only and does not constitute investment advice.
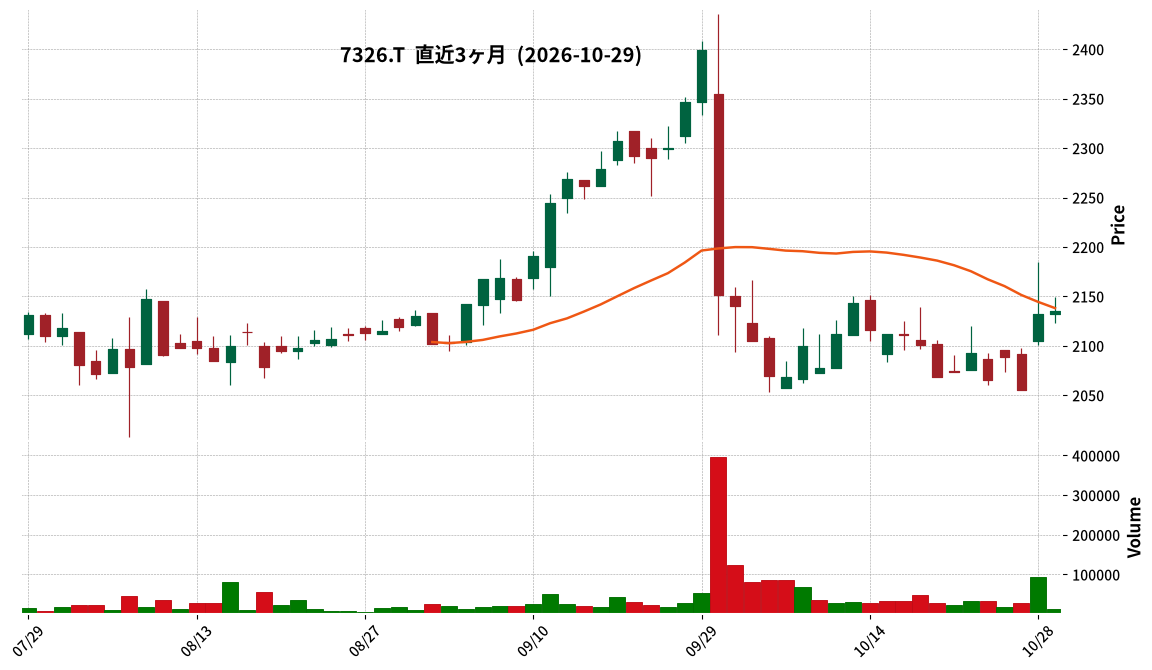
7326|G-SBIインシュ
2135.0
▲ +0.14%
📎 Source:G-SBIインシュ Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- G-SBI Insurance Group has announced preliminary consolidated financial results for the interim period of the fiscal year ending March 2027 (April 1, 2026 – September 30, 2026).
- For this interim consolidated accounting period, ordinary revenue is projected to be JPY 78,631 million (up 13.6% year-on-year), ordinary profit JPY 9,209 million (up 26.0% year-on-year), and net income attributable to parent shareholders JPY 2,587 million (up 14.8% year-on-year).
- These key profit metrics are expected to set new record highs for an interim consolidated accounting period.
- The increase in ordinary revenue is primarily attributed to a steady rise in the number of in-force policies across all business segments (non-life insurance, life insurance, and small-amount short-term insurance).
- By segment, the life insurance business’s segment profit is expected to reach JPY 904 million, a significant increase of 92.5% year-on-year, partly due to favorable asset management performance.
🤖 AI Perspective
The preliminary interim consolidated financial results indicate that G-SBI Insurance is on track for record-high key profit figures, suggesting strong growth momentum for the company. The consistent increase in in-force policies across all segments, driving revenue growth, is a notable point, as is the substantial profit growth in the life insurance segment. Investors may find these results indicative of the company’s operational strength. The final financial announcement is scheduled for November 11, 2026, which will provide a comprehensive overview.
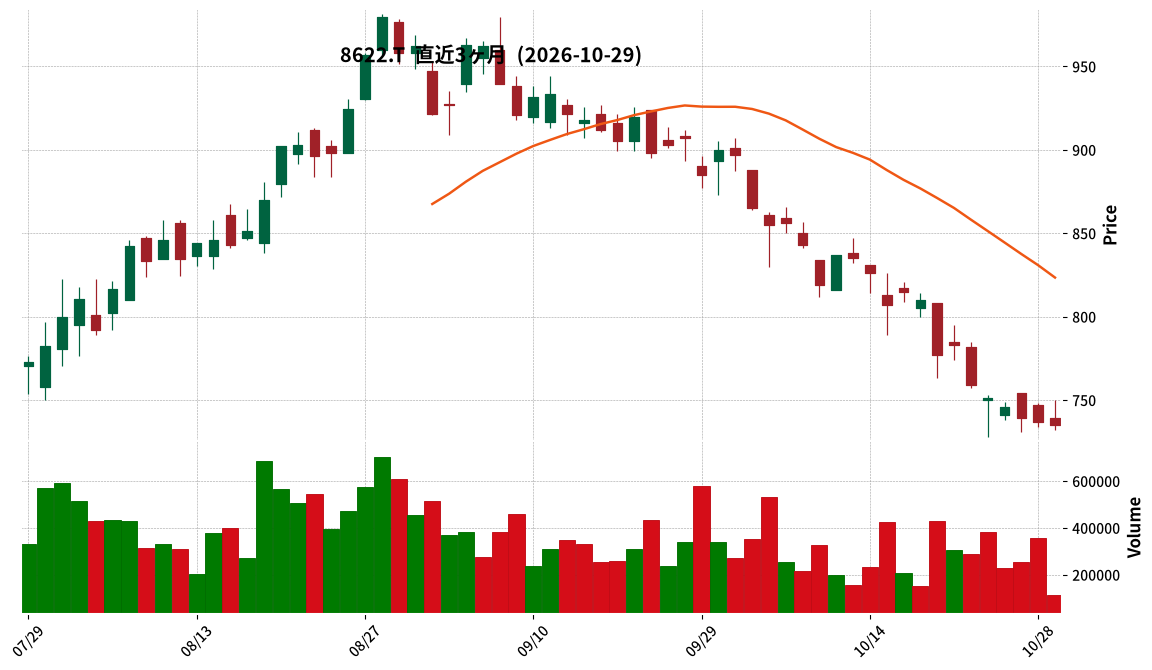
8622|水戸証
735.0
▼ -0.27%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Mito Securities reported operating revenue of ¥9.798 billion for the second quarter of FY2027 (interim period), a 33.4% increase year-on-year.
- Interim net income reached ¥1.923 billion, marking a 104.1% increase compared to the previous interim period.
- Interim net income per share was ¥32.03.
- The interim dividend is projected to be ¥20.00 per share, comprising an ordinary dividend of ¥17.00 and a 105th anniversary commemorative dividend of ¥3.00.
- The company announced a policy to set the minimum annual dividend per share at ¥30 for the five-year period of its Seventh Medium-Term Management Plan (FY2026 to FY2030).
🤖 AI Perspective
The significant year-on-year increase in both operating revenue and interim net income for this period suggests strong operational performance, potentially driven by favorable market conditions or strategic initiatives. The substantial growth in commissions received, up 34.7% overall, appears to be a key contributor to this positive trend. Furthermore, the commitment to a minimum annual dividend for the next five years could be viewed as a signal of confidence in future profitability and a robust shareholder return policy.
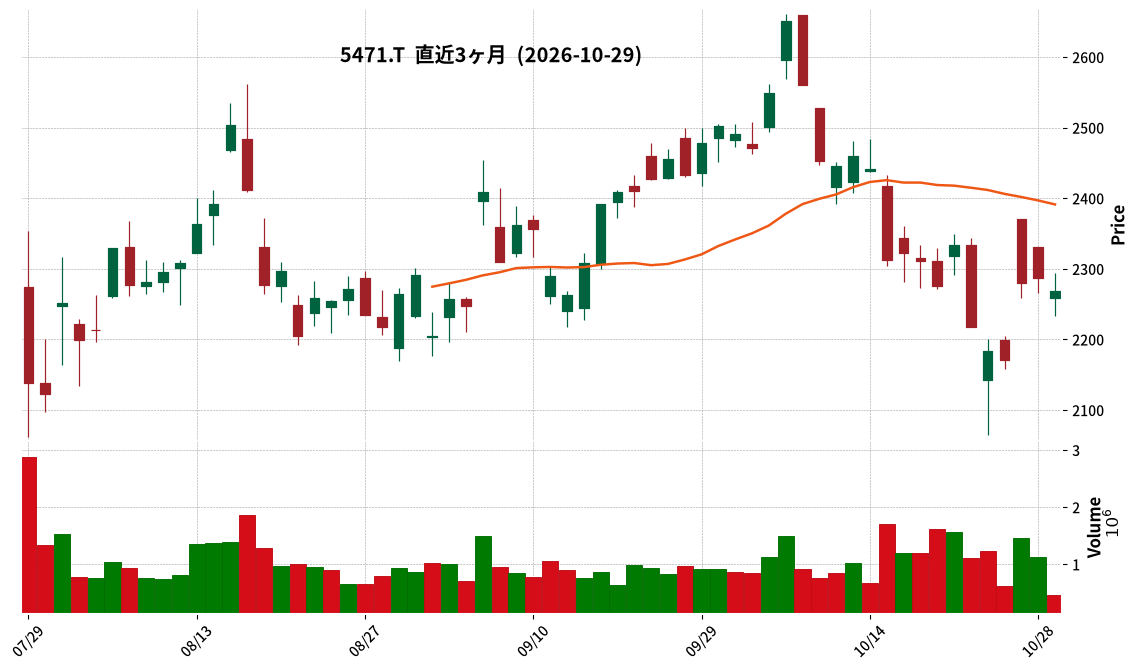
5471|大同特鋼
2269.0
▼ -0.77%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Daido Steel Co., Ltd. announced its consolidated financial results for the second quarter of the fiscal year ending March 2027.
- For the interim period, revenue was ¥330,652 million (up 16.2% year-on-year), operating profit was ¥26,068 million (up 41.2% year-on-year), and net profit attributable to owners of the parent company was ¥18,262 million (up 41.2% year-on-year).
- By segment, Functional Materials & Magnetic Materials and Automotive & Industrial Machinery Parts reported increased revenue and profit. Special Steels reported increased revenue but decreased profit, while Engineering reported decreased revenue and profit.
- The full-year consolidated performance forecast for the fiscal year ending March 2027 was revised, with revenue projected at ¥680,000 million and net profit attributable to owners of the parent company at ¥31,000 million.
- The dividend forecast was also revised, with the interim dividend per share for Q2 FY2027 set at ¥28.00 and the year-end dividend at ¥28.00, totaling ¥56.00 for the full year.
- Tohoku Special Steel Co., Ltd. was newly included in the scope of consolidation during this interim period.
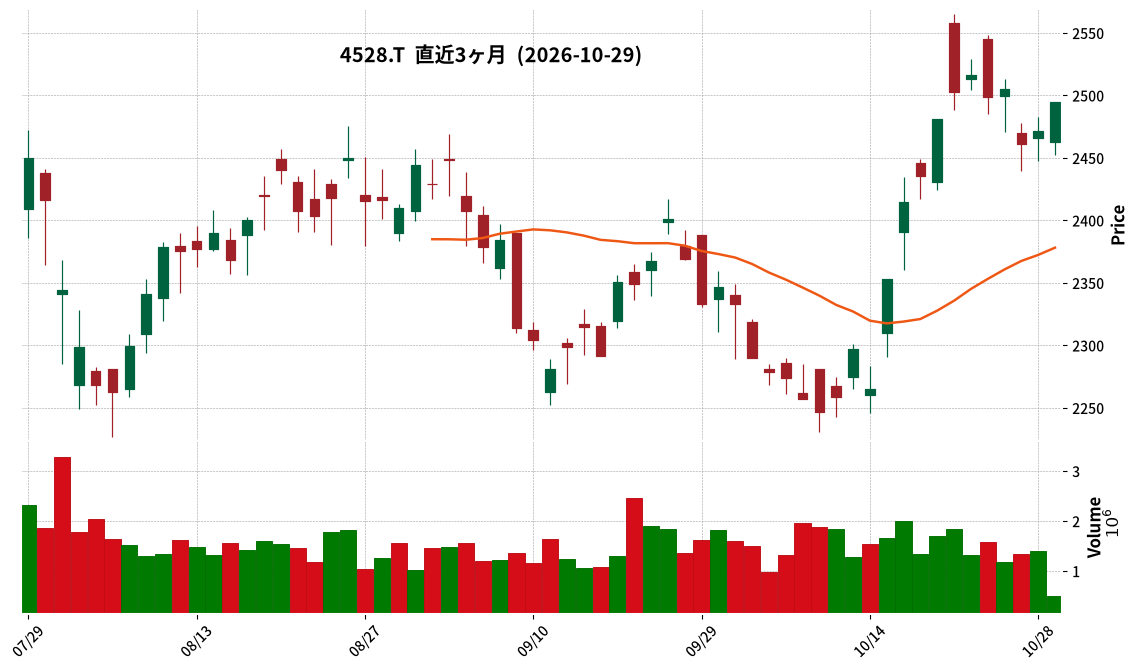
4528|小野薬
2494.5
▲ +0.93%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- For the second quarter of the fiscal year ending March 2027, consolidated revenue was ¥232,504 million, a 9.6% decrease from the prior interim period.
- IFRS (full) basis operating profit increased by 11.2% to ¥57,907 million, and interim profit attributable to owners of the parent increased by 12.1% to ¥44,930 million.
- On a core basis, core operating profit rose by 5.1% to ¥73,626 million, and core interim profit (attributable to owners of the parent) increased by 5.5% to ¥56,765 million.
- Domestic product sales decreased due to drug price revisions and the termination of the “Forxiga” co-promotion agreement, while overseas product sales increased due to strong performance of “Qinlock” and “Turalio (BL-Luvimza).”
- The full-year dividend forecast for the fiscal year ending March 2027 remains unchanged at ¥80 (interim ¥40, year-end ¥40).
🤖 AI Perspective
Ono Pharmaceutical’s H1 FY2027 results show a decline in revenue but an increase in both IFRS and core operating and interim profits, which is a key highlight for investors. This suggests the company effectively offset domestic sales reductions with growth in overseas products and royalties, alongside reduced selling, general and administrative expenses and R&D costs. The focus on cost efficiency and contributions from new products appear to have driven profitability, indicating potential stability in their profit structure moving forward.
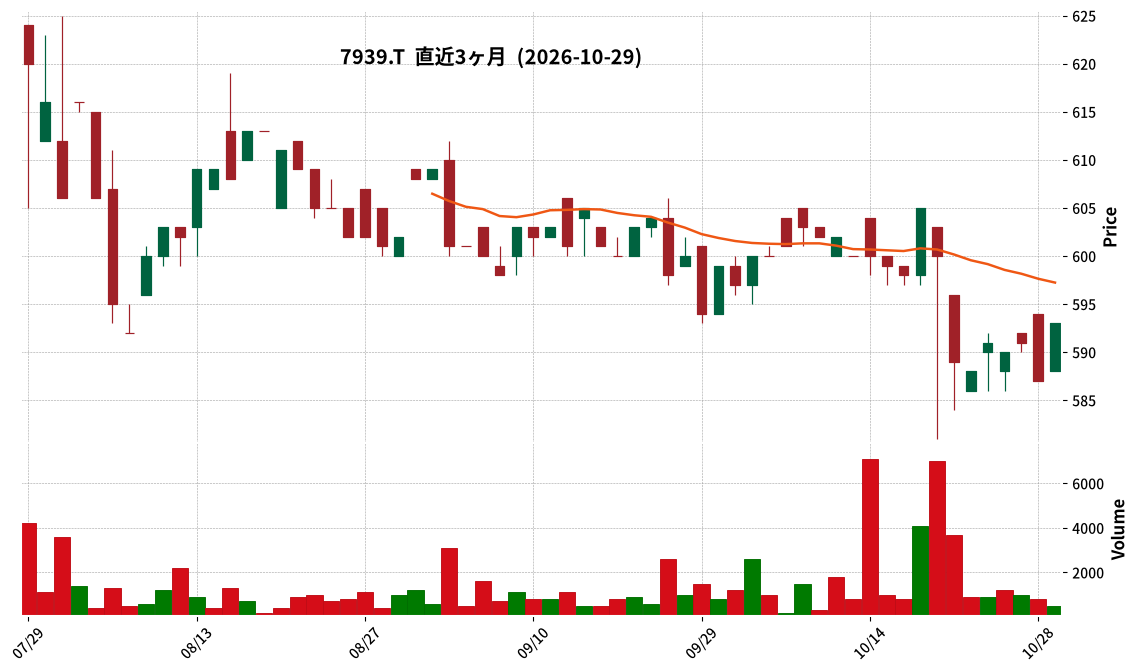
7939|研創
593.0
▲ +1.02%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Kensoh Co., Ltd. announced its Q2 FY2027 (interim period) financial results on October 29, 2026.
- For the interim period, net sales were ¥3,005 million (up 2.4% year-on-year), operating profit was ¥88 million (up 1.5%), ordinary profit was ¥83 million (up 0.4%), and interim net profit was ¥55 million (down 2.2%).
- Regarding the financial position, total assets at the end of the interim accounting period were ¥5,368 million, net assets were ¥3,363 million, and the equity ratio was 62.7%.
- The full-year forecast for FY2027 remains unchanged, projecting net sales of ¥6,555 million (up 2.2% year-on-year), operating profit of ¥333 million (up 29.3%), ordinary profit of ¥329 million (up 32.7%), and net profit of ¥222 million (up 7.6%).
- The annual dividend forecast for FY22027 remains at ¥23.00 for the year-end dividend (¥0.00 for the interim period), with no revisions from the previous forecast.
🤖 AI Perspective
While Kensoh reported increased sales and operating profit for the interim period, interim net profit slightly decreased. The company notes that demand for its sign products is seasonally skewed towards the second half of the fiscal year, which is a factor to consider when evaluating progress towards the full-year forecast. The improvement in the equity ratio may suggest strengthening financial health.
8613|丸三証
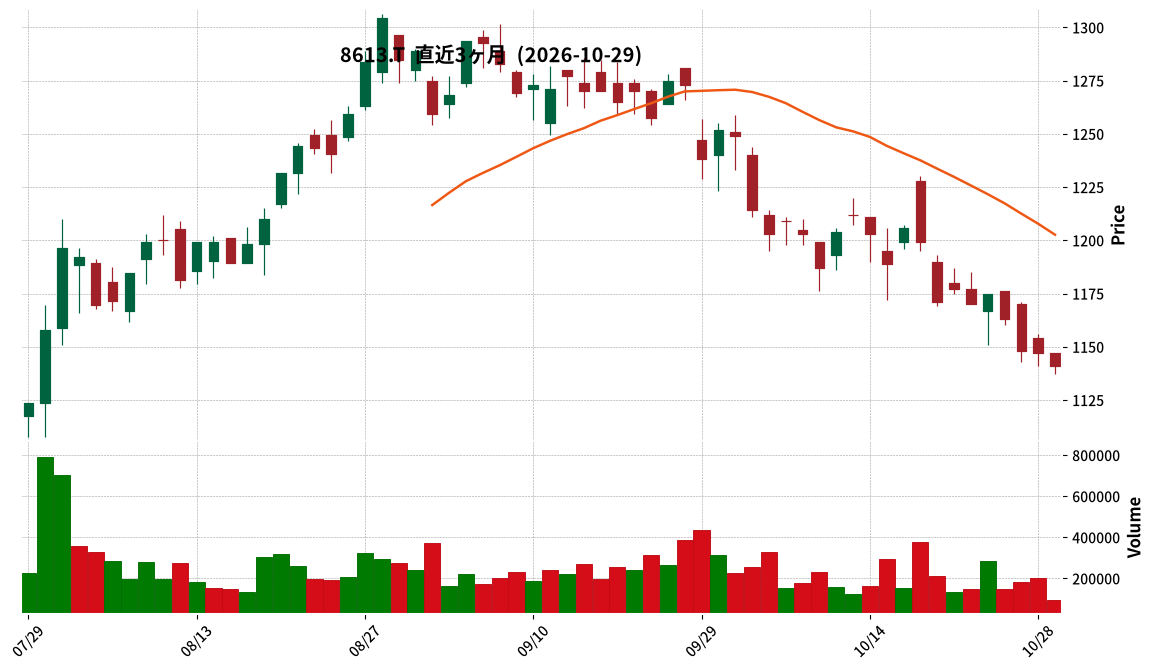
1141.0
▼ -0.52%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Marusan Securities Co., Ltd. officially determined its interim dividend (ordinary and special) for the fiscal year ending March 2027 at a Board of Directors meeting held on October 29, 2026.
- The interim dividend per share, based on the record date of September 30, 2026, will be ¥21.00 for ordinary dividends and ¥15.00 for special dividends, totaling ¥36.00.
- This decided amount remains unchanged from the most recent dividend forecast announced on September 15, 2026.
- The total dividend amount is ¥2,392 million, with an effective date of December 1, 2026.
- The company reiterated its plan to continue implementing an annual special dividend of ¥30 (¥15 interim, ¥15 year-end) from the interim dividend of the fiscal year ending March 2024 through the year-end dividend of the fiscal year ending March 2029.
🤖 AI Perspective
This announcement indicates that Marusan Securities’ interim dividend for the fiscal year ending March 2027 has been officially determined as previously forecast. The reaffirmation of the special dividend’s continuation until the fiscal year ending March 2029 may suggest a stable, long-term commitment to shareholder returns. The ordinary dividend exceeding the previous year’s actual result could reflect the company’s policy of linking ordinary dividends to performance.
4221|大倉工
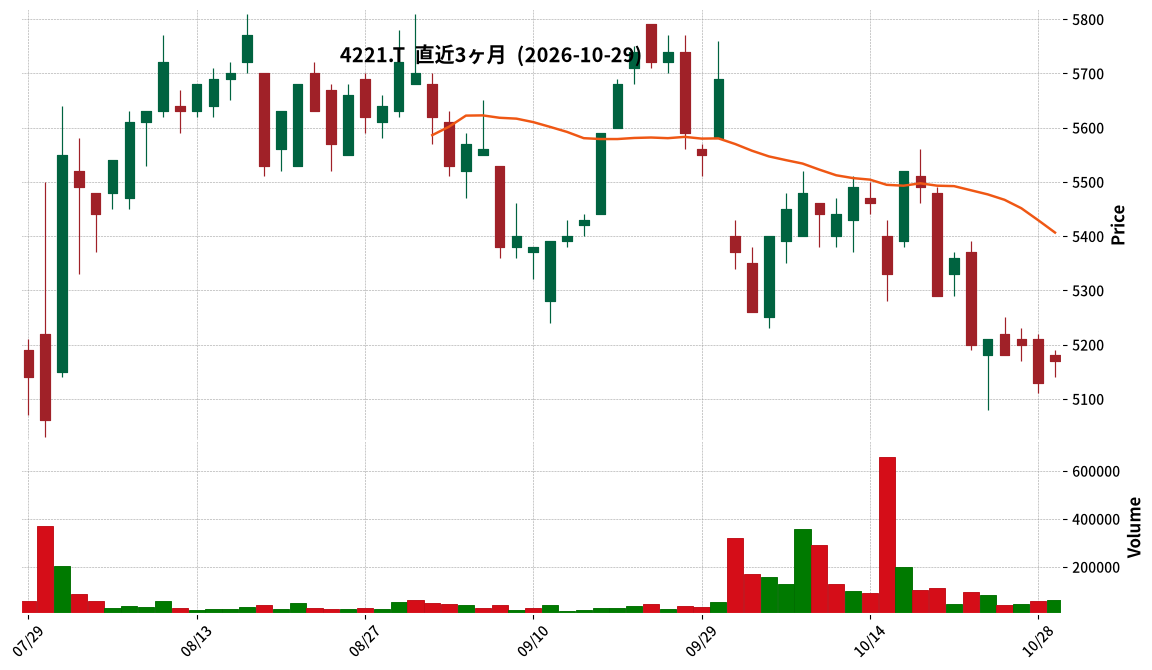
5170.0
▲ +0.78%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Okura Industrial Co., Ltd. announced its consolidated financial results for the third quarter of the fiscal year ending December 2026 (January 1, 2026 – September 30, 2026).
- Net sales reached ¥80.22 billion, marking a 24.9% increase compared to the same period of the previous year.
- Operating income grew by 91.0% to ¥8.947 billion, ordinary income by 89.9% to ¥9.082 billion, and net income attributable to owners of parent by 77.8% to ¥6.192 billion.
- In its main segments, the Synthetic Resin business reported net sales of ¥54.728 billion (+39.3% YoY) and operating income of ¥8.794 billion (+106.4% YoY). The New Materials business recorded net sales of ¥14.355 billion (+4.1% YoY) and operating income of ¥2.06 billion (+18.6% YoY).
- Two companies, Fujico Co., Ltd. and OKURA VIETNAM CO., LTD., were newly included in the scope of consolidation during this cumulative third quarter.
- The consolidated full-year earnings forecast for the fiscal year ending December 2026 remains unchanged from the forecast announced on July 30, 2026.
- The projected year-end dividend is ¥130.00, with a total annual dividend forecast of ¥240.00 (including the interim dividend of ¥110.00).
🤖 AI Perspective
Okura Industrial’s third-quarter results show substantial year-on-year growth across net sales and all profit metrics. The consolidation of Fujico Co., Ltd. in the synthetic resin business, coupled with dynamic product pricing and robust raw material procurement capabilities, appears to have been significant drivers of performance. While total assets increased, the decline in the equity ratio, influenced by changes in the scope of consolidation, may be an aspect for investors to monitor going forward.
Disclaimer: This article is for informational purposes only and does not constitute investment advice.
4345|シーティーエス
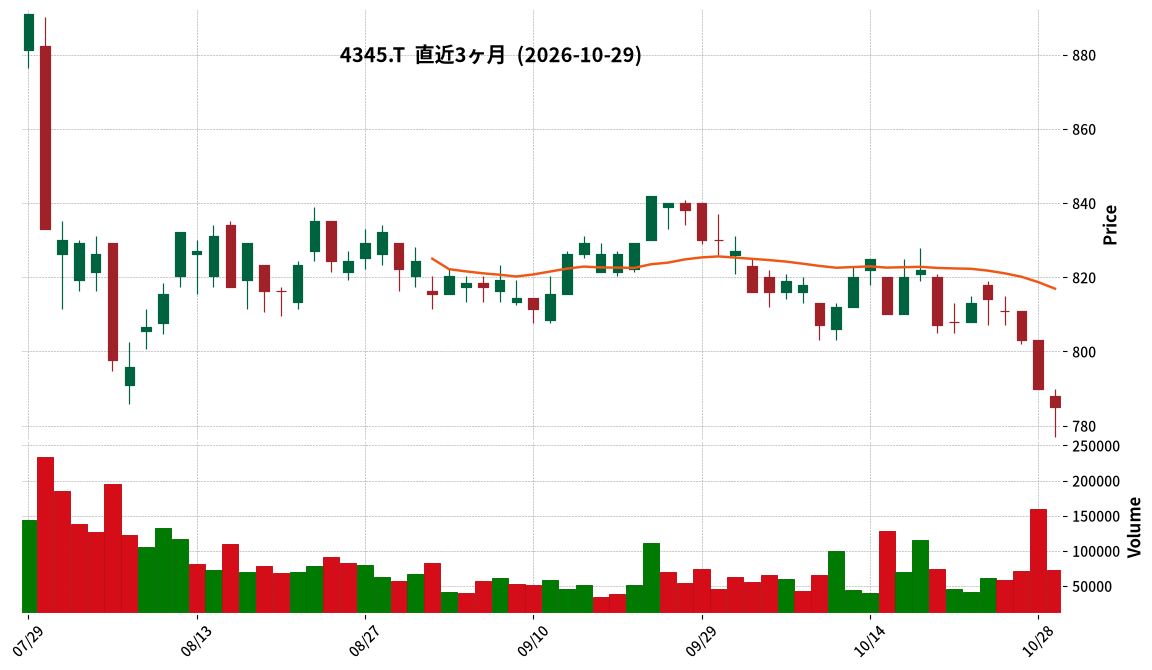
785.0
▼ -0.63%
📎 Source:シーティーエス Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- CTS Co., Ltd. has announced its consolidated financial results for the second quarter (interim period) of the fiscal year ending March 2027.
- For the interim period, consolidated net sales were JPY 6,205 million (up 0.3% year-on-year), operating profit was JPY 1,545 million (up 1.5% year-on-year), ordinary profit was JPY 1,787 million (up 4.3% year-on-year), and profit attributable to owners of parent was JPY 1,238 million (up 0.9% year-on-year).
- Interim net income per share was JPY 30.13 (compared to JPY 29.70 in the previous interim period).
- The consolidated financial position shows total assets of JPY 23,603 million, net assets of JPY 17,771 million, and an equity ratio of 75.3%.
- The full-year consolidated earnings forecast for the fiscal year ending March 2027 remains unchanged: net sales of JPY 13,500 million (up 5.9% from the previous year), operating profit of JPY 3,530 million (up 4.8%), ordinary profit of JPY 3,890 million (up 4.2%), and profit attributable to owners of parent of JPY 2,720 million (up 1.2%).
- The estimated year-end dividend is JPY 15.00 per share, making the total annual dividend JPY 30.00 per share (including the interim dividend of JPY 15.00).
🤖 AI Perspective
While net sales saw a modest increase, operating profit, ordinary profit, and interim net profit all surpassed prior-year figures. This may suggest that the company’s strategic shift towards becoming a specialized construction ICT company, centered on its “SAP (Site Assist Package)” services, is contributing positively to profitability. Furthermore, a high equity ratio of 75.3% indicates a strong financial foundation, which could be a key strength supporting strategic investments under its medium-term management plan.
4507|塩野義薬
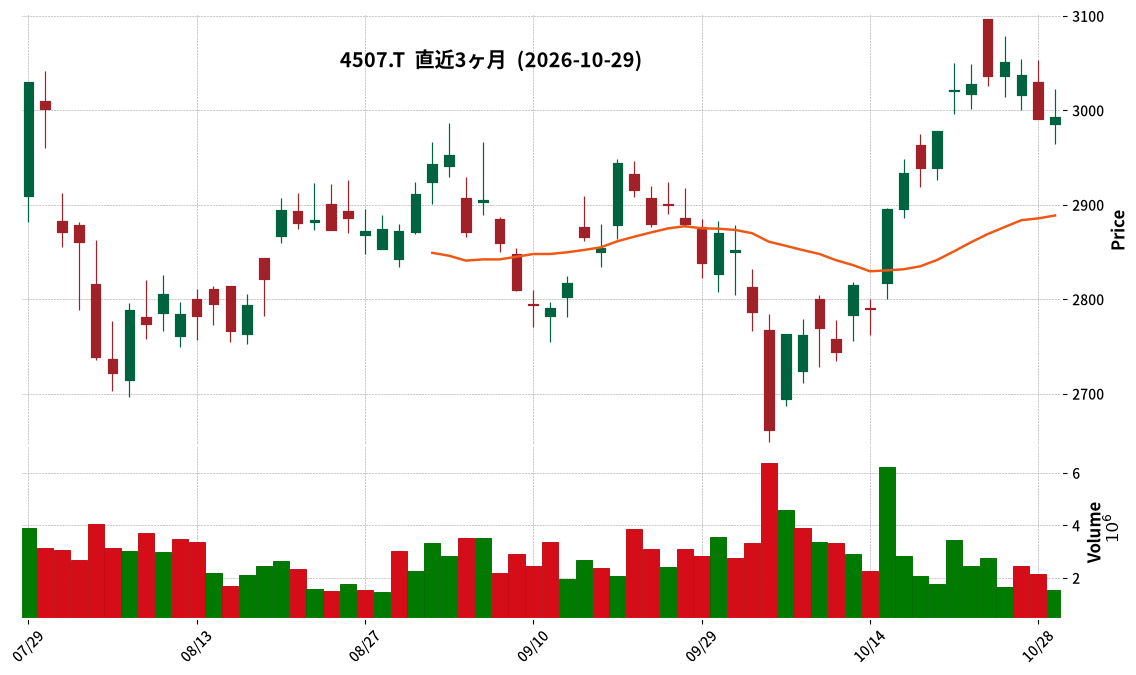
2992.5
▲ +0.05%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Shionogi & Co., Ltd. has revised its consolidated earnings forecast for the fiscal year ending March 2027.
- The revised forecast for net sales is ¥720,000 million (an increase of ¥20,000 million or 2.9% from the previous forecast), and profit attributable to owners of the parent is ¥212,500 million (an increase of ¥2,500 million or 1.2% from the previous forecast).
- The interim dividend forecast for the fiscal year ending March 2027 has been revised to ¥40 per share (an increase of ¥2 from the previous forecast), and the year-end dividend forecast to ¥46 per share (an increase of ¥8 from the previous forecast).
- The annual dividend forecast, combining the interim and year-end dividends, is ¥86 per share, representing an increase of ¥15 compared to the previous fiscal year.
- The revisions are primarily attributed to the successful outcomes of growth investments made in fiscal year 2025, strong progress in key businesses, and increased royalty income and equity method investment gains from the HIV business.
🤖 AI Perspective
The upward revision of earnings forecasts and the dividend increase suggest that the growth investments undertaken by Shionogi since FY2025 are yielding tangible results. This includes the successful build-out of rare disease platforms in overseas markets, growth in the infectious disease area, and expansion in domestic QOL disease areas, indicating a diversification and stabilization of revenue streams. The projection of a 15th consecutive year of dividend increases could be interpreted as a strong commitment to shareholder returns, potentially drawing investor attention to the company’s sustained profitability and capital allocation strategy.
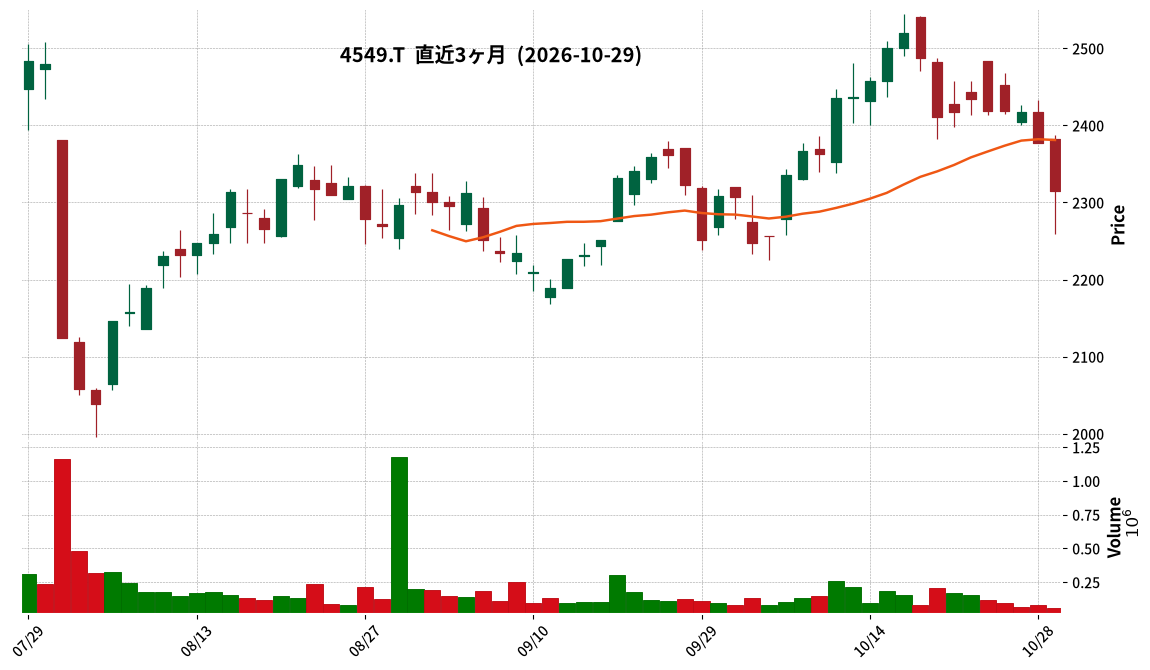
4549|栄研化
2315.0
▼ -2.61%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Eiken Chemical Co., Ltd. has announced its consolidated financial results for the second quarter of the fiscal year ending March 2027 (interim period: April 1, 2026 – September 30, 2026).
- Sales revenue for the interim period was JPY 21,388 million, representing a 4.7% increase compared to the prior interim period.
- Operating profit decreased by 8.2% to JPY 1,587 million, and ordinary profit decreased by 6.6% to JPY 1,616 million year-on-year.
- Net income attributable to owners of parent significantly decreased by 62.2% to JPY 1,125 million. This decline is attributed to the impact of a one-time extraordinary gain from the sale of shares in a consolidated subsidiary recorded in the previous corresponding period.
- The full-year consolidated performance forecast for the fiscal year ending March 2027 (April 1, 2026 – March 31, 2027) remains unchanged from the forecast announced on May 12, 2026.
🤖 AI Perspective
Eiken Chemical’s interim results show increased sales, but profits declined when excluding the one-off gain from the previous year. This suggests that changes in sales composition and a decrease in patent royalty income may have impacted profitability. The unchanged full-year forecast could indicate that the company anticipates recovery in the latter half of the fiscal year or that the interim profit decrease was already factored into their expectations. Investors might want to monitor future cost management, the performance of key products, and progress towards achieving the full-year forecast.
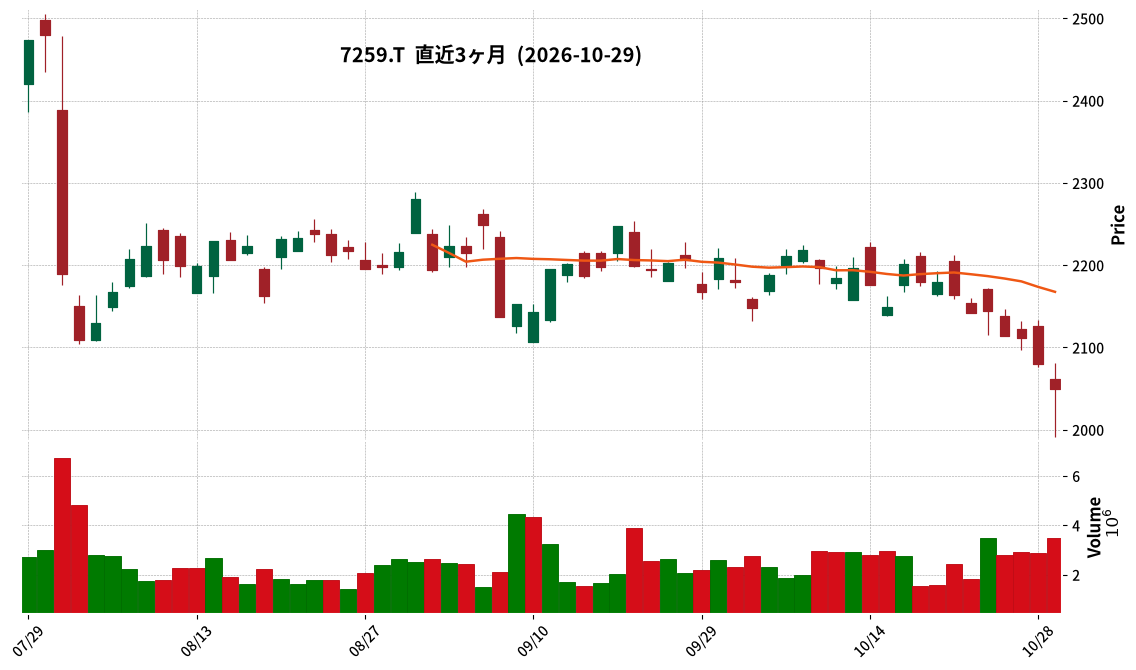
7259|アイシン
2049.0
▼ -1.47%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Aisin’s consolidated revenue for the first half of the fiscal year ending March 2027 increased by 7.3% year-on-year to ¥2,653,133 million.
- Consolidated operating profit for the same period decreased by 16.3% year-on-year to ¥80,419 million. Profit attributable to owners of the parent decreased by 28.9% to ¥49,667 million.
- By segment, North America and ASEAN/India regions reported increases in both revenue and operating profit, while Japan, Europe, and China saw decreases in operating profit. Europe recorded an operating loss of ¥2,000 million.
- The full-year consolidated earnings forecast for the fiscal year ending March 2027 was revised downwards for operating profit to ¥215,000 million (down 6.0% from previous forecast) and profit attributable to owners of the parent to ¥135,000 million (down 21.4% from previous forecast), while revenue was maintained at ¥5,250,000 million.
- The annual dividend forecast remains unchanged from the most recently published forecast, with an interim dividend of ¥35 and a year-end dividend of ¥40, totaling ¥75.
🤖 AI Perspective
Aisin’s Q2 FY2027 results indicate that while revenue grew, partially due to yen depreciation, surging material costs and special charges negatively impacted profits. The decline in profitability in the European and Chinese markets appears to have been a key factor affecting overall earnings. The downward revision of the full-year forecast reflects anticipated changes in the business environment and a projected decrease in powertrain unit sales, while the unchanged dividend forecast could be seen as an important consideration for investors.
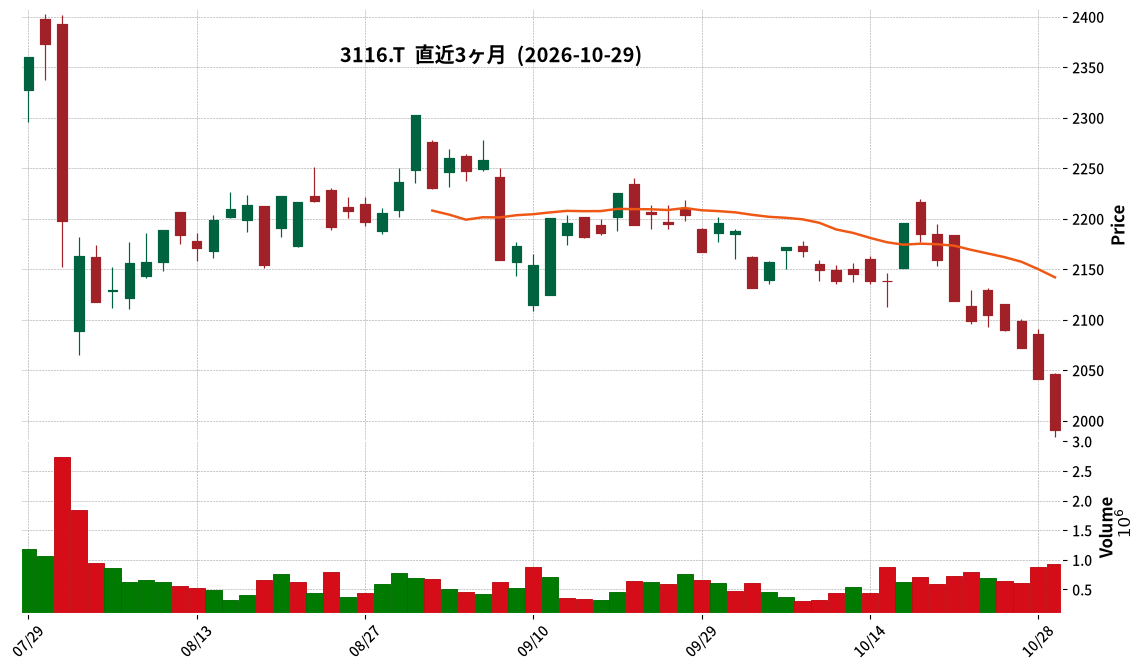
3116|トヨタ紡織
1990.5
▼ -2.50%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Toyota Boshoku Co. announced its consolidated financial results for the second quarter of the fiscal year ending March 2027.
- Revenue increased by 9.9% year-on-year to ¥1,068,337 million for the interim period.
- Operating profit decreased by 20.3% year-on-year to ¥29,524 million.
- Profit attributable to owners of the parent for the interim period rose by 29.0% year-on-year to ¥22,484 million.
- The full-year consolidated performance forecast for the fiscal year ending March 2027 has been revised to: Revenue ¥2,110,000 million, Operating Profit ¥71,000 million, Profit Before Tax ¥75,000 million, and Profit Attributable to Owners of the Parent ¥51,000 million (revised from the forecast announced on July 31, 2026).
- The interim dividend is ¥43.00 per share, with an annual dividend forecast of ¥86.00 per share (¥43.00 at fiscal year-end).
🤖 AI Perspective
While revenue grew, the significant decline in operating profit suggests challenges from shifting vehicle models, market conditions due to the Middle East situation, and increased expenses, despite new product effects and foreign exchange impacts. The substantial increase in profit attributable to owners of the parent is noted to be influenced by the recognition of deferred tax assets, which may have buffered the net profit. The upward revision of the full-year forecast indicates that the company anticipates improved performance in the latter half of the fiscal year, a point that investors may find noteworthy.
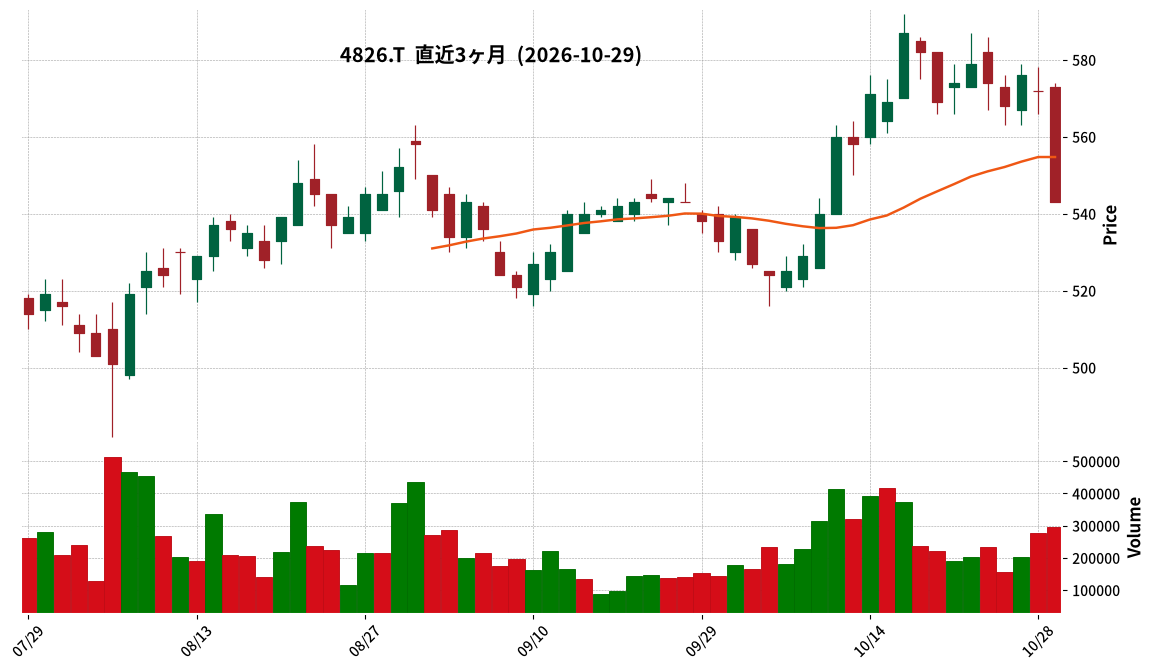
4826|CIJ
543.0
▼ -5.07%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- CIJ announced its consolidated financial results for the first quarter of the fiscal year ending June 2027 (July 1, 2026 – September 30, 2026).
- Net sales reached ¥7,428 million (up 7.5% year-on-year), operating profit was ¥649 million (up 2.9%), and ordinary profit was ¥662 million (up 3.5%).
- Profit attributable to owners of parent was ¥422 million (down 2.9% year-on-year).
- Key factors for increased revenue included robust orders in the information & communications and public sectors, as well as contributions from consolidated subsidiary Infotech Solutions Co., Ltd.
- The decrease in profit attributable to owners of parent was attributed to an increase in corporate taxes due to factors such as a rise in the estimated effective tax rate.
- There are no revisions to the full-year consolidated earnings forecast or the annual dividend forecast for the fiscal year ending June 2027.
🤖 AI Perspective
CIJ’s Q1 results indicate robust growth in net sales and operating profit, suggesting sustained strong demand in the information & communications and public sectors. The slight decrease in net profit attributable to owners of parent is noted as being due to higher corporate taxes, highlighting the impact of tax rate changes on profitability. Given that the full-year forecasts remain unchanged, it may suggest that the company considers this quarter’s performance to be in line with their expectations.
5832|ちゅうぎんFG
3491.0
▲ +1.07%
📎 Source:ちゅうぎんFG Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
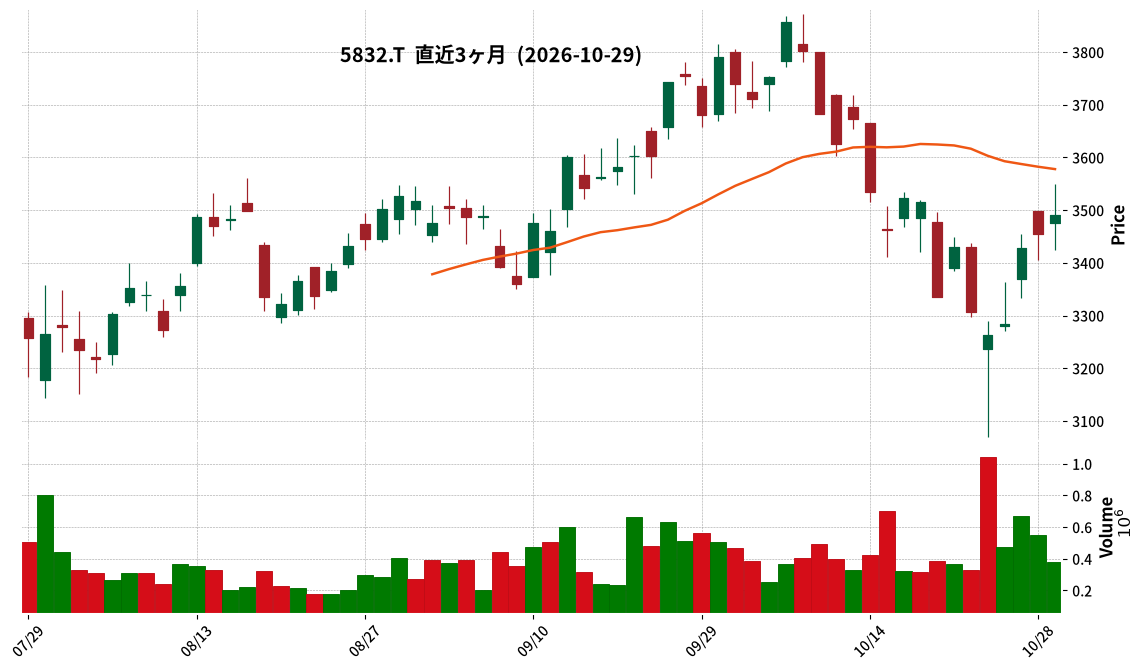
- Chugin Financial Group has revised its consolidated earnings forecast upward for the fiscal year ending March 2027.
- The revised recurring revenue is ¥347,000 million (up 31.9% from previous forecast), recurring profit is ¥80,000 million (up 23.0%), and profit attributable to owners of parent is ¥55,000 million (up 22.2%).
- Earnings per share (EPS) have been revised from ¥253.14 to ¥309.19.
- The year-end dividend forecast for FY2027 has been revised from ¥51.00 per share to ¥73.00, resulting in a projected annual dividend of ¥124.00.
- Key reasons for the revision include robust stock market performance in the interim period, the Bank of Japan’s policy interest rate hike, securities trading aimed at portfolio rebalancing, and increased funding income such as loan interest and securities interest/dividends.
🤖 AI Perspective
This upward revision to the earnings forecast appears to reflect favorable financial market conditions and effective business strategies. The Bank of Japan’s policy rate hike may suggest an improved revenue environment for the banking sector as a whole, from which Chugin FG seems to be benefiting. The increased dividend, aligned with a shareholder return policy targeting a payout ratio of approximately 40%, could indicate a commitment to returning profit growth to shareholders.
7989|立川ブライ
2493.0
▼ -2.66%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
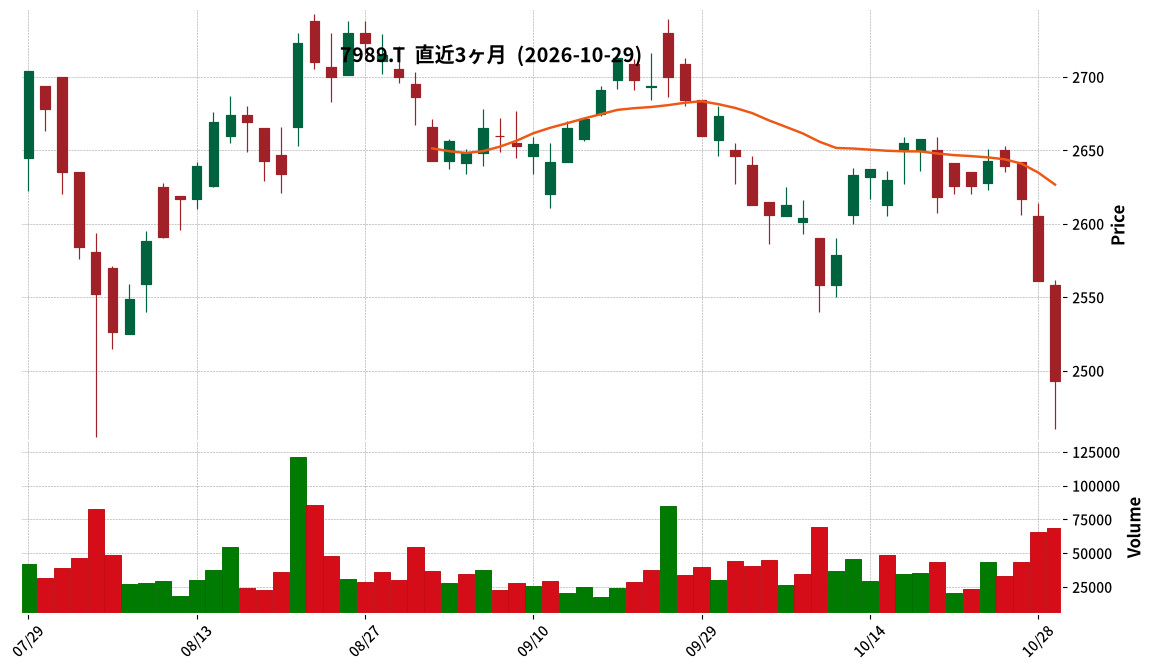
- Tachikawa Blind Industry Co., Ltd. announced its Q3 FY2026 consolidated financial results for the period from January 1, 2026, to September 30, 2026.
- Consolidated cumulative results show net sales of ¥32,845 million (up 5.7% year-on-year), operating income of ¥3,449 million (up 9.1% year-on-year), ordinary income of ¥3,631 million (up 10.4% year-on-year), and profit attributable to owners of parent of ¥2,387 million (up 1.2% year-on-year).
- As of the end of the third quarter, total assets stood at ¥67,875 million, an increase of ¥140 million from the previous consolidated fiscal year-end. The equity ratio was 85.2%.
- The full-year consolidated earnings forecast for FY2026 remains unchanged, projecting net sales of ¥43,500 million (up 2.1% year-on-year), operating income of ¥4,500 million (up 2.0% year-on-year), ordinary income of ¥4,700 million (up 1.5% year-on-year), and profit attributable to owners of parent of ¥3,280 million (up 1.2% year-on-year).
- By segment, Parking System-related Business reported sales of ¥3,437 million (up 77.6% YoY) and operating income of ¥582 million (up 116.9% YoY). Reducer-related Business saw sales of ¥2,879 million (up 13.5% YoY) and operating income of ¥221 million (up 91.6% YoY). The Interior and Exterior Finishing Products Business reported sales of ¥26,528 million (down 0.3% YoY) and operating income of ¥2,645 million (down 4.7% YoY).
🤖 AI Perspective
Tachikawa Blind Industry’s Q3 FY2026 results show a positive trend with increased revenue and profit, primarily driven by strong performance in the parking system and reducer-related segments. While the core interior and exterior finishing products segment experienced a slight decline, efforts to stimulate demand through new showrooms and marketing initiatives could be worth monitoring. The unchanged full-year forecast suggests the company anticipates steady performance through the final quarter, and investors may focus on the progress towards these annual targets.
8708|アイザワ証G
1486.0
▼ -1.78%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
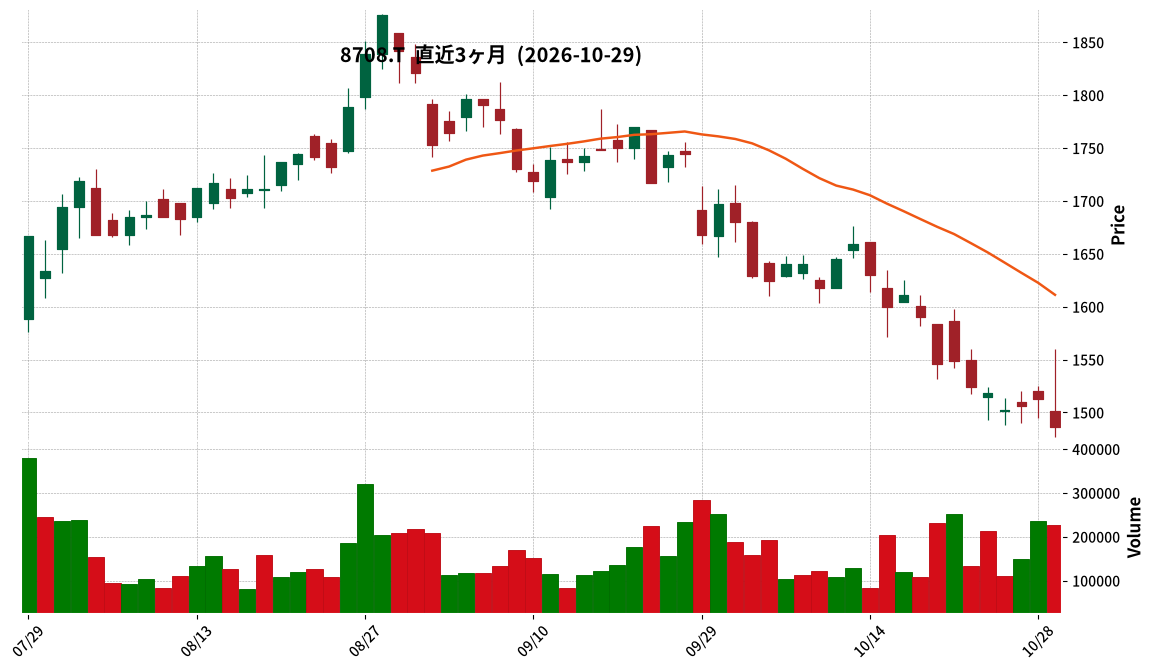
- Aizawa Securities Group Co., Ltd. announced its consolidated financial results for the second quarter (interim period) of the fiscal year ending March 2027.
- Consolidated operating revenue reached ¥11,695 million, marking a 17.7% increase compared to the same period last year.
- Net income attributable to owners of parent was ¥1,836 million, an 83.5% increase year-on-year.
- Diluted earnings per share for the interim period stood at ¥58.87.
- An interim dividend of ¥48.00 per share (ordinary dividend ¥13, special dividend ¥35) is planned.
- The company will not disclose its consolidated earnings forecast for the full fiscal year ending March 2027 due to the nature of the financial instruments business.
- Total assets under custody reached ¥2,665 billion (up 15.4% year-on-year), with stock-related assets under custody at ¥681.3 billion (up 31.9% year-on-year).
🤖 AI Perspective
The interim period saw significant growth in both operating revenue and net income attributable to owners of parent. The substantial increase in stock-related assets under custody, a key focus of the company’s mid-term management plan, suggests progress in building a stable revenue foundation. This expansion in assets under custody could contribute to more stable performance in the future for the securities business, which is typically sensitive to market fluctuations.
9534|北海瓦斯
852.0
▼ -4.59%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
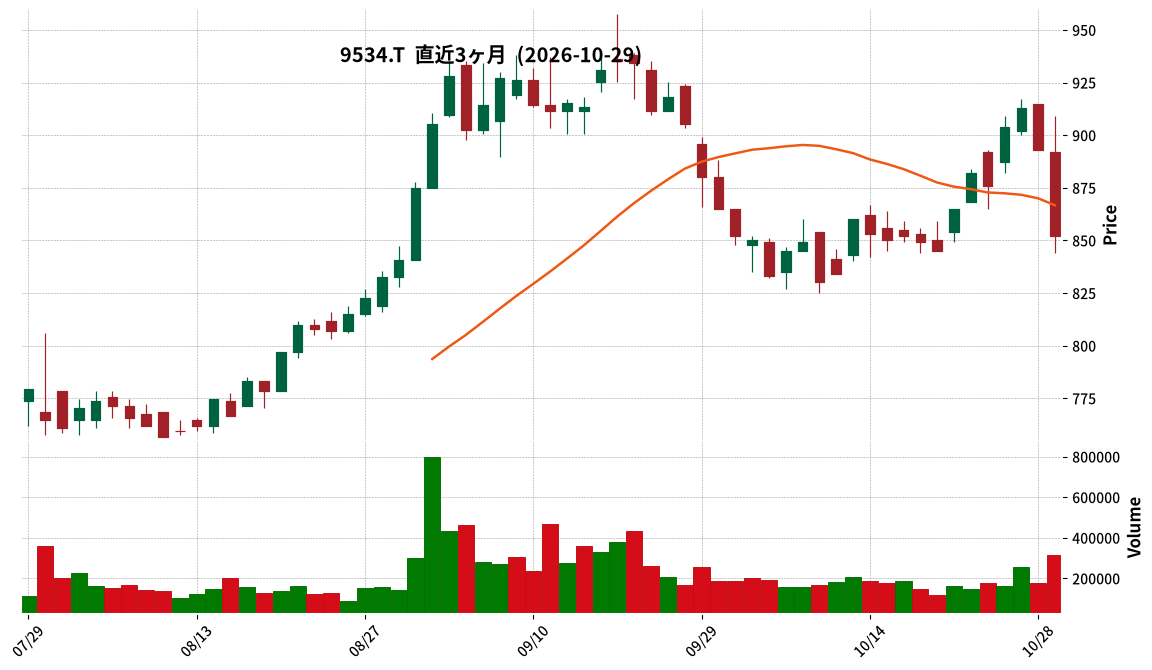
- Hokkaido Gas Co., Ltd. announced its consolidated financial results for the second quarter of the fiscal year ending March 2027 (April 1, 2026 – September 30, 2026).
- Consolidated net sales amounted to ¥71,690 million, an increase of 0.5% compared to the same period of the previous year.
- Consolidated operating profit was ¥3,452 million (down 48.3% year-on-year), ordinary profit was ¥3,615 million (down 47.3% year-on-year), and net income attributable to owners of parent was ¥2,595 million (down 47.0% year-on-year).
- Diluted EPS for the interim period was ¥29.49.
- The forecast for the annual dividend for FY2027 remains ¥27.00 per share (interim ¥13.50, year-end ¥13.50), with no revisions from the most recently announced forecast.
- The full-year consolidated performance forecast for FY2027 projects net sales of ¥190,200 million (up 9.0% year-on-year) and ordinary profit of ¥13,000 million (down 21.2% year-on-year), with no revisions from the most recently announced forecast.
🤖 AI Perspective
While net sales saw a slight increase, the profit figures experienced significant declines. This appears to be attributable to a decrease in sales unit prices under the fuel cost adjustment system and raw material cost adjustment system, alongside increased strategic expenses for smart meter implementation and DX-related fields. As the full-year forecast remains unchanged, recovery in the second half of the fiscal year could be worth monitoring.
9701|東京会館
4775.0
▲ +0.32%
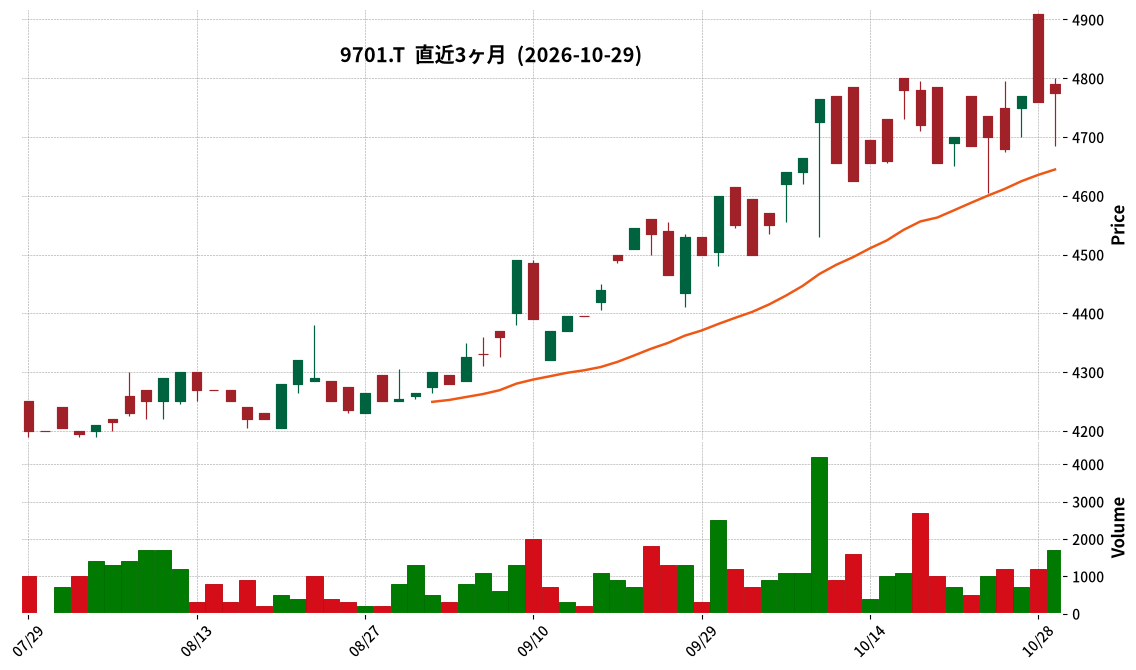
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Tokyo Kaikan reported net sales of ¥7,651 million for the first half of fiscal year 2027 (April 1 to September 30, 2026), marking a 3.3% increase year-on-year.
- Operating profit for the same period was ¥432 million (up 19.7%), ordinary profit was ¥510 million (up 33.3%), and net income attributable to owners of parent was ¥329 million (up 39.6%).
- Diluted earnings per share for the interim period stood at ¥99.99.
- The full-year forecast for fiscal year 2027 has been revised upwards, projecting net sales of ¥16,550 million, operating profit of ¥1,510 million, ordinary profit of ¥1,640 million, and net income of ¥1,100 million, with diluted EPS of ¥333.41.
- The projected annual dividend for fiscal year 2027 is ¥50.00 per share (compared to ¥45.00 for the previous year).
- As of September 30, 2026, total assets were ¥30,781 million, net assets were ¥13,885 million, and the equity ratio was 45.1%.
🤖 AI Perspective
Tokyo Kaikan’s interim results for FY2027 show notable growth across profit metrics, building on a steady increase in net sales. The company’s ability to achieve higher sales in all divisions, combined with effective cost management, appears to have driven the significant profit improvement. The upward revision of the full-year guidance suggests a positive outlook for the remainder of the fiscal year, which could be a point of interest for investors.
Disclaimer: This article is for informational purposes only and does not constitute investment advice.
9818|大丸エナ
1510.0
▼ -2.08%
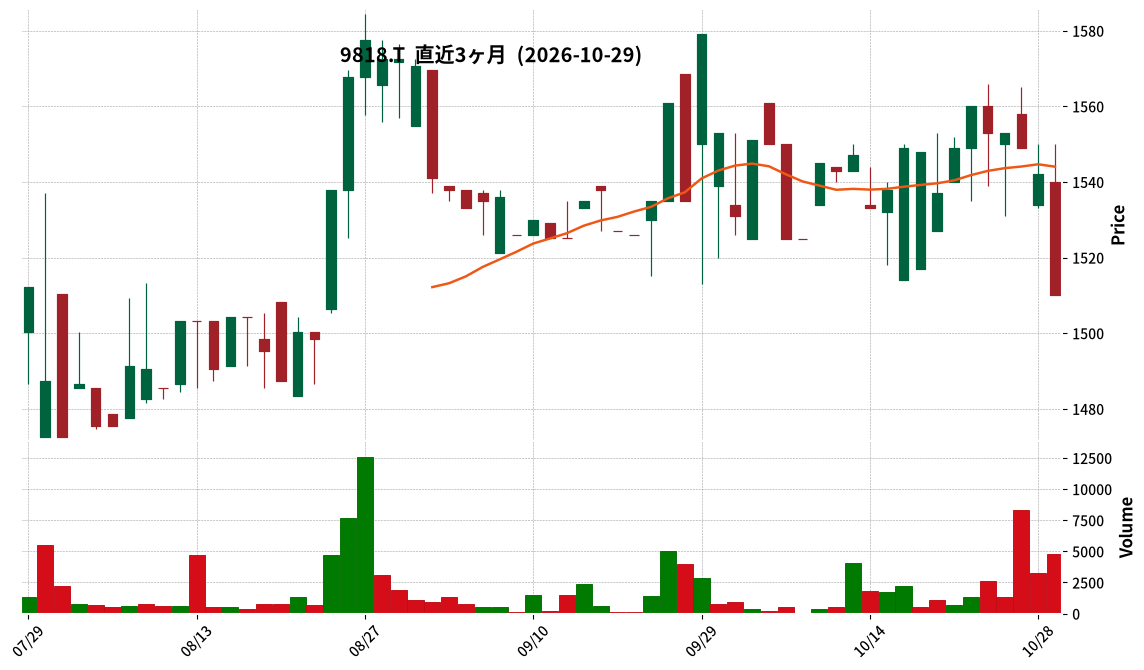
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Daimaru Enawin Co., Ltd. has announced its consolidated financial results for the second quarter (interim period) of the fiscal year ending March 2027.
- For the cumulative consolidated operating results, sales amounted to JPY 17,698 million (an increase of 18.4% compared to the same period last year), operating profit was JPY 575 million (up 61.7%), ordinary profit was JPY 651 million (up 61.9%), and net profit attributable to parent company was JPY 412 million (up 92.2%).
- By segment, sales for the Living business were JPY 12,247 million (up 23.6%), Medical and Industrial Gas business sales were JPY 4,783 million (up 9.1%), and Aqua business sales were JPY 667 million (up 1.2%).
- Interim net income per share at the end of the interim period was JPY 53.70.
- There are no revisions to the full-year consolidated earnings forecast or the annual dividend forecast (JPY 15.00 for interim, JPY 15.00 for year-end, total JPY 30.00), based on the latest public announcement.
🤖 AI Perspective
Daimaru Enawin’s interim results indicate significant year-over-year growth across sales and all profit metrics, with net profit attributable to the parent company showing a substantial 92.2% increase. This strong performance is attributed to factors such as higher LP gas sales prices and increased shipments in the Living business, along with a rise in home medical equipment rentals in the Medical and Industrial Gas business, suggesting broad-based strength across its operational segments. As the full-year earnings forecast remains unchanged, investors may monitor the company’s performance relative to these targets in the coming quarters.
4366|ダイトーケミックス
468.0
▼ -0.64%
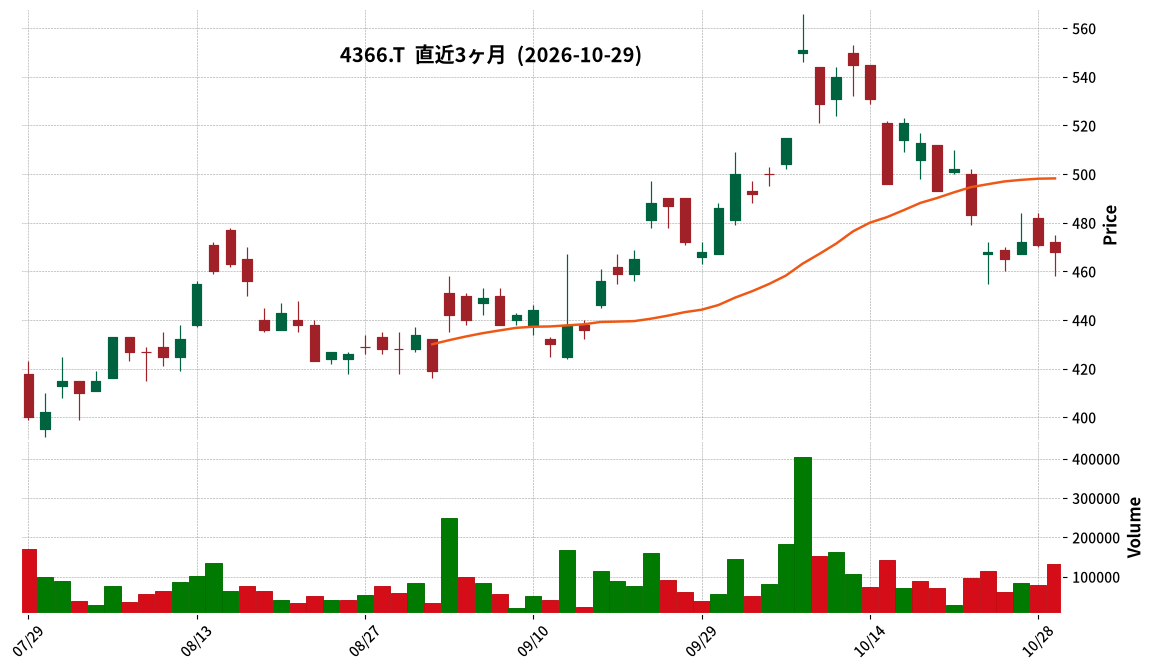
📎 Source:ダイトーケミックス Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Daito Chemix announced its consolidated financial results for the second quarter (interim period) of the fiscal year ending March 2027 (covering April 1, 2026 to September 30, 2026).
- Consolidated net sales for the interim period amounted to ¥10,909 million, representing a 14.1% increase compared to the prior interim period.
- Consolidated operating profit reached ¥653 million (up 50.5% year-on-year), and consolidated ordinary profit was ¥727 million (up 73.5% year-on-year).
- Net profit attributable to owners of the parent significantly increased by 176.8% to ¥582 million. Earnings per share for the interim period were ¥18.08.
- The consolidated full-year forecast for FY2027 has been revised, projecting net sales of ¥22,600 million (up 16.0% from previous fiscal year), operating profit of ¥1,400 million (up 60.4%), ordinary profit of ¥1,400 million (up 56.5%), and net profit attributable to owners of the parent of ¥1,110 million (up 40.3%).
- The financial position shows total assets of ¥30,509 million (an increase of ¥1,712 million from the previous fiscal year-end) and net assets of ¥16,902 million (an increase of ¥544 million). The equity ratio stood at 55.4%.
- The annual dividend forecast for FY2027 is ¥9.00 per share (interim ¥0.00, year-end ¥9.00), with no changes from the most recent forecast.
- A change in depreciation methods has been applied from the current interim consolidated accounting period.
🤖 AI Perspective
Daito Chemix’s H1 FY2027 results demonstrate robust growth across sales and all profit metrics, with a notable 176.8% increase in net profit attributable to owners of the parent. This strong performance could suggest that the company’s growth investments outlined in its medium-term management plan are beginning to yield positive returns. The upward revision of the full-year forecast further underscores this positive trend, making the company’s future trajectory worth monitoring.
6301|コマツ
6776.0
▼ -0.57%
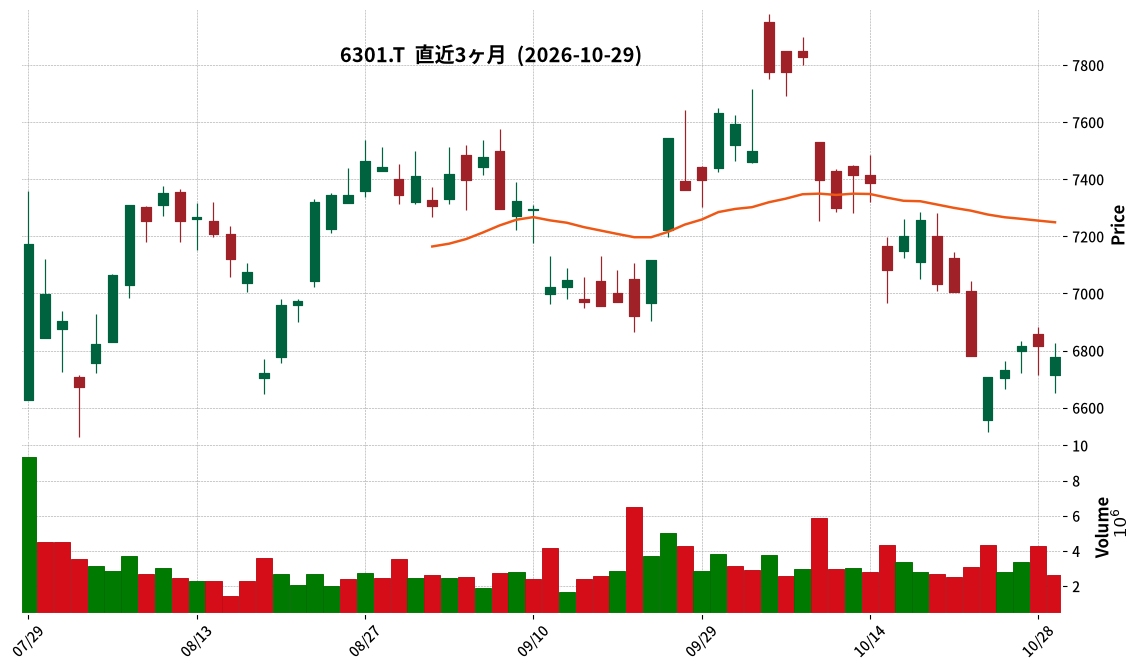
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Komatsu reported consolidated net sales of JPY 1,115.5 billion for the second quarter of FY2026 (July-September), marking a 13.6% increase year-on-year.
- Consolidated operating profit for the same period was JPY 135.1 billion, a 1.2% decrease year-on-year. The operating profit margin declined by 1.8 percentage points to 12.1%.
- Net profit attributable to owners of the parent company increased by 13.3% year-on-year to JPY 95.8 billion.
- The Construction, Mining, and Utility Equipment segment recorded net sales of JPY 1,032.6 billion (+15.1% YoY) and segment profit of JPY 114.3 billion (▲4.5% YoY).
- The Retail Finance segment’s net sales were JPY 32.7 billion (+7.2% YoY), with segment profit at JPY 7.7 billion (+3.0% YoY).
- The Industrial Machinery and Others segment reported net sales of JPY 61.6 billion (▲2.9% YoY) and segment profit of JPY 12.1 billion (+28.4% YoY).
🤖 AI Perspective
Komatsu’s Q2 FY2026 results show a robust increase in net sales, primarily driven by the weaker yen, higher sales volume, and improved selling prices, reaching a record quarterly revenue. However, the decline in operating profit suggests that rising material costs and other expenses may be impacting profitability. Investors may want to monitor cost management strategies, particularly within the core Construction, Mining, and Utility Equipment segment, where sales increased but profit decreased.
5482|愛知鋼
2790.0
▼ -1.41%
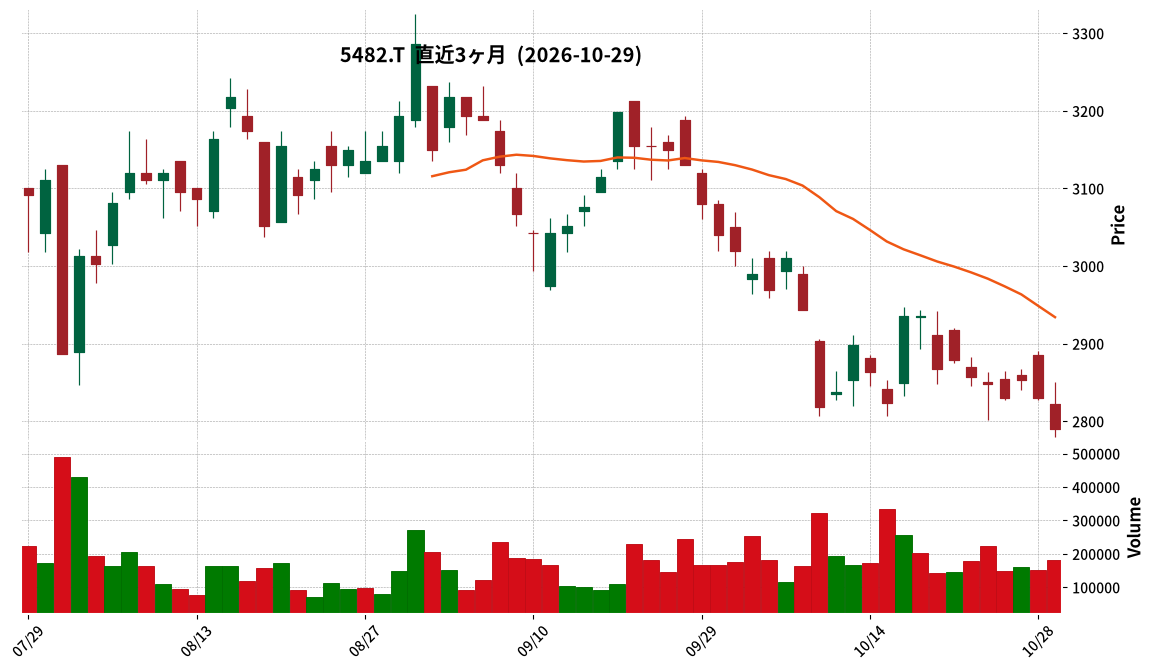
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Aichi Steel has announced its consolidated results for the second quarter (interim period) of the fiscal year ending March 2027.
- Revenue reached ¥162,572 million, an 8.5% increase compared to the same period last year.
- Operating profit was ¥7,336 million (down 16.5% year-on-year), profit before tax was ¥8,071 million (down 13.3%), and interim profit attributable to owners of the parent was ¥5,299 million (down 5.5%).
- The interim dividend for the fiscal year ending March 2027 was revised upward from the initial forecast of ¥69.00 to ¥75.00 (ordinary dividend ¥36.00, special dividend ¥39.00).
- The full-year consolidated performance forecast was also revised, projecting revenue of ¥330,000 million (up 8.4% year-on-year), operating profit of ¥15,000 million (down 13.7%), and profit attributable to owners of the parent of ¥10,000 million (down 11.1%).
🤖 AI Perspective
While revenue increased year-on-year, operating profit and net profit declined, which may suggest that increases in sales volume and prices were not sufficient to offset rising purchase costs. The upward revision of the annual dividend forecast, however, could indicate a positive stance on shareholder returns. Investors might consider monitoring how the company manages cost pressures in the coming periods to improve profitability.
1959|クラフティア
7780.0
▼ -0.01%
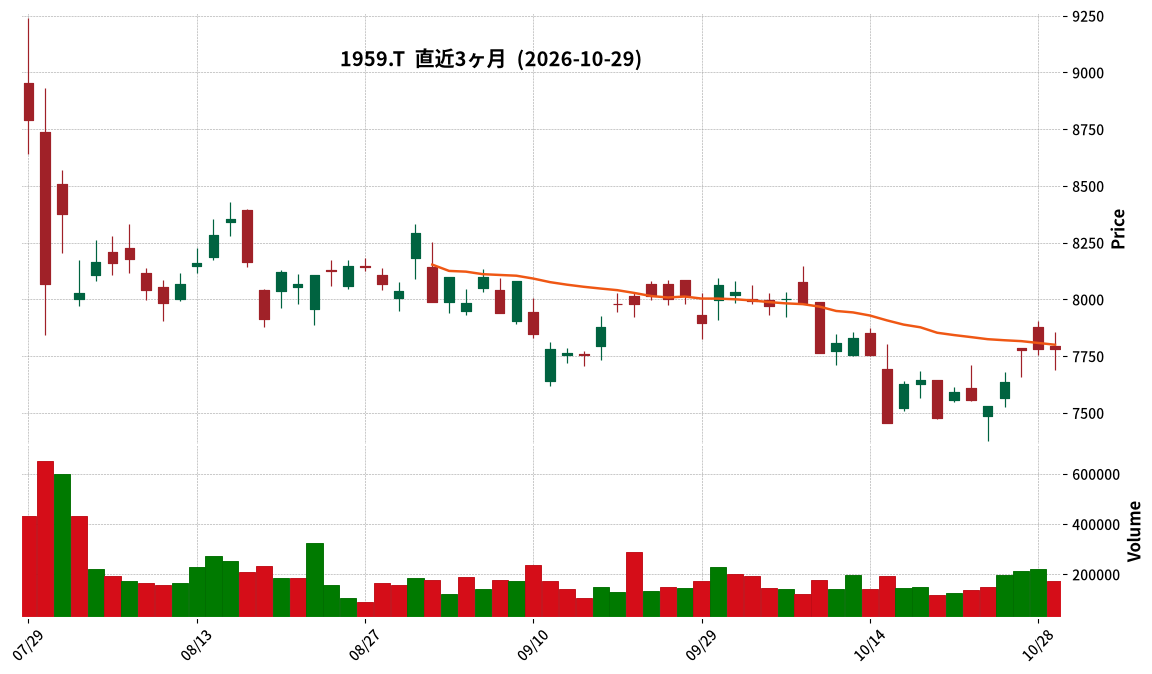
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Craftia Co., Ltd. resolved to revise its interim dividend and year-end dividend forecast (increase) at a Board of Directors meeting held on October 29, 2026.
- The interim dividend for the record date of September 30, 2026, was decided at ¥120.00 per share, an increase from the previously announced forecast (April 28, 2026) of ¥110.00 per share.
- The total interim dividend amount is ¥8,503 million, with an effective date of December 1, 2026.
- The year-end dividend forecast for the fiscal year ending March 2027 has been revised from the previous annual forecast (April 28, 2026) of ¥220.00 per share to a total annual dividend of ¥240.00 per share (Interim: ¥120.00, Year-end: ¥120.00).
- The company stated that the reason for the dividend forecast revision is based on their fundamental policy of stable and progressive dividends, targeting a consolidated dividend payout ratio of 40%, and taking into account the revised earnings forecast for the fiscal year ending March 2027.
🤖 AI Perspective
This announcement highlights Craftia’s clear commitment to shareholder returns through its “progressive dividend” policy, which aims for stable or increasing dividends. The upward revision in dividends, tied to a revised earnings forecast, could be interpreted as a sign of confidence in the company’s business environment and future profitability. Investors may monitor the company’s financial performance closely moving forward, as the increase in both interim and year-end dividends suggests a consistent shareholder return stance.
6436|アマノ
3635.0
▼ -0.03%
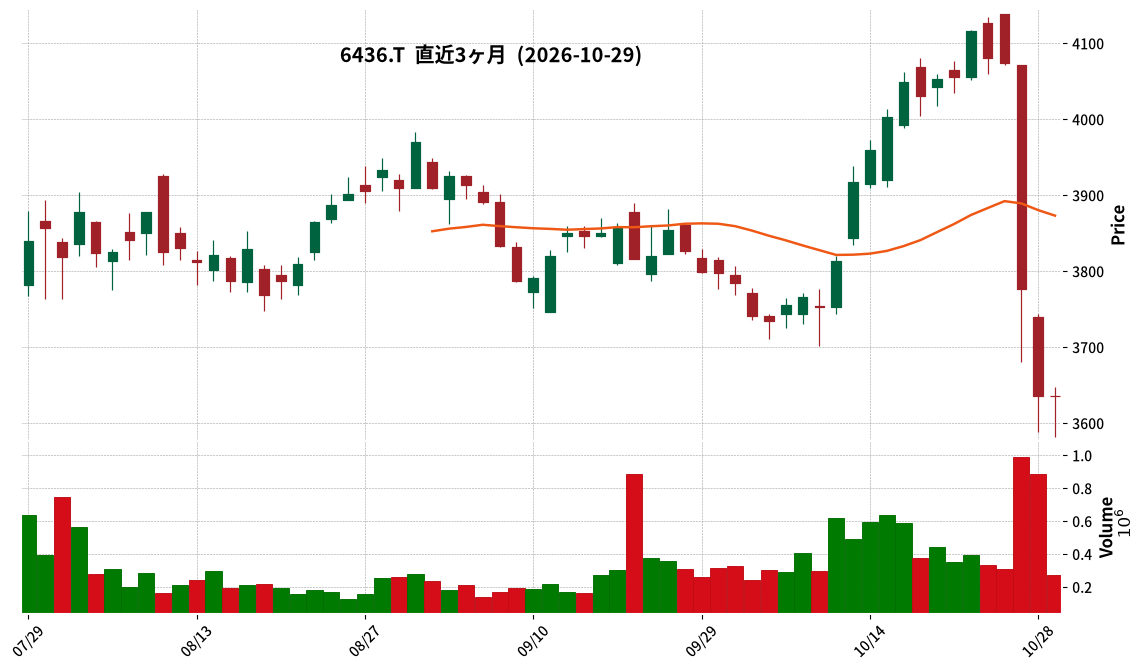
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Amano announced its consolidated financial results for the second quarter (interim period) of the fiscal year ending March 2027.
- Revenue for the interim period was ¥84,933 million, a 1.2% increase compared to the same period in the previous year.
- Operating profit decreased to ¥7,519 million (22.4% decrease year-on-year), ordinary profit to ¥8,375 million (20.1% decrease year-on-year), and net income attributable to owners of parent to ¥4,979 million (25.4% decrease year-on-year).
- By business segment, the “Time Information Systems Business” saw its parking systems revenue increase to ¥45,989 million (5.4% increase year-on-year).
- The full-year consolidated earnings forecast remains unchanged: revenue of ¥184,000 million (4.3% increase from previous year), operating profit of ¥20,000 million (11.3% decrease), ordinary profit of ¥21,500 million (11.7% decrease), and net income attributable to owners of parent of ¥14,500 million (28.0% decrease).
🤖 AI Perspective
While revenue increased in this interim period, key profit metrics experienced declines, suggesting potential pressures on profitability. The growth in the parking systems business stands out, offsetting some decreases in information systems and environmental systems. With the full-year forecast unchanged, investor attention may focus on whether the company can recover profitability in the second half of the fiscal year.
6473|ジェイテクト
2039.5
▼ -2.11%
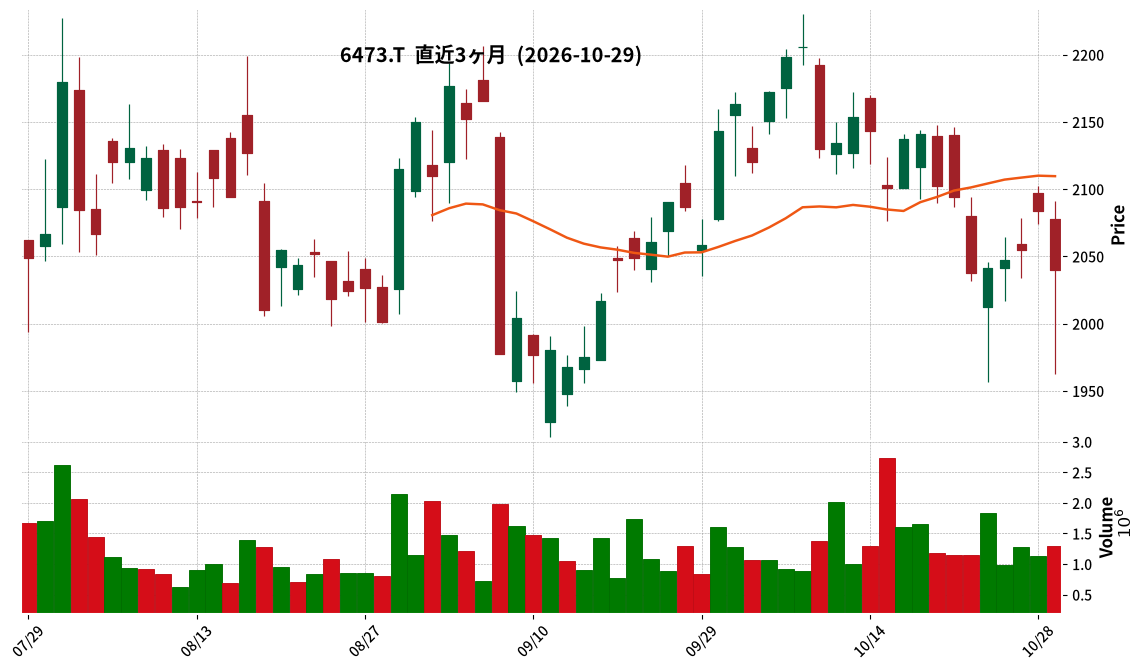
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- JTEKT’s consolidated results for the second quarter (interim period) of the fiscal year ending March 2027 show revenue of 970,788 million yen, a 4.4% increase from the prior interim period.
- Operating profit reached 36,049 million yen (up 38.4%), and business profit was 50,684 million yen (up 52.8%) for the interim period.
- Net profit attributable to owners of the parent was 21,751 million yen, marking a 78.8% increase, with basic interim EPS of 68.32 yen.
- The full-year dividend forecast for FY2027 remains unchanged at 70 yen per share (interim 35 yen, year-end 35 yen).
- The consolidated full-year forecast for FY2027 has been revised, with projected revenue of 1,920,000 million yen (down 0.3% year-on-year) and net profit attributable to owners of the parent of 50,000 million yen (up 317.6% year-on-year), as detailed in a separate announcement on business forecast revisions.
- Two subsidiaries, JTEKT EUROPE S.A.S. and JTEKT TORSEN HOLDINGS S.A., were excluded from the scope of consolidation during this interim period.
8071|東海エレ
—
▲ +0.00%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Tokai Electronics announced a discrepancy between its Q2 FY2027 consolidated financial forecast and actual results, along with revisions to its full-year consolidated earnings and dividend forecasts.
- For Q2 FY2027, actual net sales were JPY 19,869 million, a 0.7% decrease from the previous forecast of JPY 20,000 million.
- However, Q2 FY2027 net income attributable to parent company increased by 27.5%, reaching JPY 229 million against the previous forecast of JPY 180 million.
- The full-year consolidated earnings forecast for FY2027 was revised upwards: net sales are now projected at JPY 47,200 million (up 18.0% from JPY 40,000 million), and net income attributable to parent company is projected at JPY 660 million (up 46.7% from JPY 450 million).
- The annual dividend forecast for FY2027 was also revised, with the year-end dividend increasing by JPY 1.00 to JPY 58.00 per share, making the total annual dividend JPY 115.00.
- The revision reasons include weaker-than-expected sales in the automotive sector for the interim period, offset by improved profitability due to the weaker yen. For the full year, increased sales in the FA/machine tool and information & communication sectors, combined with the full acquisition of SEIDENSHA Co., Ltd. effective October 1, 2026, are expected to contribute to the upward revision.
🤖 AI Perspective
While interim sales slightly missed expectations, the significant outperformance in profits, driven by the weak yen, is a key highlight for investors. The upward revision of the full-year forecast suggests that a combination of strong performance in certain existing segments and the strategic acquisition of SEIDENSHA Co., Ltd. is expected to contribute positively to future earnings. The increased dividend forecast may indicate the company’s confidence in its improved financial outlook and commitment to shareholder returns.
9914|植松商会
—
▲ +0.00%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Uematsu Shokai Co., Ltd. announced its unaudited financial results for the second quarter of the fiscal year ending March 2027 on October 29, 2026.
- For the interim period, net sales were ¥3,553 million (up 8.1% year-on-year), operating income was ¥35 million (up 75.1%), ordinary income was ¥110 million (up 62.0%), and net income attributable to owners of parent was ¥70 million (up 55.3%).
- Interim net income per share increased to ¥31.61 from ¥20.35 in the prior interim period.
- As of the end of the interim period, total assets stood at ¥5,016 million, net assets at ¥3,458 million, and the equity ratio improved to 68.9%.
- The full-year forecast for FY2027 remains unchanged from the most recently published figures, projecting net sales of ¥6,800 million (up 2.5% year-on-year) and net income of ¥113 million (down 8.9%), with basic earnings per share of ¥50.68.
🤖 AI Perspective
The significant year-on-year increases across sales and all profit metrics in this interim period indicate strong operational performance. The substantial growth in operating income, ordinary income, and net income, ranging from approximately 60% to over 75%, is a key highlight. Despite the strong interim results, the company’s decision to maintain its full-year forecast suggests a cautious outlook for the latter half of the fiscal year, which could be worth monitoring. The improvement in the equity ratio may suggest strengthening financial health.
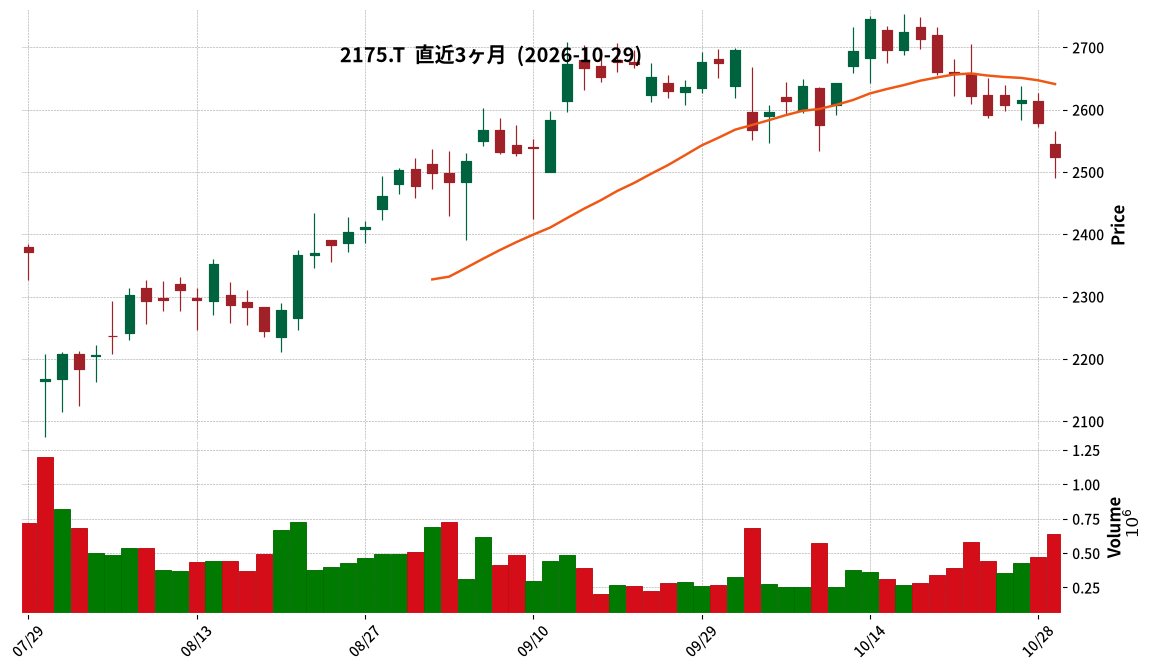
2175|SMS
2524.0
▼ -2.13%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- SMS Co., Ltd. released its Q2 FY2027 earnings presentation material on October 29, 2026.
- For the first half of FY2027, consolidated net sales were ¥36.4 billion (+9% year-on-year), EBITDA was ¥6.7 billion (+3% year-on-year), and operating profit was ¥4.9 billion (+12% year-on-year).
- The operating profit progress against the full-year plan (net sales: ¥71.8 billion, EBITDA: ¥10.4 billion, operating profit: ¥6.8 billion) stands at 72%.
- The Career segment reported sales of ¥23.2 billion (+7% year-on-year) and EBITDA of ¥6.1 billion (+2% year-on-year). The Nursing Care & Disability Welfare Management Support segment reported sales of ¥7.1 billion (+11% year-on-year) and EBITDA of ¥3.0 billion (+6% year-on-year).
- In the Overseas segment, the company has initiated the process for selling/withdrawing from the Medical Platform and decided to sell its remote chat guidance and stress check businesses in the healthcare domain.
🤖 AI Perspective
SMS’s first-half results show robust revenue and profit growth, with operating profit achieving a high 72% of the full-year target. The planned growth investments in the second half could be a key area for investors to monitor, as they may influence future business development and profit structures. The “selection and concentration” strategy in overseas and other businesses suggests a focus on optimizing the business portfolio, which could aim to enhance long-term corporate value.
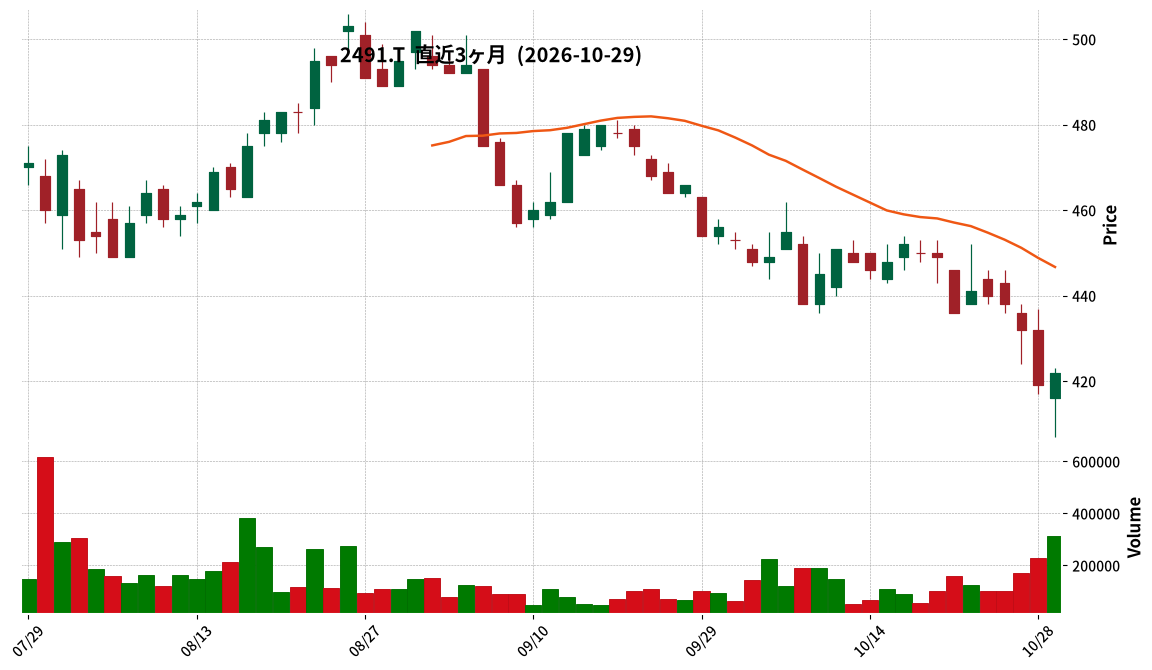
2491|Vコマース
422.0
▲ +0.72%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Vcommerce reported for the third quarter of the fiscal year ending December 2026 (cumulative): Revenue of ¥8,379 million, Operating Loss of ¥767 million, Ordinary Loss of ¥749 million, and Net Loss attributable to owners of parent of ¥661 million.
- The company started disclosing non-consolidated results from the first quarter of the fiscal year ending December 2026; therefore, year-on-year comparisons with Q3 FY2025 are not provided.
- The full-year forecast has been revised: Revenue of ¥11,000 million (down 53.8% from previous forecast), Operating Loss of ¥1,000 million, Ordinary Loss of ¥1,000 million, and Net Loss attributable to owners of parent of ¥900 million.
- The annual dividend forecast is ¥8.00 at Q2 end and ¥8.00 at fiscal year end, totaling ¥16.00.
- During the cumulative third quarter, the termination of transaction agreements related to online mall store services (effective July 31, 2025), strategic investments in narrative marketing for the AI search era, and temporary expenses related to head office relocation were noted.
🤖 AI Perspective
Vcommerce has released its first Q3 results following the transition from consolidated to non-consolidated reporting. The company recorded ¥8,379 million in revenue, with operating and net income figures showing losses. The downward revision of the full-year forecast appears to be influenced by the termination of the online mall service contract, strategic investments, and head office relocation costs. Despite the losses, the dividend forecast of ¥16 per year has been maintained, indicating a policy that considers financial soundness and free cash flow.
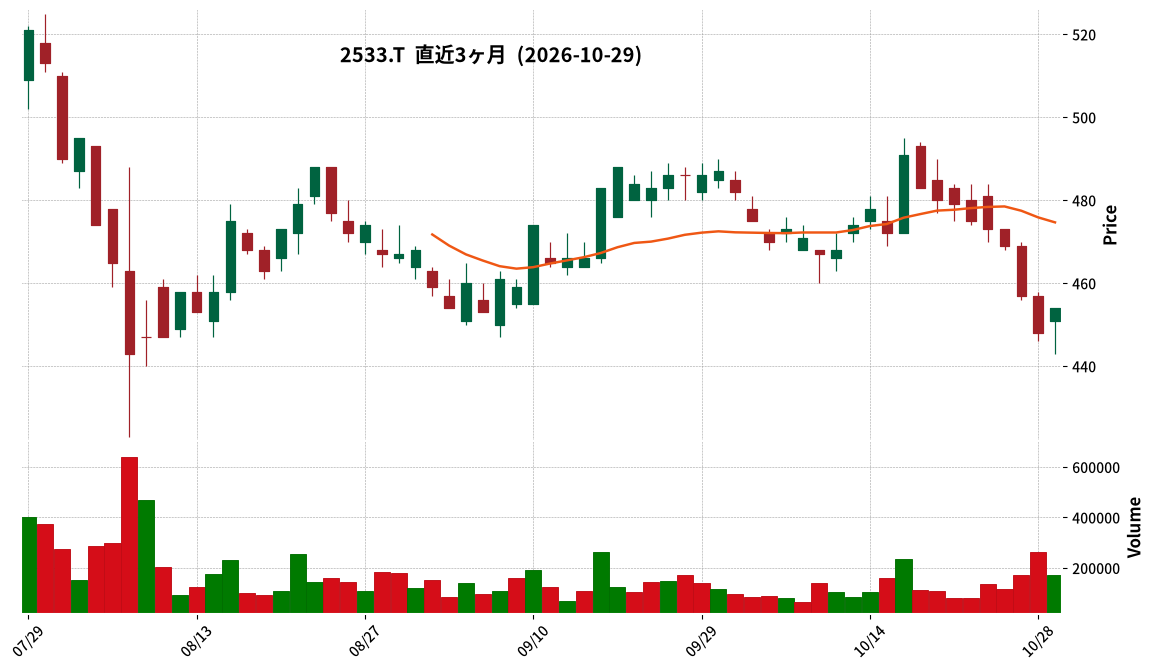
2533|オエノンHD
454.0
▲ +1.34%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Oenon Holdings Co., Ltd. resolved to change its shareholder return policy and revise its dividend forecast at a Board of Directors meeting held on October 29, 2026.
- The shareholder return policy changes include raising the DOE target from 2.5% to 3% and increasing the total return ratio target from over 30% to over 40%.
- These changes will be applied starting from the fiscal year ending December 2026.
- Following the change in the shareholder return policy, the year-end dividend forecast for the fiscal year ending December 2026 was revised upwards by ¥3 per share to ¥15.
- The previous year-end dividend forecast for the fiscal year ending December 2026 was ¥12.00 per share.
🤖 AI Perspective
This IR suggests the company’s commitment to further enhance shareholder returns, moving from conservative targets set during the initial “Medium-Term Management Plan 2028” due to sustained profit growth and strengthening financial health. The increased DOE (Dividend On Equity) target indicates a higher dividend payout ratio relative to shareholder equity, while the raised total return ratio target reflects a greater overall commitment to returning profits through dividends and share repurchases. This proactive stance could be seen as a clear signal of the company’s focus on enhancing shareholder value.
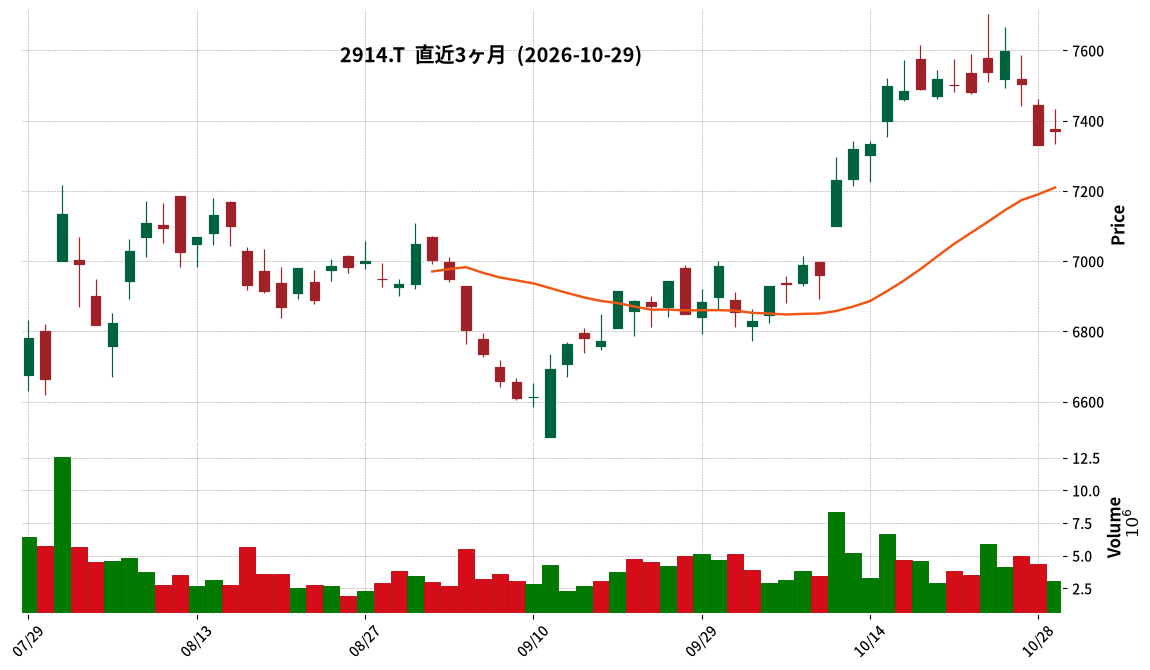
2914|JT
7372.0
▲ +0.55%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- For the third quarter of fiscal year 2026 (cumulative), consolidated revenue totaled JPY 2,991,382 million, an increase of 13.6% year-over-year.
- Consolidated operating profit for the same period was JPY 947,710 million, a 24.2% increase year-over-year.
- Profit attributable to owners of the parent for the quarter reached JPY 618,892 million, up 20.9% from the previous year.
- The full-year consolidated financial forecast for fiscal year 2026 has been revised, projecting revenue of JPY 3,903,000 million (up 12.6% year-over-year), operating profit of JPY 1,041,000 million (up 20.1% year-over-year), and profit attributable to owners of the parent of JPY 662,000 million (up 29.8% year-over-year).
- The annual dividend forecast is JPY 272, comprising an interim dividend of JPY 136 and a year-end dividend of JPY 136.
🤖 AI Perspective
JT’s Q3 results show solid performance with significant increases in both revenue and operating profit compared to the prior year. The reclassification of the pharmaceutical business as a discontinued operation is a key factor in year-on-year comparisons, with focus shifting to the growth trajectory of continuing operations. The upward revision of the full-year forecast could suggest management’s positive outlook on sustained profitability.
3426|アトムリビン
1300.0
▼ -0.84%
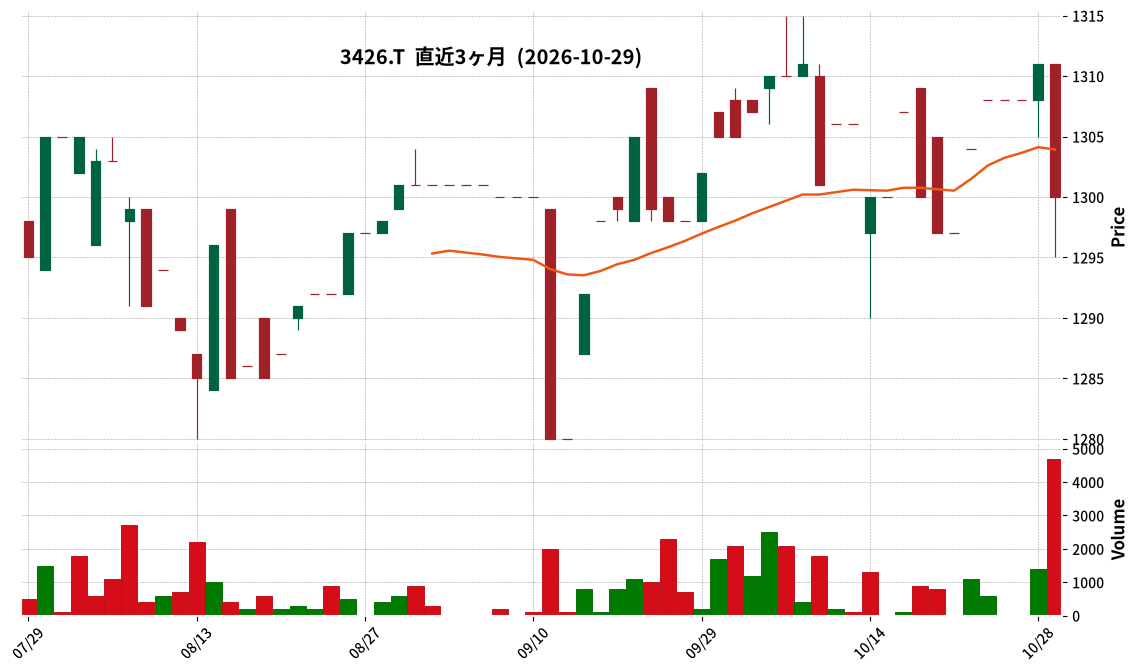
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Atom Livin Tech Co., Ltd. announced its unaudited financial results for the first quarter of fiscal year 2027 (July 1, 2026 – September 30, 2026).
- Net sales for the first quarter totaled ¥2,482 million, a decrease of 0.5% compared to the same period of the previous fiscal year.
- Operating profit significantly increased by 51.4% to ¥133 million, while ordinary profit rose by 50.3% to ¥155 million.
- Quarterly net income amounted to ¥108 million, up 48.8% year-on-year.
- Earnings per share for the quarter were ¥27.17, compared to ¥18.26 in the prior year’s first quarter.
- Total assets stood at ¥11,866 million, net assets at ¥10,733 million, and the equity ratio was 90.4%.
- The company’s full-year earnings forecast and dividend forecast (total annual dividend of ¥33.00, including a year-end dividend of ¥16.50) remain unchanged from the most recently announced figures.
🤖 AI Perspective
Despite a slight dip in net sales, the substantial growth in all profit metrics suggests that the company’s efforts to enhance profitability, potentially through cost controls and operational efficiencies, may be bearing fruit. The high equity ratio of 90.4% indicates a strong financial foundation, which could provide stability amid an uncertain economic outlook for the housing market.
4307|NRI
6033.0
▼ -1.69%
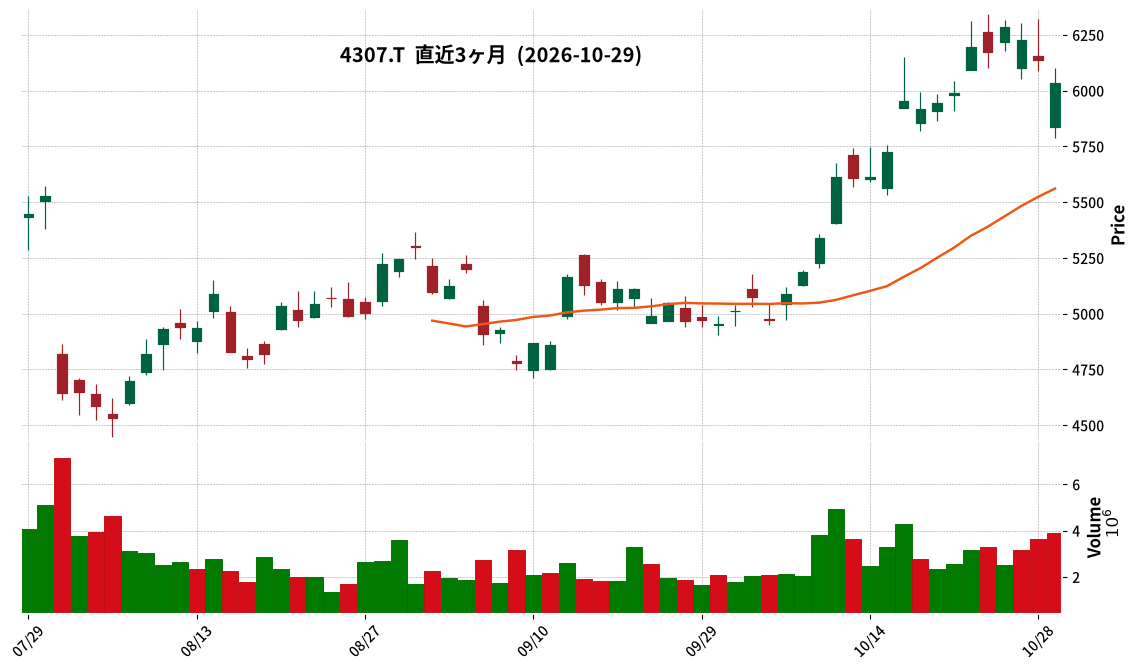
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- NRI announced its consolidated financial results for the second quarter of the fiscal year ending March 2027.
- Revenue for the period was ¥429,906 million (an 8.3% increase year-on-year), and operating profit was ¥88,272 million (a 12.0% increase year-on-year).
- Profit attributable to owners of the parent company amounted to ¥60,014 million (a 12.0% increase year-on-year).
- The full-year consolidated earnings forecast for the fiscal year ending March 2027 was revised upwards, with revenue projected at ¥870,000 million (a 2.4% increase from the previous forecast) and profit attributable to owners of the parent company at ¥123,000 million (a 10.8% increase from the previous forecast).
- The annual dividend forecast was revised to ¥46.00 for the year-end, totaling ¥88.00 (a 1.1% increase from the previous forecast). An interim dividend of ¥42.00 is planned.
- The company canceled 20,044,102 shares of treasury stock on June 30, 2026.
🤖 AI Perspective
The robust growth in key revenue and profit figures during the second quarter suggests a strong operational performance by NRI. The upward revision of both full-year earnings and dividend forecasts could indicate management’s positive outlook on future business conditions and profitability. The cancellation of treasury shares may reflect the company’s commitment to enhancing capital efficiency.
4502|武田薬
6399.0
▲ +1.46%
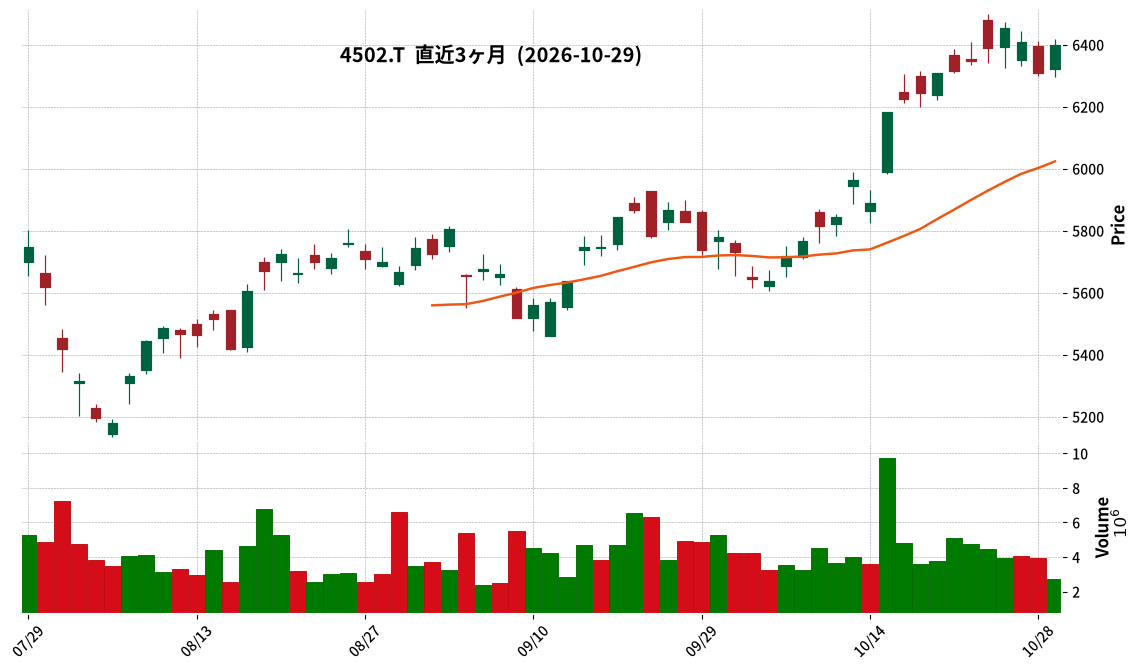
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Takeda Pharmaceutical announced its consolidated financial results for the second quarter (interim) of the fiscal year ending March 2027.
- Revenue for the interim period was ¥2,406,997 million, representing an 8.4% increase compared to the prior interim period.
- Net profit attributable to owners of the parent reached ¥305,626 million, marking a 171.8% increase year-on-year.
- Core Operating Profit was ¥7,106 billion, an increase of 11.2% from the previous interim period.
- The full-year consolidated earnings forecast for the fiscal year ending March 2027 has been revised to ¥4,700,000 million for revenue, ¥209,000 million for net profit attributable to owners of the parent, and Core EPS of ¥482.
🤖 AI Perspective
The interim consolidated results show significant growth across revenue, operating profit, and net profit attributable to owners of the parent, which may suggest a strong operational performance in the period. The substantial increase in net profit attributable to owners of the parent could be a key focus for investors. The revision of the full-year forecast indicates the company’s updated outlook, and its realization will be worth monitoring.
4552|JCRファーマ
511.0
▼ -0.20%
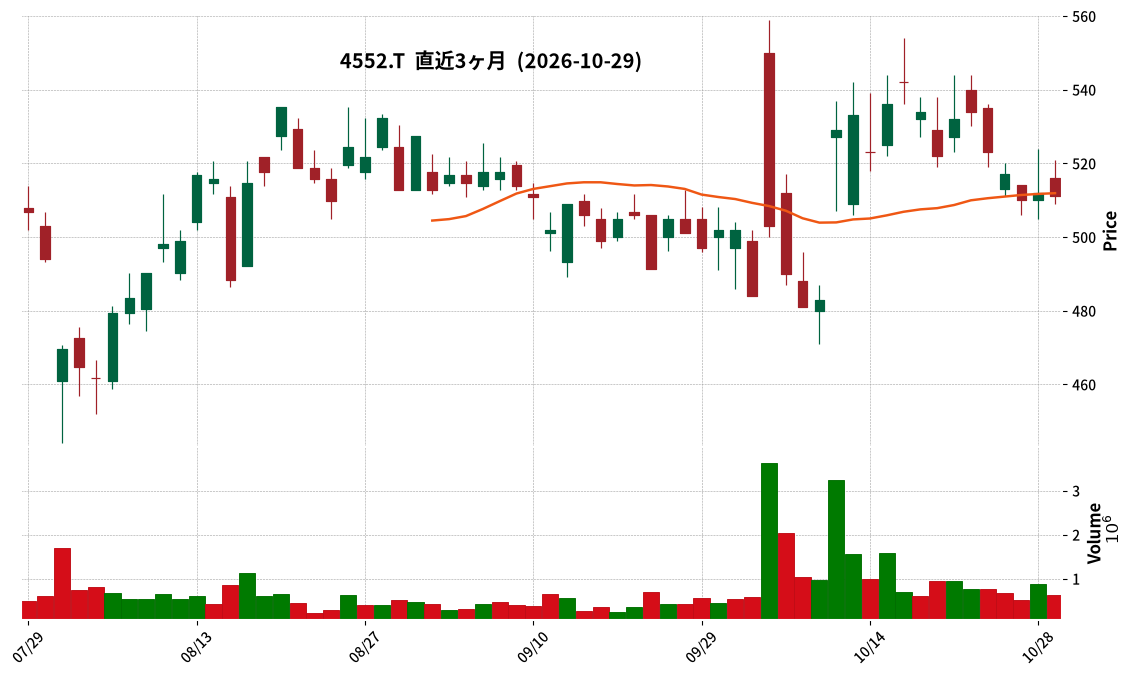
📎 Source:JCRファーマ Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- For the second quarter of FY2027, JCR Pharmaceuticals reported net sales of 19,974 million yen (decrease year-over-year) and an operating loss of 3,504 million yen (compared to 2,429 million yen profit in the prior year).
- Selling, general and administrative expenses totaled 17,726 million yen, with research and development expenses accounting for 10,230 million yen, representing an increase from the previous fiscal year’s corresponding period.
- For givinostat, a Duchenne Muscular Dystrophy (DMD) treatment, the company aims for a manufacturing and marketing approval application in Japan by 2026 and approval and sales launch by 2027, with domestic clinical trials having commenced.
- In Alzheimer’s disease treatment development, Acumen exercised its option for an AβO-selective antibody utilizing J-Brain Cargo®, with an Investigational New Drug (IND) application expected in mid-2027.
- Izcargo® (JR-141), an enzyme replacement therapy for Mucopolysaccharidosis II, obtained marketing approval in two Middle Eastern countries (UAE, Kuwait) and the company signed an exclusive license agreement with Italfarmaco for development and commercialization in the US, Europe, and Latin America.
🤖 AI Perspective
While the Q2 FY2027 results show a decrease in revenue and an operating loss primarily due to reduced upfront payments, the increase in R&D expenses can be viewed as an investment in future pipeline development. The in-licensing of givinostat for DMD and the advancement of J-Brain Cargo® technology out-licensing across multiple programs are notable steps towards the company’s long-term goal of achieving 100 billion yen in sales by the 2030s. Global approvals and licensing agreements could indicate accelerating international expansion.
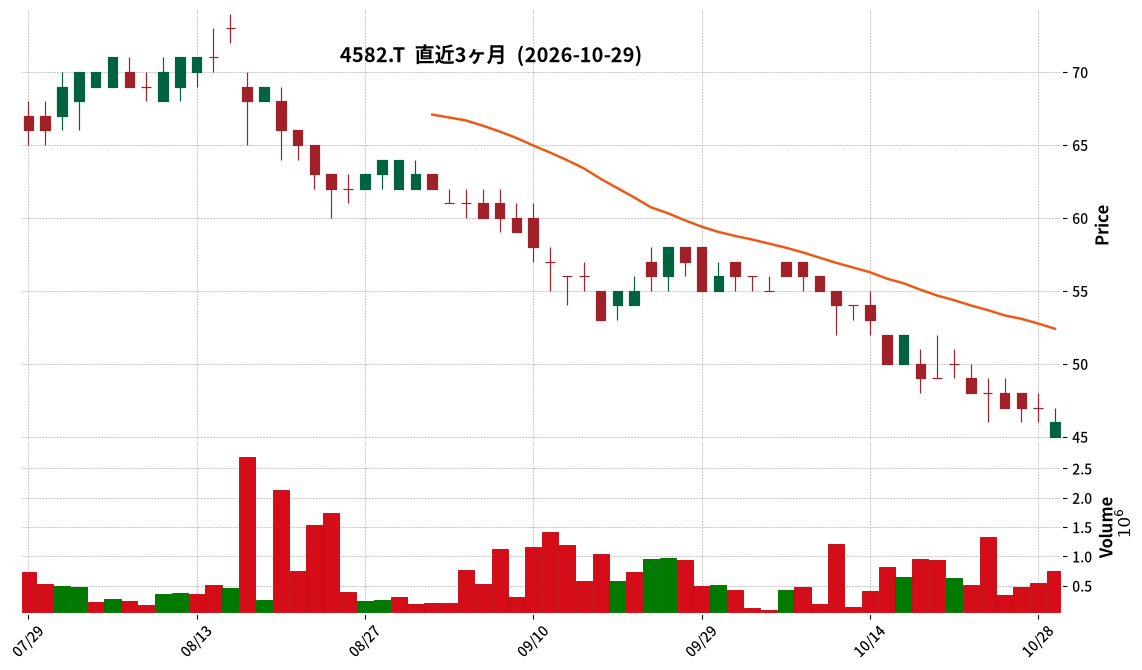
4582|G-シンバイオ製薬
46.0
▼ -2.13%
📎 Source:G-シンバイオ製薬 Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- For the nine months ended September 30, 2026 (Q3 FY2026), net sales were ¥722 million, representing a 25.6% decrease year-over-year.
- The company reported an operating loss of ¥4,870 million, an ordinary loss of ¥4,849 million, and a net loss attributable to owners of parent of ¥4,879 million.
- Selling, general and administrative expenses totaled ¥5,397 million (a 33.8% increase YoY), with R&D expenses accounting for ¥3,968 million (a 61.9% increase YoY).
- As of the end of the third quarter, total assets were ¥932 million, net assets were negative ¥1,295 million, and the equity ratio was -165.1%.
- Regarding brincidofovir (BCV), 41 patients were enrolled in the global Phase III clinical trial for adenovirus infection after hematopoietic stem cell transplantation as of October 22.
🤖 AI Perspective
G-シンバイオ製薬’s Q3 FY2026 results show a notable increase in research and development expenses despite a decrease in net sales. This suggests a continued aggressive investment in core development pipelines such as brincidofovir (BCV). This financial profile is typical for a biotech company with significant upfront R&D investments, and the progress of ongoing clinical trials and the commercialization prospects of its pipeline will likely remain key areas for investor focus.
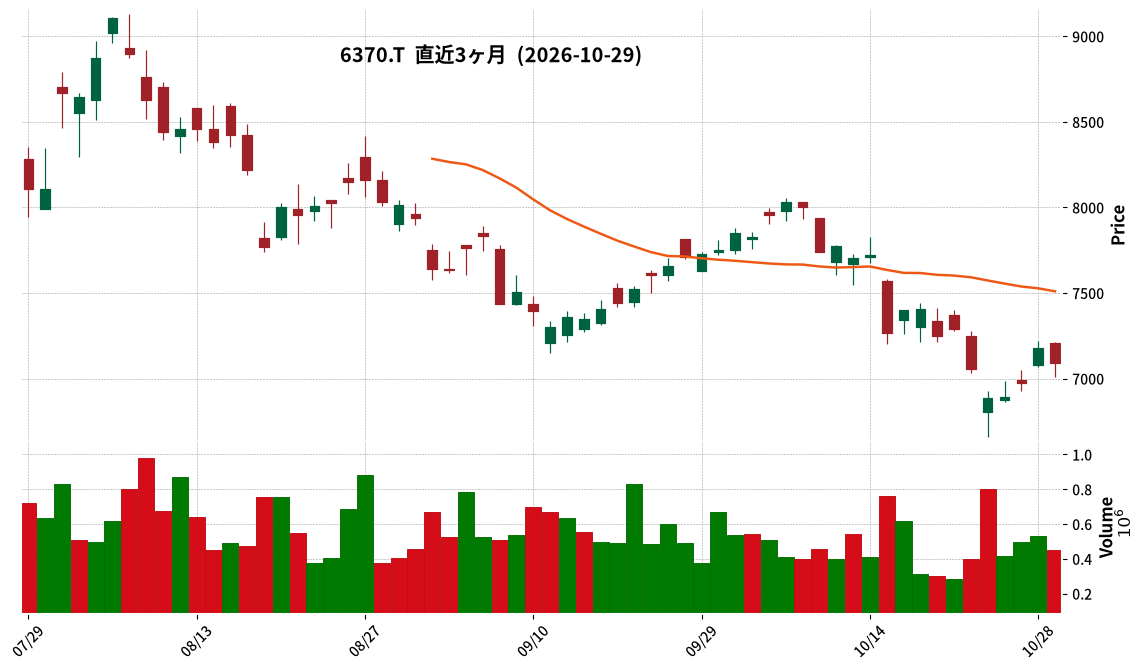
6370|栗田工
7090.0
▼ -1.20%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Kurita Water Industries has revised its consolidated earnings forecast downward for the second quarter (interim) and full year of the fiscal year ending March 2027.
- The primary reason for the revision is an estimated construction loss of 20 billion JPY (interim) and 23.6 billion JPY (full year) for a single large-scale water treatment equipment project for the electronics industry undertaken by its US consolidated subsidiary, Kurita America, Inc., due to significant increases in estimated total construction costs stemming from design delays and quality issues.
- For the interim period of FY2027, the consolidated earnings forecast has been revised to net sales of 206.8 billion JPY (up 4.4% from previous forecast), operating profit of 6.2 billion JPY (down 73.6%), and profit attributable to owners of the parent of 7.3 billion JPY (down 70.3%).
- For the full year of FY2027, the consolidated earnings forecast has been revised to net sales of 455.0 billion JPY (up 7.1%), operating profit of 40.0 billion JPY (down 35.0%), and profit attributable to owners of the parent of 28.7 billion JPY (down 43.4%).
- In the non-consolidated financial statements, a special loss of 36.2 billion JPY for impairment loss on shares of affiliates will be recorded in the interim period of FY2027 due to a significant decrease in the fair value of shares in Kurita America Holdings, Inc.; this loss will be eliminated in the consolidated financial statements and thus has no impact on consolidated earnings.
- There is no change to the dividend forecast.
🤖 AI Perspective
This earnings forecast revision appears to be primarily driven by a substantial increase in construction costs for a specific large-scale US project, significantly impacting profits despite an upward revision in sales. The recording of a special loss in the non-consolidated financial statements, while not affecting consolidated results, suggests a considerable devaluation of the subsidiary. Investors may want to monitor the company’s upcoming financial results briefing for further details, particularly regarding strengthened management systems and the application of gained knowledge to future projects.
6702|富士通
4322.0
▼ -2.88%
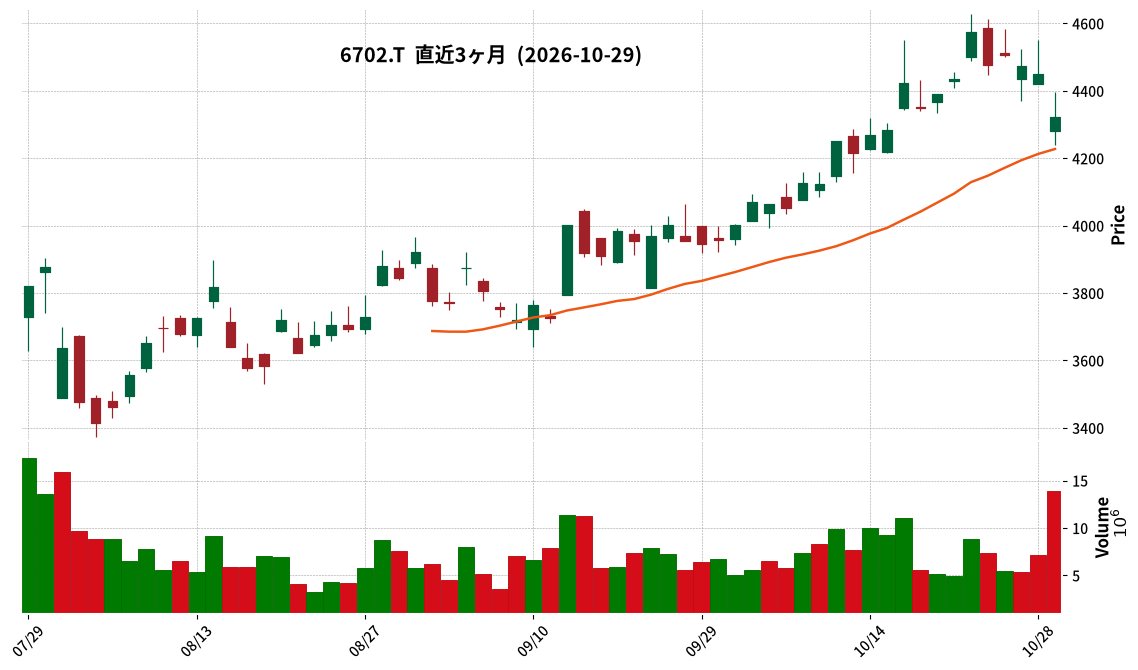
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Fujitsu Limited announced its consolidated financial results for the second quarter (interim period) of the fiscal year ending March 2027.
- Revenue for the interim period of FY2027 was ¥1,626,358 million, marking a 3.8% increase compared to the prior interim period.
- Operating profit was ¥107,602 million, an increase of 2.1% year-on-year for the interim period.
- Interim profit attributable to owners of the parent was ¥82,581 million, a decrease of 68.5% compared to the prior interim period.
- Basic interim earnings per share stood at ¥47.68.
- The forecast for the full-year dividend for FY2027 is ¥55 per share (interim ¥25, year-end ¥30), with an interim dividend of ¥25 per share planned, which is the same amount as the prior interim period.
- The full-year consolidated earnings forecast remains unchanged, with revenue projected at ¥3,510,000 million and profit attributable to owners of the parent at ¥310,000 million.
🤖 AI Perspective
Fujitsu’s interim results show a solid increase in revenue, while profit attributable to owners of the parent significantly decreased. This notable decrease in profit may be attributed to a high base effect from the previous year, which included substantial adjustments related to business reorganization and M&A activities. When considering adjusted interim profit, which aims to reflect core business performance, an increase was observed, suggesting underlying operational stability. The company’s decision to maintain its full-year earnings forecast could indicate an expectation for a stronger performance in the second half of the fiscal year.
6754|アンリツ
3120.0
▲ +3.00%
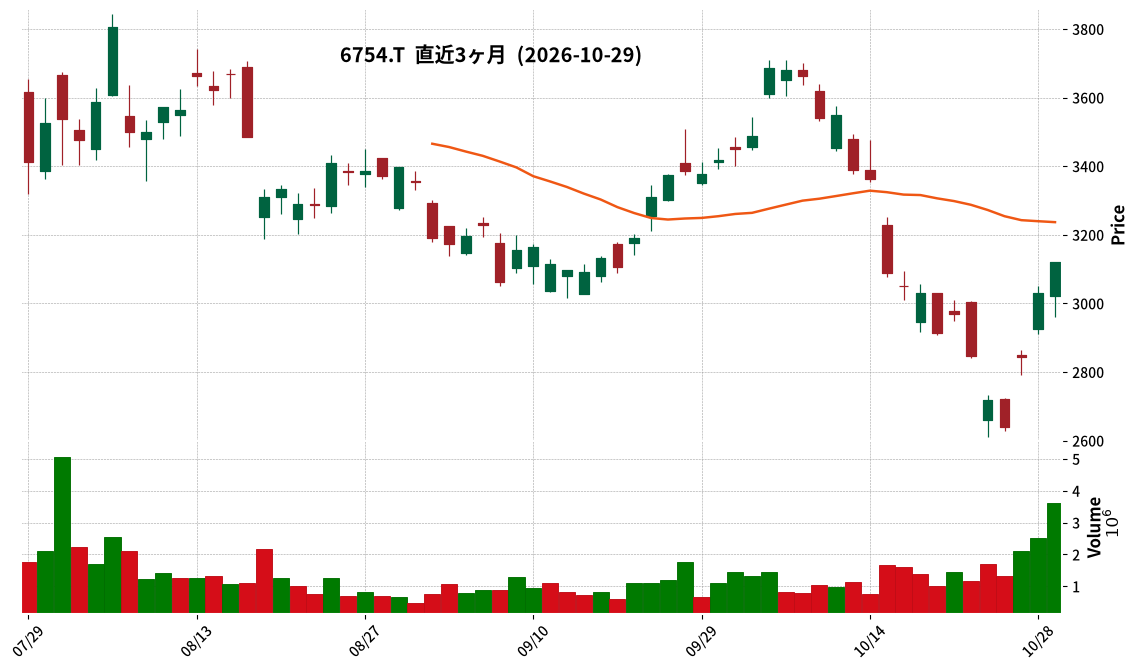
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Anritsu announced its consolidated financial results for the second quarter (H1) of the fiscal year ending March 2027. Revenue reached ¥69,313 million (up 34.1% year-on-year), operating profit was ¥9,553 million (up 89.8% year-on-year), and profit attributable to owners of the parent was ¥6,553 million (up 72.0% year-on-year).
- The consolidated full-year earnings forecast was revised upwards, with revenue projected at ¥145,000 million (up ¥15,000 million from previous forecast), operating profit at ¥22,000 million (up ¥5,000 million), and profit attributable to owners of the parent at ¥16,000 million (up ¥3,500 million).
- The annual dividend forecast was also revised to a total of ¥63.00 (mid-term: ¥25.00, year-end: ¥38.00), an increase of ¥13.00 from the previous forecast.
- By segment, the Communications Test and Measurement business recorded revenue of ¥42,115 million (up 36.1% year-on-year) and operating profit of ¥8,693 million (up 120.2% year-on-year).
- In the Environmental and Measurement business, an impairment loss was recorded for a portion of goodwill at its consolidated subsidiary, Takasago Ltd.
🤖 AI Perspective
These interim results suggest that robust demand in the Communications Test and Measurement business, particularly driven by data center expansions and the production increase of 800GE and 1.6TE optical transceivers, has been a key factor in the strong performance. The upward revision of full-year earnings and dividend forecasts could reflect positive momentum and future outlook. However, the impairment loss in the Environmental and Measurement business indicates specific market challenges in that segment, which may be worth monitoring in the context of the company’s overall business portfolio.
6810|マクセル
2496.0
▼ -1.34%
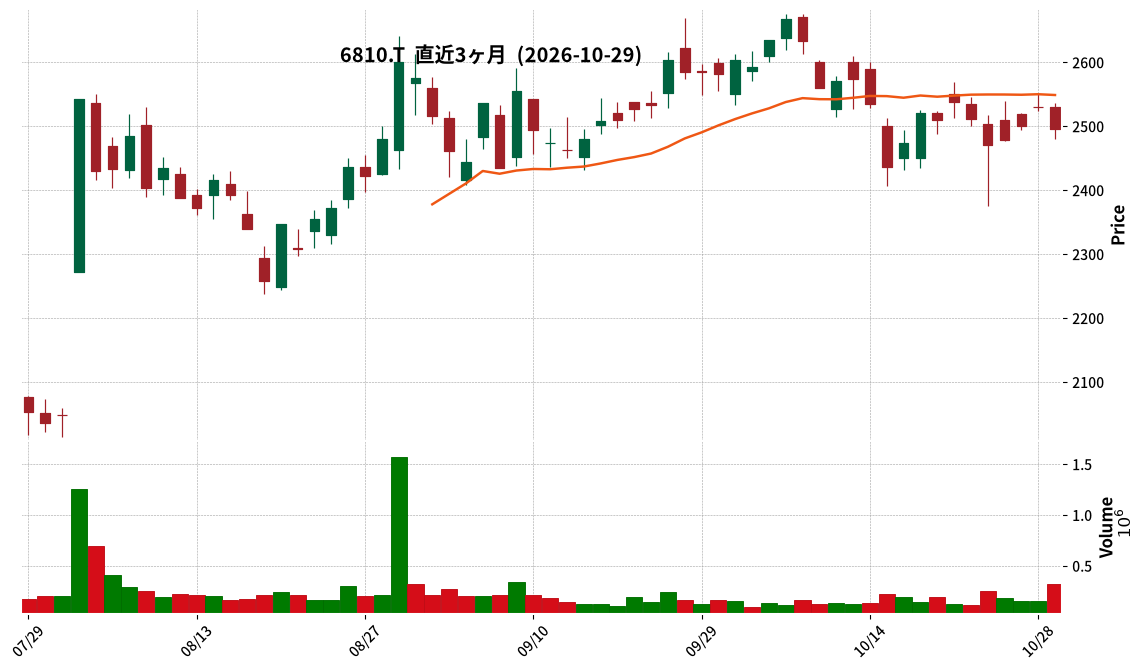
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Maxell Co., Ltd. announced its consolidated financial results for the second quarter (interim period) of the fiscal year ending March 2027.
- Revenue for the interim period was ¥74,850 million (up 15.8% year-on-year), operating profit was ¥5,762 million (up 14.0%), ordinary profit was ¥5,814 million (up 13.8%), and net profit attributable to owners of parent was ¥4,747 million (up 12.1%).
- Diluted earnings per share for the interim period were ¥128.76.
- The full-year dividend forecast remains unchanged at ¥28.00 for the second quarter end and ¥28.00 for the fiscal year end, totaling ¥56.00.
- The full-year consolidated earnings forecast also remains unchanged, projecting revenue of ¥143,000 million (up 10.5% year-on-year), operating profit of ¥10,000 million (up 26.7%), and net profit attributable to owners of parent of ¥6,700 million (down 18.9%), with diluted earnings per share of ¥181.74.
🤖 AI Perspective
Maxell’s interim results for FY2027 indicate robust growth across key financial metrics, with revenue and profits showing significant year-on-year increases. This performance appears to be driven by strong contributions from the energy and functional materials segments. While the full-year forecast remains consistent with previous announcements, the positive interim performance could suggest a strong trajectory for the company’s fiscal year.
7191|イントラスト
1162.0
▼ -0.85%
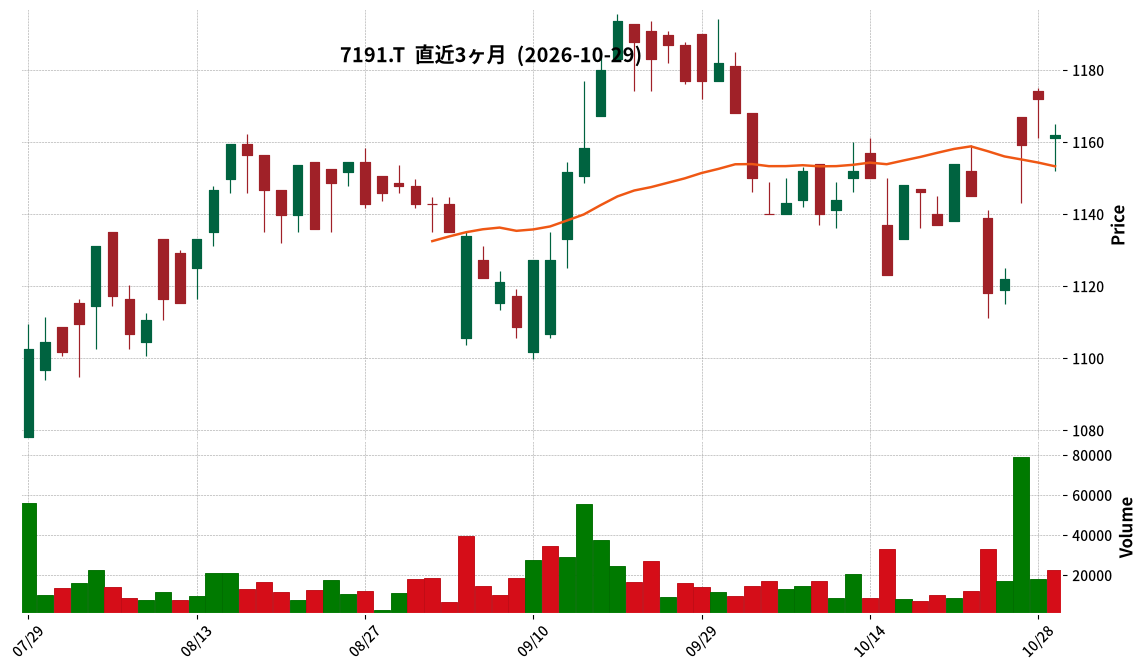
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Entrust’s consolidated results for the second quarter (interim) of the fiscal year ending March 2027 show net sales of ¥7,017 million (up 19.7% year-on-year), operating income of ¥1,582 million (up 14.0%), ordinary income of ¥1,596 million (up 14.0%), and net income attributable to owners of parent of ¥975 million (up 10.8%).
- Sales from the guarantee business amounted to ¥6,040 million (up 12.4% year-on-year), and IT services sales were ¥585 million. The IT services sales are attributed to the consolidation of Carol System Co., Ltd. in January 2026.
- The forecast for the full-year dividend for the fiscal year ending March 2027 is ¥53, consisting of ¥26 at the interim period-end and ¥27 at the fiscal year-end, with no revision from the most recently announced dividend forecast.
- The consolidated full-year earnings forecast for the fiscal year ending March 2027 remains unchanged from the previous announcement, projecting net sales of ¥14,370 million (up 17.0% from the previous fiscal year), operating income of ¥3,180 million (up 14.9%), and net income attributable to owners of parent of ¥1,960 million (up 12.4%).
- Total assets at the end of the interim consolidated accounting period were ¥13,576 million, with an equity ratio of 63.0%.
🤖 AI Perspective
Entrust demonstrated robust growth in its interim results, driven by strong performance in its core guarantee business and the contribution of IT services sales following a subsidiary acquisition. The consistent full-year dividend forecast may suggest a stable commitment to shareholder returns. The affirmation of the full-year earnings forecast could indicate management’s confidence in achieving its targets.
Disclaimer: This article is for informational purposes only and does not constitute investment advice.
7388|FPパートナー
2282.0
▼ -1.21%
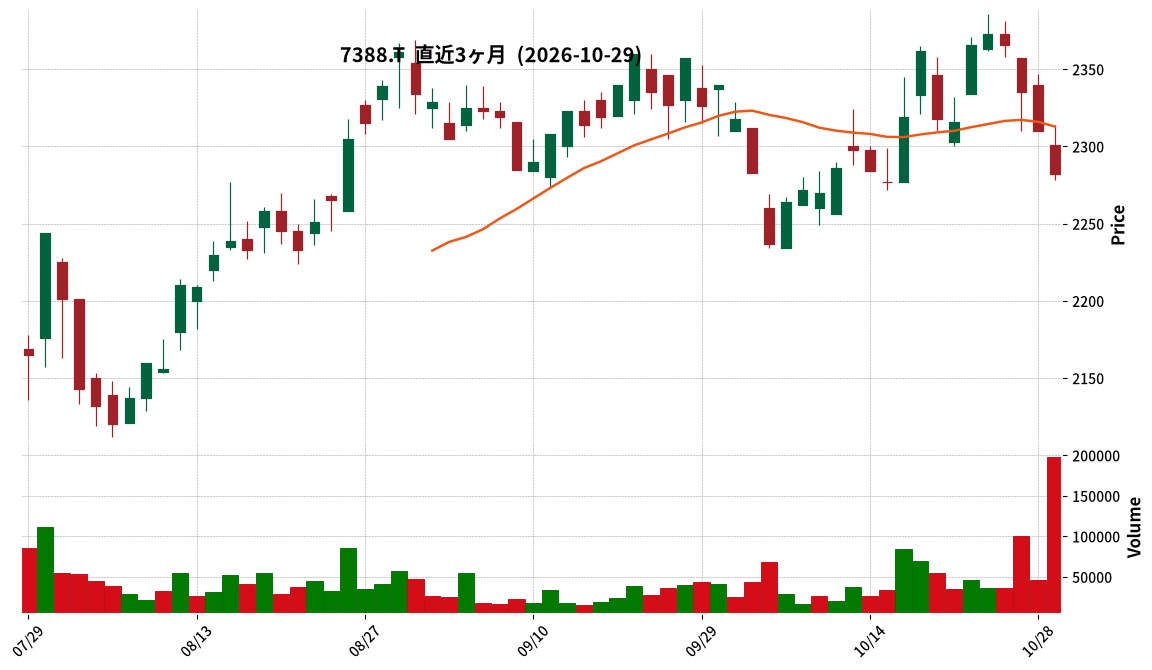
📎 Source:FPパートナー Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Q3 FY2026 standalone net sales and operating profit decreased from Q2, primarily due to seasonal factors and a change in fee payment methods for major lump-sum products (from one-time upfront payment to approximately 50% next month + remaining over 7 years).
- Cumulative Q3 progress rates against the revised full-year forecast are: Net Sales 73.7%, Operating Profit 67.1%, Ordinary Profit 69.1%, and Net Profit 67.7%. While profit aspects lag the 75% elapsed period, progress is described as “largely as expected.”
- Efforts with all partner companies, which were suspended due to the administrative improvement order in August last year, have resumed, and customer acquisition is on a recovery trend.
- Although the number of sales employees decreased by 188 year-on-year, Q3 saw a net increase of 15, marking a shift from sequential net reductions to net increases. This includes three consecutive months of net increases from July to September.
- In the contract transfer business, contract signings were delayed awaiting public comments on insurance business law revisions. However, regulatory outlook is clarifying, and business negotiations are being concretized. Projects exceeding the scale of the previous period’s Prestige case are also under consideration.
🤖 AI Perspective
The change in fee payment methods for lump-sum products in Q3 may impact short-term profit margins but could contribute to long-term recurring revenue growth. The recovery in customer acquisition from partner firms and the shift to a net increase in sales employees appear to be crucial indicators for future performance recovery. The progress in the contract transfer business is also a point to monitor as a potential future growth driver.
1946|トーエネック
2189.0
▲ +0.41%
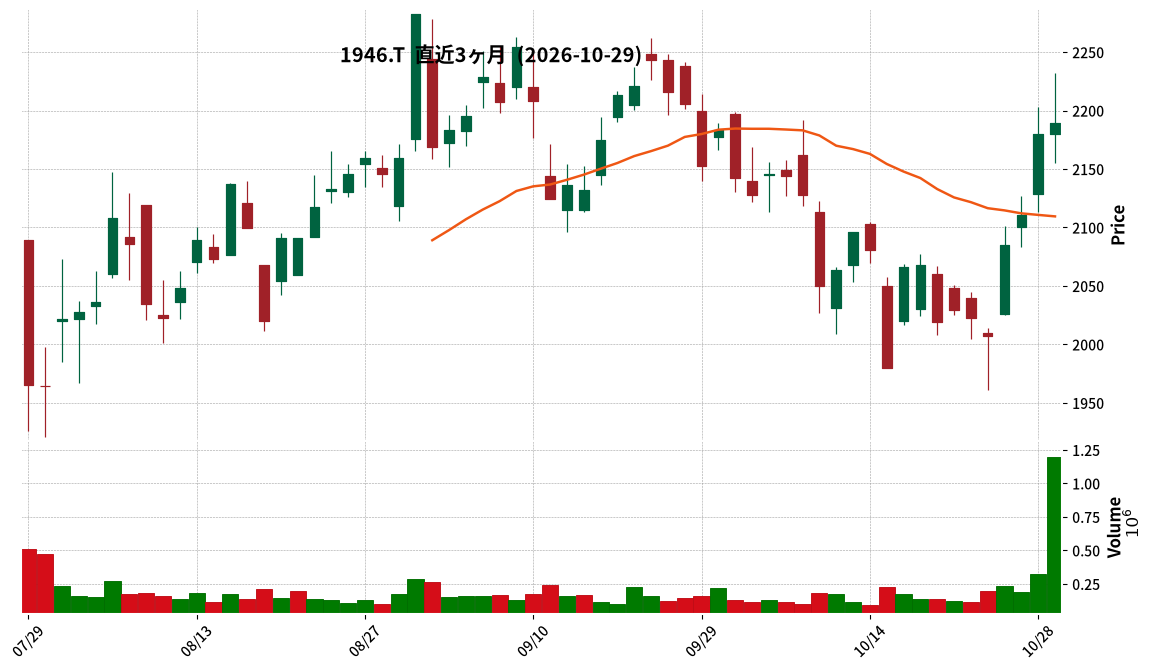
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Toenec Inc. announced its Q2 FY2027 (interim) consolidated financial results on October 29, 2026.
- For the interim period, consolidated net sales were ¥125,276 million (up 0.5% year-on-year), and operating profit was ¥10,178 million (up 18.8% year-on-year).
- Ordinary profit reached ¥9,881 million (up 13.8% year-on-year), and net income attributable to owners of parent was ¥7,573 million (up 5.0% year-on-year).
- Interim net income per share was ¥81.03.
- The annual dividend forecast for the fiscal year ending March 2027 remains ¥76.00 (interim dividend of ¥31.00 and year-end dividend of ¥45.00), with no revisions from the latest public forecast.
- The full-year consolidated earnings forecast remains unchanged: net sales of ¥285,000 million (up 4.6% year-on-year), operating profit of ¥24,000 million (up 12.0% year-on-year), ordinary profit of ¥23,500 million (up 3.8% year-on-year), and net income attributable to owners of parent of ¥18,000 million (up 1.1% year-on-year).
🤖 AI Perspective
Toenec’s Q2 FY2027 results show solid growth in both revenue and profit, with operating profit notably increasing by 18.8% year-on-year. This performance may suggest the company’s strategies to improve project profitability and the recording of settlement payments have been effective. The unchanged full-year earnings and annual dividend forecasts could indicate the company maintains confidence in its current trajectory and outlook for the fiscal year.
2811|カゴメ
2696.0
▲ +0.60%
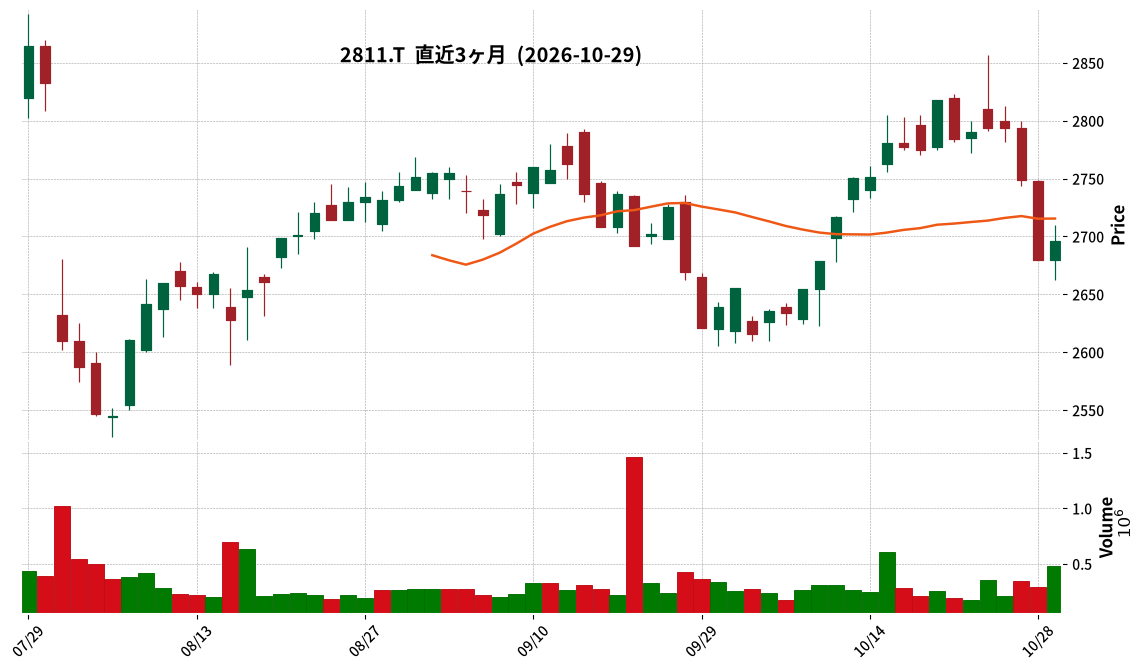
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Kagome Co., Ltd. has announced its consolidated financial results for the third quarter of the fiscal year ending December 2026.
- For the nine months ended September 30, 2026 (January 1 to September 30, 2026), revenue was ¥226,666 million, a 4.8% increase year-on-year.
- Business profit was ¥14,806 million (down 14.5% YoY), operating profit was ¥15,594 million (down 11.2% YoY), and profit attributable to owners of the parent was ¥8,548 million (down 20.0% YoY).
- The company has early adopted IFRS 18 “Presentation and Disclosure in Financial Statements” from the current consolidated fiscal year, and prior-year comparative figures have been retrospectively restated to reflect this change.
- There are no revisions to the full-year consolidated performance forecast for the fiscal year ending December 2026, nor to the dividend forecast (year-end ¥58.00, total ¥58.00) from the latest publicly announced figures.
🤖 AI Perspective
While revenue increased, business profit, operating profit, and profit attributable to owners of the parent all declined, which may draw investor attention to profitability and cost management. The early adoption of IFRS 18 has changed the presentation of profit metrics, suggesting that comparisons with the prior year period should consider this accounting policy change. The reaffirmation of the full-year forecast could indicate that the company views the current profit decline as temporary or anticipates a recovery in the remaining period.
7357|ジオコード
1697.0
▼ -0.24%
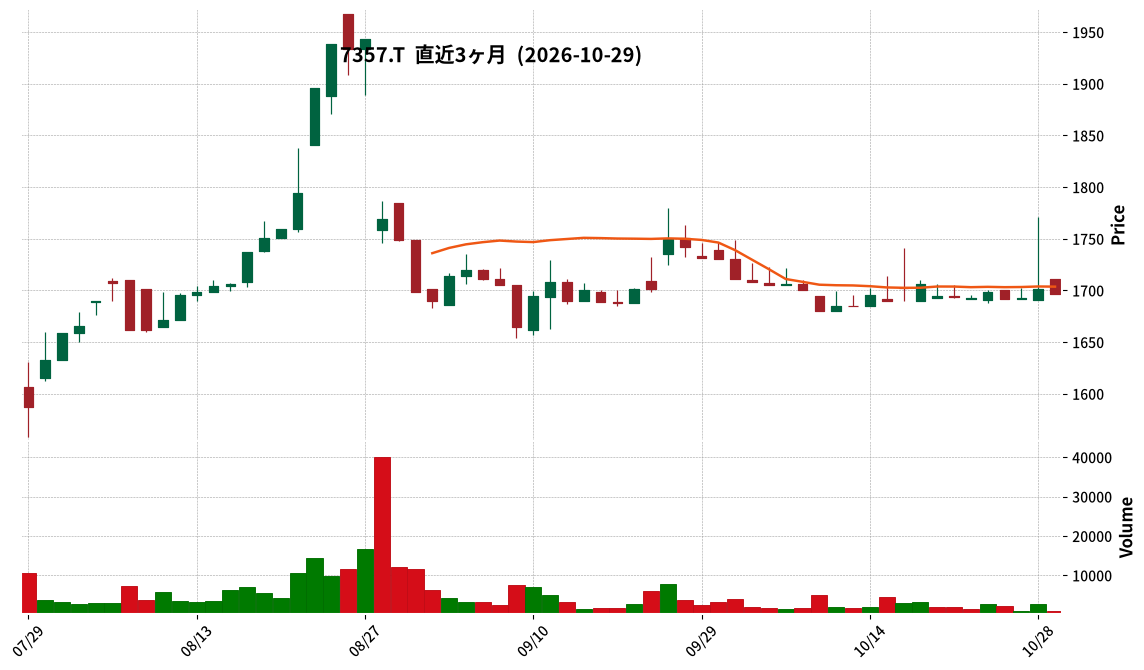
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Geocode Inc. has set the dispatch date for the “Digital Gift” shareholder benefit guide for the interim period of February 2027 as November 12, 2026 (Thursday).
- Eligible shareholders are those listed or recorded in the shareholder registry as of August 31, 2026, who hold 2 or more units (200 shares) of the company’s stock.
- The benefit consists of a 5,000 yen “Digital Gift,” with the redemption period from November 13, 2026 (Friday) to January 29, 2027 (Friday).
- Among the exchangeable items for the “Digital Gift,” “Hulu Ticket” is currently temporarily suspended, making the total number of exchangeable items 29.
- The “Shareholder Benefit Guide” will be mailed to the address registered in the shareholder registry, along with interim dividend related documents.
🤖 AI Perspective
This announcement provides clear timelines for shareholders to receive their benefits, which could be seen as an effort to enhance shareholder convenience and transparency. The slight adjustment in the list of exchangeable items might be noteworthy for shareholders planning their redemption choices. Such regular updates on shareholder returns may contribute to the company’s appeal to long-term investors.
7950|デコラックス
—
▲ +0.00%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Japan Decoluxe Co., Ltd. announced its unaudited financial results for the second quarter of the fiscal year ending March 2027 (interim period) on October 29, 2026.
- For the interim period of FY2027, net sales were ¥3,072 million, representing a 1.5% increase compared to the prior interim period.
- Operating income was ¥380 million (+25.3% YoY), ordinary income was ¥473 million (+34.1% YoY), and interim net income was ¥380 million (+55.7% YoY).
- Diluted earnings per share for the interim period stood at ¥488.01.
- The year-end dividend forecast is ¥220.00, resulting in a full-year estimated dividend of ¥370.00 (including an interim dividend of ¥150.00). There is no revision to the most recently announced dividend forecast.
- The full-year forecast for FY2027 remains unchanged, projecting net sales of ¥6,400 million (+2.5% YoY), operating income of ¥600 million (-8.0% YoY), ordinary income of ¥730 million (-4.7% YoY), and net income of ¥1,630 million (+217.8% YoY).
3174|ハピネス&D
325.0
▼ -0.61%
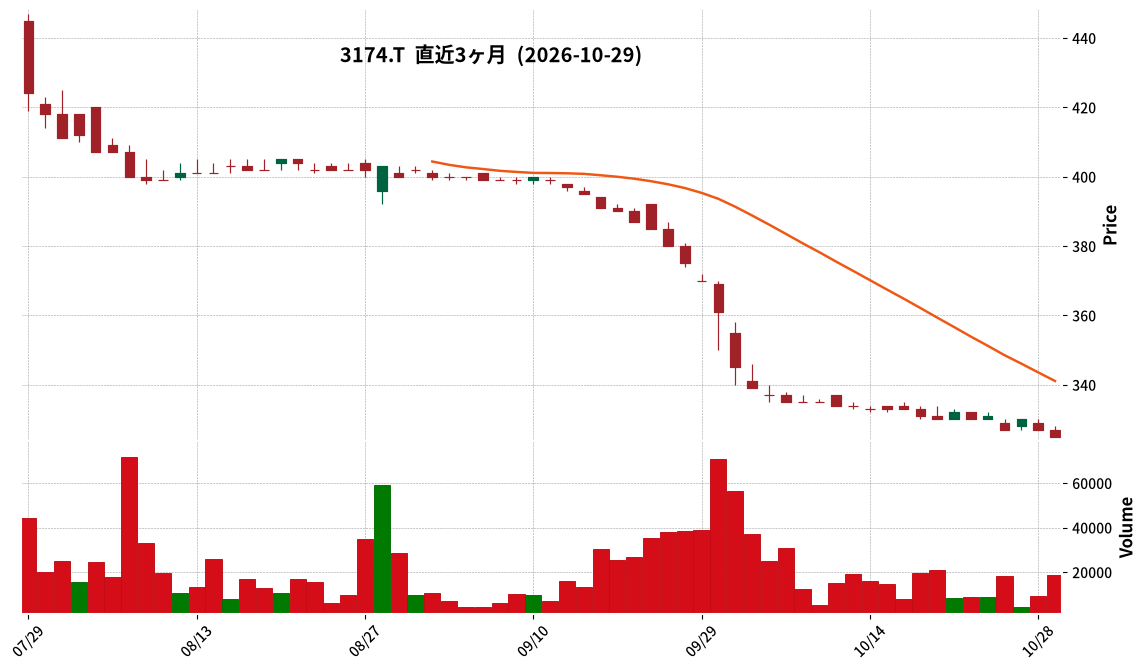
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Happiness & D published its earnings presentation for the fiscal year ended August 2026 on October 29, 2026.
- Stores handling vintage (reused) products expanded to 51 out of 52 locations.
- Despite a slight decrease in like-for-like sales of 98.2%, gross profit increased by 104.9% year-on-year due to gross margin improvement initiatives.
- Jewelry sales performed strongly, while gold bullion product sales grew in the first half but decelerated in the second half due to gold market fluctuations.
- The number of stores handling buyback services expanded to 29 out of 52, with a target of 50 stores for the next period.
- All share options issued via third-party allotment in November 2025 were fully exercised, and those issued in June 2026 were fully exercised by October 2026.
🤖 AI Perspective
Happiness & D’s fiscal year 2026 results indicate a progressing business model transformation, driven by the expansion of vintage product handling and the strengthening of buyback operations. While gold price fluctuations significantly impact gold bullion jewelry sales, ongoing efforts to improve profitability through better gross margins and a reinforced financial base are evident. The evolution of the business portfolio and its contribution to future earnings will be worth monitoring.
4290|PI
678.0
▼ -2.45%
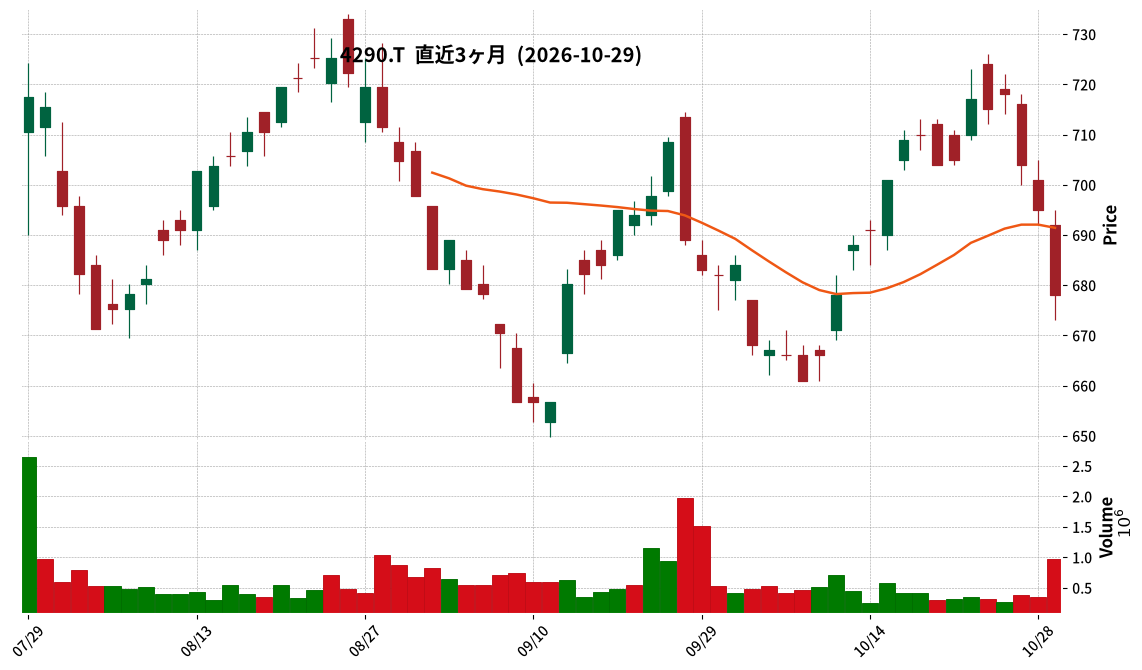
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- For the first half of FY2027, consolidated net sales reached 37,467 million JPY (up 8.9% year-on-year) and consolidated operating profit was 4,669 million JPY (up 9.7% year-on-year).
- Net profit attributable to parent company shareholders decreased by 11.4% year-on-year to 2,359 million JPY, primarily due to commemorative shareholder benefit expenses, increased corporate tax burden, and extraordinary losses from temporary asset disposals related to new office openings.
- The full-year forecast remains unchanged, with projected net sales of 76,000 million JPY and operating profit of 9,600 million JPY.
- By segment, the full-year performance forecast for the Financial Guarantee business was revised upwards for both sales and operating profit, while Automotive, Global, Customer, and Social segments were revised downwards.
- The share repurchase of approximately 1 billion JPY resolved on July 28, 2026, has been completed, demonstrating progress towards the 13 billion JPY total shareholder return target set in the 8th Medium-Term Management Plan.
🤖 AI Perspective
The increase in net sales and operating profit for the interim period, driven by growth in core businesses, appears to be a positive aspect. However, the decline in net profit due to one-off expenses and the offsetting adjustments across segments to maintain the full-year forecast could suggest a balanced approach to managing its business portfolio. The progress in shareholder returns may also be a point of interest for investors.
4755|楽天グループ
617.2
▲ +0.03%
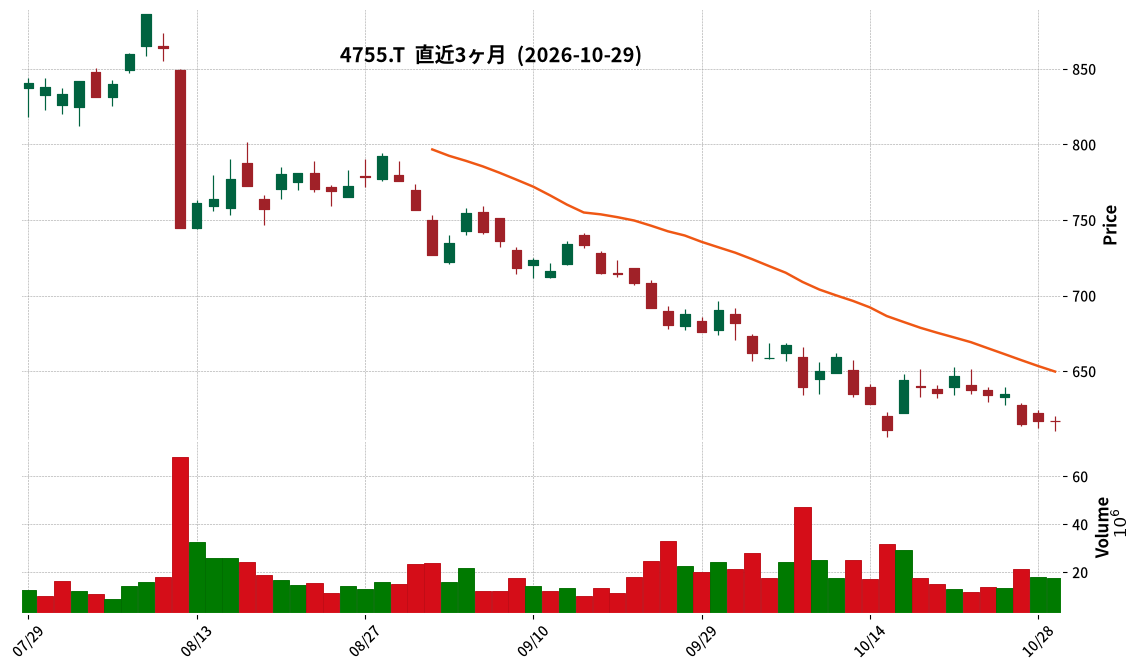
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Rakuten Group, Inc. announced the Q3 FY2026 consolidated financial results (Japanese standards) for its consolidated subsidiary, Rakuten Securities, Inc., on October 29, 2026.
- Rakuten Securities’ operating revenue for the nine months ended September 30, 2026 (Q3 FY2026 consolidated cumulative period) was JPY 165,978 million.
- During the same period, net operating revenue was JPY 148,226 million, operating profit was JPY 55,093 million, and ordinary profit was JPY 55,203 million.
- Net profit attributable to owners of the parent company amounted to JPY 28,581 million.
- Compared to the prior year period (January 1 to September 30, 2025), operating revenue increased from JPY 112,338 million to JPY 165,978 million (approximately 47.7% increase), and net profit attributable to owners of the parent company increased from JPY 14,357 million to JPY 28,581 million (approximately 99.1% increase).
🤖 AI Perspective
Rakuten Securities’ Q3 FY2026 results indicate significant year-over-year growth in both operating revenue and net profit attributable to owners of the parent company, suggesting sustained robust business expansion. The nearly doubled net profit could reflect improvements in operational efficiency or favorable market conditions. It is important to note that Rakuten Group’s consolidated financial results are reported under IFRS, which may differ from Rakuten Securities’ Japanese GAAP figures.
5819|カナレ電気
1716.0
▼ -0.06%
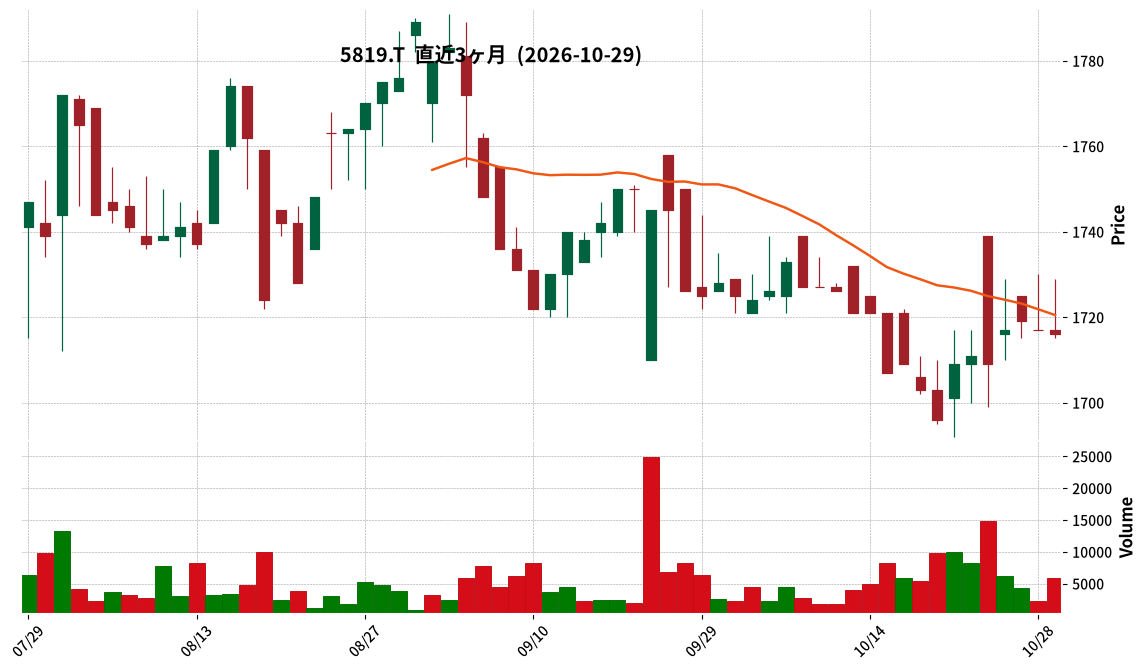
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Canare Electric announced its consolidated financial results for the third quarter of the fiscal year ending December 2026.
- Net sales were ¥9,796 million (0.0% decrease year-on-year), operating profit ¥1,311 million (3.1% decrease), ordinary profit ¥1,375 million (3.1% decrease), and net profit attributable to owners of parent ¥969 million (1.1% decrease).
- Overseas sales increased in regions such as the U.S., South Korea, and Singapore, partly due to foreign exchange translation effects, but domestic sales decreased in the broadcasting market, leading to a slight decline in consolidated net sales compared to the previous year.
- By segment, Japan saw a decrease in both sales and profit, while the U.S., South Korea, and Singapore recorded increases in both. China experienced decreases in both sales and profit. Notably, the U.S. segment achieved sales of ¥1,537 million (19.3% increase year-on-year) and segment profit of ¥238 million (764.5% increase).
- The full-year consolidated earnings forecast remains unchanged from the most recently published figures: net sales ¥13,200 million, operating profit ¥1,480 million, ordinary profit ¥1,630 million, and net profit attributable to owners of parent ¥1,180 million.
🤖 AI Perspective
Canare Electric’s Q3 results show a slight decrease in profit despite consolidated net sales remaining almost flat year-on-year. While a decline in the domestic broadcasting market impacted overall performance, the strong growth in the U.S. market, particularly the significant increase in segment profit, is noteworthy. As the full-year earnings forecast remains unchanged, the future trends in both domestic and international markets are worth monitoring to assess their impact on the company’s performance.
6861|キーエンス
76360.0
▼ -3.57%
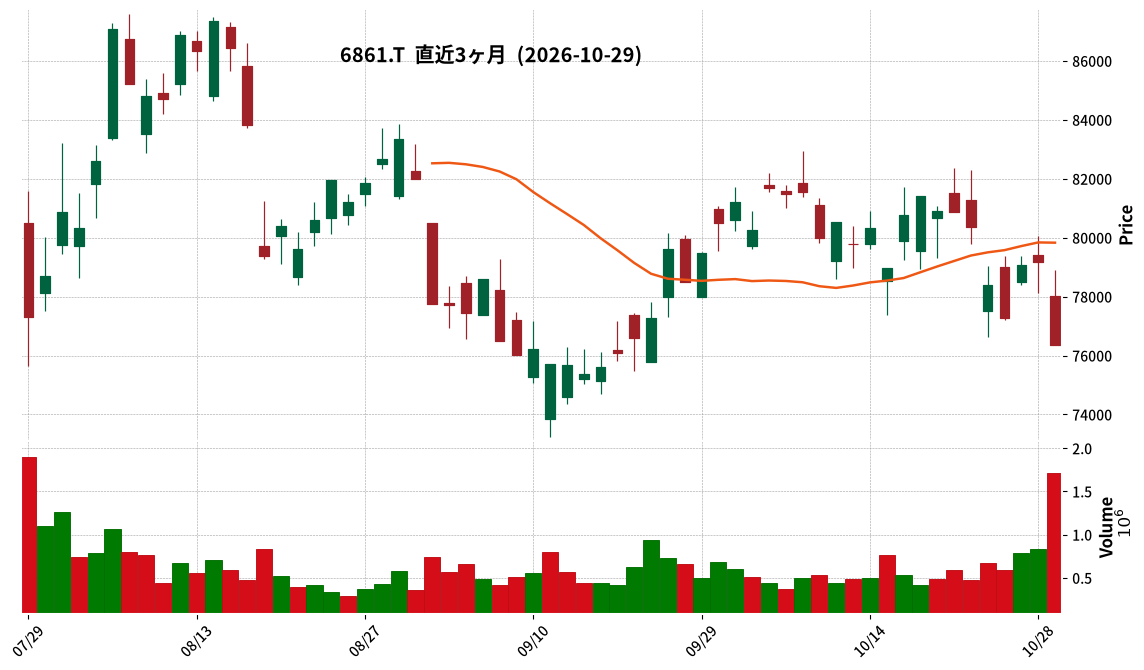
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Keyence Corporation announced its consolidated financial results for the second quarter (interim period) of the fiscal year ending March 2027.
- Interim net sales reached ¥735,399 million, marking a 34.9% increase compared to the same period in the previous fiscal year.
- Operating profit was ¥408,262 million, up 50.0% year-on-year. Ordinary profit increased by 48.9% to ¥424,348 million, and profit attributable to owners of parent grew by 49.4% to ¥298,675 million.
- Interim earnings per share (EPS) stood at ¥1,231.53.
- Total assets amounted to ¥3,955,137 million (up ¥284,482 million from the previous fiscal year-end), and net assets were ¥3,704,958 million (up ¥233,486 million).
- The interim dividend per share is ¥325 (compared to ¥275 in the prior interim period). A 1-for-5 stock split is scheduled for November 21, 2026, with the year-end dividend forecast after the split being ¥65.00 per share.
🤖 AI Perspective
Keyence’s interim results for FY2027 indicate robust growth across key revenue and profit metrics, suggesting a positive impact from continued capital expenditure in the manufacturing sector globally and the company’s strategic initiatives. The strong performance in North, Central, and South America, as well as the Asian market, appears to be a significant driver of overall results. Furthermore, the high equity ratio and increases in total and net assets suggest the company continues to maintain a strong financial position.
Disclaimer: This article is for informational purposes only and does not constitute investment advice.
7775|大研医器
416.0
▼ -0.95%
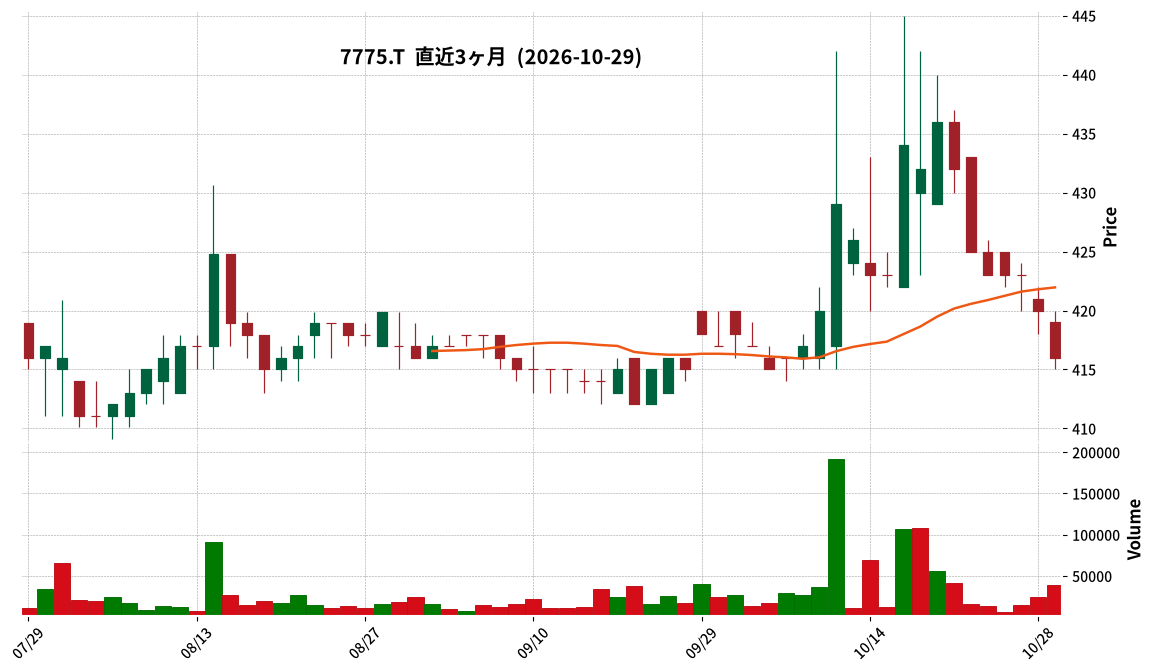
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Daiken Medical Co., Ltd. announced its H1 FY2027 (Interim) Financial Results (Non-consolidated).
- Interim net sales reached ¥5,097 million, marking a 0.8% increase compared to the same period last year.
- Operating profit was ¥478 million, a decrease of 29.3% year-on-year. Ordinary profit was ¥474 million (down 29.7%), and interim net profit was ¥368 million (down 28.0%).
- Diluted interim net profit per share was ¥12.84.
- The forecast for the annual dividend per share remains unchanged at ¥20.00, including a year-end dividend of ¥11.00 (and an interim dividend of ¥9.00 already declared).
- The full-year FY2027 earnings forecast remains unchanged, projecting net sales of ¥10,500 million (up 2.0% YoY), operating profit of ¥840 million (down 34.3% YoY), and net profit of ¥590 million (down 36.1% YoY).
🤖 AI Perspective
While Daiken Medical achieved sales growth in the interim period, driven by strong performance in products like Fit-Fix (suction devices) and Coody-Q Aimi PCA (infusion devices), the decline in operating profit suggests that increased material costs and personnel expenses significantly impacted profitability. The unchanged full-year forecast could indicate the company anticipates an improvement in profitability during the second half of the fiscal year. Investors might focus on the company’s ability to manage cost pressures moving forward and translate sales growth into stronger earnings.
7962|キングジム
761.0
▲ +1.60%
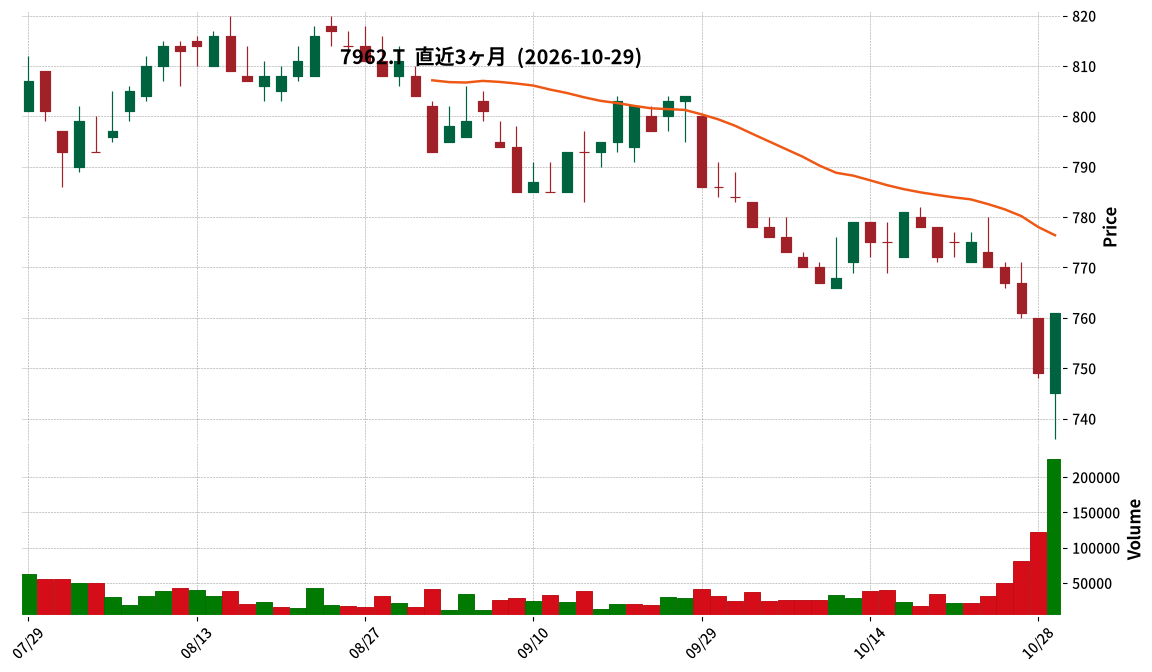
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- King Jim Co., Ltd. announced its consolidated financial results for the first quarter of the fiscal year ending June 2027 (June 21, 2026 – September 20, 2026).
- Net sales reached ¥8,892 million, representing a 7.8% increase compared to the same period of the previous year.
- Operating loss was ¥△38 million (compared to ¥△213 million loss in the prior year period), and ordinary profit was ¥73 million (compared to ¥△135 million loss in the prior year period).
- Net loss attributable to owners of parent was ¥△30 million (compared to ¥△298 million loss in the prior year period).
- By segment, stationery and office supplies business recorded net sales of ¥5,138 million (up 4.4% YoY), and lifestyle products business recorded net sales of ¥3,754 million (up 12.8% YoY).
🤖 AI Perspective
The increase in net sales for this quarter, particularly driven by the strong performance of the lifestyle products business, appears to have contributed to the overall revenue growth. While the gross profit margin declined, the increase in sales coupled with an improvement in selling, general and administrative expenses ratio led to a narrowing of both operating loss and net loss attributable to owners of parent. The shift to ordinary profit from a loss in the prior year period could suggest an improving trend in profitability.
7984|コクヨ
861.5
▼ -0.57%
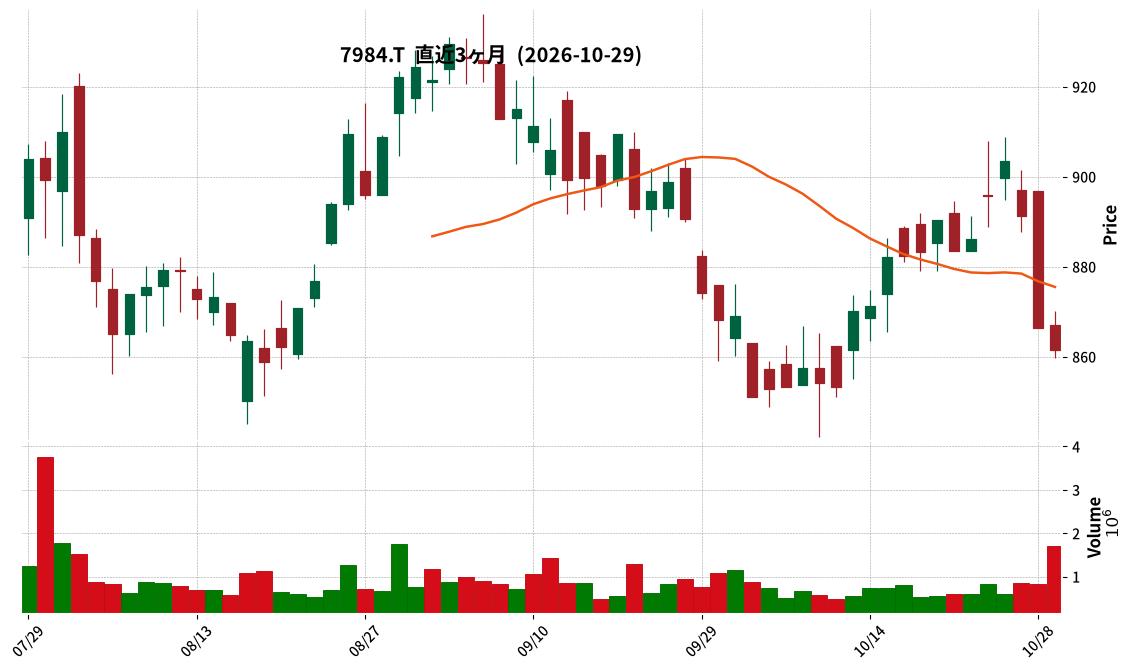
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- For the third quarter (cumulative) of the fiscal year ending December 2026, consolidated net sales were ¥290,174 million, representing a 9.2% increase year-on-year.
- Operating profit reached ¥23,384 million, an 8.8% increase compared to the same period last year.
- Ordinary profit increased by 13.4% year-on-year to ¥24,714 million.
- Net profit attributable to owners of parent was ¥18,068 million, an 8.0% increase from the prior year’s third quarter.
- By segment, the Furniture business reported net sales of ¥143,391 million (an 11.3% increase YoY), and the Stationery business reported net sales of ¥68,075 million (a 9.3% increase YoY).
🤖 AI Perspective
KOKUYO’s latest earnings report indicates a broad-based improvement across key financial metrics, with net sales and all profit figures showing solid year-over-year growth. This performance suggests a robust operational environment for the company. The contributions from the Furniture and Stationery segments are specifically highlighted as drivers of sales growth, making the strategic progress within these areas a point of interest for investors.
8151|東陽テクニカ
1855.0
▼ -2.98%
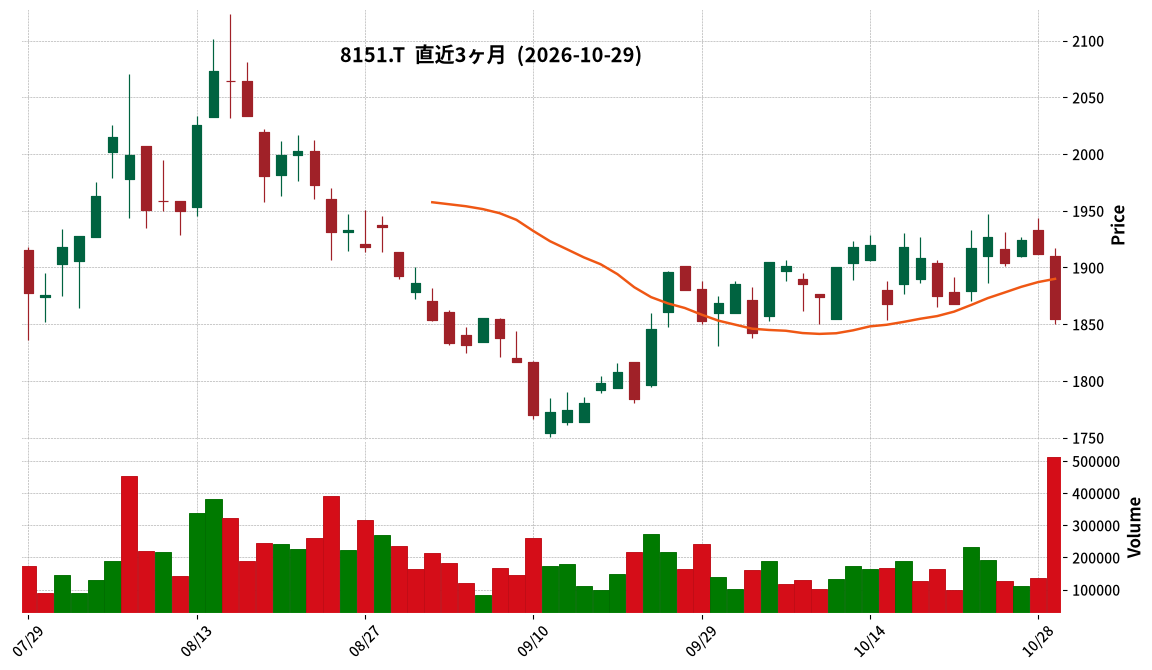
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- TOYO Corporation resolved on October 29, 2026, to acquire all shares of AROKA Inc., making it a wholly-owned subsidiary.
- AROKA Inc. is a specialized manufacturer of radiation measurement devices, with key clients including government agencies, municipalities, medical institutions, and research organizations.
- Upon acquisition, AROKA is expected to become the largest subsidiary by business scale within the TOYO Corporation Group.
- The share transfer is scheduled for November 18, 2026, and AROKA is anticipated to become a consolidated subsidiary of TOYO Corporation during the first quarter of the fiscal year ending September 2027.
- The acquisition price is currently undisclosed at the seller’s request and will be disclosed after the share transfer is executed.
🤖 AI Perspective
TOYO Corporation’s acquisition of AROKA Inc. represents a significant step in realizing its “TY2027” medium-term management plan focused on M&A for growth. This strategic move could diversify TOYO’s business into the radiation measurement sector, addressing anticipated long-term demand in nuclear energy, medical, and defense fields. As AROKA is projected to be the largest subsidiary, its integration and the subsequent impact on TOYO Corporation’s consolidated earnings, which will be reflected in the fiscal year ending September 2027 forecast, are key aspects for investors to monitor.
8894|REVOLUTION
15.0
▲ +0.00%
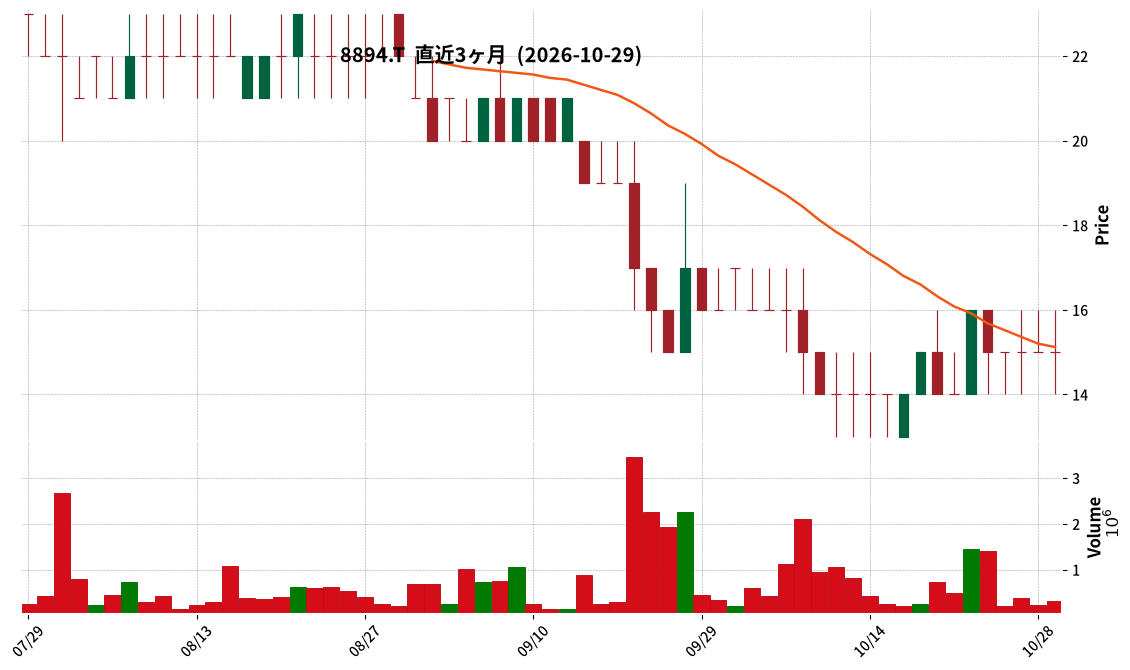
📎 Source:REVOLUTION Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- REVOLUTION Co., Ltd. announced a further postponement of the disclosure of its Q3 FY2026 consolidated financial results.
- The disclosure was originally scheduled for September 14, 2026, and had previously been delayed to October 2026.
- The primary reason for the re-postponement is the ongoing discussions with Audit Firm Aria regarding corrections to past securities reports and other documents.
- Audit Firm Aria indicated that several cases previously classified as “Category 3 Not applicable” in the internal investigation committee’s report for subsidiary YE Co. (Yamakake Estate Co., Ltd.) may in fact be categorized as “buyback transactions.”
- Furthermore, Audit Firm Aria requested further clarification of the actual transaction status of YE Co.’s crowdfunding projects.
🤖 AI Perspective
The re-postponement of REVOLUTION’s Q3 financial results suggests that the company is still facing challenges stemming from internal control deficiencies and the review obligations under the Financial Instruments and Exchange Act. The new points raised by the audit firm highlight the ongoing importance of the company’s efforts to ensure the appropriateness of its accounting treatments. Investors may need to closely monitor future disclosures and the company’s specific responses to these identified issues.
8898|センチュリー21
1133.0
▲ +0.44%
📎 Source:センチュリー21 Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- CENTURY 21 Japan Co., Ltd. has announced its non-consolidated financial results for the second quarter (interim) of the fiscal year ending March 2027.
- Operating revenue for the interim period was ¥2,107 million, marking a 0.8% increase compared to the prior interim period.
- Operating profit reached ¥607 million, a 13.6% increase year-on-year for the interim period.
- Ordinary profit was ¥665 million (up 10.1% YoY), and interim net profit was ¥446 million (up 8.7% YoY).
- Interim net profit per share stood at ¥43.48.
- The equity ratio was reported at 84.6%.
- The full-year dividend forecast remains unchanged, with an interim dividend of ¥25.00 and a year-end dividend of ¥28.00, totaling ¥53.00.
- The full-year earnings forecast for FY2027 also remains unchanged, projecting operating revenue of ¥4,426 million, operating profit of ¥1,136 million, ordinary profit of ¥1,238 million, net profit of ¥830 million, and net profit per share of ¥80.88.
9502|中部電力
2681.5
▲ +1.48%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Chubu Electric Power reported consolidated net sales of ¥1,945,206 million for the second quarter of the fiscal year ending March 2027, an increase of 11.3% compared to the same period of the previous year.
- Operating income recorded a loss of ¥78,054 million, a significant change from the ¥145,544 million profit in the prior interim period.
- Ordinary income decreased by 79.1% year-on-year to ¥41,047 million.
- Net income attributable to owners of parent resulted in a loss of ¥280,459 million, reversing from a ¥166,381 million profit in the previous interim period.
- The full-year consolidated earnings forecast for the fiscal year ending March 2027 was revised, projecting net sales of ¥4,200,000 million (an 18.4% increase year-on-year), ordinary income of ¥110,000 million (a 62.2% decrease), and net income attributable to owners of parent of △¥215,000 million.
- Interim net income per share was △¥371.25, with the year-end dividend forecast remaining at ¥35.00 (total annual dividend of ¥70.00), with no revision from the most recently announced forecast.
🤖 AI Perspective
Chubu Electric Power’s Q2 FY2027 results show a notable divergence, with increased sales contrasted by a significant swing to operating and net losses. This substantial decline in profitability, as evidenced by the nearly 80% decrease in ordinary income, may suggest underlying operational challenges or specific one-off factors impacting the company’s financial performance. The revised full-year forecast, still projecting a net loss, indicates that these pressures are anticipated to persist, making future management actions and market conditions key areas for investors to monitor.
9558|G-ジャパニアス
2020.0
▲ +0.60%
📎 Source:G-ジャパニアス Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- G-Japanus announced the acquisition of shares in dotsline Co., Ltd. (change of specified subsidiary) and its subsequent full acquisition through a simplified share exchange.
- The initial share acquisition is scheduled for October 30, 2026, involving 9,312 out of 9,900 issued shares of dotsline for ¥2.5 billion, making dotsline a specified subsidiary of G-Japanus.
- Subsequently, effective November 26, 2026, the remaining 588 shares will be acquired via a share exchange, making dotsline a wholly-owned subsidiary.
- The share exchange ratio is 136.40 shares of G-Japanus common stock for every one share of dotsline common stock, with an estimated 80,203 treasury shares of G-Japanus to be delivered.
- This transaction aligns with G-Japanus’s long-term vision of “employment and creation of digital talent in the advanced engineering business.”
🤖 AI Perspective
This acquisition appears to be a strategic move aligning with G-Japanus’s mid-term management plan to achieve 10,000 digital talents and pursue growth through M&A. Integrating dotsline, a company specializing in data infrastructure construction, could enhance G-Japanus’s capabilities by leveraging its own engineers and expanding its service offerings to its client base, particularly listed companies. The use of a simplified share exchange may also indicate a focus on efficient transaction execution.
6111|旭精機
—
▲ +0.00%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- ASAHI SEIKI’s Q2 FY2027 (interim) results show net sales of JPY 5,596 million, an increase of 11.7% compared to the prior interim period.
- The company reported an operating loss of JPY 149 million (compared to JPY 53 million loss in the prior interim period), an ordinary loss of JPY 138 million (compared to JPY 9 million loss), and a net loss of JPY 98 million (compared to JPY 693 million net income).
- Sales in the Precision Processing Division increased by 53.3% year-on-year to JPY 4,678 million, driven by next-generation automotive parts (xEV parts) and small-caliber ammunition.
- Sales in the Machine Division decreased by 53.1% year-on-year to JPY 917 million, with declines in press machines, spring machines, and automatic/dedicated machines.
- The full-year FY2027 earnings forecast has been revised, anticipating net sales of JPY 14,000 million (up 4.5% YoY), operating profit of JPY 1 million (down 99.2% YoY), ordinary profit of JPY 10 million (down 94.4% YoY), and net income of JPY 20 million (down 97.5% YoY).
🤖 AI Perspective
The interim period results suggest that the launch costs for next-generation automotive parts in the precision metal processing business, along with decreased sales in the machine business, primarily impacted profitability. While revenue increased, the significant increase in expenses related to business restructuring appears to be a key factor. Investors may focus on the company’s strategies to improve profitability moving forward, especially in light of the revised full-year forecast.
2989|R-東海道リート
85200.0
▼ -2.07%
📎 Source:R-東海道リート Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- R-Tokaido Reit announced corrections to errors in portions of its “REIT Financial Results Briefing” for the July 2025 term (published September 16, 2025), the January 2026 term (published March 16, 2026), and the July 2026 term (published September 17, 2026).
- The reason for the correction was the discovery of numerical errors in past financial results reports during a re-verification of figures for the July 2026 term securities report.
- The errors occurred during the transcription of DCF method prices from appraisal reports into the financial results reports.
- The corrected figures relate to “DCF method price (million yen)”, “Subtotal”, and “Total/Average” within “3. Reference Information (1) Information on Prices of Managed Assets (3) Summary of Real Estate Appraisal Reports” in each financial results brief.
- The company states that these corrections have no impact on the performance of previous fiscal years.
5029|G-サークレイス
2013.0
▲ +0.00%
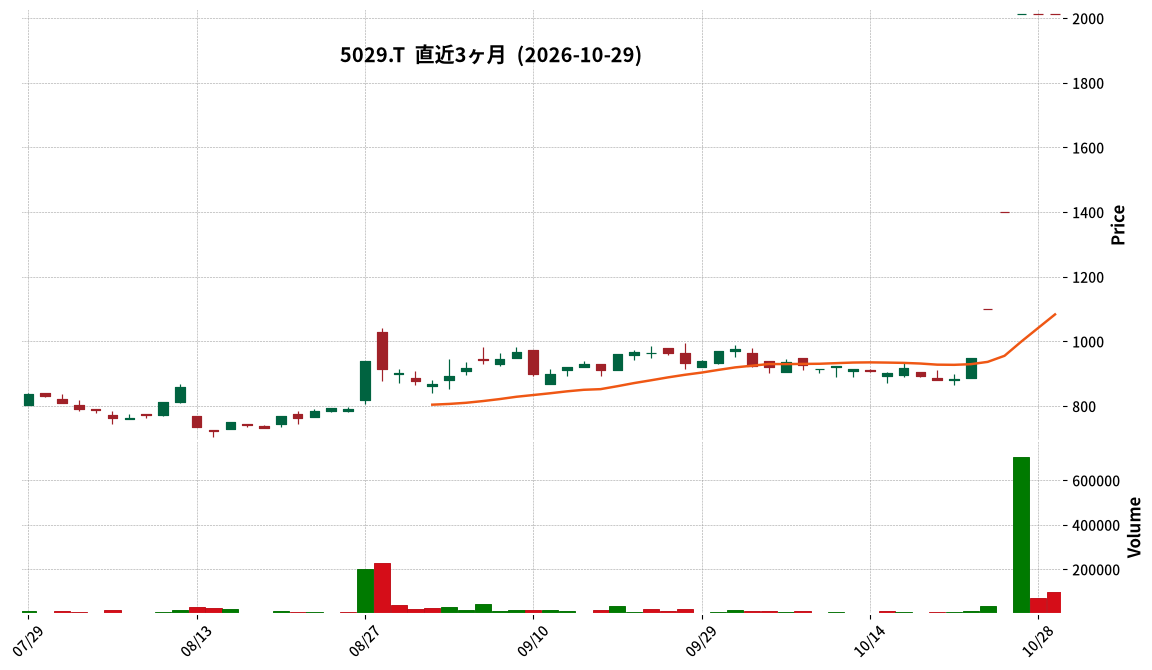
📎 Source:G-サークレイス Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- G-Circleace has decided to acquire shares of arcbricks Inc. by exercising stock acquisition rights attached to its 1st unsecured convertible bond-type bonds with stock acquisition rights.
- Through this share acquisition, arcbricks Inc. is scheduled to become a consolidated subsidiary of G-Circleace as of October 30, 2026.
- The number of shares acquired is 1,000, resulting in a post-acquisition voting rights ownership ratio of 89.20%. The acquisition price is 50 million yen, equivalent to the convertible bond conversion price.
- arcbricks Inc. reported an operating loss of 78,770 thousand yen and was in an insolvency state (net assets △74,365 thousand yen) in its most recent fiscal year (March 2026).
- G-Circleace has determined that the impact of arcbricks’s performance and financial condition due to this subsidiary acquisition on the G-Circleace Group’s medium-to-long-term financial soundness will be limited.
🤖 AI Perspective
G-Circleace’s decision to make arcbricks Inc. a consolidated subsidiary by converting convertible bonds into shares appears to be a strategic move aimed at ensuring the recovery of invested capital and maximizing the capital efficiency of the group. While arcbricks’s current operating losses and insolvency are noteworthy, G-Circleace has assessed the impact on its overall financial health as limited, suggesting an expectation for future business synergies and corporate value enhancement.
7148|FPG
1597.0
▼ -0.99%
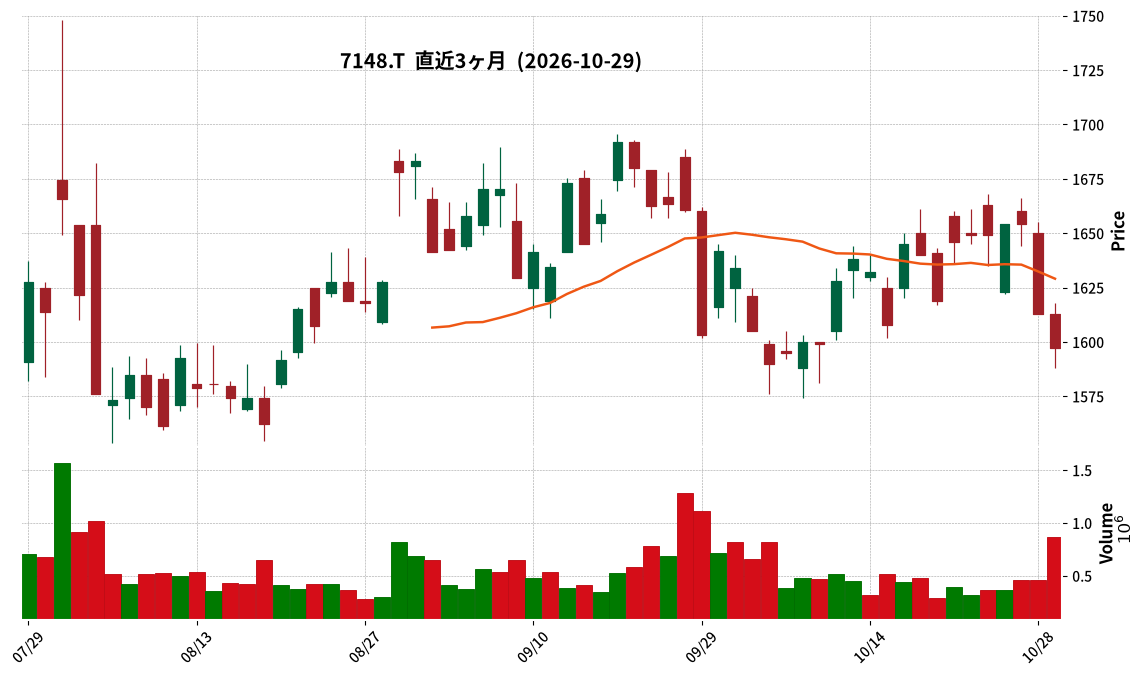
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- FPG’s consolidated revenue for the fiscal year ended September 2026 was ¥81,810 million, a 37.0% decrease year-on-year.
- Consolidated operating profit was ¥24,735 million (down 2.7% YoY), and ordinary profit was ¥24,735 million (down 6.6% YoY).
- Net income attributable to parent company shareholders was ¥16,957 million, a decrease of 6.6% from the previous fiscal year.
- Basic earnings per share for FY2026/9 stood at ¥202.51.
- For the fiscal year ending September 2027, the company forecasts consolidated revenue of ¥67,343 million (down 17.7% YoY) and net income attributable to parent company shareholders of ¥15,005 million (down 11.5% YoY).
- The annual dividend per share was ¥101.25 for FY2026/9 (compared to ¥130.40 for the prior year) and is projected to be ¥89.60 for FY2027/9.
🤖 AI Perspective
FPG’s FY2026/9 results show a significant decline in revenue, yet the decreases in operating profit and net income attributable to parent shareholders were less pronounced. This suggests a relatively stable gross profit margin and potentially strong performance in the lease fund business. The outlook for FY2027/9 projects further decreases in both revenue and profit, indicating that shifts in segment contributions and the impact of tax reforms could be key factors influencing future performance.
7185|ヒロセ通商
3645.0
▲ +0.69%
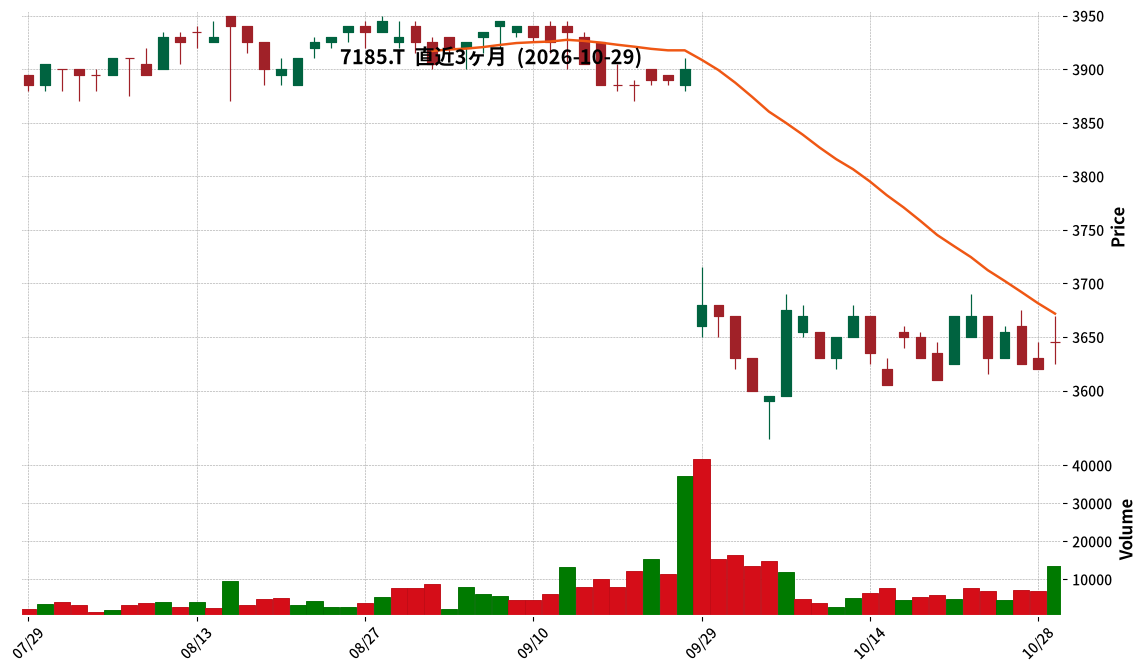
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Hirose Tusyo, Inc. announced its consolidated financial results for the second quarter (interim period) of the fiscal year ending March 2027 (period: April 1, 2026 – September 30, 2026).
- Consolidated operating revenue for the interim period was JPY 7,294 million, a 55.6% increase compared to the previous interim period, and net operating revenue was JPY 7,230 million, up 55.3% YoY.
- Operating income increased by 151.1% to JPY 2,782 million, ordinary income by 147.3% to JPY 2,782 million, and net income attributable to owners of parent surged by 162.1% to JPY 1,805 million.
- Diluted earnings per share for the interim period were JPY 292.07, and diluted earnings per share (adjusted for potential shares) were JPY 291.40.
- Customer accounts stood at 478,175 at the end of the period, a 6.1% increase from the previous consolidated fiscal year-end, and foreign exchange customer deposits amounted to JPY 97,770,940 thousand, up 10.7%.
- The company does not provide consolidated earnings forecasts due to the difficulty in predicting performance influenced by foreign exchange rate fluctuations and market conditions.
🤖 AI Perspective
Hirose Tusyo’s Q2 FY2027 results show substantial year-over-year growth across key revenue and profit metrics, suggesting robust operational performance. The increase in customer accounts and foreign exchange customer deposits, despite a decrease in foreign exchange trading volume, may indicate the success of new service offerings and promotional campaigns, or potentially improved revenue generation per transaction. The company’s ability to achieve significant profit growth in the face of decreased trading volume suggests a positive shift in its business model or a greater contribution from other revenue streams, such as CFD trading.
8163|SRSHD
1746.0
▲ +4.61%
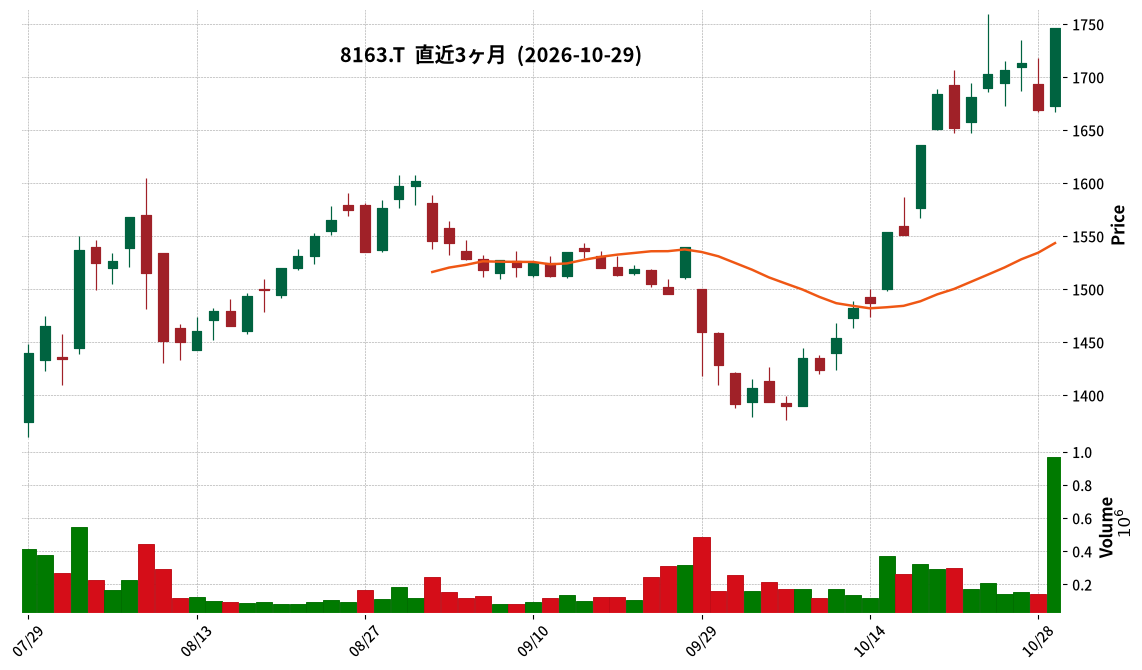
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- SRS Holdings Co., Ltd. announced a change in the acquisition price for shares of Kyotaru Co., Ltd.
- The acquisition price for Kyotaru’s common shares was revised from JPY 3,745 million to JPY 3,693 million.
- Advisory fees (estimated) increased from JPY 45 million to JPY 49 million.
- The total estimated acquisition price decreased from JPY 3,790 million to JPY 3,742 million.
- This change is based on the price adjustment procedures stipulated in the share transfer agreement.
- The impact of this price change and the acquisition of Kyotaru shares on SRS Holdings’ consolidated financial results for the fiscal year ending March 2027 is currently under review, and any revisions to earnings forecasts will be promptly disclosed.
🤖 AI Perspective
The revision of the acquisition price for Kyotaru shares by SRS Holdings, resulting in a total reduction of JPY 48 million, is a notable point. This adjustment is stated to be based on the price adjustment procedures within the share transfer agreement, which can be a standard part of M&A transactions. Investors may wish to monitor the forthcoming disclosure regarding the specific impact on the consolidated financial results for the fiscal year ending March 2027.
4380|G-Mマート
657.0
▲ +0.00%
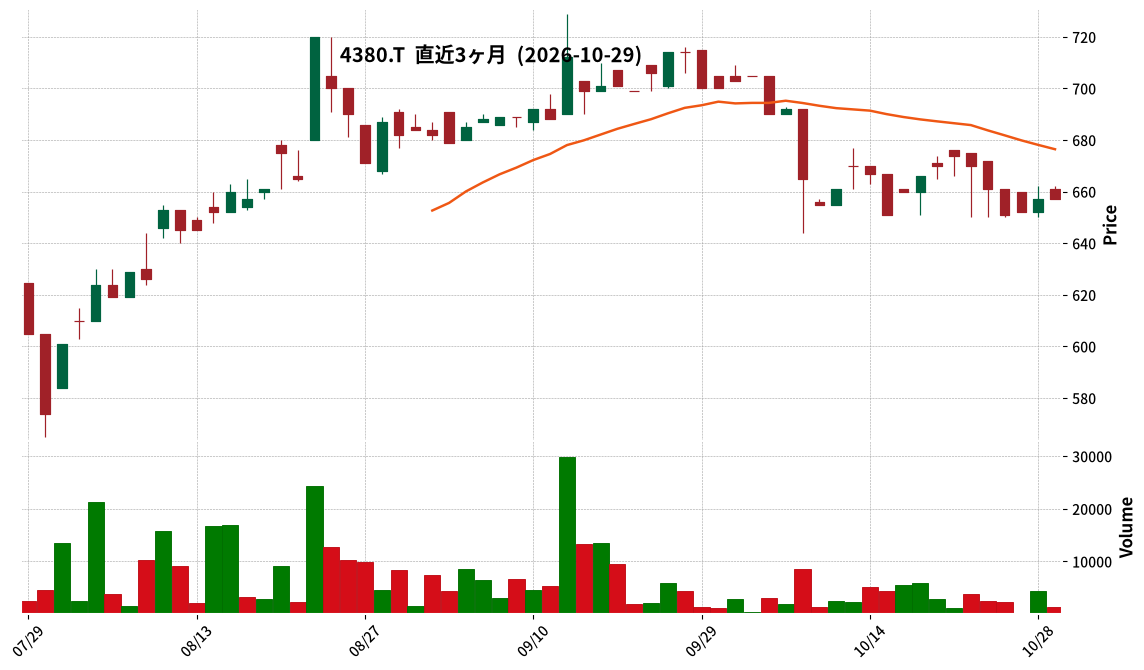
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- G-MART Co., Ltd. announced its financial results for the first half of the 27th fiscal year (Q2 FY2027, ending January 2027).
- For the first half of FY2027 (cumulative up to Q2), net sales were ¥752 million (up 11.7% year-on-year), operating profit was ¥370 million (up 21.8% year-on-year), and interim net profit was ¥252 million (up 28.9% year-on-year), marking record highs for both sales and profits.
- EPS (earnings per share) was ¥25.78, an increase of ¥5.77 per share compared to the same period last year.
- The full-year forecast for FY2027 (ending January 2027) remains unchanged from the announcement on March 17, 2026, with projected net sales of ¥1,473 million (up 8.4% from previous year), operating profit of ¥689 million (up 9.0% from previous year), and net profit of ¥456 million (up 7.8% from previous year).
- The number of buyer members reached approximately 245,000 companies, continuing to increase at a pace of about 1,000 companies per month.
🤖 AI Perspective
G-MART’s first-half results indicate robust growth, with both sales and profits reaching new highs. The high profitability, reflected in an operating profit margin of 49.3% and an interim net profit margin of 33.5%, suggests that the company’s “asset-light” business model and “prepayment system” continue to be effective. The sustained increase in buyer members may also contribute to further market expansion in the future.
💡 Start investing with IR insights


※ 本ページには広告が含まれます(PR)
Disclaimer: This article is for informational purposes only and does not constitute investment advice. All investment decisions are at your own risk.
コメント