📌 Today’s Highlights
Today we cover 103 IR announcements. Notable among them: G-トグルHD (652A), 塩野義薬 (4507), G-J・TEC (7774). Use the table of contents below to navigate to each company.
- 652A|G-トグルHD
- 6768|タムラ製
- 4507|塩野義薬
- 7774|G-J・TEC
- 4679|田谷
- 5386|鶴弥
- 3190|ホットマン
- 6230|SANEI
- 6897|ツインバード
- 8616|東海東京
- 9040|大宝運
- 1878|大東建
- 4709|IDホールディングス
- 5482|愛知鋼
- 5929|三和HD
- 7434|オータケ
- 9687|KSK
- 2768|双日
- 3776|BBタワー
- 8285|三谷産業
- 1942|関電工
- 3153|八洲電機
- 4410|ハリマ化成G
- 4568|第一三共
- 5257|ノバシステム
- 5440|共英製鋼
- 5491|日本金属
- 6325|タカキタ
- 6356|日ギア
- 6445|ジャノメ
- 7381|CCIグループ
- 7988|ニフコ
- 8133|エネクス
- 9830|トラスコ中山
- 2216|カンロ
- 4203|住友ベーク
- 4578|大塚HD
- 5410|合同鉄
- 5464|モリ工業
- 7741|HOYA
- 1850|南海辰村建設
- 1972|三晃金
- 2883|大冷
- 4045|東亜合
- 4220|リケンテクノス
- 6888|アクモス
- 7218|田中精密
- 8076|カノークス
- 5994|ファインシンター
- 2908|フジッコ
- 7475|アルビス
- 1941|中電工
- 4015|G-ペイクラウドHD
- 4463|日華化学
- 4531|有機薬
- 4968|荒川化学
- 6262|PEGASUS
- 6488|ヨシタケ
- 6557|G-AIAI
- 7947|エフピコ
- 8119|三栄コーポ
- 8803|平和不
- 9539|京葉瓦斯
- 5333|NGK
- 6586|マキタ
- 7177|GMOFHD
- 1381|アクシーズ
- 2218|日糧パン
- 2479|ジェイテック
- 2481|タウンニュース
- 2492|インフォマート
- 2689|オルバDVx
- 2700|木徳神糧
- 2926|篠崎屋
- 2929|ファーマフーズ
- 3439|三ツ知
- 3542|G-VEGA
- 3675|クロスマーケティング
- 3762|テクマト
- 3836|アバントグループ
- 4308|G-Jストリーム
- 6632|JVCKW
- 6920|レーザーテック
- 2428|ウェルネット
- 2445|タカミヤ
- 3760|ケイブ
- 3835|eBASE
- 4069|G-BlueMeme
- 4216|旭有機材
- 6472|NTN
- 8052|椿本興
- 8783|abc
- 9362|兵機海運
- 9679|ホウライ
- 4685|菱友システム
- 1939|四電工
- 4193|ファブリカHD
- 6863|ニレコ
- 7897|ホクシン
- 3657|ポールHD
- 3647|アスリナ
- 244A|G-グロースエクスパ
- 6946|日アビオ
652A|G-トグルHD
—
▲ +0.00%
📎 Source:G-トグルHD Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- G-Toggle HD was listed on the Tokyo Stock Exchange Growth market on October 30, 2026.
- The consolidated earnings forecast for the fiscal year ending September 2027 projects net sales of ¥43,034 million (up 68.4% year-on-year), operating profit of ¥6,280 million (up 124.4% year-on-year), and net profit attributable to parent company shareholders of ¥4,005 million (up 139.2% year-on-year).
- The consolidated earnings forecast for the fiscal year ending September 2026 projects net sales of ¥25,560 million (up 106.9% year-on-year), operating profit of ¥2,798 million (up 146.1% year-on-year), and net profit attributable to parent company shareholders of ¥1,674 million (up 196.8% year-on-year).
- The earnings forecasts include both “Land Creation” and “Agentic Platform” businesses, with Land Creation accounting for the majority of net sales.
- The earnings forecasts for the fiscal years ending September 2026 and September 2027 do not include the impact of M&A deals not yet consolidated as of the date of this announcement.
🤖 AI Perspective
G-Toggle HD’s listing on the TSE Growth market is accompanied by robust earnings forecasts, indicating significant growth in both revenue and profit for the upcoming fiscal years. The strong performance appears to be driven by its Land Creation business, with a substantial projected increase in operating profit for FY2027. The company’s note on M&A not being factored into these forecasts could suggest additional growth potential in the future, making it a point of interest for investors.
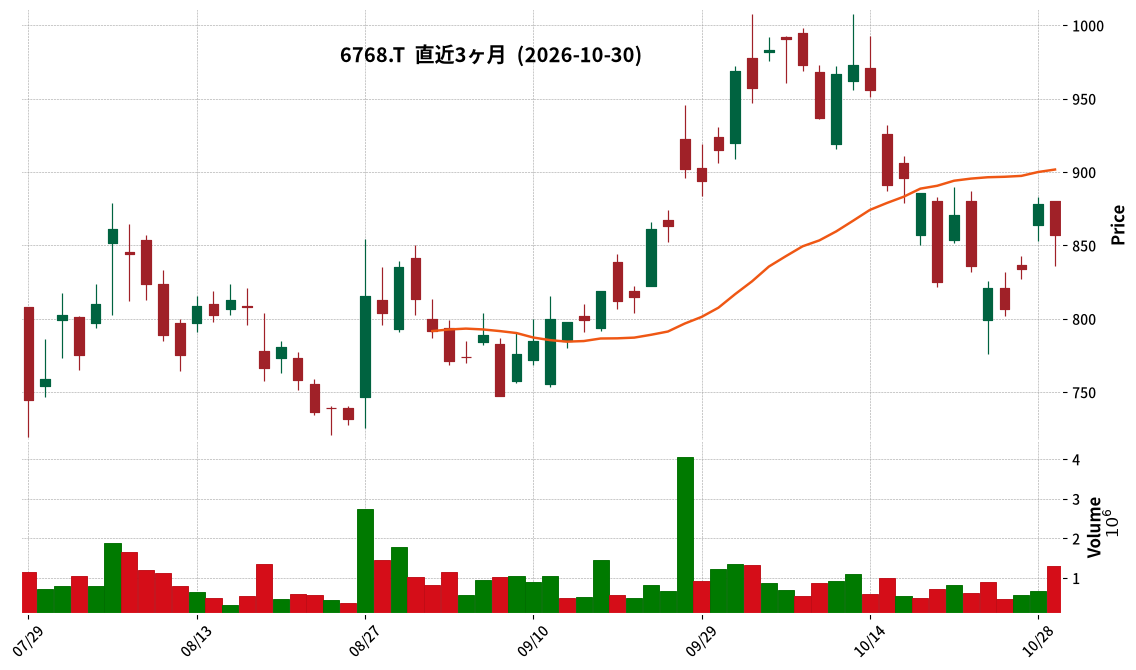
6768|タムラ製
857.0
▼ -2.39%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Tamura Corporation announced the completion of its acquisition of 80% of shares in EMG Power Electric S.r.l. (hereinafter “EMG”) on October 29, 2026 (Italy time), through its consolidated subsidiary TAMURA-EUROPE LIMITED.
- EMG has officially become a consolidated subsidiary of Tamura Corporation as a result of this acquisition.
- Mr. Marco Puliti has been appointed as CEO of EMG, while co-founder Mr. Filippo Galastri will continue to be involved in business operations as Managing Director.
- Tamura Corporation positions EMG as a core base for Medium Voltage (MV) dry-type transformer technology, aiming to strengthen competitiveness and expand its technological base in the high-value-added MV segment of the large transformer and reactor business.
- EMG’s profits and losses are expected to be included in Tamura Corporation’s consolidated financial results starting from the fourth quarter of the fiscal year ending March 2027.
🤖 AI Perspective
This acquisition marks a strategic move for Tamura Corporation to enhance its capabilities in MV dry-type transformer technology, which is critical for next-generation energy solutions. The integration of EMG’s expertise in sectors such as renewable energy and battery energy storage systems could significantly bolster Tamura’s position in the evolving energy market. Investors may want to monitor the impact of this consolidation on Tamura’s financial results, particularly from the fourth quarter of the fiscal year ending March 2027, as it begins to contribute to the company’s consolidated performance.
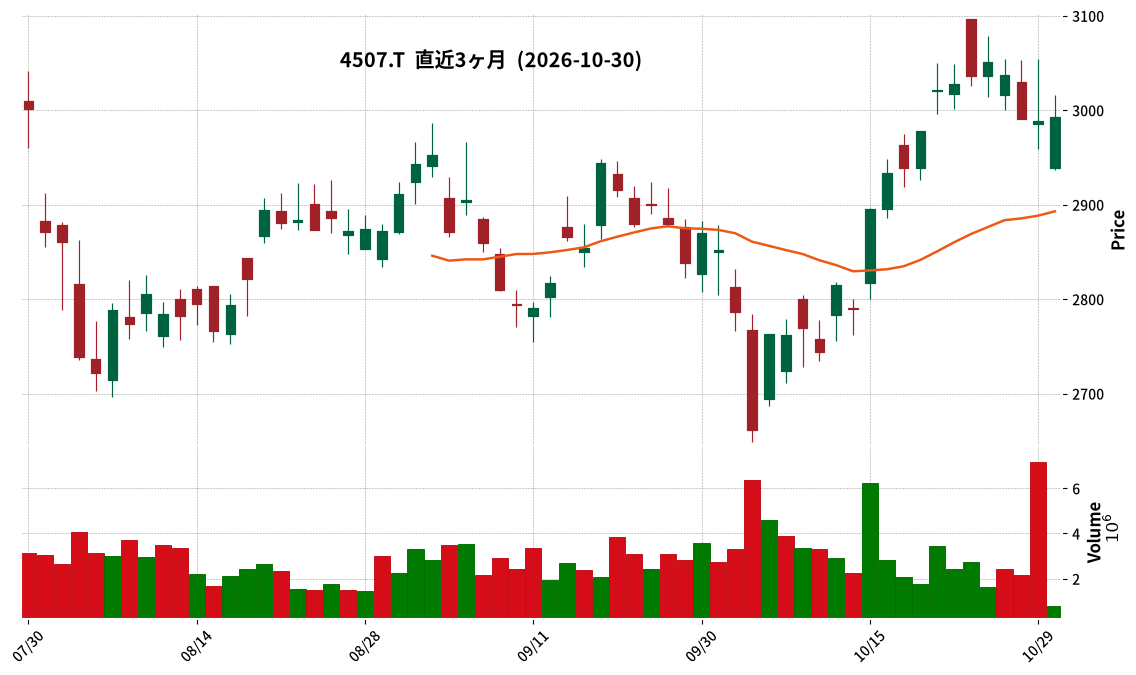
4507|塩野義薬
2993.0
▲ +0.13%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Shionogi & Co. announced on October 30, 2026, a partial correction to its “Notice of Revision to Financial Forecasts and Annual Dividend Forecast (Increased Dividend) for the Fiscal Year Ending March 31, 2027.”
- The correction was made due to a discrepancy identified between the previously announced forecast and the “Consolidated Financial Results for the Second Quarter of the Fiscal Year Ending March 31, 2027 [IFRS]” released on October 29, 2026.
- The specific change concerns the “Basic earnings per share (yen)” in the consolidated full-year earnings forecast for the fiscal year ending March 31, 2027, which was revised from ¥249.72 to ¥249.67.
- There are no changes to the revised forecasts for Revenue, Operating Profit, Profit before Tax, and Profit attributable to owners of the parent.
- The company stated that this correction is an error in disclosure and has no impact on its financial statements or consolidated financial statements.
🤖 AI Perspective
This correction primarily addresses a numerical discrepancy in a previously released earnings forecast, with no stated impact on the core financial statements. For investors, while the change in basic earnings per share is minor, it highlights the importance of precise reporting in corporate disclosures. Such revisions, even if minor, may warrant close attention to ensure full transparency and accuracy in information provided to the market. Monitoring how the company communicates future updates could be relevant for maintaining investor confidence.
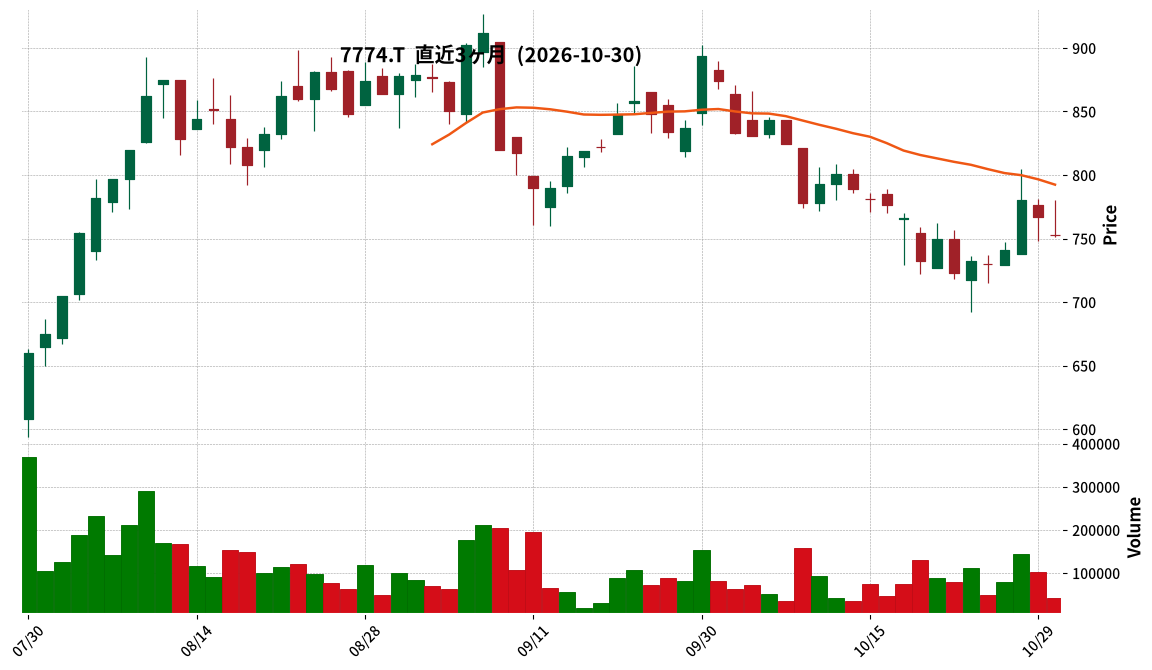
7774|G-J・TEC
753.0
▼ -1.83%
📎 Source:G-J・TEC Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- For the second quarter of the fiscal year ending March 2027, revenue reached ¥1,499 million, representing a 50.1% increase compared to the prior interim period.
- Operating income turned positive at ¥0 million, a significant improvement from an operating loss of ¥376 million in the previous interim period. Ordinary income was ¥7 million, and interim net income was ¥4 million.
- Interim net income per share was ¥0.10.
- Sales for the Regenerative Medicine Products business were ¥1,144,118 thousand (up 80.6% YoY), the Regenerative Medicine Contract Manufacturing business recorded ¥215,721 thousand (down 5.1% YoY), and the Labsite business generated ¥139,184 thousand (up 1.0% YoY).
- Regarding new pipelines, the allogeneic cultured epidermis (development name: Allo-JaCE03) had its manufacturing and marketing approval application submitted in March 2026, with progress towards approval within the fiscal year ending March 2027. Physician-initiated clinical trials for the autologous CAR-T cell product started at Nagoya University, progressing towards completion of Phase I and transition to Phase II within the fiscal year ending March 2027.
🤖 AI Perspective
G-J.TEC’s interim financial results for FY2027 show a substantial revenue increase and a return to operating profitability, which may signal a positive turn in the company’s financial performance. The significant growth in the Regenerative Medicine Products business appears to be a key driver for these results, suggesting effective market penetration or expanded adoption of its products. Furthermore, the reported progress in the development of new pipelines, such as allogeneic cultured epidermis and CAR-T cell products, could indicate potential for future revenue streams and long-term growth for the company.
4679|田谷
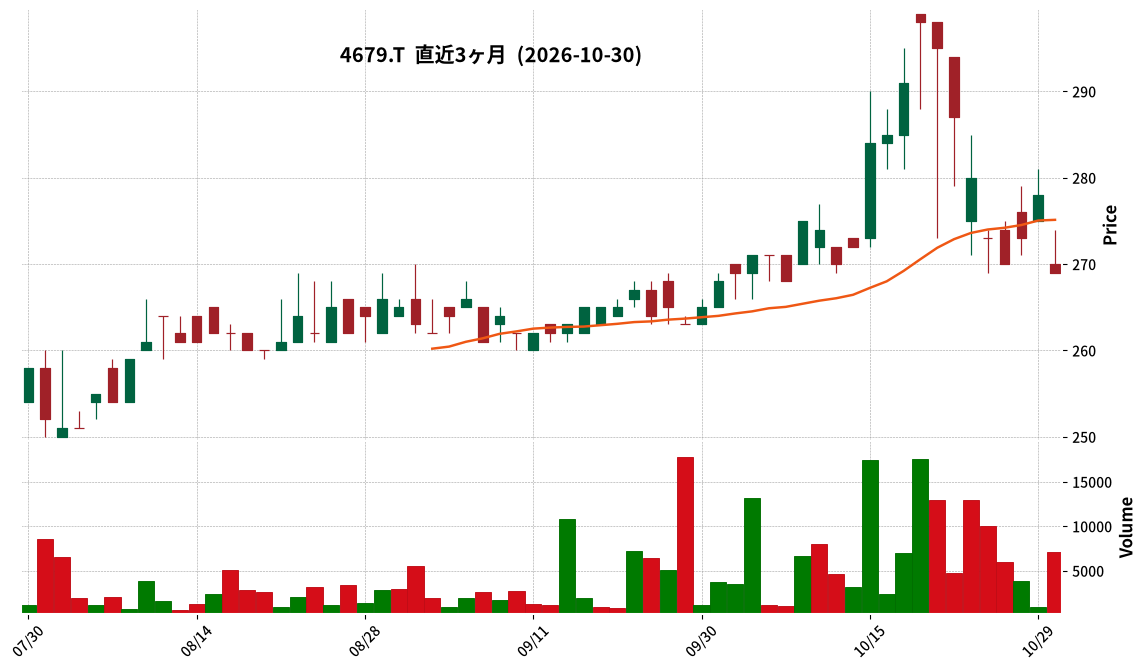
269.0
▼ -3.24%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- TAYA Co., Ltd. announced its unaudited financial results for the second quarter of the fiscal year ending March 2027.
- Net sales for the interim period were JPY 2,476 million, a decrease of 2.7% compared to the same period of the previous year.
- The company reported an operating loss of JPY 106 million (vs JPY 27 million loss in the prior year interim period) and an ordinary loss of JPY 99 million (vs JPY 25 million loss in the prior year interim period).
- Net loss for the interim period widened to JPY 105 million, compared to a net loss of JPY 53 million in the prior year interim period.
- The equity ratio decreased from 36.0% at the end of the previous fiscal year to 32.3% at the end of the interim period.
- The full-year forecast for FY2027 (Net Sales JPY 5,200 million, Net Profit JPY 10 million) remains unchanged from the most recently announced figures.
- As of the end of the interim accounting period, the total number of stores was 65, reflecting 2 new openings, 4 renovations, 3 closures, and 5 business acquisitions.
🤖 AI Perspective
While the interim period showed decreased sales and widened losses, the unchanged full-year forecast may suggest management anticipates an improvement in the second half of the fiscal year. The strategic adjustments in store operations, including new openings and business acquisitions, indicate ongoing efforts to optimize the business model. Investors may want to monitor whether these initiatives translate into the expected recovery as outlined in the full-year guidance.
5386|鶴弥
—
▲ +0.00%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Tsuruya Co., Ltd. announced its non-consolidated financial results for the second quarter (interim period: April 1, 2026 – September 30, 2026) of the fiscal year ending March 2027.
- For the interim period, sales reached JPY 3,826 million (up 18.0% year-on-year), operating profit JPY 242 million (up 247.8% year-on-year), and ordinary profit JPY 310 million (up 94.6% year-on-year). However, interim net profit was JPY 207 million (down 24.7% year-on-year).
- The decrease in interim net profit is primarily attributed to the reversal effect of JPY 233 million in extraordinary profit from the sale of fixed assets recorded in the same period of the previous year.
- The full-year performance forecast for the fiscal year ending March 2027 (sales JPY 7,370 million, operating profit JPY 230 million, ordinary profit JPY 360 million, net profit JPY 240 million) remains unchanged from the most recently announced figures.
- The interim dividend forecast for the current period is JPY 2.50 for the year-end, totaling JPY 11.00 annually. For the previous year, the interim dividend was JPY 4.00, year-end dividend JPY 10.50, totaling JPY 14.50 annually.
🤖 AI Perspective
The significant increase in sales and operating profit during the interim period is reported to be driven by a rebound from construction code revisions and rush demand ahead of product price revisions. However, the decrease in interim net profit appears to be influenced by the extraordinary gains recorded in the prior year’s period. As the full-year forecast remains unchanged, investors may focus on the business environment in the second half, particularly the potential反動減 from price revisions, persistent high energy costs, and any future impacts from the Kinuura Plant fire (currently deemed minor, but potential future asset utilization effects are not yet incorporated into the forecast).
3190|ホットマン
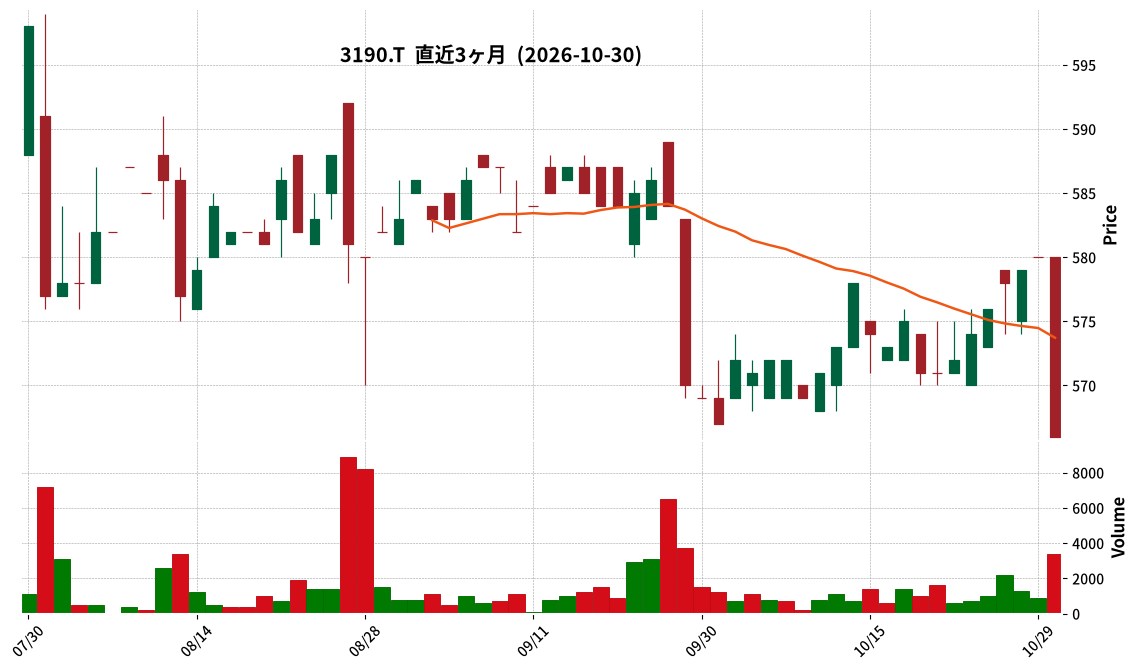
566.0
▼ -2.41%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Hotman Co., Ltd. announced its unaudited Non-consolidated Financial Results for the Second Quarter of the Fiscal Year Ending March 2027 on October 30, 2026.
- Net sales for the interim period reached ¥9,949 million, representing a 3.9% increase compared to the previous interim period.
- Operating loss narrowed to ¥(62) million (from ¥(201) million in the prior year interim period), and ordinary loss improved to ¥(36) million (from ¥(173) million).
- Net loss attributable to owners of parent for the interim period was ¥(48) million, a reduction from ¥(143) million in the previous interim period.
- The Yellow Hat segment reported sales of ¥7,495 million (up 4.2% YoY) and a segment profit of ¥55 million (compared to a segment loss of ¥34 million in the prior year).
🤖 AI Perspective
Hotman’s Q2 FY2027 results show an increase in net sales and a reduction in losses, with the strong performance of its core Yellow Hat segment appearing to be a key driver for overall operational improvement. This indicates a positive shift in profitability despite persistent cost pressures mentioned in the report. Investors may monitor whether this momentum can be sustained into the second half of the fiscal year to meet full-year forecasts.
6230|SANEI
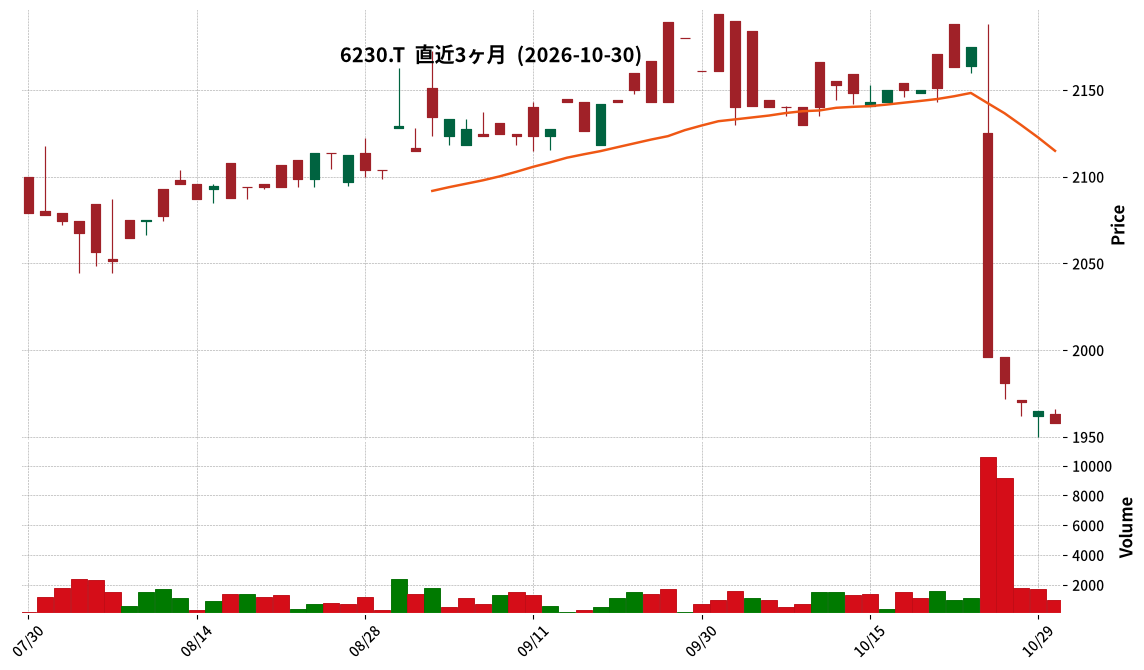
1958.0
▼ -0.36%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- SANEI has revised its consolidated full-year earnings forecast for the fiscal year ending March 2027. Sales are revised from ¥30,800 million to ¥29,500 million (down 4.2%), operating profit from ¥2,000 million to ¥1,100 million (down 45.0%), ordinary profit from ¥1,950 million to ¥1,000 million (down 48.7%), and net profit attributable to parent company shareholders from ¥1,280 million to ¥650 million (down 49.2%).
- The reasons for the earnings forecast revision include sluggish demand due to a downturn in the housing market and a continued surge in copper prices, a key raw material.
- For the first half of fiscal year 2027, consolidated net sales were ¥14,441 million (up 2.9% year-on-year), operating profit was ¥333 million (down 50.1% year-on-year), ordinary profit was ¥283 million (down 59.2% year-on-year), and net profit attributable to parent company shareholders was ¥175 million (down 60.3% year-on-year).
- The company announced that it adopts a progressive dividend policy and expects an annual dividend of ¥75 per share for the fiscal year ending March 2027, consistent with the previous forecast.
- Sales increased due to the expansion of high-value-added products such as the “IENI” series and “automatic faucets,” but profits decreased due to soaring raw material prices.
🤖 AI Perspective
SANEI’s ability to achieve increased sales through high-value-added products, despite external headwinds, suggests a degree of product strength. However, the downward revision of full-year earnings highlights the significant impact of the declining housing market and raw material price inflation on profitability. The company’s commitment to maintaining its progressive dividend policy, even amidst a profit revision, may indicate management’s confidence in long-term value creation or its dedication to shareholder returns. Investors might monitor the effectiveness of pricing adjustments and the expansion into non-residential markets as key factors for future performance improvement.
6897|ツインバード
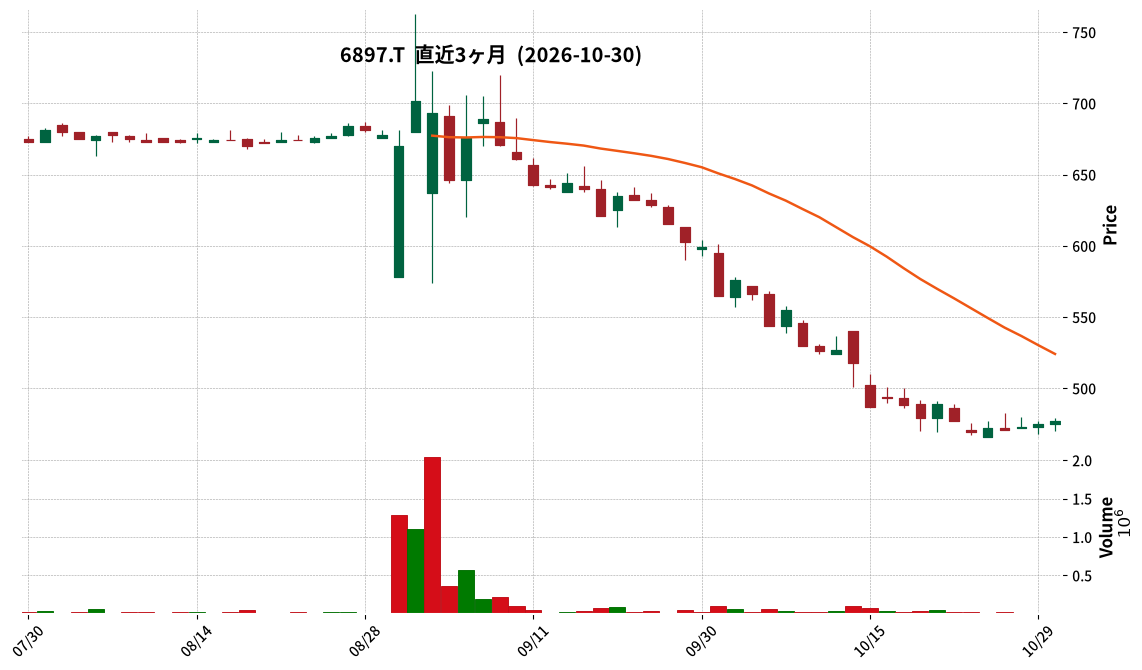
477.0
▲ +0.42%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Twinbird Corporation held its Q2 FY2027 Financial Results Briefing and New Mid-Term Management Plan 2026-2030 Briefing on October 30, 2026.
- For Q2 FY2027 (interim), sales revenue reached ¥4.67 billion, marking a 10.1% increase year-on-year.
- Operating profit for the same period was ¥0.11 billion (an improvement of ¥0.51 billion YoY), ordinary profit was ¥0.10 billion (an improvement of ¥0.53 billion YoY), and interim net profit was ¥0.03 billion (an improvement of ¥0.46 billion YoY), returning to profitability for the first time in 5 years.
- The equity ratio improved to 69.6%, a 3.5 percentage point increase from the end of the previous fiscal year.
- The full-year earnings forecast (sales ¥9.60 billion, operating profit ¥0.10 billion, ordinary profit ¥0.075 billion, net profit ¥0.045 billion) remains unchanged from the values announced on April 14, 2026.
- An interim dividend of ¥3 per share was announced for FY2027.
🤖 AI Perspective
Twinbird’s announcement suggests that the strategic shift towards high-profitability B2B businesses is progressing as planned, leading to the company’s first interim profit in five years. The significant increase in orders for small refrigerators for hospitals and metal floor materials for semiconductor manufacturing plants appears to be a key driver of this performance improvement. The improved equity ratio and the new shareholder return policy, which prioritizes progressive dividends, may indicate a strengthening financial position and a commitment to shareholder returns.
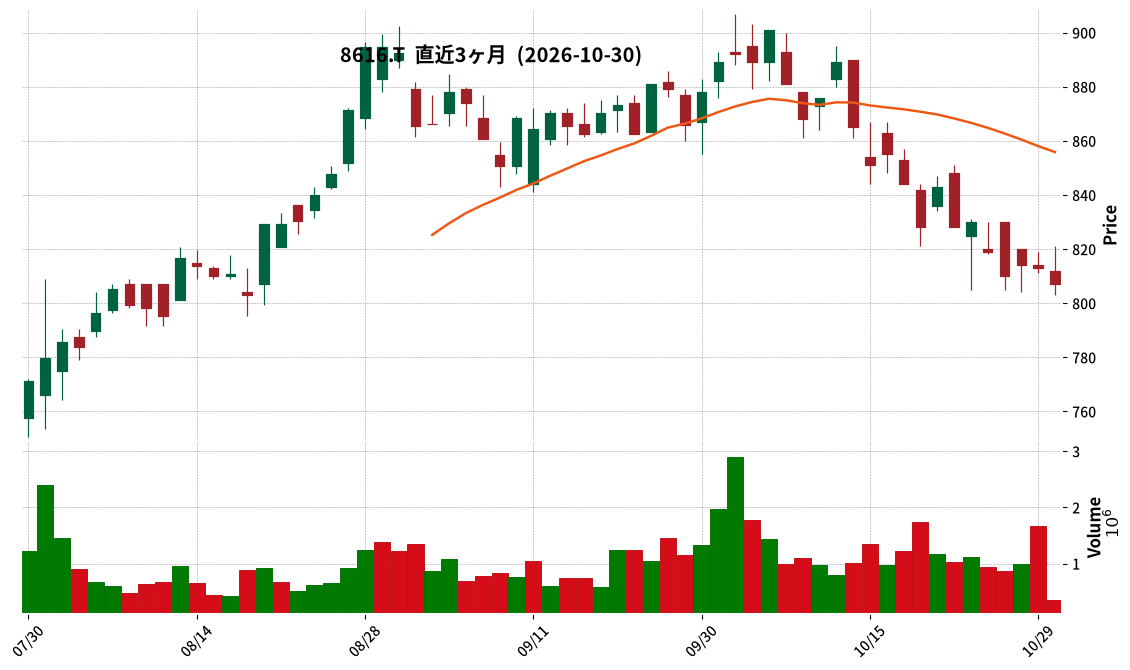
8616|東海東京
807.0
▼ -0.74%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Consolidated operating revenue for the second quarter (interim period) of FY2027 reached ¥53,709 million, an increase of 17.3% compared to the same period in the previous year.
- Net income attributable to owners of parent was ¥10,165 million, marking a 58.0% increase year-on-year.
- Interim net income per share stood at ¥40.04, up from ¥25.62 in the prior year’s interim period.
- An interim dividend of ¥25 per share is planned (up from ¥22 in the previous interim period). The year-end dividend forecast remains undecided.
- Supplementary financial materials were prepared on October 30, 2026, and an earnings briefing for securities analysts and institutional investors will be held.
🤖 AI Perspective
Tokai Tokyo Financial Holdings has reported substantial year-on-year growth across key revenue metrics, suggesting a strong operational performance. The significant increases in operating revenue and net income attributable to owners of parent are particularly noteworthy. The planned increase in the interim dividend may indicate a positive stance on shareholder returns. Given the nature of the financial instruments business, which is highly sensitive to market fluctuations, no full-year earnings forecast has been provided, making future market conditions a key factor to monitor for potential impacts on performance.
9040|大宝運
—
▲ +0.00%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Taiho Transport (9040) released its Q2 FY2027 (interim) financial results on October 30, 2026.
- For the interim period, operating revenue was ¥4,346 million, marking a 5.5% increase compared to the prior interim period.
- Operating profit reached ¥249 million (up 37.1% year-on-year), and ordinary profit was ¥266 million (up 39.6% year-on-year).
- Interim net profit amounted to ¥174 million, representing a 44.1% increase from the previous interim period.
- Diluted earnings per share for the interim period stood at ¥234.24.
- The company maintains its year-end dividend forecast of ¥50.00 per share, for a total annual dividend of ¥100.00 per share.
- The full-year FY2027 earnings forecast remains unchanged from the most recent announcement: operating revenue of ¥8,300 million (up 2.7% year-on-year), operating profit of ¥280 million (down 12.9% year-on-year), ordinary profit of ¥300 million (down 9.9% year-on-year), and net profit of ¥190 million (down 7.0% year-on-year).
🤖 AI Perspective
Taiho Transport reported robust growth across all key profitability metrics for the interim period, suggesting strong operational performance. The substantial increase in interim net profit could indicate effective cost management or favorable market conditions during the period. However, investors might note the full-year forecast projects a decline in profits, which may suggest potential headwinds or increased costs anticipated in the latter half of the fiscal year. This divergence between interim performance and full-year guidance could be a point of interest for further analysis.
Disclaimer: This article is for informational purposes only and does not constitute investment advice.
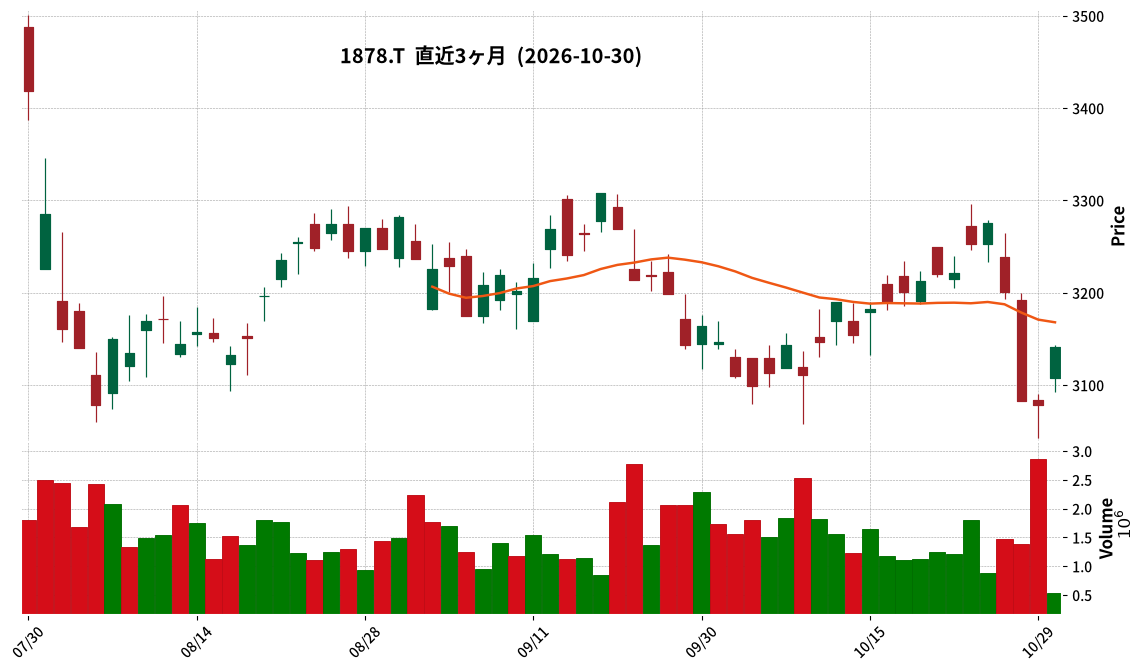
1878|大東建
3141.0
▲ +2.01%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Daito Trust Construction has announced its consolidated financial results for the second quarter (interim period) of the fiscal year ending March 2027.
- Net sales reached ¥988,686 million, representing a 3.0% increase year-on-year, while operating profit was ¥79,299 million, an increase of 14.3% year-on-year.
- Net income attributable to parent company shareholders rose significantly by 28.6% year-on-year, reaching ¥64,175 million.
- The full-year consolidated performance forecast has been revised, with net sales projected at ¥2,080,000 million (up 4.8% from the previous year) and net income attributable to parent company shareholders at ¥109,000 million (up 10.1% from the previous year).
- The dividend forecast for the fiscal year was also revised, with a year-end dividend of ¥84, making the total annual dividend ¥165 (revised from the most recently published forecast).
- During this interim period, a significant change in the scope of consolidation included the addition of THE GLOBALSHA Corporation.
🤖 AI Perspective
Daito Trust Construction’s Q2 FY2027 results show solid growth across all key financial metrics, with a notable increase in net income attributable to parent company shareholders. The upward revision of both full-year guidance and dividend forecasts suggests a positive outlook from the company regarding its future performance. The improved profitability in the construction segment due to price revisions and stable revenue growth in the real estate leasing business appear to be key drivers of these results, which investors may find noteworthy.
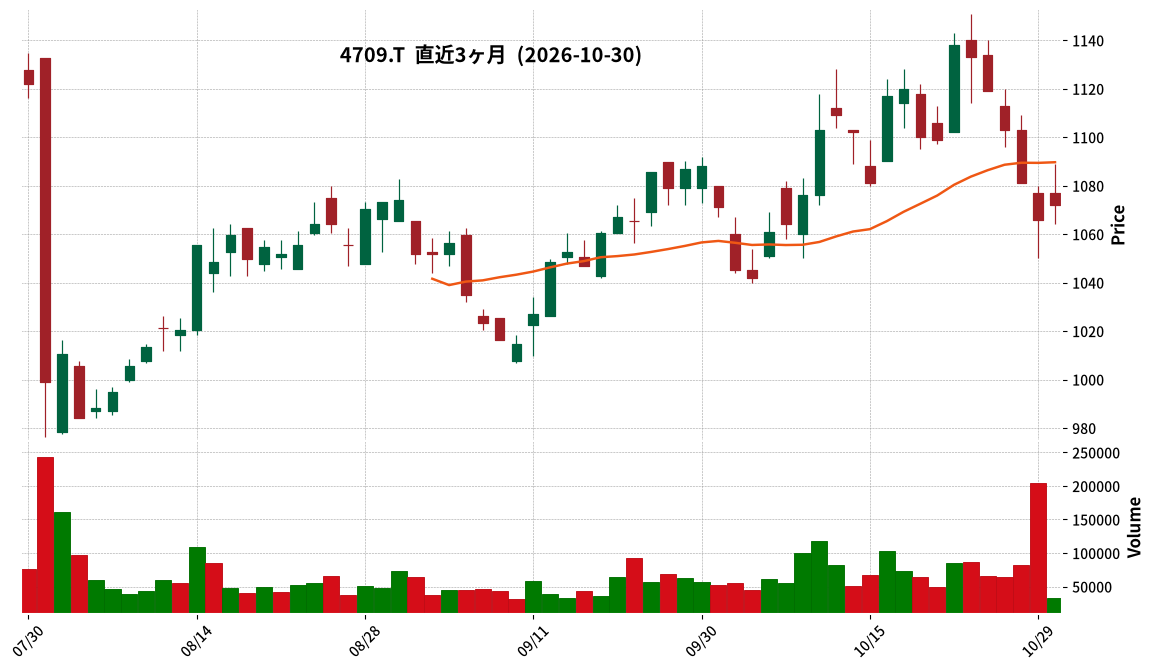
4709|IDホールディングス
1072.0
▲ +0.56%
📎 Source:IDホールディングス Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- ID Holdings announced its consolidated financial results for the second quarter (interim period) of the fiscal year ending March 2027.
- Net sales were JPY 19,399 million (down 0.4% year-on-year), EBITDA was JPY 2,073 million (down 6.2% YoY), and operating income was JPY 1,898 million (down 6.0% YoY).
- Net income attributable to owners of parent was JPY 943 million (down 26.0% YoY), impacted by the recognition of JPY 243 million as an allowance for loss on damages due to fraudulent activities by a former employee, recorded as an extraordinary loss.
- By segment, IT Infrastructure reported sales of JPY 2,487 million (up 6.5% YoY), and Consulting & Education reported sales of JPY 1,017 million (up 21.2% YoY), both showing revenue growth.
- The forecast for the annual dividend for the fiscal year ending March 2027 remains unchanged, with an interim dividend of JPY 25.00 and a year-end dividend of JPY 25.00, totaling JPY 50.00.
🤖 AI Perspective
While net sales remained largely stable compared to the prior year, the decline in interim net income due to increased expenses and an extraordinary loss may draw investor attention. The extraordinary loss from fraudulent activity is considered a one-time event, but its impact on future performance warrants careful monitoring. The strong growth in IT infrastructure and consulting & education segments could indicate potential strengths for the company’s future business development.
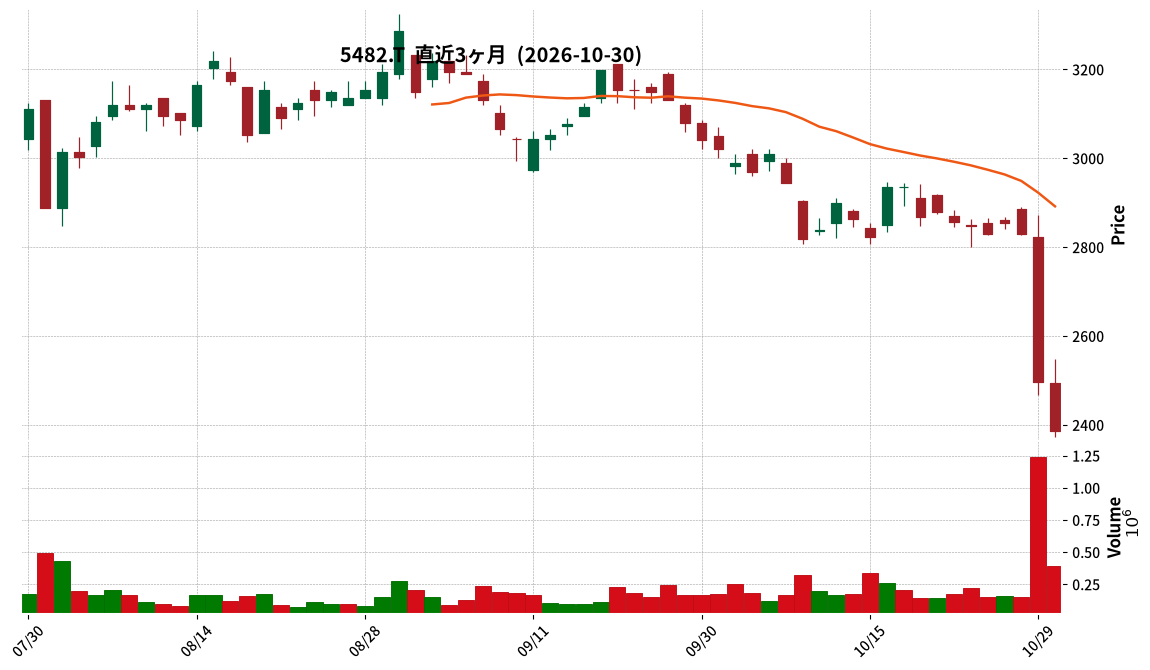
5482|愛知鋼
2385.0
▼ -4.45%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Aichi Steel announced its interim financial results for the fiscal year ending March 2027 (April 1, 2026, to September 30, 2026).
- Consolidated net sales for the interim period reached JPY 162.5 billion, a 9% increase year-on-year, marking a record high for an interim period.
- Consolidated operating profit was JPY 7.3 billion (down 16% year-on-year), and profit attributable to owners of the parent was JPY 5.2 billion (down 5% year-on-year).
- The decline in operating profit was attributed to the rise in input material prices outweighing positive factors such as increased sales volume and higher sales prices.
- The full-year forecast for FY2027 was revised downwards: consolidated net sales JPY 330.0 billion (up JPY 20.0 billion from previous announcement), consolidated operating profit JPY 15.0 billion (down JPY 2.5 billion), and profit attributable to owners of the parent JPY 10.0 billion (down JPY 1.3 billion).
- The year-end dividend for the full year is projected to be JPY 142 per share, with the ordinary dividend reduced from JPY 72 to JPY 64 per share, in addition to the special dividend.
🤖 AI Perspective
Aichi Steel’s interim results show a dichotomy of record-high revenue contrasted with declining profits, primarily driven by surging input material costs. This situation led to a downward revision of the full-year outlook and a reduction in the year-end dividend, suggesting that fluctuations in raw material prices will remain a critical factor impacting future performance. The influence of the “slide gap” on profitability warrants close observation, and the company’s progress in cost reduction efforts and effective price pass-through mechanisms could be key to its recovery.
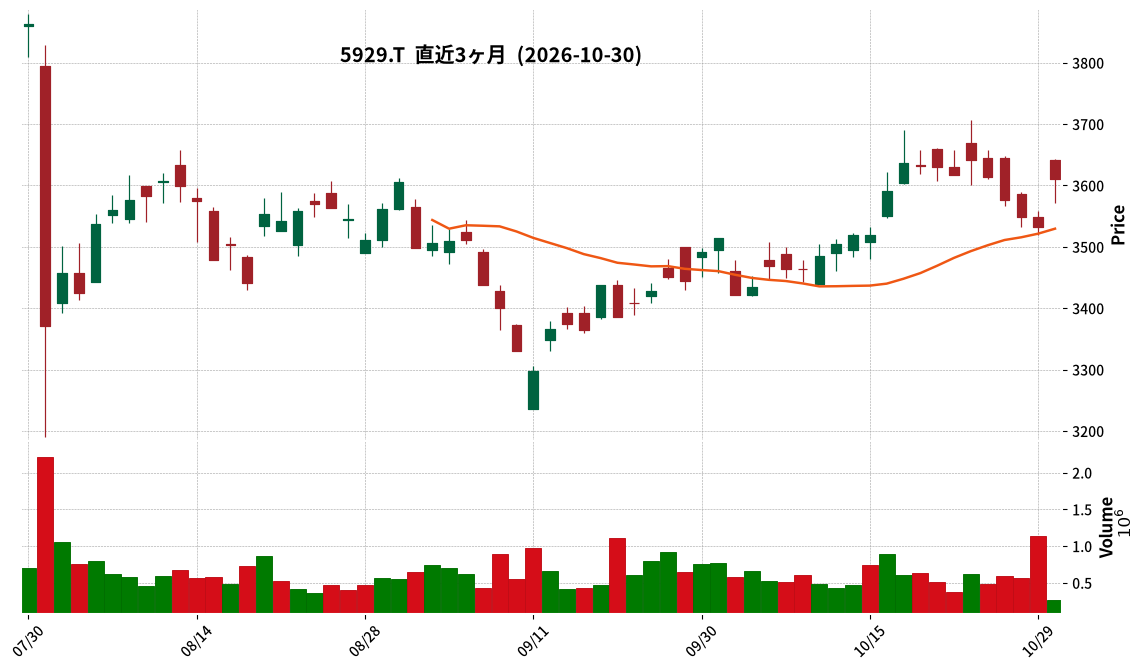
5929|三和HD
3610.0
▲ +2.18%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Sanwa Holdings Corporation resolved to change its dividend policy and revise its year-end dividend forecast for the fiscal year ending March 2027 (increased dividend) at a Board of Directors meeting held on October 30, 2026.
- The dividend policy’s target DOE (Dividend on Equity) has been raised from the conventional 10% to 15%.
- This change will be applied starting from the year-end dividend for the fiscal year ending March 2027.
- The year-end dividend forecast for the fiscal year ending March 2027 has been revised from the previous forecast of ¥73 (including a ¥7 commemorative dividend) announced on May 14, 2026, to ¥96 (including a ¥7 commemorative dividend), representing an increase of ¥23.
- Consequently, the annual dividend forecast for the fiscal year ending March 2027 will be ¥169 (including a ¥14 commemorative dividend), up from ¥146.
🤖 AI Perspective
This dividend policy change suggests the company’s commitment to enhancing shareholder returns and further improving capital efficiency. The increase in the DOE target may raise expectations for continued shareholder distributions alongside stable business growth. Investors might monitor how this policy change contributes to long-term corporate value.
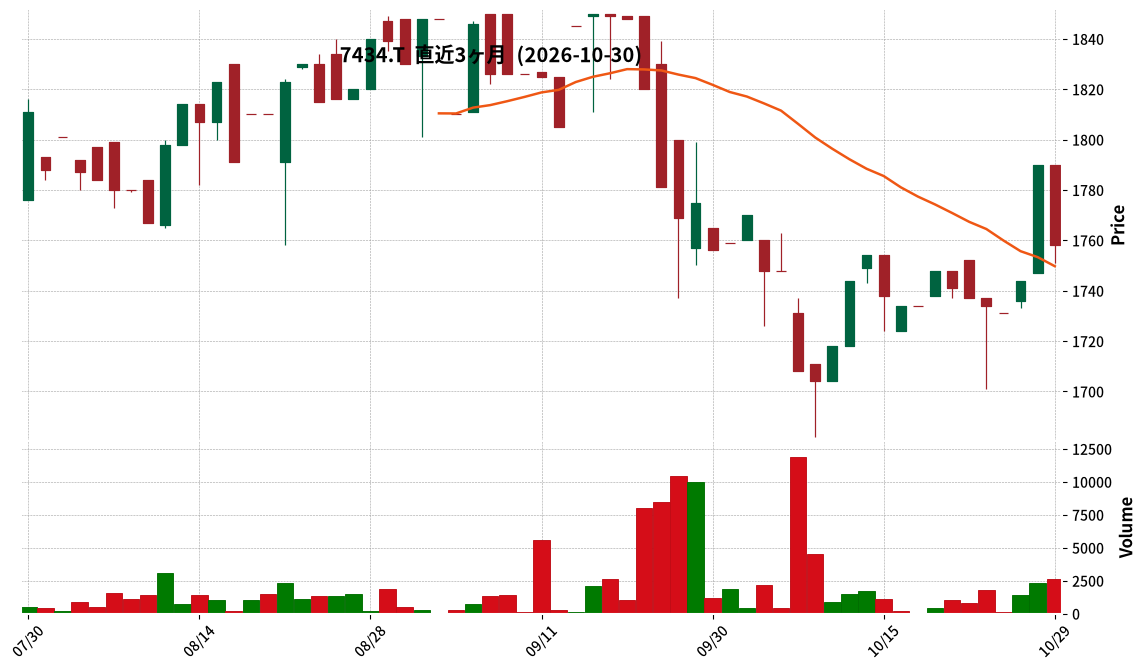
7434|オータケ
1758.0
▼ -1.79%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Otake Co., Ltd. announced the scheduled disclosure date for its Q1 FY2027 financial results.
- The new scheduled disclosure date is Friday, November 13, 2026.
- This announcement follows the “Notice Regarding the Disclosure of Financial Results for the First Quarter of the Fiscal Year Ending May 2027 Exceeding 45 Days After the End of the Quarter” issued on October 6, 2026, which informed of the delay.
- The company expressed its deep apologies for the significant inconvenience and concern caused to shareholders, investors, and other stakeholders.
🤖 AI Perspective
This announcement provides a specific date for the previously delayed earnings report, which could alleviate some uncertainty among investors. It represents a step towards fulfilling the company’s disclosure obligations after the initial delay. Investors will likely be focused on the content of the upcoming earnings report, particularly regarding the reasons for the initial delay and any potential implications for financial performance.
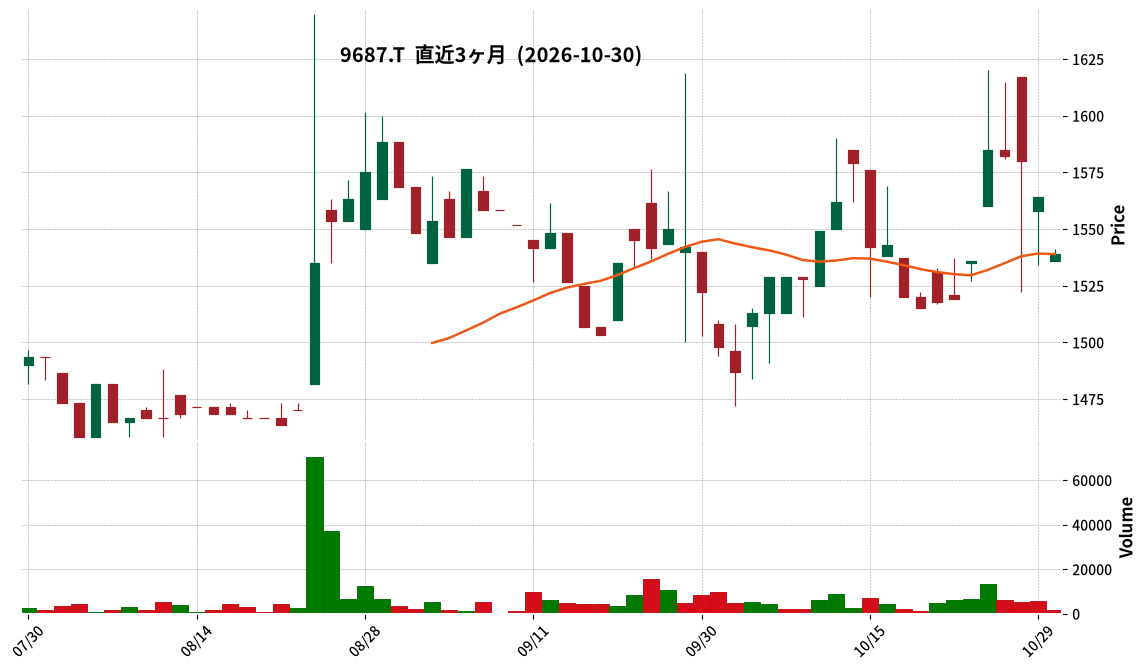
9687|KSK
1539.0
▼ -1.60%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- KSK Co., Ltd. announced its consolidated financial results for the second quarter (interim period) of the fiscal year ending March 2027.
- Net sales for the interim period amounted to ¥13,634 million, representing an 8.7% increase compared to the prior interim period.
- Operating profit was ¥1,784 million (down 3.2% year-on-year), and ordinary profit was ¥1,871 million (down 1.6% year-on-year).
- Net income attributable to owners of parent was ¥1,276 million (down 8.5% year-on-year).
- Basic earnings per share for the interim period was ¥70.14 (compared to ¥76.79 in the prior interim period).
- The full-year consolidated performance forecast remains unchanged: Net sales ¥28,100 million (up 9.1% year-on-year), operating profit ¥3,100 million (up 13.1% year-on-year), ordinary profit ¥3,300 million (up 14.6% year-on-year), and net income attributable to owners of parent ¥2,300 million (up 5.4% year-on-year).
- The company conducted a 1-for-3 stock split of common shares effective October 1, 2026.
🤖 AI Perspective
KSK’s interim financial results for the fiscal year ending March 2027 show increased net sales but a decline in profits. This was attributed to increased human capital investments, such as regular salary increases, base-up adjustments, and aggressive recruitment activities, as well as higher corporate income taxes due to the non-application of the wage increase promotion tax system and the introduction of a special defense corporate tax. While sales growth remains solid, increased investments for future growth and higher tax burdens appear to have impacted short-term profitability, which may be a point of interest for investors.
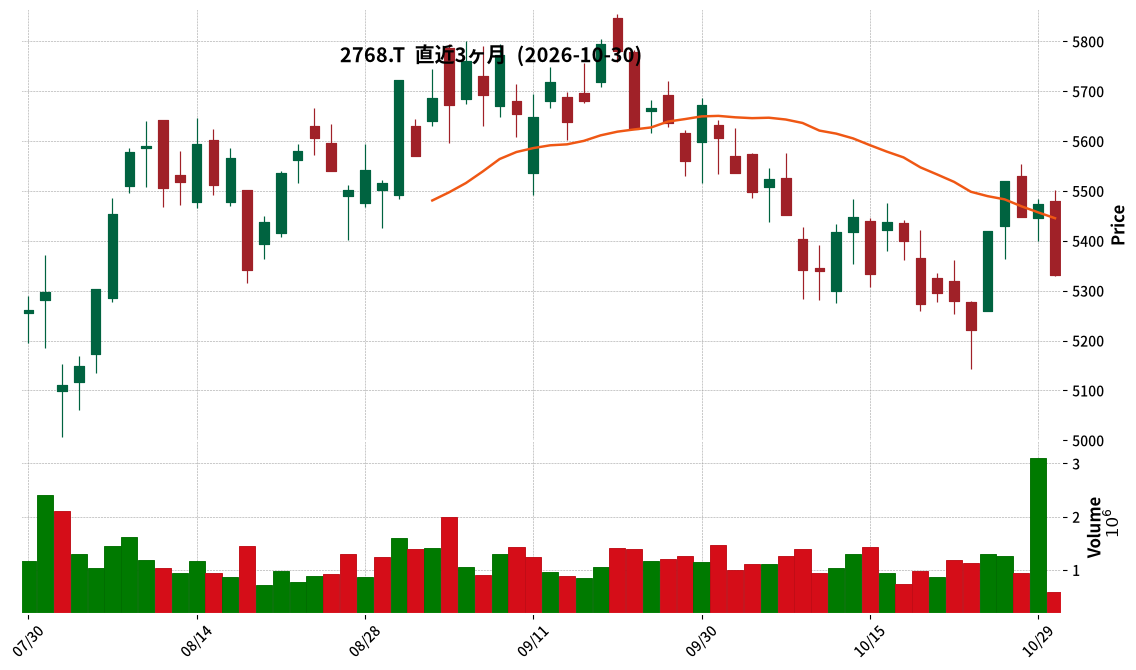
2768|双日
5332.0
▼ -2.59%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- For the second quarter of the fiscal year ending March 2027, consolidated revenue totaled ¥1,672,130 million, an increase of 34.8% compared to the prior year’s interim period.
- Profit attributable to owners of the parent for the interim period was ¥63,588 million, marking a 40.4% increase year-on-year.
- Profit before tax for the interim period grew by 60.0% year-on-year to ¥86,088 million.
- The annual dividend forecast remains unchanged from the most recently announced forecast, with an interim dividend of ¥90.00 and a year-end dividend of ¥90.00, totaling ¥180.00.
- Key drivers of profit increase include the “Energy & Social Infrastructure” segment, up ¥6,169 million year-on-year, the “Chemicals” segment, up ¥9,530 million, and the “Retail & Consumer Services” segment, up ¥6,543 million.
🤖 AI Perspective
Sojitz’s Q2 FY2027 results show substantial year-on-year increases in key revenue and profit metrics, suggesting robust performance across its diverse business segments. The strong contributions from Energy & Social Infrastructure, Chemicals, and Retail & Consumer Services segments indicate that the company’s diversified portfolio may be effectively driving overall growth. The unchanged annual dividend forecast could suggest management’s confidence in achieving the full-year earnings projections.
3776|BBタワー
245.0
▼ -1.61%
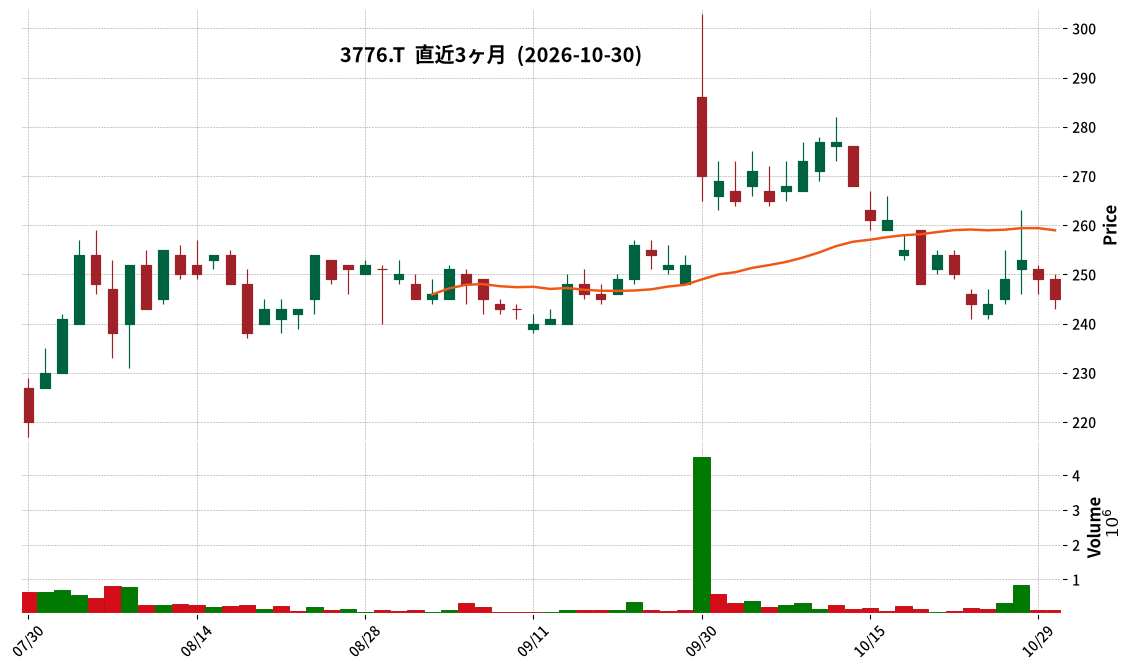
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- For the nine months ended September 30, 2026, consolidated net sales were ¥9,507 million, a decrease of 18.2% year-on-year.
- Operating profit was ¥676 million, a 21.7% increase year-on-year, and ordinary profit was ¥800 million, a 19.7% increase year-on-year.
- Net income attributable to parent company shareholders increased by 44.1% to ¥689 million.
- Basic earnings per share for the quarter were ¥11.20, up from ¥7.79 in the prior year period.
- The full-year consolidated earnings forecast remains unchanged from the most recently announced figures: net sales of ¥14,000 million (down 8.4% YoY) and net income attributable to parent company shareholders of ¥480 million (up 59.9% YoY).
🤖 AI Perspective
Despite a decline in revenue, the significant increase in operating profit, ordinary profit, and net income attributable to parent company shareholders suggests an improvement in profitability. This performance, even with a strong prior-year comparison in the data solution business, could indicate effective cost management or growth in other business segments. The launch of a new suburban data center and acquisition of new customers in the data center business may offer future growth opportunities, which is worth monitoring.
8285|三谷産業
751.0
▲ +0.67%
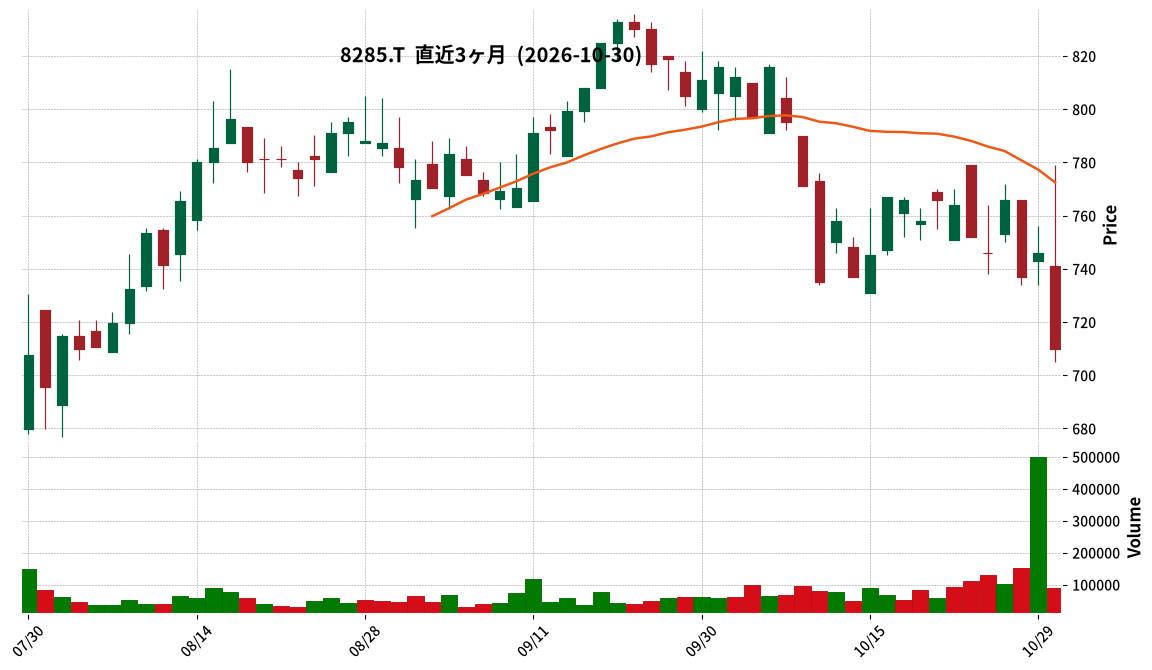
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Mitani Sangyo announced on October 30, 2026, that its Board of Directors resolved to increase the interim dividend for shareholders as of the record date of September 30, 2026.
- The interim dividend per share will be ¥6.00, an increase of ¥1.00 from the most recent dividend forecast (announced on April 27, 2026) of ¥5.00.
- The total dividend amount is ¥369 million, with an effective date of December 2, 2026, and the source of the dividend is retained earnings.
- The reason for this increase is the expectation that sales and all stages of profit for the interim period of the fiscal year ending March 2027 will reach record highs, attributed to the smaller-than-anticipated impact of the Middle East situation and the company’s efforts in alternative proposals utilizing its procurement capabilities.
- The full-year dividend forecast for the fiscal year ending March 2027 is ¥6.00 for the interim period and ¥8.00 for the year-end, totaling ¥14.00.
🤖 AI Perspective
This dividend increase announcement is noteworthy as the company explicitly states an expectation of “record-high performance for the interim period of the fiscal year ending March 2027.” This decision aligns with the company’s policy of balancing stable dividends with internal reserves for future business expansion, and suggests progress in its mid-term management plan. With the full-year dividend forecast also exceeding the previous fiscal year’s actual results, the company’s future performance and shareholder return policies may be of interest to investors.
1942|関電工
4994.0
▼ -6.27%
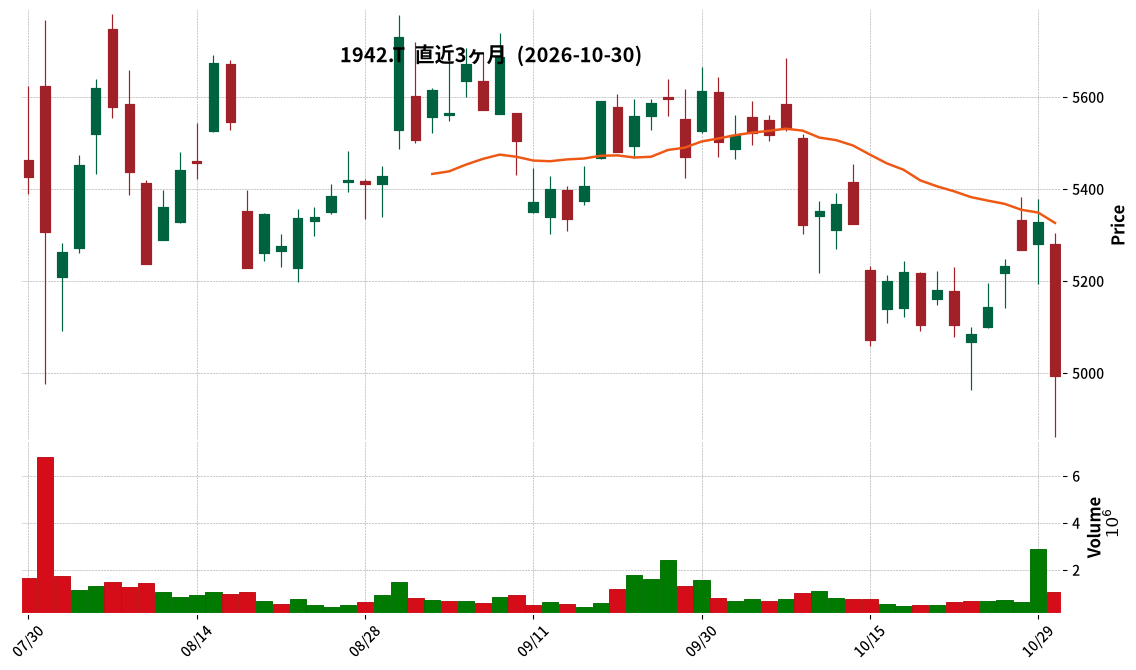
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Kandenko Co., Ltd. announced its consolidated financial results for the second quarter (interim period) of the fiscal year ending March 2027 on October 30, 2026.
- In the consolidated operating results (cumulative), net sales were ¥351,534 million (up 3.2% year-on-year), operating profit was ¥43,920 million (up 15.9%), ordinary profit was ¥45,043 million (up 15.6%), and profit attributable to owners of parent was ¥29,090 million (up 10.2%).
- Diluted earnings per share were ¥146.17, an increase from ¥129.18 in the previous interim period.
- Regarding the consolidated financial position, as of the end of the second quarter of the fiscal year ending March 2027, total assets were ¥617,751 million, net assets were ¥416,773 million, and the equity ratio was 64.8%.
- The forecast for the annual dividend is ¥65.00 per share at the end of the second quarter and ¥65.00 at the fiscal year-end, totaling ¥130.00, with no revisions from the most recently announced dividend forecast.
- The consolidated earnings forecast for the fiscal year ending March 2027 remains unchanged from the most recently announced forecast, with net sales of ¥780,000 million, operating profit of ¥90,000 million, ordinary profit of ¥90,500 million, and profit attributable to owners of parent of ¥65,000 million.
🤖 AI Perspective
Kandenko’s interim results for the fiscal year ending March 2027 show increases across sales and all profit categories compared to the prior year, with double-digit growth in operating, ordinary, and net profit attributable to owners of parent. The strong equity ratio of 64.8% at the end of the period may suggest a sound financial position. Investors could find the consistent earnings forecast, without revision, a point of stability.
3153|八洲電機
2974.0
▲ +0.81%
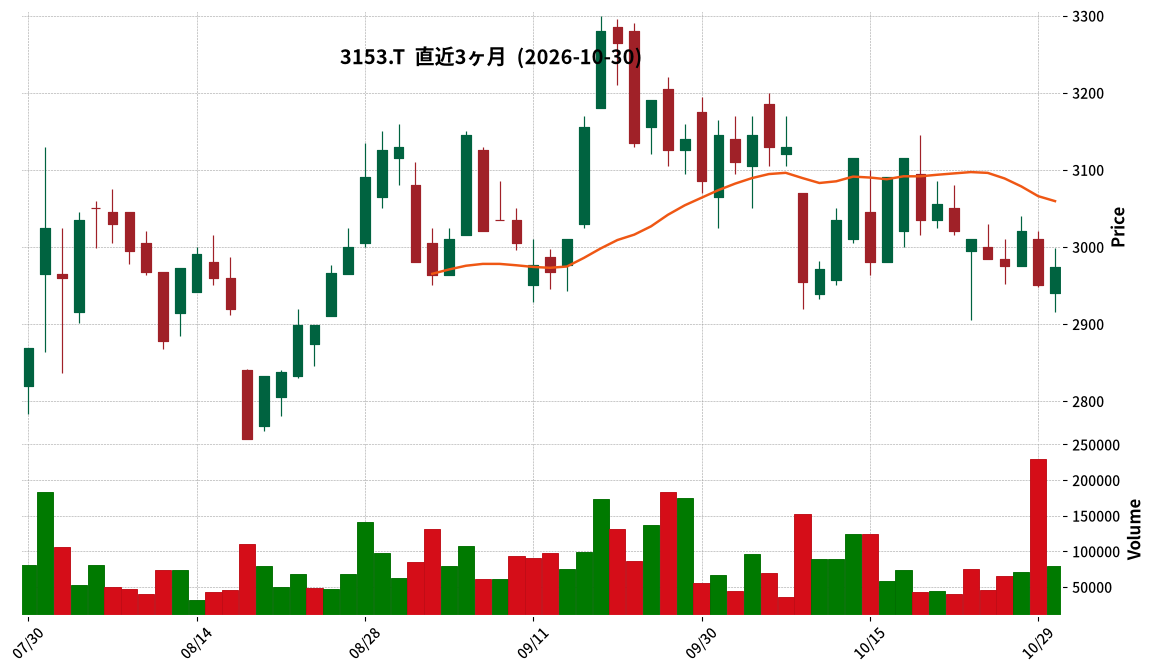
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Yashima Denki announced its consolidated financial results for the second quarter (interim period) of the fiscal year ending March 2027.
- Net sales reached ¥34,719 million, marking a 20.9% increase compared to the prior interim period.
- Operating profit was ¥2,765 million (up 48.8% year-on-year), and ordinary profit was ¥2,915 million (up 51.7% year-on-year).
- Net profit attributable to owners of parent amounted to ¥1,904 million, an increase of 57.0% from the previous interim period.
- The company revised its full-year consolidated earnings forecast and annual dividend forecast. The revised annual dividend forecast is ¥66.00 per share (ordinary dividend ¥60.00, 80th anniversary commemorative dividend ¥6.00).
- By segment, the Public & Facility Business reported significant increases in both sales and operating profit, with sales of ¥16,236 million (up 26.7% year-on-year) and operating profit of ¥1,970 million (up 78.5% year-on-year). In contrast, the Plant Business saw a decrease in both sales and operating profit.
🤖 AI Perspective
Yashima Denki’s H1 FY2027 results show substantial growth across key financial metrics, suggesting strong operational performance. The robust performance of the Public & Facility Business segment appears to be a primary driver for the overall positive results. The upward revision of both full-year earnings and dividend forecasts could signal management’s confidence in the company’s future prospects and profitability.
4410|ハリマ化成G
1082.0
▲ +2.56%
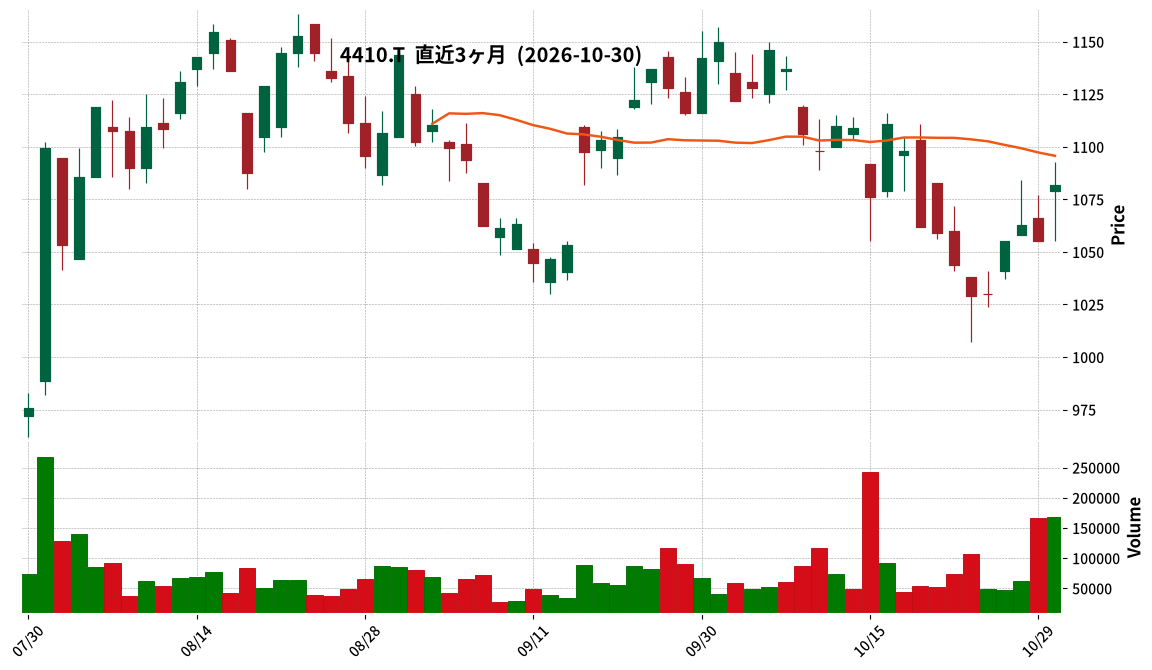
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Harima Chemicals Group reported consolidated financial results for the second quarter of FY2027 (ending September 30, 2026), with net sales of ¥60,407 million against a forecast of ¥54,500 million (an increase of 10.8%).
- Operating profit reached ¥3,630 million compared to a forecast of ¥1,400 million (a 159.3% increase), ordinary profit was ¥3,469 million against ¥1,050 million (a 230.4% increase), and net income attributable to owners of the parent was ¥2,714 million against ¥1,450 million (an 87.2% increase), all exceeding initial forecasts.
- The full-year consolidated earnings forecast for FY2027 was revised upward: net sales from ¥110,000 million to ¥125,000 million, operating profit from ¥3,500 million to ¥5,800 million, ordinary profit from ¥2,800 million to ¥5,000 million, and net income attributable to owners of the parent from ¥2,650 million to ¥4,400 million.
- The interim dividend for FY2027 was decided at ¥25.00 per share (¥23.00 ordinary, ¥2.00 special), an increase from the previously forecast ¥21.00 per share.
- The year-end dividend forecast was also revised upward from ¥21.00 to ¥25.00 per share (¥23.00 ordinary, ¥2.00 special), making the total annual dividend ¥50.00 per share.
🤖 AI Perspective
The substantial outperformance in the second quarter was driven by increased demand across multiple business segments and revisions in selling prices. Specifically, higher sales in coatings resins and semiconductor photoresists, coupled with price adjustments in paper chemicals and electronic materials businesses, contributed to the positive results. The upward revision of the full-year forecast suggests that the favorable business conditions experienced in the first half are expected to continue into the second half. The increased interim and year-end dividends may reflect both the strong financial performance and the company’s commitment to shareholder returns.
4568|第一三共
2629.0
▲ +0.44%
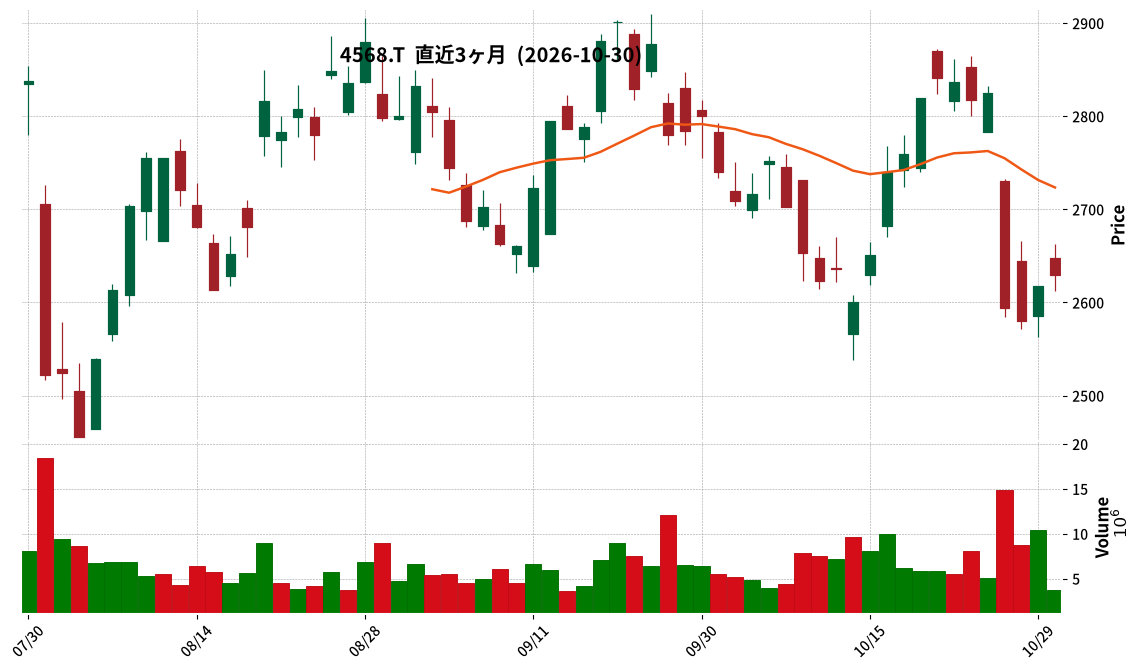
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Consolidated revenue for the first half of fiscal year 2027 (April 1 to September 30, 2026) reached JPY 1,167,233 million, representing a 19.7% increase year-on-year.
- Core operating profit amounted to JPY 221,331 million, a 46.9% increase compared to the same period last year.
- Interim profit attributable to owners of the parent company rose by 15.8% year-on-year to JPY 151,534 million.
- The interim dividend per share was JPY 50, an increase from JPY 39 in the prior year period. The forecast for the full fiscal year 2027 dividend is JPY 100 per share.
- Revenue growth was attributed to the robust performance of global key products, Enhertu and Dato-DXd, along with a JPY 73.9 billion positive foreign exchange impact due to yen depreciation.
- The definition of core operating profit has been revised for FY2027, excluding items such as amortization of intangible assets related to products.
🤖 AI Perspective
These results indicate strong operational performance driven by key product sales and a significant boost from foreign exchange movements. The substantial increase in both revenue and core operating profit could suggest robust underlying business momentum. The raised interim dividend may also signal confidence in future earnings and a commitment to shareholder returns. Investors should note the change in core operating profit definition when comparing figures across periods.
5257|ノバシステム
2833.0
▲ +0.28%
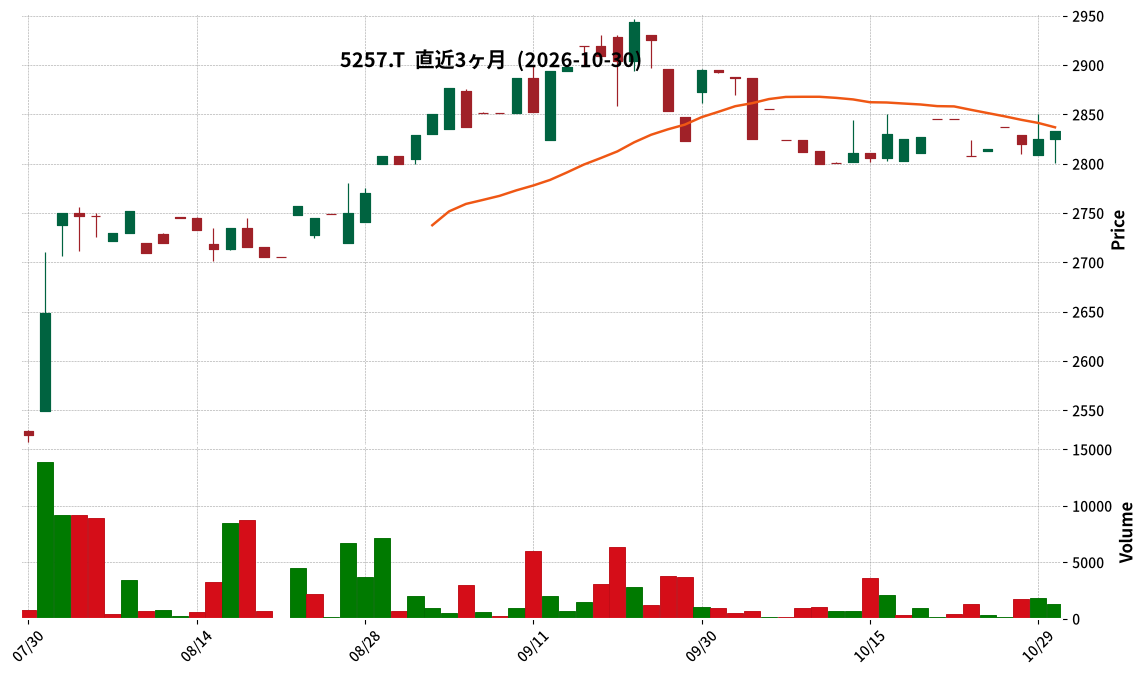
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Nova System Co., Ltd. released its Q3 2026 financial results presentation material.
- For the cumulative Q3 2026, net sales were ¥5,374 million (up 7.8% year-on-year), and operating profit was ¥434 million (up 170.4% year-on-year).
- The operating profit margin improved from 3.2% in the prior year to 8.1%.
- Progress rates against full-year forecasts (net sales ¥7,535 million, operating profit ¥617 million) are 71.3% for net sales and 70.4% for operating profit, respectively.
- There are no changes to the full-year performance forecast or dividend forecast (¥105 per share) for the fiscal year ending December 2026.
- The System Integration business recorded net sales of ¥5,285 million (up 7.8% year-on-year), and the Cloud Services business recorded net sales of ¥89 million (up 6.7% year-on-year).
🤖 AI Perspective
The Q3 cumulative results indicate steady revenue growth and a significant recovery in profits, with a notable improvement in the operating profit margin, which could suggest strengthening profitability. The high progress rate against full-year targets may imply increased confidence in achieving annual objectives. This performance warrants monitoring as the company approaches its fiscal year-end.
5440|共英製鋼
1811.0
▼ -1.36%
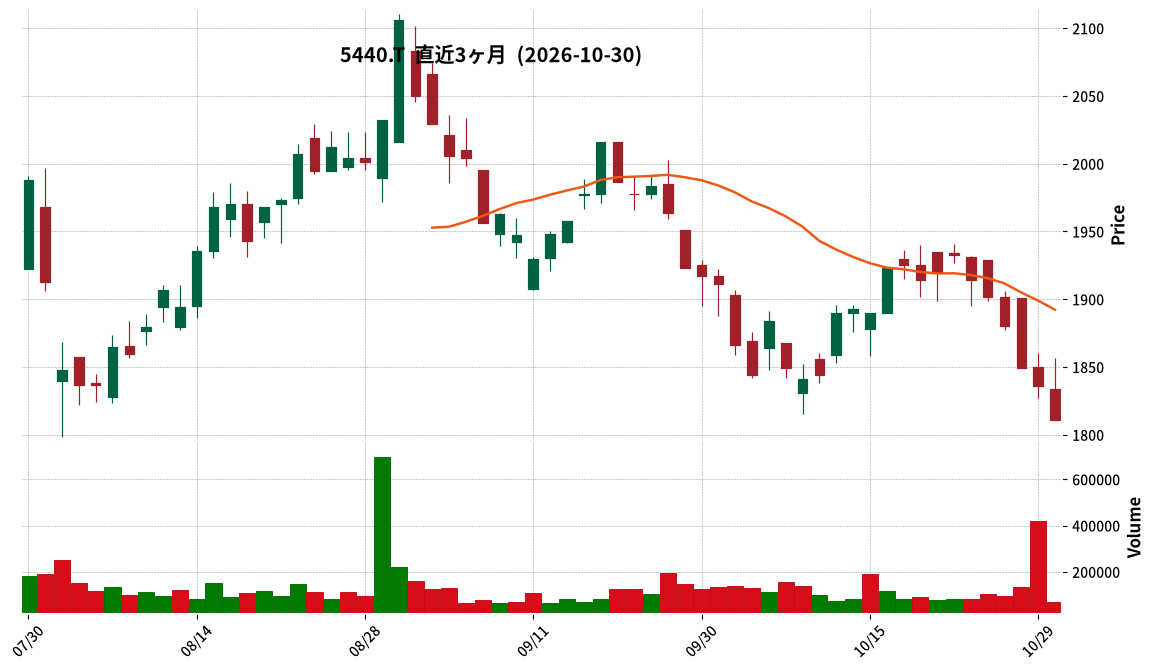
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Kyoei Steel has announced its financial results for the second quarter of the fiscal year ending March 2027.
- Consolidated net sales reached ¥177,703 million, marking a 14.9% increase compared to the prior interim period.
- Consolidated operating profit was ¥6,112 million (down 33.6% year-on-year), ordinary profit was ¥5,929 million (down 30.1%), and net profit attributable to owners of the parent was ¥3,262 million (down 40.0%).
- Interim earnings per share stood at ¥75.05.
- The full-year consolidated performance forecast has been revised: net sales are projected to be ¥362,000 million (up 14.9% year-on-year), operating profit ¥9,500 million (down 44.0%), ordinary profit ¥9,000 million (down 44.5%), and net profit attributable to owners of the parent ¥4,800 million (down 51.3%).
- An interim dividend of ¥30.00 per share was declared (same as previous year), with an anticipated year-end dividend of ¥40.00 per share (¥10.00 increase from previous year-end).
🤖 AI Perspective
While net sales increased, the notable decline in various profit metrics suggests pressure on profitability. The domestic steel business appears to have been impacted by rising raw material costs and a limited increase in product prices, leading to a narrower price spread. Conversely, the overseas steel business and environmental recycling business reported increased sales and profits, indicating a shifting contribution from different segments to the overall performance, which is worth monitoring.
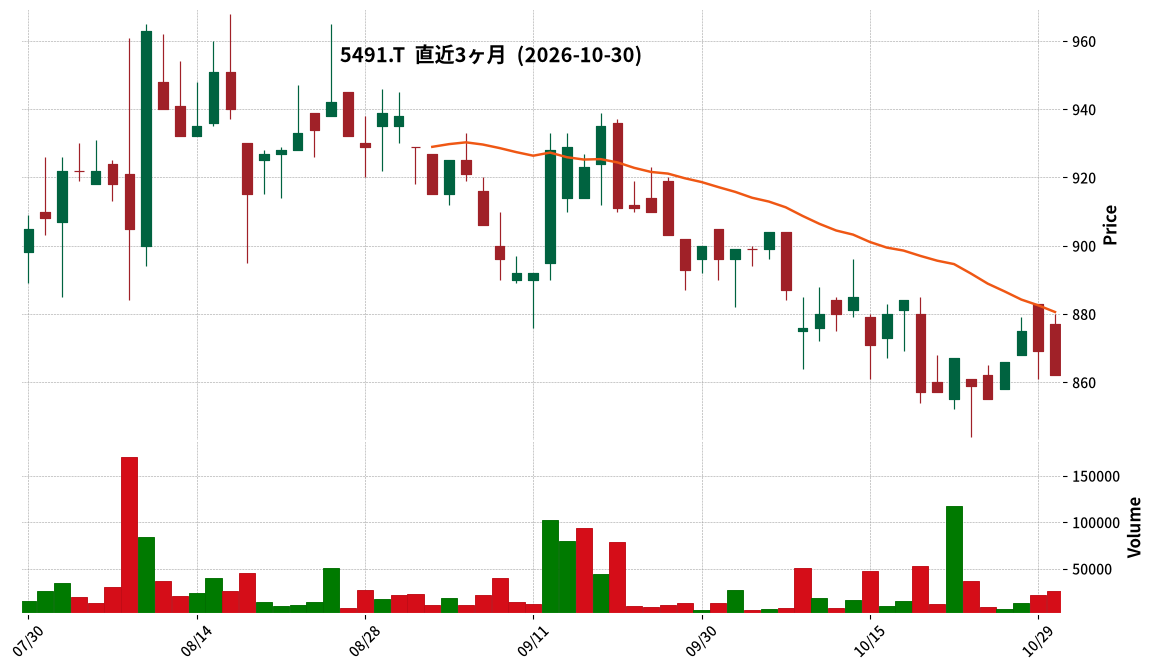
5491|日本金属
862.0
▼ -0.81%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Nippon Kinzoku announced that its consolidated financial results for the second quarter (interim period) of the fiscal year ending March 2027 significantly exceeded previous forecasts. Revenue increased by 3.0% (from ¥24.6 billion to ¥25.342 billion), operating income by 22.6% (from ¥630 million to ¥772 million), ordinary income by 76.6% (from ¥360 million to ¥635 million), and net income attributable to owners of parent by 94.0% (from ¥230 million to ¥446 million).
- Individual company results for the second quarter also substantially surpassed initial forecasts, with operating income up 138.2% (from ¥210 million to ¥500 million), ordinary income up 623.1% (from ¥70 million to ¥506 million), and net income reaching ¥390 million compared to the ¥30 million forecast.
- The full-year consolidated earnings forecast for FY2027 was revised upwards: revenue by 1.2% (from ¥49.6 billion to ¥50.2 billion), operating income by 3.9% (from ¥1.27 billion to ¥1.32 billion), ordinary income by 21.1% (from ¥760 million to ¥920 million), and net income attributable to owners of parent by 21.6% (from ¥510 million to ¥620 million).
- The year-end dividend forecast for the fiscal year ending March 2027 was revised from ¥5.00 per share to ¥10.00 per share, representing an increase of ¥5.00. The total annual dividend will be ¥10.00 per share.
- The reasons for the discrepancy and revisions include the success of profit improvement activities, such as shifting sales to high-margin products, adjusting sales prices to reflect rising costs, thoroughly reducing business costs, and improving production efficiency and quality, despite a challenging business environment primarily in the automotive sector.
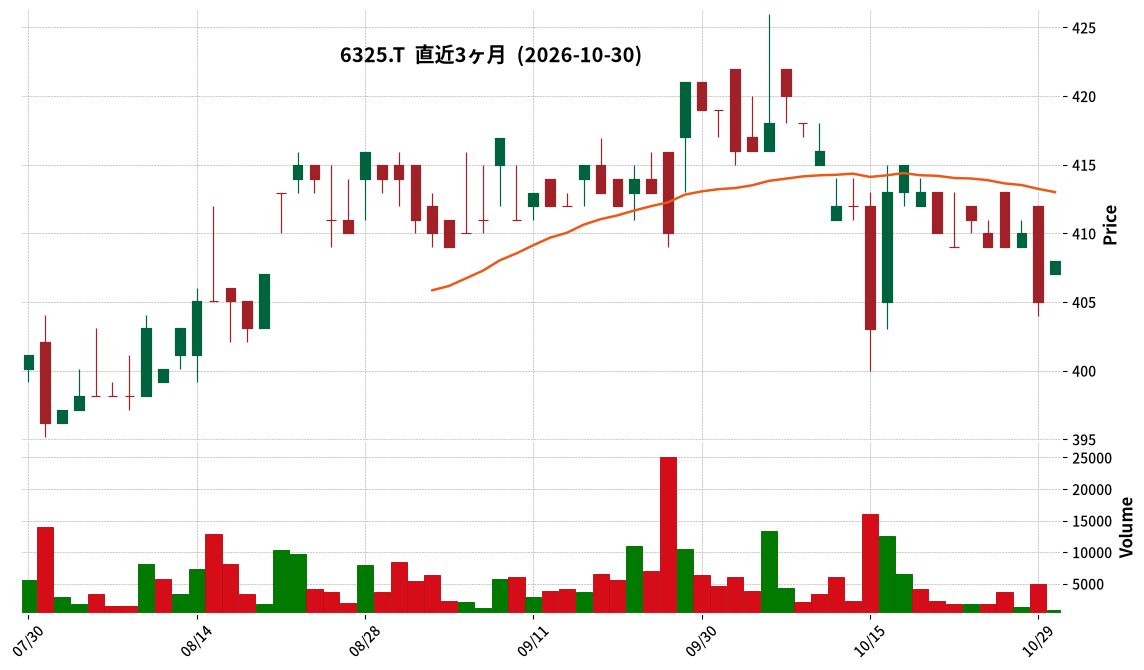
6325|タカキタ
408.0
▲ +0.74%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Takakita Co., Ltd. announced its non-consolidated financial results for the second quarter of the fiscal year ending March 2027.
- Net sales for the interim period were ¥2,893 million, representing a 2.8% decrease compared to the same period last year.
- Operating profit significantly increased by 696.5% year-on-year to ¥136 million.
- Ordinary profit rose by 306.7% year-on-year to ¥165 million.
- Net income for the interim period was ¥134 million, an increase of 664.5% year-on-year.
- Earnings per share for the interim period stood at ¥11.90.
- The equity ratio improved to 86.2% from 84.2% at the end of the previous fiscal year.
- There are no revisions to the full-year earnings forecast or dividend forecast for the fiscal year ending March 2027.
🤖 AI Perspective
While sales experienced a slight decline, the company reported substantial increases in operating, ordinary, and net profits for the interim period. This robust profit growth may suggest effective cost reduction strategies and pricing adjustments have significantly improved profitability. The strengthening of the equity ratio to 86.2% also indicates a solid financial position, which could be a point of interest for investors.
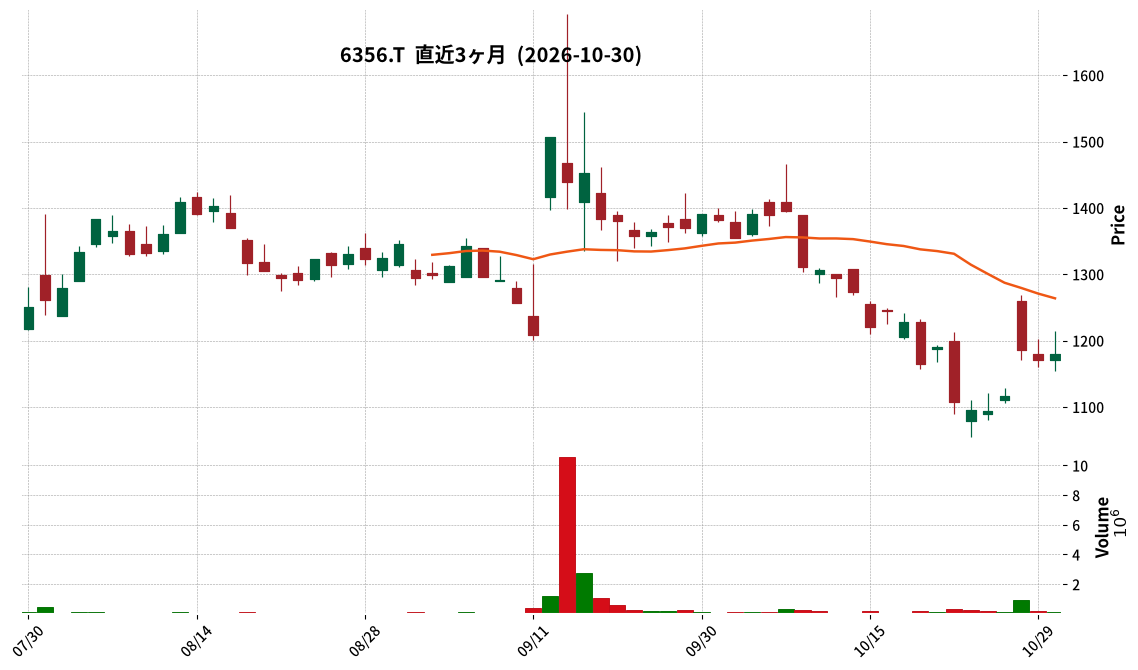
6356|日ギア
1179.0
▲ +0.77%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Nippon Gear Co., Ltd. announced its non-consolidated financial results for the second quarter (interim period) of the fiscal year ending March 2027.
- For the interim period, net sales were ¥4,451 million (up 5.7% year-on-year), operating profit was ¥1,266 million (up 59.9%), ordinary profit was ¥1,302 million (up 59.4%), and interim net profit was ¥888 million (up 60.0%).
- Interim net profit per share was ¥62.38 (compared to ¥39.00 in the prior interim period).
- Order intake for the interim accounting period amounted to ¥7,264 million (up 20.5% year-on-year), and the order backlog was ¥8,516 million (up 49.3% from the end of the previous fiscal year).
- The full-year forecast for the fiscal year ending March 2027 remains unchanged from the most recently published forecast, projecting net sales of ¥10,000 million (up 1.2% year-on-year), operating profit of ¥2,500 million (up 1.7%), ordinary profit of ¥2,560 million (up 2.1%), and net profit of ¥1,760 million (up 0.5%).
- The projected year-end dividend is ¥5.00 per share, with a total annual projected dividend of ¥10.00 (including the interim dividend of ¥5.00).
🤖 AI Perspective
Nippon Gear’s interim results for FY2027 show significant year-on-year increases in sales and all profit categories, indicating a notable improvement in profitability. This performance appears to be primarily driven by a reduction in cost of sales and selling, general and administrative expenses. Additionally, robust growth in order intake and backlog, particularly from sectors like nuclear power plants, oil & gas, steel, and semiconductors/LCDs for valve actuators and gears, may suggest a healthy demand environment for the company’s products.
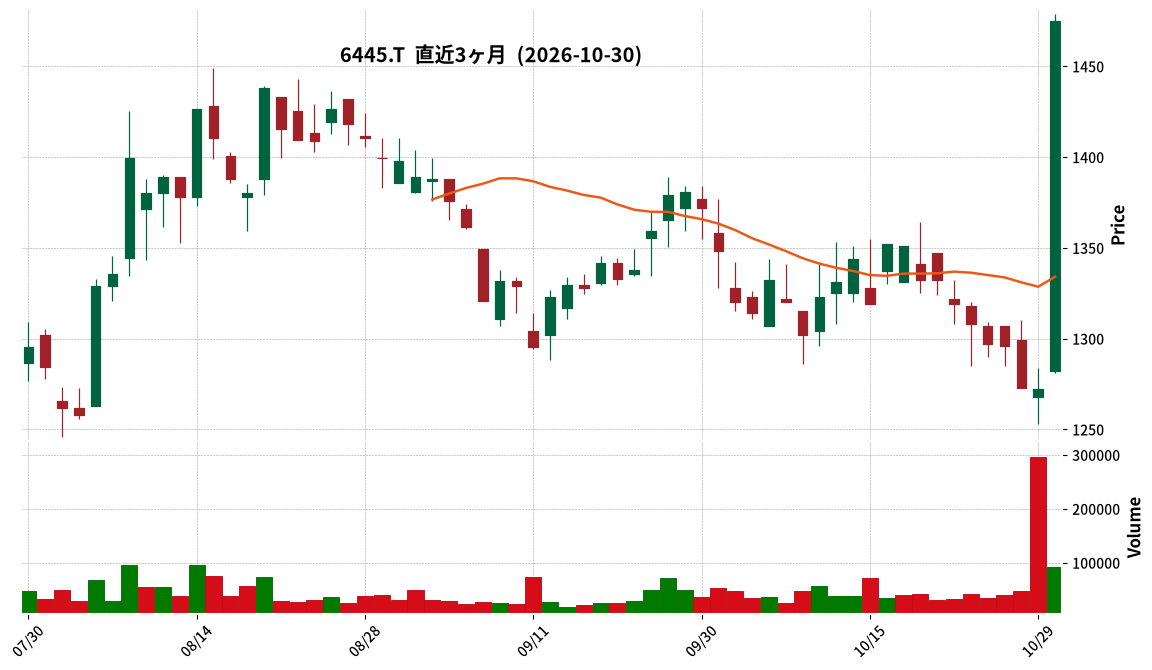
6445|ジャノメ
1475.0
▲ +15.96%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Janome Corporation resolved to revise its dividend forecast for the fiscal year ending March 2027 at a Board of Directors meeting held on October 30, 2026.
- The year-end dividend per share for the fiscal year March 2027 has been revised from the previous forecast of ¥40.00 to ¥55.00.
- Consequently, the annual dividend per share is now projected to be ¥75.00, an increase of ¥15.00 from the previous forecast of ¥60.00.
- The consolidated dividend payout ratio is expected to be revised from 51.1% to 63.6%.
- The reason for the dividend forecast revision is stated as a comprehensive consideration of current business performance and enhanced shareholder returns, based on the dividend policy that emphasizes progressive dividends, with a target DOE of 3% or more and a consolidated payout ratio of 40% or more.
🤖 AI Perspective
This dividend forecast revision aligns with Janome’s stated shareholder return policy, which includes progressive dividends and a consolidated payout ratio of 40% or more. The significant increase in the year-end dividend could be interpreted by investors as a positive indication of the company’s earnings stability and commitment to shareholder returns. Future business performance and the continuation of this dividend policy will be worth monitoring.
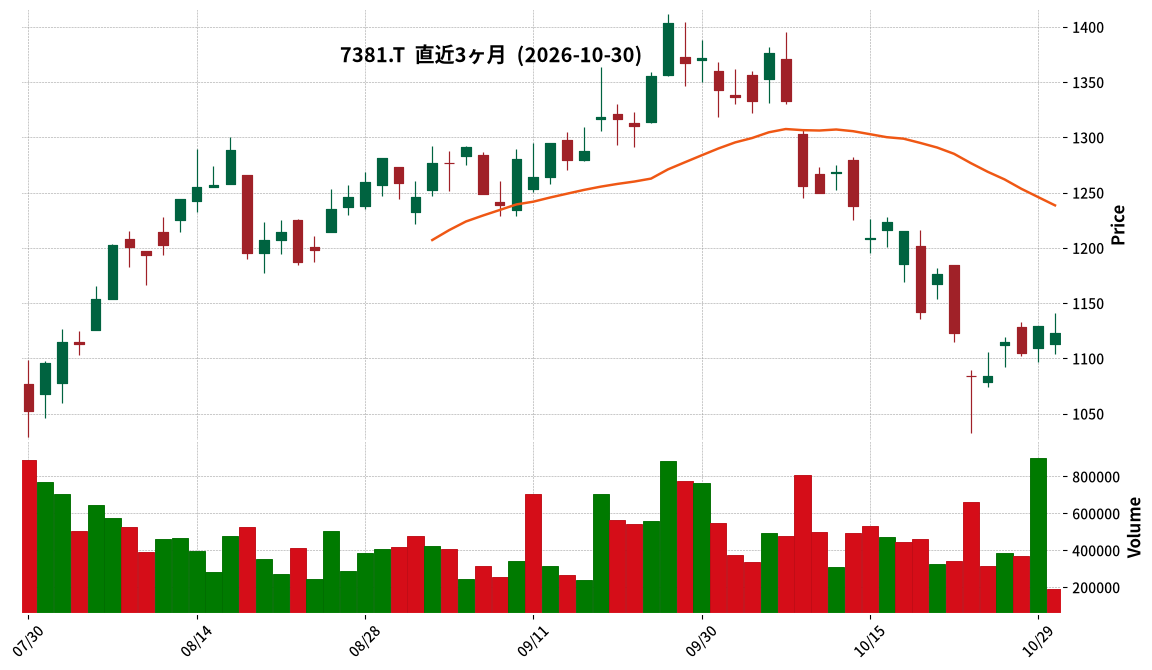
7381|CCIグループ
1123.0
▼ -0.53%
📎 Source:CCIグループ Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- CCI Group announced on October 30, 2026, revisions to its consolidated earnings forecast and dividend forecast for the fiscal year ending March 2027.
- Net profit attributable to owners of parent for FY2027 has been revised upwards by ¥2.0 billion (11.7%) from the previously announced ¥17.0 billion to ¥19.0 billion. Ordinary profit remains unchanged at ¥26.5 billion.
- Earnings per share (EPS) have been revised from ¥76.15 to ¥85.88.
- The revision is attributed to an expected increase in funding gains at its consolidated subsidiary, Hokkoku Bank, driven by factors such as rising interest rates, and an expected decrease in the effective corporate tax rate due to tax effect accounting.
- The annual dividend forecast for FY2027 has been revised upwards by ¥5 from the previously announced ¥30 to ¥35 per share. The year-end dividend will increase from ¥15 to ¥20.
- This dividend revision aligns with the company’s shareholder return policy (payout ratio of approximately 40%) following the earnings forecast revision, with a projected full-year consolidated payout ratio of 40.6%.
🤖 AI Perspective
This IR release from CCI Group highlights the positive impact of its subsidiary, Hokkoku Bank, on the group’s overall earnings forecast. The environment of rising interest rates appears to be favorably influencing the financial segment, leading to an upward revision of the dividend forecast in line with the company’s 40% payout ratio policy. The projected full-year consolidated payout ratio of 40.6% suggests a strong commitment to shareholder returns, which investors may find noteworthy.
Disclaimer: This article is for informational purposes only and does not constitute investment advice.
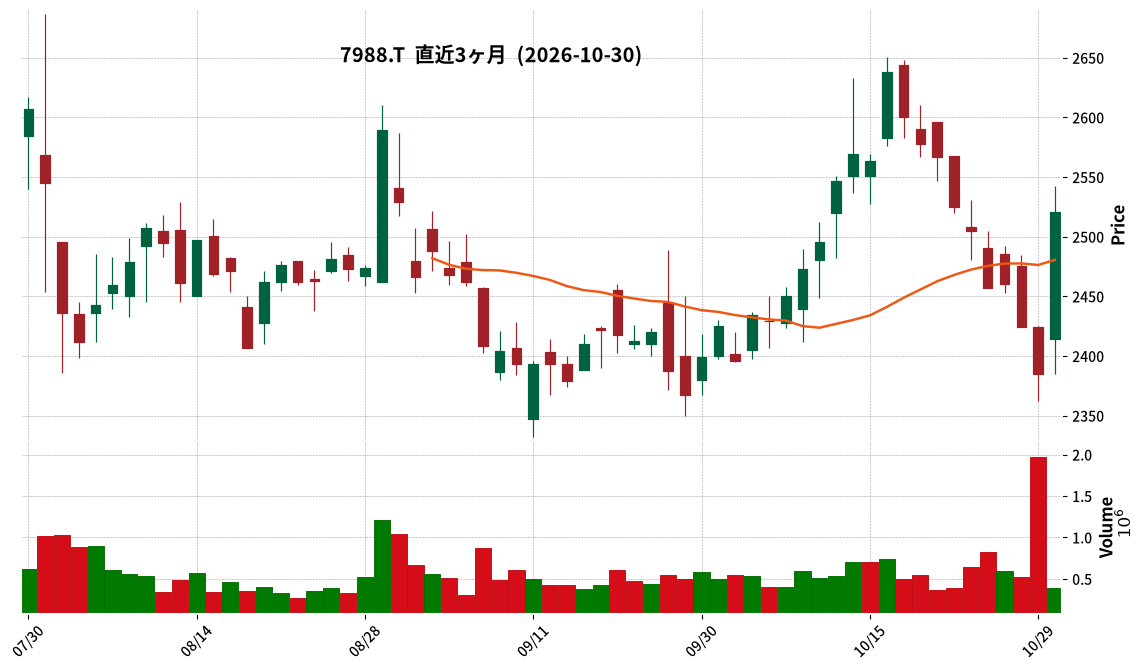
7988|ニフコ
2521.0
▲ +5.72%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Nifco’s consolidated net sales for the second quarter of the fiscal year ending March 2027 increased by 7.4% year-on-year to ¥185.95 billion.
- Operating income rose by 6.7% year-on-year to ¥26.81 billion, and ordinary income increased by 9.4% to ¥27.597 billion.
- Net income attributable to owners of parent for the interim period decreased by 6.9% year-on-year to ¥17.214 billion.
- Interim earnings per share were ¥93.48, compared to ¥97.26 in the prior year’s interim period.
- The interim dividend for the fiscal year ending March 2027 is ¥56.00, with a forecast year-end dividend of ¥28.00 (post-stock split).
🤖 AI Perspective
Nifco’s Q2 FY2027 results show solid growth in net sales and operating income, indicating robust business performance driven by both the plastic fastening systems and bed & furniture segments. However, the decline in interim net income, despite increased operating and ordinary profits, could be attributed to higher income taxes, which is worth monitoring for investors. The positive performance across both core business segments suggests underlying operational strength despite the decrease in net income.
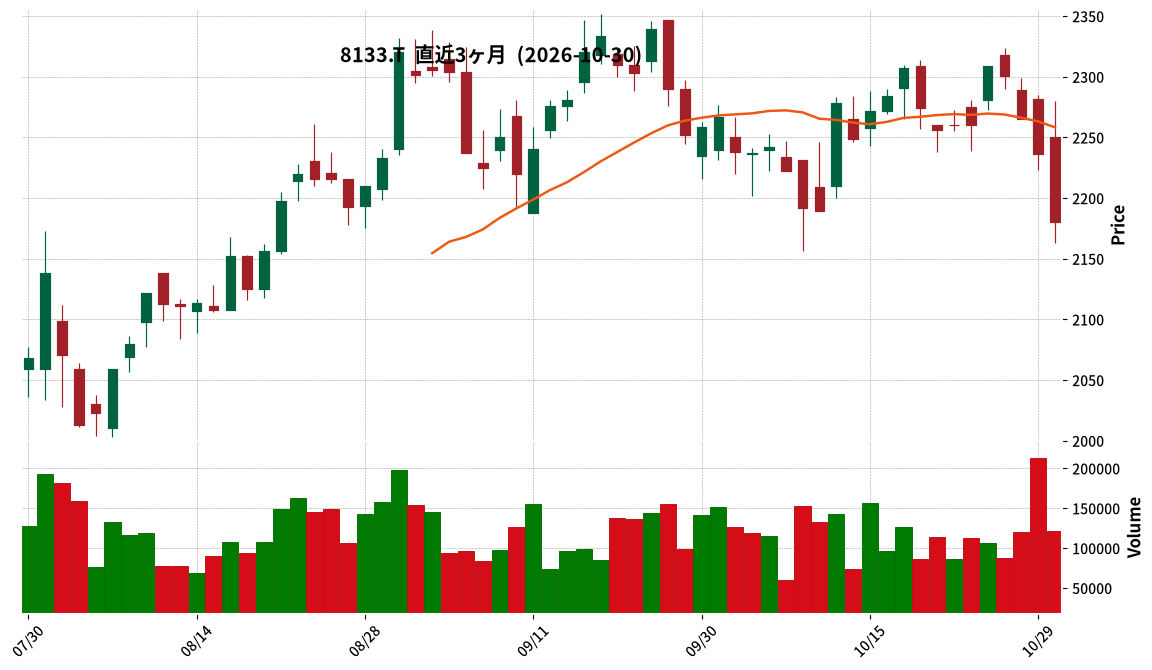
8133|エネクス
2180.0
▼ -2.50%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Itochu Enex announced its consolidated financial results for the second quarter of the fiscal year ending March 2027, reporting revenue of JPY 476,283 million (up 15.7% year-on-year).
- Profit from operating activities was JPY 19,635 million (up 75.8% year-on-year), and profit attributable to owners of the parent company was JPY 14,586 million (up 111.4% year-on-year).
- Key drivers for the profit increase included one-time gains from the sale of CS (Car Life Stations) in the Car Life Business, robust performance in the petroleum sales business, and one-time gains from the sale of affiliated companies in the Industrial Business, combined with effective market-driven operations.
- By segment, the Car Life Business reported revenue of JPY 307,093 million (up 6.2% year-on-year) and profit from operating activities of JPY 7,463 million (up 156.4% year-on-year).
- The full-year consolidated earnings forecast for the fiscal year ending March 2027 and the dividend forecast (year-end JPY 34.00, interim JPY 34.00, total JPY 68.00) remain unchanged from the most recently announced figures.
🤖 AI Perspective
Itochu Enex’s Q2 FY2027 results show significant year-on-year growth in both revenue and profit, with a notable increase of over 100% in profit attributable to owners of the parent. This performance appears to be largely influenced by one-time gains from asset sales in the Car Life and Industrial Business segments, alongside solid core business operations. As the full-year guidance remains unchanged, investors might focus on the company’s strategies and market conditions in the second half of the fiscal year to assess sustained growth potential.
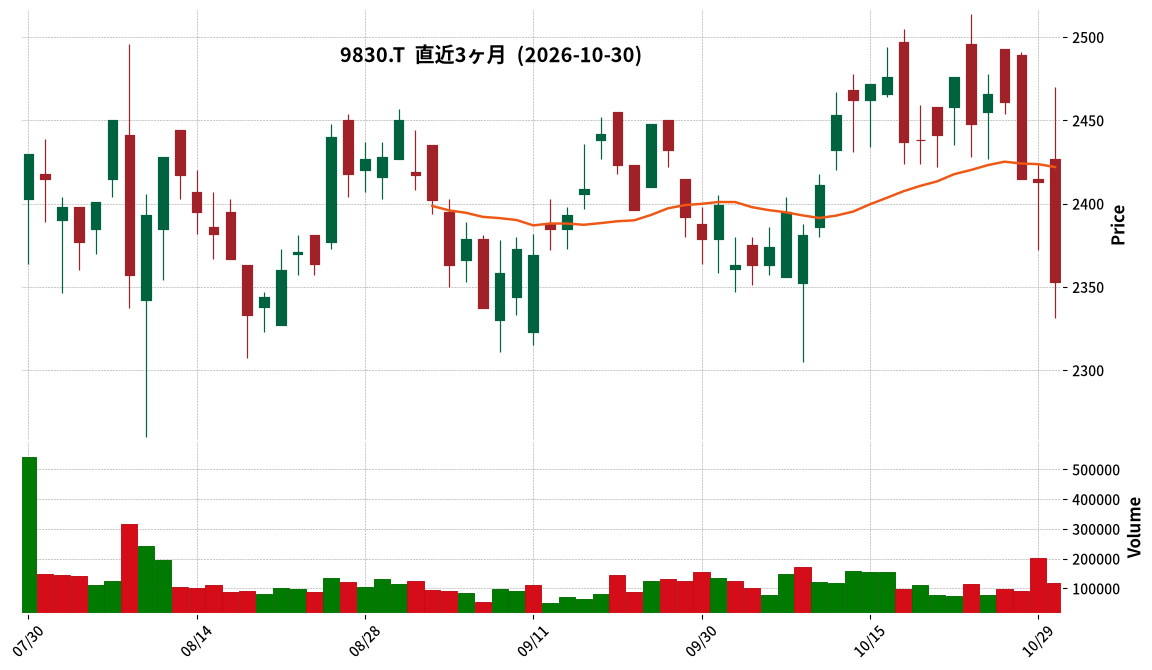
9830|トラスコ中山
2353.0
▼ -2.49%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- TRUSCO NAKAYAMA announced its Q3 FY2026 consolidated financial results for the period from January 1, 2026, to September 30, 2026.
- Consolidated net sales reached ¥266,081 million, marking a 12.1% increase year-over-year.
- Net income attributable to owners of the parent company was ¥12,100 million, an increase of 4.4% from the prior year period.
- Basic earnings per share for the quarter were ¥183.50.
- Consolidated total assets stood at ¥321,830 million, with net assets at ¥194,559 million, resulting in an equity ratio of 60.5%.
- The full-year consolidated earnings forecast, including net sales of ¥350,000 million and net income attributable to owners of the parent company of ¥15,127 million, remains unchanged.
🤖 AI Perspective
The robust double-digit growth in net sales and solid increases in key profit metrics observed in this quarter’s results could suggest the company is effectively navigating the current economic landscape. Factors such as strong demand in AI/semiconductor-related sectors and improved business conditions in certain material industries appear to be contributing to these positive figures. However, with concerns over rising costs and interest rates potentially impacting future economic sentiment, the company’s progress towards its unchanged full-year forecast will be worth monitoring.
2216|カンロ
1034.0
▲ +0.88%
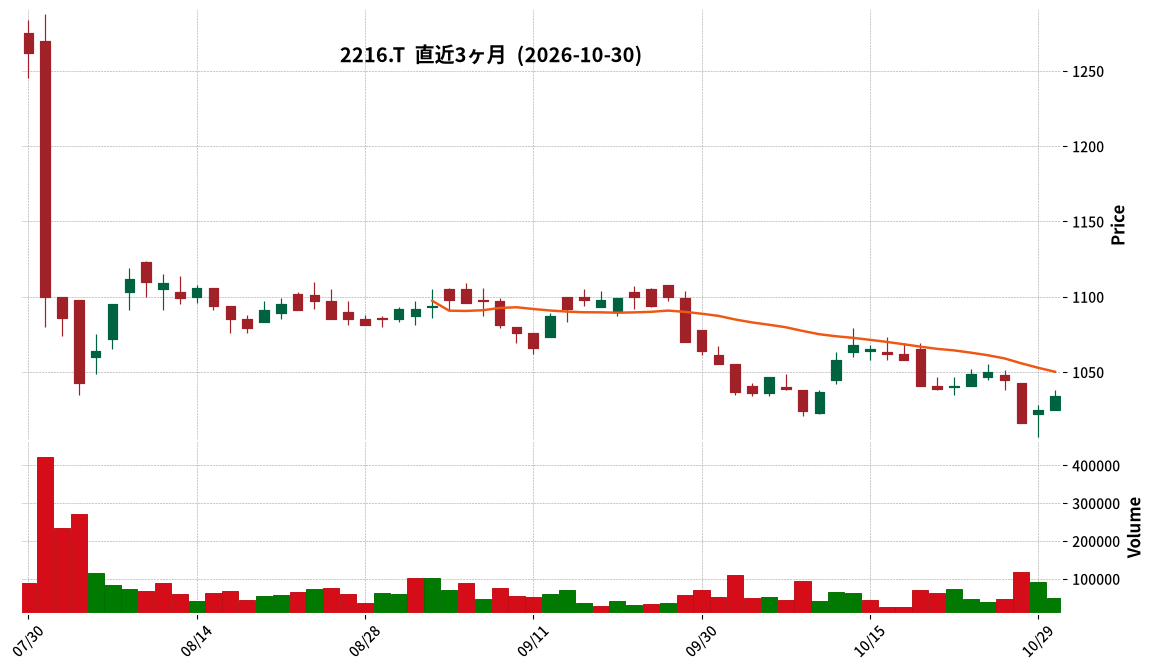
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Kanro Co., Ltd. announced its consolidated financial results for the third quarter of the fiscal year ending December 2026 (January 1, 2026, to September 30, 2026).
- Consolidated net sales amounted to ¥25,542 million, operating income was ¥2,658 million, and ordinary income was ¥2,679 million.
- Net income attributable to owners of parent for the quarter was ¥1,904 million.
- The full-year consolidated earnings forecast for the fiscal year ending December 2026 remains unchanged, projecting net sales of ¥36,500 million, operating income of ¥4,200 million, ordinary income of ¥4,200 million, and net income attributable to owners of parent of ¥3,000 million.
- As of the end of the third consolidated accounting period, total assets stood at ¥33,206 million, net assets at ¥18,217 million, and the equity ratio at 54.9%.
🤖 AI Perspective
Kanro’s third-quarter results show specific figures for revenue and profits, reflecting its performance in the current fiscal year. The confirmation of the full-year forecast indicates the company’s confidence in its current projections despite ongoing economic conditions. Investors may want to monitor the impact of increased raw material and fixed costs mentioned in the report on future profitability.
Disclaimer: This article is for informational purposes only and does not constitute investment advice.
4203|住友ベーク
8060.0
▼ -4.36%
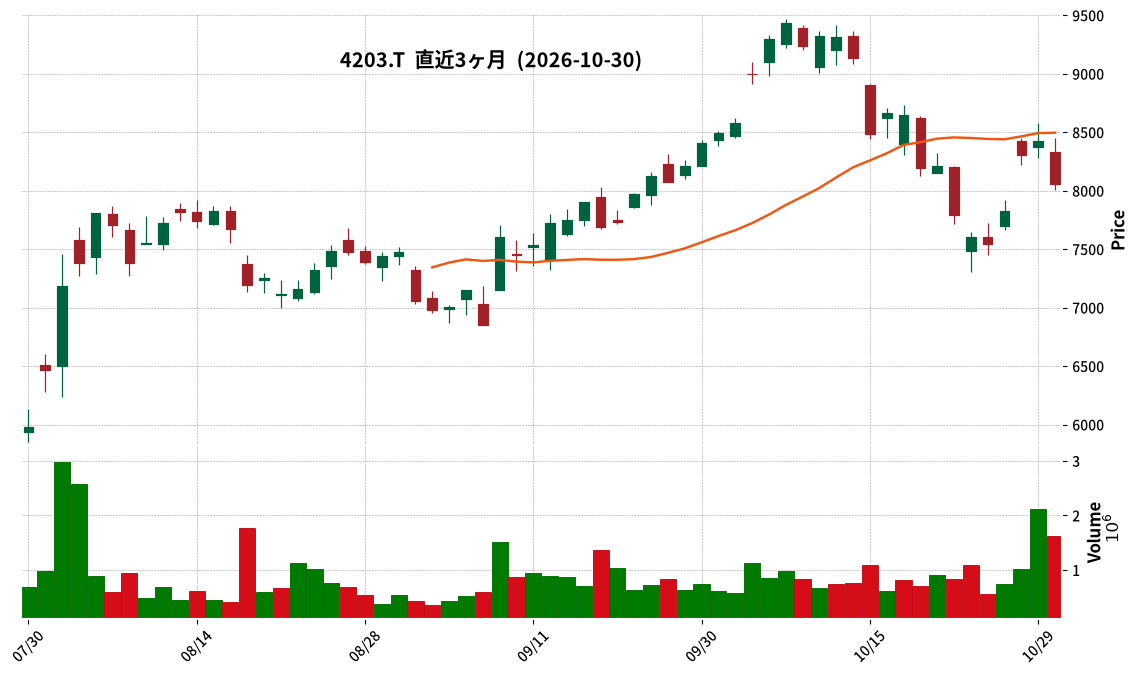
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Sumitomo Bakelite Co., Ltd. announced the completion of the acquisition of all shares and subsequent subsidiarization of a new company that will succeed a portion of Kyocera Corporation’s chemical business via an absorption-type company split, effective October 30, 2026.
- The name of the subsidiary is Sumitomo Bakelite Chemical Solutions Co., Ltd.
- The subsidiary’s location is 2-5-8, Higashi-Shinagawa, Shinagawa-ku, Tokyo, and its representative director and president is Ken Mori.
- The subsidiary’s business activities include the manufacturing and sales of epoxy molding compounds for semiconductor encapsulation, bonding pastes for semiconductors, and industrial resins.
- The subsidiary has a capital of 200 million JPY and was established on July 9, 2026.
- The impact of this matter on the consolidated financial results for the fiscal year ending March 2027 has been incorporated into the revised consolidated earnings forecast announced on the same day in the “Notice of Revisions to Consolidated Earnings Forecast, Dividend of Surplus (Interim Dividend), and Dividend Forecast.”
🤖 AI Perspective
This announcement confirms the completion of Sumitomo Bakelite’s previously disclosed acquisition of a portion of Kyocera’s chemical business. The integration of semiconductor-related materials could bolster Sumitomo Bakelite’s functional materials segment, a core business area. Investors may view this as a strategic move to strengthen their position in the growing semiconductor materials market through the newly established subsidiary, Sumitomo Bakelite Chemical Solutions Co., Ltd.
4578|大塚HD
12475.0
▲ +1.55%
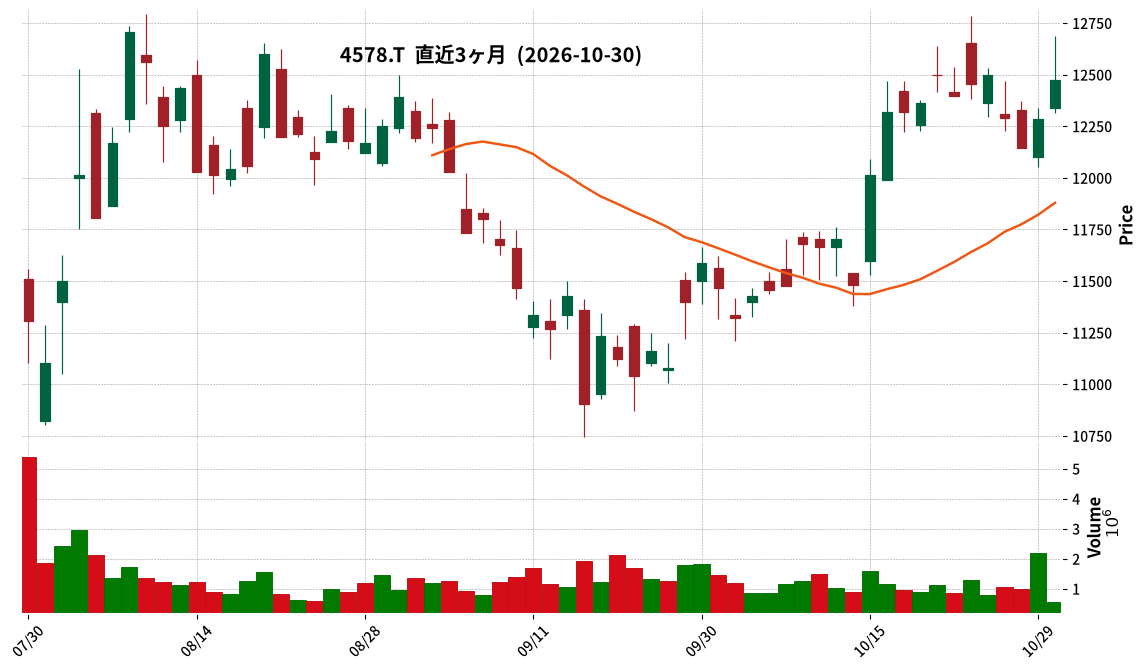
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Consolidated revenue for the third quarter of fiscal year 2026 (cumulative) reached ¥2,042,439 million, a 12.3% increase year-over-year.
- Profit attributable to owners of the parent company amounted to ¥322,105 million, an 8.2% increase compared to the same period last year.
- Business profit was ¥436,884 million (up 19.2% year-over-year), and operating profit was ¥423,733 million (up 4.0% year-over-year).
- The consolidated full-year forecast for fiscal year 2026 has been revised to ¥2,725,000 million in revenue and ¥370,000 million in profit attributable to owners of the parent.
- The year-end dividend forecast for fiscal year 2026 has been revised to ¥100, resulting in a total annual dividend forecast of ¥200.
🤖 AI Perspective
The robust performance in the third quarter appears to be driven by strong sales of key products and increased royalty income in the pharmaceutical business, alongside growth in the nutraceuticals business. The upward revision of the full-year earnings forecast and the increased dividend forecast could suggest management’s confidence in the company’s operational strength. Investors may want to monitor the impact of R&D investments and contributions from newly consolidated entities, Otsuka Clinical Nutrition America LLC and Transcend Therapeutics, Inc., going forward.
5410|合同鉄
2780.0
▼ -0.25%
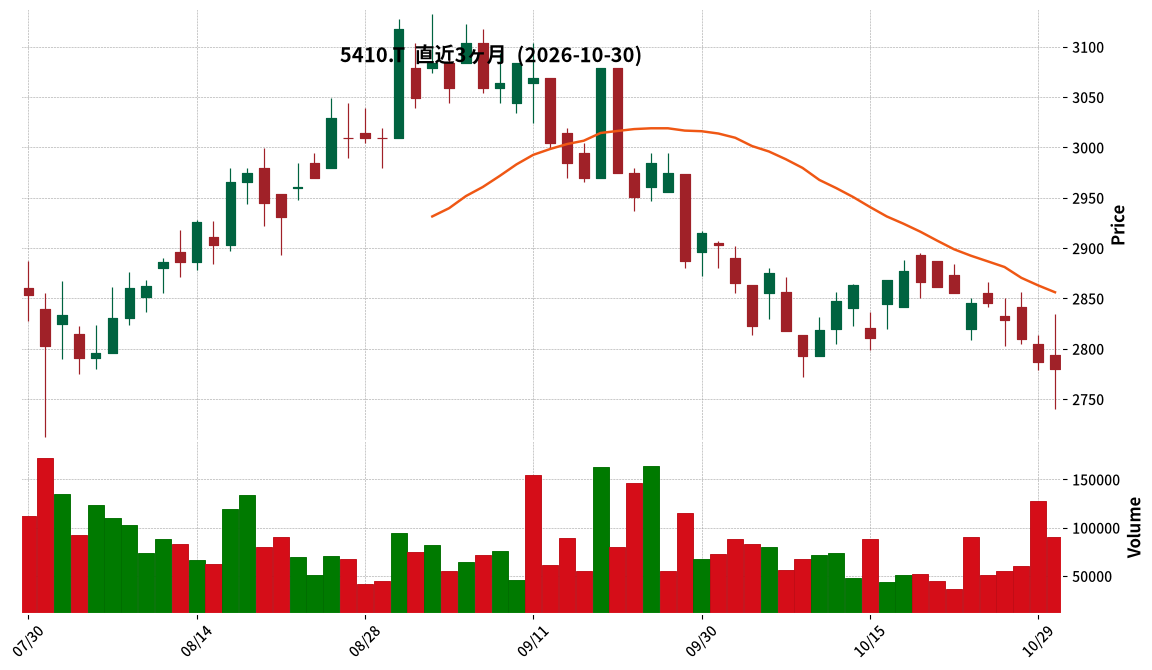
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Godo Steel announced its consolidated financial results for the second quarter (interim period) of the fiscal year ending March 2027.
- Consolidated net sales totaled ¥96,109 million, an increase of 2.8% compared to the prior interim period.
- The consolidated operating loss was ¥157 million, a significant decline from the ¥5,431 million operating profit in the prior interim period.
- Net income attributable to owners of parent was ¥383 million, a decrease of 91.8% year-over-year.
- The full-year consolidated earnings forecast has been revised to net sales of ¥200,000 million, operating profit of ¥1,800 million, and net income attributable to owners of parent of ¥1,600 million.
- The company announced a policy to set a minimum annual dividend of ¥100 per share for the five-year period from FY2027 to FY2031.
🤖 AI Perspective
Godo Steel’s Q2 FY2027 results show a mixed picture, with sales growth but a shift to an operating loss, which appears to be driven by sluggish demand for construction steel products and rising raw material and energy costs. The newly established policy of a minimum annual dividend of ¥100 per share may signal a commitment to stable shareholder returns. Investors might focus on the company’s ability to manage costs and effectively pass on price increases, alongside the revised full-year forecast.
Disclaimer: This article is for informational purposes only and does not constitute investment advice.
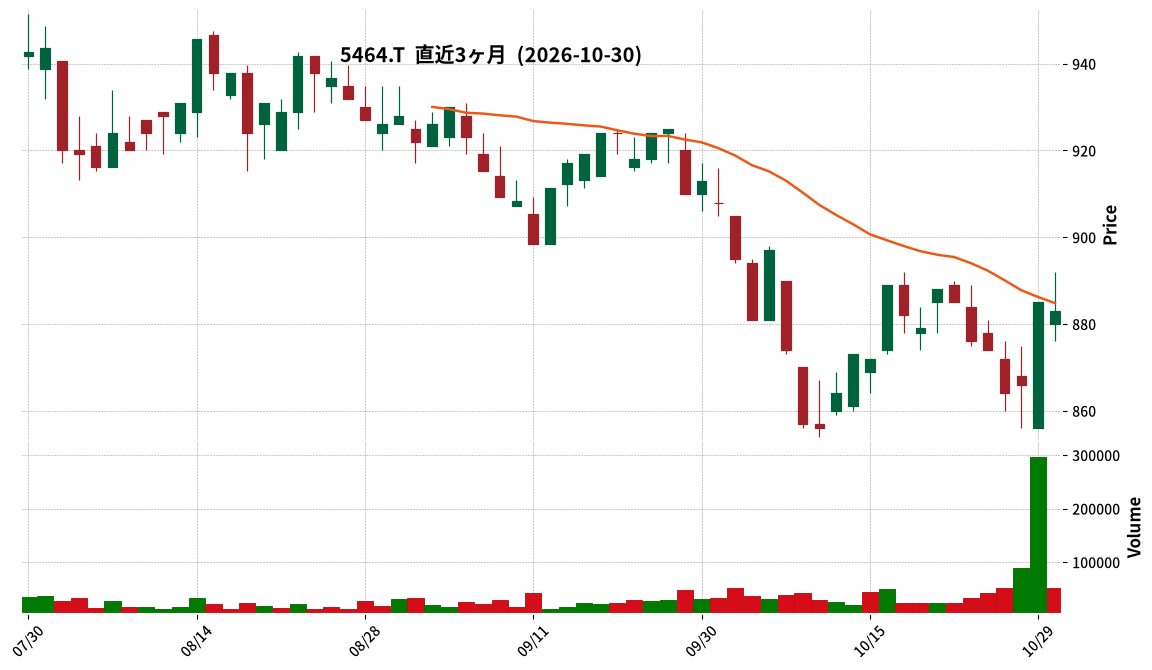
5464|モリ工業
883.0
▼ -0.23%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Mori Kogyo announced its consolidated financial results for the second quarter of the fiscal year ending March 2027 (interim period), covering April 1, 2026, to September 30, 2026.
- Net sales reached ¥21,901 million, marking a 1.3% increase compared to the prior interim period.
- Operating profit was ¥2,549 million, representing a significant increase of 23.3% year-on-year.
- Ordinary profit totaled ¥2,767 million (+20.4% YoY), and net profit attributable to parent company shareholders was ¥1,854 million (+16.6% YoY).
- Diluted earnings per share for the interim period stood at ¥48.82.
- The full-year dividend forecast for the fiscal year ending March 2027 remains unchanged at ¥34.00 per share (¥16.00 for Q2-end and ¥18.00 for year-end).
- The full-year consolidated earnings forecast is maintained: net sales of ¥44,300 million (+2.3% YoY), operating profit of ¥4,100 million (-6.4% YoY), ordinary profit of ¥4,600 million (-5.7% YoY), and net profit attributable to parent company shareholders of ¥3,200 million (-4.7% YoY), with EPS of ¥84.22.
- As of the end of the interim period, total assets were ¥75,521 million, net assets were ¥60,093 million, and the equity ratio was 79.5%.
- The Japan segment saw increased sales in Stainless Steel Pipes (¥12,354 million), Stainless Steel Bars (¥5,036 million), and Steel Pipes (¥2,775 million). The Indonesia segment also reported increased sales of ¥958 million (+8.0% YoY) and increased operating profit.
🤖 AI Perspective
Mori Kogyo demonstrated strong performance in Q2 FY2027, achieving an increase in both sales and profits, with operating profit notably rising by 23.3% year-on-year. This growth appears to be driven by improved sales prices, enhanced productivity, and cost reduction efforts, alongside solid contributions from key divisions in Japan and the Indonesia segment. However, the unchanged full-year profit forecast, which anticipates a decline compared to the previous fiscal year, may warrant attention from investors regarding the latter half of the fiscal year.
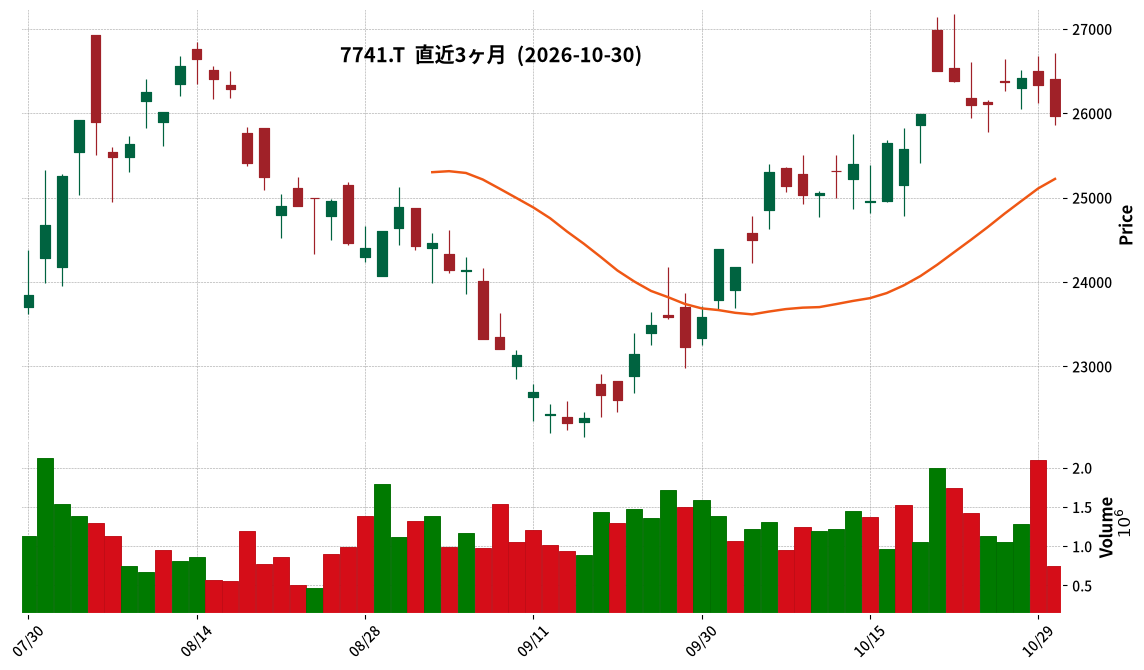
7741|HOYA
25965.0
▼ -1.39%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- HOYA Corporation reported consolidated revenue of ¥515,895 million for the first half of FY2027 (ended September 30, 2026), marking a 13.4% increase compared to the prior-year period.
- Operating profit reached ¥173,431 million (up 31.6% year-on-year), profit before tax was ¥177,586 million (up 27.5%), and profit attributable to owners of the parent was ¥136,500 million (up 27.3%).
- Basic earnings per share for the interim period stood at ¥408.44.
- The Life Care segment recorded revenue of ¥308,154 million (up 8.5% year-on-year) and segment profit of ¥62,569 million (up 24.8%).
- For the full fiscal year 2027, the company forecasts consolidated revenue of ¥1,043,000 million (up 10.1% year-on-year), while profit forecasts remain undetermined.
🤖 AI Perspective
HOYA’s interim results demonstrate robust growth across revenue and all profit metrics, indicating solid business expansion. The improved profitability of the Life Care segment, combined with increased revenue from the high-margin Information & Communication segment, likely contributed significantly to the overall profit growth. Investors may also note the early adoption of IFRS 18, which has impacted year-on-year comparisons for certain figures like operating profit.
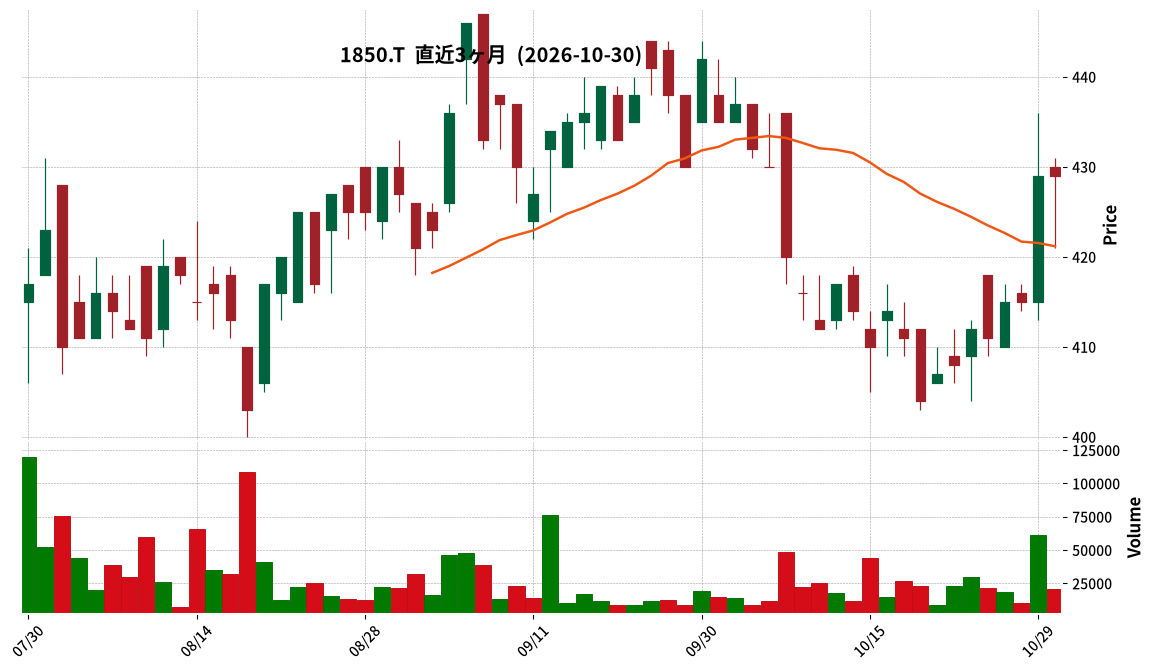
1850|南海辰村建設
429.0
▲ +0.00%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Nankai Tatemurakensetsu reported consolidated net sales of ¥21,440 million for the second quarter of FY2027, a 4.4% decrease compared to the same period last year.
- Consolidated operating profit for the same interim period was ¥1,162 million, an increase of 1.7% year-on-year.
- Net profit attributable to owners of parent for the interim period was ¥771 million, a 1.6% decrease from the prior year’s interim period.
- The full-year consolidated earnings forecast for FY2027 remains unchanged, projecting net sales of ¥52,700 million, operating profit of ¥2,500 million, ordinary profit of ¥2,410 million, and net profit attributable to owners of parent of ¥1,640 million.
- As of the end of the interim period, total assets stood at ¥33,253 million, net assets at ¥19,946 million, and the equity ratio at 60.0%.
🤖 AI Perspective
While net sales declined, the increase in operating profit could suggest improved operational efficiency or effective cost management within the company. The construction segment, despite a decrease in sales, saw an increase in segment profit due to improved profitability of ongoing projects, which is worth noting. The reaffirmation of the full-year forecast indicates management’s current outlook on future performance.
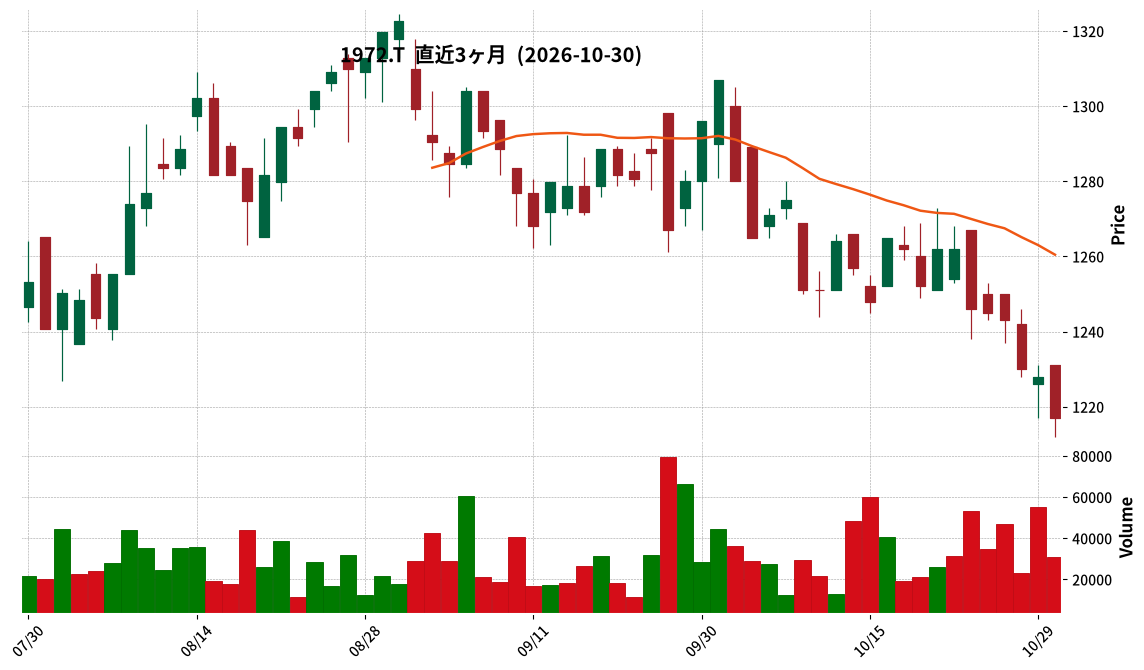
1972|三晃金
1217.0
▼ -0.90%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Sanko Metal Industrial announced on October 30, 2026, a revision to its full-year earnings forecast for the fiscal year ending March 2027.
- Net sales have been revised down by ¥500 million (△1.1%) from the previous forecast of ¥47,000 million to ¥46,500 million.
- Conversely, operating profit has been revised up by ¥70 million (2.0%) from ¥3,500 million to ¥3,570 million, ordinary profit by ¥100 million (2.8%) from ¥3,600 million to ¥3,700 million, and net income by ¥40 million (1.6%) from ¥2,450 million to ¥2,490 million.
- The reason for the sales revision down is attributed to delays in pre-processes and adverse weather affecting construction sales, while the increase in ordinary profit is due to improved sales profit margin, reduced selling, general and administrative expenses, and increased interest income.
- Concurrently, the company decided to increase the interim dividend for the fiscal year ending March 2027 by ¥1 per share, from the previously forecast ¥30.00 to ¥31.00. This brings the annual dividend forecast to ¥65.00 per share.
🤖 AI Perspective
While net sales have been revised downwards, the upward revision of profit items suggests potential improvements in profitability. Specifically, the enhanced sales profit margin and reduction in selling, general, and administrative expenses appear to have offset the impact of decreased sales, contributing to increased profits. Furthermore, the increase in interim dividend aligns with the company’s policy of profit distribution based on performance, indicating a commitment to shareholder returns.
2883|大冷
1958.0
▲ +0.15%
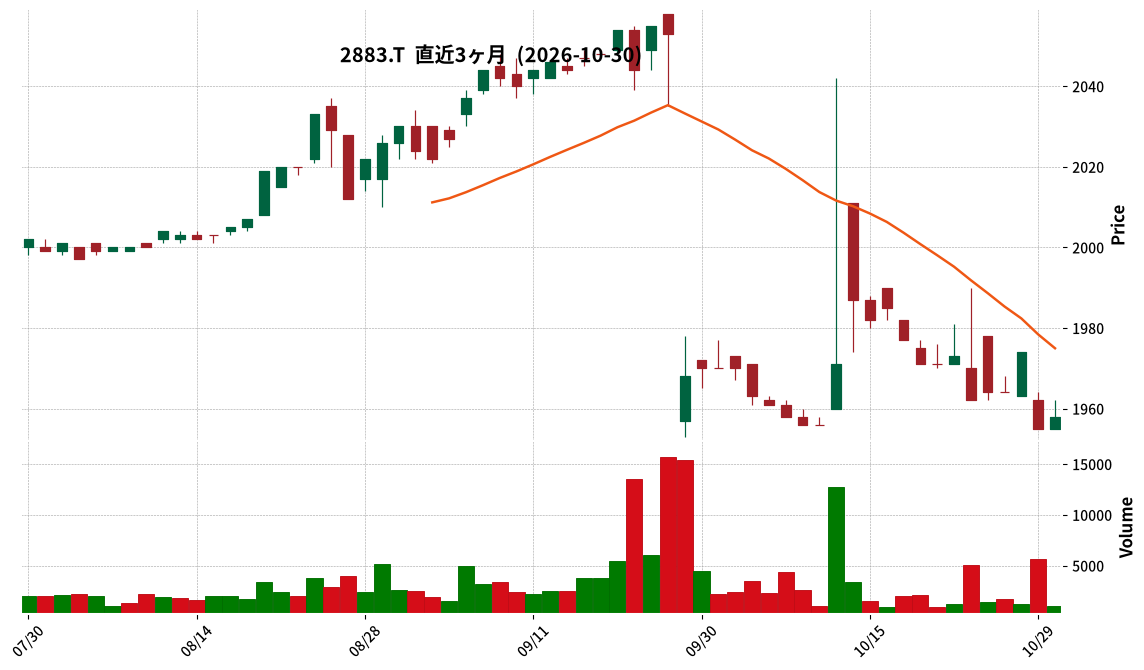
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- For the second quarter (interim period) of the fiscal year ending March 2027, net sales were ¥12.46 billion, a 1.4% increase from the prior year’s interim period.
- Operating profit was ¥139 million, a 47.4% decrease compared to the prior year’s interim period.
- Ordinary profit was ¥126 million, a 54.1% decrease compared to the prior year’s interim period.
- Interim net income was ¥85 million, a 55.8% decrease compared to the prior year’s interim period.
- Sales for the boneless fish business increased by 4.7% to ¥4,492,371 thousand, and the meat business sales increased by 5.8% to ¥1,306,096 thousand.
- The full-year earnings forecast (Net sales ¥25.2 billion, Operating profit ¥780 million, Ordinary profit ¥780 million, Net income ¥525 million) remains unchanged.
- The full-year dividend forecast is maintained at ¥60 per share.
🤖 AI Perspective
While sales increased, the significant decline in profits is attributed to delays in sales price revisions and an increase in sales of lower-margin products. It is noteworthy that specific segments like boneless fish and meat businesses achieved sales growth, indicating varied performance across operations. With the full-year forecasts and dividend unchanged, the focus for investors may shift to the company’s ability to improve profitability in the second half of the fiscal year.
4045|東亜合
1824.5
▼ -0.14%
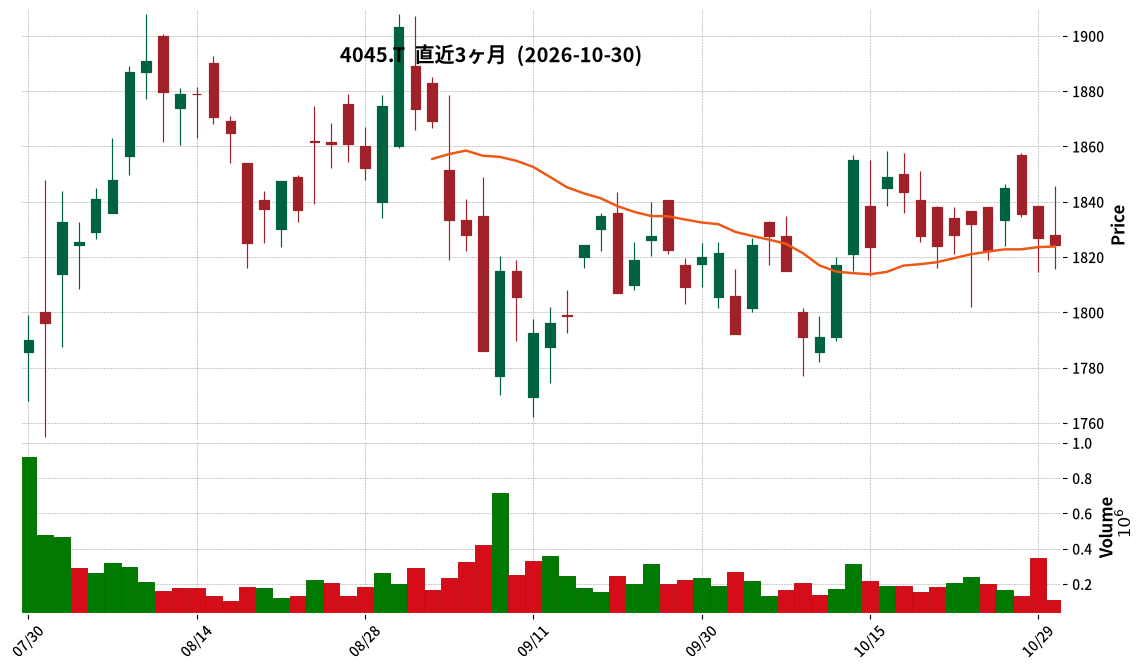
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Toagosei Co., Ltd. announced its consolidated financial results for the third quarter of the fiscal year ending December 2026 on October 30, 2026.
- For the nine months ended September 30, 2026, consolidated net sales were ¥125,461 million (up 4.7% year-on-year), operating income was ¥11,787 million (up 11.1%), ordinary income was ¥12,098 million (up 8.5%), and net income attributable to owners of parent was ¥8,927 million (up 11.6%).
- By segment, the Polymer/Oligomer business reported sales of ¥29,907 million (up 12.4% YoY) and operating income of ¥3,550 million (up 60.7%). The Adhesives business posted sales of ¥11,026 million (up 9.7% YoY) and operating income of ¥422 million (up 95.4%). The High-Performance Materials business achieved sales of ¥8,661 million (up 16.5% YoY) and operating income of ¥1,420 million (up 91.7%). The Resin Processed Products business recorded sales of ¥22,042 million (up 6.5% YoY) and operating income of ¥2,906 million (up 47.1%).
- The full-year consolidated earnings forecast remains unchanged, projecting net sales of ¥170,000 million (up 4.7% from prior year), operating income of ¥15,500 million (up 9.3%), ordinary income of ¥16,300 million (up 8.2%), and net income attributable to owners of parent of ¥11,800 million (down 7.6%).
- The forecasted annual dividend for the fiscal year ending December 2026 is ¥72.00 per share, comprising an interim dividend of ¥36.00 and a year-end dividend of ¥36.00.
🤖 AI Perspective
The robust growth in net sales and profit figures for the first three quarters, particularly driven by key segments such as Polymer/Oligomer and High-Performance Materials, suggests effective strategic execution. Investors may find it noteworthy to monitor the progress towards the full-year forecast, especially concerning the projected year-on-year decline in net income attributable to owners of parent, despite overall strong segmental performance.
4220|リケンテクノス
2445.0
▼ -4.31%
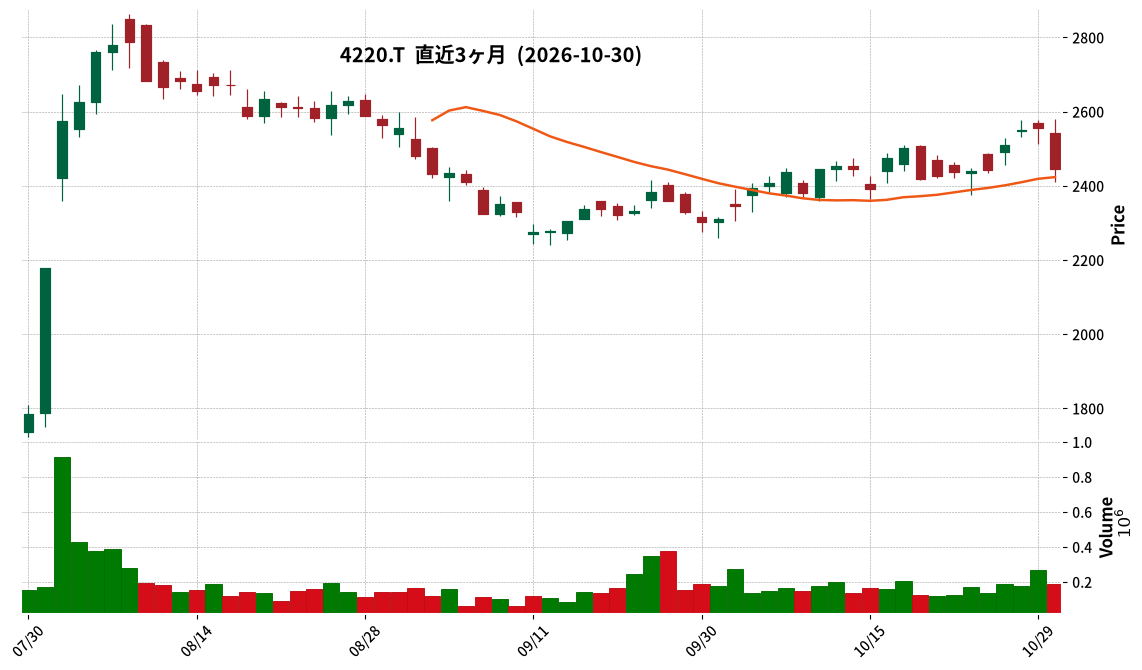
📎 Source:リケンテクノス Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Riken Technos reported consolidated net sales of JPY 72,509 million for the second quarter of the fiscal year ending March 2027, representing a 10.6% increase year-on-year.
- Operating income reached JPY 8,688 million (up 57.0% year-on-year), ordinary income JPY 8,663 million (up 57.9%), and profit attributable to owners of parent JPY 6,233 million (up 80.1%).
- All segments—Transportation, Daily Life & Healthcare, Electronics, and Building & Construction—reported increases in both net sales and segment profit. The Electronics segment notably saw a 130.5% increase in profit year-on-year.
- The full-year consolidated earnings forecast for the fiscal year ending March 2027 has been revised upward, projecting net sales of JPY 145,500 million (up 10.7% from the previous fiscal year), operating income of JPY 15,500 million (up 35.9%), and profit attributable to owners of parent of JPY 10,000 million (up 32.1%).
- The dividend forecast has also been revised, with an interim dividend of JPY 42.00 per share and a year-end dividend of JPY 47.00 per share, totaling JPY 89.00 for the fiscal year ending March 2027.
🤖 AI Perspective
The robust growth across all key financial metrics, especially the significant 57.0% increase in operating income, suggests effective cost management and successful pricing strategies, potentially including the pass-through of higher raw material costs and increased overseas sales. The upward revision of the full-year earnings forecast and the increased annual dividend forecast may indicate management’s confidence in the company’s sustained performance and future outlook. These factors could be points of interest for investors evaluating the company’s financial health and shareholder returns.
6888|アクモス
511.0
▼ -0.78%
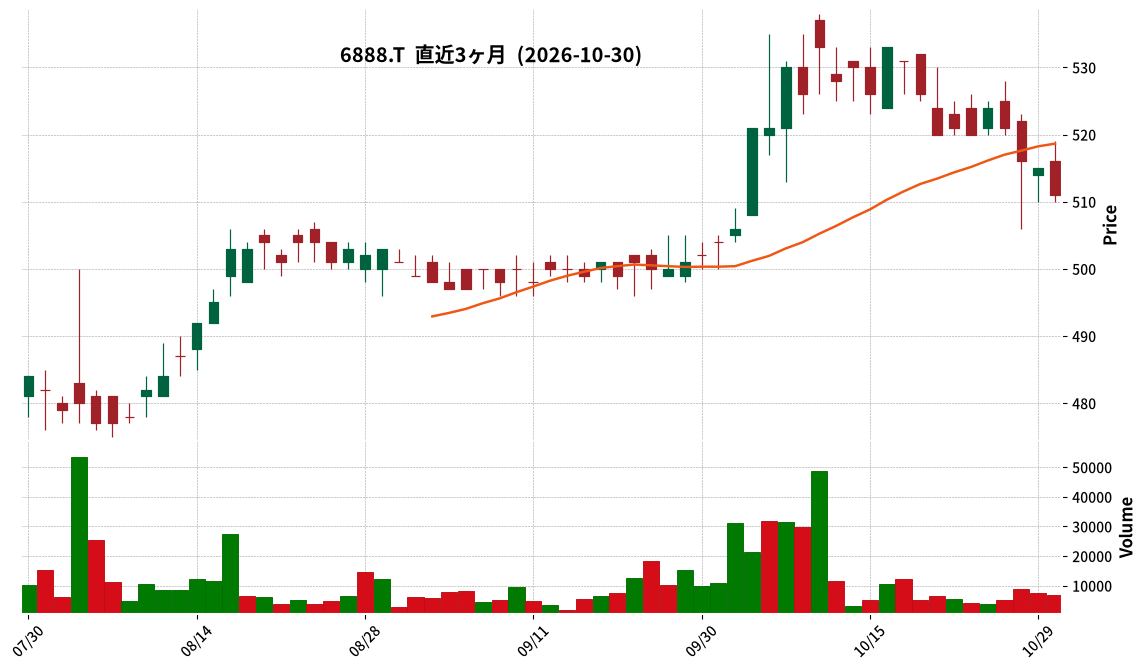
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Acmos announced its consolidated financial results for the first quarter of the fiscal year ending June 2027 (July 1, 2026 – September 30, 2026).
- Net sales reached ¥1,608 million, marking a 20.4% increase compared to the same quarter of the previous year.
- Operating profit was ¥4 million, a turnaround from an operating loss of ¥30 million in the prior year’s comparable quarter.
- Ordinary profit was ¥12 million, also a turnaround from an ordinary loss of ¥32 million in the prior year’s comparable quarter.
- Net loss attributable to owners of the parent was ¥26 million, a reduction from a net loss of ¥39 million in the prior year’s comparable quarter.
- The full-year consolidated earnings forecast (Net sales: ¥8,000 million, Operating profit: ¥700 million, Ordinary profit: ¥700 million, Net profit attributable to owners of the parent: ¥430 million) remains unchanged.
- Total consolidated assets were ¥5,464 million, net assets were ¥3,421 million, and the equity ratio was 57.9%.
🤖 AI Perspective
Acmos’s Q1 FY2027 results show a significant increase in net sales and a return to profitability at the operating and ordinary income levels, which may be a key point for investors. This performance appears to be primarily driven by contributions from the fully acquired subsidiary, Systems Service Inc., and growth in the IT Solutions and IT Services segments. While the net loss attributable to owners of the parent continues, the reduction in its magnitude could indicate a positive trend toward improved profitability in future periods.
7218|田中精密
1140.0
▲ +2.33%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Tanaka Seimitsu resolved on October 30, 2026, to revise its consolidated earnings forecast for the fiscal year ending March 2027, as well as to amend its interim and year-end dividend forecasts (increased dividends).
- The consolidated earnings forecast for FY2027 has been revised upwards: net sales from ¥45.3 billion to ¥47.2 billion, operating profit from ¥1.8 billion to ¥2.4 billion, ordinary profit from ¥1.9 billion to ¥2.6 billion, and profit attributable to owners of parent from ¥2.1 billion to ¥2.4 billion.
- The reason for the revision is that order intake in the parts manufacturing business has exceeded initial expectations.
- The interim dividend per share was increased by ¥2 from the previous forecast of ¥17 to ¥19 (record date: September 30, 2026).
- The year-end dividend forecast per share was also increased by ¥2 from the previous forecast of ¥17 to ¥19, resulting in an expected annual dividend of ¥38.
🤖 AI Perspective
Tanaka Seimitsu’s upward revision of its earnings forecast suggests robust performance in its core parts manufacturing business. The increase in annual dividends, aligning with improved profitability, may indicate the company’s commitment to shareholder returns. This move could also reflect the company’s efforts towards establishing a stable management foundation and achieving sustainable growth.
8076|カノークス
2006.0
▼ -0.45%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Canox Co., Ltd. announced its Consolidated Financial Results for the Second Quarter of the Fiscal Year Ending March 31, 2027 (Japanese GAAP) on October 30, 2026.
- For the interim period (April 1, 2026 – September 30, 2026), consolidated results showed net sales of JPY 83,014 million (up 6.7% year-on-year), operating profit of JPY 1,227 million (down 5.7%), ordinary profit of JPY 1,491 million (down 1.1%), and net profit attributable to owners of parent of JPY 1,017 million (down 2.7%).
- Diluted earnings per share for the interim period were JPY 103.70.
- As of the end of the interim period, total assets were JPY 81,626 million, net assets were JPY 33,864 million, and the equity ratio was 41.5%.
- An interim dividend of JPY 53.00 (forecast) is planned for the fiscal year ending March 31, 2027, with a full-year dividend forecast of JPY 106.00.
- The full-year consolidated earnings forecast for FY2027 remains unchanged from the most recently announced forecast, projecting net sales of JPY 169,852 million (up 7.0%), operating profit of JPY 2,725 million (up 8.6%), ordinary profit of JPY 3,000 million (up 1.2%), and net profit attributable to owners of parent of JPY 2,059 million (down 2.1%), with diluted EPS of JPY 215.02.
- During this interim period, Ogawa Masanori Shoten Co., Ltd. was newly included in the scope of consolidation.
🤖 AI Perspective
Canox’s interim results show revenue growth but a decline in various profit metrics, which may reflect the uncertain economic conditions in Japan and external factors such as Middle East tensions and rising prices. The inclusion of Ogawa Masanori Shoten Co., Ltd. in the consolidated scope indicates a strategic move to expand business in the Tohoku area. The improvement in the equity ratio suggests a strengthening of the company’s financial position.
5994|ファインシンター
908.0
▼ -1.09%
📎 Source:ファインシンター Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Finesinter Co., Ltd. released its Q2 FY2027 earnings presentation materials on October 30, 2026.
- For the second quarter of fiscal year 2027, consolidated results showed net sales of JPY 23.119 billion (up 0.3% year-on-year), operating profit of JPY 0.241 billion (down 79.9% year-on-year), ordinary profit of JPY 0.026 billion (down 97.4% year-on-year), and net profit of JPY 0.324 billion (down 64.9% year-on-year).
- By segment, Automotive Sintered Parts reported sales of JPY 21.158 billion (up 1.0% year-on-year), and Hydraulic Equipment Products sales were JPY 0.998 billion (up 11.5% year-on-year), while Railway Sintered Parts sales decreased to JPY 0.956 billion (down 19.5% year-on-year).
- The full-year forecast for fiscal year 2027 has been revised from the initial forecast disclosed on May 14, 2026. The revised forecast includes net sales of JPY 46.0 billion (initially JPY 44.5 billion), operating profit of JPY 0.8 billion (initially JPY 1.2 billion), ordinary profit of JPY 0.36 billion (initially JPY 0.8 billion), and net profit of JPY 0.14 billion (initially JPY 0.5 billion).
- Reasons for the full-year forecast revision include a delay in passing on higher raw material and energy costs, with some transfers deferred to the next fiscal year, and increased expenses related to the cessation of operations at the U.S. subsidiary as part of the medium-term management plan.
🤖 AI Perspective
Finesinter’s Q2 FY2027 results show a slight increase in revenue but a significant decline in profits. This appears to be primarily driven by the delay in price adjustments for surging raw material and energy costs, alongside one-off expenses related to the discontinuation of the U.S. subsidiary’s operations. The company’s ongoing global site reorganization, a key initiative under its medium-term management plan, may be worth monitoring as it aims to strengthen its profitability structure.
Disclaimer: This article is for informational purposes only and does not constitute investment advice.
2908|フジッコ
1594.0
▲ +1.59%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Consolidated net sales for the first half of FY2027 were ¥27,860 million, a 0.4% increase from the prior year’s same period.
- Consolidated operating profit reached ¥773 million, marking a significant 52.7% increase year-over-year.
- Consolidated ordinary profit was ¥988 million, up 38.5% compared to the previous interim period.
- Net income attributable to owners of parent decreased by 14.4% to ¥653 million.
- Basic earnings per share for the interim period stood at ¥22.94.
- The full-year consolidated forecast remains unchanged, projecting net sales of ¥57,000 million (up 2.6%), operating profit of ¥1,500 million (up 2.3%), ordinary profit of ¥1,800 million (down 5.3%), and net income attributable to owners of parent of ¥1,240 million (down 13.2%).
🤖 AI Perspective
While net sales saw a slight increase, the substantial growth in operating and ordinary profits suggests effective cost control and successful pricing strategies, particularly for yogurt and kelp products. The decline in net income attributable to owners of parent is noted to be primarily due to increased income taxes resulting from higher taxable income. Investors may want to monitor whether the company can maintain profit growth in the second half of the fiscal year, in line with its unchanged full-year forecasts.
7475|アルビス
3770.0
▲ +0.00%
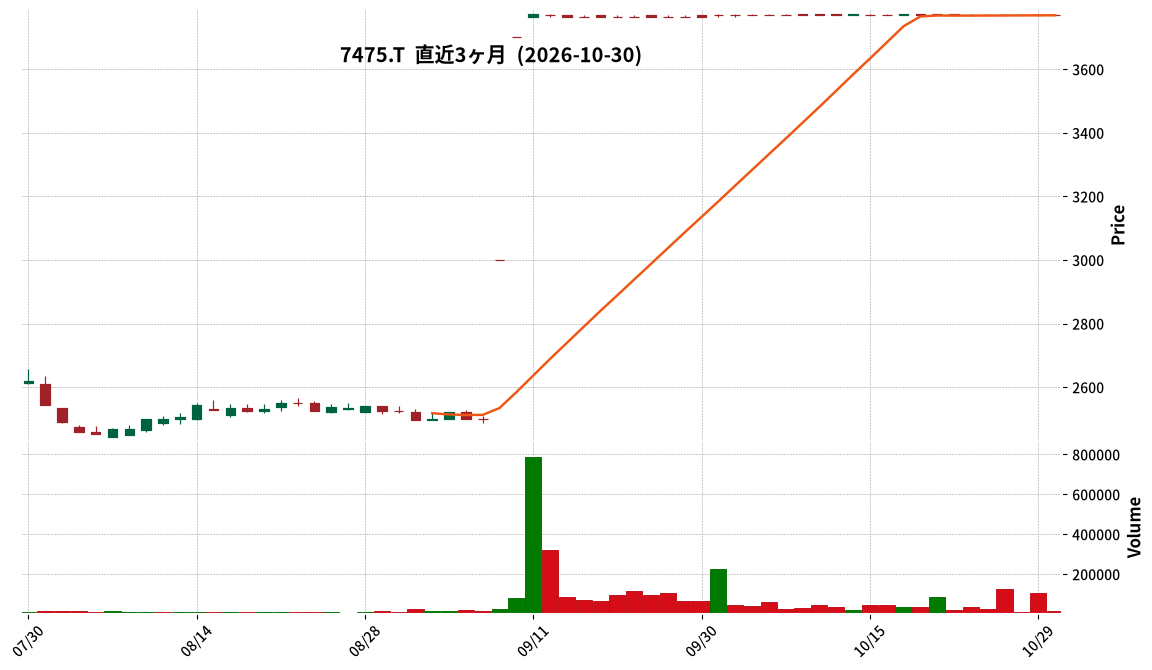
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Albis Co., Ltd. announced its consolidated financial results for the second quarter (interim period) of the fiscal year ending March 2027.
- Operating revenue was ¥49,899 million, a decrease of 0.7% compared to the same interim period of the previous year.
- Operating income was ¥684 million (down 4.7% YoY), ordinary income was ¥814 million (down 17.7% YoY), and net income attributable to owners of parent was ¥532 million (down 7.7% YoY).
- Diluted earnings per share for the interim period were ¥63.74.
- The full-year consolidated earnings forecast remains unchanged: operating revenue of ¥102,147 million (up 1.2% YoY), operating income of ¥1,970 million (down 8.6% YoY), ordinary income of ¥2,207 million (down 8.7% YoY), and net income attributable to owners of parent of ¥1,167 million (down 11.9% YoY).
🤖 AI Perspective
Albis’s Q2 FY2027 results show a year-over-year decline across operating revenue and various profit metrics, which may suggest the impact of persistent consumer frugality, intensified market competition, and increased operating costs. Despite these interim declines, the company has not revised its full-year earnings forecast. Investors may find it worthwhile monitoring how the company’s cost management and sales strategies evolve in the latter half of the fiscal year to align with the unrevised annual guidance.
1941|中電工
5130.0
▼ -1.91%
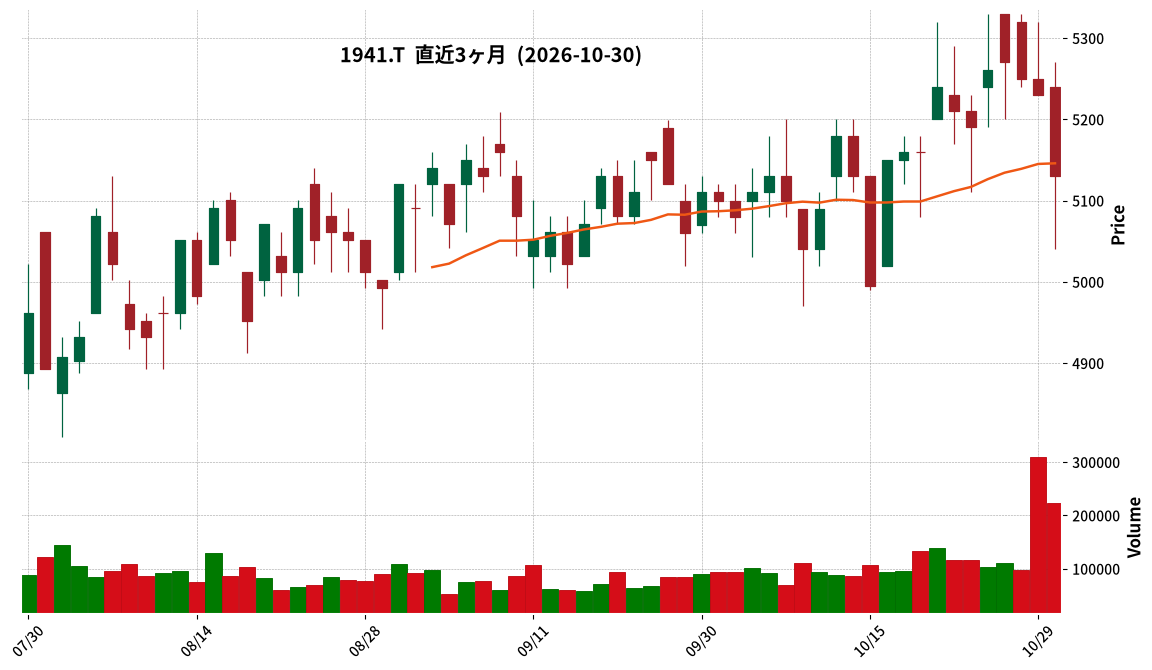
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Chudenko announced its consolidated financial results for the second quarter of the fiscal year ending March 2027.
- Consolidated net sales reached ¥106.376 billion (up 11.1% year-on-year), operating profit was ¥13.197 billion (up 24.7%), ordinary profit was ¥13.846 billion (up 26.4%), and net profit attributable to owners of parent was ¥8.771 billion (up 20.3%).
- The full-year consolidated earnings forecast has been revised upwards: net sales to ¥257.0 billion (up 4.9% from previous forecast), operating profit to ¥31.0 billion (up 14.8%), ordinary profit to ¥34.3 billion (up 16.3%), and net profit attributable to owners of parent to ¥22.8 billion (up 15.7%).
- The annual dividend forecast has been revised from ¥135 to ¥150, with the year-end dividend forecast increased from ¥70 to ¥80.
- A resolution for a share buyback was approved at the Board of Directors meeting held on October 30, 2026.
🤖 AI Perspective
The increase in sales and profits for the interim period is attributed to growth in indoor electrical work and HVAC work, alongside thorough cost management, improved construction efficiency, and overall company-wide cost reductions. The upward revision of the full-year consolidated earnings forecast reflects these same factors. The increased dividend forecast and the resolution for a share buyback may suggest a commitment to shareholder returns.
4015|G-ペイクラウドHD
526.0
▼ -1.68%
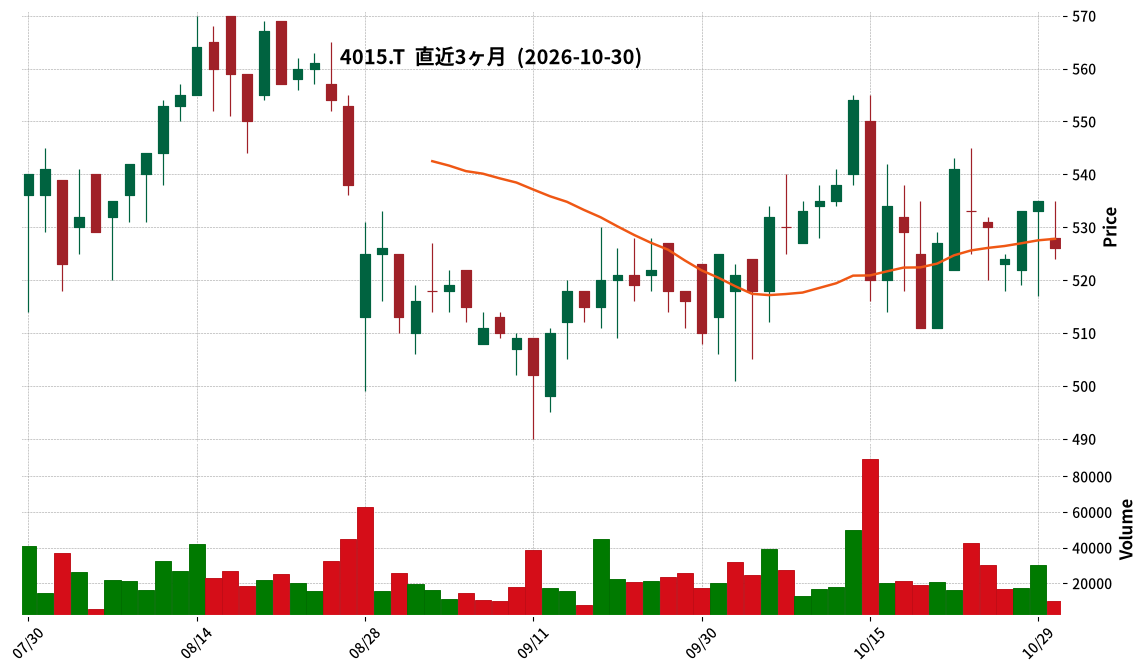
📎 Source:G-ペイクラウドHD Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- G-PayCloud HD announced on October 30, 2026, a “Correction to a part of the ‘Full-Year Financial Results Briefing Material for the Fiscal Year Ending August 2026’.”
- The correction pertains to the “Full-Year Financial Results Briefing Material for the Fiscal Year Ending August 2026” originally disclosed on October 15, 2026.
- The reason for the correction is that errors were discovered in some parts of the stated content after the document’s submission.
- The corrected section is detailed on page 16 (P16) of the financial results briefing material, showing both the uncorrected and corrected versions.
4463|日華化学
1936.0
▼ -1.83%
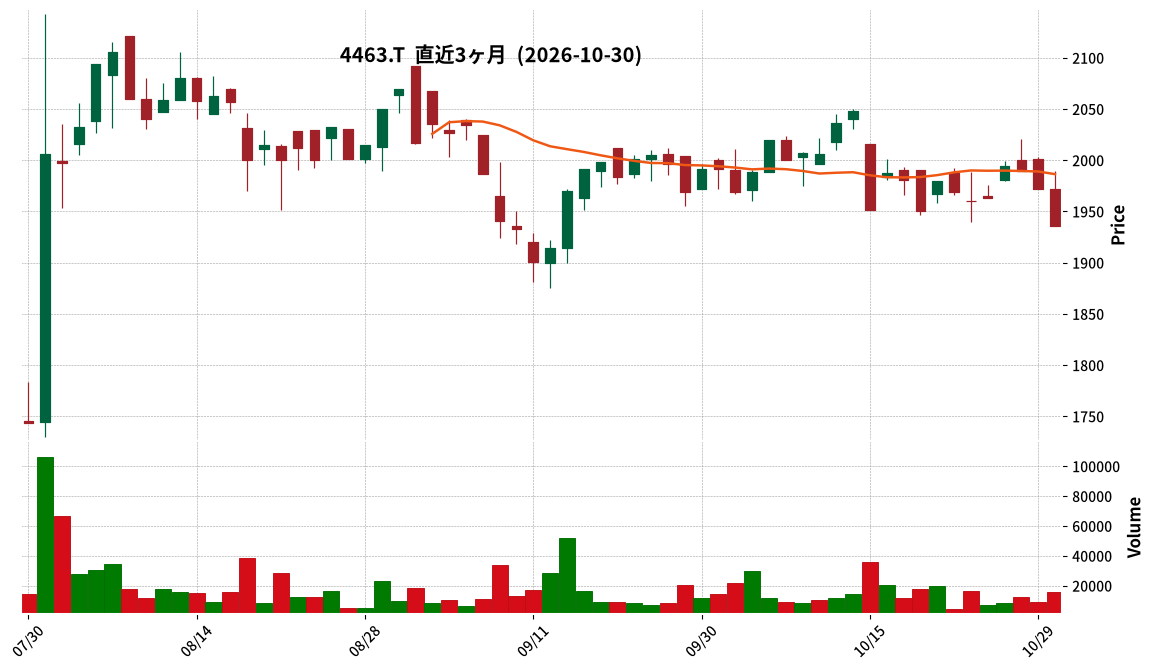
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Nicca Chemical Co., Ltd. has announced its consolidated financial results for the third quarter of the fiscal year ending December 2026.
- For the nine months ended September 30, 2026 (January 1, 2026 to September 30, 2026), consolidated net sales were ¥47,281 million (+14.7% YoY), operating profit was ¥4,243 million (+46.2% YoY), ordinary profit was ¥4,291 million (+55.5% YoY), and net income attributable to owners of parent was ¥3,084 million (+91.2% YoY).
- By segment, the Chemical Products business reported net sales of ¥35,953 million (+22.0% YoY) and segment profit of ¥4,857 million (+63.0% YoY), marking record highs for both in a third quarter period.
- The Cosmetics business recorded net sales of ¥10,765 million (-5.1% YoY) and segment profit of ¥951 million (-33.5% YoY).
- The full-year consolidated earnings forecast for the fiscal year ending December 2026 remains unchanged from the most recently announced forecast, projecting net sales of ¥64,000 million (+14.9% YoY) and net income attributable to owners of parent of ¥3,800 million (+59.4% YoY).
🤖 AI Perspective
Nicca Chemical’s Q3 FY2026 results demonstrate significant growth across sales and all profit metrics, primarily driven by the robust performance of its Chemical Products business. This segment’s success appears to be fueled by new business acquisitions for high value-added products, as well as efforts in raw material substitution and price revisions. In contrast, the Cosmetics business experienced a decline in both revenue and profit, which could be attributed to the impact of the domestic economy and market deterioration, highlighting differing performances across business segments.
4531|有機薬
356.0
▼ -1.11%
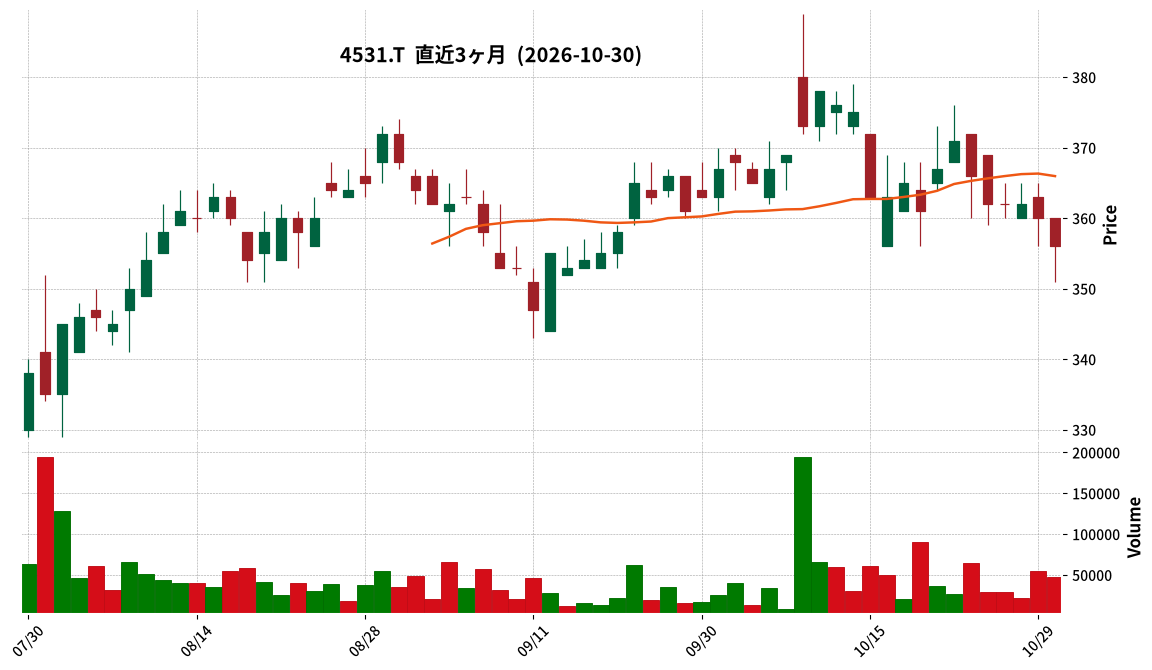
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Yuki Gosei Kogyo announced its interim financial results for the second quarter of the fiscal year ending March 2027.
- Interim sales totaled ¥8,739 million, marking an 11.7% increase year-on-year. The company reported an operating loss of ¥23 million (compared to an operating profit of ¥262 million in the previous interim period) and an ordinary loss of ¥48 million (compared to an ordinary profit of ¥227 million previously).
- Net income for the interim period was ¥331 million, a significant 101.0% increase from the prior year.
- By product segment, Amino Acid related sales increased to ¥3,272 million (+34.3%) and Chemical Products related sales rose to ¥3,779 million (+26.7%), while Pharmaceutical related sales decreased to ¥1,687 million (-29.8%).
- The full-year earnings forecast for the fiscal year ending March 2027 has been revised to: Sales ¥17,700 million (+14.6% YoY), Operating Profit ¥550 million (+43.3% YoY), Ordinary Profit ¥500 million (+64.8% YoY), and Net Income ¥600 million (+91.5% YoY).
🤖 AI Perspective
The interim results show a solid increase in sales, yet a shift to operating and ordinary losses. This could be attributed to rising raw material costs and ongoing challenges in improving profitability for electronic materials products, as stated in the IR report. Conversely, the substantial rise in net income for the interim period may suggest the impact of other financial factors such as tax effects. The upward revision of the full-year earnings forecast could indicate the company anticipates a recovery in profitability during the second half of the fiscal year.
4968|荒川化学
2153.0
▼ -0.23%
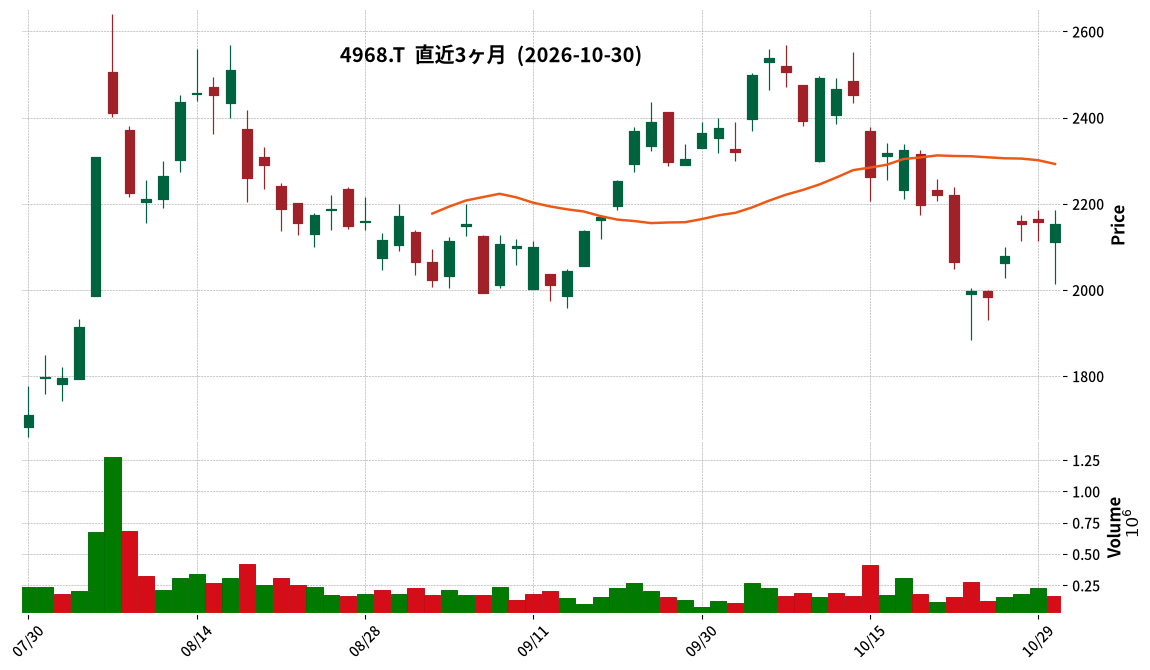
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Arakawa Chemical Industries, Ltd. announced on October 30, 2026, an upward revision to its consolidated performance forecasts for the second quarter (interim) and full fiscal year ending March 2027.
- For the second quarter of FY2027 (April 1 to September 30, 2026), consolidated sales are revised from ¥43,000 million to ¥46,500 million, and interim net income attributable to owners of the parent is revised from ¥1,000 million to ¥2,160 million.
- For the full fiscal year ending March 2027 (April 1, 2026 to March 31, 2027), consolidated sales are revised from ¥87,000 million to ¥94,000 million, and net income attributable to owners of the parent is revised from ¥2,250 million to ¥3,200 million.
- Reasons for the revision include expanding demand in semiconductor, generative AI, and data center related fields, strong sales of photo-curable resins and precision polishing agents for hard disks, a temporary demand increase due to the Middle East situation, and the permeation of price revisions reflecting soaring raw material costs.
- The annual dividend forecast for FY2027 has also been revised upward from the previous forecast of ¥55.00 per share (interim ¥27.50, year-end ¥27.50) to ¥70.00 per share (interim ¥35.00, year-end ¥35.00).
🤖 AI Perspective
This upward revision to the earnings forecast suggests that expanding demand in key product areas and progress in price pass-through have contributed to the company’s improved profitability. The emphasis on contributions to high-growth sectors such as semiconductors, generative AI, and data centers highlights the importance of these areas for future business development. The increased dividend forecast may indicate the company’s intention to return improved performance to shareholders.
6262|PEGASUS
537.0
▲ +8.92%
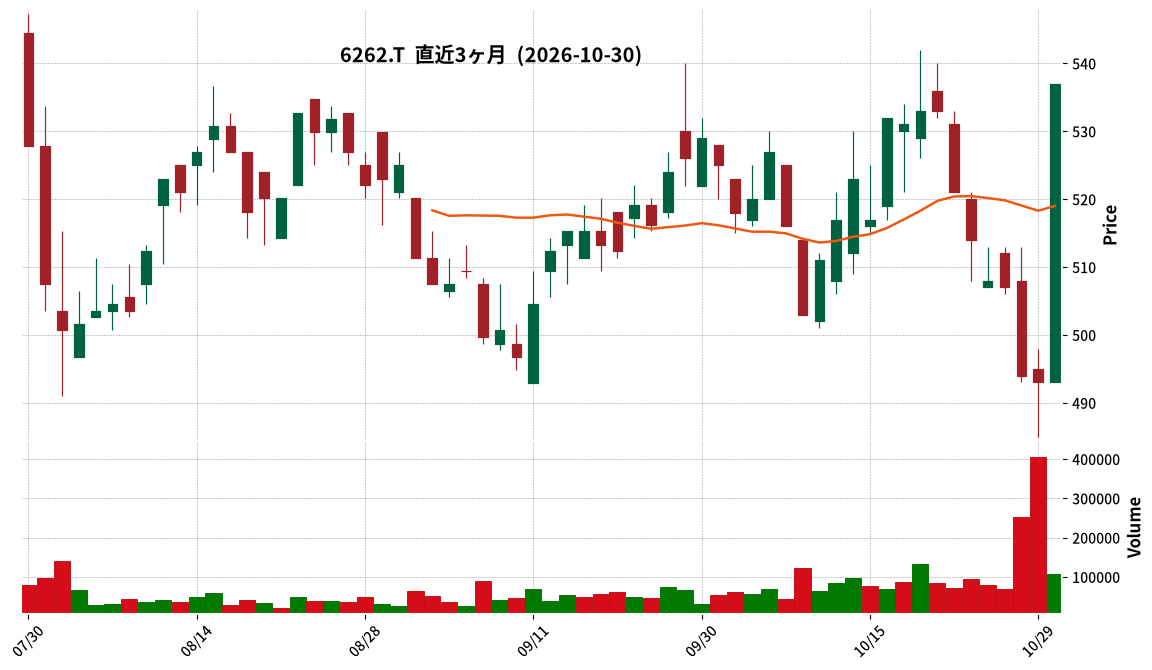
📎 Source:PEGASUS Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- PEGASUS reported net sales of ¥9,877 million for the second quarter (interim period) of the fiscal year ending March 2027, marking a 13.4% decrease compared to the same period in the previous year.
- Operating profit stood at ¥79 million (an 88.2% decrease year-on-year), and the company recorded an ordinary loss of ¥64 million, compared to an ordinary profit of ¥662 million in the prior interim period.
- Net loss attributable to owners of the parent company was ¥225 million (compared to a net profit of ¥414 million in the prior interim period), with interim net loss per share at △9.43 yen.
- Sales for the Apparel Machinery business were ¥6,031 million (down 20.6% year-on-year), while Automotive business sales were ¥3,845 million (up 0.8% year-on-year).
- The consolidated full-year earnings forecast for the fiscal year ending March 2027 has been revised, projecting net sales of ¥20,306 million (down 6.2% year-on-year), operating profit of ¥131 million (down 86.2% year-on-year), an ordinary loss of ¥122 million, and a net loss attributable to owners of the parent company of ¥435 million.
🤖 AI Perspective
The interim period results indicate a significant decline in revenue and profitability, with a substantial reduction or shift to loss across key profit metrics. The notable decrease in sales within the Apparel Machinery business appears to be a primary contributor to the overall performance. The downward revision of the full-year earnings forecast suggests that challenges in the business environment may persist, making future strategic developments and market conditions important to monitor.
6488|ヨシタケ
1013.0
▲ +1.20%
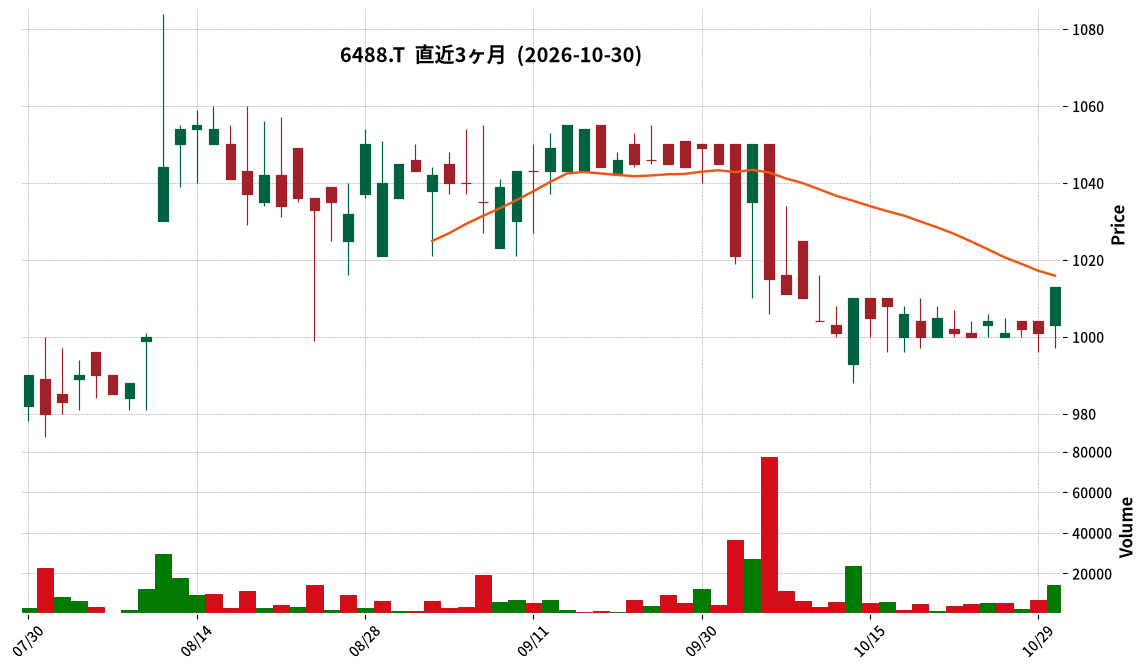
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Yoshitake Co., Ltd. announced its consolidated financial results for the second quarter (interim period) of the fiscal year ending March 2027.
- Net sales for the interim period amounted to 5,840 million yen, representing a 14.5% increase compared to the same period of the previous year.
- Operating profit reached 826 million yen, up 19.7% year-on-year.
- Net profit attributable to owners of parent significantly increased by 40.4% to 763 million yen.
- The full-year consolidated earnings forecast and the annual dividend forecast (36.00 yen at fiscal year-end) remain unchanged from the most recently published figures.
🤖 AI Perspective
The interim results show significant growth across key revenue items, with a particularly strong increase in net profit attributable to owners of the parent. This performance may suggest effective sales strategies both domestically and internationally, alongside production efficiency improvements. As the full-year forecast remains unchanged, investors might continue to monitor the company’s performance against these projections.
6557|G-AIAI
753.0
▲ +14.96%
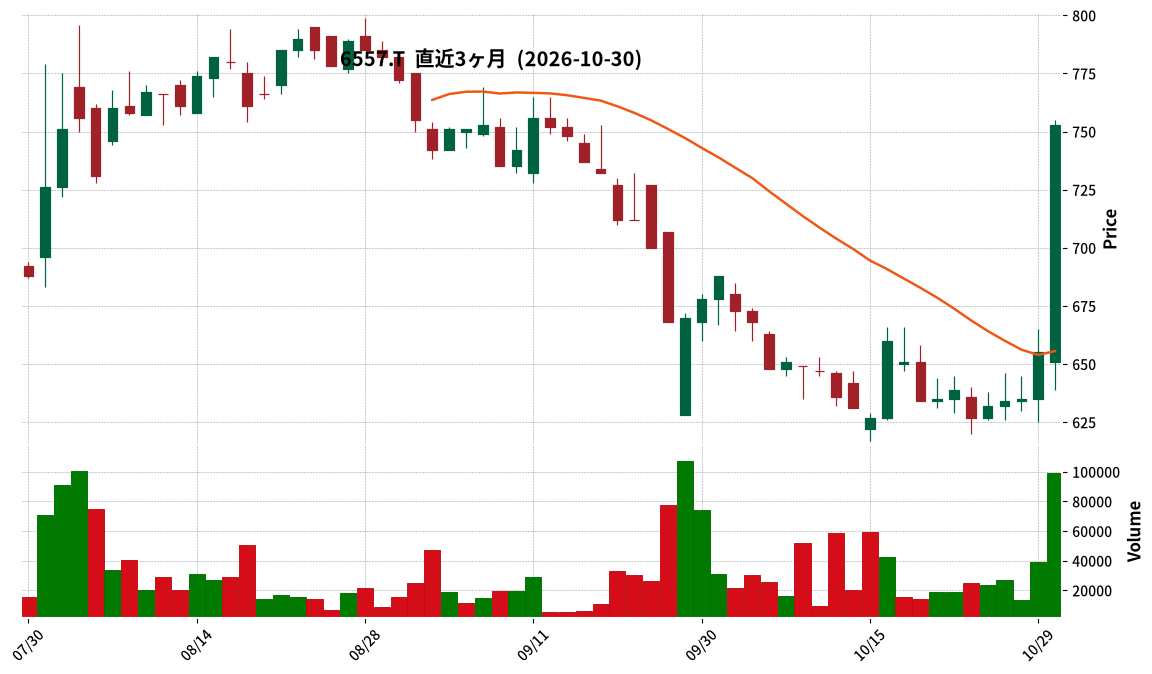
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- AIAI Group Corporation announced an upward revision to its consolidated full-year earnings forecast for the fiscal year ending March 2027 on October 30, 2026.
- The revised forecast includes net sales of ¥30,000 million (previously ¥26,000 million), EBITDA of ¥3,500 million (previously ¥2,700 million), operating profit of ¥2,000 million (previously ¥1,200 million), ordinary profit of ¥2,000 million (previously ¥1,000 million), and interim net profit attributable to parent company shareholders of ¥1,100 million (previously ¥700 million).
- Reasons for the revision include an increase in public prices for childcare facilities, improved occupancy rates, growth in therapy facilities, and the consolidation of Haby Inc. and its subsidiaries (Iris Inc. and Happiness Comes Inc.) as of September 1, 2026.
- These factors are expected to absorb increased personnel costs and amortization of goodwill resulting from the consolidation, leading to higher profit figures.
🤖 AI Perspective
This upward revision to earnings forecasts appears to be driven by both organic growth in existing businesses and inorganic growth through M&A. The significant 66.7% increase in operating profit from the previous forecast could be a key point of interest for investors. Furthermore, the accompanying announcement regarding a revised dividend forecast (first dividend payment) may draw attention to the company’s future shareholder return policies.
7947|エフピコ
2745.0
▼ -2.10%
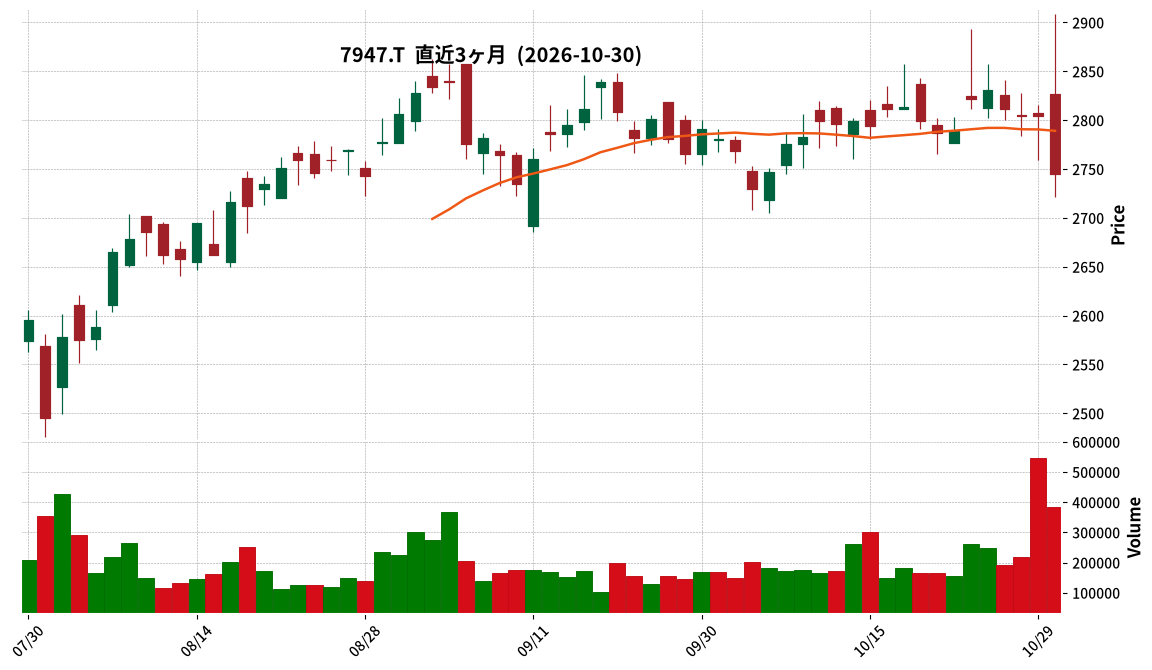
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- FPCO Corporation announced its consolidated earnings forecast for the fiscal year ending March 31, 2027 (April 1, 2026 to March 31, 2027).
- The consolidated earnings forecast includes net sales of ¥264.0 billion, operating profit of ¥25.8 billion, ordinary profit of ¥25.8 billion, net profit attributable to owners of parent of ¥17.2 billion, and basic earnings per share of ¥212.62.
- An increase in the interim dividend, with a record date of September 30, 2026, was resolved at the Board of Directors meeting held on October 30, 2026.
- The interim dividend per share will be ¥36.50, an increase of ¥5.00 from the previous forecast of ¥31.50.
- As a result, the full-year dividend for the fiscal year ending March 31, 2027, is projected to be ¥78.00 per share (interim: ¥36.50, year-end: ¥41.50).
- Reasons for the earnings forecast publication include the stable procurement of key raw materials and the comprehensive consideration of the penetration of product price revisions of over 20% implemented from June 1, 2026 shipments.
🤖 AI Perspective
The publication of the consolidated earnings forecast, which was previously undetermined, may suggest a clearer outlook for the company, potentially addressing some market uncertainties regarding future performance. The increase in the interim dividend, aligned with the company’s policy of progressive dividends targeting a consolidated payout ratio of 40%, could indicate a consistent commitment to shareholder returns. The impact of product price revisions and stabilized raw material procurement on future profitability is worth monitoring.
8119|三栄コーポ
766.0
▲ +0.66%
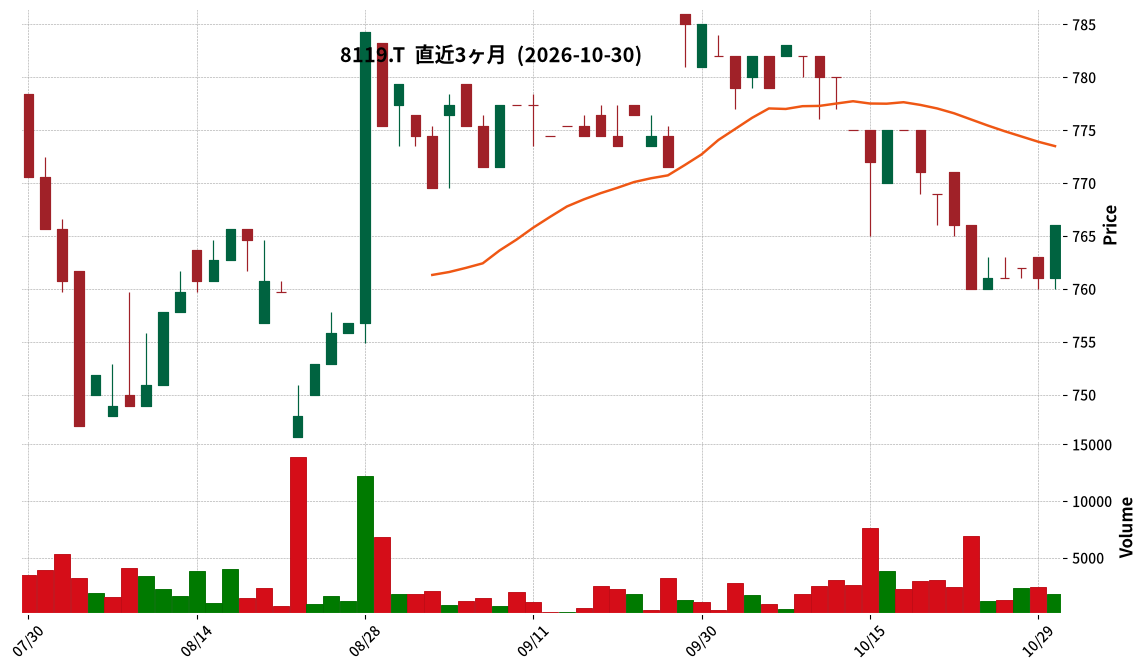
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Sanyei Corporation announced its consolidated financial results for the second quarter (interim period) of the fiscal year ending March 2027.
- Consolidated net sales amounted to ¥18,348 million (up 3.9% year-on-year), operating profit was ¥472 million (down 38.2% year-on-year), and ordinary profit was ¥486 million (down 39.9% year-on-year).
- Net income attributable to owners of parent increased significantly by 50.1% year-on-year to ¥685 million, primarily due to the recognition of deferred tax assets (income) following the liquidation of its consolidated subsidiary, Benefy Inc.
- By segment, the Furniture and Household Goods segment reported sales of ¥10,187 million (up 13.6% year-on-year) and segment profit of ¥650 million (up ¥117 million year-on-year). The Apparel and Fashion Accessories segment recorded sales of ¥5,830 million (down 9.0% year-on-year) and segment profit of ¥437 million (down ¥288 million year-on-year).
- The consolidated full-year earnings forecast for the fiscal year ending March 2027 has been revised to net sales of ¥36,500 million (up 0.5% year-on-year), operating profit of ¥1,000 million (down 2.6% year-on-year), ordinary profit of ¥1,000 million (down 13.5% year-on-year), and net income attributable to owners of parent of ¥900 million (up 58.3% year-on-year).
🤖 AI Perspective
Sanyei Corp.’s interim results for FY2027 show an increase in net sales but a decline in operating and ordinary profit. This could be attributed to a decrease in gross profit margin in certain business segments and inventory disposal sales related to the dissolution of a subsidiary. The significant increase in net income attributable to owners of parent appears to be driven by a one-off tax adjustment benefit, suggesting that investors may want to examine the underlying profitability trends. The revised full-year net income forecast also seems to incorporate similar one-time factors.
8803|平和不
2264.0
▲ +1.39%
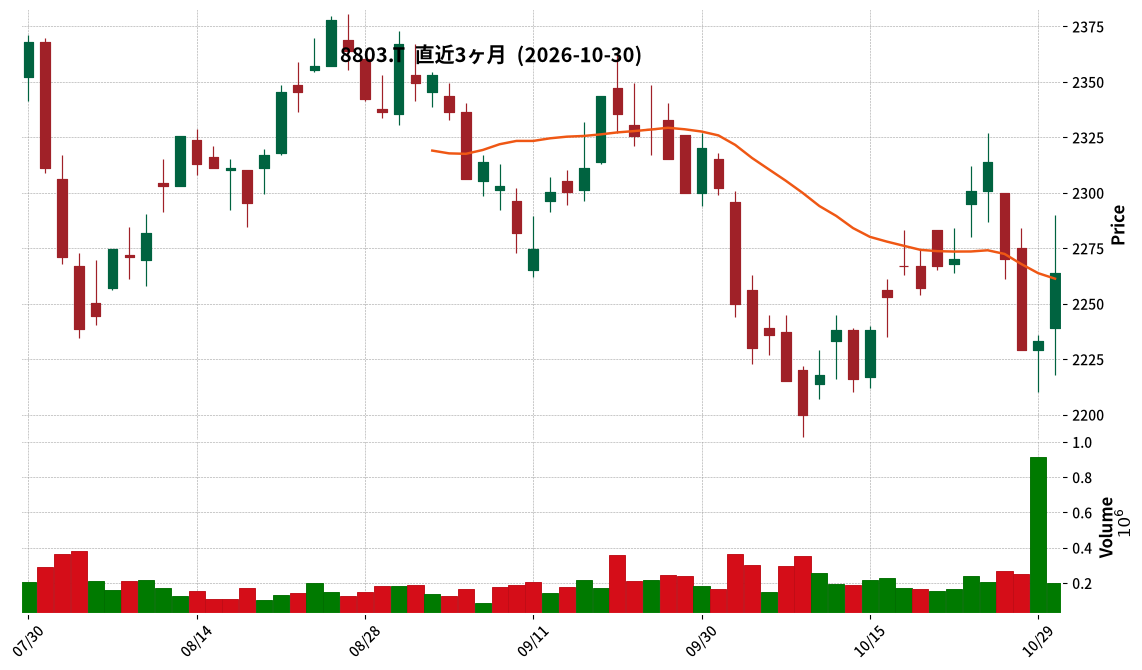
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Heiwa Real Estate Co., Ltd. announced the formulation of a new Mid-Term Management Plan “Bazukuri Transformation 5 (BX5),” covering the period from FY2027 to FY2031.
- The company significantly revised upwards its consolidated operating profit target in the long-term vision “WAY 2040” to consolidated business profit of over ¥45 billion (from the initial target of over ¥25 billion).
- Under the new Mid-Term Management Plan “BX5,” numerical targets for FY2031 include EPS of over ¥220, consolidated business profit of over ¥29 billion, and ROE of over 10%.
- The shareholder return policy for FY2027-2031 aims for a consolidated dividend payout ratio of approximately 50%, with progressive dividends starting from the FY2026 annual dividend per share of ¥103 (including a special dividend of ¥15).
- As one of its BX strategies, the company announced its first entry into overseas real estate business since its establishment, aiming to strengthen its business portfolio.
🤖 AI Perspective
The announcement of a new mid-term management plan provides key insights into the company’s future growth strategy and commitment to shareholder returns. The significant upward revision of long-term financial targets and the first-ever entry into overseas real estate operations could suggest a strategic shift for portfolio diversification and enhanced growth opportunities. The ROE target of over 10% and the progressive dividend policy with a 50% payout ratio indicate a strong focus on capital efficiency and investor returns, which may be viewed positively by the market.
9539|京葉瓦斯
1257.0
▼ -1.87%
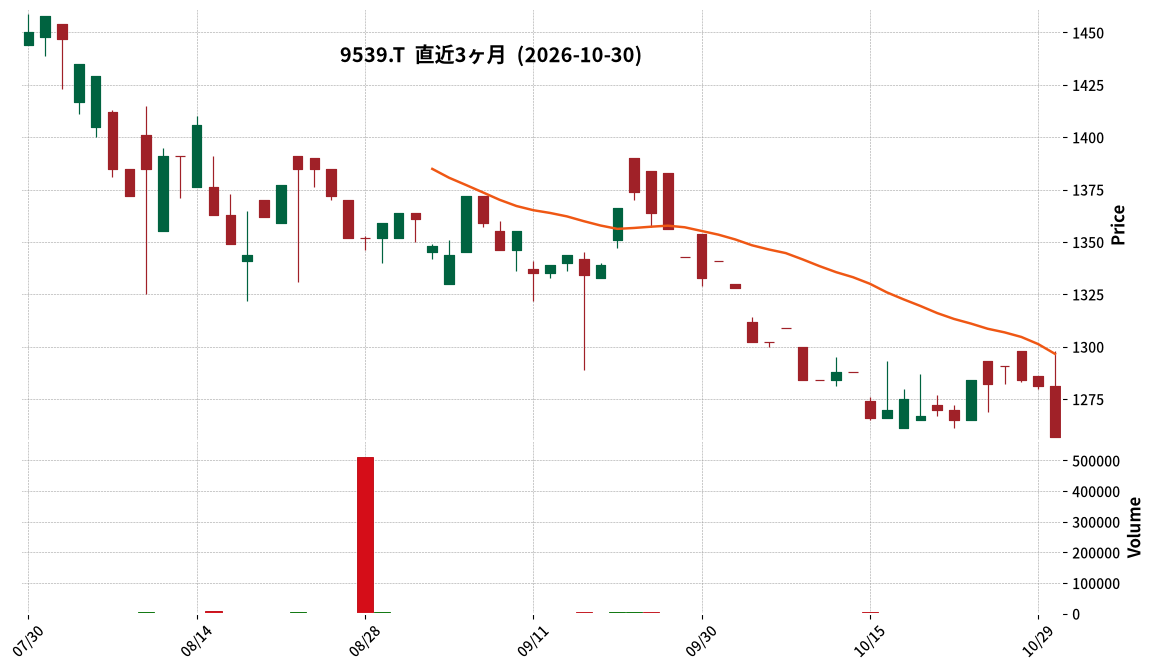
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Keiyo Gas Co., Ltd. announced its consolidated financial results for the third quarter of the fiscal year ending December 2026 (January 1, 2026, to September 30, 2026).
- During this cumulative third quarter, net sales totaled ¥91,306 million, marking a 1.6% increase compared to the same period of the previous year.
- Net income attributable to owners of parent was ¥4,154 million, an increase of 17.4% year-on-year. Operating income was ¥4,795 million (up 7.3% YoY), and ordinary income was ¥5,840 million (up 17.9% YoY).
- By segment, “Life Services” net sales increased by 26.9% year-on-year, and “Real Estate” net sales increased by 22.9%. The “Energy” segment’s net sales decreased by 0.3%.
- The consolidated full-year earnings forecast for the fiscal year ending December 2026 has been revised, with net sales projected at ¥122,800 million and net income attributable to owners of parent at ¥1,800 million. The IR states that there is a revision from the most recently announced earnings forecast.
🤖 AI Perspective
Keiyo Gas’s Q3 FY2026 results show growth in both revenue and various profit metrics, suggesting an overall positive performance for the period. The strong contributions from the Life Services and Real Estate segments appear to be key drivers of this increase. However, the announced revision to the full-year earnings forecast could be a significant factor for investors to consider, and the specific details behind this revision may warrant further investigation.
5333|NGK
4589.0
▼ -5.40%
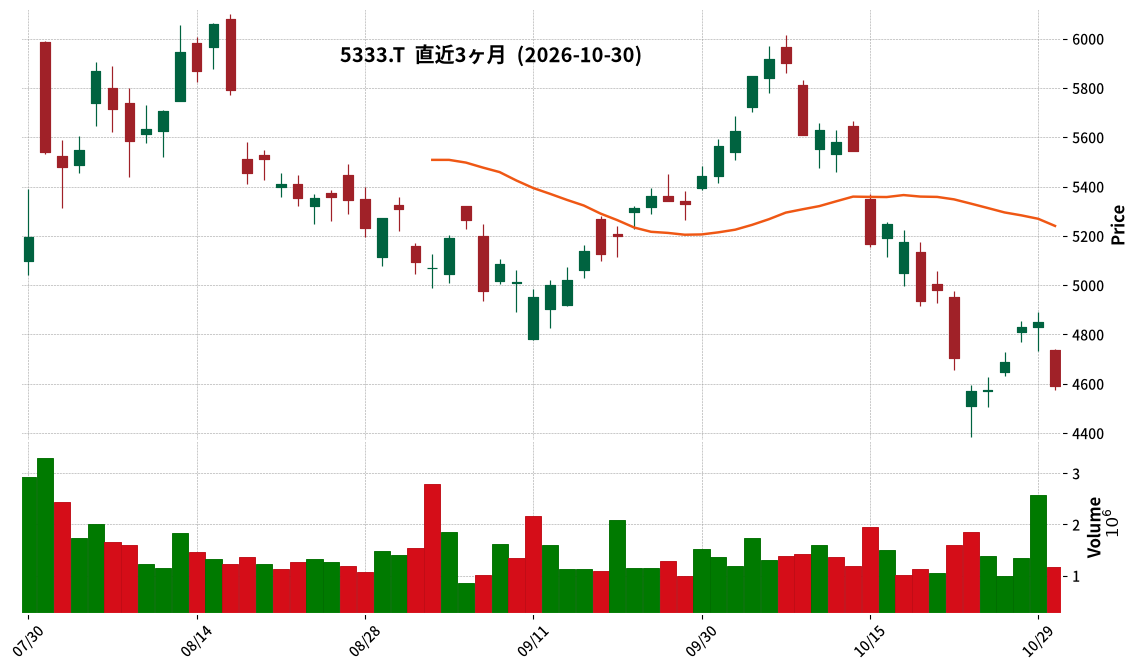
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- NGK Corporation announced on October 30, 2026, a revision to its interim dividend and year-end dividend forecast, resulting in an increase.
- The interim dividend for shareholders as of September 30, 2026, has been revised from the most recent forecast of ¥53.00 per share to ¥63.00 per share.
- The year-end dividend forecast has also been revised from the previous forecast of ¥53.00 per share to ¥63.00 per share.
- Consequently, the full-year dividend forecast has been adjusted from ¥106.00 per share to ¥126.00 per share.
- The interim dividend will take effect on December 2, 2026, with the source of the dividend being retained earnings.
- The revision is attributed to the company’s first-half performance exceeding plans and the full-year outlook surpassing previous forecasts, influenced by actual business conditions and the depreciation of the yen.
🤖 AI Perspective
This dividend increase announcement appears to directly reflect the company’s strong performance and the impact of the depreciating yen on its financial results. The significant upward revision in the annual dividend could be interpreted as a reinforcement of NGK’s commitment to shareholder returns. Investors may find it worthwhile to monitor the company’s future earnings trends and dividend payout ratios.
6586|マキタ
5239.0
▼ -0.27%
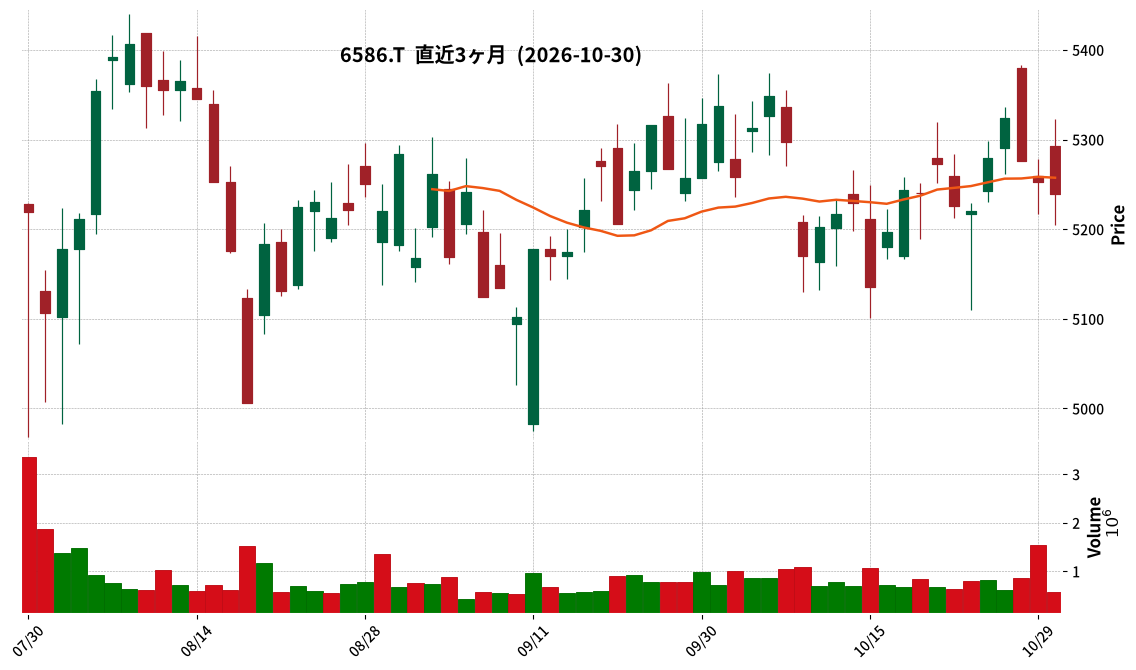
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Makita Corporation announced its consolidated financial results for the second quarter of the fiscal year ending March 2027 (interim period).
- Revenue totaled ¥414,713 million, an increase of 9.6% compared to the previous interim period.
- Operating profit was ¥63,335 million, marking a 23.0% increase year-on-year.
- Interim profit attributable to owners of the parent reached ¥47,918 million, up 23.5% from the prior interim period.
- An interim dividend of ¥79.00 per share is planned.
- The full-year consolidated forecast for FY2027 remains unchanged, projecting revenue of ¥820,000 million (up 5.5% YoY) and profit attributable to owners of the parent of ¥81,000 million (up 2.0% YoY).
🤖 AI Perspective
The significant increase in revenue and profits for the interim period appears to be largely driven by the depreciation of the Japanese Yen and refunds of U.S. tariffs. While most regions showed revenue growth, strong performance in North and Latin America is particularly notable, suggesting robust regional demand or market penetration. The unchanged full-year forecast indicates that the company believes its performance is in line with its initial projections, which could provide a degree of stability for investors to consider.
7177|GMOFHD
1068.0
▼ -1.29%
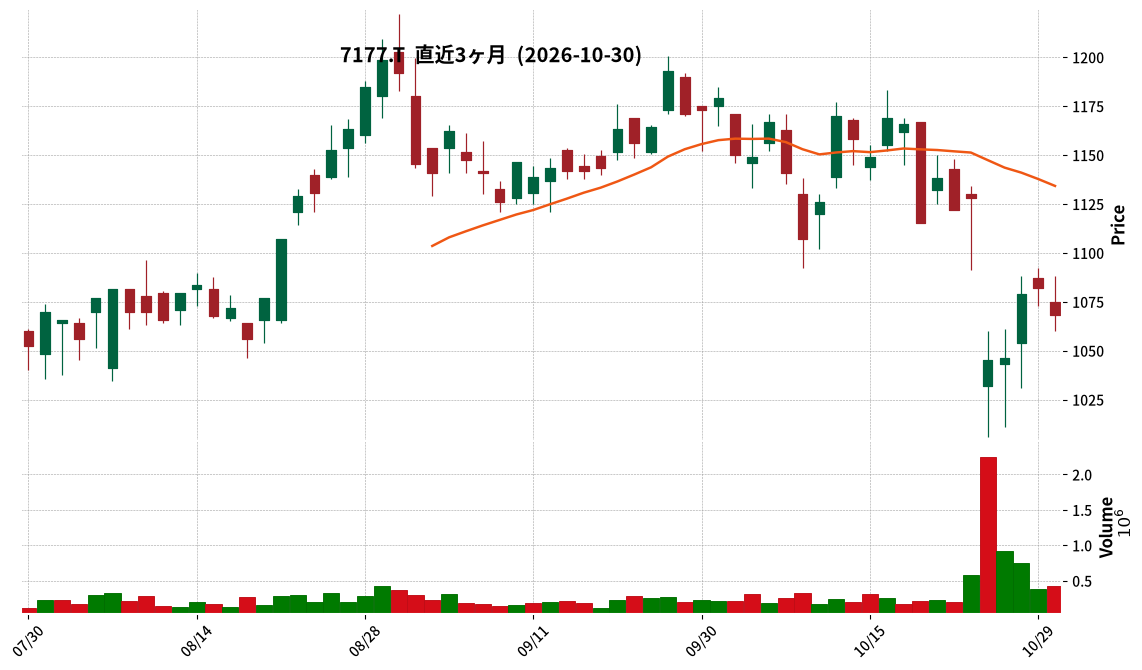
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- GMO Financial Holdings reported record-high cumulative performance for the first nine months of the fiscal year ending December 2026 (Q3), with operating revenue of JPY 44.50 billion and operating income of JPY 16.06 billion.
- Operating revenue increased by 15.9% year-on-year, and operating income increased by 17.3% year-on-year.
- CFD revenue and financial revenue remained high, driving overall performance. Retail FX profitability significantly improved in Q3 alone.
- The crypto asset business experienced a year-on-year decrease in revenue and profit due to subdued market conditions, though its domestic trading volume share showed an upward trend.
- The company introduced a dividend policy with a payout ratio of 65% or more and a DOE (Dividend on Equity) lower limit of 10%. Based on Q3 results, the full-year dividend forecast for FY2026 was revised upwards to JPY 68.60 per share.
- Regarding the unauthorized access incident within the GMO Internet Group, while no direct impact on the consolidated subsidiaries’ trading systems or fraudulent operations on customer accounts has been confirmed, an increase in account cancellations and withdrawals, and a decrease in new account openings are observed.
1381|アクシーズ
3425.0
▼ -0.87%
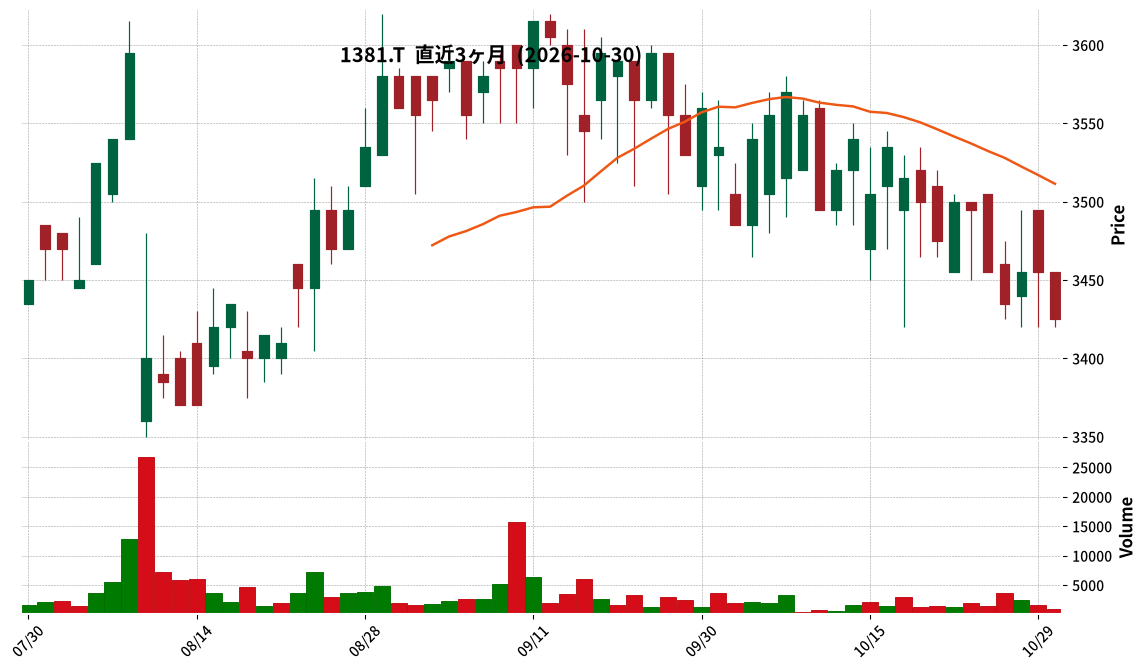
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Axyz Co., Ltd. announced its consolidated financial results for the first quarter of the fiscal year ending June 2027 (July 1, 2026, to September 30, 2026).
- Consolidated operating results show net sales of ¥7,396 million (up 2.5% year-on-year), operating profit of ¥871 million (down 16.8%), ordinary profit of ¥898 million (down 18.8%), and net profit attributable to parent company shareholders of ¥626 million (down 19.4%).
- Segment-wise, the Food business recorded sales of ¥6,082 million (up 0.4%) and segment profit of ¥652 million (down 22.5%). The Restaurant business reported sales of ¥1,158 million (up 13.8%) and segment profit of ¥89 million (down 1.3%). The Energy business saw sales of ¥155 million (up 8.3%) and segment profit of ¥129 million (up 13.0%).
- Regarding the consolidated financial position, total assets at the end of the first quarter were ¥27,462 million (down ¥998 million from the end of the previous fiscal year), and net assets were ¥24,095 million (up ¥10 million).
- The consolidated earnings forecast for the fiscal year ending June 2027 and the dividend forecast (¥120.00 per year) remain unchanged from the most recently announced figures.
🤖 AI Perspective
While sales showed a slight increase, the double-digit decline in operating profit, ordinary profit, and net profit attributable to parent company shareholders is a key observation. This appears to be primarily driven by falling chicken prices and rising manufacturing costs within the Food business segment. With the full-year earnings forecast remaining unchanged, the company’s performance in the second quarter and beyond will be worth monitoring for signs of recovery.
2218|日糧パン
—
▲ +0.00%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Nichiryo-Pan reported net sales of ¥9,228 million for the second quarter of the fiscal year ending March 2027, marking a 0.9% decrease year-on-year.
- Operating profit reached ¥133 million, a 47.1% increase compared to the previous year’s interim period, and ordinary profit was ¥134 million, up 39.9%.
- Interim net profit significantly increased by 81.9% year-on-year to ¥95 million, with interim basic earnings per share at ¥45.48.
- As of the end of the interim period, total assets stood at ¥14,694 million, net assets at ¥5,727 million, and the equity ratio was 39.0%.
- The full-year earnings forecast for the fiscal year ending March 2027, including net sales of ¥19,700 million and net profit of ¥120 million, remains unchanged from the most recently announced figures.
🤖 AI Perspective
Despite a slight decrease in net sales, the substantial increases in operating, ordinary, and interim net profits suggest an improvement in profitability. This performance may indicate that the company’s strategies, such as price revisions, operational reviews, and expense controls, have been effective in a challenging environment marked by rising raw material costs and cautious consumer spending. The progress towards the unchanged full-year earnings forecast will be worth monitoring.
2479|ジェイテック
228.0
▼ -1.30%
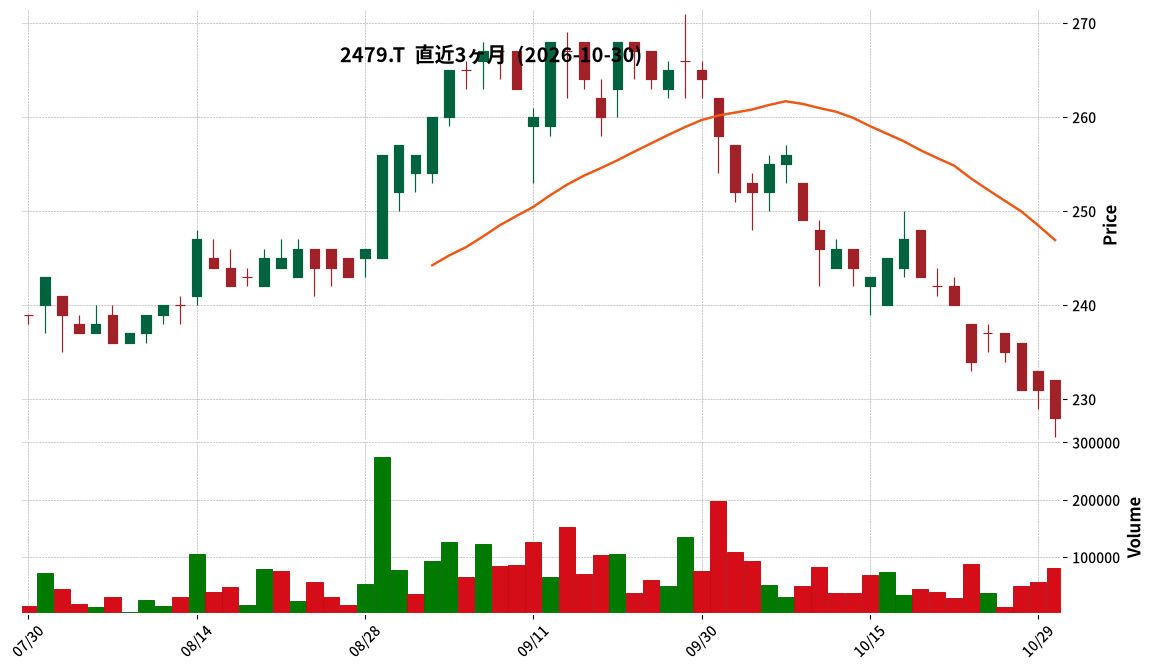
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- J-TEC Co., Ltd. announced its consolidated financial results for the second quarter (interim period) of the fiscal year ending March 2027.
- Net sales reached ¥1,686 million, marking a 3.7% increase year-on-year and a record high for an interim period.
- Operating profit was ¥47 million (a 23.5% decrease year-on-year), while ordinary profit increased to ¥48 million (a 29.0% increase year-on-year), and net income attributable to owners of parent grew to ¥28 million (a 21.8% increase year-on-year).
- The decrease in operating profit is attributed to increased labor costs due to the introduction of a new personnel system, including improvements in talent compensation and investments in recruitment and training.
- As of the interim period end, the equity ratio was 66.5% (compared to 69.0% at the end of the previous fiscal year).
🤖 AI Perspective
J-TEC’s interim results indicate a strategic phase where the company achieved record sales while simultaneously making significant investments in human capital, which impacted operating profit. This suggests a focus on long-term sustainable growth through enhancing its workforce. The increase in ordinary profit, despite the operating profit decline, may reflect effective cost control measures outside core operations and the absence of one-off expenses from the prior fiscal year, a trend that investors might consider important for future profitability.
2481|タウンニュース
722.0
▼ -1.77%
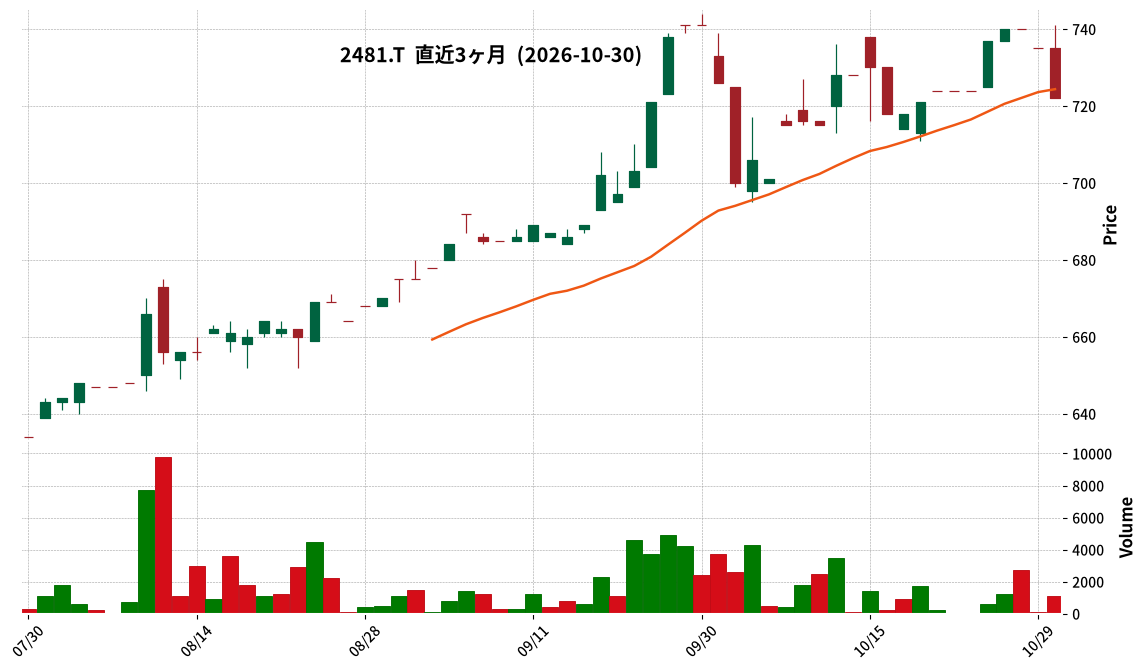
📎 Source:タウンニュース Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Townnews Co., Ltd. announced its non-consolidated financial results for the first quarter of the fiscal year ending June 2027 (July 1, 2026 – September 30, 2026).
- Net sales for the first quarter reached ¥962 million, representing a 5.1% increase compared to the same period of the previous year.
- Operating income was ¥134 million (up 33.0% year-on-year), ordinary income was ¥150 million (up 32.1% year-on-year), and quarterly net income was ¥97 million (up 28.3% year-on-year).
- Basic earnings per share for the quarter were ¥17.68.
- There are no revisions to the full-year earnings forecast for FY2027 or the dividend forecast (¥22.00 per share annually) from the most recently published figures.
🤖 AI Perspective
Townnews’ Q1 results indicate a strong start to the fiscal year with solid growth across all key profitability metrics. The significant increase in operating income relative to sales growth, at 33.0% versus 5.1% respectively, suggests effective cost management and operational efficiency. The sustained growth in digital and non-paper businesses, including PPP (Public-Private Partnership) projects, could be important for the company’s future revenue diversification and overall financial health, and is worth monitoring.
2492|インフォマート
766.0
▼ -0.91%
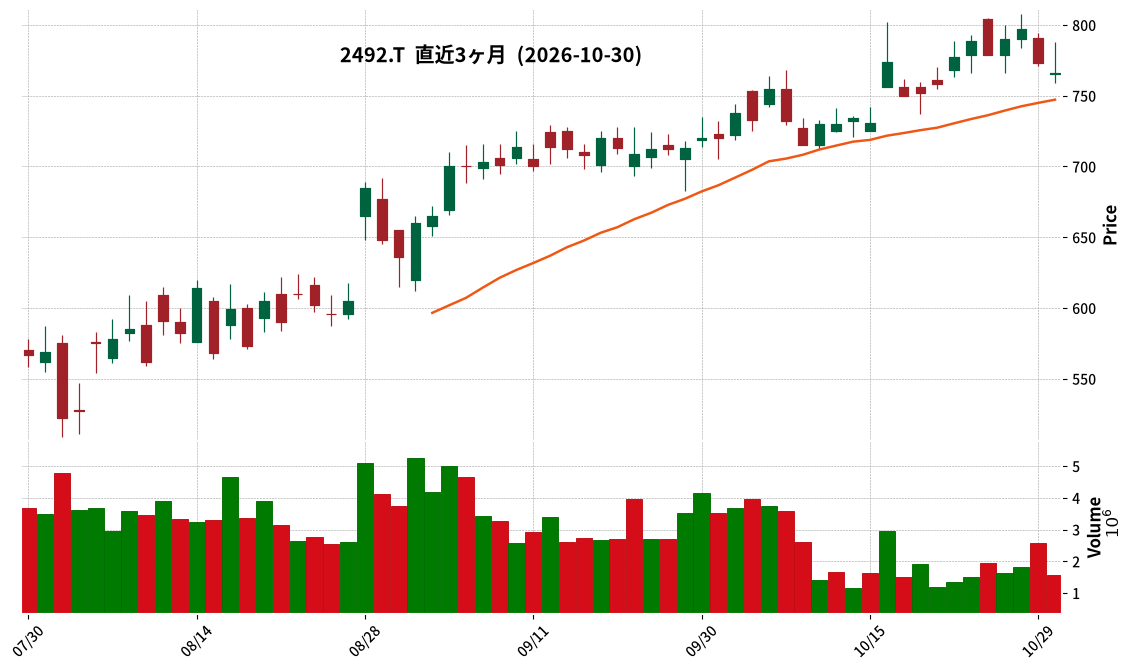
📎 Source:インフォマート Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- For the nine months ended September 30, 2026 (Q3 FY2026), Infomart reported consolidated net sales of ¥15,253 million, a 10.5% increase year-over-year.
- During the same period, EBITDA was ¥4,850 million (+23.0% YoY), operating profit was ¥3,393 million (+40.9% YoY), ordinary profit was ¥3,259 million (+36.0% YoY), and net profit attributable to parent company shareholders was ¥1,973 million (+31.4% YoY).
- The total number of companies utilizing the BtoB platform reached 1,326,714 as of September 30, 2026, an increase of 75,545 companies from the end of the previous fiscal year.
- In the BtoB-PF FOOD business, buyer companies for “BtoB Platform Order” increased to 4,494, and seller companies increased to 49,683.
- The full-year consolidated earnings forecast for FY2026 remains unchanged from the most recently announced figures, including net sales of ¥21,348 million and operating profit of ¥5,000 million.
🤖 AI Perspective
Infomart’s Q3 FY2026 results demonstrate solid growth in sales and substantial increases across all profit metrics, suggesting an improvement in profitability. The consistent expansion of the BtoB platform user base could indicate a strengthening of its business foundation and future growth potential. Contributing factors to the profit increase, such as reduced data center costs and capitalization of development expenses, may also reflect ongoing efforts to optimize its cost structure.
2689|オルバDVx
1920.0
▲ +0.47%
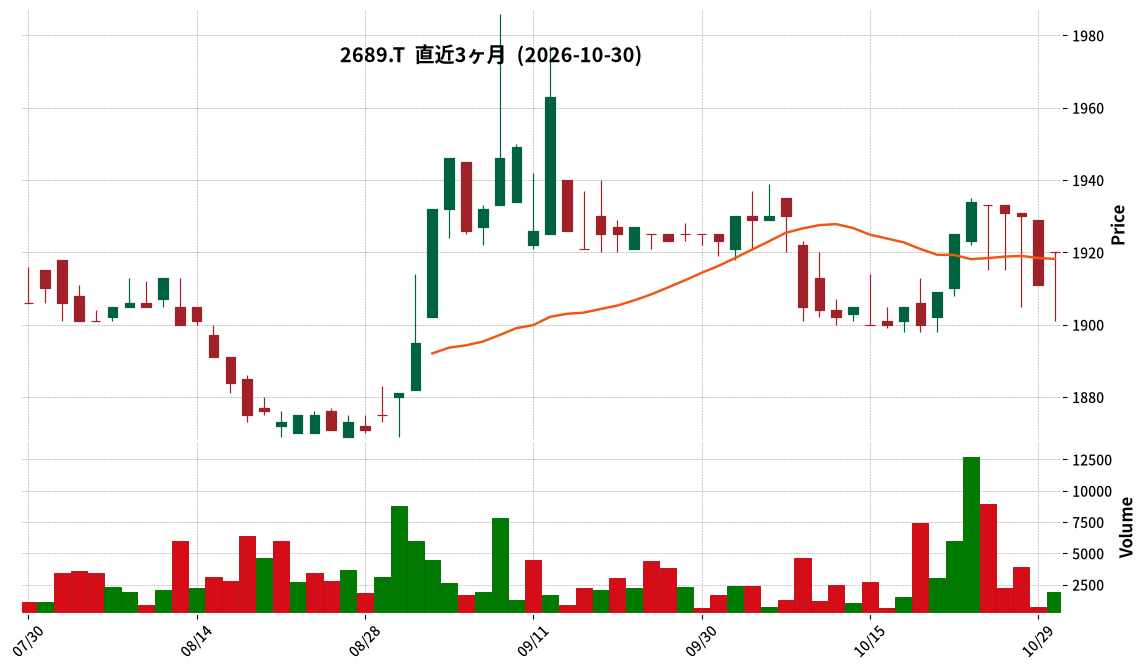
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- ORBA DVx Healthcare Inc. reported consolidated net sales of ¥31,454 million for the first quarter of fiscal year 2027 (July 1, 2026 – September 30, 2026), marking a 2.0% increase year-on-year.
- Consolidated operating profit was ¥141 million (down 45.5% YoY), ordinary profit was ¥122 million (down 52.2% YoY), and profit attributable to owners of parent was ¥36 million (down 77.9% YoY).
- Sales of consumables in the Medical Equipment business increased by 2.3% year-on-year, with growth observed in surgical-related, orthopedic, and cardiovascular consumables categories.
- The company completed a business integration with DVx Co., Ltd. on September 1, 2026. As of the end of Q1, only the balance sheet is consolidated, and DVx’s operating results are not included in the Q1 income statement.
- The full-year consolidated earnings forecast and annual dividend forecast for fiscal year 2027 have been revised, with details provided in the “Notice Regarding Revisions to Earnings Forecast and Dividend Forecast” released on October 30, 2026.
🤖 AI Perspective
While sales show an increase, the significant decline in operating profit, ordinary profit, and net profit appears to be influenced by one-off expenses related to the business integration and system investments for DX promotion. As the impact of the business integration with DVx Co., Ltd. will only be fully reflected in the consolidated income statement from the next quarter onwards, the realization of integration synergies will be a key point for investors to monitor.
2700|木徳神糧
1743.0
▼ -0.68%
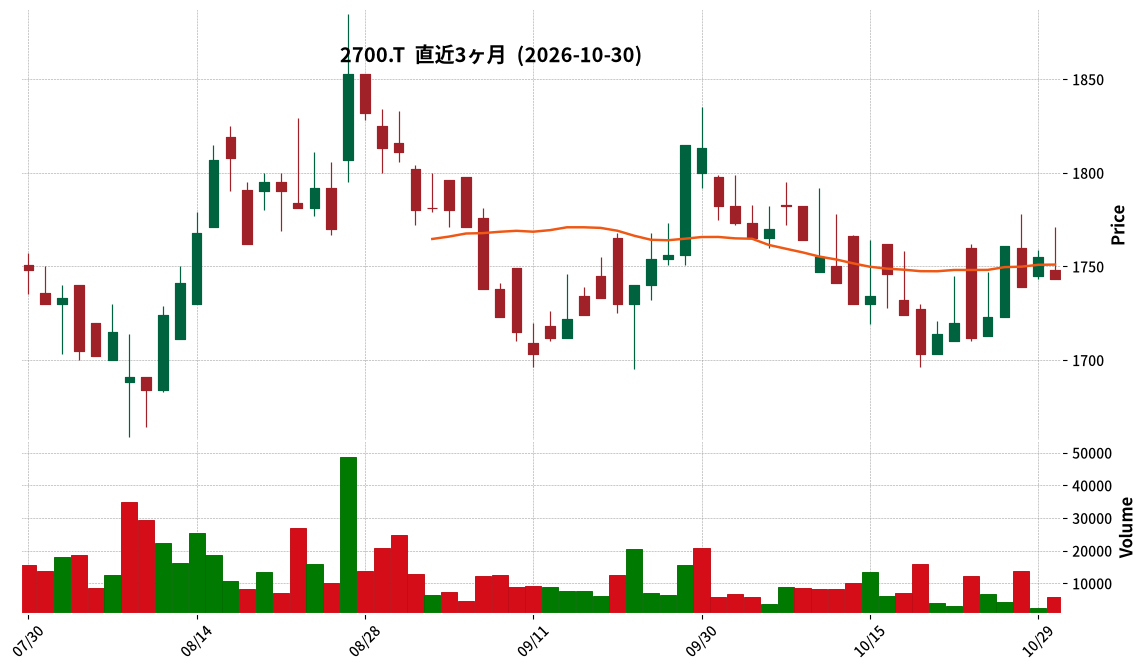
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Kitoku Shinryo has decided to expand its shareholder benefit program.
- For the December-end record date, a new category for shareholders holding 200 shares to less than 500 shares will be established, offering rice products equivalent to 5kg.
- Existing categories for the December-end record date (500 shares or more, held for less than 3 years; 500 shares or more, held for 3 years or more) will also see an increase in the quantity of rice products. Specifically, 10kg equivalent for less than 3 years and 15kg equivalent for 3 years or more.
- For the June-end record date (1,000 shares to less than 2,000 shares; 2,000 shares or more), the quantity of rice products will also be increased. Specifically, 10kg equivalent for 1,000 shares to less than 2,000 shares, and 10kg equivalent of rice products plus two 750g packages of “Kirimochi” for 2,000 shares or more.
- This expansion will be applied starting from shareholders recorded in the shareholder register as of December 31, 2026, with changes for the June-end record date applying from shareholders as of June 30, 2027.
🤖 AI Perspective
The expansion of the shareholder benefit program appears to aim at increasing the investment appeal to a broader range of individual shareholders and encouraging stable, long-term share ownership. The introduction of a new category for 200 to less than 500 shares, which was previously excluded, could serve as a new incentive for individual investors considering smaller investments. Furthermore, by increasing the benefits for existing shareholders, the company demonstrates a commitment to rewarding continued loyalty, which may support shareholder retention.
2926|篠崎屋
116.0
▲ +10.48%
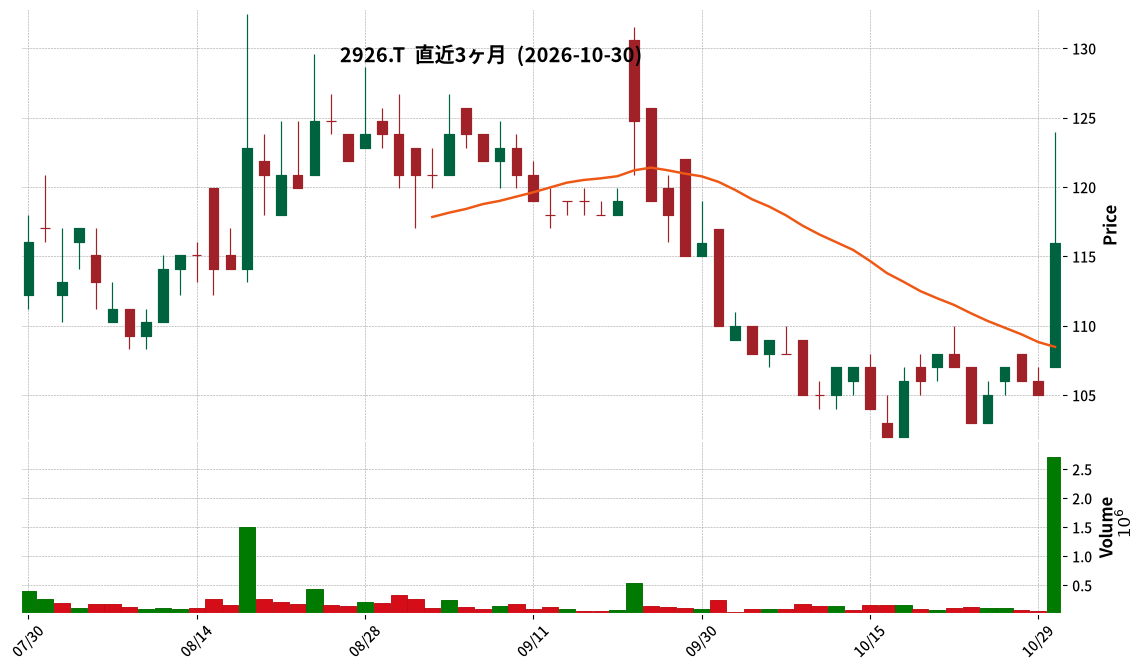
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Shinozakiya Co., Ltd. announced its non-consolidated financial results for the fiscal year ended September 2026 (October 1, 2025, to September 30, 2026).
- Net sales reached JPY 3,230 million, an increase of 9.9% compared to the previous fiscal year.
- Operating profit was JPY 77 million (+30.9% YoY), ordinary profit was JPY 81 million (+27.0% YoY), and net income was JPY 64 million (+69.2% YoY).
- Retail segment sales were JPY 2,920 million (+11.8% YoY), with segment profit of JPY 206 million (+5.5% YoY). Pop-up stores, under the “real storeless sales” concept, saw sales increase by 251.2% YoY.
- A year-end dividend of JPY 4 per share (JPY 3 ordinary, JPY 1 special) was declared, totaling JPY 56 million with a payout ratio of 87.9%.
- The earnings forecast and dividend forecast for the fiscal year ending September 2027 are not disclosed at this time due to the difficulty in predicting performance influenced by external factors such as weather.
🤖 AI Perspective
Shinozakiya’s fiscal year 2026 results show significant growth across all key financial metrics, particularly net income. This performance appears to be supported by increased productivity in existing stores and the successful expansion of “real storeless sales” pop-up formats. While the company has not provided a forecast for the upcoming fiscal year, the commitment to monthly disclosures and updates on Q2 and full-year outlooks could offer valuable insights into future business trajectory for investors to monitor.
2929|ファーマフーズ
635.0
▼ -0.16%
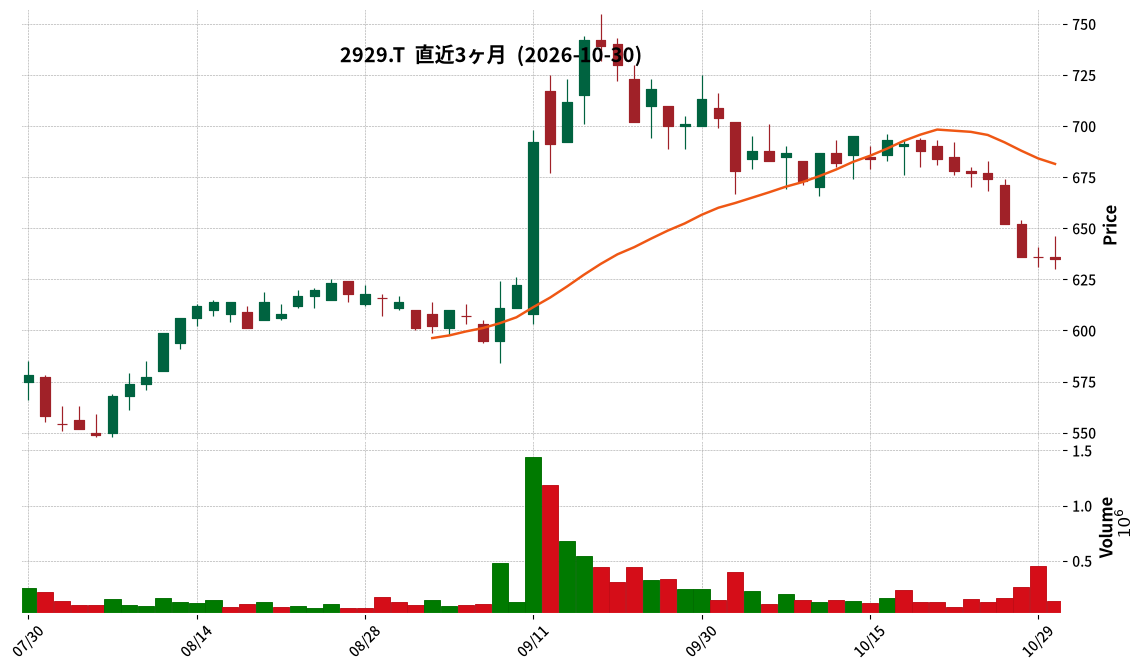
📎 Source:ファーマフーズ Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Pharmamfoods Co., Ltd. announced on October 30, 2026, the completion of the acquisition process for all shares of Marine Pro Foods Co., Ltd.
- This acquisition is a progress report following the “Notice Regarding Acquisition of Shares (Making Subsidiary) of Marine Pro Foods Co., Ltd.” disclosed on October 6, 2026.
- The business activities of the new subsidiary, Marine Pro Foods Co., Ltd., include the planning, development, and sales of agricultural, livestock, and marine products, as well as soy-based processed foods.
- Marine Pro Foods Co., Ltd. is located at 2-2-1 Uchikanda, Chiyoda-ku, Tokyo, has a capital of 100 million yen, and was established on November 11, 2021.
- At the time of acquisition completion, the major shareholder and ownership ratio was Investment Business Association “DPIP Corporate Support No. 1” with 100%.
🤖 AI Perspective
This announcement confirms Pharmamfoods’ official acquisition of Marine Pro Foods as a subsidiary. The business activities of Marine Pro Foods, focused on agricultural, livestock, and marine products, suggest potential synergies with Pharmamfoods’ existing operations, which investors may monitor for future developments. The specific impact of this acquisition on Pharmamfoods’ financial performance is currently under review, and further disclosures are anticipated.
3439|三ツ知
680.0
▼ -2.16%
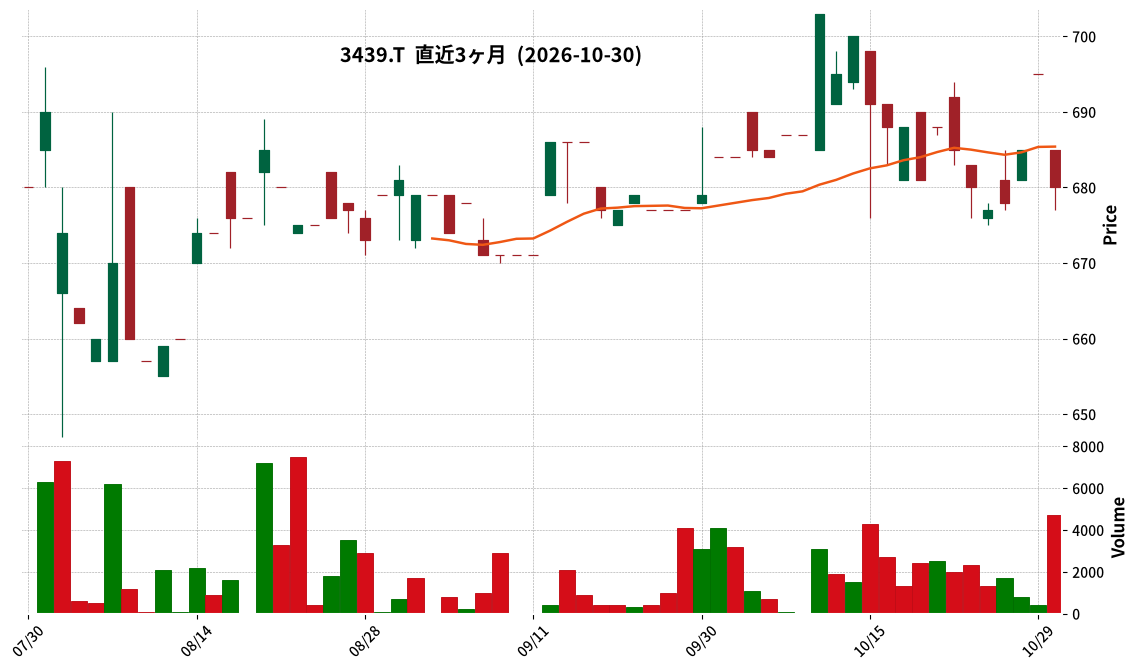
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Mitsuchi Co., Ltd. announced its consolidated financial results for the first quarter of the fiscal year ending June 2027 (July 1, 2026 to September 30, 2026).
- Consolidated net sales for Q1 amounted to ¥3,359 million, representing an 8.3% increase compared to the same period last year.
- Consolidated operating profit reached ¥81 million, marking a substantial increase of 264.9% year-on-year.
- While consolidated ordinary profit was ¥85 million (up 57.5% YoY), net profit attributable to owners of parent decreased by 36.6% year-on-year to ¥42 million.
- Total assets increased by ¥881 million from the previous fiscal year-end to ¥16,515 million, with the equity ratio at 63.0% (compared to 66.2% at the end of the previous fiscal year).
- The full-year consolidated earnings forecast and dividend forecast for the fiscal year ending June 2027 remain unchanged from the most recently announced figures.
🤖 AI Perspective
Mitsuchi’s Q1 FY2027 results show significant increases in net sales and operating profit, which may suggest positive operational momentum, particularly from its overseas segments. However, the decline in net profit attributable to owners of parent, despite strong top-line growth, could indicate the impact of extraordinary losses. The slight decrease in the equity ratio is also worth monitoring as it reflects changes in the company’s asset and liability structure.
Disclaimer: This article is for informational purposes only and does not constitute investment advice.
3542|G-VEGA
1535.0
▼ -0.97%
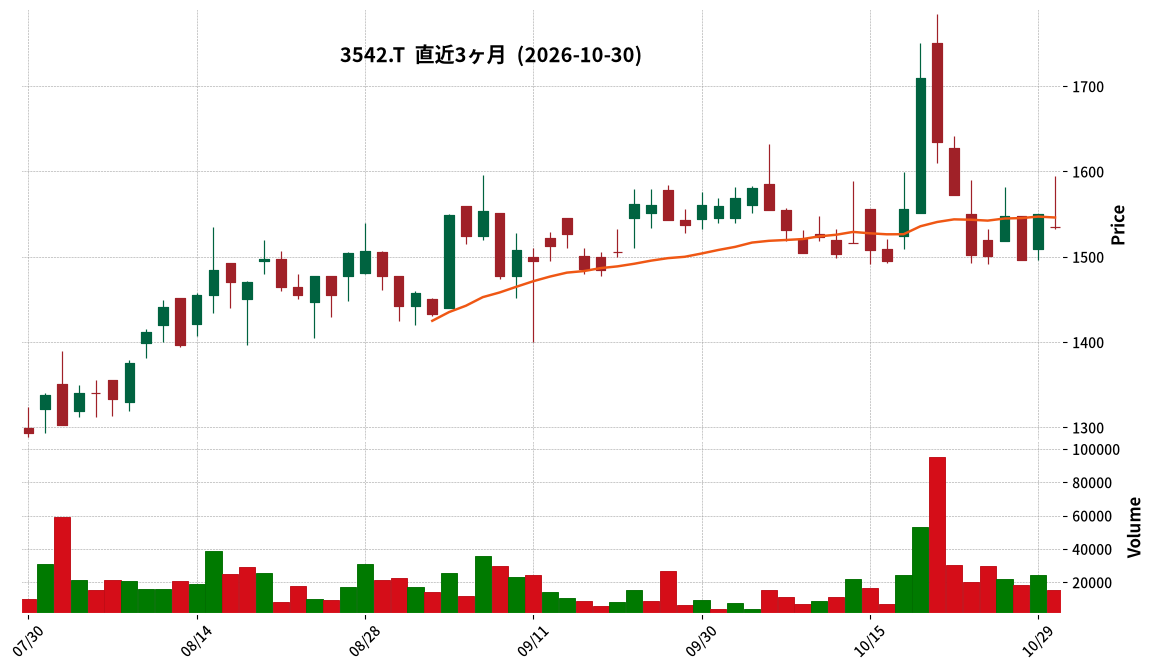
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- VEGA CORPORATION has revised its full-year earnings forecast for the fiscal year ending March 31, 2027 (April 1, 2026 – March 31, 2027).
- The revised forecast includes net sales of ¥21,600 million (up 3.8% from previous forecast), operating profit of ¥1,700 million (up 13.3%), ordinary profit of ¥1,710 million (up 13.2%), and profit attributable to owners of parent of ¥986 million (up 7.0%), with earnings per share at ¥92.65.
- Reasons for the revision include the successful opening of 5 new physical stores during the second quarter (bringing the total to 18 stores), successful new product development through OMO strategies combining proprietary e-commerce and physical stores, thorough cost ratio control utilizing foreign exchange forward contracts, and an improvement in gross profit margin beyond initial expectations due to enhanced product strength and brand value through OMO strategy.
- The dividend forecast for the fiscal year ending March 31, 2027, has also been revised, with the year-end dividend increasing by ¥2 from the previous forecast of ¥18 to ¥20 per share.
- The company’s dividend policy is based on paying the greater of a 20% payout ratio or 2.0% DOE.
🤖 AI Perspective
This upward revision of earnings and dividend forecasts suggests that the company’s business strategies are yielding positive results. The acceleration of physical store expansion and the integrated OMO strategy, blending online and offline channels, appear to be contributing not only to sales growth but also to improved profit margins. The implementation of measures to address foreign exchange rate fluctuations could also indicate efforts towards enhancing operational stability, which may be a point of interest for investors.
3675|クロスマーケティング
555.0
▼ -0.18%
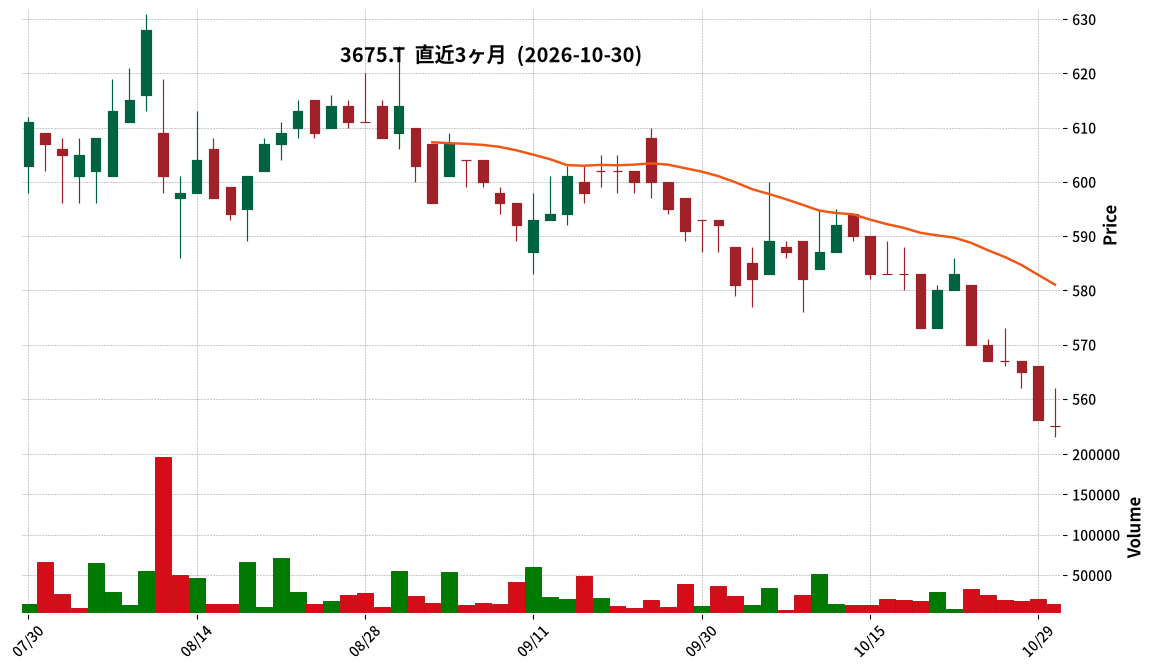
📎 Source:クロスマーケティング Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Cross Marketing announced on October 30, 2026, its decision to acquire all shares of Chotto Co., Ltd. and make it a consolidated subsidiary.
- Chotto Co., Ltd. possesses an engineering team strong in modern frontend technologies like Next.js and React, with a proven track record in frontend development for AI-powered applications.
- Prior to the acquisition, Chotto Co., Ltd. will spin off its CMS business into a newly established subsidiary. Cross Marketing will acquire 100% of Chotto Co., Ltd.’s shares, which will then solely operate the frontend development support business.
- The share transfer execution date is scheduled for December 1, 2026.
- The impact of this acquisition on Cross Marketing’s consolidated earnings for the fiscal year ending June 2027 is expected to be minor.
🤖 AI Perspective
This acquisition aligns with Cross Marketing’s mid-term management strategy “Unite & Generate,” suggesting a strategic focus on strengthening its digital domain and AI utilization capabilities. Chotto’s expertise in modern frontend development and AI application experience could contribute to enhancing the group’s overall service development framework. The divestiture of the CMS business might indicate Cross Marketing’s emphasis on acquiring specialized frontend development capabilities.
Disclaimer: This article is for informational purposes only and does not constitute investment advice.
3762|テクマト
3320.0
▼ -1.92%
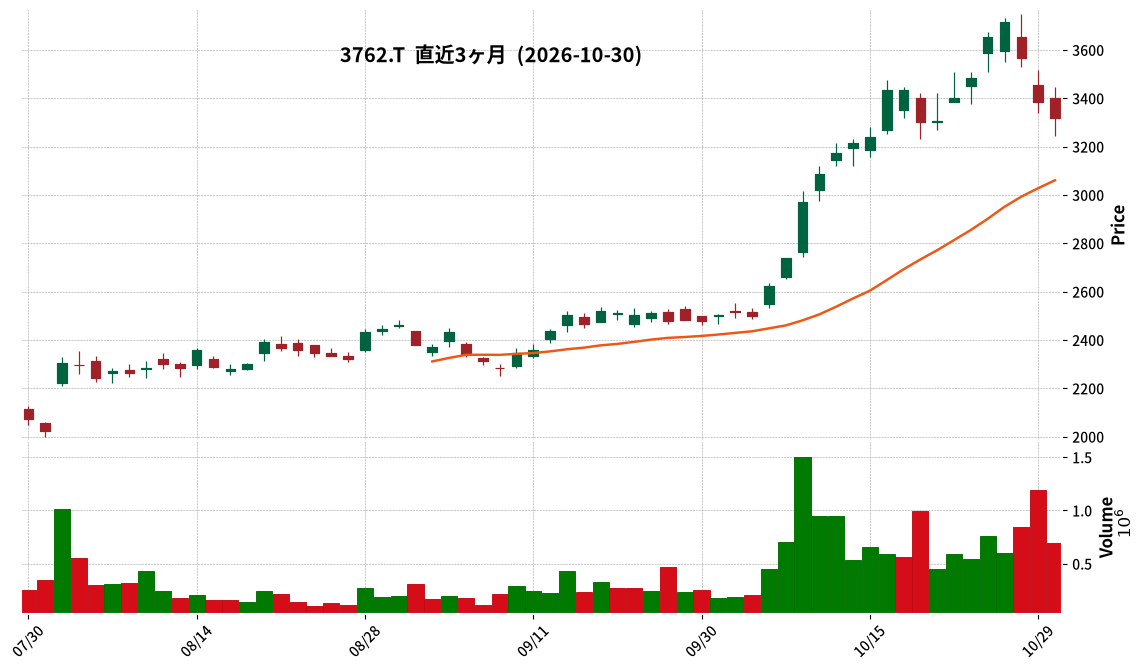
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- TechMatrix Corporation announced its consolidated financial results for the second quarter (cumulative) of the fiscal year ending March 2027.
- Revenue reached ¥38,999 million (+16.8% year-on-year), and operating profit was ¥3,507 million (+10.5% year-on-year), both marking record highs for a Q2 cumulative period.
- Orders received increased to ¥53,745 million (+23.1% year-on-year), and the order backlog grew to ¥120,262 million (+22.2% year-on-year).
- By segment, the Information Infrastructure business reported revenue of ¥28,872 million (+19.2%) and operating profit of ¥3,220 million (+10.0%), showing both revenue and profit growth.
- The Application & Service business recorded revenue of ¥5,458 million (+15.7%) and returned to profitability with an operating profit of ¥206 million. The Medical Systems business saw revenue increase to ¥4,668 million (+5.3%) but experienced a decline in operating profit to ¥80 million (▲73.3%).
🤖 AI Perspective
The robust performance across key consolidated metrics, particularly the record-high revenue and operating profit, suggests a strong operational quarter, largely driven by the Information Infrastructure segment. The turnaround to profitability in the Application & Service business could indicate improving efficiency or strategic success in that area. Conversely, the decline in operating profit for the Medical Systems business is attributed to investment-phase costs and a loss from Medmain, which may warrant continued monitoring by investors to assess its long-term impact on profitability.
3836|アバントグループ
1240.0
▲ +1.72%
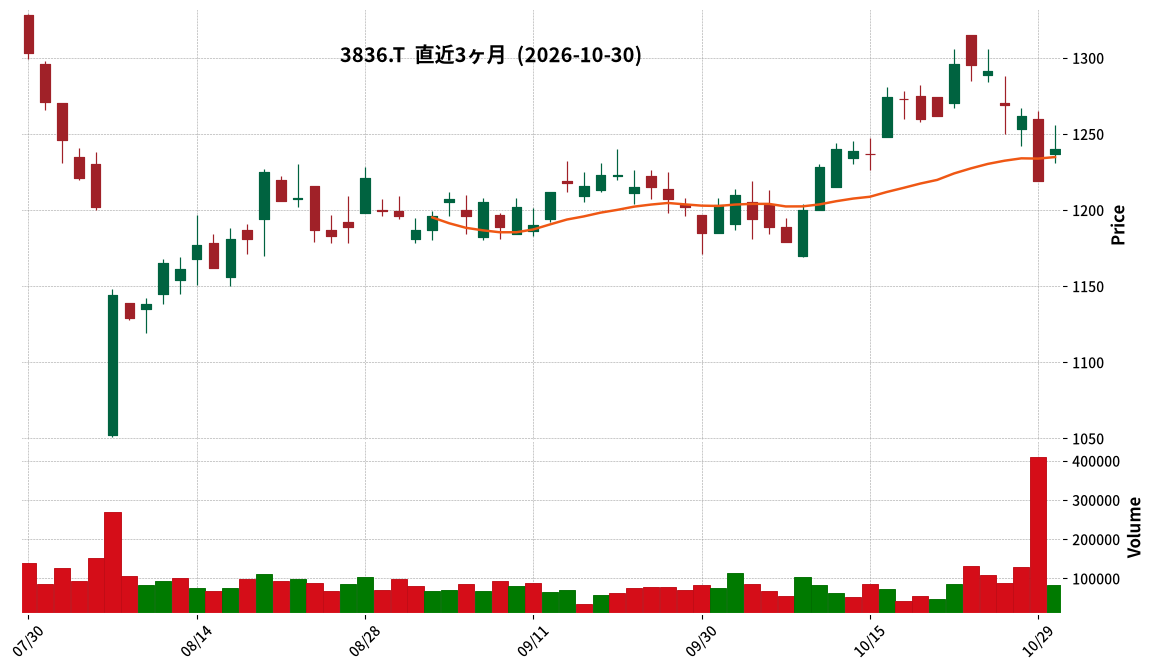
📎 Source:アバントグループ Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- For Q1 FY2027, consolidated net sales reached ¥7,650 million, an increase of 1.8% compared to the same period last year.
- Consolidated operating profit was ¥1,277 million, marking a decrease of 4.8% year-on-year.
- Net profit attributable to owners of the parent company amounted to ¥793 million, down 6.9% from the previous year’s Q1.
- By segment, the Consolidated Financial Disclosure Business saw sales grow by 11.0% and operating profit by 6.8%, while the Management Control Solution Business reported sales up 8.2% and operating profit up 88.7%.
- The Digital Transformation Promotion Business experienced a decrease in sales by 11.0% and operating profit by 48.0%.
🤖 AI Perspective
AVANT Group’s Q1 FY2027 results show a modest increase in sales but a decline in profits compared to the prior year. This trend may suggest increased operational costs, including personnel and office expenses, along with strategic investments for future growth, impacting current profitability. Investors might note the divergence in segment performance, where strong growth in the Consolidated Financial Disclosure and Management Control Solution businesses contrasts with a significant decline in the Digital Transformation Promotion Business.
4308|G-Jストリーム
352.0
▼ -2.49%
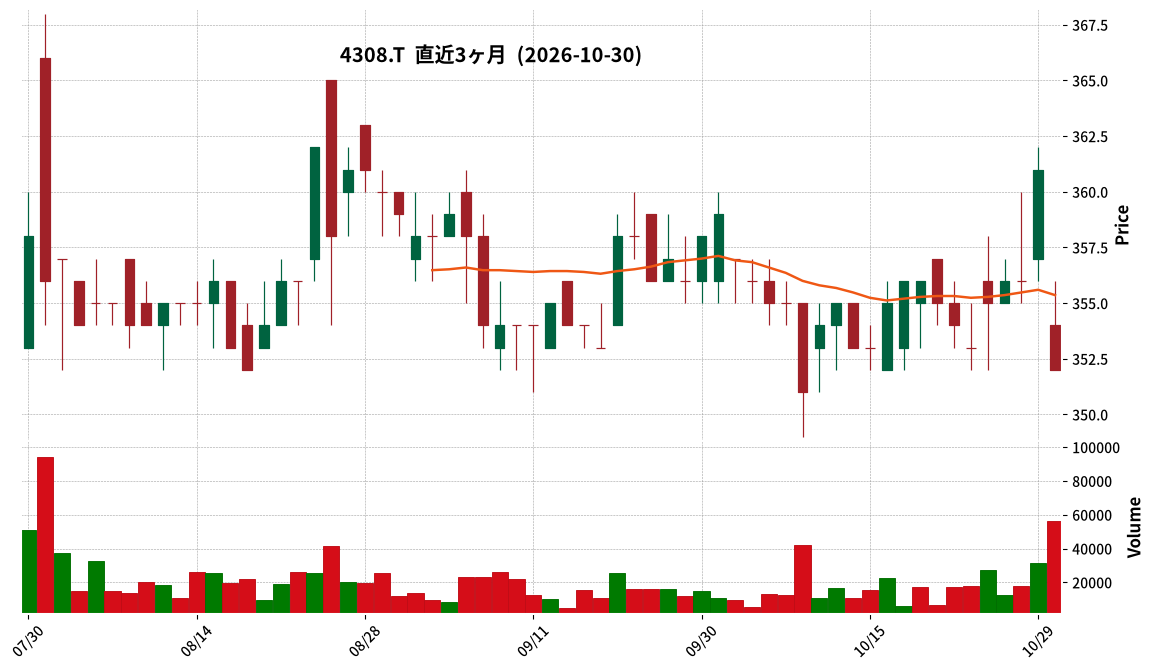
📎 Source:G-Jストリーム Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- G-STREAM Inc. released its Q2 FY2027 earnings presentation materials.
- For the first half of FY2027 (H1 FY2026), consolidated net sales amounted to ¥6,081 million, marking a 6.5% increase year-on-year.
- During the same period, consolidated operating income was ¥414 million (+14.5% YoY), ordinary income was ¥438 million (+14.2% YoY), and net income attributable to owners of the parent was ¥237 million (+17.1% YoY).
- Consolidated subsidiaries reported strong performance, with sales increasing by 17.5% YoY (including M&A effects) and operating income by 48.0% YoY, contributing significantly to the consolidated revenue and profit growth.
- Factors influencing cost of sales included an increase in group personnel due to M&A, higher AWS usage, and increased outsourcing costs linked to higher本社 production sales.
- Selling, general and administrative expenses saw increases in outsourcing fees related to internal system investments (which concluded this half) and sales support expenses.
🤖 AI Perspective
The first half results highlight that the robust performance of consolidated subsidiaries and M&A effects were key drivers of increased revenue and profit. Strong performance in specific business segments, such as Big M’s Y in pharmaceuticals, VideoStep and IPL in EVC, and “Stream CORE” usage in OTT, appears to have propelled the consolidated results. The completion of head office system investments may also impact the cost structure going forward, which is worth monitoring.
6632|JVCKW
885.0
▼ -1.59%
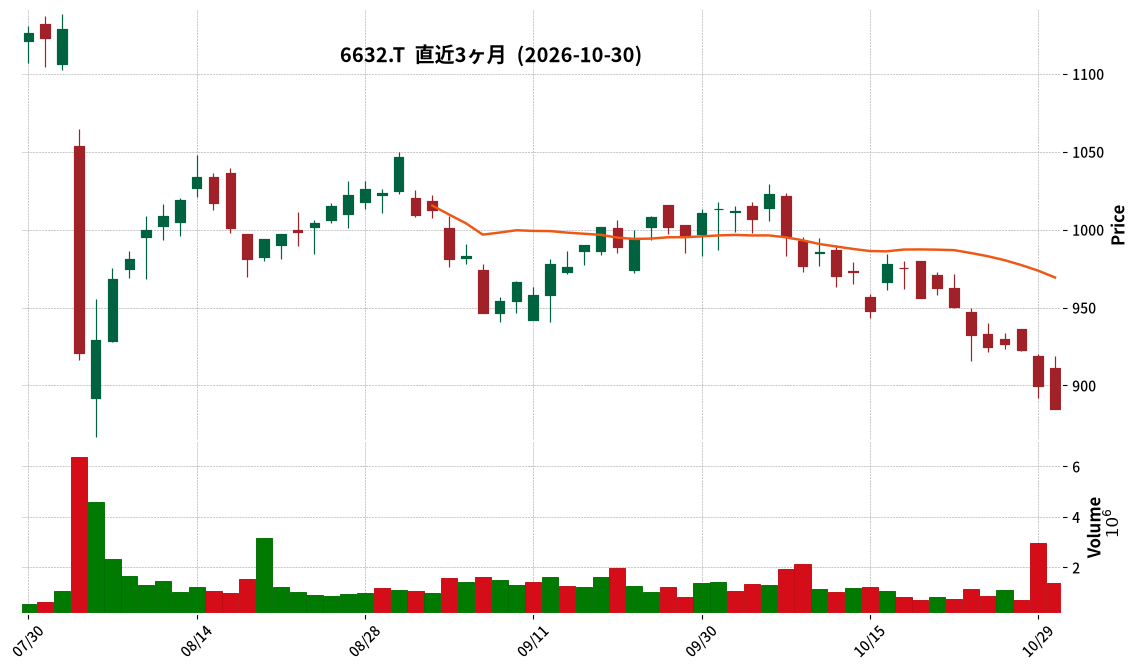
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- JVCKENWOOD’s consolidated financial results for the second quarter (interim period) of the fiscal year ending March 2027 show revenue of ¥183,778 million, an increase of 8.5% compared to the previous interim period.
- Business profit was ¥12,265 million (up 47.4% year-on-year), operating profit was ¥11,488 million (up 19.2%), and interim profit attributable to owners of the parent was ¥8,213 million (up 9.5%).
- The Mobility & Telematics Services (M&T) segment’s domestic aftermarket business and the Entertainment Solutions (ES) segment’s entertainment business performed strongly, with a weak yen also contributing to the revenue increase.
- The increase in business profit was also contributed by approximately ¥4.3 billion in U.S. IEEPA (International Emergency Economic Powers Act) tariff refunds recognized as a reduction in cost of sales.
- The consolidated full-year earnings forecast for the fiscal year ending March 2027 has been revised, with projected revenue of ¥376,000 million (up 5.4% from previous year), business profit of ¥22,300 million (up 6.8%), and profit attributable to owners of the parent of ¥14,700 million (down 12.4%).
🤖 AI Perspective
JVCKENWOOD’s interim results show notable growth in both revenue and business profit, with a significant surge in the latter. This appears to be driven by strong performance in key business segments, favorable currency movements, and a one-time benefit from U.S. IEEPA tariff refunds. While the full-year revenue and business profit forecasts were revised upwards, the projected decrease in profit attributable to owners of the parent suggests other factors may be at play, which investors might consider examining in the detailed report.
6920|レーザーテック
37700.0
▼ -8.81%
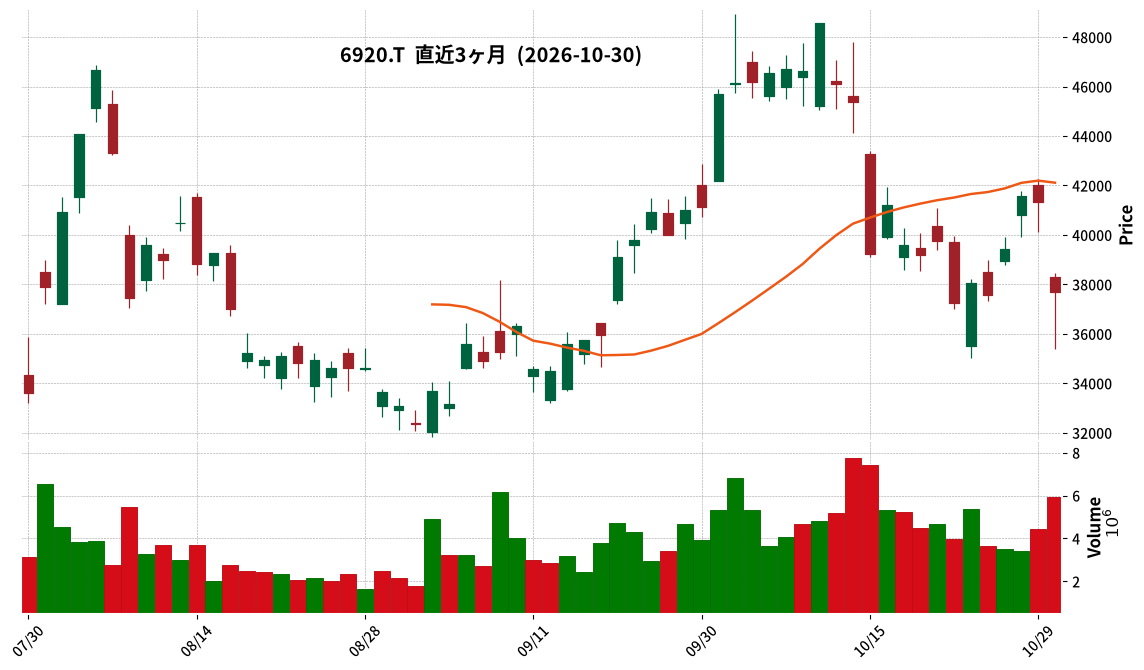
📎 Source:レーザーテック Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Lasertec announced its consolidated financial results for the first quarter of FY2027 (July 1, 2026 to September 30, 2026).
- For the quarter, net sales were ¥40,369 million (down 25.5% YoY) and operating income was ¥15,769 million (down 41.0% YoY).
- Ordinary income was ¥14,711 million (down 45.8% YoY), and profit attributable to owners of parent was ¥10,734 million (down 43.7% YoY).
- By product category, sales of semiconductor-related equipment were ¥23,849 million (down 42.9% YoY), services were ¥16,011 million (up 31.2% YoY), and other products were ¥508 million (up 134.7% YoY).
- The consolidated full-year FY2027 earnings forecast and annual dividend forecast remain unchanged from the estimates announced on August 6, 2026, maintaining full-year net sales of ¥290,000 million, operating income of ¥125,000 million, and a dividend forecast of ¥351 per share (interim ¥140, year-end ¥211).
🤖 AI Perspective
While consolidated net sales and all profit metrics decreased year-on-year in the first quarter, the company stated that sales progressed generally as initially planned. The decline in semiconductor-related equipment sales contrasted with an increase in service sales, which may suggest a shift in business composition. The unchanged full-year outlook indicates the company anticipates a recovery in performance in subsequent quarters.
2428|ウェルネット
599.0
▲ +0.00%
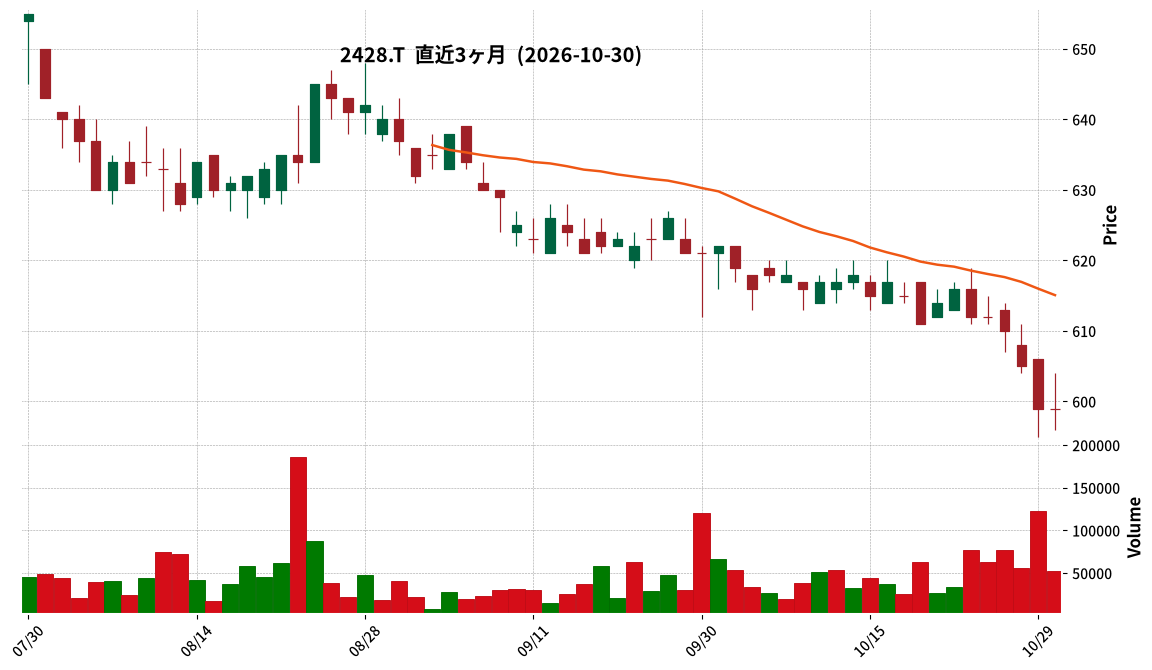
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Wellnet announced its Q1 FY2027 financial results for the period from July 1, 2026, to September 30, 2026.
- Net sales for the first quarter totaled ¥2,370 million, representing an 8.4% decrease compared to the same period last year.
- Operating profit was ¥266 million (down 25.1% year-on-year), ordinary profit was ¥295 million (down 19.9% year-on-year), and quarterly net profit was ¥224 million (down 12.0% year-on-year).
- The decrease in revenue and profit was primarily attributed to a decline in transaction volume from major clients and an increase in selling, general and administrative expenses due to personnel costs and temporary projects.
- The full-year forecast for FY2027 remains unchanged from the most recently announced figures: net sales of ¥10,500 million (up 4.4% year-on-year), operating profit of ¥1,500 million (up 6.3% year-on-year), and net profit of ¥1,150 million (up 6.3% year-on-year).
- The annual dividend forecast for FY2027 is also maintained at ¥30.50 per share (interim ¥12.50, year-end ¥18.00).
🤖 AI Perspective
While the first quarter saw a decline in both revenue and profit, the company’s unchanged full-year forecast projects an increase in both. This suggests that the company anticipates a recovery in subsequent quarters, making the nature of the factors impacting the first quarter a key point for investors. The progress of strategic initiatives, such as the OEM development of its electronic money business and DX projects for the transportation industry, could also be important for evaluating future earnings potential.
2445|タカミヤ
383.0
▲ +1.32%
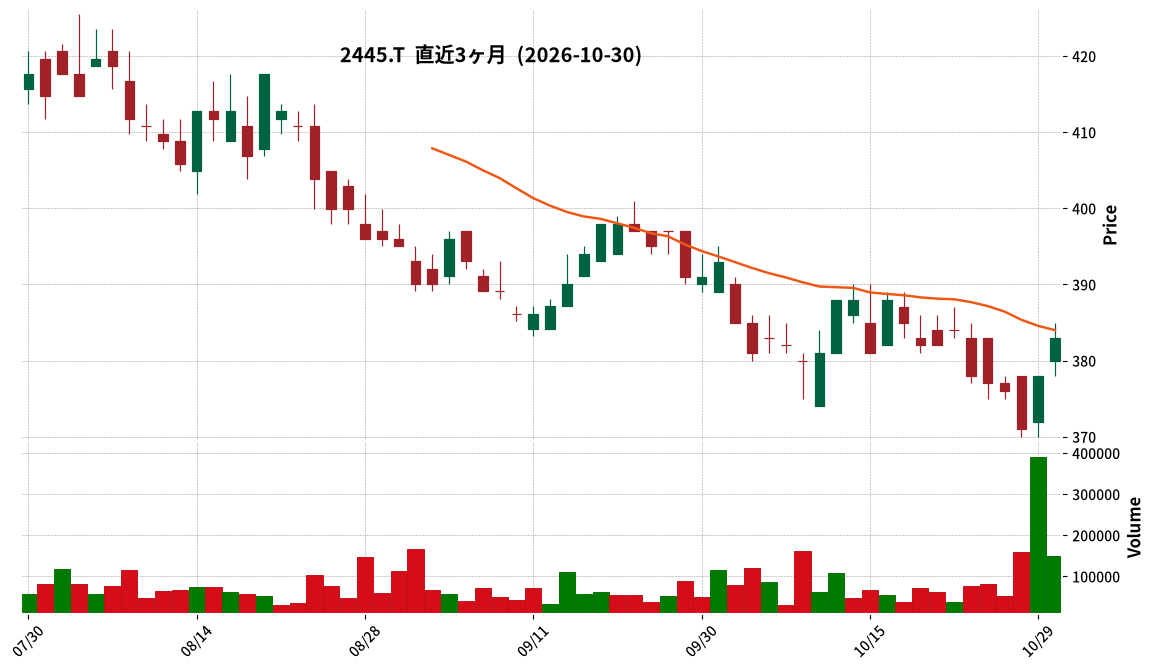
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Takamiya Co., Ltd. resolved to acquire all shares of Chuo Build Kogyo Co., Ltd. from Asahi Kasei Homes Corporation, making it a subsidiary, and signed a share transfer agreement.
- The acquisition will target Chuo Build Kogyo after a carve-out, where rights and obligations related to its residential steel frame business will be succeeded by Asahi Kasei Juko Co., Ltd.
- Chuo Build Kogyo’s primary businesses include the manufacturing, sales, and rental of temporary civil engineering and construction materials.
- Through this acquisition, the Takamiya Group will add six new equipment bases (2 in Kyushu, 1 in Chubu, 2 in Kanto, 1 in Kansai).
- The share transfer execution date is scheduled for April 1, 2027, and Chuo Build Kogyo is expected to become a consolidated subsidiary of Takamiya from the first quarter of the fiscal year ending March 2028.
- The acquisition price is undisclosed at the request of the counterparty.
🤖 AI Perspective
This acquisition appears to be a strategic move to bolster Takamiya’s “Temporary Platform Business,” aiming to expand its national network of bases and strengthen its supply system for temporary construction materials. The integration of Chuo Build Kogyo’s expertise and business foundation with the Takamiya Group could lead to synergistic effects. This addition of six new bases is a significant step towards Takamiya’s goal of establishing 50 bases nationwide over the next five years, which is worth monitoring for its impact on future growth.
3760|ケイブ
805.0
▼ -0.62%
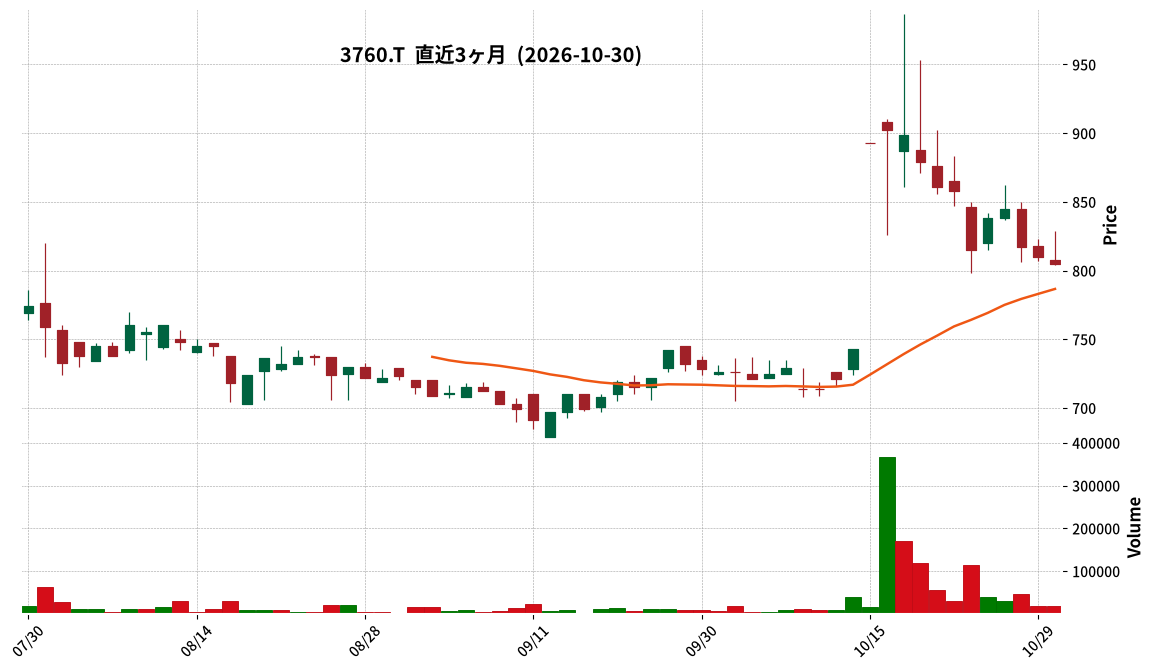
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- CAVE Inc. announced on October 30, 2026, the release of its Q1 FY2027 earnings presentation video, presentation materials, and answers to pre-submitted questions.
- Regarding shareholder return policy, the company stated its basic principle is to execute stable and continuous profit distribution while securing internal reserves for future business development and strengthening management foundations.
- The Q1 ordinary profit of 908 million yen included non-operating income of 284 million yen from canceled insurance policies and 67 million yen in dividend income; the insurance surrender value was a one-off item but factored into the full-year forecast from the outset.
- The operating profit margin for Q1 was 20.7%, attributed to increased revenue from major IP collaborations, significant reductions in fixed costs, and an increase in the proportion of external payment settlements.
- The difference between the Q1 operating profit margin and the full-year forecast of 13.8% is explained by a conservative and cautious outlook that incorporates risks such as future business uncertainty and rising procurement costs.
🤖 AI Perspective
CAVE’s proactive release of detailed explanations to investor questions post-earnings report suggests a commitment to enhancing transparency. This approach to clarifying one-off profit factors, the drivers behind a strong operating profit margin, and the shareholder return philosophy could be particularly valuable for investors seeking a deeper understanding of the company’s financial performance and strategic direction. Furthermore, the company’s acknowledgement of its P/E ratio being below the industry median and its stated intention to strengthen IR activities may indicate a strategic effort to engage more effectively with the market.
3835|eBASE
448.0
▲ +1.13%
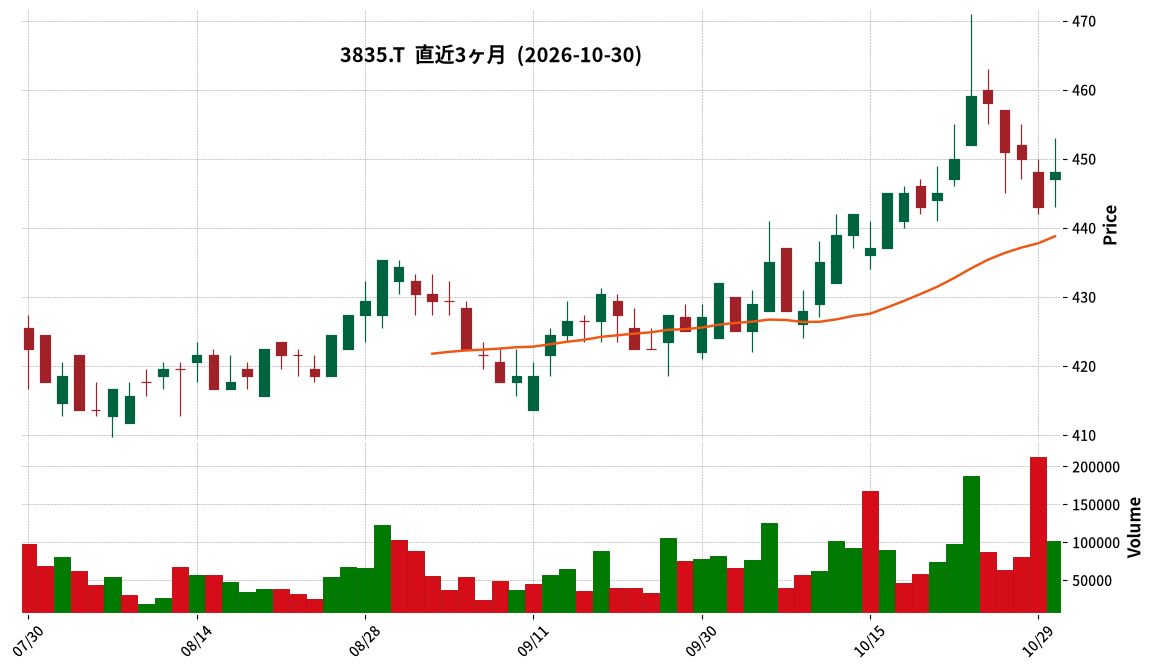
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- eBASE announced its consolidated financial results for the second quarter (interim period) of the fiscal year ending March 2027.
- For the interim period, consolidated net sales were ¥2,655 million (up 8.9% year-on-year), operating profit was ¥505 million (down 8.2%), ordinary profit was ¥534 million (down 5.9%), and profit attributable to owners of parent was ¥346 million (down 10.5%).
- The full-year dividend forecast remains ¥15.20, consisting of an interim dividend of ¥7.60 (ordinary dividend ¥6.10, 25th anniversary commemorative dividend ¥1.50) and a year-end dividend of ¥7.60 (ordinary dividend ¥6.10, 25th anniversary commemorative dividend ¥1.50).
- The consolidated full-year earnings forecast for the fiscal year ending March 2027 has been revised to: net sales of ¥5,700 million (up 8.4% year-on-year), operating profit of ¥1,340 million (down 6.4%), ordinary profit of ¥1,400 million (down 4.6%), and profit attributable to owners of parent of ¥935 million (down 8.9%).
- The company also announced today a new “Mid-Term Management Plan – Towards Performance Recovery and Sustainable Growth” covering FY2028-FY2030, stating that initiatives including price revisions and new strategies (food manufacturer penetration, e-food & housing series, DATA eBASE) have already begun in the current fiscal year.
- During the interim period, KSP-SP Co., Ltd. was newly included in the scope of consolidation.
🤖 AI Perspective
While the interim results showed increased sales but decreased profits, the upward revision of the full-year earnings forecast, even after factoring in M&A acquisition costs and advertising expenses, could suggest the company’s confidence in future growth. The concurrent announcement of the mid-term management plan, which outlines strategies such as price revisions and new business initiatives, may be seen as a clear direction for accelerating the growth of the eBASE business and aiming for performance recovery and sustainable growth. The inclusion of a new company in the scope of consolidation could also indicate proactive moves towards business expansion.
4069|G-BlueMeme
442.0
▼ -1.78%
📎 Source:G-BlueMeme Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- G-BlueMeme Co., Ltd. announced on October 30, 2026, the “Notice Regarding Determination of the Scheduled Disclosure Date for the First Quarter Financial Results for the Fiscal Year Ending March 31, 2027.”
- The scheduled disclosure date for the Q1 FY2027 financial results is November 13, 2026 (Friday).
- The Q2 (interim) FY2027 financial results are also scheduled to be disclosed on the same day, November 13, 2026.
- The delay in disclosure was due to an ongoing investigation by a special investigation committee regarding transactions with a specific business partner in past fiscal years, as previously announced on July 30, 2026.
- The company received the investigation report from the special investigation committee on September 4, 2026, disclosed the FY2026 financial results on September 30, 2026, and submitted amended securities reports for FY2026 and prior years.
- The scheduled disclosure date was determined based on the progress of financial procedures reflecting past corrections and the ongoing interim review by the accounting auditor for Q1 FY2207.
🤖 AI Perspective
This announcement provides a definitive date for the previously delayed earnings reports, indicating progress in addressing the issues that caused the delay. The simultaneous release of both Q1 and Q2 results could offer a more comprehensive view of the company’s financial status following the resolution of past accounting irregularities. Investors may find it useful to review how the company’s financial procedures and auditing processes have advanced.
4216|旭有機材
6240.0
▼ -3.41%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Asahi Yukizai announced its consolidated financial results for the second quarter (interim period) of the fiscal year ending March 2027.
- For the interim period, consolidated net sales reached 43,755 million yen (up 9.8% year-on-year), operating profit was 5,595 million yen (up 28.6%), ordinary profit was 5,605 million yen (up 26.1%), and net income attributable to owners of parent was 3,935 million yen (up 30.7%).
- Interim net income per share was 209.36 yen.
- The annual dividend forecast for the fiscal year ending March 2027 is 180.00 yen in total, consisting of an interim dividend of 90.00 yen and a year-end dividend of 90.00 yen, with no revisions from the latest forecast.
- The full-year consolidated performance forecast for the fiscal year ending March 2027 projects net sales of 93,000 million yen (up 16.1% year-on-year), operating profit of 12,000 million yen (up 58.3%), ordinary profit of 12,300 million yen (up 54.6%), net income attributable to owners of parent of 8,200 million yen (up 146.6%), and net income per share of 436.33 yen.
🤖 AI Perspective
The interim period showed significant growth across all key financial metrics compared to the previous year. The recovery in semiconductor factory construction investment in the U.S. appears to have contributed to the increased sales of core products. Both the piping systems and resin businesses achieved higher revenues and profits, suggesting that passing on increased raw material costs to sales prices also played a role in improving profitability.
6472|NTN
359.1
▼ -2.76%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- NTN Corporation reported consolidated net sales of 413,579 million yen for the second quarter of the fiscal year ending March 2027, representing a 2.8% increase year-on-year.
- Operating income for the same period was 17,371 million yen (+35.0% YoY), and ordinary income was 12,202 million yen (+39.8% YoY).
- Net income attributable to owners of parent reached 5,461 million yen, marking a 76.2% increase from the previous year.
- The consolidated full-year forecast for March 2027 was revised, with net sales projected at 825,000 million yen (-0.2% YoY) and operating income at 33,000 million yen (+6.3% YoY).
- An interim dividend of 6.50 yen per share is planned, compared to 5.50 yen in the prior year’s interim period.
🤖 AI Perspective
NTN’s Q2 FY2027 results show a notable improvement across key profitability metrics, with significant increases in operating and net income, which may suggest effective cost management and pricing strategies. The upward revision of the full-year operating income forecast, despite a slight decrease in net sales forecast, along with an increased interim dividend, could indicate a positive outlook on future performance. Investors may find these improvements in profitability and the revised outlook noteworthy.
8052|椿本興
2967.0
▲ +0.82%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Tsukamoto Corp. announced an increase in its interim dividend following a resolution at today’s Board of Directors meeting.
- The determined interim dividend is ¥40.00 per share, consisting of an ordinary dividend of ¥30.00 and a commemorative dividend of ¥10.00.
- This amount is an increase from the previously forecast interim dividend of ¥30.00 per share (ordinary dividend ¥30.00), which was announced on May 8, 2026.
- The actual interim dividend for the previous fiscal year (FY2026 March interim) was ¥20.00 per share (ordinary dividend ¥20.00).
- The total dividend amount is ¥746 million, with an effective date of December 2, 2026, and the dividend source is retained earnings.
- The company cited its 110th anniversary in October 2026 and strong recent business performance as reasons for the increase, adding a ¥10 commemorative dividend to express gratitude to shareholders.
- The year-end dividend forecast remains unchanged at this time, with the company stating it will consider investments for medium-to-long-term growth and the need for internal reserves to stabilize its financial foundation, and will make a decision after confirming the performance in the second half of the fiscal year.
🤖 AI Perspective
Tsukamoto Corp.’s decision to increase its interim dividend, including a commemorative dividend for its 110th anniversary, may suggest a commitment to shareholder returns. The announcement also highlights the company’s strong current business performance as a contributing factor, which could be a positive signal for investors assessing the company’s financial health and growth trajectory. However, with the year-end dividend forecast currently unchanged, investors may wish to monitor the company’s performance in the second half of the fiscal year for further indications of future dividend policy.
8783|abc
38.0
▲ +2.70%
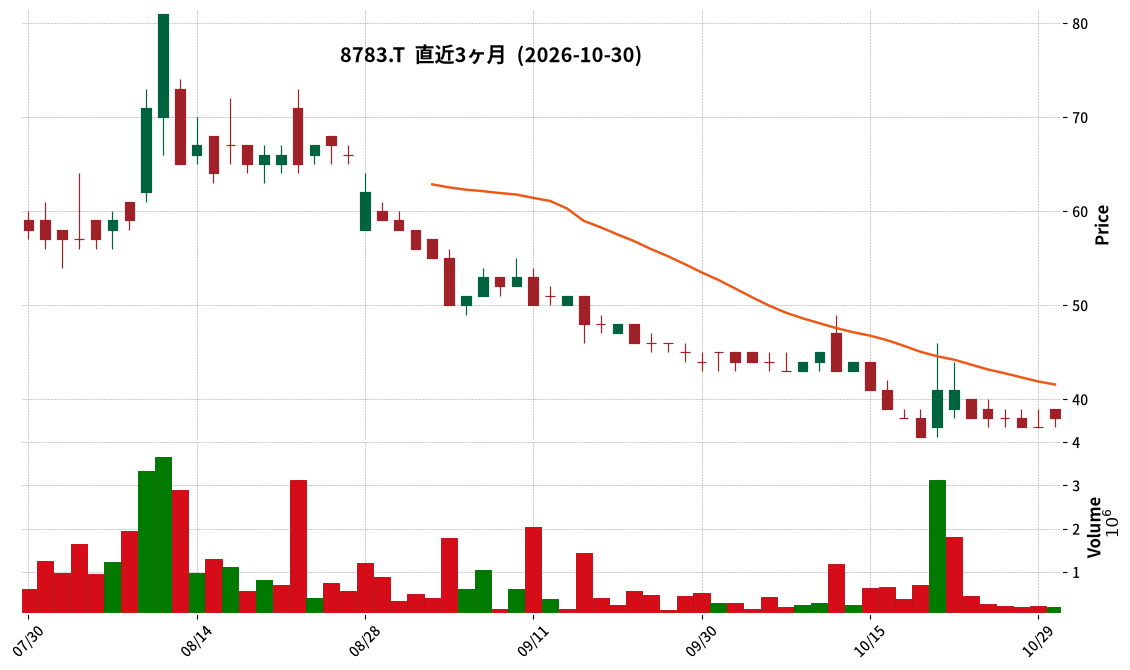
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- abc Co. has signed partnership agreements with four companies, totaling over 500 stores, for its shareholder benefit point service “Yutai no Izumi.”
- The partnered industries include dining, accommodation, fitness, and relaxation.
- Additionally, agreements on benefit content have been reached with three other companies, with negotiations for partnership agreements ongoing.
- Use of the service at partner locations is scheduled to commence sequentially from partner companies starting November 5, 2026 (tentative).
- Shareholder benefit point usage on the dedicated app will be temporarily suspended from November 1, 2026, 0:00 JST to November 4, 2026, 23:59 JST, for point transfer work.
- The impact of this matter on the consolidated performance for the fiscal year ending August 2027 is expected to be minor, with no change from the disclosure on October 14.
🤖 AI Perspective
The expansion of partnerships for the “Yutai no Izumi” service could suggest an increased utility and attractiveness for shareholders, potentially enhancing shareholder value through more diverse redemption options. The broad range of industries involved may indicate an effort to cater to a wider array of shareholder preferences, which could be a positive factor for service adoption. Investors might monitor the continued growth of partner establishments as an indicator of the service’s momentum.
9362|兵機海運
3975.0
▲ +1.66%
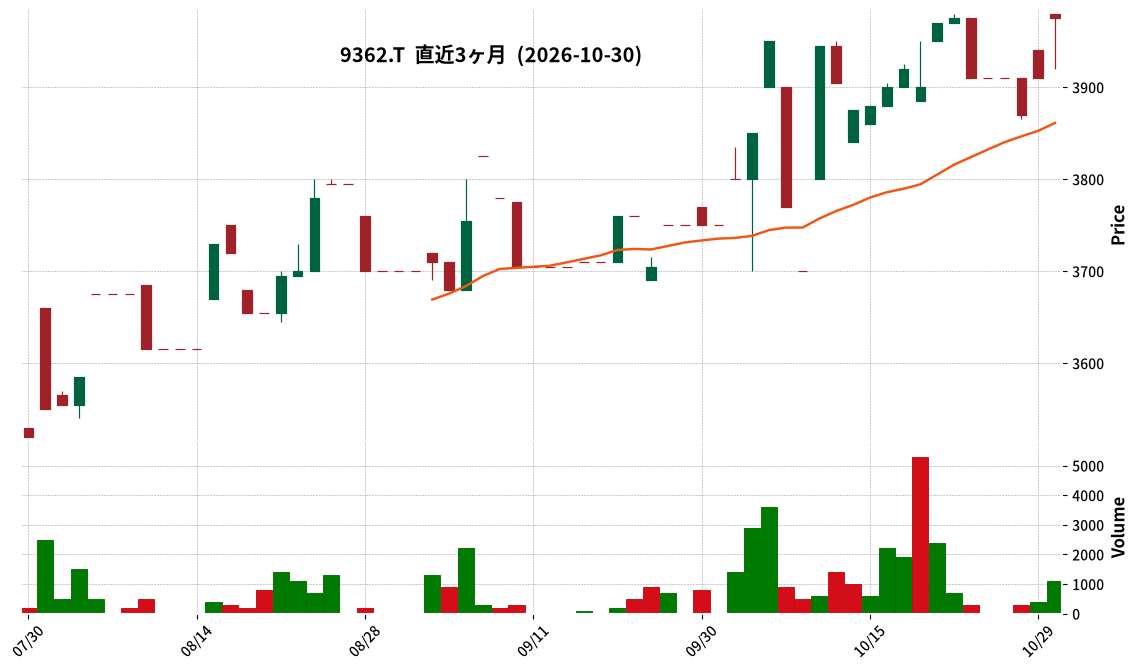
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Hyoki Kaiun Co., Ltd. has announced its unaudited non-consolidated financial results for the second quarter of the fiscal year ending March 2027.
- For the interim period, net sales were ¥7,954 million (up 19.7% year-on-year), operating profit was ¥234 million (up 6.1%), ordinary profit was ¥286 million (up 10.8%), and interim net profit reached ¥242 million (up 35.9%).
- Within the marine transportation business, the overseas shipping segment saw increased sales and profit, while the domestic shipping segment experienced decreases in both.
- Both the port transportation and warehousing segments achieved increased sales and profits.
- The full-year earnings forecast has been revised upwards, projecting net sales of ¥16,500 million (up 23.2% from the previous fiscal year), operating profit of ¥530 million (up 21.4%), ordinary profit of ¥600 million (up 20.1%), and net profit of ¥440 million (up 10.8%).
- Interim earnings per share were ¥201.99, and the equity ratio at the end of the period was 43.9%.
🤖 AI Perspective
Hyoki Kaiun’s Q2 FY2027 results show solid growth across key financial metrics, with interim net profit notably rising by 35.9% year-on-year. The upward revision of the full-year forecast suggests management’s positive outlook, likely driven by strong performance in its overseas shipping and port transportation/warehousing segments. While the domestic shipping segment faced some headwinds, the overall robust performance across other segments could indicate a diversified operational strength for the company.
9679|ホウライ
2135.0
▲ +0.28%
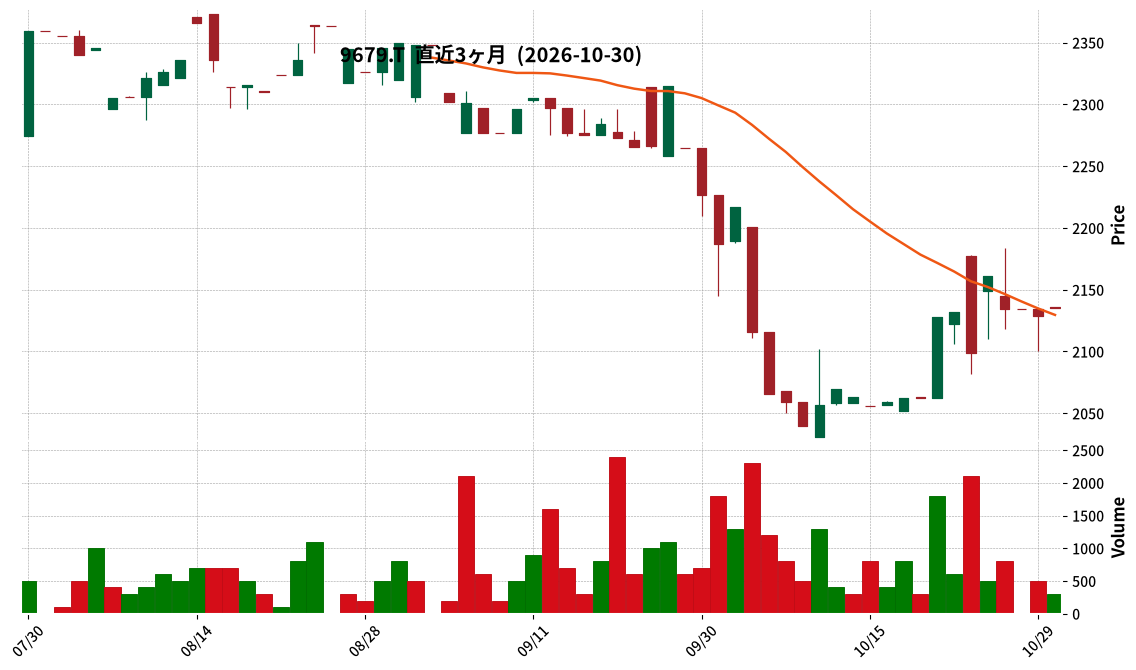
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- HORAI Co., Ltd. announced its non-consolidated financial results for the fiscal year ended September 2026.
- Operating revenue increased by 8.3% year-on-year to ¥6,618 million, operating income by 5.9% to ¥653 million, ordinary income by 4.6% to ¥768 million, and net income by 9.7% to ¥546 million.
- Earnings per share (EPS) for the period was ¥130.29 (compared to ¥118.89 in the previous fiscal year).
- The annual dividend per share was raised by ¥2 from the previous year’s ¥24, reaching ¥26 (year-end).
- For the fiscal year ending September 2027, the company forecasts operating revenue of ¥6,800 million (up 2.7% year-on-year), operating income of ¥675 million (up 3.3%), ordinary income of ¥775 million (up 0.8%), and net income of ¥540 million (down 1.1%).
- As of the end of September 2026, total assets stood at ¥19,997 million, net assets at ¥10,533 million, and the equity ratio was 52.7%.
🤖 AI Perspective
HORAI’s FY2026 results show a robust increase across key financial metrics, driven by revenue growth in all business segments. The increase in the annual dividend may suggest management’s confidence in the company’s performance and commitment to shareholder returns. While the forecast for FY2027 anticipates continued revenue growth, the slight projected decrease in net income could indicate potential shifts in expenses or other factors worth monitoring by investors.
4685|菱友システム
2665.0
▼ -2.67%
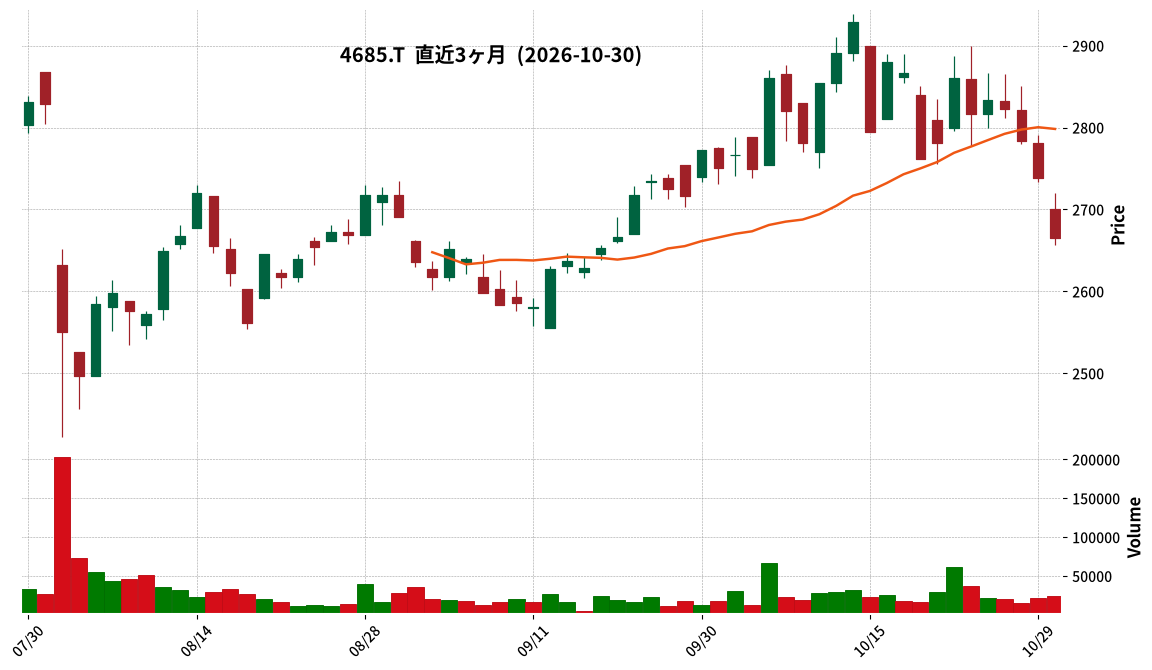
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Ryoyu Systems Corporation announced its consolidated financial results for the second quarter of the fiscal year ending March 2027 on October 30, 2026.
- For the interim period, consolidated net sales were ¥20,162 million, a 0.7% increase compared to the same period in the previous year.
- Consolidated operating profit was ¥1,945 million (down 11.8% YoY), ordinary profit was ¥2,045 million (down 9.6% YoY), and net income attributable to owners of parent was ¥1,285 million (down 19.3% YoY).
- Interim net income per share was ¥100.72 (compared to ¥124.85 in the prior interim period).
- The annual dividend forecast for the fiscal year ending March 2027 is a total of ¥100.00, consisting of ¥50.00 for the second quarter end and ¥50.00 for the fiscal year end.
- The consolidated full-year earnings forecast for the fiscal year ending March 2027 has been revised to net sales of ¥48,000 million (+11.0% YoY), operating profit of ¥5,450 million (-0.7% YoY), ordinary profit of ¥5,650 million (+0.5% YoY), and net income attributable to owners of parent of ¥3,600 million (-7.9% YoY).
🤖 AI Perspective
Ryoyu Systems’ Q2 FY2027 results showed a slight increase in net sales but a decline in all profit categories. This is attributed to increased selling, general, and administrative expenses related to personnel development and the early integration of new employees. Such investments in talent and technology, crucial for adapting to new technologies and strengthening competitiveness in the IT services industry, may have temporarily impacted profitability. The revised full-year forecast suggests that these strategic investments are being made with a view towards long-term growth, which is a point worth monitoring for investors.
1939|四電工
2149.0
▼ -6.03%
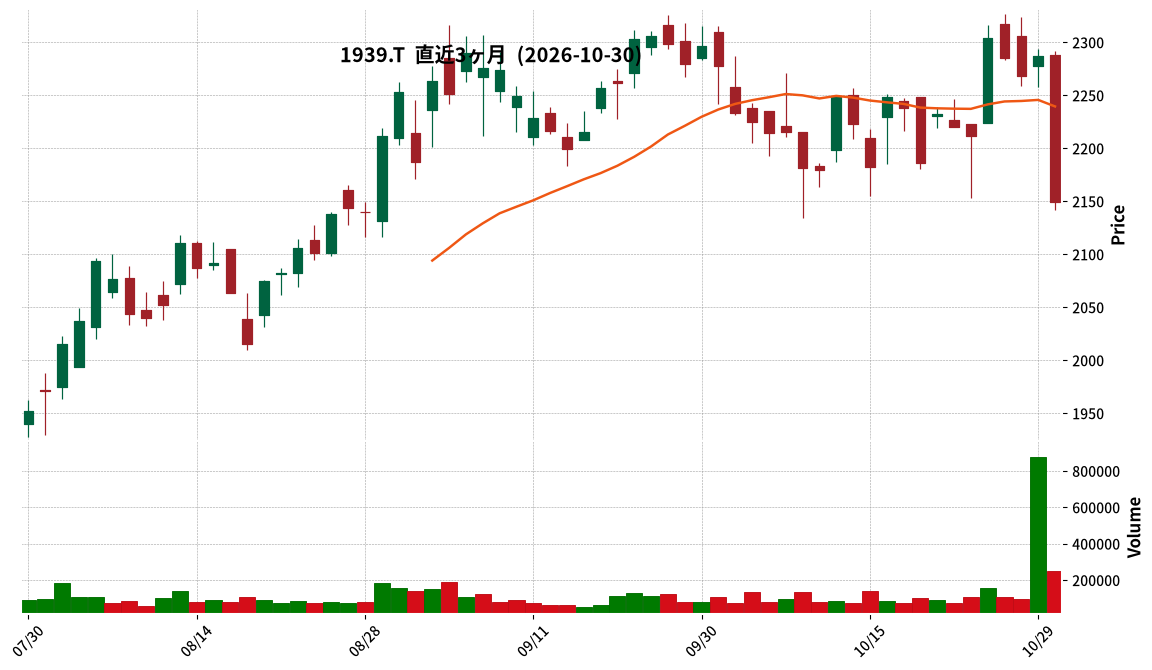
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Yondenko announced on October 30, 2026, that its Board of Directors resolved to revise the consolidated earnings forecast for the fiscal year ending March 2027.
- The consolidated net sales forecast was revised upwards from ¥108,000 million to ¥110,000 million, operating profit from ¥9,400 million to ¥11,000 million, ordinary profit from ¥9,900 million to ¥11,500 million, and profit attributable to owners of parent from ¥6,600 million to ¥7,900 million.
- The interim dividend forecast for the fiscal year ending March 2027 was revised from ¥42.00 per share to ¥50.00 per share.
- The year-end dividend forecast for the fiscal year ending March 2027 was also revised, increasing the annual dividend from the previously announced ¥84.00 per share to ¥100.00 per share (interim ¥50.00, year-end ¥50.00).
- The reason for the earnings forecast revision was attributed to steady construction progress through the second quarter and the current status of order backlogs.
🤖 AI Perspective
The upward revision of the earnings forecast suggests favorable operational performance, potentially driven by efficient project execution and a strong pipeline of ongoing projects. The increase in dividends indicates the company’s commitment to shareholder returns, aligning with its “Medium-Term Management Plan 2030” which outlines a strategy for enhancing capital efficiency and optimizing capital structure. This move may be viewed by investors as a tangible outcome of the company’s strategic financial management.
4193|ファブリカHD
1950.0
▲ +0.83%
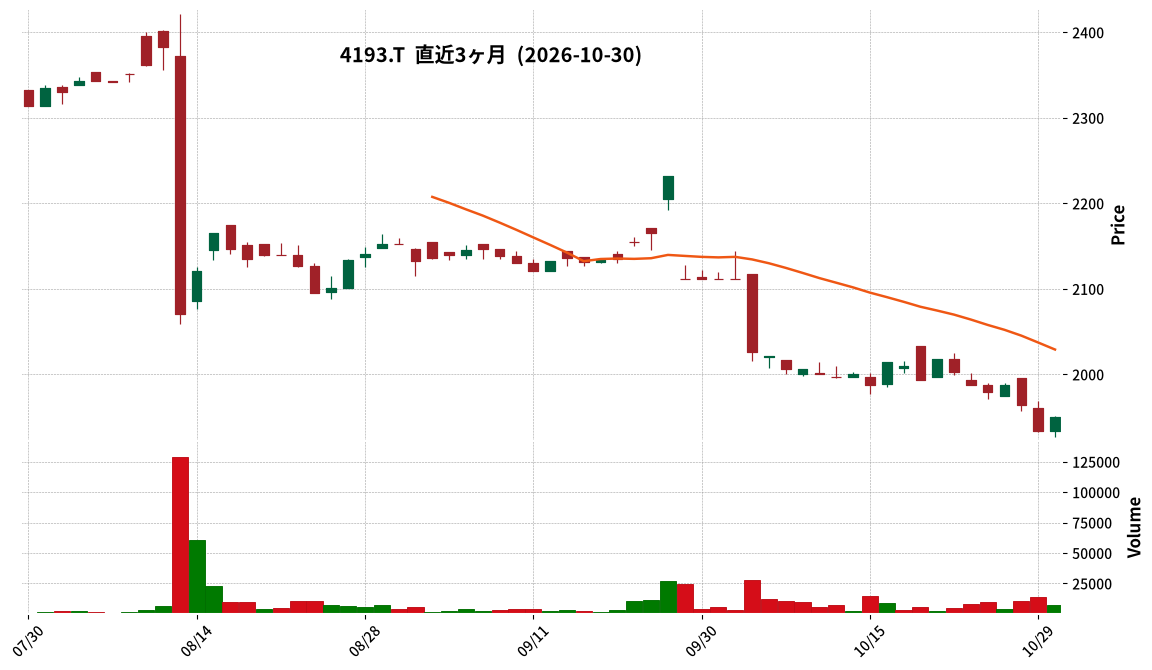
📎 Source:ファブリカHD Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Fabrica Holdings Co., Ltd. resolved to acquire shares of TRES Co., Ltd. at a board meeting held on October 30, 2026.
- Following this acquisition, Fabrica HD’s ownership stake in TRES will exceed 40%, and with the dispatch of executives, TRES will become a consolidated subsidiary of Fabrica HD.
- TRES operates “Dracule,” a vehicle delivery matching platform, aiming to resolve the shortage of vehicle transport providers and enable swift, low-cost delivery arrangements.
- Fabrica HD will acquire 1,470 shares, resulting in a post-acquisition voting rights ratio of 49.00%. The acquisition price is undisclosed but is less than 15% of net assets and does not meet disclosure criteria.
- The scheduled date for the share acquisition is November 30, 2026.
🤖 AI Perspective
This acquisition suggests Fabrica HD’s strategic move to expand its business domain by integrating TRES’s vehicle delivery matching platform with its existing automotive platform business, citing high affinity and complementarity. The company appears to be addressing logistics infrastructure challenges in the used car distribution market. Investors may want to monitor how this consolidation contributes to the overall corporate value and the specific synergies achieved through this new subsidiary.
6863|ニレコ
1020.0
▼ -3.41%
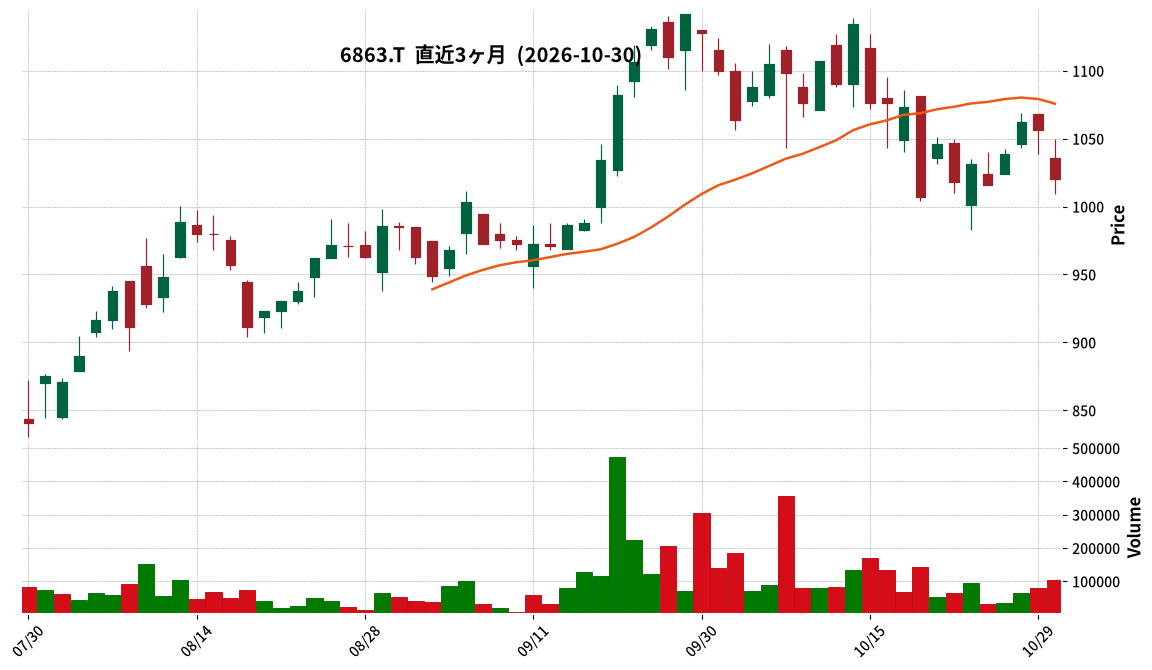
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Nireco announced the acquisition of shares in YGK Corporation, making it a subsidiary, following a board resolution on October 30, 2026.
- YGK Corporation designs, manufactures, and sells semiconductor wafer inspection equipment, and is also engaged in developing inspection technologies for next-generation materials such as SiC, GaN, and glass substrates.
- Nireco will acquire 400 shares of YGK Corporation’s common stock for 1,600 million yen, resulting in a 100.0% voting rights ownership.
- The share transfer execution date is scheduled for November 20, 2026.
- YGK Corporation’s performance for the fiscal year ended June 2026 included net sales of 1,016 million yen, operating income of 443 million yen, and net income of 297 million yen.
🤖 AI Perspective
Nireco’s acquisition of YGK Corporation may suggest a strategic move to strengthen its presence in growth sectors, aligning with its “NIRECO-VISION 100” mid-term management plan. Gaining advanced semiconductor wafer inspection technology, especially for next-generation materials, could complement Nireco’s existing technology base and expand its business opportunities. The fact that YGK is a high-profit business also makes its potential impact on Nireco’s consolidated performance worth monitoring.
7897|ホクシン
114.0
▲ +0.88%
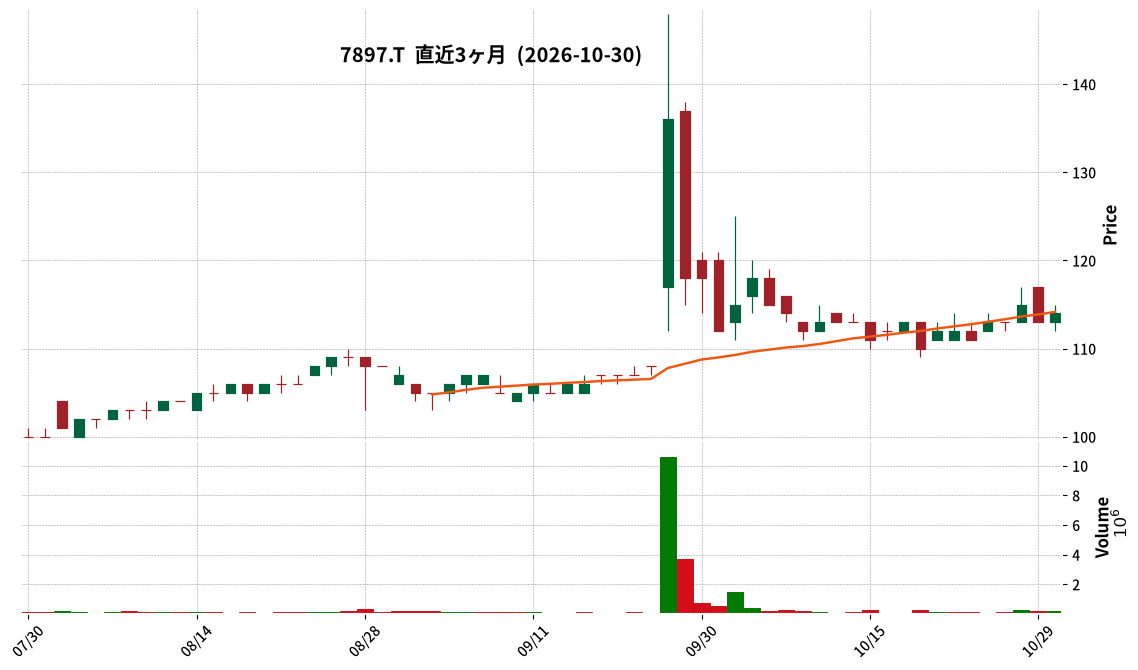
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Hokushin announced its financial results for the second quarter (interim period) of the fiscal year ending March 2027.
- Net sales for the interim period were JPY 5,433 million, a 7.3% increase compared to the same period last year.
- Operating profit reached JPY 182 million and ordinary profit JPY 183 million, marking a turnaround from losses in the prior year’s interim period.
- Interim net profit amounted to JPY 122 million, an improvement from an interim net loss of JPY 90 million in the previous year.
- Earnings per share for the interim period was JPY 4.31.
- The full-year forecast for FY2027 remains unchanged, projecting net sales of JPY 11,400 million, operating profit of JPY 210 million, ordinary profit of JPY 190 million, and net profit of JPY 130 million, with earnings per share of JPY 4.59.
- The annual dividend forecast for FY2027 is JPY 2.00 per share for the fiscal year-end, totaling JPY 2.00.
🤖 AI Perspective
Hokushin’s Q2 FY2027 results highlight a notable increase in net sales and a return to profitability across key profit metrics. This performance may suggest that proactive pricing adjustments and increased demand ahead of price revisions have contributed to improved earnings. However, the company has maintained its full-year forecast, which could indicate a cautious outlook regarding future market conditions and geopolitical risks such as the situation in the Middle East.
3657|ポールHD
340.0
▼ -0.29%
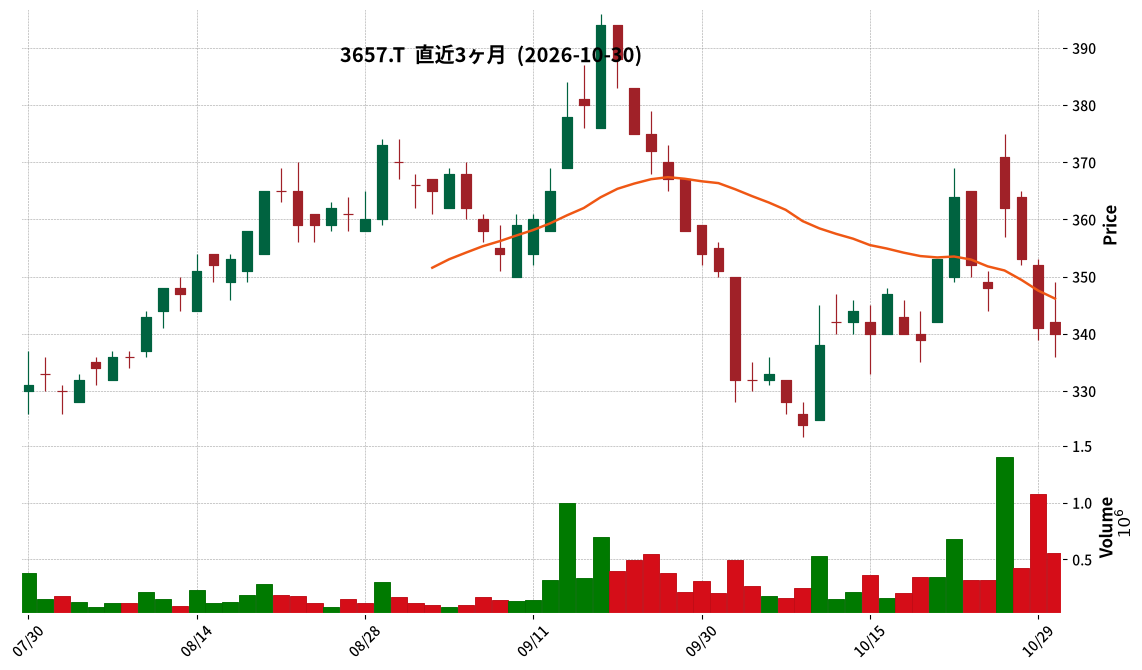
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Pole HD announced on October 30, 2026, answers to questions from investors following the announcement of its Q2 FY2027 financial results.
- For the first half of FY2027, both domestic and overseas solutions performed strongly, exceeding initial plans for net sales, operating profit, ordinary profit, and net profit for the quarter.
- In overseas solutions, the effects of business structural reforms implemented since the previous fiscal year became evident, leading to improved profitability through the reorganization of less profitable businesses and optimization of organizational structures.
- The full-year performance forecast for FY2027 remains unchanged from the initial announcement. While some impact is expected in domestic solutions, overseas solutions are projected to compensate, with the company anticipating achieving its operating profit target.
- For the next fiscal year and beyond, the company aims for sustainable growth through enhancing productivity in existing businesses, advancing services utilizing AI, and expanding into domestic tech areas including cybersecurity.
🤖 AI Perspective
This Q&A suggests that Pole HD is effectively demonstrating the results of its business structural reforms, with the consistent improvement in profitability, especially within its overseas solutions, being a key point of interest for investors. While first-half results exceeded plans, the decision to maintain the full-year forecast despite short-term operational day impacts in domestic solutions, alongside continued improvement in overseas operations, indicates a stabilizing effect from its balanced business portfolio. Furthermore, the company’s approach to leveraging AI technology as a means for transitioning to high-value-added services, while emphasizing the importance of human sensory value in game debugging, provides crucial insight into its competitive strategy in the AI era.
3647|アスリナ
117.0
▲ +1.74%
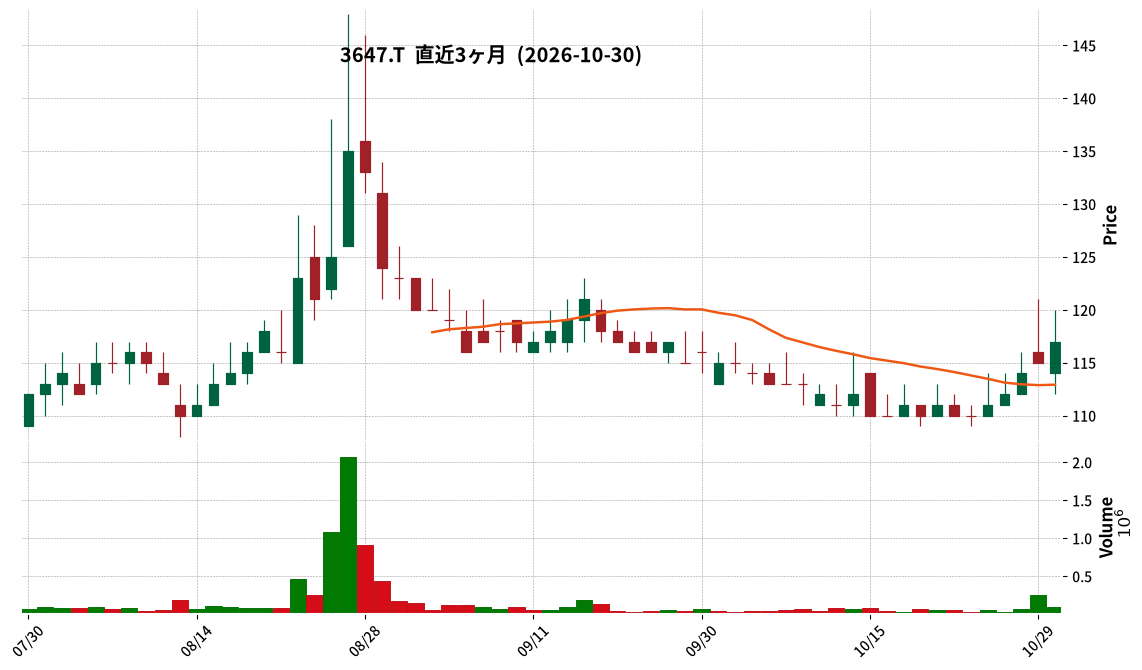
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Athlina Co., Ltd. resolved to enter into a strategic business alliance agreement with CHECKMATE JAPAN Corporation for new entry into the AI data center business at its Board of Directors meeting on October 30, 2026.
- This alliance is part of Athlina Group’s efforts to reallocate management resources and establish a diversified revenue base.
- CHECKMATE JAPAN Corporation is a Japanese entity linked with CHECKMATE GOVERNMENT RELATIONS LLC, based in Washington D.C., USA, and is promoting AI data center development projects in Japan with a planned power capacity exceeding 300MW.
- Under the alliance, both companies will discuss and explore new entry into and development of AI data center business, securing land and power infrastructure, procuring advanced GPUs, building revenue models, and collaborating with domestic and international investors and partners.
- As of now, specific business entry, joint development, capital investment, or fundraising are undetermined, and the impact on the company’s consolidated performance for the August 2027 fiscal year is currently undecided.
🤖 AI Perspective
Athlina’s decision to enter the AI data center business, a growth sector, signals a strategic shift aimed at addressing its recent performance stagnation and volatility. The collaboration with CHECKMATE JAPAN, which has already invested in power-related construction costs for large-scale AI data center projects, may suggest a path towards concrete business implementation. However, as the detailed business plan and financial impact are yet to be determined, future disclosures will be worth monitoring for investors.
244A|G-グロースエクスパ
1179.0
▲ +0.08%
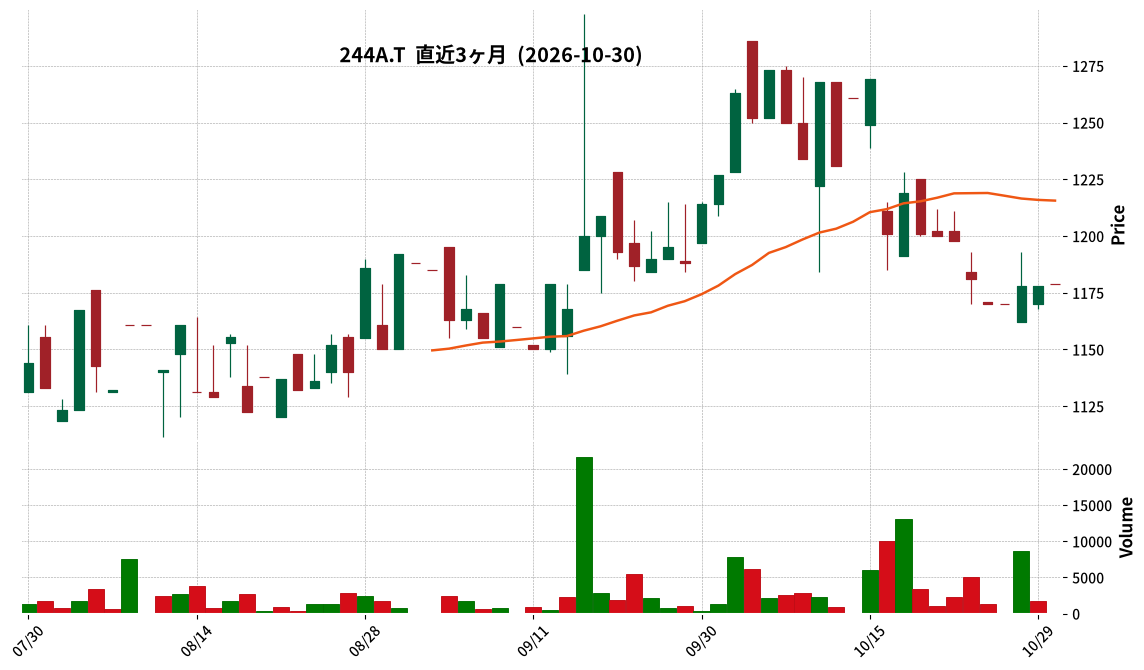
📎 Source:G-グロースエクスパ Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- For the fiscal year ended August 2026, the company recorded ¥95 million in special gains from the sale of investment securities and ¥26 million in special losses from impairment of investment securities, clarifying these as temporary items.
- The company states that its core earning power should be assessed based on operating profit of ¥503 million (operating profit margin of 10.8%), which excludes these special gains and losses.
- For the fiscal year ending August 2027, the company forecasts a net profit of ¥338 million (a 14.5% decrease), while projecting an operating profit of ¥523 million (a 3.8% increase).
- The improvement in gross profit margin during Q4 FY2026 is attributed to project composition, selective project acceptance emphasizing profitability, progress in insourcing, and enhanced productivity through AI-driven development.
- The number of new client accounts increased to 28 in FY2026 (up from 15 in the prior period), primarily through product/service introductions, referrals from existing clients, and strategic dialogues with management via the Social Value Transformation Institute (VXI).
- The DX promotion support business is projected to achieve ¥4,336 million in sales (a 20.3% increase) in FY2027, primarily driven by expanding projects with existing clients and increasing consulting engagements with new clients via VXI collaboration.
- Costs associated with office expansion in FY2027, both temporary and ongoing, are already factored into the performance forecast, with temporary expenses expected to occur mainly in the first half, particularly Q2.
- The company views AI advancements as an opportunity to streamline system development and expand applicable business areas, having launched “GxRaptor,” an AI agent construction service, and secured multiple projects.
- Services for India’s semiconductor industry leverage expertise in AI-driven development productivity, quality, and manufacturing site systems cultivated domestically, supporting semiconductor equipment manufacturers entering the Indian market.
- The medium-term management plan, to be announced at the end of November 2026, will outline the growth trajectory beyond the FY2027 initiatives presented in this earnings release, detailing the overall growth strategy and target performance levels amidst the proliferation of generative AI.
- Progress in the “business transformation phase” can be confirmed by the growth in sales of the DX promotion support business (projected 20.3% increase in FY2027), among other indicators.
🤖 AI Perspective
G-Growth xPartners’ Q&A session suggests a clear distinction between one-off special gains/losses and core operating profit, aiming to highlight the stability of its underlying business growth. For FY2027, the company appears to be positioning the expansion of existing client engagements, new client acquisition in its DX promotion support business, and productivity enhancements through AI-driven development and insourcing as key growth drivers. Investors may find it worthwhile to monitor how the company’s “business transformation phase” progresses and how its strategy to leverage AI as an opportunity is further articulated in the upcoming medium-term management plan.
6946|日アビオ
5910.0
▼ -9.22%
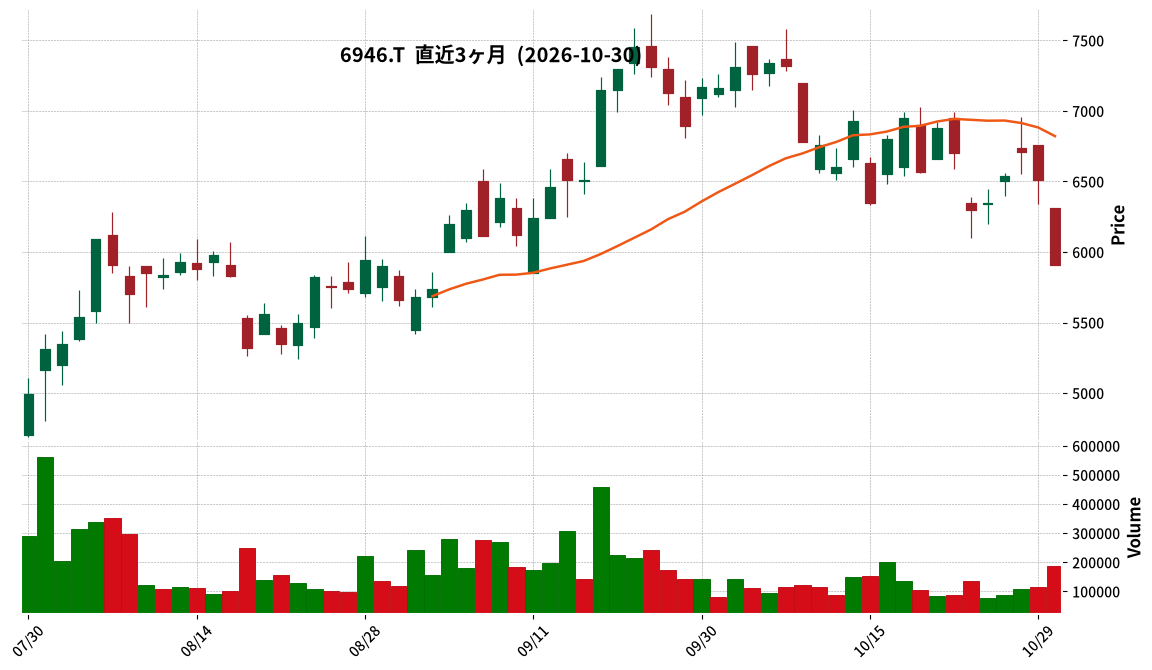
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Japan Avio Co., Ltd. has announced its consolidated financial results for the second quarter (interim period) of the fiscal year ending March 2027.
- For the interim period, consolidated financial results showed Net Sales of ¥17,948 million (up 41.3% year-on-year), Operating Profit of ¥3,849 million (up 94.6%), Ordinary Profit of ¥3,738 million (up 96.5%), and Net Income Attributable to Owners of Parent of ¥2,548 million (up 96.0%).
- By segment, Information Systems recorded Net Sales of ¥15,084 million (up 48.5% year-on-year) and Segment Profit of ¥3,541 million (up ¥1,731 million year-on-year). Electronic Devices recorded Net Sales of ¥2,863 million (up 12.5% year-on-year) and Segment Profit of ¥307 million (up ¥139 million year-on-year).
- The consolidated full-year forecast for FY2027 has been revised upwards, projecting Net Sales of ¥35,000 million (up 19.9% year-on-year), Operating Profit of ¥7,200 million (up 30.5%), Ordinary Profit of ¥6,900 million (up 28.8%), and Net Income Attributable to Owners of Parent of ¥4,900 million (up 28.3%).
- The year-end dividend forecast for FY2027 has been increased to ¥15.00, compared to ¥10.00 for FY2026.
🤖 AI Perspective
Japan Avio’s interim results show substantial year-on-year increases across sales and profit metrics, with the Information Systems segment being a significant driver of this performance, potentially benefiting from strengthened defense-related investments. The upward revision of the full-year forecast and the increased dividend forecast could suggest management’s confidence in sustained positive performance. These figures may be worth monitoring for investors interested in the defense and electronics sectors.
💡 Start investing with IR insights


※ 本ページには広告が含まれます(PR)
Disclaimer: This article is for informational purposes only and does not constitute investment advice. All investment decisions are at your own risk.
コメント