
📌 Today’s Highlights
Today we cover 53 IR announcements. Notable among them: G-NPC (6255), ビックカメラ (3048), ヴィッツ (4440). Use the table of contents below to navigate to each company.
- 6255|G-NPC
- 3048|ビックカメラ
- 4440|ヴィッツ
- 9381|エーアイテイー
- 6908|イリソ電子工業
- 7981|タカラスタン
- 9835|ジュンテンド
- 8127|ヤマトインター
- 9313|丸八倉
- 9974|ベルク
- 9982|タキヒヨー
- 1997|暁飯島
- 2747|北雄ラッキー
- 3201|ニッケ
- 7713|シグマ光機
- 137A|G-Cocolive
- 2157|コシダカHD
- 2669|カネ美食品
- 2687|CVSベイ
- 2698|キャンドゥ
- 2722|IKホールディングス
- 2928|A-RIZAP G
- 3192|白鳩
- 3627|テクミラ
- 3815|G-メディア
- 3996|サインポスト
- 4187|大有機化
- 4443|Sansan
- 4760|アルファ
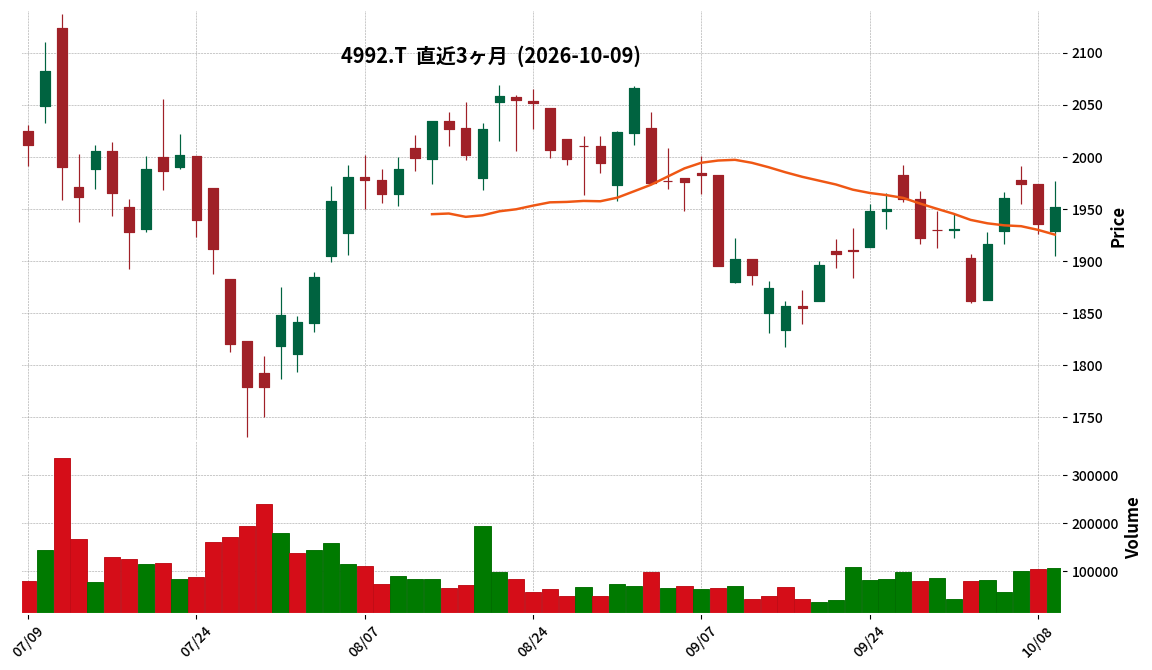
- 4992|北興化
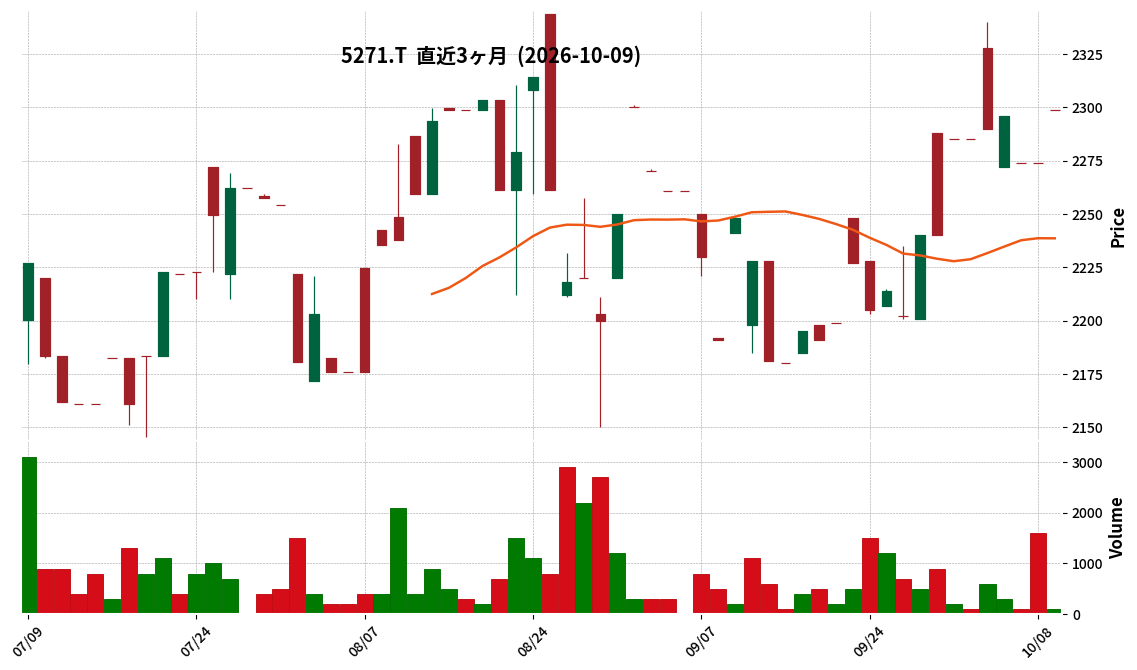
- 5271|トーヨーアサノ
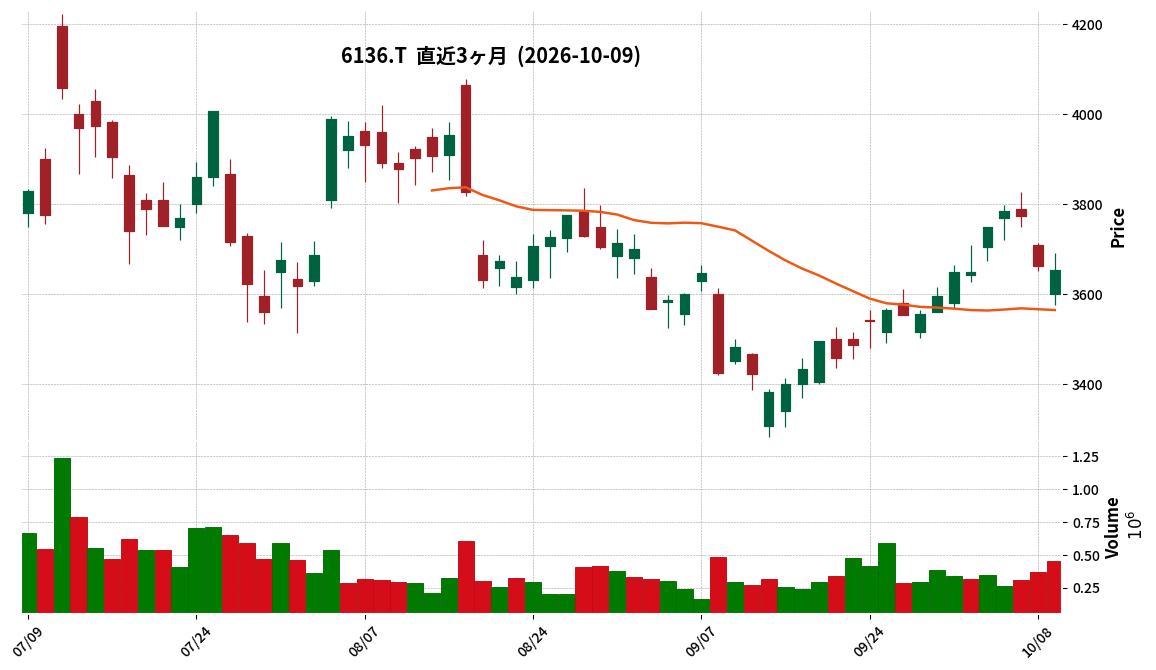
- 6136|OSG
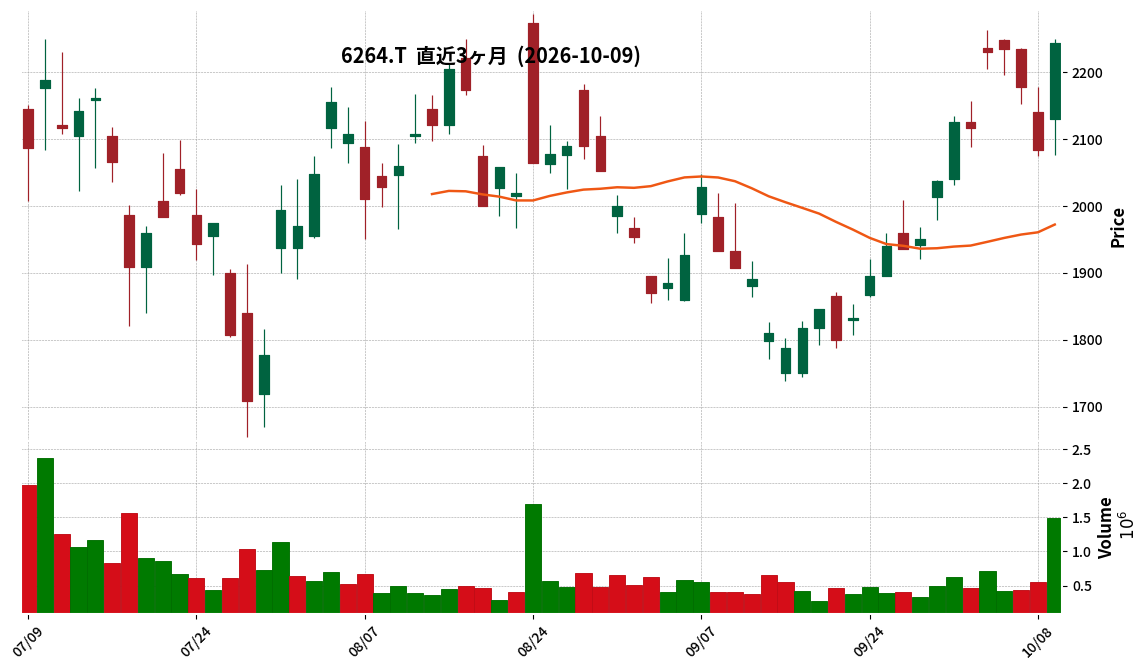
- 6264|マルマエ
- 6289|技研製作所
- 6668|アドテック プラズマ
- 6814|古野電気
- 7069|G-サイバー・バズ
- 7370|G-Enjin
- 7501|ティムコ
- 7427|エコーTD
- 2751|テンポスHD
- 3063|G-jGroup
- 3550|G-スタジオアタオ
- 3936|G-グローバルウェイ
- 4240|クラスターT
- 5341|ASAHI EITO
- 6506|安川電
- 9270|G-バリュエンスHD
- 2735|ワッツ
- 9972|アルテック
- 7463|アドヴァングループ
- 3454|ファーストブラザーズ
- 3907|シリコンスタジオ
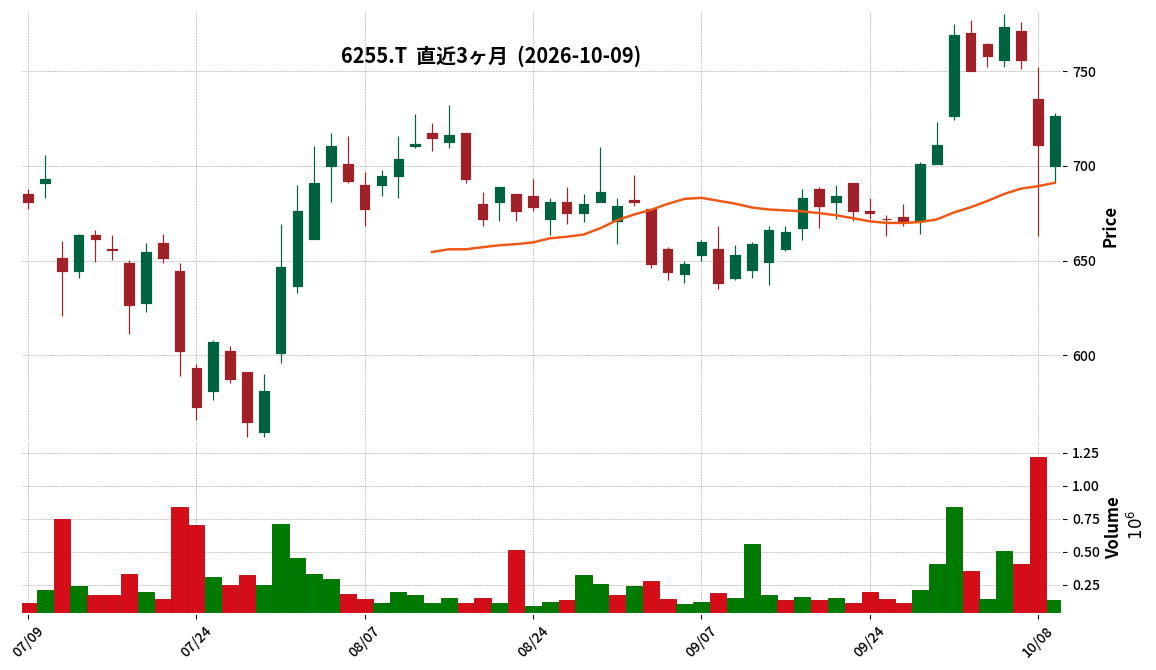
6255|G-NPC
726.0
▲ +2.11%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- For the fiscal year ended August 2026, consolidated net sales were ¥5,811 million, representing a 37.3% decrease year-on-year and a 27.5% decrease from the initial forecast.
- Net income attributable to owners of parent was ¥481 million, a 63.7% decrease year-on-year and a 9.4% decrease from the initial forecast.
- The gross profit margin improved to 34.8% from 33.4% in the previous fiscal year, exceeding the initial forecast of 24.4%.
- A year-end dividend of ¥10 per share is planned, as initially scheduled.
- The mid-term management plan targets total net sales of ¥60,495 million (average ¥12,099 million annually) over the five years from FY2027 to FY2031.
🤖 AI Perspective
The significant decrease in net sales and net income for FY2026 is attributed primarily to delays in large domestic projects and postponed orders for solar panel recycling equipment. However, the improvement in gross profit margin, driven by high-margin projects and cost reduction measures, is noteworthy. Investors may find it worthwhile to monitor the company’s initiatives in growth markets such as perovskite solar cell manufacturing equipment and solar panel recycling equipment, as well as efforts to diversify its customer and market portfolio, as outlined in the mid-term management plan, which could be key to future performance recovery.
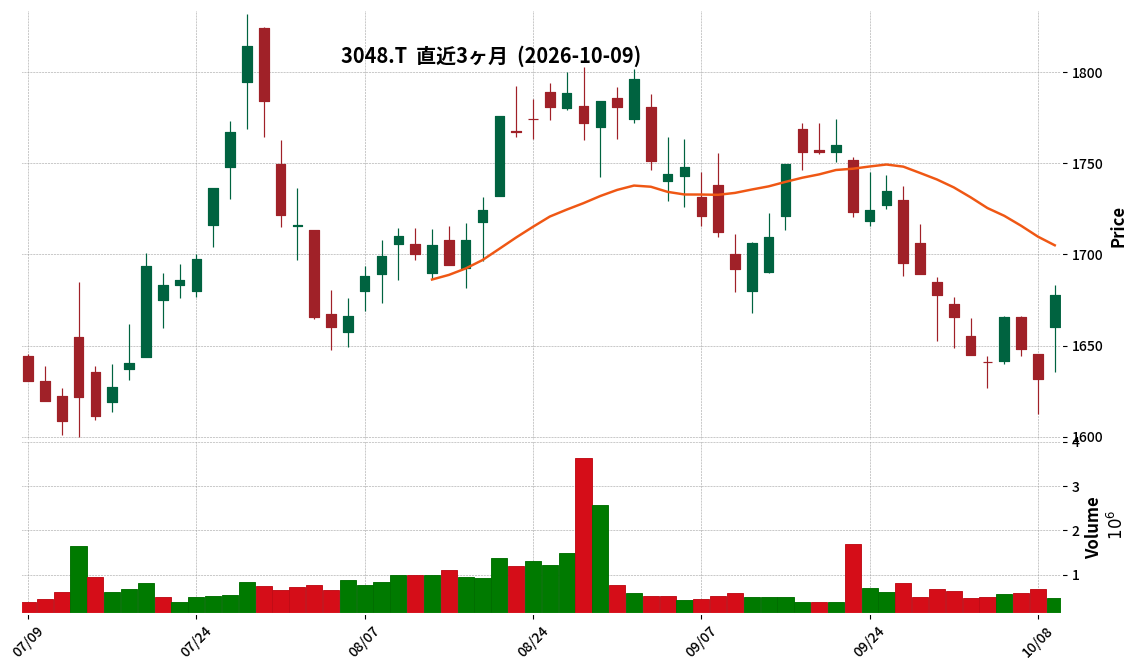
3048|ビックカメラ
1677.5
▲ +2.82%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Bic Camera Co., Ltd. resolved to increase the year-end dividend for the fiscal year ending August 31, 2026, at its Board of Directors meeting held on October 9, 2026.
- The per-share year-end dividend for the fiscal year ending August 2026 is scheduled to increase by ¥5 from the most recent dividend forecast (announced on April 10, 2026) of ¥23.00, to ¥28.00.
- This revision results in a total annual dividend of ¥48.00 per share for the fiscal year ending August 2026, including the interim dividend of ¥20.00.
- The total amount of dividends is projected to be ¥4,795 million.
- This proposal will be submitted for approval at the 46th Ordinary General Shareholders’ Meeting, scheduled for November 19, 2026.
- The company states its basic policy is to aim for a consolidated dividend payout ratio of 40%.
- For the ongoing fiscal year ending August 2027, the company forecasts an annual dividend of ¥50.00 per share (interim dividend ¥25.00, year-end dividend ¥25.00).
🤖 AI Perspective
This announcement suggests Bic Camera’s commitment to shareholder returns as a key management priority, adhering to its policy of distributing profits commensurate with business performance. The increase in the year-end dividend, an upward revision from the previous forecast, may be a point of interest for investors focused on future shareholder distributions. Additionally, the disclosure of the projected annual dividend for the subsequent fiscal year (ending August 2027) could offer insights into the company’s mid-to-long-term dividend policy.
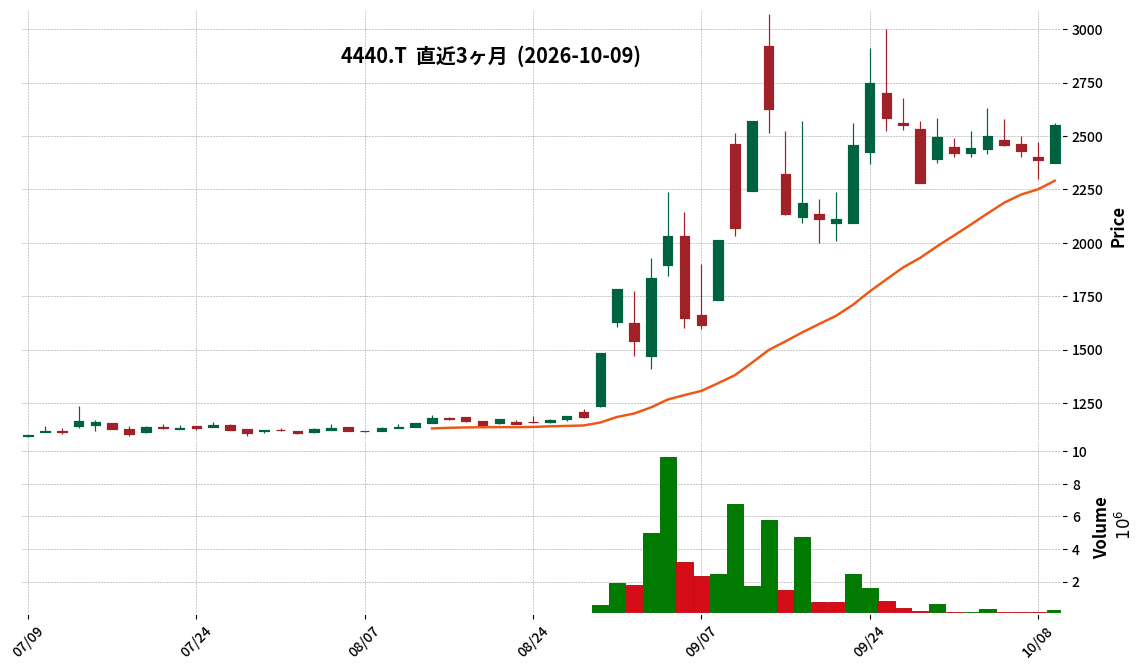
4440|ヴィッツ
2551.0
▲ +6.74%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Witz Inc. announced its consolidated financial results for the fiscal year ended August 31, 2026.
- Net sales reached ¥5,790 million, marking a 19.2% increase compared to the previous fiscal year.
- Operating profit was ¥673 million (up 18.9% YoY), ordinary profit ¥700 million (up 19.0% YoY), and profit attributable to owners of parent was ¥491 million (up 15.8% YoY), demonstrating growth in both revenue and profit.
- Diluted earnings per share were ¥122.97.
- The annual dividend for FY2026 was set at ¥21.00 per share (including a ¥3.00 commemorative dividend), an increase from ¥15.00 in the previous fiscal year.
- For the fiscal year ending August 2027, the company forecasts consolidated net sales of ¥6,000 million (up 3.6% YoY), operating profit of ¥680 million (up 0.9% YoY), ordinary profit of ¥710 million (up 1.3% YoY), and profit attributable to owners of parent of ¥450 million (down 8.4% YoY).
🤖 AI Perspective
Witz Inc.’s financial results for FY2026 show solid growth across revenue and various profit metrics, suggesting robust performance driven by its software business, particularly in automotive embedded software and simulation/virtual space technologies, security, and safety. While the company projects continued revenue growth for FY2027, the forecast for a decrease in profit attributable to owners of parent could indicate a shift in financial priorities or anticipated operational changes that warrant monitoring by investors.
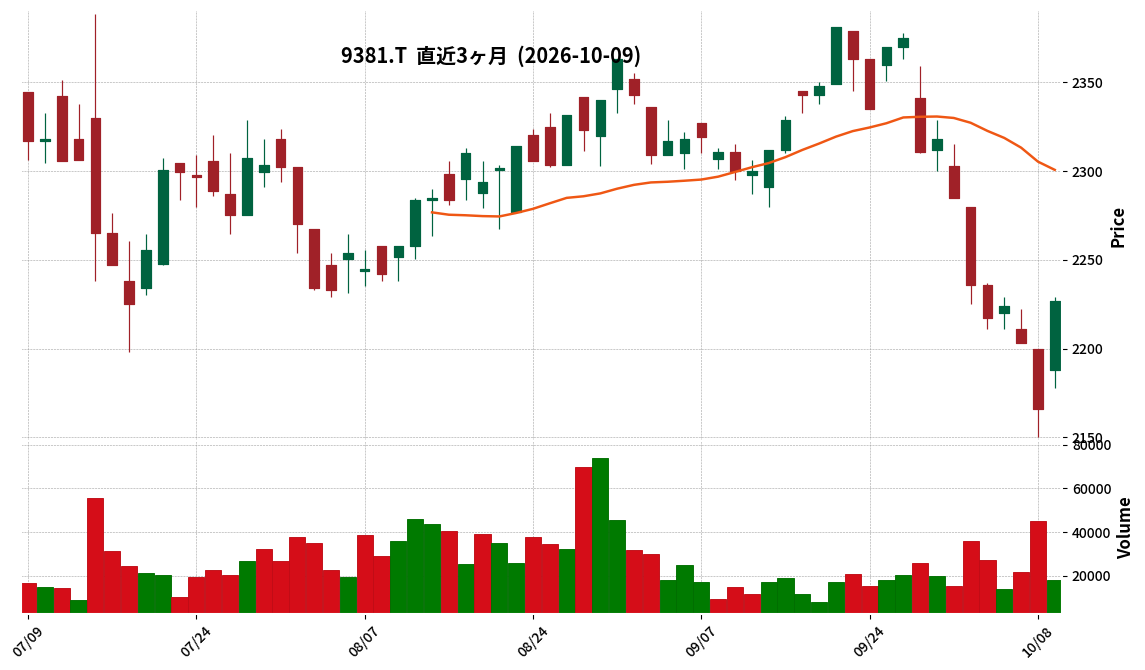
9381|エーアイテイー
2227.0
▲ +2.82%
📎 Source:エーアイテイー Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- AIT Co., Ltd. announced its consolidated financial results for the second quarter (interim) of the fiscal year ending February 2027.
- For the cumulative interim period, consolidated operating revenue reached ¥30,517 million (up 8.0% year-on-year), and operating profit was ¥2,243 million (up 10.9% year-on-year).
- Ordinary profit stood at ¥2,390 million (down 0.3% year-on-year), and net profit attributable to parent company shareholders was ¥1,589 million (down 2.4% year-on-year).
- Interim basic earnings per share were ¥67.66 (compared to ¥69.34 in the previous interim period).
- The forecast for the annual dividend for the fiscal year ending February 2027 remains at ¥110.00 per share (¥55.00 for interim and ¥55.00 for year-end), with no revisions from the most recently announced forecast.
- The consolidated full-year earnings forecast for the fiscal year ending February 2027 remains unchanged, projecting operating revenue of ¥62,500 million, operating profit of ¥4,530 million, ordinary profit of ¥4,960 million, and net profit attributable to parent company shareholders of ¥3,390 million.
🤖 AI Perspective
AIT’s Q2 FY2027 results showed increases in operating revenue and profit, yet ordinary and net profits declined compared to the prior year. This divergence may be attributed to a reversal of foreign exchange gains recorded in the previous period. However, the company’s decision to maintain its full-year earnings and dividend forecasts could suggest confidence in a recovery during the second half of the fiscal year or in achieving its annual targets.
6908|イリソ電子工業
2811.0
▲ +1.70%
📎 Source:イリソ電子工業 Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
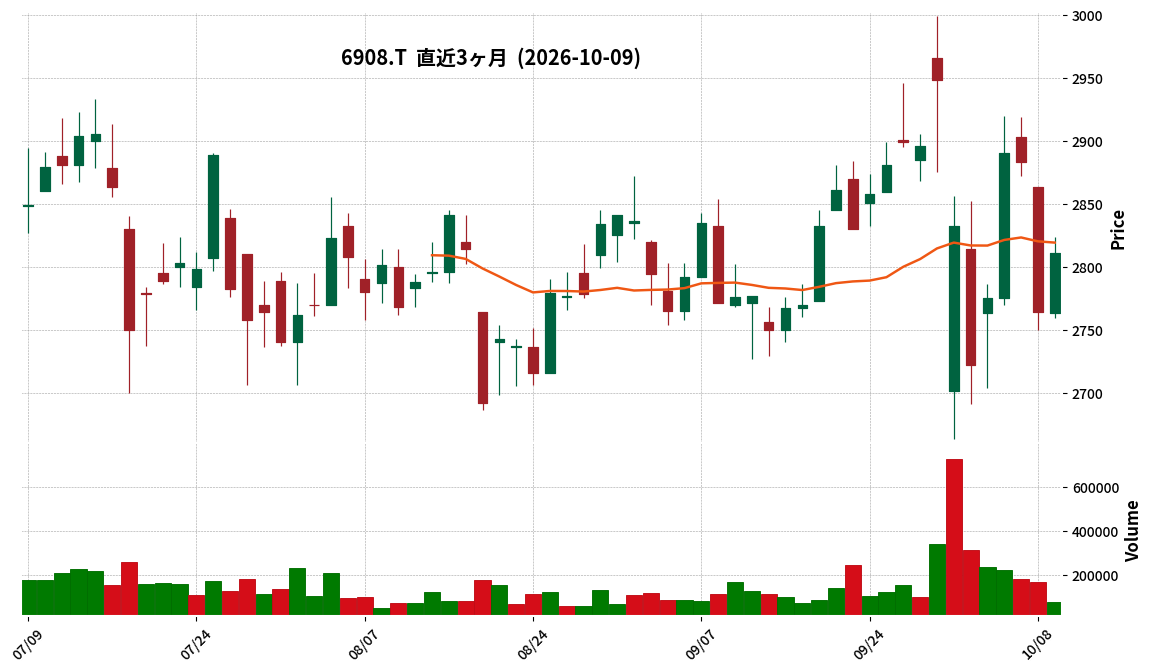
- Iriso Electronics Co., Ltd. released supplementary materials for its fiscal year ending March 2026 on October 9, 2026.
- A third-party committee investigation revealed incidents including improper monetary payments at an overseas subsidiary, issues concerning financial reporting and accounting, and problems with quality control and assurance.
- Improper monetary payments included high fees to a lawyer (with the possibility of judicial officer payments) and payments to customs officials.
- Financial and accounting issues reported included delays in closing procedures and audits, as well as premature revenue recognition.
- Quality control and assurance issues cited were failure to obtain customer approval for 4M changes, misuse/falsification of past test data in reliability labs, and non-execution of sampling inspections at factories.
- In response to these incidents, a new management structure, including a change in the Representative Director and President, and voluntary executive compensation cuts were announced.
- For FY2025 (April 1, 2025 – March 31, 2026), consolidated net sales reached JPY 61.9 billion, a 9.9% increase year-on-year, marking a new record high for full-year sales.
- Operating profit for the same period was JPY 5.43 billion (a 0.2% decrease year-on-year), with an operating profit margin of 8.8% (down 0.9 percentage points year-on-year).
🤖 AI Perspective
This document outlines the findings of a third-party committee investigation into a series of misconducts, the subsequent recurrence prevention measures, and an overview of the company’s FY2025 performance. While the company achieved record-high sales, the disclosure of multiple serious compliance-related issues suggests that the market will closely monitor the refreshed management structure and the effectiveness of the recurrence prevention measures. The company’s efforts towards strengthening corporate governance and restoring trust will likely be a key focus for investors moving forward.
7981|タカラスタン
2984.0
▲ +0.74%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Takara Standard decided to acquire all shares of Sigma Consulting Co., Ltd. in phases, making it a subsidiary, based on a board resolution on October 9, 2026.
- The acquisition will occur in two stages: 70.18% of Sigma Consulting’s outstanding shares are expected to be acquired by October 2026, and 100% by July 2031.
- The purpose of the acquisition is to accelerate the digitization of customer touchpoints, enhance customer data utilization, strengthen marketing strategies, improve customer experience, and create new services to expand Takara Standard Group’s domestic renovation business.
- Sigma Consulting specializes in leveraging cloud technology and software development capabilities to build new businesses and web services from planning to operation, supporting clients in solving business challenges.
- The impact of this share acquisition on the consolidated financial results for the full fiscal year ending March 2027 is expected to be minor.
🤖 AI Perspective
This acquisition suggests Takara Standard’s strategic move to enhance its renovation business through digital transformation, leveraging Sigma Consulting’s digital expertise. Accelerating the digitization of customer touchpoints and advanced data utilization are critical factors for competitive advantage in the current market, potentially contributing to long-term business growth. The phased acquisition schedule may also indicate a deliberate approach to the integration process.
9835|ジュンテンド
508.0
▼ -0.59%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Juntendo’s operating revenue for H1 FY2027 (interim period) was ¥22,523 million, a 4.1% decrease compared to the same period last year.
- Operating profit increased by 9.9% year-on-year to ¥958 million.
- Ordinary profit rose by 8.1% year-on-year to ¥918 million.
- Interim net profit increased by 10.4% year-on-year to ¥632 million.
- Interim net profit per share was ¥77.96.
- During the interim accounting period, one home center store was closed.
🤖 AI Perspective
While operating revenue declined, the simultaneous increase in operating, ordinary, and interim net profits suggests that the company’s efforts to minimize the decrease in gross profit and reduce selling, general and administrative expenses were effective. This improvement in the profit structure, despite a challenging business environment marked by decreased consumer purchasing intent and price competition, could indicate a strengthened operational efficiency.
8127|ヤマトインター
494.0
▼ -1.20%
📎 Source:ヤマトインター Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Yamato International Co., Ltd. has announced its consolidated financial results for the fiscal year ended August 2026.
- Consolidated net sales amounted to JPY 19,882 million, marking a 2.2% increase compared to the previous fiscal year.
- Operating income was a loss of JPY 289 million, and ordinary income was a loss of JPY 100 million.
- Net profit attributable to owners of parent was JPY 203 million, an increase of 42.1% year-on-year.
- For the fiscal year ending August 2027, the company forecasts consolidated net sales of JPY 20,300 million (up 2.1% year-on-year), operating income of JPY 150 million, ordinary income of JPY 250 million, and net profit attributable to owners of parent of JPY 200 million (down 1.7% year-on-year).
🤖 AI Perspective
Yamato International has achieved an increase in sales and a substantial improvement in net profit attributable to owners of parent. However, the company continues to report operating and ordinary losses, suggesting that improving the profitability structure alongside sales growth may be a key focus. The FY2027 forecast, which projects continued sales growth and a return to profitability for operating and ordinary income, could indicate an expectation of positive outcomes from ongoing business strategies.
9313|丸八倉
1080.0
▲ +3.55%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
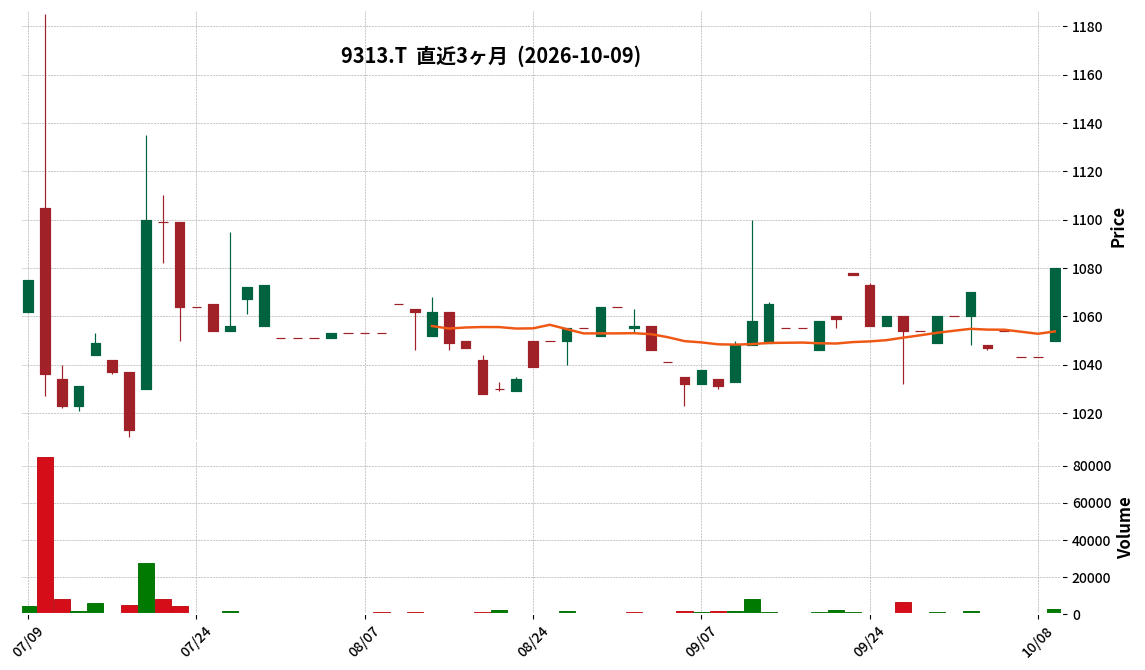
- Maruhatsu Soko Co., Ltd. announced its consolidated financial results for the third quarter of the fiscal year ending November 2026 (December 1, 2025 – August 31, 2026).
- Consolidated net sales amounted to ¥3,772 million, marking a 2.2% increase compared to the same period of the previous fiscal year.
- Consolidated operating profit was ¥472 million (+8.1% YoY), and consolidated ordinary profit was ¥519 million (+22.0% YoY).
- Net income attributable to owners of parent reached ¥384 million, a 35.0% increase from the prior year’s third quarter.
- The full-year consolidated earnings forecast (Net sales ¥5,100 million, Net income attributable to owners of parent ¥480 million) remained unchanged from the most recently announced figures.
🤖 AI Perspective
Maruhatsu Soko’s Q3 results show growth across sales and all profit metrics, with a notable increase in net income attributable to owners of parent. This performance appears to be supported by revenue growth in both its logistics and real estate segments, along with a special gain from the partial sale of investment securities contributing to net profit. The unchanged full-year forecast suggests that the company views its current progress as aligned with its plans, which investors may find reassuring regarding stability.
9974|ベルク
6540.0
▲ +0.93%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
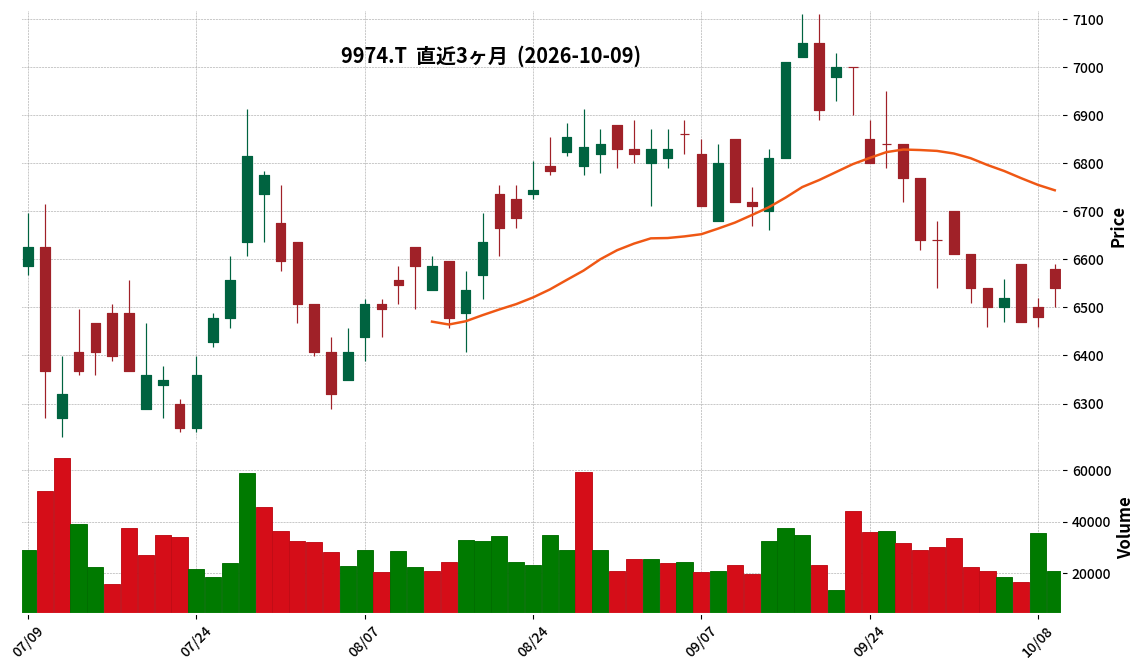
- Belc Co., Ltd. announced its consolidated financial results for the second quarter (interim period) of the fiscal year ending February 2027.
- Consolidated operating revenue for the interim period was ¥216,905 million, a 2.8% increase compared to the previous interim period.
- Consolidated operating profit was ¥6,914 million (22.2% decrease), consolidated ordinary profit was ¥7,040 million (21.9% decrease), and net profit attributable to parent company shareholders was ¥4,583 million (25.4% decrease).
- Interim net income per share was ¥220.03.
- The year-end dividend forecast is ¥66.00 (total annual ¥132.00), with no revision from the latest public forecast.
- The consolidated full-year performance forecast for the fiscal year ending February 2027 has been revised to operating revenue of ¥443,000 million, operating profit of ¥15,400 million, ordinary profit of ¥15,600 million, and net profit attributable to parent company shareholders of ¥9,900 million.
🤖 AI Perspective
While Belc’s operating revenue showed growth, the decline across all profit metrics (operating, ordinary, and net) could be a key focus for investors. The company cited rising procurement costs, intensified pricing strategies for competitiveness, and increased selling, general and administrative expenses as contributing factors. The revision of the full-year earnings forecast downwards may also influence market sentiment and warrants monitoring.
Disclaimer: This article is for informational purposes only and does not constitute investment advice.
9982|タキヒヨー
2754.0
▼ -0.65%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
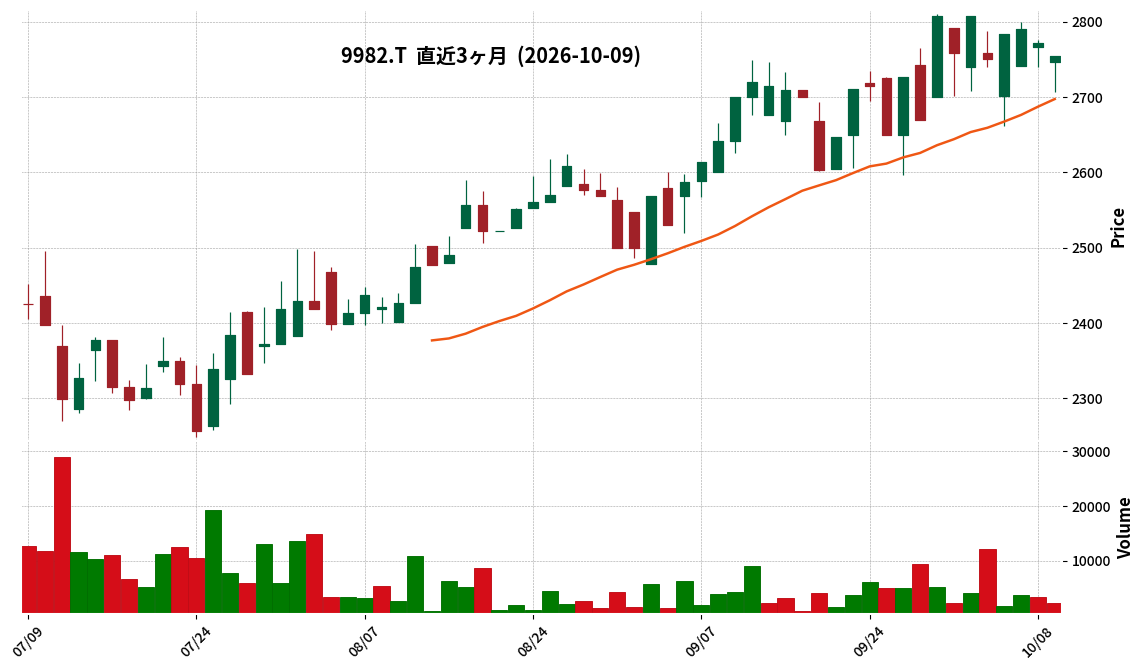
- Takihyo Co., Ltd. announced its consolidated financial results for the second quarter (interim period) of the fiscal year ending February 2027, covering the period from March 1, 2026, to August 31, 2026.
- Net sales amounted to 31,682 million yen, a decrease of 0.4% compared to the same interim period of the previous year.
- Operating income was 748 million yen, a 33.0% decrease year-on-year, and ordinary income was 776 million yen, a 32.0% decrease year-on-year.
- Net income attributable to parent company shareholders increased by 7.8% year-on-year to 1,001 million yen, primarily due to the recording of a 400 million yen gain on the sale of fixed assets as extraordinary income.
- The forecast for the annual dividend for the fiscal year ending February 2027 remains unchanged, with a year-end dividend of 25.00 yen, totaling 50.00 yen (including an interim dividend of 25.00 yen).
- The full-year consolidated earnings forecast remains unrevised, projecting net sales of 64,800 million yen (up 1.3% YoY), operating income of 1,950 million yen (up 0.4% YoY), ordinary income of 1,950 million yen (up 0.1% YoY), and net income attributable to parent company shareholders of 1,620 million yen (up 0.3% YoY).
🤖 AI Perspective
While Takihyo’s interim results showed a slight decrease in sales and a significant decline in operating and ordinary income, the increase in net income attributable to parent shareholders due to extraordinary gains is a key highlight. The company attributes the profit contraction to stagnant consumer sentiment and rising raw material and logistics costs. The unchanged full-year forecast may suggest management anticipates a recovery in the latter half of the fiscal year. Investors may want to monitor how Takihyo manages ongoing cost pressures and currency fluctuations to meet its annual targets.
1997|暁飯島
4300.0
▲ +0.23%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
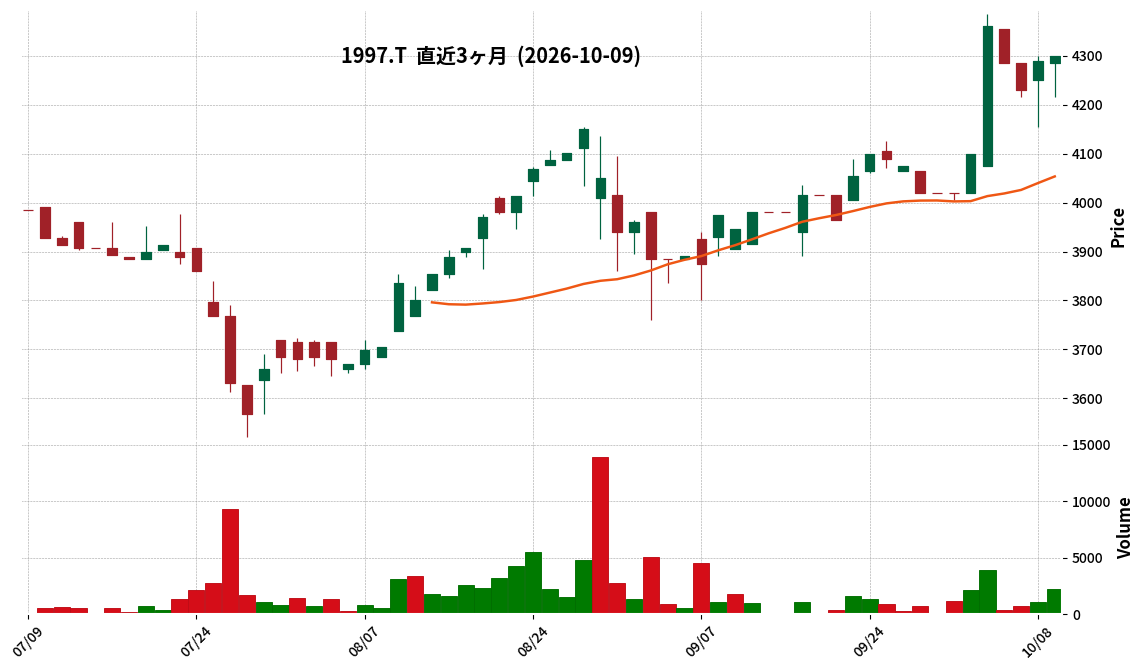
- Akatsukiiijima Kogyo Co., Ltd. announced its non-consolidated financial results for the fiscal year ended August 31, 2026 (September 1, 2025 – August 31, 2026).
- Net sales reached ¥10,129 million (up 10.9% year-on-year), operating profit was ¥1,437 million (up 27.5%), ordinary profit was ¥1,504 million (up 29.6%), and net profit attributable to owners of parent was ¥1,070 million (up 34.4%).
- Earnings per share for the period were ¥529.43, compared to ¥393.90 in the previous fiscal year.
- In the Equipment Business segment, orders received increased by 8.4% to ¥11,064 million, completed construction work rose by 11.3% to ¥9,953 million, and operating profit grew by 25.6% to ¥1,932 million. The Solar Power Generation Business reported net sales of ¥174 million (down 7.8%) and operating profit of ¥71 million (down 5.8%).
- The year-end dividend for the fiscal year ended August 31, 2026, was ¥155.00 per share, up from ¥110.00 in the previous year.
- The forecast for the fiscal year ending August 31, 2027, projects net sales of ¥10,500 million (up 3.7% year-on-year), operating profit of ¥1,200 million (down 16.5%), ordinary profit of ¥1,250 million (down 16.9%), and net profit of ¥850 million (down 20.6%).
🤖 AI Perspective
The robust performance in FY2026, with significant increases in all profit metrics driven by the Equipment Business, highlights the company’s strong operational execution during the period. However, the projection for FY2027, which indicates a decrease in profits despite an increase in net sales, may suggest a changing operational environment or increased cost pressures that investors will want to monitor.
2747|北雄ラッキー
3145.0
▼ -0.47%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
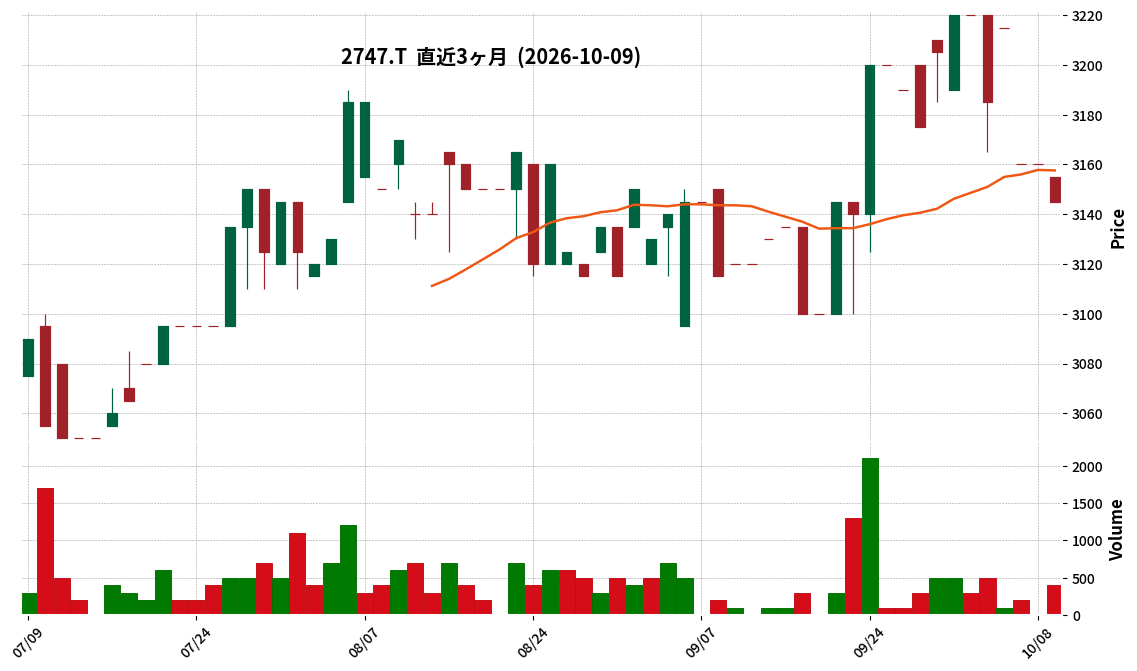
- Hokuyu Lucky announced its Q2 FY2027 (interim period: March 1, 2026 – August 31, 2026) financial results.
- Net sales for the interim period amounted to ¥18,338 million, representing a 0.8% decrease compared to the prior interim period.
- Operating profit was ¥7 million (down 87.3% year-over-year), ordinary profit was a loss of ¥11 million (compared to a profit of ¥47 million in the prior interim period), and interim net profit was a loss of ¥33 million (compared to a profit of ¥22 million in the prior interim period).
- Interim net loss per share was ¥26.51.
- The full-year FY2027 earnings forecast remains unchanged, projecting net sales of ¥37.2 billion (0.0% YoY), operating profit of ¥180 million (down 21.6% YoY), ordinary profit of ¥130 million (down 41.5% YoY), and net profit of ¥52 million (down 52.0% YoY).
🤖 AI Perspective
Hokuyu Lucky’s Q2 FY2027 results show a slight dip in net sales but a notable decline in profitability, with operating profit down significantly and a shift to ordinary and net losses. This appears to be influenced by increased depreciation expenses and personnel costs within selling, general, and administrative expenses, indicating a challenging operating environment. However, the unchanged full-year forecast could suggest the company anticipates a recovery in the latter half of the fiscal year.
3201|ニッケ
1922.0
▲ +1.75%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
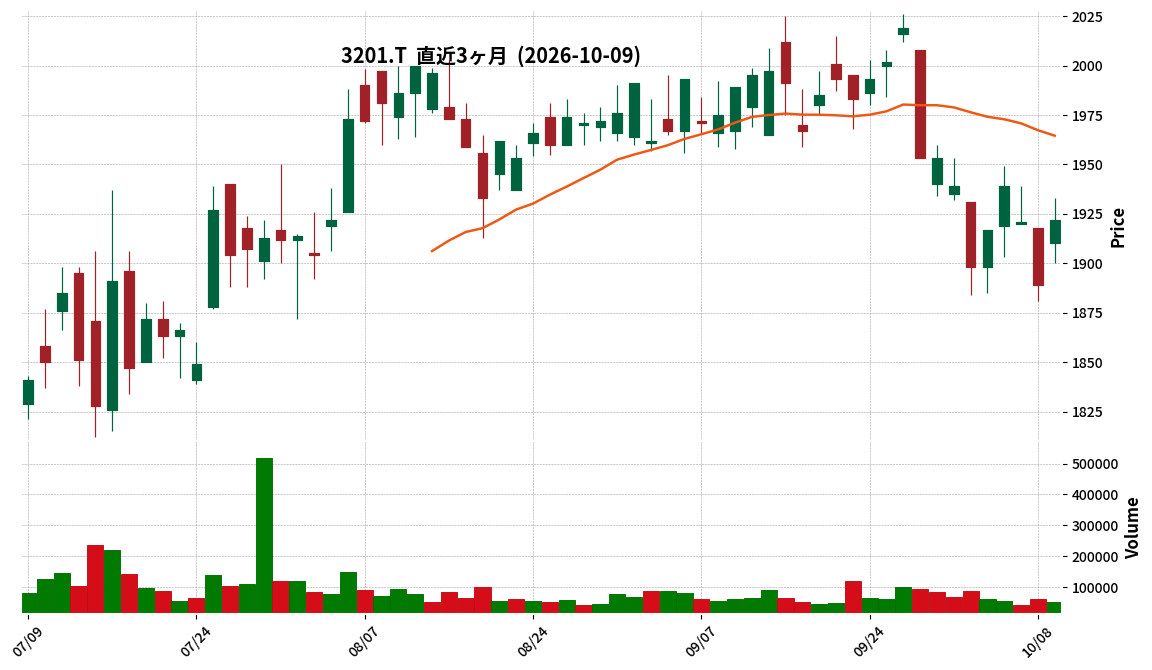
- Nikke (Nippon Keori Co., Ltd.) announced its Q3 FY2026 financial results for the period from December 1, 2025, to August 31, 2026.
- Consolidated cumulative results showed net sales of ¥89,186 million (+2.4% YoY), operating income of ¥8,673 million (+13.1% YoY), ordinary income of ¥9,730 million (+13.0% YoY), and net profit attributable to parent company of ¥7,044 million (+26.9% YoY).
- By segment, the Industrial Equipment business reported net sales of ¥29,735 million (+14.2% YoY) and operating income of ¥2,341 million (+29.2% YoY, with newly consolidated KAKO TECHNOS Co., Ltd. contributing to performance.
- The Human & Future Development business’s operating income reached ¥5,899 million (+12.0% YoY), driven by strong performance in real estate leasing, including the “Yaesu-dori Fil Terrace” office building completed in January 2025.
- The annual dividend forecast for FY2026 has been revised, with the year-end dividend expected to be ¥42.00 per share (¥32.00 ordinary, ¥10.00 commemorative), totaling ¥60.00 for the full year.
🤖 AI Perspective
Nikke’s Q3 FY2026 results demonstrate growth across all key financial metrics, with a notable increase in net profit attributable to the parent company. This performance appears to be supported by contributions from a newly consolidated subsidiary in the Industrial Equipment segment and stable earnings from the real estate leasing business within the Human & Future Development segment. While the full-year earnings forecast remains unchanged, the upward revision of the annual dividend forecast could indicate a positive stance on shareholder returns.
7713|シグマ光機
2680.0
▲ +3.08%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
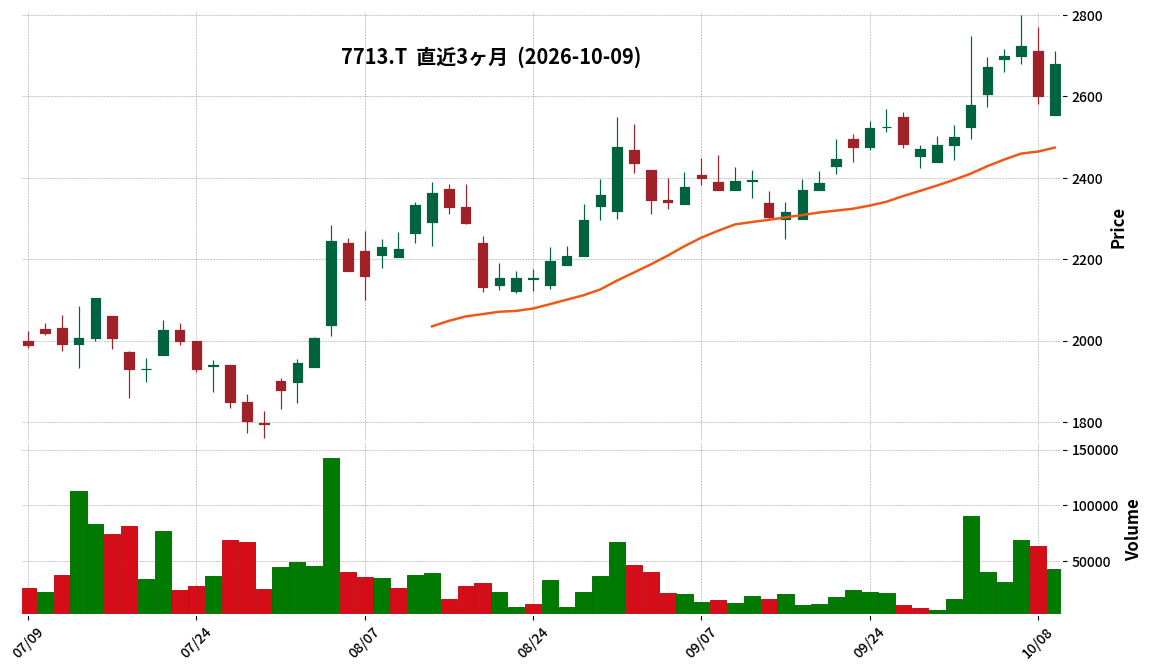
- Sigma Koki announced its consolidated financial results for the first quarter of the fiscal year ending May 2027 (June 1, 2026 – August 31, 2026).
- Net sales reached 3,382 million yen, marking a 35.0% increase year-over-year.
- Operating income was 518 million yen (up 240.6% year-over-year), and ordinary income was 556 million yen (up 193.7% year-over-year).
- Net income attributable to owners of the parent company amounted to 373 million yen, representing a 244.8% increase year-over-year.
- The Component Products Business segment reported sales of 2,954 million yen (up 38.6% year-over-year) and operating income of 608 million yen (up 132.0% year-over-year). The System Products Business segment recorded sales of 461 million yen (up 18.3% year-over-year) and operating income of 78 million yen (up 342.9% year-over-year).
- The consolidated full-year forecast for May 2027 has been revised, with projected net sales of 13,805 million yen (up 20.7% from previous year), operating income of 2,000 million yen (up 69.6%), and net income attributable to owners of the parent company of 1,480 million yen (up 78.1%).
🤖 AI Perspective
Sigma Koki’s Q1 FY2027 results show significant growth across sales and all profit categories, with operating, ordinary, and net income demonstrating triple-digit percentage increases. This strong performance appears to be driven by robust demand in the electronics industry, particularly in optoelectronics fusion, supported by the booming AI sector. Furthermore, healthy demand from overseas regions likely contributed to these positive results.
137A|G-Cocolive
665.0
▼ -5.27%
📎 Source:G-Cocolive Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
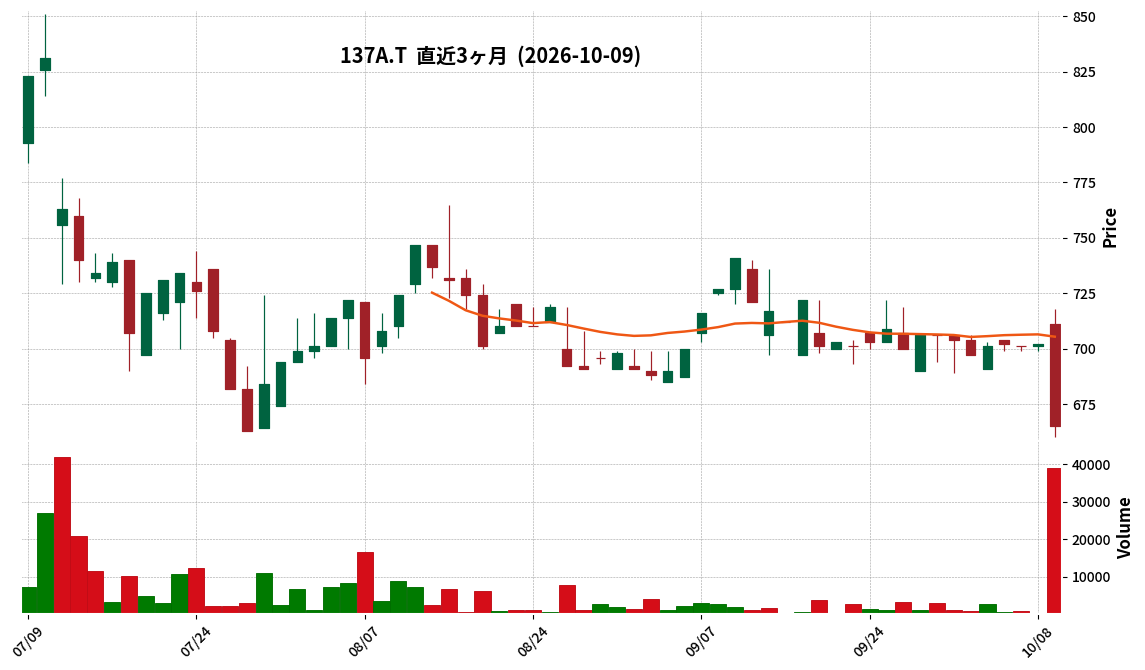
- G-Cocolive announced its Q1 FY2027 financial results for the period from June 1, 2026, to August 31, 2026.
- Revenue reached ¥383.45 million, an 8.3% increase compared to the same quarter of the previous year.
- Operating profit was ¥37.35 million (a 43.0% decrease year-on-year), ordinary profit was ¥38.02 million (a 43.1% decrease), and net profit for the quarter was ¥24.85 million (a 45.7% decrease).
- Earnings per share for the quarter stood at ¥8.45.
- The full-year earnings forecast and dividend forecast remain unchanged from the most recently published figures.
🤖 AI Perspective
While revenue showed a year-on-year increase, the significant decline in profits is a key point for investors to consider. This could be attributed to the rise in selling, general, and administrative expenses compared to the prior year’s quarter. The company’s decision to maintain its full-year forecast may suggest that management views the current quarterly fluctuations as not materially impacting the overall annual performance.
2157|コシダカHD
970.0
▼ -1.42%
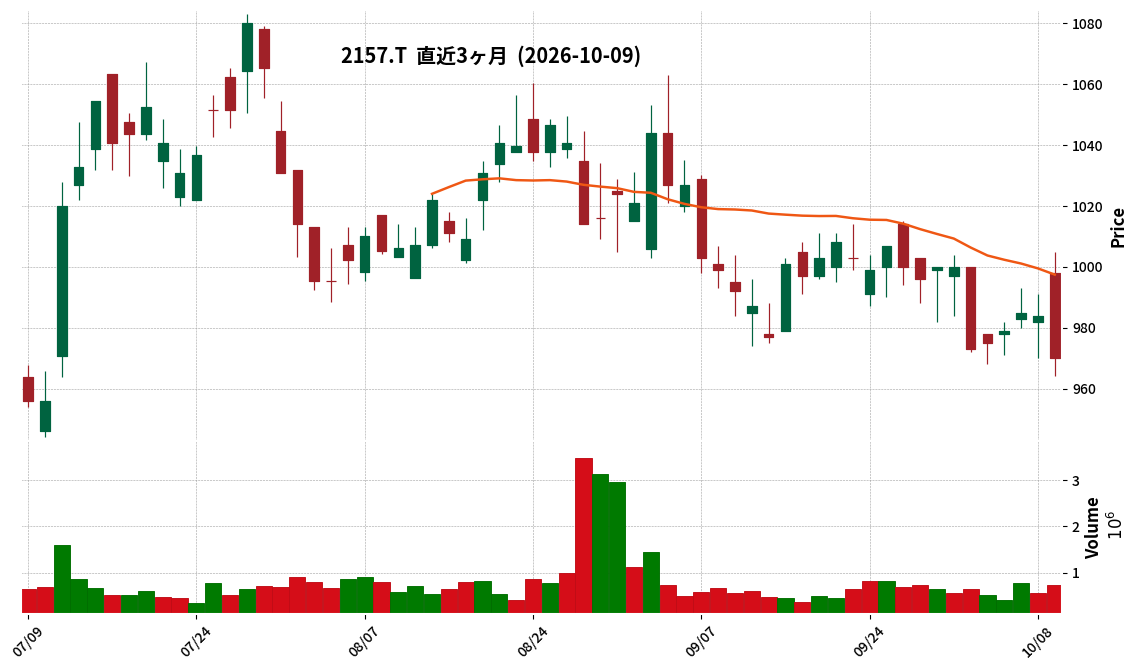
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- For the fiscal year ended August 2026, consolidated net sales increased by 15.9% year-on-year to ¥80,401 million.
- Operating profit decreased by 5.5% year-on-year to ¥10,771 million.
- Ordinary profit decreased by 5.1% year-on-year to ¥11,003 million.
- Net profit attributable to owners of parent increased by 20.7% year-on-year to ¥6,346 million.
- The year-end dividend was ¥15 per share, making the annual dividend ¥28 (compared to ¥24 in the previous period). A full-year dividend of ¥30 is projected for FY2027.
- For the fiscal year ending August 2027, the company forecasts consolidated net sales of ¥90,358 million (up 12.4% year-on-year), operating profit of ¥12,604 million (up 17.0% year-on-year), and net profit attributable to owners of parent of ¥7,142 million (up 12.5% year-on-year).
- During the fiscal year, KOSHIDAKA MALAYSIA SDN.BHD. was newly included in the scope of consolidation, and the karaoke store business of K.K. Standard (formerly K.K. Koshidaka SP) was added due to its consolidation.
🤖 AI Perspective
Koshidaka Holdings’ FY2026 results show robust revenue growth but a decline in operating and ordinary profit. This could indicate pressure from rising costs such as personnel and utility expenses, along with increased expenditures related to DX investments and new initiatives. However, the increase in net profit attributable to owners of parent suggests the impact of tax effects or extraordinary gains/losses. The positive forecast for FY2027, projecting increases in both revenue and profit, suggests that the company anticipates benefits from its international expansion and new strategies, which investors may find worth monitoring.
2669|カネ美食品
3905.0
▲ +0.51%
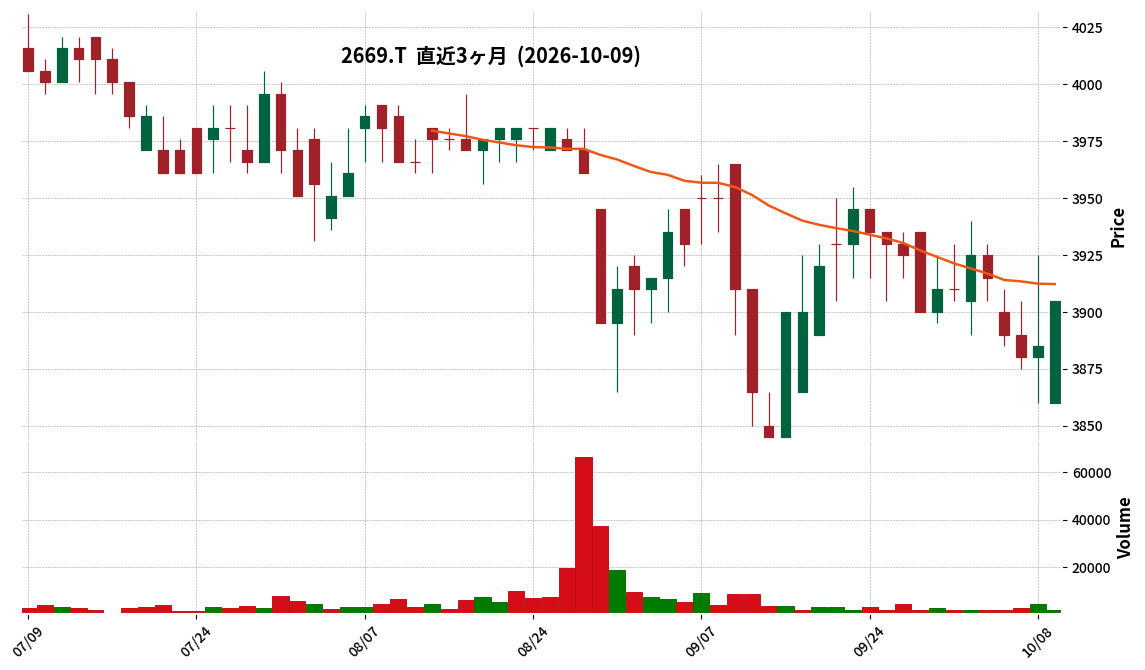
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Kanemi Foods Co., Ltd. has announced its unaudited financial results for the second quarter (interim period) of the fiscal year ending February 2027.
- Net sales reached ¥44,353 million, marking a 3.4% increase compared to the same period of the previous fiscal year.
- Operating profit stood at ¥1,587 million (+40.6% YoY), ordinary profit at ¥1,646 million (+41.7% YoY), and interim net profit at ¥925 million (+34.8% YoY).
- The Tenant Business segment recorded sales of ¥24,281 million (+4.1% YoY) and segment profit of ¥1,218 million (-6.7% YoY).
- The External Sales Business segment reported sales of ¥20,071 million (+2.5% YoY) and segment profit of ¥368 million (compared to a loss of ¥178 million in the prior interim period).
🤖 AI Perspective
Kanemi Foods’ Q2 FY2027 results show notable top-line and bottom-line growth. The turnaround in profitability of the External Sales Business segment appears to be a key driver for the overall profit increase. While the Tenant Business saw sales growth, its segment profit declined, which could be attributed to proactive investment and rising costs, suggesting a need to monitor the balance between growth investments and cost management moving forward.
2687|CVSベイ
488.0
▲ +0.21%
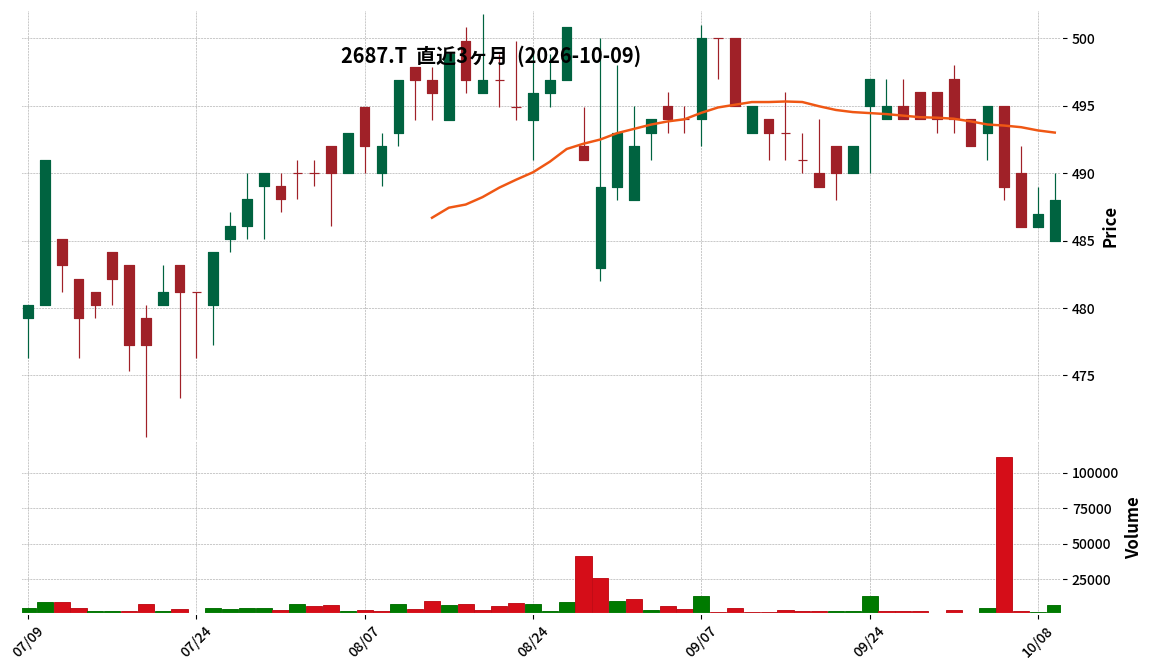
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- CVS Bay announced its consolidated financial results for the second quarter (interim period) of the fiscal year ending February 2027.
- Total operating revenue reached JPY 4,024 million, representing a 1.2% increase compared to the prior interim period.
- Operating income was JPY 77 million (up 241.3% year-on-year), and ordinary income was JPY 81 million (up 76.2% year-on-year).
- Net income attributable to parent company shareholders turned profitable at JPY 62 million, reversing a net loss of JPY 66 million in the prior interim period.
- Basic earnings per share for the interim period was JPY 12.63.
- The dividend forecast remains unchanged, with an expected year-end dividend of JPY 10.00, totaling JPY 20.00 for the full year (consistent with the previous fiscal year’s actual).
- The full-year consolidated performance forecast remains at JPY 8,159 million for total operating revenue (up 3.3% year-on-year), JPY 309 million for operating income (up 137.9% year-on-year), and JPY 165 million for net income attributable to parent company shareholders (turning profitable).
🤖 AI Perspective
These interim results show a significant increase in profit compared to the previous year, with net income attributable to parent company shareholders returning to profitability, which is a key highlight. The substantial 241.3% increase in operating income suggests a notable improvement in the company’s operational profitability. The unchanged full-year forecasts might indicate that management anticipates the current recovery trend to continue, which investors may find reassuring.
2698|キャンドゥ
3215.0
▼ -0.16%
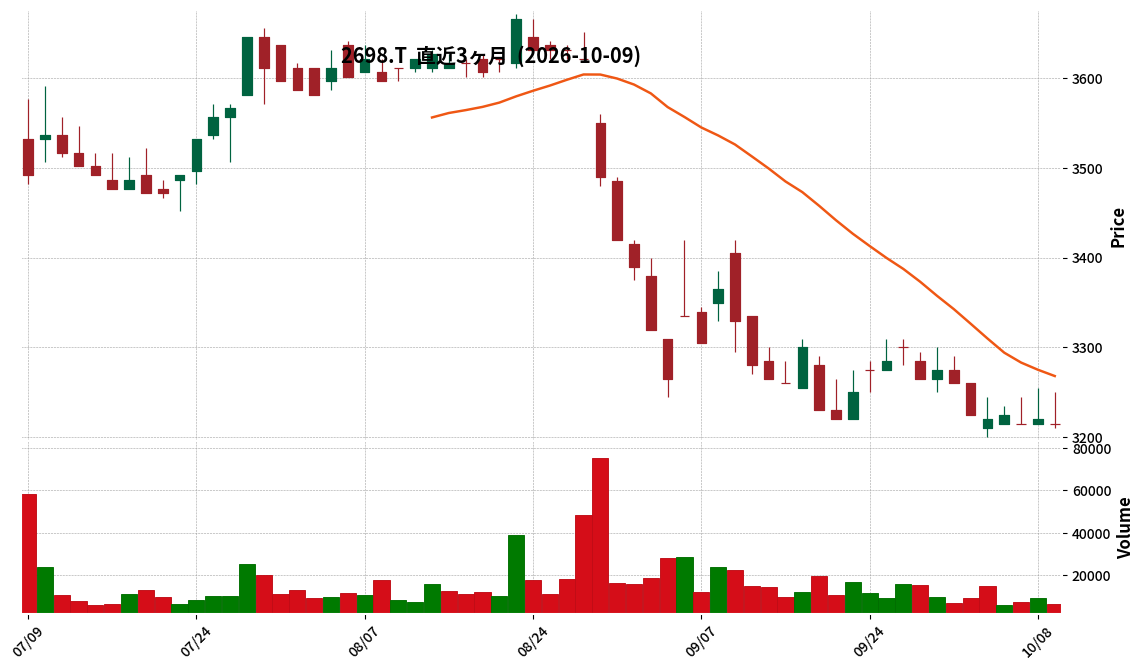
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Can★Do Co., Ltd. announced its financial results for the second quarter of the fiscal year ending February 2027.
- Consolidated net sales increased by ¥1,370 million compared to the previous fiscal year.
- All stages of profit (gross profit, operating profit, ordinary profit, and net income for the interim period) decreased year-on-year. Specifically, operating profit decreased by ¥326 million, ordinary profit by ¥370 million, and net income for the interim period by ¥244 million.
- Existing directly managed store sales increased by 2.6% year-on-year for the June-August period and by 3.3% for the cumulative second quarter (March-August).
- The full-year business forecast remains unchanged from the figures disclosed on April 9, 2026, with sales and profits generally progressing as planned.
- Capital expenditures saw a significant decrease in store equipment investment due to fewer directly managed store openings, while digital investment, including the introduction of self-checkout registers aimed at productivity improvement, increased.
- The cumulative number of stores that introduced self-checkout registers in Q2 FY2027 was 71 (full-year plan: 160 stores).
🤖 AI Perspective
Can★Do’s Q2 FY2027 results show an increase in sales but a decline across all profit stages, which could be a key focus for investors. The decrease in gross profit margin and the rise in selling, general, and administrative expenses appear to have contributed to the profit decline, influenced by factors such as a review of product price point composition, rising costs, and increased labor and other SG&A ratios. However, the company’s commitment to digital investments for productivity improvement and the affirmation of its full-year forecast suggest an ongoing focus on structural reforms for long-term value enhancement, which is worth monitoring.
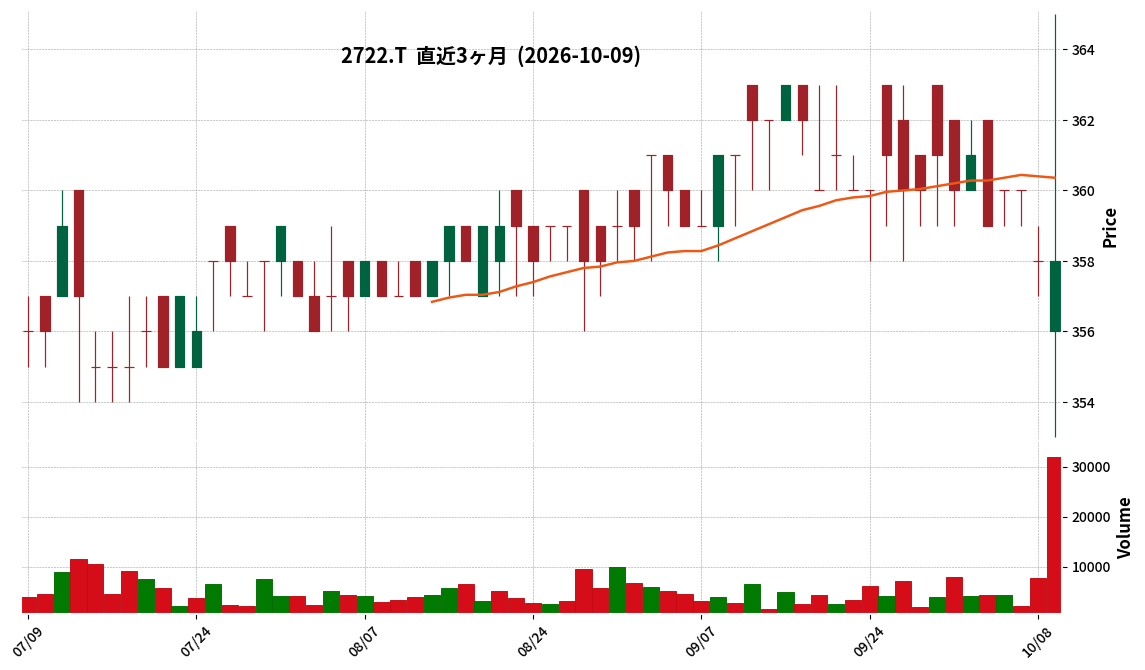
2722|IKホールディングス
358.0
▲ +0.00%
📎 Source:IKホールディングス Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- IK Holdings announced its consolidated financial results for the first quarter of the fiscal year ending May 2027 (June 1, 2026, to August 31, 2026).
- Consolidated net sales amounted to ¥3,069 million, representing a 16.5% decrease compared to the same quarter of the previous fiscal year.
- The company reported a consolidated operating loss of ¥54 million (compared to an operating profit of ¥68 million in the prior-year quarter) and a consolidated ordinary loss of ¥61 million (compared to an ordinary profit of ¥63 million in the prior-year quarter).
- Net loss attributable to owners of the parent company was ¥36 million (compared to a net profit of ¥35 million in the prior-year quarter).
- The consolidated full-year earnings forecast and the annual dividend forecast of ¥9.00 for the fiscal year ending May 2027 remain unchanged from the most recently published figures.
- The Direct Marketing segment reported sales of ¥530 million (down 31.2% year-on-year) and operating profit of ¥28 million (down 19.1% year-on-year).
- The Sales Marketing segment reported sales of ¥2,538 million (down 12.6% year-on-year) and operating profit of ¥119 million (down 41.5% year-on-year).
🤖 AI Perspective
IK Holdings’ first-quarter results for fiscal year 2027 show a decrease in net sales and a shift to losses across all profit indicators compared to the prior year. The decline in sales appears to be influenced by reduced revenue in TV shopping and web channels within the Direct Marketing segment, and a decrease in store sales within the Sales Marketing segment. As the full-year forecast remains unchanged, the company’s performance in subsequent quarters will be a key area for investors to monitor.
2928|A-RIZAP G
—
▲ +0.00%
📎 Source:A-RIZAP G Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- RIZAP Group, Inc. announced on October 9, 2026, the holding of an online earnings briefing for the second quarter of the fiscal year ending March 2027 and the acceptance of pre-submitted questions.
- The earnings briefing will be livestreamed online on November 13, 2026 (Friday) from 17:00 to 18:00 JST (tentative).
- Pre-registration is required to view the briefing, with the URL provided as https://zoom.us/webinar/register/WN_wsBR04-9SZKjlq2y8-DUZA. An archived video will be made available on the company’s website after the live broadcast.
- The acceptance period for pre-submitted questions is from 15:30 JST on October 9, 2026 (Friday) to 18:00 JST on November 9, 2026 (Monday).
- Questions can be submitted via the earnings briefing pre-question form (https://forms.gle/uZYyeJtgy7hS7Bxy6) or by email to qa@rizapgroup.com.
🤖 AI Perspective
RIZAP Group’s decision to host an online earnings briefing suggests an emphasis on transparent information disclosure to shareholders and investors. The online format may enhance accessibility for a broader audience, contributing to equitable information dissemination regardless of geographical or time constraints. Furthermore, accepting questions in advance offers a valuable channel for investors to receive direct responses from management on specific matters of interest.
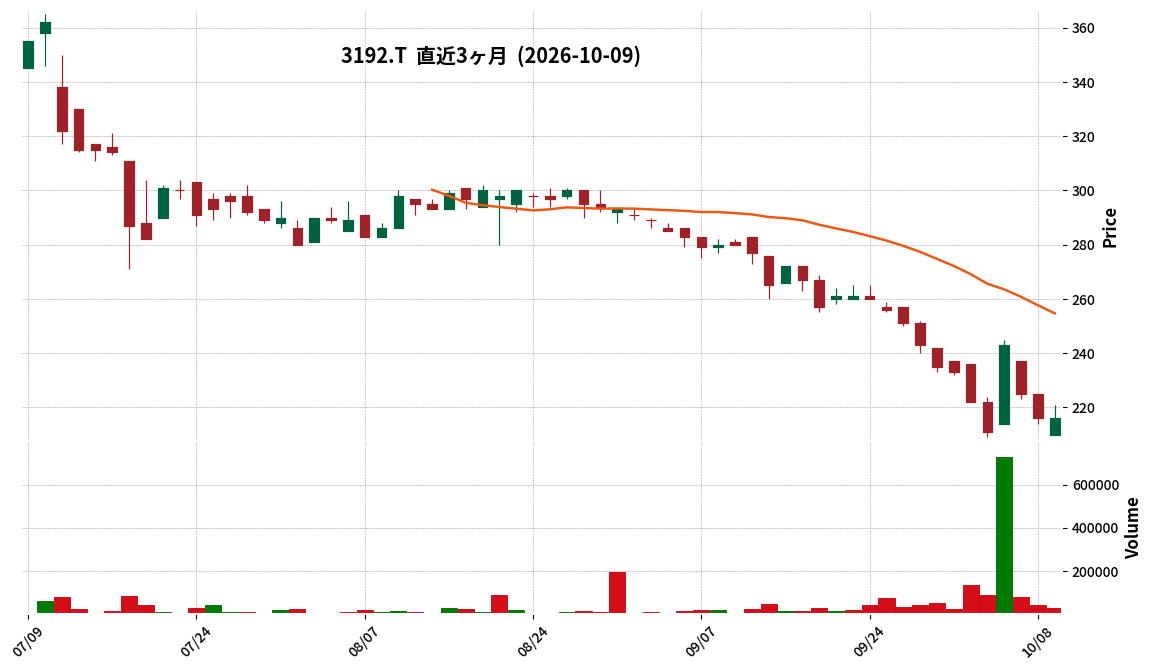
3192|白鳩
216.0
▲ +0.00%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Shirohato Co., Ltd. announced its non-consolidated financial results for the third quarter of the fiscal year ending November 2026 (December 1, 2025 – August 31, 2026).
- For the cumulative third quarter, the company reported net sales of ¥4,584 million, an operating loss of ¥62 million, an ordinary loss of ¥84 million, and a quarterly net loss of ¥86 million.
- Year-on-year comparisons for the same period were not provided due to a change in the fiscal year-end, which resulted in no comparable financial statements for the prior year’s third quarter.
- As of the end of the third quarter, total assets stood at ¥5,106 million, net assets at ¥2,434 million, and the equity ratio at 47.7%.
- The full-year forecast for FY2026 has been revised to net sales of ¥6,230 million, an operating loss of ¥100 million, an ordinary loss of ¥130 million, and a net loss of ¥135 million.
🤖 AI Perspective
Shirohato’s third-quarter results show losses, accompanied by a downward revision to its full-year earnings forecast. This may suggest that sluggish performance in the domestic e-commerce private brand sector and conservative consumer spending habits have impacted overall sales and profit margins. Investors may want to monitor how the company navigates the challenging market environment and implements strategies for revenue recovery.
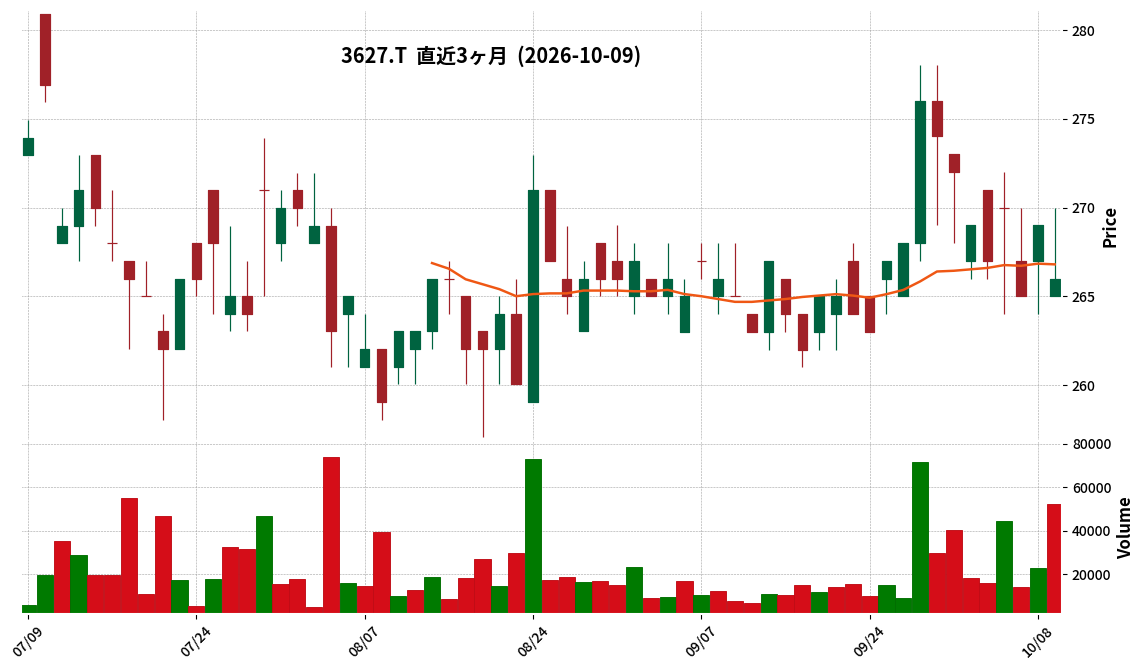
3627|テクミラ
266.0
▼ -1.12%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Tecmira Holdings Co., Ltd. announced its consolidated financial results for the second quarter (interim period) of the fiscal year ending February 2027.
- Consolidated net sales for the interim period were ¥5,297 million, an increase of 8.7% year-over-year.
- The company reported an operating loss of ¥74 million, an improvement from an operating loss of ¥153 million in the prior interim period.
- Ordinary income turned positive to ¥32 million, a reversal from an ordinary loss of ¥180 million in the previous interim period.
- Net loss attributable to owners of parent was ¥55 million, an improvement from a net loss of ¥206 million in the prior interim period.
- Basic earnings per share for the interim period were ¥△4.61.
- The full-year consolidated earnings forecast remains unchanged, with projected net sales of ¥11,000 million, ordinary income of ¥300 million, and net income attributable to owners of parent of ¥150 million.
- The interim dividend is ¥2.00, and the year-end dividend forecast is ¥3.00, resulting in a total annual dividend forecast of ¥5.00, with no changes from previous announcements.
🤖 AI Perspective
Tecmira Holdings’ interim results show notable improvements, particularly the shift to ordinary income from a loss in the previous year, supported by an increase in net sales. This turnaround appears to be driven by strong performance in its core consumer business, including a new game release, and continued growth in its SaaS business. The reduction in losses from strategic upfront investments also suggests a positive trend in strengthening the company’s profitability structure.
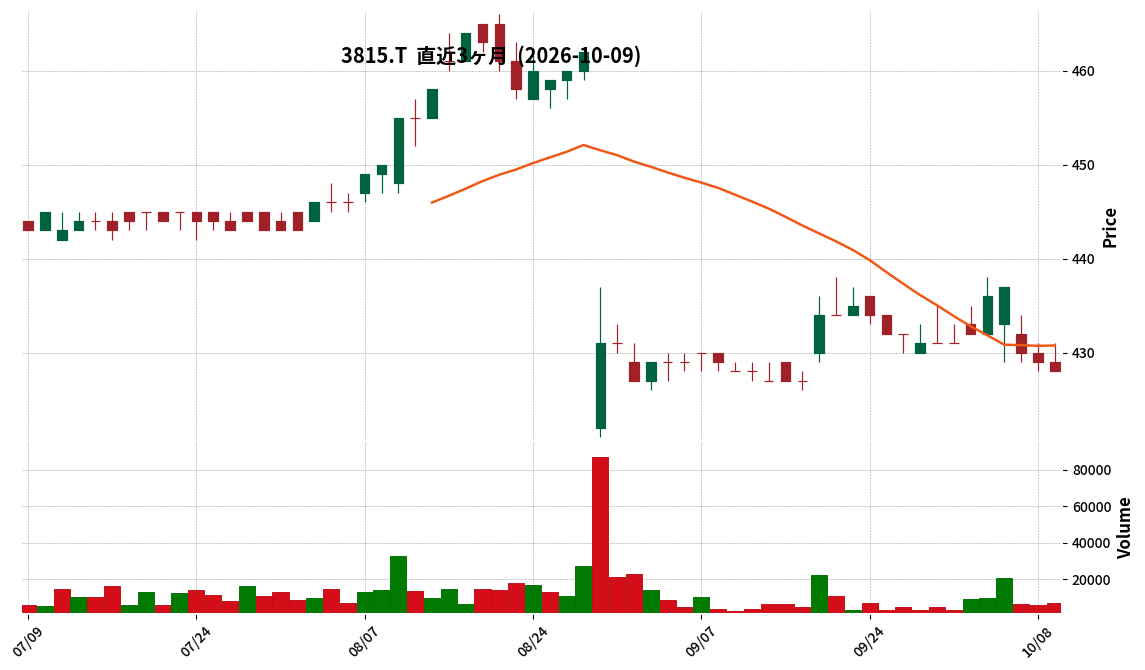
3815|G-メディア
428.0
▼ -0.23%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- G-MEDIA reported consolidated net sales of 1,612 million yen for the fiscal year ended August 2026, marking a 13.9% decrease from the previous fiscal year.
- The company posted an operating loss of 533 million yen (previous year: loss of 323 million yen), an ordinary loss of 537 million yen (previous year: loss of 317 million yen), and a net loss attributable to parent company shareholders of 716 million yen (previous year: loss of 508 million yen).
- Diluted earnings per share were -66.61 yen (previous year: -50.21 yen), and the equity ratio was 24.2% (previous year: 30.9%).
- For the fiscal year ending August 2027, the company forecasts consolidated net sales of 1,756 million yen (an 8.9% increase year-on-year), an operating loss of 208 million yen, an ordinary loss of 208 million yen, and a net loss attributable to parent company shareholders of 208 million yen.
- The company has been promoting business structural reforms, as announced on June 3, 2026, and expects the full impact of these measures on profitability to materialize from the fiscal year ending August 2027 onwards.
🤖 AI Perspective
G-MEDIA’s FY2026 results show a decline in net sales and an expansion of losses, which may suggest challenges in existing businesses and impacts from upfront investments. However, the company forecasts a recovery in net sales and a reduction in losses for FY2027, indicating that the effects of business structural reforms and new business developments could be key drivers for future performance. The deterioration in cash flow also warrants monitoring for potential implications on liquidity.
Disclaimer: This article is for informational purposes only and does not constitute investment advice.
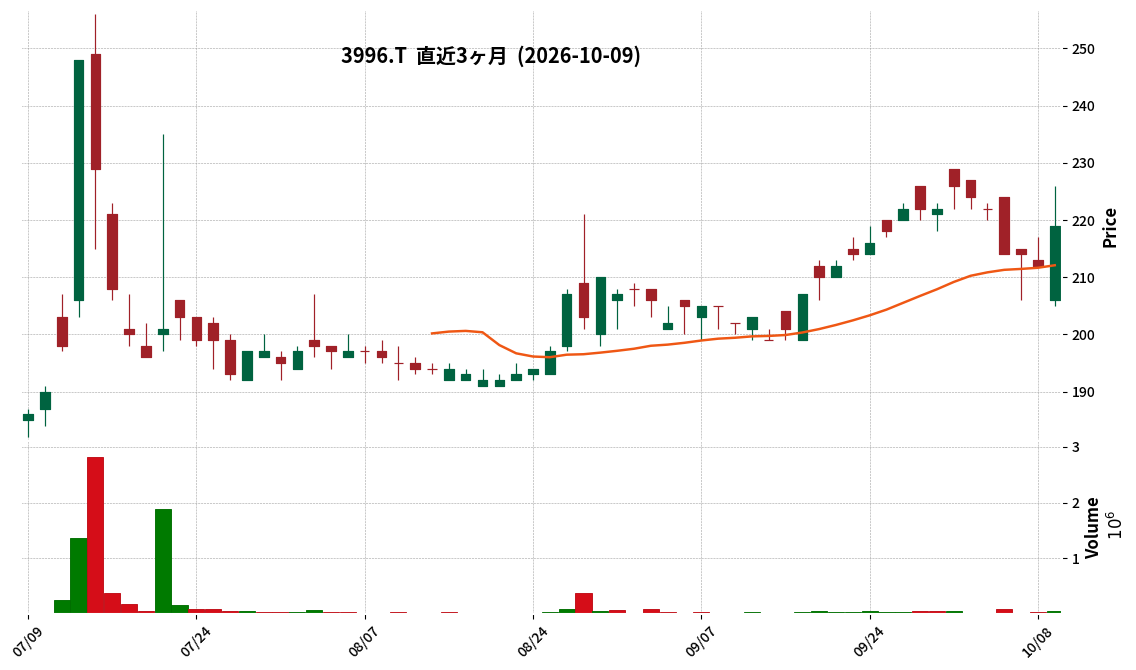
3996|サインポスト
219.0
▲ +3.30%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Signpost Co., Ltd. has announced its unaudited financial results for the second quarter (interim) of the fiscal year ending February 2027.
- For the period from March 1, 2026, to August 31, 2026, net sales reached ¥1,892 million, representing a 30.2% increase compared to the same period in the previous year.
- The company reported an operating income of ¥76 million (compared to an operating loss of ¥20 million in the prior year’s interim period) and an ordinary income of ¥76 million (compared to an ordinary loss of ¥25 million in the prior year’s interim period), marking a return to profitability.
- Interim net income was ¥92 million (compared to an interim net loss of ¥26 million in the prior year’s interim period), partly due to a ¥19 million gain on the sale of shares in TOUCH TO GO Corporation, recorded as extraordinary income.
- The annual dividend forecast has been revised from the most recently published forecast to ¥6.00 per share, consisting of a ¥1.00 ordinary dividend and a ¥5.00 commemorative dividend.
- The full-year earnings forecast for the fiscal year ending February 2027 has also been revised, projecting net sales of ¥3,850 million (up 22.7% YoY), operating income of ¥125 million (up 27.0% YoY), net income of ¥137 million (up 79.7% YoY), and earnings per share of ¥10.70.
- By segment, the Consulting Business recorded sales of ¥1,802 million (+29.9% YoY) and segment profit of ¥367 million (+52.7% YoY). The DX & Regional Co-creation Business reported sales of ¥78 million (+90.6% YoY) and segment profit of ¥13 million (vs. segment loss of ¥11 million YoY). The Innovation Business had sales of ¥11 million (-52.1% YoY) and a segment loss of ¥111 million (vs. segment loss of ¥68 million YoY).
🤖 AI Perspective
These interim results demonstrate a significant increase in net sales and a return to profitability, primarily driven by the robust growth of the Consulting Business. The extraordinary gain from the sale of shares in TOUCH TO GO Corporation also contributed to the interim net income. The upward revision of the annual dividend forecast and full-year earnings projections may suggest management’s increased confidence in future performance.
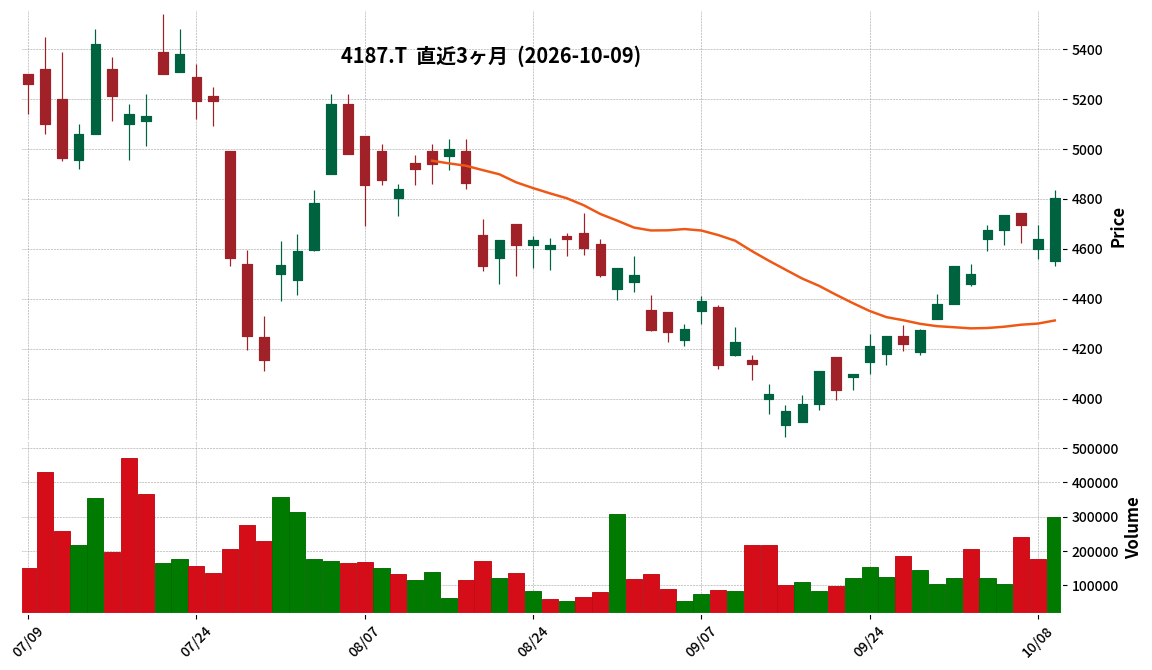
4187|大有機化
4805.0
▲ +3.56%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- For the nine months ended August 31, 2026 (Q3 FY2026), consolidated net sales amounted to ¥32,293 million, representing a 21.0% increase year-on-year.
- Operating profit for the same period was ¥7,578 million (up 63.6% YoY), ordinary profit was ¥7,893 million (up 62.9% YoY), and profit attributable to owners of parent was ¥5,325 million (up 55.0% YoY).
- The full-year consolidated earnings forecast for FY2026 has been revised: net sales to ¥42,500 million (up 17.2% YoY), operating profit to ¥9,300 million (up 50.3% YoY), ordinary profit to ¥9,600 million (up 46.4% YoY), and profit attributable to owners of parent to ¥6,600 million (down 4.2% YoY).
- The annual dividend forecast has been revised, with the year-end dividend set at ¥50.00, resulting in a total annual dividend of ¥93.00 (revised from the previous forecast of ¥75.00).
- Visnex Chemicals Corporation was newly included in the scope of consolidation during the cumulative third quarter.
🤖 AI Perspective
The reported Q3 results indicate robust performance with significant year-over-year growth across key financial metrics, suggesting strong operational momentum. The substantial increase in sales and profits appears to be driven by factors such as strong demand in the electronic materials business, particularly for semiconductor-related materials. The upward revision of the full-year earnings and dividend forecasts could signal management’s confidence in future performance, though the projected decline in full-year net profit attributable to owners of parent relative to the previous fiscal year’s actual result may be a point of interest for investors to monitor.
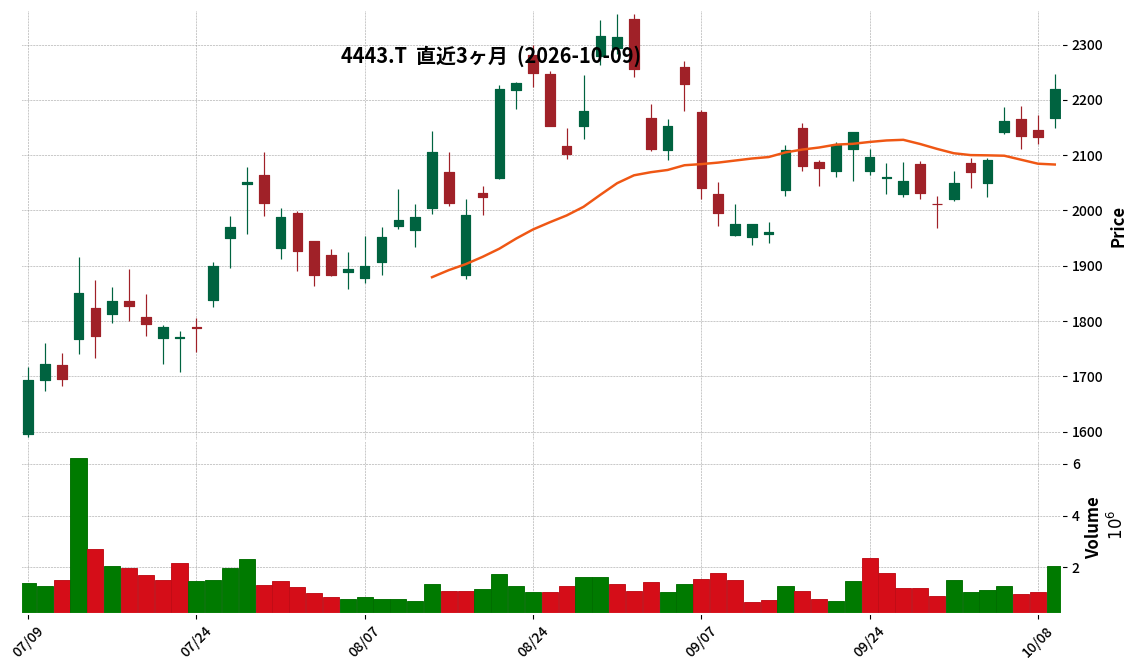
4443|Sansan
2219.0
▲ +4.03%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Sansan Inc. announced its consolidated financial results for the first quarter of the fiscal year ending May 2027 (June 1, 2026, to August 31, 2026).
- Revenue for the quarter reached ¥14,753 million, representing a 20.1% increase compared to the same period last year.
- Adjusted operating profit surged to ¥2,475 million, marking a substantial 328.3% increase year-on-year.
- Net profit attributable to owners of the parent company was ¥1,545 million, up 418.4% from the prior year’s first quarter.
- The consolidated full-year forecast for May 2027 remains unrevised, projecting revenue between ¥63,706 million and ¥65,319 million, and adjusted operating profit between ¥12,741 million and ¥14,696 million.
🤖 AI Perspective
Sansan’s first-quarter results demonstrate significant growth in both revenue and profit, with a particularly notable increase in adjusted operating profit. This robust performance is primarily attributed to a decrease in advertising and personnel costs. Given the expanding market for AX (AI Transformation) services, on which the company focuses, these results could indicate strong operational efficiency and market penetration.
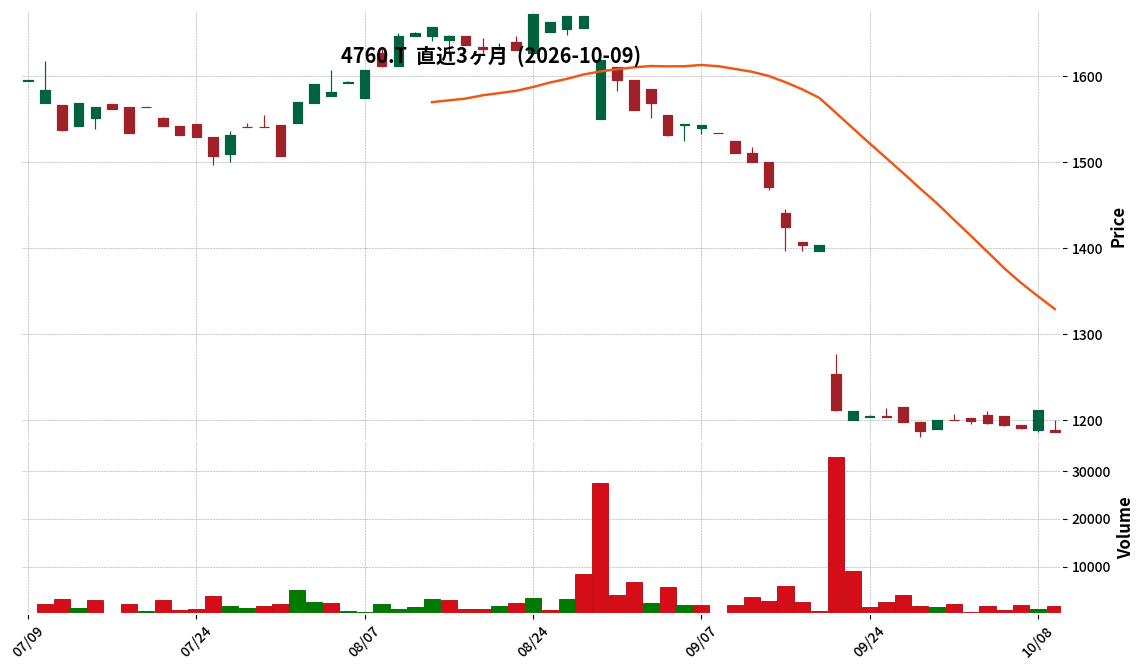
4760|アルファ
1186.0
▼ -2.15%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Alpha Inc. announced its consolidated financial results for the fiscal year ended August 31, 2026 (September 1, 2025 – August 31, 2026).
- Consolidated net sales were ¥6,364 million (△0.0% year-on-year), operating profit was ¥163 million (△30.5% year-on-year), ordinary profit was ¥147 million (△34.4% year-on-year), and profit attributable to owners of parent was ¥32 million (△74.7% year-on-year).
- By segment, Pop Gallery manufactured products generated ¥2,699 million in sales (△2.8% year-on-year), custom-made products ¥2,359 million (0.0% year-on-year), and service activities ¥1,304 million (6.3% year-on-year).
- The annual dividend per share for the fiscal year was ¥70 (compared to ¥60 in the previous year) for a total of ¥56 million (compared to ¥48 million in the previous year).
- For the fiscal year ending August 31, 2027, the company forecasts consolidated net sales of ¥6,600 million (3.7% increase year-on-year), operating profit of ¥210 million (28.8% increase), ordinary profit of ¥200 million (35.9% increase), and profit attributable to owners of parent of ¥65 million (101.5% increase).
🤖 AI Perspective
Alpha’s fiscal year 2026 results show a flat sales performance but a significant decline in operating, ordinary, and net profits compared to the previous year. This appears to be influenced by a decrease in gross profit margin due to rising procurement costs and increased selling, general, and administrative expenses. However, the service activities segment demonstrated sales growth, which may suggest positive contributions from digital and SNS-based services. The company’s forecast for FY2027 projects increases in both revenue and profit, which could be a key point for investors to monitor going forward.
4992|北興化
1952.0
▲ +0.83%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Hokko Chemical Industry Co., Ltd. announced its consolidated financial results for the third quarter of the fiscal year ending November 2026 (December 1, 2025 – August 31, 2026).
- Consolidated net sales reached ¥44,924 million (up 8.0% year-on-year), operating profit was ¥5,408 million (up 11.6%), ordinary profit was ¥6,268 million (up 12.3%), and net profit attributable to owners of parent was ¥4,504 million (up 9.1%).
- By segment, the Agricultural Chemicals business reported net sales of ¥30,580 million (up 13.1%) and operating profit of ¥3,002 million (up 82.6%).
- The Fine Chemicals business recorded net sales of ¥12,911 million (down 1.4%) and operating profit of ¥2,346 million (down 25.5%).
- The consolidated full-year earnings forecast and dividend forecast (year-end ¥54.00) for the fiscal year ending November 2026 remain unchanged from the most recently published figures.
🤖 AI Perspective
Hokko Chemical’s Q3 results show an increase in net sales and all profit metrics compared to the previous year. The Agricultural Chemicals business appears to be the primary driver of this growth, supported by strong domestic and international sales and the weakening yen. Conversely, the Fine Chemicals business experienced declines in both net sales and operating profit, indicating divergent performance between segments. As the full-year forecast remains unchanged, investors may focus on the progress of the remaining period.
5271|トーヨーアサノ
2299.0
▲ +1.10%
📎 Source:トーヨーアサノ Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Toyo Asano announced its consolidated financial results for the second quarter (interim period) of the fiscal year ending February 2027.
- For the period from March 1, 2026, to August 31, 2026, net sales were ¥6,285 million, representing a 13.4% decrease compared to the same period in the previous year.
- Operating profit was ¥42 million (down 91.0% year-on-year), and ordinary profit was ¥32 million (down 92.5% year-on-year).
- Net income attributable to owners of parent amounted to ¥13 million, a 77.0% decrease from the prior year’s interim period.
- The full-year consolidated earnings forecast for the fiscal year ending February 2027 remains unchanged from the most recently published forecast, projecting sales of ¥11,500 million, operating loss of ¥200 million, ordinary loss of ¥280 million, and net loss attributable to owners of parent of ¥170 million.
- The interim dividend is ¥40 per share, with an expected year-end dividend of ¥45, totaling ¥85 for the full year, with no changes from the latest forecast.
🤖 AI Perspective
Toyo Asano’s Q2 FY2027 results show significant year-on-year declines in sales and profit metrics, primarily attributed to reduced demand and intensified competition in its core foundation business, alongside rising raw material costs. However, the real estate leasing business maintained stable performance, potentially acting as a stabilizing factor within the company’s business portfolio. With the full-year forecast unchanged, the effectiveness of intensified “Reform strategy” measures in the latter half of the fiscal year will be a key area for observation.
6136|OSG
3653.0
▼ -0.27%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- OSG’s consolidated net sales for the nine months ended August 31, 2026 (Q3 FY2026) reached ¥143,245 million, a 23.5% increase year-over-year.
- Operating profit was ¥27,543 million (up 100.2%), ordinary profit was ¥29,495 million (up 96.8%), and net profit attributable to owners of parent was ¥21,364 million (up 121.5%).
- All key financial metrics—net sales, operating profit, ordinary profit, and net profit attributable to owners of parent—set new record highs for the third quarter cumulative period. The overseas sales ratio increased to 70.3% (from 67.9% in the prior year).
- The full-year consolidated earnings forecast for FY2026 has been revised upwards, projecting net sales of ¥193,000 million (up 20.2% year-on-year), operating profit of ¥36,000 million (up 77.1%), ordinary profit of ¥38,000 million (up 70.0%), and net profit attributable to owners of parent of ¥24,000 million (up 67.4%).
- The annual dividend forecast has also been revised for FY2026, with an interim dividend of ¥39.00 and a year-end dividend forecast of ¥91.00, totaling ¥130.00.
🤖 AI Perspective
OSG’s strong Q3 performance, achieving record highs across key metrics, appears to be driven by robust demand in semiconductor-related and labor-saving investments, alongside the tailwind from a weaker yen and the impact of sales price revisions. The upward revision of full-year earnings and dividend forecasts may suggest management’s confidence in the continued favorable market conditions. The improved equity ratio could also indicate a strengthening financial position, which investors might consider a positive sign.
6264|マルマエ
2243.0
▲ +7.63%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Marumae Co., Ltd. announced on October 9, 2026, a revision to its dividend forecast per share for the fiscal year ending August 2026.
- The total annual dividend is revised upwards from the previously announced ¥26.00 to the newly revised ¥28.00 per share.
- This revision is due to an increase in the year-end dividend amount.
- The reason for the dividend forecast revision is an expected upward revision in net profit for the current period, in line with the company’s dividend payout ratio target of 35% or more.
- The revised dividend forecast accounts for the 2-for-1 stock split of common shares effective April 1, 2026.
🤖 AI Perspective
Marumae’s upward revision of its dividend forecast may signal management’s strong commitment to shareholder returns. An increased dividend, driven by an expected rise in net profit, could be interpreted as an indicator of the company’s robust operational performance. The reaffirmation of a dividend payout ratio target of 35% or more under the current medium-term business plan might also suggest a sustained focus on stable shareholder distributions in the future.
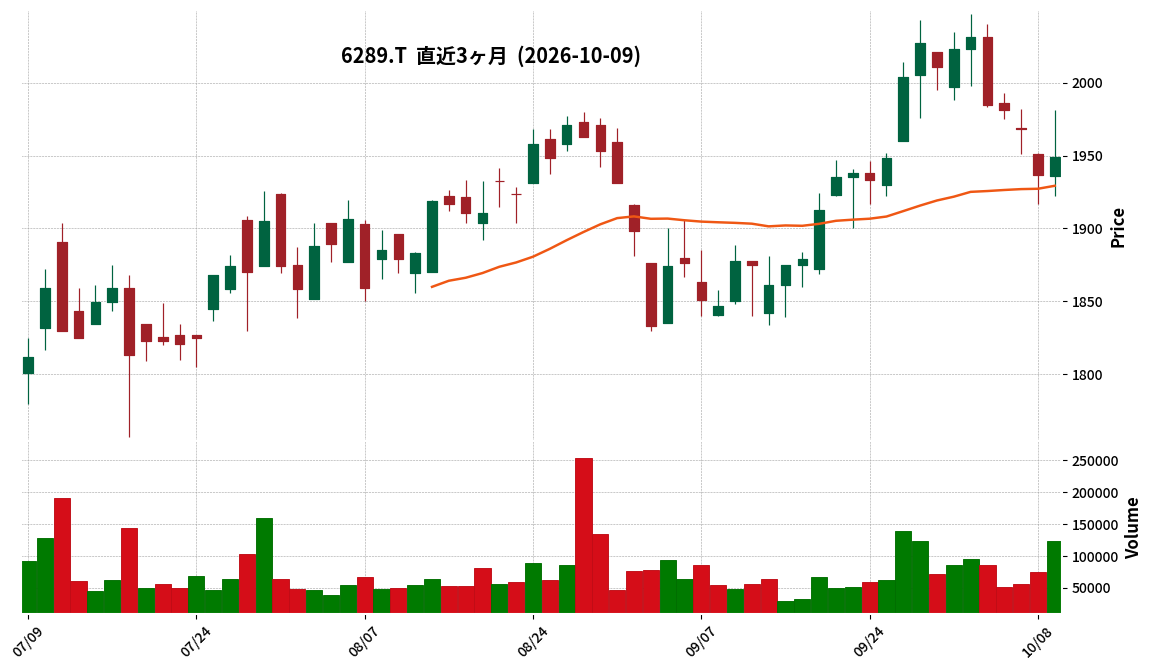
6289|技研製作所
1949.0
▲ +0.62%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Giken Ltd. announced its financial results for the fiscal year ended August 2026 (September 2025 to August 2026) and provided explanations for the full-year forecast for August 2027 on October 9, 2026.
- Consolidated net sales for FY2026 August reached ¥28,424 million, marking a 7.9% increase year-on-year, while operating profit rose by 19.3% to ¥3,062 million.
- The Construction Machinery segment reported net sales of ¥19,203 million (up 8.8% year-on-year) and operating profit of ¥4,331 million (up 11.3% year-on-year), driven by steady demand for hard-ground compatible machines and the new “SX Series” in Japan.
- The Press-in Works segment achieved net sales of ¥9,220 million (up 6.2% year-on-year) and operating profit of ¥1,157 million (up 6.1% year-on-year), attributed to an increase in domestic development-type projects and overseas rental services with operators.
- Profit attributable to owners of parent was ¥2,522 million (up 69.5% year-on-year), with basic earnings per share at ¥98.62. Special losses totaling ¥812 million were recorded due to a settlement with a former overseas consolidated subsidiary, including litigation-related losses and allowance for doubtful accounts.
🤖 AI Perspective
Giken Ltd.’s FY2026 August results demonstrate overall revenue and profit growth, with the Construction Machinery business showing notable strength, which may suggest effective product strategy and market demand. While both core segments contributed positively, investors might consider monitoring the impact of special losses and regional variations in overseas sales on future performance. The focus on new machines and development-type projects appears to be a key driver for the reported growth.
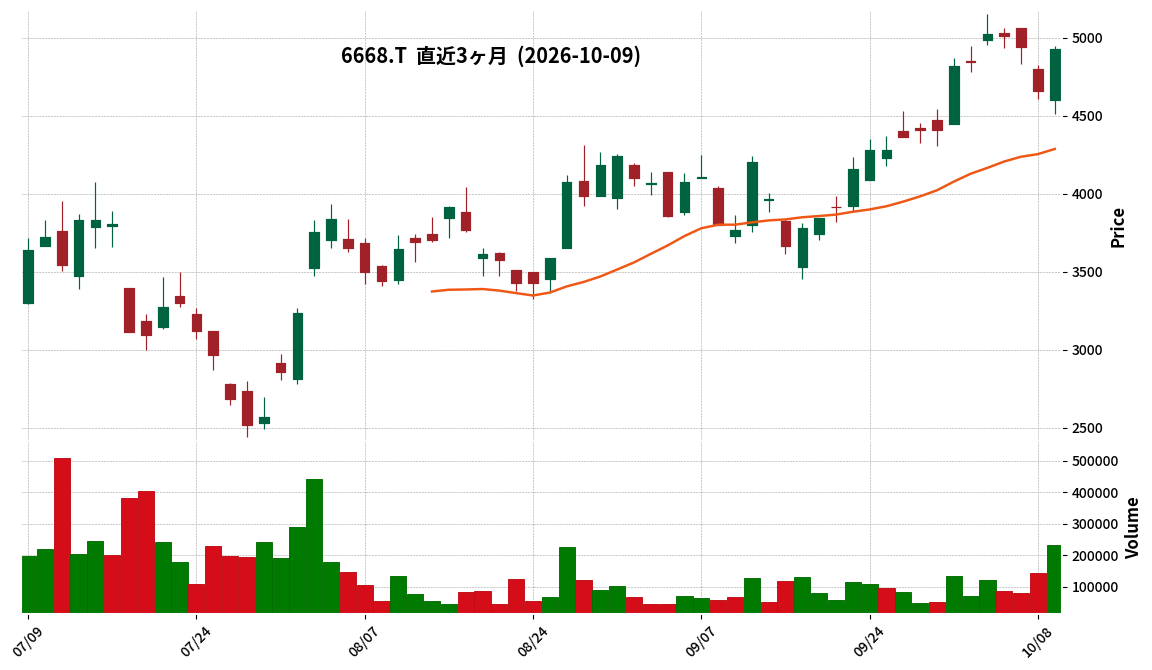
6668|アドテック プラズマ
4925.0
▲ +5.69%
📎 Source:アドテック プラズマ Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Adtec Plasma Technology Co., Ltd. reported consolidated results for the fiscal year ended August 2026: net sales of ¥13,884 million (up 9.5% year-on-year), operating profit of ¥2,562 million (up 41.7%), ordinary profit of ¥3,010 million (up 58.6%), and profit attributable to owners of parent of ¥2,127 million (up 6.0%).
- By segment, the Semiconductor/LCD-related business recorded sales of ¥13,059 million (up 15.3% year-on-year) and operating profit of ¥2,438 million (up 43.2%). The Research Institutions/Universities-related business reported sales of ¥825 million (down 39.0%) and operating profit of ¥46 million (up 24.2%).
- The consolidated earnings forecast for the fiscal year ending August 2027 projects net sales of ¥21,500 million (up 54.8% year-on-year), operating profit of ¥5,300 million (up 106.8%), ordinary profit of ¥5,000 million (up 66.1%), and profit attributable to owners of parent of ¥3,700 million (up 73.9%).
- The annual dividend for FY2026 was ¥30.00 (year-end ¥18.00), and the forecast for FY2027 is ¥50.00 (interim ¥25.00, year-end ¥25.00).
- As of August 2026, consolidated total assets were ¥29,515 million, net assets were ¥15,517 million, and the equity ratio was 52.6%.
🤖 AI Perspective
Adtec Plasma demonstrated strong performance in FY2026, achieving increases in all key profitability metrics, including sales, operating profit, ordinary profit, and net profit attributable to parent company shareholders. The significant rise in operating profit, largely driven by the semiconductor and LCD-related business, is notable. Furthermore, the company’s forecast for FY2027 indicates substantial growth across all segments, with operating profit projected to more than double year-on-year. This positive outlook, coupled with a significant increase in the anticipated annual dividend, may suggest a strong underlying business momentum worth monitoring for investors.
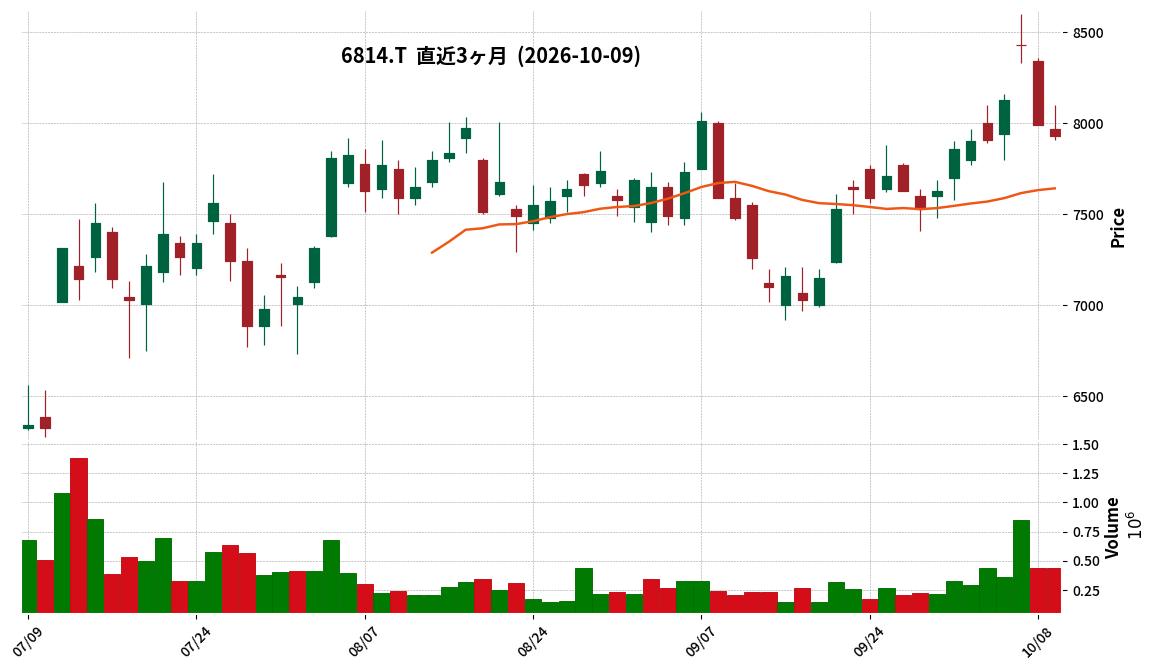
6814|古野電気
7930.0
▼ -0.75%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- FURUNO ELECTRIC revised its consolidated earnings forecast for the fiscal year ending February 2027 upward. Revenue is projected to increase from ¥148,500 million to ¥158,000 million (up 6.4%), operating profit from ¥17,000 million to ¥21,000 million (up 23.5%), ordinary profit from ¥17,000 million to ¥22,000 million (up 29.4%), and profit attributable to owners of parent from ¥13,000 million to ¥17,000 million (up 30.8%).
- The interim dividend for the fiscal year ending February 2027 was revised upward by ¥35, from the previous forecast of ¥80 per share to ¥115 per share. The record date is August 31, 2026, and the effective date is November 10, 2026.
- The year-end dividend forecast for the fiscal year ending February 2027 was revised upward by ¥15, from the previous forecast of ¥80 per share to ¥95 per share. This results in an estimated annual dividend of ¥210 per share.
- Reasons for the revisions include better-than-expected performance in the second quarter and stronger-than-anticipated sales in the core marine business due to robust market conditions.
- The assumed exchange rates for the full-year forecast were changed to USD 159 (previously USD 153) and EUR 184 (previously EUR 183).
🤖 AI Perspective
FURUNO ELECTRIC’s upward revision of its earnings forecast appears to be primarily driven by strong performance in its marine business, despite facing headwinds from rising component prices. The significant increase in both interim and year-end dividend forecasts may signal the company’s commitment to achieving its medium-term management plan target of a total shareholder return ratio of approximately 40%. Investors may view these revisions as an indication of the company’s robust operational execution and shareholder return policy.
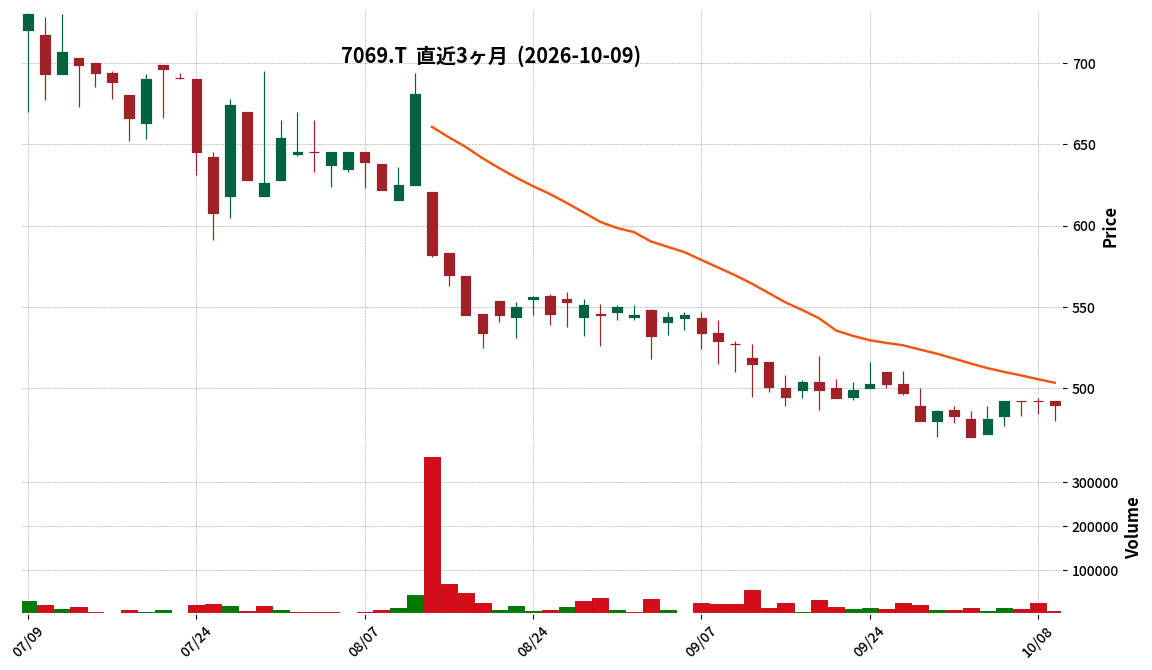
7069|G-サイバー・バズ
490.0
▼ -0.41%
📎 Source:G-サイバー・バズ Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- G-Cyberbuzz Co., Ltd. announced on October 9, 2026, an upward revision to its consolidated financial forecast for the full fiscal year ending September 2026.
- The revised consolidated net sales are JPY 8,600 million (an increase of JPY 400 million from the previous forecast of JPY 8,200 million), and consolidated operating profit is JPY 668 million (an increase of JPY 148 million from JPY 520 million).
- Consolidated ordinary profit is revised to JPY 647 million (up JPY 160 million from JPY 487 million), and profit attributable to owners of parent is JPY 520 million (up JPY 152 million from JPY 368 million).
- Earnings per share (EPS) are now JPY 64.12 (from the previous forecast of JPY 45.55).
- Reasons for the revision include robust order acquisition and sales growth in the core SMM and live streaming platform businesses, improved operational efficiency through AI utilization, cost management, and the deferral of some strategic investments to subsequent periods.
🤖 AI Perspective
This upward revision to the financial forecast highlights strong performance not only in revenue but also significant improvements in profitability. A noteworthy aspect is that the deferral of some strategic investments to the next fiscal year has contributed to the current period’s profit, which is a factor for investors to consider when evaluating the balance between short-term results and future investments. This suggests that the company’s core businesses are performing robustly, supported by the growth of the domestic internet advertising market.
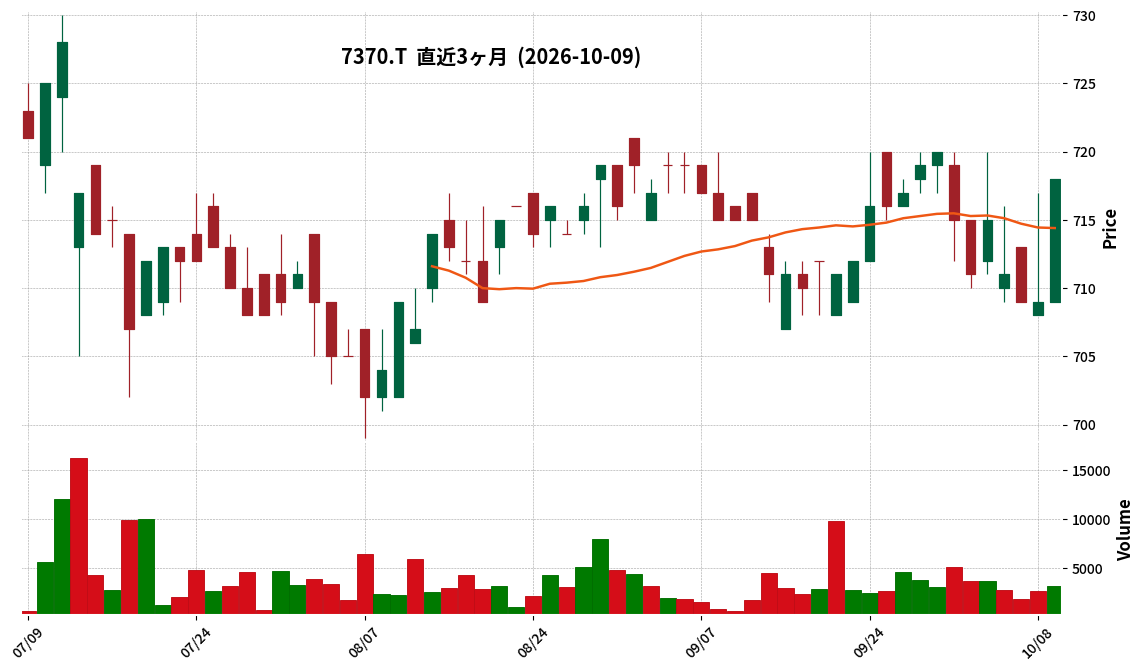
7370|G-Enjin
718.0
▲ +1.27%
📎 Source:G-Enjin Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- G-Enjin announced its consolidated financial results for the first quarter of FY2027 (June 1, 2026 – August 31, 2026).
- Consolidated revenue reached ¥755 million, marking a 48.6% increase compared to the same period in the previous year.
- Consolidated operating profit was ¥35 million (up 8.5% year-on-year), ordinary profit was ¥35 million (down 29.8% year-on-year), and net profit attributable to parent company shareholders was ¥30 million (down 2.5% year-on-year).
- By segment, the PR business reported revenue of ¥582 million (up 14.6% year-on-year) and segment profit of ¥82 million (up 153.3% year-on-year). The Real Estate business and Tourism business recorded revenue but posted segment losses.
- The full-year consolidated earnings forecast remains unchanged from the announcement made on July 13, 2026.
🤖 AI Perspective
G-Enjin’s first-quarter results indicate strong top-line growth, with the PR business appearing to be a significant driver. However, the decline in ordinary and net profits suggests that investors may want to monitor cost structures and the impact of investments in new business segments. The reaffirmation of the full-year forecast could imply that the company’s management has already factored in the current performance trends.
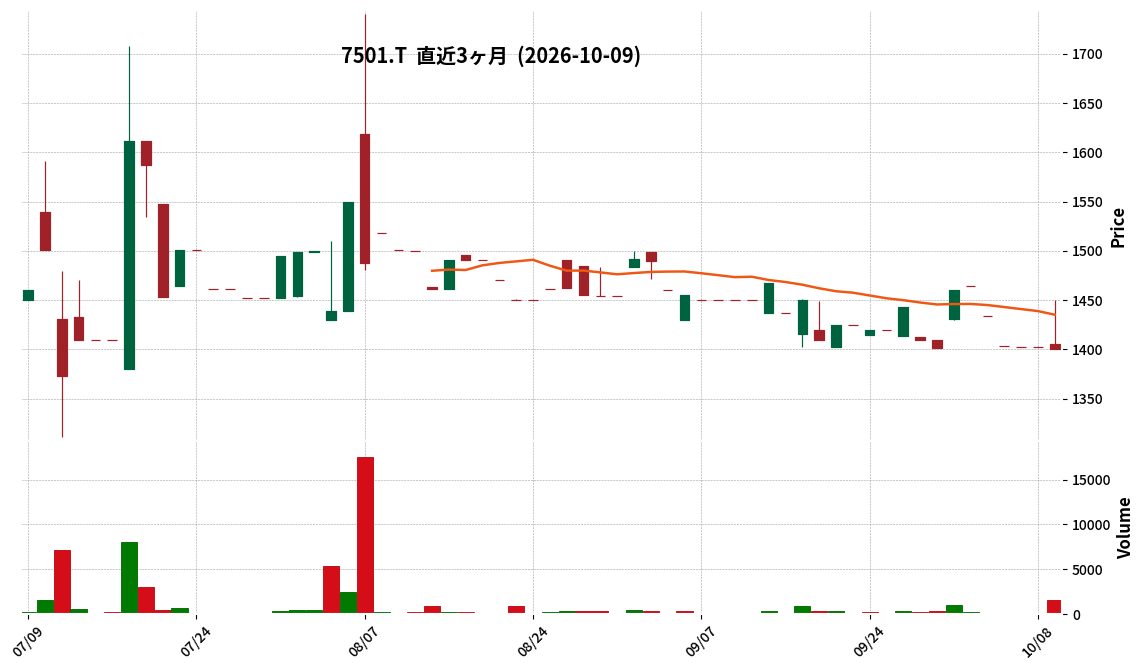
7501|ティムコ
1400.0
▼ -0.21%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Tiemco Co., Ltd. announced its financial results for the third quarter of fiscal year 2026 (December 1, 2025 – August 31, 2026).
- During this cumulative third quarter, net sales reached JPY 2.613 billion, marking a 12.2% increase compared to the same period in the previous year.
- The company reported an operating loss of JPY 68 million, an ordinary loss of JPY 58 million, and a net loss of JPY 86 million for the period.
- Loss per share for the quarter was JPY △34.76.
- The full-year performance forecast has been revised downwards, projecting net sales of JPY 3.502 billion (up 8.8% year-on-year), an operating loss of JPY 75 million, an ordinary loss of JPY 63 million, and a net loss of JPY 103 million (loss per share JPY △41.59).
- The annual dividend forecast remains unchanged at JPY 12.00 per share.
🤖 AI Perspective
Tiemco achieved increased revenue in the third quarter but continued to record losses. The decline in gross profit margin, increased selling, general, and administrative expenses including personnel costs, and the recording of JPY 14 million in special losses for public tender offer response costs appear to have contributed to the losses. The downward revision of the full-year earnings forecast is a key factor for investors to monitor going forward.
Disclaimer: This article is for informational purposes only and does not constitute investment advice.
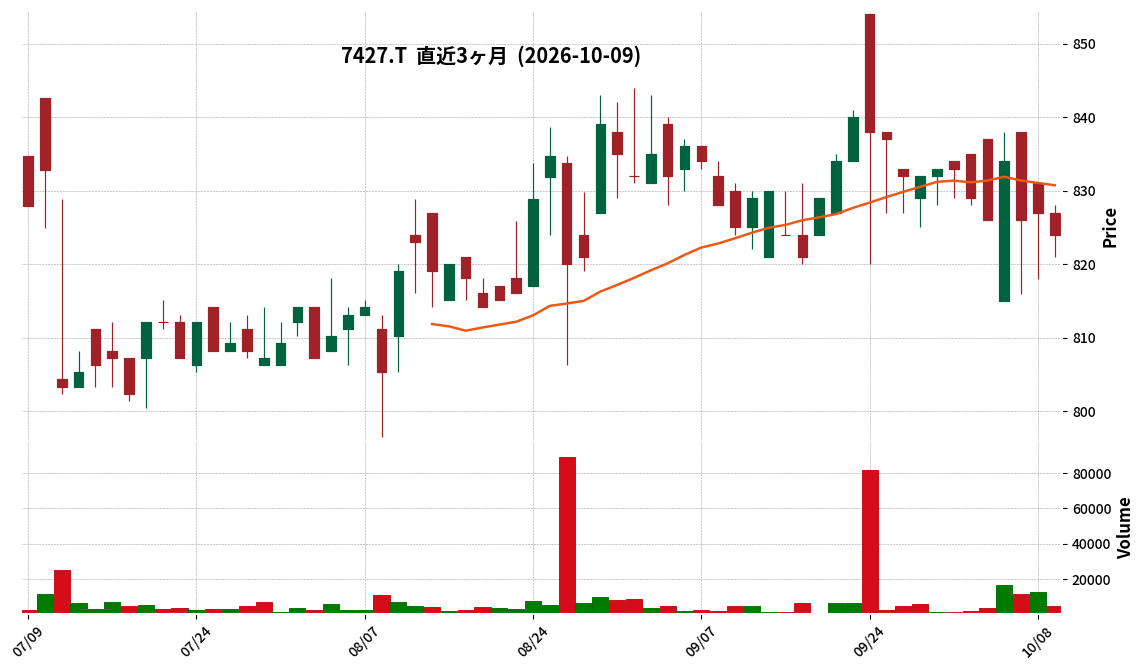
7427|エコーTD
824.0
▼ -0.36%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Echotd Co., Ltd. announced its consolidated financial results for the second quarter (interim period) of the fiscal year ending February 2027.
- For the interim period, net sales were ¥55,064 million, an increase of 4.1% compared to the same period of the previous year.
- Operating income was ¥330 million, representing a decrease of 51.2% year-on-year.
- Ordinary income was ¥314 million, a decrease of 53.7% year-on-year.
- Net income attributable to owners of parent was ¥187 million, down 58.7% from the previous year.
- Basic earnings per share for the interim period was ¥30.84.
- The full-year consolidated earnings forecast remains unchanged from the most recently published forecast, projecting net sales of ¥110,000 million (up 4.0% YoY), operating income of ¥1,150 million (up 3.6% YoY), ordinary income of ¥1,147 million (up 3.6% YoY), and net income attributable to owners of parent of ¥758 million (down 2.6% YoY), with basic earnings per share of ¥124.81.
- The equity ratio at the end of the interim period was 32.6%.
🤖 AI Perspective
While Echotd reported an increase in net sales for the interim period, a significant decline in profit margins was observed. This appears to be attributable to rising procurement costs and increased logistics expenses, which impacted the gross profit margin and led to a substantial decrease in operating income, as detailed in the attached materials. With the full-year earnings forecast remaining unchanged, investors may monitor the company’s strategies for profit improvement and cost management in the second half of the fiscal year.
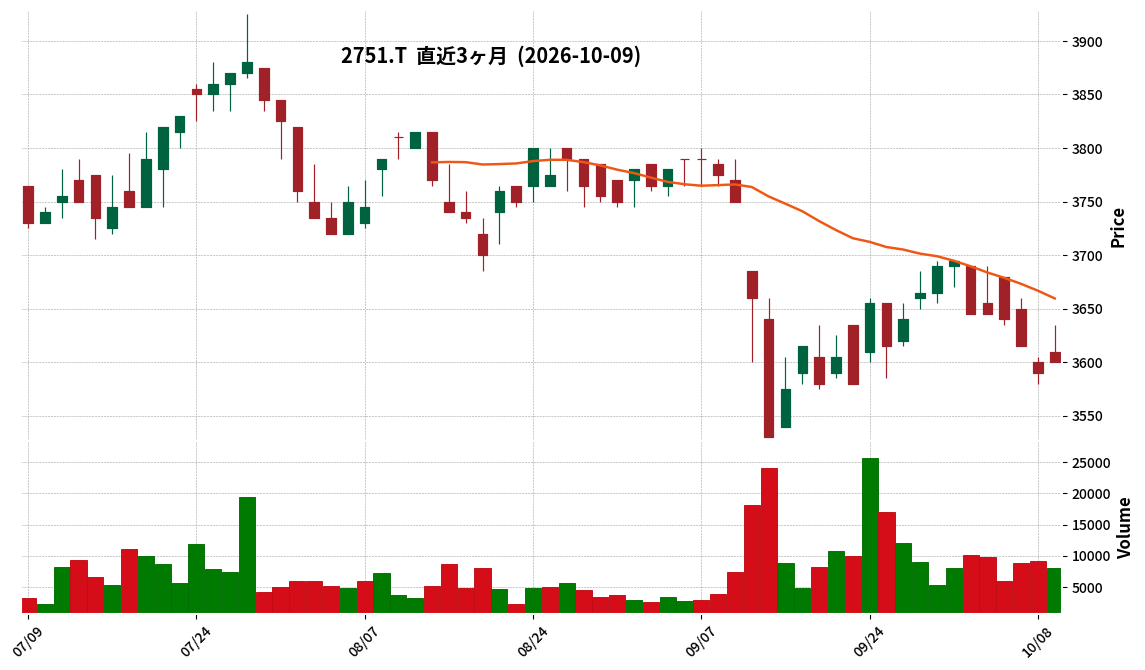
2751|テンポスHD
3600.0
▲ +0.28%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Tempo Holdings Co., Ltd. announced a correction to a part of its “Consolidated Financial Results for the First Quarter of the Fiscal Year Ending April 2027 [Japanese GAAP]”, originally disclosed on September 9, 2026.
- The reason for the correction was the discovery of an error in a part of the financial results document.
- The correction specifically applies to the “Net Sales” figure in the summary information, under “1. Consolidated Operating Results for the First Quarter of the Fiscal Year Ending April 2027 (May 1, 2026 – July 31, 2026) (1) Consolidated Operating Results (Cumulative)”.
- The net sales for the first quarter of the fiscal year ending April 2027 were corrected from “14,097 million yen” to “14,092 million yen”.
- This correction has no impact on profit or loss, including operating income, ordinary income, and net income attributable to owners of the parent.
🤖 AI Perspective
This correction addresses a minor discrepancy in the reported net sales figure for the first quarter. The fact that this adjustment does not affect the company’s profitability or loss figures could be a key point for investors. Such revisions typically underscore a company’s commitment to accurate financial reporting and transparency.
3063|G-jGroup
1119.0
▲ +0.99%
📎 Source:G-jGroup Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
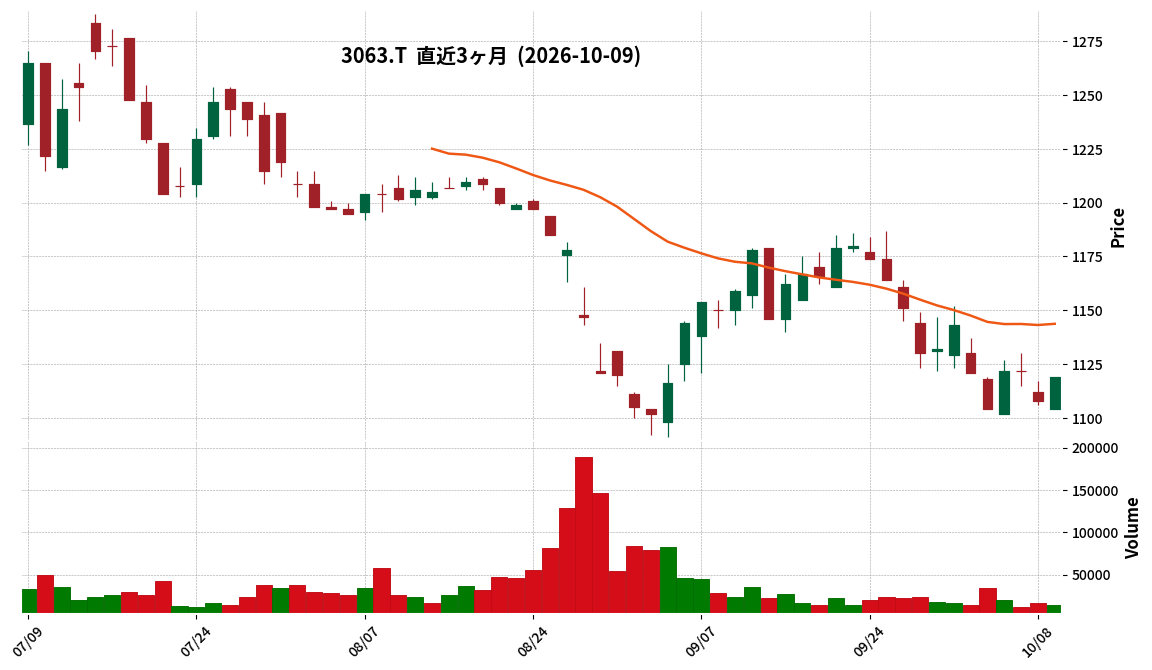
- G-jGroup announced its consolidated financial results for the second quarter of the fiscal year ending February 2027 (March 1, 2026, to August 31, 2026).
- Net sales totaled ¥6,219 million, representing a 12.0% decrease compared to the same period last year. Operating profit was ¥121 million (down 55.6% YoY), ordinary profit was ¥90 million (down 60.3% YoY), and net profit attributable to parent company shareholders was ¥62 million (down 62.2% YoY).
- By segment, the Food & Beverage business reported net sales of ¥5,860 million (up 3.6% YoY) and operating profit of ¥653 million (up 4.4% YoY). The Real Estate business reported net sales of ¥224 million (down 83.1% YoY) and operating profit of ¥27 million (down 95.6% YoY).
- The consolidated full-year earnings forecast (March 1, 2026, to February 28, 2027) remains unchanged from the most recently published forecast, with net sales of ¥13,300 million, operating profit of ¥450 million, ordinary profit of ¥370 million, and net profit attributable to parent company shareholders of ¥320 million.
- An interim dividend of ¥3.00 per share is planned, consisting of a ¥2.00 ordinary dividend and a ¥1.00 30th-anniversary commemorative dividend.
🤖 AI Perspective
G-jGroup’s Q2 FY2027 results show a year-over-year decline in sales and profits, primarily driven by a significant decrease in the Real Estate segment’s sales and profits, which had benefited from inventory sales in the prior interim period. Conversely, the Food & Beverage segment demonstrated revenue and profit growth, suggesting a recovery in core operations and the positive impact of M&A activities. The unchanged full-year outlook may indicate management’s expectation for stronger performance in the second half of the fiscal year.
3550|G-スタジオアタオ
216.0
▲ +0.00%
📎 Source:G-スタジオアタオ Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
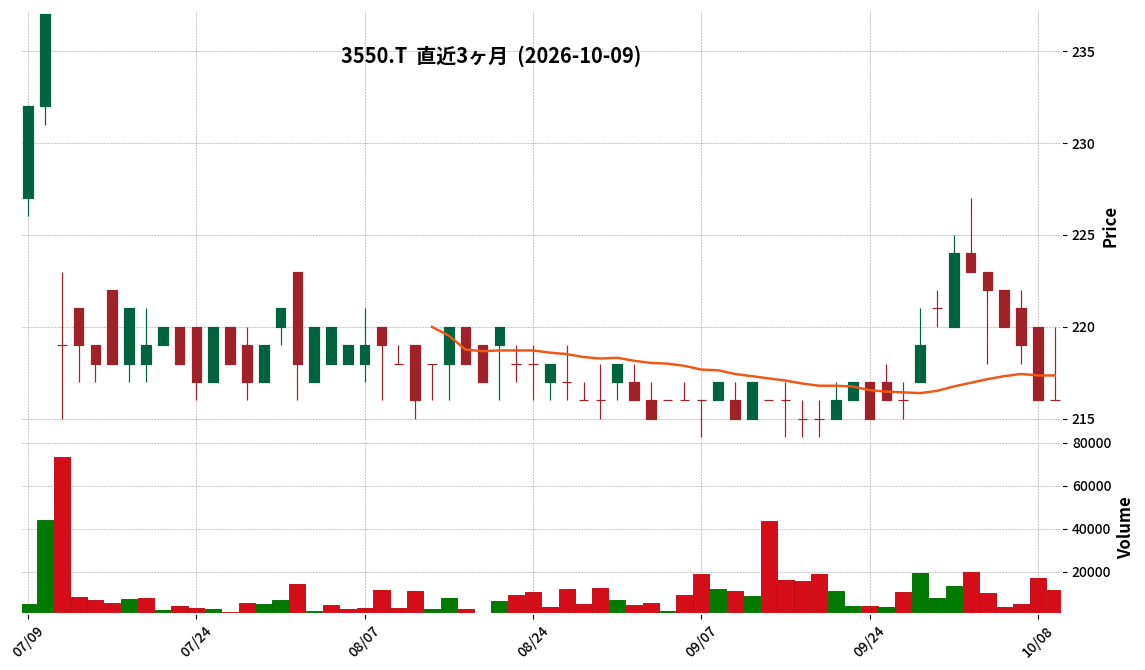
- G-Studio ATAO (3550) reported net sales of ¥1,959 million for the second quarter (interim period) of the fiscal year ending February 2027 (March 1, 2026 to August 31, 2026), marking a 5.3% increase compared to the previous interim period.
- Operating profit was ¥99 million (a 7.0% decrease year-on-year), and ordinary profit was ¥104 million (a 3.3% decrease year-on-year).
- Interim net profit reached ¥69 million, an increase of 2.0% year-on-year.
- Interim net profit per share was ¥4.99.
- The full-year forecast for FY2027 remains unchanged from the most recent announcement, projecting net sales of ¥4,500 million (a 9.1% increase from the previous period), operating profit of ¥330 million (a 37.9% increase), ordinary profit of ¥335 million (a 37.8% increase), and net profit of ¥220 million (a 45.2% increase).
- The annual dividend forecast is ¥5.00 per share (¥5.00 at year-end), with no revisions from the latest publicly announced forecast.
🤖 AI Perspective
G-Studio ATAO’s interim results for FY2027 show an increase in net sales, while operating and ordinary profits declined, despite a slight increase in interim net profit. This could be attributed to increased promotional activities, new store openings, and relocation-related temporary expenses. The unchanged full-year forecast may suggest that the company anticipates a recovery in performance during the second half of the fiscal year.
3936|G-グローバルウェイ
127.0
▲ +1.60%
📎 Source:G-グローバルウェイ Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
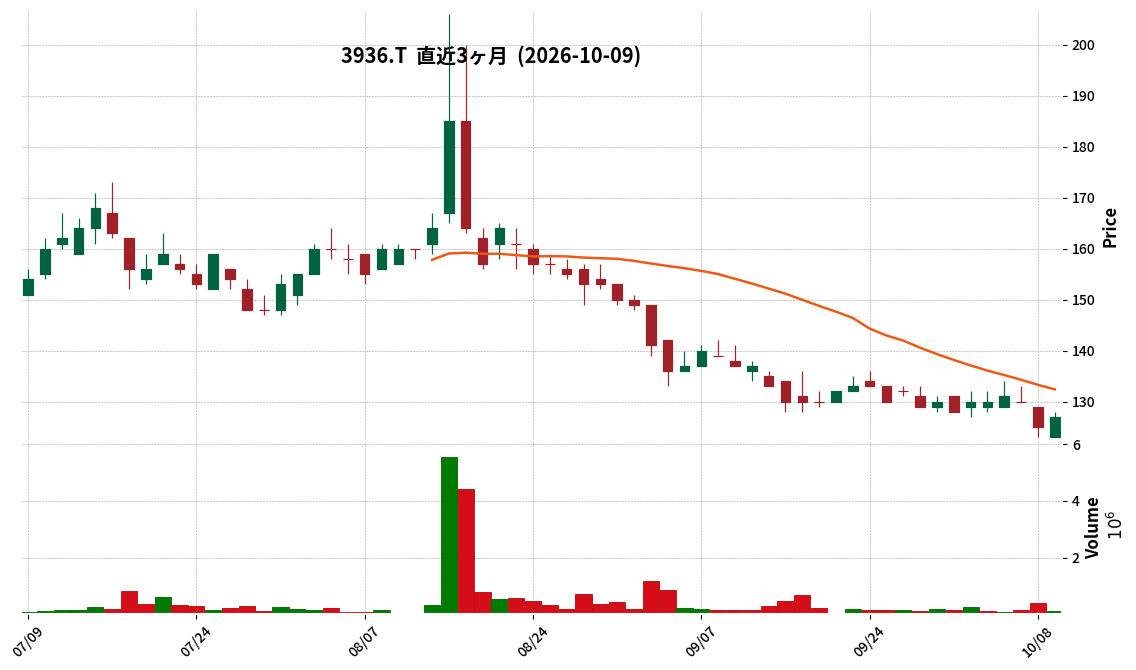
- G-Globalway Co., Ltd. resolved on October 9, 2026, to form a capital and business alliance with Snow Mountain AI Private Limited (SM Co.) and establish a joint venture (subsidiary).
- SM Co. is an Indian company developing and providing the AI agent platform “QwikBuild.” G-Globalway aims for exclusive deployment of this platform in the Japanese market.
- G-Globalway will subscribe to 1,190 common shares issued by SM Co. for 500,000 USD (approximately 77 million JPY), with an anticipated ownership ratio of 5.00% (on a fully diluted basis) after the acquisition.
- The joint venture, “QwikBuild Co., Ltd. (tentative name),” is scheduled for establishment in December 2026, with Mr. Masato Kagami, G-Globalway’s Representative Director, Chairman & President CEO, appointed as its Representative Director.
- Investment in the joint venture will occur in three stages, with G-Globalway’s total investment amounting to 92,400,000 JPY. After the third stage, G-Globalway’s voting rights ratio is expected to be 70.0% and SM Co.’s 30.0%.
🤖 AI Perspective
This alliance appears to be a strategic move for G-Globalway to leverage Indian AI technology and strengthen its entry into the Japanese AI agent market. The combination of SM Co.’s AI platform technology and G-Globalway’s customer base could potentially accelerate the launch of AI businesses in Japan. However, SM Co. is a newly established startup and was in a state of insolvency as of the end of the fiscal year March 2026, which may be a factor to monitor as the business develops.
4240|クラスターT
302.0
▲ +0.33%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
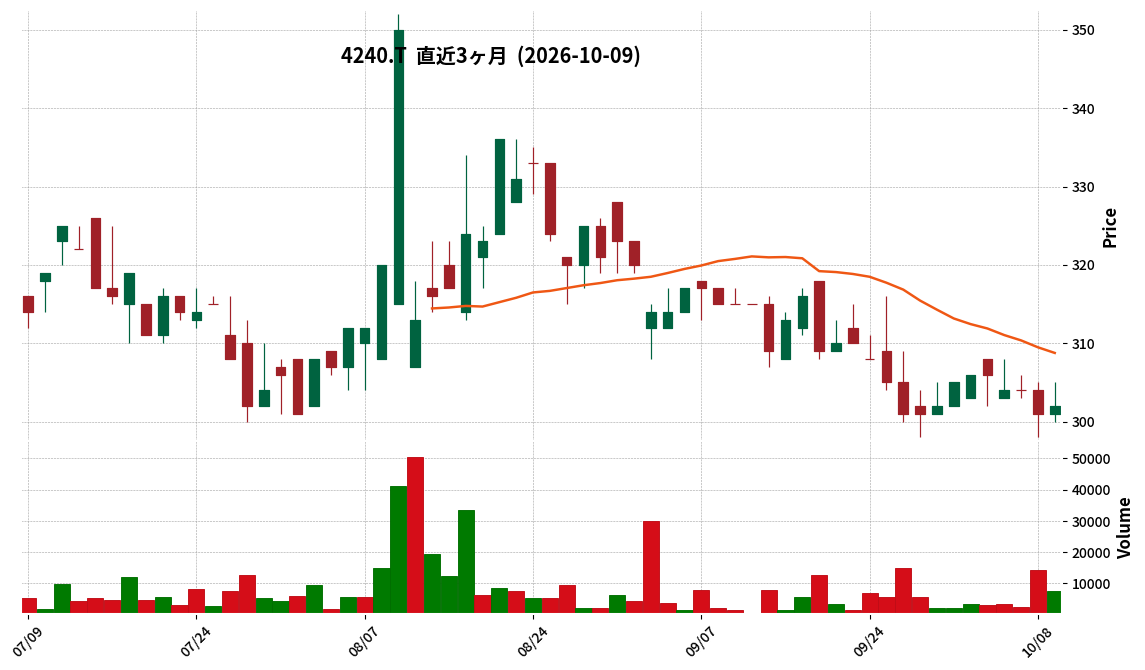
- Cluster Technology Co., Ltd. resolved at its Board of Directors meeting on October 9, 2026, to conclude a business alliance agreement with Seiko Epson Corporation and to issue new shares through a third-party allotment to Seiko Epson.
- The third-party allotment will involve the issuance of 996,677 shares of common stock, with an issue price of 301 yen per share, raising a total of 299,999,777 yen. The payment date is scheduled for October 27, 2026.
- Following this third-party allotment, Seiko Epson is expected to become a major shareholder and the largest major shareholder of Cluster Technology as of October 27, 2026.
- The proceeds will be allocated towards a portion of costs for factory expansion, renovation, and equipment enhancement for production capacity strengthening (178 million yen), factory building expansion and environmental improvement work for installing equipment to be loaned by Seiko Epson (59 million yen), and a portion of costs for advancing joint development themes (59 million yen).
- The business alliance includes activities such as strengthening Cluster Technology’s supply system for the long-term stable supply of components for Epson products, and joint development aimed at product commercialization utilizing Epson’s information equipment technology and Cluster Technology’s resin composite material and molding processing technologies.
🤖 AI Perspective
This announcement suggests Cluster Technology’s strategic move to strengthen its ties with a key client, Seiko Epson, and secure funding for business growth. The capital injection through the third-party allotment, coupled with expanded joint development efforts with Epson, could potentially enhance the company’s long-term corporate value. While dilution for existing shareholders will occur, the detailed allocation of funds indicates clear investment plans, making their execution a key area for investors to monitor.
5341|ASAHI EITO
123.0
▼ -1.60%
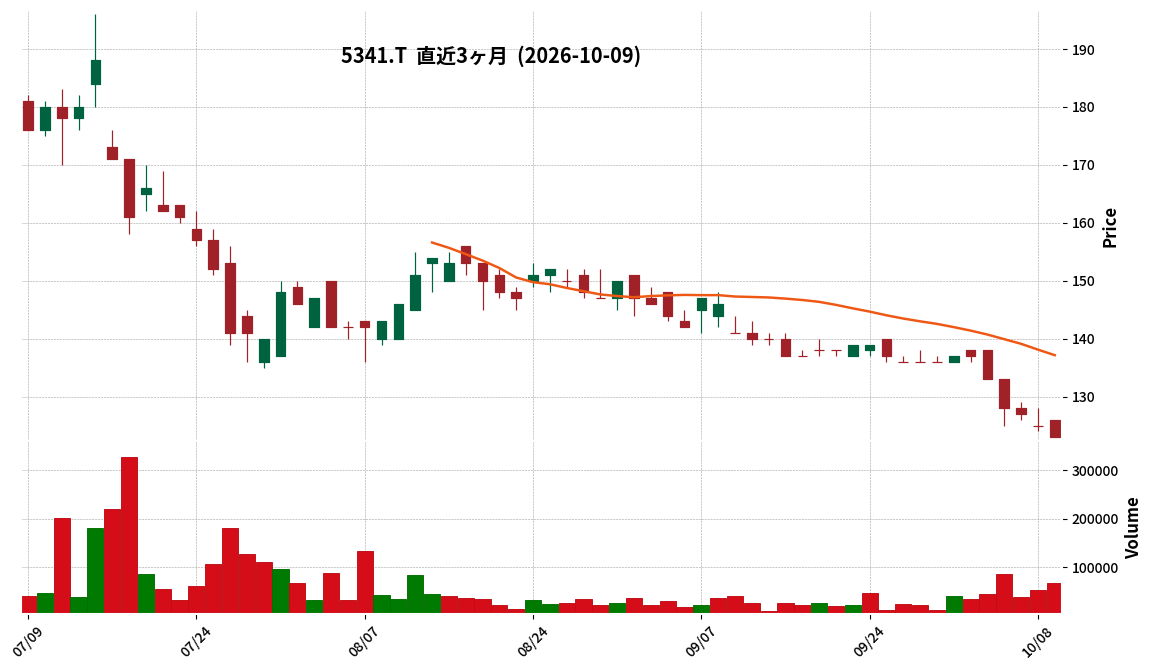
📎 Source:ASAHI EITO Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- ASAHI EITO Holdings announced its consolidated financial results for the third quarter of FY2026 (December 1, 2025 – August 31, 2026).
- Consolidated net sales for the period amounted to ¥3,099 million, representing a 3.7% decrease compared to the same period in the previous year.
- The company reported an operating loss of ¥90 million, which is a reduction from the operating loss of ¥177 million in the prior year’s same period.
- Ordinary loss was ¥92 million, and net loss attributable to parent company shareholders was ¥122 million, both indicating a reduction in losses compared to the previous year.
- As of the end of the third quarter, total assets stood at ¥3,022 million, net assets at ¥1,626 million, and the equity ratio was 49.2%.
- During the consolidated third quarter cumulative period, the company raised ¥623 million in funds, of which ¥229 million was allocated to the acquisition of crypto assets.
🤖 AI Perspective
ASAHI EITO’s Q3 results show a decrease in sales but a notable improvement in operating, ordinary, and net losses compared to the previous year, indicating a reduction in the magnitude of losses. The allocation of funds to crypto asset acquisition as part of its treasury business suggests progress in its business diversification strategy. Investors may monitor the impact of these new ventures on future financial performance.
6506|安川電
4783.0
▼ -0.13%
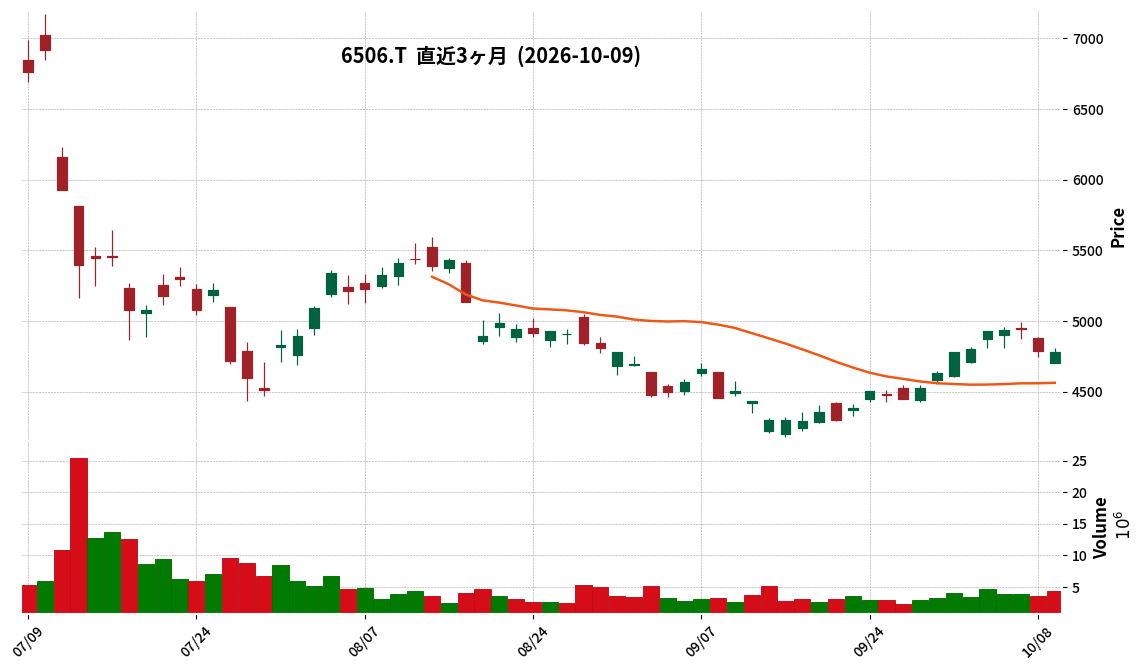
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Yaskawa Electric announced its consolidated financial results for the second quarter (interim period) of the fiscal year ending February 2027.
- Interim revenue reached ¥285,598 million (up 9.8% year-on-year), while operating profit was ¥22,058 million (down 5.5% year-on-year).
- Profit attributable to owners of the parent for the interim period was ¥18,988 million (up 4.1% year-on-year).
- By segment, Motion Control revenue was ¥137,286 million (up 21.7% year-on-year) with operating profit of ¥15,973 million (up 32.8% year-on-year).
- Robot segment revenue was ¥118,404 million (down 0.7% year-on-year) with operating profit of ¥5,974 million (down 43.3% year-on-year).
- The full-year consolidated performance forecast was revised to revenue of ¥600,000 million (up 10.7% year-on-year) and operating profit of ¥57,500 million (up 21.5% year-on-year).
- The annual dividend forecast is ¥72.00 per share, comprising ¥36.00 for the interim period and ¥36.00 for the fiscal year-end.
🤖 AI Perspective
The increase in revenue was primarily driven by robust demand in data centers and semiconductor-related investments, while the decline in operating profit appears to be influenced by expenses related to a core system migration and business structure reforms in Europe. The divergent performance between the Motion Control and Robot segments could indicate differing market dynamics or internal challenges within each business. The upward revision of the full-year forecast may suggest management’s confidence in an improved performance in the second half of the fiscal year.
9270|G-バリュエンスHD
1851.0
▲ +0.60%
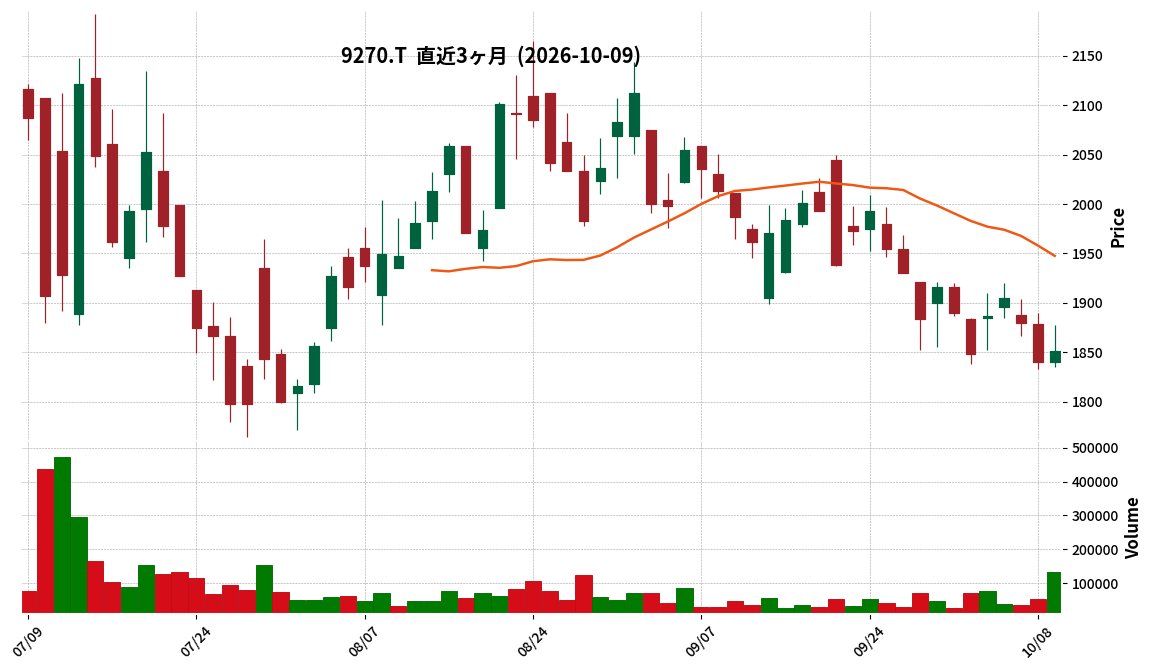
📎 Source:G-バリュエンスHD Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Valuence Holdings reported consolidated results for the fiscal year ended August 2026, with net sales of ¥106,656 million (up 25.7% year-on-year), operating profit of ¥5,780 million (up 297.6% year-on-year), ordinary profit of ¥5,399 million (up 310.4% year-on-year), and profit attributable to owners of parent of ¥3,073 million (up 350.7% year-on-year).
- Basic earnings per share increased to ¥233.15 from ¥52.00 in the previous fiscal year.
- The annual dividend for the fiscal year ended August 2026 was announced as ¥45.00 per share, a significant increase from ¥10.00 in the prior period.
- For the fiscal year ending August 2027, the company forecasts consolidated net sales of ¥115,000 million (up 7.8% year-on-year), operating profit of ¥6,750 million (up 16.8% year-on-year), and profit attributable to owners of parent of ¥4,000 million (up 30.2% year-on-year).
- The company projects an annual dividend of ¥55.00 per share for the fiscal year ending August 2027.
🤖 AI Perspective
Valuence Holdings’ FY2026 results show substantial growth across key profitability metrics, which may suggest that its structural reforms and targeted investments are yielding positive outcomes. The nearly 300% increase in operating profit is particularly noteworthy. The significant increase in the annual dividend, coupled with projections for continued revenue, profit, and dividend growth in the next fiscal year, indicates a positive outlook from the company regarding its future business performance and shareholder returns.
2735|ワッツ
712.0
▼ -0.56%
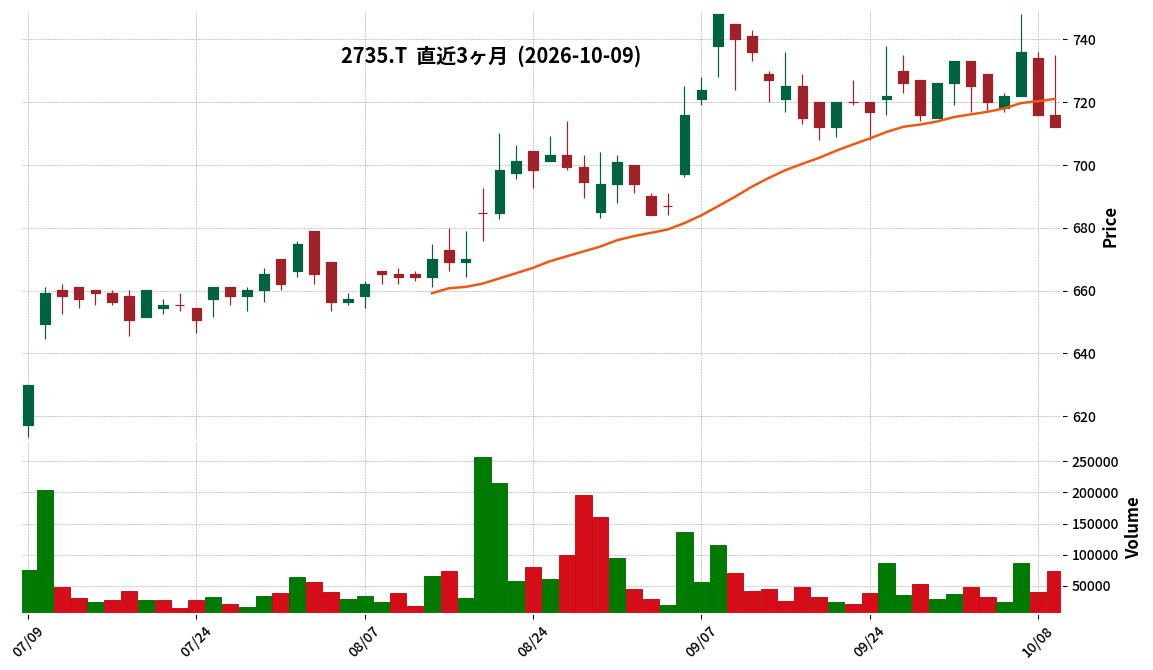
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Watts Co., Ltd. resolved to increase its surplus dividend for the period ending August 31, 2026, at its Board of Directors meeting held on October 9, 2026.
- The per-share dividend for the fiscal year ending August 2026 will be revised to ¥18.50 from the most recent forecast (announced August 18, 2026) of ¥15.50. This includes an ordinary dividend of ¥7.50 and a special dividend of ¥11.00.
- Consequently, the projected annual dividend per share for the fiscal year ending August 2026 is ¥26.00.
- The total dividend amount is ¥245 million, sourced from retained earnings.
- The effective date for the dividend is scheduled for November 26, 2026, pending approval at the ordinary general meeting of shareholders to be held in November 2026.
🤖 AI Perspective
This announcement indicates that Watts Co., Ltd. has decided to increase its year-end dividend for the fiscal year ending August 2026. The implementation of a special dividend, exceeding the previous forecast, suggests that the company is considering its performance in its shareholder return policy. This dividend increase is expected to result in a higher annual dividend per share compared to prior estimates, which may be of interest to investors.
9972|アルテック
271.0
▼ -4.24%
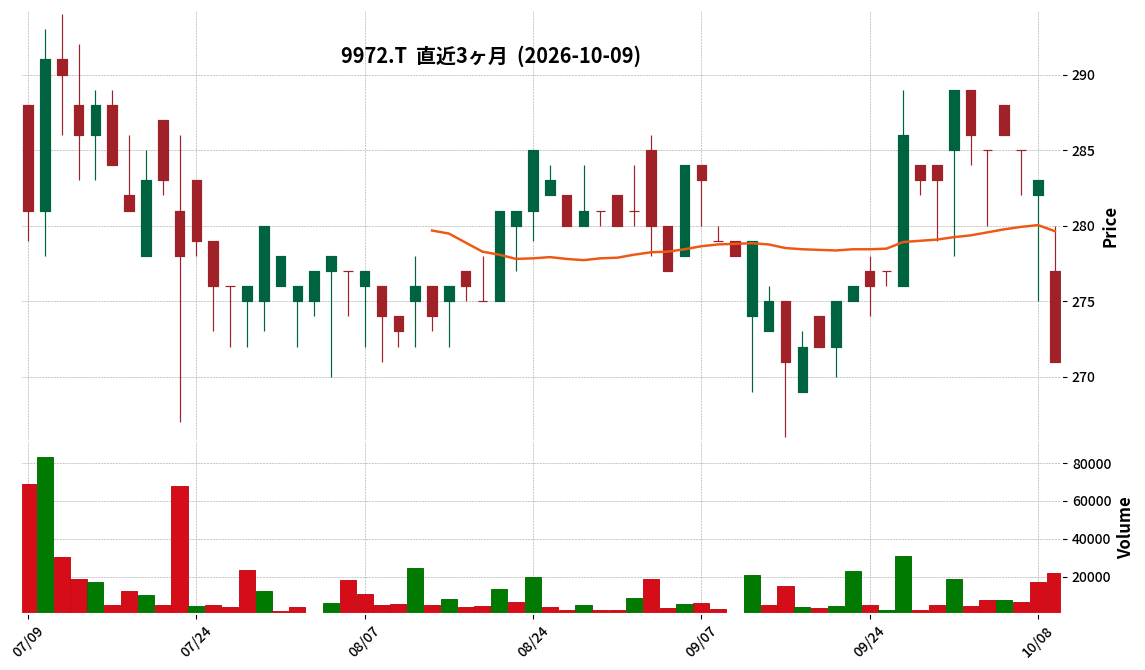
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Altech announced its consolidated financial results for the third quarter of the fiscal year ending November 2026.
- For the nine months ended August 31, 2026, net sales were ¥11,893 million, a decrease of 3.4% compared to the same period of the previous fiscal year.
- Operating income reached ¥586 million, a turnaround from an operating loss of ¥104 million in the prior year’s comparable period.
- Net income attributable to owners of parent increased by 243.1% year-on-year to ¥393 million.
- The Preform business reported an increase in sales and a segment profit of ¥512 million, while the Trading business experienced a decrease in both sales and profit, recording a segment profit of ¥195 million.
- The full-year consolidated forecast for “Net income attributable to owners of parent” and “Net income per share” for the fiscal year ending November 2026 has been revised to “undetermined” due to ongoing assessment of flood damage impact.
🤖 AI Perspective
Altech’s Q3 FY2026 results show a notable improvement in profitability, with operating and ordinary income turning positive despite a slight decline in overall sales. The turnaround and significant contribution from the Preform business segment appears to be a key driver for this profit recovery. Investors may want to monitor future disclosures regarding the impact of the recent heavy rain damage, as this has led to the withdrawal of the full-year net profit forecast.
Disclaimer: This article is for informational purposes only and does not constitute investment advice.
7463|アドヴァングループ
912.0
▼ -0.33%
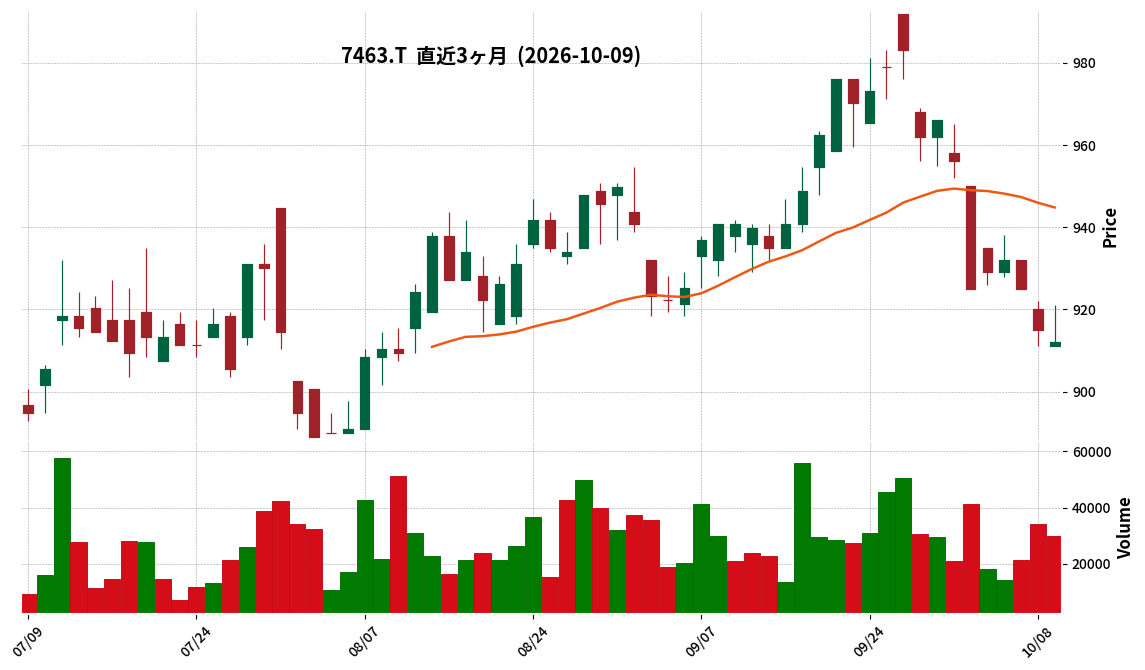
📎 Source:アドヴァングループ Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Advan Group announced its consolidated financial results for the second quarter (interim period) of the fiscal year ending March 2027.
- Consolidated net sales for the interim period reached ¥8,929 million (up 7.8% year-on-year), and operating profit increased by 81.4% to ¥1,946 million.
- Due to the recognition of a foreign exchange forward contract valuation loss of ¥2,470 million as non-operating expenses, ordinary profit decreased by 77.1% to ¥773 million, and net profit attributable to parent company shareholders declined by 55.6% to ¥893 million.
- Interim net profit per share was ¥26.60.
- The full-year consolidated earnings forecast for the fiscal year ending March 2027 remains unchanged: net sales of ¥18,500 million (up 8.6% year-on-year) and operating profit of ¥2,800 million (up 25.4% year-on-year). Ordinary profit and net profit attributable to parent company shareholders are not forecasted due to the difficulty in projecting foreign exchange gains/losses and foreign exchange forward contract valuation gains/losses.
🤖 AI Perspective
Advan Group’s interim results show robust growth in net sales and operating profit, which may suggest the effectiveness of their pricing adjustments, operational efficiencies, and inventory management. However, the significant decline in ordinary profit and net profit, primarily due to foreign exchange forward contract valuation losses, highlights the impact of currency fluctuations on their profitability. While the full-year operating profit forecast remains positive, the influence of foreign exchange factors on the overall profit structure is a point for investors to continue monitoring.
Disclaimer: This article is for informational purposes only and does not constitute investment advice.
3454|ファーストブラザーズ
1262.0
▼ -0.24%
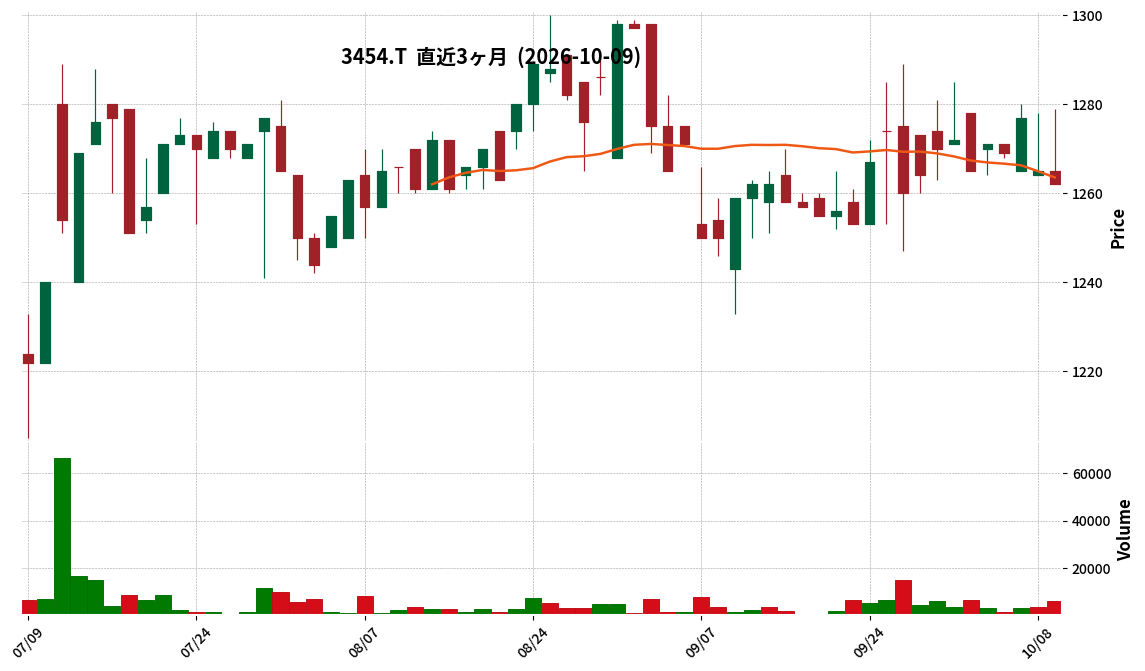
📎 Source:ファーストブラザーズ Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- First Brothers released its Q3 FY2026 financial results presentation on October 9, 2026.
- Consolidated performance showed gross profit of JPY 4,764 million (up 38.5% year-on-year), ordinary profit of JPY 2,308 million (up 86.3% YoY), and net income attributable to parent company shareholders of JPY 2,554 million (up 287.2% YoY).
- Gross profit for the Investment Banking business was JPY 4,470 million, Facility Management business was JPY 251 million (up 0.8% YoY), and Investment Management business was JPY 11 million (down 68.4% YoY).
- The company decided to acquire all shares of Sawara City Co., Ltd. as of September 30, 2026, with the transfer scheduled for October 30, 2026, making it a consolidated subsidiary.
- Discussions regarding the shareholder return policy and business direction, considering share price and cost of capital, are ongoing at the Board of Directors, with additional disclosure of the results planned for November 2026.
3907|シリコンスタジオ
1545.0
▼ -11.21%
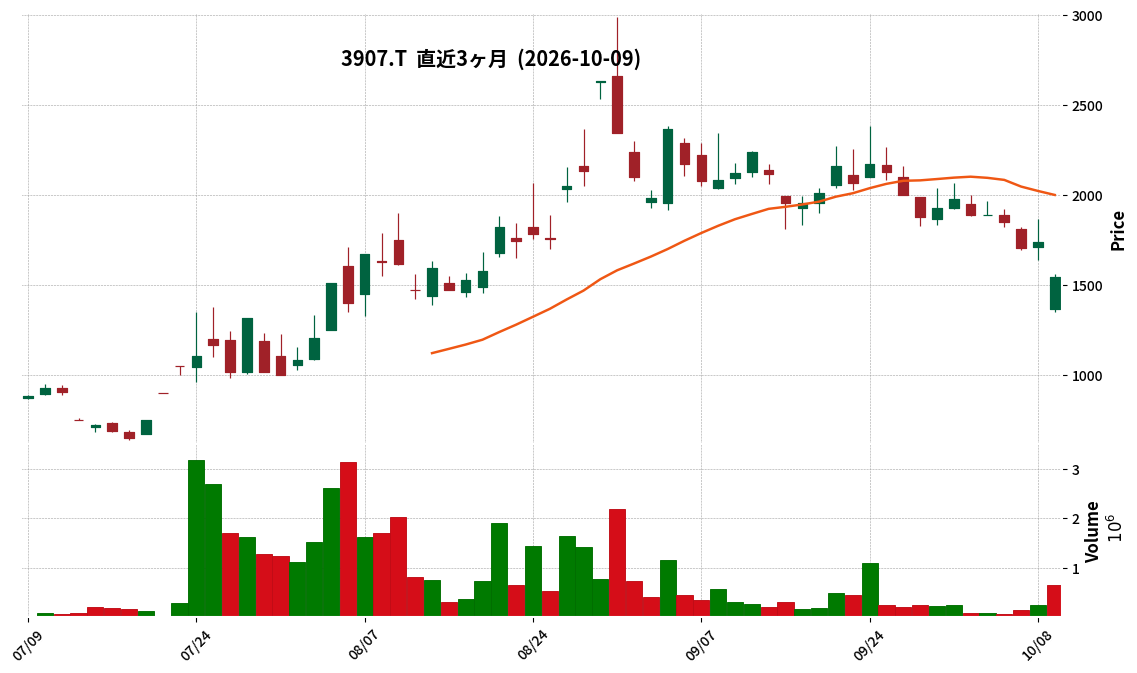
📎 Source:シリコンスタジオ Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Silicon Studio Co., Ltd. issued a correction on October 9, 2026, regarding a portion of its “Q3 FY2026 Earnings Supplementary Material” initially released on October 8, 2026.
- The corrections are located on lines 3 and 5 of page 7 of the supplementary material.
- The original statement on line 3, attributing the shortfall to “the loss of large-scale projects for industrial clients and differences in accounting periods,” was revised to include more specific reasons: “revenue reduction due to the completion of major large-scale commissioned development projects not being offset by other projects, as well as the postponement of revenue recognition for some projects and revenue reduction due to the termination of services by major conventional customers.”
- On line 5, the original statement of “booked a special loss of 39 thousand yen” was corrected to “booked a special loss of 39 million yen,” rectifying the amount.
- The company reported a net loss of ¥300 million for Q3 FY2026, which includes the special loss of ¥39 million.
🤖 AI Perspective
This correction provides a more detailed breakdown of the factors contributing to the Q3 financial performance falling short of initial plans. The clarification of specific reasons for revenue decline in the Development Promotion & Support business, alongside the accurate special loss amount, allows investors to assess the company’s situation with greater precision. The monetary correction highlights the criticality of accuracy in financial reporting.
💡 Start investing with IR insights


※ 本ページには広告が含まれます(PR)
Disclaimer: This article is for informational purposes only and does not constitute investment advice. All investment decisions are at your own risk.
コメント