📌 Today’s Highlights
Today we cover 43 IR announcements. Notable among them: JPX (8697), PLANT (7646), 北海電工 (1832). Use the table of contents below to navigate to each company.
- 8697|JPX
- 7646|PLANT
- 7921|TAKARA&CO
- 1832|北海電工
- 2212|山崎パン
- 3068|WDI
- 3697|SHIFT
- 3911|Aiming
- 4063|信越化
- 4479|G-マクアケ
- 4684|オービック
- 4733|OBC
- 4765|SBIGアセットM
- 4992|北興化
- 5344|MARUWA
- 5532|G-リアルゲイト
- 5609|日鋳造
- 6089|ウィルグループ
- 6337|テセック
- 7175|今村証券
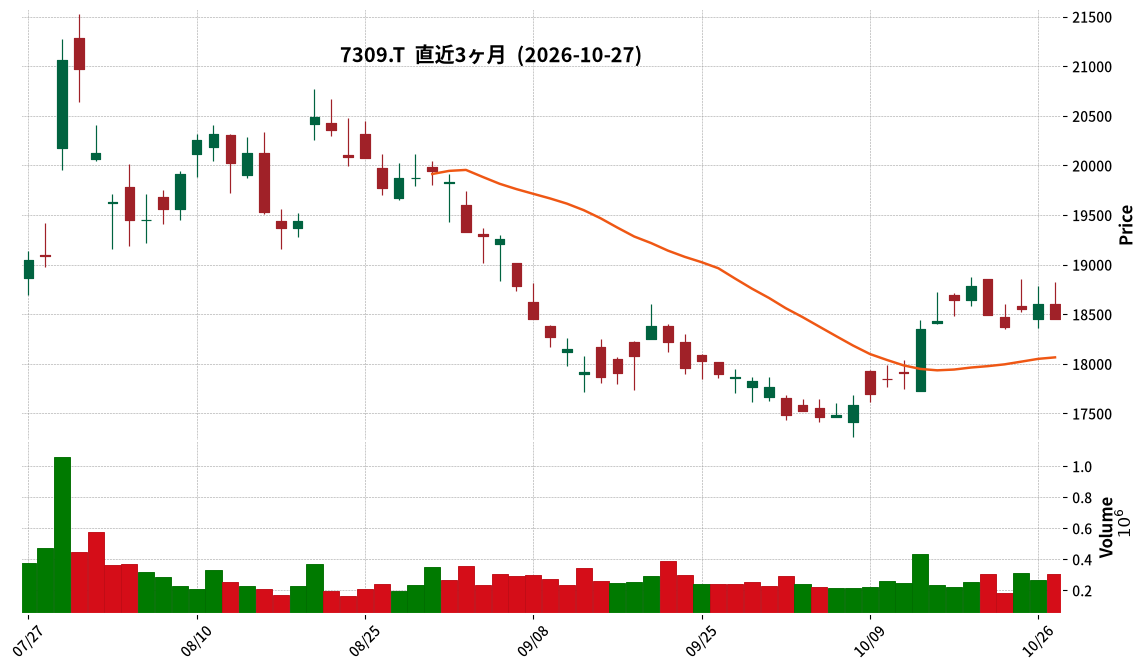
- 7309|シマノ
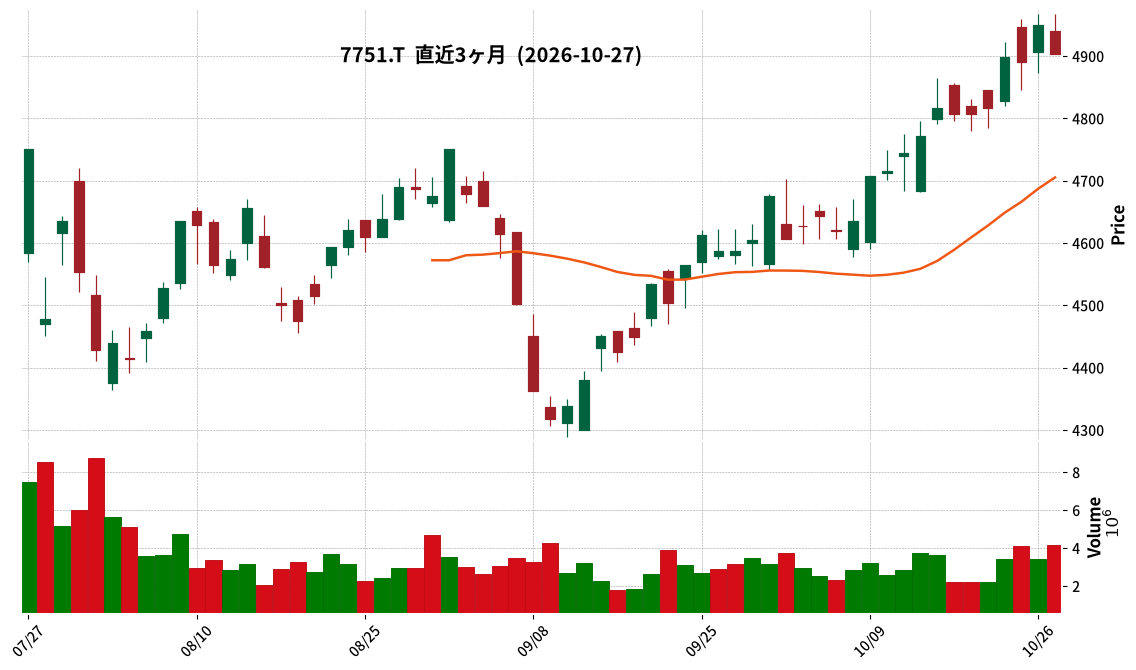
- 7751|キヤノン
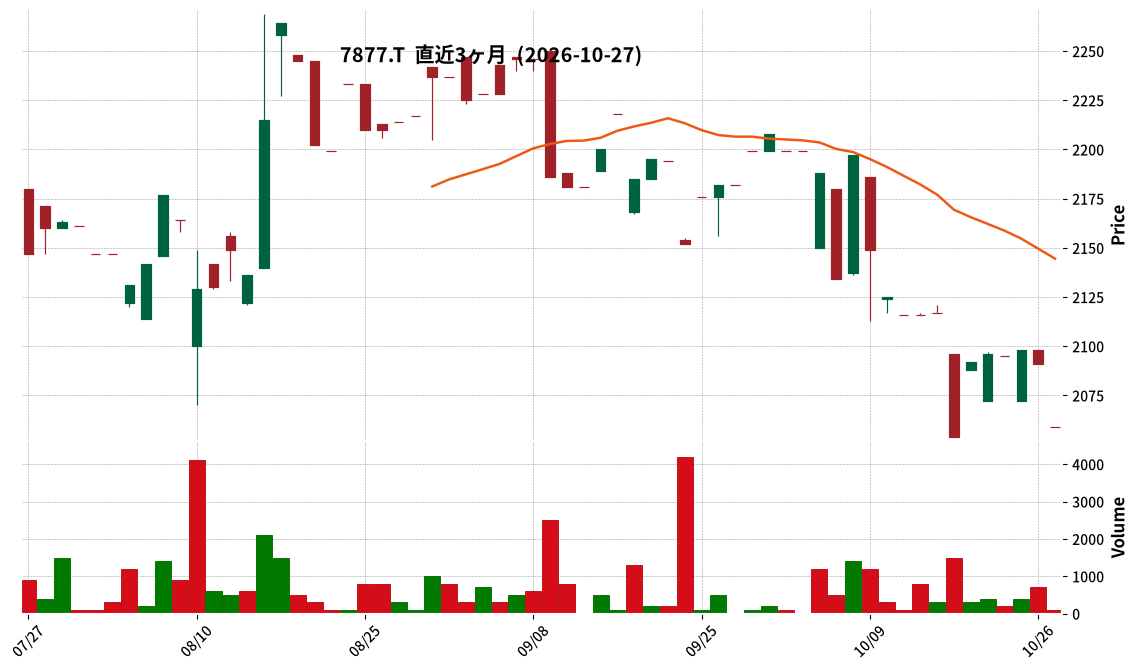
- 7877|永大化工
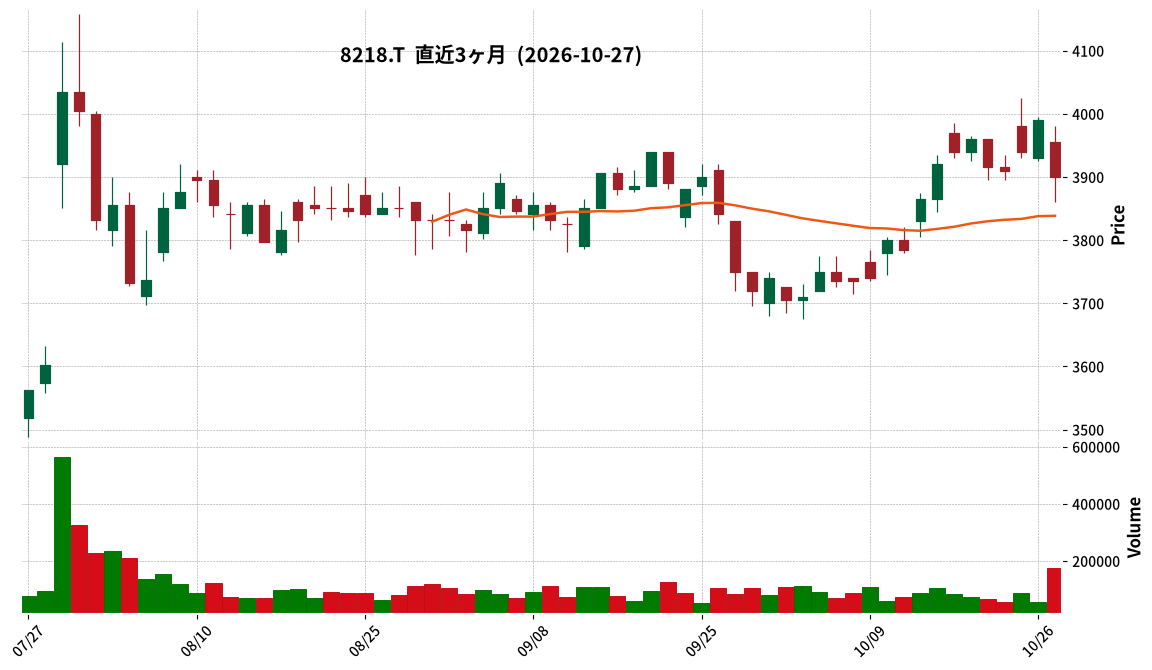
- 8218|コメリ
- 8892|エスコン
- 8975|R-いちごオフィス
- 9629|ピーシーエー
- 9782|ディーエムエス
- 7102|日車輌
- 9697|カプコン
- 2798|Y’s
- 3823|WHY HOW DO
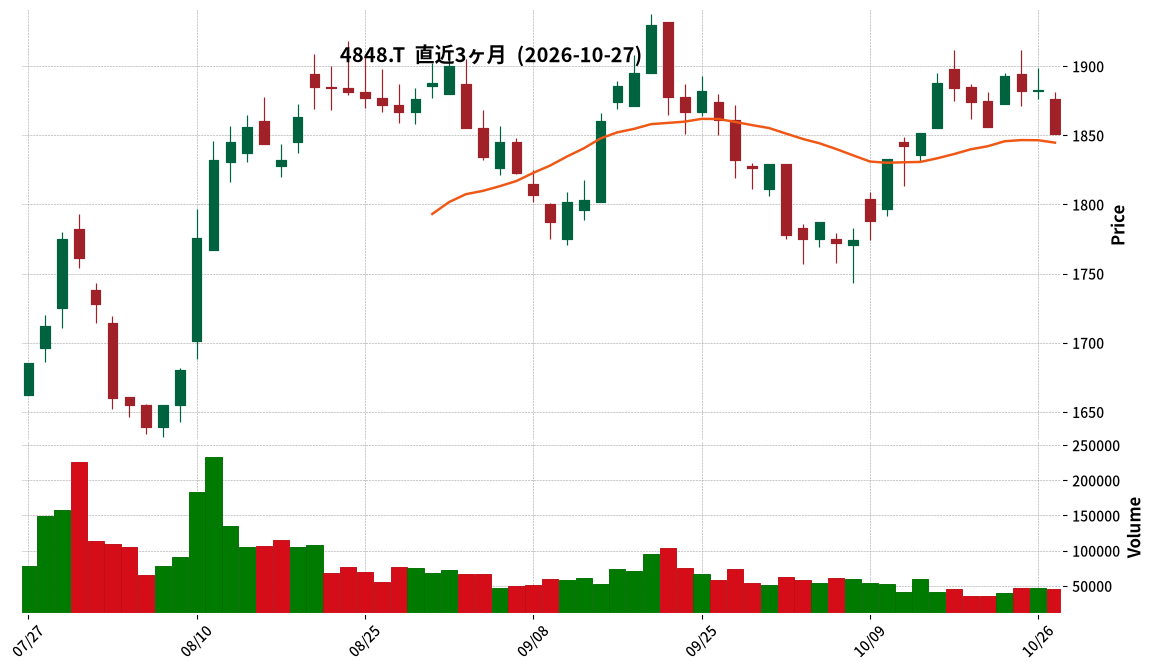
- 4848|フルキャストHD
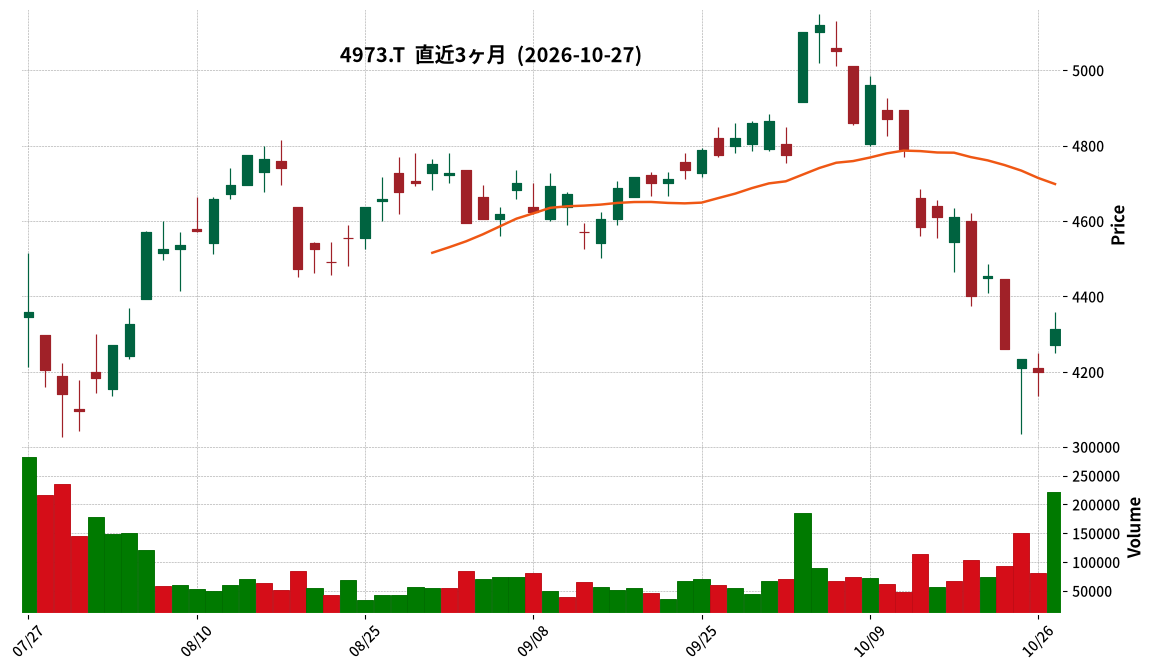
- 4973|高純度化
- 562A|P-寶結
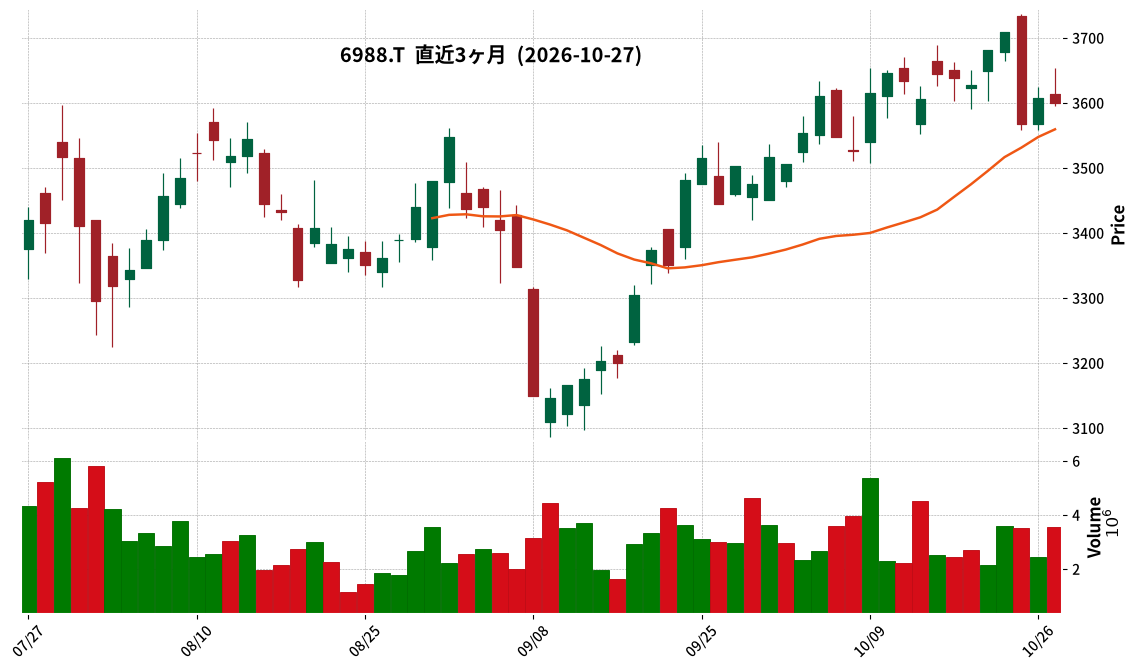
- 6988|日東電
- 7299|フジオーゼ
- 7434|オータケ
- 9213|セイファート
- 5279|日本興業
- 4519|中外薬
- 8098|稲畑産
- 2894|石井食
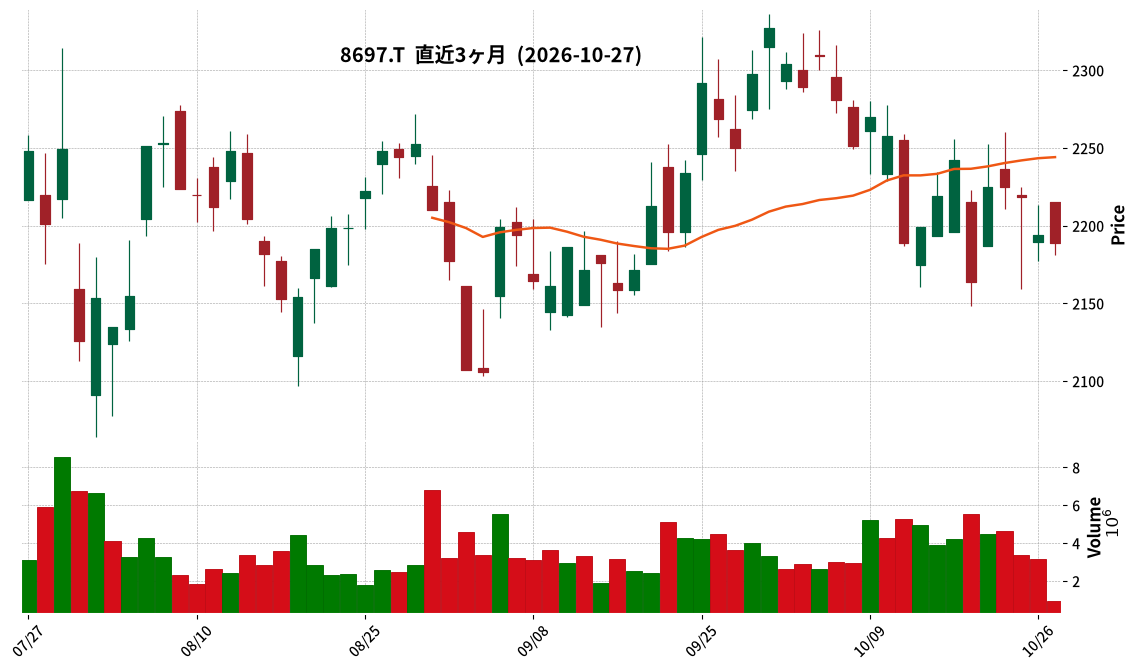
8697|JPX
2189.0
▼ -0.23%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- JPX (Japan Exchange Group, Inc.) announced its consolidated financial results for the second quarter (interim period) of the fiscal year ending March 2027.
- Operating revenue for the interim period was JPY 131,002 million, marking a 46.7% increase compared to the previous corresponding interim period.
- Operating profit reached JPY 84,668 million, a 65.1% increase year-on-year for the interim period.
- Profit attributable to owners of the parent was JPY 57,210 million, up by 65.6% from the prior interim period.
- Transaction-related revenue was JPY 53,870 million (+54.9% YoY), Clearing-related revenue was JPY 41,399 million (+79.5% YoY), and Listing-related revenue was JPY 9,198 million (+16.4% YoY).
- The consolidated full-year forecast for FY2027 remains unchanged, with operating revenue projected at JPY 252,500 million, operating profit at JPY 154,500 million, and profit attributable to owners of parent at JPY 105,000 million.
- An interim dividend of JPY 41.00 per share is planned (compared to JPY 25.00 in the previous corresponding period).
🤖 AI Perspective
JPX’s interim results for FY2027 show significant growth across key revenue segments, suggesting that increased market activity may have been a primary driver. The substantial increases in transaction-related and clearing-related revenues appear to be strong contributors to the overall performance. The unchanged full-year forecast indicates management’s view on continued positive momentum, and the proposed interim dividend increase could be seen as a positive signal for shareholder returns.
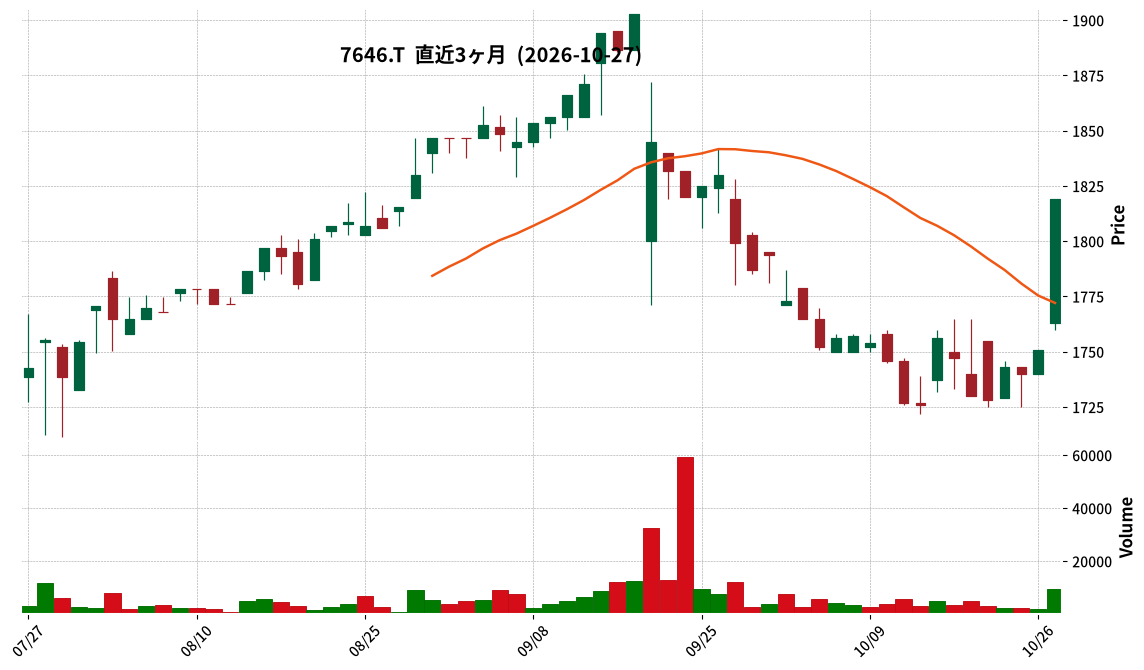
7646|PLANT
1819.0
▲ +3.88%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- For the fiscal year ended September 2026, sales were ¥96,018 million, representing a 1.8% decrease from the previous fiscal year.
- Operating profit was ¥1,668 million (down 16.9% YoY), and ordinary profit was ¥1,753 million (down 17.7% YoY).
- Net profit for the period was ¥1,298 million, a 3.5% decrease from the previous fiscal year.
- The annual dividend for the fiscal year ended September 2026 was ¥55.00 at year-end, totaling ¥95.00 (an increase of ¥20.00 from the previous year).
- For the fiscal year ending September 2027, the company forecasts sales of ¥97,312 million (up 1.3% YoY), operating profit of ¥1,900 million (up 13.9% YoY), and net profit of ¥1,365 million (up 5.1% YoY).
🤖 AI Perspective
PLANT reported a decrease in both revenue and profit for the fiscal year ended September 2026, but has issued an optimistic forecast for the fiscal year ending September 2027, projecting increases in both. This suggests a potential turnaround, and investors may focus on how the company’s initiatives under its medium-term management plan, such as “creating thriving stores” and “profit structure reform,” contribute to future performance. The increase in dividends could be interpreted as a positive sign regarding shareholder returns.
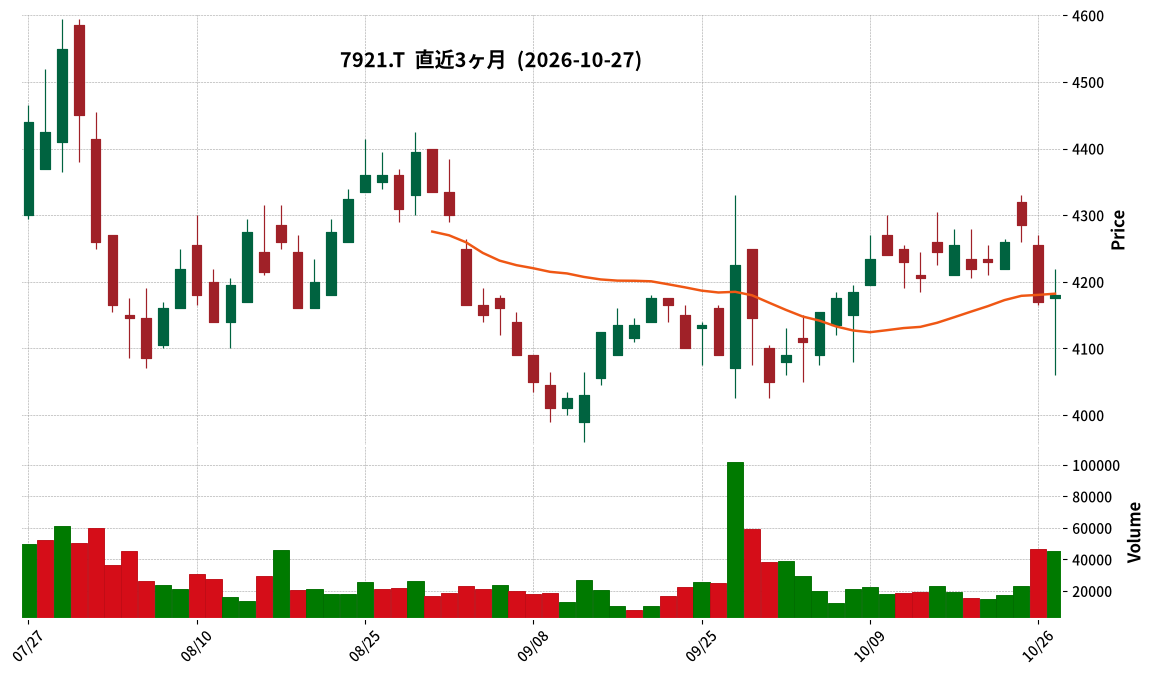
7921|TAKARA&CO
4180.0
▲ +0.24%
📎 Source:TAKARA&CO Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- TAKARA & COMPANY resolved to conduct a stock split at its Board of Directors meeting held on October 27, 2026.
- The stock split will be at a ratio of 3 shares for every 1 common share held by shareholders recorded in the final shareholder registry on November 30, 2026. The effective date is December 1, 2026.
- Post-split, the total number of outstanding shares will be 39,459,879, and the total number of authorized shares will be 111,000,000.
- Concurrently with the stock split, a portion of the Articles of Incorporation (total number of authorized shares) will be amended, effective December 1, 2026.
- Regarding the shareholder benefit program, there are no changes to the benefit content or conditions. Following the split, the investment amount required to hold 100 shares or more will be one-third of the current amount, representing a practical enhancement of the program. However, the application of the shareholder benefit program based on the post-split shareholding quantity (100 shares or more) will commence from the record date of November 30, 2027.
🤖 AI Perspective
This stock split aims to lower the investment unit price, potentially making the shares more accessible to a wider range of investors, which could enhance liquidity and expand the shareholder base. The practical enhancement of the shareholder benefit program might also attract new investors. Furthermore, the increase in authorized shares post-split could suggest the company’s intention to maintain flexibility for future capital raising or M&A strategies.
1832|北海電工
—
▲ +0.00%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Hokkaidenko announced its consolidated financial results for the second quarter (interim period) of the fiscal year ending March 2027.
- Net sales reached 34,910 million yen, an increase of 18.9% compared to the same period in the previous year.
- Operating profit was 2,055 million yen (up 77.8% YoY), ordinary profit was 2,164 million yen (up 76.5% YoY), and net income attributable to owners of the parent was 1,485 million yen (up 85.3% YoY).
- Order intake amounted to 47,372 million yen, marking an 11.8% increase year-on-year.
- The equity ratio improved to 75.4%, an increase of 8.5 percentage points from the end of the previous fiscal year.
- There are no revisions to the full-year consolidated earnings forecast or the dividend forecast (interim 10 yen, year-end 10 yen, total 20 yen).
🤖 AI Perspective
The significant growth in sales and various profit metrics for this interim period appears to be driven by increased demand in power-related and renewable energy projects. The solid order intake suggests a robust foundation for future business activities. Furthermore, the improvement in the equity ratio could indicate enhanced financial stability for the company.
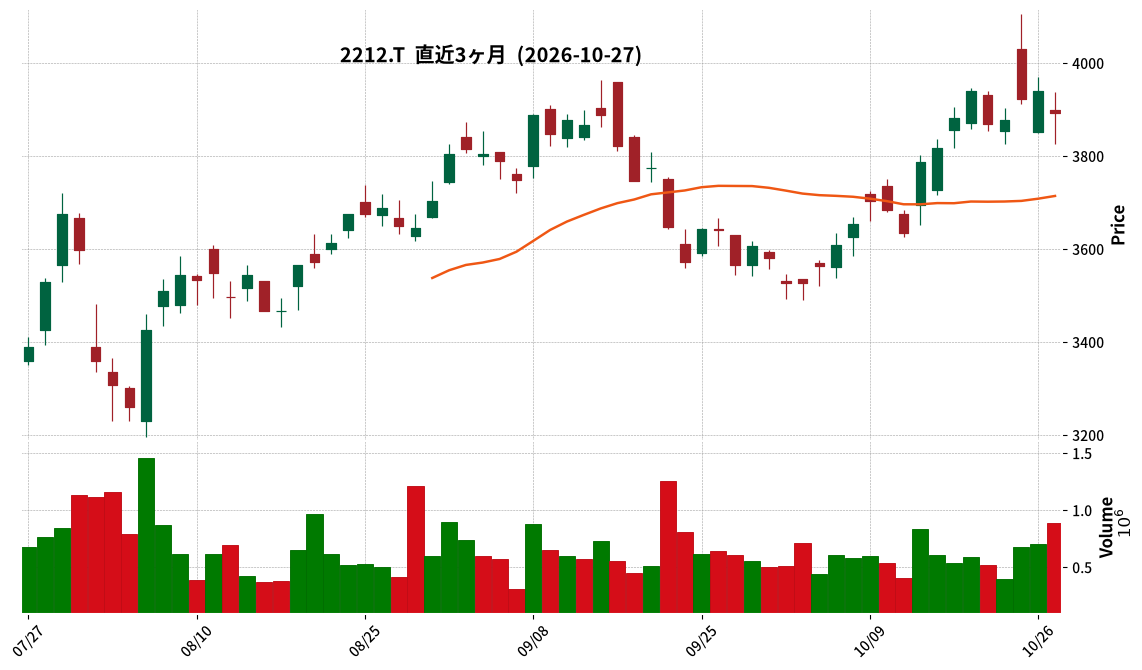
2212|山崎パン
3893.0
▼ -1.19%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Yamazaki Baking Co., Ltd. announced its consolidated financial results for the third quarter of the fiscal year ending December 2026 (January 1, 2026, to September 30, 2026).
- Consolidated cumulative results showed net sales of ¥1,011,499 million (up 4.5% year-on-year), operating profit of ¥47,218 million (up 5.6% year-on-year), ordinary profit of ¥49,888 million (up 7.7% year-on-year), and profit attributable to owners of parent of ¥31,872 million (up 7.2% year-on-year).
- Diluted earnings per share (EPS) for the quarter were ¥161.76.
- The consolidated financial position reported total assets of ¥924,671 million, net assets of ¥533,902 million, and an equity ratio of 52.0%.
- The full-year consolidated earnings forecast for the fiscal year ending December 2026 remains unchanged, projecting net sales of ¥1,338,000 million, operating profit of ¥64,000 million, ordinary profit of ¥67,000 million, and profit attributable to owners of parent of ¥42,500 million.
🤖 AI Perspective
Yamazaki Baking’s Q3 2026 results demonstrate solid growth across all key financial metrics, suggesting effective operational execution during the period. The company attributed this performance to quality improvements, price revisions, and improved results from consolidated subsidiaries, which could indicate a successful adaptation to market conditions. The reaffirmation of the full-year forecast implies that management expects the current positive trend to continue and align with their initial projections, which is worth monitoring for investors.
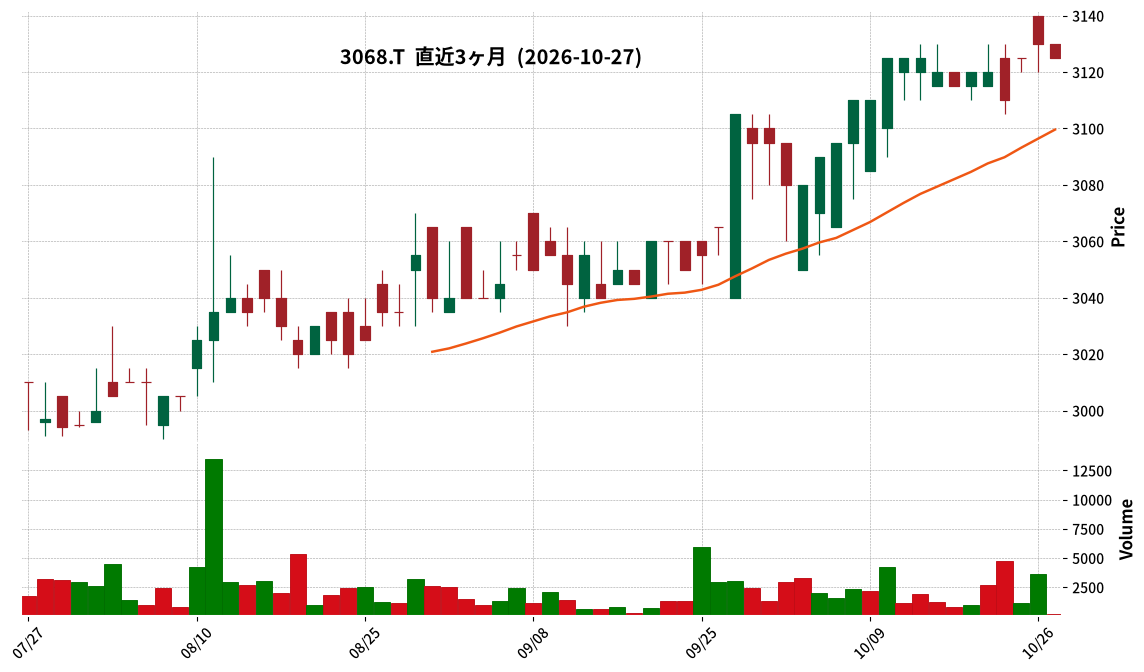
3068|WDI
3125.0
▼ -0.16%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- WDI Co., Ltd. announced that its consolidated subsidiary, WDI JAPAN Co., Ltd., will absorb its sub-subsidiary, WDI Dim Sum Japan Co., Ltd., through an absorption-type merger.
- The effective date of the merger is scheduled for January 1, 2027.
- WDI JAPAN will be the surviving company, and WDI Dim Sum Japan will be the absorbed company in this merger.
- The purpose of the merger is to consolidate management resources, optimize the management structure, and improve operational efficiency as part of a group reorganization following WDI Dim Sum Japan becoming a wholly-owned subsidiary of WDI JAPAN.
- WDI stated that the merger between its consolidated subsidiary and sub-subsidiary will have a minor impact on WDI’s consolidated financial results.
🤖 AI Perspective
This merger follows WDI Dim Sum Japan becoming a wholly-owned subsidiary of WDI JAPAN on October 1, 2026, suggesting a strategic move towards streamlining internal operations. The consolidation of the “Tim Ho Wan” dim sum specialty restaurant business under WDI JAPAN could lead to improved operational synergies and resource allocation for the WDI Group. Investors may wish to monitor how this internal restructuring potentially supports future growth strategies and brand development.
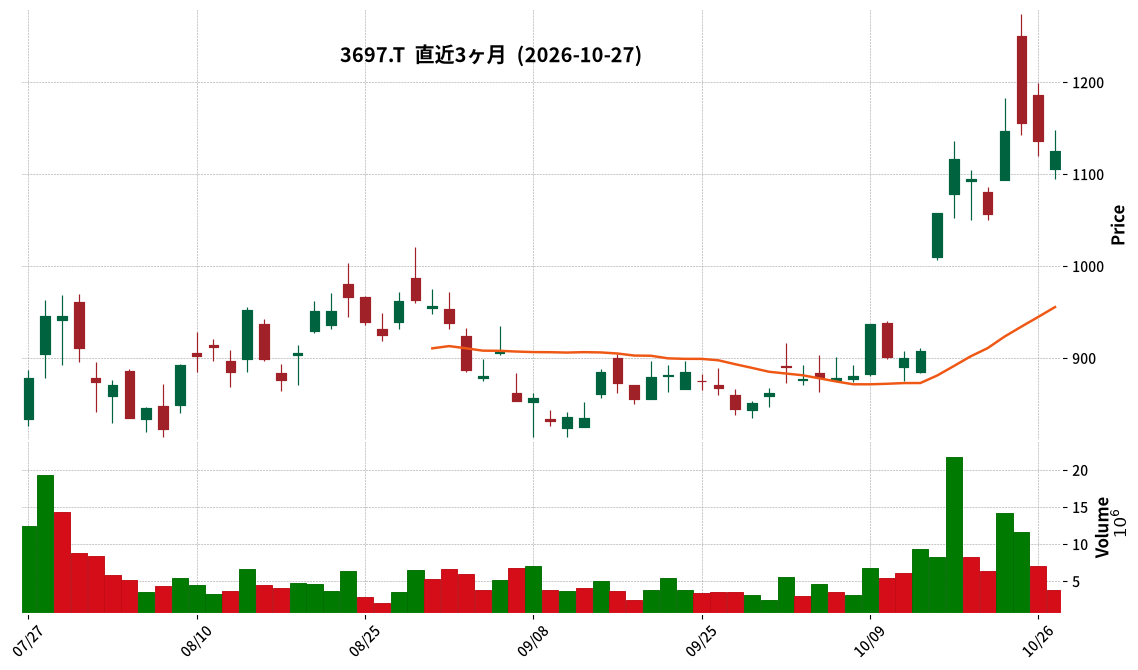
3697|SHIFT
1124.5
▼ -1.01%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- 株式会社SHIFT announced an internal group reorganization resolved at its Board of Directors meeting on October 27, 2026.
- SHIFT will acquire 100% of the shares of its consolidated subsidiary, SHIFT AXIS, from 株式会社SHIFT Growth Capital (SGC) through an absorption-type company split.
- SHIFT AXIS will then be absorbed and merged into 株式会社SHIFT without consideration, under a tax-qualified structure.
- The effective date for the company split is scheduled for March 31, 2027, and for the absorption-type merger, April 1, 2027.
- This reorganization is an intra-group transaction, and no shares, cash, or other consideration will be exchanged in either the company split or the merger.
- 株式会社SHIFT anticipates a minor impact on its business performance and financial condition as a result of this transaction.
🤖 AI Perspective
This organizational restructuring appears to be a strategic move by the SHIFT Group to accelerate business expansion and synergy creation within the insurance sector. By integrating AXIS’s specialized system development expertise for the insurance industry with SHIFT’s broader customer base and resources, the company aims to strengthen its business foundation in this domain. The establishment of an insurance consulting function within SHIFT could enhance cross-selling and proposal activities, potentially leading to increased customer value and overall group growth.
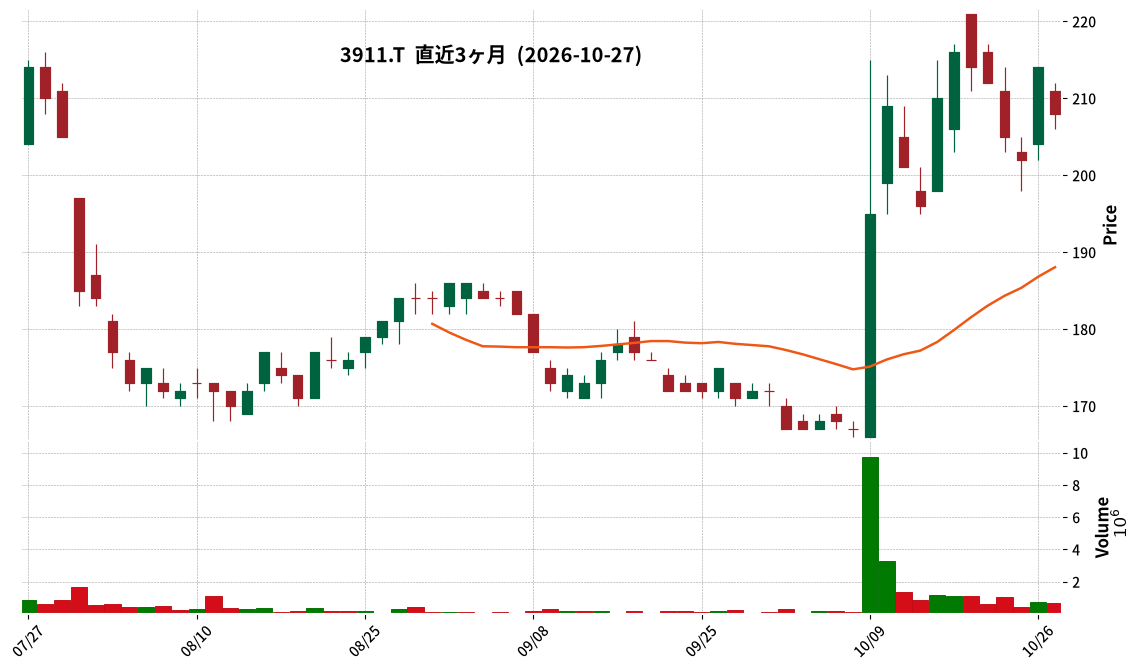
3911|Aiming
208.0
▼ -2.80%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Aiming reported consolidated net sales of ¥11,167 million for the third quarter of the fiscal year ending December 2026 (January 1, 2026 to September 30, 2026), representing an 11.6% decrease year-over-year.
- Operating income for the same period was ¥1,289 million (down 38.6% YoY), and ordinary income was ¥1,023 million (down 31.1% YoY).
- Net income attributable to owners of the parent reached ¥901 million, a decrease of 23.3% compared to the prior year’s third quarter.
- Total assets increased by ¥1,392 million from the end of the previous consolidated fiscal year to ¥10,598 million, primarily due to an increase of ¥1,370 million in accounts receivable and contract assets.
- The consolidated full-year forecast for FY2026 indicates net sales of ¥14,676 million (down 7.3% YoY), operating income of ¥1,419 million (down 31.7% YoY), and net income attributable to owners of the parent of ¥938 million (down 13.6% YoY), with a revision noted from the most recently published forecast.
🤖 AI Perspective
Aiming’s Q3 FY2026 results show a year-over-year decline in key profitability metrics, yet highlight the contribution of the newly launched collaborative title “Inazuma Eleven Cross” to revenue. The revision to the full-year earnings forecast suggests ongoing adjustments to business projections or market conditions that could be worth monitoring. The increase in total assets, particularly accounts receivable and contract assets, may warrant attention regarding future cash flow generation.
4063|信越化
5870.0
▲ +1.50%
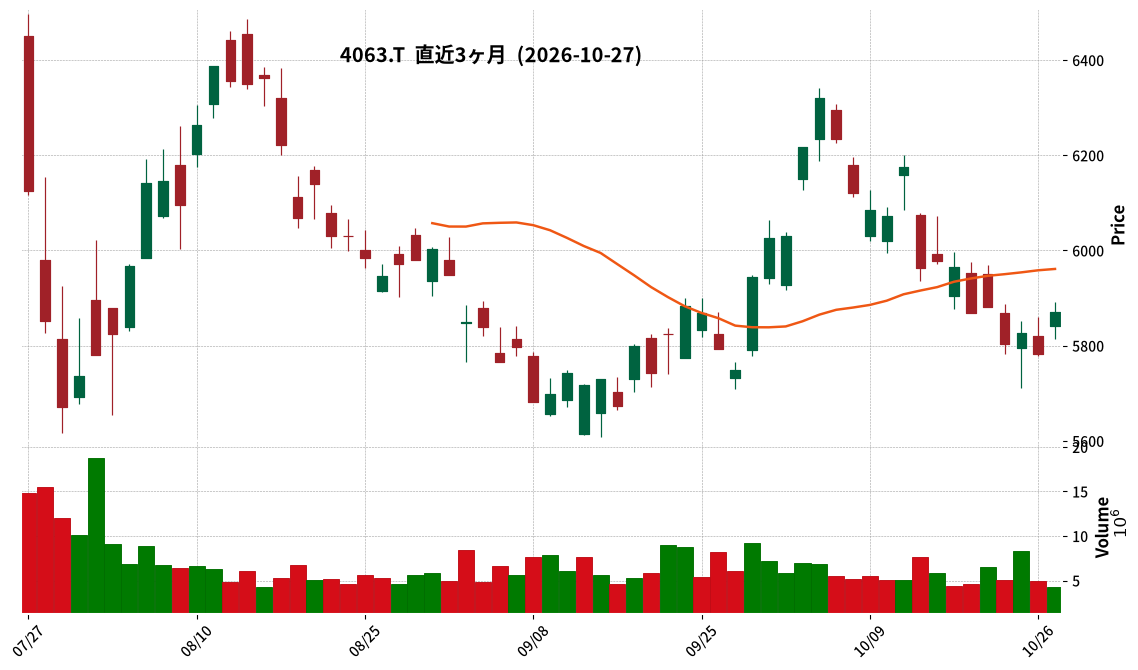
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Shin-Etsu Chemical Co., Ltd. announced its consolidated financial results for the second quarter (interim period: April 1, 2026 – September 30, 2026) of the fiscal year ending March 2027.
- For the interim period, consolidated net sales were ¥1,420,684 million (up 10.6% year-on-year), operating profit was ¥385,918 million (up 15.6%), ordinary profit was ¥415,108 million (up 13.0%), and net profit attributable to owners of the parent was ¥286,939 million (up 11.3%).
- Earnings per share (interim) were ¥155.71, an increase of 14.0% compared to the previous interim period.
- The interim dividend for the fiscal year ending March 2027 is ¥78.00 per share (including an ordinary dividend of ¥58.00 and a 100th anniversary commemorative dividend of ¥20.00), an increase from ¥53.00 in the prior year. The full-year dividend forecast, including the year-end dividend, remains unchanged at ¥136.00.
- The full-year consolidated earnings forecast remains unrevised from the most recently announced figures: Net sales of ¥2,700,000 million (up 4.9% year-on-year), operating profit of ¥700,000 million (up 10.2%), ordinary profit of ¥770,000 million (up 8.7%), and net profit attributable to owners of the parent of ¥525,000 million (up 10.7%).
🤖 AI Perspective
Shin-Etsu Chemical achieved double-digit growth in sales and all profit categories during the interim period of FY2027. The Electronic Materials segment showed significant strength, with a 16% increase in sales and a 28% increase in operating profit, which may suggest a positive impact from the expanding AI-related investments in the global economy. Furthermore, the increase in the interim dividend, including a 100th-anniversary commemorative dividend, could indicate a proactive stance on shareholder returns.
Disclaimer: This article is for informational purposes only and does not constitute investment advice.
4479|G-マクアケ
898.0
▼ -3.65%
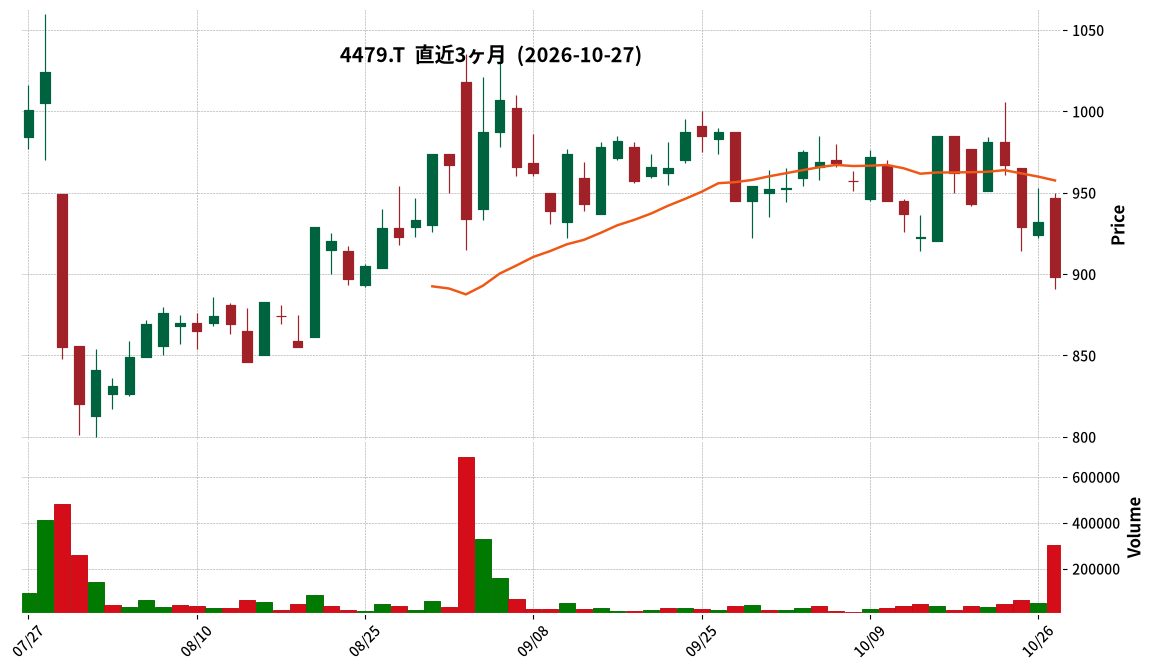
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Makuake, Inc. reported non-consolidated financial results for the fiscal year ended September 2026, with net sales of ¥5,944 million (up 29.9% year-on-year), operating profit of ¥881 million (up 97.2%), ordinary profit of ¥888 million (up 86.9%), and net profit of ¥798 million (up 96.1%).
- Basic earnings per share for FY2026 were ¥62.63, an increase from ¥31.95 in the previous fiscal year.
- The annual dividend for FY2026 was ¥14.00 per share, with no dividend paid in the previous fiscal year.
- For the fiscal year ending September 2027, the company forecasts net sales of ¥6,000 million to ¥7,000 million (up 0.9% to 17.7% year-on-year), operating profit of ¥800 million to ¥1,000 million (down 9.3% to up 13.4%), and net profit of ¥670 million to ¥840 million (down 16.1% to up 5.2%).
- As of the end of September 2026, total assets were ¥8,793 million, net assets were ¥6,219 million, and the equity ratio was 70.3%.
4684|オービック
5920.0
▼ -2.15%
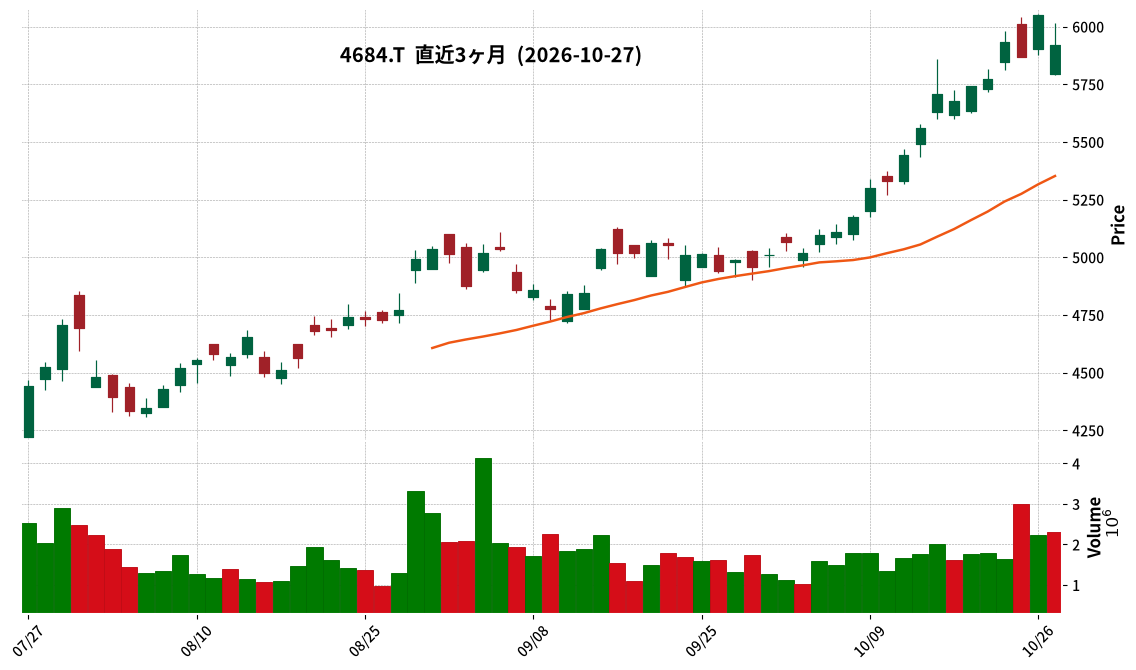
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- OBIC Co., Ltd. resolved to revise its full-year earnings forecast and year-end dividend forecast for the fiscal year ending March 2027 at its Board of Directors meeting held on October 27, 2026.
- For the fiscal year ending March 2027, net sales are revised upward from ¥148.7 billion to ¥151.2 billion, operating income from ¥98.0 billion to ¥100.5 billion, ordinary income from ¥114.5 billion to ¥120.0 billion, and net income attributable to owners of the parent from ¥82.0 billion to ¥85.0 billion.
- Earnings per share (EPS) is revised from ¥189.23 to ¥198.59.
- The year-end dividend forecast for the fiscal year ending March 2027 is revised from ¥47.00 per share to ¥53.00, an increase of ¥6.00, bringing the annual dividend forecast to ¥100.00 from ¥94.00.
- The reason for the upward revision of the earnings forecast is attributed to the progress of results in the second quarter, indicating that full-year net sales and all profit stages are expected to exceed the previously announced forecast.
🤖 AI Perspective
OBIC’s upward revision of its full-year earnings forecast could suggest that its business operations are progressing at a stronger pace than initially projected at the time of the announcement. The simultaneous increase across all profit stages—sales, operating income, ordinary income, and net income—may indicate an improvement in the company’s profitability. Furthermore, the decision to raise the year-end dividend forecast alongside the improved earnings outlook could be viewed as a commitment to stable shareholder returns, a factor often considered by investors.
4733|OBC
9386.0
▼ -0.35%
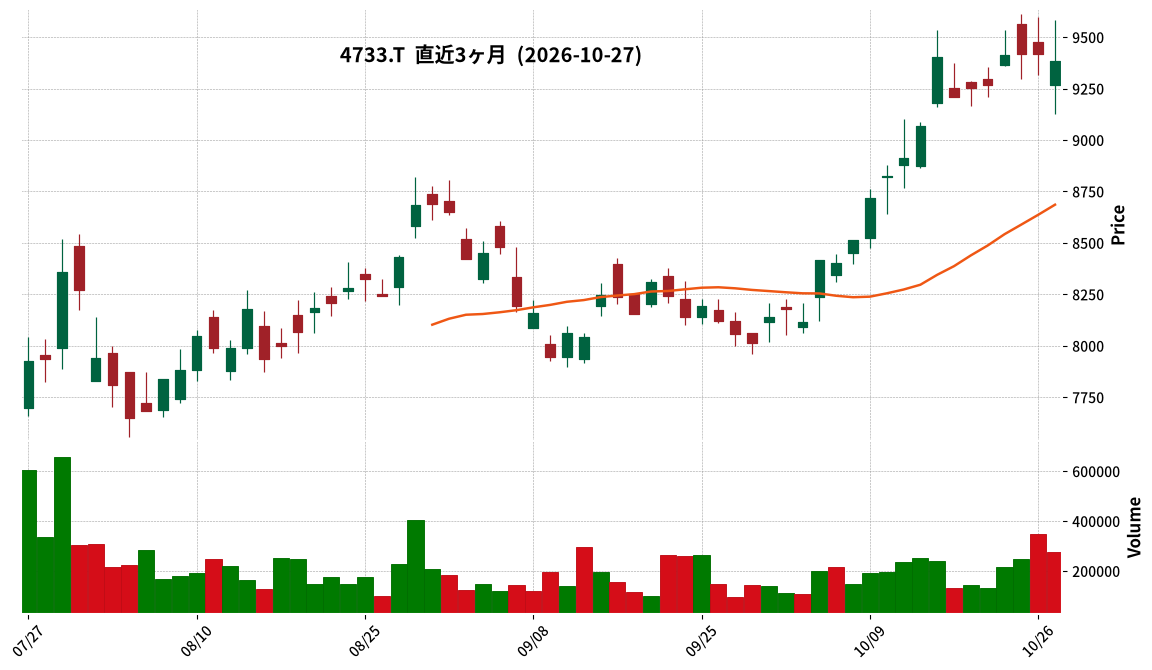
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- OBC Co., Ltd. announced its financial results for the second quarter (interim period) of the fiscal year ending March 2027.
- For the interim period, net sales were ¥28,666 million (up 15.0% year-on-year), operating profit was ¥13,598 million (up 21.8% year-on-year), ordinary profit was ¥14,809 million (up 24.0% year-on-year), and net income was ¥10,135 million (up 22.5% year-on-year).
- Interim net income per share was ¥134.82.
- The forecast for the annual dividend is ¥130.00, comprising an interim dividend of ¥65.00 and a year-end dividend of ¥65.00.
- The full-year earnings forecast has been revised, with projected net sales of ¥58,500 million (up 13.8% from the previous period), operating profit of ¥27,600 million (up 17.0%), ordinary profit of ¥29,800 million (up 18.2%), and net income of ¥20,400 million (up 12.5%).
🤖 AI Perspective
OBC’s Q2 FY2027 results show significant year-over-year increases in both sales and profits. The company attributes these gains primarily to increased cloud service revenue, a rise in demand for cloud migration from on-premise products, and successful new customer acquisition efforts, which suggests effective strategic execution. The upward revision of the full-year earnings forecast may further enhance investor confidence in the company’s future profitability.
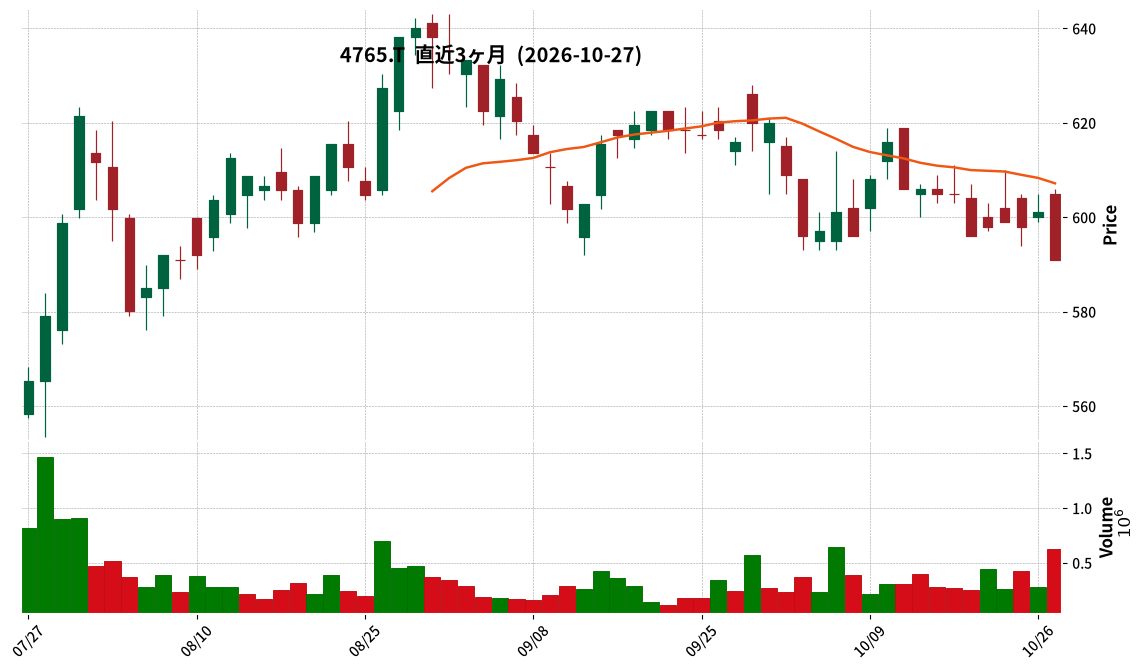
4765|SBIGアセットM
595.0
▼ -1.00%
📎 Source:SBIGアセットM Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- SBI Global Asset Management Co., Ltd. has decided to pay an interim dividend of 9 yen 50 sen per share, with the record date set for September 30, 2026.
- This amount matches the latest dividend forecast announced on July 27, 2026.
- The previous interim dividend (record date September 30, 2025) was 9 yen 00 sen per share, indicating an increase for the current interim dividend.
- The total dividend amount is expected to be 1,313 million yen, an increase compared to the previous period’s 925 million yen.
- The effective date for the dividend is scheduled for December 1, 2026.
- For the interim period of the fiscal year ending March 2027, the company reported 15 consecutive periods of increased sales, 17 consecutive periods of increased ordinary profit, and 17 consecutive periods of increased interim net profit attributable to parent company shareholders, setting new record highs for sales and all profit items.
- This marks the 8th consecutive interim dividend increase since the company began paying interim dividends in the fiscal year ending March 2019 (record date end of September 2018).
- The company has also maintained 17 consecutive annual dividend increases up to the fiscal year ended March 2026.
🤖 AI Perspective
SBI Global Asset Management’s decision to increase its interim dividend suggests a continued strong commitment to shareholder returns. The robust interim performance, particularly the record-high sales and all profit items, appears to underpin this dividend hike. The company’s track record of multiple consecutive dividend increases may indicate stable earnings power and a management philosophy focused on shareholder value.
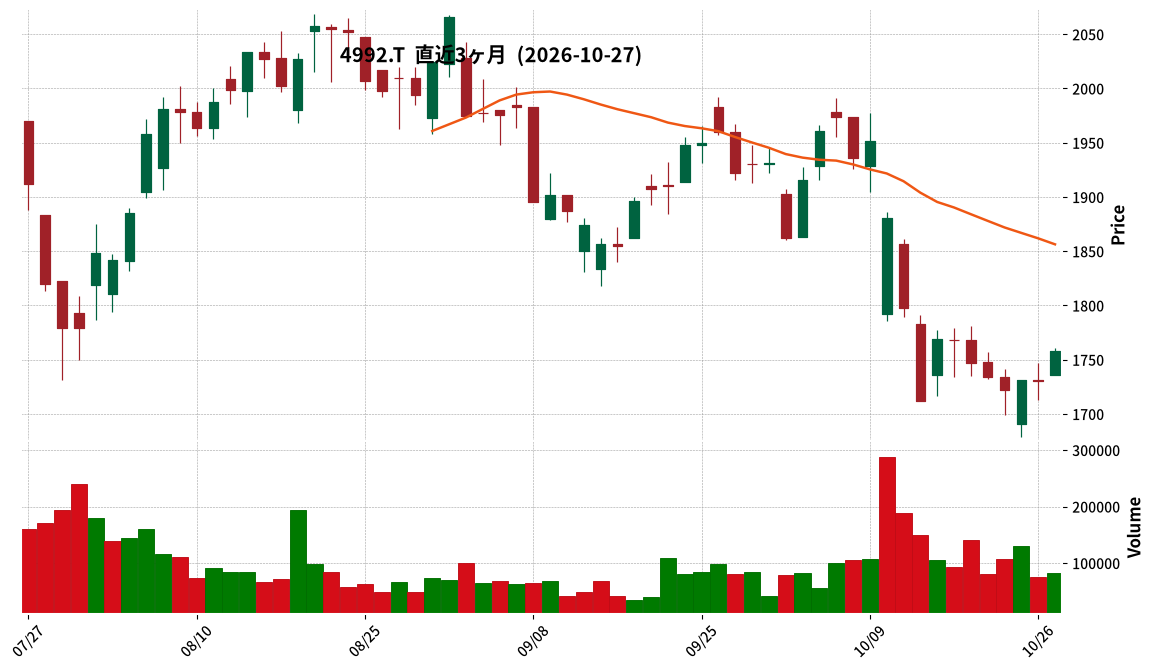
4992|北興化
1758.0
▲ +1.62%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Hokko Chemical Industry Co., Ltd. resolved to revise its dividend forecast for the fiscal year ending November 2026 on October 27, 2026.
- The year-end dividend forecast has been revised upwards by ¥10, from the previous forecast of ¥27 per share to ¥37 per share.
- Consequently, the annual dividend per share is now projected to be ¥64, an increase of ¥10 from the previous forecast of ¥54.
- The revision is attributed to a new long-term management plan (FY2027-2035) approved by the Board of Directors, which emphasizes improving capital efficiency and enhancing shareholder returns.
- Under the first three-year management plan (FY2027-2029) based on the long-term plan, the company targets a consolidated dividend payout ratio of 40% (excluding extraordinary gains/losses) for FY2029 and will continue its progressive dividend policy.
🤖 AI Perspective
This dividend increase can be viewed as a tangible outcome of the company’s newly articulated commitment to enhanced shareholder returns within its long-term management plan. The continuation of a progressive dividend policy and the setting of a payout ratio target may signal a strong dedication to shareholder value for the upcoming years. Investors might consider this move as an indication of potential for stable dividends and further increases in the future.
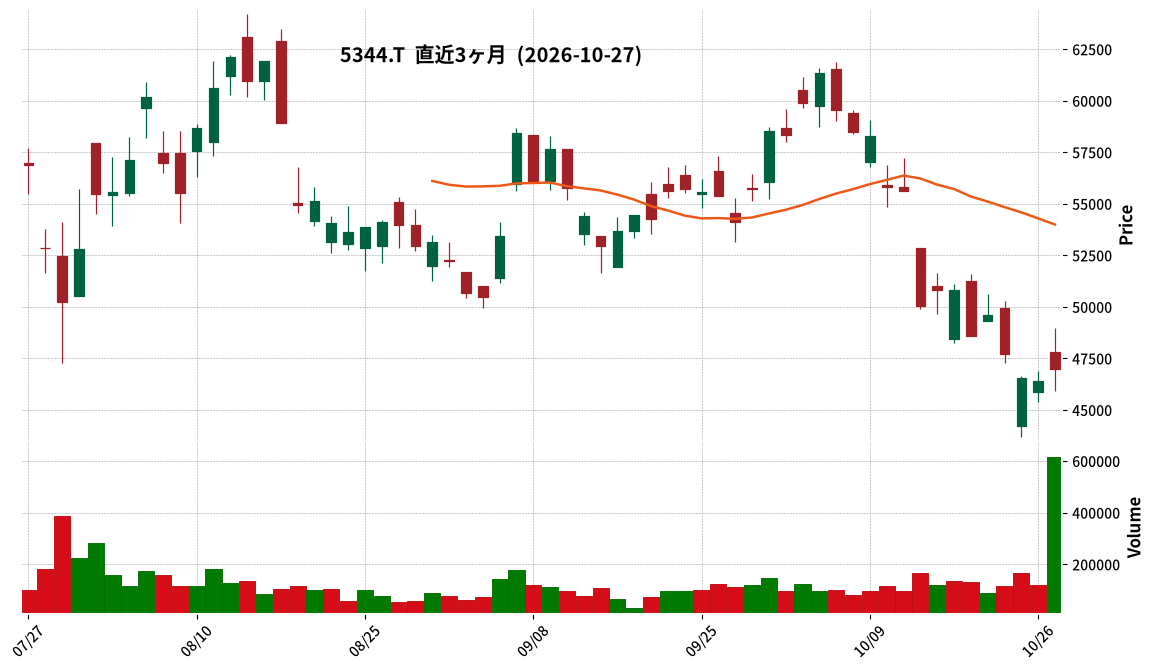
5344|MARUWA
47000.0
▲ +1.27%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- MARUWA has announced its consolidated financial results for the second quarter (interim period) of the fiscal year ending March 2027.
- For the interim period, net sales were ¥46,921 million (up 41.7% year-on-year), operating profit was ¥17,605 million (up 62.4%), ordinary profit was ¥17,640 million (up 58.6%), and profit attributable to owners of parent was ¥12,119 million (up 63.5%).
- Net sales and all profit metrics reached new record highs.
- The Ceramic Components business reported net sales of ¥41,879 million (up 44.7% year-on-year) and segment profit of ¥17,806 million (up 62.7%).
- The Lighting Equipment business reported net sales of ¥5,041 million (up 21.1% year-on-year) and segment profit of ¥890 million (up 26.7%).
- The consolidated full-year forecast for FY2027 has been revised upwards to net sales of ¥101,500 million, operating profit of ¥38,300 million, ordinary profit of ¥38,300 million, and profit attributable to owners of parent of ¥26,000 million.
- An interim dividend of ¥55 per share was announced.
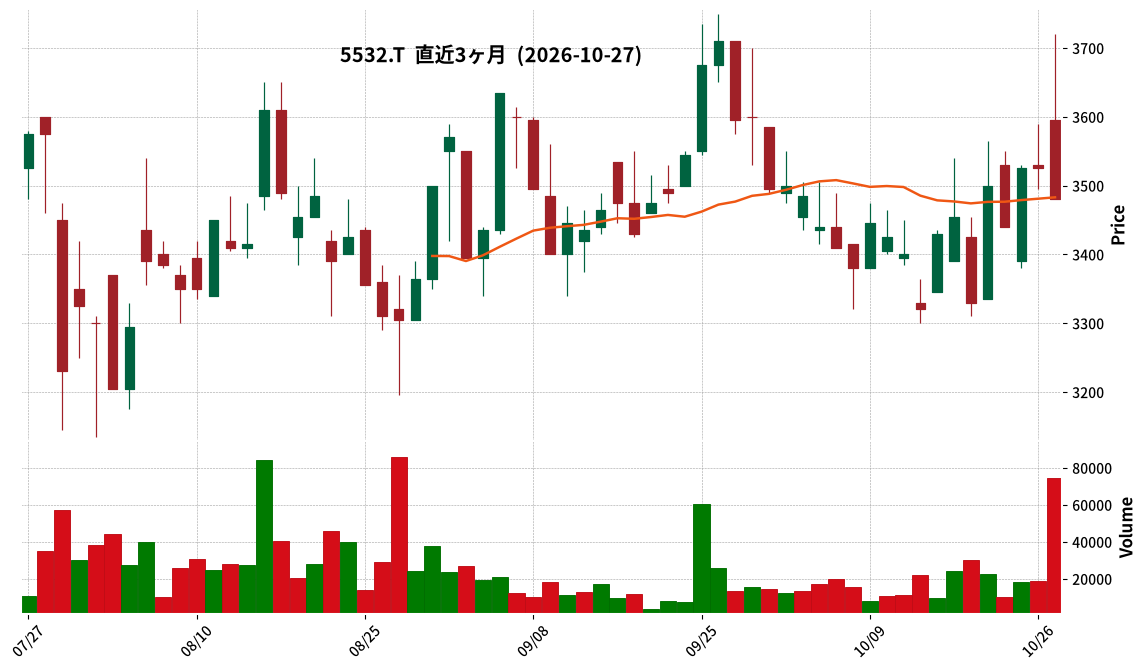
5532|G-リアルゲイト
3480.0
▼ -1.28%
📎 Source:G-リアルゲイト Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- G-REALGATE announced its non-consolidated financial results for the fiscal year ended September 2026 (October 1, 2025 – September 30, 2026).
- For the current fiscal year, net sales were ¥10,877 million (up 11.1% YoY), operating profit was ¥1,536 million (up 47.3% YoY), ordinary profit was ¥1,139 million (up 37.8% YoY), and net profit was ¥741 million (up 32.6% YoY).
- Earnings per share (EPS) were ¥123.46, and diluted EPS were ¥120.32.
- As of the end of September 2026, total assets were ¥29,462 million, net assets were ¥6,739 million, and the equity ratio was 22.4%.
- For the fiscal year ending September 2027, the company forecasts net sales of ¥13,500 million (up 24.1% YoY), operating profit of ¥2,160 million (up 40.6% YoY), and net profit of ¥1,000 million (up 34.9% YoY).
🤖 AI Perspective
G-REALGATE’s FY2026 September financial results highlight significant year-over-year growth in net sales and all profit categories, achieving record-high profits. The substantial 47.3% increase in operating profit could indicate enhanced operational efficiency and profitability. Furthermore, the company’s positive forecast for increased sales and profits in FY2027 suggests a confident outlook on continued business expansion, which may be worth monitoring for investors.
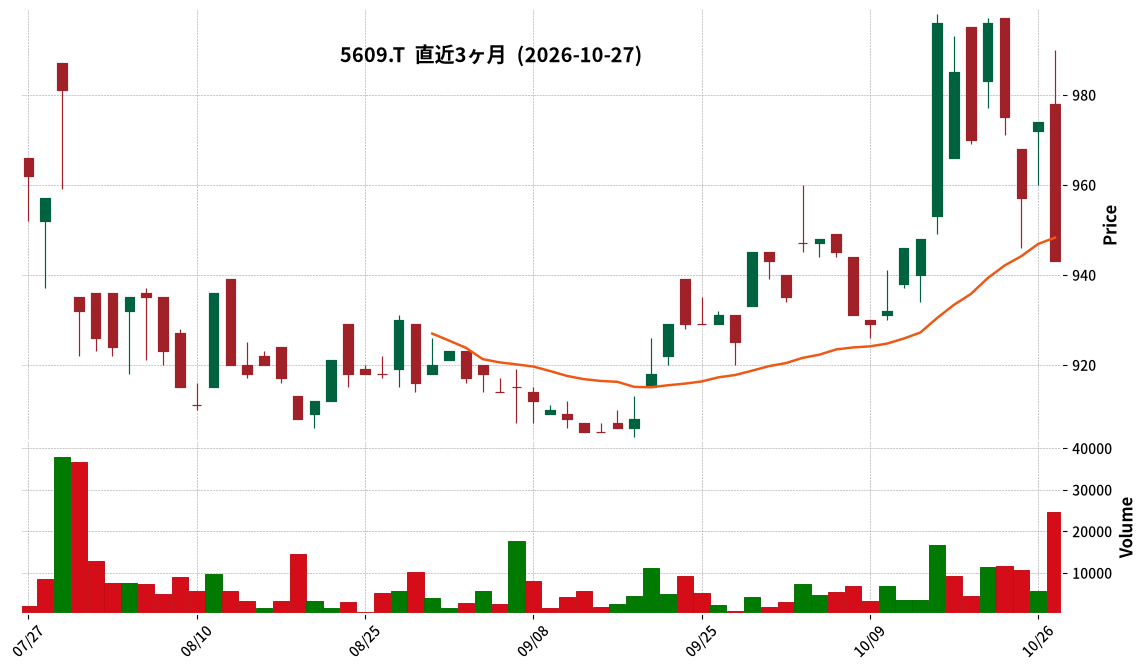
5609|日鋳造
943.0
▼ -3.18%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Nippon Chuzo announced its financial results for the second quarter (interim period) of the fiscal year ending March 2027.
- For the interim period, net sales were ¥6,527 million (up 8.8% year-on-year), operating profit was ¥584 million (up 665.6%), ordinary profit was ¥567 million (up 120.3%), and interim net profit was ¥354 million (up 59.3%).
- The company reported strong shipments of steel castings for semiconductor manufacturing equipment, driven by robust demand related to AI in its component materials business.
- A special loss of ¥34 million was recorded due to a warehouse fire that occurred in July.
- The full-year forecast for FY2027 (Net sales ¥14,500 million, Operating profit ¥780 million, Ordinary profit ¥730 million, Net profit ¥480 million) remains unchanged from the forecast announced on July 29, 2026.
🤖 AI Perspective
Nippon Chuzo’s interim results demonstrate significant growth across all key financial metrics, primarily driven by strong demand for steel castings linked to AI-related semiconductor manufacturing equipment. While the company recorded a special loss from a warehouse fire and experienced temporary delays in its engineering segment, the unchanged full-year forecast may suggest management’s confidence in mitigating these impacts. Investors might observe how the company manages these factors while continuing to capitalize on AI-driven demand.
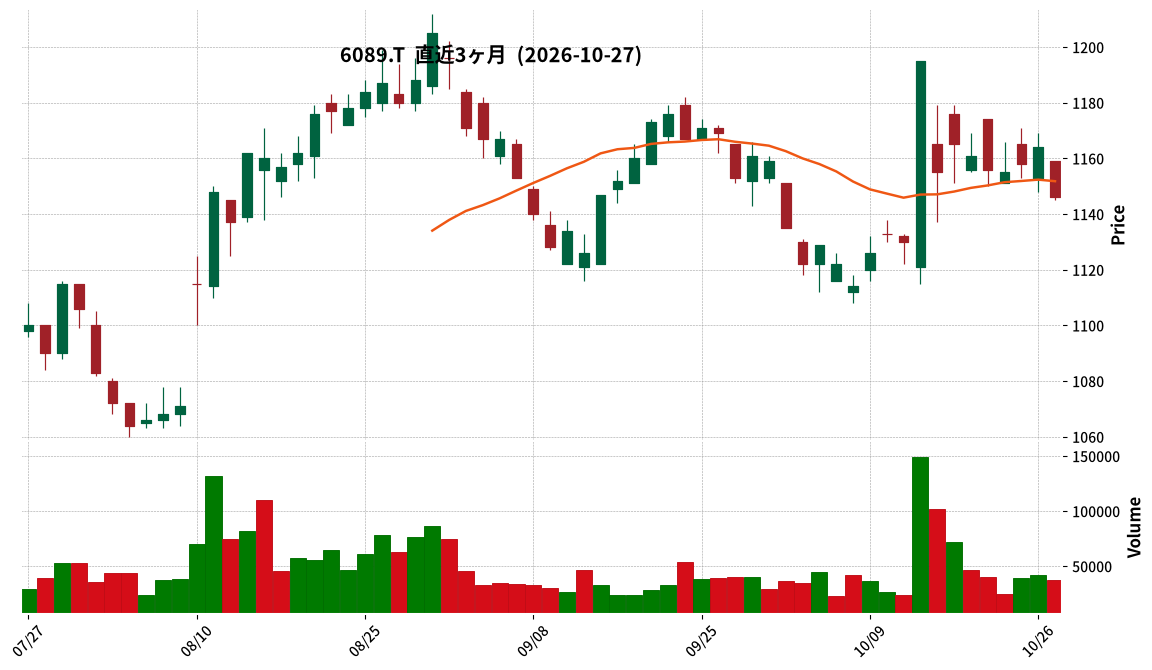
6089|ウィルグループ
1146.0
▼ -1.55%
📎 Source:ウィルグループ Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- WILL GROUP announced that its consolidated subsidiary, WILL OF WORK, will absorb WILL OF CONSTRUCTION, another consolidated subsidiary, with an effective date of April 1, 2027 (planned).
- Following the merger, WILL OF WORK, the surviving company, is scheduled to change its trade name to “WILL OF” on the same date.
- Ken Tanaka, currently President and Representative Director of WILL OF CONSTRUCTION, is planned to assume the role of President and Representative Director of WILL OF, succeeding Hideo Murakami.
- Another consolidated subsidiary, HR CAREER Co., Ltd., is scheduled to change its trade name to “WILL OF CAREER Co., Ltd.” on April 1, 2027.
- This internal group reorganization is expected to have a minor impact on the company’s consolidated financial performance.
🤖 AI Perspective
This internal reorganization aligns with the company’s mid-term management plan (WILL-being 2029), specifically targeting the expansion of “full-time and foreign HR business” within its domestic Working segment. The consolidation of operations may suggest an aim to enhance talent acquisition capabilities and operational efficiency amidst a competitive HR market. The unified branding through name changes could also indicate a strategic effort to improve brand recognition and service quality.
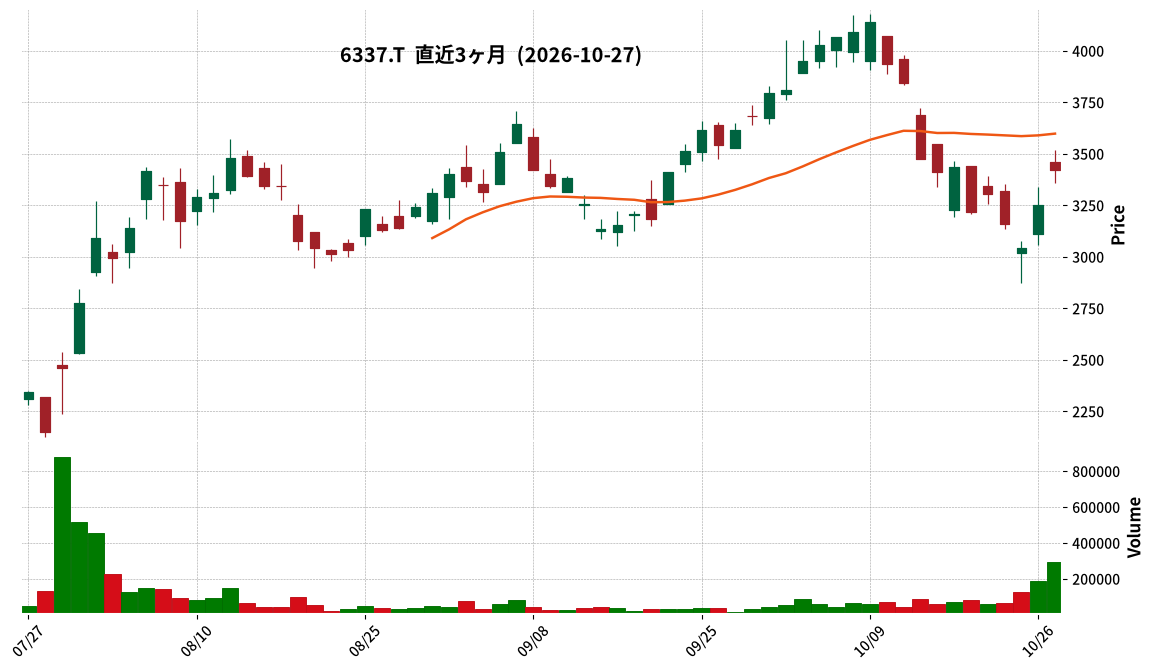
6337|テセック
3420.0
▲ +5.23%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- TESEC Corporation announced its consolidated financial results for the second quarter (interim) of the fiscal year ending March 2027.
- Net sales reached ¥3,803 million (up 44.5% year-on-year), operating profit was ¥741 million (up 286.6% year-on-year), ordinary profit was ¥861 million (up 183.1% year-on-year), and net income attributable to owners of parent was ¥663 million (up 209.2% year-on-year).
- By product category, sales for Handlers were ¥2,557 million (up 118.4% year-on-year), Testers were ¥565 million (down 44.5% year-on-year), and Parts, etc., were ¥681 million (up 54.4% year-on-year).
- The full-year consolidated earnings forecast for the fiscal year ending March 2027 remains unchanged from the most recently announced forecast: Net sales of ¥7,000 million (up 25.7% from previous fiscal year), operating profit of ¥1,100 million (up 265.4% from previous fiscal year), ordinary profit of ¥1,300 million (up 130.2% from previous fiscal year), and net income attributable to owners of parent of ¥1,040 million (up 124.6% from previous fiscal year).
- The annual dividend forecast is ¥100.00 per share (interim dividend of ¥50.00 and year-end dividend forecast of ¥50.00), with no changes from the most recently announced forecast.
🤖 AI Perspective
TESEC’s interim results for FY2027 show substantial year-on-year growth across all key financial metrics, with handler sales being a significant contributor to the revenue increase. The improvement in gross profit margin appears to have also played a role in the expanded profitability. The unchanged full-year outlook may suggest the company expects this positive momentum to continue into the second half of the fiscal year.
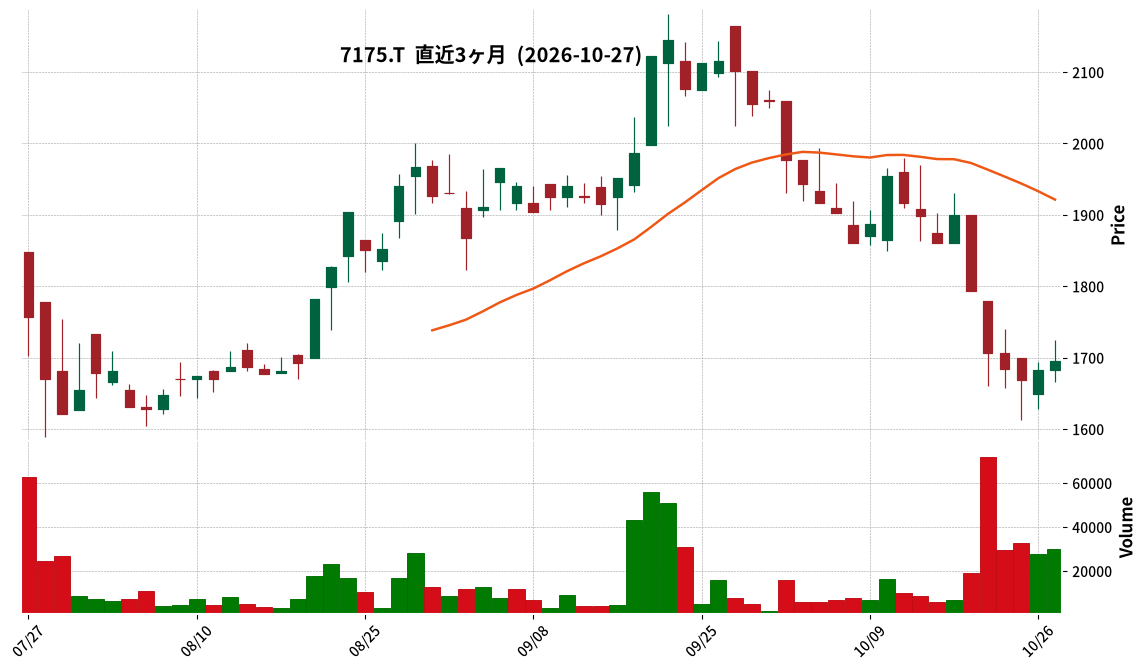
7175|今村証券
1695.0
▲ +0.77%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- For the second quarter of the fiscal year ending March 2027, operating revenue was ¥2,999 million, representing a 40.7% increase year-on-year.
- Net operating revenue reached ¥2,982 million, a 40.7% increase compared to the previous year’s interim period.
- Ordinary profit rose to ¥1,078 million, an increase of 108.4% from the prior year.
- Interim net profit amounted to ¥727 million, marking a 110.8% increase year-on-year.
- Earnings per share (interim net profit) were ¥142.25.
- The equity ratio at the end of the interim period was 52.6%, up from 49.6% in the previous fiscal year.
- An interim dividend of ¥37.00 per share was announced.
- The expense coverage ratio by beneficiary certificates was 34.8% (30.4% in the previous year), and assets under custody amounted to ¥489.2 billion (¥386.4 billion at the end of the previous year).
🤖 AI Perspective
Imamura Securities’ Q2 FY2027 results show significant year-on-year increases across key profit metrics, which may suggest a favorable market environment coupled with effective business strategies. The growth in assets under custody and the rising expense coverage ratio from beneficiary certificates could indicate progress in establishing a more stable revenue base less reliant on market fluctuations. The increase in the interim dividend payment also reflects the company’s commitment to shareholder returns.
7309|シマノ
18450.0
▼ -0.83%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Shimano announced its Q3 FY2026 consolidated financial results for the period from January 1, 2026, to September 30, 2026.
- Consolidated net sales reached ¥375,248 million, a 6.9% increase year-on-year.
- Operating income was ¥44,532 million (+21.8% YoY), and ordinary income was ¥51,864 million (+71.5% YoY).
- Net income attributable to owners of the parent significantly increased by 148.5% year-on-year to ¥40,022 million.
- The full-year consolidated earnings forecast has been revised, projecting net sales of ¥495,500 million (+6.3% YoY), operating income of ¥54,300 million (+5.1% YoY), ordinary income of ¥62,300 million (+32.5% YoY), and net income attributable to owners of the parent of ¥47,000 million (+38.3% YoY).
- The Bicycle Components segment reported net sales of ¥278,361 million (+4.6% YoY) and operating income of ¥33,440 million (+10.9% YoY).
- The Fishing Tackle segment reported net sales of ¥96,572 million (+14.4% YoY) and operating income of ¥11,079 million (+72.9% YoY).
🤖 AI Perspective
Shimano’s Q3 FY2026 results show a robust increase across all key financial metrics, with a particularly strong rise in net income attributable to owners of the parent. This significant profit growth appears to be primarily driven by a notable increase in ordinary income, which includes foreign exchange valuation gains. The upward revision of the full-year earnings forecast is attributed to anticipated demand increases stemming from progress in market inventory adjustments in regions such as Europe and China, alongside favorable foreign exchange impacts, predominantly from Asian currency depreciation.
7751|キヤノン
4904.0
▼ -0.91%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Canon Inc. announced its consolidated financial results (U.S. GAAP) for the third quarter of the fiscal year ending December 2026 (January 1, 2026, to September 30, 2026) on October 27, 2026.
- Consolidated net sales for the third quarter of FY2026 amounted to ¥3,433,357 million, representing a 4.0% increase compared to the same period in the previous year.
- Operating profit grew by 8.4% year-on-year to ¥327,684 million, and net income attributable to Canon Inc. shareholders increased by 12.2% year-on-year to ¥246,409 million.
- Basic earnings per share attributable to Canon Inc. shareholders were ¥287.24, up 19.2% from ¥240.99 in the prior year’s period.
- The consolidated full-year forecast for FY2026 has been revised, projecting net sales of ¥4,766,000 million (a 3.1% increase from the previous year) and net income attributable to Canon Inc. shareholders of ¥333,000 million (a 0.3% increase from the previous year).
🤖 AI Perspective
Canon’s third-quarter results demonstrate consistent growth in key revenue and profit metrics, suggesting robust business performance. The upward revision of the full-year forecast may indicate confidence in continued positive momentum from current business operations and potential contributions from strategic investments. Investors might closely monitor factors such as the company’s equity ratio and the performance of individual business segments to assess the sustainability of this growth.
Disclaimer: This article is for informational purposes only and does not constitute investment advice.
7877|永大化工
2059.0
▼ -1.53%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Eidaikako Co., Ltd. has issued a correction to its “Consolidated Financial Results for the First Quarter of the Fiscal Year Ending March 31, 2027 (Japanese GAAP)” initially announced on August 7, 2026.
- The reason for the correction is a re-evaluation of the accounting treatment for a new transaction involving subcontracting a portion of the manufacturing process for air conditioning copper pipes within the industrial materials segment, which commenced in the first quarter. It was determined that recognizing the consideration for processing services as net sales under a consignment sales transaction is appropriate.
- This correction revises the presentation of net sales, cost of sales, and related assets, but it has no impact on profit.
- The corrected consolidated financial results for the first quarter of FY2027 show net sales of 2,518 million yen (up 8.3% year-on-year), operating income of 131 million yen (down 9.0%), ordinary income of 141 million yen (up 18.0%), and net income attributable to owners of parent of 102 million yen (up 40.9%).
- Due to numerous revisions, the full corrected financial statement is attached, with changes highlighted by underlines.
🤖 AI Perspective
This correction primarily concerns the reclassification of revenue and cost of sales for a specific transaction, with the key takeaway for investors being that there is no impact on the company’s reported profit. While the revenue figures have been restated, the underlying profitability remains unchanged, which may offer some reassurance. Investors may wish to review the detailed corrected figures to understand the full scope of the accounting treatment change and its implications for sales and cost structures.
8218|コメリ
3900.0
▼ -2.26%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Komeri Co., Ltd. announced its consolidated financial results for the second quarter (interim period) of the fiscal year ending March 2027.
- For the interim period, consolidated operating revenue was ¥208,803 million (up 3.8% year-on-year), operating income was ¥17,301 million (up 12.6%), ordinary income was ¥17,279 million (up 10.7%), and profit attributable to owners of parent was ¥11,310 million (up 9.2%).
- Interim net income per share was ¥241.68.
- The dividend forecast for the fiscal year ending March 2027 remains unchanged from the most recently announced forecast, with an expected year-end dividend of ¥29.00 (total annual dividend of ¥58.00).
- The full-year consolidated earnings forecast for FY2027 is operating revenue of ¥400,800 million (up 4.0% year-on-year), operating income of ¥24,000 million (up 4.1%), ordinary income of ¥23,900 million (up 2.2%), and profit attributable to owners of parent of ¥15,000 million (up 2.4%). This forecast remains unchanged from the most recently announced forecast.
- The company noted a change in accounting policies due to revisions of accounting standards during the interim period.
- It was mentioned that special losses were recorded due to damage to buildings and merchandise caused by the “Reiwa 8 Kumamoto Earthquake” on July 28, 2026.
- During the interim period, 5 new stores were opened and 5 stores were closed.
🤖 AI Perspective
Komeri’s Q2 FY2027 results indicate solid performance, with increased revenue and profits compared to the prior year. The double-digit growth in all profit categories suggests improved operational efficiency. The unchanged full-year earnings forecast may indicate management’s confidence in achieving its financial targets, which could be a point of interest for investors.
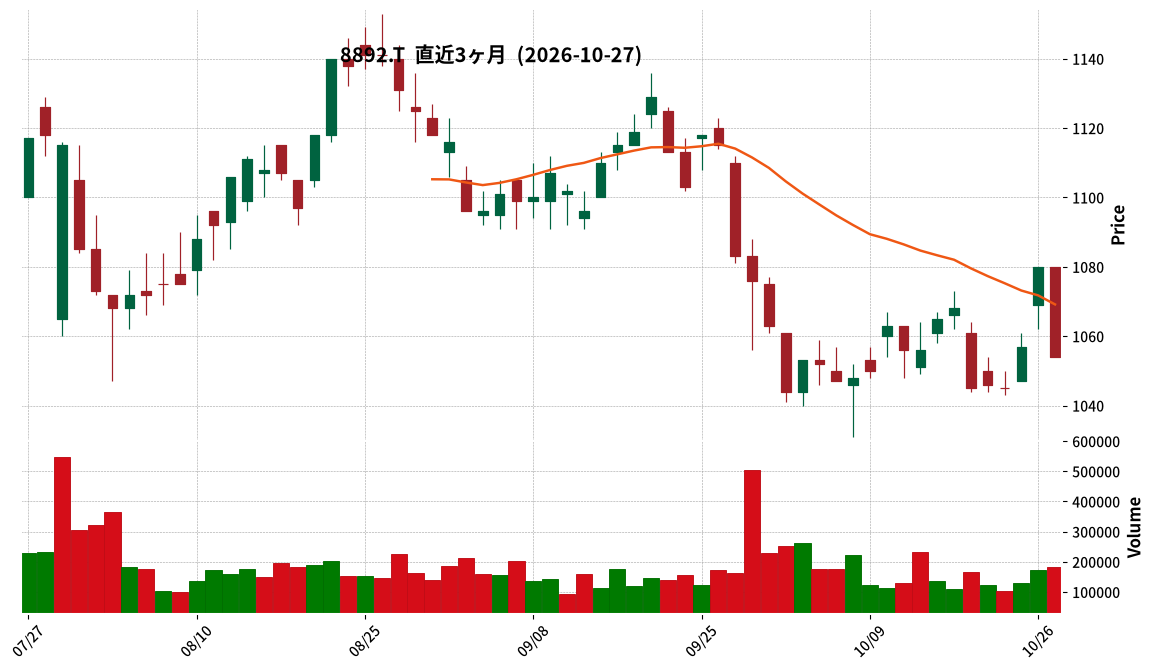
8892|エスコン
1054.0
▼ -2.41%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- ES-CON Japan’s consolidated financial results for the second quarter (interim period) of FY2027 show sales of ¥55,523 million (up 57.8% year-on-year), operating profit of ¥10,578 million (up 115.6%), ordinary profit of ¥6,878 million (up 189.0%), and net profit attributable to owners of parent of ¥4,920 million (up 164.8%).
- The residential development business reported sales of ¥19,429 million (up 5.5% year-on-year) and segment profit of ¥3,203 million (up 1.0%), primarily due to an increase in the average sales price per condominium unit.
- The real estate development business achieved sales of ¥24,651 million (up 295.3% year-on-year) and segment profit of ¥8,638 million (up 445.5%).
- The full-year consolidated earnings forecast remains unchanged from the most recently announced figures: sales of ¥145,000 million, operating profit of ¥26,500 million, ordinary profit of ¥20,000 million, and net profit attributable to owners of parent of ¥14,000 million.
- The forecast for the annual dividend is ¥53 per share for the fiscal year-end, totaling ¥53, with no revision from the latest public announcement.
🤖 AI Perspective
This interim financial report highlights significant growth across key financial metrics, with the real estate development segment showing particularly strong increases in both sales and segment profit. The residential development business also contributed to revenue and profit growth, and the solid contract progress rate of 84.7% for condominium units for the full year suggests continued positive momentum. The company’s decision to maintain its full-year earnings and dividend forecasts may indicate management’s confidence in achieving its current plans.
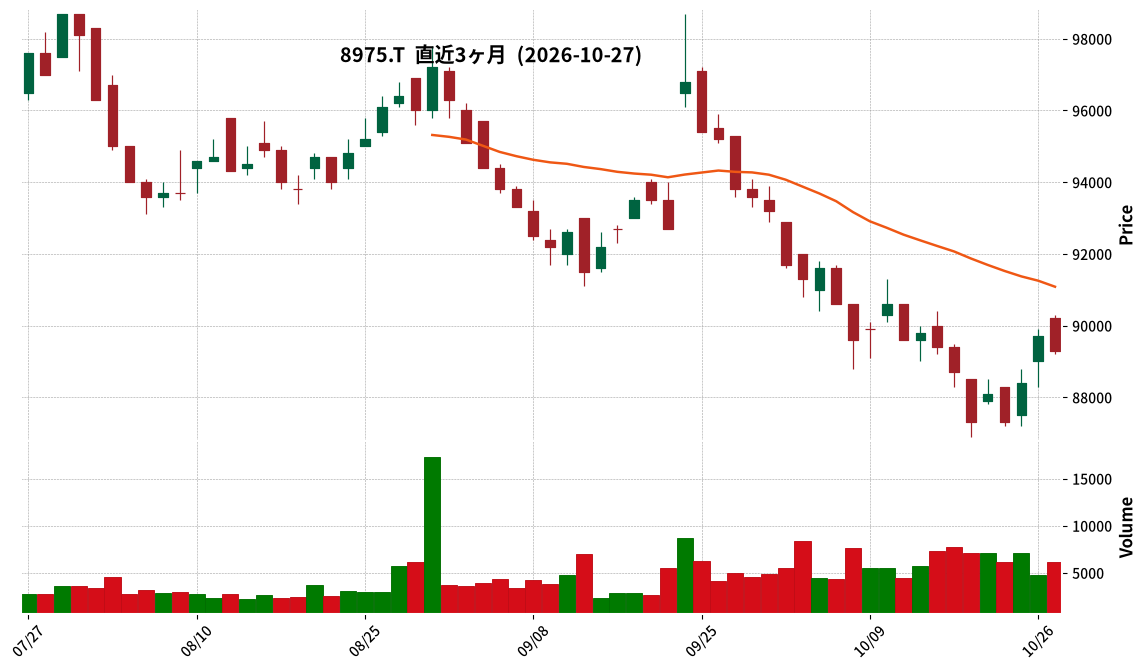
8975|R-いちごオフィス
89300.0
▼ -0.45%
📎 Source:R-いちごオフィス Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- R-Ichigo Office has revised upwards its operating performance and distribution forecast for the April 2027 period.
- The revised distribution per unit (DPU) is ¥5,552, an increase of ¥3,542 from the previous forecast of ¥2,010, representing a +176.2% change.
- Operating revenue is revised to ¥15,637 million, an increase of ¥7,375 million from the previous forecast of ¥8,261 million, a +89.3% change.
- Ordinary profit is revised to ¥10,910 million, an increase of ¥7,944 million from the previous forecast of ¥2,966 million, a +267.8% change.
- This revision is primarily due to an estimated gain on sale of approximately ¥7,930 million to be recorded in the April 2027 period, resulting from the transfer of five properties as announced today, with the handover scheduled for November 27, 2026.
- Of the aforementioned gain on sale, ¥2,520 million is planned to be retained as a replacement special depreciation reserve, and ¥101 million as a dividend reserve.
🤖 AI Perspective
This significant upward revision in the distribution forecast appears to be primarily driven by the recognition of special gains from property transfers. While this leads to a substantial increase in DPU for the period, investors may wish to note that a portion of these gains will be retained internally. This retention strategy could suggest a focus on strengthening the REIT’s financial foundation or preparing for future investment opportunities.
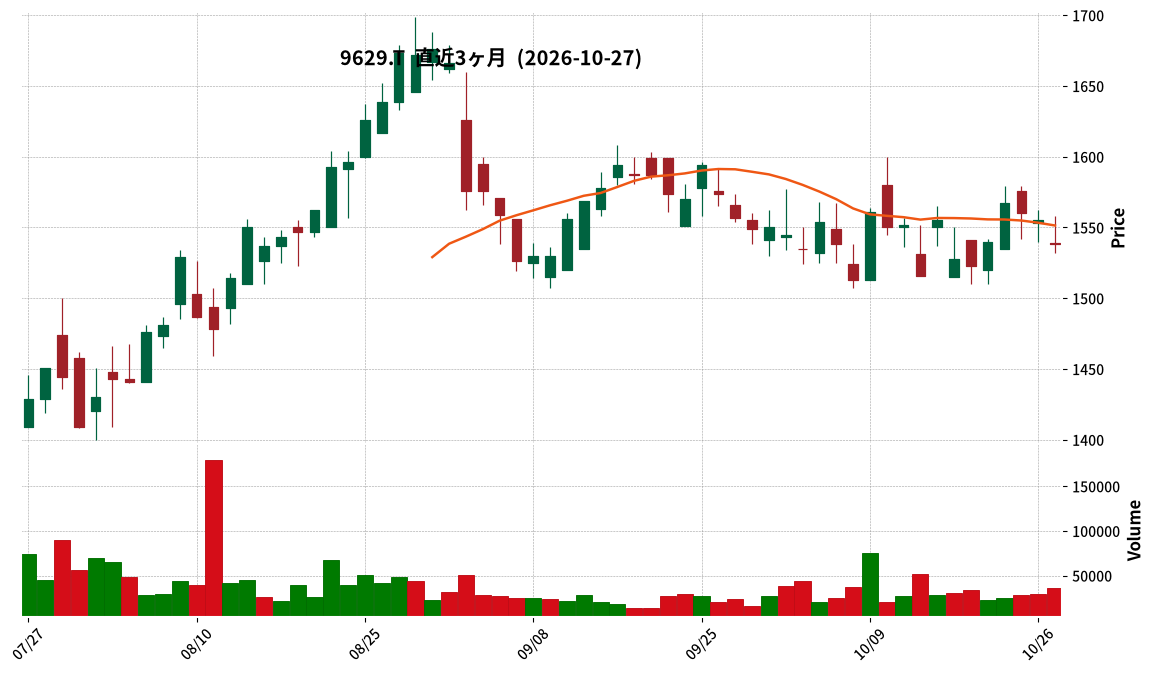
9629|ピーシーエー
1538.0
▼ -1.09%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- For the second quarter of the fiscal year ending March 2027, consolidated net sales were JPY 8,907 million, an 8.3% increase compared to the same period last year.
- Operating profit was JPY 790 million (down 34.7% YoY), ordinary profit was JPY 840 million (down 30.3% YoY), and net income attributable to owners of parent was JPY 470 million (down 38.1% YoY).
- Diluted earnings per share for the interim period were JPY 23.43 (compared to JPY 37.90 in the prior year’s interim period).
- The number of recurring subscription contracts reached 41,565 (up 23.7% YoY), and Annual Recurring Revenue (ARR) was JPY 12,020 million (up 14.6% YoY).
- During the interim period, PRIMAS Co., Ltd. was newly consolidated as a subsidiary, representing a significant change in the scope of consolidation.
🤖 AI Perspective
While sales show growth, the significant decline in profits is a key area of focus, which may suggest increased upfront investments for business expansion and costs associated with the consolidation of a new subsidiary. Conversely, the strong growth in recurring subscription contracts and ARR indicates positive momentum in the company’s shift towards a subscription-based business model and its growth strategies.
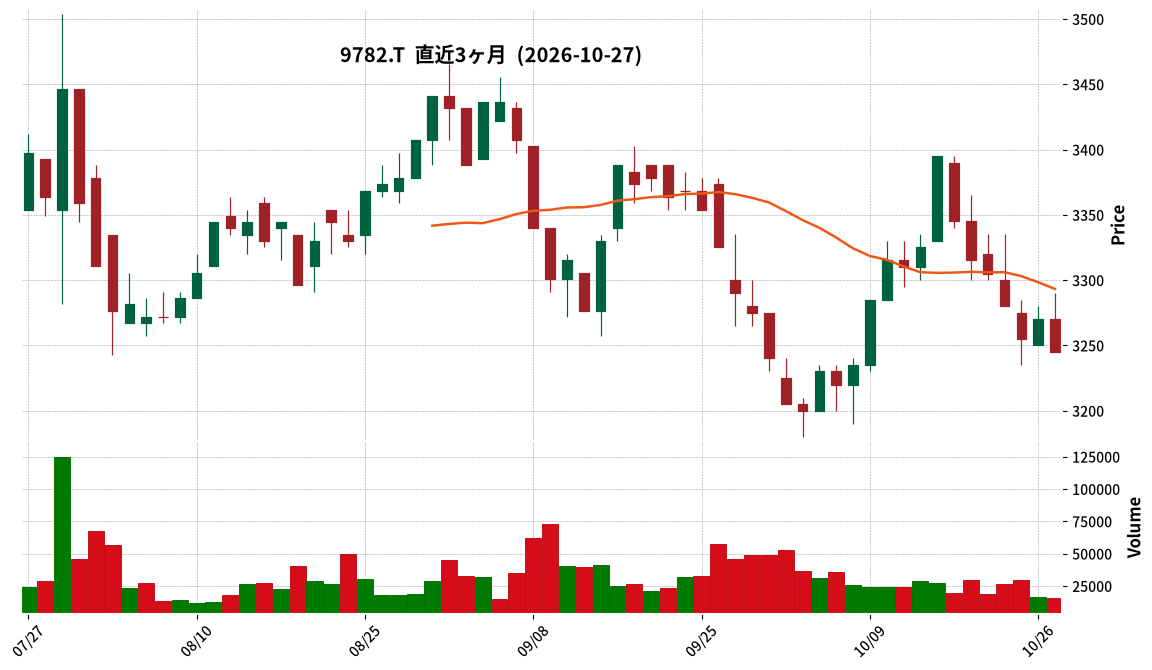
9782|ディーエムエス
3245.0
▼ -0.76%
📎 Source:ディーエムエス Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- DMS Inc. announced its Q2 FY2027 interim financial results (non-consolidated) for the period from April 1, 2026, to September 30, 2026.
- For the interim period, net sales were ¥13.81 billion (down 0.3% year-on-year), operating profit was ¥482 million (down 8.9% YoY), ordinary profit was ¥517 million (down 7.8% YoY), and net income attributable to owners of the parent was ¥354 million (down 10.5% YoY).
- By segment, the Logistics business reported sales of ¥1.548 billion (up 17.1% YoY) and segment profit of ¥62 million, a turnaround from a segment loss of ¥1 million in the prior year. The Direct Mail business recorded sales of ¥11.437 billion (down 0.9% YoY) but segment profit of ¥940 million (up 22.4% YoY).
- The full-year forecast for FY2027 remains unchanged, projecting net sales of ¥30.70 billion (up 1.3% YoY), operating profit of ¥1.53 billion (up 2.0% YoY), ordinary profit of ¥1.59 billion (up 0.5% YoY), and net income of ¥1.10 billion (up 0.2% YoY).
- The interim dividend is ¥110.00 per share, and the annual dividend forecast is ¥122.00 for the year-end, totaling ¥232.00 (compared to ¥234.00 in the previous fiscal year), with no revisions.
🤖 AI Perspective
While the interim results show a decline in sales and profits compared to the previous year, the strong performance of the Logistics segment, with significant sales and profit growth, stands out. The decrease in operating profit is attributed to research and development expenses related to “Physical AI,” which may suggest the company’s continued investment in future growth areas. The unchanged full-year forecast could indicate management’s confidence in a recovery during the second half of the fiscal year, making the company’s future performance worth monitoring.
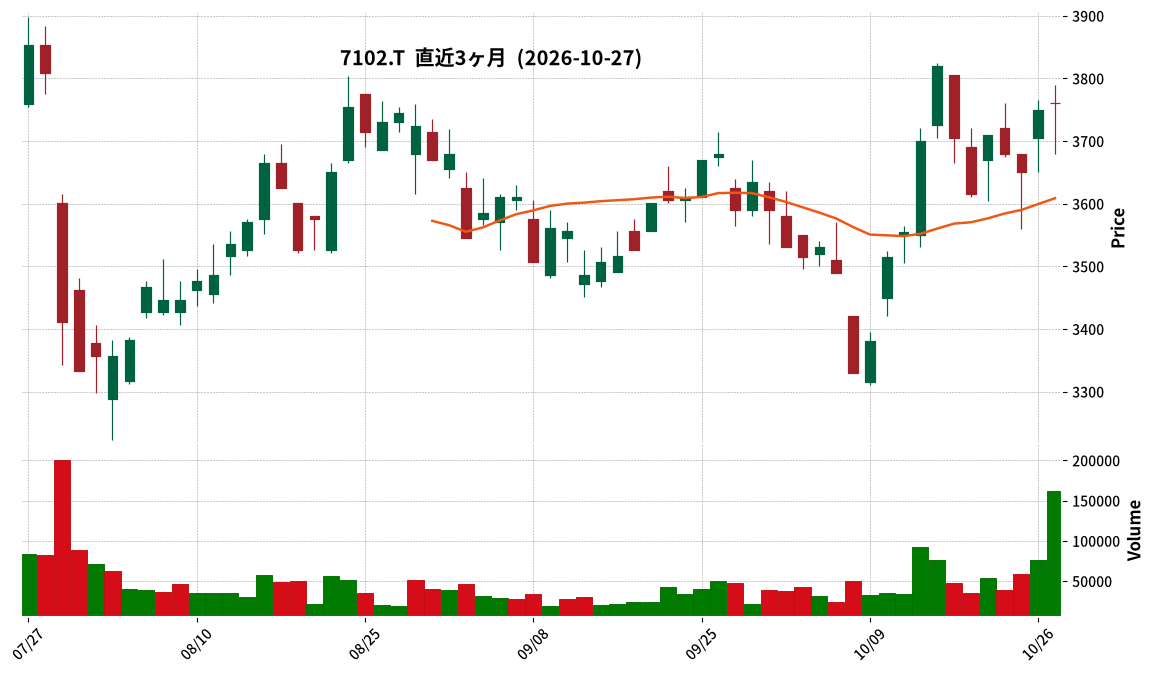
7102|日車輌
3760.0
▲ +0.27%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- For the second quarter (interim period) of the fiscal year ending March 2027, consolidated net sales were ¥47,960 million, a 3.0% increase year-over-year.
- Consolidated operating profit for the same interim period was ¥5,433 million, representing a 34.5% increase year-over-year.
- Consolidated ordinary profit for the interim period increased by 35.3% year-over-year to ¥5,769 million.
- Net profit attributable to owners of parent for the interim period was ¥5,500 million, a 4.4% decrease year-over-year.
- The full-year consolidated earnings forecast for the fiscal year ending March 2027 has been revised upwards, projecting net sales of ¥113,000 million (up ¥6,000 million from previous forecast), operating profit of ¥12,700 million (up ¥3,900 million), ordinary profit of ¥13,400 million (up ¥4,100 million), and net profit attributable to owners of parent of ¥9,600 million (up ¥2,100 million).
🤖 AI Perspective
Nippon Sharyo’s interim results show increased sales, operating profit, and ordinary profit, though net profit attributable to owners of parent declined compared to the prior year. The upward revision of the full-year earnings forecast suggests a positive outlook from the company for the remainder of the fiscal year. This indicates that while the interim net profit saw a slight decrease, the company’s forward-looking projections reflect confidence in its operational performance.
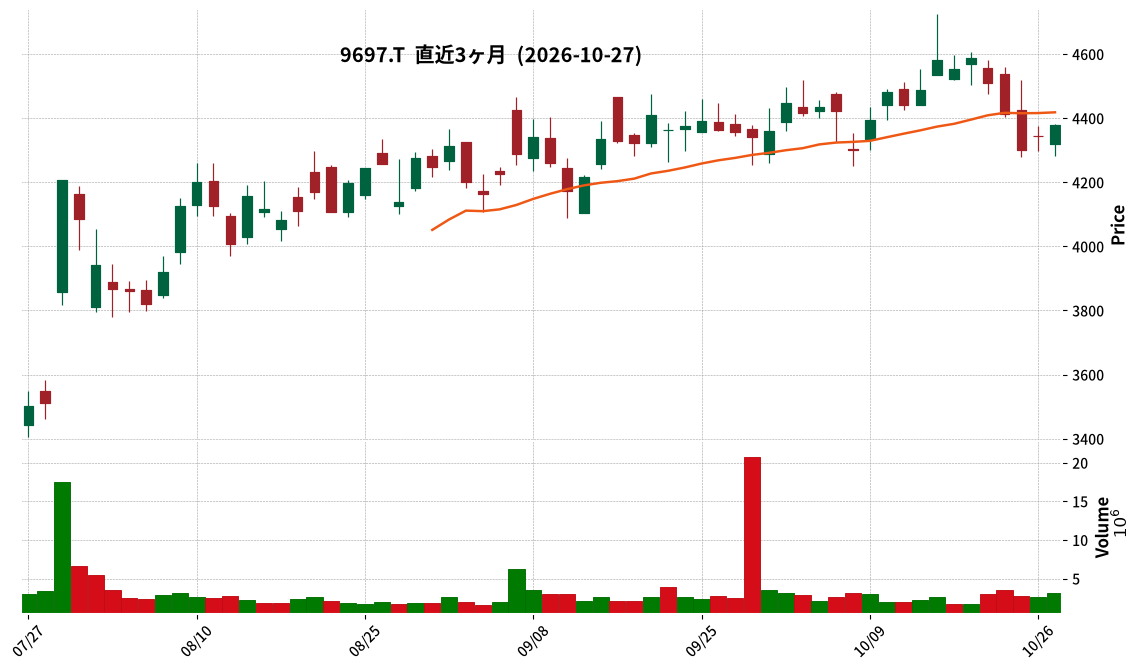
9697|カプコン
4380.0
▲ +0.85%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Capcom Co., Ltd. has announced its consolidated financial results for the second quarter (interim period) of the fiscal year ending March 2027.
- For the interim period, consolidated net sales were ¥120,887 million (up 49.0% year-on-year), operating income was ¥60,769 million (up 54.5%), ordinary income was ¥61,212 million (up 67.5%), and net income attributable to owners of the parent was ¥43,083 million (up 56.6%).
- In the Digital Contents business, the completely new IP “Pragmata” sold 2.7 million units, and the latest title in the “Onimusha” series in 20 years, “Onimusha Way of the Sword,” sold 1.7 million units.
- For repeat titles, “Resident Evil Requiem” surpassed 8 million units in cumulative sales, and total repeat title sales reached 32.18 million units, exceeding the prior-year period.
- The full-year consolidated earnings forecast remains unchanged: net sales of ¥210,000 million (up 7.5% year-on-year), operating income of ¥83,000 million (up 10.2%), and net income attributable to owners of the parent of ¥58,000 million (up 6.3%).
🤖 AI Perspective
Capcom’s interim results suggest a successful strategy combining new IP launches with sustained sales from existing popular titles, leading to significant increases in both revenue and profit. The strong performance of new titles and the continued growth in repeat title sales within the Digital Contents business indicate the robustness of the company’s IP strategy. The unchanged full-year forecast could signal a cautious but stable outlook, making future developments worth monitoring for investors.
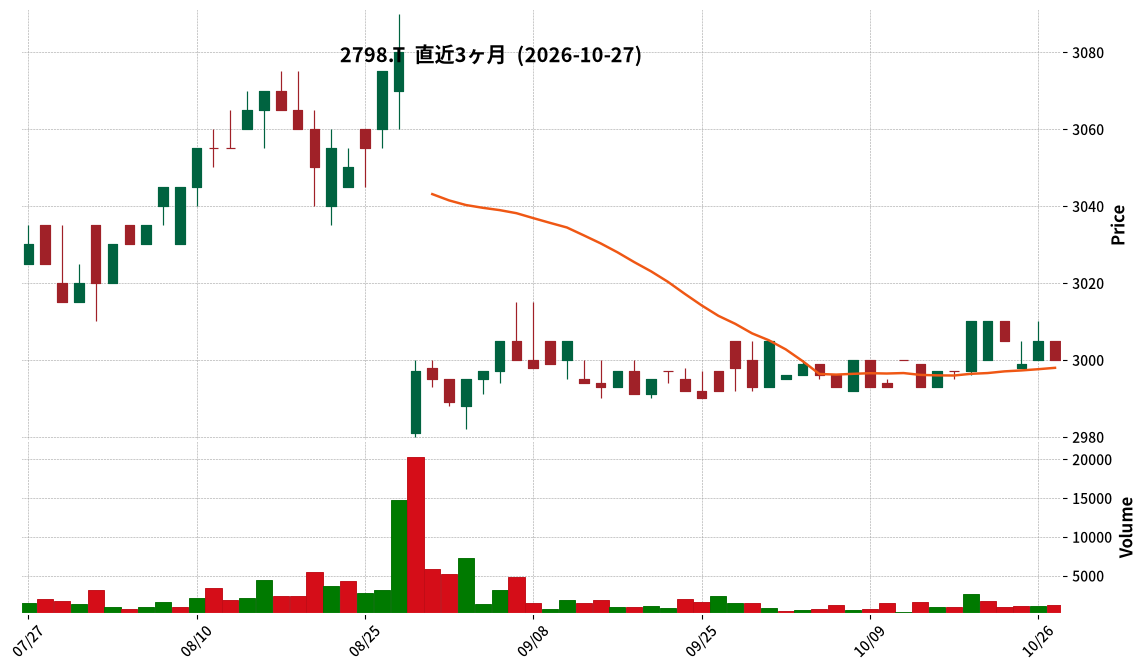
2798|Y’s
3000.0
▼ -0.17%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- For the second quarter of the fiscal year ending February 2027 (interim period), consolidated net sales reached 7,069 million JPY (up 109.8% YoY), operating income was 157 million JPY (up 163.6% YoY), and ordinary income was 168 million JPY (up 132.3% YoY).
- Net income attributable to owners of the parent was 382 million JPY (up 318.1% YoY), exceeding the plan of 120 million JPY.
- While net sales and operating income fell below plan, the interim net income attributable to owners of the parent surpassed the plan due to the recognition of negative goodwill from the consolidation of Yamano-ue Hotel Co., Ltd. (now Tempura Yamano-ue Co., Ltd.).
- Existing store sales showed the Casual Restaurant Group performing well at 106% of the previous year, while the XEX Group struggled at 99%.
- The full-year consolidated forecast has been revised to net sales of 14,649 million JPY, operating income of 341 million JPY, ordinary income of 385 million JPY, and net income attributable to owners of the parent of 536 million JPY.
🤖 AI Perspective
The interim results indicate that while the Casual Restaurant Group performed strongly, the XEX Group faced challenges due to international situations and natural disasters. The shortfall in net sales and operating income compared to plans is noteworthy. However, the negative goodwill generated from the acquisition contributed significantly to the interim net income, suggesting a positive short-term impact from M&A strategy. The revised full-year forecast likely reflects adjustments based on first-half performance and planned second-half initiatives, such as new store openings and existing store improvements.
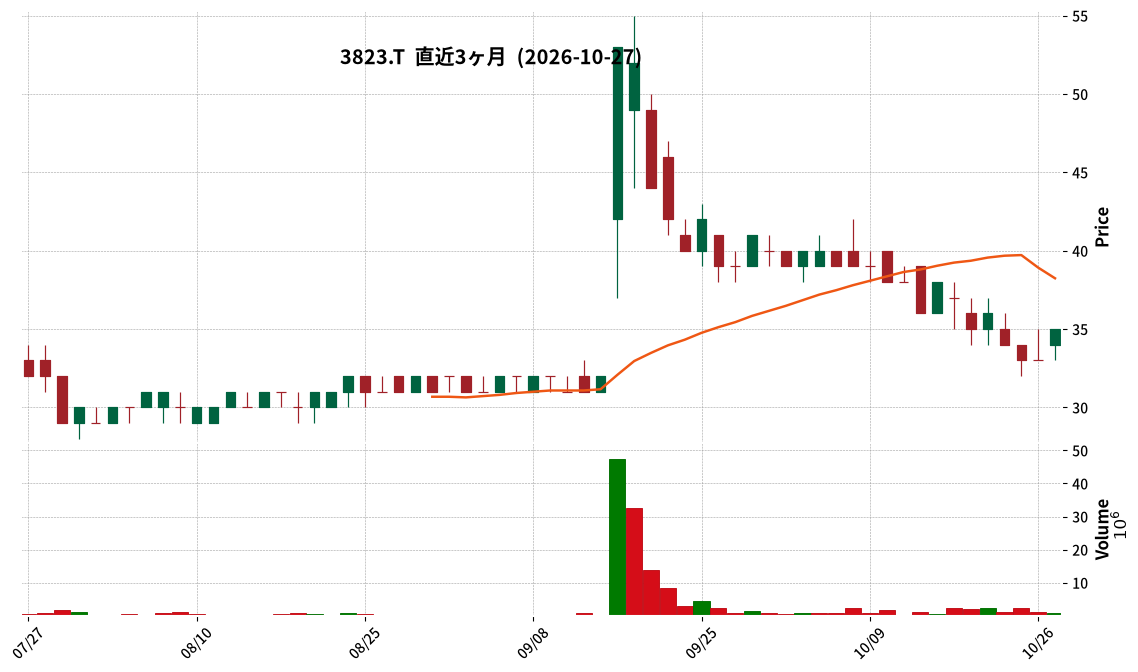
3823|WHY HOW DO
35.0
▲ +6.06%
📎 Source:WHY HOW DO Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- WHY HOW DO Co. resolved to introduce a shareholder benefit program utilizing pure gold at its Board of Directors meeting held on October 27, 2026.
- The program targets shareholders who hold 3,000 shares (30 units) or more as of January 31, 2027.
- A total of 1,103 shareholders will be selected by lottery to receive pure gold products valued at 16.0 million JPY (including tax, retail price), comprising: 1st prize 30g pure gold coin (1 winner), 2nd prize 10g pure gold coin (2 winners), 3rd prize 1g gold grain (100 winners), and 4th prize 0.2g pure gold logo mark (1,000 winners).
- All shareholders are eligible to purchase the four pure gold products produced for this program (30g/10g pure gold coins, 1g gold grain, 0.2g pure gold logo mark) at a 5% discount from the retail price (including tax).
- The benefit items are scheduled to be shipped by the end of April 2027, and the costs associated with implementing this program are expected to be recorded in the consolidated financial results for the fiscal year ending April 2027, with a minor impact anticipated.
🤖 AI Perspective
The introduction of this shareholder benefit program appears to leverage the precious metal trading business of Nihon Junkin-Kou Co., which became a subsidiary on April 16, 2026, suggesting an intent to strengthen collaboration with its new business segment. Utilizing pure gold products as benefits may aim to enhance investment appeal and encourage long-term shareholding. The discount sales offered to all shareholders, regardless of holdings, could provide a broader opportunity for shareholder returns while potentially expanding interest in pure gold products.
4848|フルキャストHD
1851.0
▼ -1.70%
📎 Source:フルキャストHD Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Fullcast Holdings has decided to enter into a capital and business alliance agreement with Seyfert Inc., contingent on subscribing to a third-party allotment of new shares issued by Seyfert.
- Through this alliance, Fullcast Holdings will acquire an additional 85,000 common shares of Seyfert Inc. at ¥1,030 per share, totaling ¥87,550,000.
- This transaction will increase Fullcast Holdings’ total ownership of Seyfert Inc. shares from 30,000 to 115,000, raising its voting rights ratio from 2.27% to an estimated 7.15%.
- The business alliance includes initiatives such as reviewing Seyfert’s cost structure, implementing operational improvements leveraging Fullcast Holdings’ management foundation (e.g., concentrating resources on the “re-quest/QJ navi” job platform), and developing specialized RPO (Recruitment Process Outsourcing) services for the beauty industry.
- The decision date for the capital and business alliance and the contract signing date are October 27, 2026, with the share acquisition execution date set for November 13, 2026.
🤖 AI Perspective
This alliance suggests Fullcast Holdings’ strategic move to expand into new growth areas by partnering with Seyfert Inc., a company specializing in recruitment and HR services for the beauty industry. By combining Fullcast Holdings’ HR solution expertise with Seyfert’s industry network, the collaboration aims to address structural challenges in the beauty sector, such as talent mobility and diversified work styles, by promoting HRDX (Human Resources Digital Transformation) and establishing new revenue models. The stated goals are to restore Seyfert’s business profitability and maximize its long-term corporate value, making the realization of future synergistic effects a key point for investors to monitor.
4973|高純度化
4315.0
▲ +2.74%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- For the second quarter of FY2027 (interim period), sales reached ¥11,878 million, marking a 57.6% increase compared to the prior year’s interim period.
- Operating profit for the same period was ¥53 million (an 80.5% decrease year-on-year), and ordinary profit was ¥169 million (a 55.1% decrease year-on-year).
- Interim net profit amounted to ¥694 million, an 11.3% increase from the prior year’s interim period.
- Interim earnings per share were ¥119.60.
- The interim dividend for FY2027 is ¥115.00, with a year-end forecast also at ¥115.00, totaling ¥230.00 for the full year, with no revisions from the most recently announced forecast.
- Full-year performance forecasts remain unrevised, projecting sales of ¥24,000 million (a 32.8% increase year-on-year) and net profit of ¥2,170 million (a 20.3% increase year-on-year).
🤖 AI Perspective
High Purity Chemical’s Q2 FY2027 results highlight significant growth in sales and interim net profit, with the 57.6% increase in sales suggesting robust demand in specific product segments. However, the decline in operating and ordinary profits may warrant investor attention, as it could indicate pressures on cost of goods sold or selling, general and administrative expenses, or impacts from factors like exchange rate fluctuations or rising resource and energy prices. Monitoring the company’s profitability trends in future reports will be crucial.
562A|P-寶結
1000.0
▲ +0.00%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- P-HOHKETSU announced a change in its audit firm, effective December 1, 2026 (scheduled).
- Josui Audit Corporation (the absorbed firm), the current auditor, will merge with SCS International Limited Liability Audit Firm (the surviving firm) on the same date.
- The merged entity will be named SCS Josui Limited Liability Audit Firm.
- Consequently, SCS Josui Limited Liability Audit Firm will provide audit certification for P-HOHKETSU from December 1, 2026, onwards.
- The surviving SCS Josui Limited Liability Audit Firm is registered under the Certified Public Accountant Act for auditors of listed companies.
🤖 AI Perspective
This announcement primarily reflects a procedural change due to the merger of audit firms, rather than a direct alteration in the company’s accounting audit framework. The continuity of audit services by a firm registered under the Certified Public Accountant Act for listed companies is generally seen as maintaining the transparency and reliability required for corporate financial reporting. This type of change typically does not indicate a material impact on the company’s operational integrity or the credibility of its financial statements.
6988|日東電
3600.0
▼ -0.22%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Nitto Denko’s Board of Directors resolved on October 27, 2026, to pay an interim dividend for the record date of September 30, 2026, implement a share buyback, and revise the year-end dividend forecast for the fiscal year ending March 2027 (an increase).
- The interim dividend was set at ¥36.0 per share (compared to the previous forecast of ¥32.0 and the previous year’s actual of ¥30.0).
- The year-end dividend forecast for the fiscal year ending March 2027 was revised from ¥32.0 to ¥72.0 per share, resulting in an annual dividend revision from ¥64.0 to ¥108.0 per share.
- The share buyback program targets common shares, with a maximum of 17,000,000 shares (2.58% of outstanding shares excluding treasury shares) and a maximum total acquisition cost of ¥50,000 million.
- The acquisition period for the share buyback is from November 4, 2026, to March 24, 2027.
🤖 AI Perspective
The announced increase in interim dividends, revised year-end dividend forecast (increase), and share buyback program are consistent with the company’s financial strategy and capital policy outlined in its medium-term management plan, aiming to enhance shareholder returns and improve ROE. The simultaneous announcement of multiple shareholder return measures may suggest a strong corporate commitment to improving capital efficiency. Investors may monitor how these initiatives contribute to future corporate value enhancement.
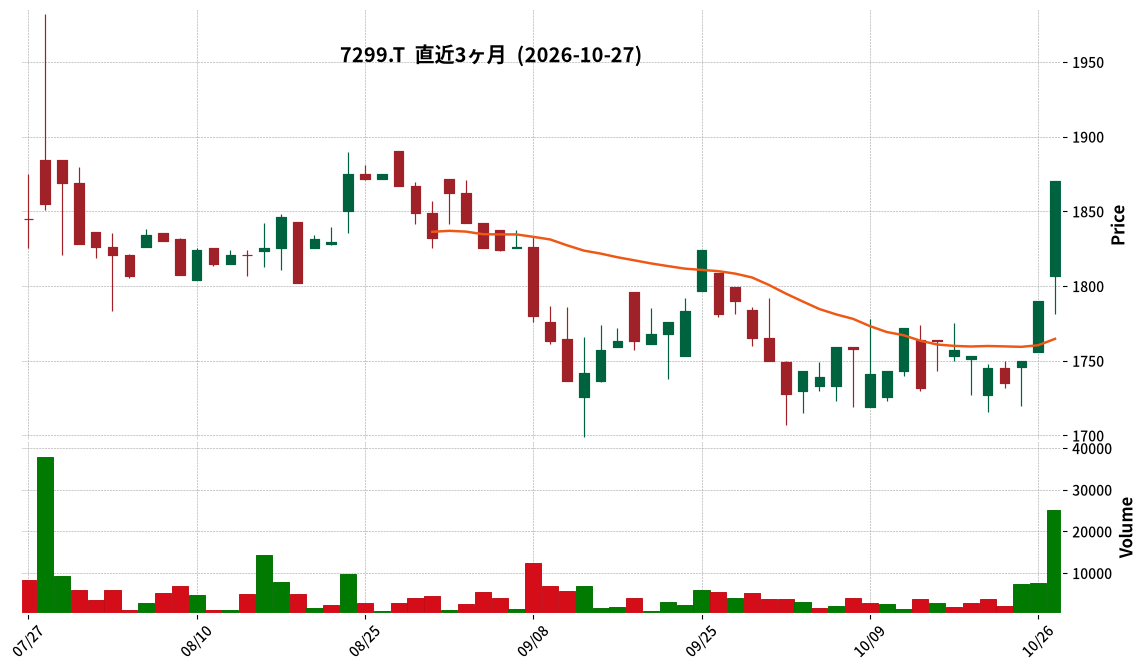
7299|フジオーゼ
1870.0
▲ +4.47%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Fujioh Co., Ltd. announced its consolidated financial results for the second quarter (interim period) of the fiscal year ending March 2027.
- Consolidated net sales for the interim period were ¥14,542 million (up 2.6% year-on-year), operating profit was ¥1,731 million (up 61.8%), ordinary profit was ¥1,693 million (up 47.1%), and net income attributable to owners of parent was ¥1,194 million (up 22.0%).
- The full-year consolidated earnings forecast has been revised upward, with net sales projected at ¥29,200 million, operating profit at ¥2,920 million, ordinary profit at ¥2,920 million, and net income attributable to owners of parent at ¥1,850 million.
- The annual dividend forecast has been revised from ¥54 to ¥60, with an interim dividend of ¥30 (compared to ¥22 in the previous interim period).
- A significant change in the scope of consolidation occurred, with Tetos Co., Ltd. excluded from consolidated subsidiaries.
- The equity ratio improved to 85.3% from 83.9% at the end of the previous fiscal year.
🤖 AI Perspective
The interim consolidated financial results show an increase in net sales and all profit items year-on-year, with a significant 61.8% rise in operating profit. This robust performance appears to be supported by increased domestic sales, cost reduction efforts, price pass-through, and a partial tariff refund for the Mexican subsidiary. The upward revision of both the full-year earnings forecast and the annual dividend forecast could be viewed as a positive development for investors.
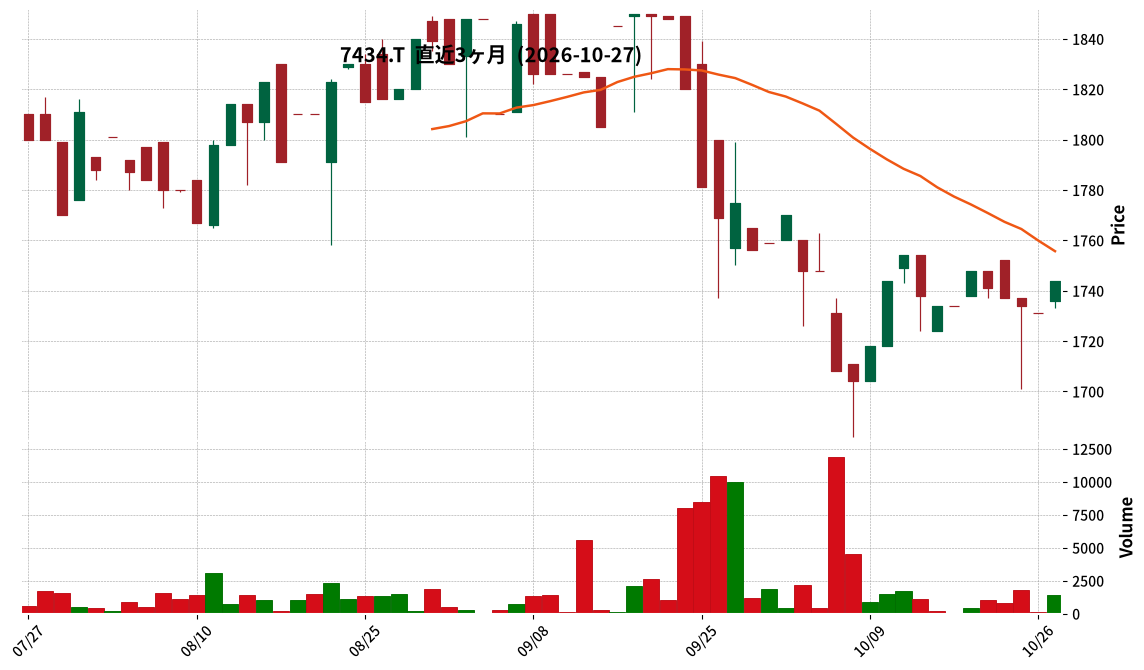
7434|オータケ
1744.0
▲ +0.75%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Otake Co., Ltd. announced its consolidated financial results for the fiscal year ended May 2026.
- Net sales were ¥35,653 million (up 8.1% year-on-year), operating profit was ¥1,121 million (up 14.7% year-on-year), and ordinary profit was ¥1,362 million (up 12.3% year-on-year).
- Profit attributable to owners of parent was ¥878 million (up 2.8% year-on-year).
- The year-end dividend for FY2026 was ¥40 per share (compared to ¥37 in the previous year), with a total annual dividend of ¥156 million.
- For the fiscal year ending May 2027, the company forecasts consolidated net sales of ¥36,000 million (up 1.0% year-on-year), operating profit of ¥1,130 million (up 0.7% year-on-year), ordinary profit of ¥1,370 million (up 0.6% year-on-year), and profit attributable to owners of parent of ¥920 million (up 4.7% year-on-year).
🤖 AI Perspective
Otake’s FY2026 results show solid year-on-year growth across net sales and profit metrics, with operating profit increasing by 14.7%. While net profit growth was more modest, the increase in the year-end dividend may indicate a commitment to shareholder returns. The company’s FY2027 forecast projects continued revenue and profit growth, suggesting expectations for ongoing business expansion.
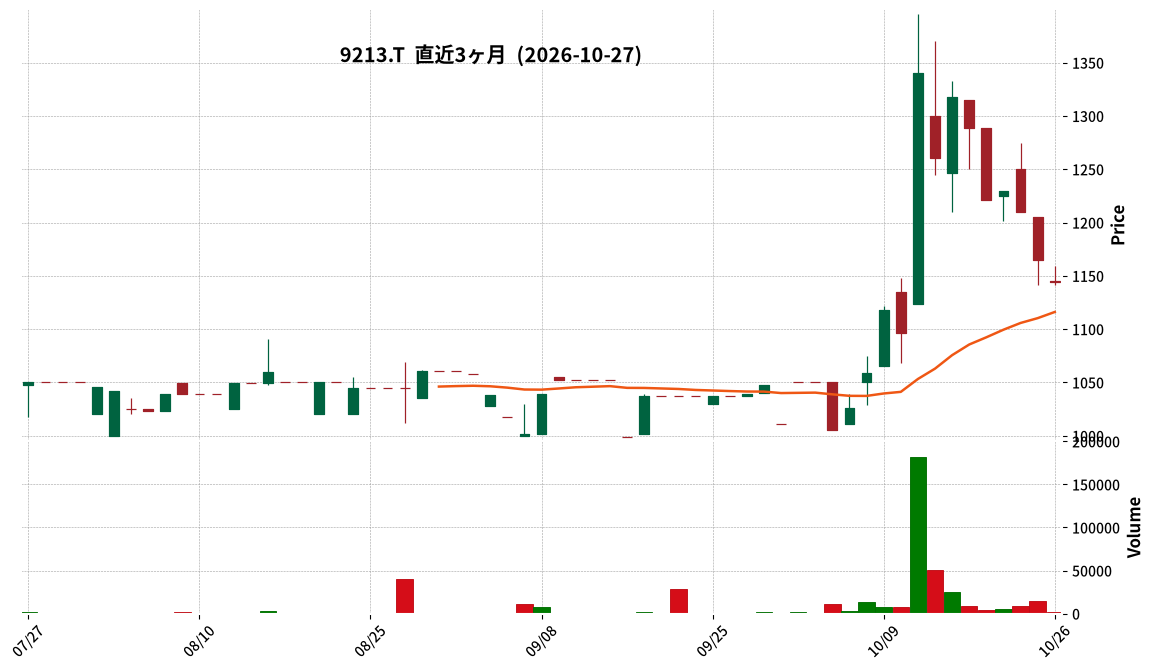
9213|セイファート
1144.0
▼ -1.80%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Seyfert Co., Ltd. resolved to enter into a capital and business alliance agreement with Fullcast Holdings Co., Ltd. at its board meeting on October 27, 2026.
- In connection with this alliance, Seyfert resolved to issue 288,000 new shares through a third-party allotment to Fullcast Holdings and others.
- The issue price is 1,030 yen per share, aiming to raise 296.64 million yen.
- The allottees for the third-party allotment are Deep Growth Partners Co., Ltd. (105,000 shares), Fullcast Holdings Co., Ltd. (85,000 shares), Hirano Associates Co., Ltd. (45,000 shares), and Mr. Takefumi Hirano (53,000 shares).
- The business alliance includes Seyfert providing its business foundation, such as its advertising recruitment services for the beauty industry, and Fullcast Holdings offering new graduate recruitment support, consulting, and advice on business reconstruction, leveraging its HR business expertise.
🤖 AI Perspective
This capital and business alliance appears to be an initiative to enhance the profitability of existing businesses and create new growth opportunities by combining Seyfert’s HR expertise in the beauty industry with Fullcast Holdings’ extensive knowledge in the human resources market. The capital raised through the third-party allotment is expected to address the funding needs for business reconstruction, growth strategy promotion, and market expansion outlined in Seyfert’s mid-term management plan, making future business developments worth monitoring.
Disclaimer: This article is for informational purposes only and does not constitute investment advice.
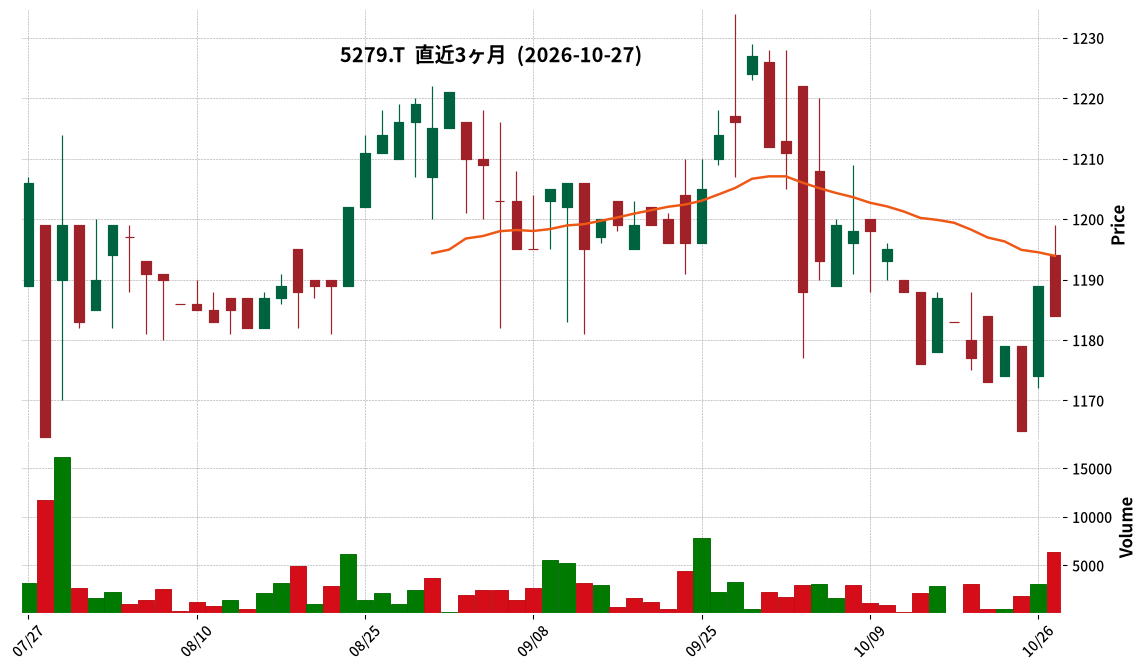
5279|日本興業
1184.0
▼ -0.42%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- For the second quarter of the fiscal year ending March 2027 (interim period), consolidated net sales were ¥6,002 million (down 12.5% compared to the same period last year).
- The interim consolidated operating loss was ¥77 million (compared to a profit of ¥107 million in the prior interim period), ordinary loss was ¥58 million (compared to a profit of ¥128 million), and net loss attributable to owners of the parent was ¥78 million (compared to a profit of ¥74 million).
- By segment, Civil Engineering Materials recorded sales of ¥4,020 million (down 19.8% YoY) and a segment loss of ¥112 million. Landscape Materials reported sales of ¥1,476 million (up 7.7% YoY) and a segment profit of ¥42 million. Exterior Materials recorded sales of ¥504 million (up 6.4% YoY) and a segment loss of ¥7 million.
- The full-year consolidated earnings forecast for FY2027 remains unchanged from the most recently announced forecast, projecting net sales of ¥15,300 million (down 6.2% YoY), operating profit of ¥680 million (down 14.0% YoY), ordinary profit of ¥700 million (down 14.9% YoY), and net profit attributable to owners of the parent of ¥410 million (down 29.1% YoY).
- The year-end dividend forecast is ¥45.00 per share, with no revisions from the most recently announced forecast.
🤖 AI Perspective
Nihon Kogyo’s interim results for the fiscal year ending March 2027 show a decrease in sales and a shift to losses across profit metrics, primarily attributed to a reaction from large projects in the civil engineering materials business during the previous period. Conversely, the Landscape Materials and Exterior Materials segments demonstrated sales growth, suggesting potential shifts in business emphasis. The unchanged full-year forecast indicates the company anticipates a recovery in profitability in the second half of the fiscal year.
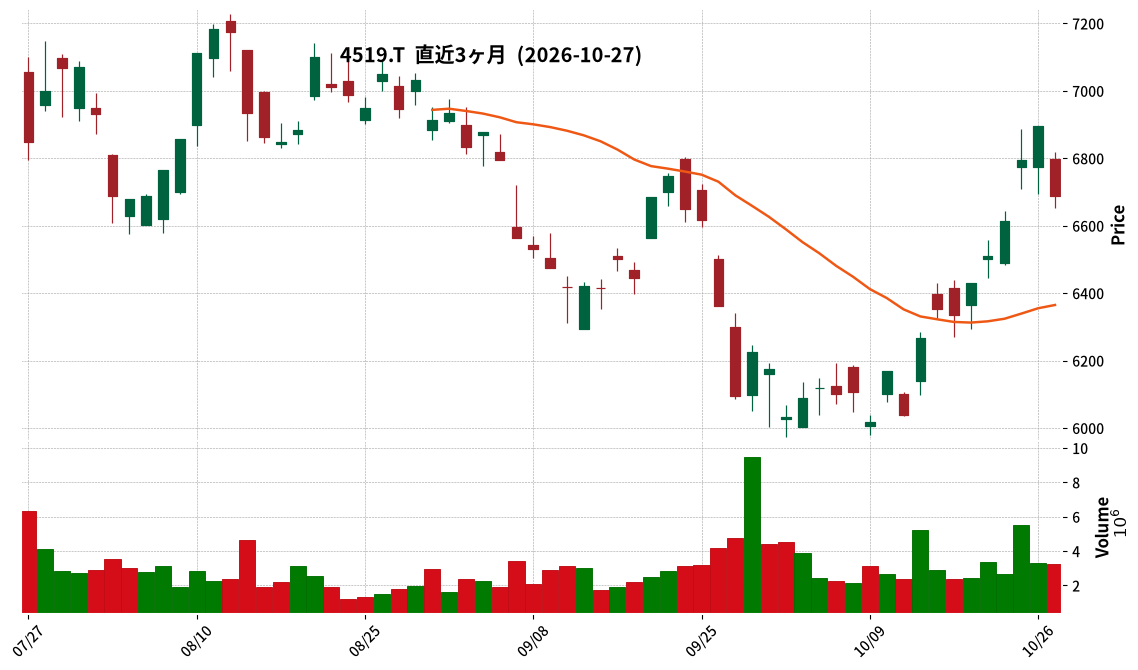
4519|中外薬
6688.0
▼ -3.03%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Chugai Pharmaceutical announced its consolidated financial results for the third quarter of the fiscal year ending December 2026 (January 1, 2026, to September 30, 2026).
- Consolidated revenue reached JPY 1,068,074 million, marking a 17.2% increase compared to the same period in the previous year.
- Consolidated operating profit amounted to JPY 522,570 million, an increase of 21.6% year-on-year.
- Quarterly profit attributable to owners of the parent was JPY 375,302 million, up 22.8% year-on-year.
- Domestic product sales increased due to higher sales of key products (Polivy, Hemlibra, Vabysmo) and new products (Lunsumio, Elevidys), alongside an accelerated shipment schedule to pharmaceutical wholesalers for the transition to a next-generation ERP system.
- Overseas product sales surpassed the previous year, driven by a significant increase in exports of NEMLUVIO to Galderma and Alecensa to Roche.
- Other revenue increased by 37.7% year-on-year, primarily due to higher royalty income related to Hemlibra and NEMLUVIO, as well as an increase in upfront payments.
- The full-year consolidated performance forecast (Core basis) for FY2026 remains unchanged, projecting revenue of JPY 1,345,000 million, Core operating profit of JPY 670,000 million, Core net profit of JPY 485,000 million, and Core EPS of JPY 295.00.
🤖 AI Perspective
The announced results indicate robust growth in both revenue and profit, demonstrating a strong performance trajectory. The expansion of sales in core and new products domestically, coupled with significant increases in international exports, appears to be key drivers. While the full-year forecast remains unchanged, the high achievement rate of revenue at 79.4% and Core operating profit at 80.0% through the third quarter suggests positive momentum that investors may find worth monitoring as the company approaches the fiscal year-end.
Disclaimer: This article is for informational purposes only and does not constitute investment advice.
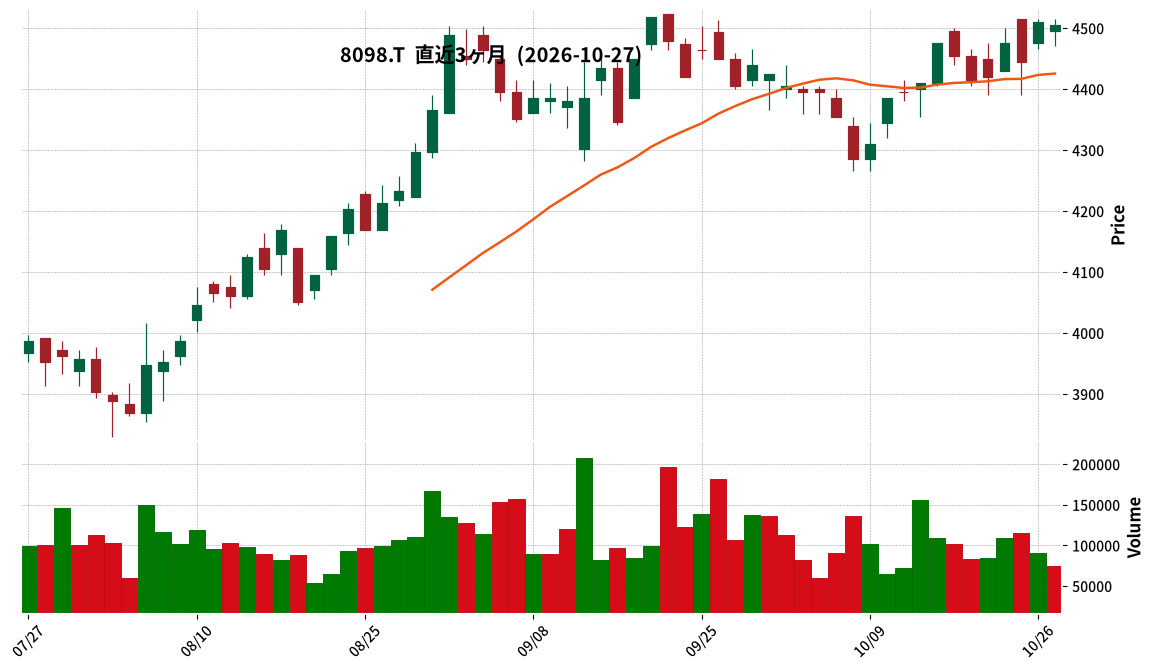
8098|稲畑産
4505.0
▼ -0.11%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Inabata & Co., Ltd. has decided to acquire an additional 65% stake in ULVAC Coating Corp., an equity method affiliate, from ULVAC, Inc., making it a wholly-owned subsidiary.
- This acquisition will also result in ULVAC Coating’s subsidiaries, Taiwan Coating Optronics Corp., ULVAC Coating Technology (Hefei) Co., Ltd., and Fine Surface Technology Co., Ltd., becoming wholly-owned subsidiaries of Inabata.
- The scheduled share transfer date is December 18, 2026, and the acquisition price is 4.9 billion JPY.
- ULVAC Coating Corp. is engaged in the manufacturing and sales of mask blanks for semiconductors and flat panel displays, as well as quartz substrate processing. Inabata previously held a 35.0% stake.
- This decision aligns with Inabata’s mid-term management plan “New Challenge 2026,” which targets the fiscal year ending March 2027, specifically as part of its “aggressive investment for profit expansion” growth strategy.
🤖 AI Perspective
This full acquisition appears to be a strategic move to accelerate Inabata’s expansion in the semiconductor and electronic components sector, consistent with its mid-term business plan. Integrating ULVAC Coating, a key manufacturer of mask blanks essential for semiconductor production, could potentially strengthen Inabata’s supply chain and enhance profitability. The decision may also reflect Inabata’s focus on capitalizing on the long-term growth of the semiconductor market and the pursuit of higher value-added opportunities in the FPD market.
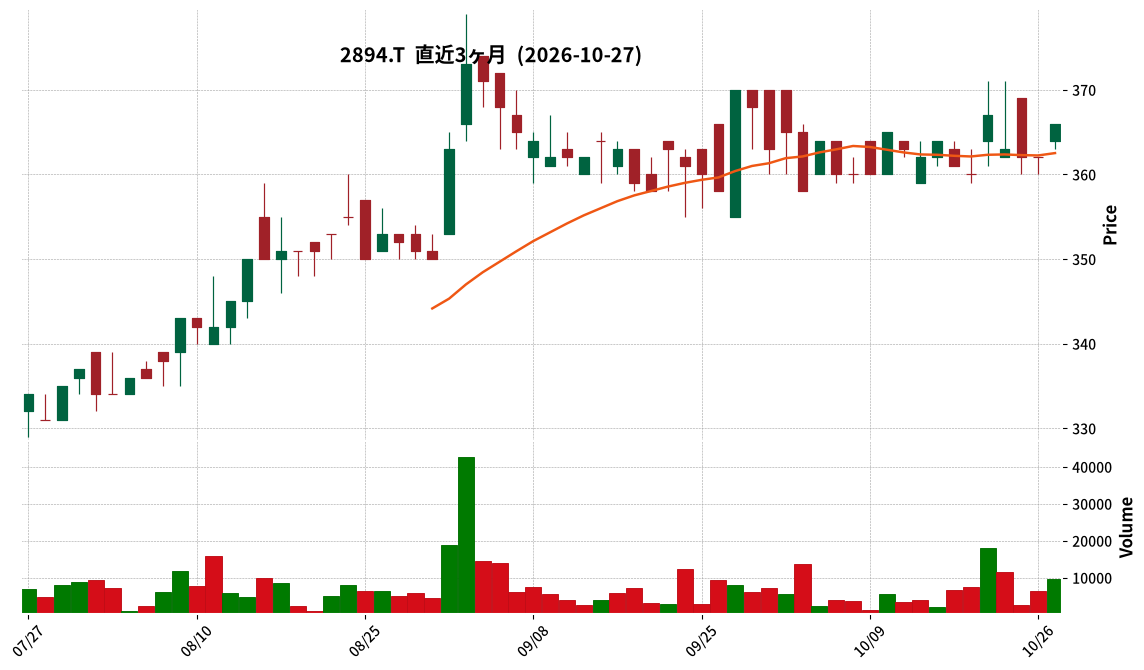
2894|石井食
366.0
▲ +1.10%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Ishii Food Co., Ltd. resolved to expand and revise its shareholder benefit program at a Board of Directors meeting held on October 27, 2026.
- The revised shareholder benefits will apply to shareholders recorded on the record date of March 31, 2027.
- Under the revised program, effective from the March 31 record date each year, shareholders can choose EC coupons ranging from JPY 5,000 to JPY 8,000, with the value determined by the holding period (less than 6 months, 6 months to less than 3 years, 3 years to less than 7 years, 7 years or more) and the number of shares held (1,000 shares to less than 2,000 shares, 2,000 shares or more).
- In addition to EC coupons, shareholders can also choose a “Product Assortment Set (valued at JPY 3,500)” or a “Donation (JPY 3,000)”.
- Shareholders who have held 1,000 shares or more for 10 years or longer (recorded consecutively 21 times or more with the same shareholder number) will receive a “Premium Commemorative Gift” separate from the regular shareholder benefits.
- For the first year of the change only (March 31, 2027 record date), shareholders holding 1,000 shares to less than 2,000 shares for less than 6 months will still be eligible for benefits under the current terms.
🤖 AI Perspective
This revision of the shareholder benefit program appears to aim at enhancing shareholder returns and encouraging long-term stock ownership. The tiered EC coupon values based on holding period and the introduction of a “Premium Commemorative Gift” for shareholders holding for 10 years or more may signal a focus on rewarding loyal, long-term investors. The inclusion of product assortment sets and donation options also suggests an effort to cater to diverse shareholder preferences.
💡 Start investing with IR insights


※ 本ページには広告が含まれます(PR)
Disclaimer: This article is for informational purposes only and does not constitute investment advice. All investment decisions are at your own risk.
コメント