📌 Today’s Highlights
Today we cover 16 IR announcements. Notable among them: オータケ (7434), 三陽商 (8011), サンエー (2659). Use the table of contents below to navigate to each company.
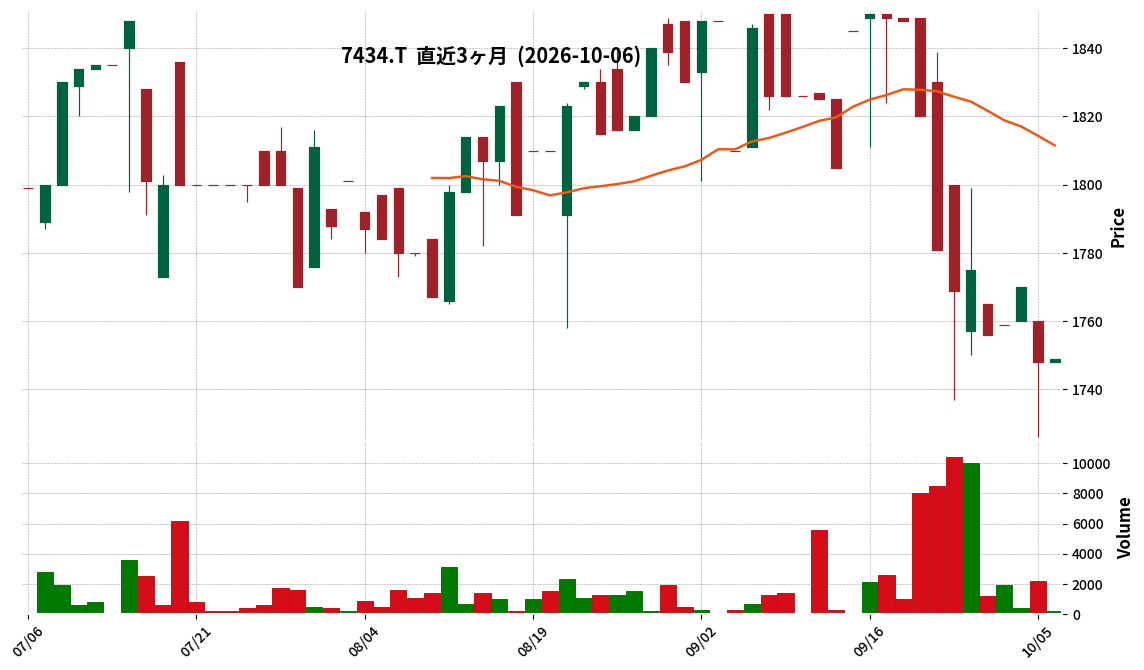
7434|オータケ
1749.0
▲ +0.06%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Otake Co., Ltd. announced on October 6, 2026, that the disclosure of its Q1 FY2027 financial results will be delayed beyond 45 days after the quarter-end.
- The reason for the delay is the ongoing discussions with the audit firm regarding the FY2026 financial closing procedures, which have not yet been completed, following the “Announcement Regarding Publication of Special Investigation Committee’s Report” dated September 18, 2026.
- As per the “Approval of Extension Application for Submission Deadline of FY2026 Annual Securities Report” dated August 31, 2026, the deadline for submitting the FY2026 Annual Securities Report has been extended to October 30, 2026.
- The company stated that the new announcement date for the Q1 FY2027 financial results will be promptly disclosed once determined.
🤖 AI Perspective
This announcement suggests that the ongoing delays in the company’s FY2026 financial closing procedures are impacting the disclosure of its subsequent Q1 FY2027 results. The careful process of finalizing accounting treatments based on the special investigation committee’s report, in consultation with the audit firm, appears to be a contributing factor. Investors may need to monitor further updates regarding the submission of the FY2026 Annual Securities Report and the new announcement date for the Q1 financial results.
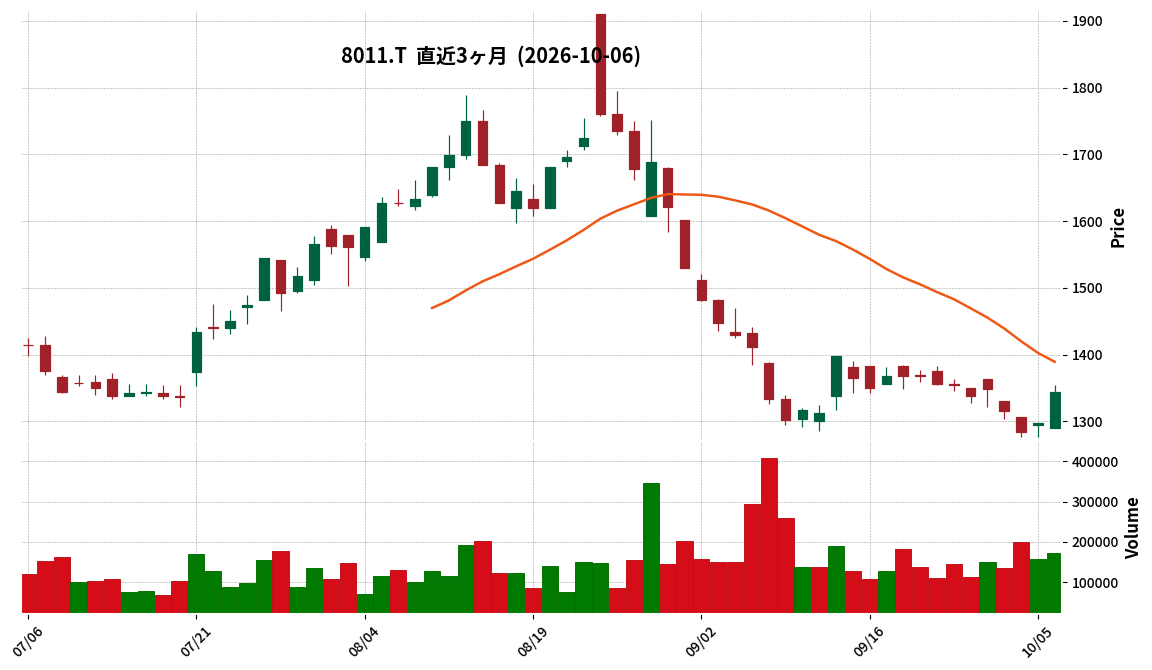
8011|三陽商
1344.0
▲ +3.62%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- SANYO SHOKAI announced its consolidated financial results for the second quarter (interim period) of the fiscal year ending February 2027.
- Net sales were ¥25.953 billion, representing a 4.0% decrease compared to the previous interim period. The company reported an operating loss of ¥499 million, compared to an operating loss of ¥213 million in the prior year’s interim period.
- Ordinary loss stood at ¥421 million (compared to ¥149 million ordinary loss in the prior year’s interim period), and net loss attributable to owners of parent was ¥555 million (compared to ¥299 million net loss in the prior year’s interim period).
- The interim dividend forecast for the fiscal year ending February 2027 has been revised to ¥76.00 per share.
- A stock split was conducted on September 1, 2026, at a ratio of three shares for every one common share.
🤖 AI Perspective
While net sales decreased, the gross profit margin recovered to approximately the same level as the previous year due to improvements in the second quarter. Efforts to control selling, general, and administrative expenses may also be worth monitoring as part of the company’s strategy to improve profitability. The revision of the current year’s dividend forecast could be a significant point for investors to consider regarding shareholder returns.
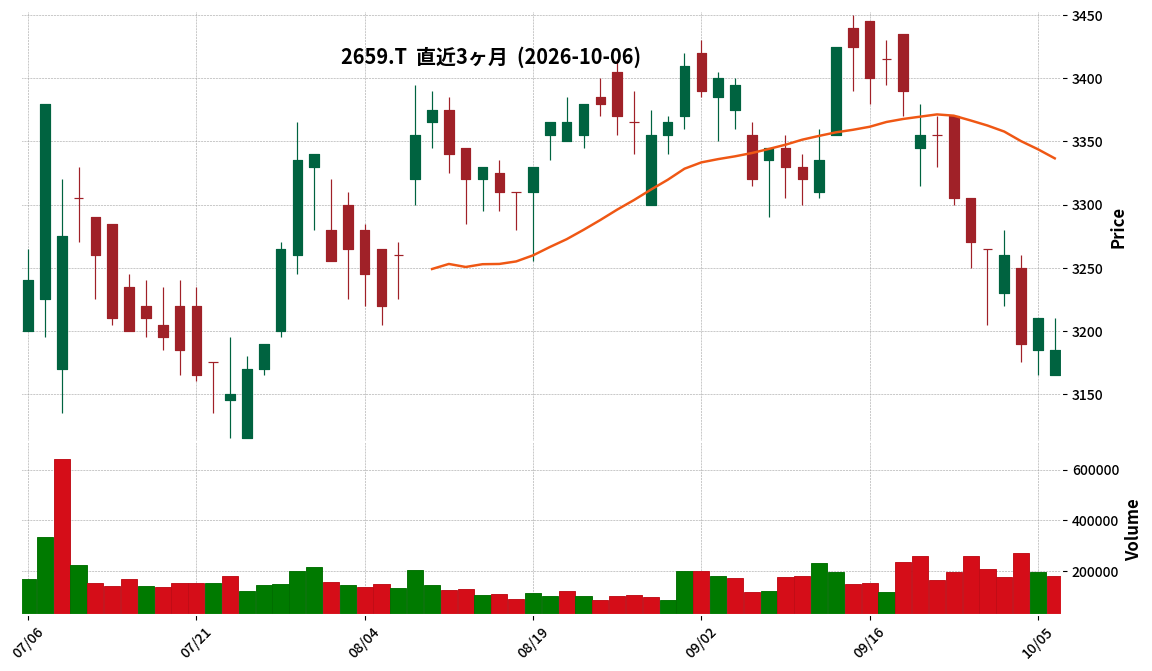
2659|サンエー
3185.0
▼ -0.78%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- San-A Co., Ltd. has announced its consolidated financial results for the second quarter (interim period) of the fiscal year ending February 2027.
- Consolidated operating revenue for the interim period reached ¥129,929 million, marking a 6.3% increase compared to the previous interim period.
- Consolidated operating profit was ¥9,849 million (up 13.1% YoY), consolidated ordinary profit was ¥10,219 million (up 12.2% YoY), and net profit attributable to owners of parent was ¥6,414 million (up 9.2% YoY).
- Interim net income per share stood at ¥105.44.
- The full-year consolidated earnings forecast and the annual dividend forecast of ¥110.00 per share remain unchanged from the most recently announced figures.
- As of the end of the interim period, consolidated total assets were ¥197,743 million, net assets were ¥151,693 million, and the equity ratio was 74.6%.
- The retail business segment reported operating revenue of ¥124,986 million (up 6.4% YoY) and segment profit of ¥8,600 million (up 14.4% YoY).
- The convenience store business segment reported operating revenue of ¥4,947 million (up 4.9% YoY) and segment profit of ¥1,248 million (up 5.3% YoY).
🤖 AI Perspective
San-A’s Q2 FY2027 results show a strong increase in both revenue and profit, with operating profit growing by double digits. This performance may suggest the positive impact of initiatives to enhance product and store appeal, alongside robust sales from existing stores. The unchanged full-year forecast could indicate that the company is progressing as planned, making its future performance worth monitoring for investors.
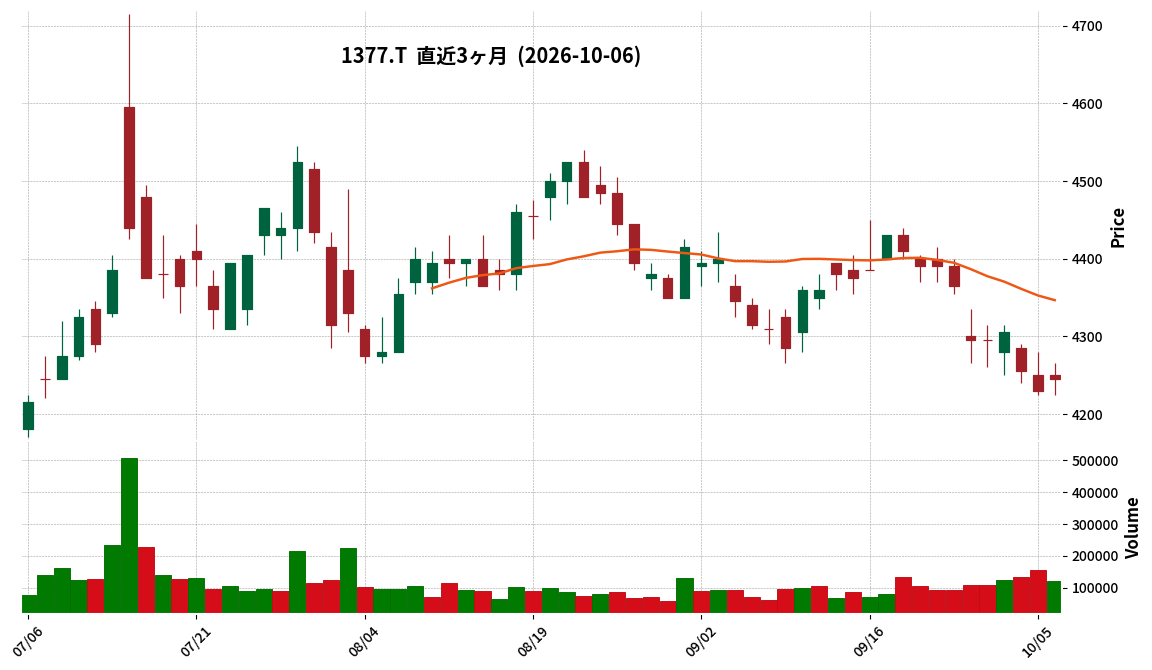
1377|サカタのタネ
4245.0
▲ +0.35%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- For the first quarter of fiscal year 2027 (June 1, 2026 – August 31, 2026), consolidated net sales increased by 7.2% year-over-year to ¥24.67 billion.
- In the same quarter, consolidated operating profit was ¥3.387 billion (down 24.1% YoY), ordinary profit was ¥3.671 billion (down 24.6% YoY), and net profit attributable to owners of parent was ¥2.239 billion (down 38.4% YoY).
- The increase in net sales was primarily due to the depreciation of the Japanese Yen, with a positive impact of ¥1.776 billion from exchange rate fluctuations.
- Factors contributing to the decrease in profits include a lower gross profit margin, increased selling, general, and administrative expenses (mainly personnel costs), increased foreign exchange losses, and the absence of settlement income recorded in the previous year.
- The domestic wholesale business recorded robust performance in vegetables (e.g., tomatoes, cabbage), materials, and flowers (e.g., pansies, violas), achieving sales of ¥4.441 billion (up 2.2% YoY) and operating profit of ¥2.453 billion (up 6.8% YoY).
🤖 AI Perspective
Sakata Seed’s Q1 results reveal a scenario where yen depreciation boosted sales, while deteriorating profitability weighed down earnings. The decline in gross profit margin and increased expenses appear to have significantly impacted profit ratios. While the domestic wholesale business performed steadily, the international wholesale business saw a local currency-based revenue decrease, which was offset by the weaker yen, suggesting underlying operational challenges that may warrant closer monitoring.
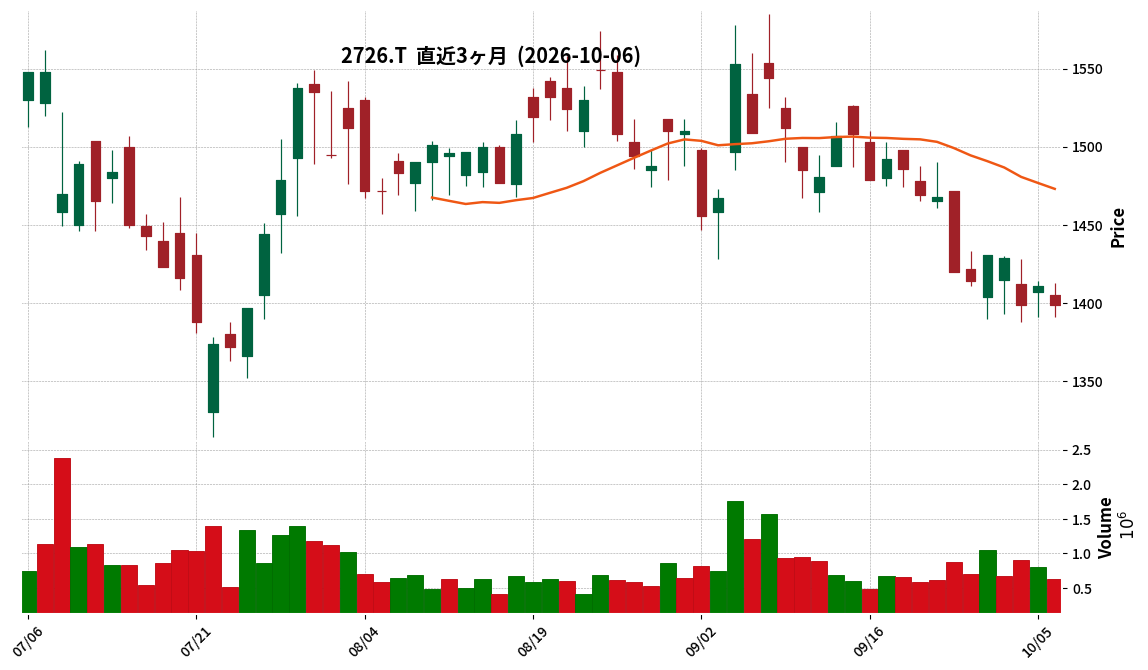
2726|パルグループHD
1399.0
▼ -0.85%
📎 Source:パルグループHD Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- PAL GROUP HOLDINGS Co., Ltd. has announced its consolidated financial results for the second quarter (interim period) of the fiscal year ending February 2027.
- Consolidated net sales totaled ¥121,931 million, representing a 4.1% increase compared to the same period of the previous fiscal year.
- Operating income was ¥14,254 million (+1.1% YoY), and ordinary income was ¥14,216 million (+1.0% YoY).
- Net income attributable to owners of the parent company amounted to ¥9,428 million, an increase of 2.6% from the prior interim period.
- Interim net income per share was ¥54.36.
- The full-year consolidated earnings forecast remains unchanged from the most recently published projections: net sales ¥253,000 million, operating income ¥29,400 million, ordinary income ¥29,400 million, net income attributable to owners of the parent company ¥19,000 million, and net income per share ¥109.80.
🤖 AI Perspective
PAL GROUP HD’s interim results show continued growth in net sales and profits, suggesting a stable performance trajectory. The recovery of in-store sales, strengthening customer base, and thorough inventory management in the apparel business may have contributed to improved gross profit margins. The unchanged full-year forecast could indicate the company’s confidence in achieving its current plans, while the decrease in operating income for the general merchandise business and its future recovery bear watching.
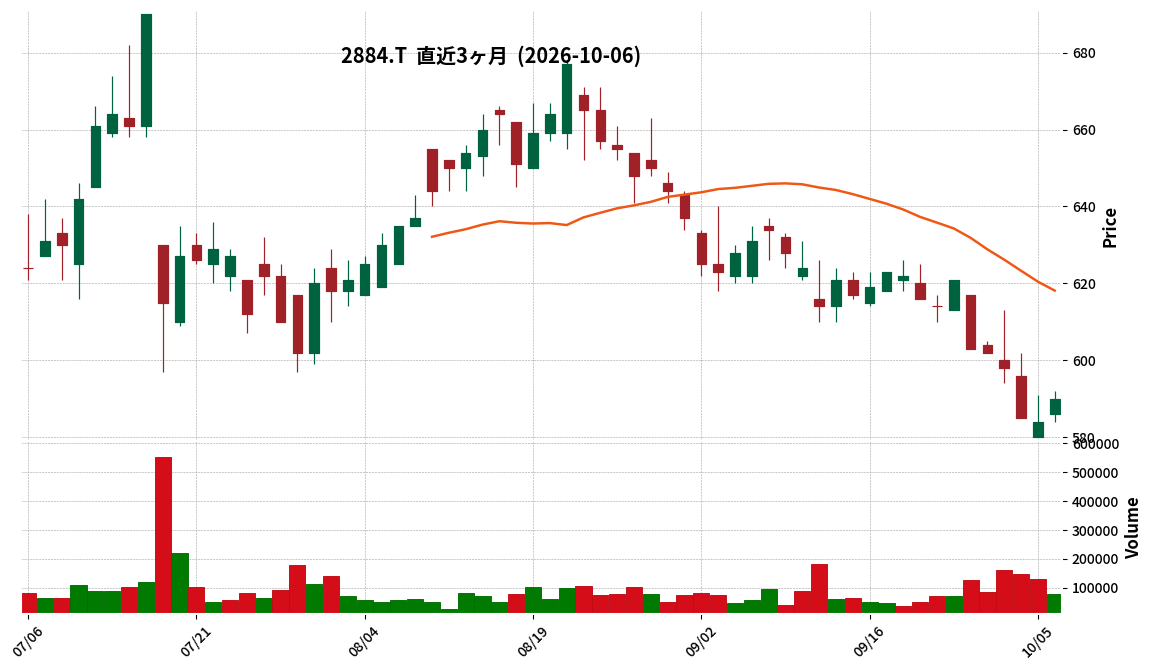
2884|ヨシムラ・F・HD
590.0
▲ +1.03%
📎 Source:ヨシムラ・F・HD Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Yoshimura F HD resolved to acquire 100% of the issued shares of Nippon Kanzume Co., Ltd., making it a subsidiary, at its Board of Directors meeting held on October 6, 2026.
- Nippon Kanzume Co., Ltd., headquartered in Memuro-cho, Hokkaido, manufactures and sells frozen vegetables, retort pouch products, etc., primarily using agricultural products from Hokkaido’s Tokachi region. It holds a high market share in the domestic frozen corn market.
- The scheduled share transfer execution date is November 1, 2026.
- Prior to this acquisition, Nippon Kanzume plans to issue one common share through a third-party allocation to Meiji Co., Ltd., to resolve its negative net worth.
- The acquisition price is undisclosed due to a confidentiality agreement with the counterparty but is considered a reasonable price based on the results of due diligence by external institutions.
🤖 AI Perspective
This acquisition appears to be part of Yoshimura F HD’s M&A strategy to strengthen its business foundation in Hokkaido and expand its agricultural product procurement and processing capabilities. Nippon Kanzume’s expertise in production and quality control, along with its long-standing relationships with contract farmers, could contribute to creating synergies across the group, potentially highlighting the importance of the Hokkaido region in the group’s future growth strategy. The impact of this subsidiarization on consolidated financial results from the fiscal year ending February 2027 onwards will be worth monitoring.
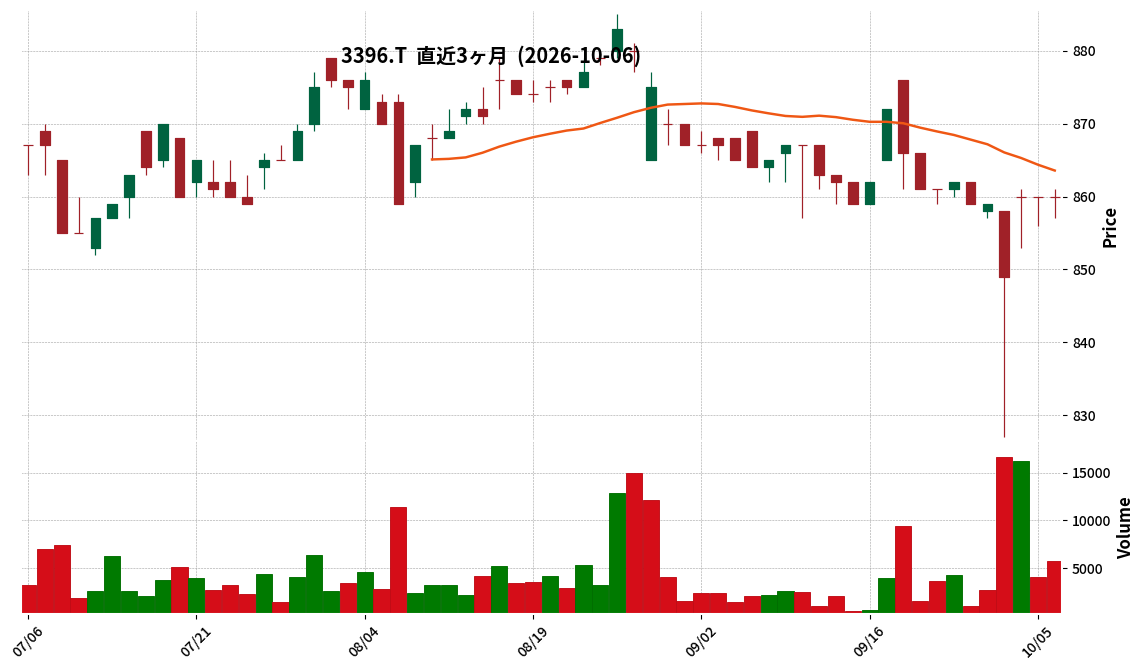
3396|フェリシモ
860.0
▲ +0.00%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Felissimo has announced its consolidated financial results for the second quarter (interim) of the fiscal year ending February 2027.
- Net sales were ¥14,147 million, representing a 0.8% decrease year-on-year. Operating profit was ¥122 million, a 39.4% decrease year-on-year.
- Ordinary profit increased by 6.1% year-on-year to ¥262 million, and net profit attributable to parent company increased by 7.0% year-on-year to ¥231 million.
- Interim net earnings per share were ¥32.43.
- The full-year consolidated earnings forecast and dividend forecast (year-end ¥25.00, total annual ¥25.00) remain unrevised from the most recently published predictions.
🤖 AI Perspective
While net sales and operating profit declined, the increase in ordinary profit and net profit attributable to the parent company, driven by non-operating income, is noteworthy. This suggests that factors such as foreign exchange gains contributed positively to overall profitability despite challenges in core business areas. Investors may want to monitor the company’s future business strategies and revenue structure for potential implications on its financial performance.
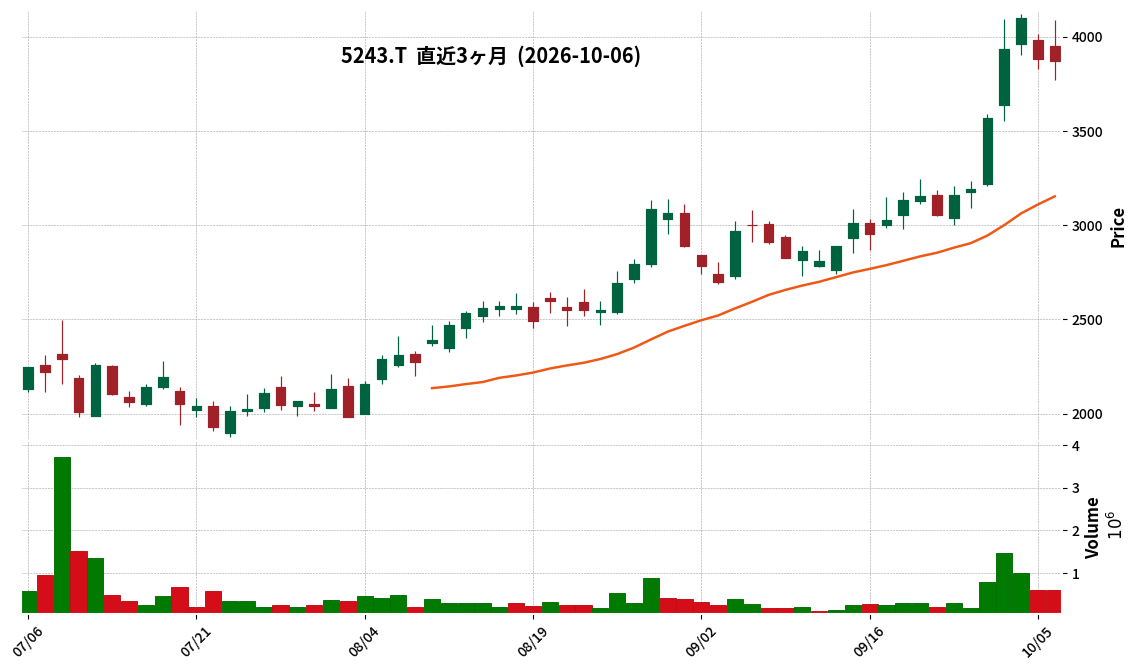
5243|G-note
3870.0
▼ -0.26%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- For the third quarter of fiscal year 2026 (December 1, 2025 – August 31, 2026), consolidated net sales totaled ¥4,058 million, an increase of 33.2% compared to the same period of the previous year.
- Net income attributable to owners of the parent for the period was ¥994 million, marking a substantial increase of 368.1% year-on-year.
- Adjusted EBITDA reached ¥923 million (up 452.0% YoY), operating profit was ¥849 million (up 567.0% YoY), and ordinary profit was ¥858 million (up 513.6% YoY).
- As of the end of Q3 FY2026, consolidated total assets stood at ¥11,455 million, net assets at ¥8,166 million, and the equity ratio at 70.6%.
- The full-year consolidated earnings forecast for FY2026 (net sales ¥5,650 million, net income attributable to owners of the parent ¥1,200 million) remains unchanged from the most recently announced figures.
🤖 AI Perspective
G-note’s Q3 FY2026 results indicate robust growth across revenue and profit metrics, with a particularly significant rise in net income. This growth may suggest a successful expansion in its core media platform business, alongside contributions from its IP and content creation business and the newly launched AI-related business. The unchanged full-year forecast could imply that the company is progressing steadily towards its initial targets.
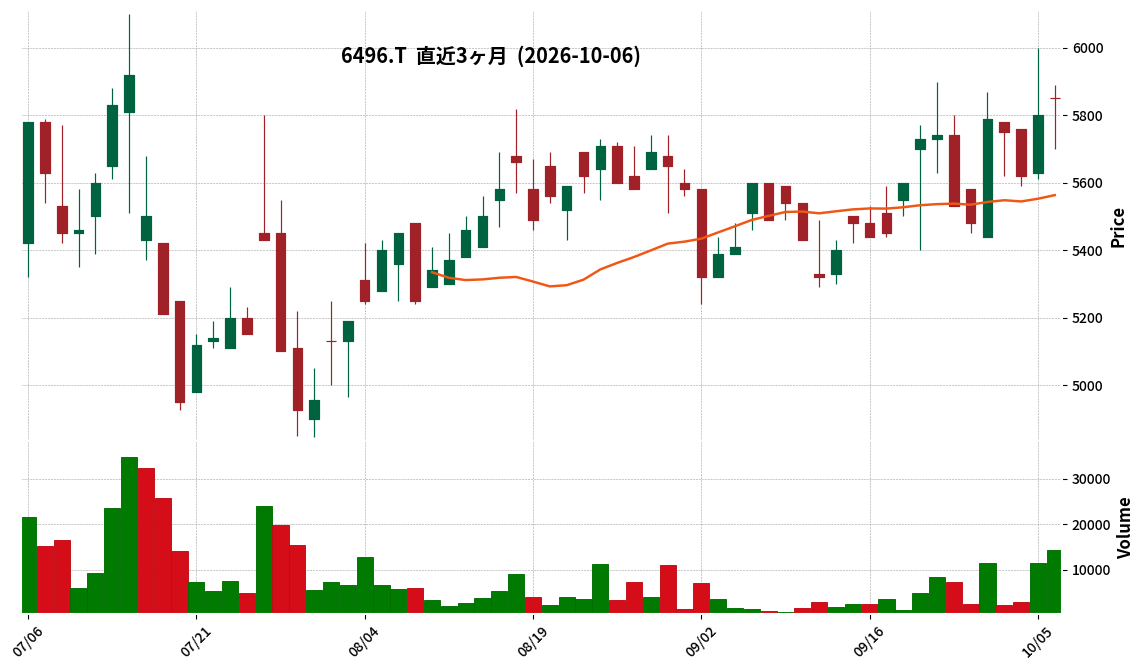
6496|中北製作所
5850.0
▲ +0.86%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Nakakita Seisakusho announced its consolidated financial results for the first quarter of the fiscal year ending May 2027 (June 1, 2026 – August 31, 2026).
- Net sales increased by 1.7% year-on-year to 7,199 million yen.
- Operating profit decreased by 34.4% to 253 million yen, ordinary profit decreased by 24.3% to 443 million yen, and profit attributable to owners of parent decreased by 34.3% to 289 million yen.
- Orders received increased by 24.6% year-on-year to 8,431 million yen, with an order backlog of 28,614 million yen at the end of the quarter.
- The full-year consolidated forecast remains unchanged, projecting net sales of 30,000 million yen (up 2.5% from previous year), operating profit of 1,450 million yen (down 7.1%), and profit attributable to owners of parent of 1,600 million yen (down 7.2%).
🤖 AI Perspective
While sales saw a slight increase, various profit metrics experienced double-digit declines compared to the prior year. This trend may suggest that despite a significant rise in orders received, driven by improved demand in the shipbuilding industry and power plant projects for data centers, factors such as a decrease in export-related sales or other pressures on profit margins could have influenced the results. With the full-year forecast unchanged, investors will likely be monitoring subsequent quarters for further developments.
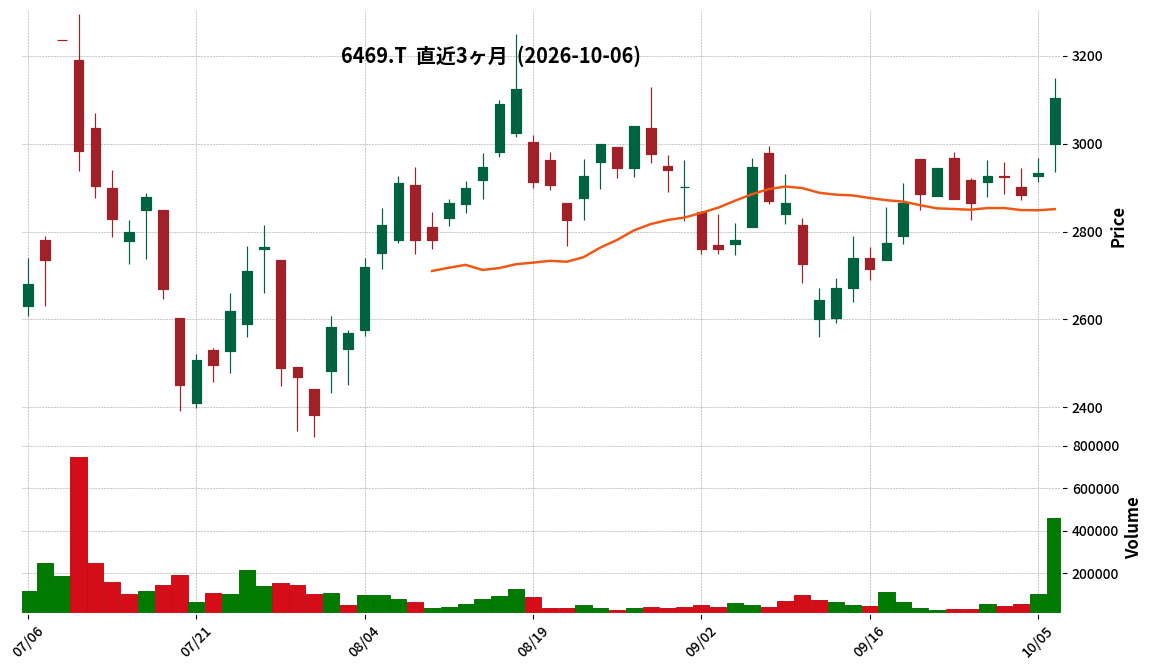
6469|放電精密
3105.0
▲ +5.83%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Hoden Seimitsu Works, Ltd. announced a discrepancy between its actual consolidated financial results for the second quarter of the fiscal year ending February 2027 and the forecast published on July 7, 2026.
- For Q2, actual consolidated results were: Net Sales ¥8,636 million (0.3% above forecast), Operating Income ¥1,132 million (39.6% above forecast), Ordinary Income ¥1,076 million (43.5% above forecast), and Net Income Attributable to Owners of Parent ¥732 million (47.1% above forecast).
- The variance was primarily attributed to increased revenue in the Dies & Molds segment and Electrical Discharge Machining & Surface Treatment segment, profit increase in the Machine Equipment segment, and reduced company-wide expenses.
- The consolidated full-year forecast for the fiscal year ending February 2027 has also been revised upward, with projected Net Sales of ¥17,067 million, Operating Income of ¥1,832 million, Ordinary Income of ¥1,715 million, and Net Income Attributable to Owners of Parent of ¥1,151 million.
- The year-end dividend forecast has been revised upward from the previous forecast of ¥20 per share to ¥25 per share.
🤖 AI Perspective
This announcement indicates that Hoden Seimitsu has performed better than its initial business plan in the interim period, leading to an improved full-year outlook. The significant positive deviation in operating income could suggest effective business operations and cost management contributing to profitability. The increased dividend forecast may reflect management’s confidence in the company’s robust performance and future prospects.
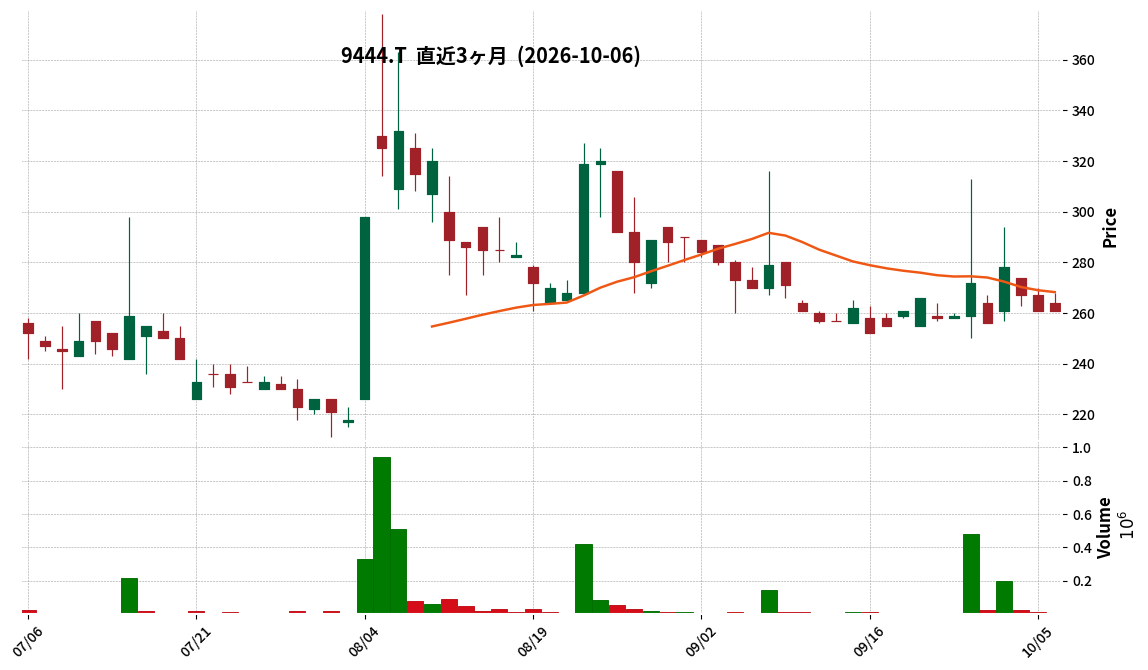
9444|トーシンHD
261.0
▲ +0.00%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Toshin HD announced its Q1 FY2026 consolidated financial results for the period from May 9, 2026, to August 8, 2026.
- Consolidated performance (cumulative) reported sales of ¥3,032 million, an operating loss of ¥81 million, an ordinary loss of ¥600 million, and a net loss attributable to parent company shareholders of ¥591 million.
- Compared to the prior year (FY22026), sales increased from ¥340 million to ¥3,032 million; however, the operating loss widened from ¥-48 million to ¥-81 million, ordinary loss from ¥-232 million to ¥-600 million, and net loss attributable to parent from ¥-236 million to ¥-591 million.
- In terms of consolidated financial position, total assets stood at ¥20,258 million (down from ¥20,966 million at the previous fiscal year-end), net assets at ¥301 million (down from ¥893 million), and the equity ratio decreased to 1.2% (from 3.9%).
- The company filed for corporate rehabilitation proceedings with the Tokyo District Court on May 8, 2026, and a commencement order was issued on the same day, resulting in no dividend distribution.
🤖 AI Perspective
Toshin HD’s first-quarter results show a significant increase in losses despite higher sales, highlighting ongoing challenges in profitability. The decrease in total assets, net assets, and the equity ratio reflects the severe financial conditions under corporate rehabilitation proceedings. These financial trends may suggest the continued difficulties in its business operations and are worth monitoring for insights into the progress of its corporate restructuring plan.
Disclaimer: This article is for informational purposes only and does not constitute investment advice.
2734|サーラ
1165.0
▼ -0.26%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
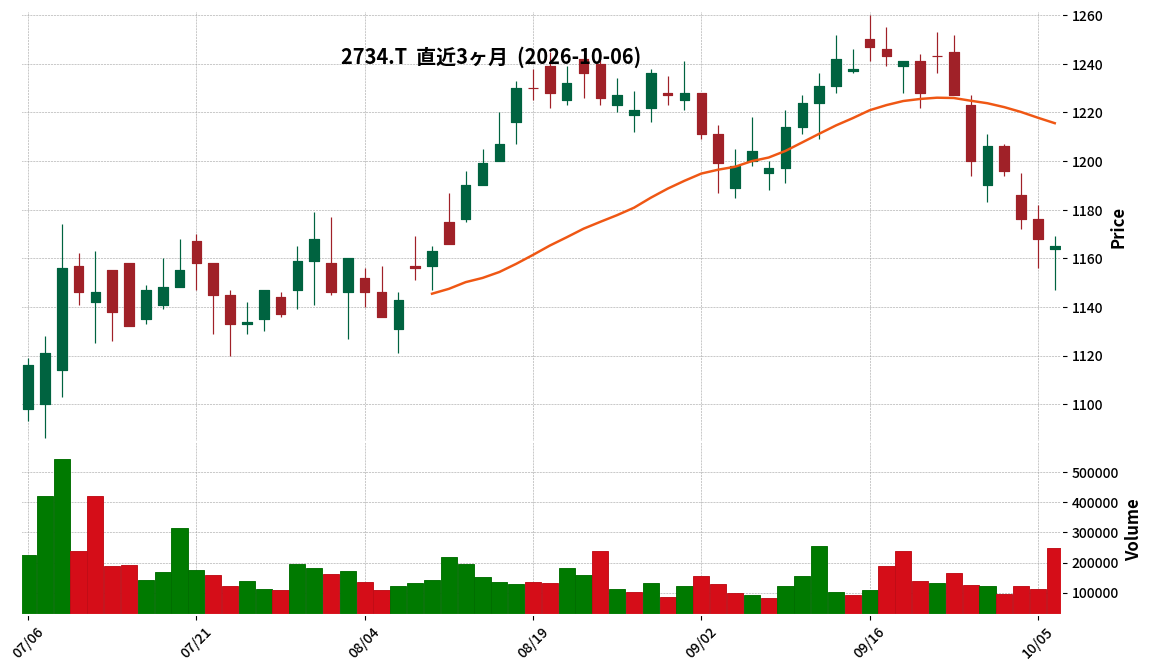
- For the cumulative nine-month period ended August 31, 2026, Sala Corporation reported consolidated net sales of 193,460 million yen, an increase of 3.5% year-on-year.
- During the same period, operating profit rose by 34.1% to 8,168 million yen, ordinary profit increased by 32.1% to 9,599 million yen, and profit attributable to owners of parent grew by 25.5% to 6,318 million yen.
- By segment, the Engineering & Maintenance business saw sales increase by 9.6% to 28,160 million yen, and the Housing business recorded a 12.7% increase in sales to 35,039 million yen.
- The full-year consolidated earnings forecast for the fiscal year ending November 2026 and the annual dividend forecast (year-end 18.00 yen, total 34.00 yen) remain unchanged from the most recently published figures.
- Share repurchases, with a ceiling of 2,000 thousand shares (3,000 million yen), have completed 1,550 thousand shares (77.75% progress) amounting to 1,695 million yen (56.50% progress) as of August 31, 2026.
🤖 AI Perspective
Sala Corporation’s Q3 FY2026 results show solid growth in both revenue and profit, with operating profit increasing by a notable 34.1%. This performance was reportedly driven by strong contributions from the Engineering & Maintenance and Housing segments, alongside an increase in derivative valuation gains from foreign exchange forward contracts. The company’s decision to maintain its full-year earnings forecast suggests that current progress aligns with its internal projections. Additionally, the ongoing share repurchase program could be viewed by investors as a positive move towards enhancing shareholder returns and capital efficiency.
4477|G-BASE
378.0
▼ -6.44%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- G-BASE announced a partial amendment to its statement of opinion regarding the tender offer for its shares by SBINM Godo Kaisha.
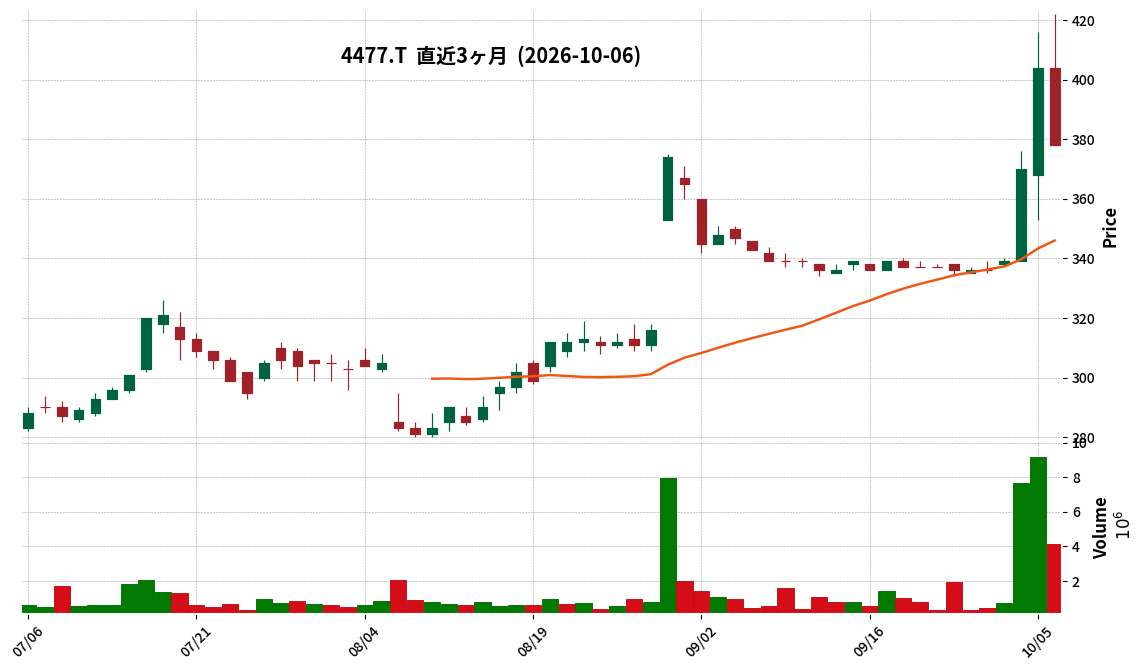
- The amendment primarily concerns the re-extension of the tender offer period, which was originally until October 15, 2026, and is now extended until October 21, 2026 (totaling 34 business days).
- The reason for the extension is attributed to SBINM Godo Kaisha receiving notification on October 1, 2026, from G-BASE’s major shareholder, Mr. Hiroyuki Maki, stating his intent to resume purchasing G-BASE shares to achieve over a 30% holding ratio.
- The tender offer price remains ¥340 per common share, with no change.
- G-BASE reiterated its endorsement of the tender offer and its stance to leave the decision of whether to tender shares to its shareholders.
🤖 AI Perspective
The re-extension of the tender offer period for G-BASE shares by SBINM Godo Kaisha is noted to be influenced by a major shareholder’s expressed intent to acquire more shares. This development suggests a potentially evolving situation around G-BASE’s ownership structure, providing shareholders with an extended window to evaluate their participation. The unchanged offer price and other terms may be key considerations for investors.
Disclaimer: This article is for informational purposes only and does not constitute investment advice.
2929|ファーマフーズ
683.0
▼ -0.73%
📎 Source:ファーマフーズ Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
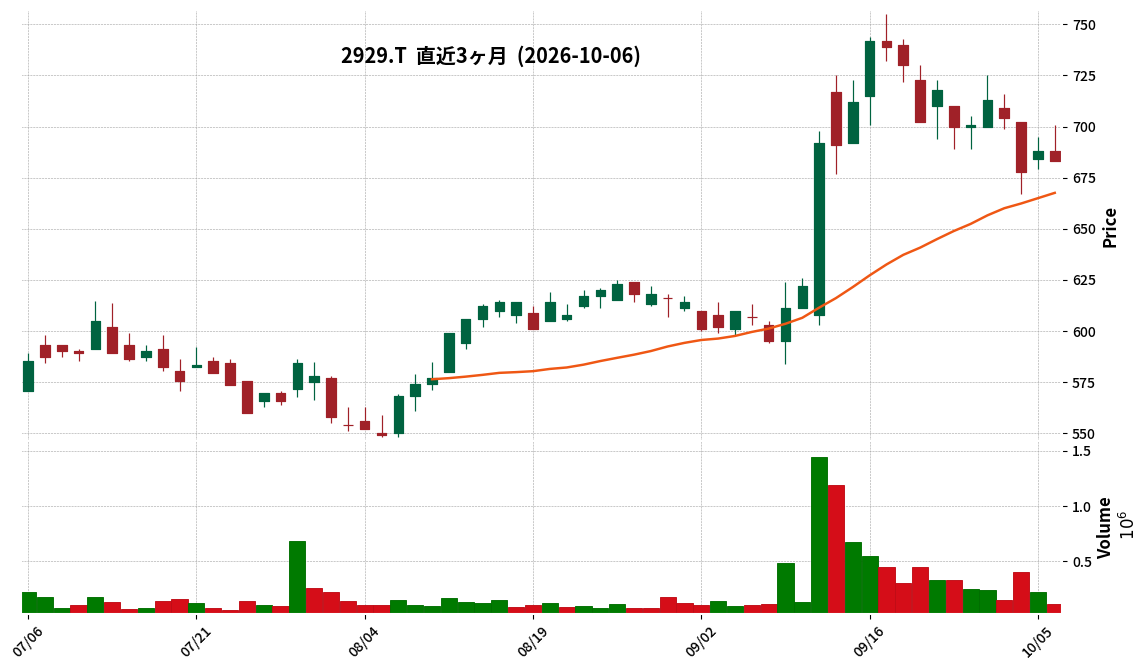
- Pharma Foods Co., Ltd. resolved to acquire all shares of Marine Pro Foods Co., Ltd., making it a subsidiary, at a board meeting held on October 6, 2026.
- Marine Pro Foods specializes in the B2B “Medical Foods Business,” planning and selling processed marine products, processed soy products, and processed agricultural products to hospitals, nursing homes, and school lunch providers.
- The acquisition price for Marine Pro Foods’ common shares is ¥5,030 million, representing 124,600 shares and a 100% voting rights ownership.
- The scheduled share transfer execution date is October 30, 2026.
- For the fiscal year ended March 2026, Marine Pro Foods reported sales of ¥9,475 million, operating profit of ¥542 million, and net profit of ¥268 million.
🤖 AI Perspective
This acquisition appears to be a strategic move to merge Pharma Foods’ functional food ingredients with Marine Pro Foods’ medical food business, aiming to create new products with enhanced health value. The expansion is anticipated to strengthen the B2B market presence and open new B2C channels through large supermarkets and convenience stores, potentially broadening the company’s business scope and sales network. The impact on consolidated financial results is currently under review, and further disclosures will be worth monitoring.
3498|霞ヶ関キャピタル
7080.0
▼ -4.45%
📎 Source:霞ヶ関キャピタル Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
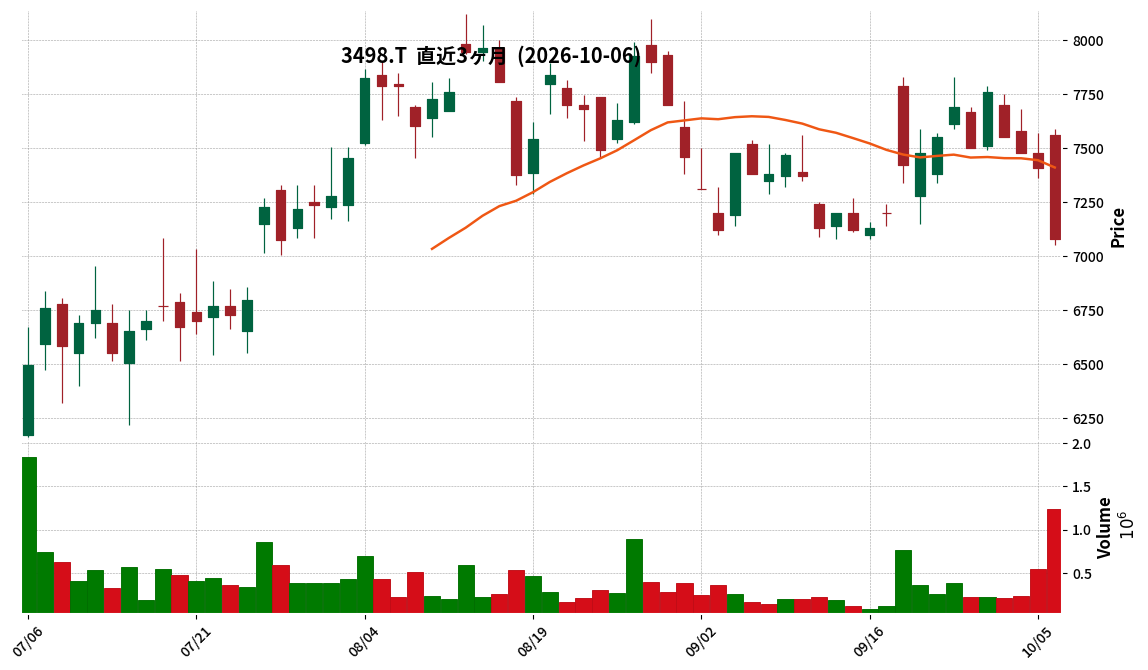
- Kasumigaseki Capital achieved a net income of ¥16.6 billion for the fiscal year ended August 2026.
- The company forecasts a net income of ¥24.0 billion for the fiscal year ending August 2027.
- A dividend of ¥165 per share for FY2026 is planned, with a proposed increase to ¥200 per share for FY2027.
- The total scale of AUM (Assets Under Management) + pipeline projects surpassed ¥1.2 trillion, representing an increase of ¥554.4 billion (84%) from the previous fiscal year-end.
- A Return on Equity (ROE) target of at least 25% and a goal of 30% have been set for the fiscal year ending August 2029.
🤖 AI Perspective
Kasumigaseki Capital’s FY2026 results indicate solid progress in its medium-term management plan. The achievement of current net income targets, coupled with a significant increase in the next fiscal year’s forecast and an elevated ROE target, may suggest the company’s confidence in its future growth strategy. The expansion of AUM and pipeline, alongside the planned dividend increase, could be key factors for investors to monitor.
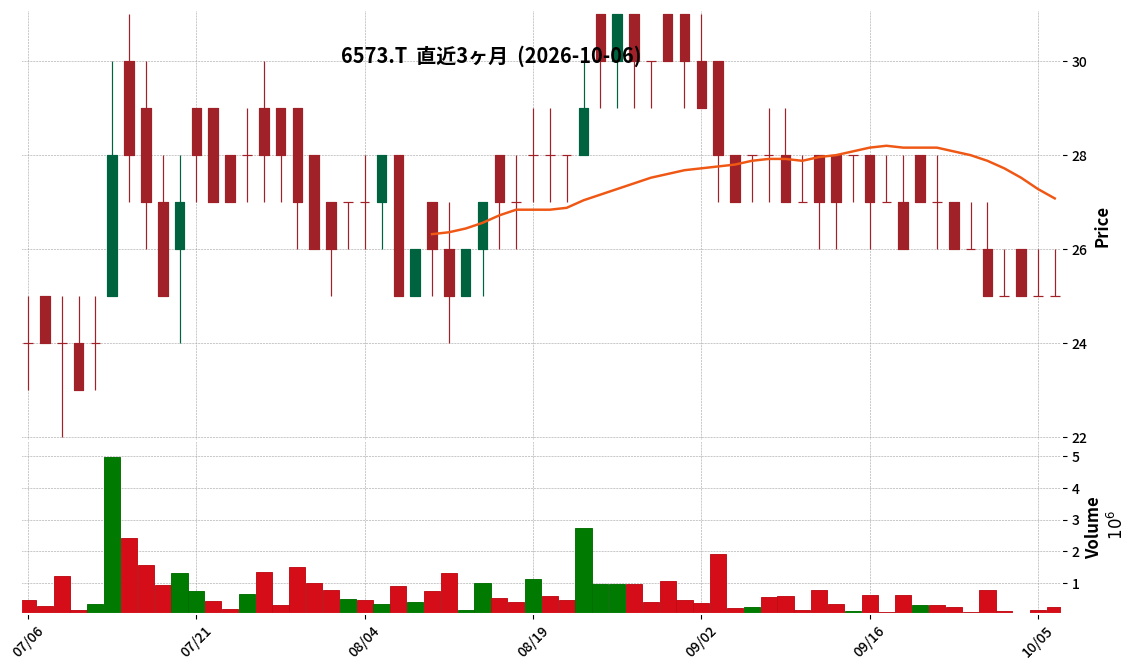
6573|G-CRAVIA
25.0
▲ +0.00%
📎 Source:G-CRAVIA Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- G-CRAVIA resolved at its board meeting to enter into a capital and business alliance with Redstart ENM Inc. of South Korea.
- G-CRAVIA will acquire 100,000 shares (50.0% voting rights) of Redstart ENM Inc. for KRW 50,000 (approx. JPY 5,000), making it an equity method affiliate.
- G-CRAVIA will provide Redstart ENM Inc. with working capital through a loan agreement, with a maximum total of KRW 1,500,000,000 (approx. JPY 165 million). The loan will be disbursed in three installments, with the first installment being KRW 500,000,000 (approx. JPY 55 million) at an annual interest rate of 6%, with principal repaid over 36 installments.
- G-CRAVIA plans to dispatch two directors to Redstart ENM Inc.
- Financial due diligence confirmed that Redstart ENM Inc. was in a state of insolvency as of December 31, 2025.
🤖 AI Perspective
This alliance may suggest G-CRAVIA’s strategic move to fully enter the K-POP related business and diversify its revenue streams. The objective appears to be creating new business opportunities by combining Redstart ENM’s artists and content with G-CRAVIA’s marketing and distribution networks in Japan. However, investors might also note Redstart ENM’s insolvency status and the measures taken to secure the loan repayment, including personal guarantees.
💡 Start investing with IR insights


※ 本ページには広告が含まれます(PR)
Disclaimer: This article is for informational purposes only and does not constitute investment advice. All investment decisions are at your own risk.
コメント