📌 Today’s Highlights
Today we cover 54 IR announcements. Notable among them: 杉本商事 (9932), ヒューリック (3003), コニシ (4956). Use the table of contents below to navigate to each company.
- 4613|関ペイント
- 9932|杉本商事
- 3003|ヒューリック
- 4956|コニシ
- 5834|G-SBIリーシング
- 6754|アンリツ
- 7793|G-イメージマジック
- 8628|松井証
- 8595|JAFCO
- 8914|エリアリンク
- 9245|G-リベロ
- 1934|ユアテック
- 3778|さくらインターネット
- 8218|コメリ
- 1930|北陸電工
- 2737|トーメンデバ
- 6023|ダイハツインフィ
- 9115|明海グループ
- 9979|大庄
- 6470|大豊工業
- 8524|北洋銀行
- 5992|中央発条
- 5659|日精線
- 7276|小糸製
- 7283|愛三工
- 8095|アステナHD
- 3839|ODK
- 155A|G-情報戦略
- 162A|AIセレクトETN
- 2136|ヒップ
- 2359|コア
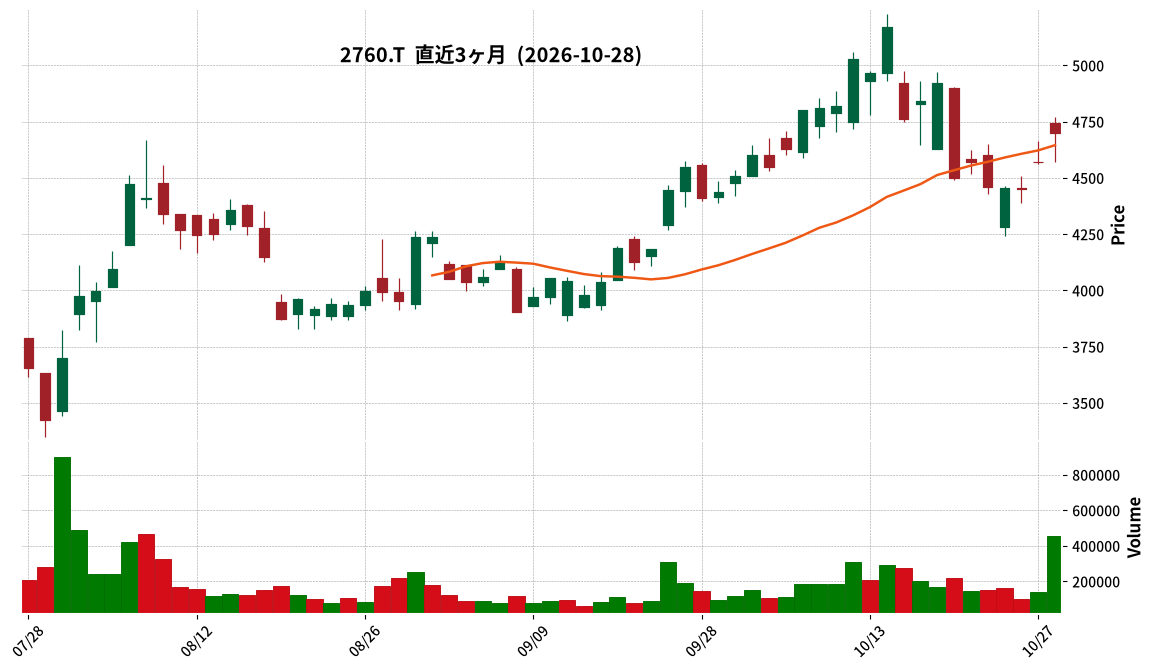
- 2760|東エレデバ
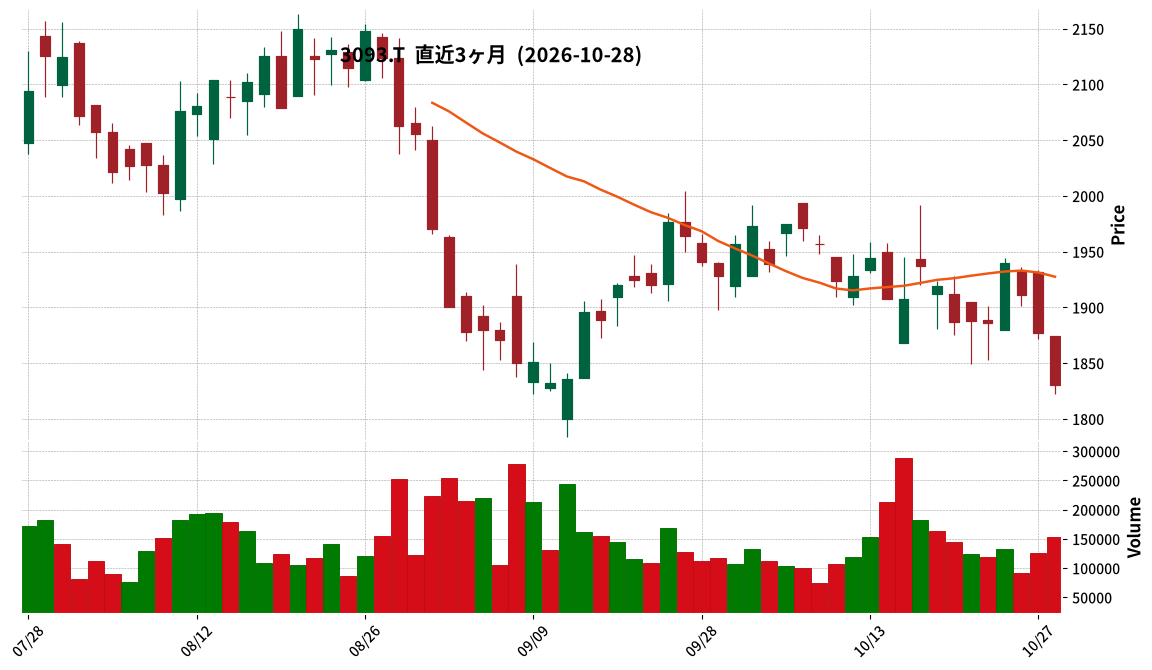
- 3093|トレファク
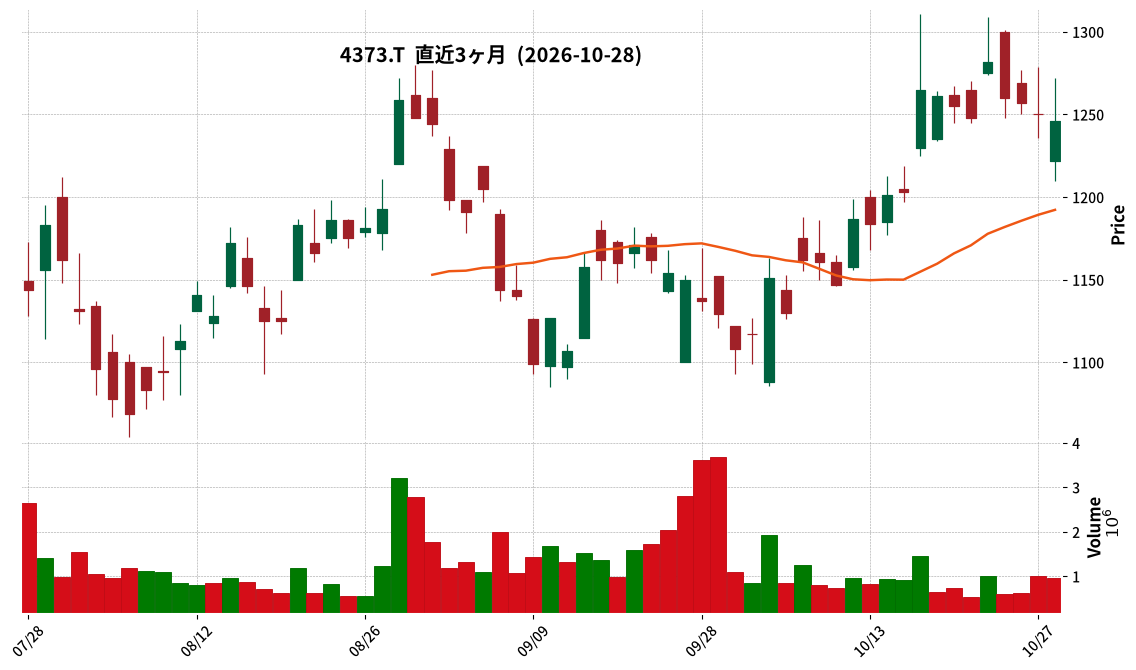
- 4373|シンプレクスHD
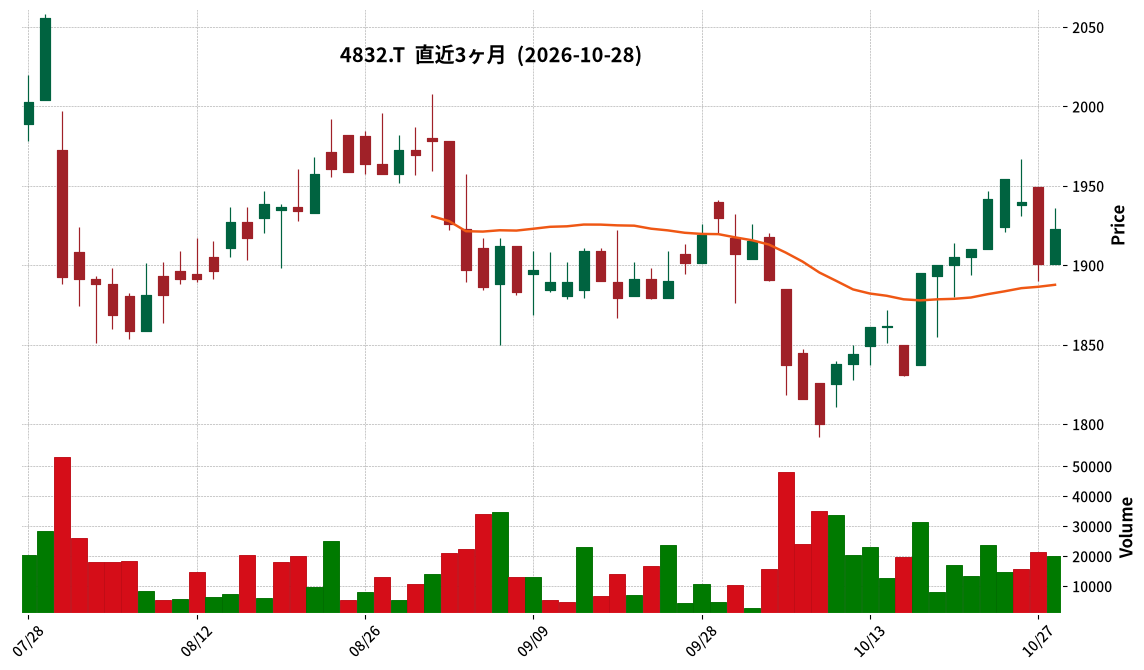
- 4832|JFE-SI
- 6501|日立
- 6573|G-CRAVIA
- 6701|NEC
- 6857|アドバンテス
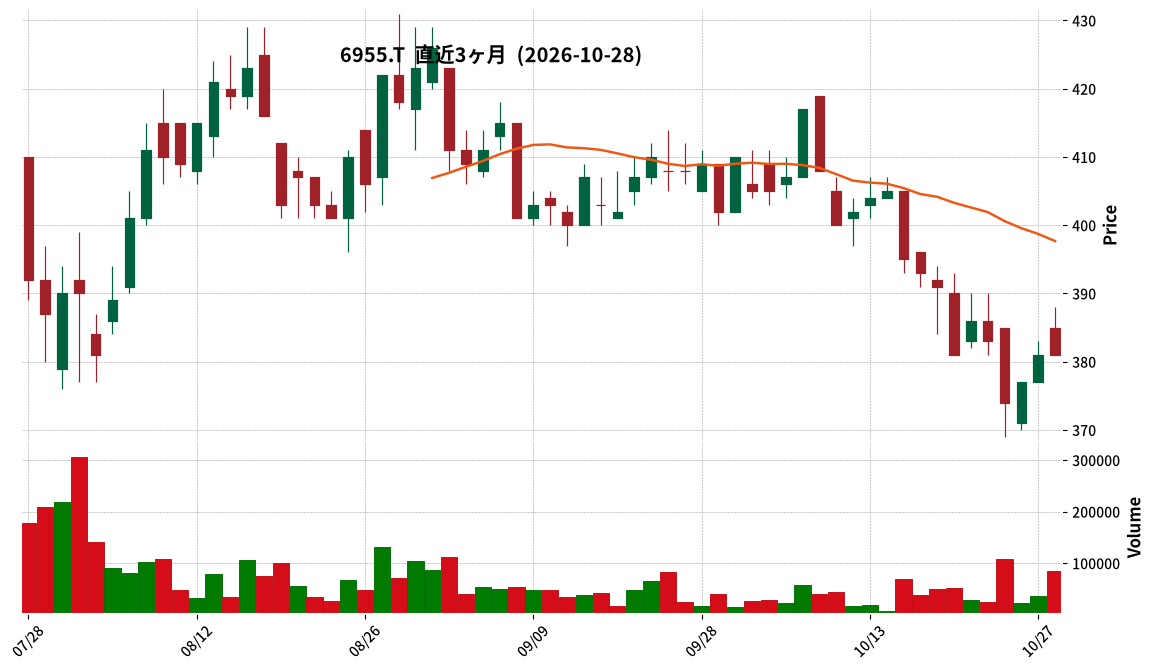
- 6955|FDK
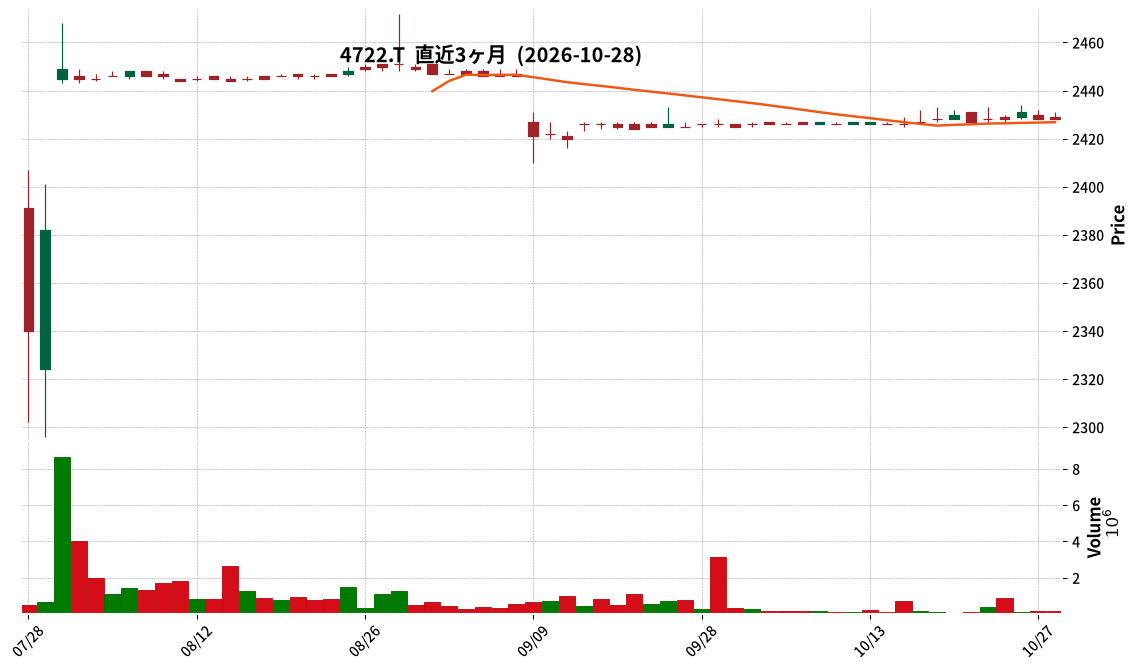
- 4722|フューチャー
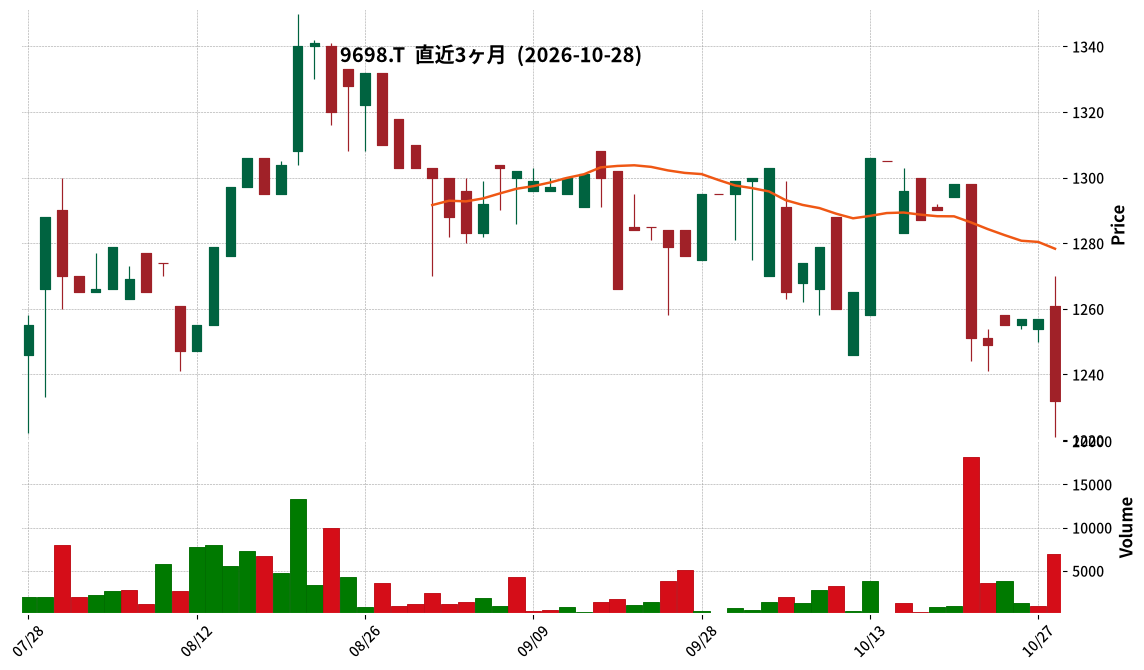
- 9698|クレオ
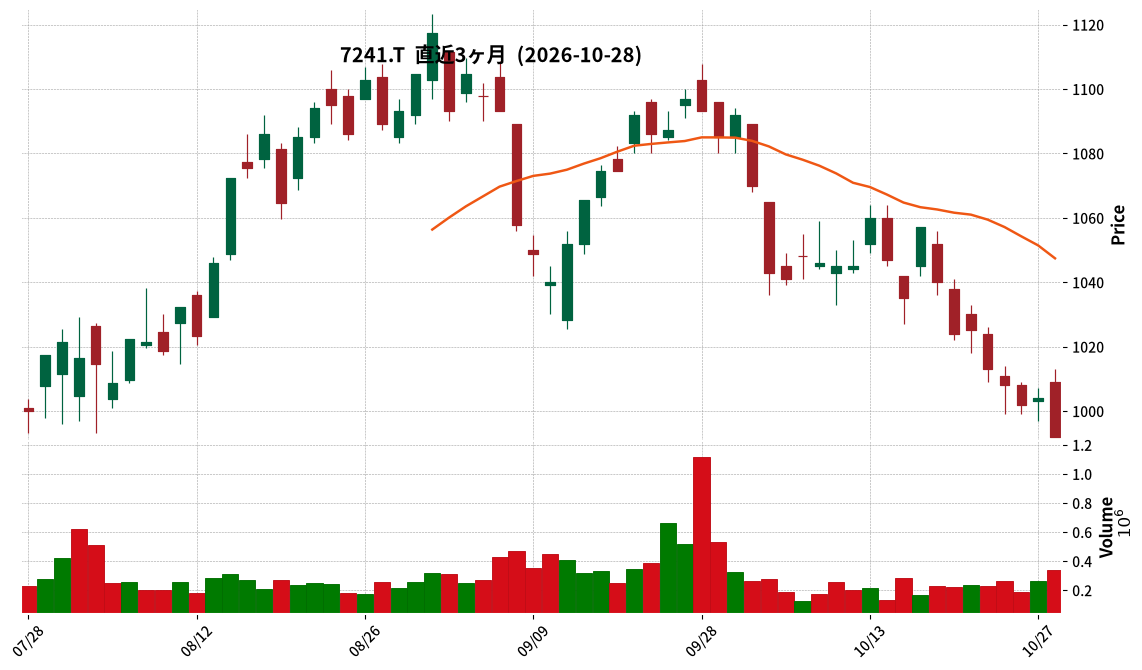
- 7241|フタバ産
- 9360|鈴与シンワ
- 3234|R-森ヒルズ
- 9307|杉村倉庫
- 2031|ハンセンブル
- 274A|ガーデン
- 284A|P-フクヤ建設
- 3189|ANAP
- 3843|フリービット
- 428A|サイプレスHD
- 8098|稲畑産
- 4446|Link-Uグループ
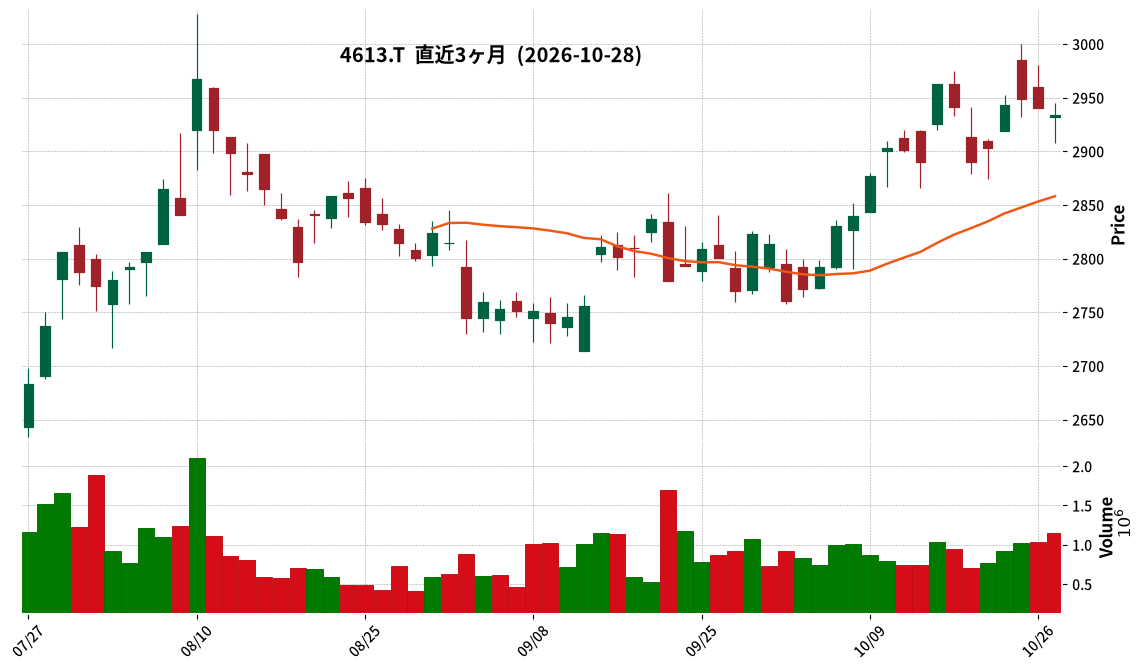
4613|関ペイント
2933.5
▼ -0.22%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Kansai Paint Co., Ltd. has completed the acquisition of additional shares in its equity-method affiliate in Turkey, Polisan Kansai Boya Sanayi ve Ticaret A.Ş. (PKB).
- All related procedures for this share acquisition were finalized as of October 27, 2026.
- The acquisition cost amounted to 93 million US dollars.
- Prior to this acquisition, Kansai Paint held a 50.0% voting rights ratio, which has now increased to 100.0% post-acquisition.
- Kansai Paint expects to record a gain on step acquisition as extraordinary income in its consolidated financial results for the fiscal year ending March 2027, due to this share acquisition.
- Following the completion of this transaction, Kansai Paint plans to promptly execute a capital increase for PKB, aimed at repaying PKB’s existing interest-bearing debt.
🤖 AI Perspective
This consolidation of PKB as a subsidiary marks a strategic step for Kansai Paint to strengthen its business operations in Turkey, potentially enhancing its global market presence. The full consolidation means PKB’s financial results will now be fully reflected in Kansai Paint’s consolidated statements, which could have a notable impact on the parent company’s revenue and profit structure. Investors may wish to monitor the specifics of the gain on step acquisition and its overall effect on consolidated performance, as detailed figures are yet to be disclosed.
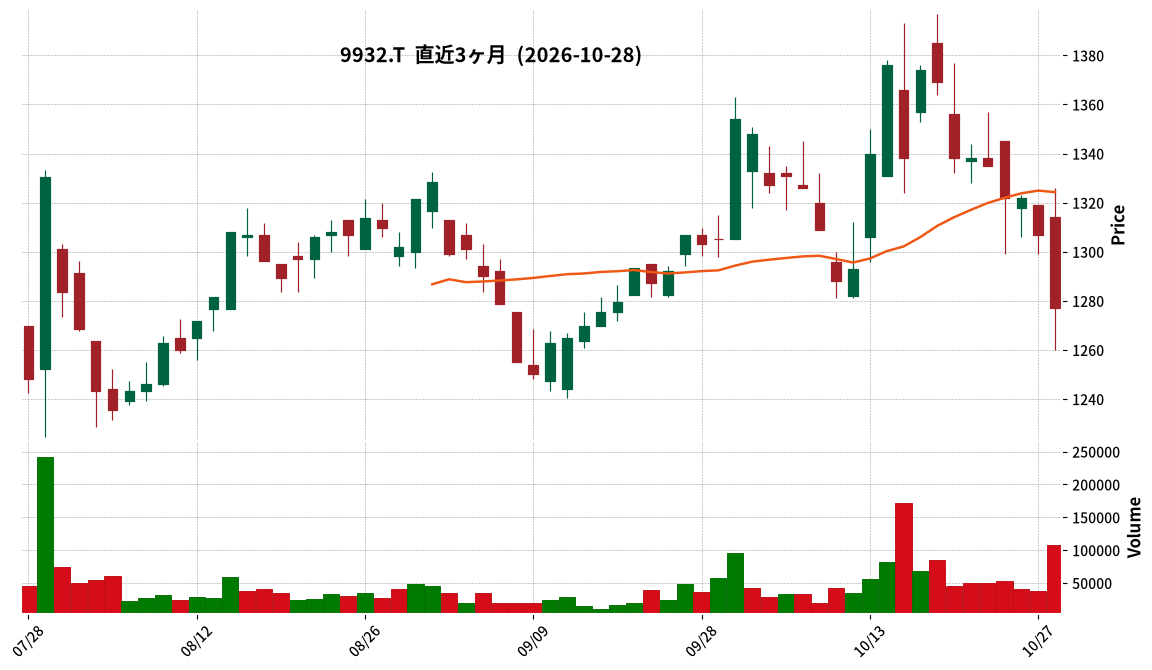
9932|杉本商事
1277.0
▼ -2.30%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Sugimoto Shoji Co., Ltd. announced its consolidated financial results for the second quarter (interim period) of the fiscal year ending March 2027 on October 28, 2026.
- For the interim period, consolidated operating results showed net sales of JPY 24,990 million (up 9.7% year-on-year), operating profit of JPY 1,023 million (up 56.9% year-on-year), ordinary profit of JPY 1,311 million (up 44.8% year-on-year), and net income attributable to owners of parent of JPY 840 million (up 27.6% year-on-year).
- Diluted earnings per share for the interim period were JPY 48.11 (compared to JPY 35.60 in the prior year’s interim period).
- The consolidated financial position reported total assets of JPY 44,426 million, net assets of JPY 35,420 million, and an equity ratio of 79.7%.
- The annual dividend forecast remains unchanged, with an interim dividend of JPY 27.00 and a year-end dividend of JPY 27.00, totaling JPY 54.00 per share.
- The full-year consolidated earnings forecast for the fiscal year ending March 2027 is maintained at net sales of JPY 51,100 million (up 5.1% year-on-year), operating profit of JPY 2,070 million (up 1.1% year-on-year), and net income attributable to owners of parent of JPY 1,736 million (down 17.8% year-on-year), with earnings per share of JPY 99.32.
🤖 AI Perspective
Sugimoto Shoji’s interim results demonstrate robust performance with significant year-on-year increases across key revenue and profit metrics. The substantial growth in operating profit, exceeding 50%, is a notable highlight. However, the full-year net income forecast projects a decrease compared to the previous year, which may indicate anticipated challenges or different factors influencing the second half of the fiscal year.
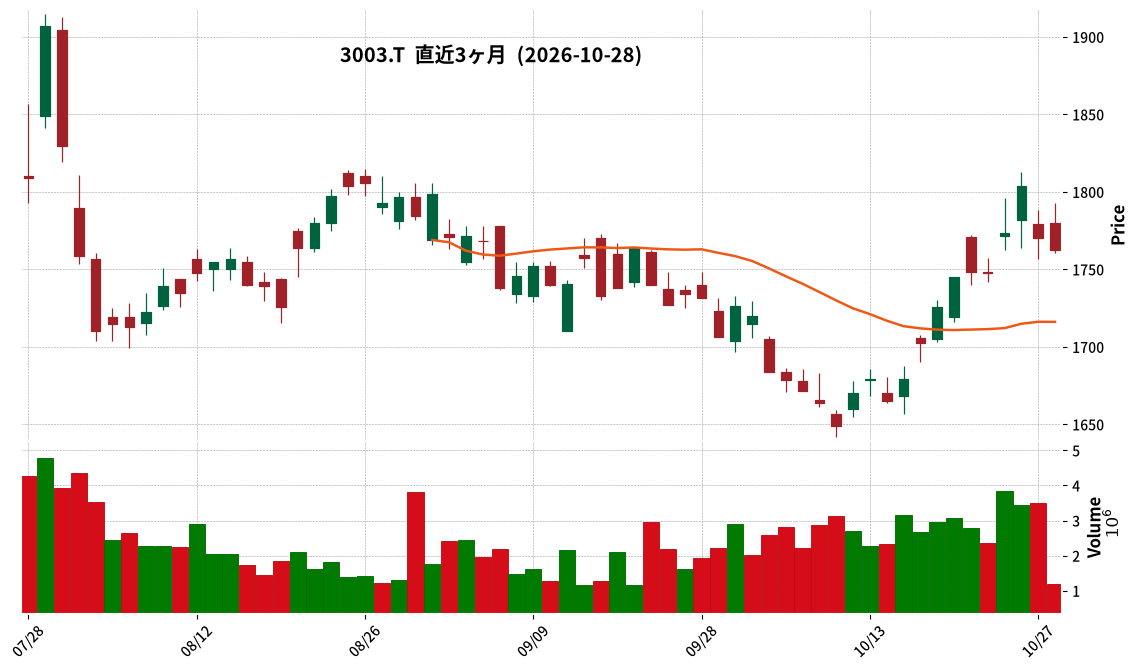
3003|ヒューリック
1762.5
▼ -0.42%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Hulic Co., Ltd. reported consolidated net sales of ¥574,725 million for the third quarter of the fiscal year ending December 2026, marking a 35.4% increase year-on-year.
- Operating profit reached ¥120,503 million (up 13.2% year-on-year), and ordinary profit was ¥101,098 million (up 10.4% year-on-year).
- Net profit attributable to owners of parent increased by 14.5% year-on-year to ¥69,470 million.
- Earnings per share for the third quarter were ¥91.48, compared to ¥79.79 in the prior year’s period.
- Revisions to the full-year consolidated earnings forecast and dividend forecast were announced, with details provided in the “Notice Regarding Revisions to Full-Year Earnings Forecast and Dividend Forecast” issued today (October 28, 2026).
- The annual dividend forecast for FY2026 (expected) has been revised to ¥70.00, up from the actual dividend of ¥62.00 in FY2025.
- Significant changes in the scope of consolidation include the addition of 4 new companies (Hamakaze Property LLC, HistoRy LLC, SaloWin Co., Ltd., Tokyo Kyoiku Ken Co., Ltd.) and the exclusion of 2 companies (Shobu Property LLC, Hulic Biz Frontier Co., Ltd.).
🤖 AI Perspective
Hulic’s Q3 FY2206 results show significant growth across key financial metrics, with net sales and net profit attributable to owners of parent increasing substantially year-over-year. The announced revisions to the full-year earnings and dividend forecasts, as detailed in the separate release, will be a key point of interest for investors. This performance may suggest a strong operational quarter, and the updated guidance will provide further context for future expectations.
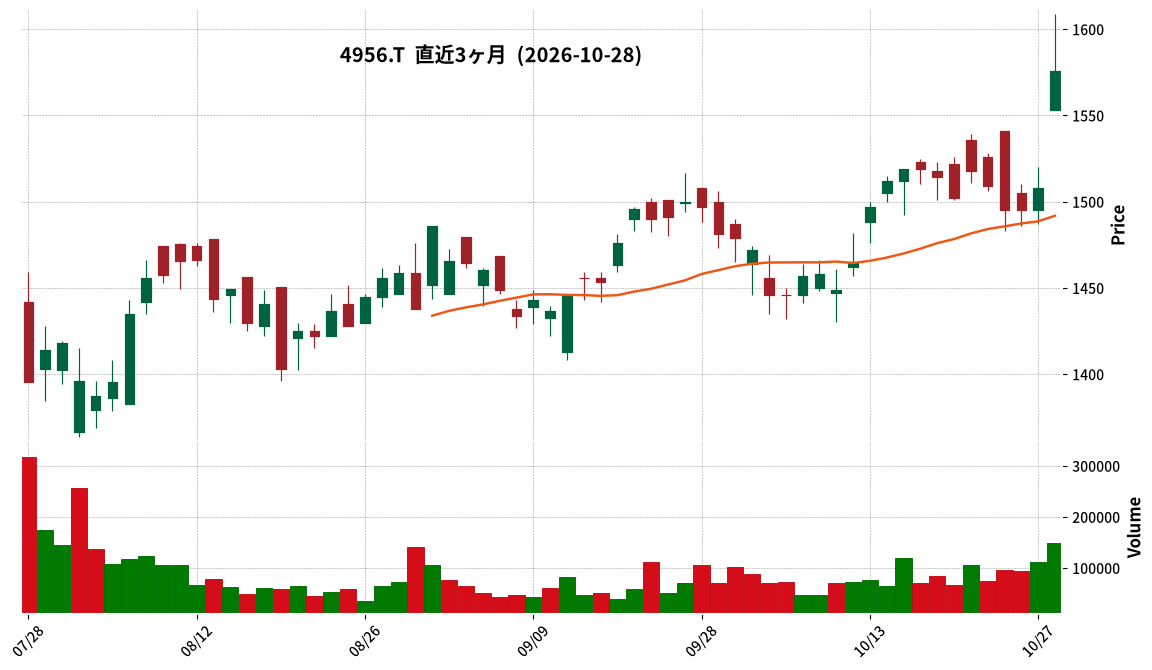
4956|コニシ
1576.0
▲ +4.51%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Konishi announced on October 28, 2026, an upward revision to its consolidated earnings forecast for the second quarter (interim period) and the full fiscal year ending March 2027.
- For the second quarter of FY2027, actual results were: Net Sales of ¥73,768 million (up 2.5% from previous forecast), Operating Profit of ¥7,358 million (up 37.5%), Ordinary Profit of ¥7,750 million (up 38.4%), and Net Income Attributable to Parent Company Shareholders of ¥5,175 million (up 54.5%).
- The full-year consolidated earnings forecast for FY2027 was revised to: Net Sales of ¥150,000 million (unchanged from previous forecast), Operating Profit of ¥14,000 million (up 21.7%), Ordinary Profit of ¥14,700 million (up 23.5%), and Net Income Attributable to Parent Company Shareholders of ¥9,500 million (up 16.0%).
- Reasons cited for the revision include favorable sales performance due to price revisions in response to rising raw material prices (driven by heightened tensions in the Middle East) and stable supply of most products achieved by adjusting shipments to prevent product shortages caused by raw material scarcity.
- The year-end dividend forecast is maintained at ¥19 per share at the current time.
🤖 AI Perspective
This upward revision suggests that the implementation of price revisions and the stability of the supply system significantly contributed to the interim period’s performance. The substantial increase in the full-year profit forecast could indicate a certain level of confidence in future business conditions. While the full-year sales forecast remains unchanged, investor focus may turn to whether factors contributing to improved profit margins will continue.
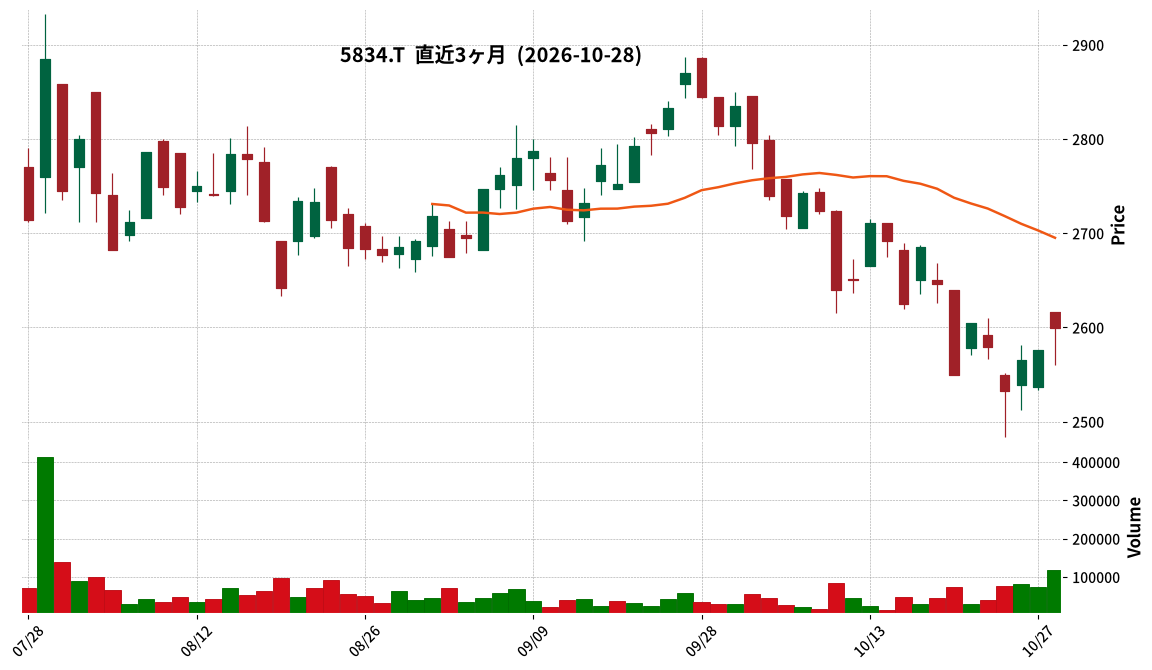
5834|G-SBIリーシング
2599.0
▲ +0.89%
📎 Source:G-SBIリーシング Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- G-SBI Leasing announced its consolidated financial results for the second quarter (interim) of the fiscal year ending March 2027.
- Revenue reached ¥32,603 million, marking a 23.6% increase compared to the same period of the previous year.
- Operating profit was ¥6,513 million (up 22.9% year-on-year), ordinary profit was ¥6,033 million (up 23.6% year-on-year), and net income attributable to owners of parent was ¥4,091 million (up 23.8% year-on-year).
- Interim net income per share was ¥256.79, and diluted interim net income per share was ¥251.10.
- Product origination amounted to ¥269,575 million (up 53.9% year-on-year), and product investment sales totaled ¥76,377 million (up 16.5% year-on-year).
- The full-year consolidated earnings forecast for FY2027 remains unchanged, projecting revenue of ¥66,000 million (up 2.7% year-on-year) and net income attributable to owners of parent of ¥6,100 million (up 0.8% year-on-year).
- The interim dividend is ¥30.00 (with an annual dividend forecast of ¥85.00).
🤖 AI Perspective
The interim results indicate robust business growth, with double-digit increases across revenue, operating profit, ordinary profit, and net income compared to the prior year. The record-high product origination and sales figures suggest a period of active business operations. As the full-year forecast remains unchanged, investors may focus on the company’s performance in the latter half of the fiscal year to assess its trajectory.
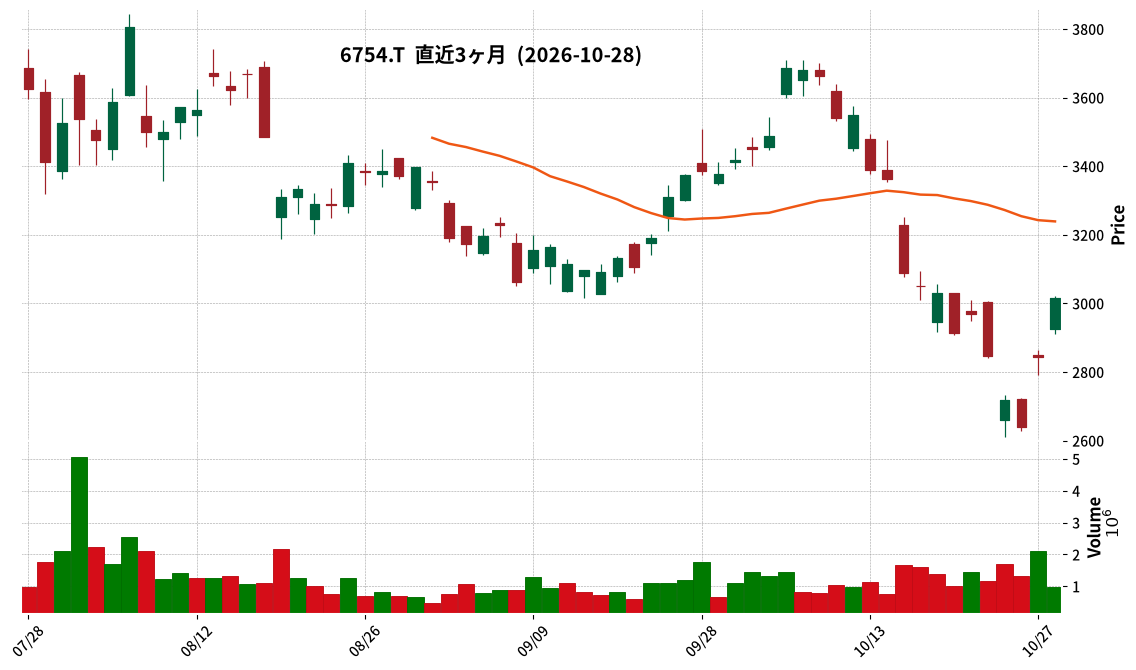
6754|アンリツ
3015.0
▲ +5.99%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Anritsu Co. announced the completion of its additional share acquisition of SmartViser SAS (Rennes, France) on October 27, 2026, as previously disclosed on March 31, 2026.
- SmartViser has now become a consolidated subsidiary of Anritsu.
- Anritsu previously acquired 32.72% of SmartViser’s shares in March 2025, and with this additional acquisition, its ownership stake has increased to 51.00%.
- SmartViser is a vendor offering automated testing solutions for mobile network operators and device manufacturers, specializing in performance evaluation, functional testing, quality monitoring for mobile networks and devices, and compliance with EU smartphone energy labeling regulations (EEI).
- Anritsu has stated that the impact of this share acquisition on its consolidated financial results will be minor.
🤖 AI Perspective
Anritsu’s move to fully consolidate SmartViser, previously an equity-method affiliate, appears to be a strategic step to bolster its testing solutions in the communication sector. The integration of SmartViser’s automated testing and efficiency technologies with Anritsu’s advanced test solutions could potentially open up new business opportunities beyond the smartphone market, extending into areas such as private networks and automotive-related fields. This consolidation may also align with Anritsu’s long-term goals of contributing to carbon neutrality and a smart society.
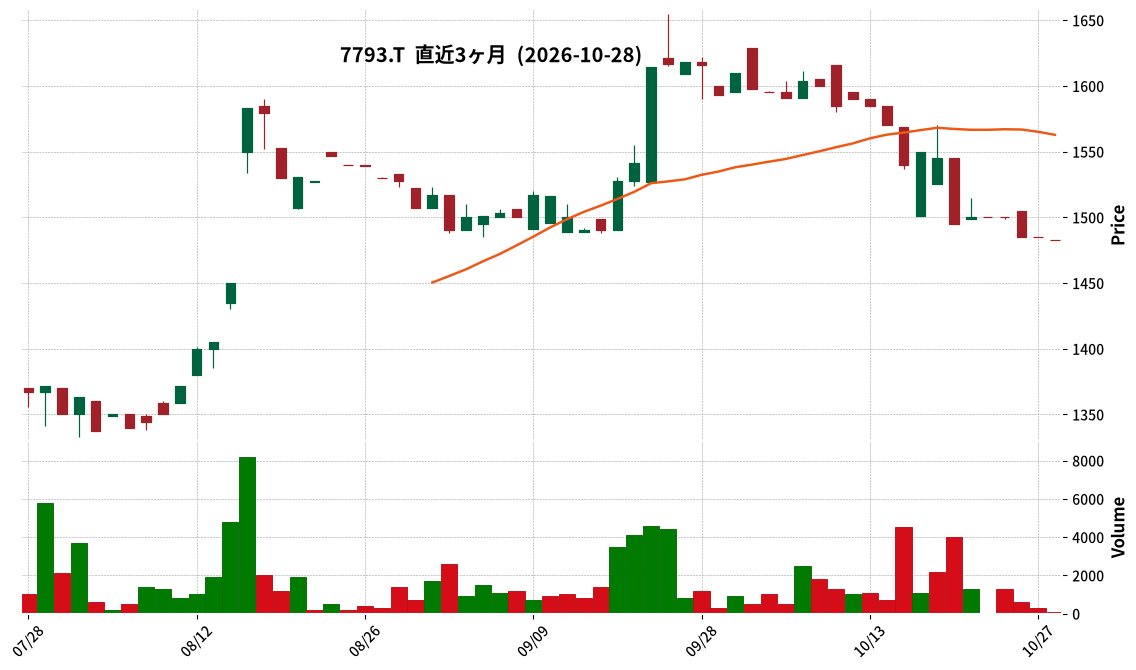
7793|G-イメージマジック
1483.0
▼ -0.13%
📎 Source:G-イメージマジック Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Image Magic Co., Ltd. announced a partial revision (expansion) of its shareholder benefit program.
- The purpose of the expansion is to express gratitude to shareholders, deepen their understanding of the company’s business and services, and encourage long-term shareholding.
- A new “Featured Product Benefit” will be added for shareholders holding 1,000 shares or more, with no change to the existing coupon entitlement criteria.
- For the initial “Featured Product Benefit” for the December 2026 record date, a “Photo AI Pet Figure” will be presented. This product uses AI to generate a 3D model from a provided pet photo, which is then 3D printed into a full-color figure, with a standard retail price of 6,380 yen (including tax) per figure.
- The program will commence with shareholders holding 1,000 shares or more recorded on the shareholder registry as of the record date of December 31, 2026. Benefit guides are scheduled to be sent in March 2027.
- The company states that the impact of this matter on its financial performance for the fiscal year ending December 2026 will be minor.
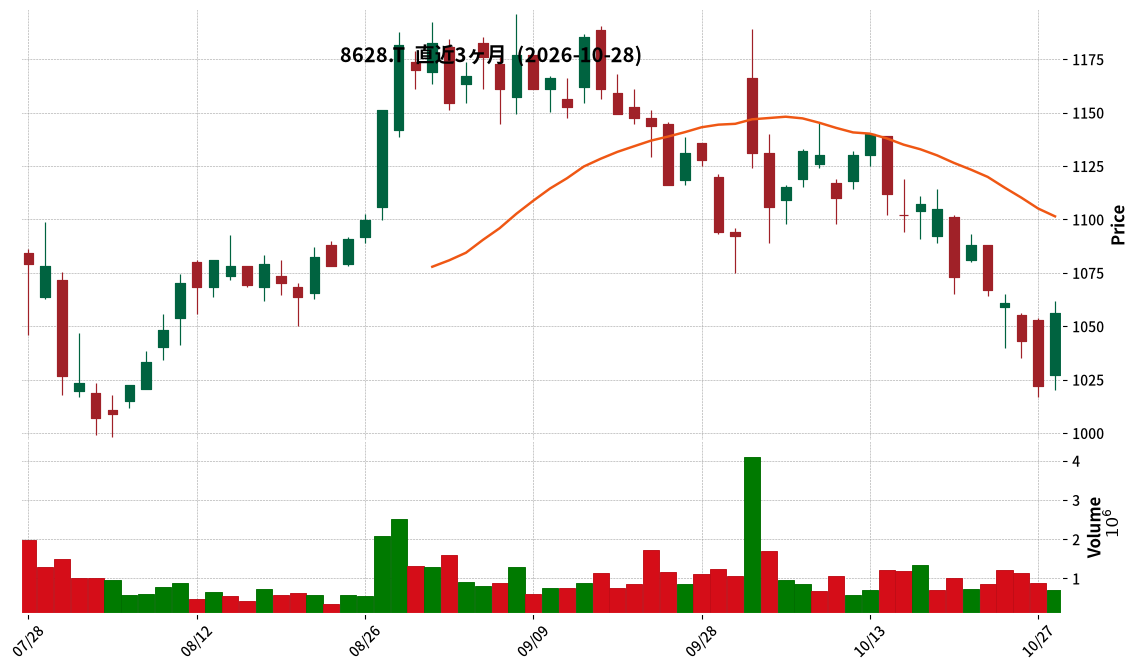
8628|松井証
1056.0
▲ +3.33%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Matsui Securities announced interim operating revenue of JPY 34,048 million for the second quarter of FY2027, representing a 42.8% increase compared to the previous interim period.
- Interim net profit reached JPY 10,435 million, marking a substantial increase of 59.7% year-on-year.
- Basic earnings per share for the interim period was JPY 40.50.
- Total assets stood at JPY 1,476,479 million (up 9.0% from the previous fiscal year-end), and net assets were JPY 86,986 million (up 5.6%).
- An interim dividend of JPY 28.00 per share has been declared.
- During the interim period, the domestic stock market saw robust performance, with the Nikkei 225 index reaching a new all-time high in June and closing at over JPY 66,000 at the end of September. Amidst this market environment, Matsui Securities’ equity brokerage transaction value increased by 100% compared to the prior interim period.
🤖 AI Perspective
These interim results demonstrate significant growth in operating revenue and net profit, largely attributed to favorable market conditions and an expansion in individual investor trading activity. The substantial increase in equity brokerage transaction value appears to have been a key driver of this revenue growth. While selling, general, and administrative expenses also rose due to increased advertising and exchange-related costs, the higher revenue growth successfully offset these increases.
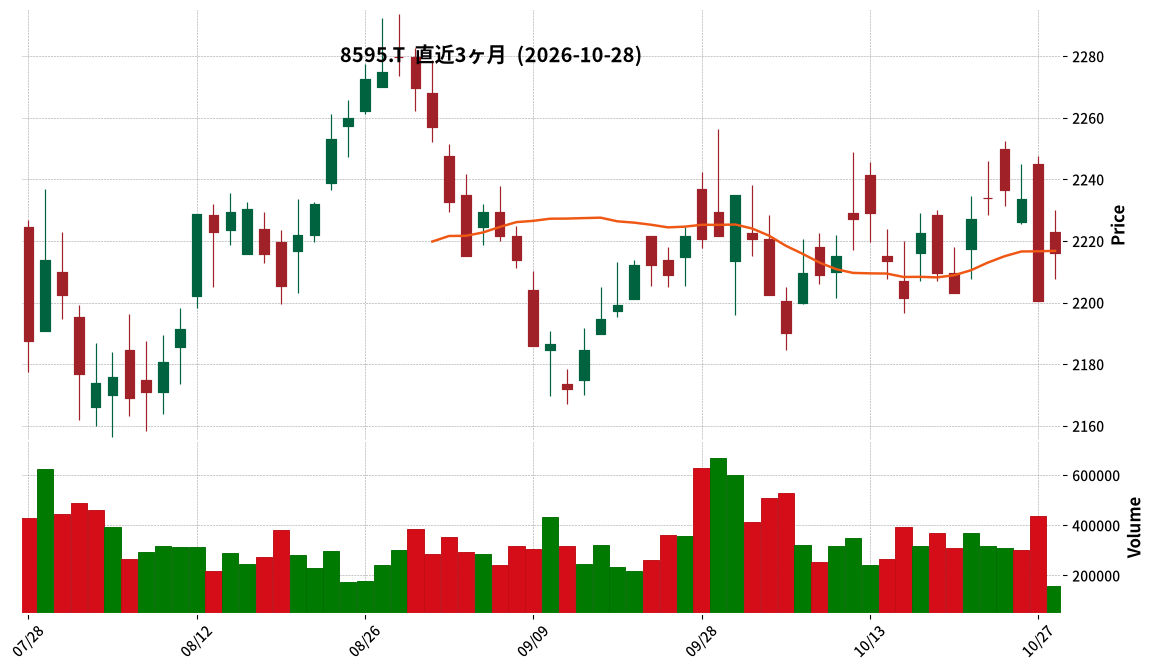
8595|JAFCO
2216.0
▲ +0.70%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- JAFCO Co., Ltd. announced its financial results for the second quarter (interim period) of the fiscal year ending March 2027 on October 28, 2026.
- For the interim period, the company reported net sales of ¥5,968 million, operating income of ¥1,570 million, ordinary income of ¥1,498 million, and interim net income of ¥1,488 million.
- Diluted interim net income per share was ¥28.27, and net assets per share were ¥2,558.50.
- Due to a transition from consolidated to non-consolidated (individual) financial statements from the third quarter of the fiscal year ended March 2026, no year-on-year comparisons for business performance are provided for the interim period of March 2026.
- During the interim accounting period, there were 2 new IPOs from venture investments and 1 M&A share transfer from buyout investments.
- The forecast for the annual dividend for the fiscal year ending March 2027 is an interim dividend of ¥66.50, a year-end dividend (minimum) of ¥66.50, totaling a minimum of ¥133.00.
🤖 AI Perspective
JAFCO’s Q2 FY2027 results show interim net income of approximately ¥1.488 billion and sales of ¥5.968 billion, with no year-on-year comparison due to a shift to non-consolidated financials. The report highlights specific exit activities, including two new IPOs from venture investments and one M&A share transfer from buyout investments, which could indicate ongoing investment realization despite challenging market conditions. Given the company’s business nature and lack of full-year earnings forecasts, these interim results and exit details are crucial for investors to monitor its operational performance.
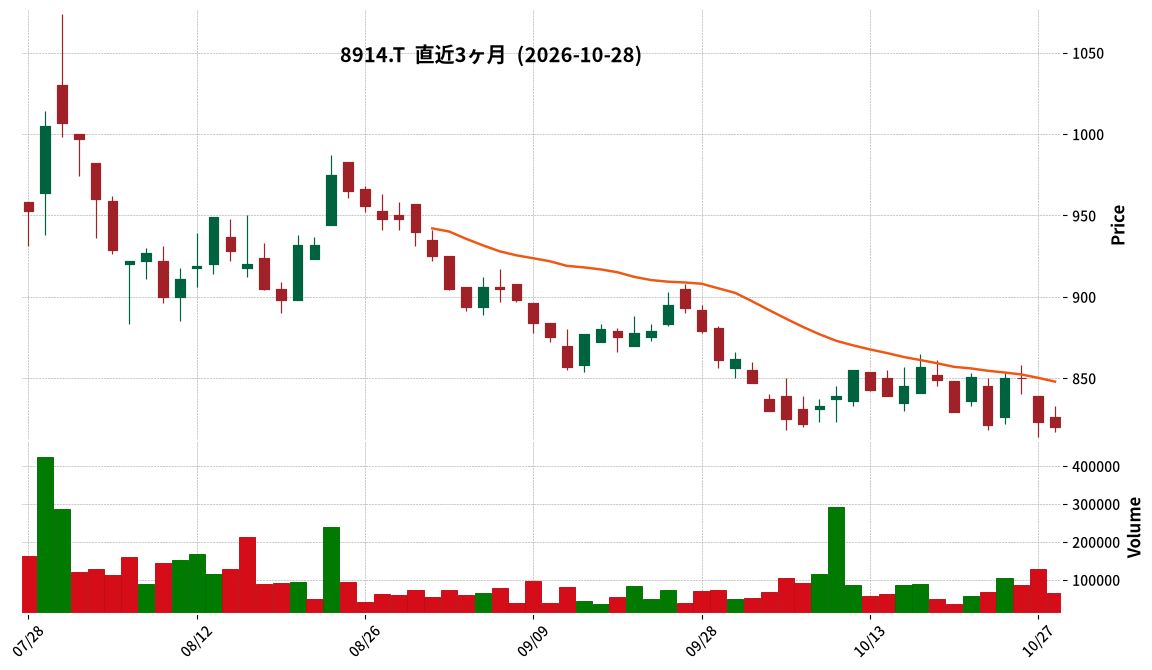
8914|エリアリンク
820.0
▼ -0.36%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Area Link announced its transition to consolidated financial reporting starting from the third quarter of the fiscal year ending December 2026.
- This transition follows the acquisition and consolidation of Storage Oh Co., Ltd. as a subsidiary, effective August 28, 2026.
- The company published its consolidated earnings forecast for the full fiscal year ending December 2026, projecting net sales of ¥29,700 million, operating income of ¥5,900 million, ordinary income of ¥5,430 million, net income attributable to owners of parent of ¥3,600 million, and earnings per share of ¥70.78.
- The consolidated forecast incorporates three months of Storage Oh’s performance (August-October 2026), ¥164 million in acquisition-related expenses, and a provisional amount for goodwill amortization.
- The company also revised upward its individual earnings forecast for the full fiscal year ending December 2026: net sales to ¥29,150 million (from ¥28,700 million), operating income to ¥6,200 million (from ¥6,050 million), ordinary income to ¥5,750 million (from ¥5,670 million), and net income to ¥3,870 million (from ¥3,815 million).
- The upward revision of the individual forecast is attributed to favorable sales progress in its flow business, including storage securitization and land rights improvement projects.
🤖 AI Perspective
This announcement marks a significant operational shift for Area Link, with the introduction of its first consolidated earnings forecast reflecting the integration of Storage Oh. The upward revision of individual earnings, driven by strong performance in the flow business, could suggest underlying strength in the company’s core operations. Investors may focus on how the consolidated reporting and continued individual business growth collectively shape the company’s future financial trajectory.
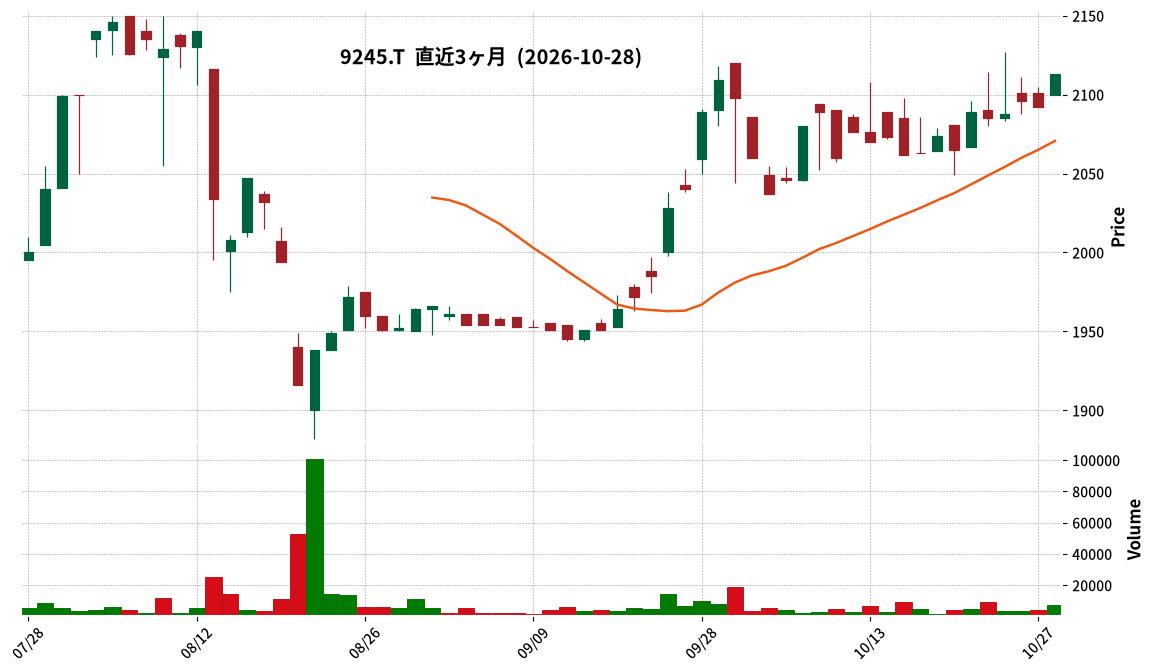
9245|G-リベロ
2113.0
▲ +1.00%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- G-Livero Co., Ltd. resolved to partially change its shareholder benefit program (item change) at a Board of Directors meeting held on October 28, 2026.
- The change will be applied starting from the shareholder benefit program with a record date of December 31, 2026.
- The previous benefit item, a “QUO Card worth JPY 10,000”, will be changed to a “Digital Gift® worth JPY 10,000”.
- Planned redemption options for the Digital Gift® include Amazon Gift Card, Google Play Gift Code, PayPay Money Light, Rakuten Point Gift, QUO Card Pay, d Point, and au PAY Gift Card, among others.
- To qualify for the benefit, shareholders must hold 2 units (200 shares) or more, with the record date remaining December 31.
🤖 AI Perspective
This change in the shareholder benefit item, aiming to enhance shareholder convenience, allows for greater flexibility in choosing preferred rewards through the introduction of Digital Gifts®. The inclusion of various options like Amazon, PayPay, and QUO Card Pay may broaden the utility for shareholders compared to the previous single-item benefit. This adjustment could be seen as an effort to better align with the company’s objective of expressing gratitude to shareholders and encouraging long-term stock ownership.
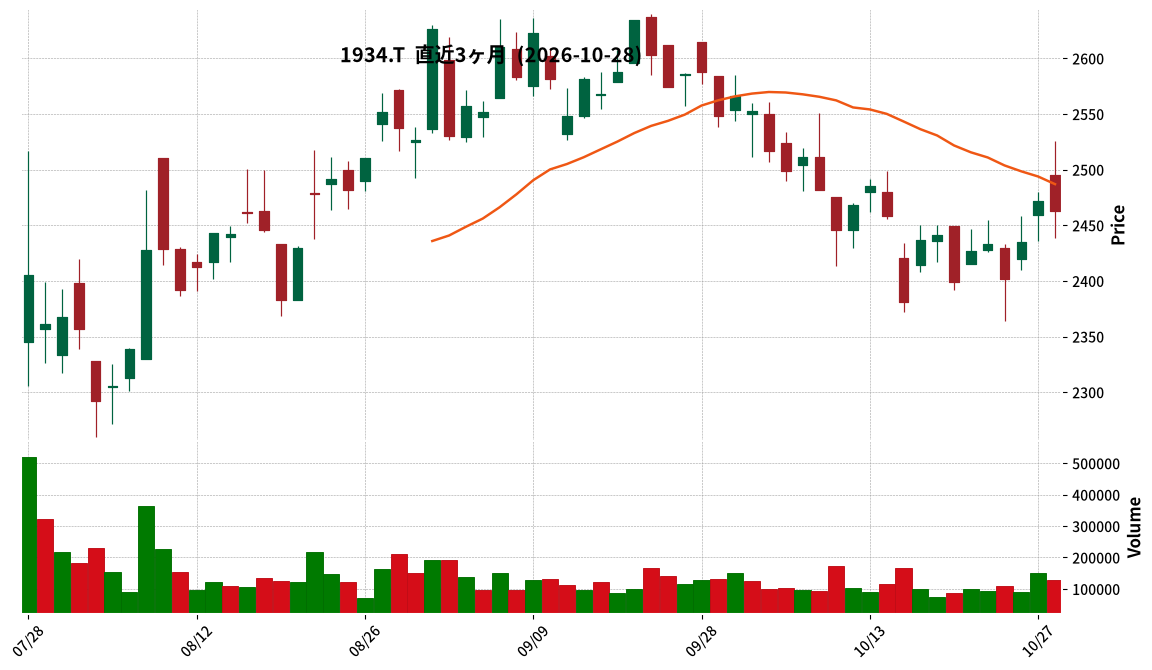
1934|ユアテック
2463.0
▼ -0.36%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Yurtec has revised its consolidated earnings forecast for the full fiscal year ending March 2027 upwards. Revenue is now projected at ¥284.0 billion (up from ¥273.0 billion), operating profit at ¥22.1 billion (up from ¥18.9 billion), ordinary profit at ¥23.2 billion (up from ¥19.5 billion), and net income attributable to owners of the parent at ¥14.3 billion (up from ¥13.2 billion).
- The non-consolidated earnings forecast for the same period has also been revised upwards, with revenue at ¥246.0 billion, operating profit at ¥20.0 billion, ordinary profit at ¥21.5 billion, and net income at ¥13.3 billion.
- Key reasons for the revised forecast include a robust backlog of construction projects, appropriate reflection of increased labor and outsourcing costs in project pricing, improved profitability through thorough cost management, and increased sales from overseas subsidiaries.
- The annual dividend forecast for the fiscal year ending March 2027 has been revised from ¥78 per share to ¥84 per share (interim dividend of ¥42, year-end dividend of ¥42).
- An interim dividend of ¥42 per share was declared, with the record date set as September 30, 2026.
🤖 AI Perspective
The upward revision of earnings forecasts, particularly the higher growth rates in operating and ordinary profits compared to revenue, may suggest an improvement in profitability alongside sales growth. The increased dividend forecast aligns with the revised earnings and the company’s policy of consistently returning at least 40% of consolidated profit as dividends. The anticipated early achievement of mid-term management plan targets could indicate positive momentum for future strategic developments.
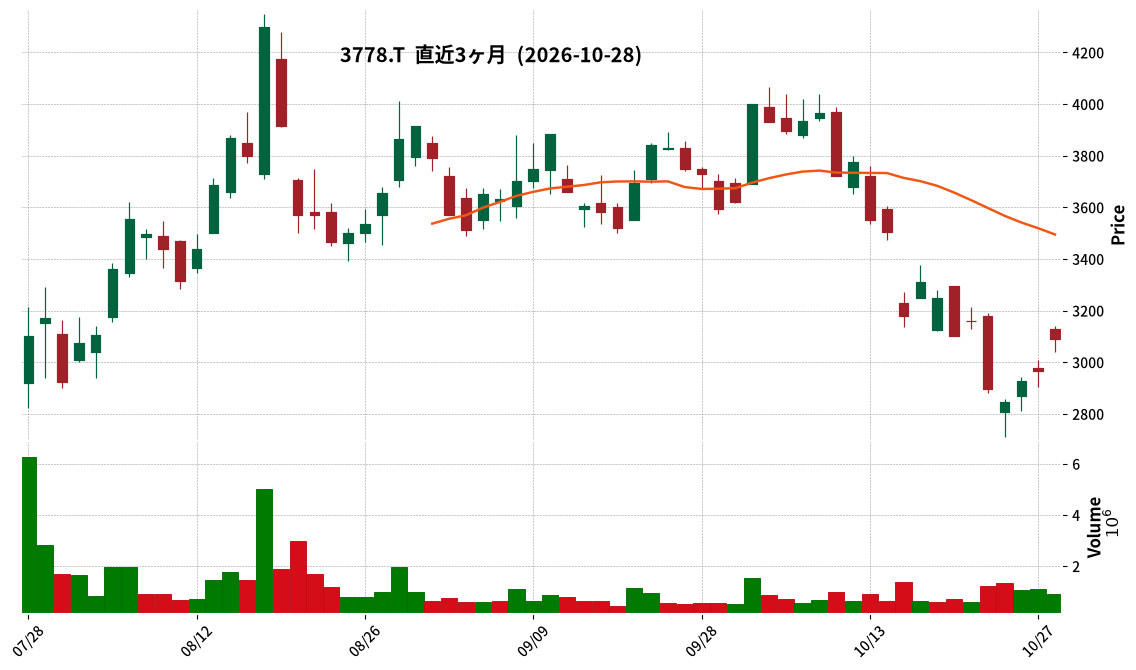
3778|さくらインターネット
3090.0
▲ +4.15%
📎 Source:さくらインターネット Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Sakura Internet announced its consolidated financial results for the second quarter (interim period) of the fiscal year ending March 2027.
- Revenue reached ¥22,827 million (up 46.0% year-on-year), operating profit was ¥2,963 million (compared to an operating loss of ¥920 million in the prior year period), ordinary profit was ¥3,013 million (compared to an ordinary loss of ¥811 million), and net income attributable to owners of the parent was ¥1,903 million (compared to a net loss of ¥626 million).
- By service category, GPU Infrastructure Services revenue significantly increased to ¥10,124 million (up 258.9% year-on-year), driving overall revenue growth.
- The full-year consolidated earnings forecast for FY2027 has been revised upward, with revenue projected at ¥46,600 million, operating profit at ¥4,100 million, ordinary profit at ¥3,900 million, and net income attributable to owners of the parent at ¥2,550 million.
- To commemorate its 30th anniversary, a special dividend of ¥2.50 per share was implemented for the Q2 FY2027 end, bringing the total Q2 dividend to ¥2.50. The year-end forecast dividend is ¥5.50, for a total annual expected dividend of ¥8.00.
🤖 AI Perspective
Sakura Internet’s interim results for FY2027 show a significant improvement across revenue and profit metrics compared to the previous year, with strong performance in GPU Infrastructure Services appearing to be a key driver. The upward revision of the full-year earnings forecast following these results could suggest management’s confidence in sustained growth. Additionally, the declaration of a 30th-anniversary commemorative dividend may signal a commitment to shareholder returns.
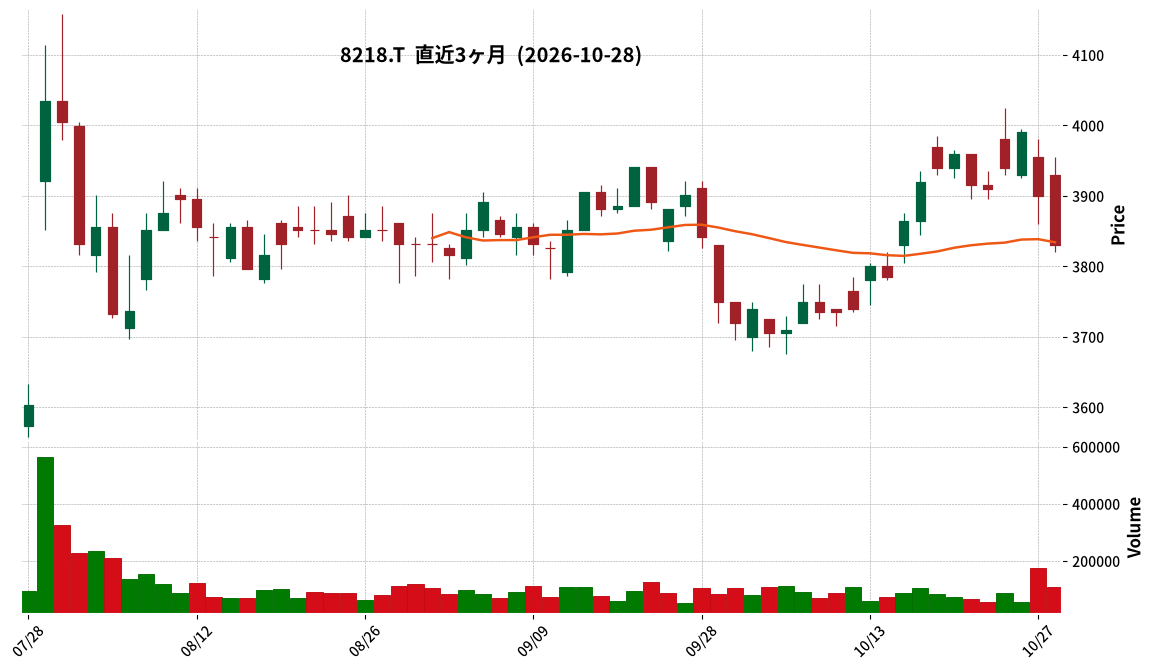
8218|コメリ
3830.0
▼ -1.79%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Komeri Co.,Ltd. announced its consolidated interim financial results for the fiscal year ending March 2027 (April 1, 2026 – September 30, 2026).
- Operating revenue reached ¥208,803 million, an increase of 3.8% year-over-year.
- Operating income was ¥17,301 million, representing a 12.6% increase compared to the previous year.
- Ordinary income stood at ¥17,279 million (up 10.7% YoY), and net income attributable to owners of the parent was ¥11,310 million (up 9.2% YoY).
- By product category, tools/hardware/work supplies increased by 7.6% YoY, and daily necessities/home appliances/car/leisure goods increased by 4.7% YoY.
- By store format, “Power” achieved a 6.2% increase YoY, and “PRO” saw a significant 33.0% increase YoY in sales.
- The full-year business forecast remains unchanged from the announcement made on April 28, 2026.
🤖 AI Perspective
Komeri’s interim results for FY2027 show a robust performance with operating revenue and income surpassing previous year’s figures, notably driven by increased demand for petroleum-related products, air conditioners, and construction materials. However, the report also highlights increased expenses due to wage hikes, higher freight costs, and depreciation expenses from the operationalization of the Kansai distribution center, which could be worth monitoring for future profitability. The unchanged full-year forecast may suggest the company anticipates continued stable operations in the second half of the fiscal year.
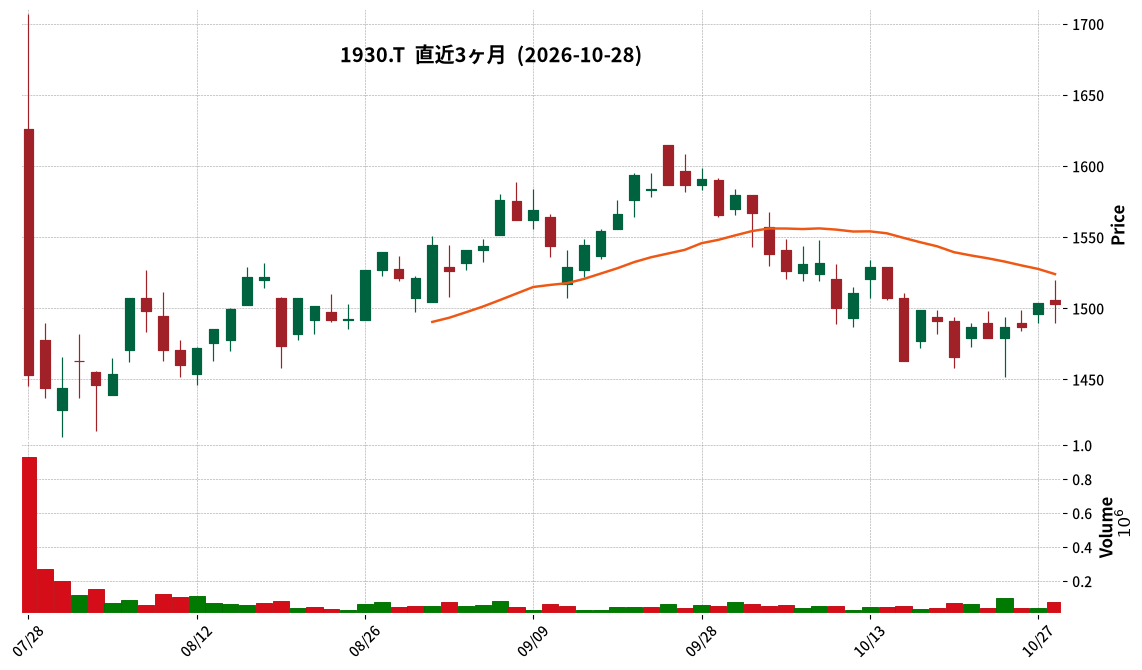
1930|北陸電工
1503.0
▼ -0.07%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Hokuriku Denko announced its consolidated financial results for the second quarter (interim period) of the fiscal year ending March 2027.
- Consolidated net sales amounted to ¥33.28 billion, representing a 24.6% increase compared to the same period of the previous fiscal year.
- Consolidated operating income reached ¥3.108 billion (up 146.3% YoY), ordinary income ¥3.296 billion (up 125.6% YoY), and interim net income attributable to owners of parent ¥2.293 billion (up 143.7% YoY).
- Interim basic earnings per share stood at ¥83.38.
- The full-year consolidated performance forecast for FY2027 remains unchanged, projecting net sales of ¥70.0 billion, operating income of ¥6.0 billion, ordinary income of ¥6.2 billion, and net income attributable to owners of parent of ¥4.1 billion.
- An interim dividend of ¥24.00 per share is planned, with the full-year dividend forecast remaining ¥48.00 per share.
🤖 AI Perspective
Hokuriku Denko’s interim results for FY2027 show significant growth across sales and profit metrics, substantially exceeding the prior year’s interim performance. This strong performance may suggest effective sales strategies and improved project profitability. The unchanged full-year forecast could indicate the company’s confidence in maintaining steady operations through the second half of the fiscal year.
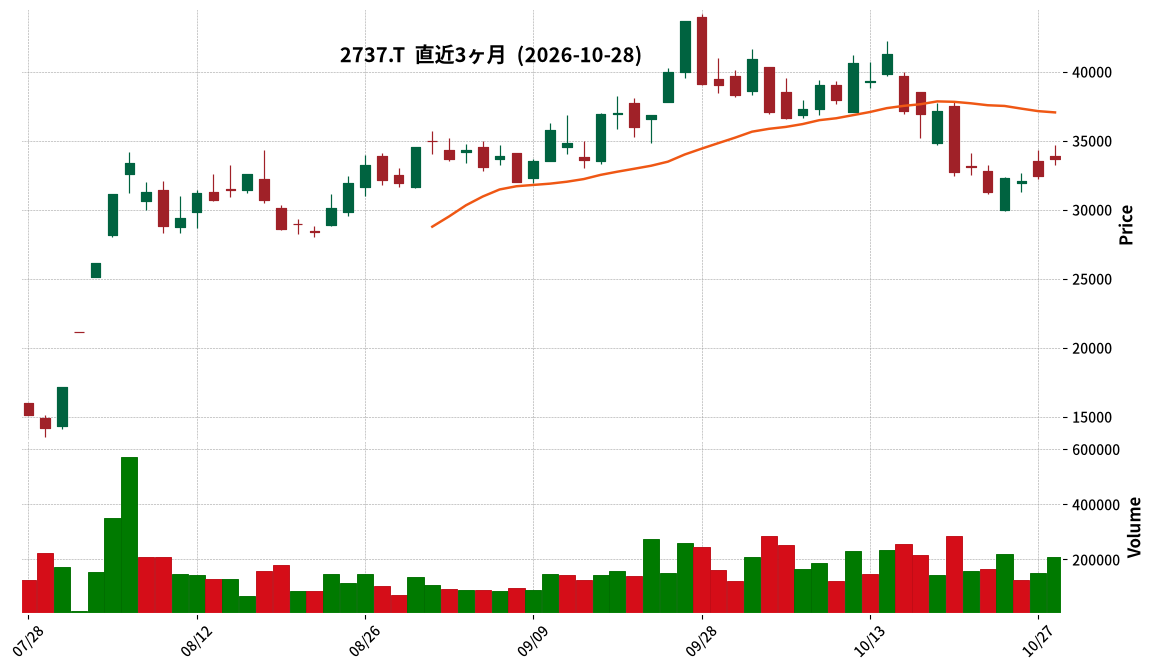
2737|トーメンデバ
33700.0
▲ +3.85%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Tomen Devices announced its consolidated financial results for the second quarter (interim period) of the fiscal year ending March 2027.
- Consolidated net sales reached ¥785,840 million, marking a 223.3% increase compared to the prior interim period.
- Operating profit was ¥37,542 million (+359.6% YoY), ordinary profit was ¥34,544 million (+393.6% YoY), and net profit attributable to owners of parent was ¥25,114 million (+425.5% YoY).
- Diluted earnings per share for the interim period stood at ¥3,692.80.
- The full-year consolidated performance forecast and dividend forecast (year-end ¥1,640.00) remain unchanged from the most recently announced figures.
- Key factors cited for the strong performance include increased sales of memory products, primarily for servers/storage and automotive applications, alongside rising memory prices.
🤖 AI Perspective
Tomen Devices’ interim results show significant year-over-year growth across all key financial metrics, suggesting strong demand in AI-related markets and increased semiconductor adoption in the automotive sector have positively impacted performance. The surge in memory product sales and prices is a notable factor, potentially indicating a robust semiconductor market environment. With the full-year forecast unchanged, it implies the company anticipates continued positive momentum into the second half of the fiscal year, which could be worth monitoring for investors.
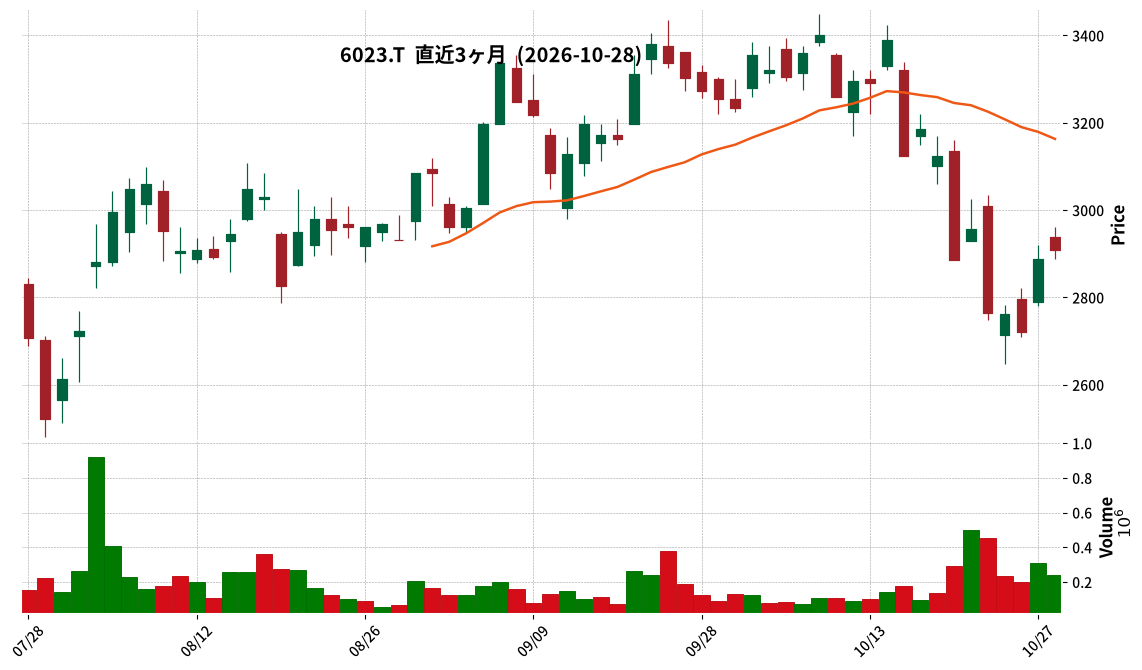
6023|ダイハツインフィ
2908.0
▲ +0.66%
📎 Source:ダイハツインフィ Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Daihatsu Infi announced its consolidated financial results for the second quarter (interim period) of the fiscal year ending March 2027.
- For the interim period, net sales reached ¥50,092 million, marking a 20.6% increase compared to the same period last year.
- Operating profit increased by 65.9% to ¥4,086 million, ordinary profit by 51.9% to ¥3,894 million, and profit attributable to owners of parent by 28.5% to ¥2,711 million.
- By segment, the Internal Combustion Engine segment reported sales of ¥47,734 million (up 21.2% YoY) and segment profit of ¥6,141 million (up 40.5% YoY), driven primarily by marine engine-related sales.
- The consolidated full-year earnings forecast and annual dividend forecast for the fiscal year ending March 2027 remain unchanged from the latest publicly announced figures.
🤖 AI Perspective
Daihatsu Infi’s Q2 FY2027 results show substantial year-over-year growth in both revenue and profit metrics, suggesting strong performance across its operations. The robust growth in the Internal Combustion Engine segment, particularly marine engine-related business, appears to be a key driver. This growth may be attributed to sustained demand for new shipbuilding due to environmental regulations and fuel efficiency improvements, as well as steady maintenance demand from active vessel operations. The unchanged full-year forecast could indicate the company is progressing as planned.
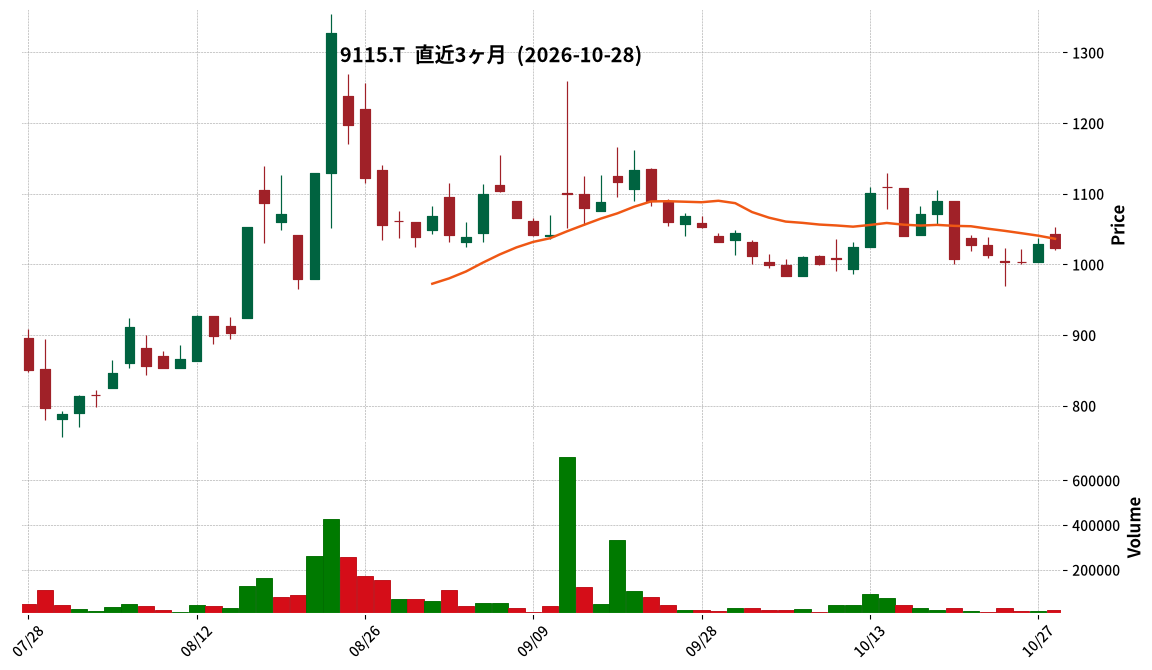
9115|明海グループ
1023.0
▼ -0.58%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Meiji Group announced its consolidated financial results for the second quarter (interim period) of the fiscal year ending March 2027.
- Consolidated revenue reached 30,870 million yen (an increase of 3.4% compared to the same interim period last year).
- Consolidated operating profit was 1,495 million yen (a decrease of 49.5% compared to the same interim period last year).
- Consolidated ordinary profit recorded 3,408 million yen (an increase of 852.4% compared to the same interim period last year).
- Net profit attributable to owners of the parent was 1,350 million yen (a decrease of 52.0% compared to the same interim period last year).
- The full-year consolidated performance forecast has been revised, projecting revenue of 66,500 million yen, operating profit of 9,300 million yen, ordinary profit of 6,600 million yen, and net profit attributable to owners of the parent of 2,800 million yen.
- During this interim period, Kiun Co., Ltd. was newly established and included in the scope of consolidation.
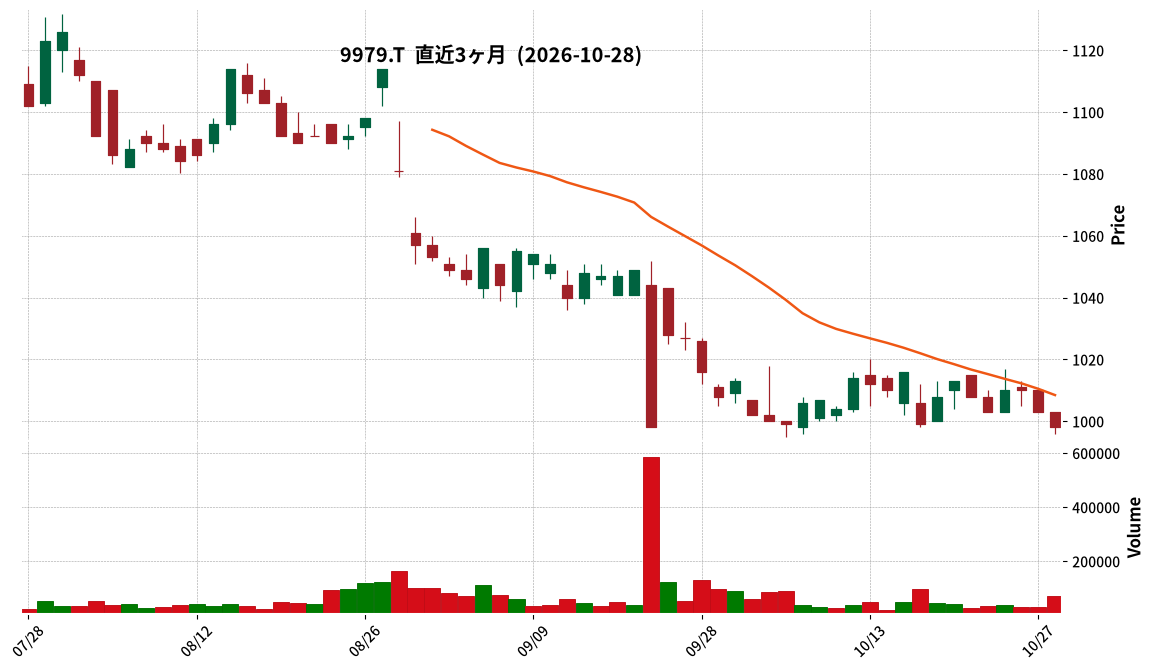
9979|大庄
998.0
▼ -0.50%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Consolidated net sales for the fiscal year ending August 2026 were ¥53,088 million (up 1.0% year-on-year).
- Operating income was ¥915 million (down ¥281 million year-on-year, from 2.3% to 1.7% of sales).
- Net income attributable to owners of the parent was ¥394 million (down ¥778 million year-on-year).
- Existing store sales in the Food & Beverage segment increased by 101.6% year-on-year, with banquet sales notably rising by 111.7%.
- The number of directly managed stores decreased to 217 at the end of the period from 232 in the previous period.
- Selling, general and administrative (SG&A) expenses decreased by ¥19 million, with the ratio to sales decreasing by 0.4%, primarily due to reductions in personnel and utility costs, and an increase in transportation costs.
🤖 AI Perspective
While consolidated net sales show an increase, the decline in operating income and net income attributable to owners of the parent could be a point of concern for investors. The robust growth in existing store sales, particularly in banquets within the Food & Beverage segment, suggests positive momentum in core operations. However, the reduction in directly managed stores and a decrease in profit from the wholesale and logistics business might be offsetting these gains. Future efforts in cost management and business portfolio optimization will be worth monitoring for potential profit improvement.
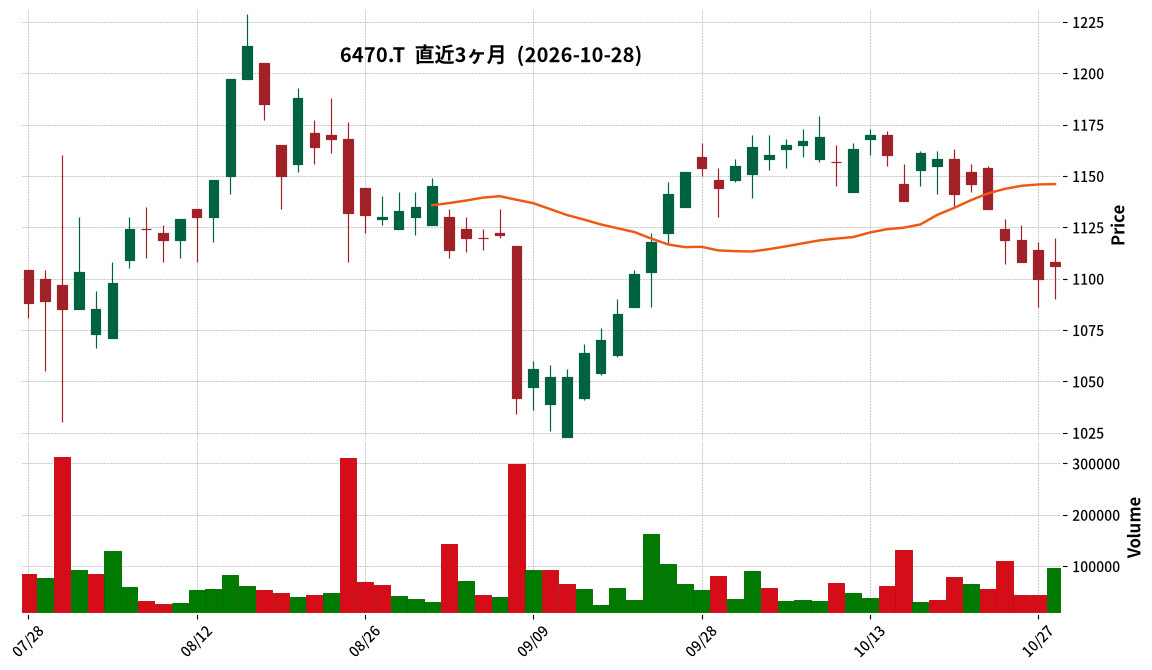
6470|大豊工業
1106.0
▲ +0.55%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Taiho Kogyo Co., Ltd. announced its consolidated financial results for the second quarter (interim period) of the fiscal year ending March 2027.
- Interim net sales reached ¥61,325 million, representing a 4.7% increase compared to the prior interim period.
- Operating profit was ¥2,511 million (up 79.4% YoY), ordinary profit was ¥2,689 million (up 80.3% YoY), and net income attributable to owners of parent was ¥2,044 million (up 138.3% YoY).
- Interim earnings per share (EPS) was ¥71.93.
- The full-year consolidated earnings forecast remains unchanged from the most recently published forecast, projecting net sales of ¥120,000 million, operating profit of ¥4,500 million, ordinary profit of ¥4,800 million, and net income attributable to owners of parent of ¥3,600 million.
- The interim dividend forecast for the fiscal year ending March 2027 has been revised upwards to ¥15.00 per share (an increase of ¥5.00 from the previous forecast), bringing the full-year total projected dividend to ¥30.00 per share (an increase of ¥5.00).
🤖 AI Perspective
Taiho Kogyo’s second-quarter results for FY2027 show solid sales growth and significant profit improvement, with net income attributable to owners of parent increasing substantially by 138.3% year-over-year. While the full-year earnings forecast remains constant, the upward revision of the annual dividend forecast could be viewed positively by investors. The company’s ability to maintain its full-year profit outlook while significantly increasing interim profitability and dividends may suggest operational efficiency and a positive outlook on cash flow.
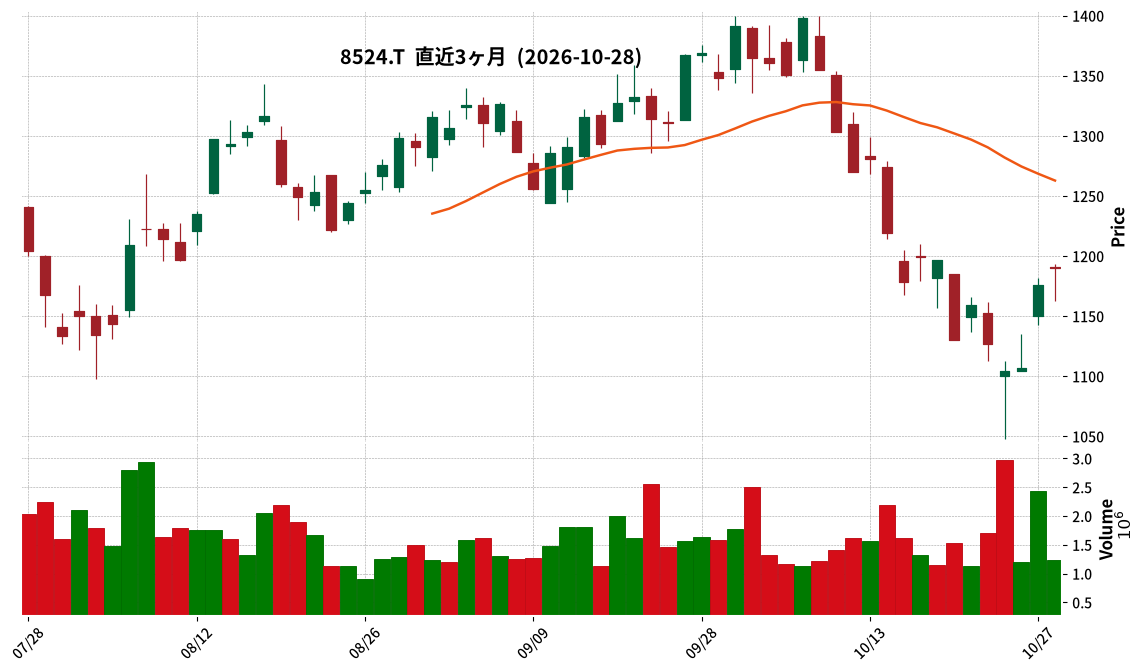
8524|北洋銀行
1190.0
▲ +1.19%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Hokuyo Bank announced on October 28, 2026, revisions to its earnings forecast and dividend forecast for the fiscal year ending March 2027, initially released on May 13, 2026.
- For the full fiscal year ending March 2027, the consolidated earnings forecast for ordinary revenue was revised upwards from ¥225.2 billion to ¥252.9 billion (an increase of 12.3%), ordinary profit from ¥44.4 billion to ¥51.1 billion (an increase of 15.1%), and profit attributable to owners of parent from ¥29.4 billion to ¥33.9 billion (an increase of 15.3%).
- The non-consolidated earnings forecast for ordinary revenue, ordinary profit, and net profit for the full fiscal year ending March 2027 were also revised upwards.
- The reason for the earnings forecast revision is attributed to an anticipated increase in funding profit, driven by an increase in the average balance of loans and the Bank of Japan’s policy interest rate hike.
- The annual dividend forecast for the fiscal year ending March 2027 was revised from the previous forecast of ¥32.00 to ¥36.50 (an increase of ¥4.50). This implies that the second quarter, third quarter, and year-end dividends will each be ¥9.50.
🤖 AI Perspective
The upward revision of the earnings forecast appears to be primarily driven by increased loan balances and the expected positive impact of the Bank of Japan’s policy rate hike on funding profits. The accompanying increase in the annual dividend forecast, following the upward revision of profit attributable to owners of parent, could suggest a commitment to shareholder returns. Investors may continue to monitor future interest rate trends and loan dynamics, as these factors could influence the bank’s performance.
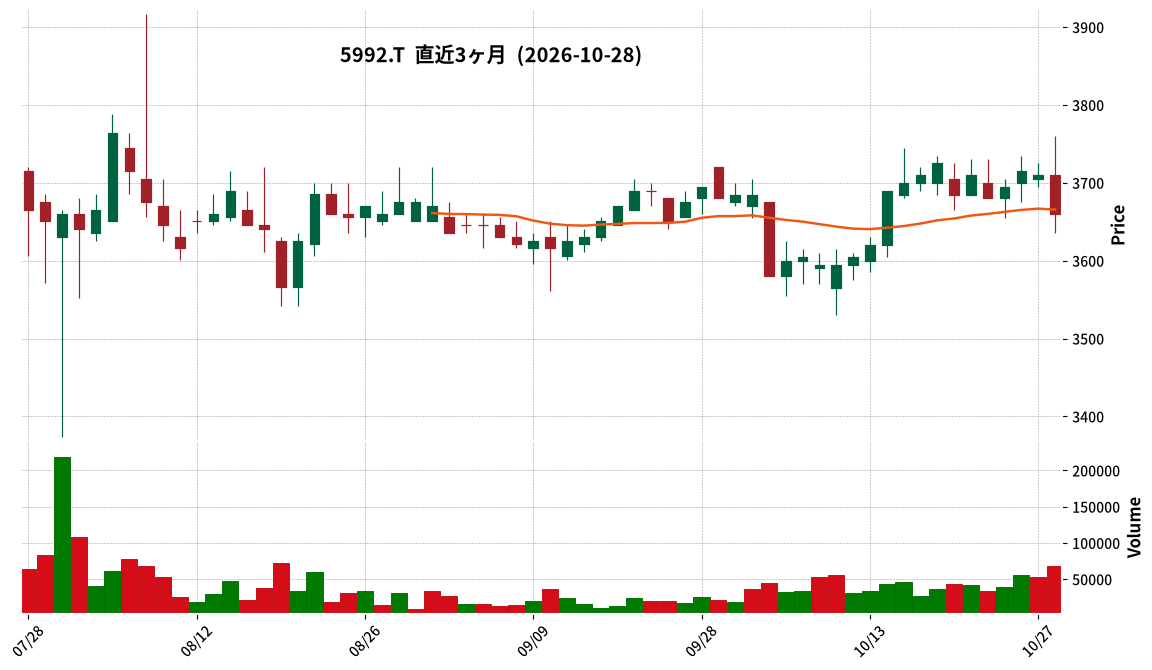
5992|中央発条
3660.0
▼ -1.35%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Chuo Spring Co., Ltd. reported consolidated net sales of ¥56.251 billion for the second quarter of the fiscal year ending March 2027, a 4.1% increase year-over-year, marking a record high for the interim period.
- Operating profit decreased by 74.0% to ¥388 million, ordinary profit decreased by 64.2% to ¥700 million, and net profit attributable to parent company shareholders decreased by 42.0% to ¥776 million.
- Key factors contributing to the profit decline include “intentional fixed cost increases” for future investments, production cuts due to the sluggish Chinese market, North American tariff impacts, and material inflation.
- The consolidated full-year earnings forecast for the fiscal year ending March 2027 has been revised downward, but the annual dividend forecast remains unchanged at ¥90 per share (¥45 interim, ¥45 year-end).
- The Half-Year Report is scheduled for submission on November 11, 2026, and dividend payment is expected to commence on November 26, 2026.
🤖 AI Perspective
While record-high sales figures demonstrate top-line growth, the significant decline in profitability could be a key focus for investors, potentially indicating the impact of strategic upfront investments and challenging external factors. The decision to maintain the annual dividend forecast despite the downward revision in full-year earnings guidance might suggest the company’s commitment to shareholder returns over the medium to long term.
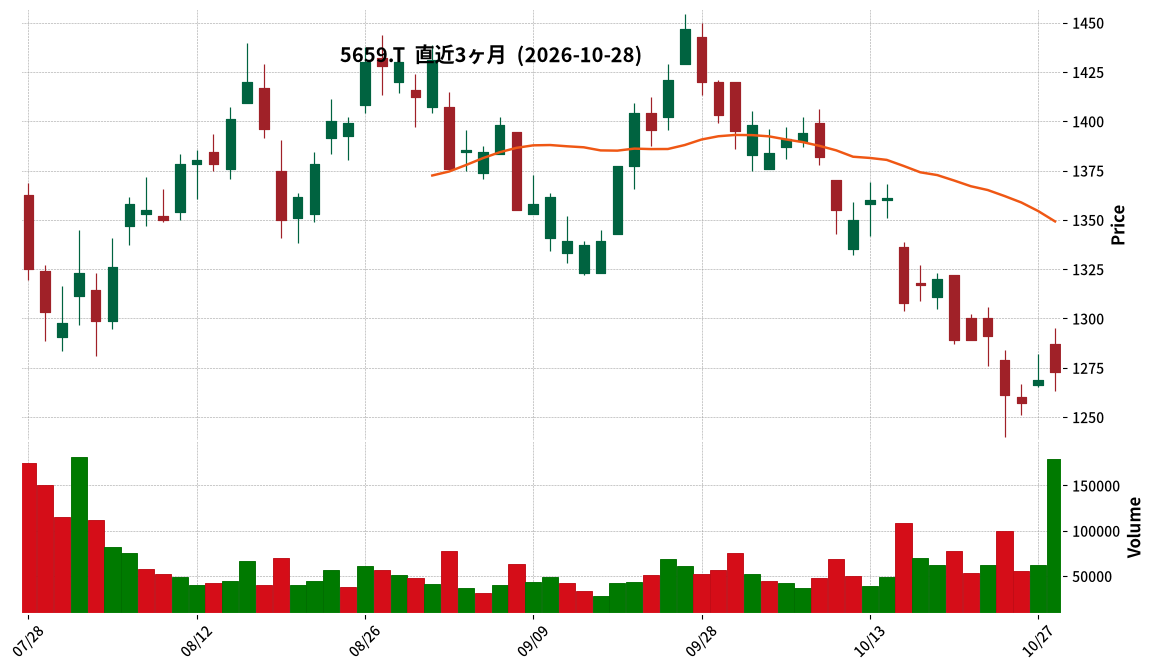
5659|日精線
1273.0
▲ +0.32%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Nippon Seisen has announced its consolidated financial results for the second quarter (interim period) of the fiscal year ending March 2027.
- Interim net sales reached ¥25,145 million, representing an 11.9% increase compared to the previous interim period.
- Operating profit was ¥1,853 million (+55.1%), ordinary profit was ¥1,986 million (+59.9%), and net profit attributable to owners of parent was ¥1,413 million (+56.6%).
- By segment, the Metal Fiber division recorded sales of ¥5,480 million (+45.4%), primarily driven by a significant increase in sales of ultra-precise gas filters (NASclean®) for the semiconductor industry. The Stainless Steel Wire division reported sales of ¥19,664 million (+5.1%).
- The interim dividend forecast for the fiscal year ending March 2027 has been revised upwards from the previously announced ¥18 per share to ¥24 per share, an increase of ¥6.
🤖 AI Perspective
Nippon Seisen’s interim results show substantial growth in sales and all profit categories year-on-year, with the Metal Fiber division emerging as a significant driver of overall performance. The strong demand from the semiconductor industry appears to have positively impacted the company’s ultra-precise gas filter products. The upward revision of the interim dividend may be viewed favorably by investors as a sign of commitment to shareholder returns.
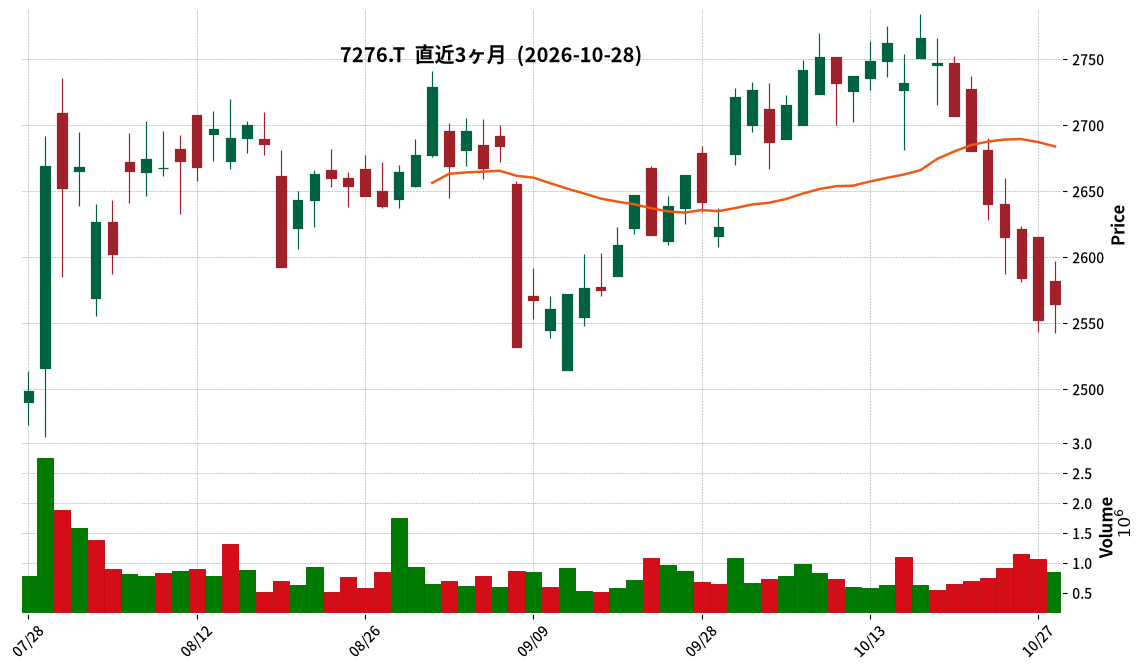
7276|小糸製
2564.5
▲ +0.47%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Koito Manufacturing Co., Ltd. has decided on an interim dividend of ¥32 per share for the record date of September 30, 2026.
- This interim dividend amount represents an increase of ¥4 from the most recent forecast (announced on July 29, 2026) of ¥28.
- The year-end dividend forecast for the fiscal year ending March 2027 has also been revised to ¥32 per share, an increase of ¥2.
- As a result, the annual dividend forecast for the fiscal year ending March 2027 is expected to be ¥64, an increase of ¥6 from the previous forecast of ¥58.
- The dividend source is retained earnings, and the effective date is December 4, 2026.
🤖 AI Perspective
This announcement suggests Koito Manufacturing’s reinforced commitment to shareholder returns. The upward revision of both interim and annual dividend forecasts is stated to be a comprehensive consideration of current business performance and the operating environment, reaffirming the company’s basic policy of stable and continuous dividends. This move may indicate a balance between ongoing business investments for sustainable growth and a dedication to rewarding shareholders.
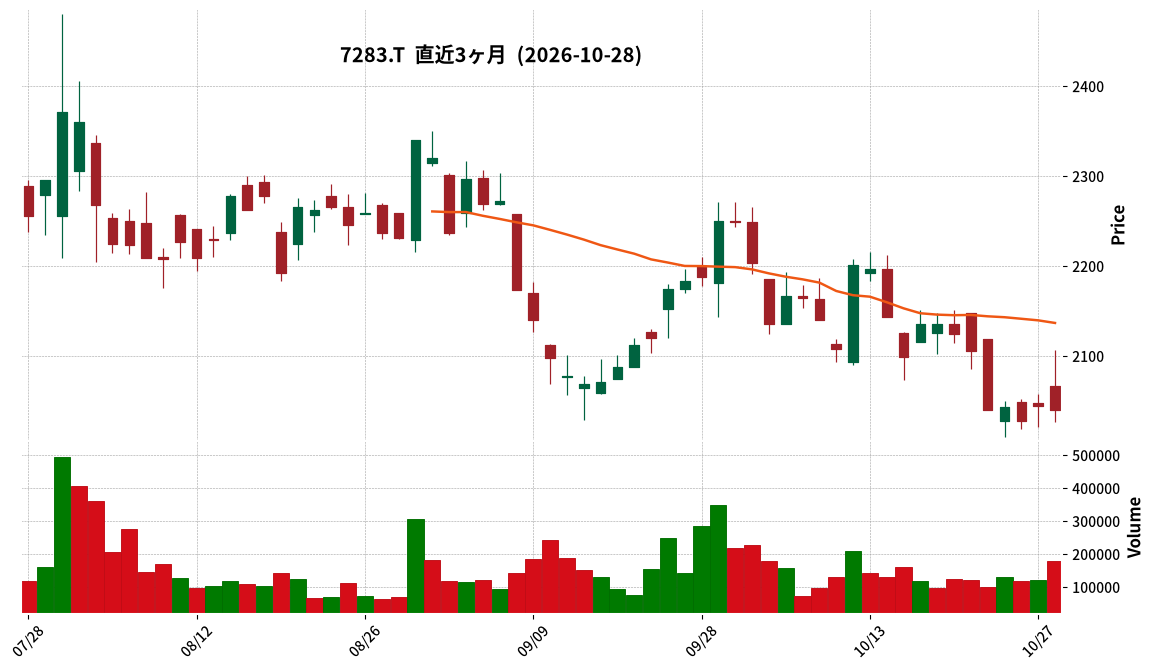
7283|愛三工
2040.0
▼ -0.20%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Aisan Industry revised its full-year consolidated earnings forecast for the fiscal year ending March 2027 upwards, as resolved at the Board of Directors meeting on October 28, 2026.
- The revised full-year consolidated forecast includes net sales of ¥340.0 billion (up 1.5% from previous forecast), operating profit of ¥20.5 billion (up 5.1%), ordinary profit of ¥21.0 billion (up 2.4%), and profit attributable to owners of parent of ¥13.8 billion (up 2.2%).
- The primary reasons for the revision are the depreciation of the yen during the interim consolidated accounting period and the positive effects of initiatives to strengthen earning power.
- The interim dividend for the record date of September 30, 2026, has been increased by ¥1 from the previous forecast of ¥41 to ¥42 per share.
- With the year-end dividend forecast remaining at ¥42 per share, the annual dividend will be ¥84, an increase of ¥1 from the previous forecast of ¥83.
🤖 AI Perspective
Aisan Industry’s announcement suggests that both the weakening yen and internal efforts to enhance earning power are positively impacting its performance. The simultaneous upward revision of the full-year earnings forecast and an increase in both interim and annual dividends could be seen as a commitment to shareholder returns, potentially drawing investor attention. The ongoing foreign exchange trends and the progress of its “strengthening earning power” initiatives will likely remain key factors for future performance monitoring.
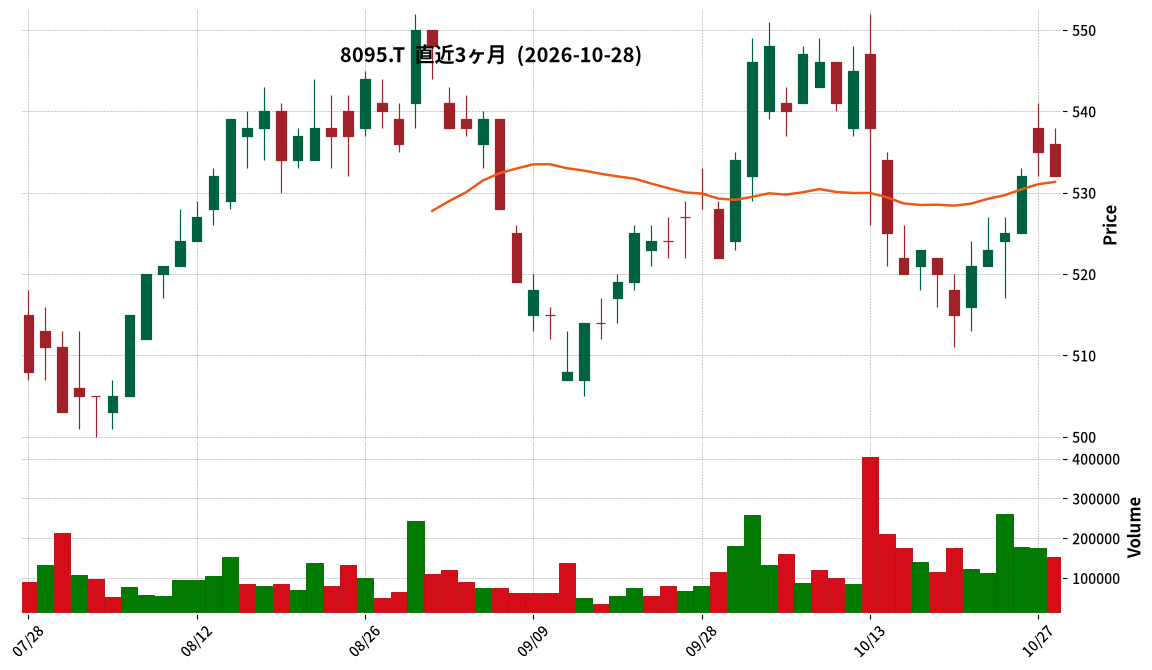
8095|アステナHD
532.0
▼ -0.56%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Astena Holdings Co., Ltd. announced a change in the determination method for shareholder benefit categories.
- Previously, benefit categories were determined based on the number of shares held at the end of November each year; this will change to a determination based on shareholdings at both the end of May and the end of November each year.
- The record date for benefits remains the end of November each year, with no change.
- “Continuous holding period” will be determined by the number of consecutive entries or records with the same shareholder number in the shareholder register at the end of May and the end of November each year, with 3 or more entries counting as “1 year or more” and 7 or more as “3 years or more.”
- “Continuous number of shares held” will be determined based on the number of shares held at the end of May and the end of November each year, confirming whether the required number of shares (500 shares or more, 1,000 shares or more, 3,000 shares or more) for each benefit category has been continuously held. This determination will begin from the end of November 2026.
- This change will apply to shareholder benefits with a record date of end of November 2027 onwards.
🤖 AI Perspective
This adjustment to the shareholder benefits program, moving from an annual to a semi-annual check of shareholdings, suggests the company’s intention to reinforce its commitment to long-term shareholders. Investors aiming to qualify for benefits may need to maintain consistent shareholdings throughout the year to meet the revised criteria, particularly for continuous holding period and share count. This change could encourage more strategic and sustained share ownership among investors seeking to benefit from the program.
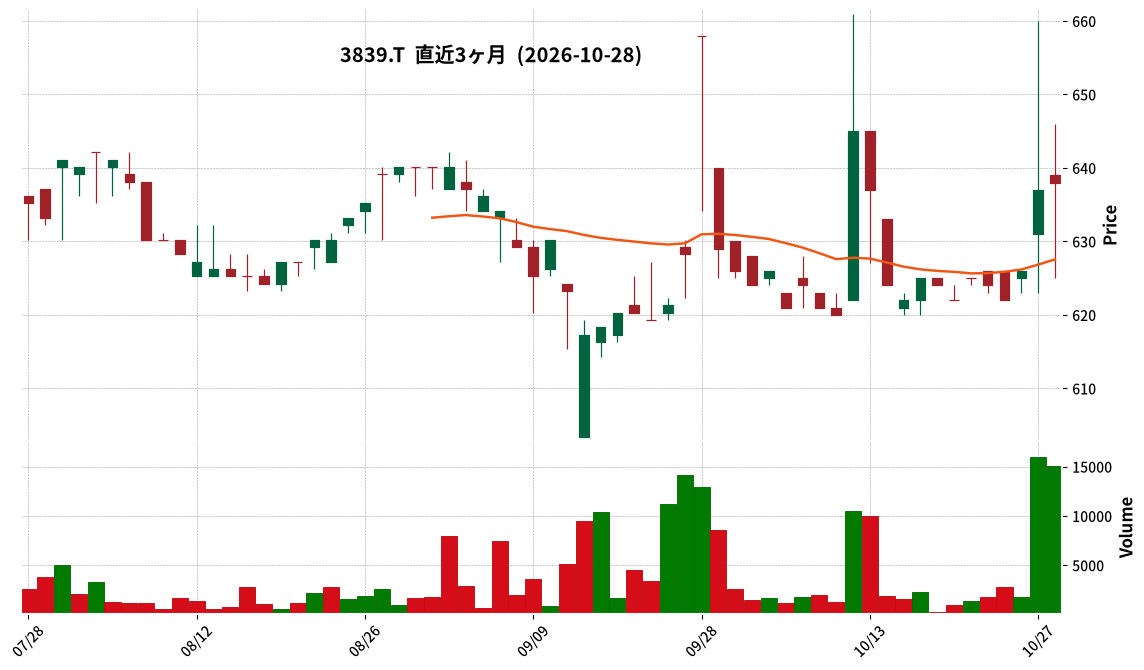
3839|ODK
638.0
▲ +0.16%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- For the second quarter of fiscal year 2027, ODK reported consolidated net sales of ¥2,020 million, a 3.8% decrease compared to the prior year’s interim period.
- During the same period, consolidated operating loss was ¥478 million, ordinary loss was ¥449 million, and net loss attributable to owners of parent was ¥391 million.
- Diluted earnings per share for the interim period were ¥-47.81.
- The full-year consolidated earnings forecast for fiscal year 2027 remains unchanged, projecting net sales of ¥7,000 million, operating income of ¥460 million, ordinary income of ¥500 million, and net income attributable to owners of parent of ¥300 million.
- The year-end dividend forecast is ¥5.00 per share, making the annual dividend ¥10.00 per share.
🤖 AI Perspective
While the interim consolidated results show a decrease in revenue and a net loss, the company notes that its business typically sees an increase in profits during the fourth quarter. The unchanged full-year forecast suggests an expectation for recovery in the latter half of the fiscal year. Investors may find it worthwhile to monitor the progress of strategic initiatives, such as the ‘Updemie®’ NFT-based business and enhanced solution offerings through M&A, as these could influence future performance.
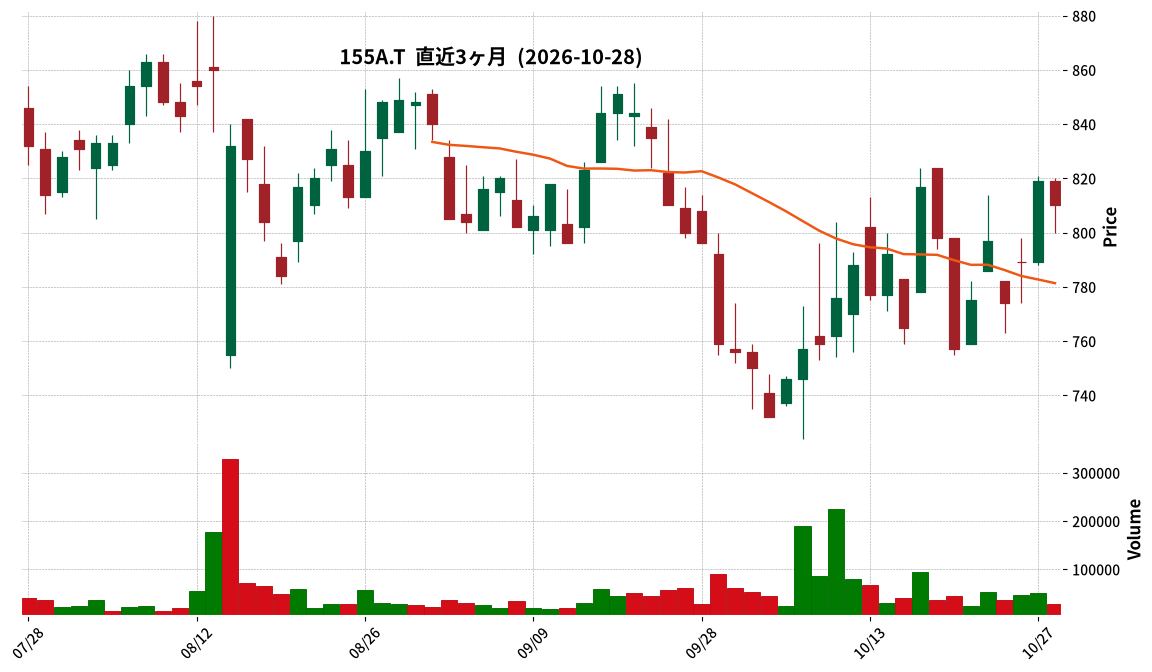
155A|G-情報戦略
810.0
▼ -1.10%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- G-Information Strategy Co., Ltd. announced on October 28, 2026, the postponement of its Q3 FY2026 financial results announcement.
- The Q3 financial results were initially scheduled for release on November 13, 2026.
- The delay is attributed to the time required for reviewing accounting treatment and finalizing financial figures, based on the investigation results mentioned in the September 18, 2026 press release concerning the “Setting of Record Date for Extraordinary General Meeting of Shareholders and Decision on Agenda (Dismissal of One Director) and Dismissal of Representative Director of our Subsidiary.”
- The company expects to receive the special investigation committee’s report by November 30, 2026, with the Q3 financial results scheduled for release in mid-December 2026.
- As of the current findings from the investigation, no events significantly impacting the company’s financial performance have been confirmed.
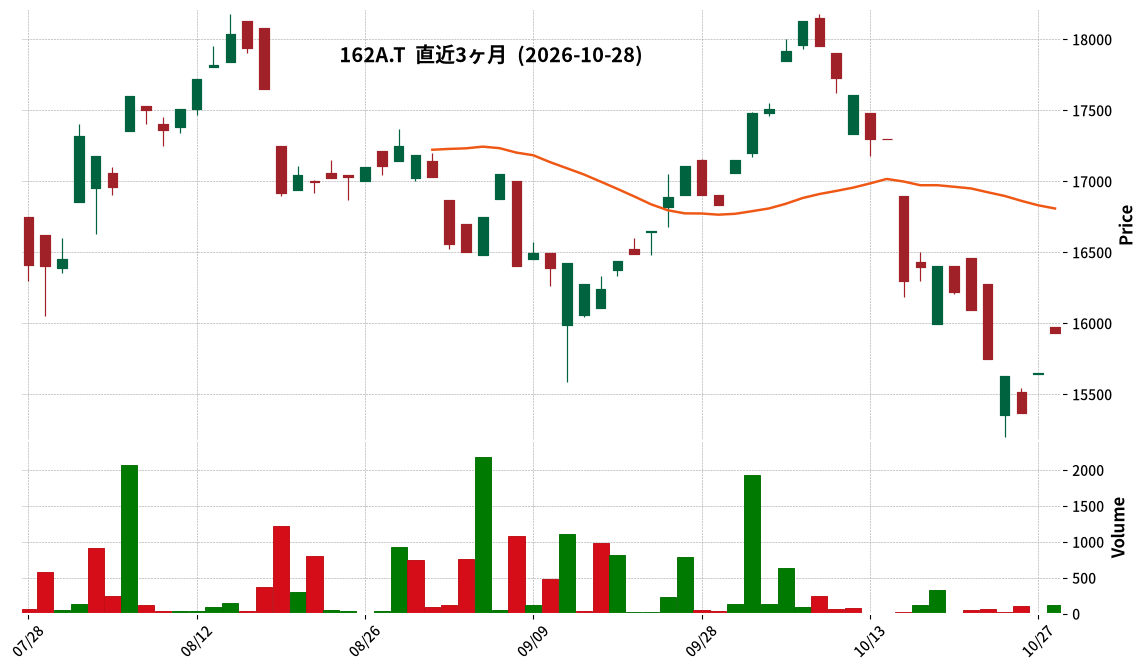
162A|AIセレクトETN
15930.0
▲ +1.79%
📎 Source:AIセレクトETN Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- AI Select ETN (issuer: Mitsubishi UFJ Securities Holdings Co., Ltd.) announced its H1 FY2027 financial results on October 28, 2026.
- For the H1 FY2027 period (April 1, 2026, to September 30, 2026), consolidated operating revenue was JPY 249,899 million, representing a 46.6% decrease compared to the same period last year.
- Net profit attributable to parent company shareholders increased by 64.4% year-on-year to JPY 39,361 million.
- Total assets stood at JPY 42,899,581 million, and net assets were JPY 790,736 million.
- As of October 26, 2026, the company’s own ETN issuance amounted to JPY 59,797 million, accounting for 7.6% of net assets.
- During the period from April 1, 2026, to September 30, 2026, additional units were observed for “AI Select Megatrend Japanese Stock ETN,” “Semiconductor Focus Japanese Stock ETN,” “Defense & Aerospace European Stock ETN,” “Data Center Infrastructure Japanese Stock ETN,” and “Defense Focus Japanese Stock ETN.” Notably, “Semiconductor Focus Japanese Stock ETN” saw an addition of 400,000 units, and “Data Center Infrastructure Japanese Stock ETN” and “Defense Focus Japanese Stock ETN” each had 300,000 units added.
🤖 AI Perspective
While operating revenue saw a significant decline, the substantial increase in net profit attributable to parent company shareholders may suggest shifts in the revenue structure or improved cost efficiency. The issuance activity across various ETNs indicates continued investor interest in specific themes. Strong additional issuance in semiconductor, data center infrastructure, and defense-related Japanese stock ETNs could reflect high market demand for these sectors. Conversely, redemptions in some ESG-related ETNs might indicate evolving investor preferences regarding thematic investments.
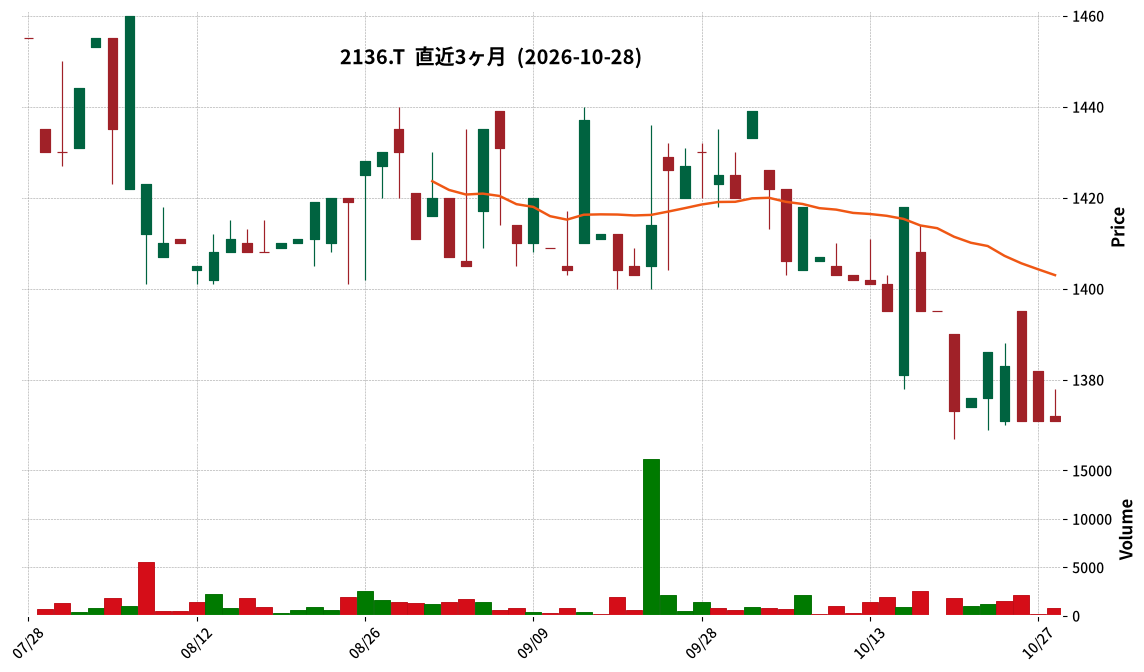
2136|ヒップ
1371.0
▲ +0.00%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- HIP Co., Ltd. announced the finalized financial results for its unlisted parent company, Best Planning Co., Ltd., for the fiscal year ended August 2026.
- Best Planning’s business activities include “acquisition, holding, and management of securities,” with a capital of 3 million yen.
- As of August 31, 2026, the balance sheet shows total assets of ¥1,342,351,480, total liabilities of ¥980,622,173, and total net assets of ¥361,729,307.
- For the period from September 1, 2025, to August 31, 2026, the income statement reported a net profit of ¥72,455,036 and ordinary profit of ¥82,858,636.
- Major shareholders are Yumiko Kameyama and Shinmei Tanaka (HIP’s Representative Director and President), each holding 50% of the shares.
🤖 AI Perspective
The financial health of an unlisted parent company can indirectly influence the management and stability of its listed subsidiary, making this disclosure relevant for investors. Best Planning’s focus on “acquisition, holding, and management of securities” suggests that its investment activities are performing well, as indicated by the reported financial figures. Furthermore, the fact that HIP’s Representative Director and President also serves as a major shareholder and representative director of the parent company is worth monitoring regarding overall group governance.
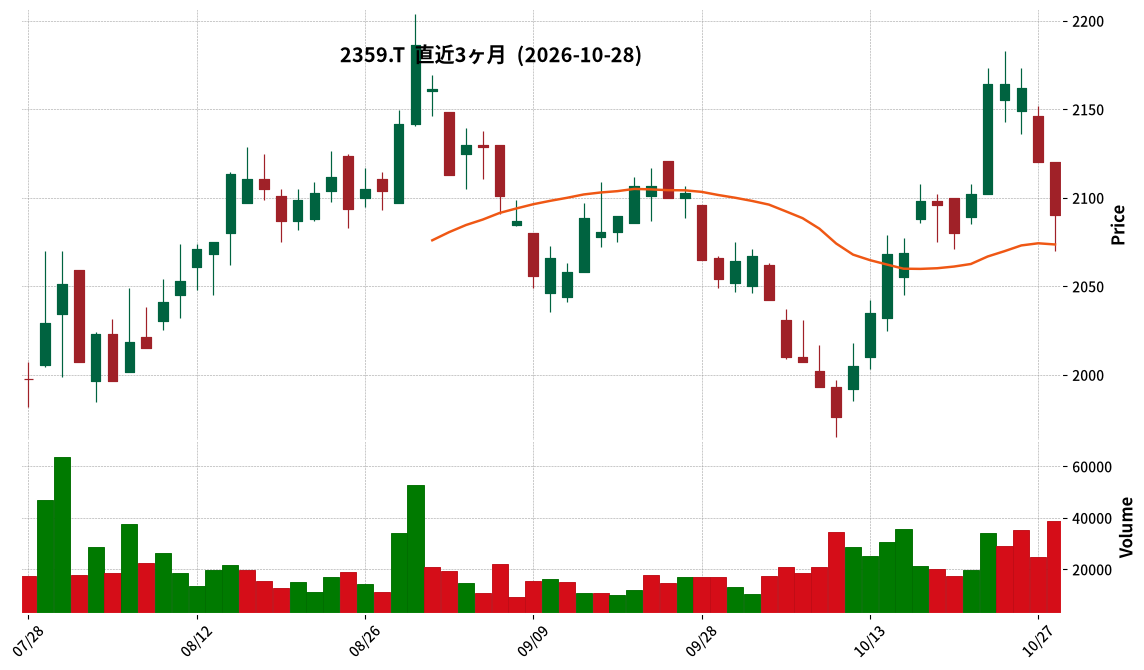
2359|コア
2090.0
▼ -1.42%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Core Co., Ltd. announced its consolidated financial results for the second quarter (interim period) of the fiscal year ending March 2027.
- Net sales for the interim period amounted to ¥13,458 million (up 9.3% year-on-year), operating income was ¥1,755 million (up 8.1% year-on-year), ordinary income was ¥1,828 million (up 10.1% year-on-year), and net income attributable to owners of parent was ¥1,228 million (up 8.0% year-on-year).
- By segment, the “Future Society Solution Business” reported net sales of ¥2,238 million (up 7.8% year-on-year) and operating income of ¥302 million (up 34.3% year-on-year). The “Industrial Technology Solution Business” generated net sales of ¥6,930 million (up 6.9% year-on-year) and operating income of ¥1,095 million (up 7.0% year-on-year). The “Customer Co-creation Business” recorded net sales of ¥4,290 million (up 14.2% year-on-year) and operating income of ¥357 million (down 4.5% year-on-year).
- The full-year consolidated earnings forecast remains unchanged from the most recently announced figures: net sales of ¥29,000 million (up 9.3% year-on-year), operating income of ¥4,200 million (up 10.0% year-on-year), ordinary income of ¥4,300 million (up 9.6% year-on-year), and net income attributable to owners of parent of ¥3,000 million (up 4.2% year-on-year).
- An interim dividend of ¥15.00 per share is planned, leading to a projected annual dividend of ¥65.00 per share (up ¥5.00 from the previous year) when combined with the year-end dividend forecast.
🤖 AI Perspective
Core’s Q2 FY2027 results indicate solid growth across all segments, with the Future Society Solution Business showing a notable increase in operating income, leading to overall revenue and profit growth for the interim period. This performance may suggest a positive impact from strong corporate IT investment, particularly in digital transformation (DX) initiatives. The company’s decision to maintain its full-year earnings forecast could indicate confidence in achieving its initial annual targets.
2760|東エレデバ
4700.0
▲ +2.84%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Tokyo Electron Device Co., Ltd. resolved to revise its consolidated earnings forecast for the fiscal year ending March 2027 at a Board of Directors meeting held on October 28, 2026.
- The revised consolidated earnings forecast for FY2027 projects net sales of ¥270,000 million (up 12.5% from previous forecast), ordinary profit of ¥16,000 million (up 17.6%), and profit attributable to owners of parent of ¥11,000 million (up 17.0%).
- The interim dividend for shareholders of record as of September 30, 2026, was set at ¥69.00 per share (an increase of ¥9.00 from the previous forecast).
- The year-end dividend forecast for FY2027 was revised to ¥82.00 per share (an increase of ¥13.00 from the previous forecast).
- Consequently, the full-year dividend forecast for FY2027, including the interim dividend, is ¥151.00 per share (an increase of ¥22.00 from the previous forecast).
🤖 AI Perspective
The upward revision of the earnings forecast is primarily attributed to expanding semiconductor demand and robust corporate IT investments. The company specifically highlights the surge in AI demand as a driver for strong demand for semiconductor and IT products, suggesting that the supply chain situation may warrant continued monitoring for its potential impact on performance. The decision to increase dividends, based on a consolidated dividend payout ratio target of 40%, in conjunction with the revised earnings forecast, may indicate the company’s commitment to shareholder returns.
3093|トレファク
1830.0
▼ -2.50%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- For the second quarter of FY2027 (June-August), Treasure Factory achieved over 10% growth in both net sales and operating profit year-over-year, with operating profit increasing by +12.5% compared to the prior year period.
- Operating profit for the first half (March-August) reached 2,330 million yen, exceeding plans with a +21.5% increase year-over-year, but the full-year earnings forecast remains unchanged.
- Reasons cited for maintaining the full-year forecast include the tapering off of margin improvement effects from a change in the purchase coupon policy in the previous third quarter, anticipated expenses for logistics center relocation and new branch openings for in-home purchasing services, and concentrated new store opening costs in the second half.
- The interim dividend increased by 5 yen year-over-year to 24 yen, while the year-end dividend forecast of 22 yen (annual 46 yen, +6 yen YoY) remains unchanged, with a review to be considered based on second-half performance trends.
- Regarding the personal information leakage incident at a subsidiary, the company has acknowledged it as a group-wide governance issue and is implementing preventive measures, including an inventory of IT tools and regular meetings of the Information Security Liaison Council.
🤖 AI Perspective
The decision to maintain the full-year forecast despite strong first-half results suggests a cautious outlook for the second half, influenced by anticipated increases in investment costs and the normalization of certain policy benefits. For investors, the second-half performance will be a key factor in any potential review of the year-end dividend. The company’s proactive measures against cybersecurity risks are critical for maintaining stakeholder trust and could be a focus for future governance assessments.
4373|シンプレクスHD
1246.0
▼ -0.32%
📎 Source:シンプレクスHD Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Simplex HD announced its consolidated financial results for the second quarter of the fiscal year ending March 2027.
- Revenue reached ¥33,122 million, an increase of 19.1% year-on-year, setting a new record for the interim period.
- Operating profit stood at ¥7,397 million, up 4.8% year-on-year, while profit attributable to owners of the parent was ¥4,810 million, a 0.7% increase year-on-year.
- By service type, all segments—Strategy/DX Consulting, System Integration, and Operation Services—reported higher revenue and gross profit margins compared to the prior year.
- The full-year consolidated earnings forecast for FY2027 has been revised, projecting revenue of ¥71,000 million (up 21.0% year-on-year) and profit attributable to owners of the parent of ¥12,420 million (up 17.9% year-on-year).
🤖 AI Perspective
Simplex HD’s Q2 FY2027 results indicate strong revenue growth, reaching a new record high, with consistent performance across all service segments. The increase in selling, general and administrative expenses, and research and development costs suggests active investments, particularly in generative AI-related R&D. The upward revision of the full-year earnings forecast could signal confidence in continued business expansion.
4832|JFE-SI
1923.0
▲ +1.16%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- JFE Systems, Inc. announced its consolidated financial results for the second quarter of the fiscal year ending March 2027.
- For the six months ended September 30, 2026, consolidated cumulative operating results were: Net Sales of ¥26,466 million (down 9.5% year-on-year), Operating Income of ¥2,295 million (down 13.9% year-on-year), Ordinary Income of ¥2,396 million (down 11.5% year-on-year), and Net Income Attributable to Owners of Parent of ¥1,528 million (down 13.4% year-on-year).
- As of the end of the interim period, consolidated financial position showed Total Assets of ¥53,309 million, Net Assets of ¥37,149 million, and an Equity Ratio of 67.4%.
- The full-year dividend forecast for the fiscal year ending March 2027 remains unchanged at ¥70 per share, but the interim dividend forecast was revised upward from ¥22 to ¥24 per share, with the year-end dividend forecast revised from ¥48 to ¥46 per share.
- The consolidated full-year earnings forecast for the fiscal year ending March 2027 remains unrevised from the previous forecast, targeting Net Sales of ¥60,000 million, Operating Income of ¥6,600 million, Ordinary Income of ¥6,800 million, and Net Income Attributable to Owners of Parent of ¥4,380 million.
🤖 AI Perspective
The interim period results indicate a decrease in revenue, attributed to the completion of a major project in the steel business. However, the company is prioritizing DX, ERP solutions, and foundational services as key growth areas under its mid-term management plan, which may suggest a strategic shift in business focus. Despite the decline in profits, the upward revision of the interim dividend, while maintaining the full-year forecast, could signal the company’s commitment to shareholder returns and confidence in its full-year performance. Investors may wish to monitor the progress in the second half of the fiscal year to assess the impact of these strategic initiatives.
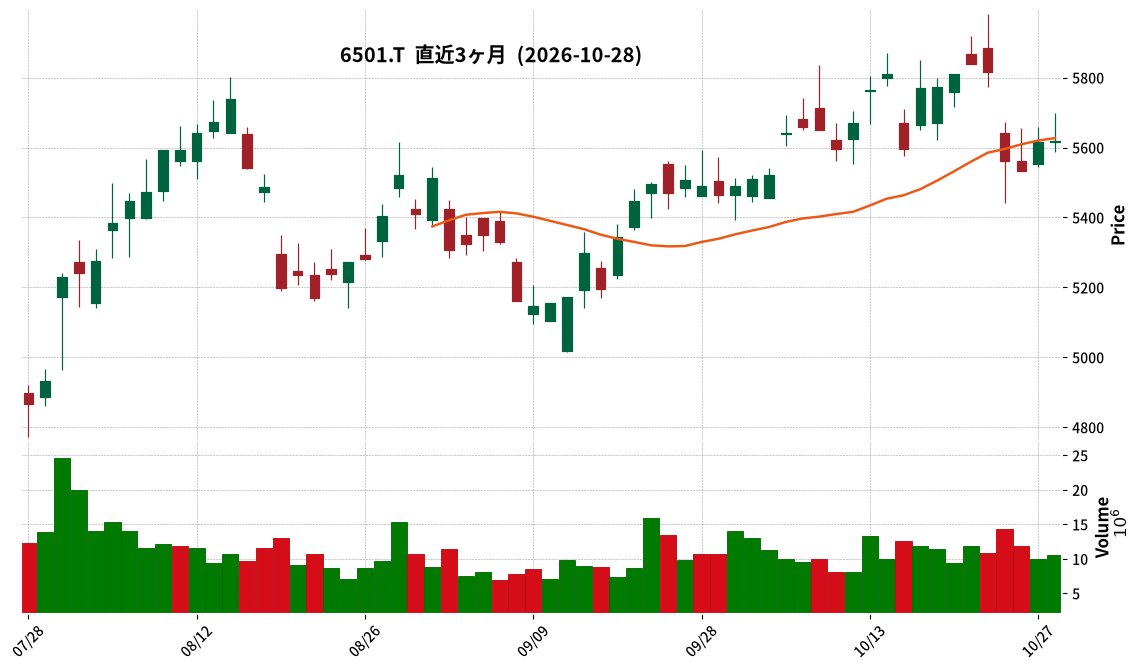
6501|日立
5620.0
▲ +0.09%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Hitachi, Ltd. announced its Consolidated Financial Results for the Second Quarter (Interim) of Fiscal Year 2027 (IFRS) on October 28, 2026.
- Consolidated revenue for the interim period of FY2027 reached ¥5,614,028 million, representing a 17.3% increase compared to the prior interim period.
- Consolidated Adjusted Operating Income was ¥643,260 million, a 26.6% increase from the prior interim period.
- Net income attributable to owners of the parent for the interim period was ¥416,621 million, an 11.9% decrease year-on-year.
- The interim dividend forecast for FY2027 was revised to ¥32.00 per share.
- The full-year consolidated forecast for FY2027 was also revised, projecting revenue of ¥12,000,000 million (a 13.3% increase year-on-year) and net income attributable to owners of the parent of ¥920,000 million (a 14.7% increase year-on-year).
🤖 AI Perspective
While Hitachi reported strong growth in revenue and adjusted operating income, the decline in net income attributable to owners of the parent may warrant further examination by investors to understand the underlying causes, which could include factors outside of operating performance such as changes in financial income or expenses. The revision of the dividend forecast and the upward adjustment of the full-year earnings forecast could be interpreted as an indication of management’s confidence in future performance.
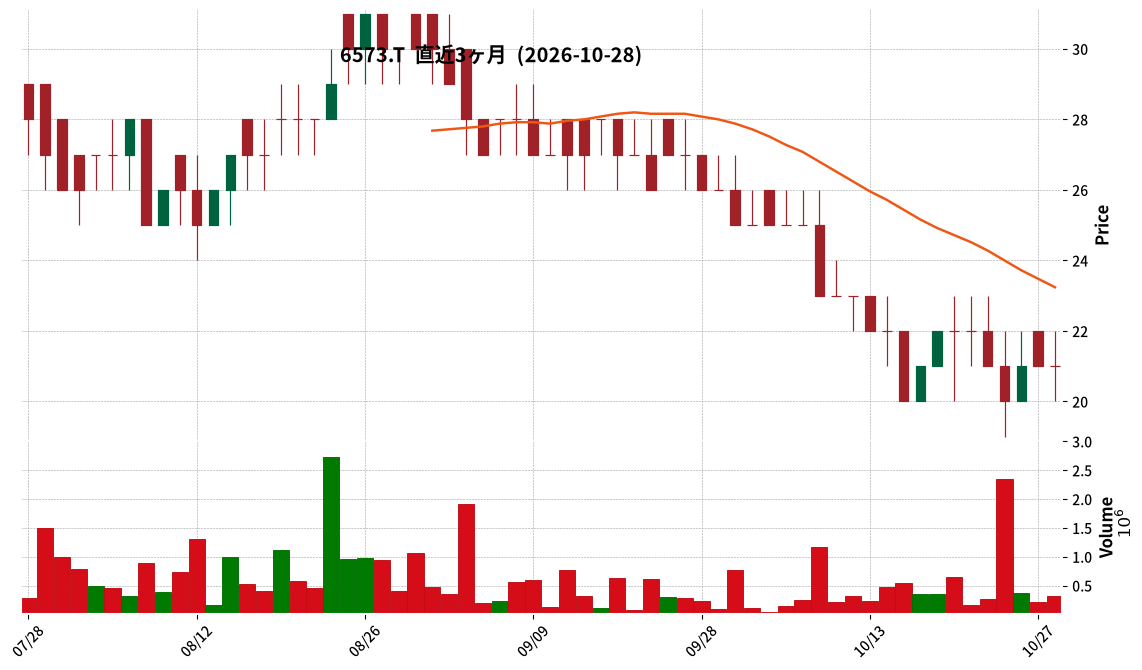
6573|G-CRAVIA
21.0
▲ +0.00%
📎 Source:G-CRAVIA Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- CRAVIA Inc. announced a change to the previously disclosed terms of a loan to Redstart ENM Inc. (South Korea), originally announced on October 6, 2026.
- The reason for the change is a review of the loan agreement terms, considering foreign exchange transaction procedures in South Korea and Redstart ENM’s specific current funding needs.
- The revised total loan amount is 500,000,000 Korean Won (equivalent to 55,000 thousand Japanese Yen) (previously 1,500,000,000 Korean Won, or 165,000 thousand Japanese Yen).
- The number of loan installments has been changed to one, with no additional loans decided at this time (previously planned for three installments).
- The scheduled loan execution date has been changed to October 30, 2026 (previously scheduled for October 6, 2026).
- The company anticipates that this change will have a minor impact on its consolidated performance for the fiscal year ending December 2026.
🤖 AI Perspective
G-CRAVIA’s amendment to the loan terms for Redstart ENM Inc. suggests an adjustment from the initial plan. The reduction in the total loan amount and the number of installments could be attributed to changes in the recipient company’s funding requirements or adaptations to foreign exchange procedures. Investors may continue to monitor how this change impacts the progress of the capital and business alliance with Redstart ENM and G-CRAVIA’s broader global strategy.
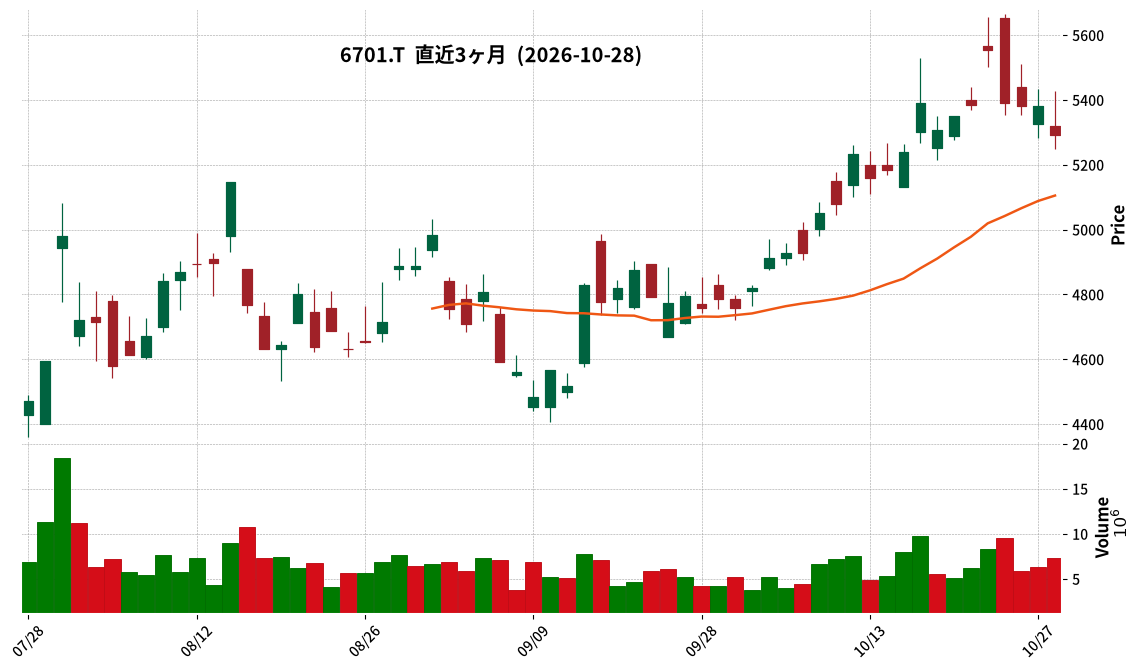
6701|NEC
5292.0
▼ -1.65%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- For the first half of FY2027 (April 1, 2026, to September 30, 2026), consolidated revenue was ¥1,753,857 million, an increase of 11.7% year-on-year.
- Consolidated operating profit was ¥146,154 million, a 23.3% increase year-on-year.
- Net income attributable to owners of the parent was ¥116,439 million, a significant 59.9% increase year-on-year.
- Non-GAAP operating profit reached ¥188,298 million, up 47.7% year-on-year.
- The full-year consolidated performance forecast for FY2027 has been revised upwards, with revenue now projected at ¥3,740,000 million (+4.4% from previous forecast), Non-GAAP operating profit at ¥460,000 million (+15.8%), and Non-GAAP net income attributable to owners of the parent at ¥310,000 million (+10.8%).
- The dividend forecast remains unchanged at ¥20.00 for the interim and ¥20.00 for the year-end, totaling ¥40.00.
- The scope of consolidation significantly changed with the addition of 47 new companies, including CSG Systems International, Inc., during the interim period.
🤖 AI Perspective
NEC’s H1 FY2027 results show substantial growth across key financial metrics, with net income attributable to owners of the parent increasing by nearly 60% year-on-year. This strong performance, coupled with an upward revision of the full-year forecast, may suggest a positive outlook for the company’s operational trajectory. The significant increase in Non-GAAP operating profit also highlights the underlying business performance, which investors may find noteworthy.
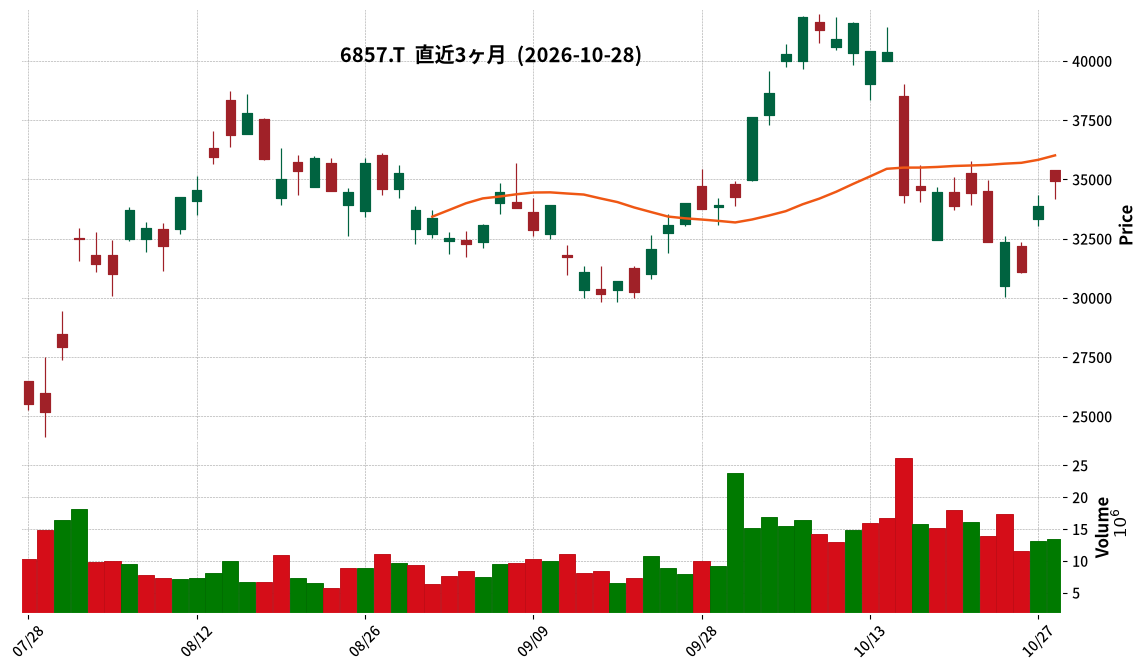
6857|アドバンテス
34930.0
▲ +3.16%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Advantest announced consolidated results for the second quarter (interim period) of the fiscal year ending March 2027, reporting revenue of ¥845.2 billion (+60.5% YoY), operating profit of ¥456.8 billion (+96.5% YoY), profit before tax for the interim period of ¥510.2 billion (+121.3% YoY), and interim profit attributable to owners of the parent of ¥368.1 billion (+116.8% YoY).
- These figures represent record highs for an interim consolidated accounting period across all respective categories.
- Basic earnings per share for the interim period of FY2027 was ¥508.99.
- The interim dividend forecast for FY2027 was revised from the previously announced ¥29 to ¥49. The full-year dividend forecast remains undetermined.
- The consolidated full-year earnings forecast for FY2027 was also revised upwards, projecting revenue of ¥1,863.0 billion (+65.1% YoY) and operating profit of ¥967.0 billion (+93.7% YoY).
- The Test System Business segment reported revenue of ¥770.2 billion (+61.2% YoY), and the Services and Others segment recorded revenue of ¥75.0 billion (+53.7% YoY).
- The average exchange rates for the interim period were USD 160 (vs. 146 in prior year) and EUR 185 (vs. 166 in prior year).
🤖 AI Perspective
Advantest’s latest earnings report reveals significant year-over-year growth in key financial metrics, with revenue and profits reaching new record highs for an interim period. This performance appears to be primarily driven by the expanding AI-related semiconductor market and the resulting increase in demand for testers. The upward revision of both the interim dividend forecast and the full-year earnings outlook may suggest management’s strong confidence in the company’s future business prospects.
6955|FDK
381.0
▲ +0.00%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- FDK Corporation announced its consolidated financial results for the second quarter (H1) of the fiscal year ending March 2027.
- Net sales for the interim period amounted to ¥28,482 million, a 4.3% decrease compared to the same period in the previous year.
- Operating profit was ¥477 million, representing a 13.7% decrease year-on-year.
- Net loss attributable to owners of parent was ¥103 million, contrasting with a profit of ¥121 million in the prior year’s interim period. This loss includes an impairment loss of ¥207 million related to fixed assets in the alkaline battery business.
- The full-year consolidated earnings forecast remains unchanged from the most recent public announcement, projecting net sales of ¥60,000 million, operating profit of ¥1,400 million, and net profit attributable to owners of parent of ¥750 million.
- FDK KOREA LTD. was newly included in the scope of consolidation during this interim period.
🤖 AI Perspective
The decline in interim sales and profits, despite growth in the battery segment (nickel-metal hydride and lithium batteries), suggests that a decrease in the electronics business significantly impacted the overall results. The reported net loss is attributed to an impairment loss related to the alkaline battery business, which might lead investors to monitor FDK’s future business portfolio strategies. The unchanged full-year forecast could imply that the company anticipates a recovery in the second half of the fiscal year.
4722|フューチャー
2428.0
▲ +0.00%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Future Corporation announced its consolidated financial results for the third quarter of the fiscal year ending December 2026 (January 1, 2026 – September 30, 2026).
- Net sales reached ¥58,441 million, marking a 5.7% increase compared to the same period of the previous fiscal year.
- EBITDA was ¥13,721 million (down 3.2% year-on-year), operating profit was ¥11,217 million (down 4.2% year-on-year), and profit attributable to owners of parent was ¥7,826 million (down 1.1% year-on-year).
- The decrease in operating profit and profit attributable to owners of parent is attributed to the反動(reaction) from initial licenses for the next-generation banking system introduced by multiple financial institutions in the prior year.
- The consolidated full-year forecast for the fiscal year ending December 2026 remains unchanged, projecting net sales of ¥80,600 million, operating profit of ¥17,500 million, and profit attributable to owners of parent of ¥11,800 million.
🤖 AI Perspective
Future’s Q3 results show solid revenue growth, but the prior year’s one-off factors impacted current period profits. The progress in new introductions of the “next-generation banking system” within the IT Consulting & Service segment appears to be a key area for future growth. Investors may focus on the underlying business growth excluding the temporary profit fluctuations and the company’s trajectory towards achieving its full-year forecasts.
9698|クレオ
1232.0
▼ -1.99%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- CREO Co., Ltd. released its supplementary financial results for the second quarter of the fiscal year ending March 2027 on October 28, 2026.
- Consolidated highlights show net sales of ¥7,068 million (up 0.2% year-on-year), operating profit of ¥527 million (up 16.7% year-on-year), and net income of ¥341 million (up 15.9% year-on-year).
- By segment, the Solution Services business reported net sales of ¥2,796 million (up 9.6% year-on-year) and segment profit of ¥574 million (up 29.0% year-on-year).
- The System Operation and Services business recorded net sales of ¥909 million (down 17.8% year-on-year) and operating profit of ¥94 million (down 34.0% year-on-year), showing a decline.
- The consolidated earnings forecast for the fiscal year ending March 2027 remains unchanged from the announcement made on May 13, 2026.
🤖 AI Perspective
This quarter’s results indicate growth in profitability, with double-digit increases in both operating profit and net income, despite a modest rise in consolidated net sales. The robust performance of the Solution Services business, marked by significant increases in both sales and segment profit, appears to be a primary driver of overall earnings. Conversely, the weaker performance of the System Operation and Services business might have tempered the overall sales growth.
7241|フタバ産
992.0
▼ -1.20%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Futaba Sangyo Co., Ltd. announced its consolidated financial results for the second quarter of the fiscal year ending March 2027 on October 28, 2026.
- For the interim period, consolidated net sales increased by 6.7% year-on-year to JPY 351.5 billion.
- Consolidated operating profit was JPY 7.8 billion (down 8.6% YoY), ordinary profit was JPY 6.9 billion (down 20.6% YoY), and net income attributable to owners of parent was JPY 4.5 billion (down 28.8% YoY).
- The full-year consolidated earnings forecast has been revised, projecting net sales of JPY 713.0 billion, operating profit of JPY 18.0 billion, and net income attributable to owners of parent of JPY 12.0 billion.
- In the China segment, sales were JPY 21.1 billion (down 35.7% YoY) and segment profit was JPY 0.1 billion (down 87.5% YoY).
🤖 AI Perspective
The interim results show a notable increase in sales but a decrease in profits, which may suggest that cost or operational challenges outweighed revenue growth. The significant decline in sales and profit from the China segment appears to be a key factor contributing to the overall profit reduction, indicating regional market dynamics are worth monitoring. The revised full-year forecast could reflect the company’s updated outlook on these factors and future performance.
9360|鈴与シンワ
2750.0
▼ -0.72%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Suzuyo Shinwart Co., Ltd. has decided to acquire 70.0% of the shares of TOCQ Systems Co., Ltd., making it a consolidated subsidiary.
- A third-party allotment of treasury shares will be executed as part of the consideration for this acquisition, involving 20,974 shares at ¥2,770 per share, totaling ¥58 million.
- TOCQ Systems’ business operations include system consulting, system development, and AI utilization solution proposals.
- The effective date for the stock acquisition is scheduled for November 30, 2026, with an estimated acquisition cost of ¥238 million (including ¥232 million for share acquisition and ¥6 million for due diligence).
- Through the treasury share allotment, the sellers of TOCQ Systems, Mr. Tatsuki Tani and Mr. Hisashi Yoshida, will become shareholders of Suzuyo Shinwart, aiming to enhance their commitment to the group’s management and contribute to business expansion.
🤖 AI Perspective
Suzuyo Shinwart’s decision to acquire TOCQ Systems, a long-standing business partner, highlights its commitment to strengthening AI services and system development capabilities. The use of treasury shares as partial consideration suggests an intention to integrate the acquired company’s management into the Suzuyo Shinwart Group, fostering long-term alignment. Investors may monitor how this strategic move, aimed at establishing AI-driven services, will translate into enhanced corporate value over the mid-to-long term.
3234|R-森ヒルズ
117000.0
▼ -1.52%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- R-Mori Hills announced a correction to its “Fiscal Year ended July 2026 Financial Results (REIT)”, originally published on September 14, 2026.
- The reason for the correction was an omission in the previously disclosed information.
- The specific section corrected is “3. Reference Information (2) Investment Assets ③ Other Major Investment Assets a. Overview of Trust Real Estate v) Overview of Leases to Related Parties.”
- The corrected totals for related-party leases changed from “Total 122,691.65 sqm, 67.4%, ¥14,023,807 thousand” to “Total 122,742.01 sqm, 67.5%, ¥14,027,455 thousand.”
- The revised information now includes Mori Building Hospitality Corporation as an end tenant, with a lease agreement for Roppongi View Tower covering 50.36 sqm, generating annual rent of ¥3,648 thousand, under a fixed-term building lease contract expiring on September 30, 2029.
🤖 AI Perspective
This correction addresses an omission in the previously published financial report regarding related-party lease information. While the newly added lease contract represents a small proportion of the total leased area and annual rent income, it contributes to improved transparency in the disclosed financial data. Investors may view this rectification as a positive step towards ensuring the accuracy of public disclosures.
9307|杉村倉庫
934.0
▲ +0.21%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Sugimura Warehouse Co., Ltd. announced its consolidated financial results for the second quarter (interim period) of the fiscal year ending March 2027.
- Consolidated operating revenue for the interim period was ¥5,602 million, a 1.0% increase compared to the prior interim period.
- Consolidated operating income decreased by 5.5% to ¥622 million compared to the prior interim period.
- Net income attributable to owners of the parent was ¥449 million, a 0.2% decrease from the prior interim period.
- Interim basic earnings per share stood at ¥27.49, a slight decrease from ¥27.57 in the prior interim period.
- The full-year consolidated earnings forecast remains unchanged from the previously announced figures: operating revenue of ¥11,200 million, operating income of ¥1,260 million, ordinary income of ¥1,280 million, and net income attributable to owners of the parent of ¥860 million.
- The year-end dividend forecast is ¥5.00, with an annual dividend forecast of ¥15.00, consistent with previous disclosures.
🤖 AI Perspective
While operating revenue showed growth in the interim period, the decline in operating income suggests increased operating costs, particularly personnel expenses and depreciation in the logistics business. The real estate segment also saw revenue growth but experienced a decrease in profit due to rising management expenses. Monitoring the company’s cost management efforts in the latter half of the fiscal year will be key. The unchanged full-year forecast indicates management’s expectation for a recovery or stability in the remaining period.
2031|ハンセンブル
—
▲ +0.00%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Hansenbull (Nomura Europe Finance N.V.) announced its Q2 FY2027 financial results (for its ETNs) on October 28, 2026, covering the period from April 1, 2026, to September 30, 2026.
- Detailed financial information for the guarantor, Nomura Holdings, Inc., for Q2 FY2027 is referenced to their separately disclosed “Consolidated Financial Results for the Second Quarter of Fiscal Year ending March 31, 2027 [U.S. GAAP]”.
- As of October 27, 2026, the guarantor’s credit ratings include A+ (Outlook: Stable) from Rating and Investment Information, Inc., AA- (Outlook: Stable) from Japan Credit Rating Agency, Ltd., Baa1 (Outlook: Stable) from Moody’s Investors Service, BBB+ (Outlook: Positive) from S&P Global Ratings, and A- (Outlook: Stable) from Fitch Ratings.
- The total outstanding amount of index-linked securities as of October 27, 2026, is JPY 172,100 million (self-issued), with JPY 0 million guaranteed by other companies, resulting in a total of JPY 172,100 million. This represents 4.38% of net assets.
- Regarding the issuance status of index-linked securities trust beneficial interests in Japan, as of October 27, 2026, “NEXT NOTES Dubai Crude Oil Double-Bull ETN” saw a redemption of 8,000,000 units during the period, while “NEXT NOTES Dubai Crude Oil Bear ETN” had an additional subscription of 5,000,000 units.
🤖 AI Perspective
This IR release provides essential information for investors in ETNs issued by Hansenbull, focusing on the financial health and credit ratings of the guarantor, Nomura Holdings, and the issuance status of the ETNs themselves. The guarantor’s creditworthiness is a key factor for ETN investors, as it directly relates to the ETN’s credit risk. Changes in the number of outstanding units (additional subscriptions or redemptions) for specific ETN products could also indicate shifts in market demand for those particular instruments.
274A|ガーデン
2054.0
▼ -0.39%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Garden Inc. disclosed the Q&A summary from its Q2 FY2027 earnings briefing, held on October 16, 2026, on October 28, 2026.
- The flagship brand “Ikkakuya” has approximately 600,000 cumulative app members and 170,000 active members, with new monthly sign-ups increasing to 20,000-30,000.
- The first store in Thailand is performing strongly with sales 140% above plan, but its impact on overall company performance is currently minor.
- Regarding the decrease in operating profit from 184 million yen in Q1 to 33 million yen in Q2, the company acknowledged falling short of budget in March and incorporated measures for the second half and a downward revision of the full-year forecast.
- The company is considering measures against soaring raw material costs, including reviewing suppliers, utilizing central kitchens, and M&A for cost reduction. It also stated that impairment losses are being discussed with auditors and are partly factored into the revised full-year forecast.
🤖 AI Perspective
The Q&A session provides insights into the current state and challenges of the core business, as well as management’s recognition and actions. While the growth in app members and strong overseas performance present potential drivers, the delay in existing store recovery and rising costs are areas warranting close attention. The impact of the management’s indicated supply chain reforms and recovery measures on future financial performance will be a key point for investors to monitor.
284A|P-フクヤ建設
2335.0
▲ +0.00%
📎 Source:P-フクヤ建設 Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- P-FUKUYA CONSTRUCTION decided to acquire all shares of Woodplan Co., Ltd., making it a subsidiary, at its Board of Directors meeting on October 28, 2026.
- Woodplan Co., Ltd. specializes in custom home construction, design, and execution, as well as bespoke furniture manufacturing and sales.
- P-FUKUYA CONSTRUCTION will acquire 500 shares, resulting in a 100% voting rights ownership ratio after the transaction.
- The acquisition price remains undisclosed at the request of the counterparty, but it was determined based on fair net asset value, among other factors, following an assessment by a third-party institution.
- Woodplan’s financial results for the fiscal year ended July 2026 reported sales of 622 million JPY, operating loss of 42 million JPY, ordinary loss of 30 million JPY, and net loss of 32 million JPY.
🤖 AI Perspective
This acquisition suggests P-FUKUYA CONSTRUCTION’s strategic move to enhance long-term growth and corporate value through anticipated synergies with its existing construction business. While Woodplan Co., Ltd. recently reported a loss, its integration into P-FUKUYA CONSTRUCTION’s business structure could potentially lead to improved financial performance and business expansion. The company’s plan to finance the acquisition through borrowing from financial institutions and its ongoing assessment of the transaction’s impact on future earnings are worth monitoring.
3189|ANAP
60.0
▲ +5.26%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- ANAP Holdings’ subsidiary, ANAP Lightning Capital (ALC), has entered into a share subscription agreement and a basic business alliance agreement with Japan Bitcoin Industry Co., Ltd. (JBI).
- ALC will subscribe to a third-party allotment of new shares issued by JBI through an in-kind contribution of Bitcoin held by ALC.
- The capital alliance involves acquiring 268,000 common shares at JPY 2,980 per share, totaling JPY 798,640,000, with payment made via Bitcoin in-kind contribution.
- Following this third-party allotment, ALC’s voting rights ratio in JBI is expected to be 19.96%.
- In the business alliance, JBI will support ALC’s Lightning Network (LN) operations, ALC will provide liquidity to JBI-operated LN nodes using its Bitcoin, and both companies will foster LN engineers and disseminate information.
🤖 AI Perspective
This announcement indicates a tangible step forward in ANAP Group’s previously stated “Bitcoin business” strategy. The in-kind contribution of Bitcoin by subsidiary ALC suggests a strategic utilization of held cryptocurrency as business capital. This partnership with JBI to enter the Lightning Network-based payment infrastructure business could be seen as an effort to establish new revenue streams within the evolving digital asset ecosystem.
3843|フリービット
1745.0
▼ -0.29%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Freebit Co., Ltd. announced its consolidated financial results for the fiscal year ended April 2026.
- Consolidated net sales reached ¥62,742 million (up 13.9% year-on-year), operating profit was ¥6,888 million (up 17.1%), ordinary profit was ¥6,619 million (up 26.5%), and profit attributable to owners of parent was ¥4,154 million (up 51.2%).
- Earnings per share (EPS) stood at ¥190.53, and diluted EPS was ¥188.82.
- The year-end dividend for the fiscal year ended April 2026 was ¥41.00 per share, bringing the total annual dividend to ¥41.00, an increase from the previous year.
- For the fiscal year ending April 2027, the company forecasts consolidated net sales of ¥66,000 million (up 5.2% year-on-year), operating profit of ¥7,250 million (up 5.2%), and profit attributable to owners of parent of ¥4,500 million (up 8.3%).
🤖 AI Perspective
Freebit’s FY2026 consolidated results show significant growth across all key financial metrics, with net profit seeing a substantial increase, which may suggest strong operational performance. The announced dividend increase could indicate a positive outlook from management and a commitment to shareholder returns. The company’s FY2027 forecasts project continued growth, making its future business trajectory worth monitoring for investors.
428A|サイプレスHD
1813.0
▼ -0.22%
📎 Source:サイプレスHD Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Cypress Holdings Co., Ltd. announced corrections to its “Consolidated Financial Results for the Fiscal Year Ended August 2026 [IFRS]” originally released on October 7, 2026.
- The corrections apply to four sections: “1. Overview of Operating Results (1) Overview of Operating Results for the Current Period”, “2. Overview of Operating Results (2) Overview of Financial Position for the Current Period”, “3. Consolidated Financial Statements and Key Notes (1) Consolidated Statement of Financial Position”, and “3. Consolidated Financial Statements and Key Notes (5) Notes to Consolidated Financial Statements (Per Share Information)”.
- Specific revisions include monthly store count for September 2025 (from 124 stores to 127 stores), total current liabilities (from 5,712,037 thousand yen to 5,712,439 thousand yen), total non-current liabilities (from 3,988,901 thousand yen to 3,988,499 thousand yen), and a change in the description of dilutive shares from “share options” to “stock options” with revised numerical values in per-share information.
- The total liabilities remain unchanged at 9,700,938 thousand yen after the corrections.
- The revised numerical data has been submitted along with the correction announcement.
🤖 AI Perspective
These corrections address errors in numerical data and descriptions identified after the initial financial report release, primarily affecting certain items within the consolidated financial statements and per-share information. Investors should note the adjustments to current and non-current liabilities as well as the clarification in the dilutive share calculation, which are important for detailed financial analysis. While the total liabilities remain consistent, suggesting no material change to the overall financial health, reviewing the corrected report is advisable for an accurate understanding of the company’s financial position.
8098|稲畑産
4460.0
▼ -1.00%
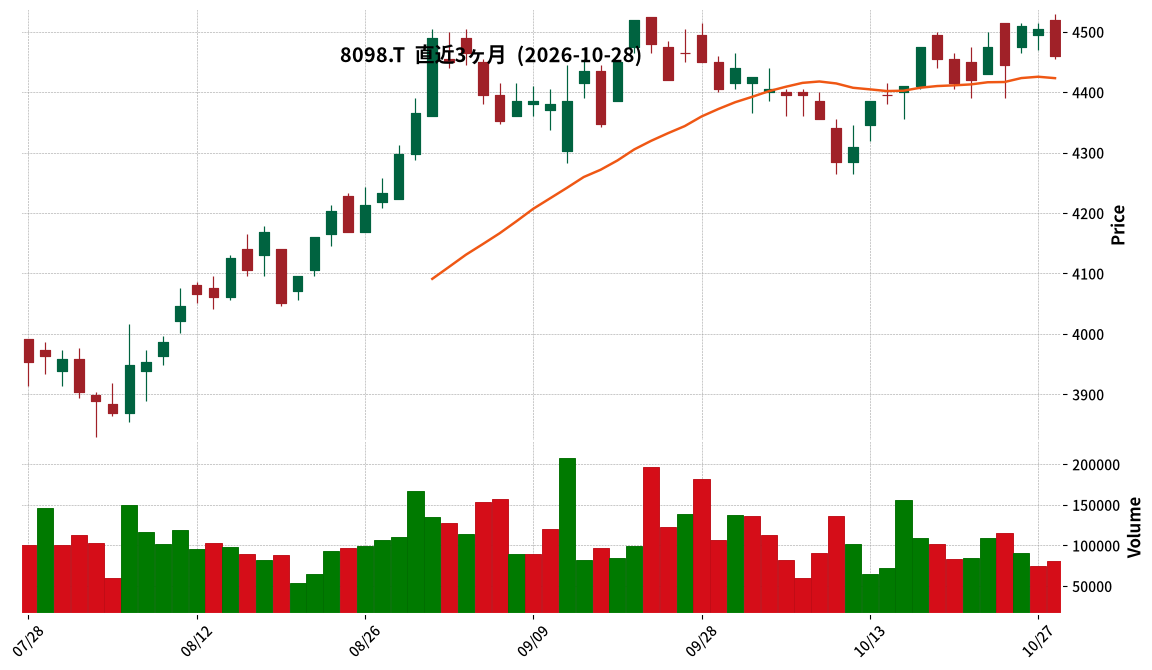
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Inabata & Co., Ltd. announced on October 28, 2026, a correction to its disclosure titled “Change in Equity-Method Affiliate (Becoming a Subsidiary)” originally released on October 27, 2026.
- The reason for the correction was the discovery of errors in the content after the initial disclosure.
- The specific correction relates to the aggregated financial figures for ULVAC Coating and its subsidiaries (Taiwan Coating Opto-Electronics Co., Ltd., ULVAC Coating Technologies (Hefei) Co., Ltd., Fine Surface Technology Inc.).
- The “Net Assets” and “Total Assets” figures were interchanged for the fiscal years ended June 2024, June 2025, and June 2026.
- For instance, the “Net Assets” figure for June 2024 was incorrectly stated as 16,037 million yen, and “Total Assets” as 4,444 million yen, which has been corrected to “Net Assets” of 4,444 million yen and “Total Assets” of 16,037 million yen.
🤖 AI Perspective
This correction addresses an error in key financial figures, specifically net assets and total assets, for an equity-method affiliate becoming a subsidiary. Investors should note this update as it changes the reported scale and financial structure of the associated companies. Such amendments highlight the importance of referring to the most accurate and current information when evaluating corporate announcements.
4446|Link-Uグループ
693.0
▼ -3.75%
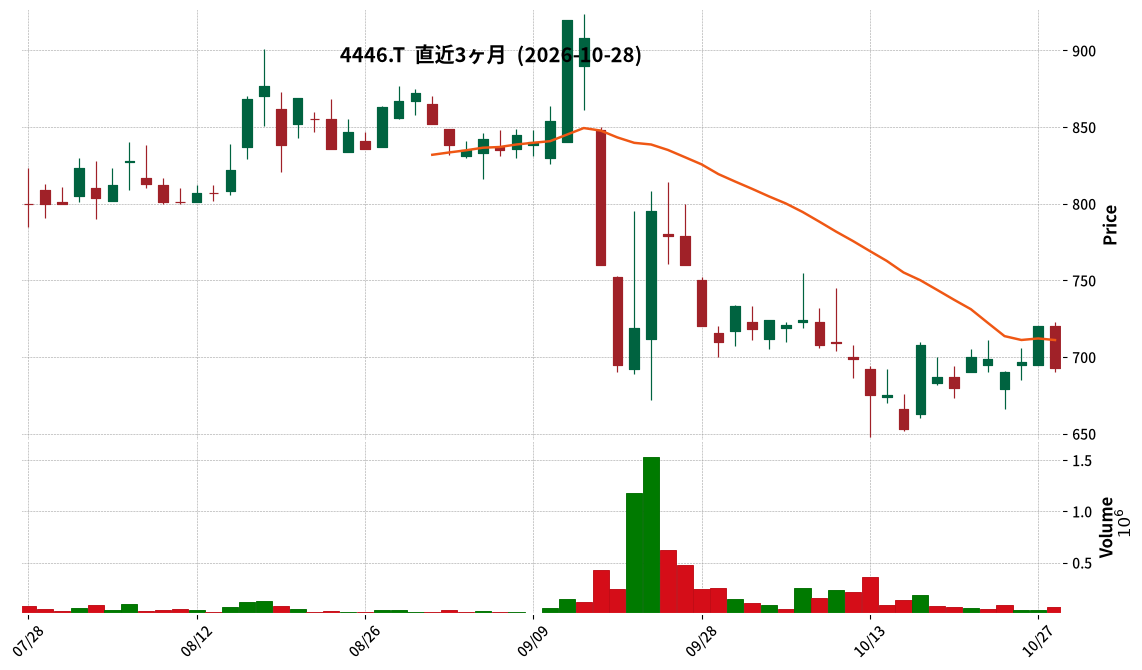
📎 Source:Link-Uグループ Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Link-U Group announced on October 28, 2026, that its Board of Directors resolved to implement an absorption merger between its consolidated subsidiaries.
- The merger will be conducted as an absorption merger, with VIEUN Inc. as the surviving company and Link-U Products Inc. as the absorbed company.
- The effective date of the merger is scheduled for January 1, 2027.
- The purpose of this merger is to integrate the management resources and expertise of both companies, create business synergies through enhanced collaboration, and reduce costs through operational efficiencies.
- As this merger involves 100% consolidated subsidiaries of Link-U Group, it is stated that there will be no impact on the company’s consolidated financial results.
🤖 AI Perspective
This absorption merger between Link-U Group’s consolidated subsidiaries appears to be a strategic move aimed at streamlining operations and fostering synergy within the group. With VIEUN Inc. as the surviving entity, integrating Link-U Products’ alliance and channel partner businesses into VIEUN’s content distribution service operations could lead to a more consolidated service delivery framework. This consolidation may suggest an effort to enhance overall group competitiveness and improve profitability through optimized internal structures.
💡 Start investing with IR insights


※ 本ページには広告が含まれます(PR)
Disclaimer: This article is for informational purposes only and does not constitute investment advice. All investment decisions are at your own risk.
コメント