📌 Today’s Highlights
Today we cover 19 IR announcements. Notable among them: 三協フロンテ (9639), G-リベラウェア (218A), ABCマート (2670). Use the table of contents below to navigate to each company.
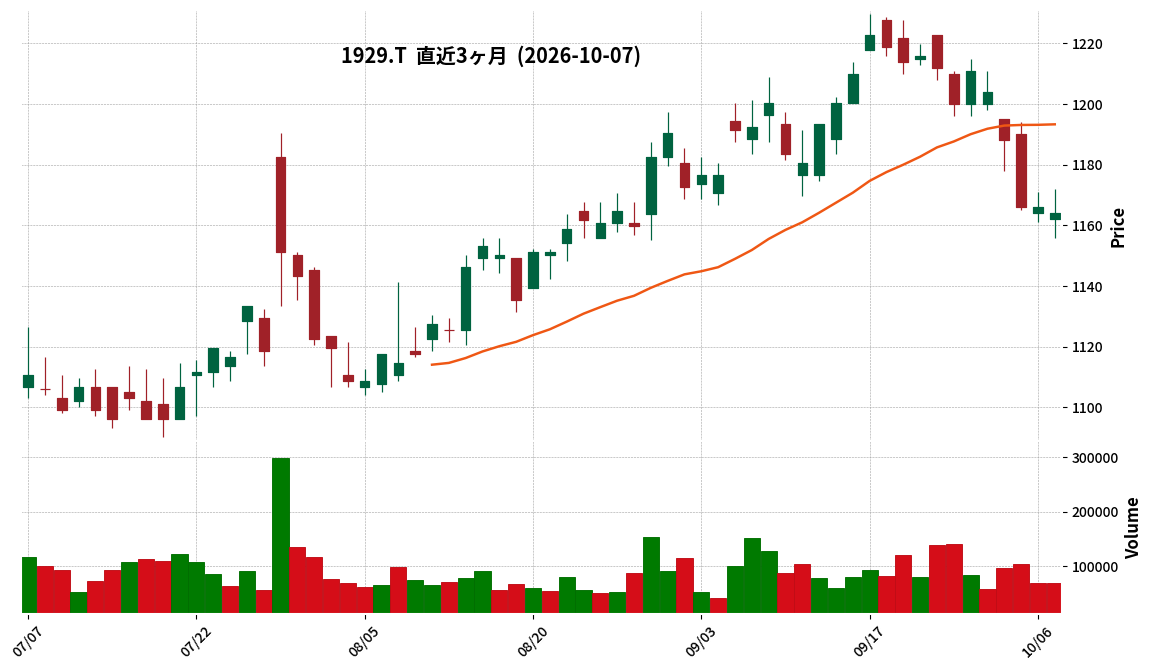
1929|日特建
1164.0
▼ -0.17%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Nittoc Construction Co., Ltd. resolved to acquire all outstanding shares of Giken Techno Co., Ltd., making it a wholly-owned subsidiary, at a board meeting on September 25, 2026.
- The share transfer agreement was signed on September 28, 2026, with the share transfer execution date scheduled for November 30, 2026.
- Giken Techno, headquartered in Sagamihara City, Kanagawa Prefecture, specializes in ground investigation, ground improvement work, and ground assurance. For the fiscal year ended March 2026, Giken Techno reported sales of 3,519 million yen and a net profit of 203 million yen.
- This acquisition is a growth investment under Nittoc Construction’s “Mid-term Management Plan 2026,” aiming to expand its customer base, technology, human resources, and construction capabilities in the foundation and ground improvement sector.
- Prior to the share acquisition, organizational restructuring, including an absorption-type merger with Giken Techno as the surviving company and a company split of the investment real estate business, is planned.
🤖 AI Perspective
This complete acquisition is positioned as a concrete execution of Nittoc Construction’s M&A strategy under its “Long-Term Vision 2035” and “Mid-term Management Plan 2026.” Giken Techno’s specialized expertise in ground investigation and improvement work for residential and low-rise buildings, along with its customer base, is expected to bring new markets and construction capabilities to Nittoc Construction’s existing businesses, potentially leading to business domain expansion and strengthened revenue streams. The post-acquisition operational policy indicates a focus on maintaining Giken Techno’s existing business foundation while enhancing construction capabilities, expanding business areas, and strengthening safety, quality, and management, suggesting that future synergy creation and long-term corporate value improvement will be worth monitoring.
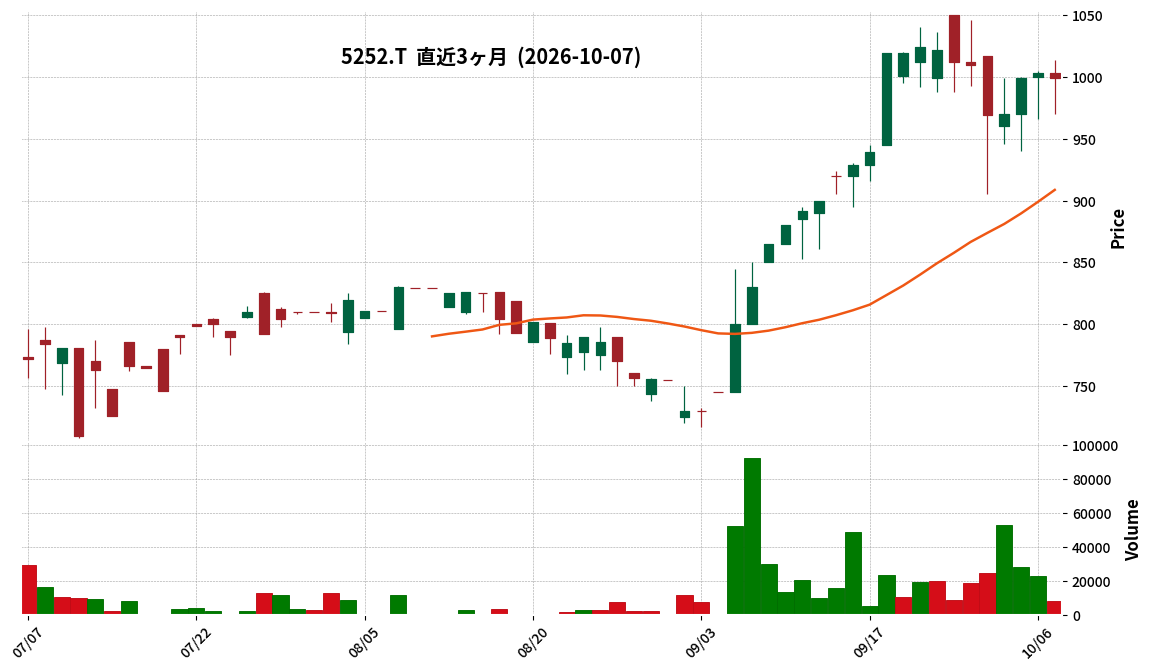
5252|G-日本ナレッジ
999.0
▼ -0.40%
📎 Source:G-日本ナレッジ Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- G-Nippon Knowledge announced on October 7, 2026, a partial correction to its IR release dated September 25, 2026, regarding the capital alliance agreement with Business Brain Ota Showa, third-party allotment of new shares, share sale, and changes in major shareholders and related parties.
- The correction involves two primary points. First, “Net income per share” for the fiscal year ended March 2026 was revised from 21.67 yen to 20.88 yen.
- Second, “Net assets per share” for the same period was revised from 291.56 yen to 290.78 yen.
- Third, the item “(9) Other” was deleted from the table in “III. About the Sale of Shares 1. Overview of the Sale.”
- Other financial figures, including Net Sales, Operating Income, Ordinary Income, Net Income, and Dividends per Share, remain unchanged.
🤖 AI Perspective
This correction primarily addresses revisions to historical financial metrics, specifically net income per share and net assets per share, along with a textual deletion in a previous disclosure. Such updates are important as they provide investors with the most accurate financial data for their analysis. Given that this concerns a disclosure related to a capital alliance and new share issuance, meticulous attention to these updated figures is generally considered valuable for investors.
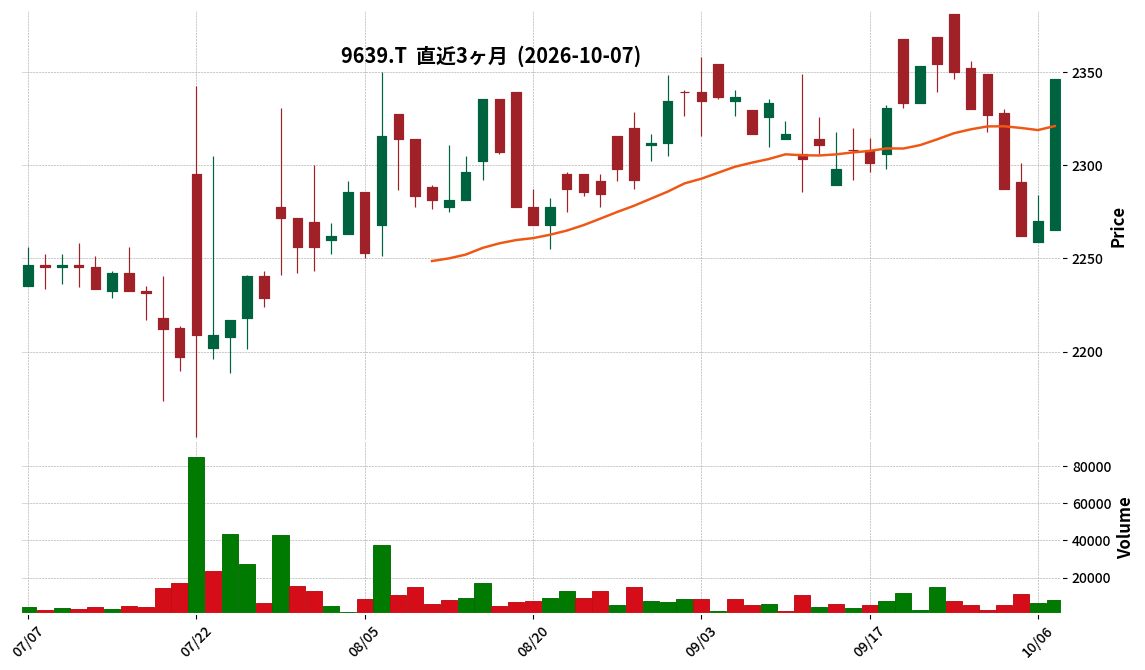
9639|三協フロンテ
2346.0
▲ +3.35%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Sankyo Frontier Co., Ltd. announced the interim financial results for its parent company, Wakou Kousan Co., Ltd., for the fiscal period ending February 2027.
- For the interim accounting period (March 1, 2026, to August 31, 2026), Wakou Kousan reported net sales of ¥40,280 thousand, ordinary profit of ¥489,675 thousand, and interim net income of ¥489,585 thousand.
- As of August 31, 2026, the summarized balance sheet showed total current assets of ¥4,981,505 thousand (up 11.1% from the previous fiscal year) and total assets of ¥9,201,639 thousand (up 5.6%).
- Wakou Kousan Co., Ltd. is the parent company of Sankyo Frontier, holding 50.63% of its voting rights as of August 31, 2026.
- Key executives include Kazuo Nagatsuma (Representative Director) and Takatsugu Nagatsuma (Director), with Takatsugu Nagatsuma also serving as Representative Director and President of Sankyo Frontier.
🤖 AI Perspective
While this announcement pertains to the parent company’s individual financial results, it offers insight into the financial health of a major shareholder. The increase in current assets may suggest improved short-term liquidity for Wakou Kousan. Investors may consider the stability of the parent company’s financial position, given its significant ownership and interlocking directorates with Sankyo Frontier, as a factor relevant to the latter’s overall corporate governance.
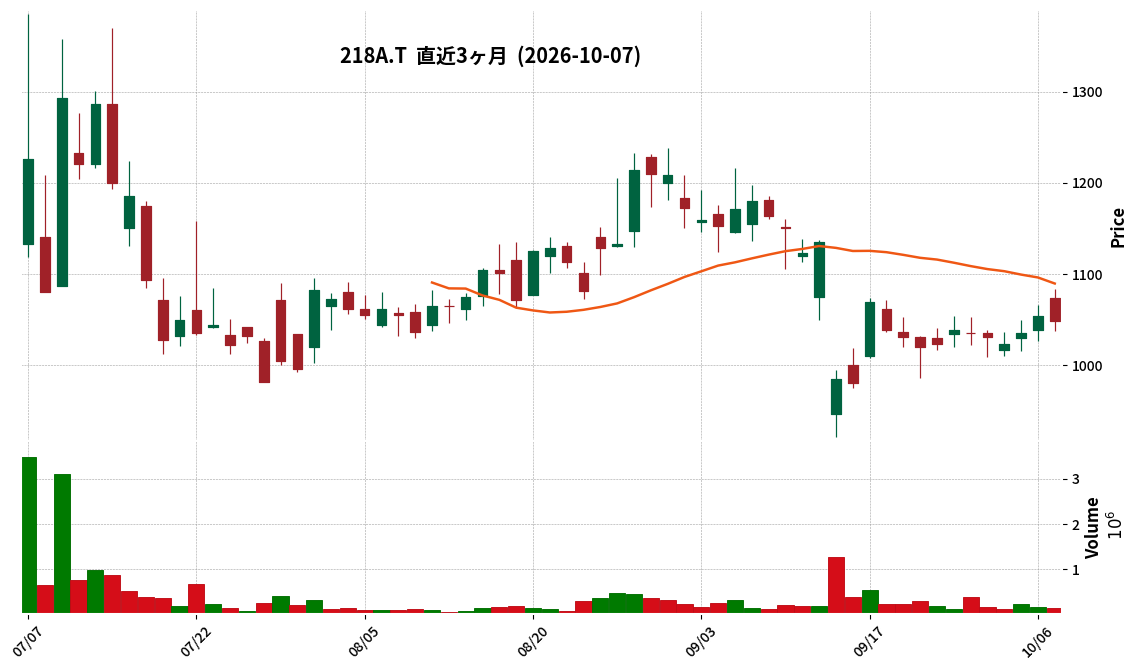
218A|G-リベラウェア
1048.0
▼ -0.57%
📎 Source:G-リベラウェア Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Liberaware Inc. recorded an impairment loss on shares of an affiliate as an extraordinary loss in its non-consolidated financial statements for the fiscal year ending July 2026 (August 1, 2025 – July 31, 2026).
- The impairment loss pertains to shares of Liberaware Korea Co., Ltd., located in Seoul, South Korea.
- The company executed impairment accounting due to a significant decline in the substantive value of these shares.
- An impairment loss of JPY 40,809 thousand was recorded as an extraordinary loss.
- This impairment loss will be eliminated in the consolidated financial statements, thus having no impact on the consolidated results for the fiscal year ending July 2026.
- A portion of the “Summary of Non-Consolidated Operating Results (Reference)” in the “Consolidated Financial Results for the Fiscal Year Ended July 2026 (Japanese Standards)” released on September 14, 2026, has been corrected.
🤖 AI Perspective
This announcement highlights a specific non-consolidated accounting event concerning an affiliate’s shares. The fact that there will be no impact on consolidated results for the fiscal year ending July 2026 suggests that the overall financial health of the group remains unaffected. However, the recognition of an extraordinary loss in the non-consolidated statements may indicate a re-evaluation or challenging operational conditions for the specific subsidiary, Liberaware Korea Co., Ltd.
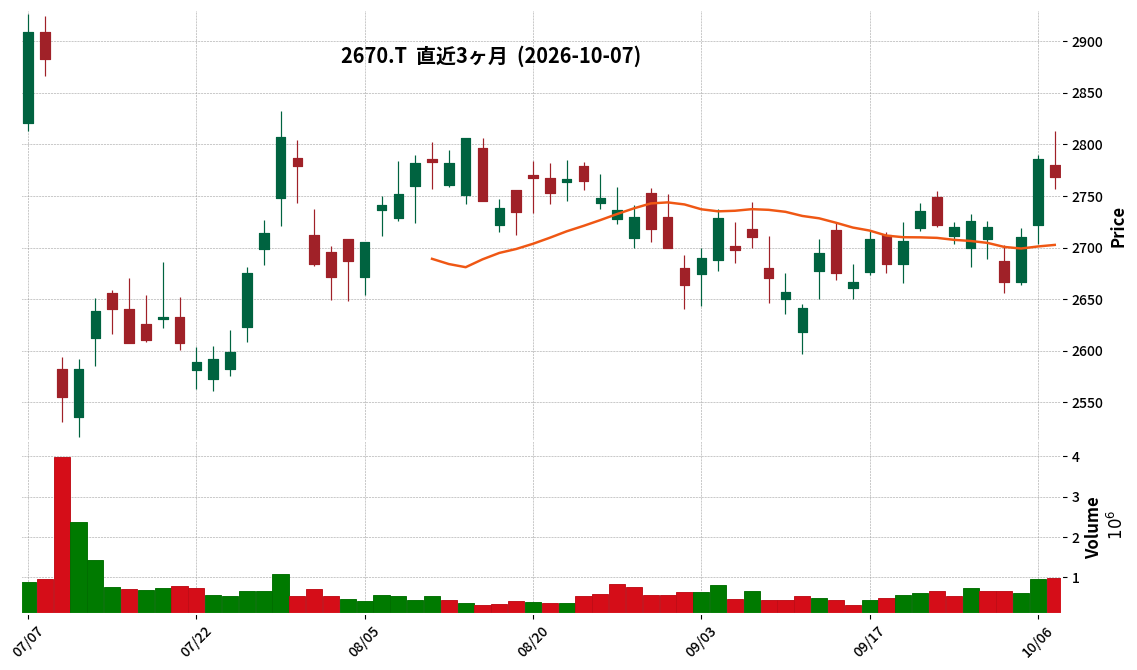
2670|ABCマート
2768.0
▼ -0.65%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- ABC-MART reported consolidated results for the second quarter of the fiscal year ending February 2027, with net sales of ¥202,298 million (up 6.4% year-on-year), operating profit of ¥36,131 million (up 7.4%), ordinary profit of ¥37,971 million (up 5.7%), and interim net profit attributable to parent of ¥25,931 million (up 6.6%).
- Consolidated financial position showed total assets of ¥475,639 million and net assets of ¥416,481 million, with an equity ratio of 86.9%.
- The annual dividend forecast for the fiscal year ending February 2027 is ¥40 per share for the interim and ¥40 per share for the fiscal year-end, totaling ¥80 per share (no revision from the most recently announced forecast).
- The full-year consolidated performance forecast for the fiscal year ending February 2027 has been revised upwards to net sales of ¥403,000 million (up 6.4% from the previous year), operating profit of ¥67,200 million (up 6.2%), ordinary profit of ¥69,800 million (up 3.9%), net profit attributable to parent of ¥47,700 million (up 2.9%), and earnings per share of ¥192.64.
- As of the end of the interim period, the total number of stores domestically and internationally was 1,522, with 23 new stores opened domestically and 23 internationally, including the acquisition of 16 “FOLDER” stores by the Korean subsidiary.
🤖 AI Perspective
ABC-MART’s Q2 FY2027 results indicate robust performance with increases across sales and profits compared to the prior interim period. Strong domestic sales, driven by a 4.5% increase in existing store sales and 4.8% overall due to inbound demand, coupled with positive foreign exchange impacts on international segments, appear to be key factors. The upward revision of the full-year consolidated earnings forecast could suggest management’s increased confidence in future performance.
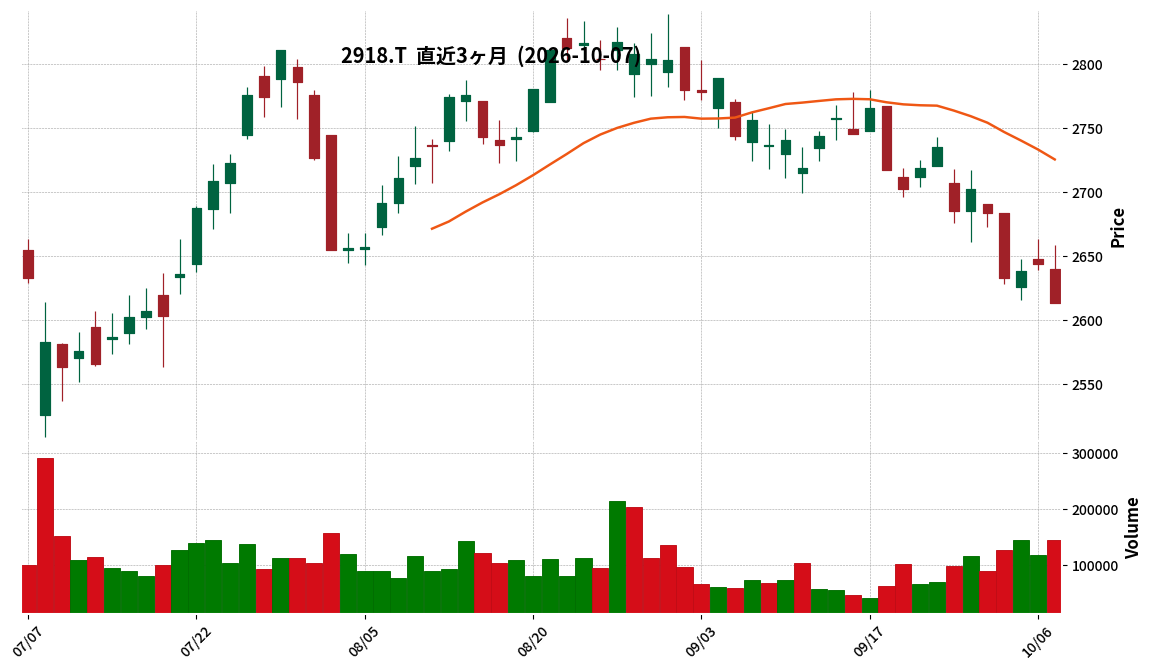
2918|わらべや
2613.0
▼ -1.17%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Warabeya Nichiyo Holdings Co., Ltd. announced its consolidated financial results for the second quarter (interim period) of the fiscal year ending February 2027.
- Consolidated net sales reached JPY 120.853 billion, marking a slight increase of 1.0% compared to the previous interim period.
- Operating profit decreased by 25.0% to JPY 3.969 billion, ordinary profit declined by 19.7% to JPY 4.203 billion, and net income attributable to owners of the parent fell by 34.1% to JPY 2.638 billion, all showing double-digit declines.
- In the Food-related Business segment, sales were JPY 108.636 billion (+1.0% YoY), but operating profit decreased by 24.7% to JPY 3.729 billion due to rising raw material and labor costs, and the impact of the Sapporo factory’s temporary suspension.
- The consolidated full-year earnings forecast for the fiscal year ending February 2027 has been revised, with projected net sales of JPY 238.0 billion (+1.8% YoY), operating profit of JPY 6.0 billion (-19.4% YoY), ordinary profit of JPY 6.05 billion (-18.4% YoY), and net income attributable to owners of the parent of JPY 3.5 billion (-34.5% YoY).
🤖 AI Perspective
While sales showed a modest increase, the interim financial results indicate that rising raw material and labor costs, alongside a factory operation suspension, significantly impacted profitability. The decline in profit across the board suggests that cost pressures, particularly within the food-related business, played a critical role. The downward revision of the full-year earnings forecast may imply an expectation that these cost challenges are likely to persist.
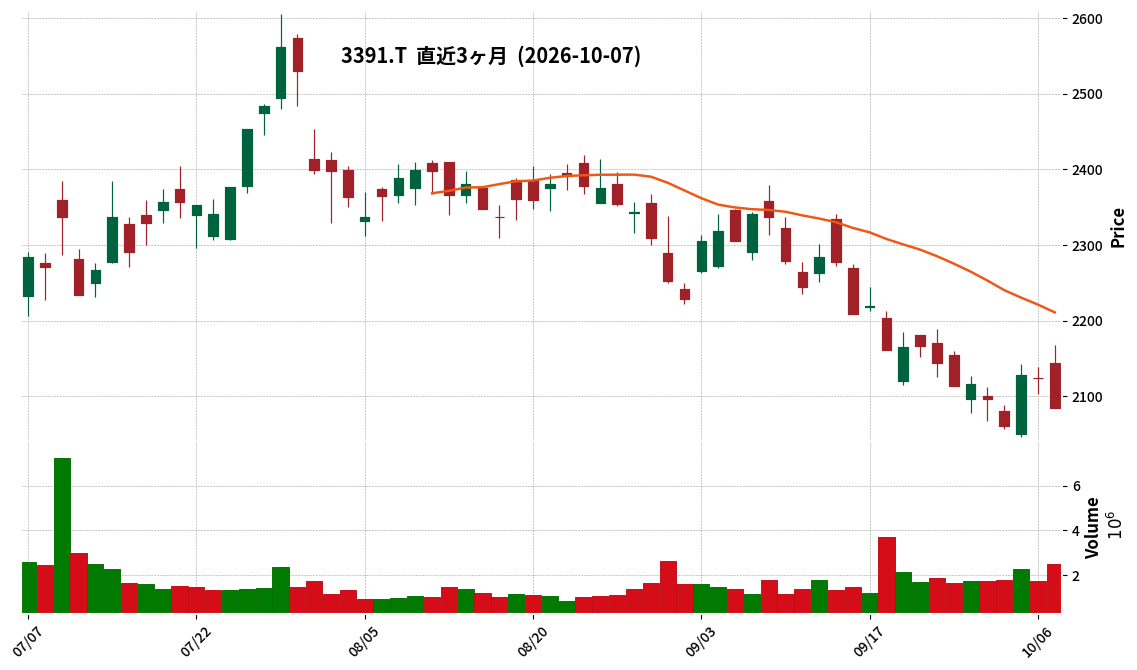
3391|ツルハHD
2085.0
▼ -1.86%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Tsuruha Holdings has announced its consolidated financial results for the second quarter (interim period) of the fiscal year ending February 2027.
- Consolidated cumulative performance shows net sales of ¥1,275,514 million, EBITDA of ¥85,530 million, operating income of ¥54,770 million, and ordinary income of ¥54,850 million. Net income attributable to owners of parent was ¥30,252 million.
- Compared to the interim period of fiscal year ended February 2026, net sales increased by 128.7%, and EBITDA increased by 126.3%.
- Basic earnings per share (interim) were ¥66.75.
- The total number of domestic stores at the end of the interim period was 5,652, resulting from 53 new store openings and 77 store closures.
🤖 AI Perspective
The reported Q2 FY2027 results show significant increases in net sales and EBITDA, which may suggest the initial impact of the business integration with Welcia Holdings. While operating income, ordinary income, and net income attributable to owners of parent also increased year-over-year, their growth rates are proportionally lower compared to the substantial increase in net sales. Investors may want to monitor how the synergy effects from the integration and ongoing investments in foundational infrastructure will influence future profitability.
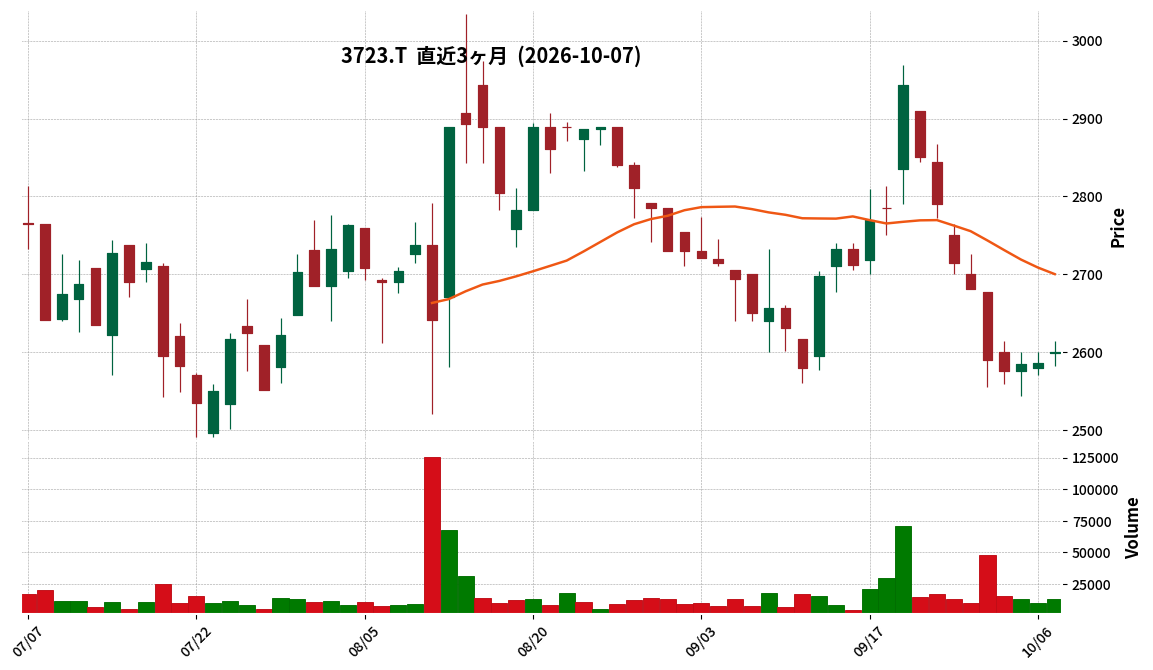
3723|G-ファルコム
2600.0
▲ +0.54%
📎 Source:G-ファルコム Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Nihon Falcom Corporation announced a revision to its dividend forecast per share for the fiscal year ending September 2026.
- The revised annual dividend per share will be ¥60, significantly up from the previous forecast of ¥10.
- This increase includes an ordinary dividend of ¥30 per share, which is a ¥20 increase from the previous ordinary dividend.
- Additionally, a commemorative dividend of ¥30 per share will be issued to celebrate the “Kiseki Series” achieving 10 million units in worldwide cumulative sales.
- The reason for the increase in ordinary dividend is the strong performance outlook for the fiscal year ending September 2026, which is expected to reach a new record high, as stated in the “Notice of Revision to Financial Forecasts” released today.
🤖 AI Perspective
This dividend forecast revision suggests the company’s commitment to shareholder returns, reflecting not only robust business performance but also the achievement of a significant sales milestone for its flagship series. The increase in the ordinary dividend may indicate confidence in future stable earnings, while the commemorative dividend could be seen as an intention to share a specific success with shareholders. For investors, this announcement highlights both corporate growth and shareholder return aspects worth monitoring.
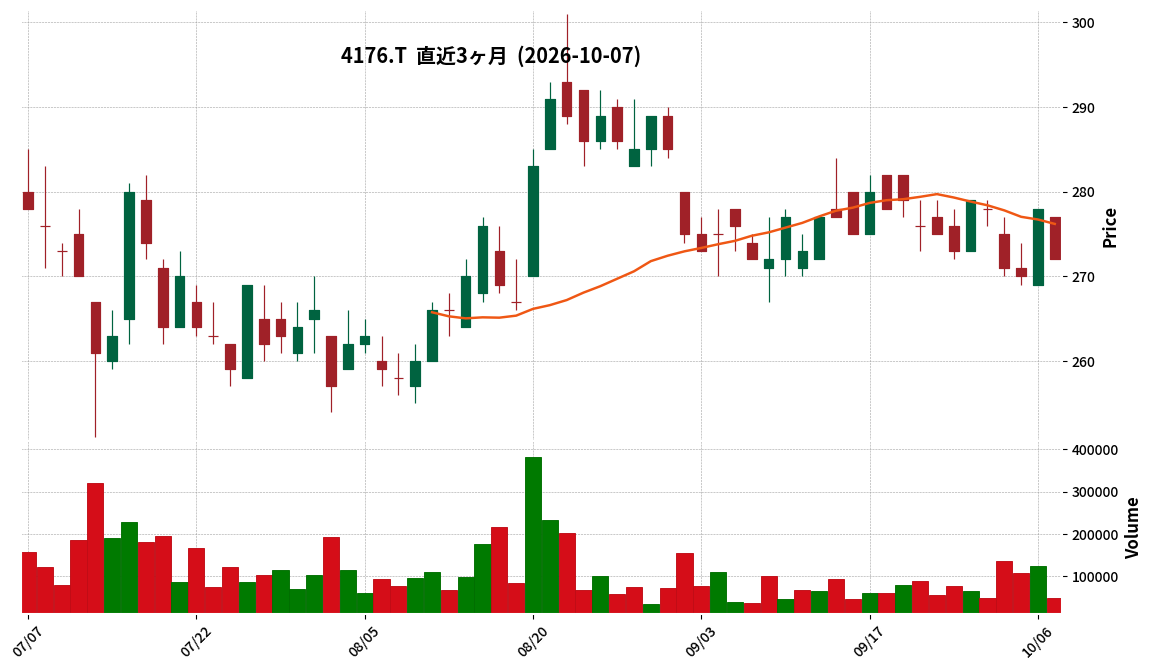
4176|G-ココナラ
272.0
▼ -2.16%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- G-Coconala resolved to acquire shares of Acrosstudio Co., Ltd., making it a subsidiary, at a Board of Directors meeting held on October 7, 2026.
- The acquisition involves 510 common shares, representing 51% of Acrosstudio’s total outstanding shares. Acrosstudio Co., Ltd. is expected to become a consolidated subsidiary of G-Coconala.
- The acquisition price is 867 million JPY, with a total estimated cost of 872 million JPY including advisory fees. The share transfer execution date is scheduled for October 30, 2026.
- Acrosstudio Co., Ltd., established in July 2021, specializes in AI consulting and AI development. For the fiscal year ended June 2026, its sales were 1,130 million JPY and operating income was 46 million JPY.
- G-Coconala positions this acquisition as a core element of its AI Company, established on September 1, 2026, aiming to expand into AI BPO services in addition to AI consulting, development, and implementation support.
🤖 AI Perspective
This acquisition appears to be a strategic move by G-Coconala to significantly strengthen its AI-related business offerings. By integrating Acrosstudio’s expertise in AI implementation consulting, problem-solving, and Forward Deployed Engineer (FDE) type support, G-Coconala aims to leverage synergies with its existing customer and talent base. This expansion into a broader range of AI utilization services for businesses could indicate a focused effort to drive new growth and enhance its market position in the AI solutions sector.
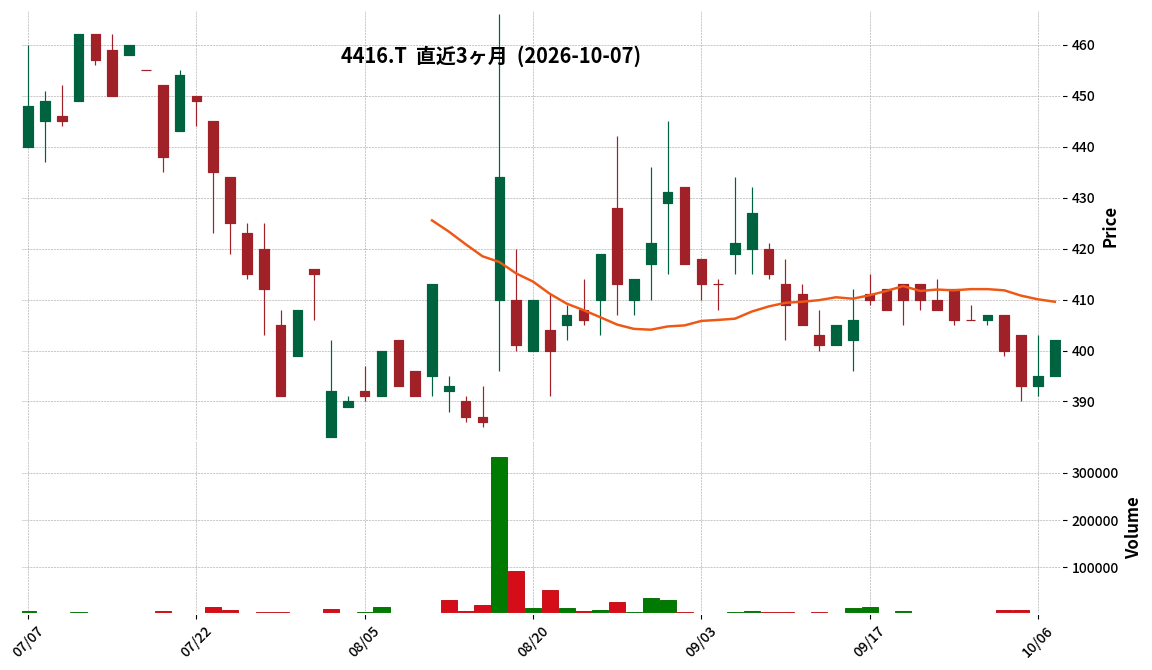
4416|G-TrueData
402.0
▲ +1.77%
📎 Source:G-TrueData Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- G-TrueData announced the acquisition of 100% of outstanding shares of Cosmonet Co., Ltd., making it a wholly owned subsidiary.
- The share transfer is scheduled for October 13, 2026, with an estimated acquisition cost of JPY 248 million.
- Cosmonet specializes in the development, sales, implementation support, and maintenance of the “MUSASI” POS-linked sales management system for hardware stores and professional shops.
- This transaction is positioned as the first execution within the M&A investment framework (over JPY 1 billion) set forth in the company’s mid-term management plan.
- Cosmonet’s standalone financial performance for the August 2025 fiscal year reported net sales of JPY 106 million, operating profit of JPY 8 million, and net assets of JPY 63 million.
🤖 AI Perspective
This acquisition appears to be a strategic move by G-TrueData to secure a data foundation in the professional market, aiming to replicate its “data x AI insights” business model in this new segment. The integration of data from both consumer and professional markets could potentially unlock new opportunities for demand forecasting and decision-making support. As the initial execution within their mid-term M&A investment framework, this development may signal G-TrueData’s future strategic direction and expansion efforts.
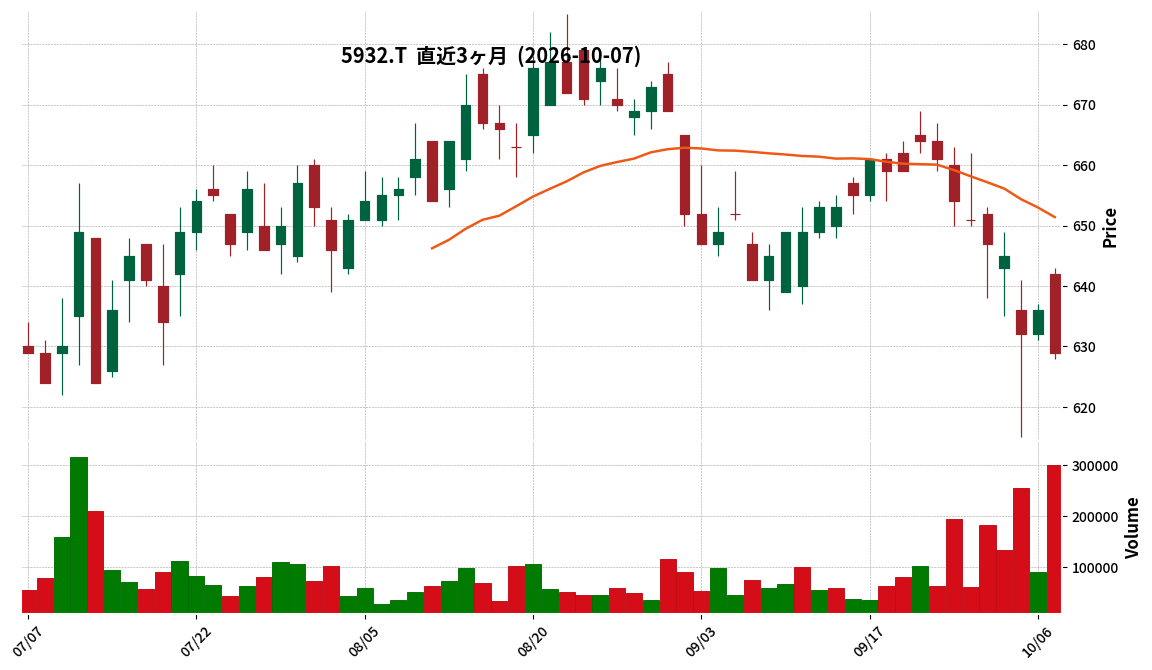
5932|三協立山
629.0
▼ -1.10%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Sankyo Tateyama announced its consolidated financial results for the first quarter of the fiscal year ending May 2027 (June 1, 2026 – August 31, 2026).
- Net sales for the first quarter were ¥97,268 million, representing a 13.3% increase year-over-year.
- Operating profit was ¥2,641 million (compared to an operating loss of ¥1,164 million in the prior year’s first quarter), and ordinary profit was ¥2,428 million (compared to an ordinary loss of ¥1,207 million in the prior year’s first quarter), both marking a return to profitability.
- Net income attributable to owners of the parent was ¥1,571 million (compared to a net loss of ¥687 million in the prior year’s first quarter).
- Diluted earnings per share for the quarter were ¥50.15 (compared to a loss per share of ¥21.95 in the prior year’s first quarter).
- The full-year consolidated earnings forecast (Net Sales: ¥390,000 million, Operating Profit: ¥4,000 million, Ordinary Profit: ¥1,500 million, Net Income attributable to owners of the parent: ¥1,000 million) remains unchanged.
🤖 AI Perspective
Sankyo Tateyama’s Q1 FY2027 results show a significant turnaround, with double-digit sales growth and all key profit metrics (operating, ordinary, and net income attributable to owners of the parent) returning to positive territory after losses in the prior year. This suggests an improvement in the company’s profitability and operational efficiency. As the full-year forecast remains unchanged, investors may monitor the progression in subsequent quarters to assess the sustainability of this positive trend relative to the annual targets.
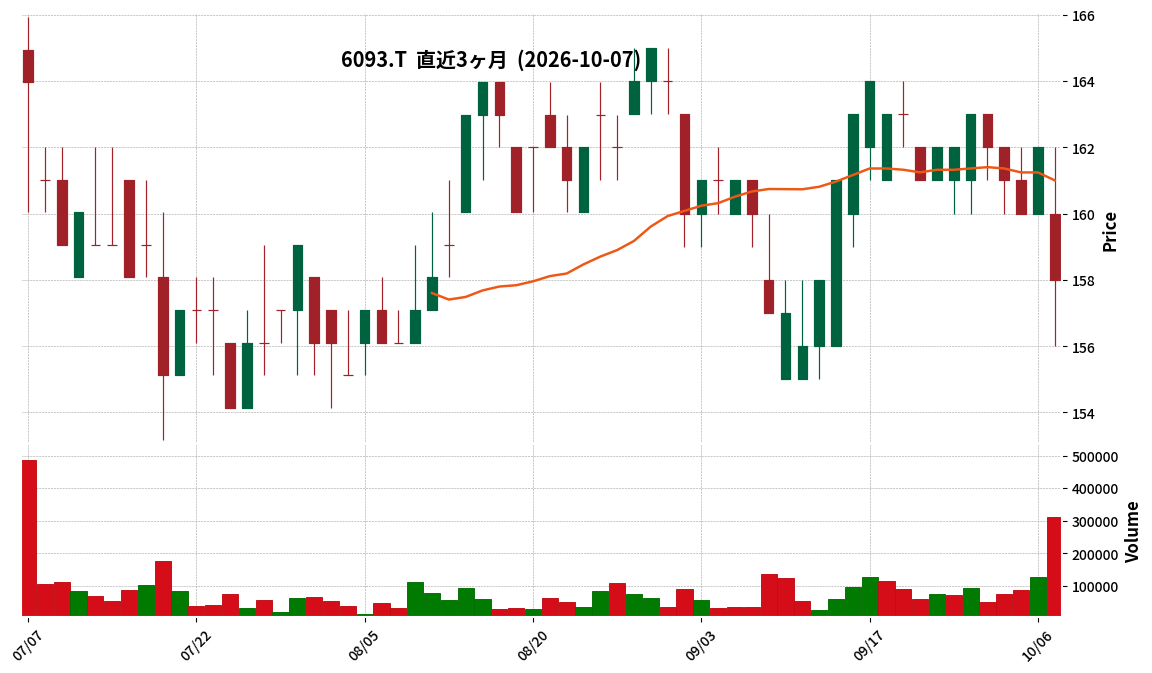
6093|ミトラG
158.0
▼ -2.47%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Mitra G has announced its consolidated financial results for the second quarter (interim period) of the fiscal year ending February 2027.
- Net sales reached ¥2,605 million, marking a 10.0% increase compared to the prior interim period.
- Operating profit was ¥159 million (up 0.4%), ordinary profit was ¥155 million (down 2.0%), and net income attributable to owners of parent was ¥120 million (down 4.6%).
- By segment, Financial Solutions recorded net sales of ¥1,004 million (up 10.3%), and Real Estate Solutions recorded net sales of ¥403 million (up 37.9%).
- The consolidated full-year forecast for FY2027 remains unchanged, projecting net sales of ¥6,211 million (up 22.3% from previous year), operating profit of ¥624 million (up 93.1%), and net income of ¥425 million (up 124.4%).
🤖 AI Perspective
While Mitra G achieved double-digit revenue growth in this interim period, ordinary profit and net income saw a slight decrease year-over-year. This outcome appears to be influenced by strong performance in the Financial Solutions segment and increased real estate auction transactions, counterbalanced by rising costs in the Construction Solutions segment due to production system enhancements. As the full-year forecast remains unrevised, the performance in the latter half of the fiscal year will be a key area for investors to monitor.
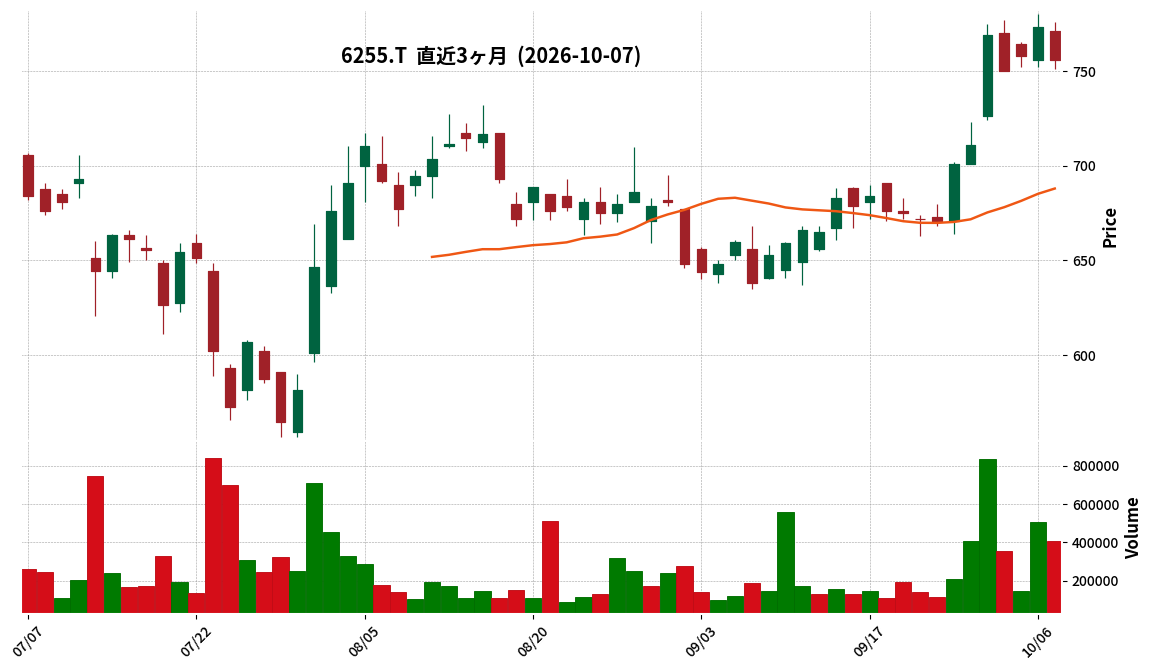
6255|G-NPC
756.0
▼ -2.20%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- G-NPC announced its consolidated financial results for the full year ended August 2026 (September 1, 2025 to August 31, 2026).
- Consolidated net sales amounted to ¥5,811 million, a decrease of 37.3% compared to the previous fiscal year.
- Consolidated operating profit was ¥846 million, down 55.9%; ordinary profit was ¥880 million, down 54.2%; and profit attributable to owners of parent was ¥481 million, down 63.7%.
- The primary reasons for the decline in revenue were attributed to delays in a portion of large domestic projects and modification projects for a major US customer.
- For the fiscal year ending August 2027, the company forecasts consolidated net sales of ¥9,895 million (up 70.3% year-on-year), operating profit of ¥1,380 million (up 62.9%), ordinary profit of ¥1,417 million (up 61.0%), and profit attributable to owners of parent of ¥826 million (up 71.6%).
🤖 AI Perspective
The significant decline in revenue and profit for FY2026 is largely attributed to project delays, which suggests that the company’s underlying business operations may not have deteriorated as much as the headline figures imply. The strong forecast for FY2027, projecting substantial increases across all profit metrics, indicates the company anticipates realizing these delayed projects and growth in the coming period. Investors may find it worthwhile to monitor the company’s progress in converting its order backlog into revenue and the impact on cash flow from operations, which turned negative in FY2026.
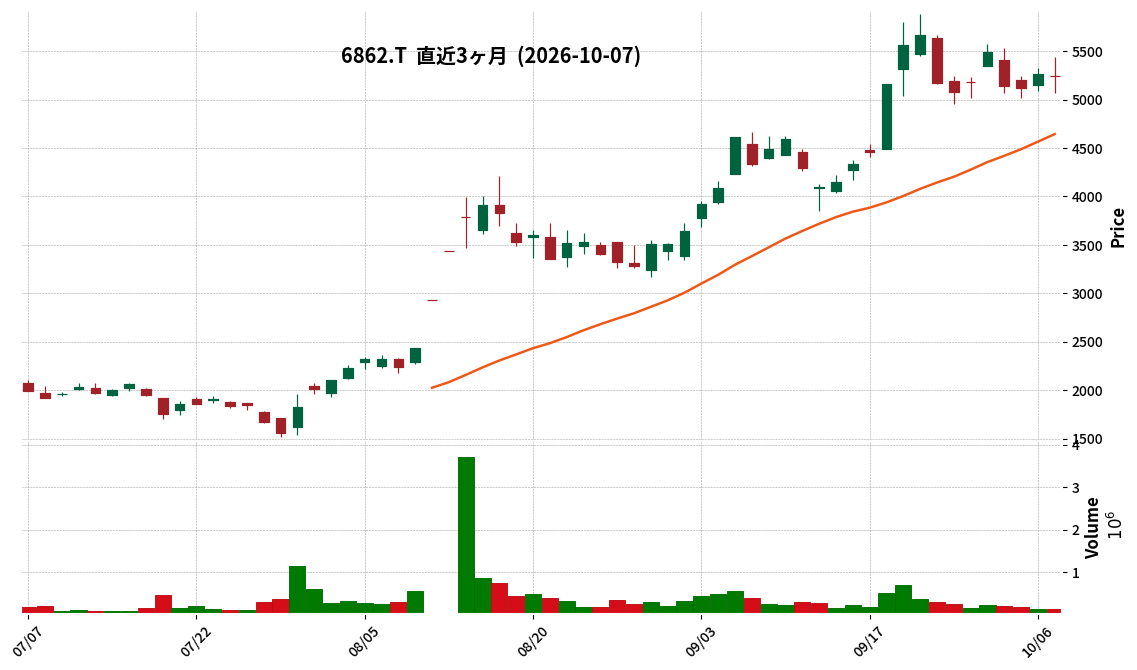
6862|ミナトHD
5240.0
▼ -0.38%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Minato Holdings has decided to terminate its capital and business alliance agreement with Media-Trust Inc. (MT), Brain Co., Ltd. (BR), and Daiki Sound Co., Ltd. (DS).
- The termination is due to discrepancies found between information provided by MT and the actual conditions, as well as multiple breaches of contract. This includes events negatively impacting DS’s financial condition by approximately 150 million yen.
- BR and DS will continue to operate as consolidated subsidiaries of Minato Holdings even after the termination of this agreement.
- Minato Holdings plans to seek redemption for the 10,000,000 shares of MT preferred stock it holds (acquisition cost 10 million yen). These preferred shares were impaired to a memorandum value of 1 yen at the end of the fiscal year ended March 2026.
- Masahiko Miura will assume the position of Representative Director and President of consolidated subsidiary Brain Co., Ltd., replacing Masanobu Kondo, who also served as Representative Director and President of MT.
🤖 AI Perspective
This announcement highlights a situation where discrepancies in information and contract breaches led to the dissolution of a capital and business alliance. The specific financial impact of approximately 150 million yen on DS’s financial state is a key figure for investors to consider in assessing potential effects on future earnings. Furthermore, the continuation of BR and DS as consolidated subsidiaries and the company’s intention to unwind existing transactions with MT suggest an ongoing restructuring of the group’s management framework, which will be worth monitoring.
7137|P-グラントマト
1200.0
▲ +0.00%
📎 Source:P-グラントマト Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Grantomato Co., Ltd. announced on October 7, 2026, a downward revision to its full-year earnings forecast for the fiscal year ending August 2026.
- The revised full-year forecast projects net sales of ¥20,426 million (down 1.8% from the previous forecast), an operating loss of ¥754 million (worsening from the previous forecast of ¥225 million loss), an ordinary loss of ¥880 million, and a net loss of ¥778 million.
- The primary reason for the revision is a substantial loss on sales in the agricultural distribution segment, resulting from a larger-than-expected decline in rice market prices.
- While core businesses such as store sales, FDC/internet sales, and rice retail sales performed steadily, they were unable to absorb the impact of extreme market fluctuations in the agricultural distribution segment.
- The company anticipates that the impact of future price declines on inventory valuation losses will be limited, as almost all of the 2025 crop year rice inventory has been sold.
🤖 AI Perspective
This downward revision appears to be primarily driven by the significant impact of the rice market’s sharper-than-expected decline on the agricultural distribution segment. The steady performance of other core business divisions suggests potential resilience in diversified operations. The completion of the 2025 crop year rice inventory sales may limit future exposure to inventory valuation risks, which could be a point of focus for investors monitoring the company’s risk management strategies.
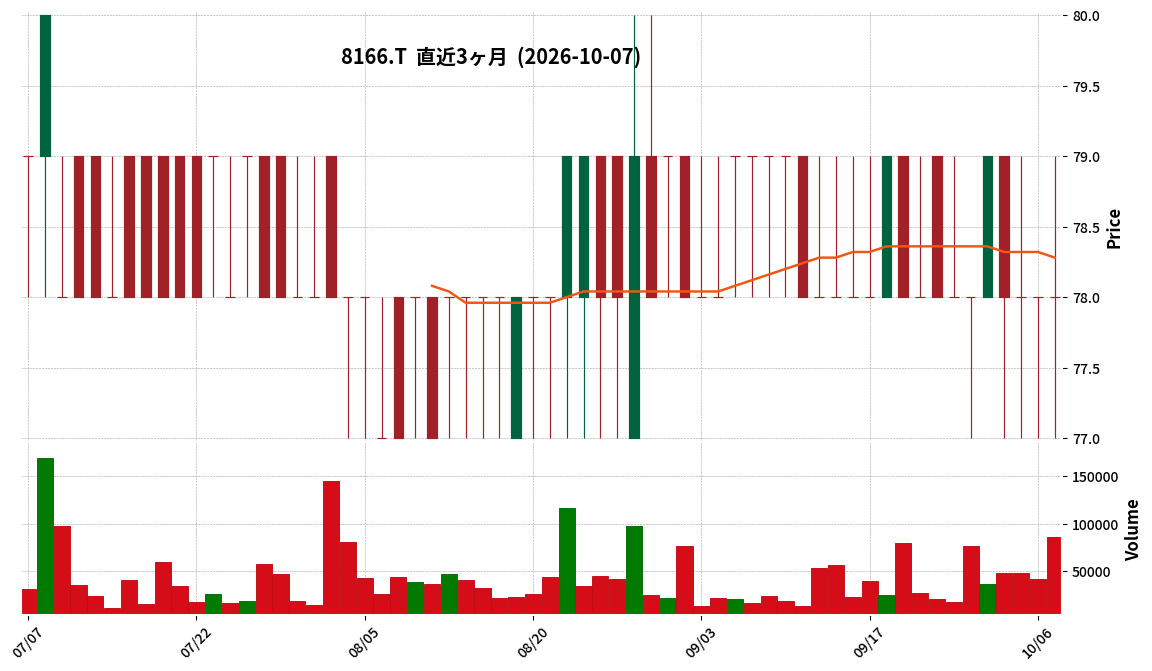
8166|タカキュー
78.0
▲ +0.00%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Taka-Q reported net sales of ¥3,851 million for the second quarter of fiscal year 2027 (interim period), representing a 10.0% decrease compared to the previous interim period.
- The company recorded an operating loss of ¥239 million, an ordinary loss of ¥201 million, and a net loss of ¥283 million for the interim period.
- Interim net loss per share was ¥-7.46.
- As of the end of the second quarter of FY2027, total assets stood at ¥5,202 million, net assets at ¥1,808 million, and the equity ratio was 34.7%.
- The full-year earnings forecast remains unchanged, projecting net sales of ¥8,700 million (up 0.4% YoY), operating profit of ¥60 million (up 205.3% YoY), ordinary profit of ¥200 million (up 48.8% YoY), and net profit of ¥130 million (down 88.4% YoY).
🤖 AI Perspective
The interim results show a decline in net sales year-on-year and reported losses across all profit metrics. This performance may be attributed to a decrease in existing store sales and a review of e-commerce business scale. While the full-year forecast remains unchanged, recovery in the second half of the fiscal year could be a key challenge to monitor.
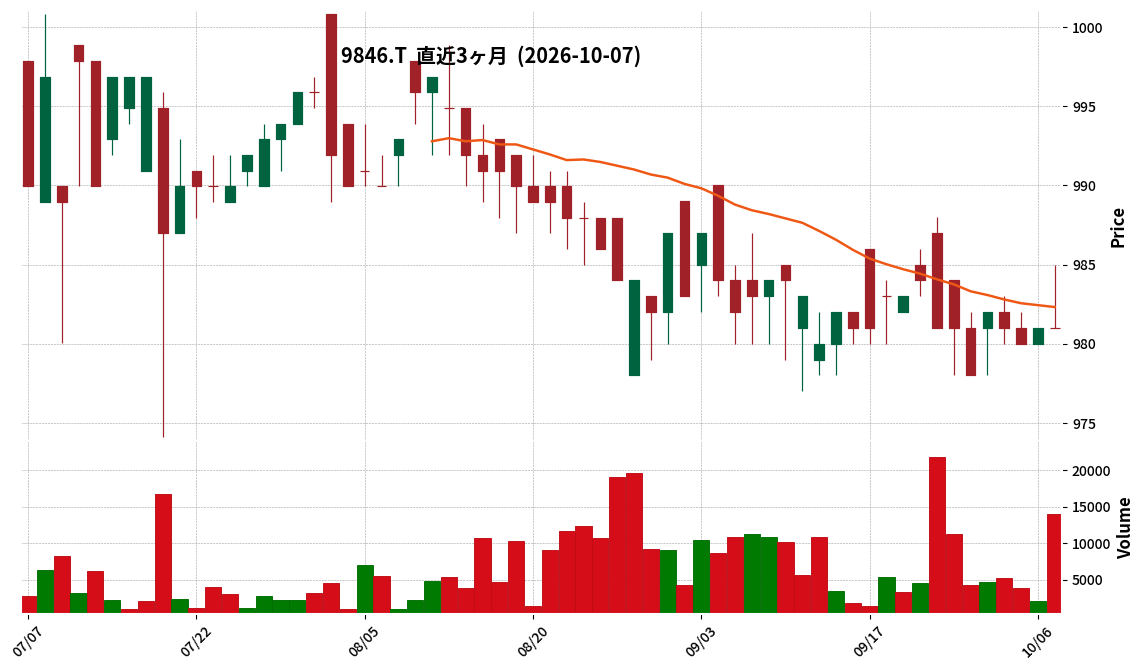
9846|天満屋ス
981.0
▲ +0.00%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Tenmaya Store announced its consolidated financial results for the second quarter (interim period) of the fiscal year ending February 2027, covering March 1, 2026, to August 31, 2026.
- Consolidated operating revenue was ¥30,016 million (up 1.6% year-on-year), operating income was ¥954 million (down 10.8%), and ordinary income was ¥970 million (down 14.0%).
- Net income attributable to parent shareholders reached ¥691 million (up 14.8%).
- Diluted earnings per share for the interim period stood at ¥60.11.
- Regarding dividends, the interim dividend for FY2027 is ¥10.00, with a forecast of ¥10.00 for the year-end dividend, totaling ¥20.00 annually.
- The full-year consolidated performance forecast remains unchanged, projecting operating revenue of ¥63,000 million (up 6.3% year-on-year), operating income of ¥2,300 million (up 5.3%), ordinary income of ¥2,300 million (up 1.3%), and net income attributable to parent shareholders of ¥1,400 million (up 3.7%), with EPS of ¥121.66.
🤖 AI Perspective
While operating revenue increased, the decline in operating and ordinary income indicates potential cost pressures or changes in profit margins. However, the notable increase in net income attributable to parent shareholders suggests that specific factors or one-off gains may have positively impacted the bottom line. The unchanged full-year outlook and maintained dividend forecast could signal management’s confidence in the company’s ability to achieve its annual targets despite the mixed interim results.
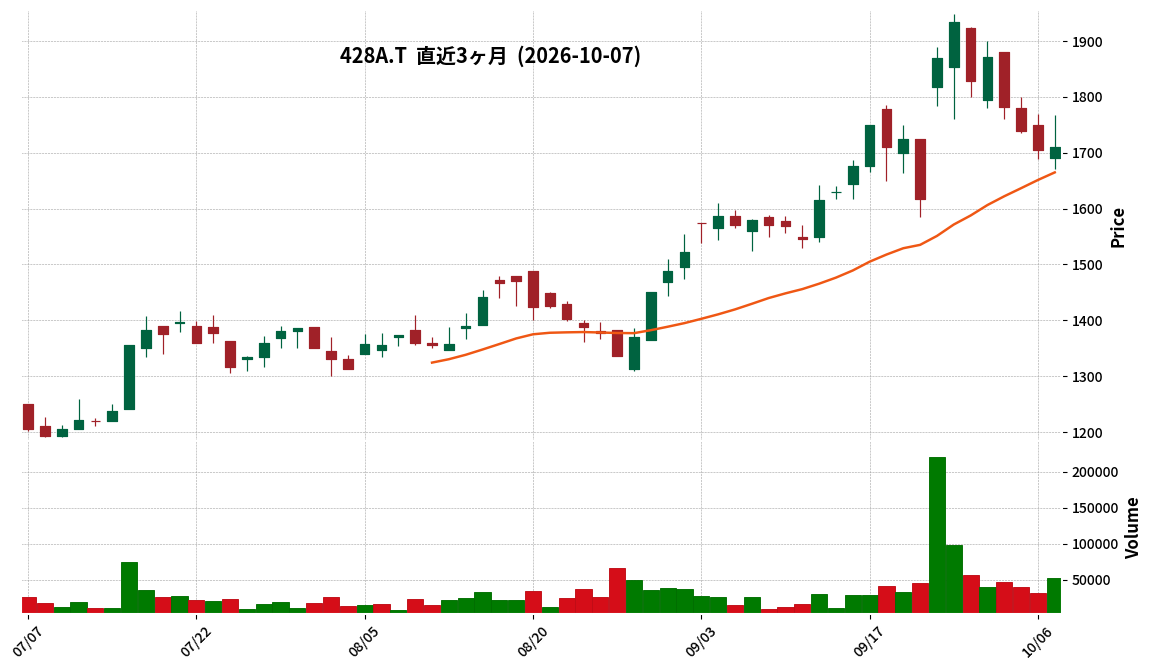
428A|サイプレスHD
1710.0
▲ +0.35%
📎 Source:サイプレスHD Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Cypress Holdings reported consolidated revenue of ¥12,878 million for the fiscal year ended August 2026, a 14.1% increase year-on-year.
- Profit attributable to owners of the parent company amounted to ¥767 million, marking a 75.8% increase from the previous period.
- Existing store sales grew by 2.1% compared to the prior fiscal year, exceeding the initial budget.
- The company opened 18 new stores during the fiscal year, bringing the total number of stores to 137 at year-end, an increase of 11 stores from the beginning of the period.
- For the fiscal year ending August 2027, the company forecasts consolidated revenue of ¥15,000 million (a 16.5% increase year-on-year) and operating profit of ¥1,130 million (a 32.8% increase year-on-year).
🤖 AI Perspective
Cypress Holdings’ significant increase in revenue and profit for FY2026 suggests the effectiveness of its growth strategies, including strong existing store performance and aggressive new store openings. The company’s diversification into new business models, such as the “Ginza Souzai-ten” yakitori takeout specialty stores and their franchising, appears to be contributing to this expansion. The positive outlook for FY2027 indicates continued confidence in their growth trajectory.
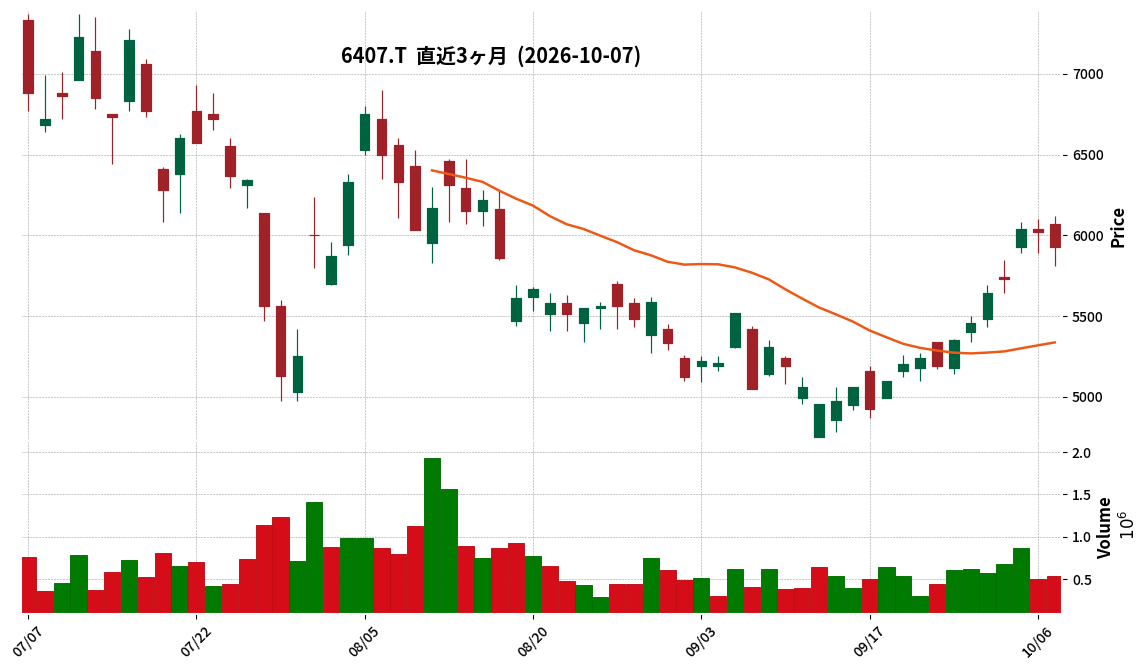
6407|CKD
5930.0
▼ -1.50%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- CKD Corporation announced on October 7, 2026, that the interim review by certified public accountants for its Q1 FY2027 Consolidated Financial Results (Japanese GAAP) has been completed.
- This interim review was conducted in connection with the offering of the company’s shares, which was resolved by the Board of Directors on October 7, 2026.
- There are no changes to the quarterly consolidated financial statements previously announced on August 10, 2026.
- For the first quarter of FY2027 (April 1, 2026, to June 30, 2026), consolidated results showed net sales of ¥49,108 million (+35.5% YoY), operating income of ¥8,032 million (+112.9% YoY), ordinary income of ¥8,242 million (+122.5% YoY), and net income attributable to owners of parent of ¥5,686 million (+129.5% YoY).
- By segment, the Equipment segment recorded sales of ¥46,072 million (+45.4% YoY) and segment income of ¥8,751 million (+112.4% YoY), while the Automatic Machinery segment reported sales of ¥3,036 million (-33.5% YoY) and segment income of ¥738 million (-26.3% YoY).
💡 Start investing with IR insights


※ 本ページには広告が含まれます(PR)
Disclaimer: This article is for informational purposes only and does not constitute investment advice. All investment decisions are at your own risk.
コメント