📌 Today’s Highlights
Today we cover 26 IR announcements. Notable among them: G-メディア (3815), iFSP500ダブル (2237), モバファク (3912). Use the table of contents below to navigate to each company.
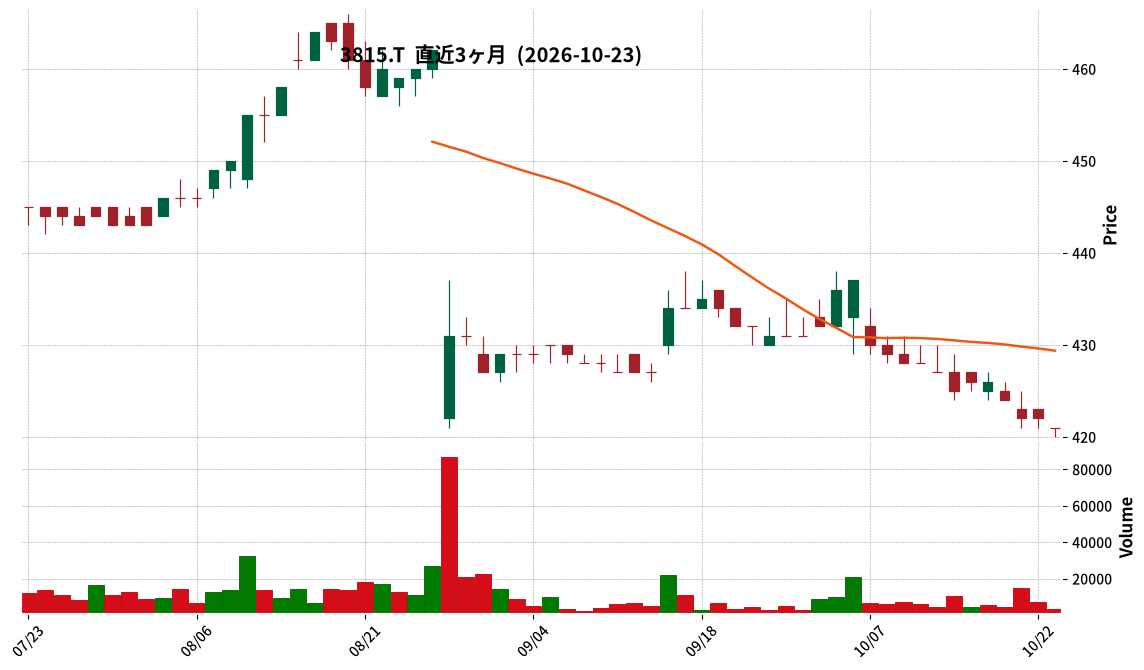
3815|G-メディア
421.0
▼ -0.24%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- G-Media’s consolidated financial results for the fiscal year ended August 2026 show net sales of ¥1,612 million (down 13.9% year-on-year), an operating loss of ¥534 million (compared to a loss of ¥323 million in the previous year), an ordinary loss of ¥537 million (compared to a loss of ¥317 million), and a net loss attributable to parent company shareholders of ¥716 million (compared to a loss of ¥508 million).
- Key factors contributing to the expanded operating loss include decreased revenue from digital content and phone/chat fortune-telling, investments in new businesses, shareholder benefit expenses due to the introduction of interim benefits, and office relocation related costs.
- Special losses totaling ¥225 million were recorded, comprising ¥82 million for disposal of fixed assets (new digital content framework, revised parts of the fortune-telling encyclopedia, shared phone fortune-telling system) and ¥142 million for impairment losses (phone fortune-telling system, phone fortune-telling management system, BtoB solution system).
- By segment, the fortune-telling business reported sales of ¥1,491 million (down 15.3% year-on-year) and an operating profit of ¥221 million (down 42.7%). The data & technology business saw sales increase to ¥113 million (up 3.9%) but recorded an operating loss of ¥171 million (compared to a loss of ¥7 million in the prior year).
- For the fiscal year ending August 2027, the company forecasts a significant reduction in its operating loss on a core business basis (excluding shareholder-related expenses) to ¥389 million (from ¥533 million in FY2026), driven by cost reductions (¥198 million), profit margin improvements (¥141 million), and sales increases (¥13 million).
🤖 AI Perspective
G-Media’s FY2026 results indicate a challenging period marked by revenue decline in core businesses and significant special losses from asset restructuring. The delays in new content production frameworks and the rise of AI-powered alternatives in the digital fortune-telling market appear to have impacted performance. However, the company’s commitment to structural reforms and a projected substantial reduction in its core business operating loss for FY2027 suggest a strategic shift towards improving profitability, making its implementation of AI and focus on digital-physical service integration a key area for investors to monitor.
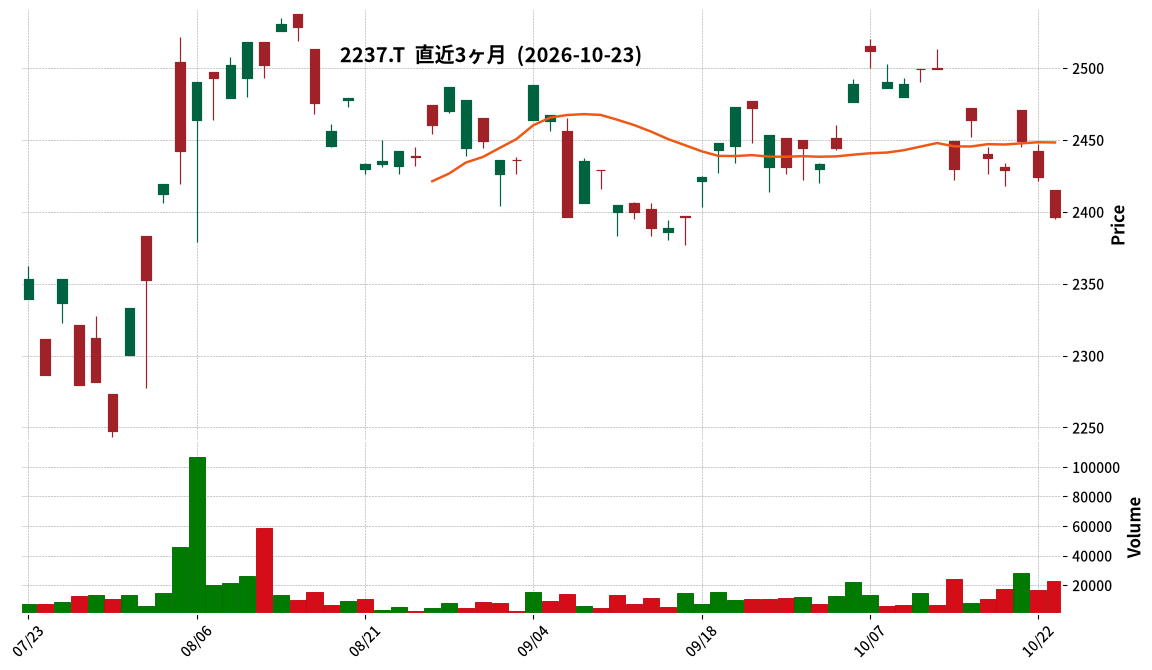
2237|iFSP500ダブル
2396.0
▼ -1.16%
📎 Source:iFSP500ダブル Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- iFreeETF S&P500 Leverage (Code 2237) announced its financial results for the September 2026 fiscal period (March 11, 2026 – September 10, 2026).
- Net assets at the end of the current period totaled ¥1,814 million, an increase from ¥1,771 million at the end of the previous period.
- The asset composition shows that major investment assets (parent fund beneficiary certificates) accounted for 55.6% (¥1,008 million), while cash, deposits, and other assets (net of liabilities) comprised 44.4% (¥806 million).
- Outstanding units at the end of the period were 751 thousand units, and the net asset value per unit was ¥2,413.24.
- The distribution per unit for the current period was ¥7, a decrease from ¥195 in the previous period.
- A unit split was conducted on July 7, 2026, at a ratio of 50 units for every 1 unit held.
🤖 AI Perspective
The September 2026 fiscal results for iFreeETF S&P500 Leverage indicate a steady increase in net assets, suggesting growth in the fund’s overall scale. The increased allocation to parent fund beneficiary certificates, a major investment asset, may signal the consistent application of its investment strategy. While the distribution per unit decreased from the prior period, it is worth monitoring this in the context of the unit split that took place, to assess the fund’s comprehensive performance.
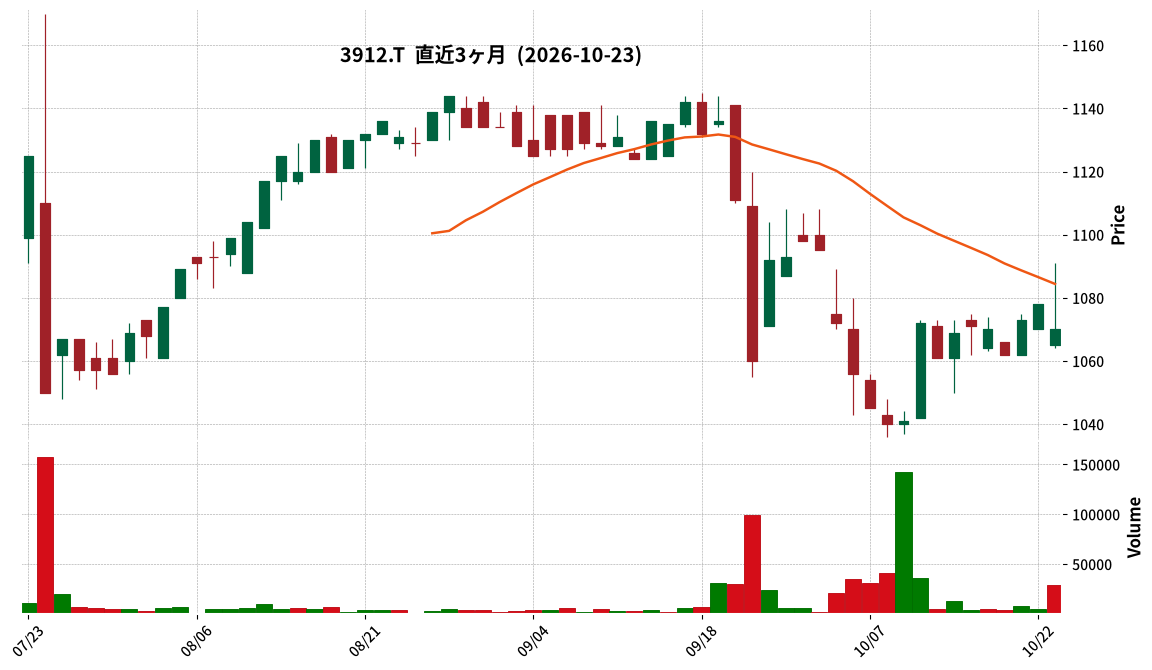
3912|モバファク
1070.0
▼ -0.74%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Mobile Factory, Inc. announced its consolidated financial results for the third quarter of the fiscal year ending December 2026 (January 1, 2026, to September 30, 2026).
- For the period, consolidated net sales were ¥2,562 million (up 3.4% year-on-year), EBITDA was ¥887 million (up 9.4%), operating profit was ¥887 million (up 9.4%), ordinary profit was ¥890 million (up 7.8%), and profit attributable to owners of parent was ¥615 million (up 6.2%).
- The Mobile Game business recorded sales of ¥2,387 million (up 4.5% year-on-year) and segment profit of ¥760 million (up 13.0%), achieving record high sales and operating profit for the segment.
- The Content business recorded sales of ¥174 million (down 9.3% year-on-year) and segment profit of ¥130 million (down 8.9%).
- The full-year consolidated performance forecast for the fiscal year ending December 2026 remains unchanged from the most recently published forecast: net sales of ¥3,500 million (up 2.1% year-on-year), operating profit of ¥1,170 million (up 4.3%), ordinary profit of ¥1,180 million (up 3.0%), and profit attributable to owners of parent of ¥819 million (up 67.7%).
🤖 AI Perspective
Mobile Factory’s Q3 FY2026 results indicate that its mobile game business is a significant driver of overall performance, achieving record highs in both revenue and profit. The introduction of new products, collaboration events for “Ekimepo!”, and reduced platform fees due to increased use of external app payment shops appear to have contributed to profit improvement. Conversely, the content business showed a slight decline, underscoring the growing importance of the mobile game segment within the company’s business portfolio.
5423|東製鉄
1650.0
▼ -3.23%
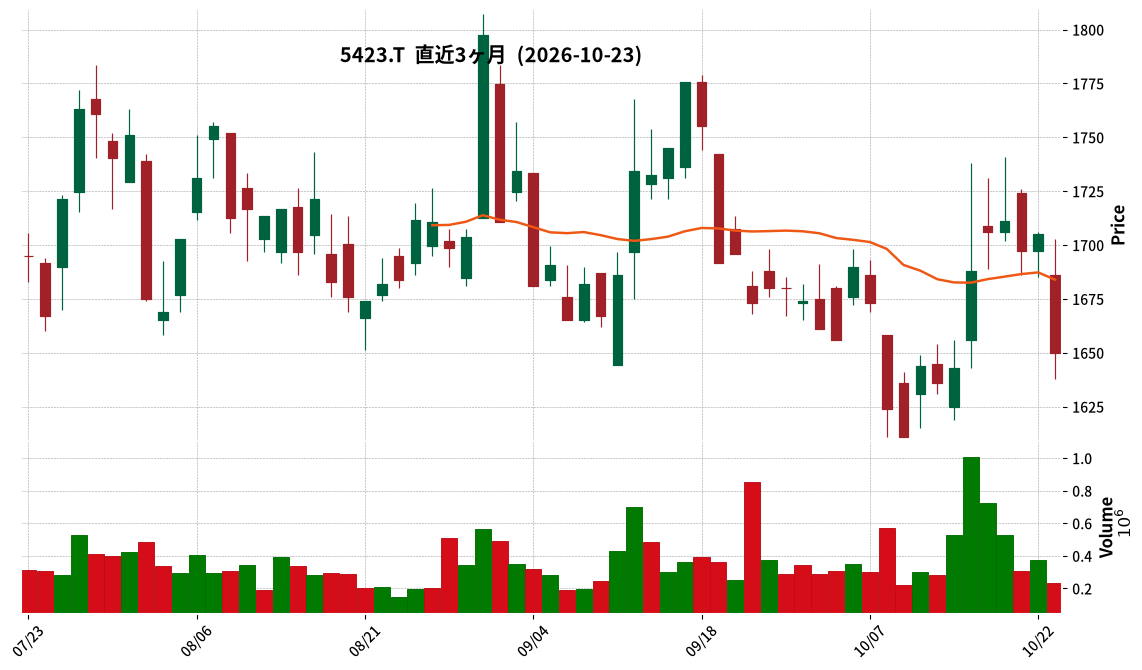
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Tokyo Steel announced its Q2 FY2027 interim financial results for the period from April 1, 2026, to September 30, 2026.
- For the cumulative interim period, net sales were JPY 150,422 million, marking a 12.3% increase compared to the previous interim period.
- The company reported an operating loss of JPY 3,543 million (compared to an operating income of JPY 6,045 million in the prior interim period) and an ordinary loss of JPY 2,949 million (compared to JPY 6,983 million).
- Net income attributable to owners of the parent for the interim period was JPY 2,389 million, a 47.7% decrease from JPY 4,568 million in the prior interim period. Earnings per share for the interim period were JPY 23.46.
- Total assets stood at JPY 276,442 million as of September 30, 2026 (a decrease of JPY 16,552 million from March 31, 2026), with total net assets at JPY 217,229 million (a decrease of JPY 4,859 million). The equity ratio was 78.6%.
- The annual dividend forecast for FY2027 remains unchanged, with an interim dividend of JPY 20.00 and a year-end dividend of JPY 20.00, totaling JPY 40.00 per share.
- The full-year forecast for FY2027 (April 1, 2026 – March 31, 2027) projects net sales of JPY 326,000 million (up 21.6% YoY), operating income of JPY 1,000 million (down 86.2% YoY), ordinary income of JPY 2,000 million (down 76.8% YoY), and net income of JPY 7,000 million (down 39.4% YoY), with EPS of JPY 69.28. This forecast remains unrevised from the most recently announced figures.
🤖 AI Perspective
The interim results indicate a mixed performance for Tokyo Steel, with a notable increase in net sales but a shift to operating and ordinary losses compared to the prior year. The sustained positive net income, despite the decrease, may suggest the impact of special gains, such as from asset sales. Investors might be particularly interested in monitoring the company’s progress towards its full-year operating income target, which anticipates a return to profitability, driven by expected price adjustments and ongoing cost reduction efforts.
9353|桜島埠頭
2933.0
▼ -0.58%
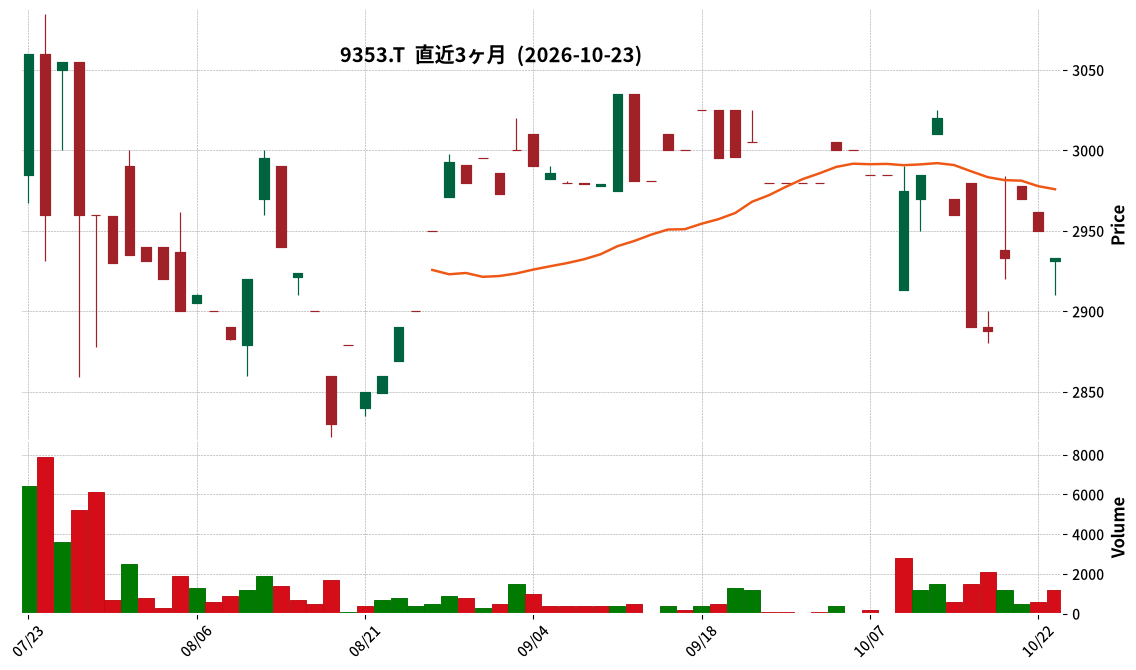
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Sakurajima Futo announced its consolidated financial results for the second quarter (interim period) of the fiscal year ending March 2027.
- Net sales amounted to ¥2,081 million, a decrease of ¥143 million (6.4%) compared to the same period last year.
- Operating income was ¥4 million, a significant decrease of ¥207 million (98.0%) from the previous year’s interim period.
- Ordinary income was ¥102 million (down 64.9%), and net income attributable to owners of parent was ¥78 million (down 67.0%).
- The full-year consolidated earnings forecast remains unchanged, projecting net sales of ¥4,280 million (+0.5%), operating income of ¥250 million (-0.4%), and net income attributable to owners of parent of ¥260 million (-10.4%).
- Segment-wise, the Bulk Cargo segment reported sales of ¥1,064 million (-14.2%) and an operating loss of ¥27 million (compared to an operating income of ¥72 million in the prior year period). The Liquid Cargo segment saw sales of ¥726 million (+3.3%) and operating income of ¥151 million (-36.8%). The Logistics Warehouse segment recorded sales of ¥277 million (+3.7%) and operating income of ¥126 million (+19.1%).
🤖 AI Perspective
Sakurajima Futo’s Q2 FY2027 results show a decrease in both revenue and various profit metrics compared to the prior year. The significant decline in the Bulk Cargo segment appears to be a primary contributor to the overall performance. Conversely, both the Liquid Cargo and Logistics Warehouse segments achieved revenue growth, which may indicate a shifting contribution from different business units within their portfolio. The unchanged full-year outlook suggests management anticipates recovery in the second half, making future developments worth monitoring.
8541|愛媛銀
3355.0
▼ -1.47%
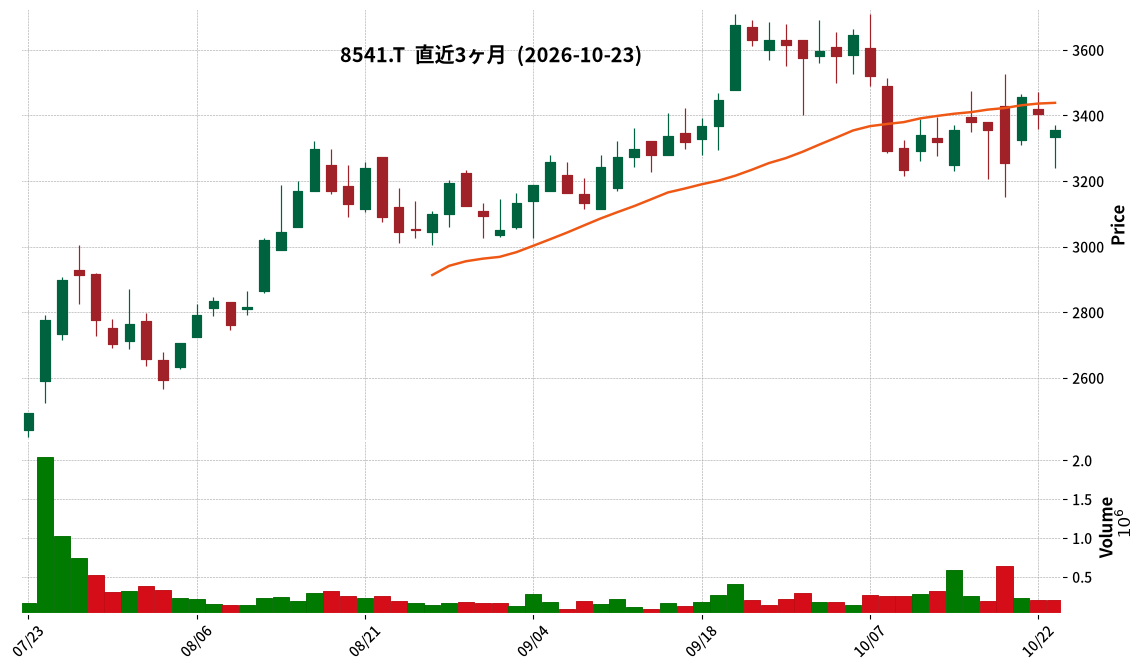
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Ehime Bank revised its consolidated financial forecast for the fiscal year ending March 31, 2024, raising ordinary profit from JPY 11 billion to JPY 14 billion, and net profit attributable to parent company shareholders from JPY 7.5 billion to JPY 10 billion.
- The non-consolidated financial forecast for the same period was also revised, increasing ordinary profit from JPY 10 billion to JPY 12.5 billion, and net profit from JPY 7 billion to JPY 9 billion.
- The year-end dividend forecast for the fiscal year ending March 31, 2024, was revised upwards by JPY 5 per share, from JPY 30 to JPY 35 per share.
- The revisions are attributed to expected increases in interest income and investment income, as well as an increase in unrealized gains on securities.
🤖 AI Perspective
Ehime Bank’s upward revision of its earnings forecast appears to be primarily driven by increased interest income and improved investment returns. The concurrent announcement of a dividend increase could be interpreted as a positive signal regarding the company’s commitment to shareholder returns. These revisions may prompt investors to further evaluate the bank’s financial health and evolving revenue structure.
2804|ブルドックソース
1857.0
▲ +0.38%
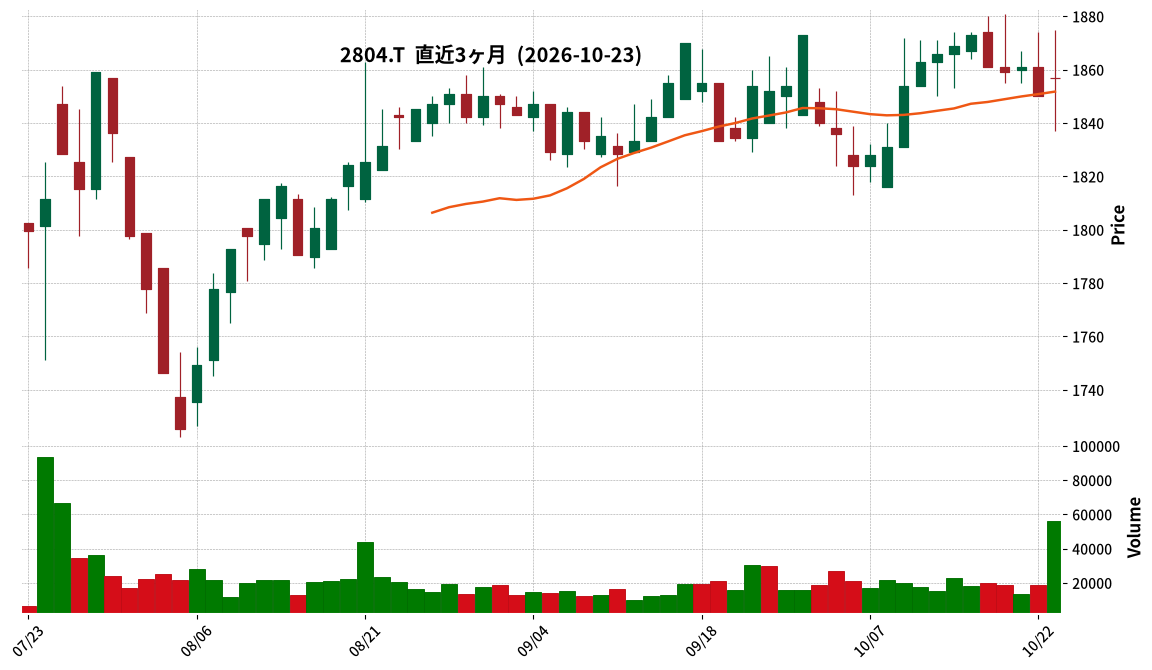
📎 Source:ブルドックソース Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- For the second quarter of the fiscal year ending March 2027, consolidated net sales increased by 0.3% year-on-year to ¥7.4 billion.
- Consolidated operating profit for the same period was ¥284 million (down 5.9% year-on-year), while consolidated ordinary profit was ¥1.042 billion (up 28.6% year-on-year).
- Net income attributable to parent company shareholders significantly decreased by 66.0% year-on-year to ¥702 million.
- Interim net income per share was ¥56.64, a decrease from ¥159.57 in the previous year’s interim period.
- The annual dividend forecast remains unchanged at ¥45.00, consisting of an interim dividend of ¥20.00 and a year-end forecast of ¥25.00.
- The full-year consolidated performance forecast for the fiscal year ending March 2027 remains unchanged, projecting net sales of ¥15.2 billion (up 3.5% year-on-year), operating profit of ¥620 million (up 1.1% year-on-year), ordinary profit of ¥1.35 billion (up 2.4% year-on-year), and net income attributable to parent company shareholders of ¥950 million (down 61.1% year-on-year).
🤖 AI Perspective
Bulldog Sauce’s Q2 FY2027 results show a slight increase in net sales, yet a substantial decline in net income attributable to parent shareholders compared to the prior year. This sharp decrease in net income warrants closer examination of specific factors that may have influenced the previous year’s interim results. The increase in ordinary profit, despite the operating profit decline, could indicate improvements in non-core earnings or financial income, which may be a point of interest for investors.
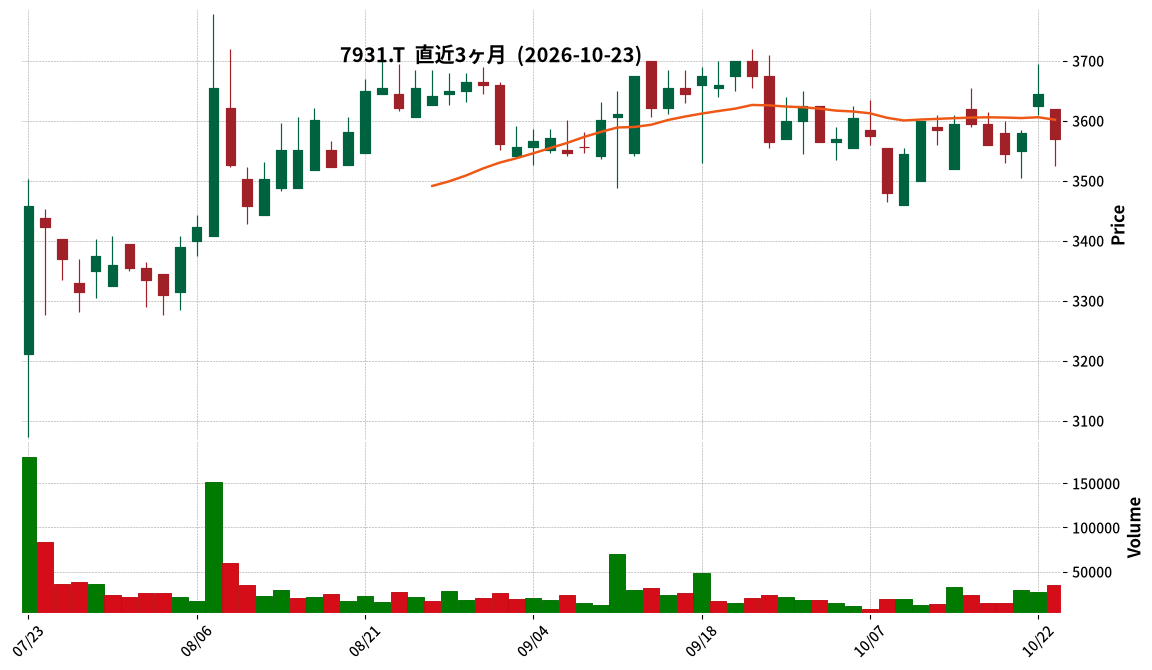
7931|未来工業
3570.0
▼ -2.06%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Mirai Industry Co., Ltd. has announced its consolidated financial results for the second quarter (interim) of the fiscal year ending March 2027.
- For the interim period, net sales reached ¥24,861 million, an increase of 8.3% compared to the previous interim period, marking a new record high.
- Operating profit was ¥3,792 million (up 20.0% YoY), ordinary profit was ¥3,925 million (up 20.7% YoY), and net profit attributable to owners of parent was ¥2,646 million (up 20.5% YoY), all setting new record highs.
- By segment, Electrical Materials & Pipes recorded sales of ¥19,033 million (up 8.4% YoY) and operating profit of ¥3,493 million (up 24.9% YoY). Wiring Devices reported sales of ¥4,325 million (up 11.6% YoY) and operating profit of ¥430 million (up 7.9% YoY).
- The consolidated full-year earnings forecast for the fiscal year ending March 2027 has been revised upwards, projecting net sales of ¥48,984 million (up 7.2% YoY), operating profit of ¥6,927 million (up 3.0% YoY), ordinary profit of ¥7,125 million (up 3.3% YoY), and net profit attributable to owners of parent of ¥4,755 million (up 1.2% YoY).
🤖 AI Perspective
Mirai Industry’s Q2 FY2027 results show robust performance with record-high sales and profits, suggesting a strong business trajectory. Factors such as pre-emptive procurement of certain products due to the Middle East situation, alternative demand driven by supply constraints, and the permeation of price revisions appear to have contributed to this growth. The upward revision of the full-year forecast could indicate management’s confidence in the current favorable market conditions.
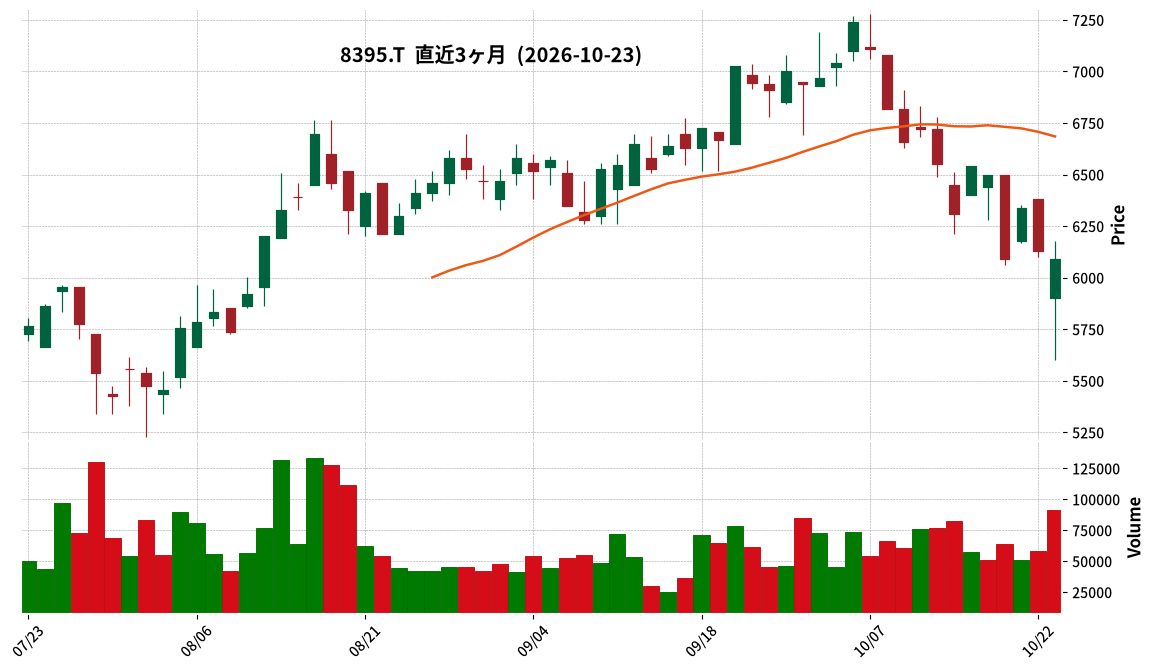
8395|佐賀銀
6090.0
▼ -0.65%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- The Saga Bank announced on October 23, 2026, a revision to its consolidated and non-consolidated earnings forecasts for the second quarter (cumulative) of the fiscal year ending March 2027.
- For the consolidated forecast, ordinary revenue is revised up by 5,000 million yen (15.6%) from the previous forecast of 32,000 million yen to 37,000 million yen. Net income attributable to parent company shareholders for the interim period is revised up by 700 million yen (13.7%) from 5,100 million yen to 5,800 million yen.
- For the non-consolidated forecast, ordinary revenue is revised up by 5,000 million yen (17.8%) from 28,000 million yen to 33,000 million yen. Net interim income is revised up by 800 million yen (16.6%) from 4,800 million yen to 5,600 million yen.
- The primary reasons for the earnings revision include an increase in ordinary revenue, mainly due to gains on sales of securities aimed at improving the bank’s portfolio, as well as an increase in interest income on loans and fee and commission income on a non-consolidated basis.
- The dividend forecast has also been revised, with the interim dividend for the fiscal year ending March 2027 increasing by 10 yen per share from 55 yen to 65 yen. The annual dividend is projected to be 120 yen, up from 110 yen previously, with the year-end dividend remaining at 55 yen.
🤖 AI Perspective
Saga Bank’s upward revision of its earnings forecast is noteworthy, particularly as it is driven by both gains on securities sales and increases in core business revenues such as interest income on loans and fee income. This may suggest an improvement in the bank’s revenue structure. Furthermore, the increase in the interim dividend, decided in consideration of current business performance, could indicate a proactive stance towards shareholder returns.
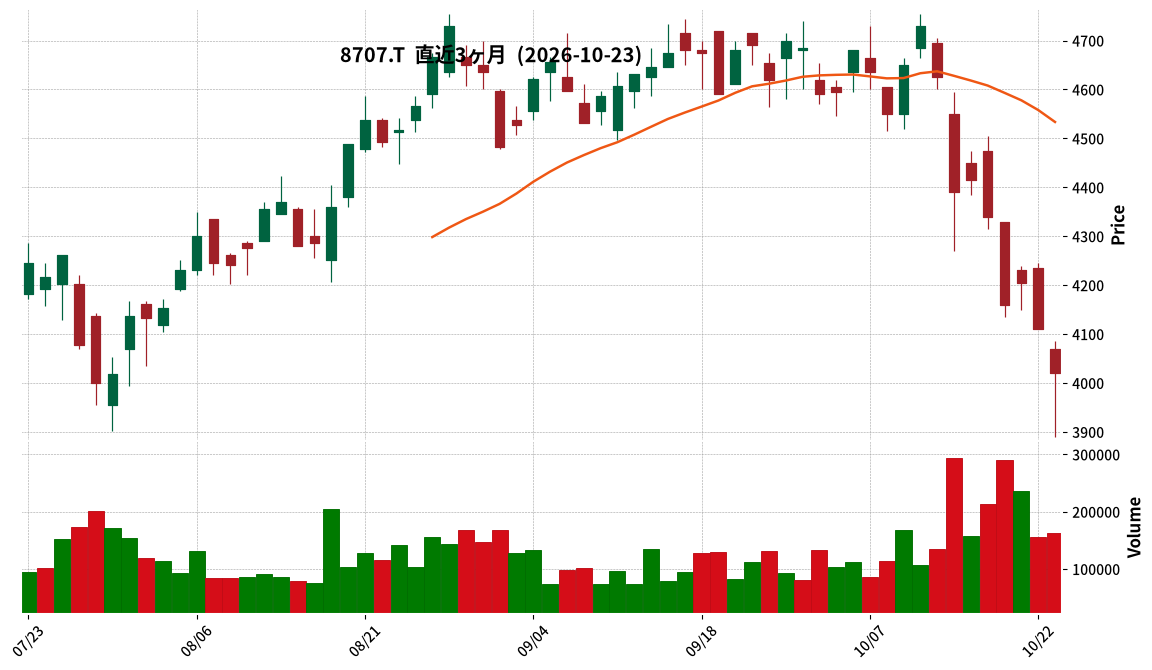
8707|岩井コスモ
4020.0
▼ -2.19%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- IwaiCosmo Holdings reported consolidated operating revenue of ¥18,141 million for the second quarter (interim period) of the fiscal year ending March 2027, representing a 25.5% increase year-on-year.
- Consolidated net operating revenue reached ¥17,902 million (up 25.3%), ordinary profit ¥8,237 million (up 42.4%), and net profit attributable to owners of parent ¥6,320 million (up 36.8%).
- Operating revenue, net operating revenue, operating profit, ordinary profit, and net profit attributable to owners of parent all reached record highs for this interim period.
- Diluted earnings per share for the interim period stood at ¥269.09.
- The company declared an interim dividend of ¥65.00 per share (compared to ¥60.00 for the previous year’s interim period), while the year-end dividend forecast remains undetermined.
🤖 AI Perspective
The strong interim financial results, with key revenue and profit metrics hitting record highs, suggest a robust performance. The substantial increases in operating revenue and various profit figures may indicate the success of the securities sales division’s focus on U.S. equities and investment trusts, as well as brand awareness efforts like TV commercials. The increase in the interim dividend could also be viewed as a positive signal regarding shareholder returns.
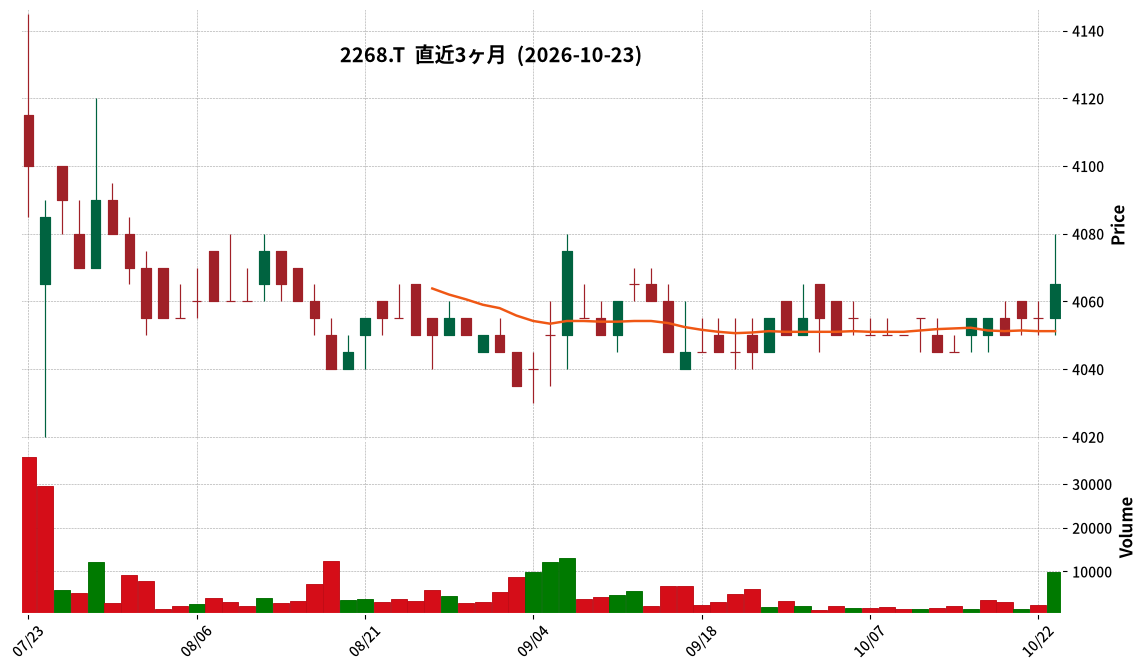
2268|サーティワン
4065.0
▲ +0.25%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- B-R 31 ICE CREAM Co., Ltd. announced its consolidated financial results for the third quarter of the fiscal year ending December 2026 (January 1, 2026, to September 30, 2026).
- For the nine months ended September 30, 2026, consolidated net sales were ¥30,037 million (up 16.2% year-on-year), operating profit was ¥3,116 million (up 2.1%), ordinary profit was ¥3,207 million (up 3.6%), and profit attributable to owners of parent was ¥2,071 million (up 4.2%).
- Basic earnings per share for the quarter were ¥214.95.
- As of the end of the third quarter, total assets stood at ¥32,573 million, net assets at ¥16,125 million, and the equity ratio at 49.5%.
- The forecast for the annual dividend for the fiscal year ending December 2026 is ¥30.00 for the interim dividend and ¥60.00 for the year-end dividend, totaling ¥90.00.
- The consolidated full-year earnings forecast for the fiscal year ending December 2026 remains unchanged, projecting net sales of ¥35,830 million (up 4.5% from the previous fiscal year), operating profit of ¥2,830 million (up 2.2%), ordinary profit of ¥2,880 million (up 0.6%), profit attributable to owners of parent of ¥1,800 million (up 1.6%), and basic earnings per share of ¥186.80.
🤖 AI Perspective
B-R 31 ICE CREAM’s Q3 FY2026 results show a significant 16.2% year-on-year increase in net sales, marking a new record, which may suggest effective business strategies. The continued positive growth in existing store sales for 22 consecutive quarters could indicate strong brand loyalty and successful marketing initiatives. The unchanged full-year forecasts suggest management’s confidence in the current progress towards their annual targets, which is worth monitoring for investors.
2531|宝HLD
2693.5
▼ -5.39%
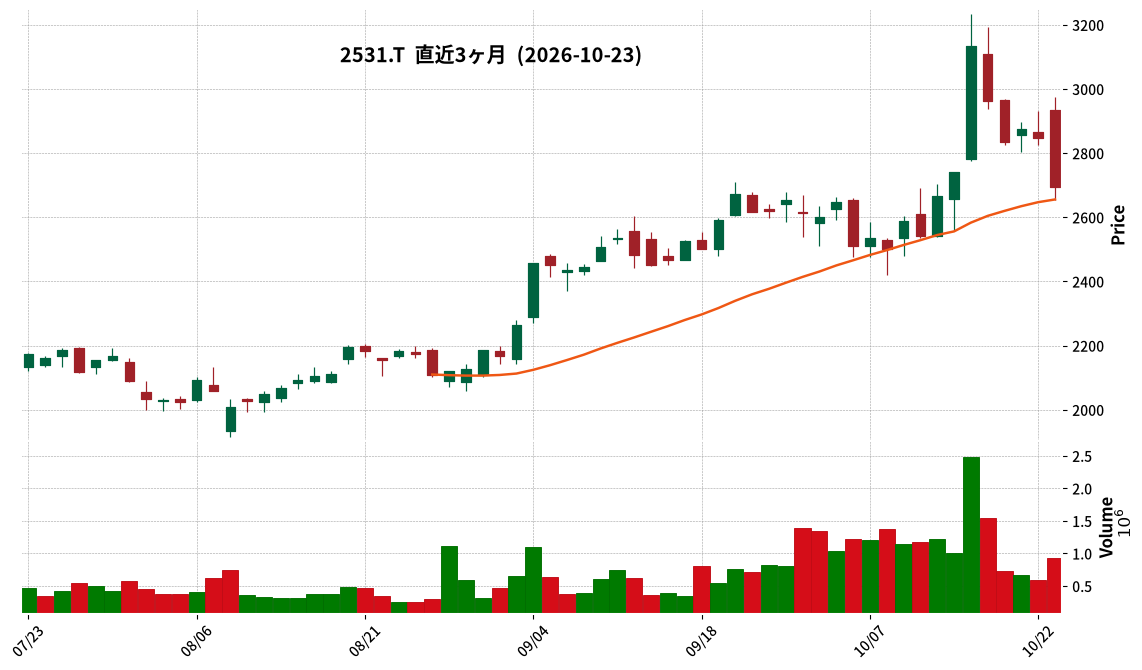
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Takara Holdings announced its consolidated financial results for the first quarter of the fiscal year ending March 2027 (April 1, 2026 – June 30, 2026).
- Net sales reached ¥103,207 million, marking a 10.6% increase year-on-year, while operating income decreased by 14.7% to ¥2,949 million.
- Ordinary income was ¥3,157 million (down 9.1% YoY), and net income attributable to owners of parent was ¥3,630 million (down 12.4% YoY).
- By segment, Takara Shuzo reported net sales of ¥30,245 million (up 2.5% YoY) and operating income of ¥1,468 million (up 47.5% YoY).
- Takara Shuzo International Group recorded net sales of ¥60,334 million (up 17.3% YoY) and operating income of ¥3,937 million (up 7.8% YoY).
- Takara Bio Group’s net sales were ¥9,204 million (down 0.7% YoY), with an operating loss of ¥3,384 million (compared to an operating loss of ¥1,796 million in the prior year’s period).
- The consolidated performance forecast for the second quarter (cumulative) of FY2027 has been revised upwards, projecting net sales of ¥210,870 million (up 13.0% YoY), operating income of ¥13,112 million (up 68.4% YoY), and net income attributable to owners of parent of ¥11,682 million (up 105.1% YoY).
- The full-year earnings forecast is currently under review and is expected to be announced on November 10, 2026, with the release of the second-quarter results.
🤖 AI Perspective
While net sales increased due to growth in the Takara Shuzo and Takara Shuzo International Group segments, operating income, ordinary income, and net income attributable to owners of parent saw declines. This trend may suggest impacts from increased selling, general and administrative expenses, an expanded operating loss in the Takara Bio Group, and the recording of extraordinary losses. The upward revision of the second-quarter cumulative earnings forecast could indicate an expected recovery in overall performance, making the upcoming full-year forecast announcement a key point for investors to monitor.
4043|トクヤマ
3761.0
▼ -1.03%
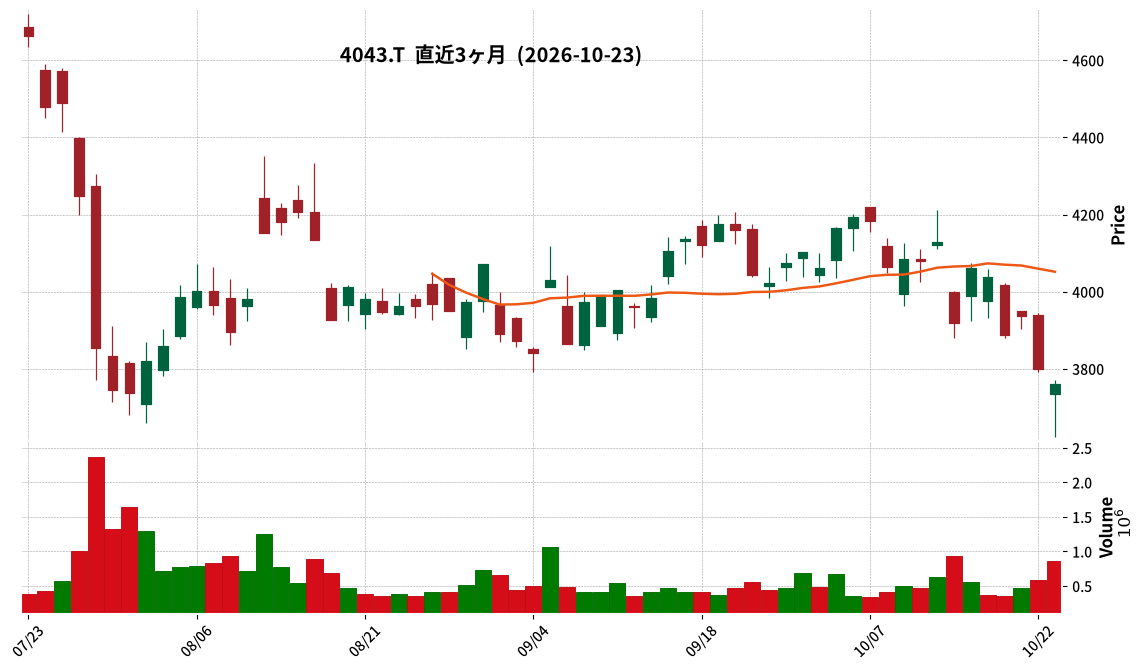
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Tokuyama Corporation resolved at its Board of Directors meeting on October 23, 2026, to absorb its wholly-owned subsidiary, Super Nano Design Co., Ltd.
- The effective date of the merger is scheduled for February 1, 2027.
- The merger will be an absorption-type merger with Tokuyama as the surviving company and Super Nano Design dissolving.
- As Super Nano Design is a wholly-owned subsidiary, no new shares will be issued, and no merger consideration will be paid.
- The purpose of this absorption merger is to streamline the organizational operations of Super Nano Design, which is engaged in the development of synthesis recipes and contract synthesis of particulate materials.
🤖 AI Perspective
This merger involves a wholly-owned subsidiary, aiming to enhance organizational efficiency. Such internal reorganizations often indicate a strategic effort to optimize group resources and simplify decision-making processes. The declared minor impact on consolidated earnings suggests that this is primarily an internal restructuring rather than a move expected to significantly alter the company’s financial outlook in the short term.
4434|サーバーワークス
3070.0
▼ -2.07%
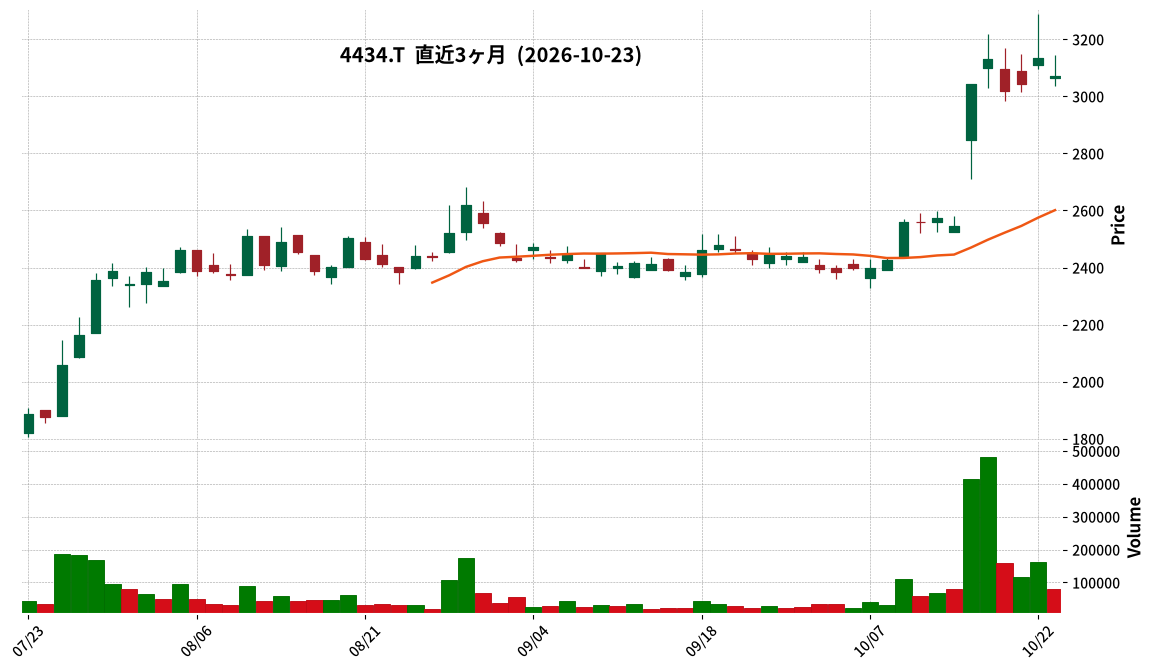
📎 Source:サーバーワークス Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- ServerWorks announced on October 23, 2026, that its Board of Directors resolved to acquire additional shares in its consolidated subsidiary, G-gen, making it a wholly-owned subsidiary.
- G-gen operates as a core company for Google Cloud business within ServerWorks’ multi-cloud strategy.
- The acquisition will increase ServerWorks’ voting rights ownership in G-gen from 66.6% to 100.0%.
- The shares are being acquired from Newberry Global Japan G.K., covering all 33.4% (65,910 shares) of G-gen shares held by them.
- ServerWorks stated that the impact of this transaction on its consolidated performance for the fiscal year ending February 2027 will be minor.
🤖 AI Perspective
ServerWorks’ move to wholly own G-gen suggests a strategic effort to strengthen its Google Cloud business within the group. This consolidation could lead to faster decision-making and optimized allocation of management resources, potentially enhancing overall corporate value. Investors may view this as a step towards more integrated and efficient execution of the company’s multi-cloud strategy.
5020|ENEOS
1418.0
▼ -0.70%
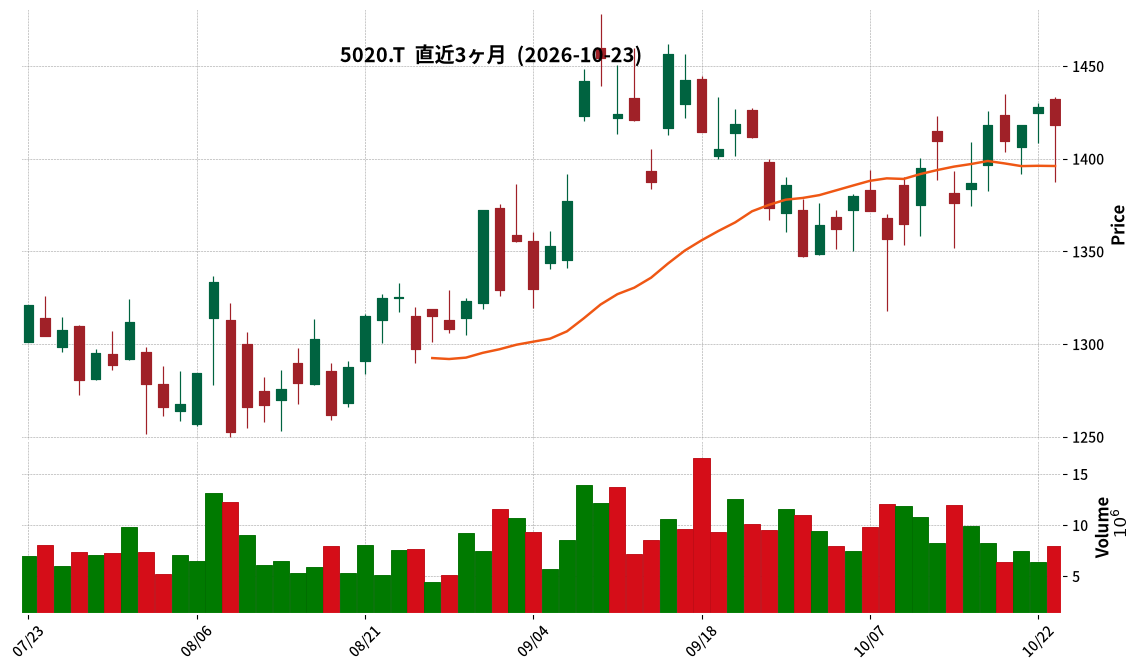
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- ENEOS Holdings resolved to acquire an additional 65% of the issued shares of its consolidated subsidiary, Roadmap Holdings Co., Ltd. (RMH), at its Board of Directors meeting on October 23, 2026.
- This acquisition will make RMH a wholly-owned subsidiary, leading to NIPPO Co., Ltd., a 100% subsidiary of RMH, also becoming 100% owned by the ENEOS Group.
- The sellers of the shares are Aether Holdings GK and J.L.Q. LLC, special purpose companies indirectly owned by The Goldman Sachs Group, Inc.
- ENEOS Group cites the optimization of the asphalt supply chain from manufacturing to road paving, and the utilization of NIPPO’s expertise in soil improvement and construction for idle land development and asset value enhancement as reasons for the acquisition.
- The share transfer is scheduled for November 2026, and the impact on the company’s fiscal year 2026 performance is expected to be minor.
🤖 AI Perspective
This full acquisition suggests a strategic shift by the ENEOS Group to strengthen core business profitability and pursue concrete synergy creation opportunities with NIPPO. The enhanced vertical integration of the asphalt supply chain and the effective utilization of idle assets may contribute to long-term group value. Transitioning from a joint ownership structure with Goldman Sachs to full ownership could enable faster decision-making and more integrated utilization of management resources.
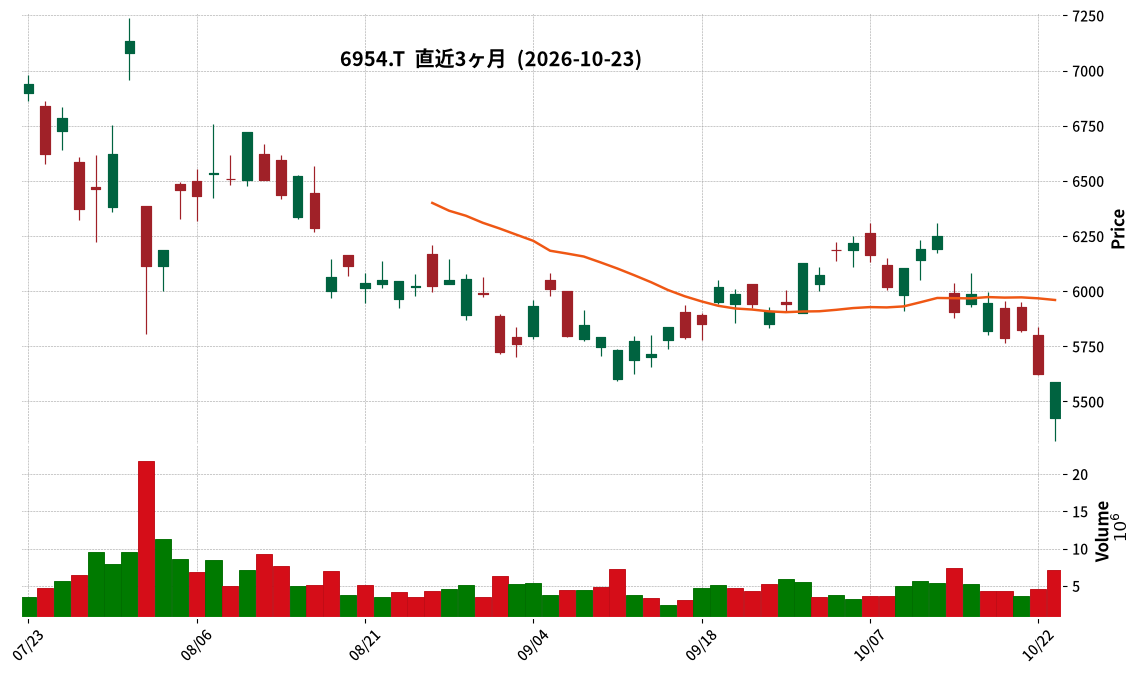
6954|ファナック
5587.0
▼ -0.66%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- FANUC announced its consolidated results for the second quarter (interim period) of the fiscal year ending March 2027, with net sales of ¥473,708 million (up 16.2% year-on-year), operating profit of ¥116,662 million (up 35.7%), ordinary profit of ¥149,045 million (up 38.1%), and profit attributable to owners of parent of ¥112,576 million (up 41.0%).
- By segment, FA segment sales were ¥119,898 million (up 15.4%), Robot segment sales were ¥194,324 million (up 12.6%), Robomachine segment sales were ¥83,272 million (up 31.2%), and Service segment sales were ¥76,214 million (up 12.7%).
- The full-year consolidated earnings forecast for the fiscal year ending March 2027 has been revised upwards, projecting net sales of ¥1,013,700 million (up 6.9% from previous forecast), operating profit of ¥240,700 million (up 10.4%), ordinary profit of ¥308,800 million (up 13.9%), and profit attributable to owners of parent of ¥228,300 million (up 15.3%).
- Regarding dividends, the interim dividend for the fiscal year ending March 2027 was announced at ¥72.54 per share (compared to ¥51.33 for the previous interim period). A revision to the full-year dividend forecast has also been disclosed.
- The exchange rate assumptions for the period from October 2026 to March 2027 are an average of ¥150 per US dollar and ¥175 per euro.
🤖 AI Perspective
The interim financial results show significant growth across all business segments, with the Robomachine segment notably increasing by 31.2%. The upward revision of the full-year earnings forecast across all key metrics suggests continued robust capital expenditure demand. The revision of the dividend forecast could indicate a positive stance towards shareholder returns.
Disclaimer: This article is for informational purposes only and does not constitute investment advice.
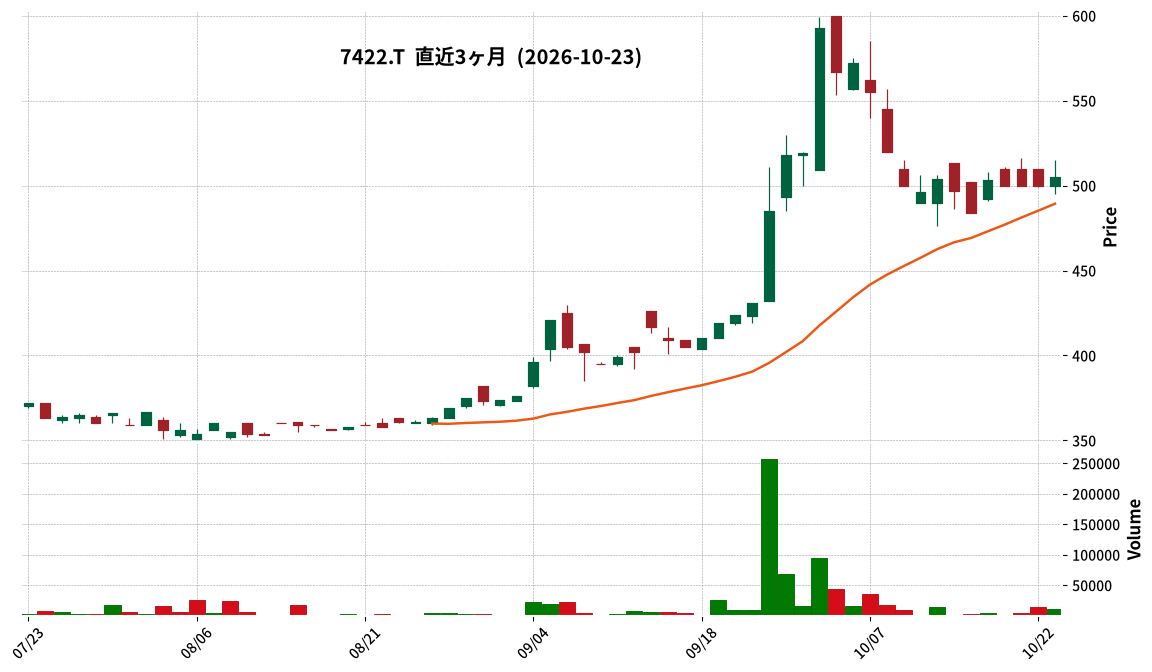
7422|東邦レマック
505.0
▲ +1.00%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Toho Lamac’s net sales for the third quarter of fiscal year 2026 (December 21, 2025 – September 20, 2026) amounted to JPY 3.308 billion, a 2.2% decrease year-over-year.
- During the same period, the company reported an operating loss of JPY 78 million (compared to an operating loss of JPY 71 million in the prior year), an ordinary loss of JPY 102 million (compared to an ordinary loss of JPY 44 million), and a net loss for the quarter of JPY 56 million (compared to a net loss of JPY 52 million).
- By segment, the Shoes business recorded net sales of JPY 2.991 billion (down 9.7% YoY) and an operating loss of JPY 100 million. The Real Estate business reported net sales of JPY 316 million (up 361.9% YoY) and an operating income of JPY 22 million.
- The full-year forecast for FY2026 (December 21, 2025 – December 20, 2026) remains unchanged from the most recently announced forecast, projecting net sales of JPY 4.816 billion (up 5.9% YoY), an operating loss of JPY 76 million, an ordinary loss of JPY 100 million, and a net loss of JPY 55 million.
- Regarding financial position, total assets increased by JPY 116 million from the end of the previous fiscal year to JPY 6.821 billion, while net assets decreased by JPY 139 million to JPY 4.382 billion, resulting in an equity ratio of 64.2%.
🤖 AI Perspective
Toho Lamac’s Q3 results indicate continued losses in key profitability metrics, with a decline in overall net sales compared to the previous year. While the Shoes business faced challenges, the significant growth in the Real Estate business suggests a potential shift in revenue drivers or a diversification of their business portfolio. The unchanged full-year forecast may imply the company anticipates future improvements in profitability, yet continued monitoring of both segments’ performance will be important for investors.
Disclaimer: This article is for informational purposes only and does not constitute investment advice.
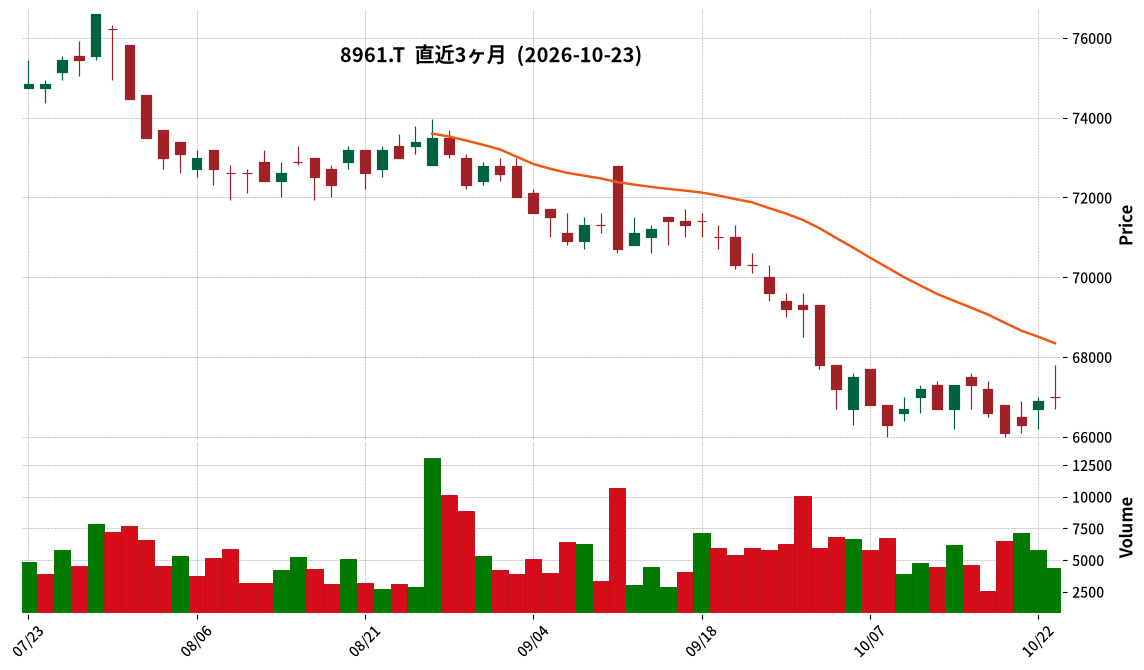
8961|R-森トラスト
67000.0
▲ +0.15%
📎 Source:R-森トラスト Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- R-MORI TRUST announced its operating results for the 2026 August fiscal period (March 1, 2026, to August 31, 2026).
- Operating revenue for the period was ¥11,830 million, a 2.1% increase compared to the previous period (2026 February fiscal period).
- Operating income reached ¥7,558 million (+1.8% YoY), ordinary income ¥6,591 million (+0.7% YoY), and net income ¥6,580 million (+0.7% YoY).
- Net income per unit was ¥1,848, and distribution per unit was ¥1,850.
- Forecasts for the 2027 February and 2027 August fiscal periods were also released, with an estimated distribution per unit of ¥1,800 for Feb 2027 and ¥1,810 for Aug 2027.
- The occupancy rate for properties held at the end of the period was 99.5% (99.1% based on sublease contracts).
🤖 AI Perspective
R-MORI TRUST’s 2026 August fiscal period results show growth across key revenue and profit metrics, suggesting a stable operational performance. The distribution per unit also increased from the previous period, which may indicate a continued commitment to unitholder returns. The forecasts for the upcoming periods, however, suggest a slight adjustment in distributions, making it important to monitor the underlying factors and future portfolio strategies.
Disclaimer: This article is for informational purposes only and does not constitute investment advice.
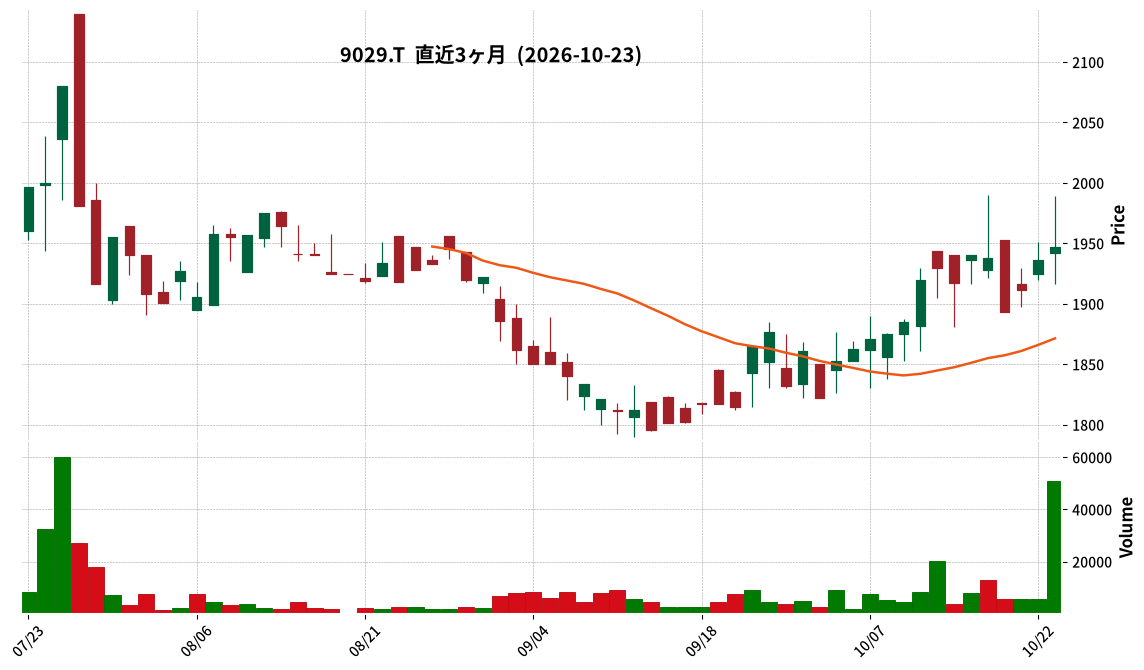
9029|ヒガシHD
1947.0
▲ +0.57%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Higashi Holdings Co., Ltd. announced its consolidated financial results for the second quarter (interim period) of the fiscal year ending March 2027.
- Consolidated cumulative performance showed net sales of ¥30,046 million (up 12.1% year-on-year), operating profit of ¥2,046 million (up 10.1%), ordinary profit of ¥2,228 million (up 15.5%), and net income attributable to owners of parent of ¥1,380 million (up 12.8%).
- Interim net income per share was ¥105.36 (compared to ¥93.76 in the prior interim period).
- The consolidated financial position indicated total assets of ¥35,333 million, net assets of ¥17,069 million, and an equity ratio of 48.3%.
- The full-year dividend forecast for the fiscal year ending March 2027 remains at ¥62.00, with no revision from the latest announced forecast.
- The consolidated full-year performance forecast for the fiscal year ending March 2027 includes net sales of ¥59,000 million, operating profit of ¥4,100 million, ordinary profit of ¥4,250 million, net income attributable to owners of parent of ¥2,703 million, and net income per share of ¥206.16, with no change from the latest announced forecast.
🤖 AI Perspective
Higashi HD’s Q2 FY2027 results demonstrate solid growth across revenue and all profit metrics, surpassing the previous interim period. This performance appears to be driven by factors such as the expanded operation of logistics centers for major e-commerce companies, growth in the office services business, and securing large IT-related projects. The strong sales increase in both the warehousing segment (up 21.1%) and the transportation segment (up 11.0%) suggests a well-balanced growth strategy across its various business areas.
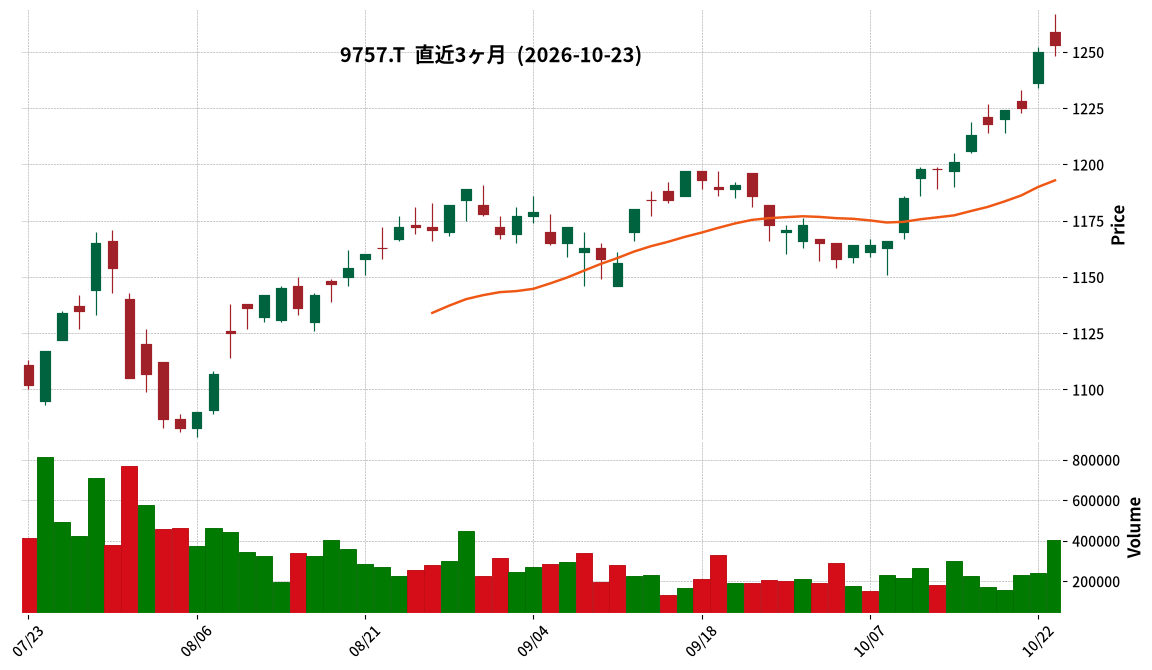
9757|船井総研HD
1253.0
▲ +0.24%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Funai Soken Holdings Co., Ltd. has resolved to change and introduce a new shareholder benefit program.
- The objectives of the change are to enhance investment attractiveness, improve liquidity, and strengthen dialogue with shareholders.
- The existing QUO card gifting system will be abolished, and the “Funai Soken Holdings Premium Shareholder’s Club” will be newly established.
- The new system will apply to shareholders holding 400 shares or more as of December 31 each year, starting from shareholders registered as of December 31, 2026.
- The benefits will consist of shareholder benefit points (1 point ≈ 1 yen equivalent) based on the number of shares held, redeemable for over 5,000 products on a dedicated website. Points can also be combined with those from other “Premium Shareholder’s Club” participating companies.
- Shareholder benefit points can be carried over for a maximum of two times, provided the shareholder maintains 400 or more shares and is listed with the same shareholder number for two consecutive record dates or more.
🤖 AI Perspective
This change in the shareholder benefit program, moving from gift cards to a points-based system with a wide selection of items, may be intended to cater to a broader range of shareholder preferences. Furthermore, the introduction of the “Premium Shareholder’s Club” for information dissemination and surveys could indicate the company’s focus on strengthening shareholder engagement and leveraging IR activities. The new eligibility threshold of 400 shares may also be a point of interest regarding its potential impact on shareholder composition and stock liquidity.
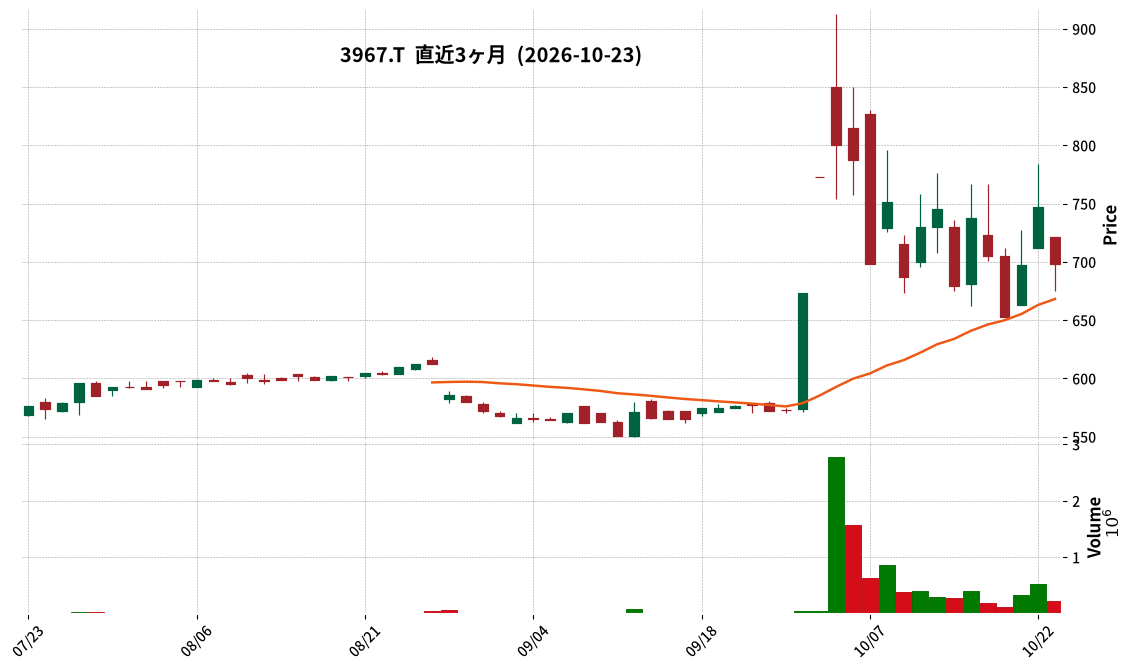
3967|G-エルテス
698.0
▼ -6.56%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Consolidated net sales for Q2 FY2027 reached ¥4,453 million (YoY +8.1%), marking a record high for the first half.
- Consolidated operating profit was ¥135 million (YoY +46.6%), and consolidated ordinary profit was ¥120 million (YoY +115.0%).
- Net profit attributable to owners of the parent for the interim period was a loss of △¥19 million, but the full-year forecast remains unchanged.
- The equity ratio improved to 32.9% (February 2026: 25.5%).
- Progress against the full-year consolidated performance forecast was 52.4% for net sales and 28.2% for operating profit. Operating profit is expected to increase significantly in the second half due to the elimination of double rent payments from office relocation.
- Negotiations are underway to sell GloLing and PlayNextLab within the current fiscal year, with expectations of improved ordinary and net profits from the next fiscal year due to reduced interest-bearing debt, goodwill amortization, and interest expenses.
- The company is considering initiating dividends, with a view to potentially changing its dividend policy within the current year.
🤖 AI Perspective
EluTES’s Q2 FY2027 earnings FAQ highlights record-high net sales and robust operating profit growth, suggesting steady business expansion. The company’s commentary on a second-half weighted profit structure, alongside the anticipated financial improvements from the divestiture of non-core businesses, could be key factors for investors to monitor. Furthermore, the explicit consideration of initiating dividends indicates a potential shift towards enhanced shareholder returns, which may attract broader investor interest.
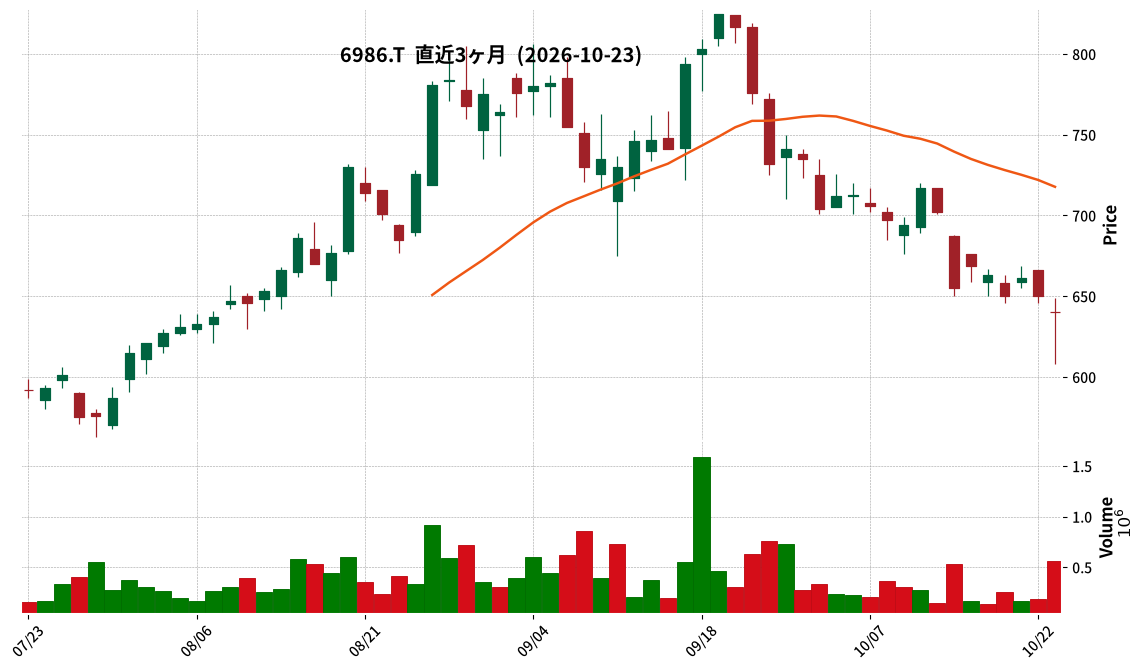
6986|双葉電子
640.0
▼ -1.54%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Futaba Corporation resolved to acquire shares of Enjyu Co., Ltd., making it a subsidiary, at its Board of Directors meeting on October 23, 2026.
- Enjyu Co., Ltd. specializes in surface robotics, primarily developing and selling unmanned surface vessels (USVs) for defense, coast guard, surveying infrastructure inspection, and agriculture/forestry/fisheries sectors.
- Futaba Corporation will acquire 4,388 shares of Enjyu for ¥698 million, resulting in a 91.9% ownership stake post-acquisition.
- The acquisition aims to expand Futaba’s robotics solutions business by integrating its UAV-related technologies with Enjyu’s USV-related technologies.
- The impact of this share acquisition on Futaba’s consolidated financial results is stated to be minor.
🤖 AI Perspective
This acquisition appears to be a strategic move by Futaba Corporation to expand its robotics solutions business beyond existing hobby radio control equipment, industrial servos, and UAVs, into the domain of surface robotics (USVs). The integration of Enjyu’s water-based technologies with Futaba’s aerial drone expertise may suggest a broader approach to unmanned systems and could strengthen its customer base in defense, local government, and infrastructure sectors. While the immediate impact on consolidated earnings is stated as minor, the long-term potential for synergistic growth in diversified robotics applications is worth monitoring.
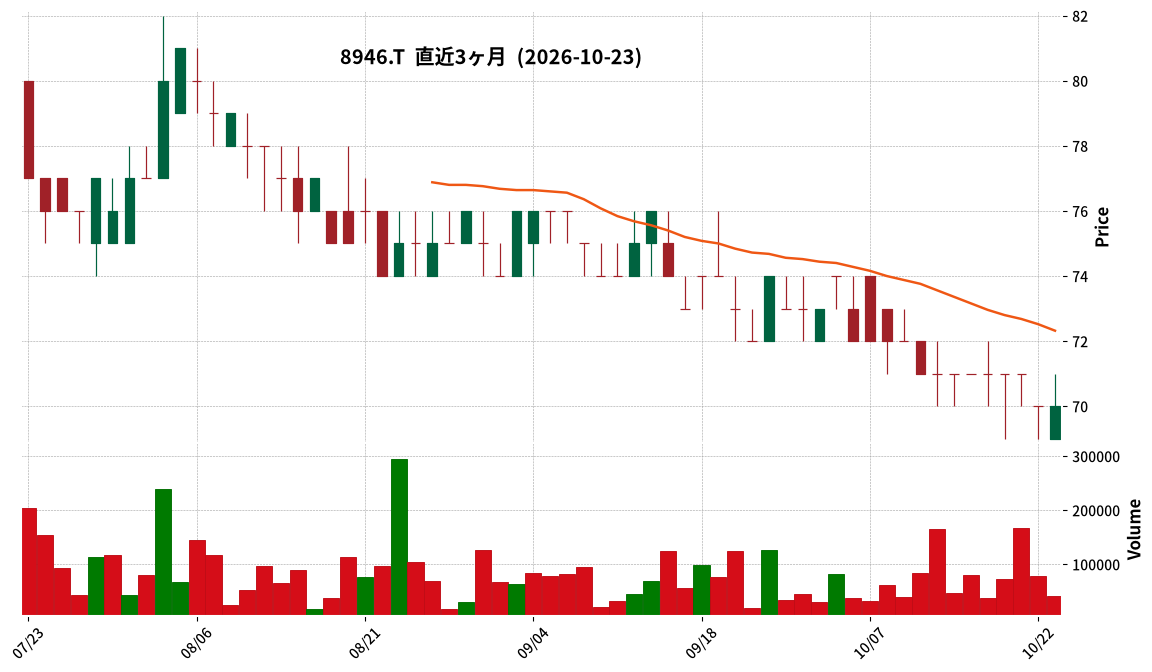
8946|エイシアンスター
70.0
▲ +0.00%
📎 Source:エイシアンスター Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- ASIAN STAR Co., Ltd. resolved to enter into a business alliance concerning real estate operations with HomeRing Co., Ltd. (HR Co.) at its Board of Directors meeting held on October 23, 2026.
- The purpose of this alliance is to leverage the expertise and project information in real estate brokerage, buying and reselling, and rental management possessed by HR Co. and its representative, Hao Hu, to accelerate revenue generation for ASIAN STAR’s wholly-owned subsidiary, ASIAN STAR Real Estate Co., Ltd. (AS Fudosan).
- Hao Hu, the representative director of HR Co., assumed the positions of Executive Officer of ASIAN STAR and Representative Director of AS Fudosan on July 10, 2026.
- The business alliance includes establishing AS Fudosan’s structure (real estate brokerage, buying and reselling, and rental management businesses), HR Co.’s referral of brokerage and buy-resell projects, partial entrustment of rental management operations, and ASIAN STAR’s acceptance of partial management of 693 rental properties (as of July end 2026) from HR Co.
- HR Co. is classified as a related party, with Executive Officer Hao Hu holding 100% of the voting rights, and a policy is in place to ensure Mr. Hu does not participate in decision-making for this transaction to manage potential conflicts of interest.
🤖 AI Perspective
This business alliance formalizes a strategic move to integrate expertise from HR Co., led by current ASIAN STAR Executive Officer Hao Hu, into ASIAN STAR’s real estate segment. The focus on leveraging HR Co.’s specialized know-how and existing project pipeline suggests a concentrated effort to boost the profitability of AS Fudosan. The disclosure of related-party transaction procedures, including Mr. Hu’s non-involvement in decision-making for this specific deal, aims to ensure governance and objectivity.
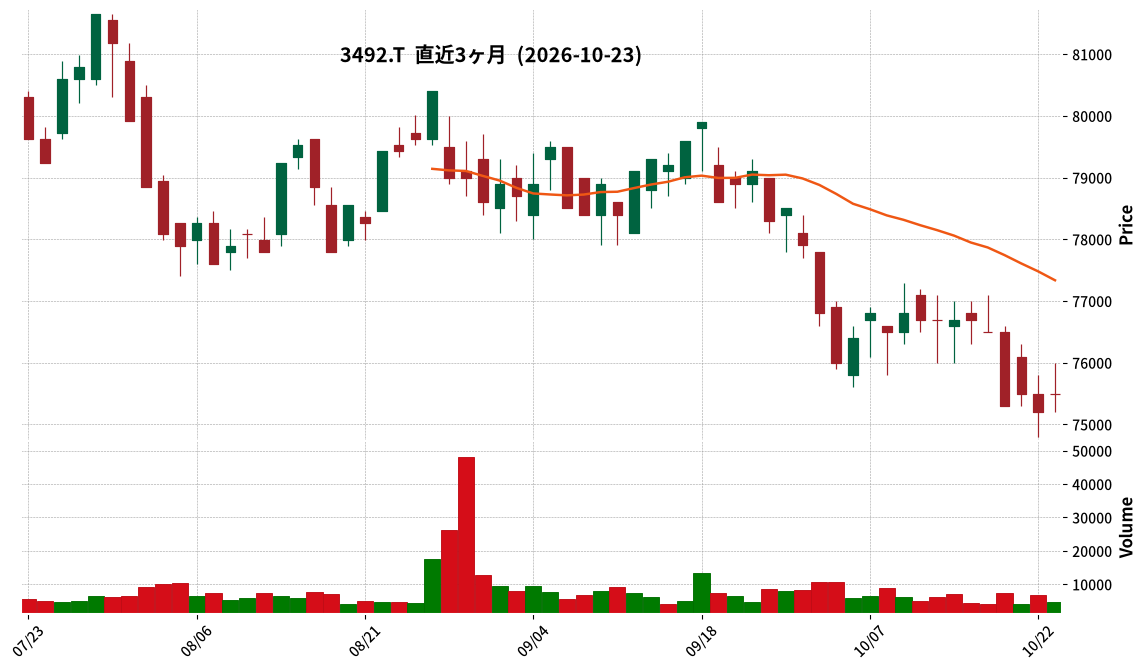
3492|R-MIRARTH
75500.0
▲ +0.40%
📎 Source:R-MIRARTH Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- R-MIRARTH announced its financial results for the fiscal period ended August 2026.
- Operating revenue reached ¥5,845 million (up 5.1% from the previous period), and operating income was ¥3,537 million (up 6.5%).
- Distribution per unit (excluding excess distribution) was ¥2,700, with a total distribution amount of ¥2,735 million.
- Total assets amounted to ¥209,942 million, and net assets were ¥99,158 million, resulting in an equity ratio of 47.2%.
- For the upcoming fiscal periods ending February 2027 and August 2027, the forecast for distribution per unit is ¥2,700 for both periods.
- The REIT acquired three residential properties, two office properties, and one retail property on March 3, 2026.
🤖 AI Perspective
R-MIRARTH’s August 2026 results show growth in operating revenue and income, alongside an expansion of its asset base, which may reflect the impact of strategic property acquisitions and operational efficiencies. The consistent distribution per unit forecast for future periods could indicate a focus on stable investor returns. Investors may find it worthwhile to monitor the continued growth in assets and its impact on long-term performance.
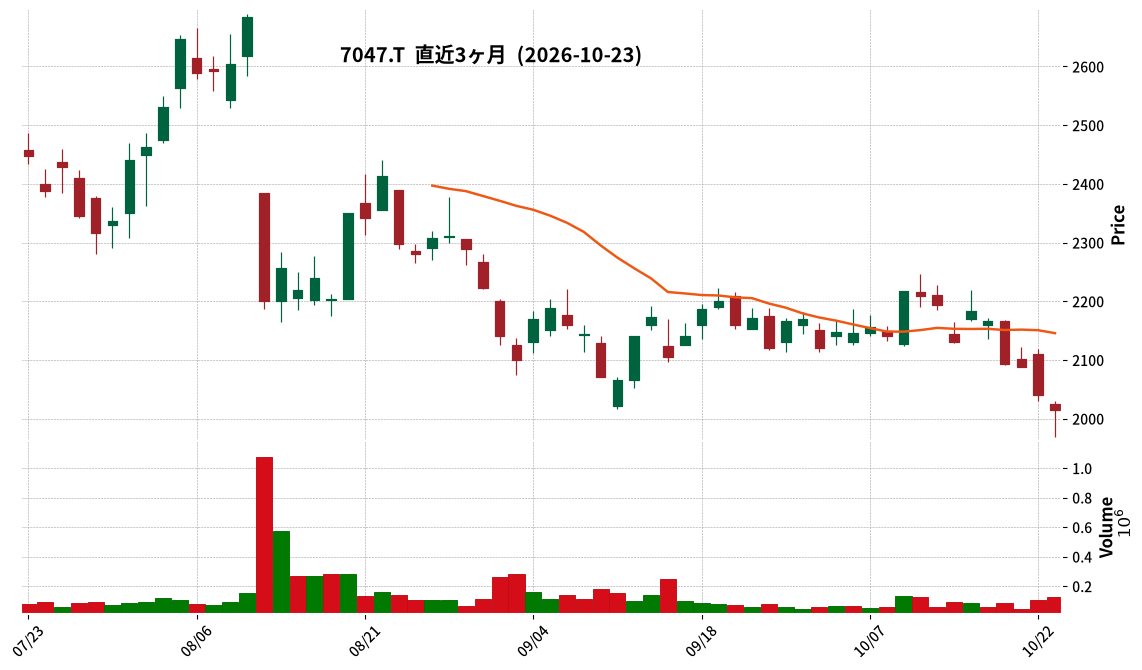
7047|G-ポート
2014.0
▼ -1.27%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- G-Port Co., Ltd. resolved to acquire all shares of ENECHANGE Customer Service Co., Ltd., a new company to be established by ENECHANGE Corporation through a company split (absorption-type split), making it a wholly-owned subsidiary.
- The execution date for this share acquisition is scheduled for December 1, 2026.
- The acquisition price is ¥200 million, to be settled in cash from available funds.
- ENECHANGE Customer Service, established on September 24, 2026, with a capital of ¥1, will succeed ENECHANGE’s call center and offline business.
- For the fiscal year ended March 2026, the acquired business recorded sales of approximately ¥2.0 billion and a business loss (before head office expense allocation) of approximately ¥0.2 billion. Sales for the fiscal year ending March 2027 are projected to be on a declining trend year-on-year.
🤖 AI Perspective
This acquisition appears to be a continuation of G-Port’s roll-up strategy in the energy contract support sector, which the company claims to be the largest in Japan. Despite the acquired business showing a declining revenue trend and operational losses, G-Port aims for early profitability through integrating its strong contract capabilities and commercial channels. This move could indicate G-Port’s strategic focus on leveraging existing assets and expertise to turn around underperforming acquisitions and enhance overall corporate value.
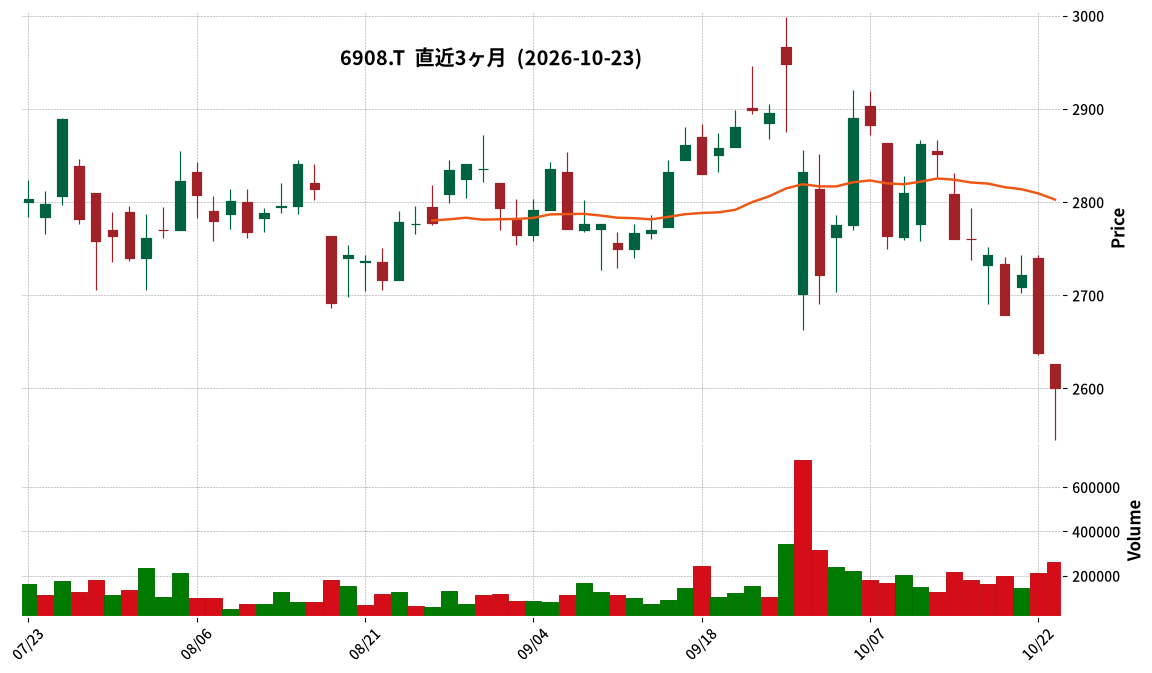
6908|イリソ電子工業
2601.0
▼ -1.40%
📎 Source:イリソ電子工業 Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- I-PEX Inc. has announced that the release date for its Q1 FY2027 financial results will be November 13, 2026.
- This announcement follows a prior notification on July 30, 2026, regarding the delay of the Q1 FY2027 earnings release beyond the 45-day post-quarter-end period.
- The company also stated that its Q2 FY2027 financial results are scheduled to be announced on the same date, November 13, 2026.
- I-PEX Inc. reiterated its apologies to shareholders, investors, and business partners for the inconvenience and concern caused by the delay in the financial results announcement.
🤖 AI Perspective
I-PEX Inc.’s decision to finalize the release date for its Q1 FY2027 earnings provides investors with a concrete timeline for overdue information. The simultaneous release of both Q1 and Q2 FY2027 results on November 13th could offer a comprehensive view of the company’s performance trends across multiple periods. This development may help to alleviate the information vacuum that has existed due to the previously announced delay.
Disclaimer: This article is for informational purposes only and does not constitute investment advice.
💡 Start investing with IR insights


※ 本ページには広告が含まれます(PR)
Disclaimer: This article is for informational purposes only and does not constitute investment advice. All investment decisions are at your own risk.
コメント