📌 Today’s Highlights
Today we cover 24 IR announcements. Notable among them: GXNDXカバコ (2865), SANEI (6230), KOA (6999). Use the table of contents below to navigate to each company.
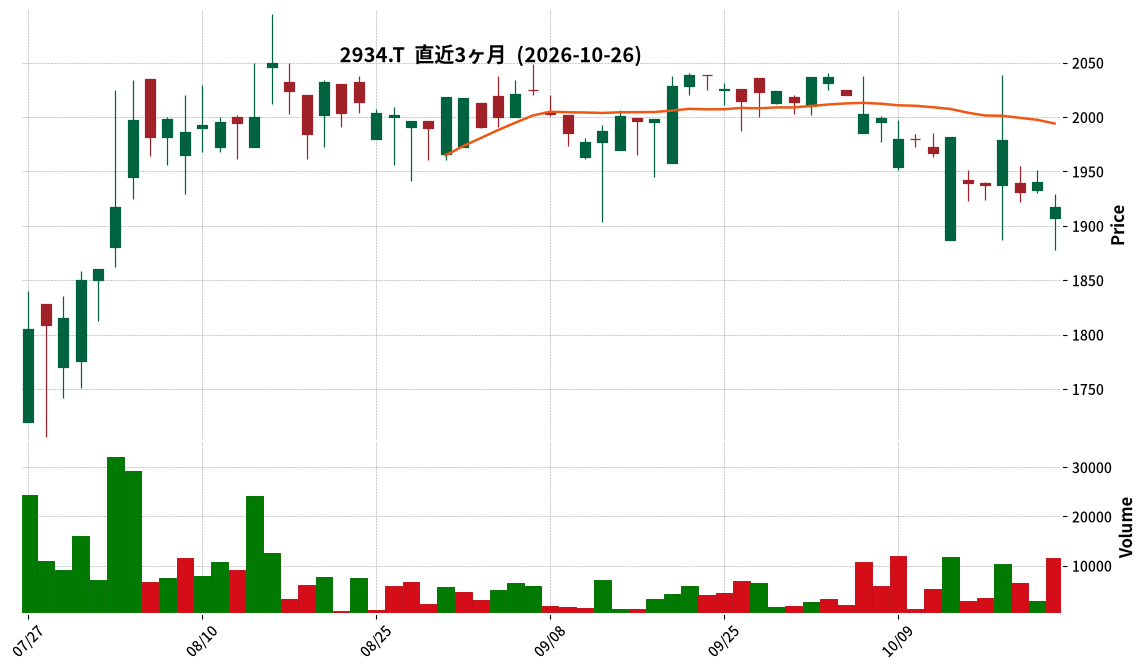
2934|G-Jフロンティア
1917.0
▼ -1.19%
📎 Source:G-Jフロンティア Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- J-Frontier Co., Ltd. has decided to add “Amazon Gift Cards” to its shareholder benefit program, “J-Frontier Premium Shareholder Benefits Club.”
- The redemption for the newly added Amazon Gift Cards is scheduled to begin in mid-January 2027, applying to shareholder benefits based on the record date of November 30, 2026.
- A fee equivalent to 5% will be included for exchanges into Amazon Gift Cards.
- There are no changes to the points awarded based on the number of shares held and holding period, which range from 5,000 points for 400 shares or more, up to 140,000 points for 1,500 shares or more.
- Shareholder benefit points are granted to shareholders recorded on the shareholder register as of November 30 each year, holding 4 units (400 shares) or more.
🤖 AI Perspective
The addition of Amazon Gift Cards to the shareholder benefits, a highly popular option, suggests an aim to enhance shareholder convenience and increase interest in the program. This expansion, responding to shareholder demand, could potentially encourage long-term stock ownership and broaden the investor base. Investors may find it worthwhile to consider the 5% exchange fee and other detailed conditions for continuous ownership.
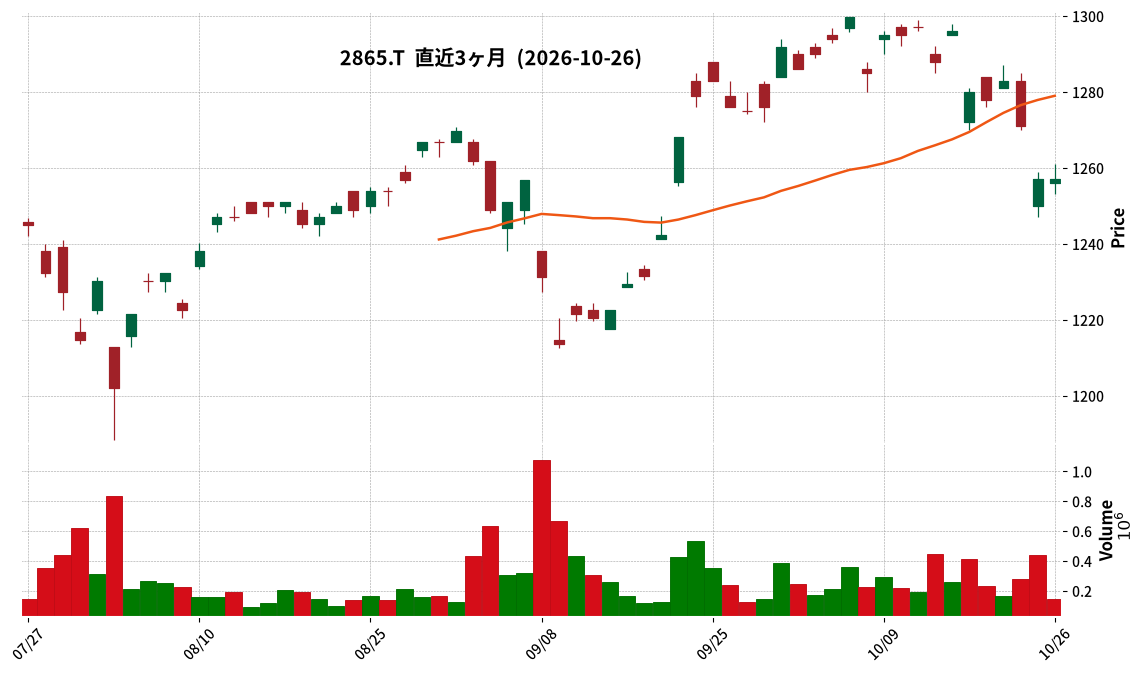
2865|GXNDXカバコ
1257.0
▲ +0.00%
📎 Source:GXNDXカバコ Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Global X NASDAQ 100 Covered Call ETF (2865) announced its financial results for the period ended September 10, 2026, on October 26, 2026.
- Total net assets as of September 10, 2026, amounted to ¥50,152 million, an increase from ¥42,619 million at the end of the previous period (March 10, 2026).
- The number of outstanding units at the end of the reporting period was 40,550 thousand units, up from 35,000 thousand units at the end of the previous period.
- The net asset value per 100 units was ¥123,681 at the end of the current reporting period, compared to ¥121,769 at the end of the previous period.
- Distributions per 100 units were ¥1,000 for September 2026 and ¥1,100 for August 2026, indicating consistent monthly payouts.
🤖 AI Perspective
The reported increase in net assets and outstanding units suggests continued capital inflow into the fund. The rise in the net asset value per 100 units may indicate stable fund performance over the period. The consistent monthly distribution payouts could be a notable aspect for investors seeking regular income from their investments.
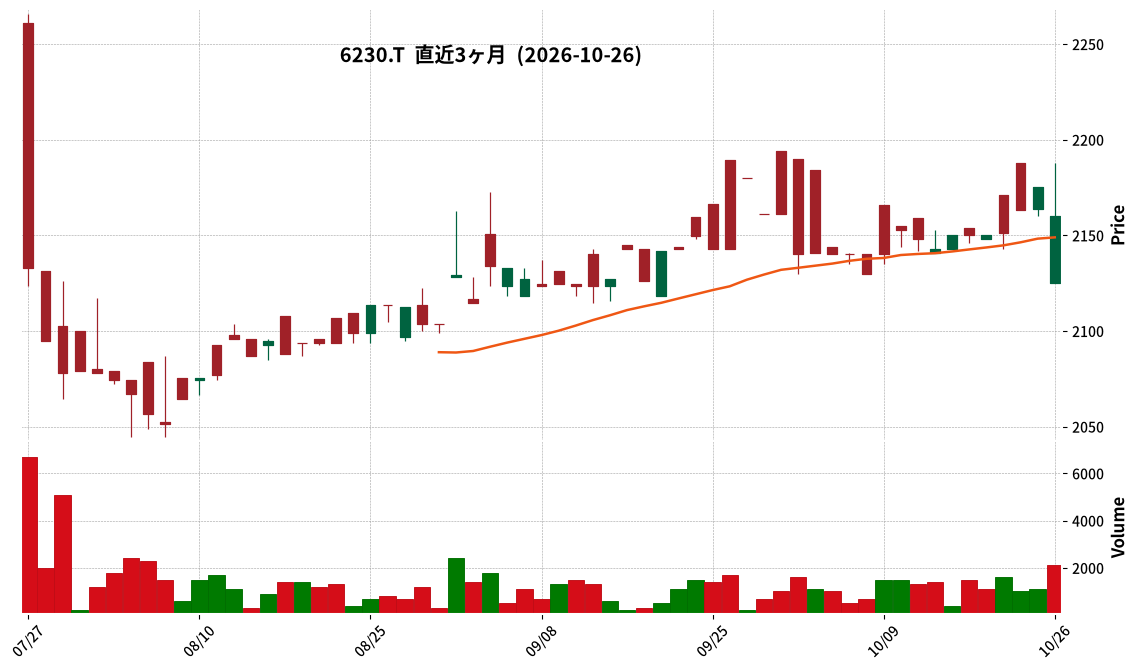
6230|SANEI
2160.0
▼ -0.69%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- SANEI Co., Ltd. announced its consolidated financial results for the second quarter (interim) of the fiscal year ending March 2027 on October 26, 2026.
- Consolidated net sales for the interim period amounted to JPY 14,441 million, a 2.9% increase compared to the same period of the previous year.
- Consolidated operating profit was JPY 333 million (a 50.1% decrease year-on-year), consolidated ordinary profit was JPY 283 million (a 59.2% decrease year-on-year), and net income attributable to owners of parent was JPY 175 million (a 60.3% decrease year-on-year).
- Interim net income per share was JPY 38.27.
- The consolidated full-year earnings forecast for the fiscal year ending March 2027 has been revised, projecting net sales of JPY 29,500 million (a 1.6% increase from the previous period), operating profit of JPY 1,100 million (a 39.9% decrease), ordinary profit of JPY 1,000 million (a 44.6% decrease), net income attributable to owners of parent of JPY 650 million (a 46.8% decrease), and earnings per share of JPY 141.99.
- The annual dividend forecast is JPY 37.00 for the interim period and JPY 38.00 for the year-end, totaling JPY 75.00.
🤖 AI Perspective
While net sales showed a slight increase, operating profit, ordinary profit, and net income attributable to owners of parent experienced significant year-on-year declines. This decrease in profitability may suggest impacts from a reduction in gross profit and an increase in non-operating expenses, including interest payments, note sales losses, and foreign exchange losses. The revision of the full-year earnings forecast warrants monitoring to understand how future business conditions and cost structure changes might influence performance.
Disclaimer: This article is for informational purposes only and does not constitute investment advice.
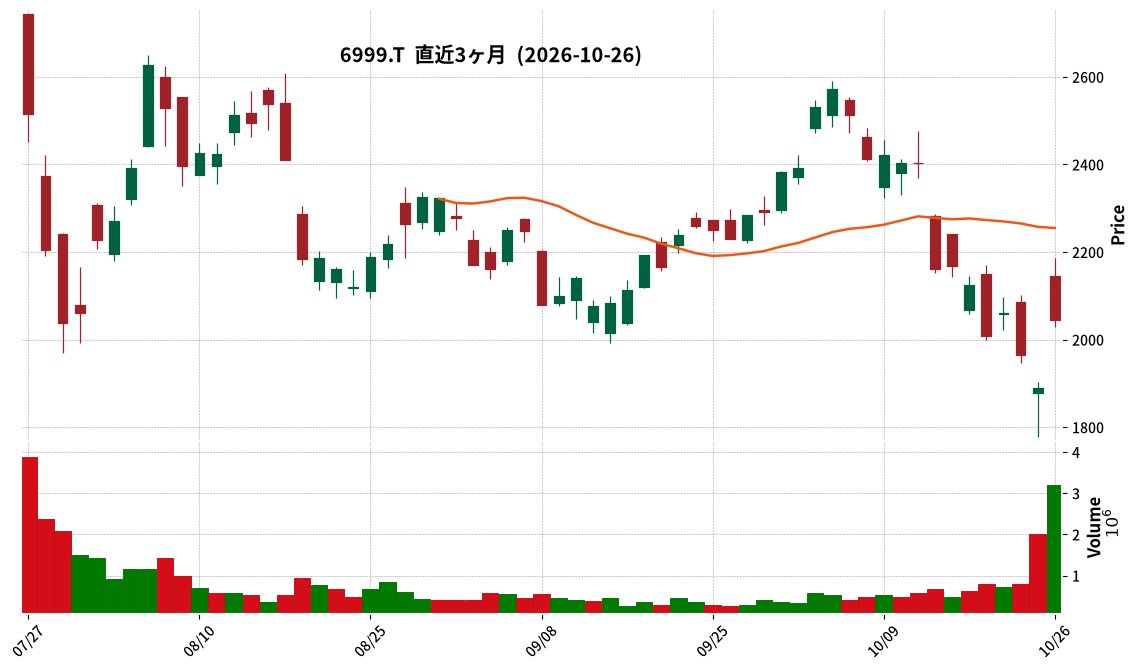
6999|KOA
2044.0
▲ +8.21%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- KOA Corporation announced its financial results for the second quarter of the fiscal year ending March 2027 (April 1, 2026 – September 30, 2026).
- Net sales for the quarter reached ¥43.63 billion, marking a record high for a half-year period and an increase of ¥9.00 billion compared to the prior year.
- Operating income was ¥3.74 billion (up ¥2.43 billion year-on-year), ordinary income was ¥3.98 billion (up ¥2.37 billion year-on-year), and net income attributable to owners of the parent was ¥5.82 billion (up ¥4.67 billion year-on-year).
- The significant increase in net income was partly due to the recording of ¥3.10 billion as extraordinary income from compensation related to the factory relocation of its consolidated subsidiary, KOWA ELECTRONICS (TAICANG) CO., LTD.
- By application, automotive accounted for 47% of sales, industrial equipment 13%, and telecommunications 9%. The Asia region contributed 44% of total sales.
- The full-year forecast for the fiscal year ending March 2027 has been revised, anticipating net sales of ¥91.50 billion, operating income of ¥8.31 billion, ordinary income of ¥8.56 billion, and net income attributable to owners of the parent of ¥9.66 billion.
🤖 AI Perspective
KOA’s Q2 FY2027 results show a strong performance with record-high net sales and a substantial increase in net income. This performance appears to be driven by robust demand across various sectors, including automotive in China, distributors in Europe, the US, and China, AI-related equipment in Asia, and industrial equipment in Japan. The upward revision of the full-year outlook suggests that the company anticipates continued strong order trends in automotive, AI-related equipment, and industrial equipment for the latter half of the fiscal year.
8190|ヤマナカ
—
▲ +0.00%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- For the second quarter of FY2027 (interim period), consolidated operating revenue was ¥42,242 million, an increase of 2.0% compared to the prior interim period.
- In the same interim period, consolidated operating income was △¥394 million, ordinary income was △¥351 million, and net income attributable to owners of parent was △¥260 million.
- Interim basic earnings per share were △¥13.68.
- As of the end of the interim period, consolidated total assets were ¥42,688 million, net assets were ¥17,994 million, and the equity ratio was 42.2%.
- The forecast for the annual dividend for FY2027 remains unchanged from the most recently announced forecast, with an expected year-end dividend of ¥5.00 per share, totaling ¥10.00.
- The full-year consolidated earnings forecast remains unchanged from the most recently announced forecast: operating revenue of ¥90,500 million (an 8.7% increase from the previous fiscal year), operating income of ¥480 million, ordinary income of ¥520 million, and net income attributable to owners of parent of ¥350 million.
🤖 AI Perspective
Yamanaka’s Q2 FY2027 results show an increase in revenue, but various profit metrics turned negative, potentially influenced by rising raw material costs. The unchanged full-year earnings forecast might suggest management anticipates a recovery in the second half of the fiscal year. The maintained dividend forecast could be viewed as the company’s commitment to shareholder returns.
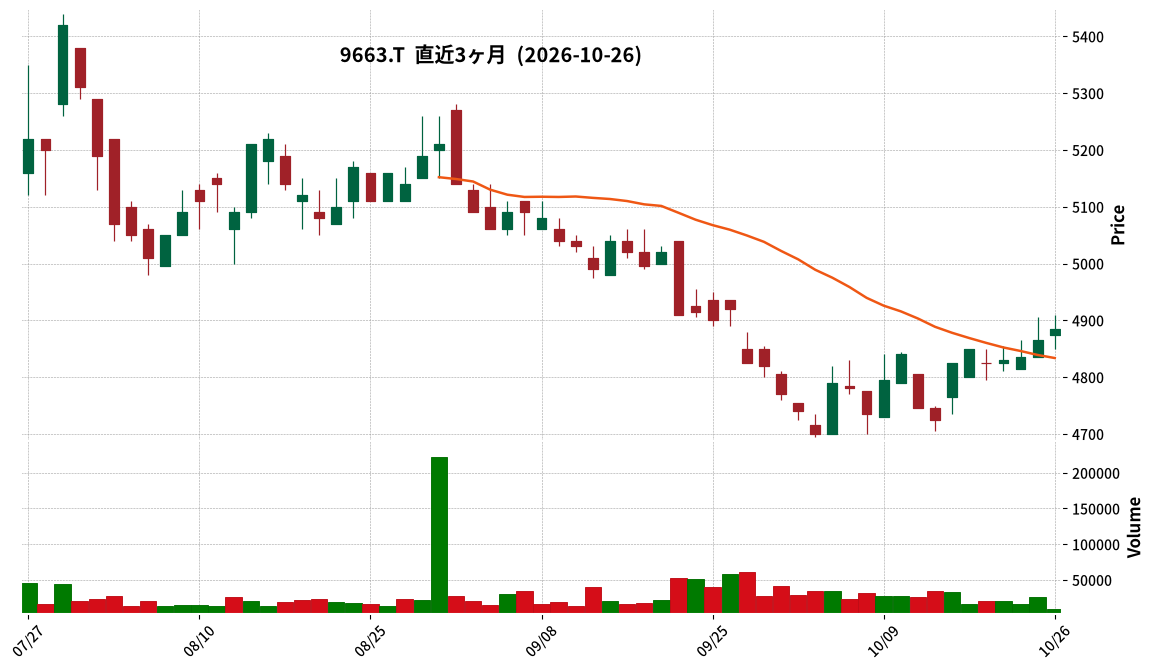
9663|ナガワ
4885.0
▲ +0.41%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Nagawa Co., Ltd. announced its non-consolidated financial results for the second quarter (interim period) of the fiscal year ending March 2027.
- For the interim period, net sales were JPY 17,445 million (up 6.3% year-on-year), operating income was JPY 2,022 million (up 10.5%), ordinary income was JPY 2,483 million (up 11.3%), and interim net income was JPY 1,626 million (up 37.5%).
- By segment, the Unit House business reported sales of JPY 14,481 million (up 5.5%), and the Modular/System Building business reported sales of JPY 2,558 million (up 14.1%). Conversely, the Construction Machinery Rental business saw sales of JPY 405 million (down 8.0%).
- The annual dividend forecast for the fiscal year ending March 2027 has been revised upwards from JPY 60 to JPY 80 per share.
- The full-year forecast remains unchanged from the most recent announcement: net sales of JPY 38,000 million (up 7.4%), operating income of JPY 4,500 million (up 2.7%), ordinary income of JPY 5,100 million (up 1.9%), and net income of JPY 3,300 million (down 25.6%).
🤖 AI Perspective
Nagawa’s interim results demonstrate robust performance, with significant increases across net sales and all profit stages compared to the prior interim period. The substantial rise in interim net income particularly highlights the company’s strong operational momentum. While the Construction Machinery Rental segment experienced a decline, growth in the Unit House and Modular/System Building segments appears to be driving overall positive results. The upward revision of the dividend forecast, despite a projected decrease in full-year net income, may signal a commitment to shareholder returns.
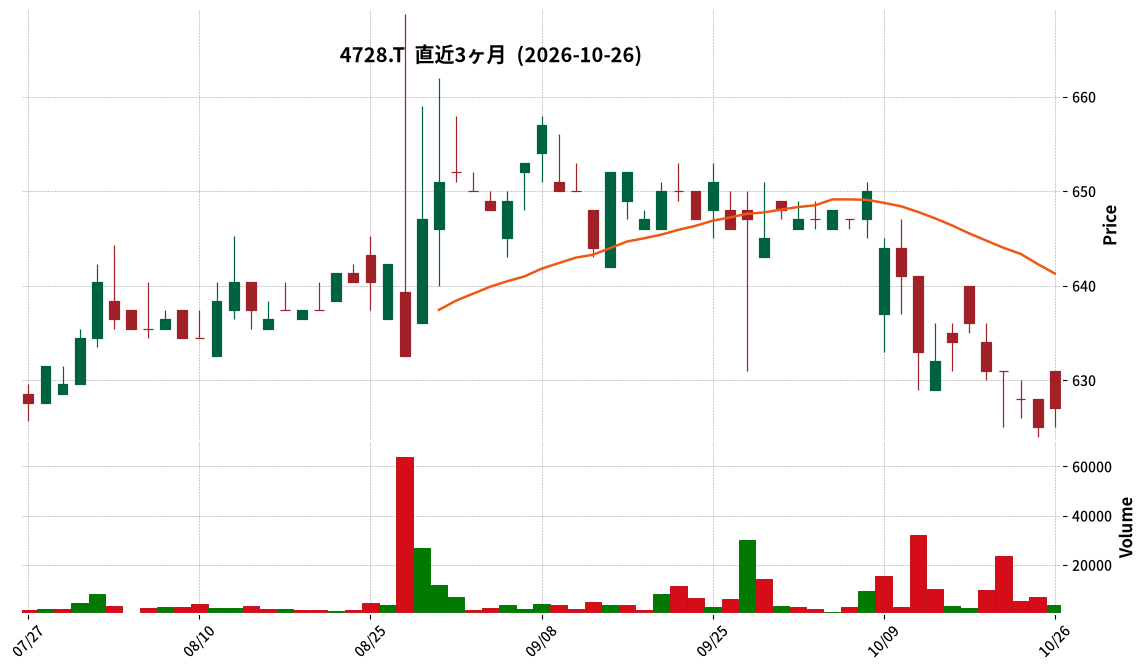
4728|トーセ
627.0
▲ +0.32%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Operating profit for the fiscal year ended August 2026 significantly decreased year-on-year, primarily due to a reduction in revenue share and the temporary suspension of a large-scale console game development project for an overseas client in February 2026.
- There is currently no expectation for the suspended overseas project to resume, and it is not factored into the FY2027 earnings forecast. Development resources have largely been reallocated.
- Three newly awarded projects (E-G) are each projected to generate cumulative sales of over JPY 500 million by completion, with development periods estimated between over 2 years and 4 years.
- The company states it is shifting its development focus to the console and PC software market, such as Nintendo Switch 2, in response to intense competition in the smartphone game market.
- For the fiscal year ending August 2027, despite an anticipated decrease in net sales, operating profit is projected to increase, driven by improved gross profit margins from the resolution of idle development resources and a reduction in external orders.
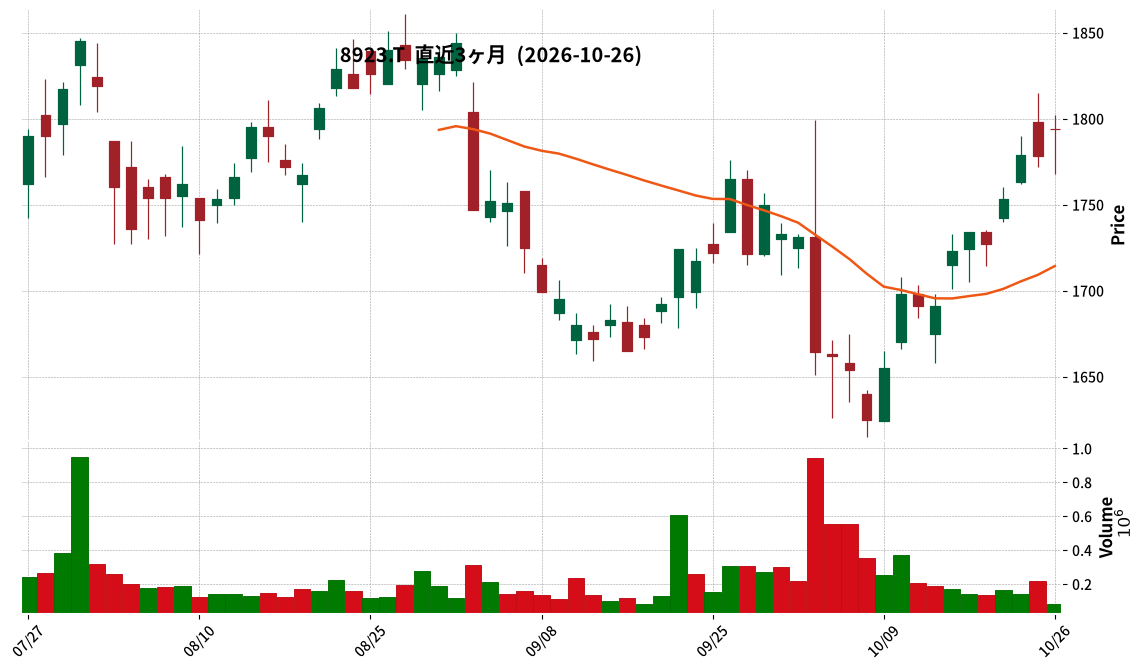
8923|トーセイ
1794.0
▲ +0.90%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Tosei Corporation announced a partial change to its shareholder benefit program, resolved at the Board of Directors meeting on October 26, 2026.
- The gift for shareholders based on continuous holding period will change from “Original QUO Card” to “Original VISA Gift Card.”
- The discount voucher, previously “Hotel Accommodation Discount Voucher,” will be modified to a “Facility Usage Discount Voucher,” which can also be used at some eligible facilities within Tosei Group hotels, such as “restaurants” and “bath facilities.”
- There are no changes to the minimum shareholding requirement (2 units or 200 shares or more), the record date (November 30), the criteria for continuous holding period, or the benefit amount.
- These changes will be applied starting from the shareholder benefit program based on the record date of November 30, 2026.
🤖 AI Perspective
The announced changes to Tosei’s shareholder benefit program aim to enhance shareholder convenience and deepen understanding of the company’s business. The shift from QUO cards to more versatile VISA gift cards and the expansion of the discount voucher’s utility from just accommodation to also include restaurant and bath services at group facilities, could make the benefits more appealing to a broader range of shareholders. Maintaining the existing tiers for continuous holding periods suggests an ongoing focus on encouraging long-term share ownership.
6923|スタンレー電
3540.0
▼ -2.21%
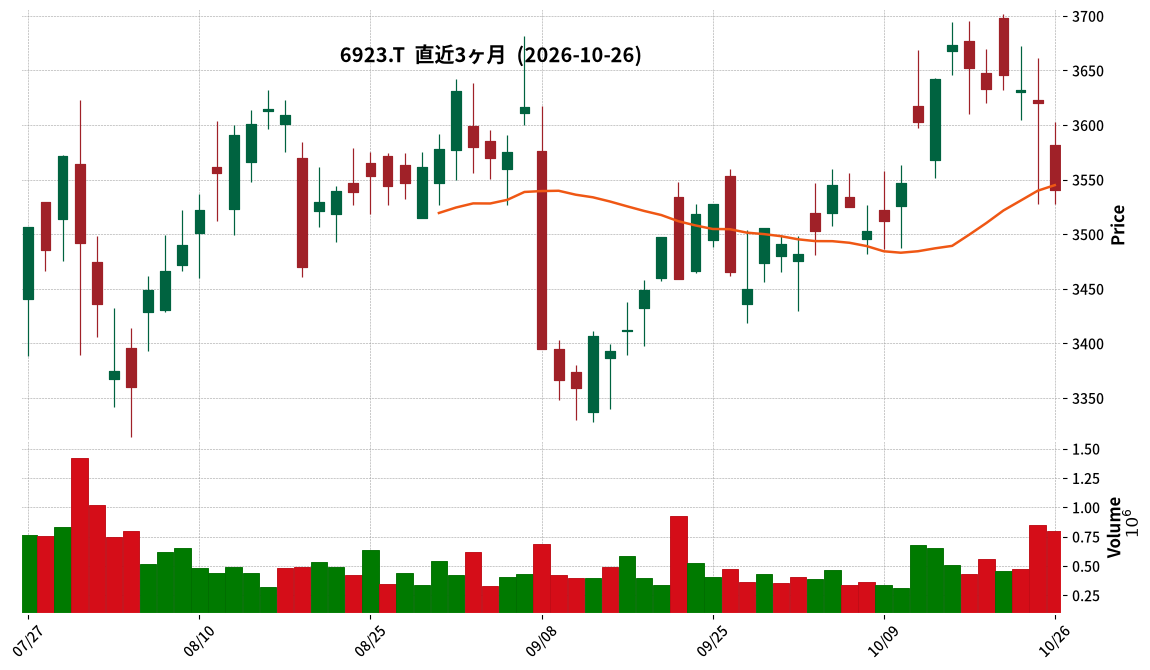
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Stanley Electric Co., Ltd. announced its consolidated financial results for the second quarter of the fiscal year ending March 2027.
- Net sales for the interim period amounted to ¥222,735 million, representing a 10.4% increase compared to the same period of the previous year.
- Operating income reached ¥19,232 million, an increase of 19.3% year-on-year.
- Ordinary income was ¥22,377 million, marking a 15.2% increase from the previous year.
- Profit attributable to owners of parent stood at ¥16,673 million, up 10.8% year-on-year.
🤖 AI Perspective
The reported interim results show an increase in net sales and all profit categories compared to the prior year, suggesting a robust business performance. The double-digit growth in net sales, in particular, may be a key metric for investors evaluating future performance. Factors such as exchange rate fluctuations and raw material price trends could continue to be worth monitoring for their potential impact on profitability going forward.
1718|美樹工業
2325.0
▲ +1.35%
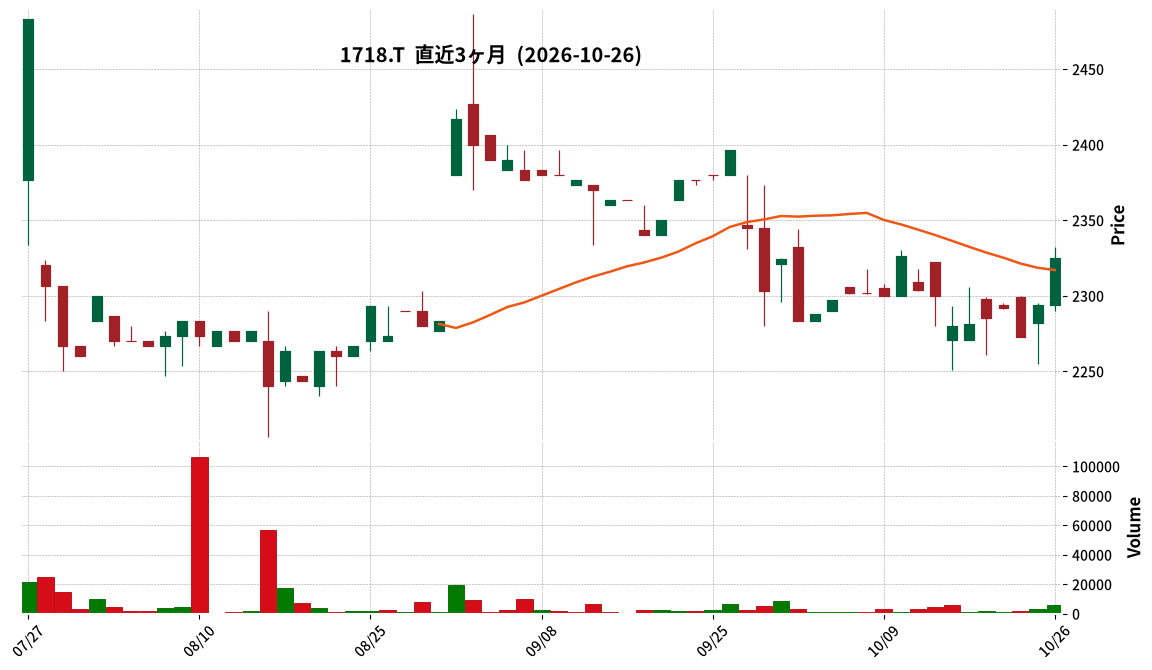
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Miki Kogyo announced its consolidated financial results for the third quarter of the fiscal year ending December 2026 (January 1, 2026 – September 30, 2026).
- Consolidated net sales reached ¥28,842 million, an increase of 5.4% year-on-year.
- Consolidated operating profit was ¥1,458 million (down 29.6% year-on-year), ordinary profit was ¥1,421 million (down 30.4% year-on-year), and profit attributable to owners of parent was ¥925 million (down 26.8% year-on-year).
- By segment, the construction business reported net sales of ¥19,033 million (up 12.7% year-on-year) and operating profit of ¥1,085 million (down 28.8% year-on-year). The housing business saw net sales of ¥9,631 million (down 6.4% year-on-year) and operating profit of ¥364 million (down 31.6% year-on-year).
- The full-year consolidated earnings forecast for the fiscal year ending December 2026 (January 1, 2026 – December 31, 2026) remains unchanged, projecting net sales of ¥40,000 million, operating profit of ¥1,800 million, ordinary profit of ¥1,800 million, and profit attributable to owners of parent of ¥1,100 million.
🤖 AI Perspective
Miki Kogyo’s Q3 FY2026 results show a divergence between revenue growth and profitability, with significant year-on-year declines in all profit metrics despite increased net sales. This trend may suggest pressure from rising construction material costs and increased personnel expenses due to HR system reforms, as highlighted in the report. However, the company’s decision to maintain its full-year earnings forecast could indicate an expectation of improved performance in the final quarter or that current challenges have already been factored into their projections.
1736|オーテック
2549.0
▲ +0.79%
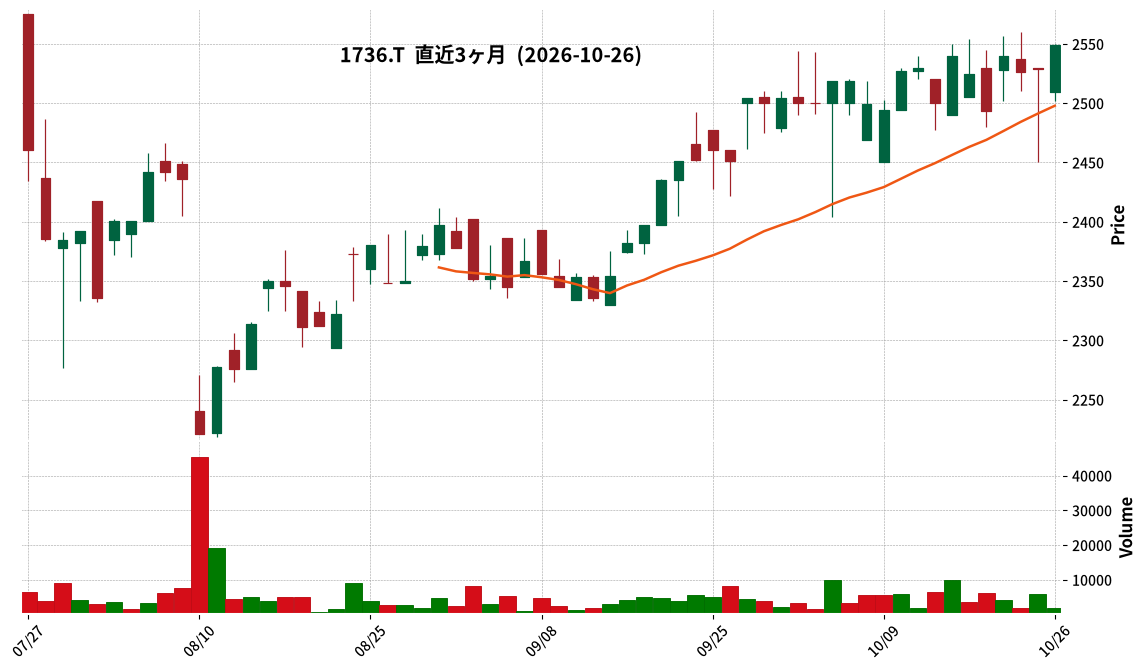
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Autech Co., Ltd. concluded a capital and business alliance agreement with Azbil Corporation on October 26, 2026.
- The business alliance primarily focuses on mutual cooperation for strengthening construction personnel training and utilization, enhancing capabilities for large-scale projects, and jointly developing new products and services.
- Azbil has agreed to acquire 2,387,000 shares of Autech’s common stock (voting rights ratio: 15.25%) through an off-market private transaction from investment limited partnerships managed by Hikari Tsushin’s group companies.
- Following the completion of this stock transfer, Azbil’s total ownership of Autech’s common stock will be 3,137,000 shares (voting rights ratio: 20.04%), leading to Azbil becoming a major shareholder and other related company.
- The execution date for the stock transfer is scheduled for early November 2026, subject to approval from the Japan Fair Trade Commission.
🤖 AI Perspective
Autech and Azbil have maintained a dealership agreement for over 60 years, and this capital and business alliance appears to solidify their existing relationship. Given the industry-wide challenge of securing and training construction personnel, the collaboration to strengthen construction systems and leverage mutual technical expertise could contribute to sustainable business growth. Azbil’s new status as a major shareholder may also suggest a more integrated strategic approach between the two companies.
2211|不二家
2523.0
▼ -0.32%
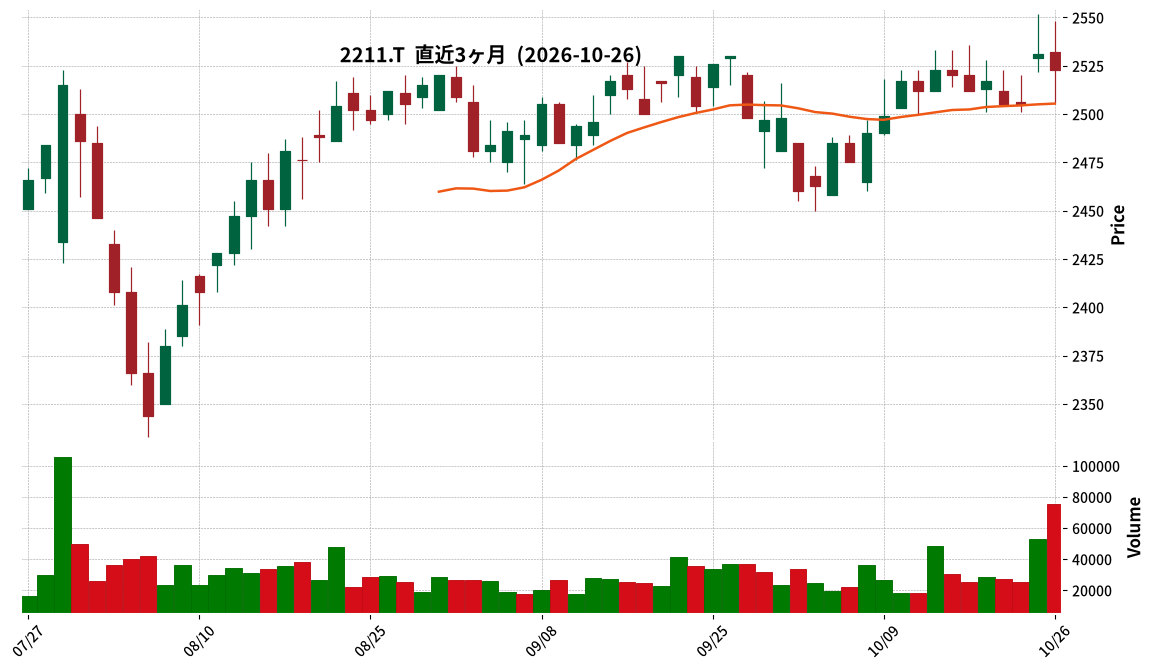
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- For the nine months ended September 30, 2026 (Q3 FY2026), consolidated net sales were ¥87.659 billion, an increase of 4.4% compared to the prior year period.
- Operating income for the same period was a loss of ¥113 million, a significant decline from an operating income of ¥1.069 billion in the previous year.
- Ordinary income decreased by 60.5% to ¥750 million, and profit attributable to owners of parent decreased by 93.7% to ¥56 million.
- The consolidated full-year forecast for FY2026 has been revised: net sales of ¥123.000 billion (+2.9% YoY), operating income of ¥1.600 billion (-43.7% YoY), ordinary income of ¥2.200 billion (-39.1% YoY), and profit attributable to owners of parent of ¥850 million (-58.2% YoY).
- Sales in the Western Confectionery business segment totaled ¥21.230 billion (95.6% of prior year), while the Confectionery business segment reported sales of ¥63.715 billion (107.9% of prior year).
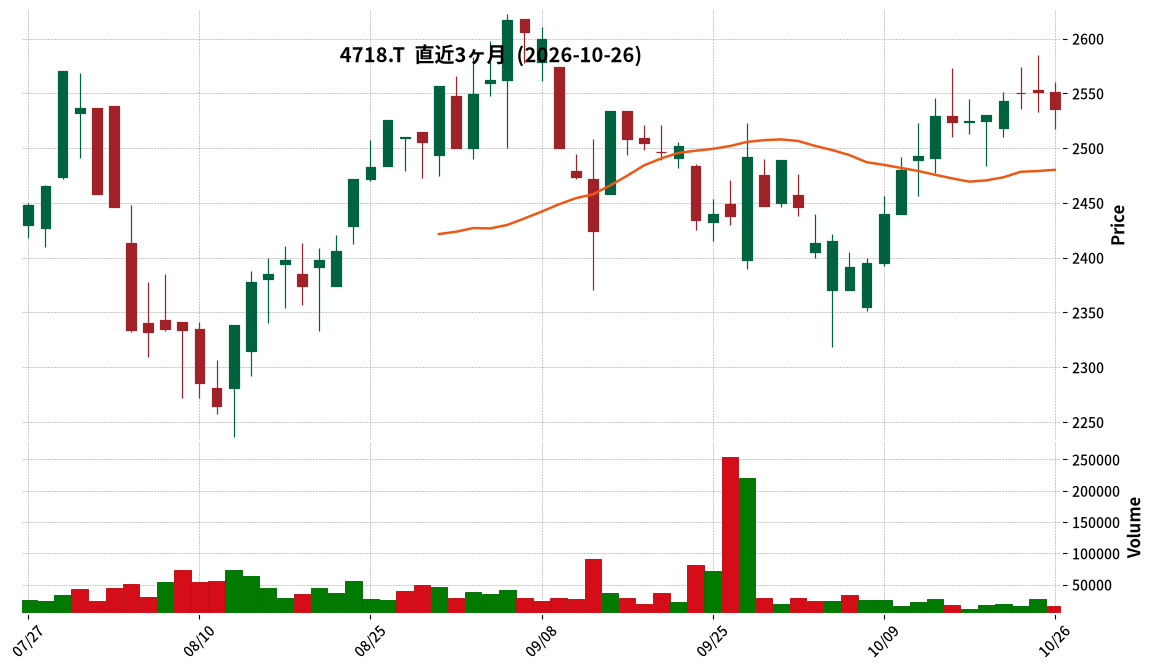
4718|早稲アカ
2536.0
▼ -0.59%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Waseda Academy Co., Ltd. announced revisions to its earnings and dividend forecasts for the fiscal year ending March 2027, effective October 26, 2026.
- The consolidated earnings forecast for the second quarter (cumulative) of FY2027/3 was revised upwards, with net sales expected to be ¥20,066 million (up 1.5% from previous), operating profit ¥2,538 million (up 35.9%), and net income attributable to owners of parent ¥1,570 million (up 38.3%).
- The full-year consolidated earnings forecast for FY2027/3 was also revised upwards, projecting net sales of ¥40,900 million (up 0.9% from previous), operating profit of ¥4,770 million (up 12.5%), and net income attributable to owners of parent of ¥3,080 million (up 11.9%).
- Reasons for the revision include higher-than-expected student enrollment, strong attendance at summer camps and intensive training, leading to increased revenue. Additionally, cost reductions resulted from a review of expense execution and improved operational efficiency.
- The annual dividend forecast was revised, with the year-end dividend increased by ¥10 from the previous forecast of ¥45 to ¥55, making the total annual dividend ¥85 (an increase of ¥30 from the previous fiscal year). This revision aligns with the company’s policy of targeting a dividend payout ratio of 50% or more under its medium-term management plan.
🤖 AI Perspective
The upward revision of earnings forecasts appears to be driven by both robust revenue growth and enhanced cost efficiency. The increase in student numbers and successful summer programs likely contributed to the strong first-half performance, while optimized expense management and operational efficiencies potentially improved profit margins. The increased dividend forecast, supported by favorable earnings, reflects the company’s commitment to its shareholder return policy and may be viewed positively by investors.
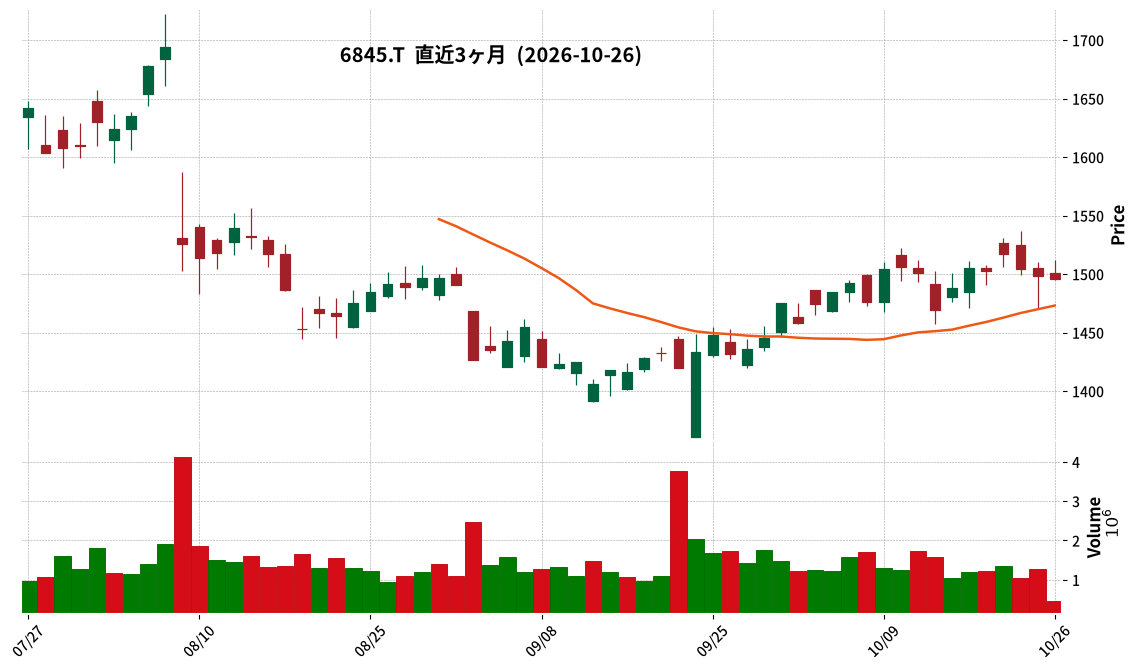
6845|アズビル
1496.0
▼ -0.17%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Azbil Corporation announced on October 26, 2026, the signing of a capital and business alliance agreement with AUTEC Corporation and the decision to acquire additional shares of its common stock.
- Following this acquisition, Azbil’s voting rights ownership in AUTEC will increase to 20.04% (combining the existing 4.79%), making AUTEC an equity-method affiliate of Azbil.
- The additional shares to be acquired total 2,387,000 shares (15.25% voting rights ownership) at an acquisition price of 7,161 million yen (3,000 yen per share).
- The business alliance primarily focuses on mutual cooperation for the development and utilization of construction personnel, strengthening capabilities for complex projects, and joint development of new products and services.
- The share transfer date is scheduled for early November 2026, with the impact on Azbil’s consolidated performance for the fiscal year ending March 2027 stated as minor.
🤖 AI Perspective
This alliance suggests Azbil’s strategic move to strengthen its building automation business by leveraging its long-standing partnership with AUTEC, addressing critical challenges such as securing and developing engineering personnel. Given AUTEC’s consistent financial performance, its conversion into an equity-method affiliate could contribute to Azbil’s overall revenue base in the future. In an industry facing staffing challenges, the expansion of construction capabilities through this collaboration may indicate a long-term strategy for enhancing competitive advantage.
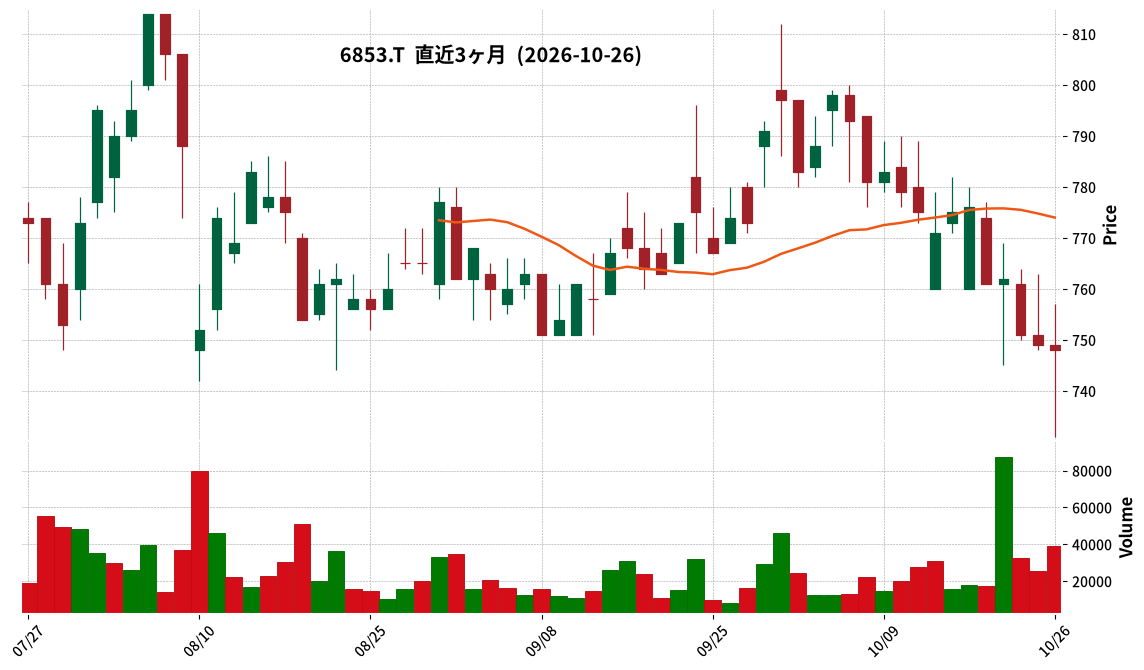
6853|共和電
748.0
▼ -0.13%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Kyowa DENGYO Co., Ltd. resolved to conduct an absorption-type merger with its three wholly-owned subsidiaries, Yamagata Kyowa DENGYO Co., Ltd., Kofu Kyowa DENGYO Co., Ltd., and Kyowa Service Center Co., Ltd., at a board meeting held on October 26, 2026, and signed the absorption-type merger agreement on the same date.
- The effective date of the merger is scheduled for January 1, 2027.
- Kyowa DENGYO will be the surviving company, and the three absorbed companies will be dissolved.
- As this merger qualifies as a simplified merger and a short-form merger under the Companies Act, it will proceed without shareholder approval.
- The merger’s purpose is to strengthen group competitiveness by centralizing production and after-sales service functions, create synergy through closer collaboration across the value chain from procurement to after-sales service, improve management and capital efficiency through optimal allocation of management resources, and enhance governance through organizational integration.
🤖 AI Perspective
This merger appears to be a strategic move by Kyowa DENGYO to streamline its operations by integrating production and after-sales service functions into the parent company. As it involves wholly-owned subsidiaries, no new shares will be issued or merger consideration paid, indicating a minimal impact on consolidated earnings. Investors may view this as a step towards optimizing management resources and strengthening corporate governance within the group.
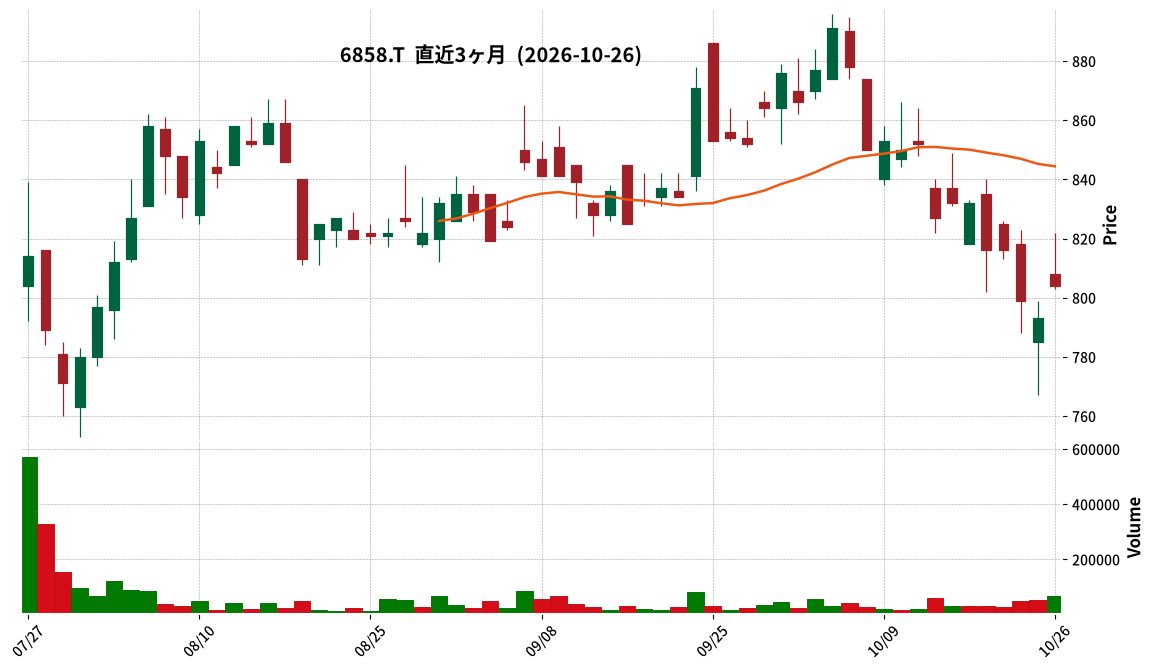
6858|小野測器
804.0
▲ +1.39%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- For the third quarter of the fiscal year ending December 2026 (January 1, 2026 – September 30, 2026), net sales were ¥10,647 million, a 19.2% increase year-over-year.
- Operating income for the period was ¥226 million, a turnaround from an operating loss of ¥227 million in the same period of the previous year.
- Ordinary income reached ¥279 million (vs. a loss of ¥175 million YoY), and net income attributable to owners of the parent was ¥150 million (vs. a loss of ¥246 million YoY).
- Basic earnings per share for the quarter were ¥14.49.
- The full-year consolidated earnings forecast remains unchanged: net sales of ¥15,000 million, operating income of ¥1,100 million, ordinary income of ¥1,200 million, and net income attributable to owners of the parent of ¥800 million.
- The annual dividend forecast is also unchanged at ¥30.00 per share.
🤖 AI Perspective
Ono Sokki’s Q3 FY22 results highlight a significant turnaround, with a return to profitability in operating income and strong sales growth compared to the prior year. This positive shift may suggest effective strategies in capturing customer demand for specialized testing equipment and services. The company’s decision to maintain its full-year earnings and dividend forecasts could indicate confidence in achieving its initial targets for the fiscal year.
Disclaimer: This article is for informational purposes only and does not constitute investment advice.
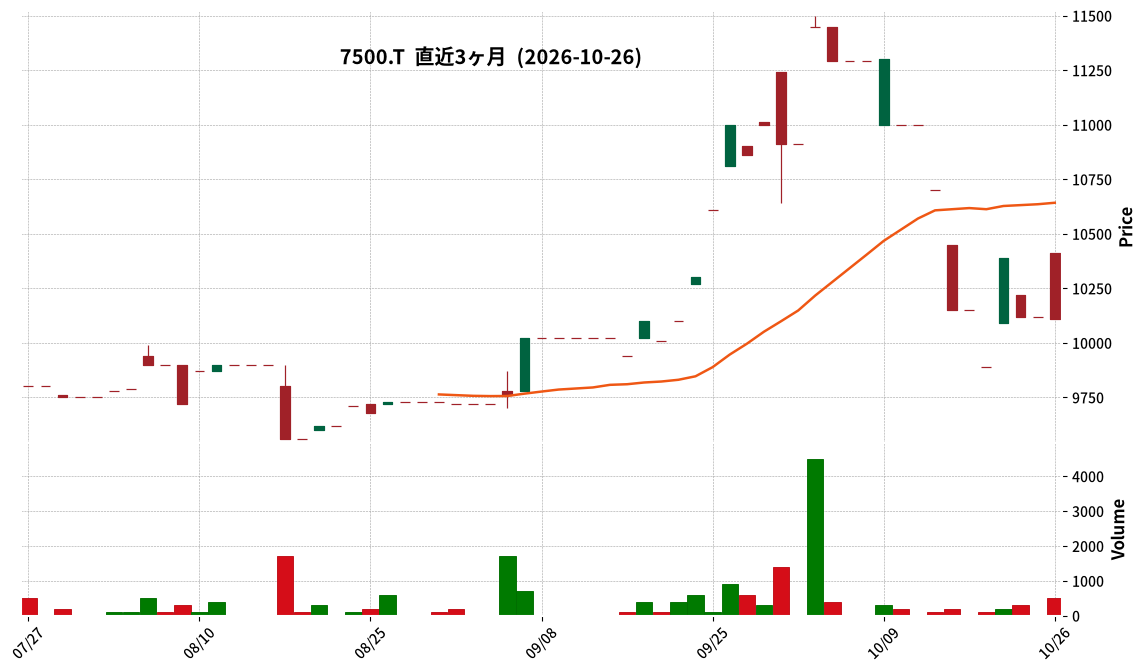
7500|西川計測
10110.0
▼ -0.10%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Nishikawa Keisoku’s Board of Directors resolved on a stock split and partial amendment to its Articles of Incorporation on October 26, 2026.
- The stock split will be conducted at a ratio of 10 shares for every 1 ordinary share, with December 31, 2026, as the record date and January 1, 2027, as the effective date.
- This will increase the total number of outstanding shares from 3,432,475 to 34,324,750, and the total number of authorized shares will change from 10 million to 100 million.
- The amendment to the Articles of Incorporation revises the total number of authorized shares in conjunction with the stock split, also effective January 1, 2027.
- The annual upper limit for the total number of shares granted under the Restricted Stock Compensation Plan will be adjusted from up to 10,000 shares to up to 100,000 shares, effective January 1, 2027.
🤖 AI Perspective
The stock split is intended to reduce the per-share investment unit, potentially making Nishikawa Keisoku’s shares more accessible to a broader range of investors. This move could enhance stock liquidity and expand the company’s investor base. The amendments to the Articles of Incorporation and adjustments to the Restricted Stock Compensation Plan appear to be consequential and administrative actions aligning with the stock split.
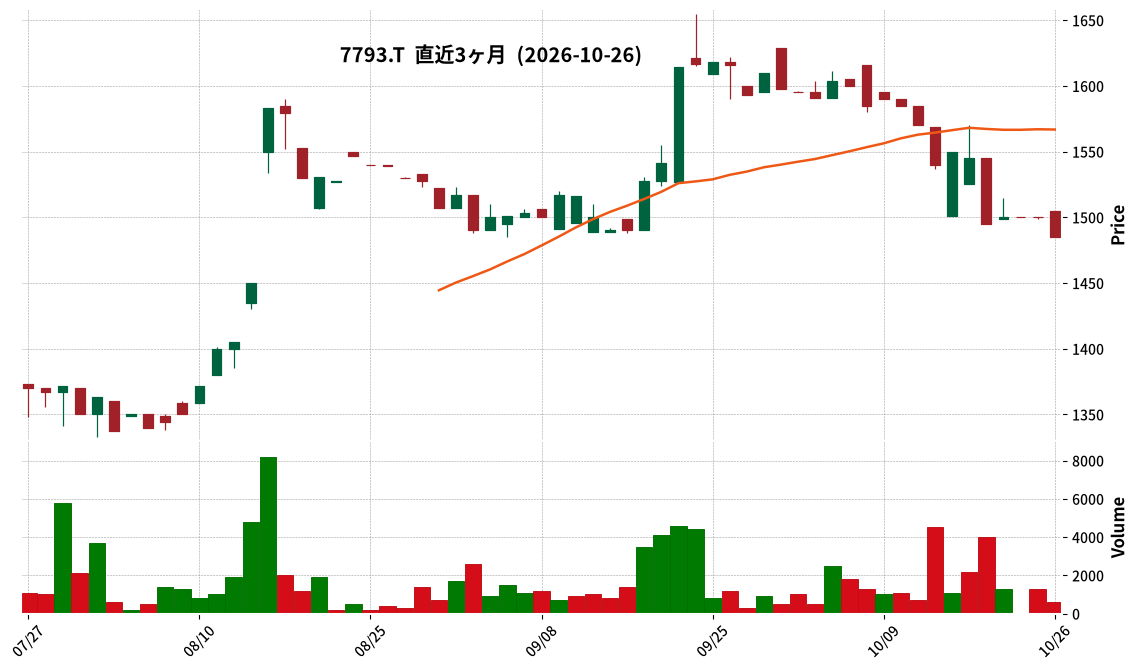
7793|G-イメージマジック
1485.0
▼ -1.00%
📎 Source:G-イメージマジック Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- G-imagemagic Inc. announced the completion of its full acquisition of Hasegawa Bigaku Co., Ltd. (hereinafter referred to as “Hasegawa Bigaku”).
- This was initially disclosed in the “Notice Regarding Share Acquisition and Simplified Share Exchange to Make Hasegawa Bigaku Co., Ltd. a Wholly Owned Subsidiary” dated September 18, 2026.
- As of today, Hasegawa Bigaku has become a wholly owned subsidiary of G-imagemagic Inc. through the completion of the share acquisition and the effective date of the simplified share exchange.
- Hasegawa Bigaku’s business primarily involves silk screen printing, and its capital is JPY 30 million.
- G-imagemagic Inc. now holds a 100.0% stake in Hasegawa Bigaku.
- The impact of this acquisition on the financial results for the December 2026 fiscal year is expected to be minor, with October 1, 2026, considered the deemed acquisition date, and only the balance sheet planned for consolidation in the current fourth quarter.
🤖 AI Perspective
This announcement confirms G-imagemagic’s successful acquisition of Hasegawa Bigaku, a company engaged in silk screen printing. While the immediate financial impact on the current fiscal year is stated as minor, this strategic move could potentially strengthen G-imagemagic’s position in related business areas. Investors may want to monitor future disclosures regarding business integration strategies and the long-term synergistic effects of this acquisition to assess its full implications.
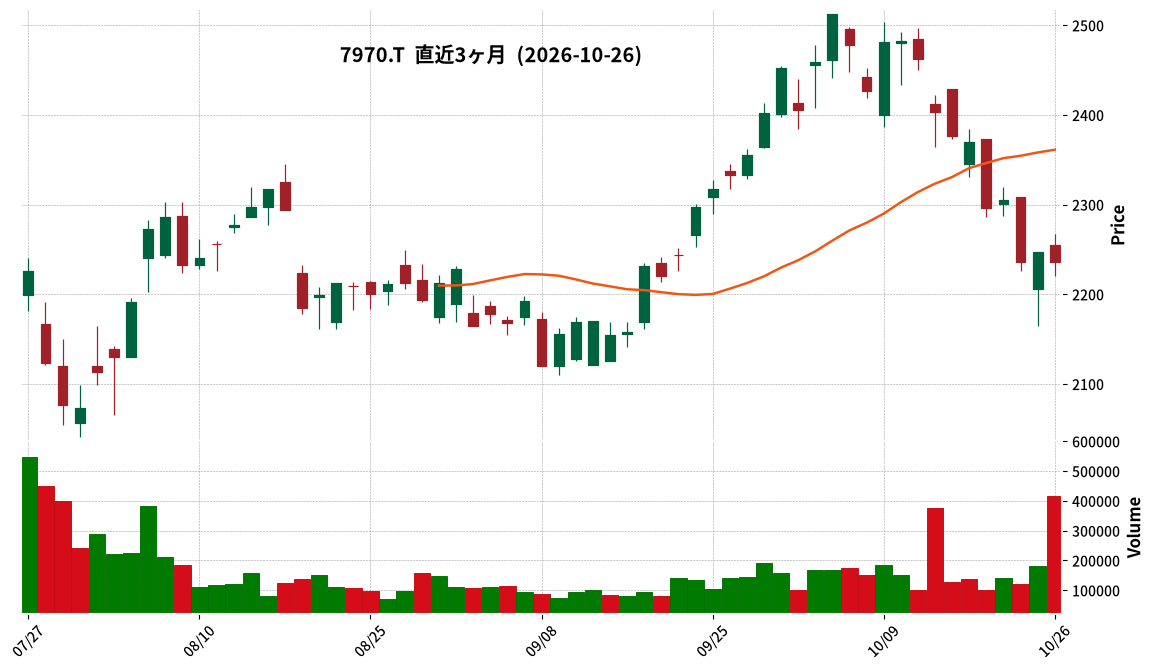
7970|信越ポリマ
2236.0
▼ -0.49%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Shin-Etsu Polymer announced on October 26, 2026, a revision to its consolidated financial forecast for the full fiscal year ending March 2027.
- The revised full-year consolidated financial forecast for FY2027 projects net sales of ¥127,000 million (up 5.8% from previous forecast), operating profit of ¥18,200 million (up 13.8%), ordinary profit of ¥18,000 million (up 12.5%), net profit attributable to owners of parent of ¥11,800 million (up 12.4%), and earnings per share of ¥146.82.
- The upward revision to the performance forecast is attributed to the continued strong performance expected from semiconductor-related containers and wrapping films.
- The company decided to pay an interim dividend of ¥36 per share and revised its year-end dividend forecast to ¥36 per share. This results in an increased annual dividend from the previously projected ¥66 to ¥72.
- The record date for the interim dividend is September 30, 2026, and the effective date is November 26, 2026.
🤖 AI Perspective
The upward revision of the financial forecast suggests strong performance in key product areas, particularly within the semiconductor-related market, which appears to be a significant driver for the company’s results. The announced dividend increase could be interpreted as a positive signal regarding the company’s commitment to shareholder returns, aligning with its stated policy of stable dividends responsive to performance. Investors may find it worthwhile to monitor the continued growth trends in its core business segments.
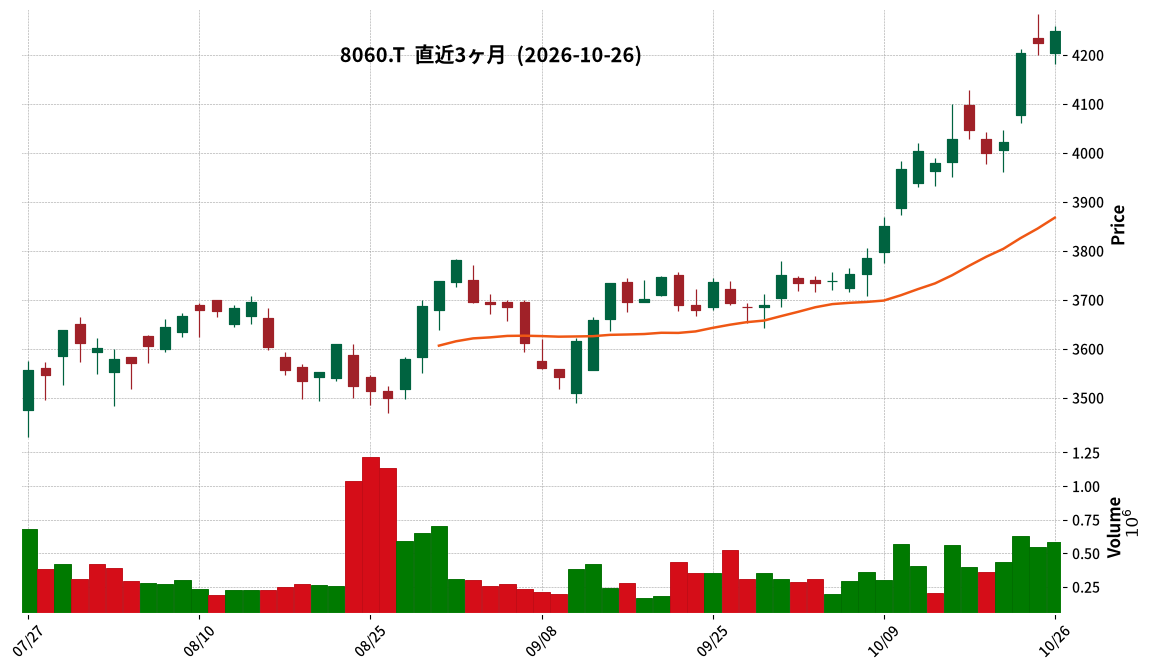
8060|キヤノンMJ
4249.0
▲ +0.62%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Canon Marketing Japan Inc. announced its consolidated financial results for the third quarter of the fiscal year ending December 2026 (January 1, 2026, to September 30, 2026).
- Net sales reached ¥507.67 billion, a 3.2% increase year-on-year. Operating profit was ¥46.91 billion, up 22.8% year-on-year.
- Ordinary profit stood at ¥47.69 billion (up 20.7% YoY), and net profit attributable to owners of parent was ¥32.59 billion (up 19.5% YoY).
- In the Enterprise segment, net sales were ¥205.32 billion (up 4.1% YoY), with segment profit at ¥16.88 billion (up 19.8% YoY).
- The full-year consolidated earnings forecast for FY2026 remains unchanged, projecting net sales of ¥685.00 billion (up 0.8% YoY), operating profit of ¥63.00 billion (up 8.3% YoY), and net profit attributable to owners of parent of ¥44.00 billion (up 6.1% YoY).
🤖 AI Perspective
Canon MJ’s Q3 results show growth across sales and all profit metrics, with operating, ordinary, and net profits achieving double-digit year-on-year increases. This performance appears to be primarily driven by the robust growth in its IT solutions business, suggesting that a higher proportion of high-value-added products and services contributed to improved profit margins. While the full-year forecast remains consistent, the company’s progress through the third quarter and its outlook for the remainder of the fiscal year may be key areas of focus for investors.
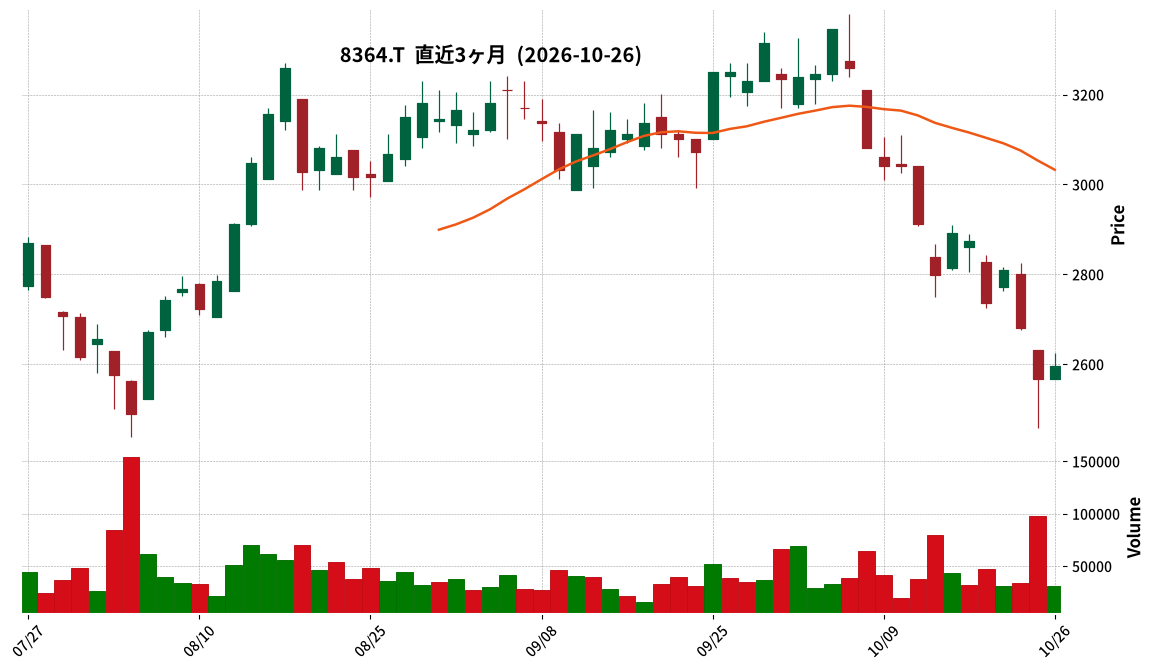
8364|清水銀
2595.0
▲ +1.09%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Shimizu Bank announced on October 26, 2026, revisions to its earnings forecasts and dividend forecasts for the fiscal year ending March 2027.
- For the second quarter (interim) of FY2027, the consolidated net profit attributable to owners of the parent is revised from the previously announced ¥1,700 million to ¥2,200 million, representing a 29.4% increase.
- For the full fiscal year ending March 2027, the consolidated net profit attributable to owners of the parent is revised from the previously announced ¥2,500 million to ¥2,900 million, an increase of 16.0%.
- The dividend forecast for FY2027 has been revised, with the interim dividend increasing from ¥30.00 to ¥35.00 per share, and the year-end dividend also rising from ¥30.00 to ¥35.00, resulting in a total annual dividend of ¥70.00 per share (previously ¥60.00).
- The reasons for these revisions are attributed to funding income, including loan interest and securities interest and dividends, exceeding initial expectations due to rising interest rates.
🤖 AI Perspective
The upward revision of earnings forecasts primarily reflects the increase in funding income driven by rising interest rates, suggesting that interest rate movements are a key factor in the bank’s profitability. The increased dividend payout may indicate a positive stance on shareholder returns. Investors might continue to monitor interest rate trends for their potential impact on the bank’s future performance.
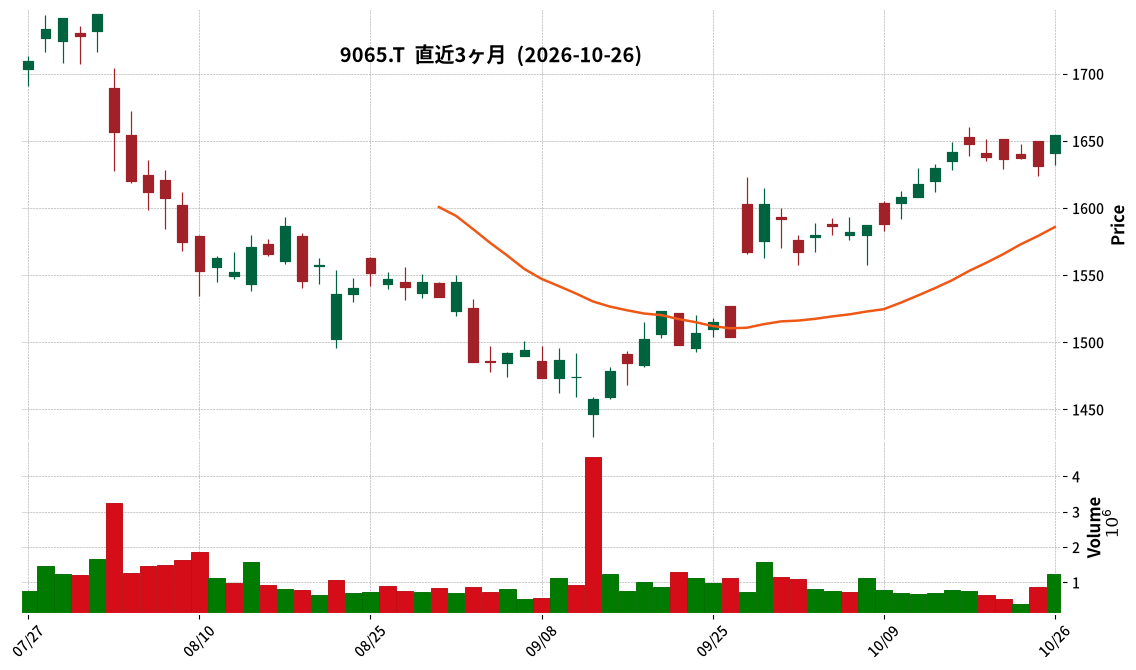
9065|山九
1654.5
▲ +1.41%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Sankyu Inc. has announced a correction to a part of its “Consolidated Financial Results for the Fiscal Year Ended March 2026 (Japanese GAAP).”
- This correction addresses errors identified in the financial results summary initially disclosed on May 14, 2026, which was partially revised on May 26, 2026.
- The reason for the correction is that certain numerical figures were incorrectly displayed after the initial announcement.
- The specific section being corrected is located on page 3 of the summary, under “(Reference) Overview of Non-consolidated Performance,” specifically “2. Non-consolidated Performance Forecast for the Fiscal Year Ending March 2027 (April 1, 2026 – March 31, 2027).”
- The representative director and CEO is Kimiharu Nakamura, and the contact person for inquiries is Moritsune Tsuga, General Manager of Accounting Department.
🤖 AI Perspective
Corrections to financial statements by listed companies are critical for investors as they reflect on the accuracy of corporate disclosures. This particular correction stems from numerical errors in previously disclosed information, which might lead to scrutiny of the company’s data verification processes post-announcement. The impact of this revision to the non-consolidated performance forecast on future company valuation will be a point for investors to continuously monitor.
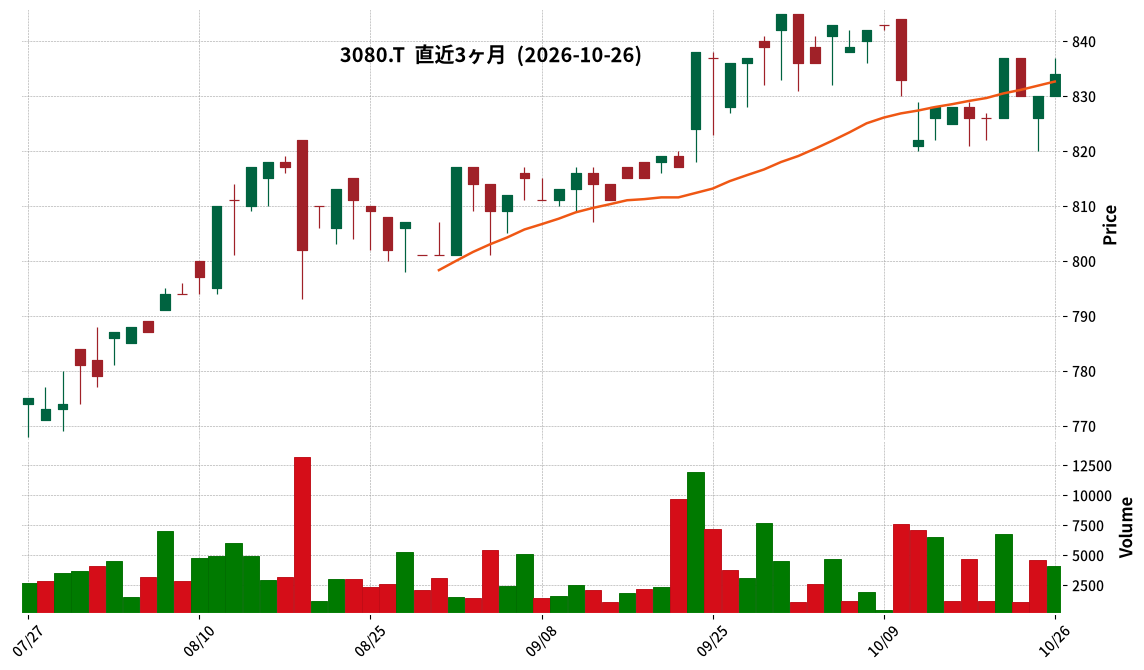
3080|ジェーソン
834.0
▲ +0.48%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- For the second quarter of the fiscal year ending February 2027, Jason Co., Ltd. reported a slight revenue decrease of 1% year-on-year and a significant operating profit decline of 40.3%.
- Revenue was positively impacted by strong sales of private brand (PB) products “Shojinzawa Natural Water” and “Sparkling Strong Carbonated Water,” along with increased production at subsidiary Shojinzawa Beverage. However, adverse weather conditions, including low temperatures and heavy rain in the Kanto region, negatively affected customer traffic.
- The substantial decline in operating profit was attributed to rising procurement costs due to inflation, decreased gross profit from lower revenue, M&A related expenses, and increased costs at subsidiary Sunmall (personnel expenses, land and building rent).
- The company announced that it secured the upper-half operating profit forecast of 170 million JPY.
- To achieve the full-year earnings forecast, the company plans to progressively implement structural reforms at Sunmall for profit improvement, strengthen original (PB) products, and enhance flexibility and diversification of product offerings in the second half of the fiscal year.
🤖 AI Perspective
Jason Co., Ltd.’s Q2 FY2027 results indicate that while PB products provided sales support, adverse weather, M&A expenses, and increased costs at Sunmall significantly impacted operating profit. The achievement of the upper-half operating profit forecast is a notable point, suggesting some resilience despite challenges. The company’s focus on structural reforms at Sunmall and strengthening PB products in the second half will be critical for achieving its full-year guidance. Investors may also monitor the effectiveness of its “integration of management and IT” strategy in maintaining low-cost operations amidst ongoing inflation.
Disclaimer: This article is for informational purposes only and does not constitute investment advice.
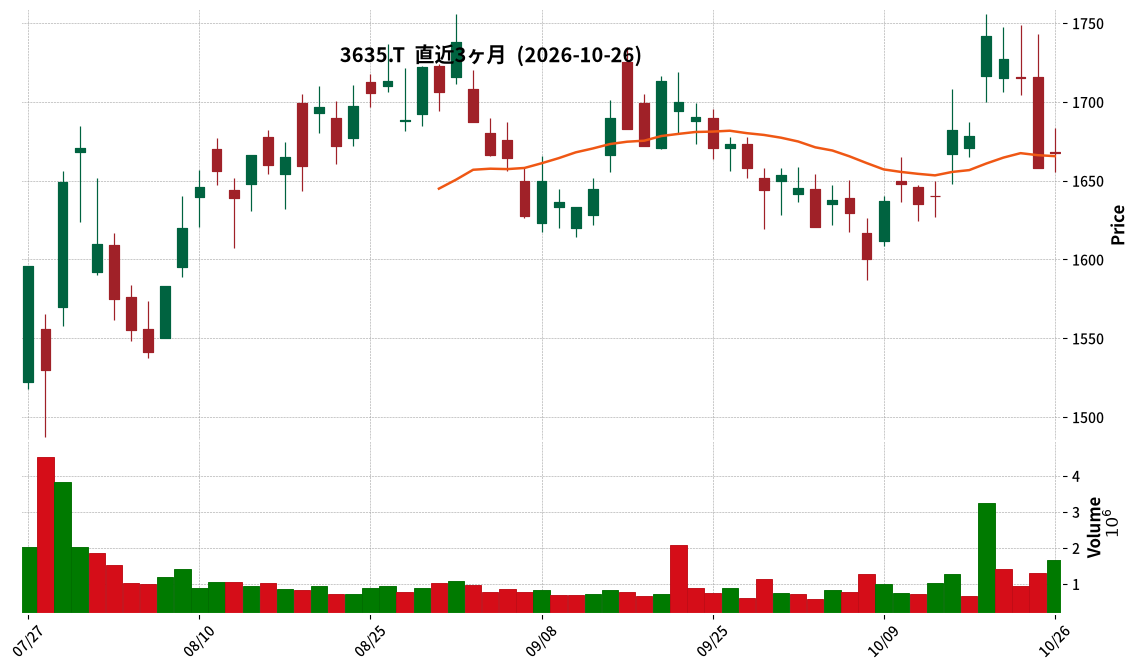
3635|コーエーテクモ
1667.5
▲ +0.57%
📎 Source:コーエーテクモ Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- For the second quarter of the fiscal year ending March 2027 (interim period), consolidated net sales reached 37,327 million yen (up 19.4% year-on-year), and operating income was 11,743 million yen (up 47.4% year-on-year).
- Recurring profit amounted to 25,523 million yen (up 43.4% year-on-year), and net income attributable to owners of parent was 18,596 million yen (up 38.1% year-on-year). Both recurring profit and net income marked record highs for an interim period.
- The full-year consolidated earnings forecast has been revised to: net sales 91,000 million yen (up 2.9% year-on-year), operating income 34,000 million yen (down 8.5% year-on-year), recurring profit 51,000 million yen (down 10.5% year-on-year), and net income attributable to owners of parent 37,000 million yen (down 13.6% year-on-year).
- The annual dividend forecast is 56.00 yen per share for the fiscal year-end, totaling 56.00 yen (a revision from the most recently announced forecast).
- The Entertainment segment’s sales increase was driven by the release of three packaged game titles, strong sales of major titles from the previous year, and back catalog titles. “Pocoa Pokemon” won the “Grand Award” at the Japan Game Awards 2026 and surpassed 5 million units in global sales.
🤖 AI Perspective
The interim financial results show significant increases across net sales and all profit metrics, with recurring profit and net income reaching new record highs for an interim period. This performance appears to be supported by new packaged game releases, robust sales of existing titles, and better-than-expected financial market gains. The upward revision of the full-year earnings forecast suggests continued positive momentum, and the performance of upcoming titles and ongoing contribution from existing IP will be worth monitoring.
💡 Start investing with IR insights


※ 本ページには広告が含まれます(PR)
Disclaimer: This article is for informational purposes only and does not constitute investment advice. All investment decisions are at your own risk.
コメント