📌 Today’s Highlights
Today we cover 52 IR announcements. Notable among them: P-東京みらい不動産 (647A), アイビスHD (9334), ツツミ (7937). Use the table of contents below to navigate to each company.
- 647A|P-東京みらい不動産
- 9334|アイビスHD
- 2884|ヨシムラ・F・HD
- 4053|サンアスタリスク
- 7937|ツツミ
- 6432|竹内製作所
- 7512|イオン北海
- 139A|P-東日本地所
- 482A|F-セールスAC
- 6142|富士精工
- 6217|津田駒工
- 7520|エコス
- 7811|中本パックス
- 8095|アステナHD
- 1419|タマホーム
- 1436|G-グリーンエナジー
- 189A|G-D&Mカンパニー
- 228A|G-オプロ
- 2379|ディップ
- 2791|大黒天
- 3086|Jフロント
- 3236|プロパスト
- 3267|フィル・カンパニー
- 3297|東武住販
- 3349|コスモス薬品
- 4178|G-Sイノベーション
- 4199|G-ワンプラ
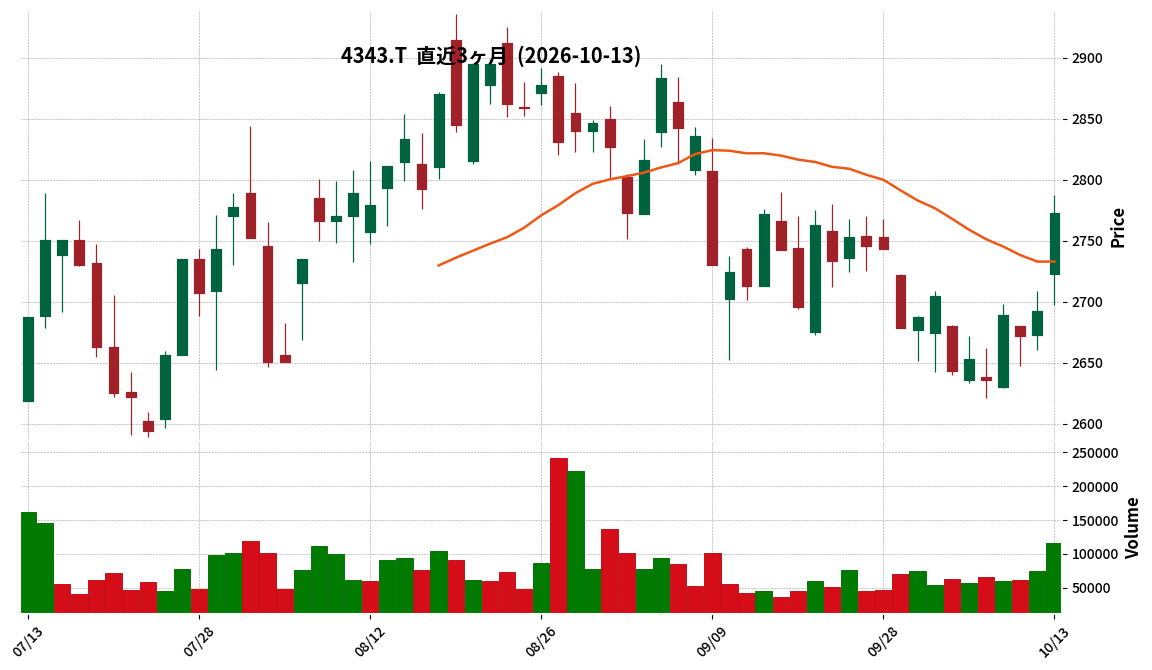
- 4343|イオンファン
- 6076|アメイズ
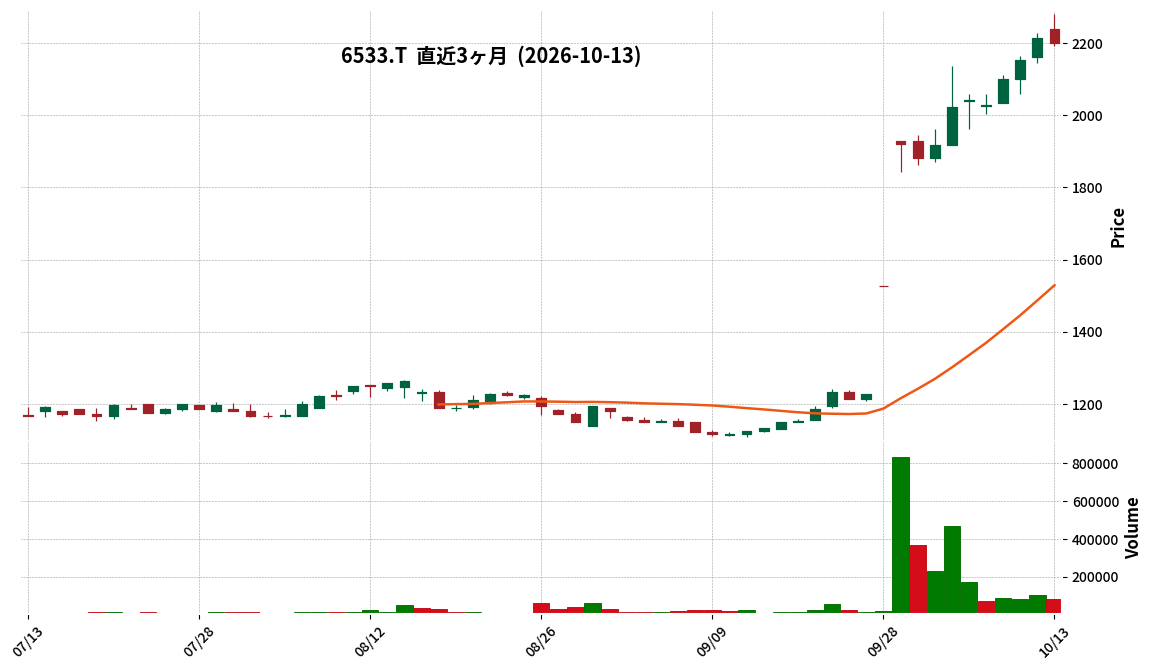
- 6533|オーケストラHD
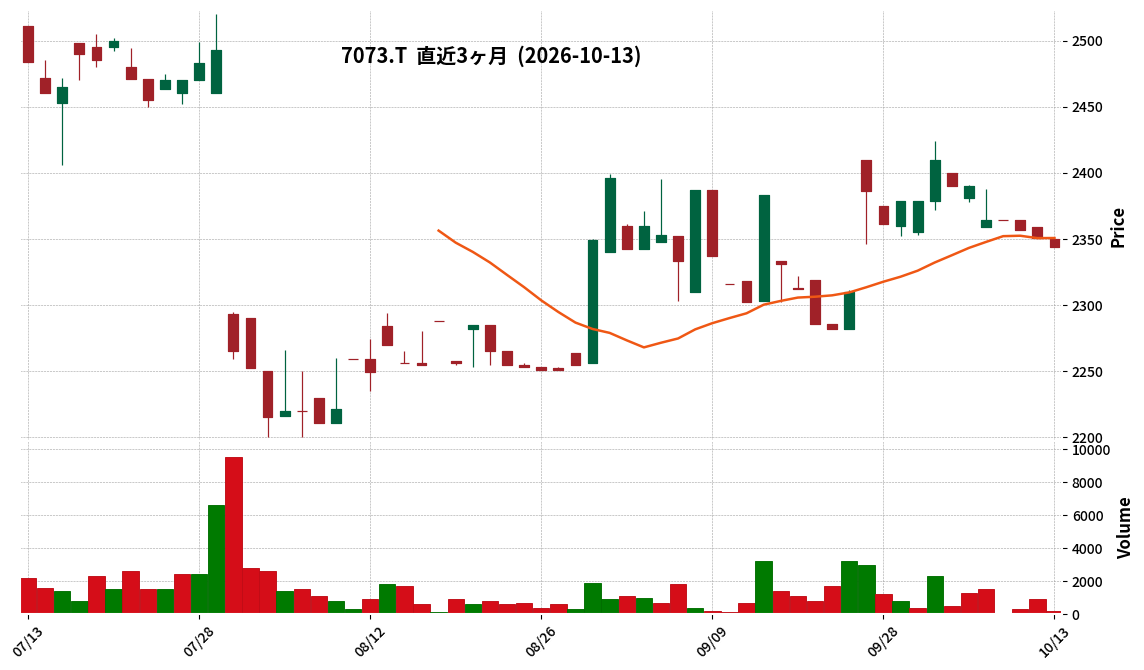
- 7073|G-ジェイック
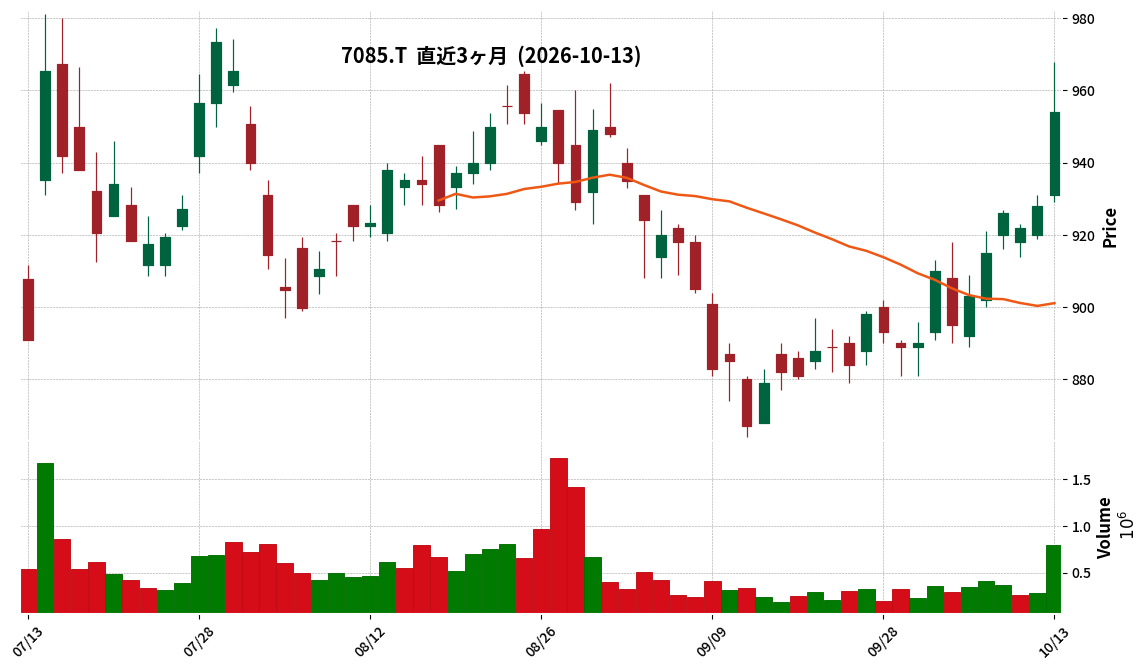
- 7085|カーブスHD
- 7219|HKS
- 7516|コーナン商
- 8181|東天紅
- 8267|イオン
- 8273|イズミ
- 8904|AVANTIA
- 2769|ヴィレッジV
- 2338|クオンタムS
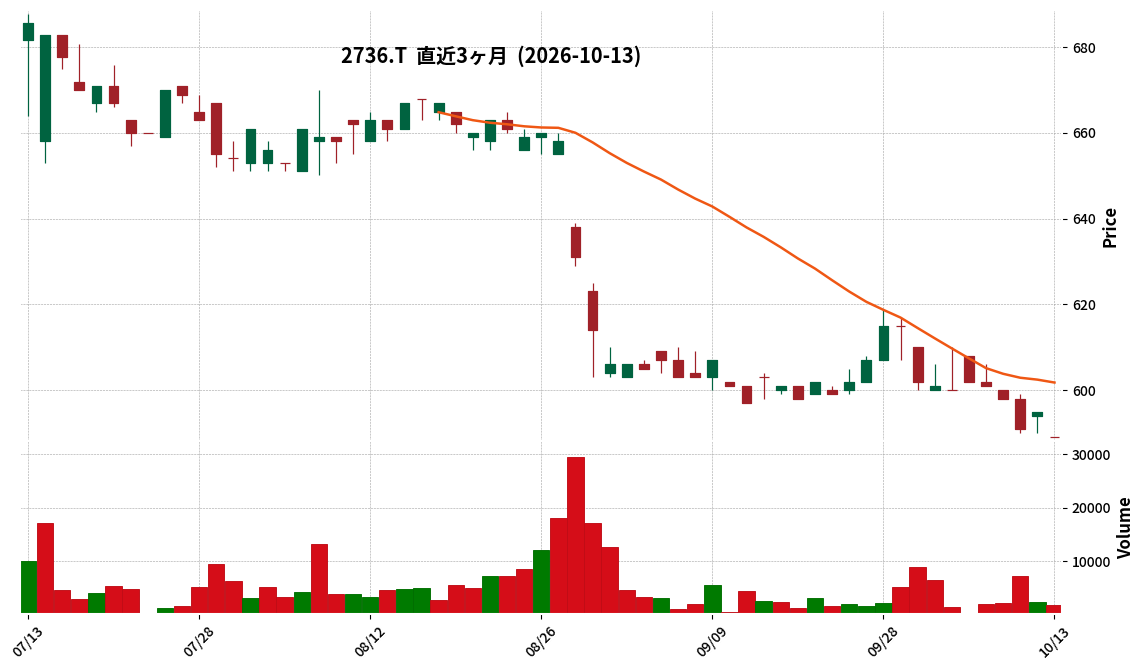
- 2736|フェスタリアHD
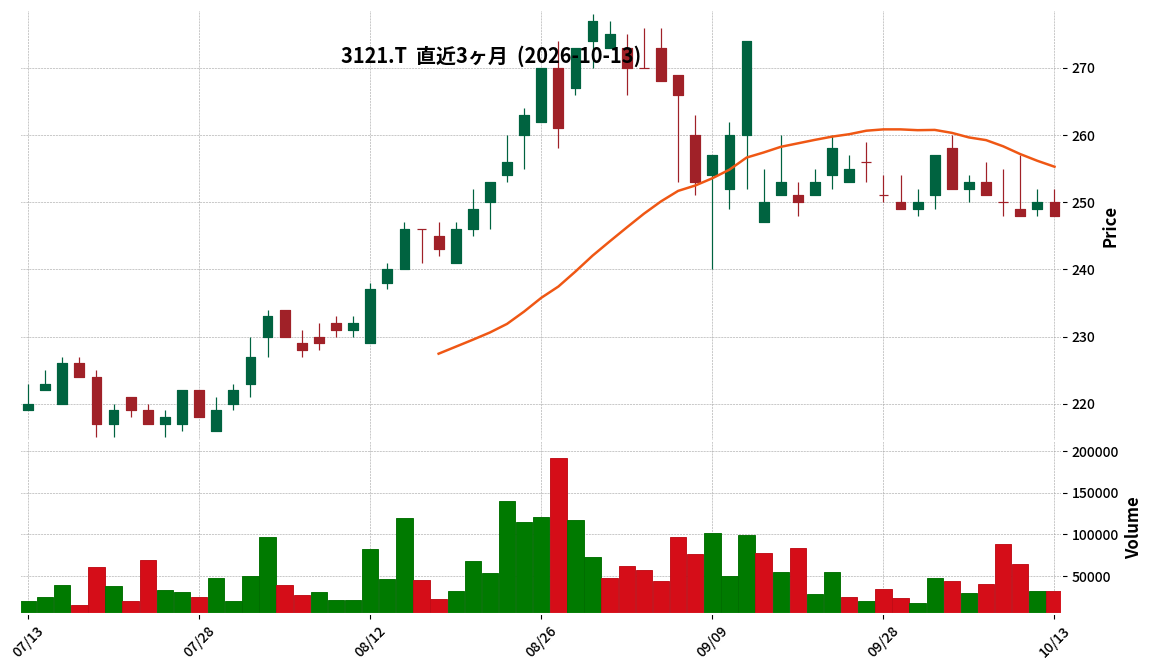
- 3121|マーチャント
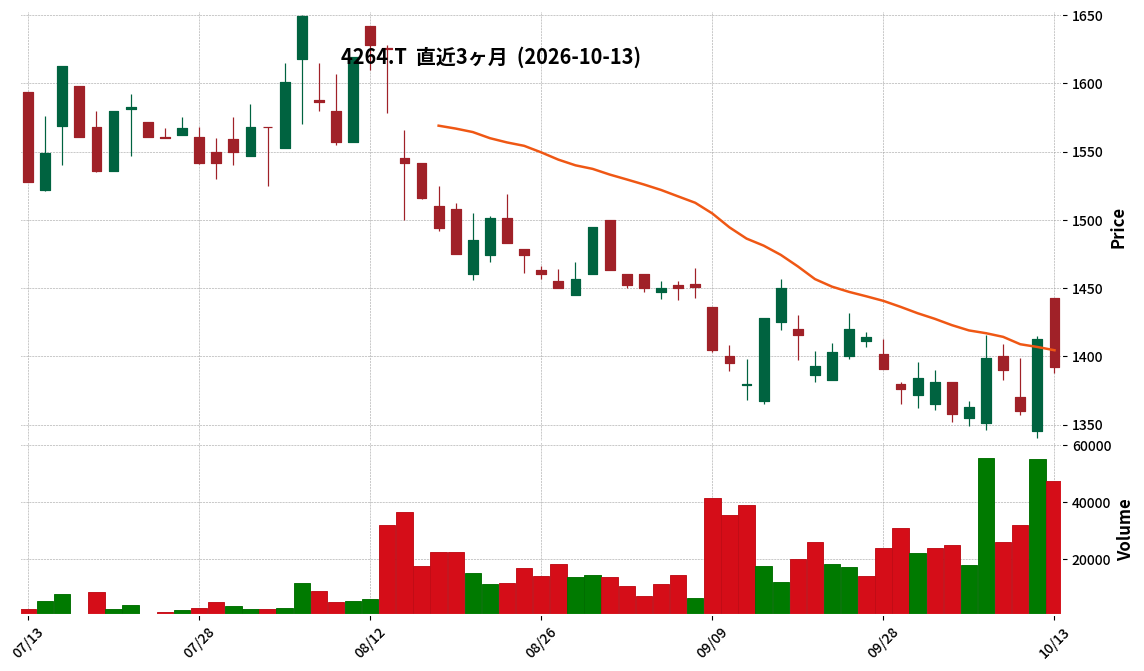
- 4264|G-セキュア
- 615A|P-インターパーク
- 7607|進和
- 9661|歌舞伎
- 575A|前澤HD
- 8081|カナデン
- 3647|アスリナ
- 4920|日本色材
- 6040|G-日本スキー
- 470A|P-ローカル
647A|P-東京みらい不動産
—
▲ +0.00%
📎 Source:P-東京みらい不動産 Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- P-Tokyo Mirai Fudosan listed on the TOKYO PRO Market of the Tokyo Stock Exchange on October 13, 2026.
- For the fiscal year ending December 2026 (forecast), the company projects net sales of ¥2,543 million (up 20.3% year-on-year), operating profit of ¥207 million (up 35.3% year-on-year), ordinary profit of ¥158 million (up 28.3% year-on-year), and net profit of ¥104 million (up 20.6% year-on-year).
- In the fiscal year ended December 2025, net sales were ¥2,113 million, operating profit was ¥153 million, ordinary profit was ¥123 million, and net profit was ¥86 million.
- Earnings per share are projected at ¥52.17 for FY2026 (forecast) and were ¥43.24 for FY2025.
- The dividend per share for FY2026 is undetermined, while it was ¥0.00 for FY2025.
🤖 AI Perspective
The announced financial forecast for the fiscal year ending December 2026, coinciding with the company’s listing on TOKYO PRO Market, indicates double-digit growth across all key metrics including net sales and profits compared to the previous year. The projected 35.3% increase in operating profit suggests a positive outlook on the company’s profitability. This forecast is set against a backdrop of rising land prices and increased costs in the real estate sector, which may suggest the company’s strategy is designed to navigate such market conditions effectively.
9334|アイビスHD
—
▲ +0.00%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- IBIS Holdings Co., Ltd. was listed on the Nagoya Stock Exchange NEXT Market and Fukuoka Stock Exchange Q-Board Market on October 13, 2026.
- The company announced its consolidated financial forecast for the fiscal year ending October 2026 (November 1, 2025 – October 31, 2026).
- The consolidated forecast projects net sales of 1,488 million yen (36.1% increase year-on-year), operating profit of 157 million yen (287.4% increase year-on-year), ordinary profit of 145 million yen (217.0% increase year-on-year), and net profit attributable to parent company shareholders of 100 million yen (185.5% increase year-on-year).
- The company also announced an estimated basic earnings per share of 56.02 yen and a dividend per share of 15.00 yen (conditional on approval at the general meeting of shareholders scheduled for January 2027).
- The company group operates in a single segment, employment support services, specifically “Type B employment support,” with 15 Type B facilities and 3 off-site work facilities as of the end of July 2026.
🤖 AI Perspective
This IR provides the initial full-year financial forecast coinciding with the company’s new listing, which may garner significant attention from the market. The substantial projected increase in profits year-on-year could be interpreted as an indicator of strong business growth potential. Furthermore, the growth in the number of users in its single-segment employment support services is highlighted as a key premise for the financial forecast, making it a critical factor for monitoring future business developments.
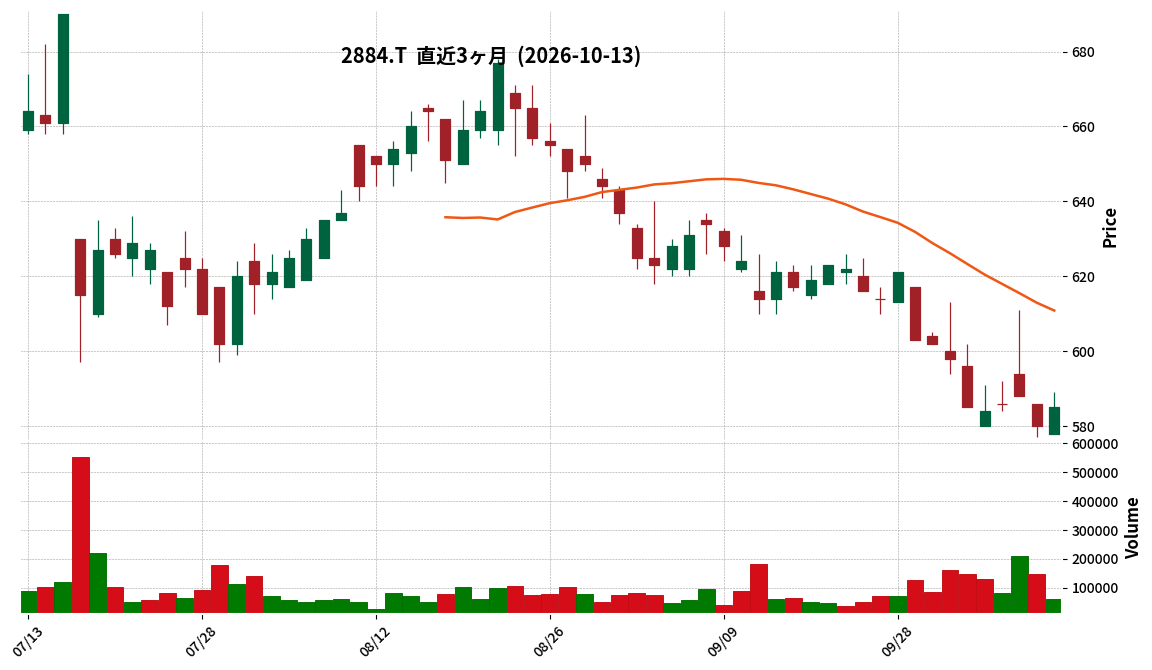
2884|ヨシムラ・F・HD
585.0
▲ +0.86%
📎 Source:ヨシムラ・F・HD Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Yoshimura Food Holdings K.K. announced the acquisition of shares in Nihon Kanzume Co., Ltd., making it a subsidiary.
- The share transfer agreement was signed on October 6, 2026, with the share transfer execution date scheduled for November 1, 2026.
- Nihon Kanzume Co., Ltd. is a food manufacturer established in 1948, headquartered in Memuro-cho, Kasai-gun, Hokkaido, engaging in the manufacturing and sales of frozen vegetables and retort pouch foods.
- For the fiscal year ended March 2026, the company reported sales of JPY 3,041 million and operating profit of JPY 209 million.
- Nihon Kanzume possesses a direct procurement network with contracted farmers in Tokachi and holds a top-class share in the domestic frozen corn market.
🤖 AI Perspective
This acquisition appears to be a strategic move aligning with Yoshimura Food Holdings’ stated objectives of strengthening ties with agricultural and fishery production sites and expanding into primary industry-related fields. Integrating Nihon Kanzume’s strong agricultural procurement network and processing technology in the Hokkaido-Tokachi region could deepen the group’s value chain, foster new product development, and expand domestic and international sales channels. Furthermore, leveraging Nihon Kanzume’s production and quality control expertise, cultivated under the Meiji Group, may enhance the overall management foundation of the Yoshimura Food Holdings group.
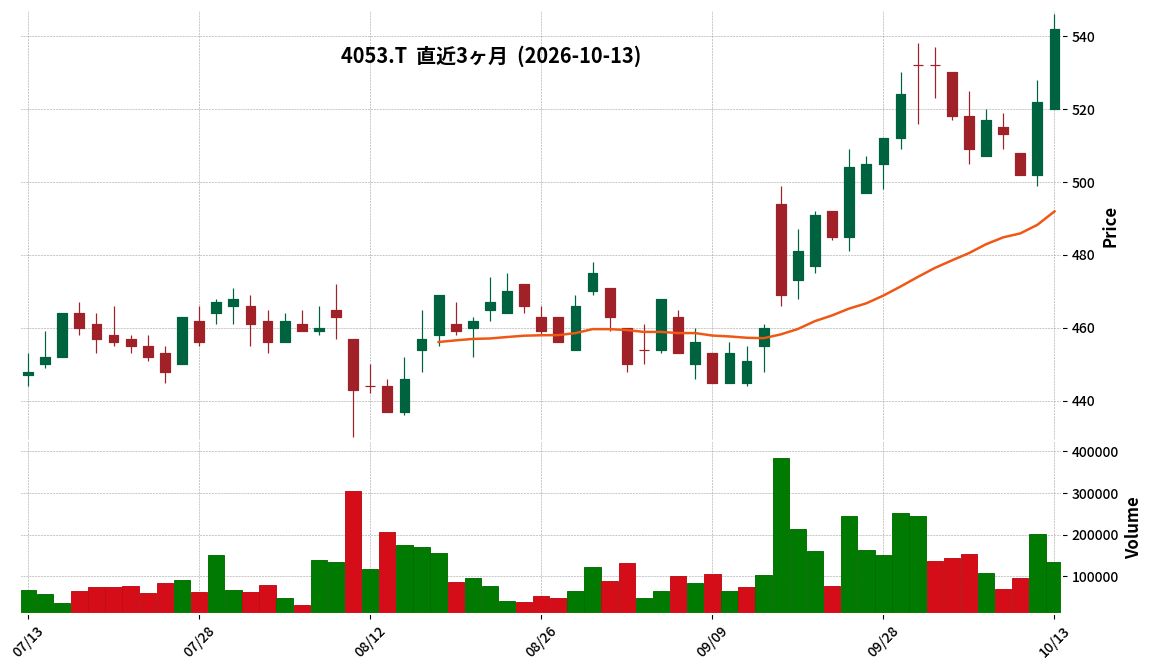
4053|サンアスタリスク
542.0
▲ +3.83%
📎 Source:サンアスタリスク Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Sun Asterisk Co., Ltd. has decided to add “Amazon Gift Cards” to its shareholder benefit program, “Sun Asterisk Premium Yu-tai Club.”
- The expansion aims to enhance the appeal of investing in the company’s shares, encourage long-term holding, and address shareholder demand for electronic money benefits.
- Shareholders eligible for the Amazon Gift Card exchange are those registered in the company’s shareholder registry as of the record date of December 31, 2026.
- The exchange is scheduled to begin in early March 2027.
- There are no changes to the number of points awarded based on the number of shares held and the holding period (1 point ≈ 1 yen). The benefit applies to shareholders holding 600 or more shares, with a maximum of two point carry-overs permitted.
🤖 AI Perspective
This expansion of the shareholder benefit program suggests Sun Asterisk’s intent to enhance shareholder convenience and broaden its appeal to investors. The addition of highly versatile Amazon Gift Cards could serve as an incentive for both existing and new shareholders, potentially strengthening the long-term shareholder base. By offering an electronic money option alongside the existing diverse product lineup, the overall attractiveness of the shareholder benefit program appears to have been enhanced.
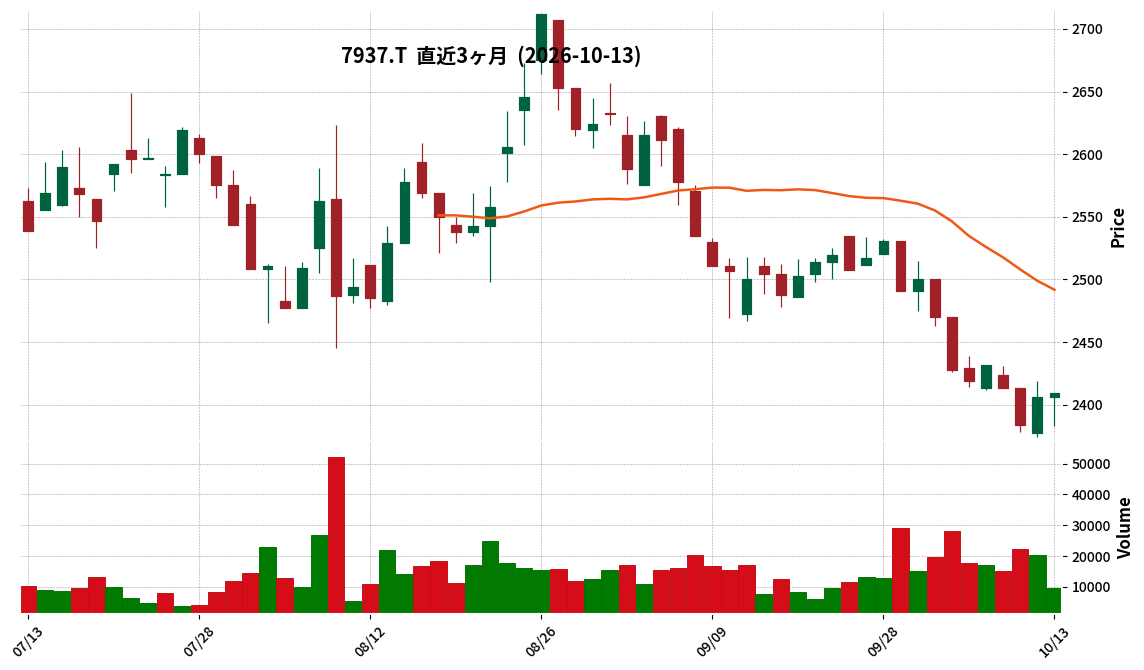
7937|ツツミ
2409.0
▲ +0.12%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- TUTSUMI Co., Ltd. announced on October 13, 2026, that its Board of Directors resolved to revise the interim dividend forecast for the period ended September 30, 2026.
- The interim dividend forecast for the fiscal year ending March 2027 has been revised upward by ¥5.00, from the previous forecast of ¥45.00 per share to ¥50.00 per share.
- Consequently, the full-year dividend forecast for the fiscal year ending March 2027 is now projected to be ¥120.00 per share, an increase of ¥5.00 from the previous forecast of ¥115.00 per share.
- The actual dividend for the previous fiscal year (ended March 2026) was ¥45.00 for the interim, ¥70.00 for the year-end, totaling ¥115.00 per share.
- The revision is attributed to a comprehensive consideration of recent business performance trends, financial position, and capital efficiency.
🤖 AI Perspective
This announcement suggests TUTSUMI’s continued emphasis on shareholder returns as a key management priority. The upward revision of the interim dividend may indicate the company’s confidence in its future performance and financial stability. Investors may view this as a positive sign regarding the company’s commitment to enhancing corporate value and providing consistent returns.
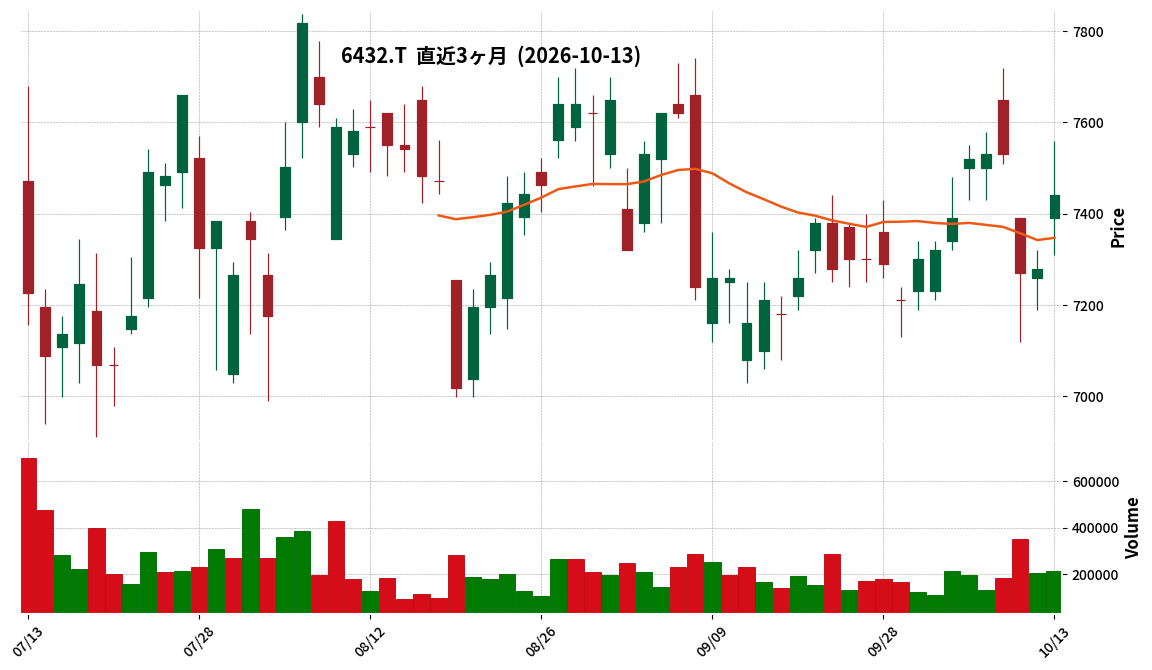
6432|竹内製作所
7440.0
▲ +2.20%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Takeuchi Mfg. Co., Ltd. reported consolidated net sales of ¥132,383 million for H1 FY2027 (up 16.0% YoY), operating profit of ¥24,198 million (up 3.4% YoY), ordinary profit of ¥25,122 million (up 6.0% YoY), and net profit attributable to parent company shareholders of ¥18,129 million (up 6.3% YoY).
- Orders received for the interim period amounted to ¥145,983 million (up 48.1% YoY), with an order backlog of ¥57,167 million at the end of the period. The disclosure of orders received and backlog will cease after FY2027.
- The full-year consolidated earnings forecast has been revised upward: net sales ¥261,000 million (up 15.9% YoY), operating profit ¥44,500 million (up 18.1% YoY), ordinary profit ¥44,200 million (up 12.8% YoY), and net profit attributable to parent company shareholders ¥31,500 million (up 11.4% YoY).
- The year-end dividend forecast has been revised from ¥210 for FY2026 to ¥245 (interim ¥110, year-end ¥135).
- Sales volumes exceeded the previous year in both key markets, North America and Europe, with strong demand for track loaders in North America and a gradual recovery in mini excavator demand in Europe.
🤖 AI Perspective
The achievement of increased revenue and profit in the interim results, coupled with upward revisions to full-year earnings and dividend forecasts, could be viewed positively by investors. The strong performance in North America and the recovery in Europe appear to be key drivers of sales growth, suggesting that regional market dynamics warrant continued monitoring in future global strategies. While strong order growth is noted, the decision to discontinue the disclosure of orders received and backlog after FY2027 may prompt investor focus on alternative indicators for future performance assessment.
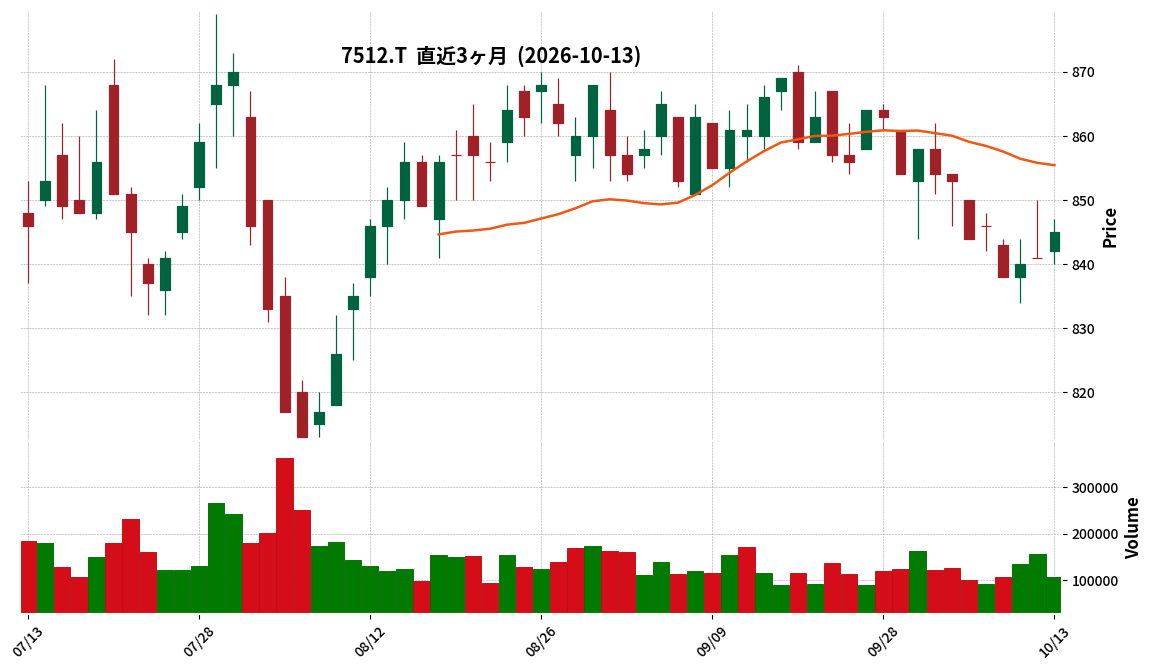
7512|イオン北海
845.0
▲ +0.48%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Aeon Hokkaido announced its financial results for the second quarter (interim period: March 1, 2026, to August 31, 2026) of the fiscal year ending February 2027.
- Net sales reached a record high of 188,263 million yen, an increase of 1.2% compared to the prior interim period.
- Operating profit decreased by 38.4% to 1,517 million yen, ordinary profit by 43.0% to 1,300 million yen, and interim net profit by 92.8% to 85 million yen, all significantly lower than the previous year.
- Interim earnings per share stood at 0.62 yen, down from 8.55 yen in the prior interim period.
- The full-year earnings forecast remains unchanged, projecting net sales of 392,000 million yen (up 3.1% YoY), operating profit of 8,700 million yen (up 4.4% YoY), ordinary profit of 8,200 million yen (up 2.1% YoY), and net profit of 3,000 million yen (down 19.6% YoY).
🤖 AI Perspective
While sales achieved a new record, the substantial decline in profits suggests challenges such as lower-than-planned sales, reduced gross profit margins due to price competitiveness, and impairment losses on some stores. With persistent consumer frugality and a competitive market, investors may want to monitor how the company’s initiatives in evolving store formats and product reforms will impact future performance.
139A|P-東日本地所
3350.0
▲ +0.00%
📎 Source:P-東日本地所 Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- For the fiscal year ended August 2026, consolidated net sales were ¥5,899 million, representing a 6.3% increase year-over-year.
- Operating profit reached ¥377 million (up 4.6% YoY), ordinary profit ¥373 million (up 6.9% YoY), and net income attributable to owners of parent ¥263 million (up 5.8% YoY).
- Earnings per share for FY2026 were ¥527.06, with an annual dividend per share of ¥60.00, an increase of ¥20.00 from the previous year.
- The consolidated forecast for the fiscal year ending August 2027 projects net sales of ¥7,000 million (up 18.7% YoY), operating profit of ¥410 million (up 8.5% YoY), ordinary profit of ¥390 million (up 4.5% YoY), net income attributable to owners of parent of ¥260 million (down 1.3% YoY), and earnings per share of ¥520.00.
- In the current fiscal year, the number of started construction projects for detached rental homes was 206 buildings (254 units), a 22.1% increase from the previous period, and completed projects totaled 188 buildings (229 units), up 9.6% year-over-year.
🤖 AI Perspective
P-Higashi-Nihon Jisho’s FY2026 results show solid revenue and profit growth, potentially driven by the strong performance of its construction business segment. The projected increase in sales and operating profit for FY2027, alongside a slight decrease in net income attributable to owners of parent, could suggest increased investments or operating costs, which may be worth monitoring. The rise in the dividend payout ratio from 8.0% to 11.4% may also indicate a growing commitment to shareholder returns.
482A|F-セールスAC
—
▲ +0.00%
📎 Source:F-セールスAC Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- F-SALES AC announced its non-consolidated financial results for the fiscal year ended August 2026.
- For FY2026, net sales were ¥186 million (up 18.2% year-on-year), operating profit was ¥23 million (up 100.6%), ordinary profit was ¥23 million (up 109.2%), and net profit was ¥18 million (up 332.0%).
- Earnings per share (EPS) for FY2026 was ¥45.55, compared to ¥10.54 in the prior year.
- The company’s financial position showed total assets of ¥103 million, net assets of ¥35 million, and an equity ratio of 34.3%.
- For the fiscal year ending August 2027, the company projects net sales of ¥220 million (up 17.8% year-on-year), operating profit of ¥42 million (up 78.2%), ordinary profit of ¥42 million (up 80.8%), and net profit of ¥27 million (up 50.4%).
🤖 AI Perspective
F-SALES AC’s fiscal year 2026 results demonstrate significant growth across all key profitability metrics, with net profit showing a remarkable increase of over 300% year-on-year. This strong performance appears to be driven by its “no-nonsense” new employee training programs aligning with market demand, leading to new client acquisitions and repeat business. The company’s forecast for continued growth in fiscal year 2027 suggests an ongoing positive trend, which could be worth monitoring for investors.
6142|富士精工
—
▲ +0.00%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Fujiseiko announced its consolidated financial results for the second quarter (interim period) of the fiscal year ending February 2027.
- Net sales for the interim period amounted to 10,568 million yen, marking a 9.1% increase compared to the prior interim period.
- Operating profit was 291 million yen (up 270.2%), ordinary profit was 429 million yen (up 141.2%), and profit attributable to owners of parent was 644 million yen (up 450.3%).
- Earnings per share (interim) were 218.93 yen.
- The company’s forecast for the fiscal year ending February 2027 includes an annual dividend of 50.00 yen, consisting of an interim dividend of 25.00 yen and a year-end dividend of 25.00 yen.
- Total assets stood at 27,775 million yen, with an equity ratio of 74.0%.
🤖 AI Perspective
Fujiseiko’s Q2 FY2027 results show significant growth in revenue and substantial increases across all profit metrics compared to the previous interim period. This performance may indicate the positive impact of optimized sales pricing and ongoing productivity improvement initiatives. While strong sales in Japan and Asia appear to have contributed to overall performance, a decline in sales was observed in the North/Central America region.
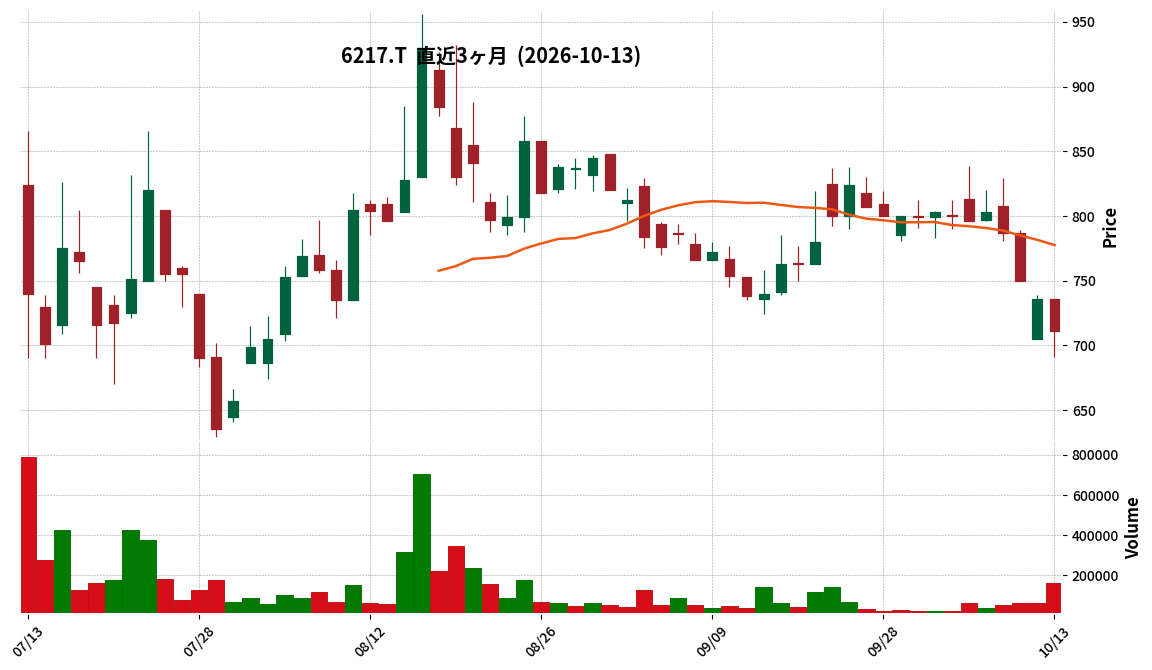
6217|津田駒工
711.0
▼ -3.40%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- For the third quarter of the fiscal year ending November 2026 (December 1, 2024 – August 31, 2025), net sales were ¥25,271 million, representing a 3.2% increase compared to the same period in the prior year.
- Operating income reached ¥77 million (compared to an operating loss of ¥331 million in the prior year period), and ordinary income was ¥8 million (compared to an ordinary loss of ¥539 million in the prior year period), marking a return to profitability.
- Net loss attributable to owners of parent was ¥129 million, narrowing from a loss of ¥554 million in the prior year period.
- Total assets stood at ¥26,648 million, net assets at ¥2,750 million, and the equity ratio was 10.0%.
- The full-year consolidated earnings forecast remains unchanged, projecting net sales of ¥36,000 million, operating income of ¥500 million, ordinary income of ¥300 million, and net income attributable to owners of parent of ¥100 million.
- Order intake for the Textile Machinery Business was ¥31,796 million (up 52.2% year-on-year), and for the Machine Tool Related Business was ¥5,474 million (up 41.1% year-on-year).
🤖 AI Perspective
Tsudakoma Corporation’s Q3 results show a notable improvement with increased net sales and a return to operating profitability, suggesting a potential recovery trend in its business operations. The significant increase in order intake across both the Textile Machinery and Machine Tool Related segments could be a positive indicator for future revenue growth. This performance against the backdrop of previous losses warrants monitoring by investors.
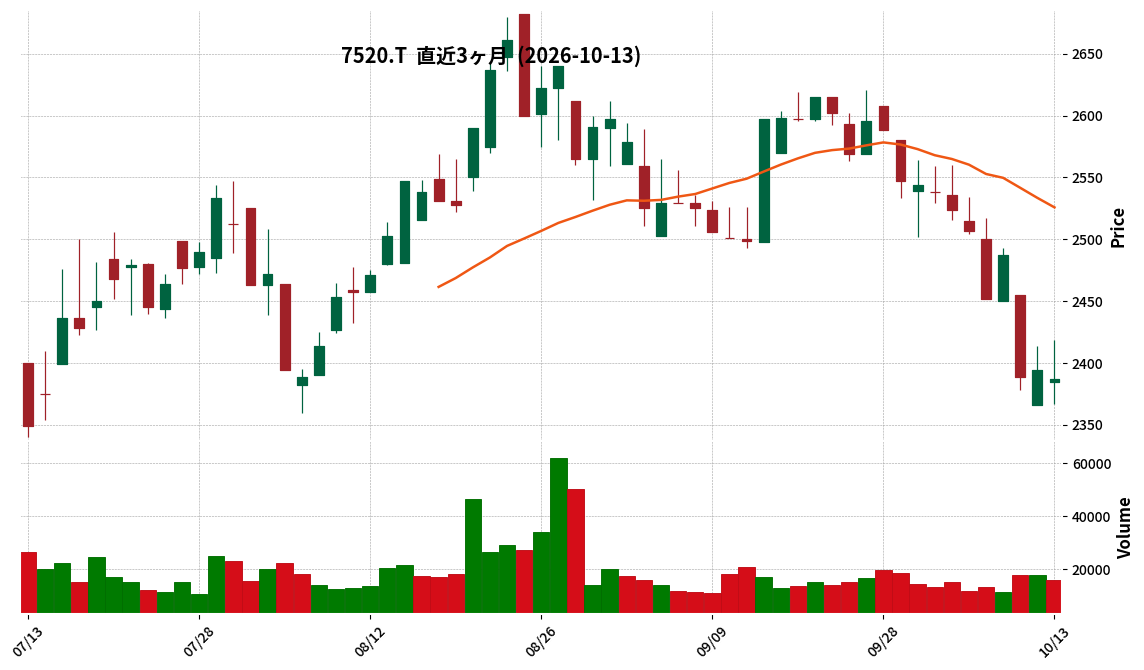
7520|エコス
2387.0
▼ -0.29%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- For the second quarter of the fiscal year ending February 2027, consolidated operating revenue was ¥69,793 million, marking a 1.4% decrease compared to the previous interim period.
- Consolidated operating profit stood at ¥2,847 million (down 5.3% year-on-year), and consolidated ordinary profit was ¥2,919 million (down 5.5% year-on-year).
- Net profit attributable to owners of the parent decreased by 30.5% year-on-year to ¥1,778 million.
- Interim net earnings per share were ¥159.37.
- The full-year consolidated earnings forecast remains unchanged from the most recently published outlook, with operating revenue projected at ¥138,000 million (0.0% change from previous year) and net profit attributable to owners of the parent at ¥3,500 million (32.3% increase from previous year).
- During this interim period, one new store, TAIRAYA Owada, was opened, and four existing stores (TAIRAYA Yamagata, Machiya, Kandatsu, and Hojuhana) underwent renovations.
🤖 AI Perspective
ECOS reported a decrease in both revenue and profit for the second quarter of fiscal year 2027, yet the full-year earnings forecast remains unchanged. In a challenging economic environment characterized by rising prices and consumer frugality, the impact of new strategies like “Price Select” and ongoing store renovations and new openings will be worth monitoring. While operating cash flow showed a positive inflow, significant outflows from investing activities suggest a continued focus on business expansion through capital expenditure.
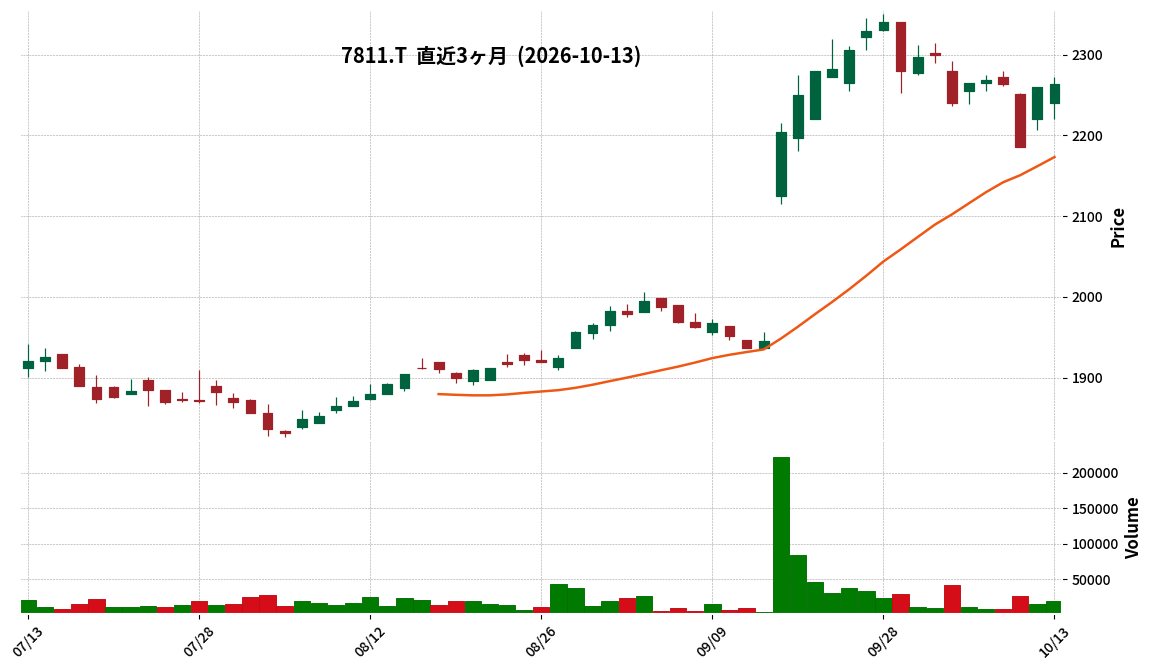
7811|中本パックス
2263.0
▲ +0.13%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Nakamoto Packs Co., Ltd. has announced its consolidated financial results for the second quarter (interim) of the fiscal year ending February 2027.
- Net sales reached 28,068 million yen, marking a 12.3% increase compared to the prior interim period.
- Operating profit was 2,454 million yen (up 52.4% year-on-year), and ordinary profit was 2,499 million yen (up 59.4% year-on-year).
- Net income attributable to owners of the parent stood at 1,641 million yen, a 54.8% increase from the previous interim period.
- Net sales, operating profit, ordinary profit, and net income attributable to owners of the parent all achieved record highs for an interim consolidated accounting period.
- Earnings per share (interim net income) were 185.38 yen.
🤖 AI Perspective
The interim results indicate that Nakamoto Packs successfully navigated rising raw material costs by implementing price transfers and benefited from increased sales of paper-related products and top seals, as well as expanded demand in the semiconductor and electronic components markets. The significant improvement in profitability is attributed to enhanced production efficiency, cost reduction measures, and an improved product mix, particularly in the IT and industrial materials segments. The record-high performance across key profit metrics for an interim period suggests the company’s effective response to market conditions and progress in business growth.
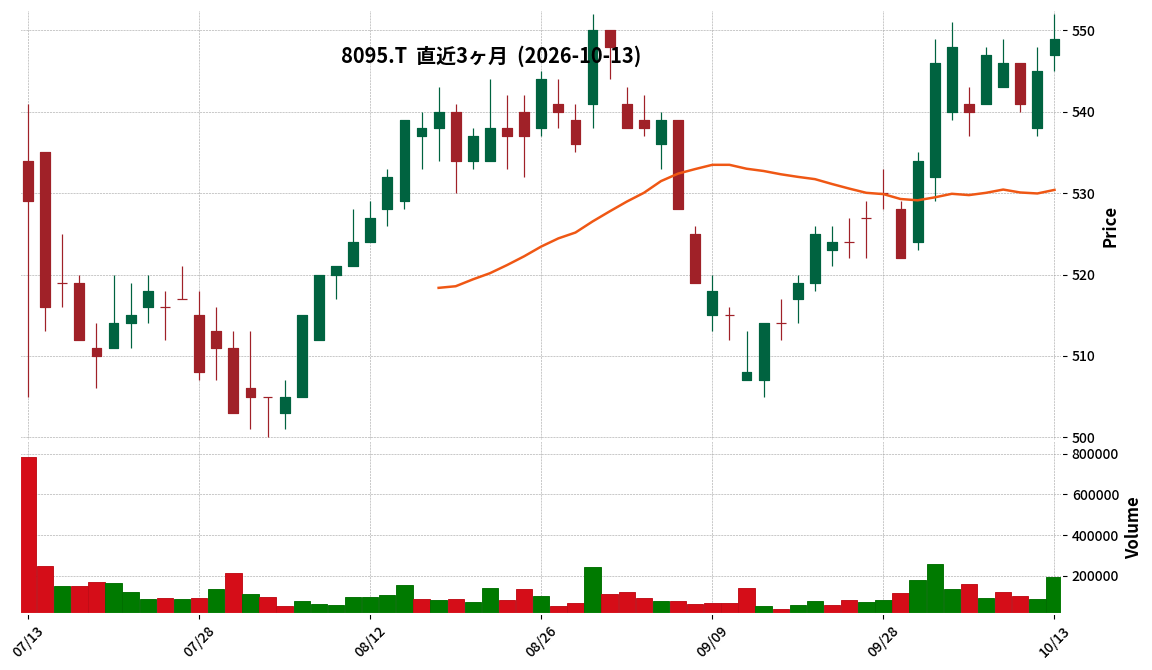
8095|アステナHD
549.0
▲ +0.73%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Astena Holdings Co., Ltd. announced its consolidated financial results for the third quarter of the fiscal year ending November 2026 (December 1, 2025 – August 31, 2026).
- For the cumulative third quarter, net sales were ¥52,247 million (up 14.9% year-on-year), operating income was ¥3,009 million (up 7.3%), ordinary income was ¥2,799 million (up 3.1%), and net income attributable to parent company shareholders was ¥2,006 million (up 22.7%).
- The HBC & Food segment recorded net sales of ¥16,989 million (up 39.9% year-on-year), driven by the consolidation of Ikeda Bussan Group and strengthened overseas expansion.
- The Chemical Products segment saw significant increases in both sales and profit in its surface treatment chemicals and equipment divisions, with net sales reaching ¥9,159 million (up 34.5% year-on-year).
- The full-year consolidated earnings forecast for the fiscal year ending November 2026 remains unchanged, projecting net sales of ¥68,000 million, operating income of ¥3,400 million, ordinary income of ¥3,300 million, and net income attributable to parent company shareholders of ¥2,350 million.
🤖 AI Perspective
Astena HD’s Q3 results show solid performance with double-digit year-on-year growth in net sales and net income attributable to parent, indicating robust operational execution. The strong contributions from the HBC & Food and Chemical Products segments highlight key growth drivers within the company’s diversified portfolio. The unchanged full-year outlook suggests that the company’s current performance aligns with its earlier projections, which investors may find as a point of stability.
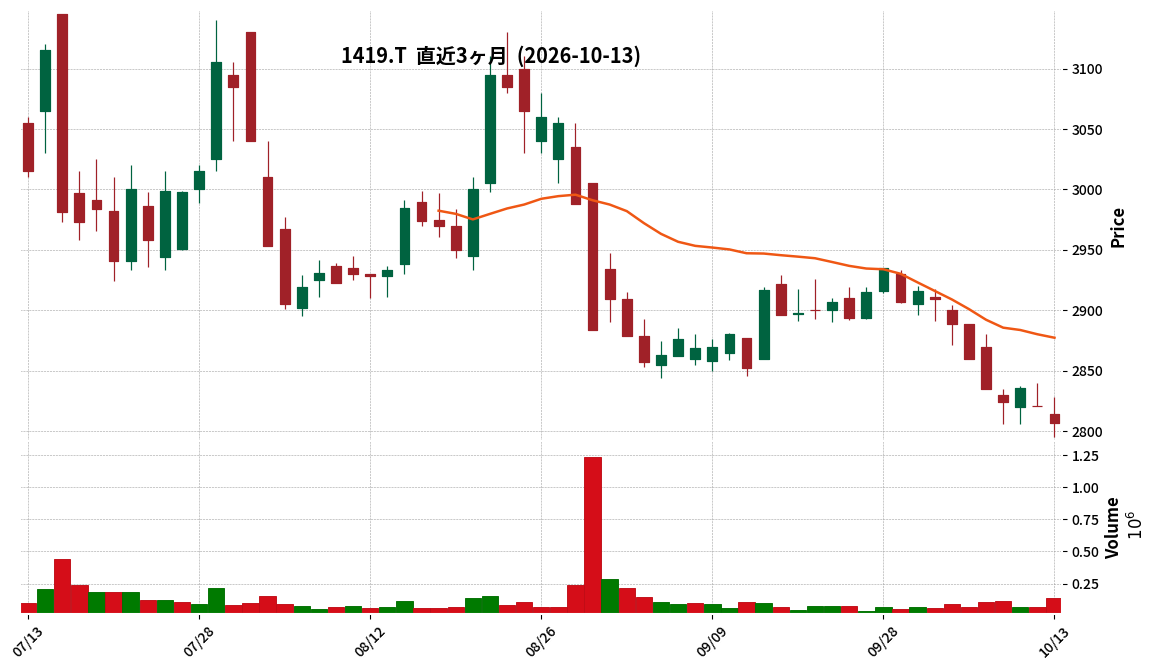
1419|タマホーム
2807.0
▼ -0.50%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Tamahome Co., Ltd. announced its consolidated financial results for the first quarter of the fiscal year ending May 2027 (June 1, 2026 – August 31, 2026).
- Consolidated net sales were ¥27,613 million, a 5.1% decrease year-over-year, while the operating loss was ¥4,559 million (compared to an operating loss of ¥4,435 million in the prior year’s first quarter). Net loss attributable to owners of the parent was ¥3,329 million (compared to a net loss of ¥2,833 million in the prior year’s first quarter).
- In terms of consolidated financial position, total assets stood at ¥102,418 million, net assets at ¥22,751 million, and the equity ratio was 22.2%.
- The housing business reported net sales of ¥14,199 million (down 11.3% YoY) and an operating loss of ¥5,327 million.
- The real estate business achieved net sales of ¥11,978 million (up 2.0% YoY) and an operating profit of ¥456 million (down 38.7% YoY).
- The full-year consolidated earnings forecast for the fiscal year ending May 2027 remains unchanged: net sales of ¥230,000 million, operating profit of ¥7,500 million, ordinary profit of ¥6,700 million, and net profit attributable to owners of the parent of ¥4,000 million.
🤖 AI Perspective
The first quarter saw a decline in consolidated net sales and an expanded operating loss, which may suggest the impact of challenging external factors such as a decrease in new housing starts and persistently high construction costs in the housing market. Conversely, the real estate business recorded increased sales, and both the financial and energy businesses improved their operating profits, indicating varied performance across segments. The unchanged full-year earnings forecast could signal the company’s confidence in its future business activities and the execution of its “Tama Step 2031” medium-term management plan.
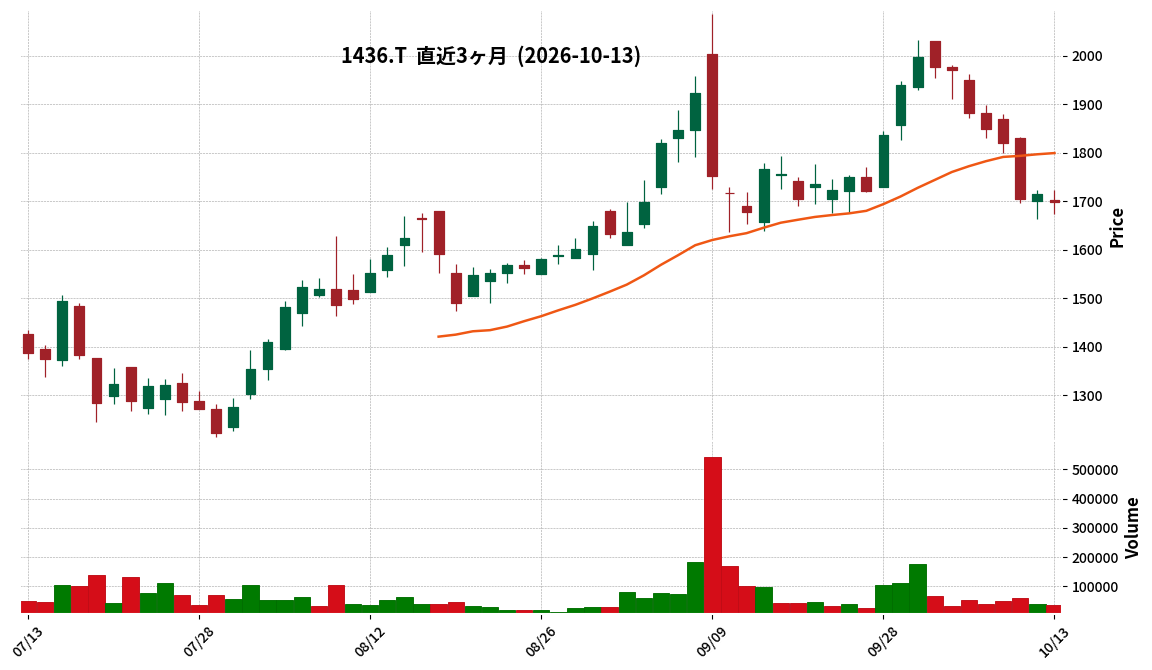
1436|G-グリーンエナジー
1699.0
▼ -0.88%
📎 Source:G-グリーンエナジー Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- G-Green Energy resolved to subscribe to a capital increase for its subsidiary, NARUTO Green Farm Co., Ltd., at a board meeting held on October 13, 2026.
- The purpose of the capital increase is to strengthen the financial base for the full-scale development and future expansion of the “Agriculture GX” (Green Transformation) business.
- NARUTO Green Farm Co., Ltd. was established on July 31, 2026, with a pre-increase capital of 1 million yen, 100% owned by G-Green Energy.
- The capital increase amounts to 9 million yen, raising the post-increase capital to 10 million yen, with G-Green Energy maintaining 100% ownership.
- NARUTO Green Farm Co., Ltd. focuses on three business areas: agriculture trading, solar sharing, and smart agriculture.
🤖 AI Perspective
This capital increase suggests G-Green Energy’s commitment to reinforcing its “Agriculture GX” business model, which integrates agriculture with renewable energy. The initiative appears to be a strategic move aimed at addressing regional agricultural challenges and contributing to food and energy self-sufficiency in Japan. Investors may monitor the progress of this business model, which is slated for initial establishment in the Tokushima and Kanto regions before nationwide expansion.
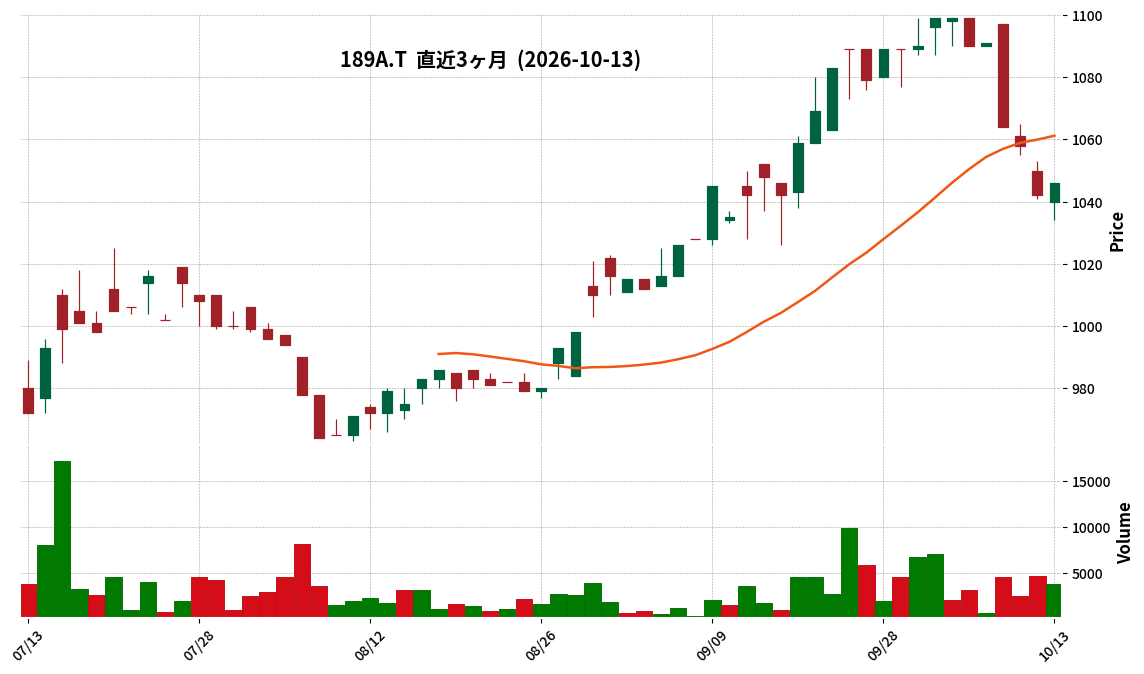
189A|G-D&Mカンパニー
1046.0
▲ +0.38%
📎 Source:G-D&Mカンパニー Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- G-D&M Company announced its consolidated financial results for the first quarter of the fiscal year ending May 2027 (June 1, 2026, to August 31, 2026).
- Net sales were ¥428 million, a 1.7% decrease compared to the same period last year, primarily due to a reactionary decline from large medical equipment sales recorded in the prior year.
- Operating profit increased by 100.7% year-on-year to ¥106 million, ordinary profit increased by 30.6% to ¥106 million, and net income attributable to owners of parent increased by 33.4% to ¥75 million, all demonstrating significant profit growth.
- The substantial profit increase was primarily driven by solid performance in F&I and HR&OS services, along with increased high-gross-margin consulting sales within C&Br services.
- Total assets at the end of the quarter were ¥11,757 million, an increase of ¥1,133 million from the end of the previous consolidated fiscal year, mainly due to a ¥1,071 million increase in land acquired for real estate utilization support in F&I services.
🤖 AI Perspective
G-D&M Company’s Q1 FY2027 results indicate a strategic shift towards higher-margin services, as evidenced by significant profit growth despite a slight dip in net sales. The robust increase in consulting sales within the C&Br segment appears to be a key driver for improved profitability. Furthermore, the expansion in total assets, particularly through real estate utilization in F&I services, may suggest the company’s commitment to strengthening its support for healthcare and nursing care providers.
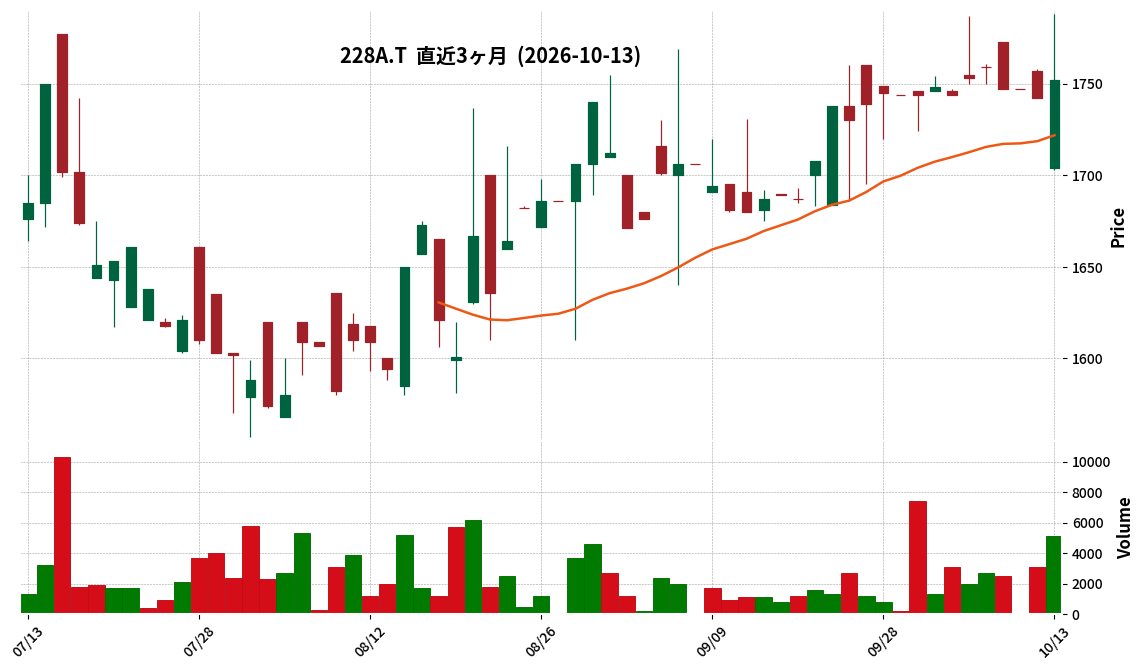
228A|G-オプロ
1752.0
▲ +0.57%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- G-Opro Co., Ltd. announced its unaudited financial results for the third quarter of the fiscal year ending November 2026 (December 1, 2025 to August 31, 2026) on October 13, 2026.
- For the nine months ended August 31, 2026, net sales reached ¥2,150 million (up 15.5% year-on-year), operating profit was ¥366 million (up 32.8%), ordinary profit ¥377 million (up 35.7%), and quarterly net profit ¥260 million (up 46.8%).
- Basic earnings per share for the quarter were ¥112.50, and diluted earnings per share were ¥109.95.
- Total assets at the end of the third quarter stood at ¥3,093 million, net assets at ¥1,529 million, with an equity ratio of 49.4%.
- The full-year forecast for FY2026 has been revised, projecting net sales of ¥2,934 million (up 15.0% from previous fiscal year) and full-year net profit of ¥343 million (up 42.5%).
🤖 AI Perspective
G-Opro’s third-quarter results demonstrate robust growth across key financial metrics, with significant year-over-year increases in both revenue and various profit categories. The substantial rise in quarterly net profit may suggest effective operational efficiency and cost management. The upward revision of the full-year earnings forecast indicates management’s confidence in maintaining this positive momentum for the remainder of the fiscal year.
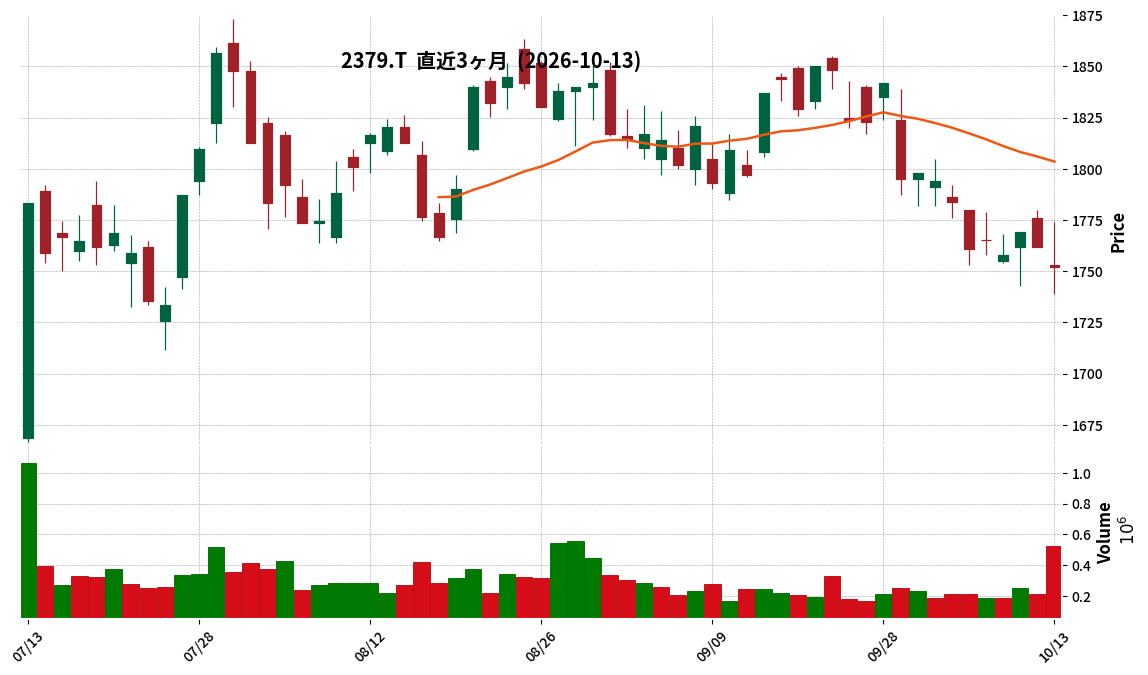
2379|ディップ
1752.0
▼ -0.57%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Dip Corporation announced its consolidated financial results for the second quarter (interim period) of the fiscal year ending February 2027.
- Consolidated net sales for the interim period were ¥25.55 billion, a decrease of 11.4% compared to the same period last year.
- Consolidated operating profit was ¥56 million (down 99.0% year-on-year), and ordinary profit was ¥3 million (down 99.9% year-on-year).
- Net loss attributable to owners of the parent was ¥578 million (compared to a net profit of ¥3.715 billion in the same period last year).
- Sales for the Human Resources Services business were ¥22.268 billion (down 12.5% year-on-year), and for the DX business were ¥3.281 billion (down 3.8% year-on-year).
- The consolidated full-year forecast for FY2027 has been revised, with net sales projected between ¥49.00 billion and ¥53.00 billion, operating profit between a loss of ¥2.50 billion and a profit of ¥2.50 billion, and net profit between a loss of ¥2.70 billion and a profit of ¥0.70 billion.
- An interim dividend of ¥48 per share is planned, with a year-end dividend forecast of ¥49, totaling a full-year dividend forecast of ¥97.
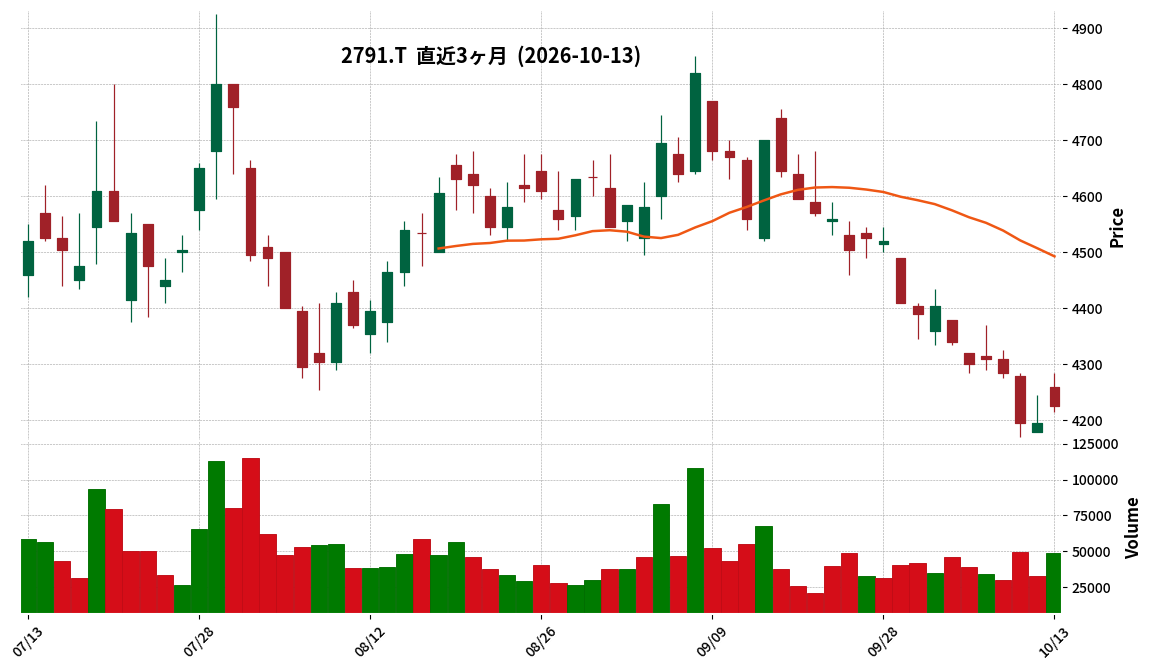
2791|大黒天
4225.0
▲ +0.72%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Daikokuten Co., Ltd. announced its consolidated financial results for the first quarter of the fiscal year ending May 2027 (June 1, 2026 – August 31, 2026).
- Net sales reached ¥83.273 billion, marking a 5.5% increase compared to the same period of the previous fiscal year.
- Operating profit decreased by 65.2% year-on-year to ¥582 million, and ordinary profit decreased by 65.6% to ¥620 million.
- Net profit attributable to owners of parent declined by 65.8% year-on-year to ¥382 million.
- The company maintains its full-year consolidated earnings forecast, projecting net sales of ¥344.1 billion (up 7.8% year-on-year) and ordinary profit of ¥7.6 billion (up 39.4% year-on-year).
🤖 AI Perspective
Daikokuten’s first quarter results show a continued increase in net sales, but a significant decline in profits is noteworthy. This may suggest the impact of challenging business conditions, including rising raw material prices, energy and logistics costs, and increased personnel expenses due to minimum wage hikes. However, the company has maintained its annual dividend forecast and full-year consolidated earnings projections, which could indicate an expectation for future cost control measures and strategic initiatives to take effect.
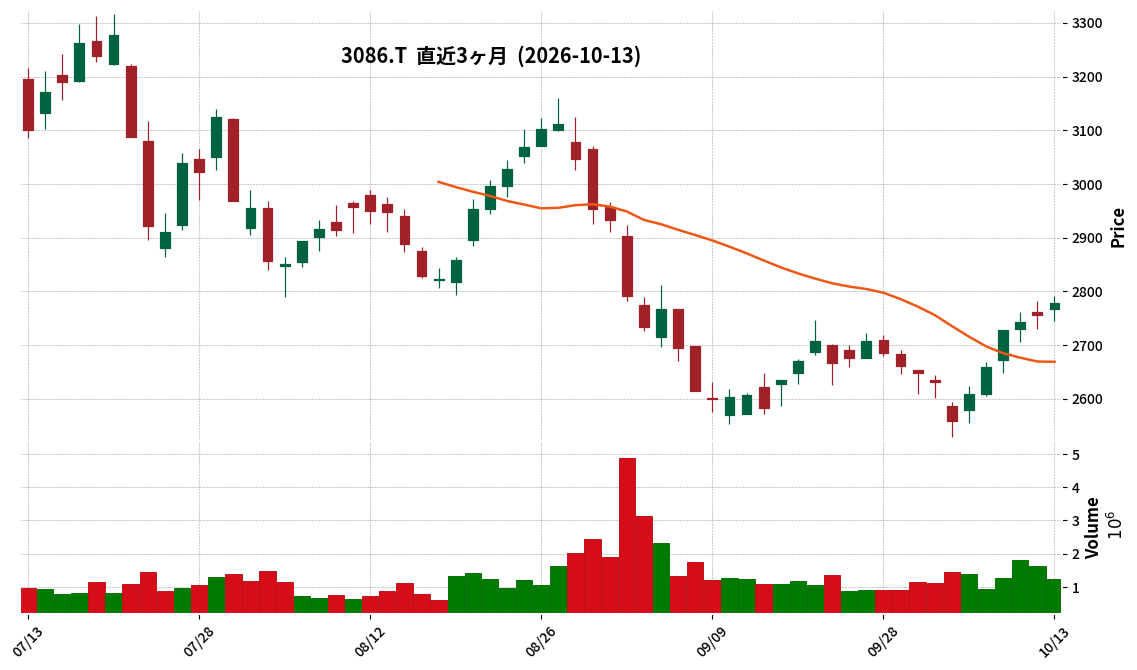
3086|Jフロント
2778.5
▲ +0.82%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- J. Front Retailing Co., Ltd. has announced its consolidated financial results for the second quarter (interim period) of the fiscal year ending February 2027.
- During this interim period, revenue was ¥213,821 million, representing a 2.8% decrease compared to the same period of the previous year.
- Operating profit (business profit) was ¥26,591 million (down 5.6% year-on-year), operating profit was ¥26,813 million (down 10.5% year-on-year), and interim profit attributable to owners of the parent was ¥17,379 million (down 5.3% year-on-year).
- The primary reasons for the decline in revenue and profit include the backlash from last year’s Osaka-Kansai Expo-related sales in the department store business, the impact of store closures due to large-scale renovations at Daimaru Umeda, and the backlash from large interior and facility-related orders in the developer business in the previous year.
- The consolidated full-year performance forecast for the fiscal year ending February 2027 has been revised, with total gross sales of ¥1,360,000 million, revenue of ¥470,000 million, and profit attributable to owners of the parent of ¥29,000 million projected.
🤖 AI Perspective
The decline in key performance indicators for the interim period compared to the previous year is noteworthy. The rebound effect in the department store business and renovation impacts appear to have influenced revenue and various profit levels. However, the revision of the full-year forecast suggests that changes in the business environment or future strategies may be reflected, which investors may wish to monitor closely.
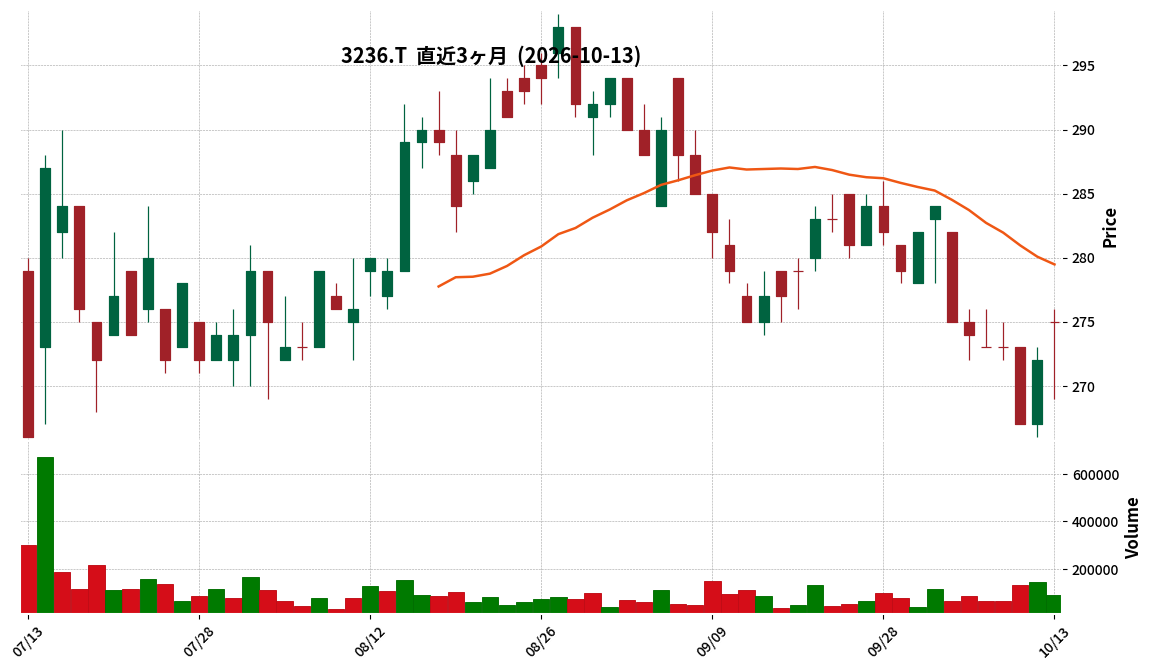
3236|プロパスト
275.0
▲ +1.10%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Properst Co., Ltd. announced its consolidated financial results for the first quarter of the fiscal year ending May 2027 (June 1, 2026, to August 31, 2026).
- Consolidated net sales for the first quarter reached ¥15,702 million, operating profit was ¥2,574 million, ordinary profit was ¥2,438 million, and net profit attributable to parent company shareholders was ¥1,410 million.
- By segment, the Rental Development business recorded ¥7,804 million in sales and ¥1,987 million in segment profit. The Value-Up business reported ¥738 million in sales and ¥134 million in segment profit. The Construction Contracting business achieved ¥7,156 million in sales and ¥751 million in segment profit.
- The Condominium Development business reported zero sales and zero segment profit for the period.
- Due to the consolidation of Ogawa Kensetsu Co., Ltd. on October 27, 2025, no comparative figures or year-on-year growth rates for the previous fiscal year’s first quarter are provided.
🤖 AI Perspective
Properst’s Q1 FY2027 results, being the first consolidated financial statement, lack year-on-year comparisons, yet indicate that the Rental Development and Construction Contracting segments are key revenue drivers. The sale of seven projects within the Rental Development business appears to have significantly contributed to revenue. Investors may also note the initial progress made towards the full-year forecast.
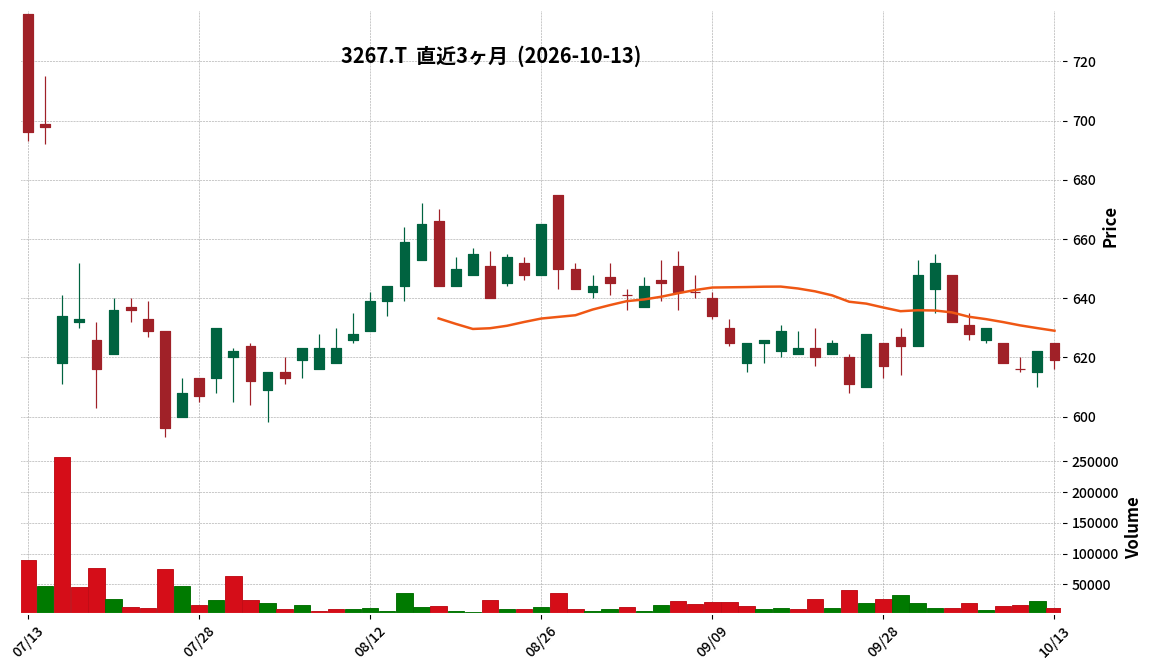
3267|フィル・カンパニー
619.0
▼ -0.48%
📎 Source:フィル・カンパニー Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Phil Company announced its consolidated financial results for the third quarter of fiscal year 2026 (December 1, 2025 – August 31, 2026).
- Consolidated net sales reached ¥6,096 million, an increase of 8.3% compared to the same period in the previous year.
- Consolidated operating profit was ¥270 million (+3.4% YoY), ordinary profit was ¥233 million (-8.9% YoY), and net income attributable to parent shareholders was ¥227 million (+46.9% YoY).
- The increase in revenue and profit was driven by the completion of sales and deliveries for three large-scale development projects within the development and sales scheme.
- Basic earnings per share for the quarter were ¥42.38.
🤖 AI Perspective
The growth in sales and net income attributable to parent shareholders appears to be driven by significant project deliveries within the development and sales scheme. However, the increase in selling, general, and administrative expenses may have mitigated operating profit growth, leading to a decrease in ordinary profit, which could be a point of interest for investors. The company’s ability to manage costs while maintaining profitability will be worth monitoring going forward.
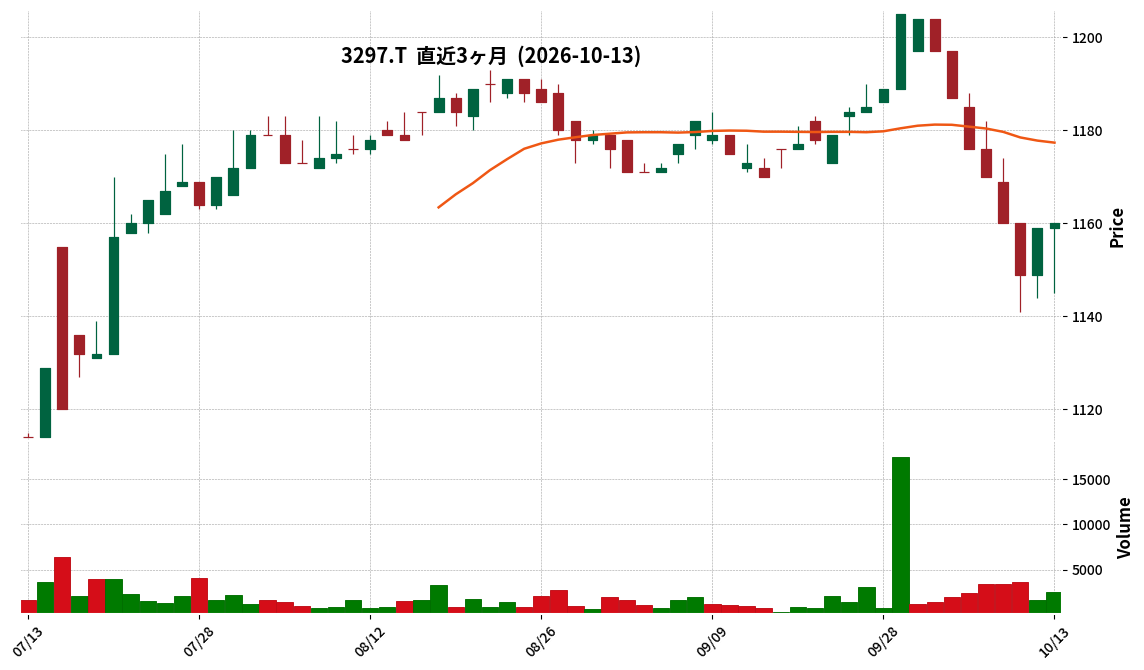
3297|東武住販
1160.0
▲ +0.09%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- For the first quarter of fiscal year 2027 (June 1, 2026 – August 31, 2026), net sales were ¥2,014 million, representing a 23.8% increase compared to the same period in the previous year.
- Operating profit reached ¥111 million (+298.9% YoY), ordinary profit was ¥113 million (+299.3% YoY), and net income for the quarter stood at ¥72 million (+302.3% YoY).
- The Real Estate Sales and Purchase Business reported sales of ¥1,936 million (+25.9% YoY) and operating profit of ¥249 million (+46.2% YoY). The number of self-owned real estate sales increased to 106 units from 89 units, with an increase in average selling price.
- The Real Estate Leasing Business saw sales decrease to ¥48 million (-18.6% YoY), but operating profit was ¥7 million (-4.1% YoY) due to a significant reduction in cost of sales.
- The full-year forecast for FY2027 remains unchanged, projecting net sales of ¥8,000 million (+3.3% YoY), operating profit of ¥570 million (-3.0% YoY), ordinary profit of ¥560 million (-5.0% YoY), and net income of ¥360 million (-8.9% YoY).
🤖 AI Perspective
Tobu Juhan’s Q1 FY2027 results showed significant year-over-year growth across all profit metrics, primarily driven by strong performance in its Real Estate Sales and Purchase Business. The increase in the number of self-owned property sales and higher average selling prices contributed substantially to these positive figures. Despite the robust start to the fiscal year, the company has maintained its full-year earnings forecast, which may suggest a cautious outlook for the remaining periods or reflect planned investments.
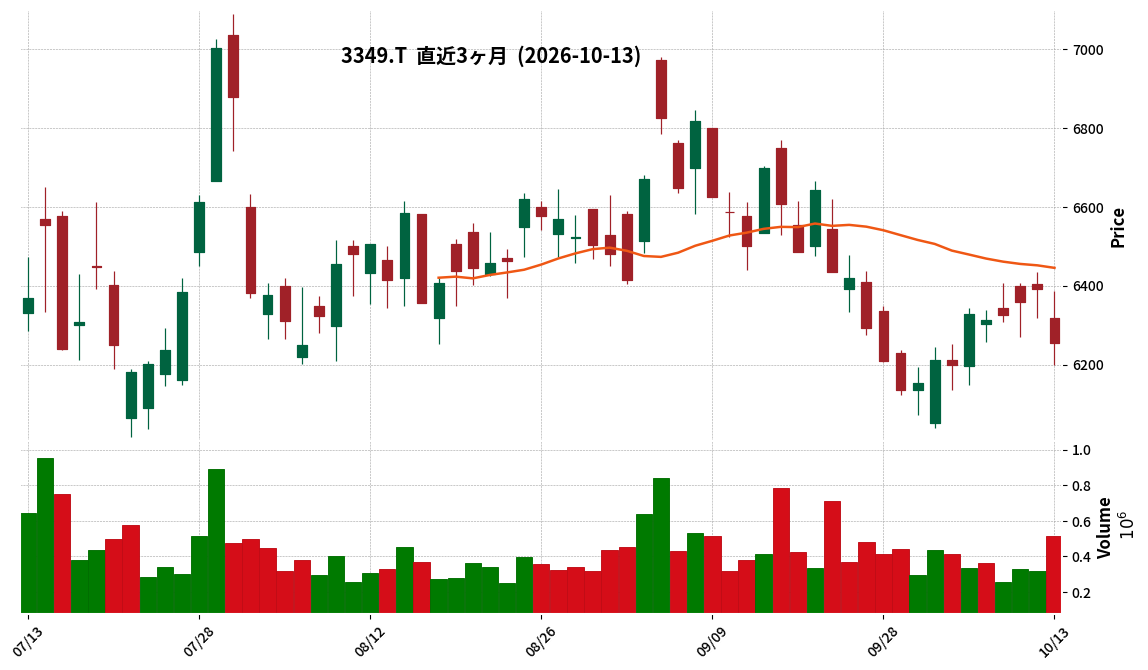
3349|コスモス薬品
6254.0
▼ -2.16%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Cosmos Pharmaceutical announced its consolidated financial results for the first quarter of FY2027 (June 1, 2026, to August 31, 2026).
- Sales for the quarter reached ¥286,653 million, representing a 5.2% increase compared to the same period of the previous fiscal year.
- Operating profit was ¥12,005 million (up 3.1%), ordinary profit was ¥12,766 million (up 4.7%), and net profit attributable to owners of parent was ¥8,251 million (up 1.0%).
- As of the end of the first consolidated accounting period, the total number of stores was 1,717, with 13 new stores opened and 4 stores closed.
- The consolidated earnings forecast and dividend forecast for FY2027 remain unchanged from the most recently announced figures.
🤖 AI Perspective
Cosmos Pharmaceutical’s Q1 results indicate a solid start to the fiscal year with increases across sales and profit metrics. The company’s strategy of continuous new store openings, expanding its network, appears to be contributing to revenue growth. While total assets decreased from the previous fiscal year-end, the self-capital ratio increased, suggesting a maintained financial soundness.
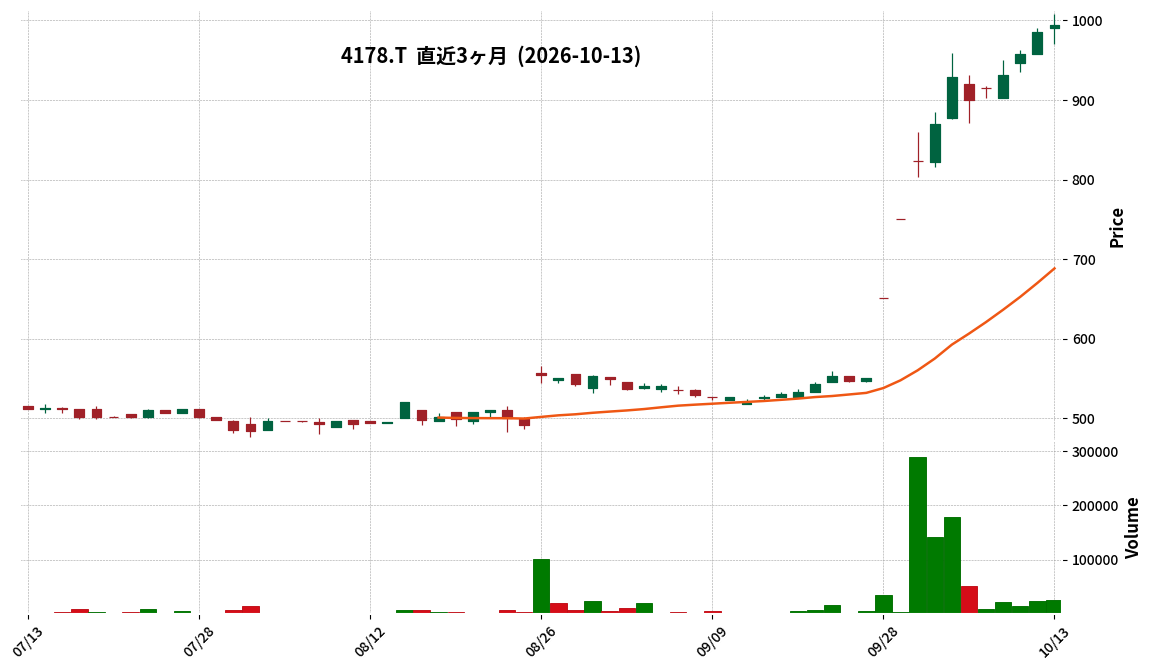
4178|G-Sイノベーション
994.0
▲ +0.91%
📎 Source:G-Sイノベーション Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Sharing Innovations Co., Ltd. (G-S Innovation) signed agreements on October 13, 2026, for an absorption-type merger with SALTO Co., Ltd. and Nihon Giken Professional Architect Co., Ltd., both wholly-owned subsidiaries of Orchestra Holdings Co., Ltd., and for the succession of VES Co., Ltd.’s SES business via an absorption-type split.
- Through this DX business reorganization, Sharing Innovations will be the surviving company in the absorption-type merger and the successor company in the absorption-type split.
- Additionally, agreements were signed for the reorganization of the Platform (PF) business, making G clef Co., Ltd., a wholly-owned subsidiary of Sharing Innovations, the absorbed company, and Sharing Innovations’ PF business the company undergoing an absorption-type split, with Land Ho Co., Ltd., a wholly-owned subsidiary of Orchestra Holdings, as the surviving/successor company.
- These transactions are contingent upon the effectiveness of the share exchange announced on August 25, 2026, regarding Orchestra Holdings’ complete acquisition of Sharing Innovations.
- The effective date for both the DX and PF transactions is scheduled for December 1, 2026.
🤖 AI Perspective
This announcement appears to be a strategic internal reorganization following the complete acquisition of Sharing Innovations by its parent company, Orchestra Holdings. The expansion of the DX business to a 600-person scale and the strengthening of internal cooperation within the PF business could indicate concrete steps towards maximizing synergies, as outlined in the previously announced share exchange. This move may suggest an effort to adapt to evolving business environments, such as intensifying competition for talent and rapid advancements in generative AI, aiming for sustainable group-wide corporate value enhancement.
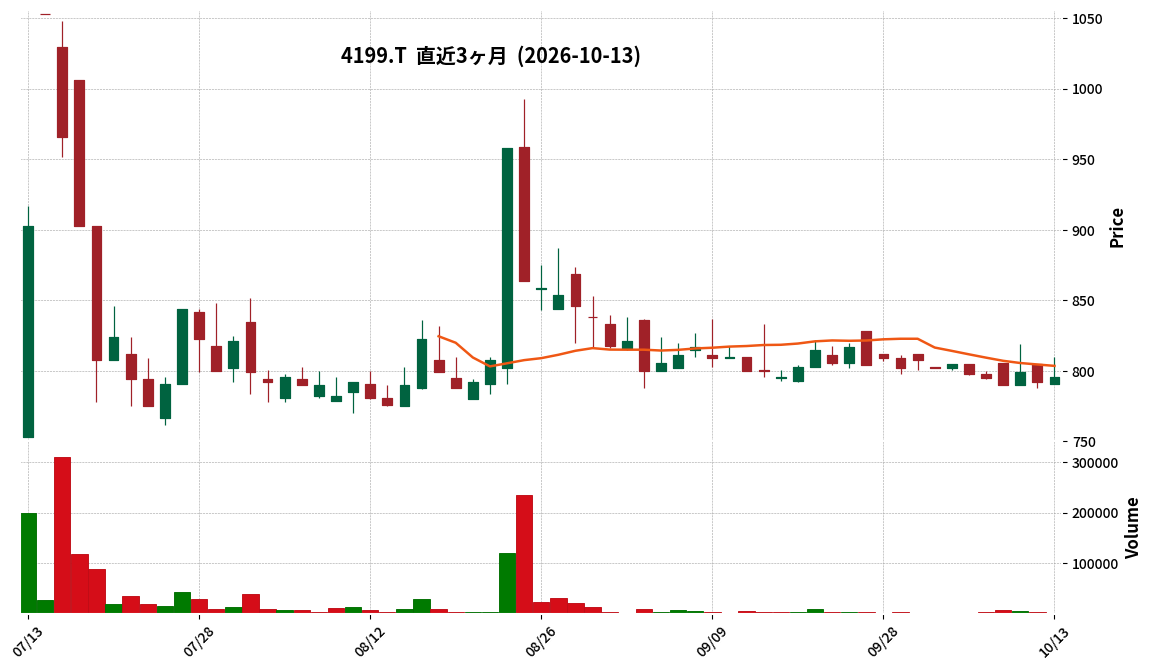
4199|G-ワンプラ
796.0
▲ +0.51%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- G-WonderPlanet (4199) announced its non-consolidated financial results for the fiscal year ended August 2026.
- Net sales were ¥1,944 million, representing a 16.0% decrease compared to the previous fiscal year.
- The company reported an operating loss of ¥162 million, an ordinary loss of ¥182 million, and a net loss of ¥329 million.
- “HUNTER×HUNTER NEN×SURVIVOR” launched on February 18, 2026, contributing to performance, while “JUMP+ JUMBLE RUSH” ceased service on September 17, 2026.
- For the fiscal year ending August 2027, the company forecasts net sales of ¥2,100 million (an 8.0% increase year-on-year), an operating profit of ¥30 million, an ordinary profit of ¥10 million, and a net profit of ¥10 million.
🤖 AI Perspective
G-WonderPlanet’s FY2026 results showed a decline in sales and expanded losses, which appears to be influenced by decreased revenue from existing titles and impairment losses. However, the company is progressing with new IP title development, and the FY2027 forecast anticipates increased sales and a return to profitability, suggesting expectations for new titles. The improving cash flow and potential shifts in the revenue structure due to upcoming new titles are worth monitoring.
4343|イオンファン
2773.0
▲ +3.01%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- AEON Fantasy (4343) reported consolidated results for the second quarter (interim period) of the fiscal year ending February 2027, with net sales of ¥52,374 million (up 12.3% year-on-year), operating profit of ¥4,156 million (up 14.5%), ordinary profit of ¥4,301 million (up 25.9%), and profit attributable to owners of parent of ¥2,155 million (up 22.2%).
- All profit categories achieved record highs for an interim consolidated accounting period.
- The domestic business recorded sales of ¥42,612 million (up 12.9% year-on-year) and operating profit of ¥3,997 million (up 2.4%), marking the fourth consecutive period of record sales and third consecutive period of record operating profit. Existing store sales increased by 6.0% year-on-year, with the capsule toy segment growing by 33.5%.
- The overseas business posted sales of ¥9,911 million (up 10.1% year-on-year) and operating profit of ¥160 million (compared to an operating loss of ¥272 million in the prior year), achieving record sales for an interim consolidated accounting period and returning to profitability.
- The full-year consolidated earnings forecast for the fiscal year ending February 2027 remains unchanged from the most recently published forecast: net sales of ¥98,000 million (up 5.0% year-on-year), operating profit of ¥8,000 million (up 30.8%), ordinary profit of ¥6,300 million (down 14.4%), and profit attributable to owners of parent of ¥3,000 million (up 7.5%).
🤖 AI Perspective
These results highlight a robust performance with record interim sales and profits, significantly driven by the domestic business. The strong performance of existing stores and the strategic expansion of specialized prize stores like “Crane Yokocho Kiwami” appear to be key contributors to domestic growth. The overseas business’s return to profitability could indicate positive effects from its revised strategy, and its continued progress will be worth monitoring.
6076|アメイズ
—
▲ +0.00%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Amaze Inc. announced its unaudited non-consolidated financial results for the third quarter of the fiscal year ending November 2026 (December 1, 2024 to August 31, 2025).
- For the nine-month period, net sales reached ¥16.318 billion, marking a 15.5% increase compared to the same period of the previous fiscal year.
- Operating profit was ¥3.241 billion (+44.4% YoY), ordinary profit ¥2.953 billion (+48.7% YoY), and net profit attributable to owners of parent ¥1.958 billion (+44.6% YoY).
- Earnings per share for the quarter were ¥146.15.
- Total assets at the end of the third quarter stood at ¥32.979 billion, net assets at ¥17.966 billion, and the equity ratio was 54.5%.
- The full-year earnings forecast and dividend forecast (year-end ¥35.00, total ¥35.00) remain unchanged.
- During the third quarter, two new stores, “HOTEL AZ Kagawa Kanonji” and “HOTEL AZ Kagawa Miki,” were opened.
🤖 AI Perspective
Amaze Inc.’s Q3 results demonstrate robust growth across all key financial metrics, with double-digit percentage increases in sales and profits. This strong performance may be attributed to the contribution from two new store openings, improved occupancy rates, and price revisions effectively offsetting rising costs. The unchanged full-year forecasts suggest the company anticipates its current progress aligns with its projections.
6533|オーケストラHD
2201.0
▼ -0.54%
📎 Source:オーケストラHD Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Orchestra Holdings announced on October 13, 2026, that its Board of Directors approved a group reorganization involving three absorption mergers and two absorption demergers among its consolidated subsidiaries.
- This reorganization is contingent upon the scheduled effective date of November 30, 2026, for the complete acquisition of Sharing Innovations through a share exchange.
- The effective date for this reorganization is scheduled for December 1, 2026, and all transactions are non-consideration.
- In the DX business, the entire businesses of SALTO and Nihon Giken Professional Architect, and the SES business of VESS, will be integrated into Sharing Innovations.
- In the Platform business, Sharing Innovations’ Platform business and the entire business of G clef will be integrated into Land Ho.
🤖 AI Perspective
This reorganization aims to integrate and efficiently utilize management resources within the group’s DX and platform businesses. The consolidation of system development functions into Sharing Innovations and the platform business into Land Ho could facilitate quicker decision-making and optimal allocation of resources. This move may indicate an effort to realize early synergies from the planned share exchange.
7073|G-ジェイック
2344.0
▼ -0.30%
📎 Source:G-ジェイック Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- G-JAIC resolved on October 13, 2026, at its Board of Directors meeting, to acquire all shares of Axia Co., Ltd., making it a subsidiary.
- Axia Co., Ltd., established on February 16, 2006, is based in Chiyoda-ku, Tokyo, and primarily engages in contract system development. Its representative is Ayumi Yonemura.
- The number of shares acquired is 190, resulting in G-JAIC owning 190 shares (100% voting rights) after the transaction.
- The share transfer is scheduled to be executed on November 1, 2026.
- This disclosure is voluntary, deemed useful for investment decisions, although it does not meet the criteria for timely disclosure regulations.
- Axia’s financial performance for the most recent fiscal year (ended March 2026) showed sales of 113,683 thousand yen, operating income of 14,676 thousand yen, and net income of 11,812 thousand yen.
🤖 AI Perspective
G-JAIC’s acquisition of Axia appears to leverage its existing SME client base from its education-integrated human resource introduction business with Axia’s system development capabilities, aiming for stable orders and business growth. The move may suggest G-JAIC’s strategic focus on expanding into AI implementation support for SMEs, a segment where Axia’s expertise in AI-driven development and “zero overtime” work reforms could provide a competitive edge. Investors might monitor how these combined strengths translate into new service offerings and operational synergies within the enlarged group.
7085|カーブスHD
954.0
▲ +2.80%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Curves Holdings announced its consolidated financial results for the fiscal year ended August 31, 2026 (September 1, 2025, to August 31, 2026).
- Consolidated net sales reached ¥43,387 million (up 15.5% year-on-year), operating profit was ¥7,755 million (up 22.3%), ordinary profit was ¥7,573 million (up 16.8%), and profit attributable to owners of parent was ¥4,908 million (up 14.1%), all setting new record highs.
- Earnings per share (EPS) for the period was ¥53.56, and the annual dividend per share totaled ¥30.00 (consisting of an ordinary dividend of ¥10.00 and a commemorative dividend of ¥10.00 for the fiscal year-end), a significant increase from ¥17.00 in the previous year.
- As of August 31, 2026, the number of “Curves for women only 30-minute fitness” domestic stores increased by 17 to 2,013, and membership grew by 32,000 to 895,000, both representing record highs at the end of the consolidated fiscal year.
- For the fiscal year ending August 31, 2027, the company forecasts consolidated net sales of ¥46,000 million (up 6.0% year-on-year), operating profit of ¥8,700 million (up 12.2%), profit attributable to owners of parent of ¥5,455 million (up 11.1%), and EPS of ¥61.23.
🤖 AI Perspective
Curves Holdings’ FY2026 results demonstrate robust business growth, with record highs in sales, profits, membership, and store count. This performance appears to be driven by successful new member acquisition campaigns, a price revision for existing members’ fees, and an expansion of merchandise sales to members. The significant increase in the annual dividend payment could indicate a strong commitment to shareholder returns, which may be a point of interest for investors.
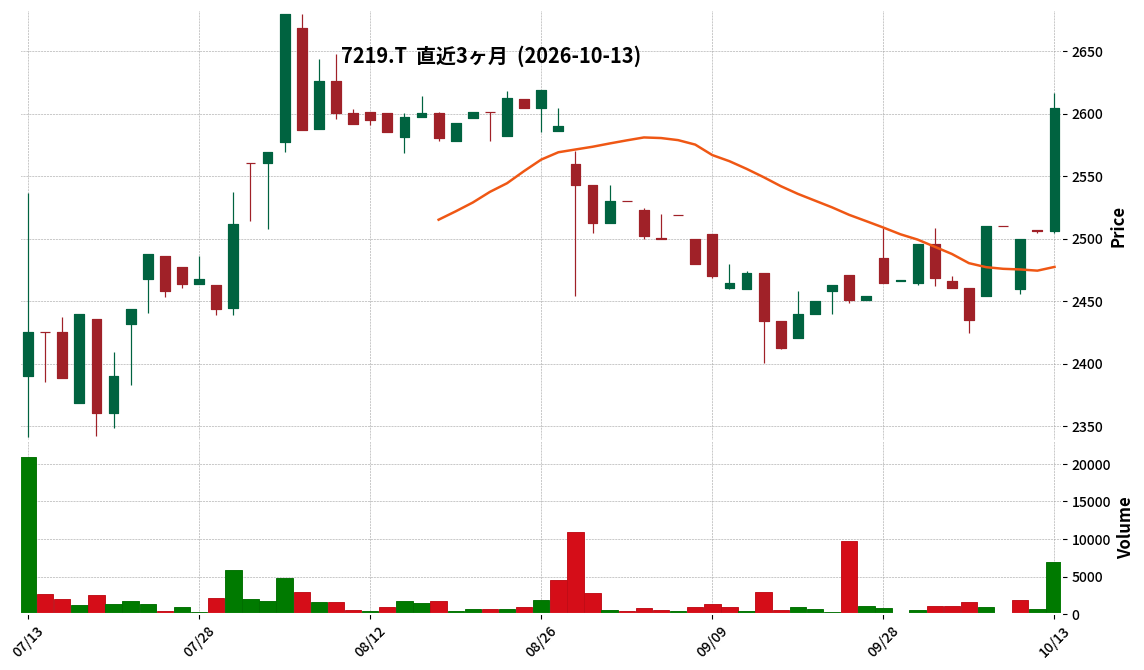
7219|HKS
2605.0
▲ +3.95%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- HKS Co., Ltd. has decided to increase its year-end dividend for the fiscal year ending August 31, 2026.
- The dividend per share for the fiscal year ending August 2026 will be 107.00 yen, an increase of 42 yen from the previously forecast 65.00 yen.
- The total dividend amount is announced as 151,389,271 yen.
- The effective date for the dividend is November 30, 2026.
- The source of the dividend is retained earnings.
🤖 AI Perspective
This dividend increase suggests that the company prioritizes shareholder returns and has considered its recent business performance. The significant upward revision from the previous dividend forecast could indicate the company’s confidence in its future earnings, which may be a point of interest for investors.
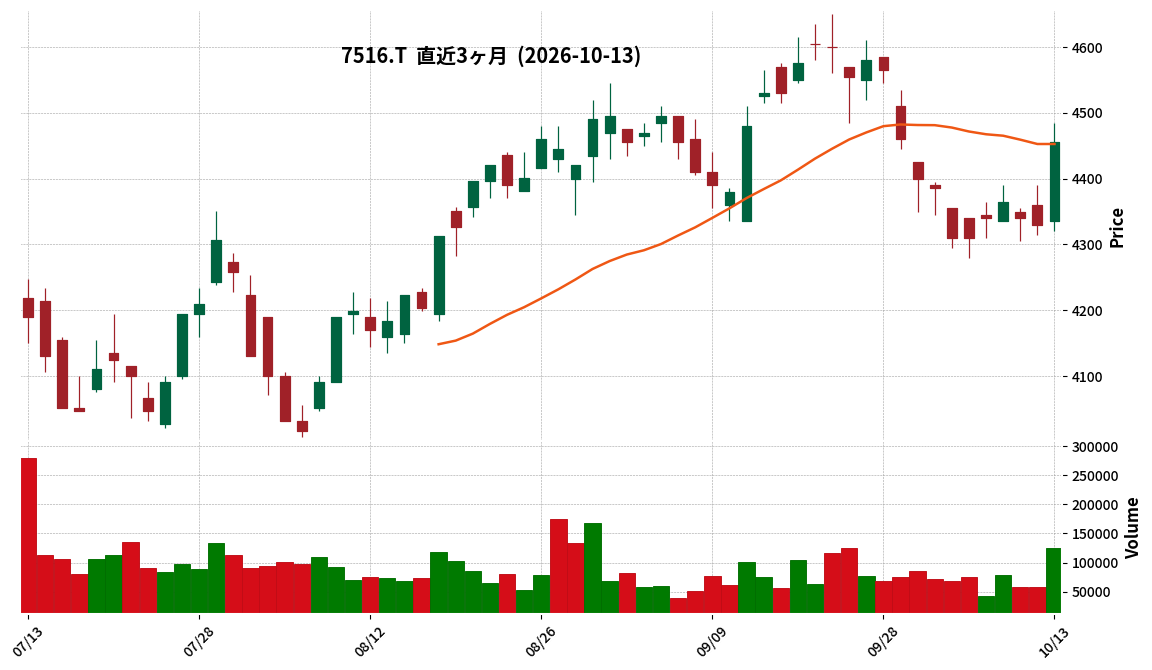
7516|コーナン商
4455.0
▲ +2.89%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Kohnan Shoji Co., Ltd. announced its consolidated financial results for the second quarter (interim period) of the fiscal year ending February 2027.
- Interim operating revenue reached ¥287,135 million, representing an 8.3% increase compared to the same period of the previous year.
- Operating profit was ¥17,662 million (up 20.1% year-on-year), ordinary profit was ¥16,435 million (up 19.7%), and profit attributable to owners of parent was ¥10,364 million (up 18.8%).
- Diluted earnings per share for the interim period stood at ¥365.55.
- The forecast for the annual dividend per share is ¥140.00 (interim: ¥70.00, year-end: ¥70.00), with no revisions from the latest publicly announced dividend forecast.
- The consolidated full-year forecast for the fiscal year ending February 2027 remains unchanged, with projected operating revenue of ¥543,500 million, operating profit of ¥23,000 million, ordinary profit of ¥21,000 million, and profit attributable to owners of parent of ¥12,500 million.
- During this interim consolidated accounting period, Alenza Holdings Co., Ltd. became a new equity-method affiliate, and the total number of group stores at the end of the period was 679.
🤖 AI Perspective
Kohnan Shoji’s Q2 FY2027 results indicate strong performance with significant year-on-year increases across key revenue and profit metrics. The double-digit growth in operating revenue and various profit categories may suggest effective business strategies or favorable market conditions. The decision to maintain the full-year forecast could imply management’s confidence in achieving the previously set targets based on current progress.
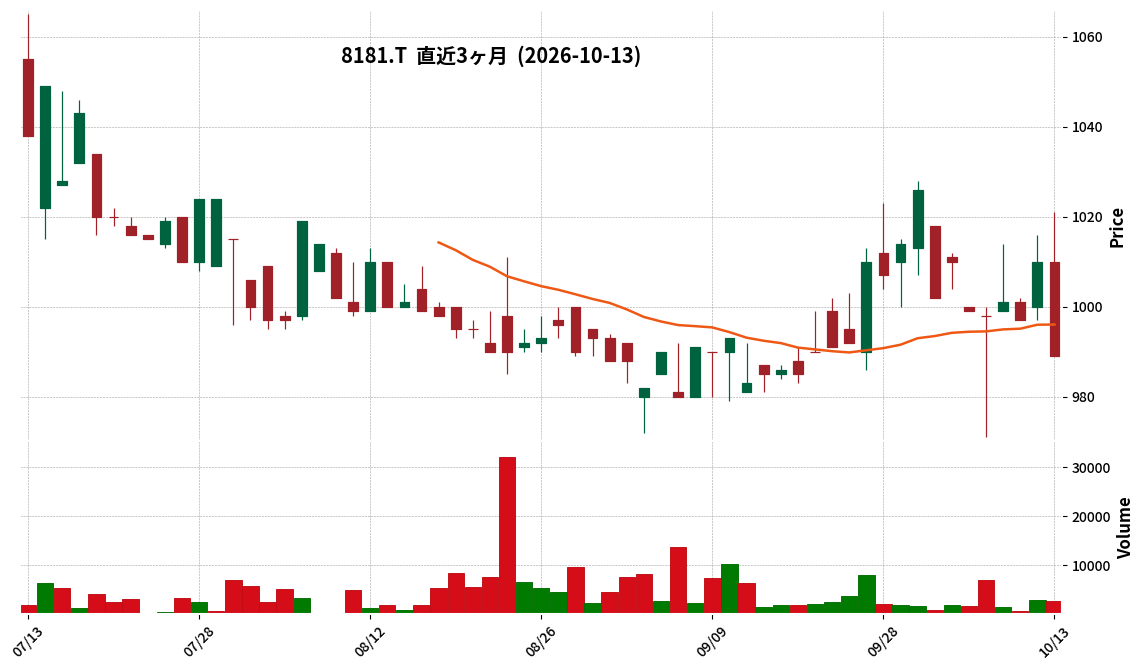
8181|東天紅
989.0
▼ -2.08%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Totenko announced its Q2 FY2027 (interim) financial results for the period from March 1, 2026, to August 31, 2026.
- Net sales for the interim period reached ¥2.182 billion, marking a 0.6% increase compared to the previous interim period.
- Operating income was ¥131 million (down 10.9% year-on-year), ordinary income was ¥113 million (down 10.8% year-on-year), and interim net income was ¥107 million (down 10.4% year-on-year).
- Total assets stood at ¥10.977 billion, net assets at ¥7.515 billion, and the equity ratio was 68.5%.
- The full-year earnings forecast (sales ¥4.900 billion, operating income ¥525 million, ordinary income ¥485 million, net income ¥455 million) remains unchanged from the most recently published forecast.
🤖 AI Perspective
Totenko’s Q2 results show a mixed performance with increased sales but decreased profits, which the company attributes to increased cost burden from store renovation investments aimed at future growth. The decline in the restaurant business segment’s profit while the rental business segment saw an increase may indicate ongoing strategic shifts or differing market conditions across its operations. Investors may want to monitor how these investments translate into future profitability.
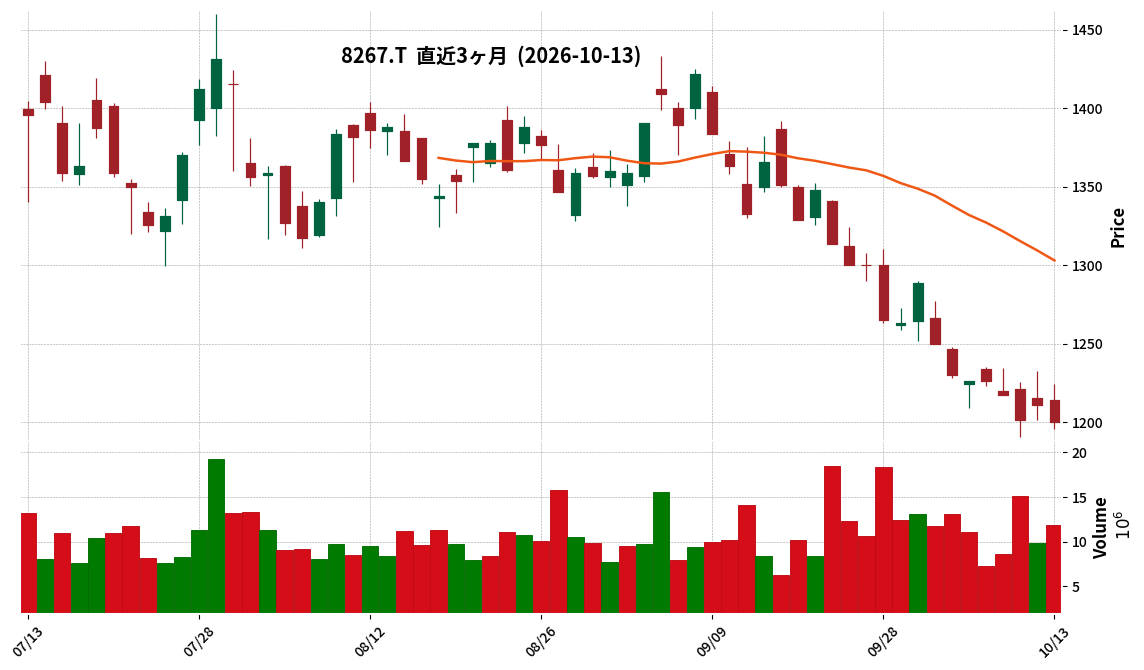
8267|イオン
1200.0
▼ -0.91%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- AEON reported record-high operating revenue of ¥5,904.1 billion (up 13.8% YoY) and operating profit of ¥130.7 billion (up 10.7% YoY) for the first half of fiscal year 2027.
- Net profit attributable to parent company increased by 229.1% year-on-year, reaching ¥13.3 billion.
- Key segments driving consolidated performance were Health & Wellness (operating profit ¥59.6 billion, up 162.9% YoY), Developer & Entertainment (¥54.2 billion, up 32.3% YoY), and International business (¥5.6 billion, up 15.0% YoY).
- The Health & Wellness segment saw significant profit growth primarily due to the consolidation of Tsuruha Holdings, with synergies reaching approximately ¥8.5 billion in H1, representing about 57% of the annual target of ¥15.0 billion.
- The Developer & Entertainment segment, including AEON Mall, reported increased revenue and profit both domestically and internationally, with domestic existing AEON Mall specialty store sales up 104.7% YoY. Overseas operating profit for this segment grew by 30.4% in general, 60.3% in China, and 36.8% in Vietnam.
🤖 AI Perspective
This earnings report suggests that strategic business structure reforms, including the consolidation of Tsuruha Holdings, significantly contributed to consolidated performance. The strong performance of the designated growth drivers—Health & Wellness, Developer & Entertainment, and ASEAN businesses—in achieving record consolidated results is particularly noteworthy. Moving forward, the progress of profitability reforms in the food retail business and further realization of synergies, including the “Drug & Food Model,” could be key areas for investors to monitor.
8273|イズミ
933.0
▼ -0.21%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
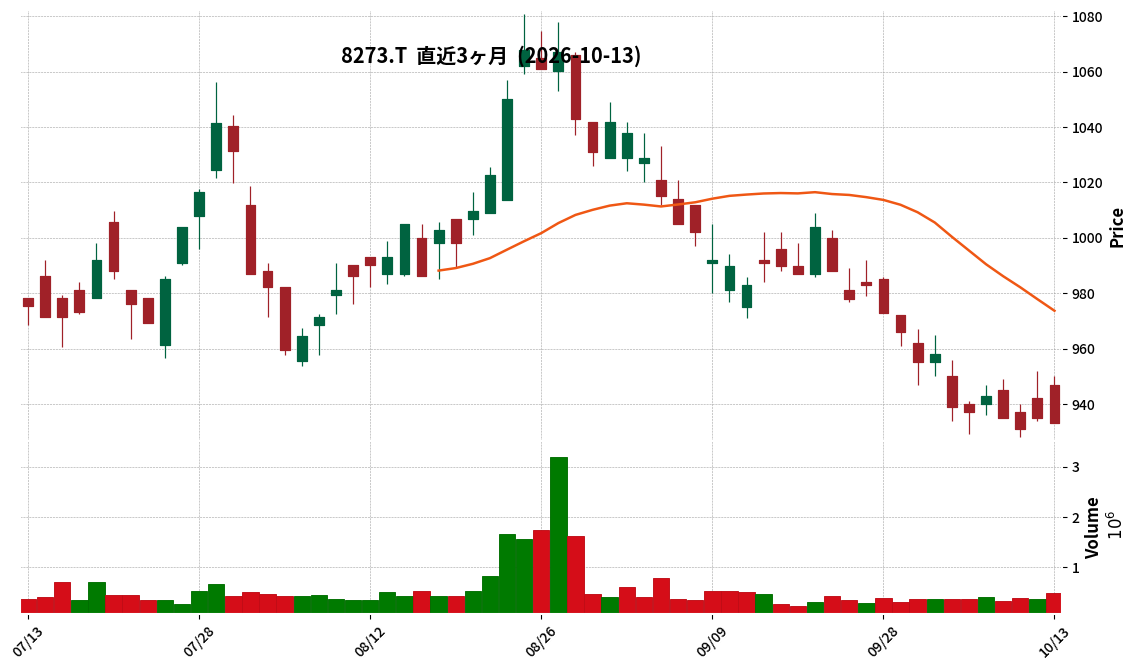
- Izumi Co., Ltd. announced its consolidated financial results for the second quarter of the fiscal year ending February 2027 (March 1, 2026 – August 31, 2026).
- Consolidated operating revenue reached 283,437 million yen, marking a 0.9% increase compared to the previous year’s interim period.
- Consolidated operating income was 13,271 million yen, an increase of 4.6% year-on-year for the interim period.
- Net income attributable to owners of parent totaled 8,426 million yen, up 4.2% from the prior year’s interim period.
- The consolidated full-year business forecast for the fiscal year ending February 2027 and the annual dividend forecast (interim ¥15, year-end ¥15, total ¥30) remain unchanged from the most recently announced figures.
🤖 AI Perspective
Izumi’s second-quarter results show steady growth in both revenue and profit, indicating resilience in its business operations amidst challenging market conditions. The reaffirmation of the full-year forecasts suggests that the company’s management considers the current performance to be in line with their initial expectations. Investors may consider these results when evaluating the company’s operational stability.
8904|AVANTIA
828.0
▲ +0.24%
📎 Source:AVANTIA Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
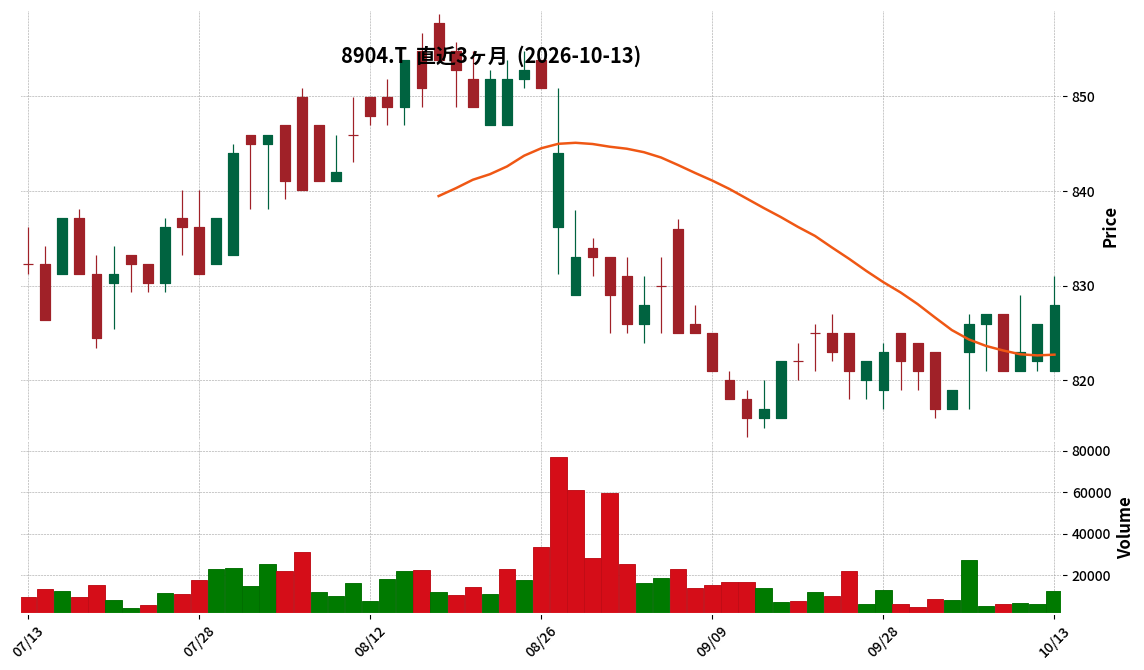
- AVANTIA Co., Ltd. reported consolidated results for the fiscal year ended August 2026, with net sales of ¥67,888 million (down 2.0% year-on-year), operating profit of ¥2,008 million (up 52.9% year-on-year), ordinary profit of ¥1,715 million (up 49.7% year-on-year), and profit attributable to owners of parent of ¥1,423 million (up 122.6% year-on-year).
- Basic earnings per share were ¥98.31 (compared to ¥44.39 in the previous fiscal year).
- The consolidated equity ratio increased to 40.1% (from 39.4% in the previous fiscal year).
- Cash flows included ¥△1,240 million from operating activities, ¥△1,009 million from investing activities, and ¥△356 million from financing activities, resulting in a cash and cash equivalents balance of ¥14,513 million at the end of the period (compared to ¥18,130 million in the previous fiscal year).
- For the fiscal year ending August 2027, the company forecasts consolidated net sales of ¥75,000 million (up 10.5% year-on-year), operating profit of ¥2,300 million (up 14.5% year-on-year), ordinary profit of ¥1,800 million (up 4.9% year-on-year), and profit attributable to owners of parent of ¥1,050 million (down 26.2% year-on-year).
- The annual dividend is expected to be maintained at ¥38.00 (¥19.00 per year-end dividend) for both the fiscal year ended August 2026 and the forecast for August 2027.
🤖 AI Perspective
AVANTIA’s FY2026 results show a significant increase in profits, including operating profit, ordinary profit, and profit attributable to owners of parent, despite a slight decline in net sales. This may suggest that the company’s focus on “improving profitability” under its medium-term management plan has been effective. However, the FY2027 consolidated earnings forecast anticipates a decrease in profit attributable to owners of parent, even with an expected increase in net sales, which could indicate a shift in profit dynamics that investors may want to monitor.
2769|ヴィレッジV
938.0
▼ -0.21%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
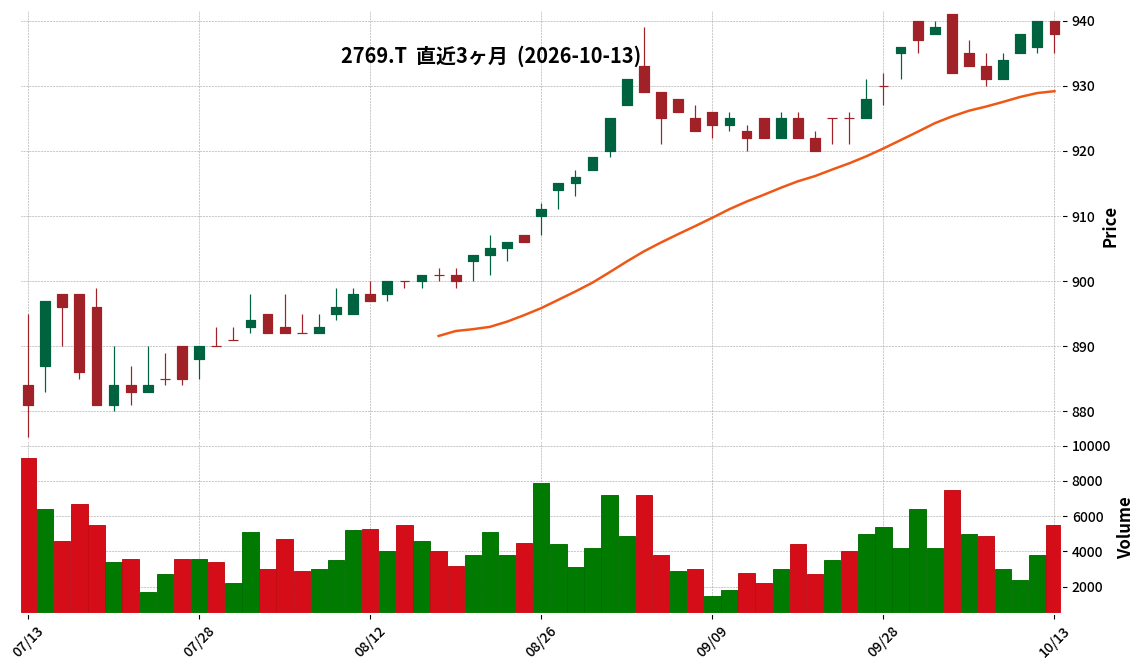
- Village Vanguard Co., Ltd. announced its unaudited consolidated financial results for the first quarter of the fiscal year ending May 2027 on October 13, 2026.
- For the first quarter (June 1, 2026 – August 31, 2026), consolidated net sales totaled ¥5,264 million, a decrease of 7.1% compared to the same period of the previous year.
- Operating profit was ¥127 million (down 27.1% YoY) and ordinary profit was ¥107 million (down 47.5% YoY).
- Net profit attributable to owners of the parent reached ¥27 million (down 86.2% YoY), resulting in basic earnings per share of ¥△0.38.
- The full-year consolidated earnings forecast for the fiscal year ending May 2027 remains unchanged, projecting net sales of ¥21,881 million (down 6.3% YoY) and net profit attributable to owners of the parent of ¥126 million (down 82.8% YoY).
🤖 AI Perspective
Village Vanguard’s Q1 FY2027 results show a year-over-year decline across key financial metrics, including a significant drop in net profit attributable to owners of the parent. However, the company has maintained its full-year earnings forecast, which may suggest management’s confidence in achieving its annual targets despite the softer start to the fiscal year. Investors may wish to monitor the company’s performance in subsequent quarters to assess the trajectory towards its full-year projections.
Disclaimer: This article is for informational purposes only and does not constitute investment advice.
2338|クオンタムS
100.0
▼ -0.99%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
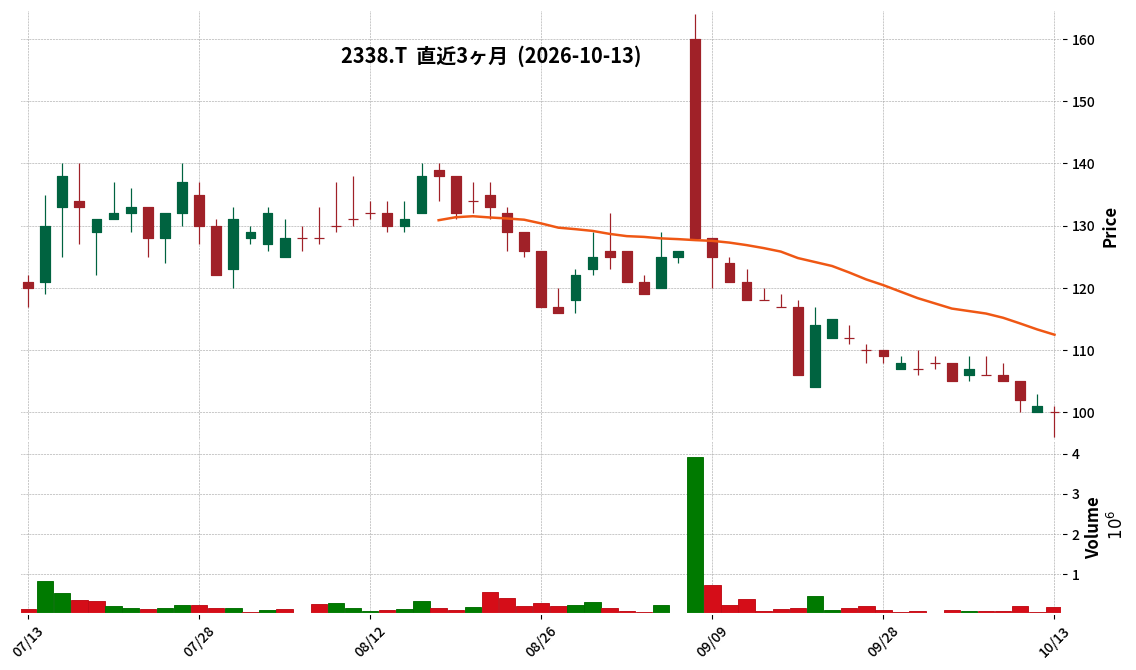
- Quantum Solutions Co., Ltd. announced its consolidated financial results for the second quarter (interim period) of the fiscal year ending February 2027.
- Net sales amounted to ¥109 million (down 20.3% year-on-year), operating loss was ¥354 million (compared to an operating loss of ¥240 million in the prior year’s interim period), ordinary loss was ¥178 million, and net loss attributable to parent company shareholders was ¥146 million.
- Net sales for the AI Solutions business segment were ¥36 million (down 43.6% year-on-year), resulting in a segment loss of ¥200 million.
- In the AIDC business, an agreement for securing data center capacity in Japan was reached, and a deposit was paid; however, the sales agreement for GPU equipment was terminated by mutual consent, and re-ordering negotiations are ongoing.
- The consolidated earnings forecast for the fiscal year ending February 2027 is currently undisclosed due to rapid changes in the business environment.
🤖 AI Perspective
The latest financial results for Quantum S indicate a continued decline in net sales and ongoing losses. The progress of GPU equipment procurement for the AIDC business appears to be a critical factor for future business development, which investors may wish to monitor closely. The non-disclosure of the full-year earnings forecast also suggests a high degree of business uncertainty.
2736|フェスタリアHD
589.0
▼ -1.01%
📎 Source:フェスタリアHD Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Festaria Holdings announced its consolidated financial results for the fiscal year ended August 31, 2026.
- Sales revenue for the period increased by 9.7% year-on-year to ¥10,315 million.
- Operating profit decreased by 17.2% to ¥239 million, and ordinary profit decreased by 5.1% to ¥270 million.
- Net profit attributable to owners of the parent company fell by 35.7% to ¥113 million.
- Earnings per share (EPS) for the period were ¥31.70 (compared to ¥49.48 in the prior period).
- For the fiscal year ending August 31, 2027, the company forecasts consolidated sales revenue of ¥10,600 million (+2.8% YoY), operating profit of ¥350 million (+46.0% YoY), and net profit of ¥170 million (+49.8% YoY).
- The annual dividend per share for both FY2026 and FY2027 (forecast) is ¥7.00.
🤖 AI Perspective
The FY2026 results indicate that while sales revenue grew, profitability was impacted, possibly due to higher raw material costs such as gold and platinum. However, the strong growth in e-commerce sales and the affluent business segment suggest a shift in the company’s business focus. The substantial recovery in profit forecasted for the next fiscal year could indicate the anticipated positive impact of these strategic initiatives.
3121|マーチャント
248.0
▼ -0.80%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- MBK Partners Inc. announced a business alliance agreement with AI TECHNOLOGY Inc. and TIGEREYE Co., Ltd., signed on October 13, 2026.
- The alliance aims to create “next-generation real estate businesses utilizing AI cameras and facial recognition technology,” combining AI TECHNOLOGY’s AI security cameras and TIGEREYE’s facial recognition and AI technology.
- Specific applications include facial recognition-based entry/exit management for condominiums/offices, enhanced building security with AI cameras, AI-driven anomaly detection and facility management, and development of smart condominiums and offices.
- MBK Partners acquired 21.0% of TIGEREYE’s issued shares in July 2026, making it an equity-method affiliate.
- The original plan to establish a joint venture with AI TECHNOLOGY was changed to this business alliance agreement after further discussions.
🤖 AI Perspective
This business alliance suggests MBK Partners is leveraging its strengths as an investment firm in the real estate sector by integrating AI camera technology from AI TECHNOLOGY and facial recognition/AI technology from TIGEREYE, aiming to create new business domains. The focus on developing “AI-native real estate” from the planning and development stages, rather than merely introducing AI devices to existing properties, may suggest a commitment to long-term real estate value enhancement. Given that TIGEREYE is an equity-method affiliate of MBK Partners, the potential for reinforced group-wide collaboration is also worth monitoring.
4264|G-セキュア
1392.0
▼ -1.49%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- G-Secure announced on October 13, 2026, its resolution to acquire all shares of Nittsu Tsushin Corporation, making it a subsidiary.
- Nittsu Tsushin, established in 1971, is a telecommunications system design, construction, and electrical engineering company with a network across the Tohoku region and holds an S-rank bidding qualification for electrical telecommunication works in Miyagi Prefecture.
- G-Secure will acquire 65,200 shares, representing 100.0% of the voting rights. The acquisition price for Nittsu Tsushin’s common shares is ¥1,405 million, with an estimated total of ¥1,423 million including advisory fees.
- The acquisition funds of ¥1,405 million will be procured through a loan from Mizuho Bank, with a scheduled execution date of December 18, 2026, and a repayment date of November 30, 2033.
- The share transfer is scheduled to be completed on December 18, 2026.
🤖 AI Perspective
This acquisition appears to be a strategic move by G-Secure to strengthen its physical security system business in the Tohoku region, aiming to accelerate local expansion by enhancing sales, construction, and maintenance capabilities. The integration of Nittsu Tsushin’s public sector and major client base, along with its skilled personnel, could indicate an effort to improve the group’s overall technical capabilities and expand its order capture domain. Financially, the acquisition is being funded by a loan from Mizuho Bank, with expectations for it to contribute to G-Secure’s performance from the fiscal year ending December 2027 onwards.
615A|P-インターパーク
305.0
▲ +0.00%
📎 Source:P-インターパーク Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- For the fiscal year ended August 2026, net sales were ¥821 million, marking a 10.3% increase year-on-year.
- Operating profit decreased by 22.1% to ¥19 million.
- Ordinary profit decreased by 21.9% to ¥20 million.
- Net profit for the period decreased by 48.6% to ¥15 million.
- Earnings per share (EPS) were ¥9.52, and the equity ratio was 5.1%.
- For the fiscal year ending August 2027, the company forecasts net sales of ¥912 million (up 11.1% YoY), operating profit of ¥40 million (up 114.8% YoY), ordinary profit of ¥41 million (up 107.1% YoY), and net profit of ¥27 million (up 78.9% YoY).
🤖 AI Perspective
P-Interpark achieved revenue growth in the fiscal year ended August 2026, yet reported declines in various profit metrics. This suggests that the company’s strategic investments in human resources, sales infrastructure, and the development of new AI-powered features, aimed at strengthening long-term competitiveness, may have impacted short-term profitability. Looking ahead, the significant projected increases in sales, operating profit, ordinary profit, and net profit for the next fiscal year could indicate that these upfront investments are expected to yield positive returns in the upcoming period.
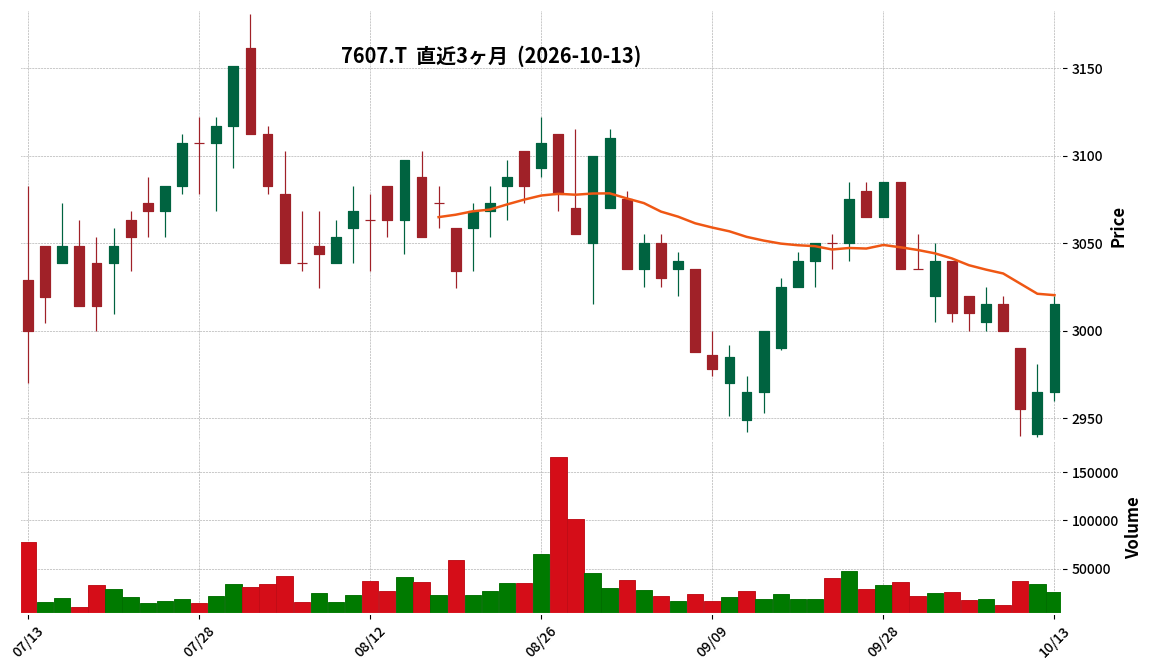
7607|進和
3015.0
▲ +1.69%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Shinwa Co., Ltd. announced its consolidated financial results for the fiscal year ended August 2026.
- Sales revenue for the period reached ¥87,512 million, representing a 1.6% increase compared to the previous consolidated fiscal year.
- Operating profit was ¥4,448 million (down 1.9% year-on-year), ordinary profit was ¥4,703 million (down 2.2% year-on-year), and profit attributable to owners of parent was ¥3,269 million (down 1.3% year-on-year).
- Earnings per share for the period were ¥243.80.
- For the fiscal year ending August 2027, the company forecasts consolidated sales revenue of ¥88,000 million (up 0.6% year-on-year), ordinary profit of ¥4,730 million (up 0.6% year-on-year), and profit attributable to owners of parent of ¥3,280 million (up 0.3% year-on-year).
- The annual dividend per share was ¥124 for FY2026 and is forecast at ¥128 for FY2027.
🤖 AI Perspective
Shinwa’s FY2026 results show a modest increase in sales revenue but a slight decline in profitability. This could be attributed to factors such as resilient capital expenditure demand from the automotive industry, yet tempered by delays or reductions in large-scale equipment projects and increased related costs, as well as a rebound effect from highly profitable projects in the prior period. Looking ahead, the company’s FY2027 forecast projects increases in both revenue and profit, which may suggest a potential recovery or improved outlook.
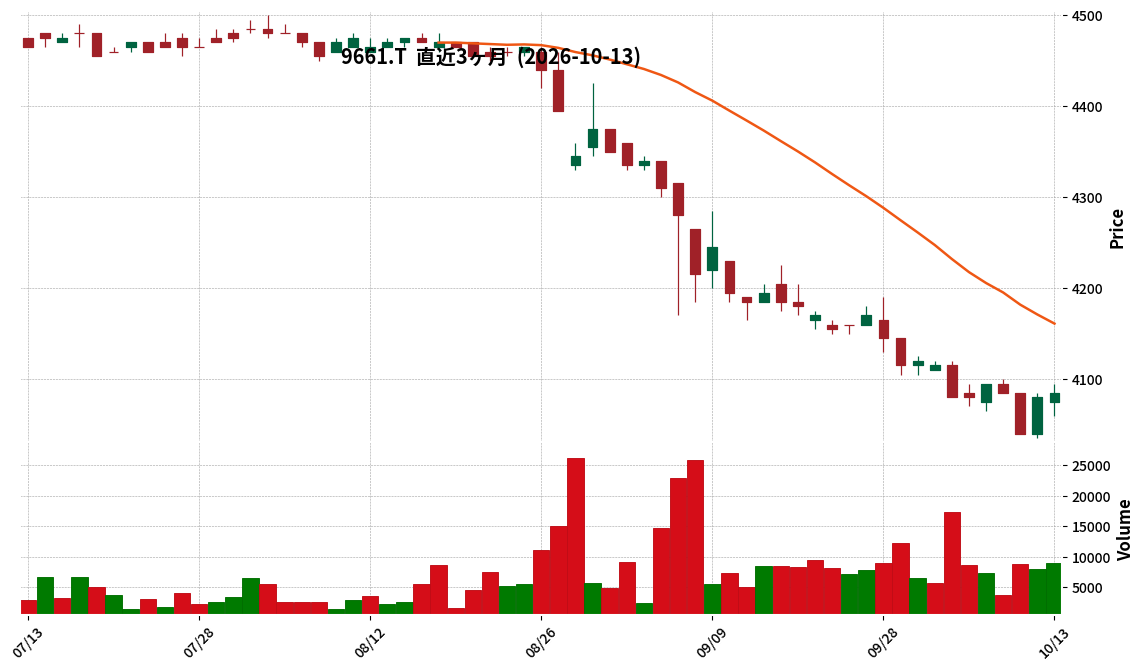
9661|歌舞伎
4085.0
▲ +0.12%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Kabuki-za Co., Ltd. announced its consolidated financial results for the second quarter (interim period) of the fiscal year ending February 2027.
- Total net sales for the interim period amounted to ¥1,830 million, an increase of 2.4% compared to the same period of the previous year.
- Operating profit was ¥183 million (down 15.2% year-on-year), ordinary profit was ¥213 million (down 10.9% year-on-year), and net profit attributable to owners of parent was ¥157 million (down 15.9% year-on-year).
- By segment, the shop business recorded sales of ¥437 million (up 12.4% year-on-year) and segment profit of ¥96 million (up 5.5% year-on-year).
- The real estate rental business reported sales of ¥1,002 million (down 0.8% year-on-year) and segment profit of ¥313 million (down 6.2% year-on-year), while the restaurant and food service business recorded sales of ¥391 million (up 0.6% year-on-year) and segment profit of ¥29 million (down 24.3% year-on-year).
- The full-year consolidated earnings forecast remains unchanged from the most recently announced figures: sales of ¥3,697 million (up 1.8% year-on-year), operating profit of ¥339 million (down 10.3% year-on-year), and net profit attributable to owners of parent of ¥237 million (down 16.5% year-on-year).
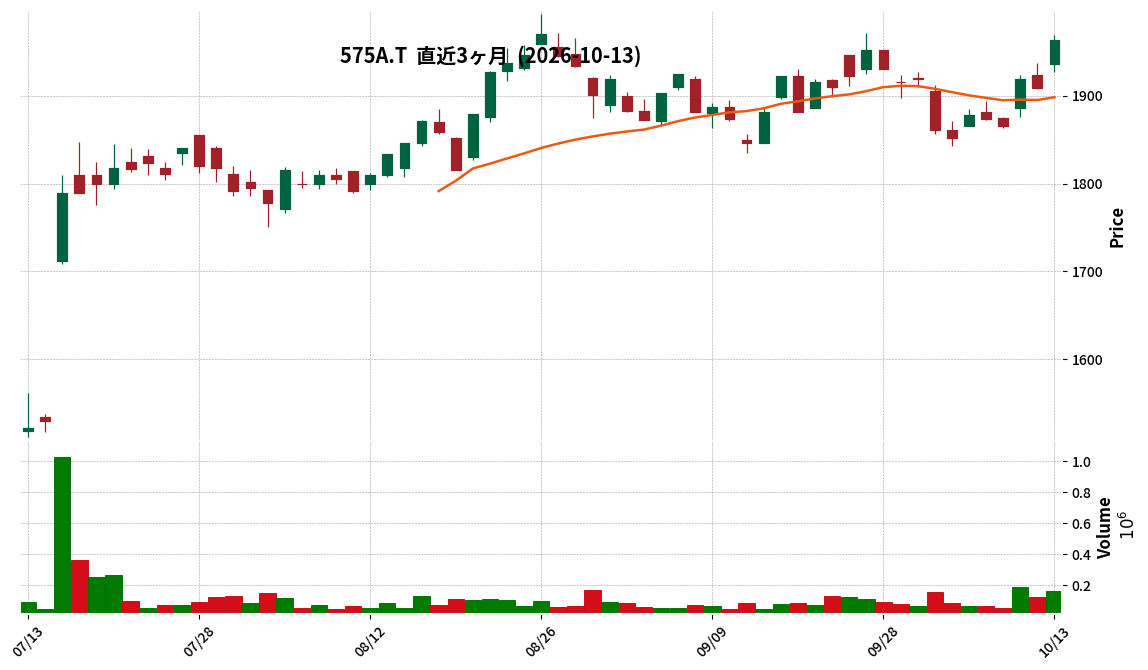
575A|前澤HD
1963.0
▲ +2.83%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Maezawa Holdings Co., Ltd. announced its consolidated financial results for the first quarter of the fiscal year ending March 2027 (June 1, 2026 – August 31, 2026).
- As the company was established on June 1, 2026, through a joint share transfer, there are no comparative figures for the prior fiscal year or the same quarter of the prior year.
- Consolidated operating results show net sales of ¥11,527 million, operating profit of ¥168 million, ordinary profit of ¥406 million, and net income attributable to parent company of ¥14,500 million.
- The net income attributable to parent company includes an extraordinary gain of ¥14,584 million from negative goodwill, recognized as a result of the business integration.
- The full-year consolidated earnings forecast remains unchanged from the most recently published figures: net sales of ¥55,000 million, operating profit of ¥6,600 million, ordinary profit of ¥7,100 million, net income attributable to parent company of ¥19,200 million, and basic earnings per share of ¥602.11.
🤖 AI Perspective
This report marks the first quarterly financial disclosure for Maezawa Holdings since its establishment via joint share transfer. The significant contribution of negative goodwill to net income is an accounting outcome of the business integration. Investors may want to monitor the performance of each segment and the progress toward realizing synergies from the integration in future periods.
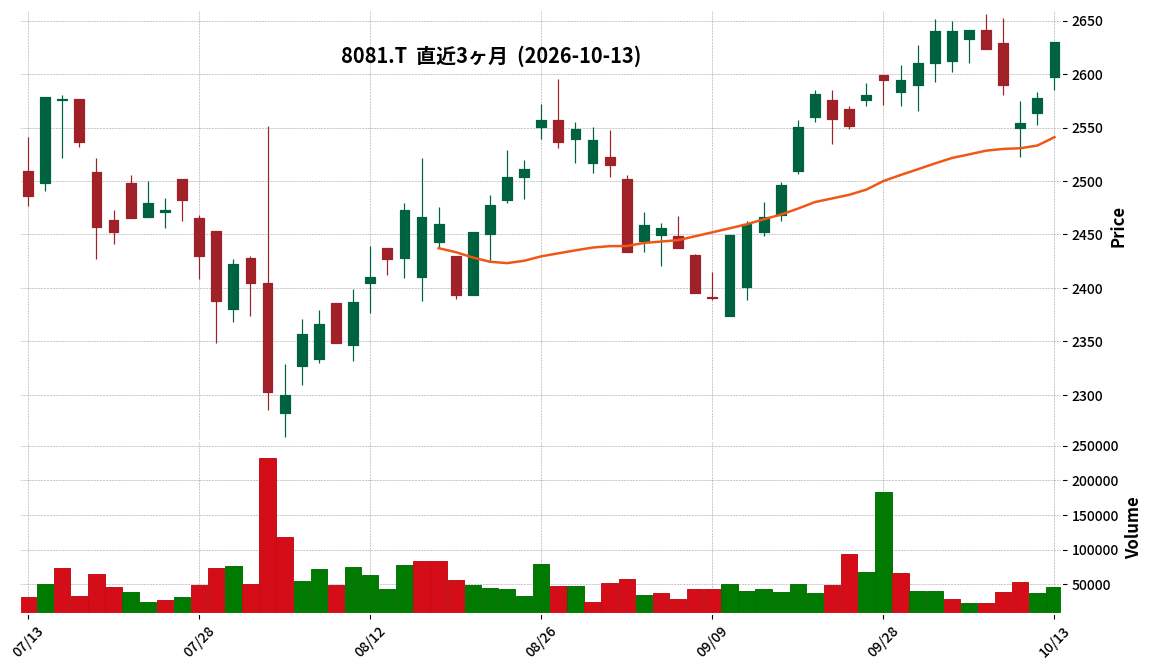
8081|カナデン
2630.0
▲ +2.02%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Kanaden Corporation announced on October 13, 2026, an upward revision to its consolidated financial forecast for the second quarter (interim) of the fiscal year ending March 2027.
- The revised forecast for the interim period includes net sales of 69,300 million yen (an increase of 10.0% from the previous forecast), operating profit of 1,950 million yen (an increase of 14.7%), ordinary profit of 2,100 million yen (an increase of 16.7%), and net income attributable to owners of parent of 1,400 million yen (an increase of 16.7%).
- The primary reasons for the revision are the strong performance in the FA System business, specifically in semiconductor manufacturing equipment and power receiving/distributing panels, and the Building Facility business, particularly in power supply equipment for data centers, driven by robust AI and data center demand.
- The Semiconductor & Device business also contributed positively, with strong sales of Wi-Fi modules for household electrical appliances.
- The consolidated full-year financial forecast for the fiscal year ending March 2027 is currently under review and remains unchanged from the figures announced on May 13, 2026.
🤖 AI Perspective
This upward revision suggests that specific market trends and product demands within certain business segments are directly impacting the company’s performance. The robust demand related to AI and data centers, in particular, may be a key factor for investors to monitor when evaluating Kanaden’s future business trajectory. The ongoing review of the full-year forecast indicates that further updates may be forthcoming, which could provide additional insights for investors.
3647|アスリナ
111.0
▼ -0.89%
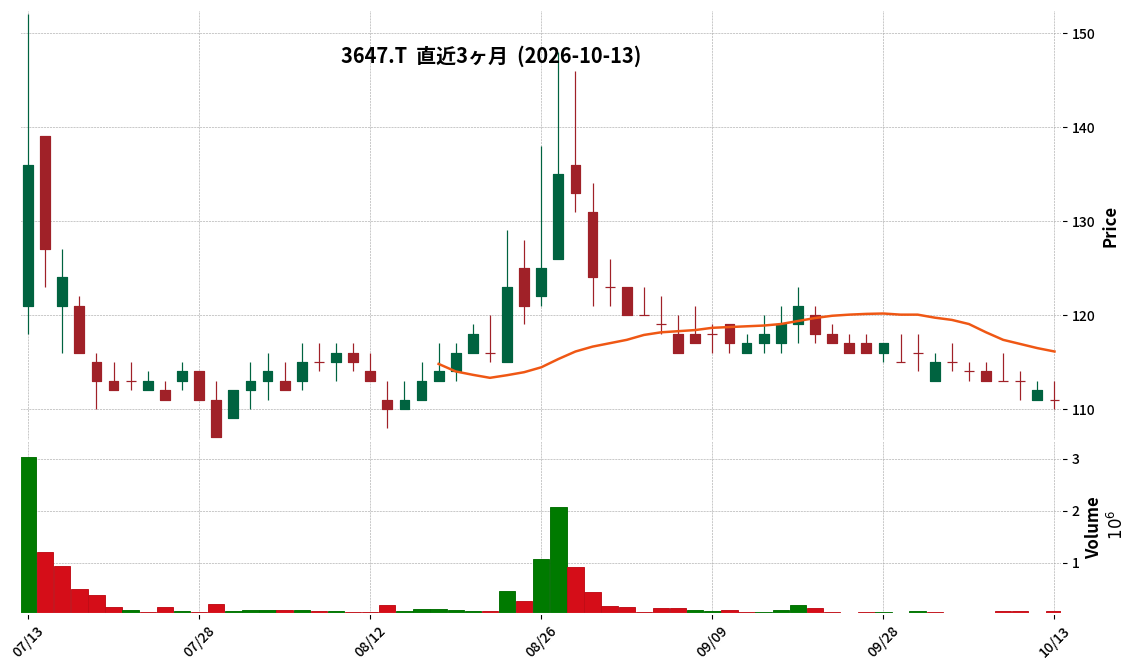
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Asrina Co., Ltd. announced a partial correction to its “Consolidated Financial Results for the Third Quarter of the Fiscal Year Ending August 31, 2026 (Japanese GAAP)” on October 13, 2026.
- The correction addresses certain discrepancies identified in the financial results originally disclosed on July 14, 2026.
- The specific amendments are made within the “Consolidated Quarterly Balance Sheet” on page 5 of the attached document, affecting the “Tangible Fixed Assets” and “Intangible Fixed Assets” sections under “Assets.”
- Specifically, “Lease assets (net)” amounting to ¥20,888 thousand were moved from “Tangible Fixed Assets” to “Intangible Fixed Assets.”
- This correction has no impact on the company’s profit or loss.
🤖 AI Perspective
This correction primarily involves a reclassification of lease assets from tangible to intangible fixed assets, with no change to the total asset value or the company’s profitability. For investors, this suggests that while the original presentation had a categorisation issue, the underlying financial health as reflected in the profit and loss remains consistent. It is generally prudent for companies to ensure accurate financial reporting, and this type of correction clarifies the asset structure.
4920|日本色材
1114.0
▼ -1.24%
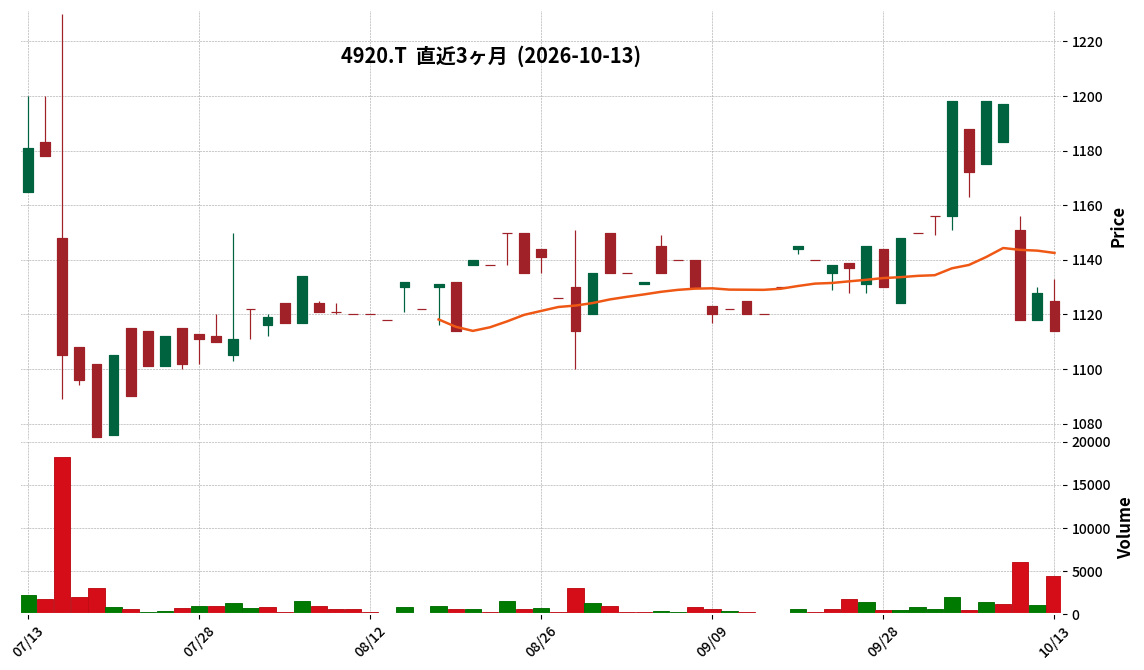
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- Nippon Shikizai Kogyo Kenkyusho Co., Ltd. announced its consolidated financial results for the second quarter (interim period) of the fiscal year ending February 2027.
- Consolidated net sales for the interim period reached ¥9,155 million, representing a 14.0% increase compared to the previous interim period.
- Consolidated operating profit was ¥50 million, a 54.4% decrease year-on-year for the interim period.
- The company reported an ordinary loss of ¥14 million (compared to a profit of ¥90 million in the previous interim period) and a net loss attributable to owners of parent of ¥21 million (compared to a profit of ¥49 million in the previous interim period).
- The full-year consolidated earnings forecast remains unchanged, projecting net sales of ¥18,328 million, operating profit of ¥261 million, ordinary profit of ¥116 million, and net profit attributable to owners of parent of ¥100 million.
🤖 AI Perspective
While Nippon Shikizai’s net sales saw a significant increase, the substantial decline in operating profit and the shift to ordinary and net losses suggest a squeeze on profitability, possibly due to rising raw material and labor costs. The performance of its domestic business and the effectiveness of cost pass-through efforts will be worth monitoring. The unchanged full-year forecast indicates management anticipates a recovery in the second half of the fiscal year.
6040|G-日本スキー
468.0
▲ +1.30%
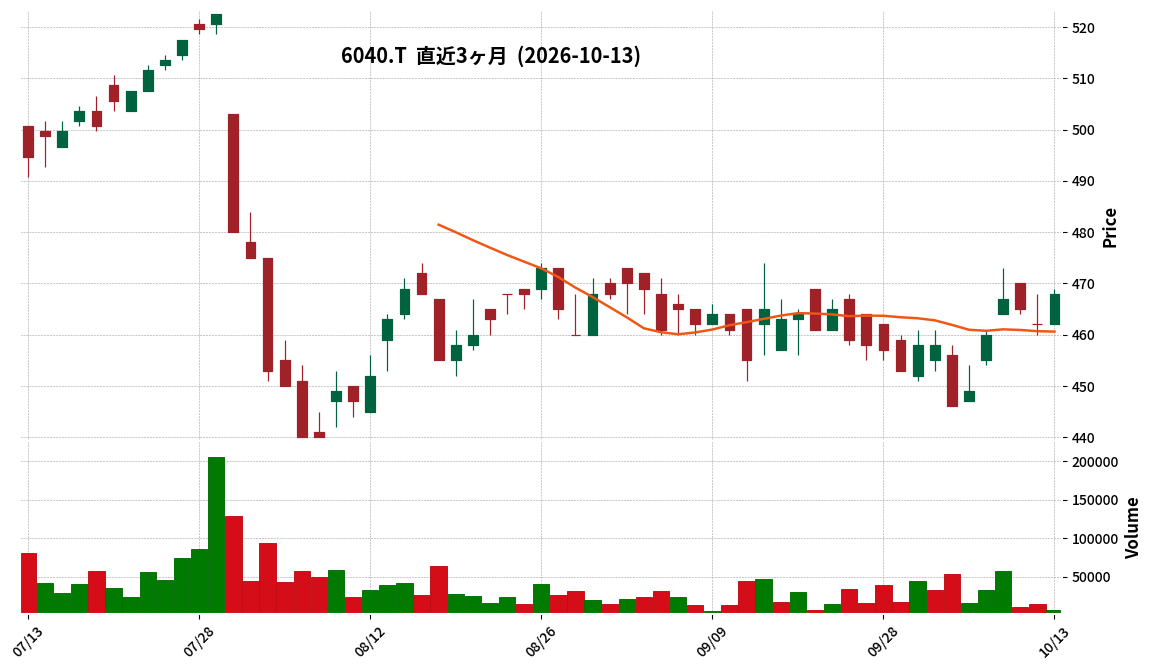
📎 Source:G-日本スキー Official IR →
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- G-NIPPON SKI announced the addition of “Marunuma Kogen Ski Resort” as a new facility covered by its shareholder benefit program.
- Marunuma Kogen Ski Resort will be eligible for both the “Lift Discount Ticket (30% off)” for shareholders holding 100 shares or more, and the “Common Winter Season Ticket” for shareholders holding 3,000 shares or more.
- Tsugaike Mountain Resort, previously only eligible for “Lift Discount Tickets,” will now also be covered by the “Common Winter Season Ticket.”
- These changes will apply to individual shareholders (holding 100 shares or more, with an address in Japan) as of July 31, 2026.
- Shareholder benefit tickets are scheduled to be shipped sequentially starting from October 19, 2026.
🤖 AI Perspective
This announcement suggests G-NIPPON SKI’s commitment to enhancing shareholder returns and fostering “investa-mers” (investors who are also customers) by expanding the scope of its shareholder benefit program. The inclusion of Marunuma Kogen Ski Resort and the expansion of Tsugaike Mountain Resort’s eligibility for common season tickets may enhance the choices and convenience for shareholders utilizing the benefits. This move could potentially strengthen the company’s appeal to shareholders who are ski and snowboard enthusiasts.
470A|P-ローカル
501.0
▲ +0.00%
This article is an AI-generated summary and analysis of official IR disclosures.
📄 Announcement (AI-Reviewed)
- P-LOCAL’s net sales for the second quarter of the fiscal year ending February 2027 reached ¥3,150 million, marking a 12.8% decrease compared to the same period last year.
- For the same interim period, the company reported an operating loss of ¥427 million (compared to an operating profit of ¥210 million in the prior year), an ordinary loss of ¥453 million (compared to an ordinary profit of ¥199 million), and a net loss of ¥296 million (compared to a net profit of ¥130 million).
- As of the end of Q2 FY2027, total assets stood at ¥3,926 million, net assets at ¥154 million, and the equity ratio at 3.8%.
- The full-year earnings forecast has been revised to “Undecided,” citing difficulties in making reasonable calculations at this time, an update from the forecast announced on April 14, 2026.
- Regarding dividend forecasts, both the interim and year-end dividends for FY2027 (forecast) are set at ¥0.00, indicating a revision from the most recently announced dividend forecast.
🤖 AI Perspective
P-LOCAL’s Q2 FY2027 results show a decline in sales and a shift to losses across all profit stages. Factors such as changes in the Furusato Nozei system, price fluctuations in the rice market, and procurement challenges due to earthquakes in Kumamoto Prefecture appear to have impacted operations. The revision of the full-year earnings forecast to “Undecided” suggests significant uncertainty regarding future business conditions.
💡 Start investing with IR insights


※ 本ページには広告が含まれます(PR)
Disclaimer: This article is for informational purposes only and does not constitute investment advice. All investment decisions are at your own risk.
コメント